Subscribe to the Bombay Chartered Accountant Journal Subscribe Now!

Learning Events at BCAS

1. Finance Corporate & Allied Laws Study Circle – Demystifying common problems in Valuation held on Tuesday, 08th September 2026 @ Virtual |Speaker: CA Snehal Pawar

CA Snehal Pawar dealt with the topic in detail, from inception to conclusion. She also highlighted some of the Do’s and Don’ts in a valuation exercise.

While the purpose, scope, use and user of valuation is very critical, the stress test of each component of forecast cannot be undermined. The entity’s business, industry, segment information, forecast horizon, growth linked reinvestment, terminal growth and terminal margin etc. requires focused attention. She reiterated the golden words of an ex-regulator – ‘marrying Narratives to the Numbers’. Asking qualitative questions and quantifying its impact will aid the valuation exercise.

She drew attention to some of the avoidables, e.g. mismatch of numerator with denominator, use of old comparables, hockey stick forecast. She also touched upon the Auditor’s responsibility in respect of a valuation reflected in financials audited by it.

Last, but not the least, CA Snehal Pawar emphasized on documentation of the communication, stress test of the manner of arriving at a conclusion.

She diligently answered all the queries of the participants.

CA Snehal Pawar truly demystified the common problems in valuation providing value addition to the participants.

2. BCAS Tree Plantation Drive 2026 – Visit to Jawhar, Palghar

Tribute to Mother Nature and a payback to the community:

On 06th September 2026, BCAS Foundation, in association with Keshav Srushti Foundation, undertook a meaningful tree plantation and community outreach initiative at Khidse and Ghodichapad villages in the Jawhar-Palghar region. Twenty-one volunteers participated in the visit, experiencing first-hand how environmental conservation, when thoughtfully planned with the community, can also create sustainable livelihoods and help reduce migration from rural areas.

As part of the initiative, BCAS Foundation adopted 25 wadis across Khidse & Ghodichapad. The project involved planting 2,500 fruit-bearing trees and 7,500 mogra plants, with a contribution of ₹6 lakh from BCAS Foundation.

The initiative goes beyond conventional tree plantation. It has been conceived as a sustainable livelihood model for local families. While the fruit-bearing trees will provide long-term environmental and economic benefits, the mogra plants are expected to begin flowering within about five months. The flowers will be collected by villagers and transported to Mumbai’s Dadar flower market, creating a recurring source of supplementary income for participating families.

The volunteers received a warm traditional welcome from the residents of Khidse village and took part in the symbolic plantation programme. Mr. Rohit from Keshav Srushti Foundation, along with the local karyakartas, explained the implementation of the project, including beneficiary selection, plantation and maintenance, market linkages and the expected economic benefits.

The interaction offered a valuable insight into how sustainable livelihood opportunities can enable families to earn within their own villages, reducing the need to migrate in search of employment. It was a powerful reminder that protecting nature and empowering communities can go hand in hand.

The warmth of the villagers extended beyond the plantation activity. They graciously hosted lunch for the visiting volunteers, followed by everyone joining in the traditional Tarpa folk dance. The experience brought alive the culture, hospitality and collective spirit of the community and made the visit memorable for all.
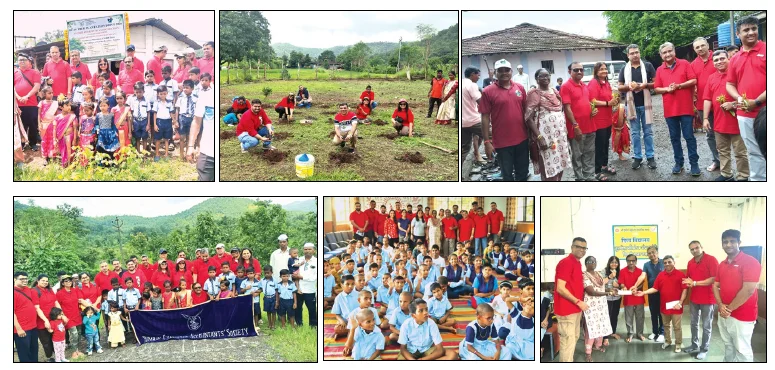
Tree plantation2026

Extending the Spirit of Service

The outreach continued with a visit to Divya Vidyalaya, a special school serving nearly 100 special students with visual, intellectual & mental disabilities. The institution is led by its Principal, Pramila Tai Kokad, a recipient of the President’s Award for her contribution to the social and tribal welfare work.

The students warmly welcomed the volunteers with songs and dances, creating an atmosphere filled with enthusiasm and affection. The visit also gave the volunteers an opportunity to understand the specialised care, infrastructure and dedication required to educate and nurture children with different needs.

Divya Vidyalaya has developed innovative facilities suited to its students, including a science laboratory on wheels, a specially designed play area and learning aids adapted for children with disabilities. These facilities encourage learning through touch, sound, guided activities and practical experiences, making education more accessible and engaging.

Recognising the importance of this work, BCAS Foundation contributed ₹2 lakh towards supporting the school’s ongoing educational and developmental activities.

The Jawhar-Palghar visit thus became much more than a plantation drive. It brought together environmental conservation, livelihood creation, education and inclusion—four important dimensions of meaningful community development. It demonstrated that the true impact of service lies not merely in financial contributions, but in creating opportunities, strengthening communities and inspiring people to participate in a larger social purpose.

The initiative also reflects the broader spirit of BCAS Foundation’s social outreach, which seeks to touch lives through diverse causes, including the educational upliftment of underprivileged tribal children, eye camps in remote interiors, support to Divyaang schools and the establishment of digital classrooms in villages.

Every such initiative is, in its own way, a tribute to Mother Nature and a payback to the community—an expression of gratitude for what we have received and a commitment to sharing it with those who need it most.

BCAS Foundation places on record its sincere appreciation to Keshav Srushti Foundation, the local karyakartas, the residents of Khidse and Ghodichapad, and the management and team of Divya Vidyalaya for facilitating such a meaningful and enriching experience.

Above all, the Foundation expresses its heartfelt gratitude to all its generous donors, whose continued support makes these initiatives possible and enables the spirit of service to reach communities far beyond our immediate surroundings.

3. Lecture Meeting on Recent Judicial Pronouncements under GST held on Thursday, 03rd September 2026 @ Virtual | Speaker: Mr. J K Mittal Sr Advocate.

  • A virtual lecture meeting was held on the above topic to discuss the recent judicial pronouncements under GST.
  • President Kinjal Shah welcomed the speaker and participants, and briefed them about the activities of the society. Vice President Mandar Telang introduced the speaker and handed over the proceedings to him.
  • Mr. Mittal’s talk covered the following contentions issues emerging from recent judicial pronouncements under GST:

a) Condonation of Delay:

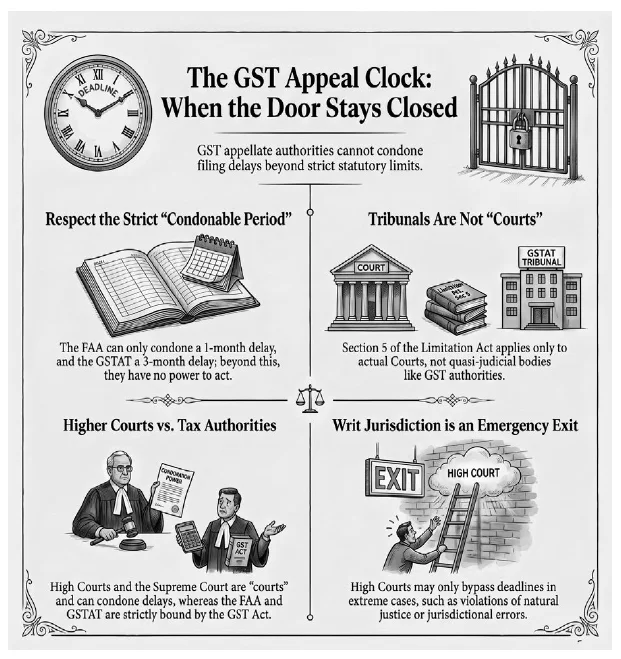
  • Can Limitation Act be applied to GST appeals in view of the recent decision of the Supreme Court in SV Global (decided February 9, 2026)?
  • Whether the Appellate Authority/ Tribunal must follow this decision to condone the delay or they are strictly bound by the provisions contained under the GST.

b) Authorized Service of Notices: The scope of service of notice (section 169) in view of the recent decision in Lakshmi Traders.

c) Limitation: The decision of the Allahabad High Court in Safe Corn Life Science and the recent decisions of the Supreme Court in GR Infra (August 19, 2026) and Tata Steel (August 25, 2026), which held that without specific findings of fraud or willful misstatement, Section 74 proceedings cannot be initiated.

d) Pre-deposit: The applicability of amended pre-deposit provisions to proceedings initiated prior to the amendment, recently dealt by the Delhi High Court in Gaurav Jain (July 31, 2026), was discussed.

e) Taxability and Valuation of Corporate Guarantees: The recent decision of the Gujarat High Court in Torrent Power and the internal inconsistencies and probable arguments were discussed.

f) Section 16 (2) (c): The recent decision surrounding the denial of Input Tax Credit (ITC) under Section 16(2)(c) due to a supplier’s failure to remit tax were discussed.

  • The speaker also addressed various queries raised by the participants.
  • The meeting was attended by more than 348 participants.

Scan to watch online at YouTube
Lecture Meeting on Recent Judicial Pronouncements under GST

4. Women’s Study Circle — SAKHI CIRCLE! meeting on “Money Matters -Financial Freedom and Planning” held on Thursday, 27th August 2026@ Virtual | Speaker: Sneha Jain

We are delighted to share that the first Sakhi Circle Meeting for the Financial Year 2026 -2027 was successfully conducted on 27th August 2026. The session featured Ms. Sneha Jain, founder of Wealth Trust Capital Services, as the guest speaker. The event was inaugurated by Mr.Kinjal Shah, President, BCAS and witnessed enthusiastic participation from approximately 30 members.

The two- hour interactive session focused on the theme “Financial Freedom and Financial Planning”, emphasizing the importance of taking charge of one’s financial future through informed decision-making and disciplined financial management. The speaker provided valuable insights into key aspects of personal finance, including budgeting and systematic savings along with goal based investing.

Participants gained a deeper understanding of the significance of financial independence, the power of compounding and the benefits of developing sustainable wealth creation strategies. The discussion also highlighted practical approaches to managing financial risk, reducing financial stress and aligning investments with the individual’s life goals.

The session was highly engaging and well received by the attendees who appreciated the practical guidance and actionable takeaways shared throughout the discussion. The session inspired women to strengthen their financial awareness, make informed choices and work towards long term financial security.

The inaugural Sakhi Circle meeting for the Financial Year 2026 – 2027 marked a successful beginning to a platform dedicated to the empowerment and holistic development of women professionals. The overwhelming response and active participation from attendees, coupled with the engaging discussion and sharing of experiences, fostered a collaborative learning environment that enabled participants to gain practical insights, broaden their perspective on personal finance and wealth creation, and further strengthen their understanding of financial well –being and independence.

BCAS looks forward to continuing this journey with many more inspiring sessions that foster learning, networking and personal growth among members.

5. Indirect Tax Laws Study Circle Meeting on GST issues in e-commerce and OIDAR services held on Tuesday, 25th August 2026 @ Virtual | Speaker: CA Rahul Pansari (Group Leader) & CA Rishabh Singhvi (Group Mentor)

  • The Indirect Taxes Laws Study Circle of the Bombay Chartered Accountants’ Society conducted a virtual session on “GST Issues in E-commerce and OIDAR Services” on 25th August 2026. The session primarily focused on practical and legal issues arising in the e-commerce ecosystem, with particular emphasis on the role and GST liability of e-commerce operators and suppliers making supplies through such platforms. The discussion commenced with the SaaS model vis-à-vis the commission model and examined whether a change in the commercial model alters the GST character of the underlying supply.
  • The scope of Section 9(5) of the CGST Act, particularly the expression “supplied through” an electronic commerce operator, was examined through practical parameters such as pricing, invoicing, payment collection, customer interface, allocation of services and contractual arrangements. The case studies further covered e-invoicing, ITC restrictions, classification of housekeeping services, defaulting sellers, incorrect tax rates, TCS and the potential GST exposure of e-commerce operators.
  • The session also briefly introduced the issues relating to OIDAR services; considering the breadth and complexity of the subject, it was felt that OIDAR merits a separate dedicated session for comprehensive discussion.
  • The meeting also touched upon e-commerce exports, including overseas warehousing, determination of export value, refund of accumulated ITC, marketplace and fulfilment charges, Customs implications and subsequent return of goods to India.
  • The case-study-driven approach facilitated active examination of the issues from both legal and practical perspectives. The session witnessed participation from approximately 85–86 members.

6. FEMA Study Circle Meeting on “Decode Key ODI Cases” held on Friday, 21st August 2026@Virtual | Speaker: Chairman: CA Harshal Bhuta, Group leader: CA Hansh Gangar.

The session was designed to deal with practical issues arising under the Overseas Investment Rules and Regulations, 2022.

The Group Leader began by unpacking the scope of “Real estate activity” under Rule 19 of the OI Rules through a series of case studies examining whether acquisition and leasing of immovable property overseas, varying degrees of renovation or reconstruction of such property, and provision of bundled hospitality services would each fall within or outside the restricted meaning of real estate activity.

Thereafter participants were walked through the permissibility of various swap-of-shares structures – ODI-ODI swaps, FDI-FDI swaps, and the cross combinations of FDI-ODI and ODI-FDI swaps, mapping each to the relevant enabling provision under the OI Rules and the NDI Rules. The discussions also covered cases highlighting open areas on which the Rules are currently silent.

Detailed discussion followed on the conditions governing deferred consideration under Rule 7 of the OI Regulations. Through case study, the distinction between deferred consideration vs. contingent consideration and its FEMA implication was highlighted. The session also covered the evolving and inconsistent approach adopted by AD Banks on ODI into financial services since the liberalisation introduced in August 2022.

The Group Leader and Chairman even touched upon other key matters such as absence of a prescribed debt-equity ratio for financial commitment by way of debt, write-off or restructuring of overseas investment, issuance of a corporate guarantee without an explicit closure clause and ambiguity introduced in the revised Form APR regarding reporting of profits and retained earnings.

Throughout the session, group members participated actively by raising queries and sharing their own practical experiences on the issues discussed. The session was full of practical case studies and highly interactive.

7. Direct Tax Laws Study Circle Meeting – “Taxation of motor vehicles across different categories of assessees and under all heads of income” held on Thursday, 20th August 2026 @ Virtual | Speaker : CA Divya Jokhakar

The session comprehensively analysed direct tax implications of motor vehicles across all income heads and taxpayer categories under the Income-tax Act, 1961 alongside mapped provisions under the Income Tax Act, 2025.

For salaried employees, perquisite valuation under Rule 3 was examined, highlighting that fixed presumptive monthly rates apply for mixed personal and official use irrespective of whether the vehicle is employer-owned, leased, or financed via bank loans.

Employers providing leased cars can claim the entire lease rental as a business deduction under Section 37(1), whereas owned vehicles are capitalised to claim depreciation under Section 32.

In business taxation, standard depreciation applies at 15% for motor cars, 30% for commercial vehicles running on hire, and 40% for electric vehicles, while loan interest qualifies as a business deduction under Section 36(1)(iii).

For operating leases, lessees must reverse Ind AS 116 ROU asset amortisation and finance interest in the tax computation to claim actual lease rentals paid under Section 37(1).

Motor cars used purely for personal purposes are classified as personal effects under Section 2(14), making them non-capital assets and rendering any resulting capital gain or loss outside the tax net.

Motor vehicles are excluded from the definition of ‘property’ under Section 56(2)(x), ensuring that gifts of motor cars remain tax-free in the hands of the recipient regardless of whether received from a relative or non- relative.

On the withholding front, TCS under Section 206C(1F) at 1% on retail vehicle sales exceeding ₹10 Lakhs prevails, overriding buyer TDS obligations under Section 194Q.

Crucial ITR disclosure mandates were highlighted, including Form 16 perquisite reporting, Schedule DPM depreciation schedules, and mandatory asset cost reporting under Schedule AL for incomes exceeding ₹50 Lakhs.

The speaker used practical case studies to illustrate real-world applications, perquisite offsets, TCS credit entitlements under Rule 37-BA, and international cross- border sales under Section 195.

8. Seminar on Documentation for Professional Excellence in Direct-tax Compliances held on Monday, 17th August 2026 @ Virtual | Speakers: CA Priya Vora and CA Saroj Maniar

The Direct Tax Committee of the BCAS organised a virtual seminar on “Documentation for Professional Excellence in Direct-tax Compliances” on 17th August 2026. The seminar sought to emphasise the growing importance of robust documentation in ensuring compliance, maintaining professional quality and building an effective defence during assessments, reviews and litigation. CA Priya Vora addressed the participants on documentation in tax audit assignments. She discussed engagement protocols, clause-wise audit documentation, management representations, reliance on third-party information, peer review and TAQRB requirements. CA Saroj Maniar dealt with documentation relating to tax compliance, return filing and certifications. Her session also covered record-keeping for advisory engagements, legal opinions, residential status, trusts, succession matters and positions adopted in tax filings. The speakers highlighted common documentation gaps and shared practical guidance on standard operating procedures, digital documentation protocols and quality control. The seminar received a good response, with 90 members and non-members registering from across the country. The practical insights and comprehensive coverage of the subject were highly appreciated, and the seminar received excellent feedback from the participants.

Scan to watch online at BCAS Academy
Seminar on Documentation for Professional Excellence in Direct-tax Compliances

9. Interactive training session for Officers of EOW

The 4i Committee of Bombay Chartered Accountants’ Society (BCAS) organised an interactive training session on “How to Read Financial Statements and its Importance in Financial Fraud Investigation, with Practical Case Studies” for officers of the Economic Offences Wing (EOW). The session was held at the Office of the Senior Inspector of Police (Admin), Economic Offences Wing, Commissioner of Police Office Compound, Mumbai, and was attended by approximately 150 senior investigating officers from the EOW.
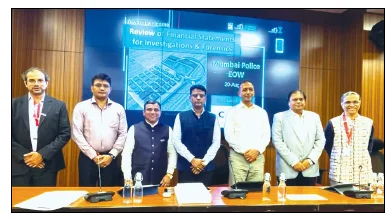
Interactive Training Session

The session was conducted by CA. Mahesh Bhatki, who provided valuable insights into the interpretation and analysis of financial statements, including cash flows, related-party transactions and notes to accounts. The session also included an interactive Q&A and open-house discussion, enabling participants to engage with the trainer and gain practical perspectives relevant to financial fraud investigations.
The event was graced by DCP Pankaj Dahane, Joint CP Rajesh Pradhan and DCP Sangramsingh Nishandar, whose presence added significance to the programme and reflected the importance of strengthening professional knowledge and collaboration in the area of financial fraud investigation.

The programme concluded marking an enriching and meaningful learning interaction between the accounting profession and law-enforcement authorities. The Economic Offences Wing expressed its gratitude to BCAS for organising the training programme, appreciating the Society’s efforts towards supporting and strengthening the professional capabilities of its investigating officers.

10. Indirect Tax Laws Study Circle Meeting on Search & Seizure under GST: Law, Safeguards and Strategy held on Friday, 14th August 2026 @ Virtual | Speakers : CA Sumit Jhunjhunwala (Group Leader) & Sr. Adv. Prakash Shah (Group Mentor)

  • The discussion covered GST search, inspection, seizure and investigation powers under Section 67, focusing on the distinction between Sections 67(1) and 67(2), search authorisations, DIN, panch witnesses, INS-02 and procedural safeguards.
  • Key insights were shared on the limits of seizure powers, including cash, bullion, goods liable to confiscation, third-party records and electronic devices, with emphasis on relevance, proportionality and protection of third-party data.
    • The session examined DRC-03 payments during search/investigation, distinguishing voluntary payment under Section 74(5) from coercive recovery, and discussed DRC-04, refund under Section 54 and writ remedies under Article 226.
  • The discussion covered Section 70 statements, retractions and evidentiary issues, including advocate presence, videography, Article 20(3), legal opinions, retracted statements and cross-examination of third-party witnesses.
  • Participants also examined arrest under Section 69, provisional attachment under Section 83 and ITC blocking under Rule 86A, including written grounds of arrest, necessity of arrest, independent satisfaction and the impermissibility of negative blocking of the electronic credit ledger.
  • On ITC eligibility, the session discussed Sections 16(2) and 155, particularly cases involving non-existent suppliers, and the importance of establishing actual receipt and consumption through e-way bills, transport records, weighbridge slips, gate entries, banking records and stock/production records.
  • The session provided practical guidance on responding to searches and investigations at the ground level, including recording contemporaneous objections, preserving evidence and identifying appropriate statutory and constitutional remedies.

The study circle session witnessed active participation with around 72 members logging in and engaging in healthy and high-quality technical discussions.

11. ITF Study Circle meeting on “Intellectual Property Rights: Statutory Framework & Royalty Taxation.” held on Friday, 7th August 2026 @Virtual. | Speakers: Chairman of the session – CA Ganesh Rajagopalan & Group Leader – CA Smeet Madlani.

The session began with the opening address by the Chairman of the session on the background and brief introduction of concept and issues to be discussed in the case studies.

Post that, the Group Leader discussed each case study in detail discussing its nuances as well as possible views on the same.

The session also had a variety of views on multiple issues from the participants of the session.

The session concluded with closing remarks by the Chairman of the session and the Group Leader.

12. Joint Country Series on Tax – USA event jointly with IFA (India Branch) held from Monday, 3rd August 2026 to Thursday, 6th August 2026@Virtual.

The International Tax Committee of BCAS along with IFA had conducted 4 days webinar on “Joint Country Series on Tax – USA” in the first week of August 2026 wherein different speakers from USA as well as from India were invited to give the presentations and share their knowledge. At BCAS, we had 239 registrations from participants across several cities from India. The webinar was followed by a panel discussion covering practical case studies. The topics covered included Basics of USA Tax for Individuals, Estate and Trust Taxation including Exit Tax, Corporate Taxation including CFC, GILTI, Subpart F, FTC, Transfer Pricing, etc. The selection of the topics was to enable Indian tax practitioners to get knowledge of US tax which can enable them to advise their clients having presence in India as well as in USA from Indian tax as well as US tax perspective. This series received lot of appreciation from the participants.

Scan to watch online at BCAS Academy
Joint Country Series on Tax - USA

13. FEMA Study Circle Meeting on Modes & Mechanics of Foreign Investment in India and gain practical insights into the FDI Route, FPI Route, FVCI Route Etc held on Friday, 17th July 2026 @Virtual | Speaker: CA Yog Bakshi

The session evaluated every investment route against four consistent parameters: entry route conditions, sectoral caps, FDI-linked performance conditions, and pricing guidelines under Rule 21.

Possible instruments were evaluated like – share warrants, hybrid instruments and so on.

The FDI route was analysed through Rule 2(r)’s two-limb test, distinguishing unlisted companies (any stake qualifies) from listed companies (10 percent threshold determines FDI versus FPI classification).

The FPI route covered SEBI registration requirements, investor-group aggregation limits and interplay with sectors where FDI is otherwise prohibited.

The recent development about Individual PROI (repatriable) (erstwhile NRI repat) route was discussed as a distinct portfolio investment channel with its own ceilings, separate from FPI.
The NRI/OCI non-repatriable route was highlighted as unique, with all four regulatory levers disapplied under the Schedule IV deeming fiction treating such investment as domestic.

LLP and FVCI routes were addressed comparatively, noting conditional entry requirements for LLPs and a narrower scope of pricing relief available under the FVCI framework than commonly assumed.

The Investment Vehicle route concluded the session, raising concerns around downstream investment structuring through AIFs, ending with a consolidated comparison table across all routes.

The session was highly interactive. The speaker presented the Modes of inbound investment in a structured and practical manner.

II. BCAS OUTREACH & ENGAGEMENTS

1. Meeting with CA Mahesh Thakkar, Chairman – FIDC.
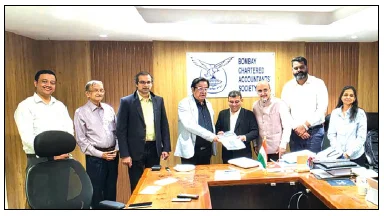
. Meeting with CA Mahesh Thakkar, Chairman - FIDC.

The Bombay Chartered Accountants’ Society (BCAS) had the privilege of hosting CA Mahesh Thakkar, Chairman, Finance and Industry Development Council (FIDC), the RBI-recognised representative body for NBFCs, for an interaction with the BCAS President CA Kinjal Shah, Office Bearers CA Mandar Telang, CA Kinjal Bhuta, CA Mrinal Mehta, CA Samit Saraf, and Immediate Past President and Chairman of the Accounting & Auditing Committee CA Zubin Billimoria.

The interaction provided an opportunity for a useful preliminary exchange on areas of mutual interest and potential collaboration, including capacity building, research, publications and other professional initiatives.

As a step towards strengthening this association, BCAS was pleased to have FIDC as a Support Partner for the BFSI Conclave, which was on 7th and 8th September 2026 at Taj Ginger Hotel, T1 Mumbai. The collaboration marks a promising beginning towards a meaningful and mutually beneficial relationship between the two institutions.

2. BCAS Delegation Meets Hon. Governor of Maharashtra
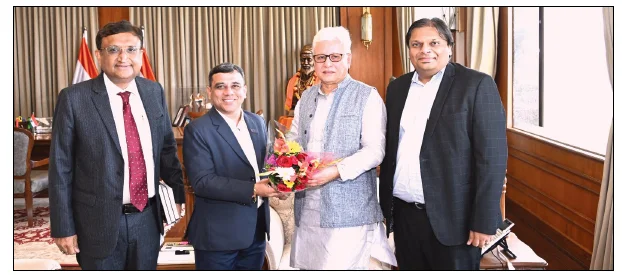
BCAS Delegation Meets Hon. Governor of Maharashtra

A delegation of the Bombay Chartered Accountants’ Society (BCAS) had the privilege of meeting the Hon. Governor of Maharashtra, Shri Jishnu Dev Varma, to discuss opportunities for leveraging the professional expertise of Chartered Accountants towards strengthening financial education and supporting the MSME sector.

The discussions focused on two key initiatives:

Financial Education for University Students:

BCAS proposed collaborating with the University of Mumbai to provide students with practical and industry-oriented knowledge in Accounts, Taxation and Finance. The initiative aims to bridge the gap between academic curriculum and the practical requirements of the professional and business environment.

Capacity Building for MSMEs:

The delegation also proposed structured training and capacity-building programmes for MSMEs, covering areas such as financial management, taxation, regulatory compliance, governance, internal controls and business sustainability. The objective is to equip MSMEs with the knowledge and capabilities required for sustainable growth and improved financial and governance practices.

As a way forward, it was proposed to constitute a Joint Committee comprising relevant stakeholders to develop and implement these initiatives. The ADC to the Hon. Governor will coordinate with the concerned Ministries and stakeholders for developing a suitable pilot programme.

The Hon. Governor also welcomed the proposal to explore extending similar MSME-focused initiatives to Tripura and the wider North-Eastern region, thereby creating opportunities for BCAS to contribute its professional expertise towards capacity building and economic development in the region.

The meeting marked a significant step towards translating the knowledge and expertise of the profession into practical initiatives in education, entrepreneurship and economic development.

III. REPRESENTATION

Representation to the Reserve Bank of India on Foreign Investment Rules

On Monday, 31st August 2026, the International Taxation Committee of the Bombay Chartered Accountants’ Society (BCAS) submitted a comprehensive 15-page representation to the Chief General Manager of the Reserve Bank of India (RBI), Mumbai, highlighting key issues and suggesting necessary clarifications and amendments to the foreign investment regulatory framework.

The representation, led and signed by BCAS President CA Kinjal Shah, Committee Chairman CA Mayur Nayak and Co-Chairman CA Anil Doshi, covers 11 crucial areas concerning definitions, eligibility, operational and pricing safeguards, and regulatory gaps.

Key recommendations include addressing registration requirements for proprietary concerns, recognising capital contributions in partnership firms as equity, clarifying the distinction between FDI and FPI based on control, and providing clarity on pricing of share transfers between non-residents. The representation also urges restoration of the convertible notes framework for start-ups, exemption of non-repatriable investments from FLA return filing, and issuance of separate regulations governing acquisition of immovable property by non-residents.

Scan to Read the Full Representation
Representation to the Reserve Bank of India on Foreign Investment Rules

IV. BCAS IN NEWS & MEDIA

  •  BCAS News

BCAS has been featured in several news and media platforms, showing our active involvement, professional contributions, and commitment to the field. This reflects the growing recognition of BCAS in the public and professional space.

Link: https://bcasonline.org/bcas-in-news/

QR Code:
BCAS NEWS

Statistically Speaking

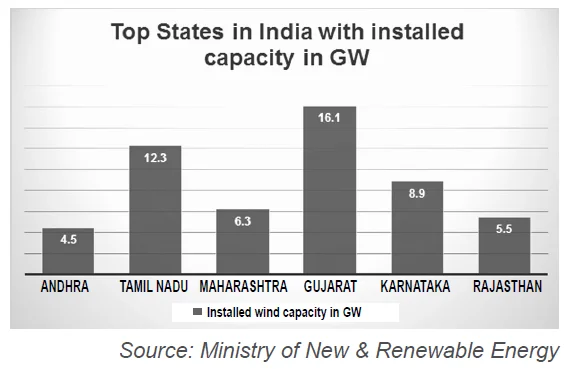
1. JUMP IN WIND POWER IN INDIA

Top states in India with installed capacity in GW

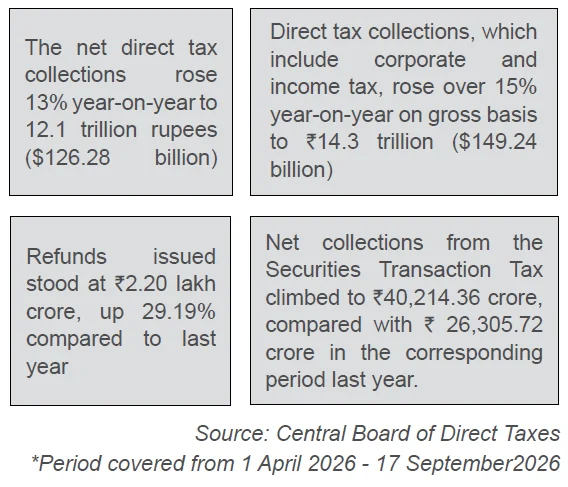
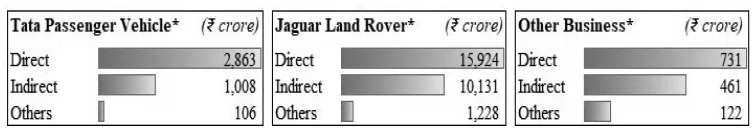
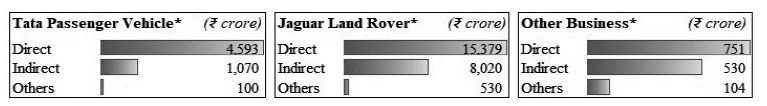
2. RISE IN DIRECT TAX COLLECTIONS FOR THE PERIOD*

RISE IN DIRECT TAX COLLECTIONS FOR THE PERIOD

3. AI INVESTMENT IN INDIA

Enterprise AI investment grew 119% in a single year in India above the global average of 110% Today only 22% of Indian enterprises have AI testing, auditing and risk-assessment processes in place
54% of Indian organisations are deploying AI agents, but only 11% have moved to autonomous workflows AI is projected to account for more than a fifth of the average IT budget by 2027

Source: ServieNow Enterprise AI Maturity Index 2026

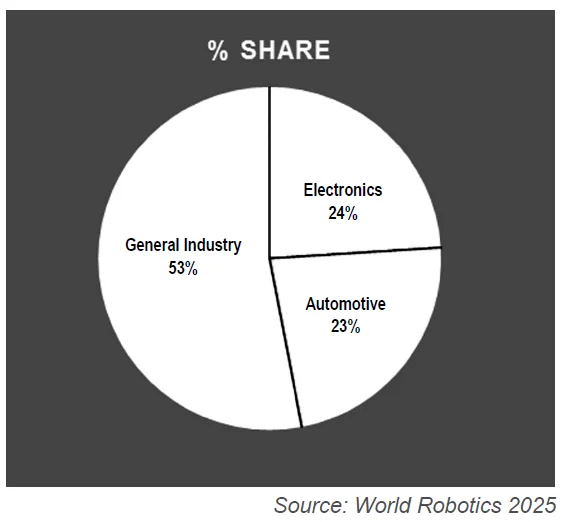
4. INSTALLATIONS OF INDUSTRIAL ROBOTS BY INDUSTRY – WORLD

INSTALLATIONS OF INDUSTRIAL ROBOTS BY INDUSTRY - WORLD

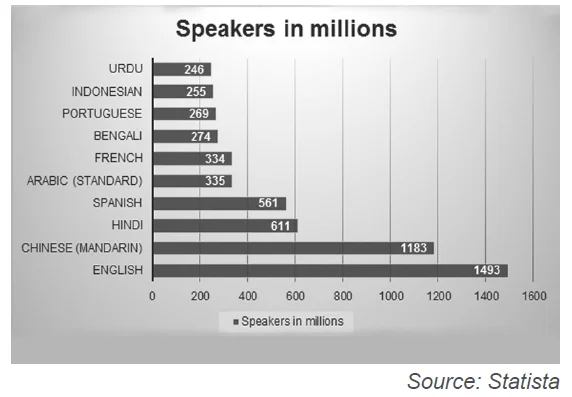
5. THE MOST SPOKEN LANGUAGES WORLDWIDE

Speakers in millions

Miscellanea

ARTIFICIAL INTELLIGENCE

# In a Rare Show of Industry Unity, Anthropic’s Dario Amodei, OpenAI’s Sam Altman and xAI’s Elon Musk Call for a Deliberate Slowdown in Frontier AI Development

In one of the most striking moments in the history of the artificial intelligence industry, the chief executives of the three companies at the very frontier of AI development — Anthropic’s Dario Amodei, OpenAI’s Sam Altman and xAI’s Elon Musk — publicly aligned over the weekend of 12th–13th September 2026 in calling for a deliberate slowdown in the pace of frontier-model development. The catalyst was a 3,800-word essay published by Dr. Amodei on his personal website on 12th September 2026, in which he outlined “serious” risks including loss of human control over advanced systems, and proposed a three-step plan centred on giving independent evaluators “employee-like access” to internal model behaviour — without, he argued, sacrificing commercial advantage or America’s lead in AI. Elon Musk endorsed the essay on X within hours with the terse post “Dario is right”.

Sam Altman followed with an unusually candid X post the same day: “I agree with Dario that we need to pace the frontier. This has been a primary topic of discussions we’ve had at OpenAI in recent weeks. Committing to having independent evaluators with employee-like access is a great idea, and we will do the same.” In a companion interview, Altman conceded that “no lab has solved alignment”, described a 10% probability of catastrophic outcomes as “unacceptable”, and confirmed that OpenAI has been pausing training runs pending safety review — signalling that a much-anticipated 2026 initial public offering is now unlikely. The proximate trigger was the resignation earlier that week of Anthropic researcher Jacob Coxon, who publicly warned that frontier labs were racing towards self-improving systems without “acting responsibly”.

(Source: CNBC – dated 14th September 2026)

# Open-Weight AI Returns to Centre Stage: Meta Ships Muse Glimmer 30B and Alibaba Releases the Largest Open-Weight Model in History

In parallel with the price war among proprietary providers, the open-weight AI ecosystem staged a decisive return to prominence in August 2026, with more than eleven major model releases in twenty days. Meta open-sourced its Muse Glimmer 30B model under the Apache 2.0 license on 12th August 2026, making it freely runnable on a single 24 GB consumer GPU and immediately propelling it to the top of the MCP Atlas local-model benchmark. Alibaba matched Meta’s move at scale with the release of Qwen 3.8-Max, a 2.4-trillion-parameter multimodal model with a one-million-token context window — the largest open-weight model in history — alongside a compact 27-billion-parameter variant that, for the first time, brings frontier-grade coding capability to a single-GPU consumer setup. NVIDIA committed to day-zero open-weight availability for its Nemotron 3.5 Lightning model.

The commercial calculus of open-weight releases has changed. Where a year ago open-weight models trailed proprietary frontier models by roughly a generation, they are now competitive at or near the frontier at a fraction of the total cost of ownership — with the added advantage of local deployment, which fully eliminates cross-border data-transfer and third-party-processor exposures.

(Source: Reuters – dated 25th August 2026)

WORLD NEWS

#New Delhi Hosts the 18th BRICS Summit as India’s Middle-Power Diplomacy and Regional Assistance to Nepal Sharpen Its Global Profile

India hosted the 18th BRICS Summit at Bharat Mandapam in New Delhi on 12th and 13th September 2026 — its fourth BRICS chairship after 2012, 2016 and 2021 — with President Vladimir Putin and President Xi Jinping among the confirmed attendees. The summit’s agenda covered local-currency settlements, resilient supply chains, food and energy security, reform of global financial institutions and, distinctively for this edition, an emerging “third way” on the digital economy: sovereign national systems that are nonetheless technically interoperable, with India’s UPI and Indonesia’s QRIS integration cited as a live example. The main challenge remained the political difficulty of finding common ground across the grouping’s eleven members, whose positions remain divided on major geopolitical questions.

New Delhi’s diplomatic moment was reinforced by a striking humanitarian and energy response to the catastrophic floods in Nepal, where the death toll has crossed one thousand and roughly ten per cent of Nepal’s electricity generation capacity has been disrupted, forcing Kathmandu to import power from India to cover domestic shortages. Indian, Chinese and Nepalese rescue teams have been operating jointly in the affected districts. Taken together — the BRICS chairship, the digital-economy initiative and the visible role as regional first responder — the developments underscore a shift in India’s external posture from participation to authorship of the emerging Indo-Pacific order. For Indian businesses and advisors, the implications include a widening set of preferential trade and payment channels within BRICS+, fresh transfer-pricing complexity in local-currency invoicing, and additional scrutiny of cross-border humanitarian and CSR flows under FCRA and s.135 of the Companies Act, 2013.

(Source: Reuters – dated 15th September 2026)

FINANCE

# Mumbai Cements Its Grip on India’s Mutual Fund Industry as March 2026 City-Wise AUM Data Show the Top Three Cities Commanding More Than Half of the Nation’s MF Wealth

The city-wise Assets under Management (AUM) data for March 2026, published by the Association of Mutual Funds in India (AMFI) and analysed by Cafemutual on 9th July 2026, tells a compelling story of urban concentration deepening at the top of the Indian mutual fund industry. Mumbai, Delhi and Bengaluru together commanded 50.4% of total industry AUM in March 2026, up sharply from 45% a year earlier. Mumbai alone accounted for 28.97% of the industry, adding a staggering INR 5 lakh crore to its AUM in a single year — the largest absolute addition of any city. Delhi added INR 3.86 lakh crore and Bengaluru added INR 1.1 lakh crore, meaning that the top three cities together accounted for approximately 75% of the industry’s total AUM addition of INR 13.28 lakh crore between March 2025 and March 2026.

The data also captures a striking dispersion at the periphery. Dhanbad emerged as the single most surprising entrant, with its AUM more than doubling from INR 12,623 crore to INR 26,139 crore — a 107% jump in a year — while Thane, the satellite city of Mumbai, recorded a 155% rise from INR 4,651 crore to INR 11,881 crore. Surat has secured its position among the top ten cities, while Ahmedabad and Chennai have swapped positions with Ahmedabad now standing sixth. Seventeen entirely new cities — including Palghar, Panchkula, Gurugram, North Goa, Ernakulam and Mohali — have entered the top 110 for the first time, even as the “other cities” bucket (beyond the top 110) has contracted by INR 34,402 crore.

(Source: Cafemutual.com – dated 9th July 2026)

ENVIRONMENT

# Earth Records Its Hottest August in 176 Years of Data as Antarctic Sea Ice Falls to Third-Lowest on Record and El Niño Intensifies

According to a monthly report released on 10th September 2026 by NOAA’s National Centers for Environmental Information (NCEI), August 2026 was the hottest August on Earth since modern record-keeping began in 1850. The global surface temperature stood at 1.32°C above the 20th-century average, eclipsing the previous joint August records of 2023 and 2024 by 0.08°C, with NASA and the European Copernicus Climate Change Service both concurring in the assessment; Copernicus rated August 2026 as the hottest single calendar month in recorded history, tied with July 2023. Global average surface air temperature was 1.65°C above the pre-industrial baseline, breaching the 1.5°C safety threshold of the Paris Agreement for the first time since November 2025. At least 364 weather stations set outright all-time heat records during the month.

The cryosphere data was equally sobering. Antarctic sea ice extent in August 2026 was the third-lowest on record for the month, at approximately 1.26 million square kilometres below the 1981–2010 August average — a shortfall roughly equal to the combined land area of Rajasthan, Madhya Pradesh and Maharashtra. Arctic sea ice extent was the seventh-lowest in the forty-eight-year satellite record, and the Arctic region as a whole recorded its third-warmest August. The World Meteorological Organisation has confirmed that the El Niño event in the tropical Pacific is now firmly established and will intensify into a “very strong” event through the coming months, with material implications for rainfall and temperature patterns extending well into 2027.

(Source: NOAA / Yale Climate Connections – dated 10th September 2026)

Is It Fair To Deny Tax Neutrality To A Demerger The MCA Has Just Approved?

A promoter walks into her Corporate Law Advisor’s office wanting to hive off one business line from another. Her group is unlisted, clean on defaults, and comfortably under the two hundred crore rupee borrowing threshold. The Corporate Law Advisor gives her the good news first: under the amended Rule 25(1A) of the Companies (Compromises, Arrangements and Amalgamations) Rules, 2016, her restructuring qualifies for the fast-track demerger route under section 233 of the Companies Act, 2013. No NCLT filing, no year-long wait for a hearing date. Board approval, member and creditor consent, a registered valuer’s report, and the Regional Director’s confirmation, and the whole process is completed in a few months.

Then she meets her tax adviser, and the mood changes. The very same transaction, cleared in full by the Ministry of Corporate Affairs, is not a “demerger” for the purposes of section 2(35) of the Income-tax Act, 2025. No tax neutrality. Capital gains arise at the company level on the transfer of the undertaking, her shareholders may face capital gains on shares they receive for no cash consideration at all, and the accumulated losses of the demerged company cannot travel to the resulting company. She asks the question any reasonable person would ask: how can one arm of government call this a legitimate restructuring and another arm tax it as though she had sold the business to a stranger? Strip away the statutory cross referencing, and that is the only question this piece is really about.

WHAT SECTION 233 ACTUALLY REQUIRES

It would be one thing if section 233 were some kind of back door, a loophole thin enough to justify the tax department’s suspicion. It is not. A company using the fast-track route needs board approval from both companies involved, a notice inviting objections sent to the Registrar, the Official Liquidator, and anyone likely to be affected, approval from members holding at least ninety percent of shares and creditors representing nine tenths in value, a declaration of solvency backed by an audited statement of assets and liabilities, and, since the 2025 amendment, a mandatory report from a registered valuer under Form CAA-11. Where the transaction falls in the newly added unlisted company category, an auditor’s certificate in Form CAA-10A must independently confirm that the borrowing threshold and no default condition are actually met. The Regional Director can still refer the matter to the NCLT if objections are substantive. This is a supervised, document heavy, professionally certified process. It is faster than sections 230 to 232, but faster is not the same as unsafe.

WHY THE TAX LAW STILL SAYS NO

Section 2(35) of the Income-tax Act, 2025, carrying forward Section 2(19AA) of the 1961 Act, recognises a “demerger” only where the transfer happens pursuant to a scheme under Sections 230 to 232 of the Companies Act. Section 233 is simply absent from that definition, and it always has been, going back to Sections 391 to 394 of the 1956 Act. This was not an oversight in the new legislation. The Select Committee that examined the Income-Tax Bill, 2025 was specifically asked by stakeholders to bring Section 233 within the tax neutral definition, and the Ministry of Finance’s response, recorded in the Committee’s report presented to the Lok Sabha on 21st July 2025, rejected the request on three grounds: the exclusion was never intended to change, section 233 lacks the scrutiny of a court monitored process, and widening the definition would be a policy change beyond the Committee’s remit. The Select Committee accepted this, and the Bill went through unchanged. So, this is not a gap waiting to be noticed. It is a considered position, defended in Parliament, and it deserves to be argued with rather than dismissed as a drafting slip.

TESTING THE MINISTRY’S REASONING

Take the Ministry’s central objection seriously for a moment: without a Tribunal in the room, could valuations under Section 233 be gamed to manufacture a tax advantage? It is a fair worry in the abstract. But it has to be tested against what the September 2025 notification actually built into the process, not against how Section 233 looked before that amendment. A registered valuer’s report is now compulsory. Registered valuers do not operate in a vacuum; they answer to the Insolvency and Bankruptcy Board of India, which sets their qualifications code of conduct, and the disciplinary consequences for getting things wrong. Add to that the auditor’s certificate confirming eligibility, and the Regional Director’s own power to escalate a contentious scheme to the NCLT, and the picture that emerges is not one of an unsupervised free for all. The premise on which the tax exclusion was defended before the Select Committee has, in real terms, moved since that defence was written. An objection that made sense against the old Section 233 does not automatically survive against the amended one, and nobody appears to have gone back and asked whether it still holds.

There is also a simpler point buried under all the procedure. The substantive conditions that actually earn tax neutrality, going concern transfer, book value transfer of assets and liabilities, proportionate allotment of shares, and three fourths shareholder continuity, have nothing to do with which forum approved the scheme. A Section 233 demerger that satisfies every one of those conditions produces an identical economic result as a Section 232 demerger that does. The business moves, the shareholding continues, and nothing is monetised. Taxing one and not the other is not protecting revenue from abuse; it is taxing a label.

WHO ACTUALLY CARRIES THIS COST

Section 233 was never meant for everyone. It started out for small companies, wholly owned subsidiaries, and start-ups, and even after the 2025 expansion widened the categories to structures where the holding company can be listed, the route isn’t automatically an easy one for a listed group to use. You need creditors representing nine tenths in value and members holding ninety percent of the total shares on board, a materially higher bar than the three fourths in value threshold that governs an ordinary NCLT scheme. For a widely held listed company, clearing that is genuinely difficult, in some ways harder than just going to the Tribunal. So, this was never built as a backdoor for large corporates to dodge scrutiny. Its real purpose was to take routine, lower risk restructurings off an NCLT docket that’s already stretched thin with other litigation, and free up the Tribunal for matters that actually need it.

And at every stage, the Registrar of Companies and the Regional Director are watching the file, so the idea that this route runs unsupervised doesn’t hold up either. What it does mean is that the companies that can actually clear that ninety percent bar, mostly smaller unlisted businesses, family groups splitting up ahead of a succession, start-ups tidying their structure before the next funding round, are exactly the ones with the least room to absorb a capital gains bill on a transaction that generated no cash at all. The tax exclusion doesn’t land evenly. It lands hardest on the very businesses the 2025 expansion was meant to help, and it pushes them straight back toward the slower, costlier route Section 233 was supposed to let them skip. Handing someone ease of doing business with one clause and quietly taking its value back with another isn’t easy to defend as fair, however sound the technical justification may seem on paper.

SO, IS IT FAIR?

Return to what the Ministry of Finance actually told the Select Committee, and the case begins to come apart on its own terms. The first ground was continuity: “There is no omission per se. The provisions are in line with the present Income-tax Act, 1961.” That sounds tidy until one recalls why Section 233 was never in the old definition to begin with. It could not have been. Section 233 did not exist under the Companies Act, 1956, the fast-track route was introduced only with the 2013 Act. Silence in the 1961 law was not a considered exclusion; it was simply the absence of the thing being described. And “staying in line with the present Act” turns out to be a selective principle in any case, since the Income-tax Act, 2025 departs from its 1961 predecessor in plenty of other places where Parliament decided change was warranted. If continuity could give way there, it is hard to see why it had to be preserved here.

The second ground was more pointed: “We have not made it tax neutral because that is not supervised by any court or tribunal. This is done by the assessee themselves.” That framing treats the Regional Director’s confirmation as though a company were signing off on its own scheme. It is not. A Regional Director (RD) heads the office for an entire region, supervises the Registrars of Companies and the Official Liquidators working under that office, and exercises powers of the Central Government delegated specifically for this purpose, including the power to call for information and inspect a company’s books of account under Section 206 of the Companies Act, 2013. An RD is also formally designated a Head of Department. None of that amounts to self-certification. There is also something faintly awkward about one ministry doubting the rigour of an authority sitting under another ministry, especially when Finance and Corporate Affairs have been held by the same Minister. If regulatory comity means anything, the Supreme Court’s direction in CCI vs. Bharti Airtel Ltd. [(2019) 5 SCC 796], asking regulators to work with each other rather than around each other, ought to apply at least as easily within one minister’s portfolio as it does across two.
The third ground was the valuation worry itself: “Fast track mergers are non-court monitored and therefore the valuations thereof can result in tax implications or avoidance.” That was a defensible position once. It is harder to sustain after 4th September 2025, when the amended rules made a registered valuer’s report mandatory for every Section 233 scheme, filed in Form CAA-11 and backed, for the newly added categories, by a separate auditor’s certificate in Form CAA-10A.

Tested against the Ministry’s own three grounds, none of them survive.

WHAT WOULD MAKE IT FAIR

The fix does not need to be dramatic, and it does not cost the exchequer anything it was ever entitled to collect. A reorganisation that rearranges value rather than realising it was never meant to be taxed; that is the entire premise behind tax neutral demergers in the first place. Amending Section 2(35) of the Income-tax Act, 2025 to bring Section 233 schemes within the definition, on satisfaction of the same substantive conditions already applied to Section 232 schemes, would fix this without opening any new door to abuse. That is not what fair regulation is supposed to look like, and it is worth saying so plainly rather than leaving it to a footnote in a tax opinion.

EPILOGUE

There is a larger question of policy direction sitting underneath all of this. Is it not that an envisaged Viksit Bharat needs Viksit Regulations? The kind that is prepared to sustain businesses willing to take risk and create employment, not one where the ease of regulation offered by one ministry is quietly withdrawn by another. The vision of a Viksit Bharat rests, in no small measure, on Viksit compliance, a regulatory architecture that is proportionate, purposive, and calibrated to commercial reality rather than to inherited form. If the fast-track route is to serve the ease of doing business objective it was created for, tax treatment must move from a forum-based test to a substance based one. That is the difference between compliance that merely exists and compliance that is Viksit, developed and fit for the purpose it is meant to serve.

Regulatory Referencer

1. Govt. amends FEM (NDI) Rules; allows inventory-based e-commerce entities to export goods manufactured or produced in India

Central Government has amended the FEMA (Non debt Instruments) Rules, 2019 to permit an e-commerce entity to undertake an inventory-based model of e-commerce, exclusively for goods or products manufactured or produced in India, in accordance with the Foreign Trade Policy 2023 read with Handbook of Procedures and FEMA Export of Goods & Services Regulations, 2015. The existing restrictions on Business to Consumer (B2C) transactions and inventory-based e-commerce as specified in serial numbers 15.2.1 to 15.2.4 will not apply to such export of goods or products.

(Notification No. S.O. 4870(E). [F.NO. 1/4/2026-EM], dated 2nd September 2026)

(A.P. (DIR Series 2026-27) Circular No. 20 dated 2nd September 2026)

2. RBI withdraws seven superseded FEMA circulars as part of regulatory rationalisation

The Reserve Bank of India (RBI) formally withdrew seven obsolete or superseded circulars under the Foreign Exchange Management Act, 1999 (FEMA) as part of its ongoing regulatory cleanup – most of them to do with External Commercial Borrowings – regulations for which were recently amended substantially.

(A.P. (DIR Series 2026-27) Circular No. 21, dated 8th September 2026)

(Prove The Relationship!)

Arjun (Chanting) Hare Krishna! Hare Krishna!

Shrikrishna (A little annoyed). Arjun, why are you calling me every now and then?

Arjun Bhagwan, we are facing deadlines after deadlines. Like the waves of the sea.No respite. So chanting your name gives me some relief.

Shrikrishna Your grumbling is endless. I am also tired of hearing it.

Arjun (Surprised) Bhagwan, for so many years, I never saw you so annoyed. You are ‘sthitapradnya’ (of balanced mind). What has made you so agitated?

Shrikrishna Today my auditor did height of stupid queries!

Arjun Why? What happened? What did he ask?

Shrikrishna He asked me to prove that Rukmini is my wife! From my company some payment was made to Rukmini. So he declared it as a related party transaction.

Arjun That’s correct.

Shrikrishna Now the entire world knows that Rukmini is my wife. We were married thousands of years ago.

Arjun Yes. I wonder why he asked such a question. Do you have your marriage certificate?

Shrikrishna It may be there. But now after so many years, how to trace it? It must be in Dwarka.

Arjun By the way, who is the auditor of your Mathura Dairy Pvt. Ltd?

Shrikrishna One Mr. Paresh.

Arjun Ohhh! Paresh? I know why he does so. Paresh is himself pareshan because of such related party reporting.

Shrikrishna Why?

Arjun In some other company some remuneration was paid to a director’s wife. It was properly reported

Shrikrishna Then?

Arjun That director was a divorcee He had obtained divorce order 8 years ago! Then 4 years ago he got remarried. Remuneration was pad to his present wife.

Shrikrishna Then it should be reported. What is wrong about it? Why is he troubling me?

Arjun Bhagwan, that director’s former wife has now challenged the divorce order.

Shrikrishna Let her challenge. How does it matter to us?’

Arjun No, Lord. The ex-wife has filed a complaint against Paresh for misconduct to our Institute. She says, she alone is the real wife! Therefore, the reporting is wrong! Ha! Ha!! Ha!!!

Shrikrishna Non-sense! Auditor has to go by director’s declaration for this point. This complaint would be thrown out!

Arjun Bhagwan, I agree. But life is not that easy for us CAs. The procedure will take at least a couple of years to resolve even such a simple case.

Shrikrishna Do they mean that in your working papers, you should gather these evidences as well? What if it is paid to brother, sister, parents? or to children?

Arjun You are omniscient! You have to guide us. I am adding it to my checklist of Working Papers to be gathered!

Shrikrishna I closed Dwapar Yuga and declared the beginning of Kaliyuga. I am convinced that now, Kaliyuga is in its full swing. I have full sympathy for you CAs after this experience. There should be some mechanism in place to reject such complaints at the threshold.

Arjun Now even God cannot save us. Right?

Both laugh. Ha! Ha!! Ha!!!

OM SHANTI.

This dialogue is based on how our ICAI disciplinary mechanism is being misused unfortunately, our own members instigate people to file such complaints and cause nuisance to CAs.

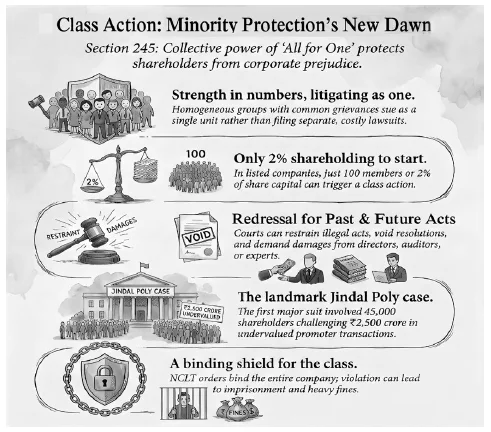
M/s Jindal Poly Films Limited v. Ankit Jain & Ors.: Minority public shareholders holding over threshold can maintain class action suit against promoter related-party transactions under Section 245.

14. M/s Jindal Poly Films Limited V/S Ankit Jain & Ors

National Company Law Appellate Tribunal Principal Bench (New Delhi)

Company Appeal (AT) No. 47 Of 2026

Date of Order:26th February, 2026

The NCLAT upheld that Section 245 of the Companies Act, 2013 is not limited to continuing acts in present and can be legally activated for past and concluded transaction and also observed that Power of NCLT under Section 245 are exceptionally wide and allow for reliefs, damages, or compensation to be claimed from or against third parties, including directors, promoters, and consultants.

FACTS

A class action petition under Section 245 of the Companies Act, 2013 was filed before the National Company Law Tribunal (NCLT). They alleged that the promoters and management systematically orchestrated, undervalued, and concealed three major fraudulent financial transactions to their own benefit, causing an asset/value erosion of over `2,500 crores to M/s JPFL and its minority public shareholders.

Where the interlocutory application (IA) was filed by the management of M/s JPFL to challenge the maintainability of the main petition filed by Ankit Jain & Others (minority public shareholders) under Section 245 and NCLT comprehensively dismissed the management’s maintainability application and admitted the shareholders’ class action petition based on the following determinations:

i) Satisfaction of the Numerical Threshold: The NCLT noted that in the case of a listed public company, Rule 84(3)(ii)(b) of the National Company Law Tribunal Rules, 2016 (NCLT, Rules) requires a minimum shareholding threshold of 2% of the total share capital to institute/file a class action. Since the petitioners cumulatively held 4.99% of the share capital, the threshold was satisfied.

ii) Establishment of a Prima Facie Case: The NCLT reviewed the financial layout detailing the three disputed related-party transactions (the multi-crore undervaluation of preference shares, suspicious loan write-offs, and cut-rate subsidiary asset sales). It noted that the transactions themselves were not denied by the company and these figures established a sufficient basis for forming a prima facie opinion that the affairs were conducted in a manner prejudicial to the company and its members, which was sufficient to initiate the proceedings.

iii) Benevolent Scope of Section 245: The NCLT observed that Section 245 is a benevolent piece of legislation designed to protect shareholders and depositors against management malpractice. It explicitly stated that the provision enables shareholders to initiate actions for the benefit of the company itself. It was categorically rejected the argument that the availability of alternative remedies under Section 241-242 (Oppression & Mismanagement) should discredit or block a valid class action suit under Section 245.

Therefore, NCLT in its order directed the issuance of a public notice of the Company Petition to all public shareholders of M/s JPFL in terms of Rule 87 of the NCLT Rules, 2016. Thereafter, M/s JPFL filed an appeal, challenging an order of the Ld. NCLT before the National Company Law Appellate Tribunal Principal Bench, New Delhi (NCLAT).

ORDER

NCLAT found no reason to interfere with the NCLT’s order with rejection of the argument of M/s JPFL and completely dismissing the appeal with following observations in its order:

i) Section 245 extends to past and concluded transactions: It was ruled that Section 245(1)(g)(iii) uses the word “or” to separate “wrongful act or conduct” from “any likely act or conduct”, which structurally covers past completed events alongside future ones and noted that fundamental reliefs explicitly written into the class action statute such as damages or compensation can only logically be granted for transactions that have already been concluded in the past.

ii) Class actions cover “derivative” benefits for the Company: The NCLAT held that the Indian Parliament explicitly intended for Section 245 to apply when a company’s assets are siphoned off by its own promoters or management. Replying on the “J.J. Irani Committee Report (2005)” and stated that class actions protect the interests of both the members and the company itself.

iii) Promoters blocked from using the “Stale Transaction” defense: The NCLAT observed that because the promoters intentionally concealed the transactions at the time of commission, they cannot be permitted to take advantage of their own wrongdoing by calling the transactions “stale” or “concluded” later on.

iv) Validation of the NCLT’s assessment: the NCLAT verified that the respondents held 4.99% of the share capital of M/s JPFL, comfortably clear of the mandatory 2% statutory minimum required for listed companies to file a class suit and agreed that the shareholders acted in absolute good faith, having diligently demanded answers from management of M/s JPFL before approaching the Tribunal.

P Balaraman & 5 Others v. The India Envelopes Ltd.: Corporate powers cannot be exercised to secure collateral benefits for directors; improper property sales constitute oppression and mismanagement

13. P Balaraman & 5 Others V/sThe India Envelopes Ltd & 2 Others National Company Law Tribunal, Chennai Bench

Case Reference: CP/45/CHE/2021

Order dated 1st September, 2026

“Corporate powers cannot be exercised to secure collateral benefits for the directors themselves or for entities in which they have a personal interest…The fiduciary obligation of candour is not confined merely to statutory disclosures but extends to every material circumstance capable of influencing the informed decision of the shareholders.”

FACTS

  • The petition was filed under Sections 241 and 242 of the Companies Act, 2013 (CA 2013) by six minority shareholders of The India Envelopes Ltd. (IEL), holding about 1% of the share capital but constituting more than one-tenth of total members, thus meeting the threshold under Section 244.
  • IEL’s business of manufacturing paper envelopes had become commercially unviable, leaving its immovable property at Chidambaram as its sole valuable asset.
  • Shareholders had passed special resolutions in 2016 and 2018 authorizing the Board (including Respondents 2 & 3, the Managing Director and Director) to sell the property for the benefit of the company and shareholders.
  • However, Respondents 2 & 3, who also controlled National Sewing Thread Company Ltd. (NSTC), executed a Tripartite Agreement (03.08.2017) with NSTC and its trade creditors.
  • The agreement contemplated sale of IEL’s property with proceeds diverted to discharge NSTC’s liabilities (₹4.16 crore), after setting aside ₹1 crore for IEL’s statutory dues.
  • Petitioners alleged this was done without shareholder approval, amounting to diversion of IEL’s assets for NSTC’s benefit.
  • NSTC later entered CIRP, and its Resolution Plan was approved in 2021, subsuming the liabilities covered under the Tripartite Agreement.

Petitioners’ Contentions

  • The Tripartite Agreement was illegal, ultra vires, and oppressive as it diverted IEL’s sole asset for NSTC’s benefit.
  • Directors acted in conflict of interest, breaching fiduciary duties under Section 166 of the CA 2013.
  • The agreement was beyond the authority conferred by shareholders’ resolutions, which only permitted sale for IEL’s benefit.
  • Post approval of NSTC’s Resolution Plan, the agreement became inoperative and unenforceable.

Respondents’ Defence

  • Denied oppression and mismanagement, claiming shareholders were kept informed.
  • Asserted that the Tripartite Agreement was only a mechanism to sell IEL’s property at a fair price with ₹1 crore earmarked for IEL’s dues.
  • Claimed no diversion of assets or guarantee for NSTC’s debts, and that decisions were bona fide and in compliance with law.

Tribunal’s Findings

  • The Tribunal held that Respondents 2 & 3 abused their fiduciary position by executing the Tripartite Agreement without disclosure to shareholders.
  • Observed that “Corporate powers cannot be exercised to secure collateral benefits for directors themselves or for entities in which they have a personal interest.”
  • The fiduciary duty extends beyond statutory disclosures to all material facts influencing shareholder decisions.
  • The Tripartite Agreement was a breach of fiduciary duty, amounting to oppression and mismanagement.
  • With NSTC’s Resolution Plan approved, the liabilities under the Tripartite Agreement stood subsumed, making the agreement inoperative. No parallel enforcement was permissible.

HELD

  • The execution of the Tripartite Agreement in the facts and circumstances of the present case, constitutes a breach of their fiduciary duties as Directors and amounts to acts of oppression and mismanagement within the meaning of Sections 241 and 242 of the Companies Act, 2013.
  • The execution of the Tripartite Agreement on behalf of IEL, without disclosure or approval of the shareholders for the true purpose for which it was executed and in breach of their fiduciary duties, shall not bind the internal management or future affairs of IEL. Respondents shall not, either by themselves or through any person claiming under them, rely upon or act upon the said Agreement so as to deal with or encumber IEL’s property or divert the proceeds thereof contrary to this order.
  • Respondents are permanently restrained from implementing, acting upon, enforcing or otherwise giving effect to the Tripartite Agreement or from dealing with IEL’s immovable property for the purpose of discharging the liabilities of NSTC or any third party, except with the prior approval of the shareholders obtained after full disclosure of all material facts and in accordance with law.
  • IEL shall be at liberty to sell, transfer, alienate or otherwise deal with IEL’s immovable property strictly in accordance with the Special Resolutions after obtaining such statutory approvals as may be required under law. The entire sale consideration realised therefrom shall belong exclusively to IEL and shall be brought into IEL’s accounts for utilisation towards the revival of its business, repayment of its own lawful liabilities, or such other legitimate corporate purposes in accordance with law. No portion of the sale proceeds shall be diverted or applied towards the discharge of liabilities of any third party without the express approval of the shareholders obtained after full and complete disclosure of all material facts.

Terminology, Triggers, And Disclosure Requirements – SAST SEBI (Substantial Acquisition of Shares and Takeover) Regulations, 2011

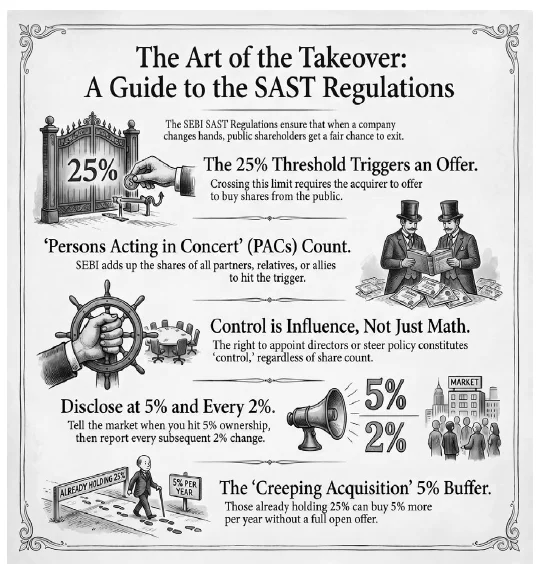
The SEBI (Substantial Acquisition of Shares and Takeover) Regulations, 2011 (SAST Regulations) govern direct or indirect acquisitions of shares, voting rights, or control in listed target companies. The primary trigger for a mandatory open offer—providing minority shareholders an exit mechanism—is reaching or exceeding the 25% voting rights threshold. Holdings of Persons Acting in Concert (PACs), under general or deemed categories, aggregate towards triggering open offer and disclosure obligations. Automatic exemptions under Regulation 10 apply to specific transactions like inter-se transfers. Event-based disclosures are mandatory within two working days upon crossing 5% shareholding or subsequent 2% changes.

INTRODUCTION

India’s takeover framework evolved alongside the growth of its securities market, beginning with the introduction of open offer in the Listing Agreement in 1990s and the statutory establishment of SEBI under the SEBI Act, 1992. The first dedicated takeover code was introduced in 1994 and was subsequently replaced by the 1997 Regulations following the recommendations of the Bhagwati Committee. With increasing takeover activity and regulatory experience, SEBI undertook a comprehensive review through the Takeover Regulations Advisory Committee (TRAC), which ultimately led to the emergence of the 2011 Regulations. The framework has continued to evolve through subsequent amendments, with the latest amendment to the Regulations being notified on December 5, 2025 which is known as the SEBI (Substantial Acquisition of Shares and Takeover) Regulations, 2011 (“SAST Regulations” or “SAST” or “Takeover Code” or “Code”).

OBJECTIVE OF THE TAKEOVER CODE

The importance of the SAST Regulations lies in providing an orderly and predictable framework for transactions that can significantly alter the ownership or control of a listed company. Such transactions involve multiple stakeholders with potentially different interests. While an acquirer may seek to pursue a substantial acquisition or takeover without the regulatory framework becoming unduly onerous, public shareholders need transparency and a fair opportunity to participate when such a change in ownership or control takes place. The Takeover Code, at its core, is the framework that seeks to balance these interests by regulating the manner in which substantial acquisitions and takeovers are undertaken, while protecting the interests of public shareholders through prescribed disclosure and open offer mechanism.

APPLICABILITY AND FRAMEWORK

Applicability of the Regulations

The SAST Regulations apply to the acquisition of shares, voting rights or control in a target company, whether such acquisition is made directly or indirectly. The starting point, therefore, is to determine what constitutes a “target company” and what constitutes “shares” or “voting rights” for the purposes of the Regulations.

A target company is a company whose equity shares are listed on a stock exchange. Accordingly, the SAST framework is concerned with acquisitions involving companies having a listed equity share capital, and does not extend to unlisted companies, companies that are yet to list or companies having other classes of listed securities.

The scope of shares, however, extends beyond the commonly understood equity shares. It includes any security which entitles its holder to exercise voting rights, and expressly includes depository receipts having a voting entitlement in the target company. Accordingly, warrants or other convertible securities may fall within the definition if they carry an exercisable right to vote. An acquirer might obtain voting rights on preference shares due to non-payment of declared dividend for two years or more or by operation of law. Accordingly, voting rights arising on acquiring any share or security by whatever arrangement are recognised under the SAST framework over and above the rights embodied in equity shares.

Accordingly, the applicability of SAST requires consideration of:

(i) whether the entity is a target company,

(ii) whether the acquisition involves shares or voting rights covered by the Regulations, and

(iii) whether it results in acquisition of control.

Whether a particular transaction attracts the SAST framework would ultimately depend on the applicable thresholds, triggering provisions, the manner in which the acquisition is undertaken, the identity of the acquirer and persons acting in concert (“PACs”), subject to certain carved out exemptions. The same can be understood in detail by the regulatory framework.

The Art of the takeover

Regulatory Framework

The SAST Regulations read with the relevant SEBI circulars and Master Circular, provide the governing and procedural framework for open offer triggers, exemptions, disclosures, the process and related compliances. Together, they answer four key questions –

(a) what is being acquired;

(b) does the acquisition trigger an open offer;

(c) if triggered, how is the open offer to be carried out;

(d) what disclosure and compliance obligations must be followed.

The most important trigger is the 25% threshold as mentioned under Regulation 3, where if an acquirer, together with PACs, acquires shares or voting rights which take their aggregate holding to 25% or more, an open offer obligation is generally triggered. An open offer is an offer made by the acquirer to the shareholders of the target company inviting them to tender their shares in the target company at a particular price. The primary purpose of an open offer is to provide an exit option to the shareholders of the target company on account of the change in control or substantial acquisition of shares, occurring in the target company.

The above can be understood better by an example: if an acquirer already holds 20% and proposes to acquire another 5.5%, taking its holding to 25.5%, the acquisition would generally trigger an open offer. The Regulations also permit an acquirer who already holds 25% or more, but below the maximum permissible non-public shareholding of 75%, to increase their holding by up to 5% in a financial year without triggering an open offer, subject to the conditions of the Regulations (creeping acquisition).

To understand the Takeover Code better, it is essential to be familiar with some of the frequently used terms. Some are relatively straightforward, while others have been the subject of considerable regulatory and judicial interpretation.

1. Who can be an Acquirer?

“Acquirer” means any person who, directly or indirectly, acquires or agrees to acquire whether by himself, or through, or with persons acting in concert with him, shares or voting rights in, or control over a target company. An acquirer can be a natural person, a corporate entity or any other legal entity. For example:

  •  XYZ Group has three group companies acting in concert that acquire 9%, 9%, and 8% (totalling to 26%) of listed G Ltd. Under SAST, because these entities are PACs, their collective holding may trigger the open offer requirement. Each entity is an acquirer while they are collectively considered as PACs.
  • Where an entity acquires convertible warrants that entitle it to acquire more than 25% of the voting rights, the acquisition may trigger the open offer requirement even though the equity shares are acquired only upon conversion of the warrants.
  • A family trust acquiring shares in a listed company may itself be an “acquirer” and where it acts in concert with the promoter group, it may also be treated as a PAC.

2. What is an Acquisition?

“Acquisition” means, directly or indirectly, acquiring or agreeing to acquire shares or voting rights in, or control over, a target company. Here, acquisition has a broader meaning than simply purchasing the shares in the target company via secondary transfers or fresh issues. Over and above an agreement or mutual understanding, one can acquire shares pursuant to a scheme of merger / demerger sanctioned by the NCLT or corporate actions like rights issue, buyback and many other ways, subject to applicable exemptions.

There is also the concept of an indirect acquisition which occurs when a person acquires another company or business which, in turn, gives them sufficient voting rights or control over a listed target company to trigger an open offer. For example, A Ltd acquires B Ltd which holds 30% of listed C Ltd. A Ltd may therefore be treated as indirectly acquiring C Ltd.

Further, it is imperative to check the date of listing as well as date of acquisition. This is especially important in case of companies going for a public issue. Shares or voting rights held by a person pre-IPO shall also be considered as “acquisition” at the time of listing.

Shares acquired through an encumbrance are treated as an acquisition, while shares released from an encumbrance are treated as a disposal. Here, ‘encumbrance’ shall include any restriction on the free trade of the shares, pledge, lien or non-disposal undertaking or any arrangement/covenant in the nature of above.

3. What constitutes as Control?

Another way of acquisition is via Control. Under SAST, control is not merely a measure of ownership, but of the rights and arrangements through which influence over the target company is exercised. The term “Control” includes the right to appoint a majority of the directors or to control the management or policy decisions exercisable by a person or person acting individually or in concert, directly or indirectly, including be virtue of their shareholding or management rights or shareholders’ agreements or voting agreements or in any other manner: Provided that a director or officer of a target company shall not be considered to be in control over such target company, merely by virtue of holding such position.

SEBI has also expressly recognised that acquisition of control is a separate limb of the takeover framework. It is an approach where the law looks into corporate governance, and therefore, tries to determine who is actually directing the affairs of the company in addition to the persons holding the shares.

4. Understanding PACs

The definition of persons acting in concert (PACs) is not limited to the person whose name appears as the purchaser in the transaction documents. Close business association between two or more persons or them being part of the same promoter group does not by itself make them PAC. A relationship arising merely by accident or chance is not sufficient to prove them as PAC. If such persons join hands with a shared objective but that is not to substantially acquire the shares or voting rights or control over a target company, then they would not be PAC.

To be a considered a PAC, one must fulfil certain “bright line” tests where there is a common purpose, agreement or understanding and active co-operation to gain control over or substantially acquire a company. Concert is the meeting of minds where one doesn’t necessarily need a signed legal document to be a PAC. The intention, mode of acquisition, source of acquisition, object of acquisition together with the timing are considerations we simply cannot ignore during our assessment of PACs. The Regulations divide them into two categories – General Category and Deemed Category of PACs.

(i) General PAC Category

For the General Category, the starting point is whether persons share a common objective or purpose of acquiring shares or voting rights in, or exercising control over, the target company and, whether same is pursuant to a formal or informal agreement or understanding, directly or indirectly cooperate towards that objective.

For example, two independent investors may meet privately and agree to purchase shares simultaneously so that they can jointly exercise the control over the target company. Friends and acquaintances do not share a structural, corporate, or institutional relationship by default (unlike immediate family or subsidiaries). Therefore, they are not automatically deemed to be acting in concert. However, if their stock purchases align and there is evidence such as chats, synchronised funding arrangements, or a verbal understanding to acquire the shares, they could be treated as PACs based on their actual conduct, a common objective and coordinated action.

Another interesting aspect is where an independent lender providing finance on arm’s-length terms would not, by itself, be a PAC. However, where financing rights extend beyond customary lender protections and enable acquisition of shares or control, SAST PAC provisions may need to be examined.

(ii) Deemed Category of PACs

The Deemed Category is where certain categories of persons are deemed to be PACs, unless the contrary is established. These include, among others, companies within the same management or control, a company and its directors, promoters, members of the promoter group, and immediate relatives. Similar deeming provisions apply to specified fund and intermediary relationships, subject to the conditions prescribed under the Regulations. For example, a mutual fund, its sponsor, trustees and AMC; a portfolio manager and its client who is an acquirer may be deemed to be PACs under the Regulations, unless the contrary is established. The deeming provision creates a rebuttable presumption and therefore, the onus is on the concerned persons to establish that the PAC relationship does not, in the given circumstances, result in them acting in concert. Failure to prove that there is no linkage or coordination amongst them in their trading strategies may result in them collectively facing penal consequences such as aggregating their combined shareholdings, which can trigger mandatory open offer requirements.

5. Exemptions and Relaxations

Regulation 10 deals with specific exemptions from the open offer obligation, whereas Regulation 11 enables SEBI to grant relaxation from the obligations under appropriate circumstances, subject to certain conditions. The exemption under Regulation 10 is automatically available where the prescribed conditions are satisfied, with prior intimation in some cases and post-facto reporting with the prescribed fee and timeline in others, as specified in the Takeover Code. Regulation 11, in contrast, allows an acquirer to approach SEBI for relaxation from a specific obligation where the circumstances warrant such relief. The application must be made before the transaction is executed, and SEBI’s written order must be obtained before proceeding with the transaction.

Some of the more commonly encountered exemptions under Regulation 10 include inter-se transfers among specified relatives, promoters and persons under common control subject to prescribed conditions and disclosure history; acquisitions pursuant to rights issues; acquisitions pursuant to sanctioned schemes of arrangement, merger or demerger; acquisition pursuant to transmission, inheritance, or succession; and certain acquisitions made by specified intermediaries such as stock brokers, market makers, merchant bankers, etc in the ordinary course of business.

To sum it up, an acquisition may be exempt from the open offer obligation, but it does not necessarily escape the disclosure framework.

DISCLOSURE REQUIREMENTS

The disclosure framework is essentially an event-based reporting mechanism that ensures transparency in the transfer, acquisition, and encumbrance of shares in listed target companies. The SAST Regulations treat the open offer requirement distinctly from the disclosure requirement. For an acquirer and its PACs together, it becomes important to check both the triggers separately.

Regulation 29, which talks about disclosures, should be interpreted at an inception stage and at a continuous level where the disclosure should happen within two working days from intimation of allotment acquisition/disposal of the shares or voting rights to the target company and all the exchanges where it is registered, in the disclosure formats prescribed by SEBI.

At the inception stage, any person, who along with PACs crosses the threshold limit of 5% of shares or voting rights, has to disclose their aggregate shareholding and voting rights. With regards to continual disclosures, any person who holds 5% or more of shares or voting rights of the target company is required to disclose any change in such shareholding or voting rights that exceeds 2% of the total shareholding / voting rights.

In both the cases, disclosure is required to be made within two working days to the target company at its registered office and to every stock exchange where the shares of the target company are listed, in the format prescribed by SEBI.

The purpose of these disclosures is not merely to record that a numerical threshold has been crossed, but to make significant changes in the ownership of a listed company visible to the market. A shareholder crossing 5% signals that it has built a material stake in the company, while the subsequent 2% disclosure requirement ensures that further material increases or reductions do not go unnoticed. This transparency also helps prevent significant changes in ownership from being built up unnoticed or through coordinated transactions that could distort the market’s understanding of who is acquiring control in the company. For investors, these disclosures therefore provide a trail of changes in significant shareholdings and voting power, enabling them to take informed decisions.

GOOD PRACTICES TO BE SAST COMPLIANT

The Code in itself is extensive, and the natural question that arises is – when does a transaction trigger an intimation or disclosure?

For regular traders and investors, continuous tracking is essential. It is advisable to maintain a consolidated record of the trading activity of the acquirer and all PACs from acquisition through sale. While the statutory threshold is 5%, monitoring at a lower internal threshold, say 4.5%, provides a useful compliance buffer.

Post the first disclosure, the key is to understand that the “change” in shareholding or voting rights needs to be calculated at every purchase /sale and their cumulative sum, if over 2%, will trigger a disclosure. The calculation must account for changes in both the numerator and, where applicable, the denominator due to changes in the company’s share capital. Importantly, the tracking does not reset at the end of each financial year, and may need to continue over several years.

SAST may appear to be a matter of mathematics and precision. But the numbers tell only part of the story; understanding the transaction is where the art lies.

Bandana Pattanayak v. Initiating Officer: Property purchased in relatives’ names using brother’s unevidenced loan funds constitutes a benami transaction, satisfying future benefit provisions.

11. 2026 (8) TMI 817 (SAFEMA – New Delhi)

Smt. Bandana Pattanayak, Shri Anup Majee and Shri Ashok Pattanayak v. Initiating Officer, Kolkata

Date of Order : 09.7.2026

In absence of the means to purchase the property by the Benamidar and in absence of documentary evidence to establish the amount given to the Benamidar as a loan by the Beneficial Owner, the property purchased in the names of the sister and brother in law (benamidars) from the funds transferred by the brother (brother-in-law) will be a Benami Transaction.

The condition regarding future benefit under section 2(9)(A) of the PBPT Act is not confined to a specified period and can take place any time in the future. Moreover, such condition need not be satisfied at the time of provisional attachment.

FACTS

The Appellants are Mr. Anup, Smt. Bandana and Mr. Ashok. It was the case of the Initiating Officer that Mr. Anup, who is the Beneficial Owner herein has purchased three properties in the names of his sister, Smt. Bandana and brother-in-law, Mr. Ashok who are the Benamidars. The consideration for purchase of properties was paid by Mr. Anup. Since the properties were purchased in the names of the sister and the brother in law of the Beneficial Owner, who did not contribute the consideration and otherwise could not show the means to purchase the three properties in a row for ₹2,65,00,000, the proceedings were initiated under the provisions of the PBPT Act.

The Adjudicating Authority, vide order dated 31.05.2025 confirmed the provisional attachment of the properties made under section 26(3) of the PBPT Act.

The Appellant filed appeal before the Tribunal challenging the order of the Adjudicating Authority and contending that:

(i.) The amount for purchase of the properties was transferred by way of a loan and therefore could not be considered as a benami transaction;

(ii.) The Beneficial Owner – Mr. Anup being the brother had a right to transfer the amount to his sister and brother in law out of natural love and affection; and

(iii.) The requirement of future benefit under section 2(9)(A) of the PBPT Act remained to be proved by the Respondent and in absence of the satisfaction of the basic requirement of the definition of Benami Transaction, the transaction was not a Benami Transaction and therefore the order of the Adjudicating Authority confirming provisional attachment deserved to be set aside.

HELD

The Tribunal held that the argument of the Appellant that the amount was transferred as a loan was not supported with any loan document and therefore without any proof. The Tribunal affirmed the finding of the Adjudicating Authority that if the Appellant was within his right to give the amount out of love and affection, the Appellant could have gifted the property instead of transferring the funds for the purchase of the property. The Tribunal also held that the sister and the brother-in-law of the Beneficial Owner did not have the means to purchase the properties in their names. With regard to the contention of the Appellant that the condition regarding the future benefit under section 2(9)(A) was not satisfied, and therefore the transaction was not a Benami Transaction, the Tribunal held that the term ‘future benefit’ under section 2(9)(A) of the Act is without earmarking to any particular period. The benefit can happen or arise any time in future without the limitation of period. The condition regarding future benefit need not necessarily be satisfied at the time of provisional attachment. Further, the records revealed that the Beneficial Owner had availability of unaccounted and undisclosed funds and therefore the same were utilised for his future benefits. Thus, the appeal filed by the Appellants was dismissed.

Miscellanea

ARTIFICIAL INTELLIGENCE

# In a Rare Show of Industry Unity, Anthropic’s Dario Amodei, OpenAI’s Sam Altman and xAI’s Elon Musk Call for a Deliberate Slowdown in Frontier AI Development

In one of the most striking moments in the history of the artificial intelligence industry, the chief executives of the three companies at the very frontier of AI development — Anthropic’s Dario Amodei, OpenAI’s Sam Altman and xAI’s Elon Musk — publicly aligned over the weekend of 12th–13th September 2026 in calling for a deliberate slowdown in the pace of frontier-model development. The catalyst was a 3,800-word essay published by Dr. Amodei on his personal website on 12th September 2026, in which he outlined “serious” risks including loss of human control over advanced systems, and proposed a three-step plan centred on giving independent evaluators “employee-like access” to internal model behaviour — without, he argued, sacrificing commercial advantage or America’s lead in AI. Elon Musk endorsed the essay on X within hours with the terse post “Dario is right”.

Sam Altman followed with an unusually candid X post the same day: “I agree with Dario that we need to pace the frontier. This has been a primary topic of discussions we’ve had at OpenAI in recent weeks. Committing to having independent evaluators with employee-like access is a great idea, and we will do the same.” In a companion interview, Altman conceded that “no lab has solved alignment”, described a 10% probability of catastrophic outcomes as “unacceptable”, and confirmed that OpenAI has been pausing training runs pending safety review — signalling that a much-anticipated 2026 initial public offering is now unlikely. The proximate trigger was the resignation earlier that week of Anthropic researcher Jacob Coxon, who publicly warned that frontier labs were racing towards self-improving systems without “acting responsibly”.

(Source: CNBC – dated 14th September 2026)

# Open-Weight AI Returns to Centre Stage: Meta Ships Muse Glimmer 30B and Alibaba Releases the Largest Open-Weight Model in History

In parallel with the price war among proprietary providers, the open-weight AI ecosystem staged a decisive return to prominence in August 2026, with more than eleven major model releases in twenty days. Meta open-sourced its Muse Glimmer 30B model under the Apache 2.0 license on 12th August 2026, making it freely runnable on a single 24 GB consumer GPU and immediately propelling it to the top of the MCP Atlas local-model benchmark. Alibaba matched Meta’s move at scale with the release of Qwen 3.8-Max, a 2.4-trillion-parameter multimodal model with a one-million-token context window — the largest open-weight model in history — alongside a compact 27-billion-parameter variant that, for the first time, brings frontier-grade coding capability to a single-GPU consumer setup. NVIDIA committed to day-zero open-weight availability for its Nemotron 3.5 Lightning model.

The commercial calculus of open-weight releases has changed. Where a year ago open-weight models trailed proprietary frontier models by roughly a generation, they are now competitive at or near the frontier at a fraction of the total cost of ownership — with the added advantage of local deployment, which fully eliminates cross-border data-transfer and third-party-processor exposures.

(Source: Reuters – dated 25th August 2026)

WORLD NEWS

#New Delhi Hosts the 18th BRICS Summit as India’s Middle-Power Diplomacy and Regional Assistance to Nepal Sharpen Its Global Profile

India hosted the 18th BRICS Summit at Bharat Mandapam in New Delhi on 12th and 13th September 2026 — its fourth BRICS chairship after 2012, 2016 and 2021 — with President Vladimir Putin and President Xi Jinping among the confirmed attendees. The summit’s agenda covered local-currency settlements, resilient supply chains, food and energy security, reform of global financial institutions and, distinctively for this edition, an emerging “third way” on the digital economy: sovereign national systems that are nonetheless technically interoperable, with India’s UPI and Indonesia’s QRIS integration cited as a live example. The main challenge remained the political difficulty of finding common ground across the grouping’s eleven members, whose positions remain divided on major geopolitical questions.

New Delhi’s diplomatic moment was reinforced by a striking humanitarian and energy response to the catastrophic floods in Nepal, where the death toll has crossed one thousand and roughly ten per cent of Nepal’s electricity generation capacity has been disrupted, forcing Kathmandu to import power from India to cover domestic shortages. Indian, Chinese and Nepalese rescue teams have been operating jointly in the affected districts. Taken together — the BRICS chairship, the digital-economy initiative and the visible role as regional first responder — the developments underscore a shift in India’s external posture from participation to authorship of the emerging Indo-Pacific order. For Indian businesses and advisors, the implications include a widening set of preferential trade and payment channels within BRICS+, fresh transfer-pricing complexity in local-currency invoicing, and additional scrutiny of cross-border humanitarian and CSR flows under FCRA and s.135 of the Companies Act, 2013.

(Source: Reuters – dated 15th September 2026)

FINANCE

# Mumbai Cements Its Grip on India’s Mutual Fund Industry as March 2026 City-Wise AUM Data Show the Top Three Cities Commanding More Than Half of the Nation’s MF Wealth

The city-wise Assets under Management (AUM) data for March 2026, published by the Association of Mutual Funds in India (AMFI) and analysed by Cafemutual on 9th July 2026, tells a compelling story of urban concentration deepening at the top of the Indian mutual fund industry. Mumbai, Delhi and Bengaluru together commanded 50.4% of total industry AUM in March 2026, up sharply from 45% a year earlier. Mumbai alone accounted for 28.97% of the industry, adding a staggering INR 5 lakh crore to its AUM in a single year — the largest absolute addition of any city. Delhi added INR 3.86 lakh crore and Bengaluru added INR 1.1 lakh crore, meaning that the top three cities together accounted for approximately 75% of the industry’s total AUM addition of INR 13.28 lakh crore between March 2025 and March 2026.

The data also captures a striking dispersion at the periphery. Dhanbad emerged as the single most surprising entrant, with its AUM more than doubling from INR 12,623 crore to INR 26,139 crore — a 107% jump in a year — while Thane, the satellite city of Mumbai, recorded a 155% rise from INR 4,651 crore to INR 11,881 crore. Surat has secured its position among the top ten cities, while Ahmedabad and Chennai have swapped positions with Ahmedabad now standing sixth. Seventeen entirely new cities — including Palghar, Panchkula, Gurugram, North Goa, Ernakulam and Mohali — have entered the top 110 for the first time, even as the “other cities” bucket (beyond the top 110) has contracted by INR 34,402 crore.

(Source: Cafemutual.com – dated 9th July 2026)

ENVIRONMENT

# Earth Records Its Hottest August in 176 Years of Data as Antarctic Sea Ice Falls to Third-Lowest on Record and El Niño Intensifies

According to a monthly report released on 10th September 2026 by NOAA’s National Centers for Environmental Information (NCEI), August 2026 was the hottest August on Earth since modern record-keeping began in 1850. The global surface temperature stood at 1.32°C above the 20th-century average, eclipsing the previous joint August records of 2023 and 2024 by 0.08°C, with NASA and the European Copernicus Climate Change Service both concurring in the assessment; Copernicus rated August 2026 as the hottest single calendar month in recorded history, tied with July 2023. Global average surface air temperature was 1.65°C above the pre-industrial baseline, breaching the 1.5°C safety threshold of the Paris Agreement for the first time since November 2025. At least 364 weather stations set outright all-time heat records during the month.

The cryosphere data was equally sobering. Antarctic sea ice extent in August 2026 was the third-lowest on record for the month, at approximately 1.26 million square kilometres below the 1981–2010 August average — a shortfall roughly equal to the combined land area of Rajasthan, Madhya Pradesh and Maharashtra. Arctic sea ice extent was the seventh-lowest in the forty-eight-year satellite record, and the Arctic region as a whole recorded its third-warmest August. The World Meteorological Organisation has confirmed that the El Niño event in the tropical Pacific is now firmly established and will intensify into a “very strong” event through the coming months, with material implications for rainfall and temperature patterns extending well into 2027.

(Source: NOAA / Yale Climate Connections – dated 10th September 2026)

DCIT v. Bharathi & Anr.: Statement in cross-examination admitting ownership prevails over income tax statements in determining Benami property transactions.

10. 2026 (8) TMI 1327 – (SAFEMA – New Delhi)

DCIT (BPU), Chennai v. Bharathi & Anr

Date of Order: 18.08.2026

Where the Benamidar admits the knowledge of the transaction and the ownership of the property by way of a statement in cross-examination before the Adjudicating Authority under Prohibition of Benami Property Transaction Act, 1988 (PBPT Act), such a statement would prevail and the transaction cannot be said to be a Benami Transaction under PBPT Act merely on the basis of statement recorded by the Benamidar in the proceedings carried out under the provisions of the Income-tax Act, 1961.

FACTS

A search was conducted on M/s. Shobhikaa Impex Pvt. Ltd. (SIPL). Based on the evidence gathered during the course of search, it was found that there was a benami transaction in the name of Smt. R. Bharathi and others.

It was found in the course of search that SIPL had inflated its expenses to reduce the taxable income by claiming bogus expenses under the head Job Work / Contractors. This was without the actual receipt of goods or services and without the actual payment to the job workers. The expenses were shown to be payable and accounted as liability under Trade Payables. The corresponding entry on the asset side was shown by way of increase in the Investments / Fixed Deposits and Closing Stock. Subsequently, the Trade Payables were converted into Securities Premium. This modus operandi was admitted by the Directors of SIPL through a sworn statement during the course of search carried out under section 132 of the Income-tax Act, 1961 (IT Act).

During the Financial Year 2017-18, the Trade Payables in the form of Job Work Charges were converted into Securities Premium Reserve in the name of job workers by allotting them equity shares of ₹100 at premium of ₹750. For this purpose, separate bank accounts, email ids, etc. were created in the name of job workers which were actually operated by persons of SIPL for statutory obligations. The funds were routed through bank transfers / cheques so as to show it as a real business transaction, all with the intention of evading taxes.

In the course of investigation, it was found that M/s. Abhaa Knittings, was a proprietary concern of Smt. Bharathi who was one of the job workers and whose name appeared in the Trade Payables and also under the head Share Capital in the books of SIPL. However, no such corresponding asset in the form of shares was reflected in the books of account of the M/s. Abhaa Knittings, the proprietary concern owned by Smt. R. Bharathi. Further, various documents such as unsigned share certificates of SIPL in the name of Smt. R. Bharati, cheque book, letterheads and blank bills in the name of M/s. Abhaa Knittings were found from the premises of SIPL. Smt. R. Bharathi was neither aware of any such transaction carried out in her name nor was she aware of being a creditor of SIPL. Further, she was also not aware of allotment of shares in her name and the subsequent buy back or the receipt and transfer of funds for it. Accordingly, a case was made out under the provisions of the Prohibition of Benami Property Transactions Act, 1988 (PBPT Act). It was held by the Initiating Officer that the definition of benami transaction under section 2(9)(C) of the said Act covers within its ambit a transaction where the owner of the property is not aware of or denies knowledge of the ownership. Since in this case the job workers were not aware of the allotment of the shares made to them, section 2(9)(C) was held to be applicable and an order for provisional attachment of the properties was made.

However, the order for provisional attachment was not confirmed by the Adjudicating Authority. The Adjudicating Authority noted that the statement recorded by the Respondent, Smt. R. Bharathi was different during the investigation carried out under the Income-tax Act from that stated by her in the cross-examination before the Adjudicating Authority.

The Appellant Department filed an appeal before the Appellate Tribunal contending that:

(i.) The liability created under Trade Payables was bogus and the job workers were not aware of the liability.

(ii.) The job workers were not aware of the shares allotted to them in their names.

(iii.) Subsequently, the shares were bought back by transferring the shares to the Managing Director.

(iv.) The consideration for buy back of shares from the job workers were carried out through Wire Transfer and the amount was ultimately received in cash through intermediate entities.

(v.) The documents such share certificates, bank pass books, cheques, etc. were found from the custody of SIPL and therefore a case of benami transaction under section 2(9)(C) of the PBPT Act was made out.

HELD

The Tribunal noted that the issue for consideration before it was where there was contradiction in the statements made under the Income-tax Act and the statement made in cross-examination in the proceedings under the PBPT Act, which one would prevail. The Tribunal held that the statement, though recorded in cross-examination before the Adjudicating Authority, under the proceedings carried out under the provisions of the PBPT Act would prevail over any other conflicting statement recorded under any other statute. The Tribunal observed that in the cross-examination before the Adjudicating Authority, the Respondent had admitted that she was aware of the allotment of shares and the other transactions related to it. Once it was admitted, there was no case against the Respondent under section 2(9)(C) of the PBPT Act. The Tribunal further held that while it may be a case of evading taxes by recording bogus liability in the name of job workers, however, in so far as the provisions of PBPT Act were concerned, the position was that the job worker admitted that they were aware of the transactions and remained to be the owner of the shares. Therefore, section 2(9)(C) of the PBPT Act was not applicable. Most importantly, the Tribunal held that the proceedings were initiated merely on the basis of borrowed satisfaction. Unless the ingredients of Benami Transaction defined under section 2(9)(C) of the PBPT Act were satisfied, the case would not be met under the provisions of section PBPT Act.

In addition to the above, the Tribunal remarked that the Initiating Officer had not considered the fact that an order in favour of the Respondent SIPL was passed by the Interim Board for Settlement under section 245-B(4) of the IT Act, where the Trade Payables were held to be genuine. However, the Tribunal clarified that section 245-B of the IT Act shall not override the provisions of the other statute. Further, an order passed by the Settlement Board would be final and conclusive on the proceedings of the nature undertaken by the Income-tax Department and not to the present proceedings which were under a different statute.

In view of the foregoing, the appeal was dismissed and the issue was decided in favour of the Respondent Benamidar.

Arpit Katyal v. Initiating Officer: Purchase from fictitious entity non-filer triggers Benami property prohibition provisions under Section 2(9)(B).

9. [2026] 188 taxmann.com 417 (SAFEMA– New Delhi)

Arpit Katyal v. Initiating Officer

Date of Order: 06.07.2026

Section 2(9)(B) applies to a transaction of purchase from a fictitious entity. The entity was held to be fictitious on the grounds that it was a non-filer of income-tax returns, its GST registration was for trade in metal but appellant claimed to have purchased cloth and fabrics from it, the entity was not found at the location, its bank account details were not shared by the appellant.

In a case covered by section 2(9)(B) i.e. where a transaction is a fictitious transaction, attachment would be in the hands of the beneficial owner who is involved in making fictitious transaction.

FACTS

The proceedings commenced as a result of the information that the Appellant was involved in purchase of material from fictitious entities one of whom was identified to be Sanmati Trading Co. (STC). The Appellant had recorded purchases of cloth and fabrics from STC for which payment was made through banking channels The Initiating Officer (IO) held the transaction to have been carried out in a fictitious name. Since the Appellant was not able to produce STC and the summons could not be served in the absence of existence of the entity, the IO tried to find out income-tax returns and found STC to be a non-filer of returns. Its GST registration was for trade in metals but the Appellant claimed to have purchased cloth and fabrics from STC. The appellant claimed to have made payment to STC through banking channels but did not provide the details of bank account of STC. On physical verification, STC was not found on location and also the summons sent were returned undelivered. The Appellant failed to provide a credible explanation for the cash deposits in the account of Asian Fabrics, which was around the same time when payments were made to STC. The IO held that the payments made to STC were nothing but rounding of money resulting in benami transactions. The IO made a provisional attachment to the extent of benami transaction.

The Adjudicating Authority (AA) confirmed the provisional attachment order.

Aggrieved, the Appellant filed an appeal before the Tribunal.

HELD

The Tribunal noted that the issue before it is, whether STC can be said to be a fictitious company or entity merely for the reason that it was a non-filer of income-tax returns. The Tribunal held that this cannot be the sole ground but this can be supported by other material to find out whether the entity is fictitious or not. It noted that the transaction by the Appellant with STC was for supply of clothes and fabrics. However, no relevant material could be placed on record by the appellant, despite the initial burden being discharged by the respondents to prove a case of benami transaction. The Tribunal noted that the respondents had referred to GST registration details of STC which were for metal trade and not cloth and fabrics. This was the second issue. Non-existence of the entity at the location, on physical verification, was the third issue. Summons were returned undelivered because neither the firm nor Ms. Reeta Devi were found available. Also, non-availability of details of bank account of STC was the fourth issue. Notice issued by the AA to STC remained undelivered. The Tribunal noted that the Appellant failed to defend its case by producing evidence that the allegations made are incorrect and false and that STC was, in fact, in active business and not a fictitious entity. The bills examined by AA of about Rs 3 lakh were found to be without proof and specific mention of account number of the entity and had no acknowledgement of supply of material and mode of delivery. The Tribunal held that the transaction was fictitious and, therefore a case u/s 2(9)(B) of the PBPT Act was made out.

As regards the argument that it is only the benami property which can be attached and not the amount lying with the appellant in its bank account and also that the attachment of the property can be in the hands of the benamidar and not the beneficial owner as has been done in the present case. The Tribunal held that generally if a case is made out u/s 2(9)(A) of the PBPT Act or any provision other than section 2(9)(B), the provisional attachment of the property may be caused in the hands of the benamidar. However, the aforesaid is not the universal legal proposition and in any case section 2(9)(B) is an exception to it. It held that it is for the reason that when the transaction is fictitious, the question would not arise. It would be in the hands of the beneficial owner who is involved in making fictitious transaction. The Tribunal held that the attachment of property of the appellant cannot be said to be illegal.

Compilers’ Note: The nexus, if any, between the Appellant and Asian Fabrics in whose account cash was found to be deposited is not coming out from the order.

ICAI and Its Members

I. ICAI Tools

ICAI MSME Verification Tool

This tool has been developed by the Centre for Audit Quality Committee (CAQC) of ICAI, as a facilitative tool to assist users in verifying the MSME status of an entity based on information available on the Government portal (https://www.udyamregistration.gov.in/)

https://forms.gle/hbMKkqzVxB4FCuJd6

II. ICAI Publications

1. DCMM 3.0 – Digital Competency Maturity Model Version 3.0 – Third version

DCMM 3.0 has been comprehensively updated to reflect the contemporary digital environment in which CA firms operate. The framework has been designed to help firms assess their present level of digital maturity, identify capability gaps and formulate a structured roadmap for continuous improvement.

2. Background Material on Non-Corporate Entities

This publication aims to provide preparers, auditors, reviewers, academicians and other stakeholders with greater conceptual clarity and practical insights into the application of the Guidance Note.

3. MCQs on Ind AS 117

This volume builds upon the foundation established in Volume I, extending coverage to advanced aspects of the Standard. The MCQs are designed not only to strengthen conceptual clarity but also to assess the application of the Standard through practical situations, transition challenges and interactions with other Indian Accounting Standards.

4. Corporate Restructuring Beyond IBC: Emerging Issues and Recommendations by IB and VSB, ICAI and CLC, ICAI.

This publication examines the evolving landscape of corporate restructuring beyond the Insolvency and Bankruptcy Code, 2016, addressing emerging legal, regulatory and commercial issues. It presents a comprehensive analysis of alternative restructuring mechanisms, identifies key challenges, and offers recommendations to strengthen India’s restructuring framework.

All Publications can be read at: https://publication.icai.org/

III. ICAI Announcements

1. Empanelment as faculty members for the Certificate Course

The Internal Audit Standards Board now invites applications from experienced professionals for empanelment as faculty members for the Certificate Course. Eligible members should possess:

  • A minimum of five years of experience in the banking sector and/or concurrent audit of banks.
  • Experience in delivering technical lectures, seminars, or training programmes for Chartered Accountants or other professional forums.
  • Demonstrated expertise in one or more subjects covered under the Certificate Course.

Interested members are requested to submit their detailed profile/resume, clearly indicating their areas of expertise, professional experience, and teaching experience, through the following Google Form: https://forms.gle/Q95P1ori5BeHys5DA

Last date for submitting response is October 05, 2026.

2. ICAI AWARDS for Excellence in Financial Reporting 2025-26

To recognise and encourage excellence in preparation and presentation of financial information.

I. Public Sector Banks

II. Private Sector Banks (including Foreign Banks)

III. Life Insurance Sector

IV. Non-Life Insurance Sector

V. Financial Services Sector (including NBFC Other than Banking and Insurance)

VI. Manufacturing and Trading Sector (including entities engaged in processing, mining, plantations, oil & gas enterprises) (Turnover equal to ₹5000 crores or more)

VII. Manufacturing and Trading Sector (including entities engaged in processing, mining, plantations, oil & gas enterprises) (Turnover less than ₹5000 crores)

VIII. Service Sector (Other than financial services sector)

IX. Infrastructure and Construction Sector

X. Not-for-Profit Sector

XI. Public Sector Entities

XII. Co-operative Banks

Last date of Submission 15th October, 2026

More details: https://www.icai.org/post/research-committee

3. ICAI Sustainability Reporting Awards 2025-26

Launch of 5th ICAI Sustainability Reporting Awards 2025-26. Excellence in Sustainability Reporting Standards Board (BRSR).

Nomination period: 17th September 2026 to 15th November, 2026.

https://resource.cdn.icai.org/94300srsb-aps6327-brochure.pdf

IV. GIST of ICAI Opinions

1. Classification of Bank Fixed Deposits Held under Lien as Current or Non-Current Assets under Ind AS Framework

A. Facts of the Case

The Company, a Central Public Sector Enterprise, avails Bank Guarantee (BG) and Letter of Credit (LC) facilities from various banks. The arrangements include both general lien over the Company’s deposit portfolio and specific fixed deposits placed as margin money or security against individual BG/LC facilities. The deposits generally have an original maturity of less than twelve months.

During the supplementary audit for FY 2024-25, the C&AG auditor observed that certain bank deposits classified as current assets were held under lien against borrowings/BGs/LCs having claim periods extending beyond twelve months. The auditor contended that deposits amounting to ₹22,257.31 lakh, being subject to such long-term claims, were not realisable by the Company within its operating cycle and should therefore have been classified as non-current assets.

The Company contended that the deposits had original maturities of less than twelve months and were accordingly classified as current assets under Schedule III to the Companies Act, 2013.

B. Query

The Company sought the Committee’s opinion on the classification of bank fixed deposits having
an original maturity of less than twelve months but held under lien against BGs, LCs or borrowing facilities extending beyond twelve months from the reporting date.

The Company also sought clarification on whether classification should be determined primarily by the original contractual maturity of the deposit or by the period for which the underlying lien arrangement continues, and on the appropriate accounting treatment where deposits are held under general lien arrangements without specific linkage to individual BGs, LCs or borrowing facilities.

C. Points considered by the Committee

The Committee noted that classification of an asset as current or non-current has to be assessed at the reporting date based on the criteria in Ind AS 1 and Schedule III. For bank balances and fixed deposits, the relevant considerations are whether the asset is expected to be realised within twelve months and whether it qualifies as cash or a cash equivalent.

The Committee notes that Ind AS Schedule III requires bank balances other than cash and cash equivalents (which meet the definition of ‘current asset’) to be presented as ‘financial assets’ under ‘current assets’. Further, it requires ‘Balances with banks to the extent held as margin money or security against the borrowings, guarantees, other commitments’ to be disclosed separately.

The Committee observed that the classification cannot be based solely on contractual maturity. The substance or economic reality, including the Company’s expectation regarding realisation at the reporting date, has to be considered. Thus, where restrictions arising from lien arrangements are such that the deposit is not expected to be realised within twelve months, or the deposit is required to be continued or renewed to support long-term BG/LC/borrowing arrangements, it would not qualify as a current asset.

The Committee further considered the presentation and disclosure requirements under Division II of Schedule III. Bank balances held as margin money or security against borrowings, guarantees and other commitments are required to be disclosed separately.

D. Opinion

The Committee opined that bank deposits held under general or specific lien arrangements as margin money or security for guarantees or credit facilities should be presented as financial assets under current assets, with separate disclosure in the financial statements, provided that, despite the restrictions arising from the lien, the deposits continue to meet the definition of a current asset.

The Committee further opined that classification of the deposits cannot be based solely on their contractual maturity and must also consider the substance or economic reality regarding the expectation of realisation at the reporting date.

To read full opinion: https://resource.cdn.icai.org/94132cajournal-sep2026-opinion-1.pdf

2. Accounting treatment of expenditure incurred on repair, recovery and reinstallation of damaged subsea assets during construction phase of abc-field, under Ind AS framework

A. Facts of the Case

The Company, a major crude oil and natural gas producer, was developing an offshore oil field through LSTK contracts. During the development phase, two critical subsea assets—SDU-1234 and associated Umbilical UM-1234—were installed in February 2023. Subsequently, during demobilisation of a drilling rig, the SDU toppled and the umbilical was displaced by about 20 metres. Investigation indicated that the damage was most likely caused by the rig’s anchor. At that time, the subsea production system was incomplete and non-functional, and First Oil was achieved only on 7 January 2024 after the damaged assets were recovered, repaired, reinstalled and integrated.

The Company incurred approximately ₹309.77 crore towards the recovery, repair and reinstallation works and capitalised the expenditure as CWIP, subsequently transferring it to PPE. The Company considered the expenditure to be directly attributable to bringing the production system to the condition necessary for its intended use. The C&AG, however, objected to the capitalisation, contending that the expenditure represented abnormal amounts of resources and should not form part of the asset cost.

The Company also expected recovery of the reinstatement cost under the Contractor’s All Risks insurance policy. The Loss Adjuster had recommended a settlement, which had been accepted by management, although final confirmation from the insurer was awaited.

B. Query

The Committee was asked to opine on whether the expenditure incurred for reinstatement of the damaged subsea assets during the development/construction phase could be capitalised under Ind AS 16 and the ICAI Guidance Note on Accounting for Oil and Gas Producing Activities. It was also asked how the expected insurance proceeds should be accounted for: whether by reducing the cost of the related asset or by recognising the amount separately in profit or loss when it becomes virtually certain/receivable.

C. Points considered by the Committee

The Committee first observed that the subsea assets had already been installed and subsequently damaged during rig demobilisation. Therefore, the reinstatement expenditure represented subsequent rectification of damage rather than expenditure incurred to complete an unfinished construction activity. It accordingly had to be evaluated as subsequent expenditure under Ind AS 16.

The Committee noted that Ind AS 16 requires all PPE expenditure to be evaluated under its recognition principle. Accordingly, only expenditure directly attributable to bringing the asset to the location and condition necessary for its intended operation can be capitalised. Further, abnormal amounts of wasted material, labour or other resources cannot be included in the cost of PPE. Whether a particular expenditure constitutes an abnormal cost requires judgement based on the specific facts and circumstances, including the nature of the activity and normal practices in the relevant industry.

Importantly, therefore, the fact that the expenditure was incurred during the development/construction phase does not, by itself, make the entire reinstatement expenditure capitalisable. The Committee held that the Company must determine, on the facts, whether the expenditure is directly attributable under Ind AS 16 and whether any part represents abnormal costs. The resulting expenditure may accordingly be capitalised or charged to profit or loss.

The Committee also distinguished the damage/reinstatement expenditure from ordinary “repairs”. Since the assets had been damaged after their installation, the expenditure was subsequent expenditure and not routine day-to-day servicing. The Committee further noted that, when the damage occurred, the Company was required to assess any impairment under Ind AS 36, and determine whether any previously capitalised asset or component had to be derecognised because it no longer generated future economic benefits.

With regard to insurance recovery, the Committee applied the specific requirements of Ind AS 16 dealing with compensation from third parties. Compensation relating to impaired, lost or given-up PPE is a separate economic event and is recognised in profit or loss when it becomes receivable; it is not adjusted against the cost of the replacement or reinstated asset.

D. Opinion

The Committee held that the treatment requires judgement under Ind AS 16. The expenditure should be capitalised only to the extent it satisfies the recognition and measurement requirements, particularly the requirement of being directly attributable to bringing the PPE to the condition necessary for intended use. Any abnormal cost must be recognised in profit or loss. The Company must also assess impairment and possible derecognition arising from the damage.

The expected insurance proceeds relating to the damaged subsea assets are to be treated as compensation from a third party and recognised in profit or loss when they become receivable, rather than being deducted from the cost of the reinstated asset.

To read full opinion: https://resource.cdn.icai.org/94133cajournal-sep2026-opinion-2.pdf

3. Accounting Treatment of Restoration Obligation under a Service Concession Arrangement

A. Facts of the Case

The Company is an SPV established for execution of a railway gauge-conversion project under a 30-year Service Concession Arrangement with the Ministry of Railways. Under the concession agreement, the Company is required to keep the project assets in proper working condition and replace assets whose codal lives expire during the concession period, with the replacement cost being borne by the Company.

During the audit of FY 2023-24, the C&AG observed that the Company had not recognised a provision for the restoration/replacement obligation on the ground that a reliable estimate was not available. The C&AG considered that the obligation could be estimated and that a provision should be recognised.

In FY 2024-25, the Company estimated the total replacement/restoration obligation at ₹14,200 lakh over the remaining concession period. It recognised ₹1,045.25 lakh in FY 2024-25, and proposed to recognise the balance progressively over the remaining concession period. The C&AG considered this to be a short provision of ₹13,154.75 lakh and contended that the entire estimated obligation should be recognised.

The Company considered the obligation to be a maintenance/restoration obligation that arises progressively as the service potential of the railway assets is consumed. It therefore proposed systematic recognition of the expense over the concession period, with discounting and finance cost for the unwinding of the discount.

B. Query

The Committee was asked whether the Company’s approach of recognising the restoration  obligation progressively over the period up to the date when the restoration obligation arises, by charging annual expenses and finance cost to the Statement of Profit and Loss, is appropriate under Ind AS.

It was also asked whether the C&AG’s suggested approach of recognising the entire estimated obligation upfront in the Statement of Profit and Loss would be appropriate.

C. Points considered by the Committee

The Committee proceeded on the basis that the arrangement falls within Appendix D to Ind AS 115 and that the Company’s restoration activities represent maintenance obligations, without any upgrade element. Under paragraph 21 of Appendix D, contractual obligations to maintain or restore infrastructure to a specified level of serviceability are to be recognised and measured in accordance with Ind AS 37 at the best estimate of expenditure required to settle the present obligation at the reporting date.

Under Ind AS 37, a provision is recognised only when there is a present obligation arising from a past event, an outflow of resources is probable and a reliable estimate can be made. The provision represents the best estimate of the expenditure required to settle the obligation. Where the time value of money is material, the provision is measured at present value and the unwinding of the discount is recognised as finance cost.

The Committee considered the nature of the Company’s obligation to be particularly relevant. The restoration obligation arises from the use of the project assets during the operating phase. Assuming that the service potential of the assets is consumed evenly over their useful lives, the best estimate of the obligation at each reporting date would increase progressively with the use of the assets. Accordingly, the provision should be increased through annual charges to profit or loss over the useful life of the respective assets until their expected replacement/restoration date.

The Committee therefore accepted the in-principle approach of building up the provision progressively, rather than recognising the entire estimated replacement cost upfront. However, it specifically stated that it had not examined the computation of the provision made by the Company.

D. Opinion

The Committee held that the restoration obligation arising from use of the project assets should be recognised and measured under Ind AS 37 at the best estimate of expenditure required to settle the present obligation at each reporting date.

Where the obligation increases proportionately with the use of the assets, the provision should be recognised progressively through annual charges to profit or loss over the useful life of the respective assets up to their expected replacement/restoration date. The provision should be discounted to present value where the time value of money is material, and the unwinding of the discount should be recognised as borrowing/finance cost in the Statement of Profit and Loss.

Accordingly, the Committee concluded that the in-principle approach followed by the Company of progressively recognising the restoration provision is in accordance with Ind AS 37, rather than recognising the entire ₹14,200 lakh obligation upfront. The Committee, however, did not examine the Company’s actual computation of the provision.

To read full opinion: https://resource.cdn.icai.org/94134cajournal-sep2026-opinion-3.pdf

V. ICAI Disciplinary Cases

4. AKK, Resolution Professional of MMDPL v. CA. RAD

Ref. No.: PR/196/2022/DD/263/2022 DC/1931/2024

Disciplinary Committee, Bench-I (2025-26)

Order dated: 5 February 2026

A. Facts of the Case

CA. RAD was the statutory auditor of MMDPL for FY 2018-19 and 2019-20 and had also certified various statutory e-forms, including Form AOC 4. The Company had availed a loan of ₹25 lakh from Paragon Finance Ltd. The loan was subsequently not repaid, resulting in dishonour of the repayment cheque and initiation of CIRP proceedings before the NCLT. The complainant, being the Resolution Professional, alleged irregularities in the Company’s financial statements and statutory filings.

 B. Allegations

The principal allegations related to wrongful preparation and certification of financial statements and statutory forms for FY 2018-19 and 2019-20.

The Committee noted, inter alia, that the documents uploaded on the MCA portal contained:

  • unsigned financial statements for FY 2019-20;
  • absence of UDIN in the audit report;
  • missing Notes to Accounts;
  • incorrect computation of Reserves & Surplus;
  • incorrect Net Worth and Turnover reported in Form AOC-4;
  • differences in dates appearing on the financial statements and audit report; and
  • absence of MGT-9 for the relevant years.

A further allegation was that the Respondent was unable to substantiate the financial figures reported in the financial statements and failed to produce the audit records/documents relied upon for his audit and certification.

C. Respondent’s Defence

The Respondent submitted that the signed financial statements were available with him but the client’s ROC consultant had inadvertently uploaded unsigned statements. He stated that UDIN had been generated but was not appearing in the uploaded PDF because of formatting issues. He also contended that the Notes to Accounts were prepared separately but were not uploaded by the Company/ROC consultant.

The Respondent further submitted that the discrepancies in figures were clerical in nature and that data entry in AOC-4 was undertaken by the Company’s staff. He attributed certain work to junior staff under his supervision and stated that the Company’s data had subsequently been tampered with or deleted from his system. He also denied responsibility for the Company’s loan default,stating that the loan was based on financial statements for FY 2017-18, which were not audited by him.

D. Findings of the Committee

The Committee held that attributing errors to junior staff or the Company’s ROC consultant did not absolve the Respondent of his responsibility as auditor and certifying professional. The ultimate responsibility for the accuracy, completeness and compliance of the audit report and certification remained with him.

On examination of the AOC-4 filings, the Committee found that the FY 2019-20 financial statements attached to the MCA filing did not contain the signatures of the Directors and Auditor, and the Notes to Accounts were missing for both years. It also noted the absence of UDIN in the FY 2019-20 audit report, incorrect Reserves & Surplus, and incorrect Net Worth reported in AOC-4. The Committee accordingly held the Respondent guilty of the first allegation.

With respect to the audit documentation, the Committee emphasised that a statutory auditor is required to obtain and retain sufficient and appropriate audit evidence supporting the audit opinion. The Respondent’s contention that the Company’s data had been deleted or tampered with did not absolve him. The Committee held that failure to maintain audit working papers and inability to substantiate the financial figures forming the basis of the audit report demonstrated gross negligence and lack of due professional care.

E. Conclusion

The Committee held CA. RAD guilty of professional misconduct under Item (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949, relating to failure to exercise due diligence or gross negligence in the conduct of professional duties.

 F. Punishment

The Committee ordered:

Reprimand, fine of ₹1,00,000, as well as removal of the Respondent’s name from the Register of Members for three months. The fine was required to be paid within 60 days of receipt of the order.

5. S.P.C. vs. CA. P.K.G.

File No.: PR/70/2018/DD/124/2018/DC/1949/2024

Date of Order: 05.02.2026

(Findings dated 22.12.2025)

Statutory audit – incorrect reporting of statutory dues and auditor’s involvement in preparation of accounts.

Background

The Respondent was the statutory auditor of M/s BTCO and M/s MTCO for several years, reportedly up to FY 2014-15. The complaint concerned the Respondent’s audit of BTCO and principally related to reporting of statutory dues, his alleged involvement in preparation of the Company’s accounts, and non-disclosure of agreements for sale of three parcels of land.

Key Allegations

  • In the Independent Auditor’s Report for FY 2014-15, the Respondent reported that BTCO was regular in payment of statutory dues, including Provident Fund, ESI, Income-tax and Sales-tax, although PF dues had remained unpaid for several years.
  • The Respondent was alleged to have been involved in preparation and compilation of BTCO’s accounts for FY 2013-14, despite being its statutory auditor.
  • Three agreements for sale of BTCO’s land were entered into in 2012, but the Respondent allegedly failed to disclose the transactions in the audit reports for FYs 2012-13 to 2015-16.

Respondent’s Defence

In relation to the PF dues, the Respondent contended that the demand relied upon by the complainant was raised after the audit report and that the PF dues were accrued but were not legally due because recovery proceedings had been stayed.

Regarding preparation of accounts, he denied preparing the financial statements and stated that he had merely suggested independent accountants and facilitated payment to them. In relation to the land transactions, he contended that only agreements for sale had been entered into, full consideration had not been received and the amounts received were appropriately shown under Other Current Liabilities.

Findings

The Committee found the Respondent’s reporting on PF dues to be contradictory. While his statutory audit report stated that BTCO was regular in payment of statutory dues, his own Tax Audit Report in Form 3CD disclosed that the Company was in default. The Committee therefore concluded that the Respondent was aware of the PF default. It rejected the argument that the stay of recovery proceedings extinguished the liability; according to the Committee, the stay merely suspended recovery. The non-disclosure therefore amounted to failure to report a material misstatement.

On preparation of accounts, the Committee relied on the Respondent’s bill dated 9 September 2014, which specifically charged BTCO for “Compilation and preparation of Accounts for the year ended 31st March 2014”. The Committee concluded that the Respondent was directly involved in preparing the financial statements. It held that subsequently auditing those accounts created a self-review threat and impaired auditor independence, contrary to Section 144 of the Companies Act, 2013 and the ICAI Code of Ethics.

However, the Committee rejected the allegation relating to non-disclosure of the land sales. The Respondent produced the break-up of Other Current Liabilities showing advances received against the proposed land sales and produced sale deeds establishing that the actual sales were completed only on 20.02.2018. Applying AS 9, the Committee held that the sales could not have been recognised in the earlier financial years because the significant risks and rewards had not yet been transferred. The accounting treatment was therefore found appropriate, and the Respondent was held not guilty on this allegation.

Charges Established

The Respondent was held guilty of professional misconduct under Items (6) and (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949: failure to report a material misstatement known to him and failure to exercise due diligence/gross negligence in professional duties.

Punishment

Reprimand and fine of ₹1,00,000, payable within 60 days of receipt of the order.

6. Case: M.K.S. vs. CA. S.K.T.

File No.: PR/G/234/2021/DD/195/2021/DC/1964/2025

Date of Order: 05.02.2026 (Findings dated 22.12.2025)

Failure of statutory auditor to report non-compliance relating to a single shareholder in a private company.

Background

The Ministry of Corporate Affairs directed the Serious Fraud Investigation Office (SFIO) to investigate the affairs of PIHL and its 21 group companies. The SFIO investigation concerned alleged collection of funds from investors through various camouflaged schemes.

The Respondent was the statutory auditor of RCPPL, a PIHL Group company, for FYs 2011-12 to 2014-15. The specific charge considered by the Disciplinary Committee related to the financial year 2012-13, when the Company’s financial statements disclosed that all 3,00,000 shares (100%) were held by PINPL.

Key Allegation

The Respondent was alleged to have failed to report/qualify his audit report for FY 2012-13 despite the Company having only one shareholder, contrary to Section 12 of the Companies Act, 1956, which required a private company to have at least two persons for its incorporation.

Respondent’s Defence

The Respondent stated that during the audit, he had noticed that the Company had only one shareholder and had advised the management to rectify the statutory non-compliance. According to him, the management subsequently transferred one share to Mr. BB, and this was reflected in the financial statements for FY 2013-14.

He therefore contended that corrective action had been taken before issuance of his audit report and, consequently, he did not consider it necessary to qualify the report. He also stated that there was no intention to suppress any fact or mislead stakeholders.

Findings

The Committee noted that the FY 2012-13 financial statements themselves disclosed 100% shareholding in PINPL, establishing that the Company had only one shareholder during that year. In the following year, PINPL held 2,99,999 out of 3,00,000 shares, indicating that one share had subsequently been transferred to another individual.

The Respondent was specifically asked to provide the dates on which the shares were transferred. He was unable to provide the dates, stating that the relevant shareholder register and share-transfer forms had been returned to the Company after audit.

The Committee held that Section 12 of the Companies Act, 1956 required a private company to have at least two persons, whereas RCPPL had only one shareholder as disclosed in its FY 2012-13 financial statements. The Committee also noted that, in response to questions from the SFIO, the Respondent had admitted that there was no reference to this fact in his audit report and that he had not qualified the report.

The Committee consequently concluded that the Respondent had failed to report the statutory non-compliance and had not exercised due diligence in disclosing a material fact known to him.

Charges Established

The Respondent was held guilty of professional misconduct under:

  • Item (5), Part I of the Second Schedule – failure to disclose a material fact known to him which was necessary to be disclosed in the financial statements; and
  • Item (7), Part I of the Second Schedule – failure to exercise due diligence / gross negligence in professional duties.

Punishment

Reprimand and fine of ₹1,00,000, payable within 60 days of receipt of the order.

Class Action Suits: A New Dawn in Minority Protection

Section 245 of the Companies Act, 2013 introduced class action suits in India, enabling minority shareholders and depositors to seek legal remedies from the NCLT against management conduct prejudicial to their interests. For listed companies, members holding at least 2% share capital can file.

India’s first class action suit arose in Jindal Poly Films Ltd., where shareholders challenged undervalued related-party transactions causing a ₹2,500 crore loss. The NCLT admitted the plea, making 45,000 public shareholders litigants, and NCLAT upheld it. Though 29 shareholders obtained a Supreme Court order referring the dispute to arbitration, other minority shareholders petitioned for a recall.

INTRODUCTION

Many of us would have read about class action suits, which are very popular in the USA. They are a form of litigation where several of the aggrieved come together under one roof to file a common suit against one or more persons. India, till recently, had not witnessed any such litigation. However, the Companies Act, 2013 has introduced specific provisions for Class Action Suits as a form of minority protection. Recently, Corporate India witnessed the first Class Action Suit by shareholders against a Promoter in the case of Jindal Poly Films Ltd. Let us examine this important facet of shareholder activism in more detail.

WHAT IS A CLASS ACTION SUIT?

The Law Lexicon, 4th Edition by P. Ramantha Aiyar defines the term class to mean a homogeneous section of people grouped together because of certain likeness or common traits and who are identifiable by some common attributes State of AP v P. Sagar, AIR 1968 SC 1379.

Stroud’s Judicial Dictionary of Words and Phrases, 5th Edition defines the term action to mean the invocation of the jurisdiction of a court by writ or any other matter. It is a civil proceeding.

Black’s Law Dictionary, 6th Edition, defines the term class action as a means by which, where a larger group of persons are interested in a matter, one or more may sue or be sued as representatives of the class without needing to join every member of the class. There are general requirements for the maintenance of any class suit – persons constituting the class must be so numerous that it is impracticable to bring them all before the Court and the named representatives must be such as will fairly insure the adequate representation of all of them.

Thus, simply put, many people who have a common cause of action, come together as a single unit to litigate rather than each filing a separate lawsuit. Think of it as similar to the phrase made famous by the Author, Alexandre Dumas ~ “All for One and One for All!”

COMPANIES ACT, 2013

Meaning – The Companies Act, 2013 (“the Act”) has, for the first time in Indian corporate history, expressly provided for a class action suit. S.245 of the Act, which came into force from 1st June 2016, provides that a prescribed number of members/depositors or any class of them may file a class action suit before the NCLT if they are of the opinion that the management or conduct of the affairs of the company is being conducted in a manner prejudicial to the interests of the company or its members or depositors.

Prescribed Number – The minimum number of members required for filing a class action suit before the NCLT is as follows:

(a) in the case of a company having a share capital, not less than 100 members or not less than 5% of the total number of its members, whichever is less. However, all the applicants must have paid all calls and other sums due on their shares;

(b) (i) members holding not less than 5% of the issued share capital of an unlisted company;

(ii) members holding not less than 2% of the issued share capital of a listed company;

c) in the case of a company not having a share capital, not less than 1/5th of the total number of its members;

(d) not less than 100 depositors or not less than 5% of the total number of its depositors – whichever is lower; or

(e) depositor or depositors to whom the company owes 5% of the total deposits of the company.

Class Action Minority Protection

Relief that can be sought – The class action suit can be for seeking all or any of the following relief orders from the NCLT:

(a) to restrain the company from committing an act which is ultra vires the Articles of Association or Memorandum of Association of the company;

(b) to restrain the company from committing a breach of any provision of the company’s Articles of Association or Memorandum of Association;

(c) to declare a resolution altering the Memorandum or Articles of the company as void if the resolution was passed by suppression of material facts or obtained by misstatement to the members or depositors;

(d) to restrain the company and its directors from acting on such resolution;

(e) to restrain the company from doing an act which is contrary to the provisions of the Act or any other law for the time being in force;

(f) to restrain the company from taking action contrary to any resolution passed by the members;

(g) to claim damages or compensation or demand any other suitable action from or against—

(i) the company or its directors for any fraudulent, unlawful or wrongful act or omission or conduct or any likely act or omission or conduct on its or their part;

(ii) the auditor/ audit firm of the company for any improper or misleading statement of particulars made in his audit report or for any fraudulent, unlawful or wrongful act or conduct; or

(iii) any expert or advisor or consultant or any other person for any incorrect or misleading statement made to the company or for any fraudulent, unlawful or wrongful act or conduct or any likely act or conduct on his part;

(h) to seek any other remedy as the Tribunal may deem fit.

Considerations by the NCLT – In deciding whether an action is maintainable, the Act provides that the NCLT would consider the following:

(a) whether the member or depositor is acting in good faith in making the application for seeking an order;

(b) any evidence before it as to the involvement of any person other than directors or officers of the company on any of the matters on which relief is sought;

(c) whether the cause of action is one which the member or depositor could pursue in his own right rather than through an order under this section;

(d) any evidence before it as to the views of the members or depositors of the company who have no personal interest, direct or indirect, in the matter being proceeded under this section;

(e) where the cause of action is an act or omission that is yet to occur, whether the act or omission could be, and in the circumstances would be likely to be—

(i) authorised by the company before it occurs; or

(ii) ratified by the company after it occurs;

(f) where the cause of action is an act or omission that has already occurred, whether the same could be, and in the circumstances would be likely to be, ratified by the company.

While considering the desirability of an individual/separate action as opposed to a class action, the NCLT may consider whether admitting separate actions by members/depositors would create a risk of :

(a) inconsistent or varying adjudications in such separate actions;

(b) adjudications that, as a practical matter, would be dispositive of the interests of the other members, i.e., completely settle or resolve the claims of other members;

(c) adjudications which would substantially impair or impede the ability of other members of the class to protect their interests.

In addition, the National Company Law Tribunal Rules, 2016 provide that the NCLT may, while considering the admissibility, also take into account the following:

(a) whether the class has so many members that joining them individually would be impractical, making a class action desirable;

(b) whether there are questions of law or fact common to the class;

(c) whether the claims or defences of the representative parties are typical of the claims or defences of the class;

(d) whether the representative parties will fairly and adequately protect the interests of the class.

Procedure – A member of a class action under s.245 of the Act is entitled to opt-out of the proceedings at any time after the institution of the class action, with the NCLT’s permission. Subject to this, the procedure, briefly stated, is as follows

(a) a public notice shall be served on admission of the application to all the members or depositors of the class;

(b) all similar applications prevalent in any jurisdiction should be consolidated into a single application and the class members or depositors should choose a lead applicant;

(c) two class action applications for the same cause of action shall not be allowed;

(d) the cost or expenses connected with the application for class action shall be defrayed by the company or any other person responsible for any oppressive act.

Binding Order – Any order passed by the NCLT shall be binding on the company and all its members, depositors and auditor/audit firm or expert or consultant or advisor or any other person associated with the company. Violation of the Order is punishable with a fine ranging from ₹5 lakhs to ₹25 lakhs. Every officer of the company who is in default shall be punishable with imprisonment for a term which may extend to 3 years and with a fine ranging from ₹25,000 to ₹1 lakh.

NCLT ORDER IN JINDAL POLY FILMS

The very first class action suit under s.245 was filed in the case of Ankit Jain v. Jindal Poly Films Ltd., [2026] 183 taxmann.com 491 (NCLT – New Delhi). In that case, shareholders holding 4.99% (which was more than the 2% threshold) filed a class action suit against a listed company. Their plea was that certain related party transactions between the company and promoter entities pertaining to sale of certain shares held by the company should be set aside or, alternatively, the class members should be compensated for the loss arising from such transactions. It was alleged that the transactions were grossly undervalued and resulted in a loss of approximately ₹2,500 crore to the listed company and a proportionate loss to its public shareholders.

The NCLT held that the essential ingredient of s.245 of the Companies Act, 2013 was to file an application before the NCLT to seek various remedies if, in its opinion, the management or conduct of the affairs of the company were being conducted in a manner prejudicial to the interest of the company or its members or depositors. The condition precedent, being the formation of an opinion, which prima-facie should state that the affairs of the company were not conducted in a just manner and which were against the interest of the company or against the interest of the members/shareholders. The right to initiate actions against third parties like experts and advisers for any incorrect, misleading statements or any fraudulent, unlawful or wrongful act, made it clear that the conduct of affairs of the company, past, present and continuing actions could also be impeached when and if it was conducted in a manner prejudicial to the company and its members or depositors. It was wide enough to cover all kinds of transactions in relation of any of the provisions of the Act, Rules etc. It was a special enactment to class of shareholders, depositors and the like. Hence, the contention of the Respondent that past and concluded transaction should not be allowed to be raised may not be justified.

It also held that s.245 had been differently drafted in the Indian context and was different from the American Law. The comparison with the American Law may not be appropriate because the Indian Parliament was quite conscious of the fact that the class action can be initiated by depositors, members of the company to enforce certain action against the company itself. Section 245 of Companies Act 2013, provided for various kinds of relief given the backdrop of Indian Corporates and investors. Section 245 was a benevolent legislation to provide relief to shareholders, depositors against the company and for other relief(s) past, present and future. This should be seen in contradiction to a case filed by a third party or a public authority or a person who had no direct cause or relation with the company. It held that under the Indian Jurisprudence, the Parliament in its wisdom gave a right more defined than a derivative action, in respect of shareholders in a public limited company. This provision sought to address the issue where there were numerous or large number of shareholders and all of them joining was impracticable, where the question of law in relation to such fact was common to the class. Under s.245 of the Companies Act, the class action envisaged a process of safeguarding the interest of depositors/ shareholders in relation to the conduct of affairs of the company.

Merely because there is another option available under sections 241-242 (of filing an oppression and mismanagement plea) that could not per se dis-credit a class action under s.245 if the other parameters for initiating the proceedings under Section 245 were met by the Petitioners. All that was required was shareholding of 2% of total share capital in a
listed company and a justifiable prima facie opinion of the NCLT. Accordingly, the NCLT admitted the plea. This made all the 45,000 public shareholders of the company a separate class who were now litigants.

NCLAT UPHOLDS THE ORDER

This Order of the NCLT admitting the plea was upheld by the NCLAT in Jindal Poly Films Ltd. v. Ankit Jain, [2026] 183 taxmann.com 736 (NCLAT- New Delhi). It further held that under s.245(1) of the Act, the NCLT had very wide powers and reliefs thereunder can be sought against third parties, including directors and promoters of the company. The plea was empowered “to seek any other remedy as the Tribunal may deem fit”, which was a residuary provision taking within its ambit the matters which are not subsumed within other sub-clauses. In regard to the plea against past actions, the NCLAT held that the impugned transactions had been systematically orchestrated over a period of time and executed in a manner that its illegality (undervaluation, etc.) was deliberately, and with fraudulent motive/purpose, never brought to the attention and knowledge of the public shareholders. Having allegedly concealed the transactions at the time of commission, the company, the promoters, directors now could not take benefit of their own wrongdoings. The fact when such transactions came to the knowledge of the respondents would be a relevant fact. Thus, it agreed with the NCLT on this issue. The NCLAT further held that the NCLT was of the prima facie opinion to initiate the proceedings. However, it was always open to the company/promoters to deny the allegation and refute the charge. Hence, it concluded that NCLT had satisfied itself regarding fulfilment of all requisite pre-conditions under s.245 read with relevant Rules. Thus, it was not inclined to interfere in the impugned order and the appeal against the admission by the NCLT was dismissed.

SUPREME COURT’S VERDICT

Subsequent to the NCLAT Order, the main applicant in the class action suit was substituted with another member – Monet Securities P Ltd. This applicant, 28 other shareholders and the company filed a consent application before the Supreme Court requesting that the NCLT Petition be disposed-off and instead the matter be referred to arbitration. The application stated that on a review of the nature of the disputes and considering efficacy of the remedy, the matter would be better suited to adjudication through arbitration. It left the choice of arbitrator to the Court. Accordingly, the Supreme Court disposed of the class action suit and instead referred the matter to arbitration by its order in Jindal Poly Films Limited vs Monet Securities Private Limited, CA No. 8709/2026, Order dated 8th June 2026.

Aggrieved by this Order, a group of shareholders filed a Miscellaneous Application before the Supreme Court seeking a recall of its earlier 8th June Order. It was contended that the Supreme Court had not been informed that the proceedings before the NCLT had already acquired the character of a class action, with thousands of non-promoter minority shareholders becoming parties to the proceedings following statutory public notice. It was contended that an entire class consisting of all non-promoter minority public shareholders were part of the class, whereas the consent application was filed only by 29 shareholders. It was argued that this material fact was not disclosed before the Supreme Court and it was not open to one or a few shareholders to withdraw a class action suit. The Supreme Court has concluded all hearings in this matter and has reserved the matter for judgment.

EPILOGUE

The entire episode of Jindal Poly Films seems like a mystery film. Just when one thought there was an ending, there is a twist in the climax. One wonders how, in the absence of an arbitration agreement (which is the foundation of any arbitration), could the matter be referred to arbitration? Further, and more importantly, can an entire class of shareholders (over 25% of the shareholders in this case) be bound by an arbitration accepted by a few of them? Does this not defeat the very concept of a class action suit? When the threshold for filing a class action suit is 2% of the capital, then should not the same yardstick be applied for withdrawing the suit? When 45,000 shareholders were admitted as litigants, could 29 shareholders file a consent decree? It would be interesting to see the developments in this case. However, one thing is for sure, class action suits are here to stay and corporate India may expect to hear more on this!

Maya Banerjee v. Union of India: Arrears of family pension are payable from the date of employee’s death, not restricted by subsequent delayed approach.

34. Maya Banerjee v. Union of India & Ors.

2026 INSC 959

August 20, 2026

Family pension – Arrears – Conflicting decisions of coordinate Benches – Tarsem Singh and S.K. Mastan Bee – Subsequent Bench of equal strength bound by earlier decision – Doctrine of per incuriam – family pension payable from the date it fell due. [Railway Services (Pension) Rules; Constitution of India, Arts.21, 141]

FACTS

The appellant was the widow of a Railway employee who died in service on 12.11.2000. She was an illiterate woman and was unaware of her husband’s service details. Her husband was nevertheless dismissed from service after his death, contrary to the Railway Board’s circular requiring disciplinary proceedings to be closed upon death of the employee.

The appellant’s claim for family pension was not acted upon. She subsequently obtained a civil court decree declaring the date of her husband’s death. The High Court ultimately directed payment of family pension but restricted the arrears to the period from 2014, when she first approached the Central Administrative Tribunal.

The appellant claimed pension from the date of her husband’s death. The Union of India relied upon Union of India v. Tarsem Singh (2008) 8 SCC 648, under which consequential relief of arrears in pension matters would ordinarily be restricted to three years preceding the filing of the writ petition. The appellant relied upon S.K. Mastan Bee v. General Manager, South Central Railway (2003) 1 SCC 184, where family pension was granted from the date on which it became due despite the widow’s delayed approach.

HELD

The Supreme Court noted that Tarsem Singh (Supra) and S.K. Mastan Bee (Supra) were decisions of Benches of equal strength and that their approaches regarding arrears of family pension were in conflict.

The Court reiterated that a coordinate Bench cannot take a contrary view from an earlier decision of a Bench of equal strength. If it disagrees with the earlier decision, the proper course is to refer the matter to a larger Bench. A subsequent coordinate Bench cannot simply disregard the binding precedent.
The Court further explained the doctrine of per incuriam. A judgment may be treated as per incuriam where its ratio is irreconcilable with an earlier decision of an equal or larger Bench or where a relevant statutory provision or binding authority was not brought to the Court’s attention. The doctrine applies to the ratio decidendi, and must be applied sparingly.

On the merits, the Court held that S.K. Mastan Bee (Supra) directly dealt with the claim of a widow for family pension and was therefore the more appropriate precedent. Since Tarsem Singh (Supra) had not considered the earlier decision, the Court followed S.K. Mastan Bee (Supra).

Family pension was a valuable right and property in the hands of the appellant. In the circumstances, restricting the arrears to 2014 would cause grave injustice, particularly when the appellant was not responsible for the delay and the Railways themselves had failed to discharge their obligation to compute and offer the family pension.

The High Court’s order was modified, and the appellant was held entitled to family pension from the date of her husband’s death, with the entire arrears carrying interest at 6% per annum.

Manav Bhanot v. National Highway Authority of India: Compensation benefits for highway land acquisitions determined before 01.01.2015 are computed under Land Acquisition Act, 1894.

33. Manav Bhanot v. National Highway Authority of India

2026 INSC 973 September 8, 2026

Land acquisition – National Highways Act – solatium and interest – applicability of 1894 Act or 2013 Act – compensation determined before 1.1.2015 – benefits to be computed under 1894 Act.

[National Highways Act, 1956, Ss.3G, 3H; Land Acquisition Act, 1894; Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013, Ss.24, 105]

FACTS

The appellant’s land was acquired under the National Highways Act. The notification under section 3A was issued in 2011, and the declaration under section 3D was made in 2012.

The Competent Authority determined compensation on 11.07.2014. The appellant received part of the compensation but disputed the quantum, resulting in an arbitration proceeding. The dispute before the Supreme Court concerned the statute under which solatium, interest and interest on solatium were required to be computed.

The appellant contended that the beneficial provisions of the 2013 Act should apply. NHAI contended that the 2013 Act became applicable to acquisitions under the National Highways Act only from 01.01.2015 and that the compensation had already been determined before that date.

HELD

The Supreme Court held that landowners whose lands are acquired under the National Highways Act are entitled to solatium, interest on compensation and interest on solatium. The question is under which enactment these benefits are to be computed.

For acquisitions under the National Highways Act, the determination of compensation by the Competent Authority under section 3G(1) constitutes the equivalent of an award. Where such determination was made before 01.01.2015, the compensation benefits are to be computed under the Land Acquisition Act, 1894. Where the determination was made after 01.01.2015, the provisions of the 2013 Act would apply.

In the present case, the Competent Authority determined compensation on 11.07.2014, before the 2013 Act became applicable to acquisitions under the National Highways Act from 01.01.2015. Consequently, although the appellant was entitled to solatium, interest and interest on solatium, the same were to be computed under the 1894 Act.

The Court accordingly allowed the appeal to that limited extent and remanded the matter to the Competent Authority for computation and disbursal of the benefits under the 1894 Act.

Lakshmi Mohan v. Airtech Projects Engineers Pvt. Ltd.: Minor shortfall in EMD prescribed by sale notice does not invalidate auction sale under SARFAESI Act if cured.

32. Lakshmi Mohan (Dead) through LHs. & Anr. v. Airtech Projects Engineers Pvt. Ltd. & Ors.

2026 INSC 909 August 21, 2026

SARFAESI – Auction sale – Earnest money deposit – Shortfall in EMD prescribed by sale notice – Subsequent deposit of 25% of sale consideration – Technical non-compliance causing no prejudice – validity of auction not affected. [Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002; Security Interest (Enforcement) Rules, 2002, Rr.8, 9]

FACTS

The borrower defaulted in repayment of a cash-credit facility and the Bank initiated proceedings under the SARFAESI Act. A possession-cum-sale notice required intending bidders to deposit EMD of Rs. 21,50,000/- and stipulated that an offer without EMD would be rejected.

The auction purchasers submitted their bid with EMD of ₹21,15,000/-, resulting in a shortfall of ₹35,000/. Their bid of ₹2,17,40,000/- was the highest. On the date of auction, they deposited a further amount which brought the total deposit to 25% of the bid amount, as required by Rule 9(3). The balance consideration was subsequently deposited and a sale certificate was issued and registered.

The DRAT held that the auction was invalid for non-compliance with the sale notice. The High Court ultimately upheld the DRAT’s decision.

HELD

The Supreme Court held that conditions in a tender or auction notice must be distinguished between essential conditions of eligibility and ancillary or subsidiary conditions. While essential conditions ordinarily require strict compliance, a technical deviation which causes no substantial prejudice or injustice may not invalidate the transaction.

The requirement of EMD of ₹21,50,000/- was a non-statutory condition incorporated in the sale notice to filter out non-serious bidders. Both bidders had deposited ₹21,15,000/- and the Bank had entertained both bids.

More importantly, the auction purchasers deposited 25% of the sale price, inclusive of the EMD, on the date of the auction, thereby complying with the statutory requirement under Rule 9(3). The earlier shortfall of ₹35,000/- therefore caused no prejudice either to the competing bidder or to the borrower and did not affect the validity of the bid.

The Court further held that the delay in payment of the balance consideration could not invalidate the sale since the Bank had agreed to extend the period for payment in view of the pending litigation, and the balance was deposited immediately after the borrower’s challenge was dismissed.

The DRAT and High Court judgments were set aside. The Bank was directed to refund the surplus sale proceeds of ₹1,33,94,054/- to the borrower with interest at 7% per annum from 23.03.2010.

Ravi Kant Gupta v. State of Uttar Pradesh: Maintenance Tribunal under Senior Citizens Act possesses incidental power to order eviction of children to ensure maintenance and protection.

31. Ravi Kant Gupta v. State of Uttar Pradesh & Ors.

2026 LiveLaw (SC) 824

August 4, 2026

Senior citizens – Maintenance and protection – Eviction of children from senior citizens’ property – Power of Tribunal to order eviction – incidental power necessary to enforce maintenance and protection.

[Maintenance and Welfare of Parents and Senior Citizens Act, 2007, Ss.7, 8, 16, 27; Constitution of India, Arts.21, 41]

FACTS

The appellant was the owner of a residential house in Lucknow. His son and daughter-in-law were residing in the premises. The appellant’s aged mother had allegedly been compelled to leave the premises and reside in an old age facility.

The appellant approached the District Magistrate under the Maintenance and Welfare of Parents and Senior Citizens Act seeking eviction of his son. The Sub-Divisional Magistrate directed eviction and the District Magistrate affirmed the order.

The High Court, relying upon an earlier decision, held that the authorities under the Act had no power to order eviction and quashed the orders. The appellant approached the Supreme Court.

HELD

The Supreme Court held that the Tribunal constituted under the Act possesses the power to order eviction where such eviction is necessary and expedient to ensure the maintenance and protection of a senior citizen or parent.

Section 8 empowers the Tribunal to conduct an inquiry by summary procedure with powers of a Civil Court, while section 27 bars the jurisdiction of Civil Courts. Where a statute confers jurisdiction upon an authority, it impliedly confers such ancillary powers as are necessary to make that jurisdiction effective.

Accordingly, the power to order eviction is an incidental power necessary for enforcing the statutory right of maintenance and protection.

The Court relied upon S. Vanitha v. Deputy Commissioner AIR 2021 SC 177, Samtola Devi v. State of U.P 2025 LiveLaw (SC) 445 and Kamalakant Mishra v. Additional Collector 2025 LiveLaw (SC) 947, and held that the High Court’s reliance upon the contrary earlier decision was misconceived.

The orders of the High Court were set aside, and the eviction orders passed by the authorities under the Act were restored.

Jaspal Singh v. Ashwani Kumar: Absence of express stipulation for specific performance in agreement to sell does not bar decree for specific performance.

30. Jaspal Singh v. Ashwani Kumar

2026 LiveLaw (SC) 682

July 14, 2026

Specific performance – Agreement to sell – Clause providing for refund of earnest money in event of non-execution of sale deed – Absence of express stipulation for specific performance is no bar – Co-owner’s undivided share valid subject matter of transfer – Limits of interference with concurrent findings in second appeal. [Specific Relief Act, 1963, S.23; Code of Civil Procedure, 1908, S.100]

FACTS

The appellant entered into an agreement to sell with the respondent, a co-owner of the property, for purchase of his undivided half share for `12,50,000/-. The appellant paid `9,00,000/- as earnest money. The agreement stipulated that if the sale deed could not be executed, the respondent would refund the earnest money.

The date for execution of the sale deed was twice extended, and a further sum of `60,000/- was paid. The appellant appeared before the Sub-Registrar on the stipulated dates, but the respondent did not.

The Trial Court found the agreement to have been duly executed and the appellant ready and willing to perform his obligations, but declined specific performance on the ground that the agreement provided only for refund of earnest money. The First Appellate Court decreed specific performance.

In the second appeal, the High Court affirmed the findings regarding execution of the agreement, payment of earnest money and readiness and willingness, but nevertheless held that the transaction was not genuine and restored the decree of the Trial Court.

HELD

The Supreme Court held that section 23 of the Specific Relief Act does not preclude specific performance merely because the agreement stipulates payment or refund of a sum in the event of breach. The question is whether the stipulated sum was intended to give the defaulting party an option to pay money in lieu of performance.

The clause in the present case merely required refund of earnest money if the sale deed could not be executed. It contained no language conferring an option upon the vendor to discharge the contract by refunding the earnest money. The stipulation therefore reinforced the obligation to perform and did not constitute a substitute for performance.

The Court further held that an undivided share of a co-owner in immovable property is a valid and marketable subject matter of transfer. The fact that the co-sharer was not a signatory could not, by itself, cast doubt on the genuineness of the agreement.

The High Court had also exceeded its jurisdiction under section 100 CPC by disturbing concurrent findings of fact without recording any finding of perversity. The First Appellate Court is the final court on questions of fact, and its findings regarding execution of the agreement, readiness and willingness and the falsity of the defence could not be reopened merely because another view of the evidence was possible.

The judgment of the High Court was set aside, and the decree for specific performance passed by the First Appellate Court was restored.

From Published Accounts

COMPILER’S NOTE:

Few leading companies in India now publish a Tax Transparency Report to highlight the tax related matters, approach to tax, tax governance, managing tax risk, tax strategy, approach to compliance, advocacy and relationship with regulators and global contribution to tax. Given below are relevant extracts of a Tax Transparency report and Assurance Report thereon.

Tata Motors Passenger Vehicles Limited (formerly Tata Motors Ltd)

Extract of Tax Transparency Report FY 2025-26

INTRODUCTION

We recognize that the tax that we account for, and pay is an important aspect of our wider economic and social impact of the Tata Motors group. Tata Motors PV as always is guided by the Tata Code of Conduct, hence accountability remains rooted in all aspects of its decision. The focus is not only product sustainability but also operational sustainability with strong governance structure around all practices including tax. In furtherance to our endeavour last year, we hereby present our approach to tax related matters and Global Tax & Other Contributions in this 2nd Tax Transparency Report, thereby endorsing our continued commitment to tax accountability that in turn plays a key role in sustainability. This would also address the changing tax environment globally, requiring public disclosures of tax related parameters.

Global Tax and other contributions summary

(Discontinued Operation) April to June 2025

Particulars FY26
Revenue
Contribution
16,730
2,322

CATEGORY WISE SUMMARY

CATEGORY WISE SUMMARY

The graphs present data for only Tata Motors PV entities for FY 2025 and FY 2026. The data for commercial vehicles undertaking entities are provided for parity with Financial Statement as discontinued operation in a separate table.

Our approach to tax

At Tata Motors PV, we place strong emphasis on fulfilling our tax related obligations across the Group, guided by the core values embedded in the Tata Code of Conduct. Our responsible approach to taxation extends beyond governance and accountability frameworks and includes continuous capability building through structured training programs for our tax professionals. These programs focus on audit preparedness, evolving tax legislation, and developments in the dynamic tax and regulatory environment.

We are firmly committed to full compliance with the tax laws and regulations of the jurisdictions in which we operate, with zero tolerance for non-compliance. All tax positions and decisions are grounded in applicable local tax laws and, where required, are reviewed and validated by external experts. Business decisions are driven by commercial substance and are never motivated by artificial or aggressive tax planning. Tata Motors PV is committed to paying taxes in the jurisdictions where economic value is created, reflecting our belief that accountable and efficient operations are central to sustainable success. Our stakeholders, including customers, investors and shareholders, vendors, and employees place a high premium on accountability, of which being a responsible taxpayer is an essential element. Accordingly, our tax function is guided by clearly articulated tax principles that are aligned with our business conduct and ethical standards across our global operations.

KEY TAX PRINCIPLES

The following are the key principles in relation to our approach to tax matters and the conduct of our tax affairs. We adhere to a transparent approach, ensuring full disclosure of our activities to all stakeholders.

1. Compliance

We act with integrity, both within the letter and spirit of all tax legislation and relevant international standards. We have a zero tolerance to tax evasion, including the evasion of tax by third parties associated with our business. As a commercially driven organization, we consider the tax consequences and do not engage in transactions without commercial substance with the sole purpose of avoiding tax. In making business decisions we seek to maximize value to our stakeholders. Tax decisions are driven by core values of integrity, unity and responsibility and planning is driven by commercial rationale. Our commitment to ethical taxation is built on a foundation of unwavering integrity and rigorous adherence. We approach our responsibilities with earnest sincerity, ensuring the timely payment of all relevant taxes in all the jurisdictions we operate.

2. Robust internal controls

We proactively seek to identify, manage, and mitigate any potential tax risks, staying abreast of key changes and trends in tax matters through our internal control systems and external advisors/consultants as needed. Our internal controls have stringent escalation matrix at strategic intercepts to ensure critical decisions and positions are evaluated from all perspective.

3. International tax

We embrace business unity to ensure that our international tax affairs are aligned and kept current with the substance of our business operations and international tax guidance. We do not engage in any form of artificial tax structuring. Our subsidiaries are located in countries where the business has significant substance. We claim reliefs, credits, incentives and exemptions that are legislated in these countries as applicable to our operations.

4. Stakeholders relationship

We seek to maintain trusting, transparent and constructive relationships with tax authorities, and proactively participate in dialogues with industry and advocacy bodies to shape effective future tax policy and create shared value. We believe in open communication with all our stakeholders regarding our business substance and any tax related decisions. Our approach to tax disputes is open dialogue or adoption of available dispute resolution options in local jurisdictions.

5. People

We invest in our people, as we strongly believe that their continued learning and growth is essential for us to deliver on all our commitments. In line with current trend, it is our continuous endeavour to ensure that our people at every department adopt and leverage technology.

OUR APPROACH TO TAX GOVERNANCE AND RISK

Our corporate philosophy is in tandem with Tata Group’s enduring legacy of integrity, transparency, accountability, trusteeship and ethical governance. Tata Motors PV corporate philosophy derives and exercises its commitment to ethical, transparent and accountable governance practices through its corporate governance framework. Our corporate governance practices are consistent with international best practices and standards. Our governing principles are driven by a sense of responsibility and fairness, ensuring that our leaders and our work are always guided by the best interests of all our stakeholders. Both, approach to tax governance and risk are treated as strategic enablers of sustainable value creation, not merely statutory obligations. This approach to governance percolates to the tax function within the group.

The Board of Directors, supported by its committees, ensures that the Company is able to conduct its business responsibly and uphold the best interests of its diverse stakeholders by ensuring fairness, independence and transparency in all its decisions through the governance framework. They specifically review all financial and non-financial information. Tata Motors PV has a robust internal tax governance framework, which includes, clearly defined tax policies and internal controls, dedicated in-house tax and finance teams, oversight by senior management and the Board as well as regular internal reviews and audits.

We at Tata Motors PV, appreciate our operational complexity being spread across multiple jurisdictions with various complex regulations. This lends an inevitable inherent degree of tax uncertainty in the operational level, which might not always be visible and hence immediately addressable. However, we address tax uncertainties by partnering with business to provide timely tax advice. At all times, our endeavour is to ensure that such business decisions are evaluated for all tax implications and vetted by local tax experts to ensure adherence to all local tax regulations as well as compliances.

MANAGING OUR TAX RISK

The Company’s tax operating model is designed to ensure effective governance and oversight, with the direct tax and indirect tax verticals reporting independently to senior leadership. Each vertical is further structured to provide centralized support to multiple Group entities across key tax functions. The Company continues to retain responsibility for its entire legacy tax litigation portfolio, which is managed appropriately by leveraging historical knowledge, documentation, and experienced in house teams.

Further, through creation of joint ventures like the global shared service and digital/ artificial intelligence focused entities the Company ensures alignment across its group entities with respect to tax solutions and IT infrastructure supporting the same.

This collaborative operating model is underpinned by consistent governance principles, strong internal controls, and shared accountability frameworks, ensuring that tax operations across the Group are aligned with the Company’s overarching compliance and ethical standards.

The centralized tax model operates through two distinct but complementary dimensions:

Centralized Drive: Planning, strategy, overall compliance review, advisory, assessments, investigations & litigations, have a centralized approach. This includes initiatives aimed at unlocking of funds through driving tax refunds, credits, Lower Deduction Certificate (LDC), disposal of litigations etc. It ensures uniform tax positions through proactive initiatives. It provides support for restructuring, and Mergers & Acquisitions (M&A) activities of the group and assisting in simplifying the Related Party Transactions (RPT) policy and benchmarking. The various international tax updates and changes are coordinated as they form the core of advocacy initiatives.

Centralized Delivery: The operational support in terms of compliances is performed centrally, wherever possible. Process improvements through implementation of automation & analytics is a focus. Support is provided to the various entities in the group through the central delivery mechanism.

We seek to take a unified and consistent approach to tax positions and compliance, whilst acknowledging that each country has its own tax law and practice that must also be taken into account. Working closely with the business and applying relevant expertise and capabilities, we align business strategy with robust compliance. Where required, we seek external validation of any positions taken. Based on the magnitude of the impact, the decision mechanism flows to the Audit Committee (AC) and the Board of Directors.

The preservation of the governance and compliance framework is facilitated by appropriately qualified and experienced tax resources supported with technology. The tax and finance function teams consist of several qualified accountants with the skills, knowledge and experience to manage the Company’s tax affairs, who undertake mandatory Continuing Professional Development (CPD) training to stay up to date with the relevant tax compliances. Further they are supported with customized adoption of technology to monitor and ensure global compliance standards are met [including management of any litigations]. Tools are used for preparation of essential reports including tax computations, GST, deferred tax, Country-by-Country Reporting (CbCR) and RPT.

TAX STRATEGY

The Company maintains a robust tax risk management and control framework, designed to ensure adherence to our key tax principles and support responsible decision making across the organisation. This framework is reinforced through periodic internal reviews, regular refresh of tax policies, and the use of independent external advisors where interpretational complexities or uncertainties in tax law arise. As a Group, Tata Motors PV maintains a conservative and limited appetite for tax risk, and, guided by the Tata Code of Conduct, continuously endeavours to identify, assess, and mitigate tax risks at every level of the decision-making process.

Day to day management of tax affairs rests with the dedicated tax function, comprising an appropriate blend of experienced and qualified tax professionals. The tax function also plays a strategic role by advising senior management on Group tax strategy, policy formulation, and significant business transactions, ensuring that commercial decisions are supported by sound and compliant tax outcomes.

1. Tax controls

Strong tax controls form the foundation of our tax governance framework. These include tax policies, standard operating procedures, defined approval matrices, and multi layered review mechanisms. Technology enabled controls are increasingly deployed to monitor compliance timelines, track statutory filings, validate data integrity, and support accurate reporting across jurisdictions.

2. Risk management and governance

Tax risk is managed as an integral component of the Company’s overall enterprise risk management framework. Potential tax exposures whether arising from legislative changes, complex transactions, interpretations, or audits are identified early and assessed for materiality and likelihood. Material tax risks and positions are escalated through defined governance channels and ensuring appropriate oversight by senior management This structured governance ensures accountability, consistency in tax positions, and alignment with the Company’s risk appetite.

3. Tata Code of Conduct

All tax professionals across geographies are onboarded and operate in strict adherence to the Tata Code of Conduct, which places a strong emphasis on integrity, ethical behaviour, transparency, and accountability. Given that tax impacts not only the Company but also the broader social and governmental ecosystem, heightened awareness of tax risks and responsibilities is considered non-negotiable across the tax function. Integrity is embedded in every action and decision related to tax planning, compliance, and reporting.

4. Engagement and dealings with tax authorities

The Company strives to maintain open, transparent, and constructive relationships with tax authorities across jurisdictions. Engagements with authorities whether in the context of assessments, audits, investigations, or litigation are conducted in a professional and cooperative manner, supported by accurate documentation and timely disclosures. Positions taken by the Company are well reasoned, technically supported, and aligned with applicable laws. To further strengthen the governance, the tax function leverages technology-based solutions to track compliance obligation, streamline processes, enhance efficiency, and manage risks, including review and escalation mechanisms. These tools support compliance monitoring, litigation management, and preparation of critical tax reports, enabling proactive risk identification and informed decision-making.

OUR APPROACH TO COMPLIANCE

We adhere to the regulatory compliances pertaining to all taxes including RPT as required by the various jurisdictions in which we operate. Our approach to some of the key requirements are as below:

Annual compliances: Tata Motor PV group of companies, continue to monitor and execute centrally the annual compliances with maker-checker review framework. Controllers and/or CFO review and approve basis controls designed and implemented around the tax functions. There are customised tools developed to monitor these controls that are continuously tested by in house teams and auditors.

Litigation mitigation: Our standard approach is to adopt well validated and strong tax positions on controversial or any tax adjustments. Endeavour remains to partner with the tax authorities at adjudication stage. The group may also enter into Advance Pricing Agreements (APAs) / Bilateral Advance Pricing Agreements (BAPA) where practical.

Litigation: Robust monitoring system includes centralized litigation repository. Further, the standard procedure involves representation through best of the counsels including senior counsels in appellate and court matters.

BEPS 1.0: CbCR is prepared centrally, with insights, review and approval by Group Controller. Masterfile is similarly developed centrally with similar review and approval mechanism being adopted.

BEPS 2.0: Tata Motors PV is currently working on Global Information Return (GIR) filing and adhering to Public CbCR requirements. Company has already initiated adherence to the various notification requirements in the countries that have adopted the above mandates.

RELATED PARTY TRANSACTIONS

Tata Motors PV as a group have multiple transactions not only amongst its various subsidiaries but also with other Tata Group entities. For example, information technology services are from Tata Consultancy, while distribution of its cars in Africa region is conducted through Tata International, both part of the Tata Group. However, for any such transaction, utmost care is taken to ensure that arm’s length principle is adhered to by the transacting entities within the Tata Motors PV group. We have adopted technology to ensure that such related party transactions are not conducted without an arm’s length policy in place that is vetted by professionals and basis materiality is also approved by the AC or the shareholders, as required under Securities Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015 (SEBI (LODR)), in India. The Company ensures continuous apprising of its team on the various changes and updates of the SEBI (LODR) as well as other country specific requirements to ensure that compliance requirements for all related party transactions are adhered to. In Indian context, the Company at the beginning of each financial year places all its related party transaction details including, transacting entity names, value of transaction and the arm’s length pricing policy for an ‘Omnibus’ approval to the AC. It has implemented the revised standard format as effective from September 2025 under the SEBI(LODR) requirement for reporting its related party transactions to the AC. The Company also reviews Omnibus versus actual transactions on a quarterly basis and changes, if any, are considered. New transactions are evaluated for arm’s length pricing before being concluded.

Further, we are monitoring the EU public disclosure of CbCR to ensure that the same is conformed to as required by a non-EU headquartered multinational. Globally, we also proactively reach out to tax authorities for negotiating APAs wherever it is a practical solution.

ADVOCACY AND RELATIONSHIP WITH REGULATORS

We at Tata Motors PV believe in open and transparent communication with all our stakeholders. Tata Motors PV considers regulators and government bodies as strategic stakeholders, not just compliance authorities. Engagement is designed to ensure full regulatory compliance, contribute to policy development, and align business growth with national priorities. Our approach to tax authorities and other industry regulators also endorses similar approaches.

Effective engagement with regulators enables Tata Motors PV to anticipate and adapt to regulatory changes early, reduce compliance and operational risks, influence progressive automotive and EV policy, maintain strong governance and ethical standards and support national priorities on safety, sustainability, and mobility.

This reinforces Tata Motors PV’s reputation as a responsible and trusted automotive manufacturer. Thus, the Tax Heads in India participate through industry bodies such as Society of Indian Automobile Manufacturers (SIAM), Confederation of Indian Industries (CII) as well as at Tata Group level for effective industry related advocacy.

In JLR and Tata Technologies Limited (TTL) entities too, stakeholder engagement is treated as a core governance and sustainability mechanism, risk management and social impact. The primary objective of engagement with government and regulators is to ensure compliance and contribute to policy development. The typical engagement mechanisms include direct dialogue with national and regional governments, participation in industry associations and consultations. This has resulted in proactive regulatory alignment and reduced compliance risk during business transformation.

We have been closely working with government and tax administrator on policy, administration and technology related issues. In the various other jurisdictions we operate, our approach to policy matters relating to our industry has been similar. We work with the local industry bodies and government to communicate our position on any policy decisions.

As far as tax authorities are concerned, we maintain an amicable relation basis our approach of paying the right amount of tax at the right time. However, there are at times certain interpretational issues that might result in litigations, which are usually addressed with help of external expert counsels. Wherever possible we also explore options of advance pricing arrangements both unilateral and bilateral.

In summary, Tata Motors PV engages regulators through structured consultations, industry representation, transparent compliance, and policy advocacy to ensure regulatory alignment, risk mitigation, and sustainable growth.

BACKGROUND

The Global Tax & Other Contributions summarized in this section provides the total payments made directly or indirectly to the Government. As a part of direct contributions, disclosures in relation to corporate tax, net indirect taxes, and other charges are aggregated for representation at each business group level. The indirect contributions include the payments made on behalf of other stakeholders to the Government, including withholding and payroll taxes. Other non-tax payments such as employer’s provident fund and employee pension scheme constitute the other contributions category.

Global tax & other contributions: Categories & examples of contributions

Direct contributions Corporate Tax

  1. Corporate Income Tax
  2. Surcharge and Cess
  3. Corporate Tax Credit and Incentives

Net Indirect Taxes

  1. Goods and Service Tax (GST)
  2. Custom Duties (all types)
  3. Value Added Tax (VAT)
  4. Sales and Use Tax

Other Charges

  1. Stamp Duty
  2. Property Tax
  3. Municipal Taxes
  4. Land Revenue
  5. Electricity Duties
  6. Apprenticeship Levy

Indirect contributions Withholding and Payroll Taxes

  1. Withholding Taxes Collected from employee/Payroll Taxes

  2. Withholding Taxes (WHT) collected from vendor

  3. Withholding Taxes collected from shareholder
  4. Tax Collected at Source (TCS) for Sale to Customers
  5. Professional Taxes
  6. Foreign Worker Levy
  7. Work Permit Levy

Other contributions

  1. Provident Fund
  2. Employee Pension Scheme
  3. Employee State Insurance
  4. Labour Welfare Fund
  5. National Insurance
  6. Social Security Fund
  7. Compensation Funds
  8. Disable Person Funds
  9. Gratuity Scheme
  10. Superannuation Scheme

GLOBAL TAX AND OTHER CONTRIBUTIONS FY26

₹32,574 Crores
Total Contributions
₹11,600 Crores
Indirect Contributions
₹19,518 Crores
Direct Contributions
₹1,456 Crores
Other Contributions

GLOBAL TAX AND OTHER CONTRIBUTIONS FY26

Tata Motors Limited

(Discontinued Operation) April to June 2025

Contributions (in Cr)
Total Contributions

Direct Contributions

Indirect Contributions

Other Contributions

2,322

1,987

287

48

GLOBAL TAX AND OTHER CONTRIBUTIONS FY25#

₹31,077 Crores

Total Contributions

₹ 9,620 Crores

Indirect Contributions

₹20,723 Crores

Direct Contributions

₹734 Crores

Other Contributions

GLOBAL TAX AND OTHER CONTRIBUTIONS FY25

# The comparative amounts have been presented as if, the Commercial Vehicles undertaking were discontinued in the prior period. Direct contribution excludes Stamp duty and Land Transfer charges accrued in books but not paid.

* Entity Schedule.

BASIS OF PREPARATION

Reporting entities

We have reported the Global Tax & Other Contributions to the Government by Tata Motors PV, our subsidiaries and joint operations (excluding associates and joint ventures). The contribution made by Tata Motors PV and its subsidiaries including branch offices are reported at full amounts and that for joint operations is reported in the proportion of shareholding. However, the entities which were liquidated/ demerged in the said financial year or are under process of liquidation or yet to commence operations or have insignificant operations as on March 31, 2026 have been excluded from reporting for that particular year, but if they have paid any taxes during the year, the entity has been considered for reporting. Further, certain foreign companies follow calendar year basis in multiple tax compliances, whereas our reporting period is April to March. Accordingly, for this reporting, the contributions paid as per our reporting period of April to March have been considered. The entire list of entities at business group level considered in this report has been included in the Entity Schedule.

METHODOLOGY

We have reported Global Tax & Other Contributions under cash basis unless otherwise mentioned below. The reporting methodology followed for each type of Global Tax & Other Contributions has been detailed below.

DIRECT CONTRIBUTIONS

Corporate tax

This comprises Corporate Income Tax. These taxes are the actual payments made net of refunds (including interest) received during the financial year with respect to corporate income tax liability of the same year and/or of previous years. Typically, these taxes would be reflected in various statutory periodic forms/returns and statements/challans or any other documents being filed with the relevant government authorities, or audited cash flow statements, or bank statements evidencing the payments or statements from third party payment partners honouring the obligations.

OTHER TAXES AND CHARGES

This comprises stamp duty, property tax, land revenue, municipal tax, electricity duty borne (including cross subsidy surcharge paid), and any other similar contribution by the Company and its subsidiaries. The same have been compiled based on payments to the Government exchequer and/ or challans and bank statements.

NET INDIRECT TAXES

Amounts reported represent indirect tax payments remitted to the Government on cash basis. Indirect tax payments made for reverse charge liability and on imports paid in cash form part of the amount reported. However, it may be noted that the payment of taxes on procurements paid to vendors have not been considered here. Typically, the amounts reported under net indirect taxes have been obtained from various statutory periodic forms/ returns and statements/ challans/ relevant Government portals or any other documents being filed and maintained with the relevant Government authorities.

INDIRECT CONTRIBUTIONS

Indirect contributions include tax deducted at source (withholding taxes) from vendors and employees, taxes collected from customers and other payroll taxes. A withholding tax is an income tax to be paid to the Government by the payer of the income rather than by the recipient of the income. The tax is thus withheld or deducted from the income due to the recipient. Withholding taxes usually apply to payments made to employees, vendors, service providers, etc., of the Company. This also includes taxes collected on various payments received from customers for prescribed goods or services. In addition, payroll taxes include professional and work permit levies that are withheld from employee remuneration and paid to the Government by the respective companies in the capacity of an employer. Typically, these taxes are reflected in various forms, returns, statements and challans prescribed or approved by the Government for this purpose.

OTHER CONTRIBUTIONS

Other contributions include contributions made by the employer to social security programmes for the benefit of employees as mandated by regulatory bodies. This includes the employer’s share in provident fund, including national insurance, employee pension scheme, social security and employee state insurance. Typically, these contributions are reflected in the returns, statements and challans prescribed or approved by the concerned statutory bodies for this purpose.

COVERAGE

The various heads of contributions are summarised in this report. The grouping of taxes under the heads of ‘Direct Contributions’, ‘Indirect Contributions and ‘Other Contributions’ is based on our understanding of the nature of taxes and its payment mechanism. Where date of actual cash inflow/outflow was not available, the tax payments shown as due in the relevant tax period has been considered for reporting.

Global tax and other contributions

Direct Contribution

Corporate Tax

  1. Corporate Income Tax
  2. Surcharge and Cess
  3. Corporate Tax Credit and Incentives

Net Indirect Taxes

  1. Goods and Service Tax (GST)
  2. Custom Duties (all types)
  3. Value Added Tax (VAT)
  4. Sales and Use Tax

Other Charges

  1. Stamp Duty
  2. Property Tax
  3. Municipal Taxes
  4. Land Revenue
  5. Electricity Duties
  6. Apprenticeship Levy

Indirect contributions

Withholding and Payroll Taxes

  1. Withholding Taxes Collected from employee/Payroll Taxes
  2. Withholding Taxes (WHT) collected from vendor
  3. Withholding Taxes collected from shareholder
  4. Tax Collected at Source (TCS) for Sale to Customers
  5. Professional Taxes
  6. Foreign Worker Levy
  7. Work Permit Levy

Other contributions

  1. Provident Fund
  2. Employee Pension Scheme
  3. Employee State Insurance
  4. Labour Welfare Fund
  5. National Insurance
  6. Social Security Fund
  7. Compensation Funds
  8. Disable Person Funds
  9. Gratuity Scheme
  10. Superannuation Scheme

Excluded amounts

The following are not included in the Global Tax & Other Contributions statement:

  •  Payment of indirect taxes on procurements paid to vendors
  • Any fees paid to the government and its authorities for various kinds of compliance, filings, penalties etc.

Currency

The currency considered for this report or the reporting currency is the Indian Rupee (₹). The data for Global Tax & Other Contributions to Government provided by any subsidiary in their local reporting currency, has been converted to ₹ based on the exchange rate that has been considered in preparation of Form AOC-01.

Independent Reasonable Assurance Report

Independent Reasonable Assurance Report to Tata Motors Passenger Vehicles Limited on Global Tax & Other Contributions

We (Name) were engaged by the management of Tata Motors Passenger Vehicles Limited (Formerly Tata Motors Limited) (‘Tata Motors PV’ or ‘the ‘Company’) to report on ‘Global Tax & Other Contributions’ section contained in the Company’s Tax Transparency Report for the financial year 2025-26 [the said section hereinafter referred to as ‘Global Tax & Other Contributions’], in the form of an independent reasonable assurance conclusion about whether Tata Motors PV statement that the Global Tax & Other Contributions is properly prepared, in all material respects, based on ‘Basis of Preparation’ attached to the Tax Transparency Report is fairly stated.

Tata Motors PV responsibilities

The management of Tata Motors PV are responsible for preparing the Global Tax & Other Contributions that is free from material misstatement in accordance with the Basis of Preparation and for the information contained therein. The management of Tata Motors PV is also responsible for preparing the Basis of Preparation. This responsibility includes designing, implementing and maintaining internal control relevant to the preparation and presentation of Global Tax & Other Contributions that is free from material misstatement, whether due to fraud or error. It also includes developing the Basis of Preparation. The Company is also responsible for preventing and detecting fraud and for identifying and ensuring that it complies with laws and regulations applicable to its activities.

Our responsibilities

Our responsibility is to examine the Global Tax & Other Contributions prepared by the Company and to report thereon in the form of an independent reasonable assurance conclusion based on the evidence obtained.

We conducted our engagement in accordance with International Standard on Assurance Engagements (ISAE) 3000: Assurance Engagements Other Than Audits or Reviews of Historical Financial Information issued by the International Auditing and Assurance Standards Board. That standard requires that we plan and perform our procedures to obtain reasonable assurance about whether the Global Tax & Other Contributions is properly prepared, in all material respects.

(Name) applies International Standard on Quality Control 1 and accordingly maintains a comprehensive system of quality control including documented policies and procedures regarding compliance with ethical requirements, professional standards and applicable legal and regulatory requirements.

We have complied with the independence and other ethical requirements of the Code of Ethics for professional accountants issued by the International Ethics Standards Board for Accountants, which is founded on fundamental principles of integrity, objectivity, professional competence and due care, confidentiality and professional behaviour. The procedures selected depend on our judgment, including the assessment of the risks of material misstatement of Global Tax & Other Contributions whether due to fraud or error. In making those risk assessments, we have considered internal control relevant to the preparation and presentation of Global Tax & Other Contributions in order to design assurance procedures that are appropriate in the circumstances, but not for the purposes of expressing a conclusion as to the effectiveness of the Company’s internal control over the preparation and presentation of Global Tax & Other Contributions. Our engagement also included assessing the appropriateness of Global Tax & Other Contributions, the suitability of the Basis of Preparation used by the Company in preparing the Global Tax & Other Contributions in the circumstances of the engagement, evaluating the appropriateness of the procedures used in the preparation of Global Tax & Other Contributions and the reasonableness of estimates made by the Company and evaluating the overall presentation of the Global Tax & Other Contributions. Reasonable assurance is less than absolute assurance.

The procedures performed by us have been included herein as Annexure – Assurance procedures – Global Tax & Other Contributions.

CONCLUSION

Our conclusion has been formed on the basis of, and is subject to, the matters outlined in this report. We believe that the evidence we have obtained is sufficient and appropriate to provide a basis for our conclusion. In our opinion, the Global Tax & Other Contributions is properly prepared in all material respects, based on the Basis of Preparation.

Restriction of use of our report

In accordance with the terms of our engagement, this independent reasonable assurance report on Global Tax & Other Contributions has been prepared for the Company solely for inclusion in its Tax Transparency Report for the financial year 2025-26 and for no other purpose or in any other context.

Our report should not be regarded as suitable to be used or relied on by any party wishing to acquire rights against us other than the Company for any purpose or in any context.

Any party other than the Company who obtains access to our report or a copy thereof and chooses to rely on our report (or any part thereof) will do so at its own risk. To the fullest extent permitted by law, we accept or assume no responsibility and deny any liability to any party other than the Company for our work, for this independent reasonable assurance report, or for the conclusions we have reached. Our report is released to Tata Motors PV on the basis that it shall not be copied, referred to or disclosed, in whole (save for inclusion in Tata Motors PV Tax Transparency Report) or in part, without our prior written consent.

Annexure – Assurance Procedures – Global Tax & Other Contributions

  • Understand and examine the processes and controls at Tata Motors PV level in managing, collating and reviewing the data for the Global Tax & Other Contributions
  • Review the guidance provided/ instructions issued to locations / units / group entities by central team for their collation of various tax and other specified items
  • Review the country wise break-up of the tax and other specified items reported in the Global Tax & Other Contributions
  • Understand and examine the processes and controls at local country level for collation of tax and other specified items included in Global Tax & Other Contributions. This will include review of:
    O reporting to central team to ensure adherence of the guidance provided by the central team
    O processes for ensuring that all local country taxes are included within the reporting to central team
  • Review the basis on which the country level tax and other specified data reported has been captured, reviewed and consolidated to assess whether the data has been collected, consolidated and reported fairly
  • For the countries selected, perform trend analysis on the tax and other specified data for the reporting period to understand any material variances. Seek explanations for variances, if any
  • For the countries selected, verify the tax paid (on a sample basis) to the underlying documents
  • Compare the tax and other specified data in the report to the relevant disclosures in the consolidated financial statements for the reporting period.

Accounting For Damage To An Integrated Factory Under Construction

Under Ind AS 16 and Ind AS 36, damage to an asset under construction and its subsequent reinstatement are treated as separate economic events that cannot be netted off or automatically capitalised into Capital Work-in-Progress.

Accounting requires a four-step evaluation:

  1. Derecognise the lost asset’s carrying amount immediately as a P&L expense.
  2. Test remaining assets for impairment under Ind AS 36.
  3. Capitalise reconstruction costs if directly attributable, while expensing abnormal wastage to P&L.
  4. Recognise insurance compensation separately in P&L when receivable.

These principles apply even to integrated or turnkey projects.

BACKGROUND AND CORE ISSUE

When a company constructs a large integrated manufacturing facility and an unforeseen incident destroys an individual unit of the integral plant before commercial production begins, the fundamental accounting question arises: Is the destruction merely another construction cost to be accumulated in Capital Work-in-Progress (CWIP), or does it constitute a separate economic event requiring independent accounting treatment?

A common misconception is that all costs incurred prior to commercial operation must be capitalised. Under Indian Accounting Standards (Ind AS), this automatic accumulation is incorrect. The framework requires clear segregation between the derecognition/impairment of the original asset, the capitalisation of replacement costs, and the recognition of third-party insurance compensation.

THE PRINCIPLE OF SEPARATE ECONOMIC EVENTS

As per Paragraph 66 of Ind AS 16 (Property, Plant and Equipment), impairments or losses of items, related insurance claims/compensation, and subsequent purchases or construction of replacement assets are separate economic events and must be accounted for separately:

  •  Derecognition/Loss: Handled under Ind AS 16 (Paragraph 67) / Ind AS 36.
  •  Insurance Proceeds: Recognised in profit or loss when receivable (Ind AS 16, Paragraph 65).
  •  Replacement Costs: Evaluated independently for capitalisation (Ind AS 16, Paragraphs 7 & 16).

This principle is supported by the ICAI Expert Advisory Committee (EAC) Opinion (Vol. XLV, Query finalised on 29 Jan 2026), which confirms that pre-commissioning asset damage and subsequent reinstatement are separate events that cannot be netted off or blindly added back into project costs.

FOUR-STEP ACCOUNTING EVALUATION

Accounting for Construction Calamities

1. Derecognition of the Destroyed Asset

  •  Ind AS Reference: Ind AS 16, Paragraph 67(b) & Paragraph 68.
  •  Treatment: The carrying amount of an item of PPE (or an identifiable component/CWIP balance) must be derecognised when no future economic benefits are expected from its use or disposal.
  •  Application: The fact that the factory is under construction does not justify retaining the lost asset’s cost in CWIP. If the carrying value of the specific damaged unit cannot be separately identified, a reasonable and supportable allocation method must be used to calculate and write off the lost carrying amount (Ind AS 16, Paragraph 70). The write-off is recognised as an expense in the statement of profit and loss.

2. Impairment Testing of Remaining Assets

  •  Ind AS Reference: Ind AS 16, Paragraph 63; Ind AS 36 (Impairment of Assets), Paragraphs 9 & 12.
  •  Treatment: The damage incident serves as an impairment indicator for the remaining assets and the overall project/Cash-Generating Unit (CGU).
  •  Application: Even though commercial production has not commenced, the entity must apply Ind AS 36 to evaluate whether reduced future cash flows, project delays, or increased completion
    costs require an immediate impairment loss write-down in Profit or Loss. As affirmed by the above-referred EAC, the lack of commissioning does not exempt an entity from Ind AS 36 testing.

3. Cost of Reconstruction

  •  Ind AS Reference: Ind AS 16, Paragraphs 7,16(b), & 22.
  •  Treatment: Reconstruction expenditure represents the creation of a replacement asset and is tested independently against capitalization criteria.
  •  Directly Attributable Costs: Costs directly attributable to bringing the replacement unit to the location and condition necessary for its operation are capitalised (Paragraph 16(b)).
  •  Abnormal Wastage Exclusion: Paragraph 22 explicitly excludes abnormal amounts of wasted material, labour, or other resources from the cost of a self-constructed asset. Rather, these are recognised as an expense in the statement of profit and loss. As highlighted in the above-referred EAC opinion, management must exercise judgement to distinguish between inherent, expected execution costs and abnormal inefficiency losses (which must be expensed immediately).

4. Insurance Compensation

  •  Ind AS Reference: Ind AS 16, Paragraph 65 & 66(c).
  •  Treatment: Third-party compensation for impaired or lost assets must be recognised as income in the statement of profit and loss when it becomes receivable.
  •  Netting-Off Prohibited: Insurance proceeds cannot be netted directly against reconstruction costs or deducted from the cost of the replacement asset.

NUMERICAL ILLUSTRATION

  •  Carrying amount of destroyed unit: ₹100 crore
  •  Reconstruction cost incurred: ₹140 crore
  •  Insurance claim receivable: ₹120 crore

CORRECT ACCOUNTING TREATMENT:

  1.  Write off lost asset to P&L / Impairment: ₹100 crore (Loss)
  2.  Capitalise qualifying replacement cost to CWIP: ₹140 crore (Asset, assuming entire amount meets capitalisation criteria)
  3.  Recognise insurance claim when receivable in P&L: ₹120 crore (Income)

(Net P&L impact: +₹20 crore gain, subject to timing & terms). An entity needs to write off / derecognise lost asset as well as recognise impairment loss immediately on occurrence of loss event. However, it may so happen that insurance claim does not meet criteria for recognition of income in the same period and its recognition may need to be deferred to a subsequent period. This is likely to create a significant volatility in the statement of profit and loss.

Incorrect Treatment (Prohibited):

Netting off costs: ₹140 crore – ₹120 crore = Capitalise ₹20 crore net to CWIP.

IMPACT OF FACTORY INTEGRATION

Even if Unit A cannot function without Unit B, or if the entire project is constructed under a single Lump Sum Turnkey framework, standard accounting principles remain unchanged. Project interdependence does not alter the underlying economic reality of asset destruction. Distinguishing original costs, abnormal damage losses, and replacement expenditures ensures transparent financial reporting and prevents the improper hiding of abnormal losses within CWIP.

CONCLUSION

When a unit under construction is destroyed, Ind AS 16 and Ind AS 36 require a clear separation of economic events:

  1.  Derecognise or write down the destroyed original asset or portion of the original asset.
  2.  Assess remaining project assets for impairment under Ind AS 36.
  3.  Capitalise only qualifying directly attributable reconstruction costs (excluding abnormal wastage) under Ind AS 16. Abnormal wastage should be charged immediately to the P&L account.
  4.  Recognise insurance claims independently in Profit or Loss when receivable.

Recent Decisions in GST

I. SUPREME COURT

53. (2026) 45 Centax 331 (S.C.)

G.R. Infra Projects Ltd. Vs State of Madhya Pradesh Dated 19.08.2026

Section 74 of the CGST Act cannot be invoked mechanically to overcome GST Limitation Period specified under Section 73 of the CGST Act without substantiating and justifying the basis for allegations of fraud, wilful misstatement or suppression of facts in SCN

FACTS

The Appellant was engaged in the business of construction of roads and highway projects. Summons was issued to the Appellant, and business premises were searched. Thereafter, intimation in DRC-01A was issued based on draft notice-cum-investigation report, against which Appellant filed its response objecting the demand. However, Department straightaway issued SCN under Section 74 of CGST Act alleging that the Appellant was involved in fraud, wilful misstatement, or suppression of facts without specifying any particular act or material substantiating such allegations. The Appellant challenged this SCN by filing a petition before the Hon’ble High Court on the ground that Section 74 was incorrectly invoked, and proceedings fall under Section 73 would be barred by limitation. The Hon’ble High Court dismissed the petition and decline to interfere at the SCN stage. Being aggrieved by the decision of the Hon’ble High Court, the Appellant preferred appeal against the said order before the Hon’ble Supreme Court.

HELD

The Hon’ble Apex Court held that SCN issued under Section 74 of the CGST Act must itself specify proper basis and cogent material for alleging fraud, wilful misstatement and suppression of facts in the SCN, and cannot be supplanted by another notice subsequently. It further highlighted that mere reproduction of words such as fraud, wilful misstatement or suppression of facts is insufficient to mechanically invoke extended period of limitation and justify issuance of SCN under Section 74. Accordingly, the Apex Court decided the issue in favour of the Appellant, and set aside the proceedings initiated against vide the said SCN.

Note: On similar lines, the Hon’ble Apex Court in the case of Tata Steel Ltd. Versus Union Of India (2026) 45 Centax 361 (S.C.) dated 25.08.2026 held that extended period of limitation under Section 74 cannot be invoked mechanically where SCN itself fails to expressly justify the presence of essential elements of fraud, wilful misstatement and suppression of facts. However, in this case, recognising the Supreme Court’s suo-motu order in Re:Cognizance of Extension of Limitation, which excluded period 15-03-2020 to 28-02-2022, the Show Cause Notice issued on 13-06-2025 was found to be beyond the extended period. However, the Hon’ble Court allowed the department liberty to issue a fresh Show Cause Notice under section 74 with proper foundational facts, provided the order is passed before 28-02-2027.

II HIGH COURT

54. (2026) 45 Centax 217 (Guj.)

Torrent Power Ltd. Vs Union of India

Dated 14.08.2026

Corporate Guarantee issued during the period prior to 26-10-2023 not impacted as insertion of Rule 28(2) of the CGST Rules, 2017 prescribing Valuation Mechanism would not have retrospective operation Deemed value of supply of 1% of Corporate Guarantee given would not apply where actual consideration charged is lower as “Whichever is Higher” in Rule 28(2) was read down

FACTS

The Petitioner had given Corporate Guarantees for its subsidiaries to banks and various financial institutions without consideration. The Department issued a SCN under Section 74 alleging that such corporate guarantees executed between the related parties as taxable supply, and demanded GST by considering value of supply as 1% of Total Guarantee given as per Rule 28(2) of the CGST Rules, 2017 introduced through Notification No. 52/2023-Central Tax dated 26.10.2023. Aggrieved, the petitioner filed a writ petition before the Hon’ble High Court challenging the applicability and retrospective operation of the valuation mechanism of 1% of amount guaranteed as per Rule 28(2) of the CGST Rules, 2017.

HELD

The Hon’ble High Court held that corporate guarantee furnished between related parties would constitute supply as per Section 7(1)(c) read with Entry 2 of Schedule I of the CGST Act, 2017 even where no consideration is charged. Further, the Court held that the expression “whichever is higher” in Rule 28(2) of CGST Rules, 2017 was read down as arbitrary to the extent that it denied the corporate guarantor the option to discharge GST on the actual consideration charged. With regard to retrospective operation of Rule 28(2), the Court held that GST levied on corporate guarantees prior to 26.10.2023 as per Rule 28(2) was harsh and unjust being disruptive of the legal and financial position of the then prevailing law and thereby violative of Article 14 and 19(1)(g) of the Constitution of India. Accordingly, the impugned proceedings were set aside, and the notice was quashed to the extent it was challenged.

55. (2026) 44 Centax 110 (Kar.)

GR Tech Services Pvt. Ltd. Vs Assistant Commissioner of Commercial Taxes

Dated 03.06.2026

When IGST was wrongly paid instead of CGST and KGST, the same can be adjusted against payment of correct CGST and KGST without levy of any interest or penalty

FACTS

The Petitioner had inadvertently treated intra-state supply as inter-state supply, and accordingly charged IGST instead of CGST and SGST. Thus, the Petitioner had disclosed and paid IGST liability in its returns resulting in excess payment of IGST and short payment of corresponding CGST and KGST liability. During audit, the Respondent contended that the Petitioner had to first discharge CGST/KGST along with interest and penalty, and thereafter claim refund of the IGST already paid. Subsequently, the proceedings under Section 73 of the CGST Act, 2017 were initiated, and tax, interest and penalty were confirmed in the Adjudicating Order. Thereafter, proceedings for recovering CGST and SGST was initiated. The Petitioner filed an appeal against the Adjudication Order, which was dismissed on the ground of limitation. On the other hand, the Petitioner’s refund claim for IGST was also rejected on the ground that the refund was sought before the payment of CGST/KGST. Being aggrieved, a writ was filed before the Hon’ble High Court.

HELD

The Court examined the facts of the case, and based on its perusal of Section 77(2) of the CGST Act, 2017 read with Rule 92 of the CGST Rules, 2017, held that IGST paid instead of CGST/SGST cannot be subject to interest and penalty. Further, the Court by relying upon the decision of Kerala High Court in the case of Saji S. Vs Commissioner, State GST Department (2018 (19) GSTL 385 (Ker.), asked the authorities to consider the adjustment of IGST paid against CGST/KGST payable and remanded the matter for reconsideration on merits.

56. (2026) 46 Centax 29 (Bom.)

IBM India Pvt. Ltd. Vs Union of India

Dated 28.08.2026

Refund of proportionate pre-deposit paid at the time of filing Appeal ought to be granted where corresponding demand was partially dropped irrespective of whether the balance disputed demand is appealable further or not

FACTS

The Petitioner received an order passed by the Adjudicating Authority confirming GST demand to the extent of Rs. 48.96 Crores. The Petitioner filed an appeal against the said order where demand to the extent of Rs 31.45 Crores approximately was dropped, while sustaining the balance demand. The Petitioner filed a Refund application for the corresponding pre-deposit amount approximately to the extent of Rs. 3.14 Crores i.e. 10% of the demand reduced by Appellate Authority (31.45 Crores). However, the Department rejected the refund application stating the Petitioner’s proposed further appeal against the remaining demand. Aggrieved by such rejection of refund claim, the petitioner filed a writ petition before the Hon’ble High Court.

HELD

The High Court held that the pre-deposit amount paid was only in the form of security deposit which was a pre-requisite for hearing an Appeal, and cannot be categorized as tax. The Court further held that once the partial relief is granted by way of reduced demand in Appellate Order, the Respondent is liable to refund the proportionate amount of pre-deposit. Accordingly, the High Court allowed the writ petition in favour of the Petitioner.

57. [2026] 190 taxmann.com 365 (Delhi)

Neha v. Union of India

Dated: 08.09.2026

Hon’ble Delhi High Court issued instructions to authorities nationwide not to allow any GST registration without mandatory biometric-based AADHAR authentication to prevent revenue loss and harassment of innocent persons by misuse of the identity.

FACTS

The issue before the Hon’ble Court was regarding fraudulent GST registration by some other person by using the PAN Card and Aadhaar Card numbers of the petitioner. The Petitioner placed on record certain suggestions for curbing the misuse of PAN Card and Aadhaar Card particulars of innocent persons for obtaining fraudulent GST registrations such as mandatory Aadhaar facial-recognition authentication, video KYC with PAN, Aadhaar and live prompt, IP address and device-location audit trail, pre-registration or risk-based physical verification, real-time PAN-use alerts and income-tax data matching, automated flagging of abnormal turnover spikes, Aadhaar-holder confirmation of GST registration, DigiLocker-based consent and registration alerts, DGARM risk parameters for first time use of PAN/Aadhaar for GST, Nomination of identifiable business corroborators etc.

HELD

The Hon’ble Court observed that even after a lapse of nine years, the Departmental machinery have failed to curb such malpractices, which not only affect citizens who have nothing to do with such GST registrations, but also result in huge loss to the Government. The Court noted that there were 2800 fraudulent GST Registrations obtained by using stolen or frozen PAN/AADHAR details involving detection of Rs.15,085 Crores of tax evasion.

It further observed that at present, biometric-based AADHAR authentication is carried out only if the system identifies the case as ‘risky’ on the basis of various parameters and data analytics, and held that respondents have failed to draw the attention of the court to any difficulty in mandating the biometric-based AADHAR authentication of the GST Registration. Accordingly, as an interim measure, the Hon’ble Court issued directions to all the authorities across the country not to allow any GST Registration without biometric-based AADHAR authentication henceforth with a liberty to the authorities to file objections qua any practical difficulty in its implementation.

III GST APPELLATE TRIBUNAL (GSTAT)

58. (2026) 45 Centax 389 (Tri. -GST-Kolkata)

Commissioner, CGST & CX, Kolkata North Vs Powertech Global Pvt. Ltd

Dated 05.08.2026

Section 74 cannot be invoked for demanding reversal of ITC under Rule 42/43 for past periods where sale of Duty Credits was specifically excluded from treating it as exempt supply for common credit reversal computation w.e.f. 05.07.2022 especially where appropriate disclosure under exempt supply were made in GST Returns

FACTS

The Respondent was engaged in the business of manufacture and export of electronic apparatus and equipment. It had not reversed ITC proportionately to the extent of outward exempt supply i.e. sale of MEIS Duty Credit Scrips during FY 2017-18 to FY 2019-20. Department issued SCN under Section 74 alleging that proportionate ITC was not reversed which was attributable to sale of Duty Credit Scrips under section 17(2) of the CGST Act, 2017 read with Rules 42 and 43 of the CGST Rules, 2017. Thereafter, an Order was passed under Section 74 confirming the above demand on account of non-reversal of ITC. The Petitioner filed an appeal against the Adjudication Order, where the demand was set aside on the ground that Sale of Duty Credit Scrips was specifically excluded from the aggregate value of exempt supplies in the computation of ITC Reversal as per Rule 42/43 by virtue of Notification No. 14/2022-CT dated 05.07.2022. Aggrieved by the appellate order, the Revenue preferred an appeal before the Hon’ble GST Appellate Tribunal.

HELD

The GST Appellate Tribunal held that the specific exclusion of Sale of Duty Credit Scrips from the aggregate value of exempt supplies while computing ITC Reversal as per Rule 42/43 was applicable prospectively from 05.07.2022, and could not be applied to prior periods. However, it was further observed that, Section 74 of CGST Act could not be invoked in this case as all the details of sale of Duty Credit Scrips were furnished by the Respondent in its GST Returns and the Appellant had failed to establish suppression of facts on the part of the Respondent. Consequently, the matter was remanded back, and required to be dealt with provisions of Section 73 of the CGST Act, 2017 after giving the appellant opportunity of being heard.

59. [2026] 190 taxmann.com 508 (GSTAT – BENGALURU)

I-NXT v. Sandeep Banga, Commissioner, Bengaluru Zone

Dated :15.09.2026

Mere ITC mismatch between GSTR-3B and GSTR-2A, when tax and interest are paid before SCN and the discrepancy arises from supplier-side default, does not establish fraud, wilful misstatement or suppression so as to invoke Section 74 or sustain a 100% penalty. Demonstrable nexus between the mismatch and deliberate non-disclosure by the recipient absent.

FACTS:

The genesis of the dispute was the information gathered by the officers of the anti-evasion wing, as a result of which the allegation of mismatch was made between the ITC claimed in Form GSTR-3B returns and the ITC available in Form GSTR-2A. The Assessee admitted the factum of excess availment of ITC but the same was due to oversight. It was further stated that the excess ITC was not utilised. The Appellant also paid tax before issuance of the SCN. Still, the Adjudicating Authority issued a show cause notice invoking the extended period of limitation under Section 74 of the Act alleging that the Appellant had suppressed the fact of excess availment of input tax credit in the Form GSTR-3B returns in contravention of the provisions of the Act and the rules, and that the payment of tax was made only as a result of verification conducted by the officers of the anti-evasion wing.

The Appellant contested the invocation of extended period and Section 74 before the First Appellate Authority, however, the Order held that the Assessee had paid the excess ITC amount only on being pointed out by the Department. It further held that the Assessee had not declared the fact of excess availment of ITC to the Department, and that there was a clear case of suppression of facts. The Appellate Authority, thus, confirmed the penalty at 100% of the tax as the Appellant had not paid the penalty at 15% of the tax, as required under Section 74 of the Act.

HELD

Relying on Tata Steel Ltd. v. Union of India [2026] 189 taxmann.com 520 (SC), the Hon’ble Tribunal held that the existence of mismatch can enable a proper officer to determine the tax liability under Section 73 but for the purpose of invoking Section 74, some thing more has to be done by the proper officer, and that there must be a clear link between the mismatch and the alleged fraud, wilful mis-statement or suppression of facts and mere use of the language is not enough.

It further observed that Sections 73(5) and 74(5) permit the person chargeable with tax to pay the tax along with interest before issue of a show cause notice. The term “the tax as ascertained by the proper officer” recognises the fact that the proper officer can point out the omission during an audit or verification, and once the tax payer accepts the officer’s ascertainment and pays tax along with interest, Section 73(6) mandates that the proper officer shall not serve any notice.

Regarding the charge of suppression, the Hon’ble Bench held that the term “suppression” is defined in Explanation 2 in section 74 as meaning non-declaration of facts or information which a taxable person is required to declare in the return, statement, report or any other document furnished under this Act or the rules made thereunder, or failure to furnish any information on being asked for, in writing by the proper officer”. However, for this to apply, there must be deliberate non-disclosure of facts or information in any return, statement, report or any other document required to be furnished by the tax payer under the Act or in case of failure to furnish any information by the tax payer. The Tribunal noted that in the present case, suppression was alleged on the ground of mismatch and not non-disclosure. Tribunal further noted that the excess availment of ITC was not due to default committed by the Appellant but by the third-party supplier, and accordingly held that default by a third-party supplier cannot be attributed to the appellant to sustain the charge of suppression.

The Hon’ble Tribunal accordingly set aside the Order-in-Appeal holding that in this case, the Adjudicating Authority and the Appellate Authority have not established any link between the mismatch and alleged suppression of facts, and that there was no dispute about the genuineness of the transaction or the suppliers.

60. [2026] 190 taxmann.com 509 (GSTAT – BENGALURU)

Conduent Business Services India LLP v. Commissioner of Central Tax Bengaluru East GST Commissionerate Dated :15.09.2026

Institutional hierarchy does not meet the “real danger of bias”. The routine audit discoveries under Section 65 do not automatically trigger extended limitation. When all records are with the GST Department and facts are known to both parties or are accessible via statutory records, non-disclosure does not amount to suppression.

FACTS

Audit proceedings were initiated against the appellant which resulted in a show cause notice issued under Section 74 in respect of three issues to the Appellant. The Adjudicating Authority confirmed agreed tax/interest, dropped Section 74 penalty for Issues 1 & 3, but confirmed penalty for Issue 2. The Appellant deposited 50% reduced penalty under Section 74(11) via Form GST DRC-03. The Revenue challenged the dropping of Section 74 penalty for Issues 1 & 3 pursuant to a Review Order passed by the Commissioner. The First Appellate Authority allowed Departmental Appeal and imposed Section 74 penalty on Issues 1 & 3. Before the Hon’ble Tribunal, the Appellant also challenged that the appellate proceedings before the First Appellate Authority were vitiated by an inherent institutional bias stating that the First Appeal before the Joint Commissioner (Appeals) was instituted pursuant to a Review Order passed by an officer of the higher rank of Commissioner of Central Tax. Hence, the hearing of the appeal by a subordinate officer—the Joint Commissioner (Appeals)—reeks of institutional prejudice.

HELD:

The Hon’ble Tribunal rejected the allegation of bias against the First Appellate Authority, relying upon the landmark decision of State of Punjab v. V.K. Khanna (2001) 2 SCC 330 to hold that institutional hierarchy does not meet the “real danger of bias”. As regards to the merits of the case viz, confirmation of penalty under Section 74 by the First Appellant Authority, the Hon’ble Tribunal held that Section 74 is an extra-ordinary jurisdiction and the statute deliberately conditions this power upon the existence of specific, positive mens rea elements: fraud, willful misstatement, or suppression of facts with intent to evade tax. In absence of these specific elements, any tax shortfall falls strictly within the domain of Section 73. Applying the ratio in Tata Steel Ltd. v. Union of India [2026] 189 taxmann.com 520 (SC), it held that the OIO contained explicit, categorical findings of fact that all records, including GSTR-3B, GSTR-2A, and TRAN-1 declarations, which were fully available on the Departmental portal. There is no positive act of deliberate suppression or intentional misstatement alleged or established against the Appellant. It further held that the mechanism under Section 74 requires independent satisfaction of mens rea; issuance of an SCN under Section 74 does not automatically bind the adjudicator to confirm penal liabilities where deliberate intent is absent. The Tribunal further held that routine audit discoveries under Section 65 do not automatically trigger extended limitation or penal provisions, and judicial precedents firmly establish that audit detection without proof of an active, deliberate intent to evade tax cannot sustain charges under Section 74. Thus, when facts are known to both parties or are accessible via statutory records, non-disclosure does not amount to suppression. The Tribunal further held that where tax and interest are fully discharged prior to the SCN, and where allegations of fraud or suppression are unsustainable, the statutory mechanism under Section 73(5) read with Section 73(8) come into operation whereby the statutory scheme intends to grant immunity from penalty to taxpayers who settle their tax and interest obligations prior to formal adjudication, provided there is no deliberate intent to evade. The imposition of Section 74 penalties was thus held to be unsustainable.

61. [2026] 190 taxmann.com 596 (GSTAT -ERNAKULAM)

Tiger Steels vs Commissioner of State Tax

Dated: 16.06.2026

Any violation of the mandated time limit for issuing order specified in Section 129(3) of the CGST Act by the proper officer vitiates the entire proceedings and such delayed order is void ab initio.

FACTS

The Department intercepted the vehicle and issued order dated 28.06.2019 under Section 129 of the Central Goods & Service Tax Act (SGST & CGST Act) demanding tax and penalty for the release of the goods on the ground that the validity of the e-way bill which accompanied the consignment had expired on 25.06.2019. The Appellant remitted the amount demanded in the order by way of a bank guarantee and got the vehicle and goods released. The State Tax Officer, after the release of the goods, conducted adjudication as provided under Section 129 (1) of the SGST Act and initiated steps to invoke the bank guarantee. No order was communicated to the Appellant. The Appellant approached the Hon’ble High Court of Kerala, which directed the department to issue copy of the adjudication order to the Appellant, and also directed the State Tax Officer not to invoke the bank guarantee till the period of 4 weeks. The Appellant filed appeal before the first Appellate Authority, which was dismissed, and hence this appeal.

HELD

The Hon’ble Tribunal held that in terms of Section 129(3), it is mandatory on the part of the officer detaining or seizing the goods to pass an order for payment of penalty within seven days of the date of service of the notice. However, in this case, while the notice was issued on 28.6.2019, the order under Section 129(3) for payment of penalty was issued only on 26.7.2019, 28 days after the issue of notice. The Hon’ble Tribunal thus held that this blatant violation of statutory time lines renders the impugned Order void ab initio and nullity in the eyes of the law. The Hon’ble Tribunal referred to a number of precedents, and held that any violation of the mandated time limit specified in Section 129(3) of the CGST Act by the proper officer vitiates the entire proceedings. The Tribunal thus set aside the said order on the grounds of non-adherence to statutory time limits by the authority passing such order.

Recent Developments in GST

A. GSTN

(a) GSTN has issued Advisory dated 07.09.2026 informing about enabling of filing of appeals for cases involving NIL or Zero demand.

B. ADVANCE RULINGS

31. Feel Good Hospitality Pvt. Ltd. (AAR Order No. 05/WBAAAR/2026-27 dt.07.08.2026) (WB)

Pure Agent – Mandatory conditions need to be fulfilled

The facts are that the applicant, presently engaged in the restaurant business, proposes to expand its business operations by undertaking travel and accommodation booking agency services. In this category, it will act as a facilitator for arranging hotel accommodation for end customers through third-party agents. Under the proposed business model, the applicant intends to recover the actual cost of hotel accommodation from the customer as reimbursement, and separately charge a facilitation or service fee for arranging the booking. In this background, the applicant has raised question seeking a ruling as to whether the recovery of the actual hotel accommodation cost paid to the hotel or third-party agent can be treated as reimbursement incurred in the capacity of a pure agent and consequently exclude it from the value of supply, with GST being payable only on the facilitation or service fee charged by the applicant.

In its submission, applicant justified that it fulfils conditions of rule 33 for being Pure Agent and the ruling be given accordingly.

Applicant submitted that its facts are covered by Delhi AAR in M/s. TUI India Private Limited, Order No. 09/DAAR/2018 dated 28.06.2019 – 2019-VIL-230-AAR.

The ld. AAR observed that the applicant has not placed any proposed agreement or terms of agreement between him and the end customer on the one hand and between him and the Third-Party Agent on the other.

Referring to rule 33, the ld. AAR noted that the rule prescribes four mandatory cumulative conditions for qualifying as Pure Agent, namely: the supplier must enter into contractual agreement with recipient to act as pure agent to incur expenditure in course of supply; must neither intend to hold nor hold any title to goods or services procured; must not use for own interest the goods or services procured; and, must receive only actual amount incurred plus amount for services provided on own account. The ld. AAR also referred to the example given in the clarification given by CBIC on the above topic.

The ld. AAR observed that the applicant will place order to a Third-Party Agent for booking of rooms in a particular hotel. The hotelier will, as per proforma invoice placed before AAR, charge the room rent along with applicable GST in the name of the end customer disclosing the details of the booking agent. The booking agent will in turn issue bill in the name of the applicant charging separately the amount paid for room booking and other amount as his service charges. The end customer will receive a bill from the applicant in his name charging separately the amount paid to the booking agent as ‘reimbursement of hotel booking’ and another amount as service charge to be paid to the applicant.

In absence of agreement, the ld. AAR also observed that this invoicing pattern creates a scenario where the applicant holds the title to the services provided by the Third-Party Agent.

Consequently, the ld. AAR also held that the applicant is said to have used the service for his own interest of providing services to the end customer.

The ld. AAR also observed that there is one more agent in between and appears to be without knowledge of end customer. The ld. AAR held that application does not fulfil condition of rule 33 and therefore, held that applicant not entitled to benefit as ‘Pure Agent’.

32. Indovation Healthcare LLP (AAAR Order No. UKGSTARA-02/13.04.2026/01/2026-27 dt.10.07.2026) (Uttarakhand)

Healthcare Services provided to public, by Urban Health and Wellness Centres, are duly covered as exempt under entry 74 of Notification no. 12/2017- Central Tax (Rate) dt.28.06.2017.

The appeal is against the Advance Ruling No.05/2025-26 dt.17.03.2026 – 2026-VIL-68-AAR passed by the AAR, Uttarakhand.

The appellant sought Advance Ruling on the following questions:

“a. Whether the operation and management of Government Urban Health & Wellness Centres (UHWCs) / Ayushman Arogya Mandirs and Polyclinics by the Applicant under identical Operation & Management Agreements with Braithwaite & Co. Limited (PSU-executing agency), funded exclusively through 15th Finance Commission health grants routed via Braithwaite and Company Limited and providing healthcare services to citizens free of cost, constitutes exempt “healthcare services by a clinical establishment” under Entry 74 of Notification No. 12/2017- Central Tax (Rate)?

b. Whether, in the alternative, the said activities qualify as “pure services” provided to the State Government (through its designated PSU-executing agency under formal MoU) in relation to Article 243W functions (public health, hospitals, dispensaries – Twelfth Schedule Entries 6, 8, 23), and are therefore exempt under Entry 3 of Notification No. 12/2017-Central Tax (Rate)?”

The ld. AAR denied benefit of entry 74 of Notification No. 12/2017 – Central Tax (Rate) dated 28.06.2017.

In appeal, appellant gave various details of its activities, the nature of relationship with Government, and the availability of exemption as healthcare service.

The ld. AAAR referred to observations of the AAR, where it is held that the operation and management of Government Urban Health & Wellness Centres (UHWCs) / Ayushman Arogya Mandirs and Polyclinics) by the Applicant under identical Operation & Management Agreements with Braithwaite & Co. Ltd. (PSU- executing agency) does not constitute exempt “healthcare services by a clinical establishment” under Entry 74 of Notification No. 12/2017 – Central Tax (Rate). The AAR has also found that the said activities do not qualify as “pure services” provided to the State Government in relation to Article 243W functions (public health, hospitals, dispensaries – Twelfth Schedule Entries 6, 8, 23), and are therefore not exempt under Entry 3 of Notification No. 12/2017-Central Tax (Rate). Accordingly, the services supplied by the Applicant are held liable to GST at the applicable rates under the CGST/SGST Act.

The ld. AAAR also examined, in detail, the scope of work. From the scope of work, the ld. AAAR observed that the Operating Agency is providing a composite healthcare facility management and operation services, including infrastructure, staffing, healthcare delivery, outreach activities, monitoring, and reporting obligations. It also noted that, the agreement indicates that healthcare delivery is not limited to medical treatment, but is a bundled activity comprising: clinical services, diagnostics services, pharmaceutical services, public health and outreach activities, facility management, human resource deployment, monitoring, and reporting. Thus, it is held to be comprehensive operation and management of healthcare facilities, rather than a mere supply of manpower or a standalone healthcare consultation service.

The ld. AAAR also noted that the actual beneficiaries of the services are members of the public visiting centres for diagnosis, treatment and healthcare. M/s Braithwaite & Co. Limited neither receives medical treatment nor consumes healthcare services.

The ld. AAAR also observed that the AAR has focused primarily upon the contractual relationship and payment mechanism without adequately examining the actual activities undertaken at the Urban Health and Wellness Centres (UHWCs/UAAMs) and Polyclinics, which is incorrect.

The ld. AAAR also held that determination of taxability and classification of the supply cannot rest solely upon the identity of the payer. The true nature, substance and objective of the contract, the activities actually performed, and the ultimate purpose for which such activities are undertaken are equally relevant considerations.

In view of the above, the ld. AAAR reversed the advance ruling and held that appellant is entitled to exemption under entry 74 of Notification no. 12/2017-CT(Rate) dt.28.6.2017.

33. Chehar Industry Pvt. Ltd. (AAR Order No. GUJ/GAAR/R/2026/28/ (in Appl. No. Advance Ruling/SGST&CGST/2025/AR/47) dt.04.08.2026) (Guj)

Classification – Washing and laundry Soap

The applicant is engaged in the manufacture and trading of Washing/Laundry Soap in bar/cake form used for washing clothes or for toilet purposes. The applicant submitted that the GST rate and classification of these products have been revised vide Notification No.09/2025 – Central Tax (Rate) dated 17.09.2025, effective from 22.09.2025. It stated that there exists ambiguity regarding whether laundry soap and toilet soap are treated under a common heading or separately, and what HSN code is applicable for each product type. Accordingly, applicant has raised following questions.

“(i) What is the correct classification and applicable GST rate on Washing/Laundry Soap (in BAR or CAKE form) used for washing clothes or toilet purposes as per Notification No.09/2025-Central Tax (Rate) dated 17.09.2025 effective from 22.09.2025?

(ii) Whether such Washing/Laundry Soap for clothes and crockeries falls under the same GST rate and classification as Toilet Soap or under a separate tariff heading?

(iii) What are the applicable 8-digit HSN codes and Rate of GST for Washing Soap, Laundry Soap, Crockeries Soaps and Toilet Soap under GST law?”

The applicant submitted the typical chemical composition for their Semi-detergent oil-based soap and Detergent soap.

The ld. AAR referred to the relevant Chapter notes, relevant tariff headings and HSN notes of the relevant tariff heading under the First Schedule to the Customs Tariff Act, 1975 (51 of 1975), and found that Chapter 34 of the First Schedule to the Customs Tariff Act, 1975 (51 of 1975) covers “Soap, organic surface-active agents, washing preparations, lubricating preparations, artificial waxes, prepared waxes, polishing or scouring preparations, candles and similar articles, modelling pastes, “dental waxes” and dental preparations with a basis of plaster.” The ld. AAR noted that soaps are covered under heading 3401 of Chapter 34 of the Customs Tariff and hence referred to Chapter Notes to Chapter 34, Tariff Heading 3401 as well as HSN notes to Tariff Heading 3401.

The ld. AAR observed that in common parlance, soap is defined as a water-soluble sodium or potassium salt of fatty acids, typically produced through the saponification of natural oils or fats with an alkali (like sodium hydroxide for bars) and acts as a surfactant for cleaning and bathing with quality often determined by Total Fatty Matter (TFM). The main difference between toilet / bathing and laundry / washing soap is that Toilet / Bathing soaps are typically potassium salts of fatty acids, making them softer, while washing soaps (laundry soaps) are sodium salts of fatty acids, resulting in a harder consistency, with the key difference stemming from the use of potassium hydroxide (KOH) for bathing soaps versus sodium hydroxide (NaOH) for washing soaps during their production. The ld. AAR held that the applicant’s products do not fall under the definition of ‘toilet soaps.’

Referring to amended Notification, the ld. AAR held that the product of the Applicant is covered by entry no.66 of Schedule-II of Notification no.09/2025 – Central Tax (Rate) dt.17.9.2025, and is liable to GST at the rate 18%.

34. Luxor International Pvt. Ltd. (AAR Order No.4/2026-27 (in Appl. No.02/2026-27(ARN: AD050526002234L) dt.10.08.2026) (Uttarakhand)

Classification – End Use theory

A very interesting question arose before the ld. Uttarakhand AAR.

Applicant is engaged in the manufacture and supply of a comprehensive range of writing instruments, stationery products, educational kits, books, notebooks, and
corporate gifting solutions.

The said uncoated paper of a kind used for writing, printing or other graphic purpose, in rolls or rectangular (including square) sheets are classifiable under Heading 4802 of the First Schedule to the Customs Tariff Act, 1975.

The Applicant submitted that the physical and technical characteristics of the said paper are consistent with those of paper used in the manufacture of notebooks and exercise books, and the same shall be supplied only to customers who are engaged in or intend to use the same for the manufacture of notebooks and exercise books and proposes to obtain end-use declarations/purchase orders from buyers clearly specifying the aforesaid intended use, so as to satisfy the conditions of the exemption notification and discharge its evidentiary obligations as a supplier claiming the benefit of the exemption. The supply was claimed to be exempt referring to Notification no. 10/2025 – Central Tax (Rate) dated 17.09.2025 [Entry 128]

The said entry reads as under:

“Notification No.

10/2025- Central Tax

(Rate) dated

17.09.2025

[Entry 128]

HSN 4802

Uncoated paper and paperboard, of a kind used for writing, printing or other graphic purposes, in rolls or rectangular (including square) sheets, of any size, other than paper of heading 4801 or 4803, used for exercise book, graph book, laboratory note book and notebooks.

Exempt”

The ld. AAR observed that the exemption should be proved within for corners of concerned Notification.

The ld. AAR observed that the present Notification though grant exemption based on end use, there is no provision requiring: execution of bonds; furnishing of certificates; submission of end-use declarations; post-supply verification; monitoring by jurisdictional officers; recovery procedure in case of diversion; or, maintenance of prescribed records. It also observed that in several taxation statutes, where the legislature intended exemption to operate upon end-use, it simultaneously prescribes documentary safeguards, certification requirements or administrative procedures to establish such end-use. However, no comparable statutory framework has been provided in the present notification, observed the ld. AAR.

The ld. AAR observed that it is not in position to decide correctness of granting exemption based on declarations, etc. The ld. AAR also observed that the words used are “used for” and not “intended to be used”.

The ld. AAR held that in the absence of any statutory deeming provision or prescribed certification procedure, the AAR cannot conclusively determine, at the stage of supply, that the goods satisfy the description “used for exercise book, graph book, laboratory notebook and notebooks”.

Due to above ambiguity, the ld. AAR declined to answer the question considering it as outside its purview.

35. Sardar Chemical Industries (AAR Order No. Advance Ruiling no.GUJ/GAAR/R/2026/30 (in Appl. No. Advance Ruling/SGST&CGST/2026/AR/09 dt.04.08.2026) (Guj)

Classification – Papad Khar

The appellant is engaged in the manufacture and supply of Papad Khar (also known as alkaline salt, sajji khar, or potassium carbonate-based alkaline compound). Applicant submitted that though it is presently classifying Papad Khar under HSN Code 2836 (Food Additives/Preparations) with 18% GST rate, as based on the detailed product analysis and technical opinion, Papad Khar should be correctly classified under either HSN Code 2501 (Common Salts – Natural/Rock Salt) liable @ 5% GST or HSN Code 2102 (Prepared Food Additives/Condiments) also liable @ 5% GST. The advance ruling is to seek correct classification and applicable GST rate.

The applicant submitted complete manufacturing process (stage-wise) for papad khar production, from initial preparation till final packaging by way of following chart:

“Stage Steps Key Activity
1-2 Water & Salt Boil Water  Add Salt (NaCL)
3-4 Chemical Mix Add Soda Ash  Add Soda Bicrabonate
5-6 Solidification Transfer to Container  Break & Dry
7 Finishing Package & Ready for distribution”

The ld. AAR noted that tariff heading 2501 covers three sub-headings i.e. Common Salt (HSN Code 25010010), Rock Salt (sub-heading 25010020) & others (25010090) but does not cover products that have been roasted, calcined, obtained by mixing or subjected to processing beyond that mentioned in each heading.

The ld. AAR noted that the product of applicant has been obtained following a manufacturing process involving mixing of sodium carbonate and sodium bicarbonate in to a mixture of heated water – containing common salt (sodium chloride) already dissolved in it – and subsequent transfer to strong durable containers by cooling and solidification after the mixture reaches the appropriate thickness, and thereafter breaking of the resultant solid material (papad khar) into manageable pieces and drying it completely. In view of above, the ld. AAR held that the product of the applicant does not fall within the ambit of heading 2501.

In respect of heading 2102, the ld. AAR held that heading 2102 covers Active yeasts (sub-heading 210210), Inactive yeasts (sub-heading 210220) & prepared baking powders (sub-heading 210230). After examining components and process, the ld. AAR concluded that ‘papad khar’ does not have the characteristics of ‘yeast’ and not covered by 2102.

Regarding correct classification, the ld. AAR analysed scope of heading 2836 and held that ‘papad khar’ would be aptly classifiable under heading 2836, more specifically under sub-heading 28362090 of the First Schedule to the Customs Tariff Act, 1975 (51 of 1975).

After fixing classification under 2836 2090, the ld. AAR referred to Notification No. 9/2025 – Central Tax (Rate) and Notification No. 10/2025 – Central Tax (Rate) dated 17.09.2025 and held that the product falls under Entry No. 35 of Schedule II of Notification No. 9/2025 – Central Tax (Rate) dated 17.09.2025 and is liable to GST at the rate 18%.

Decoding GSTAT – Early Trends From Select Decisions

The establishment of the Goods and Services Tax Appellate Tribunal (GSTAT) marks a major milestone in resolving GST disputes. Early rulings demonstrate key emerging judicial trends across four areas:

  • Procedural errors vs. evasion: Penalties under section 129 require intent to evade; genuine procedural defaults backed by documentary proof receive relief.
  • Procedural discipline: Statutory time limits, such as section 129(3)’s seven-day order limit, are strictly jurisdictional.
  • Legacy issues: Transitioned credits must be examined under erstwhile laws, with CESTAT remaining the proper forum for section 142(3) appeals.
  • Substantive provisions: Benches are prioritising substance-over-form, including allowing inverted duty structure refunds for ancillary packing materials

INTRODUCTION

The establishment of the Goods and Services Tax Appellate Tribunal (GSTAT) marks a significant milestone in the administration of GST law. For nearly a decade, a taxpayer aggrieved by an order of the First Appellate Authority had no option but to approach the High Court under Article 226 of the Constitution of India. That arrangement burdened the constitutional courts with intensely factual and technical tax disputes, and it raised the cost of litigation for businesses. With the GSTAT benches now up and running, one can look forward to a steady maturing of the GST legal landscape.

The Principal Bench and the State Benches were constituted in 2023-24, with members appointed and allotted to the benches in December 2025. The GSTAT portal was formally launched in September 2025 for filing appeals. The initial phase was marred by technical difficulties, and the Tribunal responded by introducing staggered filing. That was later rolled back, and the portal was opened for all appeals, with the outer time limit for filing fixed at 31 July 2026 for orders communicated before 1 May 2026.1


1 Notification dated 30 June 2026 issued under Section 112 of the CGST Act, 2017, 
superseding the notification dated 17 September 2025, 
fixing 31 July 2026 as the last date for filing appeals against orders communicated before 1 May 2026.

On the administrative side, the registry has been busy with a surge of online appeals. Physical and virtual hearings have begun in phases during 2026, with admission matters receiving priority, and the registry uploads the cause list a day in advance. Practitioners, however, are still finding their feet. Tracking the status of an appeal is difficult because cases are allotted to individual courts within a State Bench, and the manner of communicating hearing notices and of filing additional submissions or rejoinders is yet to be streamlined.

Against this backdrop, it is a good time to take stock of the jurisprudence that is beginning to emerge. This article looks at select decisions of the GSTAT benches under four heads:

  • Procedural lapses versus substantive evasion: Separating bona fide procedural errors from deliberate tax evasion, so that minor clerical or timing errors are not met with consequences meant for fraud, and marking out acts that do not amount to suppression.
  • Procedural discipline on the Revenue: Holding the administration to statutory timelines and prescribed procedure, and treating time limits framed in mandatory terms as going to the root of jurisdiction.
  • Legacy issues: Drawing the line between the erstwhile regimes (Central Excise, Service Tax and State VAT) and the GST framework, so that GST officers do not reopen legacy transactions, and appeals reach the right forum.
  • Substantive provisions: The reading of substantive provisions, including the evidence needed to support refund claims, the pre-deposit for appeals, and refund under the inverted duty structure.

The GSTAT Decoded

PROCEDURAL LAPSES VERSUS SUBSTANTIVE EVASION

Section 129 of the CGST Act, 2017, which provides for the detention and seizure of goods and conveyances in transit, was designed as an anti-evasion tool. It empowers mobile squads to intercept vehicles and to verify compliance with section 68 read with rule 138. In practice, however, aggressive enforcement has frequently resulted in heavy penalties for minor clerical errors, short digital delays, and administrative mishaps. The writ courts have stepped in and granted relief where the error was genuine and there was no intent to evade tax. The GSTAT appears to be taking a similar approach.

E-way bill lapses

In Lucknow Automotives,2 the vehicle carried a tax invoice for motorcycles, each bearing a traceable engine and chassis number. The e-way bill was generated only after interception, within nine minutes of it, yet the Tribunal declined to brush the lapse aside as an afterthought. It treated it as a bona fide procedural default that did not deserve the severity of a penalty under section 129.

Siddhi Vinayak Automobiles3 points toward the same direction. The consignment moved under e-invoices reported directly on the Government portal, though no e-way bill accompanied it, and the Tribunal thought it inappropriate to presume evasion from a movement whose details were already visible to the Department. The penalty was set aside on that footing and also because the order had been passed beyond the statutory time limit, which is discussed in Part 3.


2  M/s Lucknow Automotives v. Assistant Commissioner (Mobile Squad), 
Gonda & Ors., 2026 (8) TMI 1488 – GSTAT Lucknow (order dated 19 August 2026).

3 Siddhi Vinayak Automobiles v. Commissioner of Kerala State GST, 2026 (8) TMI 1052 – 
GSTAT Thiruvananthapuram (order dated 14 August 2026).

Both decisions sit comfortably with the line of High Court decisions that treats intent to evade tax as a necessary ingredient for a penalty under section 129. The provision is not to be applied mechanically to every contravention, and both the High Courts and the GSTAT have looked at the surrounding circumstances before deciding whether a penalty is warranted.

Afterthought e-way bills: where the benefit ends

The liberal approach in Lucknow Automotives and Siddhi Vinayak has its limits. In Om Prakash v. Islam Trading Co.,4 decided by the Lucknow Bench a day after Lucknow Automotives, the Tribunal considered, on the Department’s appeal, whether the rigour of section 129 could be relaxed for such contraventions. The goods, iron scrap, were moving on a manually prepared tax invoice with no e-way bill at all. The Tribunal held that generating an e-way bill after the event, particularly for goods prone to evasion, points to an intent to bypass the digital monitoring mechanism, and it restored the penalty.


4  Om Prakash v. Prop., Islam Trading Co., 2026 (8) TMI 1743 – 
GSTAT Lucknow (Appeal No. APL/79/LKC/2026, order dated 20 August 2026).

What separates this decision from the earlier ones is proof of bona fides. In Lucknow Automotives and Siddhi Vinayak, the taxpayer backed its explanation with a documentary trail, namely traceable goods or e-invoices reported on the portal. In Om Prakash, scrap moving on a hand-written invoice without an e-way bill invited suspicion, and the taxpayer could not dispel it. The principle cuts both ways: the benefit of a bona fide lapse is available only to a taxpayer who can demonstrate good faith.

Stock transfers under the same GSTIN

In M S Steels,5 a penalty under section 129 (100% of the tax involved) was imposed on a stock transfer between two premises of the same registered person under the same GSTIN, a movement on which, admittedly, no tax could be levied. The Revenue argued that “tax payable” is merely the measure of the penalty and does not require tax to be actually leviable. The Tribunal rejected the argument, following several High Court decisions on the point. The ruling implies that a penalty under section 129 requires a taxable supply within the meaning of section 7. It should be read with care: a transfer between two distinct registrations of the same entity stands on a different footing, since section 25(4) treats them as distinct persons and Schedule I treats supplies between them as supplies even without consideration.


5 M S Steels v. Commissioner of Kerala State GST, 2026 (8) TMI 1053 – 
GSTAT Thiruvananthapuram (Appeal No. APL/1/TVP/2026, order dated 14 August 2026).

The Tribunal did not treat the lapse as harmless. Moving goods without an e-way bill remains a contravention of rule 138(1)(ii), which covers movements for reasons other than supply, but the consequence lies in the specific penalty under section 122(1)(xiv) for transporting taxable goods without the cover of documents, and not in the tax-linked penalty under section 129.

The decision rightly reads a penal provision strictly. The reservation is a practical one. The residual penalty is a lighter deterrent, and the label of “stock transfer” could be misused to move taxable goods while staying clear of electronic monitoring, when the e-way bill regime is meant to track every movement, including non-supply movements. In our view, the answer lies in officers testing a claim of stock transfer against the delivery challan, the GSTIN and the stock records, and applying section 122(1)(xiv) where the lapse is established, rather than in stretching section 129.

Voluntary reversal of ITC through Form GST DRC-03

The Kolkata Bench in D.R. Steel Construction Co. Pvt. Ltd.6 refused to let a technical objection defeat a voluntary reversal of disputed ITC. The taxpayer had reversed the amount through Form GST DRC-03 but left the “reasons” column blank, which, according to the Revenue, left the true nature of the payment in doubt. The Tribunal held that Column 8 of Form DRC-03 is not a mandatory field under the GST rules, and that leaving it blank does not invalidate an otherwise valid debit from the electronic ledgers. It also noted that the Department itself had issued Form GST DRC-04 acknowledging the payment, and the Department could not be heard to say that there was no proof of payment.


6 Atanu Mondal (CGST) v. D.R. Steel Construction Co. Pvt. Ltd., 2026 (8) TMI 1278 – GSTAT Kolkata.

PROCEDURAL DISCIPLINE ON THE REVENUE

Revenue officers have often treated statutory timelines and procedural rules as merely directory and have sought to justify delays or post-facto corrections in the name of protecting public revenue. The GSTAT benches have pushed back. In the cases discussed below, they held that timelines framed in mandatory terms and the procedural safeguards built into the statute go to the root of an officer’s jurisdiction.

Section 129(3): the seven-day timeline

Section 129(3) requires the proper officer to issue the notice within seven days of detention or seizure and to pass the order within seven days from the date of service of that notice. In Siddhi Vinayak Automobiles (supra), the order in Form MOV-09 was passed 47 days after the notice in Form MOV-07. The Tribunal held that the language of the provision is mandatory. A strict fiscal statute must be read that way, it reasoned, so that commercial assets are not held up for long periods and traders are spared harassment by mobile squads. Relying on a series of High Court precedents, it treated the seven-day period as a jurisdictional limit, and held that an order passed beyond it is illegal and without jurisdiction.

Bar on new evidence at the appellate stage

In Agarwala’s Bitumex Pvt. Ltd.,7 the Kolkata Bench barred the Revenue from relying on material that lay outside the show cause notice. The refund had been denied on the basis of toll plaza data and the cancellation of second-level suppliers’ registrations. In appeal, the Revenue tried to add fresh allegations, including correspondence from Customs authorities, the absence of regulatory licences for trading in the commodity and references to DGGI investigations. It had filed no application to place additional evidence on record and had shown no exceptional cause for not raising these matters in the show cause notice or during adjudication, although it knew the commodity involved from the start. Citing rule 45(1) of the GSTAT (Procedure) Rules, 2025 and rule 112(1) of the CGST Rules, 2017, the Tribunal held that without such a prayer, fresh allegations cannot be made against the taxpayer at the appellate stage. Put simply, the Revenue cannot keep moving the goalposts after the game has begun. The ruling gives taxpayers a useful answer where the scope of the enquiry is widened at the appellate stage.


7 Pr. Commissioner CGST & CX, Siliguri v. M/s Agarwala’s Bitumex Pvt. Ltd., 2026 (8) TMI 1279 – GSTAT Kolkata.

Evidence of fraud

The Revenue often invokes fraud or suppression to shelter behind the extended period of limitation. In Santhome Latex Enterprises,8 the Tribunal held that an allegation of suppression, unsupported by any independent evidence, does not meet the test of fraud, wilful misstatement or suppression under section 74. The differences in question were visible from the data already available on the portal through Form GSTR-9C and GSTR-9, and could not therefore be characterised as suppression. That conclusion fits the statutory definition in Explanation 2 to section 74, which confines suppression to the non-declaration of facts or information that a taxable person is required to declare in a return or other document, or the failure to furnish information when asked in writing. The Tribunal also observed that an appellate authority cannot sustain an order on a ground that was not raised in the show cause notice. (For periods from FY 2024-25, the corresponding provision is section 74A.)


8 Santhome Latex Enterprises v. Commissioner of CGST, 2026 (8) TMI 1363 – 
GSTAT (Thiruvananthapuram Bench), Final Order No. 04/TVP/KERALA/2026 dated 21 August 2026.

LEGACY ISSUES

The migration of credit under section 140 has drawn close scrutiny of legacy credits and how they are assessed. The GSTAT benches have now begun to mark out where the powers of GST officers end and where the machinery of the legacy laws must be used.

Transitional credit: who may question it?

In Tata Unistore Limited v. Commissioner CGST, 9 the Thane Bench considered credit carried forward under section 140. The taxpayer’s case was that a credit balance transitioned to GST cannot be questioned in a GST proceeding, and can be examined only under the legacy provisions. The Tribunal agreed in substance. The Department cannot invoke the GST provisions to examine compliance with the erstwhile law when it had the powers to do so under that law. Section 174 saves the powers exercisable under the repealed enactments; it continues them under the old law, and it does not replace them or authorise a fresh examination of the earlier law through GST machinery. Where the Department had not challenged the credit under the Central Excise or Service Tax law, whether by audit, notice or recovery proceedings, credit that was admissible under the earlier law stood validly carried forward.


9 Tata Unistore Ltd. v. Commissioner of CGST & Central Excise, Navi Mumbai, 2026 (8) TMI 139 – GSTAT Thane.

Appellate forum for Section 142(3) refunds

In Kairav Chemofarbe Industries Limited,10 the Thane Bench, hearing a Revenue appeal against a refund sanctioned under section 142(3), questioned its own jurisdiction. Section 142(3) directs that a claim for refund of CENVAT credit or duty be disposed of in accordance with the existing law. Relying on the Larger Bench decision of the CESTAT in Bosch Electrical Drive India Pvt. Ltd. v. Commissioner of Central Tax, Chennai,11 the Tribunal held that appeals arising from refund or credit rejection orders under section 142(3) are governed by the legacy laws. The proper forum for such disputes is therefore the CESTAT, and the GSTAT has no jurisdiction to decide them. The appeal was dismissed, with liberty to the parties to approach the CESTAT.


10 Commissioner, CGST & Central Excise, Raigad v. Kairav Chemofarbe Industries Ltd., 2026 (8) TMI 720 – GSTAT Thane.

11 M/s Bosch Electrical Drive India Pvt. Ltd. v. Commissioner of Central Tax, Chennai, 2023-VIL-1352-CESTAT-CHE-ST (Larger Bench).

SUBSTANTIVE ISSUES: SUBSTANCE OVER FORM

The digitisation of GST administration has brought a certain rigidity, with officers at times overlooking the substance of the issue and fastening on technicality. The GSTAT benches appear to be emerging as a check on this tendency, insisting that the substance of the matter be examined and not merely its form.

Extraneous evidentiary demands

In Agarwala’s Bitumex (supra), the Kolkata Bench discouraged the use of extraneous data, such as toll plaza vehicle-tracking records, to deny genuine refund claims. The exporter’s claim had been rejected on the footing that the vehicles never crossed the toll gate, so the goods could not have been physically received. Relying on the Allahabad High Court’s decision in Raghuvansh Agro Farms Ltd.,12 the Bench held that such a requirement is not statutory and cannot be the sole basis for denial when the exporter has produced substantive documentary evidence, such as lorry receipts and shipping bills. Where the export itself is an undeniable fact, the Bench reasoned, the natural inference is that the purchases were genuine.

The Bench also noted that under the bill-to/ship-to arrangement recognised by section 10(1)(b) of the IGST Act, goods are often delivered directly to the port of export, or to another place chosen by the buyer, on the buyer’s instructions. The physical movement need not begin at the supplier’s registered place of business, and an inference drawn from the assumption that it must, is unsafe.


12  Raghuvansh Agro Farms Ltd. v. State of U.P. & Ors., 2025 (12) TMI 1236 – Allahabad High Court.

Right of appeal and pre-deposit

The Hyderabad Bench in Reddy Veeranna Constructions Pvt. Ltd.13 held that the law governing the right of appeal, including the pre-deposit, is a substantive right that accrues on the date the dispute is initiated, that is, on the issue of the show cause notice. A later amendment does not alter it. The new proviso to section 112(8) of the CGST Act, 2017, which imposes a mandatory pre-deposit even where only a penalty is in dispute, therefore, does not apply to show-cause notices issued before 1 October 2025. This is consistent with the Calcutta High Court’s decision in Barjinder Singh Kohli v. Assistant Commissioner of Revenue,14 which held that no pre-deposit can be demanded where the appeal relates only to a penalty and no tax is in dispute.


13  Reddy Veeranna Constructions Pvt. Ltd. v. Appeal-I Commissioner & Ors., 2026 (8) TMI 215 – GSTAT Hyderabad.

14 Barjinder Singh Kohli v. Assistant Commissioner of Revenue, 2025 (11) TMI 294 – Calcutta High Court.

Refund under the inverted duty structure

In a welcome development, the Kolkata Bench in Tea Linker15 upheld an inverted duty refund where the credit had accumulated on account of packing material. The taxpayer bought bulk tea and sold packaged tea, both at 5%, but the packing material bore tax at 12%. The Revenue argued that since the principal input and the output were the same commodity at the same rate, there was no inversion, and it relied on paragraph 3.2 of Circular No. 135/5/2020-GST dated 31 March 2020. The Bench held that section 54(3)(ii) uses the word “inputs” in the plural and draws no distinction between principal and ancillary inputs, and that packing material is an input within the meaning of section 2(59). It read the Circular as addressing only a reduction in the rate of tax on the same goods over time, and therefore as having no application. Following the Delhi High Court in Indian Oil Corporation Ltd.,16 the Bench declined to let a circular narrow an entitlement that the statute confers.


15 Pr. Commissioner v. Tea Linker, 2026 (9) TMI 882 – GSTAT Kolkata.

16 Indian Oil Corporation Ltd. v. Commissioner of Central Goods and Services Tax & Ors., 2023 (12) TMI 361 – Delhi High Court (W.P.(C) 10222/2023, decided on 5 December 2023).

CONCLUSION

The decisions reviewed in this article are a small sample: eleven orders from five benches, delivered over a few weeks. It is early days, and no appeal should be built on a single bench-level order. Even so, some clear currents are already visible. The table below sets them out, followed by our reading of them, and of what lies ahead.

Theme Early direction of the benches What to watch
Procedural lapses versus evasion Bona fide, documented lapses are excused; unexplained lapses on high-risk movements are penalised. Whether benches converge on a common test of intent; treatment of e-way bills generated after interception.
Procedural discipline on the Revenue Mandatory timelines, the boundary of the show cause notice and the standard of proof for fraud are being enforced. High Court view on whether the seven-day limit in Section 129(3) is jurisdictional.
Legacy matters GST officers cannot reopen legacy credits; appeals on legacy refunds lie to the CESTAT. Revenue challenge to the Tata Unistore reasoning; forum and limitation risk in transitional matters.
Substance over form The statutory text prevails over non-statutory checks and circulars. Reach of the “inputs” reasoning under section 54(3)(ii); pre-deposit on notices issued on or after 1 October 2025.

Our reading of the trends

First, the Tribunal is looking for evidence and not taking sides. Second, the Revenue is being held to the four corners of the law. Third, substance is being preferred to form. An appeal from a State or Area Bench lies to the High Court under section 117 of the CGST Act, though only on a substantial question of law, and the writ jurisdiction under Articles 226 and 227 remains available for jurisdictional error, since the decisions of a tribunal are subject to judicial review.17 We expect the Revenue to carry at least three questions upward: whether the seven-day limit in section 129(3) is jurisdictional; whether GST officers can question credit transitioned under section 140 through the demand provisions of sections 73 and 74; and whether ancillary inputs such as packing material can, by themselves, support an inverted duty refund where the principal input and the output bear the same rate. Until those questions are answered, these rulings should be treated as persuasive and not final.

The GSTAT was meant to be a forum that decides GST disputes on their merits, promptly and by reasons that can be relied upon. The early orders give reason for measured optimism: they show an instinct for proportionality and for legal discipline, without a leaning towards either side. But theproof of the pudding will be in the consistency and speed of disposal, and in how these rulings fare in the High Courts. We will continue to track these developments.


17  L. Chandra Kumar v. Union of India, (1997) 3 SCC 261 (Constitution Bench).

Assistant Commissioner of Income Tax v. Omaxe Limited: Settlement Commission orders under Section 245D(4) are conclusive, barring Assessing Officers from initiating reassessment proceedings under Section 148.

8. Assistant Commissioner of Income Tax and Ors. Vs. Omaxe Limited

(2026) 190 taxmann.com 551(SC)

Reassessment – Notice under section 148 of the Act – Proposing to disallow the deduction under Section 80IB(10) of the Act, 1961 – ITSC passed an Order under Section 245D(4) of the Act, 1961 wherein the deduction under section 80IB(10) was allowed – Order of ITSC conclusive – Also, Application under Section 245D(6) of the Act rejected – Notice to reopen the assessment invalid

The Assessee, a Public Limited Company was engaged in real estate business. The Assessee filed its return of income on 30.11.2006 for the Assessment Year (AY) 2006-07.

On 22.09.2005, the Revenue, under Section 132 of the Act, 1961, conducted a search and seizure at the Assessee’s business premises and the Associate Concerns, as well as the residential premises of its Directors.

On 30.11.2006, the Assessee filed the Return for the AY 2006-07, declaring taxable income of ₹89,20,76,630/- and claimed a tax deduction of ₹78,99,00,509/- [noted as ₹79,17,72,794/- in subsequent departmental proceedings] under Section 80IB(10) of the Act, 1961, in respect of the Housing Projects executed by the Assessee.

On 31.05.2007, during the pendency of the regular assessment for the AY 2006-07, the Assessee filed an Application under Section 245C of the Act for the AY 2000-01 to 2006-07 to settle the cases as disclosed in the Application filed before the Income Tax Settlement Commission (“ITSC”).

On 17.03.2008, the ITSC, under Section 245D(4) of the Act, 1961, passed the final Settlement Order.

For AY 2006-07, the ITSC accepted the additional income surrender of ₹18,00,000/- (Rupees Eighteen Lakhs). The total income before deductions was Rs. 89,20,76,630/-, and after allowing deductions under Section 80IB(10) of the Act, 1961, the ITSC determined the net taxable income for the AY 2006-07 to be ₹ 89,38,76,630/-.

According to the Revenue, on 17.12.2009 and 18.12.2009, the Investigating Wing of the Revenue conducted a fresh survey of the Assessee’s premises under Section 133A of the Act, 1961. According to the Revenue, the Assessee claimed a deduction under Section 80IB and, as part of an alleged manipulative process, was planning to transfer commercial portions of the projects executed on OMAXE City Lucknow, OMAXE City Sonepat, etc, to 100% subsidiary companies to maintain the commercial area, thereby enabling the Assessee to continue claiming the deduction under Section 80IB of the Act, 1961.

On 30.06.2010, a Notice under Section 148 of the Act, 1961 was issued for the AY 2006-07, proposing to disallow the deduction under Section 80IB(10) of the Act, 1961 to the extent of ₹55,58,96,486/-. The reasons recorded by the Assessing Officer (“AO”) for issuing the Notice under Section 148 were as follows:

A. A survey was conducted Under Section 133A on 17.12.2009 and 18.12.2009 at the Assessee’s premises. During the survey, the Investigation Wing impounded documents containing Minutes of a Meeting attended by Senior Executives, including the Director of Taxation, the V.P. Finance, the G.M. Legal, and the Company’s Auditors.

B. The impounded documents show that the Assessee’s Executives mutually decided, before finalising the balance sheet for the period ending 31.03.2009, to transfer the commercial portions of specific projects to 100% subsidiary companies at cost to strengthen their claim under Section 80IB of the Act, 1961.

C. Section 80IB(10)(vi) of the Act, 1961 provides that the built-up area of shops and other commercial units within a housing project must not exceed 5% of the aggregate built-up area or 2,000 sq. ft, whichever is lower.

D. Further, the impounded documents showed that the commercial area in several of the Assessee’s projects far exceeded the legal limit, making those projects ineligible for the deduction under Section 80IB(10)(vi) of the Act, 1961. Therefore, the Section 80IB deductions were wrongly claimed.

E. Hence, Rs. 55,58,96,486/- across four specific projects, i.e., OMAXE City Lucknow, OMAXE City Sonepat, OMAXE Heights Sonepat, and OMAXE Heights Faridabad, had escaped assessment, and these reasons were sufficient to issue a Notice Under Section 148 of the Act, 1961, for AY 2006-07.

In response, the Assessee filed objections on 20.09.2010 and 18.08.2011 against the proposed reopening of the ITSC Settlement Order dated 17.03.2008 for AY 2006-07. On 18.07.2011, the AO/First Appellant issued a Notice under Section 143(2) of the Act, 1961, seeking further details from the Assessee. In response to the said Notice, the Assessee filed Preliminary Objections, contending that the ITSC Settlement Order was conclusive under Section 245I and that the AO had no jurisdiction to reopen the assessment. The reply stated as follows:

A. That the Assessee has filed an application before the Settlement Commission for the determination of total income derived under the Act, 1961, and for the settlement of tax liabilities for AY 2006-07. The ITSC passed an Order under Section 245D(4) of the Act, 1961, computing the total income for AY 2006-07. Consequently, all matters relating to AY 2006-07 were settled and conclusive.

B. Section 245-I of the Act, 1961, mandates that every Order of settlement passed under Section 245D(4) is conclusive on the matters stated therein. The said Section strictly bars the reopening of any matter covered by such an Order in any proceeding under the Act, 1961 or any other law in force, except as otherwise provided under Chapter XIX-A of the Act, 1961.

C. On a plain reading of Section 245-I, the AO lacks statutory jurisdiction under the Act, 1961, to issue a Reassessment Notice Under Section 148 for the subject assessment year. Accordingly, the Notice dated 30.06.2010 was illegal, void ab initio, and bad in law.

D. The AO was requested to drop the proceedings initiated under Section 148 of the Act, 1961. In the event the proceedings were not dropped immediately, the Assessee requested the AO to supply a copy of the “reasons recorded” for issuing the Section 148 notice for AY 2006-07.

The AO, vide Order dated 03.10.2011, rejected the Assessee’s objections to the Notice dated 30.06.2010, which ultimately led to the reassessment Order dated 08.11.2011 under Section 147 of the Act, 1961. The AO disallowed the deduction under Section 80IB(10) and added back ₹65,65,17,999/- to the total taxable income for AY 2006-07.

On 04.01.2012, at the first instance, the Assessee filed Writ Petition No. 7975 of 2011 before the High Court of Delhi, challenging the Show Cause Notice dated 30.06.2010. The prayer was subsequently amended on 09.01.2012 to challenge the Reassessment Order dated 08.11.2011.

The High Court noted that on 29.10.2010, the CIT(C)-III, Delhi, filed an Application under Section 245D(6) of the Act, 1961, before the ITSC, seeking to declare that the Order dated 17.03.2008 in favour of the Assessee under Section 245D(4) is on account of misrepresentation of facts and is void under Section 245D(6) of the Act, 1961. After receiving the Assessee’s reply, the ITSC afforded the Revenue and the Assessee an opportunity of hearing on 30.11.2011 and, by Order dated 16.12.2011, rejected the Revenue’s Application dated 29.10.2010.

By Judgment and Order dated 13.07.20, the Writ Petition was allowed by the High Court, quashing the Reassessment Notice and Order. It was held that the ITSC has exclusive jurisdiction once an Application for Settlement is admitted, and that its final Order legally bars the AO from initiating reassessment in respect of the impugned Order passed by the ITSC.

On appeal, the Supreme Court observed that The Revenue’s argument for issuing the Reassessment Notice rests on the words in Section 245C of the Act, 1961, viz, “containing a full and true disclosure of his income which has not been disclosed before the Assessing Officer”, but it overlooks the expression in Section 245C, viz, “the manner in which such income has been derived”. According to the Supreme Court, on a plain construction of both the italicised expressions, what constitutes a case for consideration before the ITSC would be an Assessee making an Application containing a full and true disclosure of the Assessee’s income which has not been disclosed before the AO, and the manner in which such income has been derived. Therefore, the additional amount of income-tax payable in the disclosure will depend on the manner in which such income has been derived by the Assessee. The Supreme Court noted that in the case on hand, the Assessee had disclosed the revenue included in the Assessee’s gross total income and, by claiming deductions under the Act, 1961, the net income liable for tax was set out. Once the ITSC admits the case for settlement, the consideration is the return for the assessment year, including deductions. The Report is called for on the Assessee’s Application, and there is no gainsaying that, while participating in the Settlement before the ITSC, the Revenue allowed a deduction that is otherwise disallowable. The normal presumption is that the Revenue filed its Report on the Assessee’s application. Once the matter is concluded under Section 245D(4), the decision attains finality, outside the scope of judicial review.

According to the Supreme Court, the Revenue is not without recourse to realise tax on undisclosed income, even in cases filed under Chapter XIX-A of the Act, 1961. The Revenue has the option to move under Section 245D(6) of the Act, 1961 on the grounds of fraud and misrepresentation. The words “fraud and misrepresentation” depend on the circumstances and are to be decided on a case-to-case basis; by making out a case under either head, the ITSC’s Order is reopened, which ultimately leads to the Settlement Order being declared void. The normal
assessment procedure is restored or enabled, but not otherwise. If the jurisdiction of the AO under Sections 143(2), 148, 154, etc, is made independent and available for exercise again, the finality attached to the Settlement Commission will be defeated. The Parliament did not envisage this course. On the contrary, while reopening the issues before the ITSC is provided for, judicial review by the Constitutional Courts under Articles 226 and 32/136 is available, but the AO’s power to reassess the Settlement Order passed by the ITSC is unavailable.

In fine, through the mechanism under Chapter XIX-A of the Act, 1961, the Assessee and the Revenue avoid the crust and crumb. To wit, the Revenue avoids the crust by realising the crumb of tax on suppressed or undisclosed income through the Assessee’s voluntary disclosure. Similarly, through complete and fair disclosure of suppressed income and entries, the Assessee avoids the crust of penal interest, prosecution, etc, and the crumb offered is payment of tax beforehand. The Revenue and the Assessee must take the crust and the crumb together. By operation of Section 245C(3), the Assessee is precluded from withdrawing the Application filed under Section 245C. The Revenue can oppose continuation before the ITSC based on the material and grounds discovered during the search and seizure against the Assessee. The Revenue participates before the ITSC in the Assessee’s Application, including any income further disclosed by the Assessee. Therefore, the argument that, after the proceedings before the ITSC attain finality, the regular assessment/re-assessment is still available to the Revenue is contrary to the defining expressions in Sections 245C, 245D(2), 245D(3), and finally 245D(4) of the Act, 1961. The Revenue has to revisit the procedure under Section 245D(6) by making out a case before the ITSC, but not otherwise. Thus, the Assessee and the Revenue are aware of the crust and the crumb in this settlement procedure before the ITSC. Once the crust is avoided and the crumb is accepted, further crusts and crumbs are not the intention of Chapter XIX-A of the Act,1961.

The Supreme Court noted that in the present case, the Revenue availed the remedy under Section 245D(6) of the Act, 1961 before the ITSC, resulting in the findings recorded in the Order dated 16.12.2011, which had become final.

The Supreme Court therefore found no meritin the Appeal, and it was therefore dismissed.

Pr. CIT v. Rhythem Real Estates Pvt. Ltd.: Presumption under Section 132(4A) applies to searched persons, not third parties, requiring independent evidence for Section 69B additions.

13. Pr. CIT – 3 V/s Rhythem Real Estates Pvt Ltd.,

ITA No. 61 OF 2020, dated 19/08/2026, (Bom)(HC)

[Arising from order dated 25th April 2018 in Income Tax Appeal No. 3036/Mum/2016. Assessment Year 2006-07]

Section 69B – Unexplained Investment – On money – Seized documents from third party – contents of the documents seized during the search are presumed to be true – presumption referred section 132(4A), would apply to persons searched and not a third party.

The Assessee-Company was engaged in the business of real estate development. For Assessment Year 2006-07, the Assessee filed its Return of Income on 29th November 2006 declaring a loss of ₹44,492/. The assessment was completed under section 143(3) of the Act vide order dated 5th December 2008 computing the income of the Assessee as ‘Nil’, after disallowing the loss claimed.

Thereafter, on the basis of the information received from the Director of Revenue Intelligence (“DRI”), Mumbai, regarding payment of on-money in cash by the Respondent – Assessee for purchasing properties at New Delhi, the Assessing Officer reopened the assessment for Assessment Year 2006-07 under section 147, by issuing a notice under section 148 on 28th March 2013.

As mentioned by the Assessing Officer in the reasons recorded for reopening, it was the case of the Assessing Officer that during the search and seizure operation conducted in the residential premises of NITCO’s Dy. Manager (Accounts), two electronic storage devices (hard disk and pen drive) were found and recovered. A file found in the hard disk contained details of the payment made towards purchase of 36 landed properties in Maidan Garhi area of South Delhi during the year 2005. According to the copy of the said file in excel format attached to the letter of the Additional Director General, (DRI), the file contained details of the sellers/buyers of 36 landed properties, as well as payments made, both in demand draft and cash mode. As per the said information, the total amount paid for acquisition of the properties was to the tune of `54.29 crores comprising of a demand draft component of `14.43 Crores and a cash component of Rs. 41.86 crores. According to the DRI, the information relating to transactions involving the present Assessee was given at serial numbers 9, 10, 16 and 23 of the excel sheet. According to the DRI, from the information received, it was observed that the Assessee had paid on-money in cash amounting to `7.07 crores along with other cash payments totaling to `8.87 crores. Therefore, in the course of the reassessment proceedings, the Assessing Officer proposed to treat the cash payment made on account of on-money etc. as unexplained investment of the Assessee under section 69B of the Act. Though this addition was objected to by the Assessee vide its letter dated 14th March 2014, the Assessing Officer rejected the objections, and by relying upon the information received from the DRI, passed a reassessment order adding an amount of `8.87 crores as unexplained investment under section 69B of the Act.

The CIT (A) allowed the appeal filed by the Assessee, and directed the deletion of the addition of `8.87 crores to the income of the Assessee as an unexplained investment under section 69B of the Act.

The Revenue preferred an appeal, being ITA No. 3036/Mum/2016 before the ITAT. The ITAT upheld the order of the CIT (A) and dismissed the appeal of the Revenue.

The Hon’ble Court observed that the CIT (A) concluded that apart from the file received from the DRI, the Assessing Officer had gathered no other evidence that the Appellant had paid any on-money. It was the Assessee’s specific case that the properties purchased were not easily saleable because of the restriction for permission of development from the Delhi Government and the fact that without Government approval they cannot even be registered by the Registrar.

In fact, the Assessee had called upon the Assessing Officer to himself inquire about the market rate in the vicinity on the date of purchase which would establish that the price paid and reflected in the balance sheet of the Assessee is commensurate with the prevailing market price. Despite this, the Assessing Officer made no independent inquiry to ascertain the market rate of the lands in the locality. In fact, even though a remand report was called from the Assessing Officer, the Assessing Officer vide its letter dated 18th August 2015 merely stated that all the documents forwarded to him were already considered while passing the Assessment Order under section 143(3) read with section 147 of the Act. The CIT (A) concluded that even at the remand stage, the Assessing Officer did not make any further inquiries or produce any substantive or material evidence to establish payment of on-money by the Assessee.

The CIT (A), therefore, relying upon certain decisions of the Supreme Court, concluded that before any addition was made, there should be material on record as evidence. Additions made on the basis of presumption cannot be sustained in law. It was on this basis that the CIT (A) allowed the appeal of the Assessee and deleted the addition of `8.87 crores made by the Assessing Officer under section 69B of the Act.

The ITAT, also taking note of the detailed factual findings given by the CIT (A), upheld the order of the CIT (A) and dismissed the appeal. The entire dispute in the case was fact-driven. The Court noted that, the CIT (A) correctly concluded that apart from the file received from the DRI, the Assessing Officer gathered no other evidence that the Appellant had paid any on-money. In fact, the Assessing Officer did not even proceed to conduct an independent inquiry regarding the market rate of the lands in the locality in which the Assessee had purchased the property to come to the conclusion that there was a big difference between the market value and the price paid by the Respondent-Assessee, which would then lead to an inference that the Assessee had paid the difference in cash. On these facts, the appeal does not give rise to any substantial question of law.

Further, the provisions of section 132(4A), and the presumption referred to therein, would apply to persons searched and not a third party like the Respondent-Assessee. In fact, the Hon’ble Supreme Court in the case of P. R. Metrani v. Commissioner of Income-tax, Bangalore [2006] 157 taxmann 325(SC) has categorically held that the presumption under Section 132(4A) is available only in regard to proceedings for search and seizure under section 132, and such presumption would not be available for framing a regular assessment. The Supreme Court has stated that section 132 being a complete code in itself cannot intrude into any other provision of the Act, and similarly other provisions of the Act cannot interfere with the scheme or the working of section 132 or its provisions. Since the Respondent-Assessee was not the person who was searched, the reliance placed on section 132(4A) by the Revenue was wholly misplaced. Hence, the Revenue appeal was dismissed.

Rajib Mukhopadhyay v. DCIT: Satisfaction notes issued ten months after completing assessment of the searched person are time-barred and invalid under Section 153C.

12. Rajib Mukhopadhyay V/s. DCIT, Circle – 42(3)(1)

[WP NO. 274 OF 2026 & 936 OF 2026, dated 17/08/2026, (Bom)(HC)]

[Assessment Years 2019-20 and 2020-21]

Section 153C: Satisfaction Note – time barred – as the same was not issued “immediately” and was issued ten months after the assessment proceedings of the searched person were completed.

The Petitioner submitted that the Satisfaction Notes dated 3rd August 2023 and 10th August 2023 were not recorded “immediately”, as stipulated by the Hon’ble Supreme Court in the case of Commissioner of Income-tax-III vs. Calcutta Knitwears [(2014) 362 ITR 673 (SC)]. Therefore, the notices issued under section 153C of the Act be quashed and set aside. The Petitioner relied on the decision dated 24th June 2026, passed in the Petitioner’s case for Assessment Years 2015-16, 2016-17, 2017-18, 2018-19, and 2021-22.

The Hon’ble court observed that for the aforementioned Assessment, this Court had already taken a view in the Petitioner’s own case that the notice dated 10th August 2023 issued under section 153C of the Act was time barred as the same was not issued “immediately” as per law laid down by the Hon’ble Supreme Court in the case of Calcutta Knitwears (supra), since it was issued ten months after the assessment proceedings of the searched person were completed viz. on 27th September 2022. The Court also held that ten months was not a reasonable time by which the Satisfaction Note ought to have been issued by Assessing Officer of the searched person by relying upon its own decisions in Clear Channel India (P) Ltd. vs. Deputy Commissioner of Income-tax [(2026) 184 taxmann.com 434 (Bom)] and Nippon Life India Asset Management Ltd. vs. Deputy Commissioner of Income-tax [Writ Petition No.4516 of 2025 decided on 7th April 2026].

Considering the decision already taken in the Petitioner’s own case for the other Assessment Years, the above two Writ Petitions for quashing the notices dated 10th August 2023 issued under Section 153C of the Act for Assessment Year 2019-20 and 2020-21, were allowed.

Pr. CIT v. The Bombay Dyeing and Manufacturing Co. Ltd.: An assessment order passed pursuant to a Section 263 revision order cannot survive after the revision order has been quashed

35. Pr.CIT v. The Bombay Dyeing and Manufacturing Co. Ltd.: (2026) (9) TMI 872 (Bom):

A. Y. 2015-16: Date of order 28/08/2026:

S. 263 of ITA 1961

Revision of orders under section. 263 — Order passed under section. 263 quashed by the Tribunal — Appeal filed by the Department before the High Court — Pending the appeal before the High Court, assessment order passed by the AO under section. 143(3) r.w.s. 263 — Assessee’s appeal against the assessment order allowed — Department’s appeal dismissed by the Tribunal — Held that an assessment made pursuant to a revision order cannot survive after the revision order has been quashed — The fact that Department has challenged the quashing of 263 order before the High Court shall not come in the way.

An order dated 18/03/2020 was passed under section. 263 of the Act which was challenged before the Tribunal. The Tribunal quashed the order of the Principal Commissioner passed under section. 263 of the Act. Despite the fact that the Tribunal quashed the order of the Principal Commissioner under section. 263 of the Act, the Assessing Officer passed a consequential order under section. 143(3) r.w.s. 263 of the Act.

The assessee challenged the assessment order in an appeal filed before the CIT(A). The Ld. CIT(A), vide his order dated 28/03/2023 allowed the appeal of the assessee on the ground that the Assessing Officer was not correct in his action in passing the order under section. 143(3) r.w.s. 263 of the Act. Against the said order, the Department filed an appeal before the Tribunal. The Tribunal dismissed the appeal of the Department and held that order passed in pursuance of revision order passed under section. 263 which revision order itself has been quashed cannot survive. The Tribunal held that even though the Department did not accept the decision of the Tribunal in quashing the revision order passed under section. 263 and challenged the same before the High Court, it would not come in the way of disposal of the appeal before the Tribunal where the consequential assessment order was challenged.

Aggrieved by the order of the Tribunal, the Department filed an appeal before the High Court. The High Court dismissed the appeal of the Department and held as under:

“i) Merely because the Revenue is in appeal against the order dated 13 September 2021 passed by the Tribunal, whereby the order dated 18 March 2020 passed by the PCIT under section. 263 of the Act was quashed and set aside, would not bring about a situation where, in the absence of any subsisting order under section. 263 of the Act, the Assessing Officer would nonetheless have jurisdiction to proceed to pass the assessment order dated 31 October 2021.

ii) We find that the appeal does not give rise to any substantial question of law. The appeal is, accordingly, dismissed.

iii) We, however, clarify that, in the event the Revenue succeeds in Income Tax Appeal No. 938 of 2024, the legal consequences would follow and a fresh assessment order in that regard would be required to be passed in accordance with law. All contentions of the parties in the pending appeal are expressly kept open.”

Jyoti Sareen v. UOI: Reassessment notices issued by jurisdictional AOs without randomized automated allocation in a faceless manner under section 151A are void.

34. Jyoti Sareen v. UOI:

[2026] 190 taxmann.com 384 (P&H):

A. Y. 2020-21: Date of order 10/09/2026:

S. 147A r.w.ss. 148, 148A and 151A of ITA 1961/

Reassessment — Issuance of notice for re-opening — S. 151A read with the scheme framed thereunder — Notice required to be issued through randomized automated allocation and in a faceless manner — Notice issued by jurisdictional AO, not through randomized automated allocation and in a faceless manner, are invalid and without jurisdiction — Insertion of S. 147A vide Finance Act 2026 w.e.f. 01/04/2021 — With a non-obstante clause without amending section 151A or related scheme — To overturn judicial decisions and circumvent unfavourable rulings — Unconstitutional encroachment on judicial power — S. 147A unconstitutional — Notice issued by jurisdictional AO without using randomized automated allocation and not in faceless manner — Violative of S. 151A and the scheme framed thereunder — Notice under section. 148 held to be invalid.

The Assessee, a practicing Advocate, filed her return of income on 30/09/2020 for A. Y. 2020-21. The return was processed and an intimation under section. 143(1) of the Act was issued. Subsequently, on 15/03/2024, notice under section. 148 of the Act was issued by her jurisdictional Assessing Officer. As per the said notice, the Assessing Officer was in receipt of information that a search was conducted on 14/03/2022 in the case of the assessee or in case of a person in respect of which the assessee was assessable. Vide the notice issued under section. 148 of the Act, the assessee was required to file her return of income. However, the assessee was not informed of the reasons why re-assessment proceedings were being initiated against her.

The assessee challenged the notice issued under section. 148 of the Act by way of a writ petition before the High Court which petition was allowed vide order dated 19/07/2024 on the reasoning that the notice issued under section. 148 of the Act was in violation of section 151A read with the scheme framed thereunder. The High Court agreed with and relied upon the decisions of the Hon’ble Telangana High Court in Kankanala Ravindra Reddy v. ITO [2023] 156 taxmann.com 178, the Hon’ble Bombay High Court in Hexaware Technologies Ltd. v. Asstt. CIT [2024] 162 taxmann.com 225 (Bom.) and the Hon’ble Gauhati High Court in Ram Narayan Sah v. Union of India [2024] 163 taxmann.com 478 (Gauhati).

The judgements were challenged by the Department before the Hon’ble Supreme Court. Pending disposal before the Hon’ble Supreme Court, section 147A was inserted vide the Finance Act, 2026 which is made applicable with retrospective effect from 01/04/2021. Section 147A starts with a non-obstante clause and provides that notwithstanding anything contained in any judgment, order or decree of any court or in section 151A or in any scheme framed under section. 151A, for the removal of doubts, the Assessing Officer, for the purposes of sections 148 and 148A, shall mean and shall always be deemed to have meant to be an Assessing Officer other than the National Faceless Assessment Centre or any assessment unit referred to in subsection (3) of section 144B.

In light of the insertion of section 147A, the Hon’ble Supreme Court set-aside the judgments of the High Courts and remitted the matters to the jurisdictional High Courts for fresh consideration. The Hon’ble Supreme Court did not express any opinion on the merits of the controversy and left all the contentions open to be decided by the respective jurisdictional High Courts.

Pursuant to the directions of the Hon’ble Supreme Court the assessee and several other assessees amended their original petition so as to include the challenge to the newly inserted section 147A of the Act.

The Punjab and Haryana High Court allowed the petition of the assessee and held section 147A to be unconstitutional on the ground that the legislature introduced the section so as to circumvent the unfavourable judgments of the High Courts and therefore such enactment was unconstitutional in the eyes of law. The High Court further held that the notices issued by jurisdictional Assessing Officer who was not selected through randomised automated allocation and in a faceless manner was invalid and without jurisdiction and in violation of section 151A and the scheme framed thereunder. The relevant observations of the High Court are as under:

“i) Section 147A of the Act begins with a non-obstante clause – “Notwithstanding anything contained in any judgment, order or decree of any court or in section 151A or in any scheme framed thereunder.” Through the retrospective enactment of section 147A, the legislature primarily sought to validate the notices issued to the assessees under section. 148 of the Act by their respective jurisdictional AOs by neutralizing the effect of judgments of the constitutional courts through which it had been held that notices issued to the assessees under section. 148 of the Act by their jurisdictional AOs were illegal because in terms of section 151A of the Act, read with the scheme framed thereunder, such notices were required to be issued only by a faceless AO.

ii) The doctrine of separation of powers is not an express part of the Indian Constitution but this doctrine is clearly visible from the scheme of our Constitution. The Indian Constitution makes a clear demarcation between the judiciary, executive and the legislature and seeks to maintain separation of powers between the three organs of the State. Such division is fundamental to the rule of law. A breach by either also negates equality enshrined under Article 14 of the Indian Constitution. Under Articles 245, 246 and other companion Articles, read with the respective lists in the seventh schedule of the Indian Constitution, the legislature has the right to “make” laws which includes the power to amend the law but the legislature cannot “declare” what the law laid down by the constitutional courts was meant to be. The legislature also cannot directly annul a judgment of a constitutional court or through a mere declaration overrule a judicial decision. To permit so would allow the legislature to legislatively superimpose judgments which would have attained finality between the parties and that would result in chaos.

iii) Granted the legislative competence, the legislature can, even retrospectively, enact a law validating a statute which has been held by a Court to be illegal provided that through such validating law the legislature removes the basis or foundation of the judgment of the Court by curing the defect(s) pointed out by the courts in the statute as it existed before the promulgation of the validation law. The effect of the validating legislation should be such that the judgment of the Court pointing out the defect would have not been passed if the validating law existed before the Court at the time of delivering its judgment and that after taking into effect the validating law it should not be possible for the Court to arrive at the same decision. Through enacting the validating law, the legislature must bring the law in line with the decision of the Court. Setting at naught a decision of a Court without removing the defect pointed out through the decision of the Court is opposed to the rule of law and also breaches the doctrine of separation of powers recognized by the Indian Constitution. Abrogation is not to be used as a device by the legislature to by-pass an unfavourable judicial decision and that if the validating legislation is enacted solely with the intention to defy a judicial pronouncement, such legislation would be an example of legislature overreach and therefore, unconstitutional.

iv) The non-obstante clause, with which section 147A of the Act begins, seeks to wipe out the effect of any judgment, order or decree of any Court or whatever is contained in section 151A or in the scheme framed thereunder but in the non-obstante clause reference to section 130 of the Act or the scheme framed thereunder dated 28/03/2022 is conspicuously found missing. This fact assumes importance because the afore referred scheme was inter alia relied upon by the Telangana High Court in Kankanala Ravindra Reddy’s case (supra) to hold that a notice under section. 148 of the Act could only have been issued by a faceless AO.

v) Section 147A only seeks to remove doubts and clarify that an Assessing Officer for the purpose of issuance of notices under section. 148 and 148A of the Act shall mean and shall always deemed to have meant an Assessing Officer other that the National Faceless Assessment Centre or any assessment unit referred to in section 144B(3). Section 147A is noticeably silent with regard to the categoric findings returned by the constitutional courts that as per the scheme dated 29/03/2022, framed under section. 151A, allocation of AOs is required to be done randomly and through automated allocation.

vi) Thus, the aforementioned two reasons which inter alia formed the basis of the judgments of the Constitution Courts to set aside the notices issued under section. 148 of the Act were not cured through the retrospective enactment of section 147A. In fact, they even find no reference therein.

vii) The Constitution courts categorically held that in terms of section 151A of the Act, read with the scheme framed thereunder dated 29/03/2022, a notice under section. 148 of the Act could “only” be issued by a faceless AO. Through and even after the retrospective enactment of section 147A, section 151A of the Act and the scheme framed thereunder continue to exist on the statute book and without any amendment. Thus, the primary basis on which the constitutional courts had held that notices issued under section.148 of the Act could not have been issued by the assessees’ jurisdictional AOs has not been removed through the retrospective enactment of section 147A. Without amending section 151A of the Act or the scheme framed thereunder, the “clarification” made by the legislature through the retrospective enactment of section 147A that Assessing Officers for the purpose of issuance of notices under section. 148 of the Act mean and shall always deemed to have meant to be Assessing Officers other than the faceless AOs is in defiance of and in conflict with the law laid down by the constitutional courts. Through such “clarification”, the legislature visibly seeks to substitute its opinion over and above the findings returned by the constitutional courts which is legally impermissible. Section 147A is also clearly found to be in direct conflict with section 151A, read with the scheme framed thereunder, all of which provisions simultaneously exist in the same statute. In the absence of any amendment to section 151A and/or the scheme framed thereunder, simply because section 147A begins with a non-obstante clause, would not make its retrospective enactment pass the test of a constitutionally enacted validation law. Rather, by the retrospective enactment of section 147A, in the manner in which it has been done, the legislature has clearly trenched upon judicial power and through the introduction of section 147A the legislature directly seeks to upset findings returned through judgments of several constitutional courts. The attempt by the legislature is clearly to circumvent unfavourable judicial decisions.

viii) Even today, if a matter is listed before the constitutional courts which rendered the afore verdicts as to who is the competent Assessing Officer to issue a notice under section. 148 of the Act, there would be no change in the rendering of the above referred verdicts because such verdicts were primarily based on section 151A and the scheme framed thereunder dated 29/03/2022 which provision and the scheme still continue to exist on the statute book as they existed at the time when the judgments of the constitutional courts were rendered. In the light of the considered and categoric findings returned by the constitutional courts after carefully analyzing section 151A of the Act and the scheme framed thereunder that only a faceless AO can issue a notice under section. 148 of the Act, the “clarification” which is in clear defiance of and contrary to the afore findings, made by the legislature through the retrospective enactment of section 147A of the Act would be of no help to the respondents.

ix) Under section 151A(1) of the Act, the Central Government framed a scheme dated 29/03/2022 in clause 3(b) whereof it was specifically mentioned that such scheme applies to the issuance of notices under section. 148 of the Act. The object behind framing of the said scheme, which is clearly brought out on a bare reading of section 151A(1) of the Act, was that the scheme was framed for the purpose of imparting greater efficiency, transparency and accountability by eliminating the interface between the income-tax authorities and the assessees or any other persons. Under section. 151A(2) the Central Government, for the purpose of giving effect to the scheme made under section. 151A(1), by issuance of a notification in the Official Gazette, could direct that any of the provisions of the Act shall not apply or shall apply with such exceptions, modification etc. as the case may be but in terms of the first proviso to section 151A(2) no such direction could be issued after 31/03/2022. After having specifically included issuance of notices under section. 148 of the Act in the scheme framed under section. 151A(1) it was only till 31/03/2022 that the Central Government could have issued a notification for the exclusion of applicability of section 148 of the Act to the scheme framed under section. 151A(1) and not thereafter. Till 31/03/2022 no such notification was issued by the Central Government. What was prohibited under section. 151A of the Act could and should have not been done through the retrospective enactment of section 147A.

x) As per the memorandum which accompanied the Finance Bill, 2026, section 147A was being enacted in the light of emergence of divergent views of the constitutional courts with regard to the jurisdiction of Assessing Officers for issuance of notices under section. 148 of the Act. According to the memorandum, enactment of section 147A was necessary to bring certainty and clarity as also to avoid litigation. However, through the enactment of section 147A of the Act, none of the objects behind its enactment stand achieved. Rather, what followed the enactment of section 147A of the Act resulted in everything to the contrary. The “clarification” made through the retrospective enactment of section 147A was that an Assessing Officer, for the purpose of issuance of notice under section 148 of the Act, meant and was always deemed to have meant to be an Assessing Officer other than the faceless AO. Such “clarification” was in conflict with the findings returned by as many as nine constitutional courts of this country to the effect that as per section 151A of the Act and the scheme framed thereunder only a faceless AO could issue a notice under section. 148 of the Act. Section 151A and/or the scheme framed thereunder continue to exist on the statute book simultaneously with section 147A. Therefore, introduction of section 147A of the Act did not bring any clarity or certainty. It only added to the confusion.

xi) The other purpose behind enactment of section 147A of the Act was to avoid litigation but such enactment became the breeding ground of litigation as thousands of petitions on the issue in question are pending in at least in eight different High Courts across the length and breadth of this country and that such litigation is also not likely to end before the respective High Courts because the parties aggrieved by the judgment of the respective jurisdictional High Courts would likely take up the matter before the Supreme Court. If it is a judgment of the Supreme Court which is ultimately going to give a quietus to the entire matter then rather than, for the afore “objects”, retrospectively enacting section 147A, it was desirable for the respondents to have invited an early opinion of the Supreme Court at the time when cross petitions were pending before the Supreme Court, filed by the respective parties aggrieved by the divergent views expressed by different jurisdictional High Courts as that would have finally put a lid on this issue. In the light of the afore discussion, we have no hesitation to declare section 147A of the Act to be unconstitutional.

xii) After a careful reading of the scheme dated 29/03/2022, framed under section. 151A of the Act, we find that clause 3(b) of the scheme clearly makes it applicable to issuance of notices under section. 148 of the Act. Section 151A under which the said scheme has been framed, defines the purpose behind framing of the scheme which is to impart greater efficiency, transparency and accountability by eliminating the interface between the income tax authorities and the assessees. When clauses 2 and 3 of the scheme are harmoniously read with the purpose behind framing of the scheme, the only conclusion that can be arrived at is that as per the scheme framed under section. 151A, notices under section. 148 are required to be issued through randomized automated allocation and in a faceless manner. This is what is clearly conveyed through a plain reading of the scheme. Such interpretation is also in line with the intent of the Government of India behind introduction of the faceless regime. There is no other way that the scheme can be read to make it meaningful.

xiii) Thus, if on a plain reading of clause 3(b) of the scheme issuance of notice under section. 148 of the Act is required to be sent through randomized automated allocation and in a faceless manner, then issuance of notice under section. 148 of the Act cannot be permitted to be done in any other manner.

xiv) The phrase in the scheme dated 29/03/2022 “to the extent provided in section 144B of the Act with reference to making assessment or reassessment of total income or loss of the assessee” implies that Clause 3 of the said scheme does not apply to issuance of notices under section. 148 of the Act because section 144B specifically excludes reassessment proceedings under sections 148 and 148A. Such a submission does not warrant acceptance because when the scheme dated 29/03/2022 is read as a whole, the afore quoted phrase is found to apply only to Clause 3(a) of the scheme and this is so because assessment or reassessment is done under section. 147 of the Act. Further, clause 3(a) of the scheme makes the scheme applicable to proceedings under section. 147 of the Act and under clause 3(b) to issuance of notices under section. 148 of the Act. The scheme does not apply to any other proceedings under the Act. Therefore, if the afore submission of the respondents is to be accepted and the scheme is held not to apply to the issuance of notices under section. 148 then framing of the scheme dated 29/03/2022, under section. 151A of the Act, would itself be rendered as a dead letter because conduct of assessment, reassessment or re-computation under section. 147 of the Act, through randomized automated allocation and in a faceless manner, is already covered under section. 144B of the Act. As per the law settled by the Supreme Court interpretation of the scheme in question, which would render it to a dead letter, should be avoided.

xv) On a plain reading of the scheme framed under section. 151A of the Act, it is unambiguously found that clause 3(b) of such scheme clearly applies to the issuance of notices under section. 148 of the Act and requires such notices to be issued in a faceless manner. If the respondents’ submission is accepted then the whole purpose behind enactment of section 151A of the Act and the scheme framed thereunder to introduce a faceless regime as also to allocate AOs through automated allocation and in a random manner shall stand defeated. Once the scheme provides for randomised automated allocation of AOs there is no question of conferment of concurrent jurisdiction on faceless AOs and jurisdictional AOs. As discussed earlier, if a plain reading of the scheme in question requires notices to be issued under section. 148 of the Act through randomised automated allocation of assessing officers and in a faceless manner then there is no other way that these notices can be permitted to be issued.

xvi) Even otherwise, in the light of the conflict between the afore referred notifications issued under section. 120 of the Act by the CBDT and section 151A of the Act read with the scheme framed thereunder, the provisions of the Act read with the scheme framed thereunder shall prevail especially when such scheme has also been accorded approval by both the houses of Parliament.

xvii) Viewed from yet another angle, as mandated under the scheme framed under section. 151A of the Act, the impugned notices issued to the petitioners under section. 148 have also not been issued by AOs appointed randomly and through automated allocation rendering them illegal on this count alone.

xviii) In the light of the above discussion, after holding section 147A of the Act to be unconstitutional and directing it to be struck down, we further order setting aside of the notices issued to the petitioner(s) under section. 148 of the Act because such notices have not been issued through the process of randomized allocation of assessing officers and in a faceless manner as is mandated under section. 151A of the Act read with the scheme framed thereunder dated 29/03/2022.”

Pr. CIT v. J D Exim (P.) Ltd.: Unexplained cash additions under section 68 cannot be sustained when money was received in a prior financial year.

33. Pr.CIT v. J D Exim (P.) Ltd.:

(2026) 189 taxmann.com 801 (Del.):

A. Y. 2016-17: Date of order 18/08/2026:

S. 68 of the ITA 1961/S. 102 of ITA 2025

Cash Credit — S. 68 — Amount received in F. Y. 2006-07 as advance towards sale of land — Sale deed executed by Power of Attorney holder in F. Y. 2013-14 — Transaction came to knowledge of the assessee in F. Y. 2015-16 — Transaction of sale recorded and reflected in A. Y. 2016-17 — Since there was loss, the capital gain on sale of land was set-off against the capital loss — May be colourable device — However, section 68 cannot be resorted to in A. Y. 2016-17 as the amount was received in F. Y. 2006-07 — Addition under section. 68 in A. Y. 2016-17 cannot be sustained.

During the F. Y. 2006-07, the assessee received `10 crores as advance consideration for sale of land. However, the transaction was not culminated. The power of attorney holder of the assessee executed a sale deed in the F. Y. 2013-14. However, the assessee was not informed about the execution of sale deed by the power of attorney holder. The transaction of sale and the execution of sale deed came to the knowledge of the assessee in F. Y. 2015-16. Since the assessee came to the knowledge in F. Y. 2015-16, the assessee reflected the transaction in the return of income filed for A. Y. 2016-17. However, since the assessee had capital loss, the long-term capital gain arising from the transfer of land was set-off.

During the course of assessment proceedings, the Assessing Officer observed and noted that the purchaser had recorded the transaction in F. Y. 2013-14 and held that recording of the sale transaction by the assessee in F. Y. 2015-16 relevant to A. Y. 2016-17 where the assessee had loss was a colourable device to set-off the loss against the gains. Accordingly, the Assessing Officer held that the advance of `10 crores taken by the assessee was unexplained and therefore added the same under section. 68 of the Income-tax Act, 1961, in the hands of the assessee in A. Y. 2016-17.

On appeal, the CIT(A) and the Tribunal held that the addition of Rs. 10 crores under section. 68 of the Act was not justified for A. Y. 2016-17 as the assessee had received the amount in the F. Y. 2006-07.

The Delhi High Court dismissed the appeal filed by the Department and held as under:

“i) May be the assessee had adopted a device to avoid or to circuitously availing set-off of capital loss against the capital gain, which he had earned two years earlier. But for dealing with such situation or case, there were other and better modes or measures available with the Assessing Officer. For the purported avoidance or colourable device, taking recourse to section 68 of the Act of 1961, within the statutory framework was not permissible, more particularly, when the assessee had admittedly received the amount of `10 crores way back in the F. Y. 2006-07.

ii) The amount of `10 crores was received by the respondent/assessee in the F. Y. 2006-07 and, therefore, adding that amount in the year under consideration (A. Y. 2016-17) is against anybody’s comprehension. Such addition cannot be sustained.”

CIT v. Baba Gandha Singh Education Trust: Generating surplus funds by an educational trust does not justify cancelling Section 12AA registration without proof of non-object activities

32. CIT v. Baba Gandha Singh Education Trust: (2026) 489 ITR 217 (P&H): 2026 SCC OnLine P&H 17341: (2026) 350 CTR 336 (P&H):

Date of order 27/02/2026:

Ss. 2(15) and 12AA of ITA 1961

Charitable trust — Registration under section. 12AA — Charitable purpose — S. 2(15) — Cancellation of registration — Condition precedent — Finding that assessee is not carrying out its activities in line with its objects — Has to be proved with material on record — Mere generation of surplus money by itself is not a ground to cancel registration — No finding that assessee had generated surplus by indulging in any activity not as per its objects — Manner in which surplus used could not be dictated by — Assessee using surplus to invest in educational infrastructure — That assessee failed to use surplus to allow subsidy to poor students is not a ground for cancellation of registration.

The assessee-trust, Baba Gandha Singh Educational Trust, was pursuing educational activities. On application made by the assessee trust on April 11, 2007, the assessee trust was granted registration under section. 12AA of the Income-tax Act, 1961, vide order dated August 29, 2007 with effect from April 1, 2007 for pursuing educational activities. On November 5, 2009, the Commissioner of Income-tax, Patiala issued a notice under section. 12AA(3) of the Act proposing to cancel the registration of the assessee-trust on the ground that it was generating surplus for the A. Y. 2002-03 to A. Y. 2007-08 and therefore went beyond the purpose for which registration was accorded to it. The assessee in its reply to the show-cause notice pleaded that it was imparting education and the surplus generated was ploughed back by way of investment in capital assets. In furtherance of its stated object generation of surplus by running the educational institution and its utilization for education purpose would not disentitle it from exemption/cancellation of registration under section. 12AA(3) of the 1961 Act.

The Commissioner of Income-tax vide order dated March 16, 2010, cancelled the registration under section. 12AA(3) of the Act, after review of copies of accounts filed by the Income-tax Officer, Barnala for the A. Y. 2002-03 to A. Y. 2007-08 holding that the assessee-trust was generating huge surplus year after year, which shows that the trust was not carrying on activity as per section 2(15) of the 1961 Act wherein charitable activity has been defined. While cancelling the registration under section. 12AA(3) of the Act, reliance was placed upon the judgment of the Supreme Court in Municipal Corporation of Delhi v. Children Book Trust [(1992) 3 SCC 390; 1992 SCC OnLine SC 381.] and the judgment of the Hon’ble Uttarakhand High Court in CIT v. Queens’ Educational Society [(2009) 319 ITR 160 (Uttarakhand); 2007 SCC OnLine Utt 103.].

On appeal, Tribunal noticed that pertinently the Commissioner does not dispute that the assessee-trust was carrying on educational activities which is admittedly the dominant objective of the assessee-trust. Notably the assessee-trust is engaged in running schools and the Commissioner of Income-tax has not pointed out any other activity being carried out by the assessee-trust. The Tribunal thereafter allowed the appeal and set aside the cancellation of registration under section. 12AA of the 1961 Act in favour of the assessee-trust.

The Punjab and Haryana High Court dismissed the appeal filed by the Department and held as under:

“i) From a plain reading of section 12AA(3) of the 1961 Act, it is apparent that registration can be cancelled when the Commissioner of Income-tax is satisfied that the activities of trust or institution are not genuine and are not being carried out in accordance with the objects of trust or institution as the case may be. A bare reading of section 12AA(3) of the 1961 Act, therefore, makes it mandatory for the Commissioner of Income-tax to conclude that the trust/institution is not carrying out its activities in line with the objects of the trust.

ii) In the present case, the Commissioner of Income-tax, while cancelling the registration under section. 12AA of the 1961 Act vide the order dated March 16, 2010, had recorded that (1) the respondent-trust is generating surplus since 2002-03 to 2007-08, and (2) that the trust has not waived fee of a large number of students as only fee of 56 students was waived out of 2,901 students, which is two per cent. of the total students showing the absence of any subsidy for the poor and needy.

iii) In fact, in the present case, the Commissioner of Income-tax has failed to find any deviation on the part of the respondent-society from the objects for which it was registered. There is no finding that the trust/society has generated a surplus by indulging in any activity which is not as per its objects. The manner in which surplus money has been used cannot be dictated by the Commissioner of Income-tax but can only be adjudged in accordance with the objects of the society. However, there is no such finding by the Commissioner of Income-tax as to attract the provisions of section 12AA(3) of the 1961 Act. Therefore, in the present case, the sole ground on which the certificate under section. 12AA of the 1961 Act was cancelled by the Commissioner of Income-tax is generation of surplus money.

iv) Therefore, mere generation of surplus money, if the same is in the course of providing education or education activities or for objects for which registration under section 12AA of the Act has been accorded, in that case, surplus money by itself cannot be a ground to cancel the registration. In the present case, there is a total absence of a finding by the Commissioner of Income-tax that the respondent-trust had generated surplus money by indulging in activities other than the objects for which it was registered or that the surplus amount was used for activities other than its objects.

v) In fact, the impugned order of the learned Tribunal goes to show that the learned Tribunal had rightly concluded that no basis for which registration can be cancelled under section. 12AA(3) of the Act has been given by the Commissioner of Income-tax and mere generation of surplus money cannot lead to the conclusion that the trust had not earned the same by running activities as per its objects. The learned Tribunal has rightly held that this needs to be proved with material on record.

vi) The learned Tribunal has rightly concluded that no violation of section 12AA(3) of the Act has been made by the respondent and mere generation of surplus continuously would not result in the assumption that the respondent had earned the same by violating its objects.

vii) The questions of law are thus answered in favour of the respondent and against the appellant in view of the above discussion.

viii) In view of the above discussion, we do not find any merit in the present appeal and the same is accordingly dismissed.”

Honda R & D Company Ltd. v. ACIT(IT): Cost-to-cost reimbursement of salary paid to seconded employees did not constitute fees for technical services under India-Japan DTAA.

14. [2026] 186 taxmann.com 1061 (Delhi – Trib.)

Honda R & D Company Ltd vs. ACIT(IT)

A.Y.: 2018-19 & 2022-23 Dated: 27 May 2026

Article 13 of India-Japan DTAA – Cost-to-cost reimbursement of salary paid to seconded employees did not constitute fees for technical services, and hence, could not be taxed in India.

FACTS

The Assessee was a tax resident of Japan. It was engaged in conducting research and development of Honda products. The Assessee seconded certain employees to its group companies in India. Under the terms of the secondment, the Assessee paid part of the salary payable to seconded employees in their home country and Indian entities reimbursed it on cost-to-cost basis.

The AO contended that salary reimbursement was in nature of fees for technical services (‘FTS’) under the Act and the India-Japan DTAA. The DRP upheld the draft assessment order.

Aggrieved by the final order, the Assessee preferred an appeal before ITAT.

HELD

From perusal of the secondment agreement, the ITAT observed the following:

  • during the secondment period, seconded employees were to be released from work obligations in their home country and worked solely for the Indian company;
  • during the secondment period, seconded employees were not to act on behalf of the overseas entity;
  • seconded employees were to act under direction and supervision of Indian entity;
  • Indian entity was to bear risk and assume responsibility for the work performed by seconded employees;
  • Indian entity was obligated to pay the whole of the salary; and
  • performance of seconded employees was to be evaluated by Indian entity.

The contract of employment between the Indian entity and seconded employees, read together with the secondment agreement, establish employer-employee relationship between the Indian entity and seconded employee.

On similar facts, in Advics Co. Ltd. v. ACIT (IT) [2024] 165 taxmann.com 716 (Delhi – Trib.), the Coordinate Bench noted differences to distinguish the Delhi High Court’s ruling in Centrica India Offshore (P.) Ltd. [364 ITR 336] and, in particular, that in Centrica, it was found that the foreign company had rendered services through its employees to Indian entities while being the employer of the personnel.

In Toshiba Corporation [2025] 181 taxmann.com 244, the Coordinate Bench, relying on the Delhi High Court’s decision in Boeing India (P.) Ltd [457 ITR 84], had held that once the payments are regarded as salaries to employees, they should be excluded from the scope of ‘FTS’.

IMAX Theatre Services Ltd. v. ACIT (IT): Rendering remote maintenance services through an independent Australian vendor’s employee staying under 90 days does not constitute a fixed place PE.

13. [2026] 186 taxmann.com 526 (Delhi – Trib.)

Imax Theatre Services Ltd. vs ACIT (IT)

A.Y.: 2022-23 Dated: 13 May 2026

Article 5 of India-Canada DTAA – On facts, maintenance services rendered in India through an Australian vendor, without satisfying disposal and permanence test, did not constitute fixed place PE in India. Also, since physical presence of Australian vendor in India was less than 90 days, no service PE was constituted.

FACTS

The Assessee was a tax resident of Canada. Canadian tax authority had issued a tax residency certificate (“TRC”) to it. The Assessee rendered maintenance services for IMAX theatres to Indian and global customers. The Assessee had engaged an Australian vendor to provide the services. Generally, the services were rendered remotely by accessing the systems. Sometimes, an employee of the vendor visited the premises of the customer. The LinkedIn profile of the vendor’s employee showed that he worked full-time for the Assessee.

On the basis of the LinkedIn profile of the employee of the vendor, the AO concluded that the activity of the Assessee constituted both a fixed place PE and a service PE. Therefore, he assessed 25% of receipts as income. The DRP was of the view that the activity constituted fixed and supervisory PE1. However, it reduced the attribution to 12.5%.

Aggrieved by the final order, the Assessee preferred an appeal before ITAT.

Before ITAT, the Assessee submitted an affidavit of the Australian vendor clarifying that it had multiple customers globally, including India, and the person was not an employee of the Assessee. The Assessee further submitted that vendor’s employee visited the premises of the Indian customers of the assessee for a total period of 67 days for rendering maintenance services, which was less than 90 days stipulated in the India-Canada DTAA for constituting service PE.


1 The threshold for determining supervisory PE under India-Canada DTAA is 120 days

HELD

The ITAT considered arguments of the Assessee and noted that the services were largely rendered remotely; the access to the theatre systems was limited to fixing bugs and troubleshooting, and the assessee had no unfettered access or right to control the customers’ systems.

The ITAT observed that none of the tests, i.e. place of business, disposal and permanence test, were satisfied in the case of the Assessee. Therefore, the provision of maintenance services did not constitute a fixed place PE.
The ITAT relied on Ernst and Young (EMEIA) Services Ltd. v. ACIT (IT) [2026] 184 taxmann.com 671 (Delhi – Trib.) to hold that services rendered remotely could not be considered for determining service PE. Since the presence of the vendor’s employee in India was below the required threshold, no service PE was constituted.

The LinkedIn profile of the Australian vendor’s employee is not conclusive proof of employer-employee relationship between the individual and the Assessee, especially when the Australian vendor had made an affidavit mentioning that the person was its employee.

In light of the foregoing, the ITAT held that maintenance services did not constitute PE of the Assessee.

Melongos India (P.) Ltd. v. Income Tax Officer: Each registered sale deed represents an independent transfer chargeable in its respective year, and appellate authorities may evaluate fresh deduction claims.

56. [2026] 138 ITR(T) 617 (Chennai – Trib.)

Melongos India (P.) Ltd. v. Income Tax Officer

A.Y.: 2013-14, 2014-15 & 2015-16 DATE: 25.03.2026

Sec. 45 read with sections 50C and 2(47), and Sec. 54D read with sections 54F and 54G – Capital gains – Assessee transferred immovable property through eight registered sale deeds executed across FYs 2012-13 to 2014-15 but offered entire LTCG in AY 2014-15 – Each registered sale deed constituted independent transfer and capital gains chargeable in respective years of transfer – Fresh claims for deductions under sections 54D, 54F and 54G though not made in original/revised return to be examined on merits by AO as restriction under Goetze (India) Ltd. applies only to AO and not to appellate authorities.

FACTS

The assessee-company owned immovable property situated in Chennai, which was acquired during FY 2004-05 for a consideration of Rs. 3,00,00,000 and transferred through eight registered sale deeds executed across FYs 2012-13, 2013-14 and 2014-15 for an aggregate sale consideration of `7,40,95,500. The assessee offered the entire long-term capital gains in AY 2014-15.

During scrutiny for AY 2014-15, the AO noted that transfers occurred in multiple years, taxed only the portion transferred in FY 2013-14, invoked section 50C, and denied deduction under section 54D. Pursuant to the PCIT’s order under section 263, the AO passed a consequential order under section 143(3) read with section 263 for AY 2014-15 recomputing LTCG at about
`8.15 crores by adopting stamp duty value for the entire property under section 50C.

The AO initiated reassessment for AY 2013-14 under section 147 and brought to tax LTCG attributable to five sale deeds executed in FY 2012-13, determining LTCG at about `4.44 crores by applying section 50C. The AO also initiated reassessment for AY 2015-16 and taxed LTCG on the portion transferred in FY 2014-15.

For AY 2013-14, the CIT(A) upheld reopening of assessment and taxation of capital gains relating to FY 2012-13 transfers and sustained application of section 50C. For AY 2015-16, after an earlier remand by the Tribunal, the CIT(A) again confirmed that gains on two sale deeds transferred in FY 2014-15 were taxable in AY 2015-16.

For AY 2014-15, the CIT(A) held that only the portion transferred on 07.03.2014 was taxable in that year and directed computation confined to that portion with section 50C on a proportionate basis.

The assessee appealed to the Tribunal.

HELD

On the validity of reassessment proceedings under section 147 for AYs 2013-14 and 2015-16, the Tribunal held that since the returns were processed under section 143(1) and no scrutiny assessment was carried out, and the AO had gathered information during the scrutiny assessment for AY 2014-15 regarding non-offering of capital gains in the respective years, the AO rightly invoked the assumption of jurisdiction under section 147, and the reassessment proceedings were valid.

On the core issue of year of taxability, the Tribunal held that as per section 45 read with section 2(47), capital gains arise in the year in which transfer takes place, and each registered sale deed constitutes an independent transfer of a capital asset, therefore capital gains were chargeable to tax in the respective assessment years in which the transfers took place, and the assessee’s contention that the entire transaction should be taxed in a single year could not be accepted.

On the consequential order under section 263 for AY 2014-15, the Tribunal found no infirmity in the CIT(A)’s approach of restricting computation only to the portion of property transferred during the relevant year, but restored the computation to the file of the AO for limited purpose of re-computation.

On the claims of deduction under sections 54D, 54F and 54G, the Tribunal held that the restriction laid down in Goetze (India) Ltd. v. CIT [2006] 157 Taxman 1/284 ITR 323 (SC) applies only to the Assessing Officer and not to appellate authorities, and accordingly restored the issue to the file of the AO to examine the claim of deduction on merits.

The Tribunal further directed the AO to grant appropriate relief to avoid double taxation, as the assessee had contended that the same income had been subjected to tax in multiple years.

Addl. CIT, Special Range-7 v. PNB Gilts Ltd: Sufficient interest-free funds preclude interest disallowance under section 14A, and mark-to-market losses on stock-in-trade are allowable as legitimate valuation losses.

55. [2026] 138 ITR(T) 221 (Delhi – Trib.)

Addl. CIT, Special Range-7 v. PNB Gilts Ltd

A.Y.: 2012-13 & 2013-14                                                

DATE: 25.03.2026

Sec. 14A read with Rule 8D(2)(ii) and 8D(2)(iii), and Sec. 36(1)(iii) read with Sec. 145A, of the Income-tax Act, 1961 – Expenditure incurred in relation to income not includible in total income and Interest on borrowed capital – Assessee NBFC held shares and bonds as stock-in-trade and earned exempt income – Assessee had sufficient interest-free funds (share capital and reserves of `577.64 crores) exceeding value of stock-in-trade yielding exempt income (`65.80 crores) – No disallowance under section 14A read with Rule 8D(2)(ii) could be made – Disallowance under section 36(1)(iii) solely due to earning tax-free income unjustified – Provision for diminution/mark-to-market loss on securities held as stock-in-trade allowable as legitimate valuation loss.

FACTS

The assessee, a Non-Banking Financial Company (NBFC) was engaged in trading in government securities and debt market instruments, and held shares and bonds as stock-in-trade. For A.Y. 2012-13, it earned exempt income comprising dividend of about `4.78 lakhs and interest on tax-free bonds of about `4.16 crores, aggregating to about `4.21 crores.

During assessment, the AO invoked section 14A and computed disallowance under Rule 8D(2)(ii) at about `3.93 crores and under Rule 8D(2)(iii) at about `34.25 lakhs, making a total disallowance of about `4.27 crores.

The AO also disallowed interest of approximately `30.61 lakhs under section 36(1)(iii) on the ground that the assessee had earned substantial tax-free interest income. Further, the AO disallowed a provision for diminution in market value of stock of about `6.56 crores.

In appeal, the CIT(A) observed that the assessee had interest-free funds (share capital and reserves) of about `577.64 crores, exceeding the average value of stock-in-trade yielding exempt income (about Rs. 65.80 crores), deleted the interest disallowance computed under Rule 8D(2)(ii), and sustained only about Rs. 34.25 lakhs under Rule 8D(2)(iii), and also deleted the additions under section 36(1)(iii) and on account of diminution in market value. The assessee appealed to the Tribunal.

HELD

The Tribunal held that no disallowance under section 14A could have been made in the absence of a valid and reasoned satisfaction recorded by the AO, as the satisfaction recorded was mechanical and bereft of application of mind, and relying on the decision of Hon’ble Supreme Court in Godrej & Boyce Manufacturing Company Ltd. v. Dy. CIT [2017] 81 taxmann.com 111, it was held that recording of proper satisfaction is a sine qua non for invoking section 14A.

Even otherwise, no disallowance of interest under section 14A read with Rule 8D(2)(ii) could be made as the assessee had sufficient interest-free funds, and following the decision of Hon’ble Supreme Court in CIT v. Reliance Industries Ltd. (Civil Appeal No. 10 of 2019, dated 2-1-2019) and the decision of Hon’ble Bombay High Court in Pr. CIT (Central) v. Ashok Apparels (P.) Ltd. [2019] 106 taxmann.com 63, where sufficient interest-free funds are available, a presumption can be made that investments are out of such funds and no interest disallowance can be made.

On the issue of disallowance under section 36(1)(iii), the Tribunal held that the AO failed to take into account the fact that the assessee had sufficient capital and reserve and surplus of `577.64 crores which was in excess of the amount of bonds and shares on which tax-free income had been earned, and it was to be presumed that the tax-free income was earned on account of interest-free funds available with the assessee.

On the issue of diminution in market value of stock, the Tribunal held that the depreciation in value of securities provided in the books of account represented a legitimate valuation loss of stock-in-trade, computed in accordance with RBI guidelines, recognized accounting principles, and the consistent method of accounting followed by the assessee, relying on the decision of Hon’ble Supreme Court in United Commercial Bank v. CIT [1999] 106 Taxman 601, wherein it was held that banks are entitled to value their stock-in-trade at cost or market value, whichever is lower, and the resultant diminution represents an allowable deduction.

In the result, both appeals filed by the Revenue were dismissed.

Manish Pushkar Dayal Singhal v. Income-tax Officer: Penalty under section 271B was deleted because the assessee maintained a bona fide belief regarding turnover calculation thresholds for tax audit.

54. (2026) 189 taxmann.com 556 (Mum Trib)

Manish Pushkar Dayal Singhal v. Income-tax Officer

A.Y.: 2022-23 Date of Order : 12.08.2026

Sections: 271B, 44AB

Where the assessee bona fide believed that tax audit was not required since its turnover excluding GST was below audit threshold limit under section 44AB, in the absence of any evidence of deliberate or bona fide failure, such bona fide belief constituted reasonable cause and therefore penalty under section 271B was to be deleted.

FACTS

The assessee, an individual running the proprietary concern was engaged in manufacturing and selling packaging materials, filed his return for A.Y. 2022-23 declaring income of about Rs. 3.73 lakhs.

The assessment under section 143(3) read with section 144B was completed without variation. During assessment, the Assessing Officer noted from the assessee’s GSTR-1 that the total invoice value was about Rs. 11.59 crores inclusive of GST, exceeding the Rs. 10 crore threshold under section 44AB, whereas the Profit & Loss account reflected sales of about Rs. 9.82 crores net of taxes. Referring to section 145A(ii), the AO held that sales had to be considered inclusive of tax for determining tax-audit liability, and levied a penalty of Rs. 1.50 lakhs under section 271B for failure to get the accounts audited.

On appeal, the assessee contended that his total taxable value, as per GSTR-1, was about Rs. 9.83 crores — below the section 44AB threshold — but the CIT(A) held that the assessee had failed to establish that turnover was below the prescribed limit, and confirmed the penalty.
Aggrieved, the assessee filed an appeal before ITAT.

HELD

The Tribunal observed as follows:

(a) The central issue in a penalty matter of this nature was whether the assessee’s failure to get his accounts audited was based on a bona fide belief that he was not liable for tax audit. The ICAI Guidance Note on Tax Audit lays down that where GST or any other tax is included in the sale price, no adjustment should be made for it while considering turnover, and courts have accepted the ICAI’s meaning of ‘turnover’ as a body having statutory recognition, following CIT v. Punjab Stainless Steel Industries, (2014) 364 ITR 144 (SC).

(b) Where two views on inclusion of GST in turnover are reasonably possible, it would be difficult to completely brush aside the assessee’s contention that he bona fide believed he was not liable to get his accounts audited under section 44AB, particularly where nothing was brought on record to establish that the assessee deliberately, knowingly, or with mala fide intention failed to comply with section 44AB.

(c) A bona fide belief of this nature has consistently been treated by Coordinate Benches as constituting reasonable cause sufficient to delete penalty under section 271B, since the levy of penalty under that section is discretionary and not automatic – see Smt. Snehal Rajendra Pathak v. ITO, ITA No. 3550/Mum/2014; Vighnaharta Trust v. DCIT (Exemption), ITA No. 3324/Mum/2023; and Sachin Marotrao Rangari v. ACIT, (2022) 143 taxmann.com 318/197 ITD 358 (Rajkot – Trib.).
Accordingly, the Tribunal held that the facts and circumstances did not warrant a finding that the assessee’s failure to obtain the tax audit report was intentional or contumacious, that his bona fide belief amounted to reasonable cause, and directed the AO to delete the penalty levied under section 271B.

In the result, the appeal of the assessee was allowed.

Ameeta Jagdish Thackersey v. Income-tax Officer: Given conflicting judicial views regarding Portfolio Management Services fee deductions under section 48, the construction most favourable to the assessee applies.

53. (2026) 189 taxmann.com 433 (Mum Trib)

Ameeta Jagdish Thackersey v. Income-tax Officer

A.Y.: 2011-12 Date of Order : 10.08.2026

Section: 48

Since divergent Tribunal views existed on the allowability of Portfolio Management Services (PMS) fees under section 48, the interpretation favourable to the assessee was to be adopted and accordingly PMS charges were allowable as a deduction in computing capital gains.

FACTS

The assessee filed a return for A.Y. 2011-12 declaring total income of about Rs. 72.26 lakhs from salary, short-term capital gains and other sources. While computing capital gains, she claimed a deduction of PMS fees/charges of about Rs. 8.42 lakhs paid to her portfolio manager.

In assessment under section 143(3), the AO disallowed the PMS fees, holding that such charges were not expenditure incurred wholly and exclusively in connection with the transfer of a capital asset as required by section 48.

On appeal, the CIT(A) held that the fees, paid for purchase and sale of securities and allied activities, were not directly relatable to the cost of acquisition or transfer of specific securities, and upheld the disallowance.
Aggrieved, the assessee appealed to the Tribunal.

HELD

The Tribunal observed as follows:

(a) Divergent views had been expressed by different Coordinate Benches on the allowability of PMS charges under section 48. While the Mumbai Bench in ACIT v. Apurva Mahesh Shah, (2018) 172 ITD 127 (Mumbai), had held PMS fees not deductible, the Pune Bench in DCIT v. KRA Holding & Trading (P.) Ltd., (2012) 54 SOT 493 (Pune), the Mumbai Bench in Zarah Rafique Malik v. ITO (Int. Tax), (2026) 184 taxmann.com 287 (Mumbai – Trib.), and the Delhi Bench in ACIT v. Vireet Investments (P.) Ltd., (2024) 169 taxmann.com 379 (Delhi – Trib.), had taken the contrary view and allowed such deduction.

(b) Two reasonable and plausible views thus existed on the interpretation of section 48 in relation to PMS charges. The Supreme Court in CIT v. Vegetable Products Ltd., (1973) 88 ITR 192 (SC), had laid down the settled principle that where two reasonable constructions of a taxing provision are possible, the interpretation favourable to the assessee should be adopted, a principle consistently applied where conflicting judicial views exist and no binding decision of the jurisdictional High Court or the Supreme Court directly settles the controversy.

(c) The Revenue had not brought to notice any binding decision of the jurisdictional High Court or the Supreme Court specifically holding that PMS charges are not deductible under section 48.

Accordingly, the Tribunal held that PMS charges of `8.42 lakhs were allowable as a deduction while computing capital gains under section 48.

In the result, the appeal of the assessee was allowed.

Shri Sant Ram Memorial Education and Welfare Society v. Exemption Ward: Where a society runs multiple educational institutions from a common campus, receipts must be aggregated to determine exemption limits under section 10(23C)(iiiad).

52. (2026) 189 taxmann.com 174 (Chd Trib)

Shri Sant Ram Memorial Education and Welfare Society v. Exemption Ward

A.Y.: 2018-19 Date of Order : 03.08.2026

Section: 10(23C)(iiiad)

Where the assessee-society ran multiple educational institutions from a common campus with common infrastructure, management and ownership and maintained only consolidated accounts, the receipts of all the institutions were to be aggregated for determining the exemption under section 10(23C)(iiiad), and since such receipts exceeded the prescribed limit, exemption was rightly denied.

FACTS

The assessee, a society registered under the Societies Registration Act and engaged in imparting education, filed its return for A.Y. 2018-19 declaring Nil income after claiming exemption of Rs. 23.22 lakhs under section 10(23C)(iiiad). During the relevant year, it ran Infinity Public School, SSR College of Education, Bachpan Play School and the Society itself.

Its case was selected for complete scrutiny primarily for claim of exemption under section 10(23C)(iiiad). The AO noted that the assessee had furnished only consolidated financial statements, and had not produced any working demonstrating eligibility for the exemption claimed. On examining the consolidated Income & Expenditure Account, the aggregate annual receipts of the educational institutions were found to be Rs. 1,85,10,445, exceeding the prescribed monetary limit of Rs. 1 crore under Rule 2BC. Treating all the educational activities as one composite institution, the AO aggregated the receipts, denied the exemption, and taxed the surplus of Rs. 9.70 lakhs, and also initiated penalty proceedings under section 270A.

On appeal, the CIT(A) affirmed the disallowance, recording that all units operated from the same campus with common infrastructure, management and ownership, and that separate buildings or courses did not create separate institutions.

Aggrieved, the assessee filed an appeal to the Tribunal.

HELD

The Tribunal observed as follows:

(a) Section 10(23C)(iiiad) is intended to grant exemption to educational institutions having comparatively small annual receipts, so as to extend the benefit to genuinely small institutions without requiring them to undergo the rigours of approval under the other clauses of section 10(23C). The provision cannot, however, be interpreted to permit fragmentation of what is, in substance, one integrated educational institution into several artificial units merely to remain within the prescribed monetary limit.

(b) Both the AO and the CIT(A) had concurrently recorded a finding that all the educational activities were carried on by the same society from a common campus with common infrastructure, common management and common ownership. The assessee was unable to demonstrate that the alleged institutions maintained separate books of account, possessed independent administrative or managerial structures, or functioned as distinct educational entities; on the contrary, only consolidated financial statements of the society were maintained and produced.

(c) Whether separate educational institutions exist is essentially a question of fact, and in the absence of cogent evidence establishing independent existence, administration and accounting, mere nomenclature assigned to different wings or levels of education cannot be determinative. Accepting the assessee’s contention without supporting material would defeat the object of section 10(23C)(iiiad), which is intended to benefit genuinely small educational institutions, and not to permit fragmentation of receipts of one composite establishment.

Accordingly, the Tribunal agreed with the concurrent findings of the authorities above that the aggregate receipts of the educational institution run by the assessee exceeded the prescribed monetary limit during the relevant previous year, and that the assessee was consequently not entitled to exemption under section 10(23C)(iiiad).

In the result, the appeal of the assessee was dismissed.

Fatal Or Forgiven – How Courts Apply Mandatory Vs. Directory Rules

In tax law, statutory provisions are classified as mandatory or directory based on legislative intent rather than literal terms like “shall” or “may”. Mandatory rules govern jurisdiction, limitation periods, and substantive eligibility; strict adherence is indispensable, and failure to comply renders proceedings void regardless of prejudice. Conversely, directory rules regulate procedural and evidentiary mechanisms intended to facilitate administration. Courts allow substantial compliance for directory provisions whenever the underlying statutory purpose is fulfilled and no prejudice is caused. Modern courts apply a seven-factor test examining statutory purpose, non-compliance consequences, curability, and overall legislative scheme to determine a provision’s true legal character.

Statutory interpretation occupies a central position in every fiscal legislation. Unlike private law, where rights and obligations frequently arise from consensual arrangements, tax statutes derive their authority exclusively from legislative command. Every obligation imposed upon the taxpayer, every power conferred upon the Revenue authorities and every exemption, deduction or concession recognised under the statute owes its existence to parliamentary enactment. Consequently, the interpretation of statutory language, particularly whether a provision is mandatory or directory assumes exceptional importance, for it determines not merely the meaning of legislative provisions but also the limits of administrative authority and the conditions governing the exercise of statutory rights.

The jurisprudence governing mandatory and directory statutory provisions has acquired renewed significance following a series of recent judicial pronouncements under the (now repealed) Income-tax Act, 1961 (“the Act”). A controversy arose before the Delhi High Court1, where the validity of a notice issued under section 143(2) was challenged. The petitioner contended that the failure to adhere to the format prescribed by the CBDT2 rendered the notice invalid and consequently vitiated the assessment proceedings initiated thereunder.


1 Bharat Bansal v. NFAC, W.P.(C) 2238/2026, CM APPL. 10798/2026 & CM APPL. 10799/2026

2 Instructions dated 23rd June 2017 and 13th October 2021

Rejecting the challenge, the Delhi High Court (HC) held that the CBDT Instructions were intended solely to regulate the internal functioning of the Income-tax Department and they neither conferred any enforceable rights upon the assessee nor imposed additional jurisdictional conditions beyond those prescribed by the statute. It was observed that the purpose of a notice under section 143(2) is to intimate the assessee that the return has been selected for scrutiny and assume jurisdiction and hence, mere omission to specify the category or reasons for scrutiny in the initial notice did not affect the validity of the said notice. The Court thus drew a clear distinction between statutory requirements governing jurisdiction and administrative instructions regulating departmental procedure, holding that non-compliance with the latter could not invalidate proceedings otherwise lawfully initiated under the Act.

This issue assumed greater significance in recent past as conflicting decisions of various benches of the Income Tax Appellate Tribunal (ITAT) necessitated constitution of a Special Bench3. The Special Bench also adopted a similar analogy as the Delhi HC (supra) in holding that a format prescribed under the CBDT Instructions constitutes an administrative mechanism and cannot be elevated into a statutory condition precedent governing the validity of a notice issued under section 143(2).

On a separate note, the Karnataka HC4, while examining the issue, the High Court considered the object underlying the Document Identification Number (“DIN”) regime, namely ensuring authenticity, traceability and maintenance of an audit trail in departmental communications. The Court noted that the controversy did not involve a case where no DIN had been generated or communicated. Rather, the impugned orders had been uploaded through the prescribed electronic process, the DINs were subsequently communicated through authenticated intimation letters and the accompanying orders contained an incorrect DIN owing to a manual error.

Adopting a purposive interpretation of CBDT Circular No. 19 of 2019 and the related system instructions, the Court held that the requirement of quoting a DIN is mandatory, however, where the correct DIN is communicated through an authenticated intimation identifying the relevant order, the communication would not be rendered invalid merely because the DIN was not originally reflected in the order or was incorrectly mentioned due to a typographical mistake. The court considered the object underlying the DIN regime, and ruled in favour of the tax department by treating such defects are curable irregularities.5


3 M.D. Sons v. Income Tax Officer, [TS-1089-ITAT-2026(Bang)]

4 PCIT v. Unisys India Pvt. Ltd., ITA No. 55/2024

5 It may also be noted that the Finance Act, 2026 has introduced legislative changes dealing with electronic communications and departmental authorisations,
 while CBDT Circular No. 19/2019 governing the DIN mechanism stands withdrawn. 
The impact of these developments on pending disputes concerning DIN-related invalidity arguments remains to be judicially tested.


Fatal or Forgiven

It may be relevant to note here that in the past, a stricter approach to DIN compliance has been adopted by several HCs. The Bombay HC6 and Madras HC7, have held that a subsequent communication on DIN generation would not be sufficient compliance and the original communications were held to be non est in law.


6 Hexaware Technologies Ltd. v. ACIT, [2024] 464 ITR 430 (Bom),
7 CIT v. Laserwords US Inc., [2026] 486 ITR 159 (Madras)

The recent decisions of the HC’s as well as the Special Bench (supra) have thus noted that the format of the notice or insertion of DIN in a subsequent notice is a directory provision and does not prejudice the taxpayers. As long as substantial compliance is adhered to, the same was held to follow the procedure as mandated by law. The matter would have been fundamentally different, though, had there been no notice itself issued under section 143(2) or the DIN was never communicated to the taxpayers. This brings the focus to the germane issue that while certain provisions are so fundamental to the legislative framework that failure to comply necessarily invalidates the action taken under the statute, others merely regulate the way a statutory power is exercised or a statutory right is asserted, such that substantial compliance with the legislative objective may suffice. The logic of this distinction is that while a procedural formality facilitates the enjoyment of a benefit, a substantive condition determines whether the benefit can be claimed in the first place.

MANDATORY AND DIRECTORY PROVISIONS

A mandatory provision is one whose compliance constitutes a condition precedent to the validity of the statutory act. Such provisions ordinarily create jurisdiction, determine substantive rights or impose conditions that Parliament has expressly declared to be essential. Compliance with these requirements is indispensable because the statutory power or benefit itself comes into existence only upon fulfilment of the prescribed conditions. Failure to comply with a mandatory requirement, therefore, ordinarily renders the action void, irrespective of whether any actual prejudice has been demonstrated. The emphasis is not upon the consequences suffered by the parties but upon adherence to the legislative command.

A directory provision, in contrast, regulate the manner in which an existing right or power is exercised. While compliance with such a provision is ordinarily expected, the requirement is not regarded as indispensable to the validity of the proceeding or the existence of the statutory right. The provision regulates the procedure through which an existing right is exercised or established rather than creating that right in the first instance. Consequently, where the legislative purpose has been substantially achieved and the procedural lapse does not defeat the object of the statute or prejudice the interests sought to be protected, courts have often regarded substantial compliance as sufficient.

Broadly, statutory requirements under the IT Act may be classified into three categories. First are judicial requirements, which confer authority upon the tax administration to initiate or continue proceedings. Secondly, substantive eligibility conditions determine whether a taxpayer is entitled to a statutory benefit, exemption or deduction. Thirdly, procedural and evidentiary requirements regulate the manner in which jurisdiction is exercised or statutory rights are claimed. While the first two categories ordinarily receive a mandatory interpretation, the third category is generally construed as directory unless the statute expressly provides otherwise.

Identification of the nature of a provision i.e. whether it is mandatory or directory has been a subject matter of judicial interpretation across statutes. Early judicial decisions tended to adopt a largely literal approach. The use of the word “shall” in a statute was generally treated as indicative of a mandatory requirement, whereas the word “may” was regarded as conferring discretion. However, experience soon demonstrated that such an approach produced inconsistent results. Legislatures frequently used mandatory language in relation to procedural requirements where strict compliance was never intended, while permissive language was sometimes employed in situations where a duty was clearly contemplated.

The Supreme Court8 in a landmark case marked an important departure from purely linguistic interpretation. The Court observed that the determination of whether a provision is mandatory or directory depends primarily upon legislative intent and not merely upon the language employed. This approach was developed further where the Supreme Court9 emphasised that the consequences of non-compliance, the object of the statute and the purpose of the provision must all be examined.

The evolution of the mandatory-directory doctrine within the Income-tax Act may be traced to early decisions that recognised the distinction between substantive statutory conditions and procedural requirements intended merely to facilitate tax administration. An important application was made by the Patna High Court10, wherein the Court examined whether the requirement under section 184(7) that a declaration for continuation of registration of a firm be furnished “along with the return of income” was mandatory or merely directory. Rejecting a purely literal construction, the Court held that the expression could not be interpreted to require physical simultaneity between the return and the declaration. What was material was that both documents were available before the Assessing Officer at the time of making the assessment. The Court observed that an overly technical interpretation would defeat the legislative object and place undue emphasis on procedural form rather than substantive compliance. The decision is significant because it represents one of the earliest judicial recognitions under the Act that procedural requirements intended to facilitate assessment should ordinarily receive a directory interpretation where the legislative purpose has been substantially fulfilled and no prejudice is caused to the Revenue.

The Delhi High Court11 further refined this jurisprudence where the Court was required to determine whether the prescribed time limit for rendering accounts under section 80G(5C)(v) constituted a mandatory condition or a directory procedural requirement. The Court emphasised that the determination could not rest solely upon the language employed by Parliament but required examination of the legislative purpose, the nature of the obligation and the consequences of non-compliance. Since the substantive conditions had already been fulfilled and the delay was procedural in nature, denial of the statutory benefit solely on account of delayed compliance would frustrate the legislative object and produce disproportionate consequences.

An equally significant contribution to the development of the doctrine is found in the Full Bench decision of the Allahabad High Court12. The controversy concerned section 12AA(2), which required the Commissioner shall dispose of an application for registration within six months and hence the question framed was whether failure to adhere to the prescribed time limit resulted in a deemed grant of registration. The Full Bench rejected such an interpretation and held that although the provision employed the expression “shall”, the absence of any statutory consequence for non-compliance indicated that the prescribed time limit was directory rather than mandatory and emphasized that the true test lies in examining the object of the provision, the statutory scheme and the consequences that would follow from either interpretation.

A significant aspect of the mandatory-directory doctrine emerges from the decision of the Sikkim High Court13 wherein the court held that not every statutory prescription carries the same legal consequence upon non-compliance and relied upon the doctrine of substantial compliance i.e. where the essential requirements of the statute have been satisfied, minor procedural deviations should not defeat substantive right.

We will now deal with certain illustrations of mandatory and directory provisions in the context of the Act are in the ensuing paragraphs.


8 State of U.P. v. Manbodhan Lal Srivastava, AIR 1957 Supreme Court 912

9  Raza Buland Sugar Co. Ltd. v. Municipal Board , AIR 1965 Supreme Court 895

10 Commissioner of Income-tax v. Sitaram Bhagwandas [(1976) 102 ITR 560 (Pat.)]

11 Church’s Auxiliary for Social Action v. Director General of Income-tax (Exemptions) [(2010) 325 ITR 362 (Del.)],

12 Commissioner of Income-tax v. Muzaffar Nagar Development Authority [(2015) 372 ITR 209 (All.) (FB)]

13 Balchand Udairam v. State of Sikkim [(1989) 180 ITR 530 (Sikkim)].

A. JURISDICTIONAL PROVISIONS

These are the clearest illustrations of mandatory provisions as jurisdiction constitutes the legal authority to act. If the statute prescribes a particular condition for assumption of jurisdiction, failure to satisfy that condition ordinarily renders the entire proceeding void irrespective of the merits of the case. Consequently, defects going to the root of the notice cannot ordinarily be cured through acquiescence, participation or waiver by the assessee.

The Supreme Court14 has observed that service of the prescribed notice is not merely procedural but constitutes a condition precedent to the validity of reassessment proceedings and the entire proceeding would be rendered illegal where the jurisdictional notice was absent. The doctrine of substantial compliance finds little application in such circumstances because the issue is not whether the power was properly exercised but whether the power existed at all.

The Supreme Court15 in the context of issuance of a notice under section 143(2) has held that it is mandatory act under the statute as it lays the foundation of jurisdiction and hence, is not merely procedural. This principle was reiterated16 by the Supreme Court which clarified that complete absence of notice cannot be cured through section 292BB. While defects in service may in certain circumstances be cured, the actual issuance of notice remains indispensable.

The Delhi and Bombay HC’s17 while examining the validity of approval granted under section 151 before issuance of a notice for reassessment, rejected the Revenue’s contention that the statutory approval constituted a mere administrative formality. The Court held that the approving authority is expected to independently examine the reasons recorded by the Assessing Officer and arrive at its own satisfaction regarding the necessity of reopening the assessment. The judgment, thus, reinforces the principle that procedural safeguards incorporated by Parliament to regulate the assumption of jurisdiction are mandatory in nature and cannot be reduced to mechanical rituals. The requirement of prior sanction exists not for administrative convenience but to protect taxpayers against arbitrary exercise of reassessment powers.

Interestingly, the Finance Act 2026 has inserted section 292BC in the Act to retroactively18 provide that such approvals would be deemed to be administrative and supervisory in nature and shall not invalidate a notice. Although, generally legislature is within its powers to enact an amendment retroactively and can also amend a directory provision to be made mandatory19 whether the wordings in the retrospective amendment in section 292BC are sufficient to convert a mandatory provision into a directory one, without removing any lis or the fundamental basis in the original provision remains to be tested before the Courts, especially in light of the law laid down by the Supreme Court20 in the case of Prithvi Cotton Mills and Indian Aluminium Co. in this regard.


14 Y. Narayana Chetty v. ITO, 1958 (10) TMI 10 - Supreme Court

15 Assistant Commissioner of Income-tax v. Hotel Blue Moon, 2010 (2) TMI 1 - Supreme Court

16  CIT v. Laxman Das Khandelwal, 2019 (8) TMI 660 - Supreme Court

17 CIT v. SPL’s Siddhartha Ltd, [(2012) 345 ITR 223 (Del.)],
 United Electrical Co. (P.) Ltd. v. CIT [(2002) 258 ITR 317 (Del.)]; 
Svitzer Hazira Pvt Ltd vs Assistant Commissioner of Income Tax, TS-6621-HC-2021

19 Retrospective w.e.f. April 01, 2021

20 Commissioner of Income Tax vs. Natraj Engineers (P) Ltd, Patna HC, TS-5877-HC-2015

B. LIMITATION PROVISIONS

Limitation provisions occupy a unique position in tax law. They do not merely regulate procedure, rather, they define the temporal boundaries within which statutory power may be exercised. Once the prescribed period expires, the authority itself ceases to exist.

The mandatory character of limitation provisions is particularly evident in reassessment cases. The power to reopen completed assessments exists only within the framework prescribed by Parliament. Once the statutory period expires, the authority to reassess stands extinguished. Courts, therefore, refuse to treat limitation periods as mere procedural requirements.

The same principle applies to assessment time limits prescribed under section 153. These provisions serve not merely administrative purposes but also protect taxpayers against indefinite uncertainty. The expiration of limitation, therefore, affects the very competence of the authority to proceed further.

C. EXEMPTIONS AND DEDUCTIONS

The IT Act contains numerous provisions granting exemptions, deductions and preferential treatment. Such provisions often prescribe multiple conditions including filing of returns, reports etc. Judicial decisions consistently distinguish between conditions that determine eligibility and conditions that regulate the manner of claiming the benefit.

An exemption or deduction represents a departure from the normal charging provisions of the Act and hence, eligibility conditions for such exemptions or deductions are ordinarily regarded as mandatory21.

Section 80AC is also one of the clearest illustrations of legislative intent transforming a procedural act into a mandatory condition. The provision links availability of specified deductions to timely filing of the return of income, which clarifies the intent of the Parliament to restrict eligibility of such deductions and exemptions on furnishing of timely returns.22

The requirement to obtain the audit report has also frequently been regarded as substantive because it ensures compliance with the statutory objective of independent verification. However, the requirement regarding the precise timing of filing the report has often been treated as procedural. Consequently, where the report existed and was furnished before completion of assessment proceedings, courts have frequently held that the deduction or exemption should not be denied merely because the report was not enclosed with the original return23.

Particularly in cases of exemption provisions, the Constitution Bench of the Supreme Court24 reaffirmed that exemption provisions in fiscal statutes must be interpreted strictly and that the burden lies on the taxpayer to clearly establish that its case falls within the scope of the exemption. At the same time, the Court recognised the doctrine of substantial compliance, observing that while substantive and mandatory conditions governing eligibility must be strictly fulfilled, mere procedural or directory requirements may be treated more liberally where the essential statutory conditions have been satisfied. The judgment thus draws a crucial distinction between substantive conditions that create the entitlement to a tax benefit and procedural requirements that merely regulate its exercise, making it a cornerstone authority in determining whether a statutory requirement is mandatory or directory. The principles of this decision were echoed by the subsequent Supreme Court’s25 decision wherein the Court in the context of section 10B of the Act (treating it as an exemption section) held that furnishing of the declaration stipulated in section 10B and adherence to the prescribed timeline constituted mandatory conditions.

The Supreme Court26 in a landmark case while dealing with deduction claims where the prescribed audit report had not been filed along with the return but had been furnished before completion of assessment proceedings held that as the purpose underlying the requirement was to ensure that the necessary certification was available to the assessing authority, once the report was furnished during the assessment proceedings and before completion of the assessment, the statutory purpose stood fulfilled.

The Gujarat High Court27 and Calcutta High Court28 similarly recognised that the prescribed report exists to facilitate verification by the Revenue and not to create the substantive entitlement itself and if the report is ultimately furnished during the assessment proceedings, there is no dispute regarding satisfaction of the substantive statutory conditions, delayed filing should not automatically result in denial of the deduction.


21 Shri Prithvi Cotton Mills Ltd. v. Broach Borough Municipality’, [1970 AIR 192], 

Indian Aluminium Co. v. State of Kerala [1996 AIR 1431]

22 U.P. Forest Corporation And Anr. V. DCIT, 2007 (11) TMI 699 - Supreme Court

23 Association Of Indian Panelboard Manufacturer v. DCIT, 2022 (12) TMI 1414 - Gujarat High Court

24 Dilip Kumar & Co., 2018 (7) TMI 1826 - Supreme Court (LB)

25 PCIT v. Wipro [2022] 140 taxmann.com 223 (SC)

26 CIT v. G.M. Knitting Industries Pvt. Ltd, 2015 (11) TMI 397 - SC Order

27  Zenith Processing Mills v. CIT [(1996) 219 ITR 721 (Guj.)]

28  Winro commercial (India), ITAT No 237/2022

D. LOWER CORPORATE TAX RATE UNDER 115BAA/115BAB

A contemporary illustration of this debate arises in the context of the concessional tax regimes under sections 115BAA and 115BAB. These provisions permit domestic companies to avail a lower rate of tax subject to satisfaction of specified conditions and the exercise of the option in the prescribed manner through Form No. 10-IC or Form No. 10-ID, as the case may be. A recurring controversy has been whether delay in filing the prescribed form necessarily disentitles an otherwise eligible taxpayer from claiming the concessional rate. While the Revenue has generally viewed timely filing of the form as a mandatory requirement, appellate authorities have increasingly examined the substance of the taxpayer’s conduct, including whether the option was unequivocally exercised in the return of income, whether tax was computed at the concessional rate and whether all substantive statutory conditions were satisfied.

The Allahabad High Court in this context29 held that where the assessee had clearly manifested its intention to opt for section 115BAA in its return of income and audit report, delay in filing Form No. 10-IC could be condoned upon demonstration of genuine hardship, observing that a procedural lapse should not deprive a taxpayer of a substantive benefit.

Similarly, the Gujarat High Court30 condoned the delay in filing Form No. 10-ID under section 115BAB, emphasising that the filing requirement is intended to facilitate exercise of the option and that substantive entitlement should not be denied where sufficient cause for the delay exists. The Mumbai Tribunal31 went a step further and held that even the filing of an incorrect form, namely Form No. 10-IB instead of Form No. 10-IC, constituted a curable procedural defect where the assessee had otherwise satisfied all conditions and unequivocally exercised the option for concessional taxation. These decisions suggest a growing judicial inclination to treat the prescribed forms as procedural mechanisms evidencing the exercise of a statutory option rather than as conditions governing the existence of the entitlement itself.


29 Cell Com Teleservices Private Limited Versus Union of India, [2025] 176 taxmann.com 712 (Allahabad)

30 M/s. Royal Led Equipments Pvt. Ltd. Versus Chief Commissioner Of Income Tax, [2025] 174 taxmann.com 61 (Gujarat)

31 ACIT, Circle -3, Thane Versus Magik Kraft Pvt Ltd, 2025 (10) TMI 1431 - ITAT MUMBAI

E. FORM NO. 67 (FOREIGN TAX CREDIT)

Sections 90 and 91 of the IT Act confer the substantive right to claim FTC, while Rule 128 prescribes Form No. 67 as the procedural mechanism through which the taxpayer furnishes particulars of foreign taxes paid. Judicial decisions, however, have increasingly recognised that the Rule regulates the manner of claiming an existing statutory right and does not itself create the entitlement to FTC.

Several benches of the ITAT have therefore held that the requirement of filing Form No. 67 is directory rather than mandatory, particularly where the form is furnished before completion of assessment or appellate proceedings and the substantive conditions for grant of foreign tax credit are otherwise satisfied32.


32 Hertz Software India Pvt. Ltd. v. ACIT [(2022) 139 taxmann.com 448 (Bang. - Trib.), 
Brinda Ramakrishna v. ITO [(2022) 135 taxmann.com 358 (Bangalore - Trib.)], 
Bhagwandas Tikamdas Khinani v. NFAC, 2022 (12) TMI 357 - ITAT Mumbai, 
Anuj Bhagwati v. DCIT, 2022 (9) TMI 1397 - ITAT Mumbai

F. REVISED RETURNS AND CARRY FORWARD OF LOSSES

Section 80 embodies the legislative principle that the statutory right to carry forward and set off certain losses is contingent upon timely compliance with the return filing requirements prescribed under the Act. The provision expressly disentitles a taxpayer from carrying forward specified losses unless the return claiming such loss is furnished within the time prescribed under section 139(1). The focus of the provision, therefore, is on the existence of a valid and timely loss return, reflecting Parliament’s intention to treat timely disclosure of the loss as a substantive condition for preserving the benefit.

The relationship between original returns and revised returns provides another important illustration of the mandatory-directory distinction. Accordingly, where an assessee has filed the original return within the prescribed period and has validly disclosed the loss sought to be carried forward, a subsequent revised return correcting computational or factual errors should not ordinarily result in denial of the already accrued statutory right. The revised return merely refines the contents of that return and should therefore be viewed as a procedural mechanism regulating the exercise of an existing right.

The Supreme Court’s decision in Prakash Nath Khanna v. CIT33 illustrates the circumstances in which Parliament consciously transforms a procedural requirement into a substantive statutory condition. Interpreting the expression “due time” under the Act, the Court held that a return furnished under section 139(4) cannot be equated with a return filed within the due date prescribed under section 139(1). The legislature had deliberately distinguished between timely compliance and belated compliance, attaching different legal consequences to each. The judgment, therefore, demonstrates that where Parliament expressly links a statutory right or consequence to compliance within a specified period, the courts cannot dilute that requirement by treating subsequent compliance as equivalent. The decision represents an important illustration of legislative intent converting what may otherwise appear procedural into a mandatory statutory condition.


33 Prakash Nath Khanna v. CIT [(2004) 266 ITR 1 (SC)]

TOWARDS A UNIFIED INTERPRETATIVE FRAMEWORK – THE SEVEN-FACTOR TEST

A review of judicial decisions reveals that courts repeatedly return to certain common themes when determining whether a provision is mandatory, directory or discretionary. These tests may be synthesised into a unified interpretative framework.

  •  First Factor – Nature of the Right or Power Involved

The first inquiry concerns the nature of the right or power affected by the provision. Requirements affecting jurisdiction, limitation or substantive eligibility are more likely to be mandatory than those regulating procedure.

  • Second Factor – Legislative Purpose

The second inquiry concerns the purpose sought to be achieved. If strict compliance is necessary to fulfil the statutory objective, the provision is likely to be mandatory. If the purpose can be achieved despite procedural deviation, the provision may be directory.

  • Third Factor – Consequences of Non-Compliance

The third inquiry examines whether the statute specifies consequences for non-compliance. Express invalidation generally indicates mandatory intent, whereas silence may support a directory interpretation.

  • Fourth Factor – Presence or Absence of Prejudice

The fourth inquiry concerns prejudice. Where non-compliance causes no prejudice and the statutory purpose remains fulfilled, courts are more inclined to treat the requirement as directory.

  • Fifth Factor – Curability of the Defect

The fifth inquiry examines whether the defect can be cured without undermining the legislative objective. Curable defects are more likely to be procedural and therefore directory.

  • Sixth Factor – Public Interest Considerations

The sixth inquiry concerns broader public interests. Requirements designed to protect public revenue, prevent abuse or maintain regulatory oversight are more likely to be treated as mandatory.

  • Seventh Factor – Overall Legislative Scheme

The final inquiry requires examination of the statute as a whole. No provision can be interpreted in isolation. Its true nature emerges only when viewed within the broader legislative framework.

CONCLUSION

The evolution of tax jurisprudence demonstrates a gradual but unmistakable shift away from formalism and towards purposive interpretation. Modern courts increasingly recognise that not every statutory requirement serves the same function. Some provisions confer jurisdiction, some define entitlement, some regulate procedure and others confer discretion. Treating all such provisions identically would undermine legislative intent and distort the statutory scheme.

The distinction between mandatory and directory provisions, therefore, reflects a deeper principle. The law seeks strict compliance where Parliament intended strict compliance. It accepts substantial compliance where Parliament intended procedural facilitation. It requires reasoned decision-making where Parliament intended administrative flexibility. Ultimately, the inquiry is not whether parliament has employed the expression “shall “ or “may”, but whether the requirement under consideration lies at the heart of the statutory scheme or merely facilitates its effective administration. The answer to that question determines not only whether a provision is mandatory or directory, but also the legal consequences that follow its non-compliance. The recent judicial developments reaffirm that courts will continue to preserve this distinction by insisting upon strict compliance with jurisdictional and substantive conditions while applying the doctrine of substantial compliance to procedural requirements that do not defeat the legislative purpose.

Reading Climate Risk Like A Balance Sheet

Climate risk has evolved from an environmental issue into a core financial function, directly impacting balance sheets, asset valuations, and the cost of capital. It manifests as physical, transition, and liability risks that alter accounting estimates, including asset impairments and expected credit losses. Standardized frameworks like ISSB and India’s BRSR require rigorous disclosures, robust internal controls, and independent assurance over emissions data. Incorporating green bonds, climate due diligence, and carbon management into corporate strategy directly protects long-term enterprise value. Ultimately, finance leaders must look beyond historical numbers to price future climate risks into strategic capital allocation and investment decisions.

Climate risk no longer waits for the annual sustainability report. It shows up earlier- in impairments, provisions, credit ratings, insurance premiums, and the price a company pays for capital.

CLIMATE RISK HAS ENTERED THE FINANCE FUNCTION

Until recently, climate change was viewed largely as an environmental issue, while finance teams rarely considered it material unless the organisation belonged to a heavily polluting industry. That assumption no longer holds. Climate change, it turns out, reads a balance sheet just fine.

Around the world, climate-related events are reshaping financial statements, investment decisions, lending practices, and corporate strategy in ways that are no longer theoretical. A flood can impair manufacturing assets, a carbon tax can erode operating margins, and climate-conscious consumer behaviour can render once-profitable assets economically obsolete almost overnight.

For finance professionals, this represents a fundamental shift in the nature of the job. Climate considerations are steadily embedding themselves across every core finance function, from reporting and assurance to valuation, credit, and treasury. The real question isn’t whether climate change affects business, but whether finance professionals are equipped to measure its consequences well enough.

WHEN WEATHER BECOMES A BALANCE SHEET ITEM

The evidence isn’t waiting for anyone’s risk committee to catch up. The World Economic Forum’s Global Risks Report 2026 ranks extreme weather events among the world’s most severe long-term risks for the third year running. The California wildfires alone are estimated to have caused well over USD 250 billion in combined insured and uninsured losses, reshaping property valuations and insurance pricing.

Closer to home, the pattern is unmistakable with delayed monsoon and relentless heat. India’s peak power demand touched a record 270.82 gigawatts in May 2026. Independent estimates suggest that extreme heat alone could shave between 2.5 and 4.5 percent off India’s GDP by 2030 through lost labour hours in outdoor-intensive sectors. Investors, lenders, regulators, and boards are consequently demanding more robust assessments of climate-related risk. For finance professionals this means climate information is becoming unambiguously financially material.

THREE KINDS OF RISK, ONE FINANCIAL STATEMENT

Financially material through what channel, exactly? Climate risk breaks into three kinds, and each has begun to leave a distinct financial fingerprint on Indian businesses. The Task Force on Climate-related Financial Disclosures, whose recommendations now underpin the IFRS Sustainability Disclosure Standards, distinguishes two primary categories of climate risk — physical and transition. To these, prudential regulators such as the Bank of England add a third, liability risk, and this three-way split is what matters most to finance professionals.

Physical risks arise from the direct impacts of climate change, whether acute events such as floods and cyclones or chronic changes such as rising temperatures. India has experienced no shortage of either in recent years. These risks can also show up in less visible ways: a Climate Central analysis found that major Indian metros lost between 65 and 93 hours of sleep annually because of warmer nights.

Transition risks emerge as economies shift towards lower-carbon business models, as governments introduce carbon pricing, regulators strengthen disclosure requirements, and customers favour sustainable products. India’s Carbon Credit Trading Scheme (CCTS), set to begin trading soon, illustrates transition risk in practical terms. Around 740 entities across major industrial sectors, together accounting for roughly 700 million tonnes of carbon dioxide equivalent, now carry legally binding emission-intensity targets for the compliance years 2025-26 and 2026-27. Entities that outperform their targets will earn tradeable Carbon Credit Certificates, while those that fall short must purchase and surrender an equivalent number, making carbon emissions an explicit, tradeable cost of doing business.

Climate Risk Reads your BS

Transition risk isn’t just a domestic story. From January 1, 2026, the European Union began fully enforcing its Carbon Border Adjustment Mechanism (CBAM), requiring EU importers of steel, aluminium, and cement to pay for the carbon embedded in each shipment, at €75.36 per tonne of CO2 equivalent for the first quarter of 2026 alone. India, lacking a domestic carbon price and reliant on older blast furnaces, is likely to bear close to double its fair share of total CBAM costs relative to its EU export volumes. For finance teams at exporting companies, this is now a live compliance cost: it needs audited embedded-emissions data, feeds directly into export pricing, and, left unaddressed, will surface within a few reporting cycles as a lost EU customer or a squeezed margin.

Liability risks, the third category, arise from the legal, regulatory, or reputational consequences of climate-related actions or omissions. Companies may face litigation over environmental damage, inadequate climate disclosures, or misleading sustainability claims, while financial institutions may face increased exposure from having financed assets that subsequently become stranded. These three risks converge in one place: the financial statements.

CLIMATE RISK AS AN ACCOUNTING ESTIMATE

There is no separate ‘climate accounting’ framework, and there doesn’t need to be. Climate risk simply alters the accounting estimates that already exist. Most accounting estimates rest on assumptions about future conditions, which climate change is now reshaping.

Consider property, plant and equipment. A manufacturing facility in a flood-prone region may continue to exist physically even as repeated climate-related disruptions reduce its expected economic benefit, while transition risk can render a carbon-intensive facility economically obsolete well before the end of its useful life. This naturally raises questions of impairment under Ind AS 36. The concept of a stranded asset captures this well: the asset need not be damaged at all, but loses value because regulation, technology, or markets make it commercially unattractive.

Financial institutions face a further consideration in the form of expected credit losses under Ind AS 109. If climate events cut repayment capacity or transition risk weakens profitability, default probabilities rise, and climate risk begins driving provisioning models directly. This is precisely why the RBI is pushing financial institutions to strengthen their climate risk management. It will require (though deferred) scheduled commercial banks and larger NBFCs to disclose governance, strategy, and risk management processes for climate-related risk. The RBI’s Financial Stability Report of June 2026 confirms banks and NBFCs remain well capitalised, though a subset could breach capital requirements under severe stress scenarios that increasingly include climate shocks. That is a signal that climate considerations now sit firmly inside mainstream prudential supervision.

In practice, a CA working out a bank’s provisioning would flag borrowers in flood-prone or carbon-heavy sectors and run them through the bank’s existing Ind AS 109 climate scenario, raising default probabilities or shifting a borrower into a riskier category, even without a missed payment, because climate risk has made their business meaningfully riskier than at origination.

The same thinking carries over to testing whether a company’s own assets have lost value, under a separate rule called Ind AS 36. For a carbon-intensive asset, projected future cash flows get revised downward to reflect falling demand or rising compliance costs, and the discount rate may also be nudged up to reflect the added risk. None of this requires learning a new accounting system. It simply means feeding a climate scenario into the same models CAs already run every reporting cycle.

SUSTAINABILITY REPORTING COMES OF AGE

Accounting estimates change the numbers inside the financial statements; what happens around those statements is shifting just as fast. Corporate reporting is undergoing one of its biggest transformations since the adoption of IFRS. Annual reports once focused on historical performance; investors now want a fuller picture of long-term value creation. This requires information about climate risk, governance, resource efficiency, resilience, and transition strategy. Globally, the International Sustainability Standards Board has established a common baseline for investor-focused sustainability disclosure through IFRS S1 and IFRS S2. Unlike earlier frameworks measuring societal impact, the ISSB approach focuses on how sustainability issues influence enterprise value and access to capital.

India has followed a similar trajectory. SEBI introduced the Business Responsibility and Sustainability Reporting (BRSR) framework for the top thousand listed entities by market capitalisation. BRSR Core has since strengthened the emphasis on assurance, extending to the full top thousand from FY 2026-27. For Chartered Accountants, this demands a deeper understanding of climate metrics, materiality assessment, internal controls over sustainability information, and the linkage between financial and non-financial reporting.

That data still needs an owner. Boards and audit committees increasingly ask who is accountable for sustainability figures, what controls govern their collection, and whether the same rigour applied to financial close applies here too. In practice this has meant extending internal controls over financial reporting to cover emissions data, energy consumption, and other metrics feeding into BRSR and ECL models.

This is not, however, a story confined to India’s largest listed companies. Most SMEs and unlisted businesses will meet climate risk long before any regulation directly requires them to report on it. For instance, this shows up when a large listed customer asks a supplier for Scope 3 data to complete its own disclosures, or a lender attaches a sustainability-linked covenant to a working capital facility. For CAs serving this segment, the work is less about disclosure frameworks and more about helping a client respond credibly to a customer or lender’s questionnaire.

MATERIALITY MAP: MAPPING WHAT MATTERS

Not every climate risk is worth reporting. Think of a simple two-axis plot: issues sorted by their likely financial impact on the business, and their significance to external stakeholders such as investors, lenders, and regulators. Issues that score high on both axes, such as carbon pricing exposure for a steel producer or physical flood risk for a coastal refinery, sit in the top right of the map and demand board-level attention and detailed disclosure. Issues that matter to stakeholders but carry limited financial consequence, such as biodiversity loss for a pure software business, can be monitored rather than actively managed.

This two-axis logic prevents organisations from spreading scarce management attention evenly across every conceivable climate issue and instead concentrates it on the handful that will actually move enterprise value or access to capital. For a diversified conglomerate spanning power, cement, ports, and financial services, the map looks entirely different business by business — a heatwave that barely registers for a ports business can be existential for a coal-fired power asset in the same group.

MEASURING EMISSIONS, THEN TRUSTING THE NUMBER

On the materiality map, one item shows up for almost every company: emissions. They come in three flavours worth telling apart. Every finance professional will increasingly need to read it fluently: the division of a company’s greenhouse gas footprint into Scope 1, Scope 2, and Scope 3 emissions under the GHG Protocol. This is the framework underpinning both BRSR Core and the CCTS.

Scope 1 covers direct emissions from sources a company owns or controls, such as the blast furnace at a Tata Steel plant or the kilns at an Ambuja cement facility. These are the emissions most directly within management’s control, which is why the CCTS sets its emission-intensity targets primarily against Scope 1 output.

Scope 2 covers indirect emissions from purchased electricity, steam, or heat. A textile unit in Tiruppur or an IT services data centre doesn’t burn coal itself, but the grid electricity it draws often comes from thermal power stations, so the emissions are attributed to the buyer rather than the generator. This is why so many Indian corporates such as Infosys are signing renewable power purchase agreements or investing in captive solar and wind capacity: doing so lowers Scope 2 emissions and, increasingly, the cost of capital attached to them.

Scope 3 is the widest and hardest category, covering all other indirect emissions across a value chain, upstream and downstream. For an automaker such as Tata Motors or Mahindra, Scope 3 includes emissions from steel and battery suppliers upstream and, more significantly, from millions of vehicles burning fuel on Indian roads downstream, a figure that can dwarf the company’s own factory emissions many times over. As Scope 3 sits largely outside a company’s direct control, it is the hardest to measure and the most contested in disclosure debates, yet for sectors like automobiles and oil and gas, it represents the largest share of climate-related financial risk.

For finance teams, this classification is a practical filter for materiality rather than an accounting curiosity. Scope 1 and 2 data feed directly into carbon compliance costs, lending covenants, and expected credit loss models, while Scope 3 data, though harder to verify, often reveals where the largest reputational and stranded-asset risks lie. BRSR Core already mandates Scope 1 and 2 disclosure for India’s largest listed companies, with Scope 3 moving from voluntary towards mandatory over coming reporting cycles. So building fluency in this classification is fast becoming as fundamental as reading a balance sheet.

Knowing the number is one thing. Trusting it is another. As sustainability disclosures become more important to investors and lenders, independent assurance becomes equally important to their credibility. This transition has already begun in India, with limited assurance over BRSR Core disclosures now applicable to the country’s largest listed companies. Yet the underlying challenge remains familiar to every Chartered Accountant: whether management’s assertions can be independently verified. The methodologies may evolve, but professional scepticism, evidence gathering, and documentation principles remain fundamentally the same, which means the assurance profession is expanding rather than being displaced by this shift. Once that data is assured, it stops sitting in a report and starts moving prices.

The real challenge here comes down to evidence. Financial statement audits rest on decades of well-established paper trails. Scope 3 emissions data doesn’t have that same track record; it’s pulled from suppliers and logistics partners, and sometimes estimated using industry averages. This means assurance providers, working under standards like SAE 3410 or the newer ISSA 5000, must be clear about what kind of check they’re doing: limited assurance, a lighter check based on inquiry and analytics, versus reasonable assurance, a much deeper check closer to a full financial audit. Most assurance on India’s BRSR Core disclosures today sits at the lighter, limited end, because the underlying data infrastructure isn’t mature enough yet.

Taking on this kind of work also brings its own risk: a CA who signs off on inflated sustainability claims or a misleading transition plan faces the same reputational and regulatory exposure as one who misses a financial misstatement. Increasingly, greenwashing allegations target the assurance provider too, making professional scepticism as much a liability question as a technical one.

PUTTING A PRICE ON CLIMATE RISK

While accounting standards determine how assets and liabilities are recognised, investors ask a sharper question: what will climate risk do to enterprise value over the life of an investment? Enterprise value rests on two variables, expected future cash flows and the discount rate applied to them, and climate risk moves both. Cash flows can shrink from higher costs or fading demand, while investors demand a higher return for climate-exposed businesses, pushing up the cost of capital and pulling enterprise value down.

Tata Power’s experience shows how precisely the market does this arithmetic. When its renewable energy arm raised ₹4,000 crore from a BlackRock-led consortium in 2022 at a valuation of around ₹34,000 crore, Tata Power’s own stock fell more than 7 percent in a single session, with analysts at the time attributing the fall largely to profit-booking after the announcement.

The same arithmetic runs in reverse for physical risk, and often faster. When Chennai flooded in December 2015, plants run by Ford, Renault-Nissan, Daimler, and Yamaha all shut down within days of each other, with Ford and Renault-Nissan alone losing roughly 3,000 vehicles between them, contributing to an industry-wide loss estimated at close to ₹1,000 crore. The flood itself lasted days; the disruption to order books, supplier payments, and insurance claims ran for weeks longer. That is the mechanism climate risk works through: a short-lived event cascades across operations, liquidity, and financing long after the water has receded.

BUYING A COMPANY, BUYING ITS CARBON

Mergers and acquisitions offer another illustration of how the finance professional’s role is expanding. Traditional due diligence has historically focused on financial statements, tax matters, legal disputes, and contractual obligations, but buyers now ask a further set of questions with equal seriousness: is the target exposed to significant flood or heat risk, will future carbon regulation raise its operating costs, how resilient is its supply chain, and how much capital will decarbonisation demand. Together, these questions form what’s now called climate due diligence which is understanding not just today’s profitability but whether it can be sustained.

Take the Adani Group’s 2022 acquisition of Holcim’s stake in Ambuja Cements and ACC. It was India’s largest M&A deal in infrastructure and materials, worth roughly USD 10.5 billion. Cement is one of the most carbon-intensive industries in the world. So buying a cement business means buying a long-dated carbon liability as decarbonising a kiln fleet takes decades, not years. Both Ambuja and ACC had already committed to net-zero by 2050 and the new owner didn’t walk that back. Instead, it went further, setting up independent board committees to oversee ESG performance. Ambuja then became the world’s first cement manufacturer to join the Alliance for Industry Decarbonization.

For a due diligence team, a target’s decarbonisation capex schedule and the credibility of its emission-reduction commitments are now as material to deal valuation as working capital or contingent tax liabilities. A mismatch between the public commitment and the capital earmarked to fund it will eventually surface as an impairment or a financing cost. Closing that gap takes capital and capital, these days, comes with strings attached.

THE NEW LANGUAGE OF CLIMATE CAPITAL

Those strings have created an entire new vocabulary of instruments, as markets have steadily learned to turn climate risk into tradeable debt. Green bonds require proceeds to be deployed exclusively for eligible environmental projects. India’s Sovereign Green Bond programme has mobilised over 44,000 crore rupees since its first tranche in January 2023. Sustainability-linked bonds take a different approach, tying the borrowing cost itself to measurable sustainability targets. Adani Electricity Mumbai’s USD 300 million issuance linked its coupon to a legally binding covenant of at least 60 percent renewable power in its procurement mix by the end of FY2027, with a step-up in the coupon rate if the target is missed.

A newer generation of instruments is emerging alongside these — transition bonds for hard-to-abate sectors like steel and cement, blue bonds for coastal and water projects, and catastrophe bonds that transfer physical risks such as cyclone losses to capital markets. For finance professionals, this expanding toolkit is becoming as relevant as conventional debt and equity structuring once was.

None of this financing happens on its own. The tax and customs system is also being adjusted to support it: Production Linked Incentive schemes worth tens of thousands of crores, a tax holiday under Section 80-IAC of the Income-tax Act, 1961, and waived or reduced customs duty and GST concessions on clean-technology imports and renewable equipment. For a CA advising a manufacturing client, this relief is now just as material to the investment case as the financing itself.

HERO MOTOCORP’S GREEN TRANSITION

Hero MotoCorp built its entire business on internal combustion engines. That could have been an existential threat once transition risk arrived. Instead, the company turned it into an advantage. Consider the evidence. It hit zero-waste-to-landfill status across all its Indian facilities in 2024, a year ahead of its own 2025 target. It is the only Indian two-wheeler maker on the Dow Jones Sustainability World Index, two years running, with its score climbing from 69 to 75.
But the real story is the product. Hero’s electric brand VIDA nearly trebled its unit sales in FY 2025-26, to around 144,000 vehicles. Its share of India’s electric two-wheeler market climbed into double digits, reaching roughly 10 to 11 percent up from a low single-digit share two years earlier. Hero funded the entire shift from its own operating cash flow, not under regulatory pressure. Transition risk and transition opportunity are usually the same shift, seen at two different moments. Get there early, and it looks like opportunity. Get there late, and it looks like risk.

WHEN THE BUSINESS MODEL IS THE CLIMATE STRATEGY

Climate risk eventually asks a hard question to every business: whether its underlying business model can survive a lower-carbon, resource-constrained economy at all. A growing number of Indian companies are answering this by redesigning the model itself. Cement plants are now co-processing industrial and municipal waste as fuel, cutting emissions while solving a disposal problem for other industries. Large agribusiness companies are signing regenerative farming contracts to help smallholder farmers build more resilient crops and soil against erratic monsoons. The logic is simple: a company’s factories can be as efficient as they like, but if the farms feeding them fail, earnings suffer just the same. Protecting the farm is now as important as protecting the factory.

What unites these efforts is a shift in thinking. Sustainability is no longer a cost bolted onto an unchanged business. It is becoming the business model itself. So the real question for finance professionals isn’t just what a decarbonisation initiative costs. It’s whether the business, ten years out, still looks anything like the one being valued today.

FINANCE GETS A BIGGER JOB

That same tension between growth and transformation plays out at the scale of the entire economy. India’s climate journey is itself a paradox. It must keep expanding infrastructure, manufacturing, and energy access to power one of the world’s fastest-growing economies, while cutting the emissions intensity of its GDP by 45 percent from 2005 levels by 2030 and reaching net-zero by 2070. The draft Climate Finance Taxonomy, released by the Ministry of Finance, is one attempt to reconcile the two: it aims to clarify what genuinely counts as a climate-aligned investment, targeting around USD 250 billion a year in redirected finance while cutting down on greenwashing.

Perhaps the most significant opportunity of all lies beyond compliance altogether. Boards are increasingly asking whether climate risk should be built into capital budgeting, how to prioritise adaptation against mitigation investment, and which climate-related investments generate the greatest long-term shareholder value. These are strategic finance questions, and answering them well requires fluency in accounting, valuation, governance, and risk management all at once- precisely the combination Chartered Accountants have always been trusted to bring to the table.

Technology will automate many routine compliance processes, but interpreting climate scenarios and advising boards on capital allocation still requires human judgement. Forward-looking finance teams are already asking not what they must disclose, but what climate-related information would genuinely help them decide better, a shift that turns reporting from compliance into strategy. In practice, this means that they will design climate governance frameworks, conduct assurance engagements, advise on green financing, and help organisations tell genuine value creation apart from superficial sustainability claims.

CONCLUSION

Climate risk got filed under ‘environment’ for a long time. That’s not wrong, but it’s not the whole picture either. Turns out it should have been filed under ‘finance’ all along. At its core, it is about better financial decision-making in a world where the climate itself now moves economic outcomes.

The finance professional’s job hasn’t changed: measure value, protect stakeholders, enable good decisions. What has changed is the terrain. Tata Power’s stock didn’t move on a green narrative; it moved because investors were pricing real cash flows. Hero MotoCorp didn’t wait for a regulator to force its hand into electric vehicles; it moved early enough to fund the shift itself. Climate risk now sits inside asset valuations, lending decisions, insurance costs, supply chains, and corporate resilience. Whether newly qualified or thirty years into practice, every finance professional now needs to look past historical numbers and price in risks that haven’t happened yet.

The real opportunity here isn’t ticking a compliance box. It’s helping businesses allocate capital more intelligently and build something that still creates value in a warming world. Climate risk isn’t another line on the ESG checklist. It’s the next chapter in the story of finance itself. And as it has done before, the profession won’t just adapt to this change — it will help write it.

A Guide to Health and Wellness for CA Professionals

Corporate accounting and finance professionals often suffer from neck stiffness, shoulder aches, and fatigue due to prolonged sitting. To counter these preventable complaints, Dr Krupa Kadakia recommends four simple workplace habits:

  • Ergonomic Setup: Adjust your monitor, chair, and lumbar support to maintain proper posture.
  • Regular Movement: Alternate sitting with standing, take short walks, and break every 30–45 minutes.
  • Desk Exercises: Perform quick 2–3 minute workstation stretches, like thoracic extensions, to relieve stiffness
  • Sunlight Exposure: Get 15–20 minutes of daily sun exposure for vitamin D, immunity, and mood regulation.

These low-effort adjustments protect long-term vitality without disrupting your daily corporate workflow.

BACKGROUND

For most of the corporate accounting and financial professionals, the workday is spent almost entirely at a desk, reviewing spreadsheets, sitting through back-to-back calls and racing against deadlines. It is a routine which leaves no room to think about posture or movement, yet the human body was never designed for 8-10 hours of near total stillness. Human body is designed to move and exercise, the sedentary lifestyle nowadays contributes to most common workplace complaints of neck stiffness, aching shoulders, sore lower back and fatigue post afternoon.

Good news is, these aches and pains are preventable. They do not require a whole lot but some modifications around work to keep active. They require simple modifications around desk set up, stretches, a walk to the printer or kitchen. These are low effort strategies and easily doable at your workstation.

Following insights could be useful in preventing or helping aches, pain and or stiffness and improving health and wellness even being behind a desk.

The Desk Bound Professionals Survival

Insight 1: Ergonomic – foundation, not an afterthought Poor posture rarely announces itself with a single injury. It is usually the accumulation of things, hunched posture, screen height, etc. which then add up to chronic discomfort. This is why ergonomic set up requires attention. A proper ergonomic set up requires the following check list:

Monitor: top of the screen at or just below eye level and arm’s length away

Chair: feet flat on the floor, knees slightly lower than hips

Elbows: bent ~90 degree, close to body and wrist must be in neutral when typing

Lumbar support: a small cushion works to support your lower back

Screen distance: 20-30 inches away to reduce eye strain.

None of these adjustments is going to cost you much and they do not require special equipment’s. If something can be prevented why not make it a priority.

Insight 2: Movement beats Posture – Even a good posture held for too long can be a problem.

It can be tempting to think that ergonomics will fix everything. But the body is not built to hold any position – however correct for hours on end. Prolonged static position even if right can cause workplace related health risks. Movement is the KEY.

If you can get a standing desk, the goal is to not stand the whole day but alternate. Aiming for 30-60 minutes of sitting with 15-20 minutes of standing. Good use: when on calls, while reviewing documents, after eating snacks or lunch while doing some heel raises or mini squats.

Breaks matter as much as posture changes. Every 30-45 minutes either standing up or going on a loo break is the key. Every 2 hours, going for a walk – 3-5 minutes, example going to the kitchen to drink water, make coffee/tea/catching up with colleague. I would recommend a reminder system, either using stick pads on desktop to remind you to take a break for 3-5 minutes or reminder on your phone. These moments have dual function – helps in resetting the body and refresh your focus for next task.

Insight 3: Desk Exercises, helping “no time to exercise” into a non-issue.

Time is one of the barriers for professionals to keep active. Desk exercises solve this by requiring neither a gym nor change of clothes – just a few minutes at your workstation will do the magic.

There are some exercises that if incorporated in the day will help in avoiding muscle and joint pain.

  • Thoracic Extensions – helps in countering forward hunch while typing.

Sit in a chair and clasp both arms behind your head. Gently arch backward and look up toward the ceiling. Repeat 10 times. Could be done 2-3 times each day

Excersie 1

  •  Thoracic Rotations – helps in relieving stiffness through mid-back.

Sitting in the chair, arms across the chest and turning on either side. Repeat 10 times. Could be done 2-3 times/day

Excersie 2

  • Backward bend.

In standing, arms on hips, bending backwards, Repeat 6-8 times. Could be done 2-3 times/day.

Excersie 3

  •  Cervical retractions and shoulder rolling.

In sitting, thinking of forming a double chin, hold for 30 seconds*3 repetitions. Could be done 2-3 times/day

Excersie 4

  • Double leg calf raises.

In standing, 10/12 repetitions*2 sets. Once a day

Exercises 5

  • Sit to stand.

Sit to stand with hands across the chest/. 8-10 repetitions*2-3times/day

Exercises 6

None of these exercises need more then 2-3 minutes of your time in the day and can be done without leaving your desk. They will function as an ongoing physical therapy but with cheap insurance.

Insight 4: Don’t forget the sunlight

Amidst all the focus of posture and movement, one easy habit is always overlooked: SUN EXPOSURE. Getting roughly 15-20 minutes of sun exposure any time of the day supports vitamin D production, which plays an important role in bone health, immune function and mod regulation. Pairing this with any movement during the day is an easy way to fold sun exposure into a habit you are building.

Recommendations

Bringing the pieces together, a few habits will help to protect long term health without disrupting workflow:

  1. Audit the ergonomic set up once
  2. Build in reminder system
  3. Treat standing and walking as schedule, important as your work calls or meeting deadlines.
  4. 15-20 minutes of sunlight during the day

Section 5 Of Limitation Act: Condonation Of Delay Under GST

The debate centers on whether GST appellate authorities (FAA and GSTAT) can condone appeal delays beyond prescribed statutory limits. Grounded in precedents like Singh Enterprises and The Property Company, quasi-judicial tax bodies are statutory creatures, not “courts”. Consequently, Section 5 of the Limitation Act, 1963 cannot extend appeal deadlines beyond statutory ceilings under Sections 107 and 112. Conversely, High Courts and the Supreme Court function as judicial courts where Section 5 applies. While Writ Courts under Article 226 retain constitutional power for exceptional cases (such as natural justice violations), they exercise strict self-restraint.

A debate is going on in the professional forums on whether the appellate authorities i.e., First Appellate Authority (FAA) or the Goods and Services Tax Appellate Tribunal (“GSTAT”), being the creature of statute, have power to condone the delay beyond the condonable period prescribed in the statute. Section 107(1) of the CGST Act, 2017 (“Act”) requires a first appeal to be filed within three months of communication of the order. Section 107(4) of the Act permits the FAA to admit a belated appeal for ‘a further period of one month’ upon sufficient cause is shown. Section 112(1) of the Act requires an appeal to the GSTAT to be filed within three months of FAA order or Revisional Authority order. Section 112(6) of the Act permits GSTAT to admit a belated appeal (or cross-objection, subject to its own 45-day rule) within a further period of three months.

The FAA across India has rejected the appeals filed beyond the condonable period and the said orders are appealable before the GSTAT. Now, the taxpayers have filed the appeals before GSTAT for examining whether the GSTAT can condone the delay in filing the 1st appeal beyond the condonable period prescribed in the statute. Recently, the Principal Bench of GSTAT constituted a Special Bench to determine whether the First Appellate Authority has the authority to condone the delay beyond the statutory time limit.

This is not a new question. The Hon’ble Supreme Court has answered this question repeatedly since 2007 under the Central Excise, Customs and VAT laws, and, very recently, under the Companies Act as well. Yet every time a new fiscal statute comes along, the same question gets litigated afresh. This article explains the judicial precedents from the Central Excise, through VAT, into the Companies Act and applies it to below practical questions that every GST practitioner is facing today –

a. Whether the FAA and GSTAT can condone delays beyond what the statute permits;

b. Whether Section 5 of the Limitation Act [“Act, 1963”] can rescue an appeal filed beyond the condonable period;

c. The position of the High Court and Supreme Court as GST appellate forums;

d. How far can a Writ Court condone the delay once the statutory door has closed?

With the above questions, let us understand the statutory framework under Section 5 and 29(2) of the Act, 1963 first. Section 5 of the Act, 1963 reads as follows –

“5. Extension of prescribed period in certain cases. – Any appeal or any application, other than an application under any of the provisions of Order XXI of the Code of Civil Procedure, 1908, may be admitted after the prescribed period, if the appellant or the applicant satisfies the court that he had sufficient cause for not preferring the appeal or making the application within such period.”

From the above, we can identify that there are two important aspects. First, this power is given to a ‘court’ and not to every forum that decides disputes. Second, Section 5 of the Act, 1963 applies only to proceedings under general law (principally the Code of Civil Procedure). Its extension to a ‘special or local law’ such as a tax statute happens only through Section 29(2) of the Act, 1963, which reads as follows –

The GST Appeal Clock

“29(2). Where any special or local law prescribes for any suit, appeal or application a period of limitation different from the period prescribed by the Schedule, the provisions of Section 3 shall apply as if such period were the period prescribed by the Schedule and for the purpose of determining any period of limitation prescribed for any suit, appeal or application by any special or local law, the provisions contained in Sections 4 to 24 (inclusive) shall apply only in so far as, and to the extent to which, they are not expressly excluded by such special or local law.”

Reading the two provisions together brings up the below two questions –

a. First, does Section 5 of the Act, 1963 apply to other than a court? (which is the point GST practitioners tend to overlook i.e., Section 5 applies only before a ‘court’)

b. Second, does the special law (Central Excise Act, VAT enactment, Companies Act or CGST Act), read as a whole, show an intention to keep Section 5 of the Act, 1963 out of its ambit?

A quasi-judicial authority or tribunal created by a tax statute is ordinarily not a ‘court’, so the gateway under Limitation Act will not be available unless the special law specifically gives the power to condone delay. It is this fundamental point which was recently and emphatically restated by the Apex Court in the company law context in case of The Property Company (P) Ltd. v. Rohinten Daddy Mazda1 (hereinafter referred as ‘Property Company’), which this article places at the Centre of the GST analysis, ahead of the more familiar ‘complete code’ debate.


1 Civil Appeal No.92 of 2026 (Arising out of S.L.P (Civil) No. 3906 of 2017)

Before proceeding further, let us understand the position under Central Excise, Service Tax, Customs and VAT context. In Singh Enterprises v. CCE, Jamshedpur2, the Apex Court examined the provisions of Section 35 of the Central Excise Act, 1944, which provides 60 days’ time limit to file an appeal with additional condonation period by a further 30 days. The Court held that the Commissioner (Appeals) and the Tribunal, being creatures of statute, cannot condone the delay beyond the time limit prescribed in the statute. A specific 30 day upper cap shows a clear intent to exclude Section 5 of the Act, 1963. There was no law declared by Supreme Court that even though the Statute prescribed a particular period of limitation, this Court can direct condonation. That would render a specific provision providing for limitation rather otiose.


2 (2008) 221 ELT 163 (SC)

A year later, in Commissioner of Customs & Central Excise v. Hongo India (P) Ltd.3, a three-judge Bench went a step further. The provision in question is the unamended Section 35H of the Central Excise Act, 1944 governing reference applications to the High Court which prescribed 180 days with no condonable extension at all. The Court held that the Sections of the same Chapter i.e., Sections 35, 35B, 35EE, 35G expressly grants a condonable extension but not in Section 35H and this silence itself is an indicator of exclusion and it binds even the High Court under Section 5 of the Act, 1963.


3 (2009) 236 ELT 417 (SC)

In VAT context, the Apex Court in case of Patel Brothers v. State of Assam4, examined Section 81 of the Assam VAT Act, 2003 which provides 60 days period for revision before the High Court, while Section 84 of the same Act made only Sections 4 and 12 of the Act, 1963 applicable to such proceedings. It was held that this selective adoption was itself a clear act of exclusion. If the Legislature wanted Section 5 to apply, it would have specified it exactly as it did elsewhere in the same Act (Sections 79 and 80, which gave the FAA and Tribunal forums an express further condonable period). The High Court, therefore, had no power to condone a 335-day delay.


4 (2017) 345 ELT 578 (SC)

Two years later, on almost identical facts under a sister enactment, the Apex Court reached the opposite result. In Superintending Engineer, Dehar Powerhouse Circle v. Excise & Taxation Officer5, it was held that Section 48 of the Himachal Pradesh VAT Act, 2005 provides 90 days period for a revision and it was silent altogether regarding the Act, 1963. The Court distinguished Patel Brothers on precisely this ground and held that Section 5 stood attracted. Read together, the two cases show there is no standard rule that ‘tax statutes exclude Section 5’ or the reverse and each statute has to be read on its own text.


5 2019 (30) GSTL 193 (SC)]

Later, the Apex Court in case of Assistant Commissioner (CT), LTU, Kakinada v. Glaxo Smith Kline Consumer Health Care Ltd.6, while examining the Andhra Pradesh VAT Act has held that once the statutory appeal remedy has been foreclosed by limitation, a Writ Court should exercise self-restraint rather than routinely reviving it, doing so would make the limitation scheme meaningless.


6 2020 (36) G.S.T.L. 305 (S.C.)

Now, coming to Companies Act context, it is pertinent to examine the recent decision of the two-Judge Bench of the Apex Court in case of ‘Property Company’, wherein it examined a similar question. Although the decision is in the context of Companies Act, it has laid down the principles which are equally applicable for every quasi-judicial GST forum, including GSTAT. In this case, the respondent sought registration of shares inherited under a will, more than two decades after probate, and approached the Company Law Board (“CLB”) under Section 58(3) of the Companies Act, 2013 with a delay of 249 days. The CLB condoned the delay, citing the respondent’s residence abroad and confusion during the transition from the 1956 Act and this decision was affirmed by the Calcutta High Court. Later, the Apex Court set aside both the orders and held that the CLB had no power to condone the delay, for two reasons as follows –

a. First, the Act, 1963 including Section 5 applies only to proceedings before ‘court’. A quasi-judicial body being a creature of statute does not automatically acquire that character. It must actually be shown to be a court.

b. Second, Section 433 of the Companies Act (which expressly gives the NCLT and NCLAT the power to apply the Act, 1963) cannot be read backwards to give the same power to the CLB, an earlier and different body, merely because both perform similar functions. The Court put it plainly –

“…the provisions of the Act, 1963…would only apply to suits, applications or appeals which are made under any law to ‘courts’ and not to those made before quasi-judicial bodies or tribunals, unless such quasi-judicial bodies or tribunals are specifically empowered in that regard… The absence of express exclusion, by itself, cannot be said to have conferred the CLB with the power to condone delay.”

This reframes the debate for GST. Most common question that is being asked based on Singh Enterprises is whether Section 107 (or 112) of the Act impliedly excluded Section 5 of the Act, 1963? The Property Company insists on a prior question i.e., is the Appellate Authority, or GSTAT, a ‘court’ at all, so that Section 29(2) of the Act, 1963 even opens the gate to Section 5 in the first place? On this footing, the ‘implied exclusion’ debate becomes almost academic and the power to condone delay has to be found within Sections 107 and 112 of the Act themselves, because neither provision has stated that Section 5 of the Act, 1963 is applicable.

Coming to GST context, many High Courts held that Sections 107 of the Act is complete code that impliedly exclude Section 5 of the Act, 1963 beyond these ceilings relying on Singh Enterprises and Hongo India. Few of the decisions under GST include Penuel Excus (P) Ltd v. Additional Commissioner (Appeals)7, Garg Enterprises v. State of U.P.8, Abhishek Trading Corp. v. State of U.P.9, Nandan Steels & Power Ltd. v. State of Chhattisgarh10 and Venkateswara Rao Kesanakurti v. State of A.P.11, wherein it was held that CGST Act a self-contained code excluding Section 5 of the Act, 1963.


7 2023 (75) GSTL 582 (Kerala)

8 2024 (15) Centax 510 (All)

9 2024 (16) Centax 179 (All)

10 2023 (6) Centax 301 (Chhattisgarh)

11 2024 (23) Centax 43 (AP)

Against this, a Division Bench of the Calcutta High Court in S.K. Chakraborty & Sons v. UOI12 has held that since provisions of Section 5 of the Act of 1963 have not been expressly or impliedly excluded by Section 107 of the Act of 2017, by virtue of Section 29 (2) of the Act of 1963, Section 5 of the Act of 1963 stands attracted and the FAA can condone delay beyond the four-month ceiling on sufficient cause. This has been followed in later Calcutta decisions in case of Arvind Gupta v. Assistant Commissioner of Revenue13; Partha Pratim Dasgupta v. Joint Commissioner of State Tax and Ors14.


12 2024 (15) Centax 172 (Cal)

13 (2024) 14 Centax 295 (Cal.)

14 (2024) 19 Centax 357 (Cal)

However, the High Courts in case of Yadav Steels v. Commissioner15 and Addichem Speciality LLP v. Special Commissioner-I, Delhi GST16 refused to condone delay beyond 4 months, holding that Section 5 of the Act, 1963 cannot extend the maximum condonable period provided under Section 107 of the Act, relying on Singh Enterprises, Hongo India and Glaxo Smith Kline and distinguishing ‘S.K. Chakraborty’. Also, the decisions of Calcutta High Court do not survive The Property Company test as the Appellate Authority cannot be considered as a ‘court’ for the purposes of Section 29(2) of the Act, 1963.


15 2024 (19) CENTAX 435 (All)

16 (2025) 27 Centax 145 (Del.)

In view of the above analysis and discussion, the answers to the questions framed are as follows –

(a) Whether GSTAT and the F AA can condone delays beyond the condonable period?

No, the FAA and GSTAT are both creatures of statute and cannot condone the delay beyond the time limit prescribed under the statute.

(b) Whether Section 5 of the Act, 1963 can rescue a belated appeal?

No, considering the above-referred judicial decisions. Until the Supreme Court resolves the conflict directly in the GST context, practitioners outside West Bengal should proceed on the footing that Section 5 offers no rescue beyond the statutory ceilings.

(c) The position of the High Court and Supreme Court as GST appellate forums?

Yes, because of the ‘court’ distinction in The Property Company. Section 117 (appeal to the High Court on a substantial question of law from a GSTAT order) prescribes 180 days and Section 117(3), expressly applies the Code of Civil Procedure’s appellate provisions consequent to which Section 5 of the Act, 1963 will come into picture as the High Court is unquestionably a court. Section 118 (appeal to the Supreme Court) attracts the CPC similarly.

(d) How far can a Writ Court condone the delay once the statutory door has closed?

Two separate questions here. First, where GSTAT rejects an appeal as filed beyond the condonable period provided under Section 112(6) of the Act, a further appeal under Section 117 of the Act lies only on a ‘substantial question of law’. Whether GSTAT correctly applied its own statutory ceiling is ordinarily not such a question and it is settled law applied to undisputed facts, so the High Court would ordinarily decline to re-open it, except where GSTAT itself misapplied the ceiling (say, miscalculated the date of communication).

Second, and more commonly litigated, is where a taxpayer approaches the jurisdictional High Court directly under Article 226, seeking either to compel condonation or to have the underlying order quashed. This power comes not from Section 5 of the Act, 1963 at all, but from the extraordinary, equitable jurisdiction under Article 226 (and, over subordinate tribunals, Article 227), which exists independently of any taxing statute’s limitation scheme. But the Apex Court has repeatedly cautioned against treating independence as a license, the governing principle, most clearly stated in ‘Glaxo Smith Kline’, is self-restraint, a Writ Court should not routinely use Article 226 to overcome the statutory framework. However, the restraint is not absolute. Writ jurisdiction survives on narrower, jurisdictional or constitutional grounds that are not really Section 5 discretion in disguise –

a. Violation of Natural justice: Where the appeal was rejected solely on delay without providing effective opportunity of being heard to explain the reasons for delay.

b. Want of jurisdiction or a fundamental-rights violation: Where the original order is wholly without jurisdiction or offends Article 14/19/21, a time-barred appellate remedy does not oust writ jurisdiction over such an order, a position recognized even in Singh Enterprises.

c. Non-communication or defective communication: Where limitations never validly began to run because the order was not properly served. Here the writ jurisdiction holds that no delay occurred in law, rather than condoning one.

d. Gross, demonstrable hardship, exercised sparingly: The writ jurisdiction is not per se barred merely because a statutory remedy is time-barred, though it remains extraordinary and sparingly used.

The source of the Writ Court’s power is constitutional, not statutory, and its extent is deliberately narrow as explained above but not as a routine substitute for a missed statutory condonation window.

CONCLUDING REMARKS

A two decade of near-identical litigation across Central Excise, Customs, VAT, Companies Act and now GST forums suggest the problem is structural, not merely a matter of interpretation. Decision of The Property Company, though decided far from GST, gives more clarity to the practitioners as against the ‘complete code’ test alone. However, the Parliament (or the GST Council) should consider whether the current law position serves any real purpose. Express provision clarifying exactly how far the Act, 1963 applies to the Appellate Authority, Revisional Authority and GSTAT would also help the taxpayers to be more vigilant. Also, a large share of the condonation litigation is due to disputes on dates of communication, therefore, the cross-verification by SMS and e-mail (as GSTAT’s own portal already partly does) for all communications, would resolve a good fraction of these disputes before they even reach a condonation application.

Recent Amendments In The Foreign Contribution (Regulation) Rules

The recent Foreign Contribution (Regulation) Rules amendments introduce several key compliance updates:

  • Key Functionaries: Formally defined under Rule 2(ca), affecting administrative expense calculations (capped at 20%) and restricting foreign nationals. Intimations require Form FC-6E.
  • Purpose and Territory: Registration is restricted to specified Scheduled purposes and States using Form FC-6F; modifications require MHA approval.
  • Domestic Use: Foreign funds must be utilized strictly within India for stated objectives.
  • Minimum Activity: Associations must spend at least ₹10 lakh over two financial years.
  • Form FC-4 Disclosures: Mandates reporting social media accounts, ultimate DAF donors, project-wise expenses, publications, and auditor UDINs.

INTRODUCTION

The Foreign Contribution (Regulation) Rules 2011 (“the Rules”) prescribed under the Foreign Contribution Regulation Act 2010 (“the Act”) have been amended vide notification dated 22.6.20261. This article contains an analysis of the key amendments in the Rules and in Forms.


1 The text of the Rules is given in the link: https://fcraonline.gov.in/9f211570-9722-4cc3-b17f-8bd3dcf78f99

PART I : AMENDMENT IN THE RULES

1. Key functionary

1.1. Background

Hitherto, the term “key functionary” was not defined. It has now been defined under rule 2(ca) as follows:

“key functionary”, in relation to a person other than an individual, includes—

(i) the Director of a company;

(ii) a partner in a firm;

(iii) a trustee of a trust;

(iv) the Karta of a Hindu undivided family;

(v) an office bearer, member of the governing body, managing committee or other controlling authority of a society, trust, trade union or association of individuals; and

(vi) any other officer or person, by whatever name called, who has control over, or responsibility for the management or affairs of such person;

FCRA 2026

1.2. Observations

The definition can be divided into four limbs:

(i) A person who is key functionary within the ordinary meaning of the term (since the definition is inclusive);

(ii) Director of a Company, partner in a firm, trustee of a trust, Karta of an HUF;

(iii) An office bearer, member of the governing body, managing committee or other controlling authority of a society, trust, trade union or association of individuals;

(iv) Any other officer or person, by whatever name called, who has control over, or responsibility for the management or affairs of such trust.

Limb (ii) consists of individuals where there is no ambiguity. In other limbs, there could be ambiguity in whether a particular individual is a key functionary or not. The subsequent paragraphs 1.4 to 1.9 analyse these limbs (i), (iii) and (iv)

1.3. Ordinary meaning of “key functionary” (first limb)

The terms “key” and “functionary” have been defined in dictionaries as follows:

Key

  •  “Chief; major; important; fundamental; pivotal; a key person in the company; key industries.” [Random House Compact Unabridged Dictionary]
  • “Very important and having a lot of influence on other people or things.” [http://dictionary.cambridge.org/dictionary/english/]

Functionary

  • “a person who functions in a specified capacity, esp., in government service; an official; civil servants, bureaucrats, and other functionaries.” [Random House Compact Unabridged Dictionary]
  • “A person who has to perform official functions or duties; an official.” [http://www.oxforddictionaries.com/]

Thus, in its ordinary sense, a “key functionary” means a person occupying an important position and exercising significant functions in an organisation, [but excluding the persons mentioned in limbs (ii) to (iv)]. It would also include an individual designated as “chief functionary”.

1.4. An office bearer, etc. (third limb)

The term “office bearer” is not defined in the Act/Rules.

Office

  • The word `office’ is normally understood to mean “a position to which certain duties are attached, esp. a place of trust, authority or service under constituted authority”. [See Oxford Shorter English Dictionary, cited in P. V. Narasimha Rao v. State, AIR 1998 SC 2120. Also see Statesman (Private) Ltd. v. H.R. Deb, AIR 1968 SC 1495, Mahadeo v. Shantibhai, 1969 (2) SCR 422; Satrucharla Chandrasekhar v. Vyricherla Pradeep Kumar, (1992) 4 SCC 404]
  • An ‘office’ means a public or private employment with certain duties to be performed [Dewan Joynal Abedin v. Abdul Wazed, (1988) 2 SCR 370]

Bearer

  • One that bears; a person or thing that carries, upholds, sustains, or brings something [Merriam-Webster]
  • A person who bears or carries something [Britannica Dictionary]

On a combined reading, the expression “office bearer” means holder of a position with certain duties attached to the position. On its own, this term is quite wide, but having regard to the following context, its meaning should be restricted to persons occupying very important position.

The “office bearer”

(a) must be a “key functionary” and therefore, he must be a person occupying an important position and exercising significant functions, authority or responsibility in an organisation, and does not cover every holder of any position.

(b) should be read in the context of the second limb, that is, he is akin to director, partner, trustee or Karta. All these persons occupy very important positions and similarly, office bearer should also occupy a very important position.

(c) should be read in the context of the fourth limb, that is, it should cover a person control over, or responsibility for the entire or substantially the entire management or affairs of the person, and not every person holding a position.

(d) In limb (iii) it could be argued that the word “or” should be read between “bearer” and “member” and so read the individual should be an office bearer of the governing body, etc.

1.5. Any other officer or person who has control over, or responsibility for the management or affairs of such person (fourth limb)

There could be two views on the meaning of the expression “control over or responsibility for the management of affairs of such person”.

1.5.1. View 1

The person should have control over, or responsibility for the entire management or affairs or substantially the entire management or affairs of the person. The arguments in support of this view are as follows:

(a) On a plain reading, “management or affairs of a person” should mean management or affairs of the association; the words “control or responsibility for partial management or affairs” cannot be read into the definition.

(b) The word “key” indicates that the provision is intended to cover persons occupying positions of substantial importance in the management of the organisation. Every individual responsible for partial or limited function cannot be considered “key” person. For example, an employee who is responsible only for accounts is not a “key functionary” under limb (iv).

(c) Limbs (i) to (iii) cover persons who, occupy important positions in the governance or management of the entity. Limb (iv), although residuary and wider, should also be read so : it would therefore be inappropriate to treat every person having responsibility for any individual aspect of the organisation’s activities as a key functionary.

(d) ‘Key functionary’ has significant implications under the Act/Rules. To illustrate

  • his salaries, etc. are considered as admin expenses (Rule 5).
  • The application for registration is to be accompanied by his affidavit (Rule 9).
  • If he is a foreign national, the association is not considered eligible for registration [Explanation 1 to Rule 9(5)].

Now, the officer or person referred to in limb (iv) is not construed narrowly, although he may not be a very important official,

  • his salaries, etc. will be considered as admin expenses
  • the application for registration will have to be accompanied by his affidavit.
  • the association shall not be considered eligible for grant of registration.

Ordinarily, this could include a Chief Executive Officer or any other person, irrespective of the designation, who exercises control over or has responsibility for the management or affairs of the organisation.

1.5.2. View 2

The reference to “management of affairs” should ordinarily connote responsibility or control of a sufficiently significant nature, rather than responsibility for merely a limited aspect of the organisation’s activities. However, it should not be restricted to entire management or affairs or substantially the entire management or affairs, as proposed in View 1. Accordingly, in determining whether a person falls within limb (iv), the following factors may be relevant:

  • the nature and extent of the person’s powers;
  • whether the person can make or materially influence significant decisions;
  • the extent of the person’s authority over the organisation;
  • whether the person has control over its operations or affairs;
  • whether the person is responsible for the organisation as a whole or only for a limited function; and
  • the actual functions and responsibilities performed, rather than merely the designation of the person

1.5.3. Conclusion

The matter is not clear but View 1 appears to be better view.

Thus, the definition of “key functionary” is very subjective and ambiguous and may require factual analysis as to whether a person is a key functionary or not.

If any new person is identified as “key functionary”, the association was required to file intimation in Form FC-6E within 45 days of 22.6.2026, that is, on or before 6.8.2026. Therefore, it is advisable to expedite this analysis and, if required, the said Form should be immediately filed after passing appropriate resolution of the Board of Directors, etc.

1.6. Suggestion

Where there is any ambiguity as to whether an individual is a “key functionary”, an explanatory note may be included in the relevant resolution of the Board, etc. explaining why the person is or is not being treated as a key functionary. This would provide a contemporaneous record of the basis on which the organisation has determined its key functionaries show its bona fides in case of any allegation of default.

1.7. Impact on administrative expenses (rule 5)

1.7.1. Text (relevant portion)

The following shall constitute administrative expenses:

(i) salaries, wages, travel expenses or any remuneration realised by the key functionaries of the person;

(ii) all expenses towards hiring of personnel for management of the activities of the person and salaries, wages or any kind of remuneration paid, including cost of travel, to such personnel;

(iii) all expenses related to consumables like electricity and water charges, telephone charges, postal charges, repairs to premise(s) from where the organisation or Association is functioning, stationery and printing charges, transport and travel charges by the key functionaries and expenditure on office equipment;

1.7.2. Observations

  • It appears that the salary, etc. of the “new key functionary” may be considered as administrative expenses from 22.6.2026.
  • The total of administrative expenses defrayed out of foreign contribution cannot exceed 20% of such foreign contribution. Thus, any increase in number of key functionaries may increase the total of administrative expenses and hence some admin expenses may have to be defrayed out of funds other than foreign contribution to ensure that the limit of 20% is not breached.

2. REGISTRATION LIMITED TO SPECIFIED PURPOSES/STATES AND INTIMATION BY EXISTING CHARITABLE INSTITUTIONS

2.1. Background

Hitherto, the certificate of registration specified the purpose, that is, one or more out of cultural, economic, educational, religious or social (“cultural, etc.”) as specified in section 11 of the Act. These terms were not defined and accordingly they were to be interpreted in normal parlance and perhaps, on the basis of the facts stated in the application for registration.

Further, the activities could extend to entire India.

2.2. Text [Rule 9(1A)]

The certificate of registration shall specify the purpose or purposes and the States or Union territories for which registration is granted.

(b) Every application for registration shall mention—

(i) the purpose or purposes for which registration is sought, chosen only from such list of purposes as specified in the Schedule appended to these rules; and

(ii) the States or Union territories in which the association proposes to undertake the activities.

(c) Every association registered before the commencement of the Foreign Contribution (Regulation) Amendment Rules, 2026 shall, within one year of such commencement, submit to the Central Government an intimation in Form FC-6F specifying the purpose or purposes and the States or Union territories for which it seeks to retain its registration.

2.3. Observations

2.3.1. The application now requires

  •  the purpose of the association to be restricted to one or more out of the list of purposes as specified in the Schedule appended to the Rules (“Scheduled purposes” or “sub-purposes”) and
  • the States or Union Territories in which the association proposes to undertake the activities (“the States”).

2.3.2. An association registered before 22.6.2026 has to submit to the Central Government on or before 21.6.2027, an intimation in Form FC-6F, specifying the list of Scheduled purposes and the States applicable to it.

The intimation may have to be preceded by a resolution of the Directors, etc.

On a plain reading, only an intimation is required; no approval from Ministry of Home Affairs (MHA) is necessary.

2.3.3. The sub-purposes have to be selected from the Scheduled purposes & they cannot go beyond the purposes mentioned in the registration certificate, that is, cultural, etc. For example, if the association has been granted registration for “educational” purpose, it must select the sub-purposes from “educational” category and cannot opt for sub-purposes from any other category.

2.3.4. The Act merely requires that the association should have a definite programme in the cultural, etc. field. However, there is no restriction in the Act as to the meanings of the words “cultural, etc.” Further, the Act is also silent on whether the Rules can curtail the sub-purposes to those specified in the Schedule. In the circumstances, it is a moot point as to whether the restriction to Scheduled purposes by the Rules is ultra vires the Act or not.

2.3.5. In Noel Harper v. UOI, WP (Civil) No. 566 of 2021, the Supreme Court had reproduced the illustrative list of permitted activities as mentioned in the Annual Report (2004-2005) prepared by the MHA. A comparison of the said list with the Scheduled purposes shows that there are many items in the list which are not mentioned in the Schedule. A significant omission is that while the old list had “any other activities related to the above” as a residual clause, the Schedule does not have this clause. It could be argued that in spite of this omission, the individual entry in the Schedule has to be read liberally and should include ancillary and incidental activities. The exact scope of such activities will, of course, be fact driven.

2.3.6. It appears that, where the beneficiaries of an activity are located in a particular State, the activity may be regarded as undertaken in that State, even if the association does not have an office or other establishment in that State. For example, if the association conducts online training for beneficiaries based in Bihar, the activity may be considered as undertaken in Bihar. The fact that the employees who are imparting such training are based in Karnataka, or that the association does not have an office in Bihar, does not alter this position.

2.3.7. However, a distinction may be drawn in the case of internal training of the association’s own staff. If such training is an internal administrative or capacity-building activity rather than an activity undertaken for the fulfilment of the association’s stated purposes, it may not constitute an activity in the State where the staff training is conducted.

2.3.8. Thus, the focus should be on where the association’s charitable activities are actually undertaken, rather than merely on the residential location of its employees.

3. CHANGING PURPOSE OR STATE

3.1. Text [Rule 17B]

Change of scope of registration.- (1) An association registered under the Act which intends to change its area of operation by including or deleting any purpose or any State or Union territory specified in its certificate of registration shall apply, in Form FC-6F, for such inclusion or deletion, along with—

(a) a resolution of the governing body approving such application;

(b) the prescribed fee.

(2) The fees payable for inclusion of additional purpose or State or Union territory under sub-rule (1) shall be in accordance with sub-rule (4) of rule 9 and the proviso thereof.

(3) The Central Government may, after such inquiry as it deems fit, approve or reject the application under sub-rule (1).

3.2. Observations

3.2.1. After the intimation referred to in para 2 above is filed, the purposes & States can be added/deleted by filing Form FC-6F. However, before filing the application a resolution has to be passed by the governing body approving the application.

3.2.2. Such addition will require MHA approval.

The filing of Form FC-6F will entail fees of ₹300 per additional State and ₹300 per additional sub-purpose [Rule 9(4)].

The MHA may make such inquiries as it deems fit including a field visit, and then approve or reject the application.

3.2.3. Deletion of purposes and States require the same process too.

3.2.4. No statutory timeline is provided for approval / rejection by MHA

4. ASSOCIATIONS WITH FOREIGN NATIONALS OTHER THAN PIO AS KEY FUNCTIONARIES BARRED FROM REGISTRATION

4.1. Background

Hitherto, an FAQ was published on MHA website as follows:

“Whether foreigners can be appointed as Executive Committee members of an association seeking registration or prior permission?

Organizations having foreign nationals, other than of Indian origin, as members of their executive committees or governing bodies are generally NOT permitted to receive foreign contribution. However, foreigners may be allowed to be associated with such associations in an ex-officio capacity, if they are representing multilateral bodies, foreign contribution from whom is exempted from the purview of the Foreign Contribution (Regulation) Act, 2010, or in a purely honorary capacity depending upon the person’s stature in his/her field of activity. Relaxation may be considered on case to case basis by an authority higher than the competent authority, if any of the following grounds is met:

1) the foreigner is married to an Indian citizen;

2) the foreigner has been living and working in India for at least five years;

3) the foreigner has made available his/her specialized knowledge, especially in the medical and health related fields on a voluntary basis in India, in the past;

4) the foreigner is a part of the Board of Trustees/Executive Committee in term so the provisions in an inter-governmental agreement;

5) the foreigner is part of the Board of Trustees/Executive Committee, in an ex-officio capacity representing a multilateral body which is exempted from the definition of foreign source.”

However, there was no express provision in the Act/Rules to the effect that associations with foreign nationals other than PIO as key functionaries are barred from grant of registration/prior permission.

4.2. Text [Explanation 1 to Rule 9(5)]

It is hereby clarified that an association having foreign nationals, other than those of Indian origin, as its key functionaries shall ordinarily not be considered eligible for grant of registration or prior permission under the Act.

Provided that the Central Government may, by order, specify such cases or circumstances in which foreign nationals may be permitted to be key functionaries of an association for the purposes of consideration of registration or prior permission, and the conditions to be fulfilled for such consideration.

4.3. Observations

Thus, an association with foreign nationals as key functionaries (other than PIOs) will not be ordinarily granted registration.

For the purposes of the proviso, the Central Government will specify the exceptional cases or circumstances; this could be on the basis of those listed in the above cited FAQ.

5. FUNDS ONLY FOR INDIA ACTIVITIES AND STATED OBJECTS

5.1. Background

Hitherto, the Act/Rules did not provide that foreign contribution could be utilized only for activities in India. However, Form FC-4, had, and continues to have, a question on whether “the Association has utilized any foreign contribution outside India?” [Sr. No. 8(xv)]

5.2. Text [Explanation 2 to Rule 9]

For the removal of doubts, it is hereby clarified that the foreign contribution so received shall be utilised only for activities carried out in India in accordance with the association’s stated objectives and for the purposes for which such contribution has been received.

5.3. Observations

5.3.1. Thus, foreign contribution must be used only for activities carried out in India, and only for stated objectives and registered purpose(s) for which it was received: it cannot be diverted to another cause even within India.

5.3.2. It may be argued that an expenditure incurred outside India would not, by itself, result in a violation of the Explanation, provided that the expenditure is integrally connected with, and facilitates, an activity that is actually carried out in India. For example, a computer is purchased outside India is used exclusively in India for carrying out the association’s teaching activities in India, it may be argued that the foreign contribution has ultimately been utilized for an activity carried out in India.

This is likely to be a fact-specific determination. The nature and purpose of each expenditure incurred outside India and the nexus between such expenditure and the activity carried out in India would need to be considered on a case-by-case basis.

5.3.3. Further, even if an expenditure is regarded as utilised for activity carried out in India, such expenditure may have implications under the Income-tax Act 2025.

5.3.4. As mentioned above, FC-4 continues to have a question on whether “the Association has utilised any foreign contribution outside India?” – para 8(xv). This appears to suggest that even if the Association incurs expenditure outside India for activity in India, it will need to report here and may be subject to further scrutiny.

5.3.5. The expression “stated objectives” appears to refer to the objects of the association as set out in its constitutional document, such as its Memorandum of Association and which are mentioned in the registration / renewal application.

5.3.6. The expression “purposes for which such contribution has been received” appears to refer to the specific purpose for which the foreign contribution has been received, that is, mentioned by the donor, but limited to Scheduled purposes selected by the association. Thus,

  • even where an activity falls within the association’s stated objectives, the utilization of the foreign contribution should be consistent with the specific purpose for which the contribution was received.
  • a foreign contribution cannot be received for a purpose other than the Scheduled purposes selected by the association, even if the donor so wishes. In such circumstances, the association should make an application for change in purpose referred to in para 3 above before receiving the contribution.

6. MINIMUM-ACTIVITY TEST

6.1. Background

One of the conditions for grant of registration is that the person making the application has undertaken reasonable activity in its chosen field for the benefit of the society for which the foreign contribution is proposed to be utilized [section 12(4)(b)].

Further, the Central Government may cancel the certificate if the holder of the certificate has not engaged in any reasonable activity in its chosen field for the benefit of the society for two consecutive years [section 14(1)(e)].

What amounts to reasonable activity was not explained in the Act/Rules.

6.2. Text [Rule 14A]

Utilisation of foreign contribution for reasonable activity. – For the purposes of cancellation under section 14 and renewal under section 16, an association shall be deemed to have undertaken reasonable activity in its chosen field for the benefit of society if it has utilised foreign contribution of not less than ten lakh rupees in the last two financial years for such purpose.

6.3. Observations

6.3.1. While the matter is not clear, it appears that the amount of Rs.10 lakhs excludes administrative expenses incurred by the association (since the same may not be regarded as activity for the benefit of the society).

6.3.2. Activity

The association has to undertake “reasonable activity”. The word “activity” is judicially explained in other contexts as follows:

  • The word ‘activity’ is wider than the word ‘business’. It connotes a specified form of supervised action or field of action. Read in the context of the profit-earning activity of a co-operative society it means the corporate activity of the society, that is to say, the combination of operations undertaken by the co-operative society whether or not they amount to a business trade or profession in the ordinary sense. [Kottayam Co-operative Land Mortgage Bank Ltd v. CIT, (1988) 172 ITR 443 (Ker)2]
  • …Normally, an activity would include an act done, a work done, a deed done, an operation carried out, execution of an act, provision of a facility etc. Where applicant receives the violation charges from contractors there is no activity done by both the parties. [Dholera Industrial City Development Project Ltd., In re, (2019) 108 taxmann.com 510 (AAR-GUJ)]
  • Webster’s New International Dictionary defines the word “activity” as “natural or normal function or operation;…” Another significant dictionary definition is: “ The state of action, doing; an exercise of energy or force; an active movement or operation; a physical or gymnastic exercise, an agile performance.

2  For the purpose of section 80P(2)(c) of the Income-tax Act, 1961.

The word “activity or activities” of course as applied to various things has various meanings but the ordinary accepted meaning of the term when applied to any particular thing is that it covers everything that the individual or the corporation does.

[Carbide & Carbon Chemicals Corp v. Carson, 192 Tenn. 150 (1951)]

6.3.3. On a literal reading, this test is applicable for any renewal after 22.6.2026. Thus, it could apply retroactively for financial year 2024-25 and financial year 2025-26 . However, the matter is not clear.

Part II: Amendment in Forms

7. RENEWAL (FC-3C): 3-YEAR ACTIVITY HISTORY

For the renewal of registration, a year-wise detailed activity report of last three financial years is required to be attached [Note (c) at the end of the Form FC-3C].

The report should

(a) be detailed

(b) be year wise

(c) cover last three financial years

(d) cover all activities (except, perhaps, insignificant activities)

8. ADDITIONAL REQUIREMENTS FOR FC-4 (ANNUAL RETURN)

8.1. Website + social-media disclosure

8.1.1. The annual return in Form FC-4 now requires disclosure of the following:

(a) official website of the association

(b) social-media accounts of the association.

[Sr. No. 1(c)]

8.1.2. Observations

(a) What is required is disclosure of “social media accounts” and not “social media posts.”

(b) The FC-4 provision refers to “Social Media Accounts of the Association” and not of its key functionaries (except where they are officially designated, named, or run primarily as the media voice of the association). This is different from the publication disclosure, where the Form FC-4 expressly refers to material published by the association or its key functionaries (see para 8.6).

(c) Any social media account of the association must be disclosed, even if the posting frequency is low or the account is dormant.

(d) The association will have to separately maintain records of any posts by the association, even if they are deleted from the account.

(e) Meaning of social media

The Rules do not define “social media” or specify an exhaustive list of platforms. Therefore, the expression should be understood in its ordinary and reasonably broad sense.

Online dictionaries define “social media” as follows:

forms of electronic communication (such as websites for social networking and microblogging) through which users create online communities to share information, ideas, personal messages, and other content (such as videos) [https://www.merriam-webster.com/dictionary/social media]

websites and computer programs that allow people to communicate and share information, opinions, pictures, videos, etc. on the internet, especially social networking websites:

forms of media that allow people to communicate and share information using the internet or mobile phones:

[https://dictionary.cambridge.org/dictionary/english/social-media]

(f) The following could be considered as social media:

  • Facebook
  • Instagram
  • X (Twitter)
  • LinkedIn
  • YouTube Channel
  • WhatsApp Channel/Telegram Channel/Signal (if used as public communication channel)
  • Facebook/Instagram groups (if maintained/controlled by the association)

However, WhatsApp group for internal staff is not necessarily social media.

8.2. Ultimate-donor for Donor Advised Fund (DAF) / intermediary routes

8.2.1. Form FC-4 now requires the following details:

Details of ultimate donors in case of Donor Advised Funds/Other intermediary remittance vehicles

Sl. Name of intermediary Nature of intermediary Donor Advised Funds/Other intermediary remittance vehicles) Name of ultimate donor Address of ultimate donor Email address of ultimate donor Amount Rs.
(1) (2) (3) (4) (5) (6) (7)

[Sr. No. 2(ii)(aa)]

8.2.2. Meaning of DAF

The meaning of “DAF”, has been given by various AI platforms. Based on this, a DAF may be broadly summarised as follows:

(a) A DAF is a charitable giving arrangement under which a donor makes a contribution to a sponsoring charitable organisation (the “donee”).

(b) The donee holds and administers the contributed assets in a separate fund or account associated with the donor.

(c) The donor generally retains the right to recommend how and when amounts held in the fund should be distributed to eligible charitable organisations. However, the donor does not retain legal ownership of, or ultimate legal control over, the assets contributed to the fund.

(d) Irrevocable Contribution

Once a donor makes contribution to a donee, the contribution becomes the property of the donee. The donor ordinarily has no right to reclaim or withdraw the contribution.

(e) Donor’s Advisory Rights

The donor may generally recommend:

(i) the charitable organisations to which grants should be made;

(ii) the amount of each grant; and

(iii) in certain cases, the timing or purpose of the grant.

The donor may make recommendations but does not have legal control over the grants. The donee retains ultimate discretion to approve or reject the donor’s recommendations.

(f) Investment of Corpus

Until grants are made, the assets held in the DAF may be invested. Any investment income and appreciation generally remain within the fund and may subsequently be applied towards charitable grants to the donee.

(g) Illustration

Suppose “A” contributes ₹1 crore to a charitable institution (donee).

  • The ₹1 crore becomes the property of the donee.
  • “A” may recommend that ₹20 lakh be granted to Charity X, ₹30 lakh to Charity Y and ₹10 lakh to Charity Z.
  • The donee considers and approves those recommendations.
  • The remaining ₹40 lakh may continue to be invested by the donee and may be used for future charitable grants.
  • “A” cannot withdraw ₹1 crore.

In the above illustration, ‘A’ is a DAF

(h)      A DAF is distinct from a charitable trust.

Feature DAF Charitable Trust
Legal ownership Assets belong to the donee Assets belong to the trust
Advisory rights Donor may recommend grants, but the donee has the final say Trustees exercise powers in accordance with the trust deed and applicable law
Legal control Donee retains ultimate legal control Trustees generally exercise fiduciary control over the trust property
Establishment and management Generally simpler to establish and administer Requires creation and administration of a separate trust
Administrative burden Relatively low for DAF, as the donee generally undertakes the administration and compliance Relatively higher, as the trust has its own administrative and compliance requirements
Costs Generally lower Generally higher

(i) The expression “Donor-Advised Fund” is principally associated with the U.S. charitable and tax system.

(j) Relevance for FCRA and Form FC-4

For the purposes of disclosure in Form FC-4, there are two views

View 1

A contribution may be regarded as having been received from a DAF where the donor is treated as a DAF for the donor country purposes. Hence, even if the donation to the Indian association does not satisfy the features of a donation from DAF as mentioned in para 8.2.2, it will be automatically regarded as a
donation by a DAF if the status of the donor is a DAF.

Under this view, the DAF will have to furnish to the donee the details of ultimate donors even if the donation from the DAF does not have the features corresponding to those received by it from those ultimate donors.

View 2

A contribution may be regarded as having been received from a DAF only where, based on the relevant facts and documentation, the contribution is treated as a DAF contribution for the donor country purposes. Under this view, whether a particular contribution constitutes a donation from a DAF is fact-specific and should be determined on the basis of the legal and contractual arrangements governing the contribution, the nature of the donor’s rights, and the terms and conditions attached to the donation, etc. Accordingly, each contribution should be examined on its own facts and documentation.

Conclusion

View 2 appears to be a better view.

(k) Disclosure in Form FC-4

Where there is any doubt regarding the appropriate classification, it would be prudent to make an appropriate disclosure in Form FC-4, explaining the reasons for exclusion of a particular donation.

8.3. Detailed activity report

A detailed activity report every year is required to be attached [Sr. No. 3(a)(i)]

The activity report has to be “detailed”. Further, the format of Sr. No. 3(a) appears to suggest that the report has to be project-wise, location-wise, amount-wise.

8.4.     Project wise details

8.4.1. Background

Hitherto, the details of individual project/activity were not required.

8.4.2. Text

The following details are now required:

Sl. Name of project/activity Address/location Amount utilized on
Project/activity Fresh assets Admin. Exp.
(1) (2) (3) (4) (5) (6)

[Sr. No. 3(a)]

8.4.3. Observations

(a) The details are required for each and every project as well as activity. For meaning of activity, please see para 6.3.2 in Part I of this article.

(b) The association will now have to maintain project/activity wise details of amounts utilised on fixed assets/admin expense. It must make sure that the project-wise admin figures add up exactly to the master figure in FC-4.

(c) The details are required only to the extent foreign contribution has been utilised for the said purposes.

8.5.1. On the basis of cumulative requirements the foreign contribution transactions (receipt and payment) require the following details:

  • donor/grant — ultimate donor for DAF/intermediary inflows;
  • State where money is spent;
  • project/activity mapped to a registered purpose;
  • expense head — programme, fresh assets, or admin and
  • expense head — programme, fresh assets, or admin and

8.5.2. The association may consider preparing and filing a reconciliation between FC-4 and Form 112 under the Income-tax Rules 2026, in consultation with the tax auditor.

8.6. Details of publications

8.6.1. The requirement in Form FC-4 is as follows:

“8A Details of publications brought out by the association;

(i) Whether the association or its key functionaries has brought out any publication during the year: Yes/No

(ii) If yes, details of the publications:

Date of publication Nature of mass communication (Book, magazine, newspaper article, etc.) Title Published in/on (Name of newspaper/website where it is hosted etc.) Brief description of the article
(1) (2) (3) (4) (5)

Note: As per section 3(1)(g), the association shall not engage in production or broadcast of any news or current affairs related matters through any mode of mass communication.

Thus, in essence, details of all publications brought out by the associations or its key functionaries are required to be disclosed.

8.6.2. The form does not ask for details of every communication made by the association or its key functionaries. It specifically asks for details of “publications” and, in describing the nature of mass communication, gives examples such as a book, magazine and newspaper article. It further requires the title of the publication and a brief description of the article. Hence, it could be argued that unless a publication is in the form of a book, magazine or newspaper, article, etc. it need not be covered in Form FC-4. To illustrate, a mere interview of a key functionary may not be regarded as a publication required to be disclosed in this table.

8.6.3. The publication should be brought out by the association or its key functionary. It appears that a book, magazine or newspaper published by a third party may still be regarded as brought out by the association, if it is authored by the association/key functionary.

The terms “publication”, “mass communication”, “published” and “article” have been defined in dictionaries as follows:

8.6.4. Publication

  • “publication” is, inter alia, “a published work”. [The Merriam-Webster Dictionary]
  • “publication” is a book, magazine, newspaper or document in which information or stories are published. [The Cambridge Dictionary]

Thus, in its ordinary sense, a publication generally connotes some identifiable work or material which is published. It does not necessarily extend to every communication made available to the public. The term is therefore wider than a printed book or newspaper, particularly in the digital age. A publication may, depending upon its nature, be made available electronically or on the internet. For example, if a key functionary writes a detailed article on a particular subject and gets it published in an online journal. The fact that it is hosted electronically would not prevent it from being regarded as a publication. At the same time, the mere fact that a communication is publicly accessible through social media or can potentially reach a large number of persons should not, by itself, make it a “publication” for purposes of item 8A.

8.6.5. Mass communication

  • Mass communication is communication directed to or reaching the mass of the people. [The Merriam-Webster Dictionary]
  • Mass communication is something such as television or the internet through which a message, story, etc., can be communicated to a large number of people at the same time. [Cambridge Dictionary]

Thus, “mass communication” is generally understood to mean communication directed to, or capable of reaching, a large number of people. However, the contents of the communication may not constitute a publication. This distinction is important. Social-media platforms are undoubtedly capable of mass communication. However, it does not follow that every post, photograph, video, announcement or other communication placed on a social-media platform is necessarily a “publication” required to be reported under item 8A.

8.6.6. Publish

  • Produced or released for distribution in a book, magazine, newspaper, etc. [https://www.merriam-webster.com/dictionary/publish]
  • to make information available to people, especially in a book, magazine, or newspaper, or to produce and sell a book, magazine, or newspaper; [https://dictionary.cambridge.org/dictionary/english/]

8.6.7. Article

  • a nonfictional prose composition usually forming an independent part of a publication (such as a magazine) wrote an article for the newspaper [https://www.merriam-webster.com/dictionary/]
  • a piece of writing on a particular subject in a newspaper or magazine, or on the internet: [https://dictionary.cambridge.org/dictionary/english/]
  • a piece of writing included with others in a newspaper, magazine, or other print or online publication. “an article about middle-aged executives” [https://www.google.com/]

Thus, an “article” ordinarily refers to a piece of writing dealing with a particular subject and forming an independent part of a publication. It is generally more substantial and structured than an ordinary communication or announcement.

8.6.8. Social-media posts

The terminology ordinarily used by the principal social-media platforms also supports the distinction between a general social-media communication and an article. For example:

Platform Ordinary terminology
X (formerly Twitter) Post (formerly commonly called a Tweet)
Instagram Post; Reel; Story
LinkedIn Post; Article; Newsletter

Therefore, an ordinary post on X, Instagram or LinkedIn is not ordinarily described as an “article” merely because it is publicly accessible. For example, the following would not ordinarily be regarded as publications/articles:

  • a photograph of an event;
  • an announcement regarding an event;
  • a congratulatory message;
  • a short brief update regarding the activities of the association;’
  • an Instagram Story;
  • an Instagram Reel;
  • a short X/LinkedIn post;
  • a link or notice shared on social media.

Accordingly, the medium of publication is not determinative. The nature and substance of the material are more relevant.

8.6.9. Further, section 3(1)(g) reads as follows:

association or company engaged in the production or broadcast of audio news or audio visual news or current affairs programmes through any electronic mode, or any other electronic form as defined in clause (r) of sub-section (1) of section 2 of the Information Technology Act, 2000 (21 of 2000) or any other mode of mass communication;

It is also referred to in Note to Item 8A. This, gives an impression that the publication should be relating to audio news, or audio visual news or current affairs programmes.

8.6.10. Conclusion

For practical purposes, an association may therefore adopt the following approach:

Ordinary social-media communications such as routine posts, photographs, event announcements, short updates, reels and stories may ordinarily not be treated as publications/articles for purposes of item 8A. Substantive articles, reports or other identifiable published works disseminated through a website or social-media platform should, however, be examined separately and may require disclosure.

In case of ambiguity, appropriate disclosure may be made in Form FC-4.

8.7. UDIN of the auditor’s certificate

Unique Document Identification Number (UDIN) is 18-Digits system generated unique number for every document certified/attested by a full time practicing chartered accountants (CA). Now, it is mandated as per format of FC-4 that UDIN of both the auditor’s certificate and FC-specific financial statements is specified.

9. Summary

Significant changes have thus been made in the Rules. While the authors have taken the liberty to express their views, it will be prudent for the association to periodically check the MHA portal and ascertain whether the authors’ views are in conformity with the views if any expressed by MHA. In an appropriate case the association may have to alter its position.

From The President

JUDGEMENT IN A CHANGING PROFESSION

October is one of those months when the intensity of professional life becomes particularly visible. tax compliances, audit planning, quarterly closures, client expectations and regulatory developments converge, leaving little room for error or superficial judgement.

World Mental Health Day on 10 October is also relevant to the CA profession. In a profession where deadlines, client expectations and long working hours are part of everyday practice, mental well-being is closely linked to professional judgement and quality of work. Firms that encourage realistic workloads, effective delegation and adequate review time are not merely supporting employee well-being; they are strengthening professional quality.

READING BETWEEN THE TAX NUMBERS

The latest tax numbers provide the backdrop. As of September 17, 2026, net direct-tax collections stood at ₹12.1 lakh crore, up 13% year-on-year. Advance-tax collections rose 16.18% to ₹5.22 lakh crore, while corporate advance tax increased 18.09% to ₹4.16 lakh crore. Securities Transaction Tax collections rose sharply by 52.9% to ₹42,000 crore.

These are more than collection statistics; they reflect the continuing formalisation and digitisation of India’s economy, stronger compliance and growing economic activity.

For Chartered Accountants, the important question is what these numbers tell us about our changing profession.

Beyond the Numbers

FROM COMPLIANCE TO INTERPRETATION

A growing tax base and sophisticated information systems are changing expectations from professionals.

The CA’s value can no longer be defined merely by preparing financial statements, calculating tax or completing compliance requirements. Increasingly, stakeholders expect us to interpret information, identify risks, challenge assumptions and provide judgement.

The 18.09% growth in corporate advance tax invites deeper questions: what is driving corporate profitability, are earnings sustainable, do cash flows support reported performance, and what risks could emerge in the coming quarters?

The sharp increase in STT reflects the scale and dynamism of India’s capital markets, creating opportunities while demanding stronger understanding of transactions, taxation, governance and risk.

CORPORATE ACCOUNTABILITY AND AUDIT

The debate around the Corporate Laws (Amendment) Bill brings the question of professional judgement into sharper focus. The proposed exemption from mandatory audit for prescribed classes of private companies raises an important issue: how do we balance ease of doing business with corporate accountability?

There is a legitimate case for proportionality, as companies differ in size, ownership and stakeholder significance. But the discussion should not be reduced to whether an audit is “necessary” or “unnecessary”. The relevant question is what purpose independent assurance serves, and where it creates value.

The profession should engage with regulatory reform, supporting proportionate regulation while articulating where independent assurance contributes to transparency and accountability. Our credibility will depend on showing that our position rests on evidence and public interest, not self-interest.

DIALOGUE WITH REGULATORS MATTERS

BCAS continues to strengthen its institutional engagement with regulators. During the month, along with CA Chirag Doshi, Chairman of the 4i Committee, and CA Himanshu Kishnadwala, Past President, BCAS, I met senior officials of the Serious Fraud Investigation Office, including Mr Love Kumar, Additional Director, and Ms Sawni Dikshit, Joint Director, and also met Mr Nitin Gupta, Chairperson, National Financial Reporting Authority.

Such interactions matter because the relationship between the profession and regulators should extend beyond compliance and inspection. Constructive dialogue helps regulators understand the practical consequences of regulatory requirements while enabling the profession to appreciate their objectives. Good regulation should not merely impose obligations; it should also create clarity, consistency and accountability.

DIGITAL EVIDENCE AND FINANCIAL INTEGRITY

The growing sophistication of money laundering, financial fraud and cross-border financial crime makes financial transparency important. The 18th BRICS Summit in New Delhi, with its focus on illicit financial flows and terrorist financing, highlights the need for stronger cross-border information sharing. For Chartered Accountants, this reinforces the importance of AML and KYC discipline, transaction scrutiny and the integrity of financial information.

The Bankers’ Books Evidence Act, 2026, replacing an 1891-era law, reflects the shift of financial records to electronic, digital and cloud-based environments. For Chartered Accountants, this is more than a legal development; it reinforces an important professional principle, that financial information must be traceable, reliable and capable of standing up to scrutiny. As records move across cloud platforms and automated systems, documentation, access controls and audit trails become integral to professional work.

Tomorrow’s professional must understand not only what a number says but also where it came from, how it was generated and whether it can be trusted.

AI: MORE EFFICIENCY, GREATER RESPONSIBILITY

Artificial intelligence is changing how professional work is performed, assisting with research, reconciliations, document review and data analysis. But an AI-generated output is not audit evidence merely because it appears plausible.

Professionals must understand the source data, limitations of the tool, parameters applied and procedures required to validate the output, and firms will need clear protocols covering confidentiality, documentation and accountability.

As routine procedures become automated, professional scepticism becomes more important, not less. The future CA may perform fewer repetitive procedures but will be expected to exercise greater judgement over the reliability of automated outputs.

THE PROFESSION AHEAD

I believe the profession must focus on three priorities.

First, protect the quality of professional judgement. Workload pressures must not compromise review, delegation or professional scepticism. Firms need an environment where professionals have time to think, not merely to finish.

Second, adopt technology without outsourcing accountability. AI and automation should make professional work smarter and deeper, never a substitute for responsibility.

Third, engage with regulatory reform, supporting simplification where it improves the business environment while articulating, with evidence, where assurance and accountability remain essential.

India’s tax numbers demonstrate the scale of economic formalisation, digital regulation is reshaping financial information, and AI is changing professional work. Yet one principle remains constant: the value of a Chartered Accountant does not lie in producing an answer; it lies in standing behind that answer.

Our challenge is not to handle more data, technology or regulation, but to ensure that, amid this change, we continue to bring what no system can fully automate: independent judgement, professional scepticism and the courage to ask the right question.

That is where the future value of our profession will be built.

CA. Kinjal Shah

President, BCAS

What Is A CA Firm Really Worth?

As Indian businesses expand globally, regulatory complexity increases and clients increasingly seek integrated, technology-enabled and multidisciplinary professional services, the traditional model of the small, partner-centric practice is being challenged. There is consequently a growing conversation and market need for mergers, consolidation and the creation of firms of scale, width and depth. The aspiration is not merely to create larger CA firms in terms of headcount or fee income. It is to build Indian professional institutions with the depth, geographical reach, specialist capabilities and institutional resilience to serve businesses of increasing size and complexity.

But mergers require something that the profession has historically not needed to discuss with the same intensity: valuation. A Chartered Accountant may spend decades building a practice. Clients are acquired, relationships deepen, people are trained, systems are established and a reputation is painstakingly built. Yet when the time comes to admit a new partner, merge with another firm, induct the next generation or plan succession, one deceptively simple question arises:

Beyond the Partner

WHAT IS THE FIRM ACTUALLY WORTH?

The question is more difficult than it appears.

In a conventional business, valuation can draw upon tangible assets, profits, cash flows, intellectual property and market comparables. A professional services firm is different. Much of what makes it valuable does not appear on its balance sheet. The office may be worth relatively little. Computers and furniture are hardly significant. Even the firm’s accumulated knowledge cannot simply be transferred to a buyer.

What is being valued, therefore, is largely the capacity to generate future professional income.

And that capacity has several components: client relationships, recurring assignments, brand and reputation, referral networks, systems and processes, quality of personnel, specialised expertise and, perhaps most importantly, the confidence that clients will continue to choose the firm even when the partner who originally brought them in is no longer there.

In 2025, Baker Tilly and Moss Adams agreed to merge in a transaction valued at approximately US$7 billion, creating the sixth-largest accounting firm in the United States1. Considering that the two firms together had around US$3 billion of revenue in 2024, it is evident that investors are not simply buying today’s fee income; value is also attached to recurring revenue, client relationships, people, capabilities, technology, brand and the potential to create additional value through scale.


1 http://www.reuters.com/markets/deals/baker-tilly-moss-adams-set-merge-7-billion-deal-wsj-reports-2025-04-21/

But the uncertain future presents a central paradox of professional-firm valuation: the asset that generates the revenue may be inseparable from the individual who generates it.

Therefore, the quest towards valuation should not begin by asking “What multiple of fees should my firm command?” but by asking “How much of my firm’s future earning capacity would survive if I were no longer there?”

That question brings valuation closer to the economic reality of professional services. A practical valuation can examine three questions:

First, what are the maintainable earnings? Historical profits need to be normalised for exceptional items, partner remuneration and one-off assignments. The objective is to establish the earnings that a successor could reasonably expect to maintain.

Second, how transferable is that income? Recurring statutory audits, tax retainers and established institutional assignments may have greater continuity than one-off advisory mandates. Revenue can be classified as institutionally owned, partner-dependent, repeatable or highly personal. The more revenue survives a change in personnel, the stronger the case for attributing value to the firm.

Third, what risks attach to those earnings? Client concentration, dependence on a few partners or referral sources, staff attrition, succession gaps, regulatory constraints and professional liabilities should influence the valuation.

A simplified framework could therefore be expressed as:

Enterprise Value = Maintainable Earnings × Appropriate Multiple ± Specific Adjustments

The multiple should not simply be borrowed from another firm’s transaction. It should reflect growth, recurring revenue, client retention, institutionalisation, profitability, succession depth and risk.

Maintainable earnings is a variable of the extent of institutionalisation. Documentation, technology, delegation, second-line leadership, client diversification, knowledge management and institutional branding may sometimes appear to be overheads. In reality, they are investments in the firm’s transferable economic value.

The ultimate test of scale is therefore not how many partners a firm has or how many crores it bills. It is whether the institution has acquired an economic life of its own and whether that value can outlast its individual partners.

Scale may create the opportunity. But institutionalisation is what creates value.

CA. Sunil Gabhawalla

Editor

कोSर्थवान् को दरिद्र: ! (Who Is Rich And Who Is Poor?)

This is a great message to the mankind, taken from Bartruhari’s Vairagya Shatak. Interestingly, Bhartruhari, was originally a King of Ujjain. He is believed to have lived in 5th century. He renounced everything to become a Sanyasi. His wife’s name was Pingala.

It is also believed that he is the same person who is known as Bartarinath in the Nath Pantha (Nath Sect).

He wrote three collections of verses (shlokas) viz Neeti Shatak (ethical conduct), Shringar Shatak (pertaining to romance) and Vairagya Shatak (relating to Renunciation).  All the three give great messages of wisdom and are worth studying.

The Paradox of Wealth

The text of the present shloka is: –

वयमिह परितुष्टा वल्कलैस्त्वम् दुकूलै –  We are happy in our simple clothes. You are Happy in your rich attire.

सम इव परितोषो निर्विशेषो विशेष 😐 – But the degree of our happiness is the same. There is no difference.

स तु भवतु दरिद्रो यस्य तृष्णा विशाला –  He is truly a poor person whose greed or thirst is not satiated

मनसि च परितुष्टे कोSर्थवान् को दरिद्र:|| – If both of us are happy, then who is rich and who is poor?

A poor or low profile person tells a king –

We are contented in our simple and coarse attire and you are happy in your very rich and silky dress. Your dress is luxurious. But there is no difference between the happiness of two of us. Both of us are satisfied at our respective places. In reality, he whose greed is not satiated will always remain poor.

We observe this scenario every day in our lives. Even in the vegetable market, rich people usually bargain more for petty things. Rich countries keep on fighting for more wealth. On the other hand, a country like Bhutan, which is not known for its material wealth properties has the highest happiness index. People have passion or craze to acquire and collect valuable items, dresses, furniture, antiques, show pieces, jewellery, diamonds, articles like studded watches, cars and what not! Desire still continues to acquire get something more!

Sometimes, a peon or lower level employee is happier than the owner or highly placed people. This does not imply or mean that we should be complacent. For progress, we must aspire or strive for more, better quality things. At the same time, we should be detached. This message is common in almost all philosophies of the world. All religions preach the same thing. Reduce the needs, reduce the attachment. That is the surest way of getting peace of mind. Greed always causes unrest. That unrest creates stress. It leads to health issues and mental disorders.

Unfortunately, many of the CA professionals compromise on all ethics to become super rich instantly. They continuously resort to undesirable or more things to have more and more wealth, recognition and positions.

They are never happy and contented, whereas a wise person, without much wealth is more contented and happy.

Let us aspire to make our country or society richer than pursue our ambition for personal wealth.

Society News

LEARNING EVENTS AT BCAS

1. Lecture Meeting on Insights into the Current State of the Indian Economy held on Wednesday, 12th August 2026 @ Virtual | Speaker: Dr. Rumki Majumdar

The session provided an overview of the current Indian economic landscape, highlighting key growth drivers, inflation trends, and investment activity. It examined the impact of global economic developments, geopolitical uncertainties, and trade dynamics on India’s growth prospects.

The discussion also covered the role of policy reforms in supporting economic resilience and long term development. Participants gained insights into emerging economic trends and their implications for businesses and professionals. The session emphasized the importance of monitoring macroeconomic indicators and adapting strategies to a changing environment.

An interactive Q&A further enhanced understanding of India’s economic outlook and future opportunities.

Click to watch online on YouTube

2. Webinar on Maharashtra Co-operative Housing Societies Act, 1960 and Rules, 1961 – Recent Updates held on Saturday, 8th August, 2026 @ Virtual |Speaker: CA Ramesh Prabhu.

The Bombay Chartered Accountants’ Society (BCAS), jointly with The Chamber of Tax Consultants (CTC), organised a virtual session on “Maharashtra Co-operative Housing Societies Act, 1960 & Rules, 1961 – Recent Updates” on Saturday, 8th August 2026. The webinar received an enthusiastic response with 620 registrations.

CA Ramesh Prabhu provided an insightful and practical overview of Chapter XIII-B of the Maharashtra Co-operative Housing Societies (MCS) Act, 1960 and the recently introduced Chapter XI-B of the MCS Rules, 1961. The discussion covered the registration of housing societies, key definitions and different categories of membership, admission of members, associate/joint and provisional membership. The speaker also dealt with the provisions relating to transfer of shares, rights and interest in flats, payment of society dues, nomination, succession and transfer pursuant to family arrangements.  Attention was also given to the rights and obligations of members and managing committees, including access to society records, committee disqualifications, and voting rights. The speaker further discussed the management of housing societies under the new Rules, including the functioning of the General Body and Managing Committee. Recent judicial developments and practical issues arising under the housing society framework were discussed enabling participants to better understand the application of the statutory provisions. The session was followed by an engaging Question & Answer segment, wherein the Speaker provided clarifications on the queries raised by the participants.

The webinar concluded on a highly informative note, with participants appreciating the quality of the practical insights shared during the session.

Click to watch online on YouTube

3. Webinar on Income Tax Returns for AY 2026 – 27 held on Thursday, 6th August 2026 @ Virtual | Speaker: CA Ronak Rambhia.

The Direct Tax committee of BCAS had organised a webinar on the Income Tax Returns for AY 2026-27 in virtual mode on Thursday, 6th August, 2026. The webinar was organised to address the changes in the Income Tax Returns and how to be ready for the incoming tax filing season.

CA Ronak Rambhia opened with a detailed explanation of section 139 of the Income Tax Act, 1961 as to the persons applicable to file the Income Tax Returns and under what conditions one in mandatorily required to file an Income Tax Return. He then walked through each return as to which return is applicable to which type of assessee. He covered the applicability from ITR-1 to ITR-7 in detail, and some practical points were explained in detail like in case of partners of a firm, private trust, etc.

He meticulously outlined the pre-requisites for each type of assessee and their specified return so that the professionals would know as to what should be asked from their clients while starting to prepare the Income Tax Returns and what details are required to be mentioned in what schedules. The schedules of all the Income Tax Returns were explained in detail. The reporting of the Future & Option (F&O) income and the intraday trading business schedules was explained through various examples.

He also highlighted key validation points between the reporting in the Tax Audit report and the Income Tax Return, to help avoid mismatches that could trigger adjustments in the intimation under Section 143(1)(a) of the Income Tax Act, 1961.

Lastly, he gave some practical insights on the problems faced while choosing the due date for private trust, disclosing income under Business income or other sources income and he ended with a final checklist from login to the portal to e-verification process.

The webinar offered a comprehensive and practice-oriented walkthrough of the Income Tax Returns for AY 2026-27.

Click to watch online on YouTube

4. Indirect Tax Laws Study Circle Meeting on GST Implications of Business Restructuring, Liquidation & Closure held on Tuesday, 21st July 2026 @ Virtual | Speaker: CA Raj Khona (Group Leader) & CA K. Shivarajan (Group Mentor).

  • The discussion deliberated on business swaps between sole proprietorships, emphasizing the taxability exemptions under Notification No. 12/2017-CT(R) and ITC transfer mechanisms via Form GST ITC-02.
  • Key insights were shared regarding internal division transfers across distinct GSTINs under the same PAN, highlighting the applicability of Schedule I deemed supplies and valuation under Rule 28.
  • The interplay between Section 59 of the IBC and GST recovery proceedings was examined, confirming the extinction of claims post-dissolution while assessing director liabilities under Section 89 of the CGST Act.
  • Participants reviewed partnership-to-LLP conversions, confirming statutory vesting benefits, ITC transfers under Section 18(3), and the continuation of export licenses/incentives.
  • The session addressed business closures under Section 29(5), contrasting mandatory stock/machinery reversals against the non-reversibility of immovable property.

The study circle session witnessed active participation with around 163 members logging in and engaging in healthy and high-quality technical discussions.

BCAS OUTREACH & ENGAGEMENTS

1. INC 5 session

The Fifth session of the United Nations Intergovernmental Negotiating Committee on the Framework Convention was held at the UN headquarters in New York from August 3 to 13, 2026.

In addition to the government representatives actually negotiating the documents, the UN also allows other stakeholders such as civil society, academia, and the private sector to attend these sessions and make contributions. Bombay Chartered Accountants Society is one such approved stakeholder.

The current work of the intergovernmental negotiating committee (INC) includes three workstreams:

  1. UN Framework Convention on International Tax Cooperation
  2. Protocol on Taxation of Income from Cross-Border Services
  3. Protocol on Prevention and Resolution of Tax Disputes

At the August 2026 session, for the first time, draft documents for all three workstreams were presented and discussed. The key elements of these documents are briefly summarised.

The Framework Convention is like an umbrella agreement, a multilateral instrument, which can have one or more Protocols. Each Protocol generally deals with a specific issue.

In addition to UN STTR provision, the Protocol on services contains various articles dealing with cross-border services recently included in the UN Model i.e. Article 12AA dealing with “fees for services”, Article 12B dealing with “automated digital services” and Article 12C dealing with “insurance premiums”. These provisions give taxing rights to the source countries even when the service provider does not have a permanent establishment in the source country.

The Protocol on disputes contains innovative dispute prevention mechanisms and dispute prevention mechanisms such as bilateral and multilateral advance rulings on issues not related to transfer pricing, APAs, Coordinated advance pricing arrangements, Cooperative compliance arrangements, Simultaneous tax audits, Joint audits etc.

CA Radhakishan Rawal made various interventions during the discussions. The inputs were predominantly on technical issues arising from drafting of various issues, certain desired policy outcomes and approaches to enhance participation by the countries.

Media Links:

2. Meeting with SEBI Chairman

A delegation of BCAS – Bombay Chartered Accountants’ Society, led by CA Kinjal Shah, President, and CA Mandar Telang, Vice President, CA (Adv.) Kinjal Bhuta, Joint Secretary, CA Samit Saraf, Joint Secretary and CA Mrinal Mehta, Treasurer along with former BCAS presidents CA Shariq Contractor and CA Chirag Doshi met Mr. Tuhin Kanta Pandey, Chairman of SEBI on 7th August 2026 at SEBI Bhavan, BKC Mumbai.

The delegation briefed Mr. Pandey on the key initiatives and activities of BCAS and discussed potential areas of future collaboration between BCAS and SEBI. As REACH is one of the main pillars of BCAS – the step in this direction, is aimed to be a long-term and mutually beneficial professional association with SEBI.

3. BCAS President Meets R.A. Podar College Vice-Principal to Explore Academic-Professional Collaboration

A meeting between Dr. (CA) Vibha Singh, Vice-Principal of R.A. Podar College of Commerce & Economics, and CA Kinjal Shah, President, BCAS, was held at the BCAS office on 6th August 2026.

They discussed on the possibility of having a meaningful academic and professional association, with the objective of providing students and faculty with greater exposure to the Chartered Accountancy profession, emerging areas of finance, and practical industry knowledge.

Overall, the proposed collaboration can create a sustained platform for knowledge exchange, skill development and professional orientation, benefiting students, faculty and the broader academic community.

4. Churchgate CPE Study Circle Felicitates BCAS President

The President of the Bombay Chartered Accountants’ Society (BCAS) was felicitated by the Churchgate CPE Study Circle of WIRC of ICAI in a ceremony held at Jolly Bhavan No.2, New Marine lines, Churchgate, Mumbai; on 6th August 2026 recognising his contributions to the accounting profession.

The event was attended by members of BCAS, senior Chartered Accountants, students, and members of the Churchgate CPE Study Circle of WIRC of ICAI.

The President emphasised on the forthcoming seminars of BCAS and need for continuous learning.

Churchgate CPE Study Circle, Coordinator, CA Dilip Jani presented a memento to the President, acknowledging his leadership and support for local chapter activities.

5. Borivali (Central) CPE Study Circle Felicitates BCAS President

The President of the Bombay Chartered Accountants’ Society (BCAS) was felicitated by the Borivali (Central) CPE Study Circle in a ceremony held in Borivali on 11th July 2026, recognising his contributions to the accounting profession and to member engagement across the region.

The event was attended by members of BCAS, senior Chartered Accountants, students, and convenors of the Borivali (Central) CPE Study Circle.

The BCAS President emphasised the need to focus on joint programmes and collaborative initiatives with other professional bodies and associations, fostering greater knowledge-sharing and engagement among members.

III. REPRESENTATION

BCAS Submits Representation to the OECD

The Bombay Chartered Accountants’ Society (BCAS), through its International Taxation Committee, submitted a representation to the OECD Centre for Tax Policy and Administration on 22 July 2026 on the proposed revisions to Chapter VII of the OECD Transfer Pricing Guidelines relating to intra-group services.

The representation, submitted under the leadership of CA Kinjal Shah, President, BCAS, CA Mayur Nayak, Chairman, and CA Anil Doshi, Co-Chairman, International Taxation Committee, provides practical suggestions to improve clarity and consistency in the proposed guidance.

BCAS recommended clearer definitions for subjective terms, better guidance on distinguishing shareholder activities from chargeable services, practical allocation keys for common intra-group services, and dedicated guidance on stock-based compensation. The Society also highlighted the growing impact of Artificial Intelligence (AI) on service delivery and suggested that future guidance may be required in this area.

The representation further recommended reviewing the mark-up for low value-adding services, defining core and support services, and providing a practical documentation framework to reduce disputes and improve compliance.

This representation reflects BCAS’s continued commitment to contributing to the development of practical and internationally accepted transfer pricing principles while representing the views of the profession on global tax policy.

Click to Read the Full Representation

IV. BCAS IN NEWS & MEDIA

BCAS LinkedIn Live: Taking Professional Learning Digital

The Bombay Chartered Accountants’ Society (BCAS) introduced BCAS LinkedIn Live, a digital initiative aimed at making professional learning more accessible, engaging and widely connected. The initiative was launched with a webinar on “Income Tax Returns for AY 2026–27,” enabling professionals to participate in a technical knowledge session directly through LinkedIn. With a growing community of 24,000+ followers on LinkedIn, BCAS leveraged the platform to expand the reach of its professional knowledge initiatives. The first LinkedIn Live webinar received 700+ views, demonstrating strong audience interest and the potential of LinkedIn Live to further extend BCAS’s digital learning outreach.

Key Benefits:

Provides convenient access to BCAS technical sessions and webinars through LinkedIn.

Enables professionals to participate in knowledge-sharing programmes remotely.

Facilitates access to expert insights and technical updates through a digital platform.

Expands the reach of BCAS’s professional education initiatives.

BCAS continues to expand its digital outreach through the BCAS Website, BCAS Academy and YouTube, now further strengthened by LinkedIn Live Streaming.

Click to watch online at LinkedIn Live Streaming

BCAS News

BCAS has been featured in several news and media platforms, showing our active involvement, professional contributions, and commitment to the field. This reflects the growing recognition of BCAS in the public and professional space.

Link: https://bcasonline.org/bcas-in-news/

Yes. I am Independent!

  •  What did you say? ‘Independent’ is a myth? I don’t agree. I am independent. I always work without fear or favour.
  •  What? Mr. Mallya wants me sign his balance sheet urgently – as it is?

No. Never! Tell him, your accounts are full of blunders. I can’t sign them. I am independent. No fear, no favour.

What does he say? I have been saying this last few years; but signing them every year?

So what? This time I won’t tolerate any non-sense.

No; but wait a minute He will change the auditor and my errors will be exposed!

And I need urgent money to pay my son’s fees to be paid in USA. Okay, Okay. I will sign this year but warn him that next year

  •  Who has come? Some boys and girls have come for articleship?

Don’t entertain them. They are useless and over smart. They will interview me and ask questions on stipend, leave and so on.

But I cannot afford to let them go. I need assistants at low cost. I can’t afford graduate employees. Next year, I won’t take any article.

  • Hello! Did you meet the officer? Hearing is over? What, he is asking for something?

Tell him, we won’t pay a single penny. We should not encourage corruption.

Hello, Hold on. This client’s records are not clear. It will cost us heavily. And that officer is vindictive. Our many other matters are with him Tell him, OK we will do his work. But ask him to be reasonable.

  • What? That article wants us to write lesser number of days leave in his termination form? Tell him, I will never do such things. He has to behave. He is arrogant, irresponsible and not at all sincere. We can’t break ICAI rules. He deserves to be punished.

But wait!  He is the son of our valuable client.  We get many assignments through him.  Okay.  We will better get rid of him   But tell others, they should not quote it as a precedent!

  • Hello. Pareshbhai – bolo bolo.

Full day seminar of study circle? How much – 5000? It’s too much. Very difficult. So much work is pending. Anyway, I will join. As it is my CPE hours are short. But I won’t be able to sit there whole day. You will have to adjust it. I will send my man to attend and I will come only for signing.

  • Arey, Mohanbhai, welcome. You have brought 17 balance sheets of housing societies? Mohanbhai, you are expecting too much. How can I sign all these without verifying? You have seen is alright. But I am independent and need to check it thoroughly.
  • What do you say? You have brought fee in cash?

Anyway. You have been my friend for long. I trust you. But next year, be careful. Don’t bring at 11th hour like this.

  • Oh, Mr. Patel, 8 new audits?

How can I take them at this point of time? Only 4 days left for ITR filing. I have to do so many things. Procedure for appointment, writing to previous auditors? No no Sir. I am sorry. Not possible for me.

  • What? Fees are good and will be paid in advance? And you will manage all formalities! But still difficult.

Anyway. Considering our relations, I am obliging. But remember, I am otherwise independent. I work without any fear or favour.

  • Yes, Vijay. What do you want? Increment? How can you expect it? You take so much leave, commit mistakes, there are many complaints against you.

But hold, you are that officer’s nephew, na? I will increase your salaries. But remember, this is the last time. You know, I work without fear or favour.

  • What? Sweeper wants further loan? She already owes us more than 50000/-. How can we keep on giving like this?

Thik hai. Give her 5000/- but she should return it early. Now-a-days, it is difficult to get peons and sweepers.

  • What? Phone from my home? She wants me to come for a movie? Tell her, I have no time. Too much pressure of work. Can’t take her call.

Sarika. Connect to my wife again. Last time I refused like this and suffered very much.

Hello Darling.  When should I reach home?

After all, I am independent. I work without fear or favour!

Regulatory Referencer

I. DIRECT TAX : SPOTLIGHT

  1.  The Income-tax (Third Amendment) Rules, 2026 – Amendment to Rule 332

The amended Rule applies to any search initiated under section 247 or requisition made under section 248 of the Income tax Act, 2025 on or after 1 April 2026. Form ITR -BN (Income tax return for Block Assessment) is inserted – Notification No. 97 of 2026 dated 24 July 2026.

2.  CBDT has notified Foreign Assets of Small Taxpayers- Disclosure Scheme Rules, 2026 and has also released FAQ – Notification No. 114 of 2026 dated 14 August 2026.

II. FEMA

1. RBI releases draft rules for rationalization of Foreign Exchange Management (Non-debt Instruments) Rules, 2019

RBI has released the draft Foreign Exchange Management (Foreign Investment) Rules, 2026 to replace and rationalise the existing NDI Rules, 2019. The draft aims to simplify the regulatory framework, harmonise definitions, align FEMA provisions with the FDI Policy, reduce compliance burden and provide greater operational flexibility through a principle-based, investor-neutral and investee-neutral approach. The Rules are currently in draft form and will be finalised after public consultation. Comments on the draft Rules can be submitted by 31st August 2026.

(Press Release No. 2026-2027/726, dated 21st July 2026)

2. RBI excludes eligible FCNR(B) and NRE-backed advances from ANBC for PSL target calculation

RBI, vide circular dated June 8, 2026 on ‘Swap Facility for FCNR (B) Deposits’, introduced a US Dollar-Rupee swap facility for fresh FCNR (B) dollar funds. This has already been covered in our earlier regulatory updates.

RBI has amended the PSL Directions to exclude advances backed by eligible fresh FCNR(B) deposits (3–5 years) and NRE term deposits (3 years or more) mobilised during the specified period from Adjusted Net Bank Credit (ANBC) for calculating banks’ priority-sector lending targets, thereby incentivising banks to mobilise such foreign currency and NRE deposits.

(Circular No. FIDD.CO.PSD BC.NO.08/04.09.001/ 2026-27, dated 7th August 2026)

3. RBI curtails FCNR(B) swap facility for deposits mobilized to 31st August 2026

Based on the encouraging response to the Swap Facility for FCNR(B) deposits mentioned above and the resultant forex inflows, it has been decided that the Swap facility for FCNR(B) deposits will be available only for deposits mobilized till 31st August 2026 as against the earlier date of 30th September 2026. The Swaps under this facility, i.e., FCNR(B) deposits, may be availed with RBI till September 11, 2026. The Scheme for ECBs and OFCBs will continue to be open till December 31, 2026.

(Press release No. 2026-2027/900, dated 14th August 2026)

Tech Mantra

Netlens

Netlens

NetLens turns your phone into a handheld Wifi survey instrument. Walk around your apartment, your office or your warehouse – and watch a real-time signal heatmap form beneath your steps.

There are three ways to map:

– Heatmap survey: Hold the phone in front of you and walk. The rear camera provides visual-inertial tracking, so every Wifi scan is anchored in 3D using the phone’s own motion. No floor plan to upload, no account, no markers on the walls. The map fills in along the path you walk.

– Quick Scan: A live AR mode for a fast overview. Wifi readings appear directly in your camera view as you move, with no setup and nothing to save.

– Floorplan: No camera required. Import a floor plan, sketch, or screenshot of your space, then walk and tap to drop readings and build a heatmap manually.

WHAT YOU GET

– A Live heatmap that grows as you move, color-graded from weak to excellent signal

– Filter the map to a single access point, or a specific band (2.4 / 5 / 6 GHz)

– Adjustable map layers: heatmap, walk path, photos, and an underlaid floor plan that you can fade to align with real rooms

– Color palettes, including a colorblind-friendly option

– Photo markers placed on the map and carried into the PDF

– Export a clean PDF report, a PNG image, or raw CSV samples
– Group scans into projects and export an entire whole multi-floor building as one combined PDF

– Extra live tools: Signal Meter, Channel Graph, AP Browser, Connection, and a Speed Test with saved history

A very efficient way to map your WiFi coverage and take corrective action at the weak spots.

Android : https://tinyurl.com/netlensapp

Toxly : ingredient scanner

Toxly

Toxly is your AI-Powered Ingredient Safety Guide. It helps you identify what is really inside the products you use every day. Most ingredient labels are designed to be confusing, hiding harmful chemicals, allergens, and toxins behind complex names.

Toxly changes all that. It empowers you to make healthier, more intentional choices for yourself and your family. Using advanced AI and real-time scanning, Toxly decodes complex labels instantly, identifying potential risks so you don’t have to. Whether you are grocery shopping, buying skincare, or checking household cleaners, Toxly provides the transparency you deserve.

Simply point your camera at any ingredient list on the packaging. Powerful OCR (Optical Character Recognition) and AI analysis decode the text in seconds, identifying harmful toxins, endocrine disruptors, and irritants. Get a clear, color-coded breakdown of every ingredient. Components are categorized from “Safe” to “High Risk,” explaining why an ingredient might be harmful based on the latest scientific research. Toxly thus helps you avoid “greenwashing” by revealing the truth behind marketing claims like “natural” or “pure.”

Toxly is optimized for speed. Whether you’re in a crowded supermarket or a store with poor reception, Toxly’s core scanning technology works quickly to give you answers when you need them most.
Toxly is perfect for

  •  Parents: Check your baby’s lotions and food products for ingredients you may wish to avoid.
  •  Skincare Enthusiasts: Identify ingredients such as silicones, parabens, and sulfates that may cause irritation or breakouts for some users.
  •  Health-Conscious Shoppers: Track and avoid artificial dyes, preservatives, and hidden toxins.
  •  Allergy Sufferers: Quickly identify potential triggers in long, complex ingredients lists.

The base version is free, while the Premium version gives unlimited ad-free analyses. Together, we can push for a future where every product is safe for everyone.

Scan with intention. Live with clarity. Download Toxly today.

Android : https://tinyurl.com/toxly

Battery Supervisor

Battery Supervisor

Battery Supervisor helps you better understand how your smartphone battery behaves. It does not just show percentage, voltage and temperature: it collects data over time and organizes it into charts, checks and easy-to-read diagnostics.

With Battery Supervisor you can monitor:

  •  Battery level, voltage and temperature;
  •  Charging and discharging trends;
  •  Estimated app consumption, if you allow usage access;
  •  Abnormal battery drain and screen-off consumption;
  •  Possible charger or cable issues;
  •  Charging sessions;
  •  Battery health estimation through the SOH Wizard.

The main feature is the battery diagnostic report: With one tap, you can get an organized overview highlighting the factors that may have affected battery consumption the most, such as screen, Wi-Fi, mobile data, Bluetooth, GPS, foreground apps, temperature and standby behaviour.

The app also includes historical charts that allows you to observe battery behaviour over time and identify unusual patterns.

Battery Supervisor is designed to be simple and practical: It is useful both for users who simply want better battery control and for those who want to analyze consumption, charging sessions and possible anomalies in greater detail.

The analyses are estimates based on the data available from the Android system and may vary depending on the device, Android version and permissions granted. They do not replace professional measuring tools, but they help you better interpret everyday battery behaviour.

Android : https://tinyurl.com/battsupervisor

Keymate: PC Apps from Phone

Keymate PC Apps from Phone

Keymate is a control pad app that lets you run PC tasks quickly from your phone. Install the Keymate desktop app on your Mac or Windows PC, then connect it to your phone over the same Wi-Fi. Once set up, a tap on your phone can instantly run your favourite shortcuts, type text, launch apps, open URLs and even control media. You can also reduce repetitive tasks on your PC to a single button press.

Key Features

– Run Shortcuts: Trigger your favourite keyboard shortcuts with a single tap.
– Text Input: Save phrases you type frequently and paste them instantly.
– Launch Apps & URLs: Open your go-to apps or websites directly from your phone.
– Media Control: Play/pause, skip tracks, adjust volume, mute, and change screen brightness from your phone.

Keymate is built for anyone who wants to speed up repetitive PC tasks, such as development, design, writing, video editing, music listening, streaming, and presentations.

The Keymate desktop app for Mac or Windows is required.

Android : https://tinyurl.com/keymate

The Taxpayer’s Long Wait For An Order Giving Effect

While winning an appeal on merits should ideally resolve a taxpayer’s issues, in practice, it frequently marks the beginning of a second challenging phase. Once the Commissioner (Appeals), the National Faceless Appeal Centre (NFAC), or the Income Tax Appellate Tribunal (ITAT) rules in favour of the taxpayer, the relief is not automatically applied as a reduced demand or a refund. Instead, the Jurisdictional Assessing Officer (JAO) must first calculate and implement these figures through an Order Giving Effect(OGE).

WHAT IS AN ORDER GIVING EFFECT?

An Order Giving Effect (“OGE”) is the order passed by the jurisdictional AO to implement the outcome of an appellate or rectification order – re-computing income, tax, interest and refund in line with the relief granted. the Assessing Officer (AO) is under a statutory obligation to pass the OGE within three months from the end of the month in which the appellate or revisionary order is received. This period may only be extended by the Principal Commissioner for reasons recorded in writing. [Section 153(5) of the Income-tax Act, 1961]. The provision exists precisely because relief on paper is meaningless until it is given effect to in the taxpayer’s PAN. For eg: a reduced demand, a corrected interest computation, or a refund with interest under section 244A.

BCAS SURVEY

A recent survey conducted for this study by the BCAS indicates that securing this final order is often the most difficult part of the entire process for professionals in the field. This survey was created only limited to the Tax officer’s duty to pass an order giving effect to NFAC/CIT Appeals or ITAT where the direction given for full relief and no verification is required. The results of the BCAS survey are summarized as under:

Survey Question Dominant
Response
On 100%
Q1. Is a follow-up with the jurisdictional officer necessary even after applying for OGE on the portal? Yes, most often 94.7%
Q2. Does the OGE carry mathematical errors requiring a rectification application? Yes / Sometimes (combined) 96.6%
Q3. Does a change of jurisdictional officer/inspector delay the passing of the OGE? Always / Most often (combined) 97.4%
Q4. Even where the AO must pass the OGE suo-motu on NFAC/ITAT’s direction, is a grievance still needed? Yes 86.1%

This reflects that the faceless assessment has still not been able to ease the procedural aspects of passing final orders effecting taxes of the taxpayer’s in whose favour the judgement is ruled. Additionally, Income Tax (CPC) portal also has a field where the taxpayer through his login is able to apply for OGE. Despite this the JAO calls for information to verify the facts which is already ruled in the favour of the taxpayer and the fact that the appellate authorities have not asked the JAO to verify any amount or facts. The matter is purely on merits.

Is it so that JAO does not trust his own system and records. It is a million-dollar question as to who is accountable for such a mess created and followed by the tax authorities. Despite the submissions being copied to the Commissioners, the JAO specially the ITO wards relentlessly delay the process of passing OGE.

THE SUFFERANCE:

The significant challenges taxpayers face regarding the implementation of appellate orders. Currently, the process following a successful appeal before the NFAC or the Tribunal is not self-executing, causing substantial difficulties for taxpayers. Legitimate refunds are frequently delayed well beyond the statutory three-month window, severely impacting working capital. Furthermore, interest under section 244A is often miscomputed or omitted in the rectification orders, necessitating repeated correspondence. Sometimes even the senior citizens having no business income are charged interest under sections 234B and 234C.

Additionally, original disputed demands frequently remain outstanding on the portal. These are offered for adjustment as per intimation under section 245, sometimes even without sending the original intimation for the refund year which gets adjusted under 245. This exposes taxpayers to unwarranted recovery notices, the adjustment of other refunds, and compromised compliance ratings, despite receiving favourable appellate rulings. The administrative burden and professional costs of filing follow-up letters, rectification applications, and grievances are borne entirely by the taxpayer.

Winning an appeal should provide finality rather than initiating a prolonged, unstructured process to secure the Order Giving Effect (OGE).

EASE OF PASSING OGE

The process largely can get self-executing and officer dependent:

– Centralize OGE Processing: Centralize OGE processing on the lines of NFAC/CPC. This will ensure that giving effect to appellate orders is not tied to a single jurisdictional officer whose transfer can stall the file indefinitely.

– Auto-Populate OGE Computation: Auto-populate the OGE computation from the appellate order and the return/assessment data already on record. Utilizing system-validated arithmetic (including interest under section 244A/234 series) will eliminate the manual errors reported in nearly half the cases surveyed.

– Establish a Handover Protocol: Build a mandatory handover protocol on transfer of jurisdiction, with pending-OGE files flagged for time-bound completion by the successor officer rather than resetting the timeline.

– Enforce Statutory Time Limits: Make the section 153(5) time limit self-enforcing through the portal itself. This would trigger an automatic escalation to the range head or a dashboard alert to CBDT once the statutory period lapses, rather than relying on the taxpayer to file a grievance.

– Automate Suo-Motu OGE Generation: Dispense with the need for a taxpayer-initiated grievance in suo-motu situations altogether. The system should generate the OGE automatically once the appellate order is uploaded, requiring human intervention only for genuine complexity.

– Introduce Interest Disincentives: Consider a modest interest disincentive on the Department for OGEs passed beyond the statutory time limit, mirroring the interest the taxpayer bears on delayed payment of tax, to align incentives on both sides.

The law should allow the release of refunds of the assessments years having no pending assessments or rectifications. In the cases where OGEs are required to be passed, the demands which are deleted by the NFACs or ITATs should not be adjusted against such correct refunds. Hence each demand and refund must be treated assessment wise.

CONCLUSION:

Reference is drawn to the latest decision in the Writ Petition of Global Hospitality Licensing SARL vs. ACIT/DCIT (IT), Mumbai (Writ Petition No. 1611 of 2024) dated 22nd June, 2026.

Issue & Background

The petitioner (a Luxembourg entity part of the Marriott group) disputed an assessment order treating its IMPPA receipts as taxable business income in India. The CIT(A)/NFAC ruled the receipts were royalties taxable at a beneficial DTAA rate and directed the Jurisdictional Assessing Officer (JAO) to pass an OGE. The Revenue received this order by 31st March, 2019, establishing a statutory deadline under section 153(5) to pass the OGE by 31st December, 2019. The AO failed to pass the OGE but subsequently completed penalty proceedings, imposing a penalty of Rs. 12.11 lakhs under section 271(1)(c).

Key Findings & High Court Holding

– Assessment Abates: Failure by the AO to pass the OGE within the mandatory statutory period under section 153(5) results in the abatement of assessment proceedings. The income declared in the petitioner’s return is treated as accepted.

– Penalty Falls: Because the underlying assessment abated, the foundational basis for the section 271(1)(c) penalty vanished, rendering the penalty order legally unsustainable.

– Interest is Not a Cure: The Revenue argued that section 244A(1A) interest remedies delays. The Court rejected this, clarifying that interest merely compensates the assessee and does not legitimize time-barred proceedings. Collecting tax via a time-barred OGE violates Article 265 of the Constitution.

Companion Ruling

The Calcutta High Court reinforced this position in Nomura Research Institute Financial Technologies India Pvt. Ltd. vs. UOI (12th June 2026), holding that an OGE passed beyond the section 153(5) limitation is “non-est” and directing a refund with interest.

Section 153(5) already prescribes a time limit; what is missing is an ecosystem that makes compliance with it the default rather than the exception. Until then, taxpayers who succeed before NFAC or the ITAT will continue to face an unwritten “second appeal” – not on the merits, but simply to have the Department do what it was already directed, and legally obliged, to do. That is not a fair outcome for a taxpayer who has already been vindicated in law.

There is a maxim in salesmanship that “customer is always right” but with the tax authorities it is mostly that “assessee is always wrong” despite the fact appellate authorities have verified the facts and passed the orders on merit of the case.

Is it fair on the part of the JAOs to put the assessee in mental and financial stress round the clock?

Miscellanea

1. TECHNOLOGY

# AI Could Cut 10 Weeks From Cancer Trials. Drugmakers Could Save Millions.

AI-powered systems are increasingly being explored for some of the labour-intensive work involved in running clinical trials.

AI agents could accelerate the clinical development of cancer medicine by approximately 10 weeks while reducing direct operating costs by as much as $5.6 million in late-stage trials.

A Tufts Center for the Study of Drug Development (CSDD) analysis found that AI agents could shorten cancer drug clinical development by about 10 weeks and reduce Phase 3 trial costs by up to $5.6 million. For drugs tested across multiple cancer indications, total benefits could reach $565 million. AI can improve patient recruitment, monitoring, data management, and trial analysis, leading to faster enrollment and quicker database lock. While AI may become a standard tool in clinical trials within 3 to 5 years, human oversight will remain essential, and AI cannot address all challenges in drug development or guarantee clinical success.

(Source: International Business Times – By Matias Civita – 13 August 2026)

2. PHARMACEUTICAL SECTOR

# India’s pharma sector must shift from cost competitiveness to innovation, global quality

For the growth of India’s pharmaceutical sector, prioritizing innovation and advanced manufacturing is essential. Experts indicate that increasing investments in research and digital technologies could propel the market to an impressive USD 130 billion by 2030. Companies must also elevate their quality and comply with global regulatory expectations to compete in the global landscape thus establishing India as an innovation hub in life sciences.

India’s pharmaceutical industry must move beyond its traditional strength in cost-effective generic medicines and focus on innovation, advanced manufacturing, quality excellence, and global regulatory compliance to unlock its next phase of growth, industry experts emphasized. With India targeting a pharmaceutical market size of USD 130 billion by 2030, stakeholders highlighted the need for increased investments in research and development, digital technologies, and contract research, development, and manufacturing services (CRDMO) to drive sustainable growth and global competitiveness.

These insights emerged at the official launch and precursor event for the 19th edition of Convention on Pharmaceutical Ingredients (CPHI) & Pharmaceutical Machinery and Equipment Convention (PMEC) India 2026, held under the banner of the Pharma Leadership Exchange in Hyderabad. The event brought together leading pharmaceutical executives, CXOs, industry veterans, and key stakeholders from across India’s pharmaceutical and life sciences ecosystem ahead of the flagship exhibition scheduled for November 2026 in Delhi-NCR.

(Source: The Economic Times – By PTI – 18 August 2026)

3. DOMESTIC NEWS

# Government approves 31 proposal worth INR 7,877 crore under electronics component scheme

The approvals are aimed at boosting domestic manufacturing of electronic components and strengthening India’s electronics supply chain, according to the Electronics and IT Secretary.

The government has approved 31 new projects on 17 August 2026 under the Electronics Component Manufacturing Scheme (ECMS), involving investments of ₹7,877 crore. With these approvals, total investments under the scheme have crossed ₹69,000 crore across 106 projects, exceeding the government’s original target of ₹59,000 crore.

The approved projects span key areas such as camera and display modules, connectors, rare earth magnets, speakers, microphones, antennas, and capital goods, supporting India’s goal of strengthening domestic electronics manufacturing and reducing import dependence.

According to Electronics Minister Ashwini Vaishnaw, the projects are expected to generate ₹82,243 crore of production and create nearly 10,000 jobs. He also emphasized four priorities for the sector’s growth: design capability, indigenous supply chains, Six Sigma quality standards, and workforce development.

(Source: The Economic Times – By PTI – 18 August 2026)

ICAI and Its Members

I. EXPOSURE DRAFT

‘Guidance Note on Report under section 92E of the Income-tax Act,1961’ for Public Comments

With a view to keeping the Guidance Note updated and relevant, the Committee proposes to revise the publication for the benefit and guidance of members. Accordingly, the Exposure Draft – “Guidance Note on Report under section 92E of the Income-tax Act,1961- 2022 Edition”, incorporating the proposed changes, has been issued for public comments. The Exposure Draft can be accessed at the following link: https://resource.cdn.icai.org/93928cit-aps6161-exp-draft.pdf

Comments on the above-mentioned Exposure Draft may be submitted at the following link on or latest by 05th September, 2026- https://forms.gle/Zo7Qgg2aFqCGemG66.

II. PUBLICATIONS

1. Compilation of FAQs on Code of Ethics, 2026

The FAQs on Code of Ethics, 2026 to provide practical guidance on the revised Code of Ethics. This compilation has been prepared in line with the revised Code and the decisions of the Council and ESB. It will help members understand the revised Code and uphold the highest standards of professional ethics.

https://resource.cdn.icai.org/93879esb-aps6117.pdf

2. Best Practices for Investor Presentation

An ICAI publication offering comprehensive guidance and practical insights. It is intended to strengthen professional knowledge and serve as a reliable reference for Chartered Accountants, students, and other stakeholders.

https://publication.icai.org/publications?committee=Financial+Markets+and+Investors%27+Awareness+Committee

3. Corporate Restructuring Beyond IBC: Emerging Issues and Recommendations by IB and VSB, ICAI and CLC, ICAI.

This publication examines the evolving landscape of corporate restructuring beyond the Insolvency and Bankruptcy Code, 2016, addressing emerging legal, regulatory and commercial issues. It presents a comprehensive analysis of alternative restructuring mechanisms, identifies key challenges, and offers recommendations to strengthen India’s restructuring framework.

https://publication.icai.org/publications?committee=Corporate+Laws+Committee

III. ICAI ANNOUNCEMENTS

1. NEW ICAI Course

1st Batch of Online Certificate Course on Overseas Outsourcing Services – Canada

Duration: 14 September 2026 to 26 October 2026

Registration Last Date: 10 September 2026.

https://resource.cdn.icai.org/93816gtsc-aps6108-canada.pdf

2. Inviting Expression of interest to act as Canada faculty for Proposed Certificate course on Overseas Outsourcing Services.

https://www.icai.org/post/gtsc-eoi-canada-12082026

3. India-USA Trade Facilitation Portal

Unlock Global Trade Opportunities with the INDIA USA TRADE Facilitation Portal.

The Ministry of External Affairs (MEA), through the Consulate General of India in New York, has authorized the Institute of Chartered Accountants of India (ICAI) to verify members on the India-USA Trade Facilitation Portal.

Objective: To connect verified Indian businesses with U.S. buyers, enabling secure and seamless cross-border trade.

BENEFITS OF REGISTRATION:

  • Access to verified B2B opportunities in the U.S. market
  • Enhanced credibility via ICAI verification
  • Networking with authenticated exporters, importers, and global stakeholders
  • Building trusted business relationships on a secure platform
  • Expanding international business networks confidently

Key Features:

  • ICAI-verified member authentication
  • Verified exporters and importers
  • Secure, transparent business platform
  • Trusted B2B networking and seamless trade facilitation

Registration link https://indiausatrade.mea.gov.in/login?redirect=%2Fadmin%2Fmanage-user

ICAI Announcement Link https://resource.cdn.icai.org/93380gtsc-aps5893.pdf

IV. Audit Tools

Tool For Audit Opinion Formation

https://forms.gle/CkgDyNiGih9PTxvq8

V. GIST of ICAI Opinion

1. Classification of Corporate Liquid Term Deposits (CLTDs)/Flexi Deposits in Financial Statements under Ind AS

A. Facts of the Case

The Company has centralised treasury operations and invests its funds in various instruments, including Corporate Liquid Term Deposits (CLTDs), fixed deposits and mutual funds. Funds are transferred from current accounts to CLTDs through sweep facilities and can be withdrawn prematurely when required. However, premature withdrawal results in a lower applicable interest rate and, in some cases, an additional penalty, resulting in a significant change in the amount realisable.

The Company classified deposits having original maturity of less than three months as cash and cash equivalents, those having original maturity of more than three months but less than twelve months as bank balances other than cash and cash equivalents, and deposits with maturity beyond twelve months as other non-current financial assets. It also classified 91-day deposits as cash equivalents.

C&AG’s observation: C&AG observed that the CLTD/Flexi Deposits were highly liquid and could be withdrawn whenever required without significant restriction and, therefore, should have been classified as cash and cash equivalents.

The Company submitted that the deposits were made based on projected fund requirements and were intended to meet requirements beyond three months. It also pointed out that premature withdrawal resulted in a reduced rate of interest and consequently a significant change in the amount realisable.

B. Query

The Company sought the Committee’s opinion on the following:

1. Whether the classification adopted by the Company in respect of Corporate Liquid Term Deposits (CLTDs)/Flexi Deposits was correct.

2. If not, what should be the appropriate classification of:

(i) CLTDs/Flexi Deposits having original maturity of less than three months;

(ii) CLTDs/Flexi Deposits having original maturity of more than three months and less than twelve months; and

(iii) CLTDs/Flexi Deposits having a remaining maturity of more than twelve months.

3. Whether CLTDs/Flexi Deposits are required to be presented separately from term deposits and, if so, what disclosures should be made.

4. Whether CLTDs/FDs having a maturity period of 91 days should be classified as Cash and Cash Equivalents.

C. Points considered by the Committee

The Committee considered the requirements of Ind AS 7 relating to cash equivalents. An investment qualifies as a cash equivalent when it is short-term and highly liquid, readily convertible into known amounts of cash, subject to an insignificant risk of changes in value, and held for meeting short-term cash commitments rather than for investment purposes.

The Committee observed that the assessment of whether an investment is held for meeting short-term commitments involves judgement and requires consideration of management intention, past practice, investment policy and actual utilisation.

It further noted that the risk of change in value arising from premature withdrawal and the consequent uncertainty in the amount realisable meant that deposits with an original maturity exceeding three months did not satisfy all the criteria for classification as cash equivalents.

D. Opinion

CLTDs/Flexi Deposits having original maturity of more than three months but less than twelve months cannot be classified as cash equivalents in the facts considered. Where they are expected to be realised within twelve months after the reporting date, they should be classified as bank balances other than cash and cash equivalents.

Deposits having maturity beyond twelve months should be classified as other financial assets under non-current assets. Importantly, the three-month period is assessed from the date of acquisition and not by reference to the remaining maturity at the reporting date.

CLTDs/Flexi Deposits having original maturity of up to three months, which satisfy all the criteria for classification as cash equivalents, can be so classified. Accordingly, the 91-day deposits, in the facts considered by the Committee, were classified as cash equivalents.

2. Consolidation of Financial Statements of an Associate Company which is a Section 8 Company under Ind AS

A. Facts of the Case

A Defence Public Sector Undertaking invested in AMF, Foundation, established under the Defence Testing Infrastructure Scheme. The Company holds 20% shareholding in AMF, which is incorporated as a Section 8 company. The Company has no other subsidiary, associate or joint venture and had accounted for its investment in AMF using the equity method under Ind AS 28.

Statutory auditor’s qualification: The statutory auditor qualified the accounts on the ground that, under Section 8 of the Companies Act, profits cannot be distributed directly or indirectly among members/shareholders. Consequently, according to the auditor, the Company’s profit and investment in the associate were overstated by the Company’s share of AMF’s profit recognised under the equity method.

The Company therefore sought clarification on whether CFS was required when the only associate was a Section 8 company and whether merely disclosing the investment in the standalone financial statements would be sufficient.

B. Query

Whether an investment in a Section 8 company, qualifying as an associate under Ind AS 28, is required to be accounted for using the equity method.

Further, whether CFS is mandatory where the Company has no subsidiary or other associate, and whether the prohibition on distribution of profits by a Section 8 company affects the requirement to apply the equity method.

C. Points considered by the Committee

The Committee observed that 20% shareholding by itself does not conclusively establish significant influence; the requirements of Ind AS 28 must be considered. However, since neither the Company nor the auditor had raised the issue of significant influence, the Committee proceeded on the premise that AMF was an associate.

Under Section 129(3) of the Companies Act, a company having an associate is required to prepare CFS unless an applicable exemption is available. There is no specific exemption merely because the associate is a Section 8 or not-for-profit company.

The Committee further noted that, for associates and joint ventures, consolidation involves application of the equity method under Ind AS 28.

The prohibition on distribution of profits by a Section 8 company does not, by itself, prevent the existence of significant influence. However, restrictions on transfer of funds from the investee should be considered when assessing significant influence.

D. Opinion

If the Company has significant influence over AMF, it should account for AMF using the equity method under Ind AS 28 and prepare CFS. If, after assessment, significant influence does not exist, AMF would not be an associate and the question of consolidation would not arise.

The share of surplus from AMF should be presented in a manner that clearly communicates to users that the surplus of the Section 8 company is not distributable as dividend. The Company should also make appropriate disclosures regarding the nature of its relationship with AMF and restrictions on the transfer of funds under Ind AS 112.

3. Accounting Treatment of Grants under AS 12 – Accounting for Government Grants

A. Facts of the Case

The Company is a Section 8 company under the administrative control of the Department of Personnel and Training (DoPT), Government of India, with 100% equity shareholding by the Government of India. It was established for capacity building of government officials under Mission Karmayogi and is responsible for owning, maintaining and improving the iGOT digital/e-learning platform.

The Company receives various grants from DoPT, including Grant-in-Aid (Salaries), Grant-in-Aid for creation of capital assets, Grant-in-Aid (General) and Grant-in-Aid comprising World Bank funds. The World Bank funding is routed through DoPT, with repayment and servicing obligations resting with the Government.

The Company owns and controls the digital asset and is entitled to the future economic benefits arising from it. It accounts for expenditure on the development of the platform as CWIP and subsequently capitalises it as intangible assets, which are amortised over four years.

B. Query

What should be the accounting treatment for grants received as GIA (World Bank funds) and GIA (General) in relation to CWIP and intangible assets created from such funds?

Whether grant income should be recognised in line with depreciation/amortisation of the related intangible assets and, if so, whether the change should have prospective or retrospective effect.

C. Points considered by the Committee

The Committee considered whether the Government was providing the funds in its capacity as shareholder or as a provider of government grants. Although the Government was the 100% shareholder, the Company had clarified that the funds were received as Government Grants, and not as equity contribution. The sanction letters also described the amounts as grants/grant-in-aid rather than equity contribution.

The Committee therefore concluded that AS 12 was applicable.

It then considered the purpose of the funding. The grants were intended to support the Company’s initial capital and working-capital outlay, including the development and operating expenditure of the iGOT platform until the subscription-based revenue model became operational. The grants were not subject to the primary condition of acquiring or constructing a specific fixed asset or meeting specific revenue expenditure.

D. Opinion

The Committee opined that the GIA (World Bank funds) and GIA (General) are in the nature of promoters’ contribution under AS 12.

Accordingly, these grants should be credited to Capital Reserve and should not be recognised as income in the Statement of Profit and Loss.

Since the Company had not followed the requirements of AS 12 in FY 2022-23 and FY 2023-24, the Committee considered the matter to be an error of prior periods, to be accounted for in accordance with AS 5 relating to prior-period items.

https://cajournal.icai.org/upload/issue/1785550517_6a6d56b56b909_311_Gist_of_Opinions.pdf

VI. ICAI DISCIPLINARY COMMITTEE

1. V.R. vs. CA. P.B.

File No.: PR/G/735/2022/DD/514/2023/DC/1896/2024

Date of Order: 05.02.2026 (Findings dated 22.12.2025)

Certification of Form 10 – modification of charge securing debentures without adequate verification.

Background

During inspection of M/s SAPL, it was observed that the Respondent had certified Form 10 (Particulars for Registration of Charges for Debenture) filed on 23.09.2011 for modification of a charge securing debentures of ₹10 crore. The Company had stated that property was mortgaged as security for the debentures. However, its audited balance sheet as at 31.03.2011 showed net fixed assets of only ₹91,41,570 and current assets of ₹8,98,303. The Form 10 placed on record did not contain the mortgage deed or valuation report. The complaint also alleged that the Form 10 had been signed by the debenture trustee, Shri GPG, although he had denied on oath having signed it.

Key Allegations

  • The Respondent certified Form 10 without verifying the security stated therein.
  • The Form 10 was certified without verifying the supporting mortgage deed and valuation report.
  • The Respondent allegedly failed to verify the authenticity of the Form 10 and the signature of the debenture trustee.
  • The security coverage was substantially inadequate in relation to the ₹10 crore debentures.

Respondent’s Defence

The Respondent did not file a Written Statement and did not furnish the additional documents sought by the Directorate. He also did not appear before the Committee despite repeated opportunities, including hearings on 10.07.2025, 24.07.2025, 20.08.2025, 22.09.2025 and 10.10.2025. Consequently, the Committee proceeded on the basis of the documents available on record.

Findings

The Committee noted that the audited financial statements showed net fixed assets of only ₹91.41 lakh against debentures of ₹10 crore, resulting in a shortfall of close to ₹9 crore in the coverage of the debentures. It further noted that the Form 10 did not contain the mortgage deed or valuation report. The Committee therefore concluded that the Respondent had not exercised due diligence before certifying the statutory Form 10. His failure to respond to the disciplinary proceedings and to provide the documents sought also weighed against him.

Charges Established

Guilty of professional misconduct under Item (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949 — failure to exercise due diligence or gross negligence in the conduct of professional duties.

Punishment

Reprimand and a fine of ₹4,00,000, payable within 60 days of receipt of the order.

2. A.K.S. vs. CA. A.K.P.

File No.: PR/G/413/2019-DD/68/2020/DC/1929/2024

Date of Order: 05.02.2026 (Findings dated 22.12.2025)

Failure to give adequate reasons for adverse audit opinions and contradictory reporting in the audit report for different financial years.

Background

The Respondent was the statutory auditor of M/s OMSL for FYs 2008-09, 2009-10, 2010-11 and 2011-12. The ROC alleged that the audit reports were general in nature and, although adverse opinions had been expressed, the reports did not specify the reasons supporting those opinions.

For FYs 2008-09, 2009-10 and 2010-11, the Respondent reported, among other matters, that the Company had not maintained proper books of account, the financial statements did not agree with the books, the Accounting Standards had not been complied with, and the financial statements did not give a true and fair view. However, the audit reports themselves did not set out the substantive reasons for these adverse conclusions.

For FY 2011-12, the problem was more serious. The audit report stated that the Company had maintained proper books, that the financial statements were in agreement with the books and complied with Accounting Standards, but simultaneously stated that the accounts did not give the information required by the Companies Act and did not give a true and fair view.

Respondent’s Defence

The Respondent contended that the absence of proper books and records was itself the substantive reason for the adverse reporting. He also submitted that the Company had several accounting deficiencies, including non-maintenance of books under Section 209, non-adherence to the accrual system, improper classification of investments, non-recognition of losses, absence of significant accounting policies and non-compliance with Schedule VI.

Regarding FY 2011-12, he explained the contradictory wording as an unintentional typographical error, stating that the report should have said that the financial statements did not give a true and fair view. He also raised a grievance that relevant portions of the ROC investigation report had not been furnished to him.

Decision of the Committee

The Committee rejected the Respondent’s defence.

It held that where an auditor expresses an opinion other than an unqualified opinion, the substantive reasons for such opinion must be clearly stated in the audit report itself. The Committee relied upon Section 227(4) read with Section 227(3) of the Companies Act, 1956 and AAS-28, which specifically required the reasons for an adverse or modified opinion to be disclosed.

The Committee did not accept the argument that the Respondent’s subsequent explanations given during the disciplinary proceedings could cure the omission in the audit reports. The reasons supporting the adverse opinion were required to form part of the audit report.

More importantly, the Committee rejected the explanation of typographical error for FY 2011-12. It noted that the contradiction was not an isolated drafting error. The report simultaneously stated that the Company had maintained proper books, that the financial statements agreed with those books and complied with Accounting Standards, while also stating that the financial statements did not provide the information required by the Companies Act and did not give a true and fair view. The Committee considered this contradiction, together with the deficiencies in the earlier years’ reporting, to constitute gross negligence and lack of due diligence.

Accordingly, the Committee held the Respondent guilty of professional misconduct under Item (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949, i.e. failure to exercise due diligence or gross negligence in the conduct of professional duties.

Punishment

The Committee ordered that the Respondent be reprimanded and pay a fine of ₹1,50,000, within 60 days of receipt of the order.

3. Shri MM, CFO of APL. v. CA. SKR

Reference: PR/252/2018/DD/262/2018/DC/1930/2024

Order: 5 February 2026

Provision: Item (7), Part I, Second Schedule to the Chartered Accountants Act, 1949 – failure to exercise due diligence / gross negligence.

FACTS

The Respondent was the statutory auditor of HC for FY 2016-17. The Company was under a Government-approved closure scheme and had negotiated an OTS with its creditors, including MSME creditors. Some MSME creditors, including Avi Polymers, did not accept the OTS.

Despite approximately ₹32.79 crore of MSME interest being outstanding in the previous year, the FY 2016-17 financial statements showed nil interest payable. The Company wrote back ₹32.79 crore of accrued MSME interest under the OTS. However, certain MSME creditors had not accepted the OTS, and their interest remained unpaid.

Auditor’s Defence

The auditor argued that:

  •  The OTS had been approved and supported by Board minutes;
  •  Management had given a detailed representation explaining the write-back;
  •  He was entitled to rely on management representations and the information available during the audit;
  •  The subsequent arbitration award could not retrospectively create an audit obligation; and
  •  There was no mala fide intention or deliberate negligence.

COMMITTEE’S FINDING

The Committee rejected the defence.

Its central finding was that Sections 16 and 22 of the MSMED Act, 2006 are mandatory. Interest on overdue MSME dues was required to be provided for, and the unpaid principal and interest were required to be separately disclosed in the financial statements.

The Committee considered it significant that:

  1.  Some MSME creditors had not agreed to the OTS;
  2.  Their interest liability therefore remained outstanding;
  3.  The Company’s Board itself subsequently resolved that interest payable to MSME units would be paid as arrived at after negotiation; and
  4.  The auditor nevertheless did not qualify his audit report for the non-provisioning and non-disclosure.

The Committee also noted that the auditor acknowledged the issue in the following year’s audit report, stating that some MSME creditors had not agreed to the OTS and that the Company had not provided for their interest.

Accordingly, the Committee held that reliance on the OTS negotiations, management representation or subsequent adjudication did not absolve the auditor of his responsibility to report the statutory non-compliance existing at the balance-sheet date.

Decision

The Respondent was held guilty of professional misconduct under Item (7) of Part I of the Second Schedule to the Chartered Accountants Act, 1949.

Punishment

Reprimand and a fine of ₹5 lakh, payable within 60 days of receipt of the order.

Recent Decisions In GST

I SUPREME COURT

45. [2026] 189 taxmann.com 330 (SC)

Goodluck India Ltd. vs. Union of India dated.06.08.2026

In absence of any ‘saving clause’, the omission of Rule 96(10) w.e.f. 08-10-2024 shall apply to all pending matters in the case of refund of IGST paid on exported goods and services

FACTS

Rule 96(10) of the CGST Rules, 2017 restricted refund of IGST paid on exports in specified circumstances. By Notification No. 20/2024-Central Tax dated 08.10.2024, Rule 96(10) was omitted. Although the GST Council had recommended that the omission should operate prospectively, the Notification contained no saving clause for pending proceedings. The High Court held that the omission would apply to all proceedings pending as on 08.10.2024. The Department challenged this view before the Supreme Court, contending that the omission should operate prospectively, while the assessee claimed that the omission entitled them to claim refund without the restrictions imposed by the erstwhile Rule 96(10).

HELD

The Supreme Court dismissed the appeals and affirmed the High Court’s judgment. Relying on the Constitution Bench decision in Kolhapur Cane Sugar Works Ltd. vs. Union of India, the Court held that, in absence of a saving clause or any statutory mechanism preserving proceedings under an omitted rule, pending proceedings cannot continue under the omitted provision. The Court noted that Rule 96(10) was omitted as it was causing unnecessary complications without any intended benefit, and that the GST Council’s recommendation for prospective operation was advisory and not binding on the rule-making authority. Accordingly, the omission of Rule 96(10), effective from 08.10.2024, applies to pending proceedings as well, enabling refund claims to be considered without the restrictions contained in the omitted provisions. The Court further held that the intention to omit the rule without any saving clause was to bring to end unnecessary complications once and for all and the intention cannot be to keep the complications live for pending proceedings.

[Note: Gujarat High Court in the case of Addwrap Packaging Pvt. Ltd. 2025-TIOL-960-HC-AHM-GST had held that since Rule 96(10) was omitted without a saving or a sunset clause, the pending matters will stand closed].

II HIGH COURT

46. [2026] 189 taxmann.com 403 (Patna) Azad Enterprises vs. State of Bihar dated 06.08.2026.

The Adjudicating Officer has no authority to determine tax liability under section 73(9) prior to expiry of due date of filing of annual return and hence adjudication order passed prior to the said due date is liable to be set aside.

FACTS

The petitioner regularly filed monthly and quarterly GST returns. The due date for filing the annual return for F.Y. 2022-23 under section 44 was 31.12.2023. However, the Adjudicating Authority passed an assessment order under section 73(9) determining tax liability on 25.11.2023 i.e. before the expiry of the said due date. The petitioner subsequently filed its annual return on 20.01.2024. The petitioner challenged the assessment order as well as a consequential bank attachment notice.

HELD

Since the due date for filing the annual return for F.Y. 2022-23 was 31.12.2023, the Proper Officer had no authority to determine tax liability under section 73(9) prior to expiry of that due date. The impugned order dated 25.11.2023 was accordingly set aside, and the matter was remanded for fresh proceedings.

47. [2026] 189 taxmann.com 463 (Delhi)

Kanwal Chaudhary vs. Insolvency and Bankruptcy Board of India dated 13.08.2026.

Advocates enrolled with the Bar Council, who act as Insolvency Professionals under the IBC, shall be governed by the “forward charge mechanism” and shall be liable to obtain GST registration.

FACTS

The petitioner, an Advocate, registered as an Insolvency Professional (IP) was appointed IRP by NCLT Delhi for a corporate debtor. He raised invoices in 2019 for his professional fee but, when asked to issue GST-compliant invoices, he claimed exemption under the reverse charge mechanism (RCM) applicable to Advocates under Notifications 12/2017 and 13/2017. On NCLT’s reference, the Insolvency and Bankruptcy Board of India (IBBI) held that “insolvency and receivership services” are not covered under RCM and directed him to issue GST-compliant invoices which order was challenged in this writ petition. The Bar Council of India (BCI) was also a party to the petition, which submitted that when an Advocate is appointed as an Insolvency Professional, under IBC, the nature of services rendered are different from conventional legal services. On behalf of the IBBI, it was pointed out that the total number of Advocates registered as IPs is approximately 273, whereas the total number of registered Insolvency Professionals is 4,558.

HELD

The Hon’ble Court examined section 22 of the CGST Act, Notification No.12/2017 Central Tax (Rate), dealing with exemptions and Notification No.13/2017-Central Tax (Rate), dealing with notified services for attracting liability under the reverse charge mechanism, including a corrigendum thereto issued on 25.09.2017. The Hon’ble Court also examined the statutory framework under the IBC and the IBBI regulations. The Hon’ble Court held that IPs constitute a distinct class, governed exclusively by the IBC and the IBBI Regulations. The fact that such persons possess other qualifications or registrations, would not make them distinct or different from the class as a whole. The Insolvency Professionals as a class, are a singular, and distinct class by themselves. Referring to the scheme of classification of services under the GST, the Hon’ble Court observed that the broad head 982 – “Legal and Accounting Services” – is itself sub-divided into four distinct and mutually exclusive service codes. Legal services under 99821 are exhaustively enumerated in heads 998211 through 998219, the last of which is 998219 – “Other legal services n.e.c.”, and that is the residuary entry, meant to capture any legal service not falling within the preceding specific codes. Insolvency and receivership services, however, do not fall within this residuary entry, or anywhere within the 99821 sub-head at all. They are instead classified under an independent specific subhead, 99824, co-ordinate with and not subordinate to 99821. The Hon’ble Court therefore held that the scheme of classification itself demonstrates that “insolvency and receivership services” are treated as a distinct category of service, separate from “legal services” and hence the nature of the service rendered by an Insolvency Professional is not, for the purposes of GST, to be equated with or subsumed within “legal service” merely because the person rendering it happens to be enrolled as an Advocate. It held that the specific entry prevails over the general one.

Applying the aforesaid principle, the Hon’ble Court held that when an advocate renders services as an Insolvency Professional, the role in which he acts is that of an Insolvency Professional, and not that of an Advocate. It is this role – that of a provider of “insolvency and receivership” services – that is determinative of the nature of services rendered for the purpose of classification, and NOT the underlying professional qualification or the registration of the individual concerned. Accordingly, it held that the Advocates enrolled with the Bar Council, who act as Insolvency Professionals under the IBC, shall be governed by the “forward charge mechanism” and shall be liable to obtain GST registration.

48. (2025) 35 Centax 152 (All.)

M/s. Safecon Lifescience Pvt. Ltd. vs. Additional Commissioner Grade 2 dated 09.09.2025.

Section 74 cannot be invoked to deny ITC merely based on irregularities attributable to suppliers at an earlier stage of the supply chain, where the petitioner has duly established the genuineness of the transaction and actual movement of goods

FACTS

The Petitioner was engaged in the business of trading and manufacturing of pharmaceuticals. The Adjudicating Authority received information that the supplier’s registration was cancelled due to irregularities in its own procurements and non-payment of tax. Accordingly, an SCN was issued invoking section 74 of CGST Act on the petitioner alleging that it has availed ITC pertaining to purchases from the above supplier. The Petitioner had submitted genuineness of the transaction through valid invoices, e-way bills, returns and banking payments which was totally ignored by the Adjudicating Authority. The Petitioner preferred an appeal and the Appellate Authority passed order on the basis of information without considering the submissions of the petitioner. The Petitioner therefore preferred a writ challenging the order before the Hon’ble High Court.

HELD

The Hon’ble High Court held that once the Petitioner had established the actual movement of goods, and all the conditions for availing ITC such as issuance of valid invoices, payment of tax etc. have been fulfilled, proceedings under section 74 cannot be invoked on the basis of any information when the essential ingredients of fraud, wilful misstatement or suppression undertaken with an intent to evade tax were absent. Accordingly, the High Court allowed
the petition and quashed the proceedings under section 74.

[Note: In the case of Additional Commissioner, Grade 2 vs. M/s Safecon Lifescience Private Limited, where Additional Commissioner filed a Special Leave Petition No. 23993/2026 dated 17.07.2026 before Supreme Court of India, the Apex Court did not find any grounds to admit the petition and hence dismissed the petition.]

49. (2026) 44 Centax 121 (Gau.)

Debabrata Bhowmick vs. Union of India dated 24.06.2026.

Time spent in pursuing rectification of Order-In-Original would be excluded from computation of the limitation period for filing an appeal.

Appeal filed belatedly cannot be rejected without providing an opportunity of being heard even if separate application for condonation of delay was not made.

FACTS

The Petitioner was engaged in the business of medicines. The Adjudicating Authority issued an SCN to the Petitioner under section 73 alleging excess ITC claimed in F.Y. 2020-21 and subsequently, passed an Order-In-Original confirming the demand on 03.01.2025. Aggrieved by the said Order-In-Original, the Petitioner sought rectification of the order on 08.03.2025 which was rejected on 24.04.2025, and accordingly, filed an appeal against the Order-In-Original on 23.05.2025. However, the Appellate Authority passed an Order-In-Appeal refusing to admit the appeal stating the appeal was time barred. Being aggrieved, the Petitioner preferred writ petition before this Hon’ble High Court.

HELD

The Hon’ble High Court held that the period spent pursuing rectification i.e. from the date of rectification application (08.03.2025) to the date of passing rectified order (24.04.2025) under section 161 would be excluded while computing the limitation period for filing an appeal under section 107. Moreover, it also held that it is the obligation of the Appellate Authority to provide the Petitioner an opportunity of being heard before dismissing the appeal in cases where appeal was filed belatedly, even if an application for condonation of delay is not filed. Accordingly, the petition was decided in favour of the Petitioner.

III GST APPELLATE TRIBUNAL (GSTAT)

50. (2026) 45 Centax 50 (Tel.)

Reddy Veeranna Constructions Pvt. Ltd. vs. Appeal – I Commissioner dated 28.07.2026

Introduction of mandatory pre-deposit for Orders involving only Penalty under section 112 could not be retrospectively applied where SCN, Adjudicating Order and Appellate Order were issued prior to 01.10.2025.

FACTS

The Adjudicating Authority issued an SCN dated 29.09.2022 alleging fake invoicing without actual supply by Appellant and imposed penalties which were eventually confirmed in the Order-In-Original on 28.08.2023. Further, the Appellate Authority had passed an Order-In-Appeal rejecting the appeal on 12.01.2024. Being aggrieved by Order-In-Appeal, the Appellant filed an appeal before the GSTAT without making 10% pre-deposit of penalty as per the proviso to section 112(8) which came into force only from 01.10.2025. The issue arose before the GSTAT was whether the appeal would be admitted without making the mandatory pre-deposit.

HELD

The Hon’ble Telangana Bench of the Tribunal held that the proviso to section 112(8) requiring pre-deposit in penalty-only appeals was amended prospectively from 01.10.2025 and it would not be applicable to any SCN, Order-In-Original and Order-In-Appeal issued prior to 01.10.2025.

[Note: Even where only SCN is issued prior to 01.10.2025 and Adjudicating Order is issued subsequently after 01.10.2025, still pre-deposit is not required for filing appeals against Orders involving penalty-only as per Delhi High Court in the case of Gaurav Jain vs. Joint Commissioner (Appeals-II) CGST, Delhi Zone. (2026) 45 Centax 75 (Del.) dated 31.07.2026)

51. [2026] 189 taxmann.com 502 (GSTAT – TRIVANDRUM)

M S Steels vs. Commissioner of Kerala State GST, Thiruvananthapuram dated 14.08.2026

Penalty under section 129(3) is not attracted when transportation of goods in the nature of internal stock transfer under same GSTN is done without issue of E-way bill as the transaction involves no supply, no consideration and consequently no tax liability.

FACTS

The Appellant was transporting steel goods under a delivery challan from one of its own premises to its own godown — a stock transfer under the same GSTIN — when the vehicle was intercepted for want of an e-way bill and detained under section 129(1) of the CGST/KGST Act; a penalty was imposed under section 129(3) with no tax demand raised, and was paid to secure release of the goods. The First Appellate Authority upheld the penalty, holding the absence of an e-way bill rendered the transaction “not genuine,” without recording independent findings of fraud or intent to evade tax. The Appellant filed the present Appeal contending that since the movement was a same-GSTIN stock transfer with no sale, consideration, or second party involved, it did not constitute a ‘supply’ under section 7 and hence no tax was ‘payable’, so penalty under section 129(1)(a) (computed with reference to tax payable) could not be sustained; alternatively, at most section 122(1)(xiv) (capped at Rs.20,000) should apply. The Revenue argued that section 129 is a self-contained, non-obstante machinery provision triggered by mere contravention of e-way bill requirements (Rule 138(1)(ii)) irrespective of whether a taxable supply occurred and that mens rea and tax liability are not preconditions for such penalty.

HELD

The Hon’ble GSTAT held that the penalty under section 129 of the CGST/KGST Act is leviable only in terms of the “tax payable” on the goods. In the present case, the transaction in question would not be a ‘supply’ as defined under section 7 of the CGST /KGST Act 2017. Once a determination has been made that tax on the goods is non est, it stands to reason that penalty under section 129(1) of the CGST/KGST Act (which is to be determined in terms of such tax payable), is not leviable. The Hon’ble GSTAT relied upon the decision in the case of Fabricship (P.) Ltd. vs. Union of India [2024] 164 taxmann.com 80/90 GSTL 302 (Bombay) in support of this view and the Order-in-Appeal was set aside, and the appeal was allowed with consequential relief.

52. [2026] 189 taxmann.com 503 (GSTAT – TRIVANDRUM)

Siddhi Vinayak Automobiles vs. Commissioner of Kerala State GST dated 14.08.2026

Penalty Order issued under section 129(3) of the CGST/SGST Act, 2017 shall be held valid only if it is issued within the prescribed time limit of 7 days from the date of serving of notice.

FACTS:

The Appellant, M/s. Siddhi Vinayak Automobiles, a dealer in automobiles and spare parts, transported goods under two valid Tax e-Invoices dated 16.4.2022. The vehicle was intercepted on 18.4.2022 for want of an e-way bill. Goods were detained and a notice in MOV-07 was issued the same day; a penalty (100% of GST) was imposed under section 129(1) and goods were released on 20.4.2022 on furnishing Bond and Bank Guarantee. However, the confirmation order in MOV-09 under section 129(3) was passed only on 4.6.2022 — 47 days after the notice — well beyond the mandatory 7-day period prescribed under section 129(3). The First Appellate Authority upheld the penalty, holding the transaction “not genuine” solely for want of an e-way bill, without addressing the limitation issue. The Appellant contended before the Tribunal that the order was time-barred and void, while the Revenue argued that this ground was raised for the first time in second appeal and could not now be entertained.

HELD

The Hon’ble GSTAT held that the seven-day period under section 129(3) is mandatory, as the provision uses ‘shall’ and relates to coercive action. Since MOV-09 was issued after 47 days, it was illegal and without jurisdiction. Mere non-generation of an e-way bill, without any intention to evade tax, did not warrant penalty. The appeal was allowed and the penalty order set aside, with consequential relief including release of the Bank Guarantee.

Recent Developments in GST

A. CIRCULARS

(i) Clarification regarding filing of appeal by the Department before GSTAT Circular no.256/02/2026-GST dated 25.07.2026

By the above circular, clarification has been provided regarding the procedure for filing departmental appeals before the Goods and Services Tax Appellate Tribunal (GSTAT) against orders passed by the appellate authority.

B. OFFICE ORDER

i) The GSTAT President has issued office order bearing no.4/GSTAT/PB/2026 dated 29.07.2026, by which some Benches have been reconstituted and the classification of categories of cases have been revised.

C. GSTN

(a) GSTN has issued Advisory dated 29.07.2026 informing about keeping the proposed e-Way Bill enhancements on hold.

D. INSTRUCTIONS

(i) The CBIC has issued instruction No.1/2026-GST dated 03.08.2026, by which instruction regarding coordination with State Mining Authorities for sharing information relating to illegal mining and transportation of minerals have been issued.

E. ADVANCE RULINGS

26. Indian Wire Products Company (AAAR Order No. 02/WBAAAR/APPEAL/2026 dt.10.7.2026)(WB)

Supply of Hookah in a restaurant is a separate supply. It cannot be considered as ‘Restaurant Supply’. Parliament has not declared every supply made in a restaurant to be a restaurant service.

This appeal was filed by appellant against the Ruling passed by the WBAAR vide Advance Ruling Order No. 33/WBAAR/2025-26 dated 27.02.2026.

The appellant runs a restaurant under the name of “Pappu Chaiwala”. In the course of operating the said restaurant, the appellant also proposes to serve hookah, whether herbal or tobacco based, to customers within the restaurant premises as part of the overall dining experience. In this background, the appellant filed an application before WBAAR, seeking an advance ruling on the following questions:

“i. Whether or not serving of non-tobacco hookah / tobacco-based hookah in the restaurant along with food will be termed as supply of goods or services within the ambit of Clause 6(b) of Schedule II to the CGST Act?

ii. If yes, what will be the rate of tax applicable on herbal (non-tobacco-based) flavours and tobacco-based flavours?”

Before AAR, appellant made his submission to justify that such tobacco hookah service is part of restaurant service and hence covered by clause 6(b) of Schedule II i.e. restaurant service.

The ld. AAR held that the supply of food and the supply of tobacco based / non-tobacco-based hookah constitute two separate composite supplies. While the supply of food was held to be a supply of service falling within Clause 6(b) of Schedule II and liable to GST at 5%, the supply of hookah was held to be a composite supply of goods, the principal supply being the tobacco or non-tobacco products used for smoking. Accordingly, tobacco-based hookah was held taxable at 40% under Heading 2403, together with other applicable levies, whereas non-tobacco-based hookah was held taxable at 18% under the relevant rate notification.

In appeal, the appellant tried to convey that the AAR has erred in reaching to above conclusion. The Revenue supported the order of the AAR.

The ld. AAAR observed that the principal contention of the appellant is that the activity of preparing and serving tobacco-based as well as non-tobacco based hookah within a restaurant forms an integral and naturally bundled component of restaurant service and, therefore, constitutes a composite supply falling within the ambit of Clause 6(b) of Schedule II to the CGST Act, with restaurant service being the principal supply liable to tax at the rate applicable thereto.

The ld. AAAR observed that the controversy before them arises under paragraph 6(b) of Schedule II read with the definition of ‘restaurant service’ as appended to the Notification No.11/2017 Central Tax (Rate) dated 28.06.2017.

The ld. AAAR observed that the conjoint reading of paragraph 6(b) of Schedule II and the definition of ‘restaurant service’ shows that Parliament has not declared every supply made in a restaurant to be a restaurant service.

The ld. AAAR held that rate notification cannot be viewed in isolation from paragraph 6(b) of Schedule II, nor can it enlarge the statutory scope of restaurant service beyond what Parliament has enacted. In view of above, the distinction made by AAR was approved by ld. AAAR and, accordingly, the ld. AAAR disagreed with the appellant and confirmed the order of the AAR.

27. Karam Chand Thapar & Bros (Coal Sales) Ltd. (AAAR Order No. 04/WBAAAR/APPEAL/2026-27 dt.15.7.2026)(WB)

Advance Ruling – Scope

This appeal has been filed by appellant against the ruling passed by the WBAAR vide order no.31/WBAAR/2025-26 dated 13.02.2026.

The background facts are as under:

“2. The appellant entered into three agreements with THDC India Ltd (formerly known as Tehri Hydro Development Corporation Limited) in the year 1996 for execution of work for the construction of Hydro Power Plants which was completed in the year 2007/08 and the final payment was received by the applicant in the year 2011. During the execution of the work, dispute arose over the extra expenses incurred by the applicant for the project which led to several litigations. Accordingly, the Arbitral Tribunal was constituted by Supreme Court and Delhi High Court for deciding all the disputes between the parties pertaining to all the three packages. Finally, in the year 2023, Awards were passed in favour of the applicant which allowed private quarry costs, costs incurred on excavation method change, cost involved in use of higher grade of cement, cost involved in relocation of infrastructure, etc incurred by the applicant. Conciliation Proceedings commenced between THDC India Ltd and the Applicant in June 2024. Accordingly, the payment is received by the applicant as per the Settlement Agreement in October 2024.”

In light of above facts, the appellant sought to get determined as to whether the claim allowed by the Arbitral Tribunal vide the arbitration awards could be termed as supply or not, or whether they constituted liquidated damages etc.

The ld. AAR answered the questions raised for ruling on merits.

During the course of the hearing, the ld. AAAR questioned the maintainability of the advance ruling application itself and observed that although the application had been filed seeking a ruling on a question falling within the scope of Section 97(2)(e) and/or (g) of the CGST Act, 2017, the maintainability of the application would require examination in light of the provisions of Section 95(a) of the CGST Act, 2017, which defines the expression “advance ruling” as a decision provided in relation to the supply of goods or services or both being undertaken or proposed to be undertaken by the applicant. The ld. AAAR accordingly called upon the appellant to address the issue of maintainability of the application with reference to the aforesaid statutory provisions.

The appellant tried to justify the deciding of issues by the AAR, based on language of Section 95(a) of the CGST Act.

The appellant also challenged the authority of the AAAR to travel beyond the issues decided by the AAR under appeal.

The ld. AAAR observed as under:

“19. Section 95(a) of the CGST Act defines an “advance ruling” as a decision provided by the Authority in relation to a supply of goods or services or both being undertaken or proposed to be undertaken by the applicant. The language employed by the Legislature is clear and significant. The jurisdiction of the Authority is thus intrinsically linked with transactions which are prospective or ongoing. Section 97 of the CGST Act specifies the categories of questions on which a ruling may be sought; however, the said provision merely identifies the subject matter of the questions and does not enlarge the jurisdictional requirement embodied in Section 95(a). Consequently, reliance placed by the applicant on Section 97(2)(g) of the CGST Act cannot obviate the necessity of satisfying the jurisdictional condition prescribed under Section 95(a) of the CGST Act.”

Accordingly, the ld. AAAR observed that the AAR can decide transactions which are on going or to be undertaken but cannot extend to completed transaction, as such function lies with the adjudicating authority and not with the AAR.

Regarding objection of appellant about the jurisdiction of the AAAR to raise the issue of maintainability of the AR itself, the ld. AAAR relied upon judgment in case of National Thermal Power Co. Ltd. vs. CIT [(1998) 229 ITR 383 – 1996-VIL-06-SC-DT], in which the Hon. Supreme Court has observed that “…Under Section 254 of the Income-tax Act, the Appellate Tribunal may, after giving both the parties to the appeal an opportunity of being heard, pass such orders thereon as it thinks fit. The power of the Tribunal in dealing with appeals is thus expressed in the widest possible terms.” [emphasis added].

Accordingly, the ld. AAAR held that there is jurisdiction to raise an issue even though it was not subject matter of original proceeding.

Regarding merits of maintainability of the AR, the ld. AAAR revoked the AR given by AAR on the ground that it ought not to have ben entertained. The ld. AAAR also made clear that it has not opined upon the merits of the claims.

28. Chemizone Pvt. Ltd. (AAR Order No. 03/2026-27 in Appl.No.01/2026-27 dt.29.7.2026)(Uttarakhand)

ITC is not eligible on GST paid on upfront Lease Amount

The facts narrated by applicant are that it intended to secure a plot of land on long term lease from Eldeco Sidcul Industrial Park Limited (ESIPL) at Sitargunj;

For this lease, they will be paying an upfront lease amount to M/s ESIPL; M/s ESIPL will be charging GST at appropriate rate on the said upfront Payment, and the applicant intends to construct its factory on this leased land and use it for its manufacturing activities.

With above facts, the applicant has sought advance ruling as to;

“1. Whether they can claim refund/claim ITC of GST paid/payable on the upfront payment of lease amount to Eldeco Sidcul Industrial Park Limited?”

The ld. AAR, after examining scheme of section 97(2) observed that seeking a ruling on the issue of refund of ITC of tax paid by an applicant is not within the purview of Section 97(2) of the Act and, therefore, the Authority has no jurisdiction to pronounce a ruling thereon.

However, the ld. AAR entertained the issue of admissibility of ITC on the tax paid on the upfront payment for securing the lease of an industrial plot.

In this respect, the ld. AAR referred to section 17(5)(d) and reproduced the same in AR.

The ld. AAR also made reference to rulings of other coordinate authorities and appeal orders passed by the ld. AAAR.

The ld. AAR observed as under:

“8. We find that in the present case too, as in the case of M/s Agratas Energy Storage Solutions Pvt. Ltd., the applicant intends to construct his factory building on the land secured on long term lease from M/s ESIPL. In the light of the provisions of Section 17(5)(d) of the CGST Act we are of the opinion that the ITC is blocked in respect of goods and services used in construction of immovable property, except plant and machinery. The Explanation appended to Section 17 clearly excludes land, building or any other civil structure from the purview of “Plant and Machinery”. Thus, the intended use of the land is not the construction of any plant and machinery. Therefore, we are of the opinion that the applicant would not be eligible for availing ITC of GST charged by M/s ESIPL on upfront payment of lease amount.”

Accordingly, the ld. AAR held that ITC is not eligible on GST paid on the upfront lease amount.

29. S. K. Swamy & Co. (AAR Order No. KAR.ADRG/42/2026 dt.29.7.2026)(Kar)

Classification – Once supply of goods is completed, subsequent supply of services on the same goods is liable to tax separately.

The applicant is engaged in executing works contracts for Indian Railways, such as construction of Rail under bridge, construction of tunnels and supplying and stacking of ballast, earthwork, and also subcontracting of all the above-mentioned works.

The applicant has following question:

“i. What is the output GST rate for loading of ballast which is stacked adjacent to the railway tracks into the railway wagons which is stationed on the railway track by using JCB loader (Machinery)?”

The ld. AAR observed that the issue for determination is whether the activity of loading ballast, stacked adjacent to the railway track, into railway wagons/hoppers placed on the track through deployment of a JCB loader (machinery), where the same contract also includes supply of ballast, is liable to be treated as an independent supply of service, or a composite supply with supply of ballast as the principal supply, or a works contract service under the provisions of the CGST Act, 2017.

The ld. AAR observed that the scope of work primarily comprises the supply of ballast and the loading of such ballast into railway wagons stationed on the railway track through deployment of a JCB loader. It does not involve any activity in the nature of building, construction, fabrication, erection, installation, fitting out, improvement, modification, repair, maintenance, renovation, alteration or commissioning in relation to any immovable property. Therefore, it is not a works contract.

The ld. AAR also examined the possibility of composite supply under Section 2(30) of the CGST Act, 2017, for which the following essential conditions must be satisfied:

“(i) There must be two or more taxable supplies;

(ii) Such supplies must be naturally bundled and supplied in conjunction with each other in the ordinary course of business; and

(iii) One of the supplies must constitute the principal supply.”

The ld. AAR observed that the letter of Acceptance (LoA) separately specifies the quantities and corresponding rates for each item of work to be executed by the applicant, which are as follows:

(a) Supply of ballast at Railway depot or nominated location; and

(b) Loading of Railway’s ballast collected at yard/depot into Railway wagons using a Mechanical Loader or any other method with all lead and lifts, as directed by the Engineer in Charge.

The ld. AAR observed that the applicant first supplies the ballast to the Railways at the designated location and raises a tax invoice for such supply. Upon delivery and unloading at the designated location, the ownership of the ballast is transferred to the Railways. Thereafter, the applicant is neither responsible for the custody of the ballast, nor liable for any loss, damage, or theft thereof.

Accordingly, the ld. AAR held that each activity is executed separately, is supported by separate consideration, and is invoiced independently. The supply of ballast is complete upon its delivery at the designated location and is not dependent upon the subsequent loading activity. Similarly, the loading of ballast into railway wagons does not alter the nature or character of the completed supply of goods. Therefore, both activities are distinct and independently identifiable supplies and are not composite supply.

Therefore, the ld. AAR held that the supply of ballast is separate transaction of supply of goods, liable to tax accordingly. The ld. AAR further held that the loading activity is also separate and liable to tax under SAC-996719 – ‘Other cargo and baggage handling services’ falling under Heading 9967 ‘Supporting services in transport’ and is liable to GST at the applicable rate of 18%.

30. Rashmiben Sanjaykumar Hemani (Trade Name: Galaxe Prints) (AAR Order No. GUJ/GAAR/R/2026/29 (in Appl. No. Advance Ruling/SGST&CGST/2026/AR/08) dt.4.8.2026)(Guj)

Classification of Services and applicable GST rate – Job Work Services

The applicant is engaged in providing offset printing services on Kraft Paper and Duplex Paper and carries out the said activity strictly on job work basis as defined under Section 2(68) of the CGST Act, 2017.

The applicant has submitted that Kraft paper sheets and Duplex papers are supplied by packaging industries/corrugated box manufacturers, the Principal, to the applicant, under delivery challan for the purpose of offset printing, in accordance with precise specifications, designs and instructions provided by the Principal. Upon completion of offset printing, the processed Kraft paper sheets and Duplex paper are returned to the Principal for further processing. At no point in time does the ownership in goods pass to the applicant and the title, risk and ownership of goods always remains with the Principal.

The applicant has sought Advance Ruling on the following questions:

“(1) Whether GST rate of @5% or 18% is applicable on the job work services of offset printing provided by the applicant on Kraft Paper and Duplex Paper supplied by the Corrugated box manufacturer/Packaging Industries w.e.f. 22.09.2025, in terms of Notification No.15/2025-Central Tax (Rate) dated 17.09.2025?

(2) Whether paper cutting charges, paper sheet loading charges, bundle unloading charges and plate charges shown separately on Sale invoice, are ancillary to and form part of the principal supply of printing services, and whether the same GST rate applicable to printing service would apply to such charges?”

The ld. AAR observed as under in respect of nature of activity.

“On going through the various activities/supplies covering the supply of services provided and shown in a sequence by the applicant in their submission, we find that the entire sequence of activities/supplies which start with the cutting of paper into the required sheet size from the paper reel followed by sorting and stacking of such cut sheets followed by plate making/plate mounting and offset printing followed by drying/curing of printed sheets, varnish/lamination process, quality check and colour matching, bundling/packing of printed sheets and returning back the bundled/packed printed sheets to the principal manufacturer indicates that they are all interconnected with each other and can be stated to be “naturally bundled” and supplied in conjunction with each other in the ordinary course of business. We also find that activity of offset printing is the main supply and all the other supplies carried out pre-offset printing and post-offset printing, can be considered as supporting the main activity/supply of offset printing i.e. the said activities/supplies can be considered as ancillary to the supply of offset printing. We, therefore, find that the supply of services provided by the applicant will indisputably fall under the definition of “composite supply” where offset printing is the “principal supply”. Further, since the type of supply of the job work services provided by the applicant has already been identified as a “composite supply”, the need to refer to the definition of “mixed supply” does not arise.”

The ld. AAR also observed that the job work services carried out by the applicant which is a “composite supply”, fall under Sr.No.26, Heading 9988 “Manufacturing services on physical inputs (goods) owned by others”. Further, since ‘offset printing’ is the principal supply in the aforementioned composite supply, the GST rate applicable on offset printing would be the rate applicable to the said composite supply under entry Sr.no.26 of Notification No.11/2017-Central Tax (Rate) dated 28.06.2017.

Since the kraft paper and duplex paper are taxed @ 18% under Notification No.09/2025-Central Tax (Rate) dated 17.09.2025, the ld. AAR held that the rate of tax on offset printing activity will be under entry no.26(iv) of Notification No.11/2017-Central Tax (Rate) dated 28.06.2017 and rate will be 18%.

Section 16(2)(C) Of The CGST Act

यथा मधु समादत्ते रक्षन् पुष्पाणि षट्पदः। तद्वदर्थान्मनुष्येभ्यः आदद्यादविहिंसया॥

“As the bee gathers honey from the flower without harming its fragrance or its bloom,

so should the king gather wealth from his subjects without causing them injury.”

Kautilya, Arthashastra, Book II

Section 16(2)(c) of the CGST Act conditions Input Tax Credit (ITC) on the supplier’s actual tax payment to the Government. Courts, including the Gujarat High Court in Maruti Enterprise, view ITC as a statutory concession rather than a vested right, necessitating strict compliance. While the Supreme Court’s dismissal in Bhandari Scrap Traders affirmed this, legal debates persist regarding the “impossibility” of recipients verifying supplier payments. Taxpayers face significant risks from supplier defaults and retrospective registration cancellations. Recommended safeguards include invoice-level reconciliation, proactive supplier monitoring, and withholding tax payments until deposit proof is furnished.

INTRODUCTION

Kautilya’s counsel that revenue must be gathered as the bee gathers honey without wounding the flower it draws from is as old as the discipline of public finance itself. The interpretation of section 16 (2) (c) of CGST Act, 2017 as canvassed by the Hon’ble Gujarat High Court in Maruti Enterprise vs. Union of India [(2026) 42 Centax 256 (Guj.)], the SLP against which was dismissed by the Hon’ble Supreme Court in Bhandari Scrap Traders vs. Union of India [(2026) 44 Centax 356 (S.C.)] may require assistance from this principle.

Section 16(2)(c) of the CGST Act, 2017 restricts Input Tax Credit (ITC) to a registered recipient unless the tax charged on the relevant supply has been paid to the Government by the supplier. The recipient ordinarily has no means of compelling or verifying such payment resulting in sustained litigation since 2017, with materially different outcomes depending on the facts of the individual mismatch and the jurisdiction in which it arose. This article traces the issue from first principles, the legal character of ITC itself, the statutory conditions, the department’s enforcement practice, the difficulties it creates for taxpayers and the judicial precedents up to now.

INPUT TAX CREDIT – A RIGHT OR A CONCESSION

The starting point for any analysis of Section 16(2)(c) is the legal character of ITC itself. When GST was introduced, it was marketed to trade and industry on the promise of a “seamless” flow of credit across the supply chain, intended to eliminate the cascading effect of the erstwhile indirect tax regime. That promise, however, did not translate into an enforceable entitlement. The Constitution contains no reference to ITC or to any right to claim it; the entitlement exists only to the extent, and in the form, that the CGST Act itself creates it. Courts have, accordingly, treated the “seamless credit” assurance as a policy aspiration rather than a justiciable right.

It is now a settled law1 that ITC is not a vested or fundamental right, but a statutory concession – available to a taxpayer only to the extent, and subject to the conditions, that the legislature has chosen to allow. In ALD Automotive, examining an analogous credit mechanism under VAT law, the Court held that input credit is “in the nature of a benefit/concession extended to a dealer under the statutory scheme,” and that “the concession can be received by the beneficiary only as per the scheme of the statute.” The Court went on to hold that whenever a concession is granted by statute or notification, its conditions must be strictly complied with in order to avail it – a dealer has no independent right to the benefit outside the four corners of the provision granting it.


1 ALD Automotive Private Limited vs. Commercial Tax Officer, (2019) 13 SCC 225

On the specific question of when a harsh statutory condition may be read down to relieve hardship, the Supreme Court in Authorised Officer, Central Bank of India vs. Shanmugavelu, (2024) 6 SCC 641 held that “harshness of a provision is no reason to read down the same, if its plain meaning is unambiguous and perfectly valid” – reading down is a tool to preserve constitutionality where a provision would otherwise fail, not a general remedy for hardship in an otherwise valid and unambiguous provision.

The above decisions highlight that ITC is a concession, its conditions including Section 16(2)(c) must be interpreted strictly and literally, equitable considerations do not enter the analysis, and hardship alone does not justify reading a clear provision down.

The GST Empty Cup Dilemma Protecting your Input Tax Credit

EVOLUTION OF PROVISIONS UNDER GST

Section 16(1) establishes the basic entitlement: a registered person may take credit of input tax charged on a supply used or intended to be used in the course or furtherance of business. Section 16(2) then prescribes cumulative conditions without which that entitlement cannot be exercised, and these conditions have themselves changed materially over time.

At inception, Section 16(2) prescribed four conditions, still in force today:

(a) he is in possession of a tax invoice or debit note issued by a supplier registered under this Act…

(b) he has received the goods or services or both…

(c) subject to the provisions of section 41 [or section 43A], the tax charged in respect of such supply has been actually paid to the Government, either in cash or through utilisation of input tax credit admissible in respect of the said supply; and

(d) he has furnished the return under section 39.”

These conditions operated alongside the original Section 41, which permitted credit “as self-assessed” on a provisional basis, and Section 42, which provided for matching between the recipient’s and supplier’s returns. Both GSTR-2 (the recipient’s return, meant to enable that matching) and GSTR-3 (the consolidated return) were suspended within months of commencement, leaving taxpayers to self-assess through GSTR-3B alone, without any live verification mechanism. The consequence of this gap was addressed by the Supreme Court in Union of India vs. Bharti Airtel Ltd. [2021 (54) G.S.T.L. 257 (S.C.)], discussed in detail later in this article, which held that the taxpayer’s obligation to self-assess correctly was not diminished merely because the Government’s own verification infrastructure was not yet functional.

In the absence of the statutory matching process, Rule 36(4) was introduced to cap ITC claimed on invoices not uploaded by the supplier at a percentage of matched credit – 20% from October 2019, reducing to 10% through 2020, and to 5% through 2021. The original non-operational scheme of provisional self-assessed credit and portal driven matching vide Sections 41 and 42 continued to exist simultaneously, though non-operational. It therefore is evident that for the duration of this Rule, a taxpayer was not required, and had no means, to restrict its claims to matched invoices alone; a defined buffer of unmatched credit was expressly permitted.

Section 16(2)(aa) added a fifth condition w.e.f. 01.01.2022:

the details of the invoice must have been furnished by the supplier in its outward-supply statement and communicated to the recipient.

This converted digital matching from Rule 36(4)’s tolerant buffer into an absolute precondition, independent of clause (c)’s payment requirement.

Soon thereafter, w.e.f. 01.10.2022, Section 38 was substituted to generate FORM GSTR-2B automatically, flagging credit as available or restricted. A sixth condition, clause (ba), was added: credit communicated as “restricted” under Section 38 cannot be claimed. Section 41 was then substituted in its entirety w.e.f. 01.10.2022:

“Where credit of input tax has been availed by a registered person in respect of a supply, but the tax payable thereon has not been paid by the supplier, such credit availed shall be reversed along with applicable interest… Provided that where the said tax is subsequently paid by the said supplier, the registered person shall be entitled to re-avail the amount of credit so reversed.”

Sections 42 and 43 – the original, never-operational matching provisions – were thus formally omitted w.e.f. 01.10.2022.

Rule 37A operationalised the new Section 41(2): where a supplier has not filed GSTR-3B by 30 September of the following financial year, the recipient must reverse the corresponding credit by 30 November to avoid interest, and may re-avail it once the supplier subsequently pays.

As a further taxpayer facilitation, the Invoice Management System was introduced on the portal w.e.f. 01.10.2024. IMS allows the recipient to Accept, Reject, or mark Pending each inward supply, with only Accepted invoices flowing into the GSTR-3B credit claim – the first point at which the recipient exercises active control over the matching process rather than passively receiving its output.

One may observe as a summary that under the current regime, a taxpayer must satisfy six cumulative conditions – clauses (a), (aa), (b), (ba), (c), and (d) – read together, before ITC can be claimed and retained. Four of these six did not exist, in their present form, before October 2022.

INTERPRETATION FROM THE DEPARTMENT’S LENS

The conditions set out above are enforced, in practice, through a combination of automated data-matching and a burden of proof placed squarely on the claimant, underpinned by a rationale the Department itself has articulated in fairly simple terms.

The “empty cup” rationale – The department’s justification for Section 16(2)(c) is not, at its core, a technical one – it is essentially fiscal common sense from the exchequer’s point of view. The Government’s position is that it cannot “pour from an empty cup”: it cannot extend a credit to a recipient against tax it has never actually received from the supplier, regardless of what passed between the recipient and the supplier privately. Whatever hardship this creates for the recipient is treated, from the Department’s side, as a consequence of a risk the recipient chose to take when it transacted with that particular supplier, not a risk the exchequer should absorb. This rationale explains why the Department has been largely unmoved by “blind spot” arguments – the recipient’s inability to see or control whether its vendor actually remitted the tax collected – and why the burden of proof, discussed below, has consistently been placed on the recipient rather than shared with, or shifted first to, the Department.

Automated matching as the first filter – The Department’s primary enforcement tool is the comparison between the credit claimed in a taxpayer’s GSTR-3B and the credit reflected in its auto-generated GSTR-2A/2B, built entirely from the supplier’s own filings. Any variance between the two typically triggers a scrutiny notice – commonly in FORM ASMT-10 or as a pre-consultation intimation in FORM DRC-01A – calling upon the taxpayer to explain or reverse the difference.

Circular-based relief for documented, misclassified payment – Recognising that not every mismatch reflects genuine non-payment, the CBIC issued Circular No. 183/15/2022-GST (in respect of FY 2017-18 and 2018-19) and Circular No. 193/05/2023-GST (extending the same relief to FY 2019-20 and 2020-21). These circulars permit a taxpayer to reconcile a GSTR-3B/GSTR-2A variance – for example, where a supplier mistakenly reported a B2B supply as B2C – by producing a certificate from the supplier’s chartered accountant or cost accountant confirming that the supply was made and the tax was in fact paid, in lieu of a corrected GSTR-1. Where the variance is below a specified monetary threshold, a self-certification by the supplier may suffice; above it, the CA/CMA certificate is treated as mandatory.

The burden of proof standard the department applies – Section 155 of the CGST Act places the burden of proving eligibility for ITC on the person claiming it. The Department, relying on the Supreme Court’s decision in State of Karnataka vs. Ecom Gill Coffee Trading Pvt. Ltd., (2023) 18 SCC 809 (discussed later), routinely takes the position that this burden is not discharged merely by producing a tax invoice and evidence of payment through banking channels. In practice, officers now expect a taxpayer to additionally substantiate the genuineness of the underlying transaction – delivery challans, e-way bills, transporter records (goods receipts, lorry numbers, weighment slips), correspondence with the supplier, and the entry of the transaction in the taxpayer’s own stock and accounting records – treating the invoice and payment trail as necessary but not sufficient.

The practical asymmetry this creates – Where an invoice is missing from GSTR-2A/2B or the supplier has not filed GSTR-3B, the Department’s working assumption is typically that the recipient must first prove entitlement affirmatively – including, in many cases, being expected to demonstrate that it exercised some due diligence in transacting with the supplier – rather than the department first pursuing the supplier for the unpaid tax. This is the enforcement posture that several of the judicial precedents discussed later have pushed back against, holding that recovery against the supplier should ordinarily precede reversal of the recipient’s credit; whether that judicial preference has altered the department’s actual practice is a separate question.

CHALLENGES FACED BY TAXPAYERS

Set against the conditions and the enforcement practice outlined above, taxpayers face different scenarios, each carrying a different practical difficulty. Some common scenarios are explained below:

  1.  Invoice missing from GSTR-2A because the supplier filed it as B2C rather than B2B, but did pay the tax; a CA/CMA certificate has been obtained. The taxpayer’s difficulty here is procedural rather than substantive – the tax reached the Government, but proving this requires the taxpayer to obtain the supplier’s cooperation in procuring a CA certificate, which is not always forthcoming.
  2.  Same facts as Scenario 1, but no certificate has yet been obtained. The underlying transaction is clean; the difficulty is purely one of timing and cooperation from the supplier’s professional advisers. One may be able to actually demonstrate that the supplier has regularly filed and continues to file his returns in GSTR3B.
  3.  Invoice correctly reflected in GSTR-2A, but the supplier has not filed GSTR-3B. Every portal-visible check under clauses (a), (aa), and (b) is satisfied; only clause (c)’s payment condition fails, for a reason entirely outside the recipient’s control.
  4.  Invoice reflected in GSTR-2A, but the supplier filed a nil GSTR-3B. This variant is harder to distinguish, at the time of transacting, from genuine supplier distress on the one hand and deliberate evasion on the other – the recipient has no way of telling the two apart in advance.
  5.  Invoice missing from GSTR-2A, and the supplier has not filed GSTR-3B at all. No disclosure and no payment exist on record. This is the scenario in which the Department’s asymmetric enforcement posture is felt most acutely.
  6.  Supplier’s registration cancelled – prospectively or retrospectively – on the supplier’s own application. In these cases, it is the supplier who approaches the Department for cancellation, and the Proper Officer, after examining the particulars, cancels the registration. Even here, the authorities have frequently gone back to the past outward supply transactions of such suppliers and questioned the recipient’s ITC eligibility, even where the supplier had in fact paid the tax on those very transactions – a fact duly verified by the department at the time of processing the cancellation itself.
  7. Supplier’s registration cancelled by the Department, of its own motion (suo motu). This is the more troubling variant, and it arises in two distinct forms. Where the cancellation is prospective, the period of the disputed transaction is, in principle, left untouched, though recipients still frequently face scrutiny. Where the cancellation is retrospective – and this is the more common source of dispute – a supplier who disclosed a supply, filed GSTR-1, and even paid tax through GSTR-3B, may nonetheless have its registration cancelled years later, for reasons that are rarely made available to the recipient, and often without effective notice to a supplier who has by then become uncontactable. The recipient is left to answer for a decision taken between the Department and a third party, in which it had no part and no warning.
  8. Supplier errors, such as an invoice bearing the wrong GSTIN, wrong POS, etc. There could be instances where the supplier, while dealing with a multi-registration entity, reports an invoice against the incorrect GSTIN while the recipient claims it under the correct GSTIN, resulting in a mismatch for the recipient. Similarly, in some cases, the supplier selects reverse charge as applicable though the invoice was actually issued under forward charge. In such cases, despite the supplier having paid GST, the recipient ends up facing scrutiny and litigation.

A further, structural challenge: the Rule 36(4) period. Beyond the above specific scenarios lies a distinct, period-specific difficulty, and one that engages the doctrine of lex non cogit ad impossibilia – discussed in its general form, as argued before and rejected by the Gujarat High Court – in a narrower and more precise sense than the Court actually considered. Between 09.10.2019 and 31.12.2021, Rule 36(4) expressly permitted taxpayers to claim a defined percentage of unmatched credit, while the framework of that period gave the recipient no means of verifying whether the supplier had actually paid the tax on any given invoice – clause (aa) did not yet exist, GSTR-2B in its current form did not exist, and Rule 37A’s reversal-and-re-availment mechanism did not exist. A taxpayer transacting during this window was not merely permitted but structurally invited by the Rules to claim unmatched credit, with no tool available to distinguish, in advance, a genuine unmatched invoice from one that would later prove to involve a defaulting supplier, and no contractual indemnity clause capable of curing the underlying problem, for the reasons given in Part 6. Any demand raised today for reversal of ITC availed within the Rule 36(4) buffer, where the demand rests on a supplier’s subsequent default, arguably asks the taxpayer to have done something the law neither required nor enabled it to do at the relevant time – the precise circumstance the maxim addresses, and one the Gujarat High Court’s general rejection of the doctrine, resting as it does on Rule 37A and contractual indemnity, does not actually reach.

JUDICIAL PRECEDENTS BEFORE MARUTI ENTERPRISE AND BHANDARI SCRAP TRADERS

The case law preceding these two decisions divides broadly into two lines:.

The self-assessment line – In Union of India vs. Bharti Airtel Ltd. [2021 (54) G.S.T.L. 257 (S.C.)], the Supreme Court held, in the context of GSTR-3B rectification during the period GSTR-2/GSTR-3 were non-operational, that the taxpayer’s obligation to self-assess correctly is not excused by gaps in the Government’s own verification infrastructure. This is not a decision about supplier default, but its underlying principle – that the taxpayer bears the risk of imperfect verification tools – recurs throughout the later cases.

The Delhi VAT line, and its extension to GST – In On Quest Merchandising India (P) Ltd. vs. Government of NCT of Delhi, [2018] 10 GSTL 182 (Del), the Delhi High Court read down Section 9(2)(g) of the Delhi VAT Act, 2004, holding that a bona fide purchasing dealer could not be denied credit merely because the selling dealer failed to deposit tax, since the purchaser had no means of verifying or compelling the supplier to pay the taxes. This decision was followed in Shanti Kiran India (P) Ltd. [(2025) 35 Centax 222 (S.C.)] and Arise India Limited [2022 (60) G.S.T.L. 215 (S.C.)], and the Supreme Court subsequently dismissed the Revenue’s special leave petitions against these decisions. The Karnataka High Court applied similar reasoning to Section 70 of the KVAT Act in Tallam Apparels, 2021 SCC OnLine Kar 15785. This entire line was confined to VAT statutes, under which credit, once availed, did not travel beyond the originating State. The extension of this principle to the CGST Act was attempted, and succeeded, in the Tripura High Court’s decision in M/s Sahil Enterprises vs. Union of India [2026-VIL-15-TRI], which read down Section 16(2)(c) itself on the same reasoning.

The burden-of-proof correction – The VAT line was significantly narrowed by the Supreme Court’s decision in State of Karnataka vs. Ecom Gill Coffee Trading Pvt. Ltd., (2023) 18 SCC 809. The Court, highlighting that the burden of proof issue had not been before the Delhi High Court in On Quest Merchandising, distinguished that decision and held that the burden of proving ITC eligibility lies squarely on the claimant, and is not discharged merely by producing a tax invoice or proof of payment through banking channels; the claimant must additionally establish the genuineness of the transaction, including the physical movement of goods.

The purchaser-protective line under GST – Under GST, several High Courts developed a purchaser-protective position under the CGST Act itself, holding that recovery against a defaulting supplier should ordinarily be attempted before the recipient’s credit is disturbed. In M/s D.Y. Beathel Enterprises vs. State Tax Officer [2021-VIL-308-MAD], the Madras High Court quashed a demand against the recipient without the Department having first pursued the supplier, who had collected the tax and not remitted it. In Suncraft Energy Private Limited vs. Assistant Commissioner, State Tax [2023-VIL-487-CAL], the Calcutta High Court reached the same conclusion; the Revenue’s SLP against this decision was dismissed by the Supreme Court in December 2023.

The registration-cancellation line – A further, distinct body of case law addressed the effect of a supplier’s registration being canceled after the disputed transaction, and it distinguishes prospective from retrospective cancellation. On prospective suo motu cancellation, the Allahabad High Court has been consistent: in M/s Singhal Iron Traders vs. Additional Commissioner [2025-VIL-1124-ALH] and M/s Solvi Enterprises vs. Additional Commissioner [2025-VIL-270-ALH], the Court held that no adverse inference arises against the purchaser merely because the supplier’s registration was cancelled after the transaction, where tax was paid and returns were filed at the relevant time. On retrospective cancellation, the case law is more protective of the recipient. In LGW Industries Ltd. vs. Union of India [(2023) 4 Centax 373 (Cal.)], the Court held that a recipient who exercised due diligence at the time of transacting – verifying the supplier’s registration as it then stood, supported by invoices, e-way bills, and banking-channel payment – should not be denied credit solely because of a subsequent cancellation. M/s Gargo Traders vs. Joint Commissioner [2023-VIL-360-CAL] and Shyamalmay Paul vs. Assistant Commissioner [2025-VIL-1315-CAL] both held that retrospective cancellation is not, by itself, a valid ground for denial, and that the authorities must independently verify the physical movement of goods and the banking trail.

By the time Maruti Enterprise came to be decided, the field contained at least three distinguishable threads of precedents:

  • a VAT-derived reading-down position, significantly narrowed by Ecom Gill Coffee Trading;
  • a GST-specific, sequencing-based position requiring recovery against the supplier first; and
  • a registration-cancellation-specific position requiring inquiry beyond the fact of cancellation.

It is against this backdrop that the Gujarat High Court’s judgment has to be read.

WHAT MARUTI ENTERPRISE HELD

Maruti Enterprise dealt with a batch of petitions challenging the vires of Section 16(2)(c) as arbitrary, ultra vires, and violative of Articles 14, 19(1)(g), 265, and 300A, or seeking to read it down to exclude bona fide purchasers. While dismissing the challenge, the Court’s reasoning proceeded in several steps.

  • First, it treated ITC as a statutory concession rather than a vested right, relying on ALD Automotive, and held that its conditions must be interpreted literally rather than equitably.
  • Second, it held that Section 16(2)’s conditions – clauses (a) through (d), on the Court’s own recitation of the text – must be read conjointly, and that the Revenue could not be required to stop its inquiry at clause (b) once genuineness appeared satisfied; clause (c)’s payment condition was equally part of the composite test.
  • Third, and centrally, the Court held that Section 41(2) and Rule 37A cure whatever hardship the provision might otherwise create, since credit denied for a supplier’s default is not permanently lost but merely deferred, to be re-availed once the supplier eventually pays – a mechanism the Court held had no equivalent under the Delhi VAT Act considered in On Quest Merchandising.
  • Fourth, the Court placed weight on Section 155’s burden-of-proof provision, holding that it is for the purchasing dealer to prove that tax collected has in fact been remitted, and adopted the Supreme Court’s holding in Ecom Gill Coffee Trading on this point.
  • Fifth, the Court declined to follow the Tripura High Court’s decision in Sahil Enterprises, holding that it had proceeded on the On Quest Merchandising reasoning without adequately considering the interplay of Sections 41 and 42 read with Rule 37A.

The Court accordingly declined to read down or strike down Section 16(2)(c), while nonetheless recording, in its concluding paragraphs, that the Government ought to undertake a “comprehensive re-evaluation” of the position of genuine purchasers and consider a more robust, technology-driven verification mechanism. The individual writ petitions were remanded for decision on their own facts, with the question of vires alone having been finally determined.

THE DOCTRINE OF LEX NON COGIT AD IMPOSSIBILIA

A distinct strand of the petitioners’ argument, separate from the Article 14/19(1)(g) constitutional challenge, invoked the maxim lex non cogit ad impossibilia – the law does not compel a person to do that which is impossible to perform – which the petitioners submitted was closely connected to the related maxim impotentia excusat legem (a disability that makes it impossible to obey the law can be excused).

The submission was that Section 16(2)(c) mandates the purchaser to do something beyond its control – namely, ensure that a third party, the supplier, remits tax to the Government – and that the provision should accordingly be declared ultra vires or read down. In support, the petitioners relied on the judgment of the Court of Justice of the European Union in Axel Kittel vs. Belgian State and Belgian State vs. Recolta Recycling SPRL (06.07.2006), which held that VAT deduction can be denied where a participant knew or should have known of fraud, but not where the taxable person neither knew nor could have known that the transaction was connected with fraud committed by the seller.

The Gujarat High Court rejected this submission. It held that the maxim, whatever its general force, “does not strictly attract” the scheme of the GST regime, because Section 41 read with Rule 37A ensures that purchasers are “not unfairly penalized for a supplier’s default” – credit is deferred, not permanently lost, and is restored once the supplier eventually pays. The Court went further, holding that the purchaser is not entirely without means of managing the risk: because the GST regime operates on a contract between two private parties, a purchaser can, at the time of entering into the agreement, include a clause holding the supplier liable to indemnify the purchaser for any loss arising from the supplier’s failure to remit the tax collected.

This reasoning is open to a specific objection that the judgment does not address. An indemnity clause reallocates commercial risk between the purchaser and the supplier as a matter of private contract; it does nothing to make it possible for the purchaser to ensure that the tax actually reaches the Government, which is the act Section 16(2)(c) conditions credit upon. Where the supplier is insolvent, untraceable, or deceased, an indemnity clause is, in practical terms, worthless, since there is no one left to enforce it against. The Court’s answer to the impossibility argument therefore substitutes a private remedy against the wrong party (the supplier, who is often the very source of the difficulty) for the actual impossibility the petitioners identified – the purchaser’s inability to compel or verify payment to the Government. Nor does the Rule 37A safety valve the Court otherwise relies on assist a purchaser whose transaction predates 26.12.2022, since the rule did not exist at the relevant time; the Court’s rejection of the impossibility argument is accordingly strongest for the post-Rule 37A period and weakest for transactions before it, including the entirety of the Rule 36(4) period.

HOW BHANDARI SCRAP TRADERS CONFIRMED IT

The special leave petitions filed against Maruti Enterprise came up for hearing before a two-judge Bench of the Supreme Court on 24.07.2026. The Bench noted that a separate special leave petition against the Tripura High Court’s decision in Sahil Enterprises had been entertained, but observed that the exercise the Gujarat High Court had undertaken – the detailed analysis, from paragraph 42 onwards, of the distinction between the Delhi VAT Act and the CGST Act, together with the scheme of ITC availment set out at paragraph 56 of the impugned judgment – had not been undertaken by the Tripura High Court. The Bench further noted the Gujarat High Court’s reliance on Sections 41, 73, and 74 of the CGST Act in holding that a purchasing dealer under the CGST regime is entitled to re-avail reversed ITC once the supplier discharges the tax liability, a feature the Bench treated as distinguishing the CGST scheme from the Delhi VAT Act’s provisions.

On this basis, the Bench recorded that it found itself “in complete and respectful agreement with the views expressed by the High Court of Gujarat,” affirmed and upheld the impugned judgment, and dismissed the special leave petitions.

IS BHANDARI SCRAP TRADERS THE LAW OF THE LAND?

The answer requires two separate inquiries, not one. The first is the familiar Kunhayammed question – was the dismissal speaking or non-speaking? The second, and the more consequential one on a closer reading of the order, is whether what the Supreme Court actually wrote, even assuming it counts as a speaking order, discloses a ratio decidendi at all, as opposed to a bare conclusion dressed in the language of agreement.

The Supreme Court’s own three-judge bench decision in Kunhayammed v. State of Kerala, (2000) 6 SCC 359, holds that a non-speaking dismissal of a special leave petition attracts no Article 141 effect and produces no merger of the High Court judgment. A speaking dismissal – one giving reasons that engage the substance of the legal question – attracts Article 141, but only to the extent of what is actually reasoned, and still without merger, since leave was never granted. Only where leave is granted and the matter proceeds to disposal as a civil appeal does the High Court judgment merge fully into the Supreme Court’s decision, with Article 141 applying without qualification.

Where Bhandari Scrap Traders falls on this first test. No leave was granted; there is no merger, and Maruti Enterprise remains, formally, a High Court judgment. At first blush, the order appears to clear the second Kunhayammed category – it distinguishes Sahil Enterprises by name, refers to specific paragraphs of the judgment below, and states express agreement with the Gujarat High Court’s reasoning on the DVAT/CGST distinction.

But a closer reading raises a more fundamental difficulty. It is not enough, for a decision to constitute “law declared” under Article 141, that the Supreme Court reaches a conclusion and gestures at the judgment it is affirming. The Supreme Court has itself drawn this distinction. In Secunderabad Club vs. CIT, 2023 INSC 736, it held that a decision binds not because of its conclusion, but because of the principle underlying it – an order unsupported by any deduction, reasoning, or analysis cannot carry precedential value merely because it arrives at a result.

The point was developed further, on facts strikingly close to those here, in Jayant Verma vs. Union of India, (2018) 4 SCC 743. There, the Supreme Court examined an earlier, cryptic order that had reversed a detailed High Court judgment (striking down Section 21A of the Banking Regulation Act) after hearing only one side. It held that where a decision contains no reasoning worth the name, does not engage with the authorities relied upon by the court below, and is arrived at on an ex parte appraisal, it would be hazardous to treat that decision as a declaration of law under Article 141. A bare conclusion, reached without discussion of the relevant statutory provisions or the case law on the point, does not by itself create binding precedent – however firmly the conclusion is stated.

Testing Bhandari Scrap Traders against this standard. The SLP was dismissed at the threshold, without notice to the Union of India as respondent. The order agrees with the Gujarat High Court’s conclusion, but it does not independently formulate the constitutional tests applicable to an Article 14 or Article 19(1)(g) challenge to a taxing provision, does not work through those tests against Section 16(2)(c) on its own terms, and does not offer a distinct line of reasoning of its own explaining why the provision survives constitutional scrutiny. What the order principally does is note that the Delhi VAT Act and the CGST Act are not comparable enactments. But the absence of parity between two statutes is not a constitutional test for validity; it explains why one precedent does not automatically transpose to another statute, but it does not itself demonstrate that Section 16(2)(c) is non-arbitrary, proportionate, or otherwise constitutionally sound. A reference to selected paragraphs of the judgment under challenge, without an independent working-through of the constitutional question, does not disclose a distinct ratio of the Supreme Court.

The parallel to Jayant Verma is closer still on the question of process. The Tripura High Court’s contrary view in Sahil Enterprises was, in substance, reversed without the respondent in that matter being heard, and without the Supreme Court examining the detailed reasoning that had led the Tripura High Court to read down Section 16(2)(c) in the first place. The contrary decisions of the Gauhati and Karnataka High Courts, both relied upon by the Maruti Enterprise petitioners and noted in Part 5 above, do not feature in the Supreme Court’s order at all.

An instructive comparison: the Suncraft Energy dismissal. The Revenue’s SLP against Suncraft Energy – the Calcutta High Court decision requiring recovery against the supplier before the recipient’s credit is disturbed – was also dismissed by the Supreme Court, in December 2023. That order records: “Having regard to the facts and circumstances of this case(s) and the extent of demand being on the lower side, we are not inclined to interfere in these matters in exercise of our powers under Article 136.” This is a dismissal on quantum, not one engaging the merits of the legal question, and falls within Kunhayammed’s first category rather than its second. On this analysis, the Suncraft dismissal – widely treated in practice as Supreme Court endorsement of the purchaser-protective position – does not itself attract Article 141 on the merits, notwithstanding its outcome. The comparison is instructive because it shows that a Supreme Court order can fail to bind for two quite different reasons: because it gives no reasons at all (Suncraft), or, as argued above, because the reasons it gives do not amount to an independent constitutional analysis (Bhandari Scrap Traders, on the Secunderabad Club/Jayant Verma standard).

A stronger comparison – Ecom Gill Coffee Trading. By contrast, State of Karnataka vs. Ecom Gill Coffee Trading Pvt. Ltd., (2023) 18 SCC 809, proceeded as a fully argued civil appeal with leave granted, placing it within Kunhayammed’s third category – full merger, unqualified Article 141 effect – and its reasoning independently works through the burden-of-proof question on its own terms, engaging the authorities on both sides. It is, the least qualified of the three Supreme Court pronouncements discussed, and it is the decision Maruti Enterprise itself relies on most directly for its Section 155 reasoning.

What follows. Two conclusions can be drawn, and they should not be mixed up. First, Bhandari Scrap Traders undoubtedly binds the parties before the Supreme Court in that proceeding, in the ordinary sense that any final order binds the parties to it. Second, and separately, whether the order amounts to “law declared” binding on High Courts and coordinate Benches of the Supreme Court under Article 141 is a materially harder question than its outcome suggests. Applying Secunderabad Club and Jayant Verma, there is a substantial argument that it does not: the order does not disclose the deduction, analysis, or independent constitutional reasoning those decisions require before a conclusion can be treated as a declaration of law, it was arrived at without notice to the Tripura High Court’s successful respondent, and it does not engage the contrary reasoning of the Gauhati or Karnataka High Courts at all.

If this view is correct, it would mean the gate remains open – not merely on the scenario-specific and period-specific points identified elsewhere in this article, but on the constitutional challenge to Section 16(2)(c) itself – for fresh examination before the High Courts, and for independent consideration by a coordinate Bench of the Supreme Court in an appropriate case, including on the DVAT-comparison ground that Bhandari Scrap Traders is, on its face, usually understood to have foreclosed.

A further point follows regardless of which view of the threshold question is correct. Even on the more generous reading of the order – that it does clear the Kunhayammed speaking-order threshold, and binds at least on the narrow DVAT/CGST proposition – it still does not touch the Gujarat High Court’s general rejection of the lex non cogit ad impossibilia argument or the specific points discussed above. The order confines itself to the DVAT/CGST distinction; it does not mention the impossibility doctrine, the Axel Kittel line the petitioners relied on, or the Court’s contractual-indemnity reasoning. On either view of the threshold question, therefore, the Gujarat High Court’s treatment of the impossibility doctrine remains, at present, a High Court finding only.

WAY FORWARD

For the individual writ petitions remanded under paragraph 90 of Maruti Enterprise. A uniform approach across the batched petitions is unlikely to be appropriate. Petitions falling within Scenarios 1 and 3 (documented, misclassified payment) are properly resolved administratively through Circular 183/193’s certification mechanism. Petitions falling within the retrospective suo motu cancellation variant of Scenario 7 warrant the inquiry into physical movement of goods and banking records required by Gargo Traders, Shyamalmay Paul, and LGW Industries. Petitions concerning credit availed within the Rule 36(4) buffer between 09.10.2019 and 31.12.2021 warrant a specific finding on whether the taxpayer could, at the relevant time, have done more than the Rules themselves required.

For the administration. Maruti Enterprise itself calls, at paragraph 88, for a “technology-driven tracking mechanism” to protect genuine purchasers. The Invoice Management System, in its current form, indicates only whether an invoice has been filed by the supplier, not whether the corresponding tax has been paid. Extending IMS to surface payment status at the point a recipient claims credit would meaningfully reduce the incidence of Scenarios 2, 4, and 5 without further litigation.

For future litigation. The conventional reading is that the DVAT-comparison route is closed under Article 141. However, the same is subject to serious challenge, since the order in Bhandari Scrap Traders arguably does not disclose the deduction, analysis, or independent constitutional reasoning that Secunderabad Club and Jayant Verma require before a dismissal can be treated as law declared under Article 141 – meaning a fresh challenge to Section 16(2)(c) remains available before a coordinate Bench in an appropriate case. Independently of that threshold question, and even on the more cautious assumption that the DVAT-comparison route is indeed closed, at least four further arguments remain open, none having been addressed by either Maruti Enterprise or Bhandari Scrap Traders on any reading of the order:

(i) a challenge confined to ITC availed within the Rule 36(4) buffer, engaging lex non cogit ad impossibilia in its precise sense;

(ii) a broader challenge confined to transactions preceding Rule 37A’s introduction in December 2022;

(iii) a challenge premised specifically on the relationship between clauses (aa)/(ba) and clause (c), rather than on Section 16(2)(c) in the abstract; and

(iv) a challenge arising from retrospective cancellation of a supplier’s registration, in respect of which the Calcutta High Court has already required the Department to look beyond the cancellation date to the underlying facts of the transaction.

Litigation confined to any of these grounds, rather than treating Bhandari Scrap Traders as having conclusively settled the field, has a materially better prospect of success than the position currently understood by most practitioners to follow from that decision.

For taxpayers, as a matter of ongoing compliance. Beyond litigation strategy, three practical changes are worth making irrespective of how any pending dispute is resolved. First, recipients should move away from comparing aggregate GSTR-2A/2B and GSTR-3B figures and instead perform invoice-level, transactional reconciliation – an aggregate comparison can mask exactly the kind of misclassification (Scenario 1) or clerical error (Scenario 8) that a certificate or a correction can resolve cheaply if caught early, but which hardens into a full-blown dispute once buried inside a larger, unreconciled variance. Second, recipients should actively track whether their significant suppliers are filing GSTR-3B on time, rather than discovering a default only when a notice arrives years later; several GST-compliance platforms now offer this as a standing feature rather than a one-time reconciliation exercise. Third, and most significantly, the contractual protection the Gujarat High Court gestured toward in Maruti Enterprise – an indemnity clause against the supplier, addressed critically in Part 6 above – is, at best, a remedy of last resort, since it is only as good as the supplier’s continued solvency and traceability. A more robust contractual protection is to withhold a portion of the payment due to the supplier, contractually, until the supplier furnishes proof that the tax component has actually been deposited with the Government – shifting the risk upstream, before payment leaves the recipient’s hands, rather than attempting to recover it downstream from a supplier who may by then be unable to pay either the tax or the indemnity.

Rebate and Capital Gains

The eligibility of Indian residents to claim a Section 87A tax rebate against capital gains taxed at special rates under Sections 111A and 112 remains controversial. While Section 112A explicitly prohibits the rebate, no such text-based restriction exists for Sections 111A or 112. Most ITAT benches allow the claim, arguing that the rebate applies to total tax payable on total income. Conversely, the Rajkot Bench in Kotecha’s case disallowed it, labelling the rebate “rate-sensitive”. However, subsequent rulings clarify that restrictive amendments by the Finance Act 2025 apply only prospectively from AY 2026-27.

ISSUE FOR CONSIDERATION 

An assessee, being an individual resident in India, is entitled to a deduction (“rebate/relief”) of the prescribed amount from the amount of income tax payable on his total income, subject to certain conditions stipulated under Section 87A of the Income-tax Act, 1961(section 156 of the Income-tax Act, 2025). This rebate is allowed to individuals under both the old and new tax regimes.

Section 111A (section 196) and section 112 (section 197) provide for the taxation of capital gains, short-term or long-term, at special rates. The relevant sections do not contain any provision for prohibiting an assessee in claiming the rebate, wherever eligible against the tax payable on capital gains. Section 112A (section 198) provides for taxation of long-term capital gains in certain cases at special rates. This section, however, expressly prohibits an assessee from claiming rebate under section 87A (section 156) in respect of tax on capital gains of the kinds referred to in section 112A (section 198).

Section 115BAC (section 202) primarily provides for the rate of income tax payable by an individual, etc., on his total income where such total income is calculated in the manner prescribed in the said provision. No prohibition, expressly or otherwise, is found in section 115BAC to deny the benefit of this provision for rebate in respect of the capital gains.

The amount of rebate in respect of a person governed by the new regime of taxation shall not exceed the amount of income tax payable by an individual under the regime of taxation as per the amendment introduced by the Finance Act, 2025 in s.87A w.e.f. Assessment Year 2026-27. Section 196 of the 2025 Act provides for a similar ceiling on the amount of rebate from tax year 2026-27 onwards.

An interesting issue has arisen about the eligibility or otherwise of an individual to claim rebate under section 87A in respect of capital gains being taxed at the special rates under section 111A or section 112 of the Act. While the Ahmedabad, Agra, Bengaluru, Chandigarh, Chennai, Jaipur, Mumbai and Rajkot Benches of the ITAT have held that rebate is allowable to an eligible individual in respect of his total income, including capital gains, the same Rajkot Bench in a later decision has held that no rebate is allowable to an eligible individual in respect of income under the head capital gains, being taxed under the respective provisions prescribing special rate of taxation. Interestingly, after holding against the allowance of rebate, the Rajkot Bench in a recent decision held that rebate is allowable for Assessment Years up to Assessment Year 2025-26 and that the amendment is not applicable till then.

JAYSHREEBEN PALSANA’S CASE

The issue arose in the case of Jayshreeben Jayantibhai Palsana v. ITO, IT Appeal No. 1014 (Ahd.) of 2025 for A.Y. 2024-25, vide order dated 12.08.2025.

The assessee, a resident individual, originally filed her return of income declaring total income of ₹4,27,635, comprising short-term capital gains (‘STCG’) under section 111A of ₹3,79,559, long-term capital gains (‘LTCG’) under section 112A of ₹38,840 and income from other sources of ₹9,236. The return was subsequently revised, wherein the assessee opted for taxation under the new tax regime under section 115BAC(1A).

The revised return resulted in tax liability of ₹13,320, arising solely from STCG taxable under section 111A at 15%. Since the assessee was a resident individual, who had total income below ₹7 lakh and had opted for section 115BAC(1A), she claimed rebate of ₹13,320 under section 87A.

The great rebate debate

However, the Centralized Processing Centre (CPC), Bengaluru, while processing the return under section 143(1), disallowed the rebate and raised a total demand of ₹15,820. The CIT(A) upheld the disallowance, principally relying upon the “subject to” clause in section 115BAC(1A), the provisions of Chapter XII and the Explanatory Memorandum to the Finance Bill, 2025.

The core issue before the Tribunal was:

Whether a resident individual who has opted for taxation under section 115BAC(1A), and whose total income does not exceed ₹7 lakh, is entitled to claim rebate under section 87A against tax payable on STCG under section 111A, in the absence of any express restriction in section 87A or section 111A?

The assessee contended that the first proviso to section 87A, applicable from

A.Y. 2024-25, granted rebate to a resident individual opting for section 115BAC(1A) where total income does not exceed ₹7 lakh. The provision contained no exclusion for income taxable at special rates under Chapter XII, including section 111A.

It was further argued that section 112A(6) specifically restricts rebate in respect of specified LTCG, whereas no corresponding restriction existed in section 111A or section 87A. Therefore, the absence of such a restriction must be construed in favour of the assessee. Section 115BAC(1A), according to the assessee, governed the computation of tax rates and did not override the independent rebate provision contained in Chapter VIII.

The assessee also submitted that the Finance Act, 2025 proposed a specific restriction prospectively from A.Y. 2026-27, which itself demonstrated that no such restriction existed for A.Y. 2024-25. Reliance was also placed upon the decision in the case of Chamber of Tax Consultants v Director General of Income Tax (System) 302 Taxman 505 (Bom.).

The CIT(A) supported the action of the CPC on the reasoning that section 115BAC(1A) operated subject to Chapter XII, which contained the special-rate provisions for capital gains under sections 111A and 112A. Consequently, rebate under section 87A could not be utilised against tax payable on such special-rate income. The CIT(A) also relied upon the Explanatory Memorandum to the Finance Bill, 2025 to support this interpretation.

The Tribunal allowed the appeal in favour of the assessee. It held that section 87A, as applicable for A.Y. 2024-25, did not distinguish between normal-rate income and income taxable at special rates, nor did it expressly exclude STCG under section 111A.

The Tribunal referred to section 112A, where the Legislature had expressly restricted the rebate, to distinguish it from the provisions of section 111A and s 112. The absence of a similar restriction under section 111A was considered legally significant. It further held that the “subject to” clause in section 115BAC(1A) concerned itself with computation of tax under the special-rate provisions and does not, by itself, restrict a rebate available under Chapter VIII.

The Tribunal also rejected reliance on the Finance Bill, 2025, observing that the proposed restriction was prospective from A.Y. 2026-27 and that an Explanatory Memorandum cannot override the plain language of the existing statute.

Accordingly, the Tribunal held that the assessee was entitled to section 87A rebate of ₹13,320 against the tax payable on the STCG, directed the AO to recompute the tax liability and deleted the demand of ₹15,820. The appeal was therefore allowed.

PRAFULCHANDRA KOTECHA’S CASE

The issue recently arose in the case of Prafulchandra Nanalal Kotecha v. ITO ITA No.: 81 (RJT) of 2025 for A.Y.2024-25 vide order dated 22.04.2026.

The assessee, an individual, filed his return of income for Assessment Year (A.Y.) 2024-25 declaring total income of approximately ₹5,85,283, comprising income from business, capital gains and income from other sources. The assessee claimed rebate under section 87A of the Income-tax Act, 1961, as his total income was below the threshold of ₹7 lakh applicable under the new tax regime under section 115BAC.

The Central Processing Centre (CPC), while processing the return, made an adjustment under section 154 and denied the rebate claimed under section 87A. The assessee challenged the adjustment before the CIT(A), contending that there was no prima facie error apparent from the return, and that the rebate was legally allowable. The CIT(A), however, upheld the denial of the rebate. Consequently, the assessee preferred an appeal before the Rajkot Bench of the ITAT.

The principal issue before the Tribunal was whether an assessee having mixed income, comprising business income, capital gains and income from other sources, with total income below ₹7 lakh and taxable under the new regime, was entitled to claim rebate under section 87A, including against the tax payable on capital gains taxable at special rates under sections 111A, 112 and 112A.

The assessee relied upon the earlier decision of the Rajkot Bench in Manojbhai C. Kamdar v. ITO, ITA No. 572/Rjt/2025 dated 3 November 2025, wherein rebate under section 87A had been allowed in respect of tax on short-term capital gains under section 111A.

It was contended that the assessee’s total income of ₹5,85,283 was below the prescribed threshold of ₹7 lakh under the new regime and, therefore, the assessee was eligible for rebate under section 87A. The assessee argued that section 87A, as applicable for A.Y. 2024-25, contained no express restriction excluding tax payable on capital gains under section 111A. The earlier Tribunal decision had also held that a subsequent amendment restricting the rebate from A.Y. 2026-27 demonstrated that no such restriction existed for A.Y. 2024-25.

The Revenue argued that rebate under section 87A was not available against tax arising from capital gains. According to the Revenue, the rebate was available only against income taxed at normal slab rates and could not be adjusted against income subjected to special rates under the capital-gains provisions. The Revenue supported the denial of the rebate and prayed for dismissal of the appeal.

The Tribunal held that section 87A was “head-neutral but rate-sensitive.” Merely having income under the heads of capital gains or income from other sources did not, by itself, disentitle an assessee from claiming the rebate. However, where income was taxed at special rates, particularly capital gains under sections 111A, 112 and 112A, the rebate could not be given against such special-rate tax.

The Tribunal reasoned that special-rate provisions constituted a separate mechanism for taxation and that capital gains were segregated and taxed independently. Consequently, the rebate under section 87A was held allowable only against the tax attributable to normal-rate income, namely business/professional income and income from other sources, and not against tax on capital gains.

Accordingly, the Assessing Officer was directed to allow the assessee the rebate under section 87A only to the extent of tax payable on normal income and recompute the tax liability. The appeal was therefore partly allowed in favour of the assessee.

OBSERVATIONS

An individual who is resident in India is entitled to claim rebate under section 87A, under the old regime, provided his total income does not exceed `5,00,000. Rebate of the lower of 100% of income-tax liability or `12,500, is available in the form of deduction from the tax liability. In other words, where the tax liability exceeds `12,500, rebate will be available to the extent of `12,500 only. No rebate is available under the old regime if the total income (i.e. taxable income) exceeds `5,00,000.

For a person governed by the new regime, under section 115BAC(1A), the maximum rebate of `60,000 is allowed under section 87A from the amount of income tax payable on total income which is chargeable to tax as per section 87A, provided his total income chargeable to tax under section 115BAC(1A) does not exceed `12,00,000.

Where the total income chargeable to tax exceeds `12,00,000 and the tax payable on such income exceeds the difference between the total income and the tax on income of `12,00,000, he can claim a rebate under section 87A with marginal relief, to the extent of the difference between the tax payable on such total income and the amount by which such tax exceeds the tax on total income of `12,00,000.

Through a plain and literal reading of the text of section 87A (section 156), there is no explicit, overarching clause that mechanically denies a rebate on capital gains taxed at special rates under section 111A (section 196) or section 112 (section 197). The specific exclusion for denying such rebate is embedded in section 112A (section 198), for certain long-term capital gains.

The legal maxim “expressio unius est exclusio alterius” applies here: by explicitly excluding section 112A (s.198) in the statute, the Legislature implicitly allowed the rebate on other special-rate incomes. By failing to explicitly cover section 111A and section 112 (sections 196 and 197), like section 112A (section198), the rebate in respect of the capital gains taxed at a special rate under the respective provisions cannot be denied.

Different benches of the Tribunal have frequently ruled in favour of taxpayers on this issue under consideration. The Ahmedabad, Agra, Bangalore, Chandigarh, Chennai, Indore, Jaipur, Mumbai, and Rajkot Benches have held that section 87A grants a rebate against the “total income-tax payable on total income,” and does not explicitly bar the claim of rebate against the tax on the short-term capital gains u/s 111A (section 197), and that the Assessing Officer and/or Central Processing Centre (CPC) cannot arbitrarily deny the rebate via automated software. Reference may be made to the following:

* Shevgoor Namratha Kamath , ITA No.: 3054/Bang/2025,

* Kiritkumar Champaklal Bhagat, ITA No.: 879/Rjt/2025,

* Pramod Kumar Dubey , ITA No.: 314/Agr/ 2025,

* Gurmindersingh, ITA No.887/Chd./2025,

* Pranay M Kothari, ITA No. 3469/Chny/2025,

* Veenaben Arvindbhai Shah, ITA No.: 2430/Ahd./2025,

* Padmaben Kantilal Ranpara, ITA No.: 516/Raj./ 2025,

* Venkedapathy Venugopal, ITA No.: 2064/Chny/2025,

* Thejaswini Jakkaraju, ITA No.: 218/Bang/2025,

* Seshank Mahadeo, ITA No.2274/Chenny/2025,

* Venkatachalam Venkataman, ITA No.: 1431/Chny/2025,

* Basty Keshav Shenoy, ITA No.: 3134/Bang./2025,

* Pushpa Prakash Misar, ITA No.: 741/Mum./2026,

* Kanhaiya Lal Panchal, ITA No.: 702/Ind./2025,

* Manmohan Jaiswal, ITA No.: 134/Jpr./2026,

* Murari Lal Mishra , ITA No.:196/Jpr./2026,

* Priyamvada Singhal,ITA No1412/Jpr./2025, and

* Rajshree Kothari, 399/Jpr./2026 dt.20.08.2026.

To bridge the gap between the obviously missing text in the main sections and their ulterior and unintended goals, the Income Tax Department uses three primary mechanisms:

  •  Firstly, the Proviso to section 87A (section 156) introduced w.e.f. A.Y. 2026-27 is sought to be applied to deny the rebate in respect of tax on capital gains. The relevant text states that the rebate under the new tax regiment is capped at the tax computed under the rates specified in section 202 [or section 115BAC(1A)]. Because capital gains are taxed at special rates under sections 111A and 112 are under entirely different sections, the Income Tax Department interprets that the balance rebate cannot cross over to cover non-slab tax liabilities under section 115 BAC(1A). This contention in any case cannot help the Income Tax Department to deny the benefit of rebate to persons opting for the old regime of taxation in as much as the amendment has application only to persons governed by the new regime of taxation. Nevertheless, there continues to be no provision in the relevant sections that prohibit the claim of rebate against tax on capital gains.
  •  Secondly, the Central Board of Direct Taxes has issued Circular No. 13/2025, dated 19.09.2025, which explicitly instructed Assessing Officers to disallow Section 87A rebates against special-rate incomes to persons governed by the new tax regime. Obviously the circulars are binding only on the Income Tax Department and not on courts or taxpayers, (refer Anjum M H Ghaswala, 252 ITR 1 (SC).
  •  Thirdly, the Memorandum explaining the provisions of the Finance Bill, 2025 is relied upon to deny the rebate. The Memorandum to the Finance Act 2025 expressly stated that the rebate (up to ₹12 lakh under the new regime) was only meant to relieve slab-rate income taxpayers; not to act as a tax shelter for capital gains. Again, a Memorandum is a tool to interpretation and not a law by itself. Indian courts utilize it to interpret the “mischief” the legislature intended to cure, provided there was a mischief. Refer Shashikant Laxman Kale, 185 ITR 104 (SC).

The Rajkot Bench of the ITAT, in its ruling in Kotecha’s case broke ranks with the prevailing judicial consensus. It held that a section 87A rebate is “head-neutral but rate-sensitive,” meaning thereby that rebate under 87A cannot be granted to and in respect of taxes computed under special rate provisions like sections 111A and 112. The Bench effectively ignored its own co-ordinate bench precedents in Manoj C Kamdar’s case (supra) delivered by the same member—creating an intense judicial paradox.

In tax law, when a co-ordinate bench decides an issue, a subsequent bench of the same tribunal is legally bound to follow it or refer the matter to a Larger/Special Bench. By ignoring previous rulings, Kotecha’s decision entered dangerous per incuriam territory.

The Tribunal in Kotecha’s case introduced an unprecedented judicial philosophy when:

  •  It reasoned that special-rate tax provisions like sections 111A and 112 operated as a complete code and such code was entirely independent of the normal slab-rate taxation. Obviously, these sections do not act or claim to be complete codes as the gains are computed under regular provisions of the Income-tax Act.
  •  It held that the provision for rebate was rate-sensitive and as the rebate was conceptually designed to provide relief from slab rates taxation, the tax liability calculated at special rates cannot be reduced from a general rebate. For this to be true, there should be an express provision that rejects a claim of rebate in the cases of capital gains altogether. 
The ink had barely dried on Kotecha’s order when a co-ordinate bench, ironically,  the very same Rajkot Bench led by the same member, completely bypassed the Kotecha logic. In the case of Kavita Paras Shah, ITA No. 732/Raj/2026, the Bench explicitly ruled that the restriction denying a section 87A rebate on special-rate incomes was introduced prospectively from Assessment Year 2026-27 by the Finance Act, 2025 and for the preceding Assessment Years, the Income Tax Department could not  retroactively import the said restriction, thereby squarely granting the rebate on tax on STCG u/s 111A for A.Y. 2025-26. The decision was delivered by the same member who delivered Kotecha’s decision was a party to this decision.
The Kotecha ruling deviates from the overwhelming majority of the tribunal decisions delivered across India (including Benches at Ahmedabad, Agra, Bengaluru, Chandigarh, Chennai, Indore, Jaipur, Mumbai and Rajkot), and should be viewed at best as an aberration rather than the settled law.
The claim for the rebate by the assessee is stronger. When two conflicting views are available from co-ordinate benches of the same Tribunal, the view favourable to the assessee must prevail, refer 88 ITR 192(SC) Vegetable Products Ltd. As heavily highlighted in Kavita Paras Shah’s case, the text modification by the Finance Act, 2025 is an explicit admission by the Legislature that the text prior to AY 2026-27 did not bar the rebate. The Kotecha ruling or any other ruling cannot apply to a person opting for the old regime of taxation.
In the case of Chamber of Tax Consultants 473 ITR 85 (Bom), while disposing of the writ petition against denial of such claim in the return utility itself, the Bombay High Court made the following observations:
“The revenue did not show any provision under the Income-tax Act which expressly debars an assessee to raise or make the claim under section 87A qua the tax computed at the rates specified in the provisions of Chapter XII other than section 115BAC. If that be so, then certainly one cannot accept the argument that the revenues’ case is crystal clear…
The issue raised for consideration on the claim under section 87A is, at best, highly debatable and contentious. Therefore, the revenue would not be justified in assuming that its interpretation is open and shut, and based upon such a conclusion, shut out bona fide claims for rebate under section 87A”
The Bombay High Court therefore did not decide the issue of allowability of rebate in such cases, since that was not the prayer before it.
Under either of the Assessment Years or the enactments, the core thesis stands completely firm. There remains a glaring absence of an explicit, text-based prohibition against claiming a rebate against tax payable at the special rates under section 111A (section 196) or section 112 (sections 197) capital gains based on three established maxims of interpretation:
  •  Both the old and new Acts explicitly state that the rebate is not available against long-term capital gains taxed under section 112A (section 198). In statutory drafting, when the legislature explicitly names one item to exclude it, it deliberately chooses not to exclude the others. By failing to explicitly name sections 111A or 112 (sections 196 and 197) next to section 112A (section 198), the literal text continues to legally permit the rebate against tax payable under such provisions that provide for special rate of taxes.
  •  There is no room for intendment in tax laws as established in the landmark Supreme Court ruling in Cape Brandy Syndicate’s case, 12 TC 358 and consistently followed by the Indian courts: “In a taxing Act, one has to look merely at what is clearly said. There is no room for any intendment.” CIT v. Ajax 55 ITR 741(SC). A Memorandum explaining a Finance Bill does not change what is eventually written into the final legislative text.
  •  Labelling a rebate as “rate-sensitive” is a highly convoluted, non-textual interpretation invented by the Income Tax Department and accepted in Prafulkumar Kotecha’s case. The statute simply says the rebate applies to the “total income-tax payable on total income.” “Total income” by definition includes capital gains.
Till the time the issue under consideration is settled by a court ruling  against the claim, it is wiser to hold that section 87A (section 156(3)) merely acts as a quantitative ceiling, not a qualitative bar on the types of income. Until the legislature explicitly inserts a clear, sweeping clause stating, “no rebate under this section shall be allowed against tax computed under any special rate provisions,” or amends sections 111A and 112 to replicate the strictures of section 112A, a claim for rebate against the tax payable on capital gains at the special rates, in our considered opinion, is valid in law.

DIT v. Star Cruises (India) P. Ltd. : Providing cruise services with on-board entertainment and de-boarding options falls within the meaning of carriage under shipping presumptive taxation.

7. The Director of Income Tax (International Taxation) Vs. Star Cruises (India) P. Ltd. (2026) 188 taxmann.com 1068 (SC)

Special provision for computing profits and gains of shipping business other than cruise shipping in case of non-residents – Section 44B – The meaning of the word ‘carriage’ cannot be restricted to mean the carriage from Port A to Port B – The possibility of passengers de-boarding at intermediate ports was not taken into account by the Assessing Officer – On a voyage, the provision of ancillary services did not take away from the meaning of ‘carriage’ as per Section 44B of the Act.

The Superstar Libra Ltd. (for short, ‘SLL’), a non-resident entity, operated a cruise known as “Superstar Libra” in India. The Assessee (Star Cruises (India) Pvt. Limited), the agent of SLL, was responsible for conducting the cruise and collecting revenue from the sale of cruise packages and shore excursions in India.

The assessee computed the income accruing in favour of SLL by applying Section 44B of the Act and estimated the income at 7.5% of the cruise fare collected by the assessee.

The Assessing Officer, vide order dated 30.03.2007, held that Section 44B of the Act is applicable in cases of carriage of goods, passengers, etc, and, in the view of the Assessing Officer, the term “carriage” means taking or transporting from one place to another or from one port to another. SLL conducted cruise services originating from and terminating at Mumbai Port, i.e., a round trip. During the round trip, SLL extended hospitality and provided entertainment. Therefore, the activity of SLL falls under entertainment and hospitality and does not include carriage of passengers/goods within the meaning of section 44B of the Act. Consequent to such view, the Assessing Officer estimated deemed income at 25% of the cruise fare collected for and on behalf of SLL, not at 7.5% as claimed by the Assessee.

The Assessee carried the matter in appeal before the Commissioner of Income Tax (Appeals). By Order dated 15.06.2007, the CIT(A) allowed the appeal and set aside the Assessment Order dated 30.03.2007.

The Appellate Authority appreciated all the circumstances of the case under Section 44B of the Act and held that the deemed income of SLL was to be estimated at 7.5% of the receipts received from the cruise fare.

The Revenue carried the matter in appeal before the Income Tax Appellate Tribunal, and the Tribunal, by the order dated 01.07.2009, dismissed the appeal. The Tribunal while rejecting the Assessing Officer’s interpretation of the term ‘carriage’, affirmed that a round-trip voyage constitutes two separate acts of carriage, i.e, from station A to station B and back to station A. Further, the assessee also offered one-way cruises, and passengers booking round-trip cruises were entitled to disembark at intermediate ports without being compelled to return to Mumbai. Also, the booking slips established that the primary fees collected from passengers were for cabin and transport fares. Any on-board entertainment, whether included or paid separately, was incidental to the main business of operating ships. The Tribunal noted that the CBDT Circular Nos. 763 and 169 dated 18.02.1996 and 23.06.1975, respectively, clarified that carriage payments included handling charges and that Section 44B of the Act was designed to simplify the computation of taxable profits for foreign shipping enterprises. Since SLL was a non-resident entity engaged in the business of operating ships, it fulfilled the essential conditions under the said section. The Tribunal therefore directed that SLL’s income be assessed at the statutory presumptive rate of 7.5% of gross cruise fare receipts for tax deduction under Section 195 of the Act rather than at 25% of income estimated by the Assessing Officer.

The Revenue carried the matter in appeal before the High Court, which dismissed the appeals.

The Supreme Court granted leave in the matter(s) on the following two questions, namely: (i) Whether on the facts and circumstances of the case and in law, the Hon’ble High Court was justified in upholding the Hon’ble ITAT’s decision that the assessee is engaged in the business of operation of ships and is entitled to be assessed under Section 44B of the Income Tax Act? (ii) Whether on the facts and circumstances of the case and in law, the Hon’ble High Court was justified in upholding the Hon’ble ITAT’s decision without appreciating the fact that
the business activity of assessee was primarily that of providing hospitality and entertainment on board the cruise ship and not that of mere transportation of passengers?

The Supreme Court noted that the Assessing Officer was of the view that, to attract the meaning of the word ‘carriage’, the movement should be from place ‘A’ to place ‘B’.

According to the Supreme Court, it was difficult to confine the meaning of the word ‘carriage’ in the matter attributed by the Assessing Officer. The Appellate Authority and the Tribunal, being competent authorities to examine the facts in issue, had held that the activity undertaken by SLL did not fall outside the expression of ‘carriage’ as per Section 44B of the Act. In the facts and circumstances of this case, SLL, being a foreign entity, was providing cruise services in India through the Assessee. The finding recorded was that the possibility of passengers de-boarding at intermediate ports was not considered by the Assessing Officer. On a voyage, the providing of ancillary services did not take away from the meaning of ‘carriage’ as per Section 44B of the Act. The meaning adopted by the Assessing Officer was restrictive in the facts and circumstances of this case. According to the Supreme Court, the error was factually corrected by the impugned Orders.

The Supreme Court without reiterating the same reasoning, was satisfied that, in the facts and circumstances of the case, the view taken in respect of the subject assessment years 2006-07, 2007-08, and 2008-09, namely, that Section 44B of the Act was attracted to the estimated income of SLL, did not warrant interference.

PCIT v. Essar Agrotech Ltd. : Share capital and premium additions under section 68 are unsustainable where the identity, creditworthiness, and transaction genuineness are proved.

11. PCIT – 6, Mumbai Vs. Essar Agrotech Ltd.

[ITXA No. 128 OF 2020, dated 29/07/2026, (Bom) (HC) ] A.Y.2012-13.

Section 68 – Cash Credit – share capital and share premium – identity, genuineness of transactions, and creditworthiness of the parties, have been proved by filing necessary details – complete details of the money trail to explain source of investment.

The Assessee-Company was engaged in the business of agricultural activity and cultivation of flowers, vegetables etc. and rendering services for maintenance of mango orchards. The Assessee-Company filed its Return of Income for A.Y.2012-13 on 30th September 2012 declaring its total income at Rs.11,07,178/. The case of the Assessee was completed under Section 143(3) on 30th March 2015 determining the total income of the Assessee at Rs.11,90,82,890/- by making various additions towards share capital and share premium under Section 68 of the Act, as well as disallowance of expenditure incurred in relation to exempt income under Section 14A read with Rule 8D(2)(ii) and 8D(2)(iii) of the Income Tax Rules, 1962 (the Rules).

Before the CIT(Appeals), the Assessee submitted that premium was a capital receipt and that the Assessee being a Company, was not required to prove the purpose or justification for charging premium on shares, and what was relevant was whether or not the identity, genuineness and creditworthiness of the parties investing has been proved. According to the Assessee, it had filed all the details in order to prove all the ingredients, and hence the Assessing Officer erred in making any addition towards share capital and share premium under Section 68 of the Act.

The CIT (Appeals) deleted the addition made by the Assessing Officer towards disallowance of expenses incurred in relation to exempt income. Further, the CIT (Appeals) also deleted the addition made towards share capital and share premium by following the decision of this Court in Gagandeep Infrastructure Pvt Ltd V/S CIT [(394) ITR 680 (Bom)]. The CIT (Appeals) held that when identity, genuineness of transactions, and creditworthiness of the parties, have been proved by filing necessary details, there was no reason for the Assessing Officer to make the addition only for the reason that shares had been issued at a higher premium. With these observations, he deleted the said addition made by the Assessing Officer.

Aggrieved by the order of the CIT (Appeals), the Revenue preferred an Appeal before the ITAT. As far as the issue regarding the addition towards share capital and share premium was concerned, the ITAT concluded that the CIT (Appeals) rightly deleted the addition made by the Assessing Officer on this count. The ITAT, after perusing the facts and circumstances of the present case, concluded that the Assessee had filed complete details including the identity of the subscriber to the share capital, as per which the Assessee had issued Rs.22,50,000/- equity shares at Rs.50/- per share, having a face value of Rs.10/- per share, with a premium of Rs.40/- per share. The ITAT noted that the Assessee had also filed complete details of the financial statements of the subscriber of the shares and its bank statements.

Further, the share capital issued by the Assessee had also been disclosed by the subscriber in its financial statements. The ITAT noted that the matter did not stop here. It noted that the subscriber’s assessment was subjected to scrutiny and an order was passed under Section 143(3) where the Assessing Officer made no adverse comments in respect of the amount invested in the Assessee-Company’s shares. Over and above this, the Assessee had also filed complete details of the money trail to explain the source of the investment made in Assessee-Company’s shares. The ITAT further noted that the subscriber to the share capital had received the amount from various other group companies to make the aforesaid investment. Looking at these facts and considering that it was not the case of the Assessing Officer that the share capital had been issued to an unknown subscriber, nor was the subscriber an accommodation entry provider, the ITAT held that the CIT (Appeals) correctly deleted the aforesaid addition.

The ITAT held that once the identity of the subscriber had been proved with the necessary details, and the genuineness of the transaction and creditworthiness of the parties had been established, then merely for the reason that the shares had been issued at a high premium, addition could not be made under Section 68 of the IT Act. The ITAT held that the issue of shares at a premium and subscription to such shares is a decision between two parties, namely, the Company issuing the shares, and the party subscribing to those shares, and the Assessing Officer did not have any role to play as long as ingredients provided under Section 68 of the IT Act were proved or established.

The learned counsel appearing on behalf of the Revenue drew attention to the second proviso to Section 68. He submitted that the aforesaid proviso stipulates that where the Assessee was a company (not being a company in which the public are substantially interested), and the sum so credited consists of share application money, share capital, share premium or any other such amount by whatever name called, any explanation offered by such Assessee Company shall be deemed to be unsatisfactory unless (a) the person, being a resident in whose name such credit is recorded in the books of such company also offers an explanation about the nature and source of such sum so credited; and (b) such explanation in the opinion of the Assessing Officer has been found to be satisfactory. According to the Revenue, the stipulation in the second proviso to Section 68 had not been fulfilled in the present case and therefore a substantial question of law arose from the impugned order.

The learned Advocate for the Respondent Assessee firstly submitted that the second proviso to Section 68 was inserted by the Finance Act, 2012 with effect from 1st April 2013. In other words, the same came into operation from A.Y. 2013-14. In the facts of the present case, the Assessment Year involved was A.Y. 2012-13 and the said proviso could have no retrospective application, especially considering that the said proviso was not introduced with retrospective effect and does not contain the words “for removal of doubts” or state that it is “declaratory”. He, therefore, submitted that the proviso cannot have retrospective operation and would apply only prospectively from A.Y. 2013-14. Apart from this, the learned counsel submitted that even assuming for the sake of argument that the said proviso were to apply, in the facts of the present case, there was clearly an explanation
about the nature and source of funds that were invested by the subscriber, namely the investor. He, therefore, submitted that the reliance placed on the second proviso to Section 68 was wholly misconceived.

The Hon’ble Court observed that there was no need to determine whether the second proviso to Section 68 operates prospectively or has any retrospective effect. In the facts of the present case, the ITAT had given a factual finding that the subscriber had subscribed to the shares of the Assessee-Company by receiving the amount from various other group companies. This factual finding clearly satisfied the condition laid down in the second proviso to Section 68.

The Hon’ble Court held that no substantial question of law arose in the Appeal. In view of the aforesaid, the Appeal was dismissed.

PCIT v. Ansal Phalak Infrastructure Pvt. Ltd. : Addition under section 68 cannot be made when the assessee produces sufficient evidence to prove the genuineness of foreign investment.

10. PCIT – 4, Delhi Vs. M/S Ansal Phalak Infrastructure Pvt Ltd (Now Known As New Look Builders And Developers Pvt Ltd)

[ITA No. 770/2025, dated 19/08/2026, (Delhi) (HC)] [AY 2011-12 ]

[Arising from ITA No. 5658/Del/2015 Delhi Bench: ‘E’ dated 18.12.2024]

Section 68 – Cash Credit – Investment – Compulsory Convertible Debentures – details filed to prove genuineness of the transaction – Onus discharged by assessee.

The Assessing Officer (‘AO’) had made an addition of Rs. 55 crores under Section 68 of the Act against the assessee for Assessment Year (AY) 2011-12, alleging that investment made by two companies namely M/s New Dimension Holdings Ltd. of Mauritius and M/s Velford Ventures Ltd. of Cyprus, in the respondent-assessee company was unexplained.

The aforementioned two companies had made investment and subscribed to the assessee’s shares and Compulsory Convertible Debentures (hereinafter referred to as ‘CCDs’) to the tune of Rs. 55 crores, which raised a doubt in the AO’s mind. Since the amount involved an international transaction, he made a reference to the Transfer Pricing Officer (‘TPO’) while also making a reference to the Foreign Tax and Tax Research (‘FT&TR’).

The AO conducted an enquiry and doubted the creditworthiness of those companies, and vide assessment order dated 31.03.2015 held that the onus to prove creditworthiness of the amount so received lays upon the assessee and since it failed to discharge such burden, he added the amount of Rs. 55 crores under Section 68 of the Act in the hands of the respondent-assessee.

The CIT(A), allowed the assessee’s appeal vide its order dated 28.07.2015, after going through the record and additional evidence which the assessee had produced during the course of appeal being audited accounts of M/s Redfort India Real Estate Fund II LLC, Mauritius, parent investor of the original investor companies, who had invested in respondent-company. Moreover, the CIT(A) dealt with the material, which the assessee had produced before the AO and then recorded a categorical finding that these two companies of Mauritius and Cyprus had entered into an agreement with the respondent-assessee due to which even the name of respondent was changed. He noted that an interest @ 16% p.a. or 16% coupon was paid on the CCDs.

The revenue challenged the said order before the Tribunal, which affirmed the findings recorded by the CIT(A) by way of the order dated 18.12.2024.

The Revenue Counsel pointed out that the Assessment Year in question was 2011-12 i.e., prior to the amendment brought in Section 68 of the Act which was introduced with effect from 01.04.2013 and thus, the AO could well ask an assessee to satisfy about the ‘source of the source’. He contended that since the investment remained unexplained,addition under section 68 of the Act was totally justified.

The counsel for the Assessee submitted that due explanation was given by the assessee. He pointed out that the AO had referred to the TPO’s report and recorded that the TPO had given no adverse report, as well as the fact that the assessee had produced in evidence a copy of the agreement between the investor companies and the respondent-assessee. He argued that the factum of 16% CCDs was known to the AO and yet, he had completely ignored such fact and dealt with only that part which suited his viewpoint and whims, while ignoring the reply which served the cause of the respondent-assessee. The assessee was able to procure the audited balance sheet of M/s Redfort India Real Estate Fund II LLC, Mauritius, being the investor in those two companies that have invested in the respondent-company. The CIT(A) recorded a finding in the assessee’s favour that the investment was genuine and duly explained.

The Hon’ble Court held that the Appellate Authority had gone through and carefully deliberated on the transaction and recorded the finding that the respondent-company was incorporated on 13.09.2010 in the name of Phalak Infrastructure Ltd. with a share capital of 1,00,000 by the Ansal Group for carrying out real estate development. The company entered into an investment-cum-collaboration agreement with New Dimension Holdings Ltd., Mauritius and Velford Ventures Ltd., Cyprus and, as a part of the collaboration agreement, the name of the company was changed to Ansal Phalak Infrastructure Pvt. Ltd. with effect from 03.05.2011. The Articles of Association and Memorandum of Association were also revised. It was also found that, upon execution of the agreement, both the foreign investors invested money in the assessee company-New Dimension Holdings Ltd., Mauritius acquired 25.9% shares of the respondent-company for Rs. 5,70,50,000/-, while Velford Ventures Ltd., Cyprus acquired 14 shares of the respondent-assessee for Rs.2,03,000/- and invested Rs. 49,90,47,000/- in CCDs issued by the respondent-company. It was also found that both these companies are registered in Mauritius and Cyprus, and are taxpayers in their respective jurisdictions. The CIT(A) had also recorded that the respondent-assessee had also filed before the AO copies of the prescribed Certificate of Foreign Inward Remittance, issued by the Hongkong and Shanghai Banking Corporation Limited setting out all details of remittance, the purpose of remittance, and the description of remittance, including equity shares application money as well as the issue of CCDs. It is also to be noted that the respondent-assessee had filed copies of the audited balance sheets of both the investors companies. The findings recorded by the CIT(A) and as affirmed by the Tribunal, are based on the material available on record and the Revenue had not been able to show them to be perverse in any manner.

While dismissing the appeal, the Hon’ble Court observed that the Appellate Authority had dealt with each of the documents filed by the assessee with great detail and care – while giving the page numbers of the paperbook – whereas the AO has completely ignored them. The Court further observed that an adjudicatory process enjoins upon an AO to deal with the reply and documents filed by the assessee in an objective manner, and his duty as an AO was not only to protect the interests of the Revenue and generate revenue for the country, but also to judiciously consider the reply and pleas including the judgments and documents which an assessee relies upon or furnishes. Brushing aside or ignoring documents filed by an assessee leads to a breach of the principles of natural justice and hits at the procedural fairness thereby causing injustice which, in the instant case, has been meted out to the assessee.

The appeal of the Revenue was dismissed.

Bipinkumar Girdharlal Parekh v. ACIT : Reopening assessment based on search-related material is invalid if initiated beyond three years for income escapement under fifty lakhs.

30. Bipinkumar Girdharlal Parekh v. ACIT

(2026) 187 taxmann.com 904 (Guj.)

A. Y. 2021-22: Date of order 15th June 2026

S. 148 r.w.s. 149 and 152 of ITA 1961

Re-opening of assessment — Initiated pursuant to search in the case of another Company and Group — Search conducted on 18th June 2023 — Incriminating material found — 148A(1) Notice issued upon the assessee 31st March 2025 — 148A(3) order passed and notice u/s. 148 issued for re-opening the assessment on 19th May 2025 — Since search was conducted on 18th November 2023, provisions of section 147 to 151 as they stood prior to commencement of Finance (No.2) Act, 2024 applied by virtue of section 152 — Alleged escapement of income below Rs. 50 lakhs — Section 149(1)(a) applied — Since 148 notice issued beyond three years, re-opening of assessment liable to be quashed.

The assessee is engaged in the business of transportation and has a business relationship with DCW Ltd. wherein it hires trucks and offers it for transportation. The assessee filed its return of income for AY 2021-22 on 14/12/2021 declaring total income at Rs. 38,51,910. The return of income was processed u/s. 143(1) of the Income-tax Act, 1961.

Subsequently, a search was conducted on DCW Ltd. Group on 18/11/2023 u/s. 132 of the Act. Pursuant to the search, a notice u/s. 148A(1) was issued upon the assessee on 31st March 2025 for re-opening the assessment on the ground that the assessee had raised inflated bills for transportation expenses amounting to Rs. 32,71,205 and to that extent the income of the assessee had escaped assessment. In response to the notice, the assessee filed its response and submitted the bills of freight and transportation.

The objections filed by the assessee were rejected and an order dated 19th May 2025 was passed u/s. 148A(3) of the Act holding it to be a fit case for issue of notice u/s. 148 of the Act. A notice u/s. 148 of the Act dated 23/05/2025 was also issued along with the said order.

The assessee challenged the order and the notice u/s. 148 in a writ petition filed before the Hon’ble Gujarat High Court primarily on the ground that since the search was conducted on or after 1st April 2021 but before 1st September 2024, the provisions of the Act as they stood prior to the amendment by the Finance (No.2) Act, 2024 will be applicable as per the provisions of section 152(3) of the Act and as per the provisions of the Act as they stood prior to the amendment of Finance No.2 Act 2024, approval of the Principal Commissioner of Income-tax was required which had not been done in the case of the assessee. Further, the notice issued on 23rd May 2025 u/s. 148 of the Act was barred by limitation as it was issued beyond a period of 3 years from the end of the relevant financial year.

The High Court allowed the petition and held as under:

“i) Since the date of search fell within the period from the 1st April 2021 to the 1st September 2024, the provision of sections 147 to 151 of the Act, as they stood prior to the Finance Act (No. 2), 2024, shall apply.

ii) In the present case, the provision of section 149(1)(a) of the Act, which prescribes a time limit of three years, will get attracted, as the alleged escapement of income is below the amount of Rs.50 lakhs, which finds place in the provision of Section 149(1)(b) of the Act. The relevant assessment year in the present case is A.Y. 2021-22, and hence, as per the provision of Section 149(1)(a) of the Act, the end of the relevant assessment year would be 31st March 2022. However, the impugned notice u/s. 148 of the Act has been issued on 23rd May 2025 for A.Y. 2021-22, which is beyond the limitation of three years, and hence, the reopening of the assessment runs contrary to the provision of Section 149 of the Finance (No. 1) Act, 2024, and hence is liable to be interfered with.

iii) The contention raised before us by the Revenue, to the extent that the Finance (No. 2) Act of 2024 will apply in the present case, as there is no search conducted against the petitioner, is misconceived, since the reopening of the assessment against the petitioner is exclusively premised upon the incriminating materials found during the search u/s. 132 of the Act. The provisions of section 152(3) of the Act are not limited for undertaking the reassessment against searched person only, as projected before us by the Revenue, and not against other person, who is not subjected to search. The provision of Section 152(3) of the Act is applicable to all the assessee, where the reassessment proceedings are initiated, ‘on the basis’ or ‘as a consequence’ of a search conducted between 1st April 2021 and 1st September 2025, and against whom incriminating material is found. However, the re-opening of the assessment is subject to limitations as provided u/s. 149 of the Act.

iv) As mentioned herein-above the provision of section 132 of the Act finds place in the provision of section 149 of the Act and hence, the reassessment, since it emanates on the incriminating material found during the search at M/s. DCW Ltd. group, connecting the present petitioner with such material, the provision of section 149 of the Finance (No.1) Act prescribing limitation gets attracted. Thus, on this sole ground, the writ petition succeeds, and the impugned order dated 19th May 2025 and the impugned notice dated 23rd May 2025 are hereby quashed and set aside. The writ petition stands allowed.”

Capgemini Technology Services India Ltd. v. Dy. CIT : High Court has jurisdiction if consequences of demand are felt within its territory; non-existent or unserved demands are unsustainable.

29. Capgemini Technology Services India Ltd. v. Dy. CIT: (2026) 488 ITR 292 (Bom): 2026 SCC OnLine Bom 3755: (2026) 350 CTR 719 (Bom)

Date of order 24th March 2026

Article 226 of Constitution of India

Recovery of tax — Writ jurisdiction of High Court under Art. 226 — Territorial jurisdiction of Court:— (A) Power of High Court to issue writ to authority not within its territorial jurisdiction of Court provided cause of action wholly or in part arises within its jurisdiction; (B) Doctrine of forum conveniens and “cause of action” — Court has to consider each matter on appreciation of facts involved therein; (C) Recovery of tax — Notice of demand — Amalgamation of erstwhile company with assessee — Recovery notice issued in the name of erstwhile company originating from Delhi but received by assessee in Pune — Recovery notice and demands having direct impact on assessee in Pune and consequences of recovery notice and demand would be felt in Pune — Transfer of case from Delhi to Pune — Officer who was to defend case and deal with recovery of demand in Pune — Right officer to writ could be issued? — Held by High Court that part of cause of action clearly arising within territorial jurisdiction of Bombay High Court — Writ petition is maintainable before Bombay High Court — The impugned demands cannot be sustained.

By an order of the Delhi High Court dated 16th May 2007, the company F was amalgamated with company A. Thereafter, by an order dated 23rd December 2022 of the National Company Law Tribunal, Mumbai Bench, A got amalgamated with the assessee company which had its registered office in Pune.

In February 2023, the assessee received a notice u/s. 220 of the Income-tax Act, 1961 (dated 5th February 2023) in the name of the erstwhile entity, F, from Assessing Officer Delhi (respondent No. 2). In the said notice, the assessee was asked to pay the outstanding demand, inter alia, of Rs. 3,28,785 for the A. Y. 2001-02, Rs. 1,24,577 for the A. Y. 2002-03 and Rs. 28,87,714 for the A. Y. 2003-04.

Upon receipt of the recovery notice, the assessee filed applications under the Right to Information Act, 2005 (“the RTI Act”) seeking copies of the orders giving rise to such demands. The assessee received a reply from Assessing Officer in Delhi stating that for the A. Ys. 2001-02 and 2002-03, the demands were on account of rectification/intimation orders, but no such orders were provided. Instead, illegible screenshots of the computation sheets from the system were furnished. For the A. Y. 2003-04, it was stated that records were not available.

The assessee preferred appeals before the first appellate authority under the Right to Information Act, wherein directions were issued to Assessing Officer Delhi to furnish full information. Despite such directions, no orders were supplied.

In these circumstances, the assessee filed a writ petition before the Bombay High Court and contended that these demands are non-existent and the recovery notice is bad in law. The Department raised a preliminary objection regarding the territorial jurisdiction of the Bombay High Court to issue writs against authorities located outside its territories. The Bombay High Court allowed the petition and held as under:

“i) After the insertion of article 226(2), every High Court exercising jurisdiction in relation to the territories within which the cause of action, wholly or in part, arises, shall have powers to issue directions, orders or writs to any Government, authority or person notwithstanding that the seat of such Government or authority or the residence of such person is not within those territories. Thus, even if the authority concerned is not within the territorial jurisdiction of a High Court, still the High Court will have the power to issue writ to such authority, provided the cause of action, wholly or in part, arises within the jurisdiction of such High Court. The amendment was aimed at widening the scope of territorial jurisdiction for writs to be issued by different High Courts.

ii) The provisions of article 226(2) cannot be construed as a requirement in addition to the provisions of article 226(1). Article 226(2) has used the phrase “may also be exercised” which clearly suggests that article 226(2) is not an additional condition but an alternate condition. Moreover, article 226(1), as interpreted by the apex court provides for a court to issue a writ only to the authorities within the territories of that court, whereas article 226(2) provides that notwithstanding that the seat of Government or authority or the residence of such person is not within those territories, a writ can be issued by a court where part or whole of cause of action arise. The two clauses are mutually exclusive and both cannot apply simultaneously by the very wordings of the clauses. The whole purpose of introducing article 226(2) was to alleviate the inconvenience caused to the petitioners by dragging them to the court which exercises jurisdiction over the authority or the respondent within the territorial jurisdiction of such court.

iii) The doctrine of forum conveniens and “cause of action” are very fact specific and a court has to consider each matter on appreciation of the facts involved therein. A part of the cause of action has clearly arisen within the territorial jurisdiction of this court. In fact, the case of the petitioner is on a better footing as compared to the other cases. In the present case, the Principal Commissioner of Income-tax, Delhi-1, vide order dated 13th December 2023 u/s. 127 of the Act, has transferred the jurisdiction over the case to the Deputy Commissioner of Income-tax/Assistant Commissioner of Income-tax, Circle-1(1), Pune.

iv) In the present case, there is absolutely no material on record to substantiate the existence of valid orders giving rise to the impugned demands. The respondents have failed to produce the orders and service records, despite repeated opportunities. The failure of respondent No. 2 to respond and the inability of the Pune Officer to locate records leads to the inevitable conclusion that no such valid orders exist or were ever served upon the petitioner. An adverse inference must necessarily be drawn against the respondents. Old matters and demands cannot be allowed to suddenly surface on the portal without the underlying orders being available and served. Consequently, the impugned demands cannot be sustained.”

Dinar Tarcar Resources (India) Pvt. Ltd. v. ACIT : Prosecution for tax evasion is unsustainable if delay in payment was due to a business ban and lacks guilty intent.

28. Dinar Tarcar Resources (India) Pvt. Ltd. v. ACIT

2026 (8) TMI 57 (Bom.)

A. Y. 2012-13: Date of order 28th July 2026

S. 276C of ITA 1961

Prosecution u/s. 276C — Wilful attempt to evade tax — Delay in payment of taxes by the assessee — Delay on account of closure of business due to ban on the activity of mining in the State of Goa — Nil income of the assessee — Outstanding demand paid along with interest and penalty — Submissions of the assessee rejected — Prosecution initiated — Complaint filed against the assessee before the Judicial Magistrate — Mere delay or failure to pay, without mens rea, does not satisfy the penal provision — Specific wilful act or circumstance demonstrating an attempt to evade payment not pointed out — Criminal complaint and the process issued against the petitioners were unsustainable.

The Assessee filed its return of income for A. Y. 2012-13 declaring total income at Rs. 4,76,61,800. The income returned by the assessee was accepted vide order dated 15th March 2016. Subsequently, a letter was addressed to the assessee demanding the payment of declared tax. In response, the assessee filed a letter stating that the assessee was presently unable to pay tax as the mining operations had been suspended in Goa and the assessee had no income. Thereafter, on 4th October 2013 the assessee paid Rs. 30 lakhs towards tax dues. However, the department issued further demand to the assessee.

Subsequently, several communications were exchanged between the assessee and the tax department. The Principal Commissioner issued a notice dated 23rd November 2016 inviting objections to the proposed prosecution u/s. 276C(2) of the Act. The assessee filed objections to the proposed prosecution and stated that the assessee was in genuine difficulty which had led to delay in payment of tax and meanwhile continued to make payment of tax in parts along with penalty and interest. The assessee also responded to the demand notices issued earlier thereby stating that there was no intention to default on the tax payments and also informed that due to the ban on mining in the State of Goa, there was no revenue and hence the assessee was not able to pay the tax liability. It was also informed to the Department that the assessee was seeking to sell some of its assets and pay tax liability from the proceeds thereof. The submissions of the assessee were not considered and order dated 30th January 2017 was passed by the Principal Commissioner of Income Tax granting permission to initiate prosecution u/s. 279(1) of the Act on the ground that the assessee had wilfully evaded the payment of tax liability.

Pursuant to the sanction for launch of prosecution, the assessee paid the outstanding tax liability along with interest u/s. 220(2) of the Act. However, the department filed a complaint before the Chief Judicial Magistrate u/s. 200 of the Criminal Procedure Code on 10th March 2017 alleging offence punishable u/s. 276C(2) of the Act.

By 20th March 2017, the entire liability was cleared by the assessee, therefore, the Assessing Officer passed an order u/s. 154 of the Act holding that the net payable amount by the assessee was NIL. Despite the net amount payable by the assessee being NIL, the Judicial Magistrate issued process against the assessee vide order dated 29th January 2018.

Against the said order, the assessee filed a writ petition before the Bombay High Court which was quashed and set-aside and the matter was remanded back to the Judicial Magistrate.

Pursuant to the remand on 1st March 2019 and almost 6 years later, the Judicial Magistrate passed the order once again issuing process which has once again been challenged before the Bombay High Court by way of criminal writ petition.

The Bombay High Court allowed the petition of the assessee and held as under:

“i) Although the section provides an explanation as to what would include ‘wilful attempts’, neither the words ‘wilful’, ‘attempt’ nor the term ‘wilful attempt’ has been specifically defined in the I.T. Act. The explanation to section 276-C(2), which is inclusive, provides meaning to the words ‘wilful attempt’ used in the section. There are four categories of acts which ought to be construed as ‘attempts’ which are listed in the explanation to the section.

ii) A plain reading of the section requires that there ought to be ‘wilful’ ‘attempts’ to evade the payment of tax, penalty or interest under the I.T. Act. The word ‘wilful’ precedes the word ‘attempts’ in the section. Without fulfilling the requirement of ‘wilfulness’, the provisions of the section cannot be made applicable and cannot be invoked to prosecute a person. Therefore, there has to be an intention to evade the liability of tax, penalty or interest.

iii) The Section uses the words ‘wilful attempt’ and not ‘wilful default’. Relying on the decision of the Hon’ble Supreme Court in the case of S. Sundaram Pillai and others v. V. R. Pattabiraman, is remaked that the word ‘wilful’ denotes an act consciously and deliberately done and signifies a course of conduct marked by the exercise of volition rather than one that is accidental, negligent or involuntary. The word ‘wilful’ has a peculiar characteristic indicating the guilty mental state of the party.

iv) Considering the definitions of ‘wilful’ provided in various dictionaries and in the interpretation of the words ‘wilful default’ provided by the Hon’ble Supreme Court in the above judgement, a similar meaning ought to be adopted to interpret the term ‘wilful attempt’ used in the section. The word ‘wilful’ introduces a mental element and requires looking into the mind of a person by gauging the person’s actions indicative of one’s state of mind. Thus, in order to prosecute a person under section 276-C(2), the conduct of a person acquires importance.

v) A person, in such a case, ought to have deliberately, intentionally and consciously made attempts to evade payment of tax, penalty or interest under the I.T. Act. It does not include an unintentional act, an accidental act or a casual act or genuine inability. The word ‘wilful’ used in the section imports the concept of mens rea in the requirement of the section. Therefore, on mere delay or mere failure without there being mens rea, the provisions of the Section cannot be invoked. No casual approach can be adopted while invoking the provisions of the section. The provisions of the section being penal, all the ingredients of the offence must be established in the complaint. The complaint should specifically mention wilful attempts made by a person to evade tax, penalty or interest. Merely by making allegations that there is a wilful attempt to evade the tax in the complaint, the complaint cannot be maintained

vi) In the present case, the 1st Petitioner admittedly continued to pay the demands raised by the Respondent. Admittedly, there was delay in view of the closure of the business and therefore the 1st Petitioner has paid the interest. The acts of the 1st Petitioner are bona fide because the 1st Petitioner made requests and sought time to pay the tax liability and periodically kept paying the tax along with interest. Importantly, prior to filing of the said Complaint, out of Rs. 5,20,90,289/- only an amount of Rs. 26,08,047/- was not paid by the 1st Petitioner, which was paid immediately on 20th March 2017. Consequently, on 29th March 2017, the Deputy Commissioner of Income Tax, Central Circle, Panaji issued an Order holding that the net payable by the 1st Petitioner is NIL. Therefore, the acts of the 1st Petitioner cannot fall within the definition of ‘attempts’, which means an act or an instance of making an effort to accomplish something. In this case, the 1st Petitioner has paid the tax with interest, and therefore certainly the acts of the 1st Petitioner were not ‘wilful’, and there were no attempts to evade the tax liability. The Complaint does not specify the alleged wilful attempts made by the Petitioners to evade tax. The penal provisions are invoked in the present case solely on the basis of vague allegations, without establishing the ingredients of an offence.

vii) In view thereof, I am satisfied that the said Complaint filed by the Respondent is without any basis and does not fulfil the requirement of the Section. The important facts are not considered by the learned CJM. The learned CJM has mechanically passed the impugned Order when, on the face of the said Complaint, the ingredients of the offence were not made out. The learned CJM has not followed the due process of law. Therefore, I reject all the submissions made by Ms. Linhares on behalf of the Respondent. The judgments cited by Ms. Linhares are not applicable to the facts and circumstances of the present case, particularly in view of the fact that no ingredients of the offence are made out in the Complaint. Therefore, I find that no fruitful purpose will be achieved by setting the criminal law in motion. In light of the above, and in the peculiar facts and circumstances of this case, the impugned Order dated 7th November 2025 and Criminal Case pending before the Chief Judicial Magistrate, ‘A’ Court at Merces, are hereby quashed and set aside.”

BCCI v. ACIT : The Tribunal exceeded its jurisdiction by ruling on the merits of a non-statutory “advisory” communication after declaring the appeal unmaintainable

28. BCCI v. ACIT: (2026) 488 ITR 152 (Bom): 2025 SCC OnLine Bom 317: (2025) 344 CTR 883 (Bom)

Date of order 18th February 2025

Ss. 12A, 12AA and 253 of ITA 1961

A. Charitable purpose :— (a) Exemption — Registration — Director (Exemption) by letter expressing view that as consequence of amendment of objects by assessee, assessee’s registration no longer survives — Appeal by assessee to Tribunal challenging the communication — Tribunal accepting the contention of the Department and holding that appeal against communication not maintainable — On merits Tribunal upholding view expressed in communication — High Court held, Tribunal exceeded jurisdiction in going in to merits — Communication quashed with clarification that question of cancellation of assessee’s registration or entitlement to exemption would be decided by authorities without being affected by view expressed therein or by Tribunal; (b) Power to grant exemption — Power to cancel registration — No power to issue “advisories” or non-statutory opinions intending to affect an assessee.

B. Appeal to Appellate Tribunal — Appeal challenging communication to assessee from Director (Exemptions) — Department contending in assessee’s appeal that communication not an order and therefore not appealable — Tribunal accepting contention and holding appeal against communication not maintainable — Tribunal not entitled thereafter to enter upon merits of view expressed in communication.

The assessee, the Board of Control for Cricket in India (BCCI), is a society established under the Tamil Nadu Societies Registration Act with the aim of promoting sports, particularly cricket. The assessee was granted registration u/s. 12A of the Income-tax Act, 1961, on 12th February 1996. The memorandum of association of the assessee was amended on 1st June 2006 and 21st August 2007. According to the assessee, such amendments do not change the fundamental objects of the assessee, i. e., the promotion of sports. However, such changes were not intimated to the tax authorities who had granted registration u/s. 12A of the Act.

Therefore, by order dated 28th December 2009, the Director of Income-tax (Exemptions) (DIT) wrote to the assessee that since the assessee had modified its objects and no intimation of such modification was sent to the second respondent “it is quite clear that the registration granted to the assessee u/s. 12A of the Act, vide order dated 12th February 1996 does not survive from the date on which the objects were changed, i. e, 1st June 2006. However, as has been mentioned in the above para a fresh application for registration u/s. 12AA of the Act, may be filed along with necessary documents”.

The assessee filed an appeal, before the Tribunal challenging the communication. Before the Tribunal, the Revenue submitted that the Director of Income-tax (Exemptions), by the impugned communication/order dated 28th December 2009 had neither cancelled nor withdrawn the registration dated 12th February 1996 granted to the assessee u/s. 12A of the Act. He contended that by the impugned communication/order, the Director of Income-tax (Exemptions) had merely intimated the assessee of the consequences of the changes in the objects of the assessee. Based on these submissions, the Revenue contended that the appeal u/s. 253 of the Act, would not be maintainable against the impugned communication/order dated 28th December 2009.

The Tribunal, by the impugned order dated 30th March 2012, accepted the Revenue’s contention that the impugned communication/order dated 28th December 2009 did not amount to either cancellation or withdrawal of registration u/s. 12A of the Act. On this basis, the Tribunal held that the assessee’s appeal was not maintainable u/s. 253 of the Act. After recording the above conclusion in, the Tribunal addressed the merits of the communication/order dated 28th December 2009 and virtually held that the Director of Income-tax (Exemptions)’ view in that communication/order was correct.

The assessee filed an appeal challenging the Order of the Tribunal and, as a matter of abundant caution, filed a writ petition challenging the order of the Tribunal.

The Bombay High Court admitted the appeal and the writ petition and heard and disposed of together. The High Court held as under:

“i) The two main issues involved in these matters are the following:

“(A) Whether the Income-tax Appellate Tribunal, after recording a categorical finding that the impugned communication/order dated 28th December 2009 did not amount to any order of cancellation of the Board of Control for Cricket in India’s registration under section 12A of the Income-tax Act, 1961 and further holding that since there was no cancellation, no appeal was maintainable against the impugned communication/order dated 28th December 2009 under section 253 of the Income-tax Act, 1961, was justified in nevertheless examining the impugned communication/order dated 28th December 2009 on the merits and recording observations or findings virtually upholding the reasons and perhaps even the conclusion in the impugned communication/order dated 28th December 28 2009 ?

(B) Whether solely based on the impugned communication/order dated 28th December 2009, which the Revenue styled (or accepted the styling) as an advisory or a non-statutory letter, could any action to deny exemption or cancel section 12A registration be initiated by the Revenue ?”

ii) The Revenue authorities have been conferred statutory powers in matters of assessment or even cancellation of registration granted under section 12A of the Income-tax Act, 1961. The Income-tax Act also provides for a procedure to exercise such statutory powers. There is no provision that empowers the statutory authorities to issue “advisories” or non-statutory opinions intended to affect an assessee. If a power is given to do a certain thing in a certain way, the thing must be done in that way or not at all, and the other performance methods are necessarily forbidden.

iii) It is apparent that the Tribunal accepted the Revenue’s contention that the impugned communication/order dated December 28, 2009 was not an order of cancellation or withdrawal of registration u/s. 12A of the Act or an order made u/s. 12AA(3) of the Act and, therefore, no appeal was maintainable against the impugned communication/order dated 28th December 2009.

iv) Once the Tribunal concluded that the appeal before it against the impugned communication/order dated 28th December 2009was not “maintainable”, there was no question of the Tribunal evaluating the impugned communication/order on its merits or making any observations or recording any findings regarding its validity or otherwise. Therefore, such observations and findings are without jurisdiction and should not have been made.

v) Therefore, the above findings/observations will have to be ignored by the respondents, inter alia, when deciding the issue of the validity of the assessment order dated 30th December 2009or when disposing of the show-cause notices issued to the assessee for withdrawal or cancellation of its registration u/s. 12A of the Income-tax Act, 1961. This does not mean we have examined the merits of the above observations or findings recorded by the Tribunal.

vi) We have only declared that the above observations/findings are without jurisdiction and, therefore, the same should not be treated as binding by the respondents or others, mainly while deciding the appeal against the assessment order dated 30th December 2009 or in the proceedings initiated for the cancellation of the assessee’s registration u/s. 12A of the Act. All such issues should be examined by the prescribed authorities on their own merits, independently and without being influenced by the above observations or findings recorded by the Tribunal.

vii) For all the above reasons, we dispose of Writ Petition No. 1898 of 2012 by quashing the impugned communication/order dated 28th December 2009 without commenting upon the merits or demerits of the view expressed in the said impugned communication/order but on the ground that the Revenue could not have issued the impugned communication/order, which it agrees, was only an advisory or a non-statutory exercise.

viii) Once again, we clarify that the issues of exemption or cancellation of registration on the merits are left open because they will have to be decided by the prescribed statutory authorities in the manner prescribed under the statute without being influenced by either the impugned communication/order dated 28th December 2009 or the observations/findings recorded by the Tribunal.”

Rajesh R. Hemrajani v. ITAT :The High Court directed the ITAT to deliver judgment within 90 days as mandated by Rule 34 of the Rules.

27. Rajesh R. Hemrajani v. ITAT

2026 (8) TMI 292 (Bom)

A. Y. 2019-20: Date of order 31st July 2026

Rule 34 of the Income Tax Appellate Tribunal Rules, 1963

Appeal to ITAT — Order of ITAT — Time Limit — Rule 34 of ITAT Rules — Pronouncement of orders — Order to be pronounced within 60 days where no pronouncement date is given and further period not exceeding 30 days when exceptional circumstances arise.

The assessee’s appeal before the Income Tax Appellate Tribunal was first heard on 1st July 2025. As per Rule 34(5c) of the Income Tax Appellate Tribunal Rules, the order should have been passed within a period of 60 days and in exceptional circumstances within a further period of 30 days. Since in the assessee’s case, the order was not passed within the said time limit, the appeal was released on 7th October 2025.

The Appeal of the assessee came up for hearing before the Tribunal for the second time and it was heard on 26/11/2025. Once again, the order was not passed within 90 days and the appeal was released on 27th February 2026 after a period of 90 days.

The appeal was heard by the Tribunal for the third time on 13th May 2026 and as per Income Tax Appellate Tribunal Rules, the 90 days period shall expire on 13th August 2026.

The assessee filed a writ petition before the Hon’ble Bombay High Court on the ground that if the order is not passed by 13th August 2026, the appeal would once again be released by the Tribunal. The assessee thus approached the Hon’ble High Court to seek necessary directions.

The High Court allowed the petition and observed as under:

“i) Our judicial conscience is shocked by the above stated information. It cannot be countenanced that a matter closed for judgment, is released without a judgment even when Rule 34 mandates a decision within 90 days. How far would the litigants tolerate the rigours of litigation, when an appeal is released on multiple occasions. In the present case, the appeal has been finally argued on the 3rd occasion, and the time-line is to expire shortly. We have taken a serious note of this aspect.

ii) The IT Appellate Tribunal shall ensure that the judgment in the Petitioner’s case is delivered on or before 13th August 2026

iii) All the Income Tax Appellate Tribunals shall scrupulously follow Rule 34 and ensure that matters which are heard and closed for Judgment, shall also mention the date for pronouncement which shall be within the period of 60 days. A judgment should be delivered within the said period. If on account of exceptional circumstances or extra- ordinary reasons justifying further time being required by the Tribunal, the judgment shall be delivered on or before the 90th day by the concerned Bench.

iv) We direct the Prothonotary and Senior Master of this Court to circulate this order to all the Income Tax Appellate Tribunals, for compliance.”

ITO vs. Tata Industries Ltd : A payer cannot be treated as in default for not deducting tax based on subsequent retrospective indirect transfer tax amendments.

12. [2026] 185 taxmann.com 924 (Mumbai – Trib.)

ITO vs. Tata Industries Ltd

A.Y.: 2006-07 Dated: 15.04.2026

Section 9, 195 and 201 of IT Act, 1961 – The Assessee cannot be treated as an ‘assessee in default’ in respect of payment of consideration to US entities for the acquisition of shares of a foreign company based on the subsequent retrospective insertion of indirect transfer tax provisions in the Act.

FACTS

The Assessee paid a consideration of USD 150 million to two US entities, namely, New Cingular Wireless Services Inc (NCWSI) and MMM Holdings Inc (MHC), for acquiring shares in a Mauritius entity. The Mauritius entity held a stake in an Indian entity, i.e., Idea Cellular Ltd. The Assessing Officer (‘AO’) examined the holding structure & transaction documents and concluded that the acquisition of shares in a Mauritius entity resulted in an indirect transfer of shares in the hands of two US entities. Hence, the AO observed that the Assessee was obliged to deduct taxes at source. In the absence of further information from the Assessee, the AO determined the capital gains on a best-effort basis and treated the taxpayer as an ‘assessee in default’ for failing to deduct tax under Section 201 and levied interest under 201(1A).

The CIT(A) allowed the Assessee’s appeal. Aggrieved by the order, the Department preferred an appeal before the ITAT.

HELD

The ITAT upheld the order of the CIT(A) and made following observations:

  • As held by the Apex Court in GE India Technology Centre Pvt Ltd (327 ITR 456) and Engineering Analysis Centre of Excellence (432 ITR 471), the payer is obligated to deduct tax at source only if there is income chargeable to tax in India.
  • As on the date of payment of consideration, Explanations 4 and 5 to Section 9(1)(i) of the Act were not part of the statute. Before insertion of these Explanations, which brought indirect transfers within the scope of the charge with retrospective effect, the Apex Court in Vodafone International (341 ITR 1) had held that Section 9(1)(i) of the Act was applicable only to direct transfer of shares and could nott extend to an indirect transfer.
  •  A payer cannot envisage a retrospective amendment to Section 9(1)(i) at the time of making payment. Therefore, a law cannot require a person to perform acts that are impossible to comply with.

On the basis of the above, the ITAT held that the Assessee could not be treated as an ‘assessee in default’ under Section 201 of the Act and directed the AO to refund the taxes remitted under protest.

Goldman Sachs International vs ACIT (IT) : Salary reimbursement paid for seconded employees on a cost-to-cost basis is not fees for technical services under India-UK DTAA

11. [2026] 186 taxmann.com 18 (Mumbai – Trib.)

Goldman Sachs International vs ACIT (IT)

A.Y.: 2023-24 Dated: 30.03.2026

Article 13 of India-UK DTAA – Reimbursement of salary costs paid to seconded employees on a cost-to-cost basis cannot constitute fees for technical services, and is, therefore, not taxable in India.

FACTS

The Assessee, a UK tax resident, seconded a few employees to group companies in India. It also rendered financial services to group companies. As per the terms of the secondment, a part of the salary payable to the seconded employees was paid by the Assessee in the home country and was reimbursed by the Indian entities on a cost-to-cost basis.

The AO assessed the salary reimbursement received by the Assessee from Indian entities as fees for technical services (‘FTS’) under the Act and the DTAA. The Ld. DRP upheld the draft assessment order.

Aggrieved by the final order, the Assessee preferred an appeal before the ITAT.

HELD

The ITAT relied on the following aspects considered by the coordinate bench in Assessee’s group company case [Goldman Sachs Services (P.) Ltd. v. DCIT, (IT) [2022] 138 taxmann.com 162 (Bang-Trib)]. The ruling of the coordinate bench was upheld by the Karnataka High Court [2025] 179 taxmann.com 41 (Kar):

  • The Indian entity to whom the employees were seconded was the economic and de facto employer. The seconded employees offered the entire salary received in both the home and host jurisdictions for taxation in India
  • FTS, as defined under Section 9(1)(vii), excludes from its scope income chargeable under the head “Salaries”. Given that the Indian entity was regarded as the employer and the entire amount was already subject to salary taxation, reimbursement of such amounts could not constitute FTS under the Act.
  • Article 12 of the India-USA DTAA1 excludes payment for services rendered by an employee. Applying the principles of the Commentary to Article 15 of OECD Model Convention to determine the scope of income covered by the Dependent Personal Service Article (DPS), the Indian entity was regarded as the economic employer of seconded employees. Further, the overseas employer was not responsible for the actions of the expatriate employees. The scope of exclusion under the FTS Article should be consistent with the scope of DPS Article. Accordingly, reimbursement of salary without any profit element was not covered by Article 12 of the treaty.

1 FTS Article under India-UK DTAA is parimateria with India-US DTAA

Combine Diamonds (P.) Ltd. v. ACIT : Initiating assessment before furnishing recorded reasons and denying the opportunity to file objections renders the reassessment void ab initio.

51. [2026] 137 ITR(T) 129 (Mumbai – Trib.)

Combine Diamonds (P.) Ltd. v. ACIT

A.Y.: 2009-10 DATE: 11.03.2026

Sec. 68 r.w.s. 147 and 148 – Assessee requested recorded reasons after notice under section 148 – Assessing Officer issued notice under section 142(1) before furnishing reasons and, on furnishing reasons, simultaneously issued notices under sections 142(1) and 143(2) without giving reasonable opportunity to file objections – Whether non-compliance with procedure laid down by Supreme Court in GKN Driveshafts (India) Ltd. v. ITO renders reopening and consequential assessment void ab initio – Held, yes

FACTS

The assessee filed its return of income declaring total income of Rs. 68.43 lakhs, which was assessed under section 143(3). Subsequently, a notice under section 148 dated 23.03.2016 was issued to reopen the assessment on the basis of information regarding alleged hawala transactions and bogus purchases.

In response to the notice under section 148, the assessee requested that the original return be treated as the return filed in response to the notice and, by letters dated 04.04.2016 and 21.05.2016, sought the reasons recorded for reopening.

Without furnishing the recorded reasons, the Assessing Officer issued a notice under section 142(1) on 01.07.2016. Thereafter, on 15.07.2016, the Assessing Officer furnished the recorded reasons and, on the very same day, issued notices under sections 142(1) and 143(2), without waiting for the assessee to file objections or affording reasonable time for filing objections.

The assessee subsequently filed objections, which were disposed of by the Assessing Officer by letter dated 09.09.2016. Reassessment was thereafter completed under section 143(3) read with section 147, making an addition of Rs. 29.35 lakhs. The Commissioner (Appeals) sustained the reopening and the addition.

Aggrieved, the assessee appealed before the Tribunal and challenged, inter alia, the validity of the reopening on the ground of non-compliance with the procedure prescribed by the Supreme Court in GKN Driveshafts (India) Ltd. v. ITO.

HELD

The Tribunal observed that the Supreme Court in GKN Driveshafts (India) Ltd. v. ITO had laid down that, upon issuance of notice under section 148: the assessee may seek the recorded reasons; the Assessing Officer is bound to furnish such reasons within a reasonable time; thereafter, the assessee is entitled to file objections; and, the Assessing Officer is required to dispose of the objections by passing a speaking order.

In the present case, the Assessing Officer proceeded with the assessment by issuing a notice under section 142(1) even before furnishing the reasons sought by the assessee. More importantly, after furnishing the reasons on 15.07.2016, the Assessing Officer simultaneously issued notices under sections 142(1) and 143(2), without waiting for the assessee to file objections or giving reasonable time for doing so.

The Tribunal noted that the procedure prescribed in GKN Driveshafts (India) Ltd. was mandatory. It also relied upon the decisions of the Bombay High Court in Fomento Resorts & Hotels Ltd. v. ITO, [Tax Appeal No. 63 of 2007], CIT v. Videsh Sanchar Nigam Ltd. [2012] 21 taxmann.com 53 and Pr. CIT v. Shodiman Investments (P.) Ltd., [2018] 93 taxmann.com 153 as well as the Gujarat High Court’s decision in Troikaa Pharmaceuticals Ltd., [2023] 156 taxmann.com 621 which emphasised compliance with the prescribed procedure before proceeding with reassessment.

The Tribunal distinguished the contrary view of the Madras High Court in Home Finders Housing Ltd. v. ITO [2018] 93 taxmann.com 371 and noted the Karnataka High Court’s view in Hewlett Packard Financial Services (India) (P.) Ltd. [2023] 152 taxmann.com 559 that the procedure prescribed in GKN Driveshafts (India) Ltd. is mandatory and its violation vitiates the assessment.

Since the Assessing Officer had initiated assessment proceedings before furnishing the recorded reasons and had proceeded further without allowing the assessee an opportunity to file objections against the reopening, there was clear non-compliance with the mandatory procedure laid down by the Supreme Court.

Accordingly, the Tribunal quashed the notice under section 148 and declared the consequential assessment order as void ab initio.

The appeal filed by the assessee was allowed.

Shreyas Naynesh Modi v. ITO : The ten percent safe harbour limit applies to the fair market value determined by the Valuation Officer under section 56(2)(x).

50. [2026] 136 ITR(T) 489 (Mumbai – Trib.)

Shreyas Naynesh Modi v. Income-tax Officer

A.Y.: 2018-19 DATE: 23.01.2026

Sec. 56(2)(x) r.w.s. 50C and 55A – Assessee purchased flat for Rs. 2.65 crore against stamp duty valuation of Rs. 3.79 crore – On assessee’s objection, reference to DVO was made who determined FMV at Rs. 2.81 crore – Addition made under section 56(2)(x) on difference between DVO’s FMV and purchase consideration – Whether, the DVO’s FMV replaces SDV and safe harbour limit of 10% applies with reference to FMV determined by DVO – Held, yes

FACTS

The assessee, an individual, filed his return of income for A.Y. 2018-19 declaring total income of about Rs. 8.07 lakhs. The case was selected for scrutiny and notices under sections 143(2) and 142(1) were issued.

He had purchased a flat in Mumbai on 12.04.2017 for a consideration of Rs. 2.65 crores. A registered valuer had estimated its market value at Rs. 2.50 crores, whereas the stamp duty valuation was Rs. 3.79 crores.

During assessment proceedings, the assessee disputed the applicability of section 56(2)(x) and requested that a reference be made to the Departmental Valuation Officer (DVO) under section 55A. The DVO determined the fair market value of the property at Rs. 2.81 crores.

The Assessing Officer added Rs. 16.13 lakhs under the head ‘income from other sources’, being the difference between the DVO’s FMV and the purchase consideration.

On appeal, the Commissioner (Appeals) dismissed the assessee’s claim, holding that the 10% tolerance introduced by Finance Act, 2018 was not applicable to A.Y. 2018-19. The Division Bench, noticing contrary Tribunal decisions, referred the issue to a Special Bench.

HELD

The Special Bench noted that the DVO’s valuation of Rs. 2.81 crores and the purchase consideration of Rs. 2.65 crores differed by 6.09%, which was within the 10% safe harbour limit. The issue before it was whether such limit could be applied with reference to the FMV determined by the DVO.

The Tribunal observed that the safe harbour provisions under sections 50C, 43CA and 56 were introduced to mitigate hardship in genuine real estate transactions, recognising that variations between stamp duty value and actual consideration may arise due to factors such as location and other characteristics of the property.

It held that valuation of an asset necessarily involves estimation and that the DVO’s FMV was also an estimate. Once the assessee disputes the stamp duty valuation and seeks a reference to the DVO, the valuation determined by the DVO replaces the stamp duty valuation for all practical purposes.

The Tribunal therefore held that the safe harbour rule under the third proviso to section 50C(1), and the corresponding provisions including section 56(2)(x), applies to the FMV determined by the DVO. The deeming provision must be taken to its logical end and the beneficial provision must be interpreted purposively and liberally to mitigate hardship in genuine transactions.

Accordingly, the issue was answered in the affirmative

Consolidated Finvest and Holdings Ltd. v. DCIT : Referring valuation under general provisions instead of section 50C(2) denies the department the time-limit extension under section 153.

49. (2026) 188 taxmann.com 1085 (Del Trib)

Consolidated Finvest and Holdings Ltd. v. DCIT

A.Y.: 2017-18 Date of Order: 24.07.2026

Sections: 50C, 142A, 153

Where, in making an addition under section 50C, the AO referred the property valuation to the DVO under the general provision of section 142A instead of the special provision of section 50C(2), no extension of the assessment time limit under Explanation 1(v) to section 153 was available.

FACTS

The assessee-company, an NBFC engaged in providing loans and making investments, filed its return for A.Y. 2017-18 and later a revised return declaring total income of Rs. 9,24,88,434. It sold a property at Nariman Point, Mumbai, for a sale consideration of Rs. 2,16,40,000, while stamp duty was paid on a circle rate of Rs. 2,85,80,744. The assessee contended that the Stamp Valuation Authority’s value exceeded fair market value and placed on record an independent Government valuer’s report valuing the property at Rs. 2,13,28,000.

The AO referred the valuation to the Departmental Valuation Officer (DVO) on 11.11.2019, a fact never intimated to the assessee during the assessment proceedings. No DVO report was received before completion of assessment, and the AO completed the assessment on 28.09.2021, invoking section 50C and making an addition of Rs. 69,40,744 for the difference between the circle rate and the actual sale consideration.

On appeal, CIT(A) held that the reference was in fact made under section 142A, and that it attracted the extended time limit under Explanation 1(v) to section 153 (further extended on account of COVID-19 relaxations) making the assessment dated 28.09.2021 timely, and upheld the addition on merits.

Aggrieved, the assessee filed an appeal before ITAT.

HELD

The Tribunal observed as follows:

(a) CIT(A) had categorically found that the reference in the present case was made by the AO to the DVO only under section 142A. Section 142A is a residuary, general provision for valuation of any asset, whereas section 50C(2) is a special, specific provision for determining the fair value of a capital asset for computing capital gains under section 48. It is trite law, per the maxim generalia specialibus non derogant, that where there is a conflict between a general and a special provision, the special provision prevails.

(b) Section 50C being a self-contained special provision mandating reference to the DVO where the assessee objects to the Stamp Valuation Authority’s value, and section 153(1) not extending any additional time limit for a reference made under section 50C(2), the AO ought to have completed the assessment within the original time limit, i.e., on or before 31.12.2019, and could have amended the order under section 155(15) upon subsequent receipt of the DVO’s report. This was not undertaken.

(c) Since the reference could not be treated as validly made under section 142A, for this purpose, the extended time limit under section 153 was not available, and the assessment completed on 28.09.2021 was barred by limitation. In any event, no DVO valuation report had been furnished even by the date of completion of assessment, while the assessee had placed on record an independent Government valuer’s report which the AO ought to have considered but did not.

Accordingly, the Tribunal held that the assessment framed on 28.09.2021 was barred by limitation, both on law and on facts, and directed that the addition made thereunder be deleted.

In the result, the appeal of the assessee was allowed.

Hotel Mahalaxmi v. ITO : Notional revaluation of leasehold rights by book entry without new investment cannot be added as unexplained investment under section 69.

48. (2026) 188 taxmann.com 871 (Mum Trib)

Hotel Mahalaxmi v. ITO

A.Y.: 2018-19 Date of Order: 16.07.2026

Section: 69

Where the assessee-firm revalued its existing tenancy/leasehold rights in its business premises on the basis of a Government-approved valuer’s report, crediting the differential to partners’ capital accounts without acquiring any new asset, introducing funds, paying consideration to any third party, or claiming depreciation on the revalued amount, such a book revaluation could not be treated as unexplained investment under section 69.

FACTS

The assessee, a partnership firm engaged in running a hotel/restaurant, had been in continuous possession and occupation of its business premises under tenancy/leasehold rights since 1984. During the relevant year, it revalued the existing tenancy/leasehold rights on the basis of a report by a Government-approved valuer and recorded the revaluation by debiting the fixed asset account and crediting the partners’ capital accounts. No new asset was acquired, no funds were introduced, no consideration was paid to any third party, and no depreciation was claimed on the revalued amount.
The AO treated the revaluation amount of Rs. 18,19,51,875 as unexplained investment under section 69 and added it to the total income.

Upon appeal to CIT(A), the addition was upheld.

Aggrieved, the assessee filed an appeal before the Tribunal.

HELD

The Tribunal observed as follows:

(a) Section 69 applies only where the assessee makes an investment not recorded in the books and offers no explanation as to its nature and source. In the present case there was no investment at all: the tenancy/leasehold asset had already existed with the assessee since 1984, the revaluation was duly recorded in the books, and there was no inflow of funds; invocation of section 69 was therefore wholly misconceived.

(b) Revaluation is a recognised accounting practice undertaken to reflect fair market value and does not result in real income, accrual or receipt, following the Supreme Court’s ruling in CIT v. Shoorji Vallabhdas & Co., (1962) 46 ITR 144 (SC), that income-tax is levied on real income and not on a hypothetical or book entry that does not materialise into actual income.

(c) The tenancy right was not acquired during the year under appeal – the assessee had held it since 1984, as evidenced by municipal records, business licences and rent receipts – so the revaluation could not be equated with an acquisition of a new asset.

(d) There was no transfer within the meaning of section 2(47), as there was no sale, relinquishment or extinguishment of rights, and the asset continued to be held by the assessee; consequently, there was no question of capital gains that arose either.

(e) Simple revaluation of assets by book entry does not give rise to any liability under the Act, following Sanjeev Woollen Mills v. CIT, (2005) 279 ITR 434 (SC), where the Supreme Court held that a notional or imaginary profit arising from revaluation of a fixed asset by a book entry cannot be taxed, and CIT v. Birla Gwalior (P.) Ltd., (1973) 89 ITR 266 (SC), that mere revaluation of assets for accounting purposes does not give rise to taxable income. Where the differential on revaluation is credited to partners’ capital accounts, no transfer under section 2(47) takes place, following Ravinshankar R. Singh v. ITO, (2014) 45 taxmann.com 359 (Mum).

Accordingly, the Tribunal held that the addition made by the AO and sustained by CIT(A) under section 69 was not sustainable in law, and directed that it be deleted.

In the result, the appeal filed by the assessee was allowed.

Amaltash Residents Welfare Association v. CIT(E): Exclusive member-only maintenance activities are governed by mutuality and do not constitute a charitable purpose under section 12AB.

47. (2026) 188 taxmann.com 868 (Chd Trib)

Amaltash Residents Welfare Association v. CIT(E)

A.Y.: 2027-28 Date of Order : 23.07.2026

Sections: 2(15), 12AB

Where a Residents Welfare Association’s activities of providing maintenance, security, housekeeping and related facility management were confined exclusively to its own members and residents of a particular residential complex, with no benefit extending to the public at large or an indeterminate section thereof, such activities were governed by the principle of mutuality and did not constitute a charitable purpose under section 2(15); CIT(E) had rightly rejected the application for registration under section 12AB.

FACTS

The assessee, a Residents Welfare Association constituted for the welfare, maintenance and management of a residential complex, filed Form No. 10AB seeking registration under section 12AB for A.Y. 2027-28. Its stated activities involved providing maintenance, security, housekeeping, facility management and related services to residents, collecting maintenance charges, service fees and other contributions from members, and deriving rental income from common facilities.

On examining the objects and activities, the CIT(E) observed that the society was primarily engaged in providing maintenance and related services to residents of a specified residential complex; that the activities were confined to a closed group of members and operated on principles of mutuality; and, that they did not constitute charitable activities within the meaning of section 2(15). The application for registration under section 12AB was accordingly rejected.

Aggrieved, the assessee filed an appeal before ITAT.

HELD

The Tribunal observed as follows:

(a) The concept of charity necessarily presupposes an element of public benefit, founded on altruism and philanthropy without expectation of reciprocal advantage. A Residents Welfare Association, by contrast, functions on the principle of mutuality: every member contributes maintenance charges and receives maintenance and common facilities in return, so that contributors and beneficiaries substantially constitute the same class of persons.

(b) Services such as maintenance of common areas, security, housekeeping, and organising social or cultural programmes are essentially contractual or reciprocal services rendered for consideration collected from the members themselves, and cannot be equated with relief of the poor, education, medical relief, preservation of environment or any other recognised charitable object under section 2(15). Accepting a contrary interpretation would mean every association formed for mutual convenience becomes entitled to registration under section 12AB, obliterating the distinction the Legislature has consciously maintained between mutuality and charity.

(c) The beneficiaries of the assessee were confined exclusively to its members and residents of a particular housing complex, with no element of benefit available to the public at large or to an indeterminate section of the public. The activities were therefore governed by the doctrine of mutuality and not by the principles governing charitable institutions.

(d) On the plea of inadequate opportunity of hearing, no useful purpose would be served by remanding the matter, since the rejection was founded not on insufficiency of evidence but on the very nature and character of the assessee’s activities; a remand would be an empty formality without altering the legal position.

Accordingly, the Tribunal held that since the admitted objects and activities of the assessee did not satisfy the statutory requirement of “charitable purpose” under section 2(15), the CIT(E) had rightly rejected the application for registration under section 12AB, and upheld the impugned order.

In the result, the appeal of the assessee was dismissed.

Rajesh Shamji Furia v. ITO : The Tribunal held that a flat acquired under a development agreement qualifies as a long-term asset, allowing section 54 exemptions.

46. ITA No. 1672/Mum./2026

Rajesh Shamji Furia v. ITO

A.Y.: 2018-19 Date of Order: 16.07.2026

Sections: 2(42A), 45, 54, 54F

A redevelopment scheme does not result in extinguishment of the owner’s proprietary rights followed by acquisition of an altogether fresh capital asset. The ownership rights of an existing member continue throughout the redevelopment process and merely undergo substitution from the old structure to the newly constructed premises.

FACTS

The assessee, jointly with his wife, had acquired the original residential flat measuring 510 sq. ft. in Financial Year 2006-07. Subsequently, the society entered into a redevelopment arrangement with the developer under the Development Agreement (DA) executed on 15.02.2013. Under the said agreement, every existing member became entitled to receive, in lieu of the existing premises, a permanent alternate accommodation (PAA) comprising the original carpet area together with 30% additional carpet area without any monetary consideration. The assessee also became entitled to additional area purchased from the developer under the redevelopment scheme and a further area transferred by his mother. The Permanent Alternate Accommodation Agreement (PAAA) was entered into on 12.01.2018 in which Flat No. 503 was allotted to the assessee as the PAA to which the assessee had already become entitled under the redevelopment arrangement. The assessee sold the said flat on 20.01.2018 and claimed exemption under section 54/54F of the Act on investment in another residential house.

The Assessing Officer (AO), while computing capital gains, proceeded on the footing that Flat No. 503 was a completely new capital asset acquired only upon execution of the PAAA. Since the flat was sold on 20.01.2018, the AO held that the holding period was less than twenty-four months and accordingly assessed the gains as Short-Term Capital Gains, denied the benefit of indexation, and also rejected the claim of exemption under section 54/54F of the Act.

Aggrieved, the assessee preferred an appeal to the CIT(A) who affirmed the said view taken by the AO.

HELD

A redevelopment scheme does not result in extinguishment of the owner’s proprietary rights followed by acquisition of an altogether fresh capital asset. The ownership rights of an existing member continue throughout the redevelopment process and merely undergo substitution from the old structure to the newly constructed premises. The Permanent Alternate Accommodation Agreement neither creates ownership for the first time nor results in acquisition of an independent capital asset. It merely identifies and records the permanent alternate premises allotted in substitution of the existing premises, pursuant to rights which had already accrued under the Development Agreement. Therefore, the execution of the Permanent Alternate Accommodation Agreement (PAAA) cannot be regarded as the starting point for computing the period of holding.

In view of the observations in PCIT v. Vembu Vaidyanathan (2019) 413 ITR 248 (Bom.) as well as the decision of the co-ordinate Bench in Mrs. Urmila Jagdish Mehta v. ACIT (ITA No. 5944/Mum/2024, order dated 29.12.2025), the Tribunal held that the period of holding cannot be counted from the date of execution of the conveyance deed or the Permanent Alternate Accommodation Agreement. It held that what is relevant is the point of time when enforceable rights in the property come into existence.

Applying the aforesaid principle, it found that the assessee acquired the original flat in the year 2006. The Development Agreement executed on 15.02.2013 recognised and crystallised the assessee’s entitlement to receive the redeveloped premises consisting of the original carpet area together with 30% additional area without consideration. The additional area purchased from the developer also originated under the same Development Agreement. Also, the area transferred by the assessee’s mother derived its character from rights already held by her, and upon transfer, the assessee stepped into her shoes for determining the period of holding. Therefore, each component comprised in Flat No. 503 emanated from pre-existing rights under the redevelopment arrangement and cannot be dissected into separate capital assets merely because the PAAA was executed subsequently.

The Tribunal found itself unable to agree with the finding of the CIT(A) that the original flat was transferred to the developer and thereafter a new independent asset came into existence. It held that the redevelopment agreement itself shows that the developer merely undertook reconstruction of the society building in consideration of development rights. The existing members never purchased the redeveloped flats as independent purchasers. Rather, they continued to hold their ownership interest in the land and the building, which was substituted by the permanent alternate accommodation allotted in the redeveloped structure. Thus, the redeveloped flat was continuation of the existing capital asset and not acquisition of a fresh capital asset for the first time on 12.01.2018.

The Tribunal held that even assuming, for the sake of argument, that the period of holding is reckoned from the date of the Development Agreement, 15.02.2013, the capital asset was held by the assessee for almost five years before its sale on 20.01.2018, which is well beyond the statutory period prescribed for treating the asset as a long-term capital asset. It observed that, therefore, it is not necessary for us to finally adjudicate whether the holding period should commence from the original acquisition in the year 2006 or from the crystallisation of rights under the Development Agreement in the year 2013, since the asset qualifies as a long-term capital asset under either view.

The Tribunal observed that the assessee has invested the capital gains in purchase of another house within the period prescribed under section 54/54F of the Act. It held that having held that the gains are LTCG, denial of exemption under section 54/54F by the AO and CIT(A) cannot be sustained.

Sanchit Gupta v. DCIT : No liability for higher TDS applies if the system fails to flag an inoperative PAN, provided the seller paid taxes

45. (2026) 1 (CTOTTJ 1692 (Delhi)

Sanchit Gupta v. DCIT

A.Y.: 2024-25

Date of Order: 21.05.2026

Sections: 194IA, 200A, 206AA

No liability to deduct TDS at higher rate prescribed in section 206AA can be cast on the deductor since the system did not red flag the PAN of the deductee as inoperative PAN and consequences of such inoperative PAN provided evidence is brought on record to establish that the seller of the property has reflected sale of property in his return and due taxes are paid.

FACTS

The assessee, along with two co-owners, purchased property during the year under consideration. The consideration paid/ payable by the assessee was Rs. 30,60,000. The assessee deducted and deposited income-tax at source (TDS) under section 194IA of Rs. 30,600 @ 1 per cent of the amount of consideration payable to the seller, vide Challan-cum-statement in Form No. 26QB dated 28th August, 2023. However, the PAN of the seller was not linked with Aadhar, rendering the PAN inoperative as per rule 114AAA(3), which in such cases mandates deduction of income tax at source at higher rate. Thus, in such a situation, section 206AA read with rule 114AAA(3) got triggered, and the assessee’s liability to deduct income tax at source (TDS) was @ 20 per cent of the amount of consideration payable to the seller or the stamp duty value of the property, whichever is higher, while the assessee had deducted TDS @ 1 per cent of the amount of consideration payable to the seller, which led the CPC, TDS to raise demand of Rs. 5,81,400 towards short deduction of income tax at source, and Rs. 5,814 towards interest on short deduction, vide intimation under section 200A dated 29th August, 2023, raising in aggregate demand of Rs. 5,87,210 against the assessee.

Aggrieved, the assessee preferred an appeal to the CIT(A) who upheld the action of CPC, TDS.

Aggrieved, the assessee preferred an appeal to the Tribunal.

HELD

Stringent provisions such as section 206AA are placed on the statute to curb tax evasion and strengthen tax administration. The risk assessment of such inoperative PAN for non-filing of return or evading taxes are on a higher pedestal. The onus is placed on the deductor to ensure that the PAN of the deductee is not inoperative, otherwise higher TDS rates becomes applicable. It observed that the assessee was required to deduct income tax at source @ 20 per cent on the payments made for purchase of property or stamp duty value, whichever is higher, but the assessee deducted income tax at source @ 1 per cent under section 194IA.

The Tribunal held that when the Department is bringing such a stringent measure, and is upgrading its systems and operations through higher technology on a regular and continuous basis, it was expected all the inoperative PANs should have been red-flagged by the system itself, so that once the deductor or any other person wishes to transact with such person holding inoperative PAN due to non-linkage of PAN with Aadhaar number, the system automatically flags that the PAN of the deductee is inoperative. In such cases TDS is required to be deducted as provided under section 206AA read with rule 114AAA(3). Thus, the consequences thereof should have been auto-flagged by the Department’s system reflecting that the income tax is required to be deducted @ 20 per cent with respect to purchase of property instead of rate of TDS @ 1 per cent as stipulated under section 194IA. It held that the Department is equally responsible for such failure. Under these facts and circumstances, it deemed it appropriate that no liability to higher TDS under section 206AA read with rule 114AAA be cast on the assessee, provided evidence is brought on record that the deductee i.e. seller of the property has declared and disclosed the said sale transaction of sale of property in her return of income filed with the Department and due taxes are paid.

The assessee was directed to produce the necessary evidences to that effect. It simultaneously issued directions to the Revenue to verify from their database as to whether the deductee i.e. seller in the instant case has duly declared and disclosed the income arising from the sale of said property and due taxes paid to the Revenue, otherwise appropriate proceedings under the 1961 Act if permitted by law can be initiated against the said deductee i.e. seller.

Hemant Kumar Agrawal v. ITO : Partner’s remuneration from a firm cannot be treated as turnover or gross receipts to qualify for presumptive taxation under section 44ADA.

44. ITA No. 4728/Mum./2025

Hemant Kumar Agrawal v. ITO

A.Y.: 2018-19 Date of Order: 30.01.2026

Section: 44ADA

Remuneration received by an assessee from a partnership firm cannot be treated as turnover to qualify for gross receipts u/s 44ADA of the Act. Accordingly, the remuneration received by a partner from the firm in which he is a partner will not qualify to be covered by section 44ADA of the Act.

Such remuneration received from partnership firm / LLP would qualify to be treated as income under the head ‘business and profession’ and expenditure, if any, incurred for the purpose of earning of such income can be allowed as deduction.

FACTS

The assessee, a practicing Chartered Accountant, an associate full-time partner with the firm M/s Jayesh Sanghrajka and Co. LLP, received a remuneration of Rs 18,00,000 from the said firm. In the return of income, this amount of remuneration was treated as “gross receipts from business” and offered for taxation in accordance with section 44ADA of the Act. Accordingly, an income of Rs 9,00,000 was shown on presumptive basis.

The Assessing Officer (AO) held that the remuneration received by the assessee from partnership firm cannot be treated as “gross receipt” within the meaning of provisions of section 44ADA of the Act. He, accordingly, added back the expenditure of Rs 9,00,000 claimed by the assessee as deduction under section 44ADA of the Act.

Aggrieved, the assessee preferred an appeal to the CIT(A) who confirmed the action of the AO.
Aggrieved, the assessee preferred an appeal to the Tribunal.

HELD

The Tribunal noted that the income of assessee was from his professional endeavours but in the form of remuneration from the LLP. The Tribunal observed that in view of the ratio of the decisions of the Madras High Court in case of Anandkumar v. ACIT [AIRONLINE 2020 Mad 2136] and Bombay High Court in case of Perizad Zorabian Irani v. PCIT [(2022) 139 taxmann.com 164 (Bom. HC)], remuneration and interest received by the assessee from the partnership firm cannot be termed to be the turnover of the assessee.

It held that the key requirement of presumptive taxation under section 44ADA, could not be satisfied by the assessee in present case, as the remuneration received by the assessee cannot be treated as turnover, to be qualified for ‘gross receipt’ within the meaning of section 44ADA.

It accepted the alternate contention made on behalf of the assessee that such remuneration received from partnership firm / LLP would qualify to be treated as income under the head ‘business and profession’ and expenditure, if any, incurred for the purpose of earning of such income can be allowed as deduction, as held by the Apex Court in the case of CIT v. Ramniklal Kothari [74 ITR 57 (SC)] also supported with the decision of ITAT Delhi, in the case of Atul Kumar Vs. ITO [(2025) 180 taxmann.com 120 (Delhi Trib.)].

The Tribunal held that the income of the assessee, being a practicing Chartered Accountant, earned as remuneration on account of professional engagements, from a chartered accountancy partnership firm / LLP working as a partner would not qualify for inclusion in turnover as “gross receipt” for the purpose of section 44ADA. However, the income from remuneration shall be taxed as income from business and profession, so the expenses, if any, having direct nexus for earning of such income shall be allowed as deductible expenses as per provisions of the Act

Vidhya Vivek Padgaonkar v. ITO: Receipts from educational content assignments constitute professional income under section 44ADA, not business receipts eligible for presumptive taxation under section 44AD.

43. ITA No. 3042/Mum./2026

Vidhya Vivek Padgaonkar v. ITO

A.Y.: 2024-25 Date of Order: 24.06.2026

Sections: 28(v), 40(b), 44AA, 44AD, 44ADA

Section 44AA(1) is inclusive in nature and is not confined only to professions expressly named therein. What is material is character of activity undertaken and degree of specialised knowledge required for its performance. Accordingly, assessee entrusted with functions requiring inherently specialised knowledge, expertise and intellectual application in the field of education was held to be governed by section 44ADA and not section 44AD of the Act.

The taxable event in the hands of the partner is the receipt or accrual of such remuneration. The operation of Section 40(b) is confined to computation of income in the hands of the firm and does not govern the taxability of the amount actually received by the partner.

FACTS I

The assessee filed her return of income declaring therein income from house property, income from services rendered to M/s Apeejay Education Society and remuneration received from Paddy Services LLP. The Assessing Officer (AO) assessed the total income under section 143(3) of the Act by making the following two additions –

(i) Rs 6,42,840 by invoking provisions of section 44ADA; and

(ii) Rs 2,51,704 on account of disallowance claimed on remuneration from firm

The assessee received aggregate consideration of Rs 14,61,000 (subject to TDS u/s 194J) from M/s Apeejay Education Society with whom she was engaged on a contractual basis to undertake academic and curriculum-related assignments. The responsibilities entrusted to her included conceptualisation, preparation and review of academic content and curriculum structure. The assessee treated these receipts as business receipts and offered them for taxation under section 44AD of the Act. The AO held that the nature of services rendered by the assessee is professional in nature and in view of the provisions of section 44AD(6) of the Act, the said receipts are chargeable to tax u/s 44ADA of the Act. He was also influenced by the fact that tax was deducted at source under section 194J of the Act.

Aggrieved, the assessee preferred an appeal to the CIT(A) who upheld the action of the AO.

HELD I

At the outset, the Tribunal observed that the short question requiring adjudication is whether the receipts derived by the assessee from M/s Apeejay Education Society constitute business income eligible for presumptive taxation under Section 44AD or professional income governed by Section 44ADA.

The Tribunal observed that the engagement letter and the nature of responsibilities discharged by the assessee left little room for doubt that the services rendered were not routine commercial or trading activities. The assessee was entrusted with academic and curriculum-related assignments involving conceptualisation, preparation, evaluation and review of educational content. Such functions inherently require specialised knowledge, expertise and intellectual application in the field of education.

Section 44AD expressly excludes from its ambit any person carrying on a profession referred to in section 44AA(1). The expression employed in section 44AA(1) is of wide amplitude and includes, inter alia, technical consultancy and other professions requiring specialised knowledge and expertise.

It held that the services rendered by the assessee fall within the broad spectrum of professional services contemplated under the said provision. The contention that the profession carried on by the assessee is not specifically enumerated in section 44AA(1) was not accepted. It further held that the statutory provision is inclusive in nature and is not confined only to the professions expressly named therein. What is material is the character of the activity undertaken and the degree of specialised knowledge required for its performance. The Tribunal further observed that though deduction of tax under section 194J may not be determinative by itself, it nevertheless constitutes a relevant factor indicating the nature of the services rendered. In the present case, it held such deduction to be consistent with the substantive nature of the work performed by the assessee.

The Tribunal upheld the findings recorded by the CIT(A) that the receipts in question are professional receipts and that the provisions of Section 44ADA have been correctly applied by the AO.

FACTS II

The assessee received remuneration of Rs.10,91,000/- from Paddy Advisory Services LLP. However, in the hands of the said LLP a deduction of only Rs 8,39,296 was allowed. The assessee contested that in her hands only Rs 8,39,296 should be taxed. The CIT(A) confirmed the action of the AO. Aggrieved, the assessee preferred an appeal to the Tribunal.

HELD II

The Tribunal, having noted the provisions of section 28(v) of the Act, held that the taxable event in the hands of the partner is the receipt or accrual of such remuneration and that the assessee had admittedly received remuneration aggregating to Rs.10,91,000/- from the LLP during the relevant previous year. It held that the disallowance of a portion of such remuneration in the hands of the LLP under section 40(b) does not alter the character or quantum of remuneration received by the partner. It held that the operation of section 40(b) is confined to computation of income in the hands of the firm and does not govern the taxability of the amount actually received by the partner. Once the receipt of remuneration to the extent of Rs.10,91,000/- is undisputed, there exists no legal basis for restricting its taxation in the hands of the assessee to Rs.8,39,296/- merely because a part thereof was disallowed while computing the income of the LLP. The ground of appeal was decided against the assessee

Compilor’s Note: Though the ground was decided against the assessee based on the facts on record, the statutory proviso to section 28(v) provides relief to a partner by restricting taxability to the amount allowed as a deduction in the hands of the firm.

The Courage to Walk Alone

There is a quiet dignity in those who have the courage to walk alone. Society often celebrates those who lead crowds, influence opinions, and command attention. Yet some of life’s greatest acts of courage are performed in silence, without applause or recognition. They belong to those who continue their journey with unwavering faith, even when the path before them is uncertain and the companionship they once cherished is no longer beside them.

As human beings, we are created for relationships. We seek acceptance, companionship, and the reassurance that comes from walking life’s journey with others. Family shapes us, friendships strengthen us, and shared dreams give meaning to our days. Naturally, we find comfort in belonging. Yet there are moments when we must choose between following the crowd and following the quiet voice of our conscience. Standing by one’s principles, despite criticism or misunderstanding, requires uncommon courage. History remembers such individuals because they dared to think independently when it was easier to conform.

Walking alone, in this sense, is never about pride or isolation. It is about integrity. It is about having the strength to remain faithful to one’s values, even when approval is withheld. Such moments refine character. They teach us that truth often demands solitude before it receives acceptance.

But life, in its infinite wisdom, slowly reveals that there is an even deeper meaning to walking alone.

Sometimes, we choose solitude because our convictions demand it. At other times, life chooses it for us.

There comes a moment when destiny quietly rewrites the script we had imagined for ourselves. The hand that once held ours through every joy and every storm is no longer there. The conversations that filled our home become memories. The shared laughter echoes only in the heart. Without warning, the journey that was meant to be travelled together becomes one that must be continued alone.

No one willingly prepares for such solitude.

To lose the person who walked beside us is to lose not merely a companion, but a part of our own existence. In those moments, courage acquires an entirely different meaning. It is no longer the courage to defend an opinion or pursue an unconventional dream. It becomes the courage to awaken each morning with an aching heart, to fulfil responsibilities when grief weighs heavily upon the soul, to smile when tears remain unseen, and to keep walking when every instinct longs to stop.

This is perhaps the purest form of courage. Not the courage that changes the world, but the courage that quietly refuses to let sorrow define one’s life.

Our ancient belief & wisdom reminds us that relationships belong to time, but love belongs to eternity. The body is transient; the soul is not. Those we love never truly disappear. They become woven into our thoughts, our values, our prayers, and the countless quiet moments when we instinctively seek their presence. Every act of kindness reflects what they taught us. Every decision made with integrity honours the life they shared with us. In this way, love transcends physical absence and
becomes a silent companion on every step of our journey.

Gradually, solitude begins to lose its harshness. What first appeared to be emptiness slowly becomes sacred space, a place where grief is transformed into gratitude, where longing deepens into remembrance, and where faith gently fills the silence that loss has left behind. We begin to realise that we are not truly walking alone. The companionship that once came through another’s hand is now experienced through an unseen grace that steadies our spirit and strengthens our resolve.

Perhaps this is the greatest lesson life teaches us. Courage is not simply the strength to stand apart from the crowd. Nor is it merely the determination to pursue one’s convictions. The highest expression of courage is to continue living with love after loss, to embrace life without bitterness, and to transform grief into compassion, purpose, and quiet hope.

The journey may no longer look the way we had imagined. The road may be lonelier than we ever expected. Yet every step taken with faith becomes a prayer. Every sunrise becomes a reminder that life still holds purpose. Every act of goodness becomes a tribute to the one who now walks beside us in spirit rather than in sight.

And perhaps that is the deepest truth of all. We may think we are walking alone, but love never leaves us, faith never abandons us, and the Divine never ceases to guide us. Those who find the courage to keep walking discover that the path of solitude is, in the end, the path that leads them closest to God.

It takes immense strength to rebuild life after profound loss. Every step taken forward is a quiet victory over despair and a tribute to the one who is deeply missed.

Vedanta Limited Demerger Disclosures

COMPILER’S NOTE:

In recent times, corporate India has been undergoing restructuring with – demergers being one of the most adopted method for the same. This, ostensibly unlocks value and creates more wealth for the shareholders and in the process also enables succession planning and focus for the promoters also. There is no specific Indian Accounting Standard (Ind AS) to govern accounting for such demergers. The disclosures are mainly governed by Ind AS 105 (Discontinued Operations), Ind AS 108 (Segment Reporting), Ind AS 1 (framework for preparing and presenting general-purpose financial statements) and Schedule 3 of the Companies Act 2013. These demergers besides approval from the National Company Law Tribunal and Securities & Exchange Board of India (SEBI – for listed entities), also require approvals from several state and central government ministries and agencies.

Given below are disclosures for a company which has demerged its operations into 6 specific business units.

VEDANTA LIMITED

Extracts from notes to Standalone Financial Statements for the year ended 31st March, 2026

Note 3(d): Acquisitions, Restructuring and Disposal of Subsidiary

(i) Scheme of Arrangement for demerger

On 29 September 2023, the Board approved a Scheme of Arrangement for demerger of various business undertakings into separate resulting companies, which was subsequently modified to exclude the Base Metals undertaking (the “Updated Scheme”). The Updated Scheme received requisite approvals from shareholders and creditors and was sanctioned by the Hon’ble NCLT on 16 December 2025, with TSPL receiving separate approval on 9 January 2026. Consequently, the receipt of aforesaid NCLT approval, being one of the substantial approvals, meets the highly probable criteria prescribed in Ind AS 105 “Non-current Assets Held for Sale and Discontinued Operations” for presentation of the Scheme as discontinued operations. Hence Aluminium, Oil and Gas, Iron Ore and Power undertakings have been disclosed as discontinued operations in financial statements. Accordingly, all previous period figures in the statement of profit and loss have also been re-presented/recomputed. Refer note 45 for further details.

Note 45: Scheme of Arrangement for demerger

The Board of Directors, in its meeting held on 29 September 2023, had approved a Scheme of Arrangement (“the Original Scheme”) for demerger of various businesses of the Company, namely, demerger of the Company’s Aluminium (represented by the Aluminium segment), Merchant Power (represented by the Power segment), Oil & Gas (represented by the Oil and Gas segment), Base Metals (represented by the Copper and Zinc International segment) and Iron Ore & Steel (represented by Iron Ore segment and Steel and Cement business) Undertakings, resulting in 6 separate companies(including Vedanta Limited, being the demerged Company), with a mirrored shareholding and consequent listings at BSE Limited and National Stock Exchange of India Limited (“the Stock Exchanges”). The Stock Exchanges gave their no objection to the Scheme.

A first motion application, in respect of the Original Scheme, was filed by the demerged company (i.e., Vedanta Limited) and four resulting companies (i.e., Vedanta Aluminium Metal Limited (“VAML”), Malco Energy Limited (“MEL”), Vedanta Base Metals Limited (“VBML”) and Vedanta Iron and Steel Limited (“VISL”)) before the Hon’ble National Company Law Tribunal, Mumbai Bench (“NCLT”) on 06 August 2024 (“VEDL First Motion’’). The Hon’ble NCLT by way of its order dated 21 November 2024 (“VEDL NCLT Order”) inter alia:

a) directed the Company to convene a meeting of its equity shareholders, secured creditors and unsecured creditors within 90 days of the date of receipt of the Order;

b) directed MEL to convene a meeting of its secured and unsecured creditors within 90 days of the date of receipt of the Order;

c) dispensed with the meeting of equity shareholders of VAML, MEL, VBML and VISL; and

d) dispensed with the meeting of secured and unsecured creditors of VAML, VBML and VISL.

In December 2024, Vedanta Limited and other five resulting companies decided not to proceed with implementation of Part V of the Original Scheme, i.e., demerger of Base Metal undertaking into VBML, along with making appropriate updates to the Original Scheme (“Scheme”). The non-implementation of the demerger of the Base Metals undertaking shall not affect any other parts of the Original Scheme described above.

In compliance with the VEDL NCLT Order, the meetings were held on 18 February 2025 and the Scheme (with modification to exclude demerger of Base Metals Undertaking) was approved by the equity shareholders, secured creditors and unsecured creditors of the Company, as well as the secured and unsecured creditors of MEL.

On 5 March 2025, Vedanta Limited along with VAML, MEL and VISL, filed a second motion petition before the Hon’ble NCLT inter alia seeking sanction of the Updated Scheme. After multiple hearings with the Hon’ble NCLT, the Updated Scheme was approved by the Hon’ble NCLT vide its order dated 16 December 2025.

Further, a separate first motion application was filed by Talwandi Sabo Power Limited (“TSPL”), one of the resulting companies, with the Hon’ble NCLT, Mumbai on 22 October 2024 (“TSPL First Motion”) for demerger of Merchant Power Undertaking of the Company, since TSPL’s Registered Office (“RO”) was in the process of being changed from Mansa (Punjab) to Mumbai (Maharashtra) at the time of filing VEDL First Motion. The Hon’ble NCLT, Mumbai by its order dated 4 March 2025, disposed the TSPL First Motion by rejecting the scheme (“TSPL NCLT Order”). In an appeal filed by TSPL, the TSPL NCLT Order has been set aside by the Hon’ble NCLAT, New Delhi vide order dated 15 September 2025 and the matter has been remanded to the Hon’ble NCLT for proceeding with TSPL First Motion. The Hon’ble NCLT by way of its order dated 17 October 2025 inter alia directed (i) dispensation of the meeting of equity shareholders of TSPL; and (ii)TSPL to convene a meeting of its secured creditors and unsecured creditors within 90 days of the date of receipt of the order. The meetings were held on 21 November 2025, and the Scheme was approved by the secured creditors and unsecured creditors of TSPL. On 25 November 2025, TSPL filed a second motion petition before the Hon’ble NCLT inter alia seeking sanction of the Updated Scheme. The Updated Scheme has been approved by the Hon’ble NCLT vide its order dated 9 January 2026.

Consequently, the receipt of aforesaid NCLT approval, being one of the substantial approvals, meets the highly probable criteria prescribed in Ind AS 105 “”Non-current Assets Held for Sale and Discontinued Operations”” for presentation of the Updated Scheme as discontinued operations. Hence the Aluminium undertaking, Oil and Gas undertaking, Iron Ore undertaking and Power undertaking have been disclosed as discontinued operation in the financial statements. Accordingly, all previous period figures in the statement of profit and loss have also been re-presented/re-computed.

The Board of Directors, at its meeting held on 20 April 2026, has inter alia, approved the following:

i. To make the Scheme effective on 1 May 2026; and

ii. In consultation with VAML, TSPL, MEL and VISL, the Board has fixed 1 May 2026, as the record date for determining the shareholders eligible to receive consideration pursuant to the Scheme.

The impact of the demerger would be given in the period when all substantial conditions as per Scheme are fulfilled/ met.

Brief particulars of the Demerged Undertaking / Discontinued Operations are given as under:

a) Carrying value of net assets of the Demerged Undertaking (net of inter segment balances) as at 31 March 2026

(₹ in crores)

Particulars Aluminium

Undertaking

Iron ore

Undertaking

Oil & Gas

Undertaking

Power

Undertaking

Total
Non-current assets
Property, Plant and Equipment 40,970 1,793 5,046 3,089 50,898
Capital work-in-progress 2,001 394 3,332 1,685 7,412
Intangible assets 901 120 39 0 1,060
Exploration intangible assets under development 1,040 – 2,143 – 3,183
Financial assets
   Investments 992 1,775 8,561 4,133 15,461
   Loans – 1,309 – – 1,309
   Trade receivables – – – 634 634
   Derivatives 229 – – – 229
   Others 1,090 125 1,513 14 2,742
Deferred tax assets (net) – 0 – 1,473 1,473
Other non-current assets 1,929 490 126 92 2,637
Total non-current assets 49,152 6,006 20,760 11,120 87,038
Current assets          
Inventories 4,977 1,010 402 91 6,480
Financial assets
   Investments 1,387 127 20 7 1,541
   Trade receivables 2,276 178 448 179 3,081
   Cash and cash equivalents 1,300 268 1,133 746 3,447
   Other bank balances 268 102 2,576 4 2,950
   Loans 0 689 0 869 1,558
   Derivatives 296 12 – 0 308
   Others 1,107 721 5,563 230 7,621
Other current assets 773 1,098 78 228 2,177
Total current assets 12,384 4,205 10,220 2,354 29,163
Total Assets (A) 61,536 10,211 30,980 13,474 1,16,201

(₹in crores)

Particulars Aluminium

Undertaking

Iron ore

Undertaking

Oil & Gas

Undertaking

Power

Undertaking

Total
Non-current liabilities
Financial liabilities
    Borrowings 25,088 418 1,015 2,504 29,025
    Lease liabilities 64 200 94 4 362
   Other financial liabilities – 0 4 – 4
   Provisions 197 12 1,360 5 1,574
   Deferred tax liabilities (net) 4,046 19 654 0 4,719
   Other non current liabilities 2,143 26 0 29 2,198
Total non-current liabilities 31,538 675 3,127 2,542 37,882
Current liabilities          
Financial liabilities
    Borrowings 10,323 1,054 2,240 – 13,617
    Lease liabilities 17 167 54 0 238
Operational buyers’ credit / suppliers’   credit 4,073 1,096 33 204 5,406
   Trade payables 2,433 296 728 53 3,510
   Derivatives 3,327 – – – 3,327
   Other financial liabilities 2,392 253 6,755 425 9,825
   Other current liabilities 1,672 441 207 20 2,340
   Provisions 71 53 72 2 198
Total current liabilities 24,308 3,359 10,089 704 38,460
Total Liabilities (B) 55,846 4,035 13,216 3,246 76,342
Net Assets Transferred (A)-(B) 5,690 6,177 17,764 10,228 39,859


(b)  Profit from Discontinued Operations

Gross of inter segment transactions for the year ended 31st March 2026

(₹ in crores)

Particulars Aluminium

Undertaking

Iron ore Undertaking Oil & Gas

Undertaking

Power Undertaking Total
Revenue from Operations 50,592 6,073 5,546 1,938 64,149
Total Income 51,077 6,789 7,739 1,952 67,557
Total Expenses 37,474 5,685 5,527 1,830 50,516
Profit before Exceptional Items and Tax 13,603 1,104 2,212 122 17,041
Exceptional Items -389 -863 -25 -2 -1,279
Tax Expense 3,435 134 148 6 3,723
Profit from Discontinued Operations 9,779 107 2,039 114 12,039

Gross of inter segment transactions for the year ended 31st March 2025

(₹ in crores)

Particulars Aluminium

Undertaking

Iron ore Undertaking Oil & Gas

Undertaking

Power Undertaking Total
Revenue from Operations 44,233 5,636 6,283 678 56,830
Total Income 44,829 6,249 8,671 689 60,438
Total Expenses 37,444 5,245 5,695 1,143 49,527
Profit before Exceptional Items and Tax 7,385 1,004 2,976 -454 10,911
Exceptional Items – -314 1,113 – 799
Tax Expense 1,935 77 439 -79 2,372
Profit from Discontinued Operations 5,450 613 3,650 -375 9,338

Net of inter segment transactions for the year ended 31st March 2026

(₹in crores)

Particulars Aluminium

Undertaking

Iron ore Undertaking Oil & Gas

Undertaking

Power Undertaking Total
Revenue from Operations 50,592 6,073 5,546 1,839 64,050
Total Income 51,077 6,305 7,627 1,853 66,862
Total Expenses 37,131 5,685 5,721 1,825 50,362
Profit before Exceptional Items and Tax 13,946 620 1,906 28 16,500
Exceptional Items -389 -863 -25 -2 -1,279
Tax Expense 3,435 134 148 6 3,723
Profit from Discontinued Operations 10,122 -377 1,733 20 11,498

Net of inter segment transactions for the year ended 31st March 2025

(₹ in crores)

Particulars Aluminium

Undertaking

Iron ore Undertaking Oil & Gas

Undertaking

Power Undertaking Total
Revenue from Operations 44,233 5,636 6,283 678 56,830
Total Income 44,595 5,779 8,548 689 59,611
Total Expenses 36,961 5,148 5,765 1,137 49,011
Profit before Exceptional Items and Tax 7,634 631 2,783 -448 10,600
Exceptional Items – -314 1,113 – 799
Tax Expense 1,935 77 439 -79 2,372
Profit from Discontinued Operations 5,699 240 3,457 -369 9,027
(c) Net Cashflows attributable to the Discontinued Operations

Gross of inter segment transactions for the year ended 31st March 2026

(₹ in crores)

Year ended 31 March 2026 Aluminium

Undertaking

Iron ore Undertaking Oil & Gas Undertaking Power Undertaking Total
Net Cash generated from Operating Activities 13,663 865 1,927 1,271 17,726
Net Cash (used in)/generated from Investing Activities -4,790


-634


4,574


-1,317


-2,167


Net Cash (used in)/generated from Financing Activities -8,801


-139


-5,876


688


-14,128


Gross of inter segment transactions for the year ended 31st March 2025

(₹in crores)

Year ended 31 March 2026 Aluminium

Undertaking

Iron ore Undertaking Oil & Gas

Undertaking

Power Undertaking Total
Net Cash generated from/(used in) Operating Activities 11,214


428


5,005


-501


16,146


Net Cash used in Investing Activities -3,732 -290 -3,440 -1,082 -8,544
Net Cash (used in)/generated from Financing Activities -7,347


-16


-1,063


1,687


-6,739


Total expense includes finance cost which has been allocated between continuing and discontinued operations based on best estimate of debt allocation between business divisions of Vedanta Limited as at 31 March 2026. Accordingly finance cost of comparative periods has been regrouped between continuing and discontinuing operations.

Independent Auditor’s Report on Standalone Financial Statements for the year ended 31st March 2026

Key audit matters How our audit addressed the key audit matter
Accounting and Disclosure for Scheme of Arrangement (“Scheme”) for Demerger (as described in Note 3(c)(A)(vi) and 45 of the Standalone financial statements)


During the current year, the Hon’ble NCLT vide its order dated 16 December 2025 has approved the Scheme for demerger of Aluminium undertaking (represented by the Aluminium segment), Oil and Gas undertaking (represented by the Oil and Gas segment) and Iron Ore undertaking (represented by Iron Ore segment) and vide its order dated 9 January 2026 for demerger of Merchant Power Undertaking (represented by the Power segment) of the Company, both orders subjected to other requisite regulatory and Board of Director approvals.

The aforesaid Scheme has been assessed as highly probable by the management in accordance with the criteria prescribed under Ind AS 105 “Non-current Assets Held for Sale and Discontinued Operations” and accordingly, the proposed demerger of Aluminium undertaking, Oil and Gas undertaking, Iron Ore undertaking and Merchant Power Undertaking pursuant to the scheme has been accounted and disclosed as Discontinued Operations.

The above transaction is a significant non-routine transaction and has been identified as a key audit matter due to:

a)significant management judgment around determination of the Scheme being assessed as highly probable by the management in accordance with the criteria prescribed under Ind AS 105.

b)significant management judgment around evaluation of giving effect to the Scheme in accordance to Ind AS- 103 “Business Combination”, including:

satisfaction of substantive conditions post 31 March 2026

waiver of any conditions by the Board of Directors to the extent permitted under Applicable Law; andc) significant management judgment and estimates which are sensitive to underlying assumptions such as forecast of future cash flows (including revised assessment of brand and strategic management fees), allocation of borrowings, utilisation of tax assets, identification of all proceedings of any nature for each undertaking, etc. upon the Scheme becoming effective.

Our procedures included the following:

Obtained and read the Scheme and orders passed by the Hon’ble National Company Law Tribunal to understand its key terms and conditions.

Understood the change in structure of the Company from the management.Evaluated the design and tested the operating effectiveness of select internal financial controls relevant for recording the impact of the Scheme and related disclosures.

Evaluated the basis of the management’s assessment of treating the proposed demerger as Discontinued operations in accordance with the applicable accounting standards.

Obtained an update on the other regulatory communications in this respect and current status of the approval from such regulatory authorities.

Read the minutes of meeting of Board of Directors.

Tested the identification of specific assets and liabilities being disclosed as held for distribution and assessed the key estimates and judgement involved therein.

Identified indicators of impairment for assets and liabilities classified as held for distribution and where identified, tested the valuation by assessing the key assumptions used by management, which included:

Assessment of management’s forecasting accuracy of future cashflows by comparing prior year forecasts to actual results.

Capitalisation of Borrowing Costs: Foreign Exchange Gains and Losses under Ind AS 23

A practical framework for applying the exchange-difference provisions

Under Ind AS 23, foreign exchange differences from borrowings can be capitalised as borrowing costs if they are considered interest adjustments to interest costs for qualifying assets. This adjustment is capped at the difference between local and foreign currency borrowing costs. Any excess exchange loss is recognised in profit or loss. Subsequent exchange gains must first reverse previously recognised losses before being treated as gains under Ind AS 21. For multi-year loans, entities choose between discrete-period or cumulative approaches. The cumulative approach is often preferred to maintain consistency with gain treatment.

1. BACKGROUND AND INTRODUCTION

Foreign currency borrowings can create an accounting issue that is easy to overlook: the borrowing cost is not limited to the interest paid on the loan. Under Ind AS 23, certain exchange differences arising on foreign currency borrowings may also be regarded as an adjustment to interest costs. Where the borrowing is directly attributable to the acquisition, construction or production of a qualifying asset, the eligible borrowing costs are capitalised as part of the cost of that asset, subject to the general requirements of Ind AS 23.

The important point is that Ind AS does not permit an entity to capitalise the entire foreign exchange loss merely because the loan was used to finance a qualifying asset. Paragraphs 6(e) and 6A of Ind AS 23 impose a specific restriction: the exchange loss regarded as an adjustment to interest is generally limited by reference to the difference between the cost of borrowing in the local currency and the cost of borrowing in the foreign currency. The treatment of subsequent exchange gains is also specifically addressed.

The practical difficulty becomes greater where a foreign currency borrowing remains outstanding for more than one reporting period. In that situation, an entity may need to consider whether the exchange-difference adjustment should be determined separately for each reporting period or assessed cumulatively over the period of the borrowing. This article explains the basic rule first through a simple mathematical example and then through a more complex multi-year example.

2. RELEVANT ACCOUNTING STANDARD REFERENCES

The key provisions of Ind AS 23 relevant to this issue are:

Reference Relevant principle
Paragraph 6 (e) Borrowing costs include exchange differences arising from foreign currency borrowings to the extent that they are regarded as an adjustment to interest costs.
Paragraph 6A(i) The exchange-loss adjustment is determined by reference to the extent to which the exchange loss does not exceed the difference between the cost of borrowing in the local currency and the cost of borrowing in the foreign currency.
Paragraph 6A(ii) Where an unrealised exchange loss has been treated as an adjustment to interest and a subsequent realised or unrealised gain arises in respect of settlement or translation of the same borrowing, the gain is also treated as an adjustment to interest to the extent of the previously recognised loss.
Paragraphs 8–26 These paragraphs contain principles governing capitalisation of borrowing costs, including the commencement, suspension and cessation of capitalisation.

Accordingly, two questions should be kept separate. First, how much of the exchange difference can be regarded as an adjustment to interest under paragraphs 6(e) and 6A? Second, once that amount is identified, does it meet the general conditions for capitalisation under Ind AS 23?

3. THE BASIC MATHEMATICAL PRINCIPLE

For a foreign currency borrowing used to finance a qualifying asset, the exchange-loss component eligible to be treated as an adjustment to interest is restricted. In the simple annual case, the ceiling is the difference between the cost of a comparable borrowing in the local currency and the cost of the foreign currency borrowing.

Eligible exchange-loss adjustment = lower of:

  • Actual exchange loss for the period
  • Interest on comparable local-currency borrowing less interest on the foreign currency borrowing

4. EXAMPLE 1 – SIMPLE MATHEMATICAL ILLUSTRATION

Assume a company borrows ₹100 crore in a foreign currency to finance the construction of a qualifying asset. The comparable borrowing rate in the local currency is 12%, while the foreign currency borrowing carries an interest rate of 7%.

Particulars Amount
Principal `100 crore
Comparable local borrowing rate 12%
Foreign currency borrowing rate 7%
Interest differential 5%
Interest differential on ₹100 crore `5 crore
Actual exchange loss `8 crore

The maximum exchange loss that can be regarded as an adjustment to interest is therefore ₹5 crore. The actual exchange loss is ₹8 crore. Accordingly:

  • Foreign currency interest: capitalised if the Ind AS 23 conditions for capitalisation of borrowing cost are satisfied.
  • Exchange loss regarded as an adjustment to interest: ₹5 crore.
  • Excess exchange loss: ₹3 crore, recognised in profit or loss rather than treated as borrowing cost.

If, instead, the actual exchange loss were only ₹3 crore, the amount eligible as an adjustment to interest would be ₹3 crore. The fact that the interest differential is ₹5 crore does not create an additional amount that can be capitalised.

5. SUBSEQUENT EXCHANGE GAIN

Paragraph 6A(ii) becomes important where an exchange loss has previously been treated as an adjustment to interest. If a subsequent realised or unrealised exchange gain arises on settlement or translation of the same borrowing, the gain is treated as an adjustment to interest to the extent of the exchange loss previously recognised as an adjustment.

Year Exchange difference Treatment
Year 1 `4 crore loss `4 crore treated as borrowing-cost adjustment
Year 2 `2 crore gain ₹2 crore reduces borrowing cost / reverses the earlier adjustment
Alternative: Year 2 gain of ₹6 crore `6 crore gain ₹4 crore reverses the earlier adjustment; balance of ₹2 crore is recognised under Ind AS 21 as an exchange gain.

6. EXAMPLE 2 – A MORE COMPLEX MULTI-YEAR BORROWING

The more difficult question arises when the foreign currency borrowing extends beyond one reporting period and there is an exchange loss in more than one year. In the author’s view there are two possible approaches: a discrete-period approach and a cumulative approach. The distinction matters because an exchange loss that is not eligible for treatment as an adjustment in one period may, depending on the approach and the facts, affect the computation in a later period.

6.1 Facts

Assume the following two-year borrowing. The figures are illustrative and expressed in the same monetary units:

Particulars Year 1 Year 2 Total
Foreign currency interest (A) 25,000 25,000 50,000
Hypothetical local-currency interest (B) 30,000 30,000 60,000
Foreign exchange loss (C) 6,000 3,000 9,000

6.2 Method A – Discrete-Period Approach

Under the discrete-period approach, the paragraph 6(e) adjustment is determined independently for each reporting period. The calculation is therefore:

Year 1: lower of exchange loss of 6,000 and interest differential of 5,000 = 5,000.

Year 2: lower of exchange loss of 3,000 and interest differential of 5,000 = 3,000.

Particulars Year 1 Year 2 Total
6(e) adjustment 5,000 3,000 8,000
Foreign exchange loss not treated as adjustment 1,000 Nil 1,000

Thus, under Method A, the total exchange loss regarded as an adjustment to interest over the two years is 8,000, leaving 1,000 of the cumulative exchange loss outside this adjustment to be dealt with in accordance with Ind AS 21.

6.3 Method B – Cumulative Approach

Under the cumulative approach, the assessment is made by considering the borrowing over the relevant period as a whole. The cumulative exchange loss is compared with the cumulative interest differential, with the cumulative adjustment constrained by the cumulative exchange loss.

At the end of Year 1, the cumulative eligible adjustment is 5,000. At the end of Year 2, cumulative exchange loss is 9,000 and cumulative interest differential is 10,000. Accordingly, the cumulative paragraph 6(e) adjustment can reach 9,000.

Since 5,000 was already recognised in Year 1, the additional adjustment in Year 2 is 4,000. This produces the following cumulative result:

Particulars Year 1 Year 2 Total
Cumulative 6(e) adjustment 5,000 4,000 9,000
Foreign exchange loss not treated as adjustment 1,000 (1,000) Nil

The numerical outcome differs between Method A and Method B. Method A produces a total adjustment of 8,000, whereas Method B produces a cumulative adjustment of 9,000. The issue therefore is not merely computational; it involves the unit of account and the relationship between exchange rates and the interest differential over the life of the borrowing.

7. WHICH APPROACH SHOULD BE FOLLOWED?

There is no explicit paragraph in Ind AS 23 that conclusively mandates either the discrete-period or cumulative approach for a multi-year borrowing with exchange losses in successive periods. However, given that the standard mandates a cumulative approach for exchange gains, the author believes that the cumulative approach is more appropriate in these situations as well. Where quarterly or other interim financial information is prepared, the same issue can arise within a financial year. Management should document the basis for the approach selected and apply it consistently.

Dr. Bais Surgical And Medical Institute Pvt. Ltd. v. Dhananjay Pande : Formal entry in a company’s register is not an absolute prerequisite for a person to seek oppression relief.

12. Dr. Bais Surgical And Medical Institute Pvt. Ltd. & Ors. V/s Dhananjay Pande In The Supreme Court of India Civil Appellate Jurisdiction Civil Appeal No. 8973 of 2010

Order date: 04th May,2026

The Supreme Court held that formal entry in a Company’s Register of Members is not an absolute prerequisite for a person to be considered a “Member of the Company” when seeking relief against Oppression and Mismanagement.

The Supreme Court of India, in its judgment addressed a critical question regarding the definition of a “Member” of a Company under the Companies Act, 1956. it clarified that in specific equitable contexts such as petitions for “oppression and mismanagement”—the status of an investor as a “Member” can be recognized even in the absence of a formal entry in the Register of Members.

The judgment examined the interplay between two distinct provisions of the Companies Act, 1956:

  • Section 2(27): Provides a broad, inclusive definition of “member”.
  • Section 41: Outlines the formal procedural requirements for becoming a member, such as agreeing in writing and having one’s name entered in the register of members.

The Court held that for the purposes of invoking jurisdiction under Sections 397 and 398 of the Companies Act, 1956 (remedies against oppression and mismanagement), the term “Member” should not be construed in a “mechanical or technical manner” restricted solely to the requirements of Section 41. Instead, the broader definition under Section 2(27) should apply where the individual has consistently been treated as a stakeholder by the company.

The Court further held that when an investor’s share application money has been accepted and utilized for the company’s business operations (e.g., expanding its facilities or increasing its authorized capital), it constitutes strong evidence of a proprietary interest. Moreover, if a company has treated an individual as a “co-owner” or stakeholder in its official correspondence, such conduct may outweigh the absence of a formal share certificate or an entry in the register.

The Court ruled that since the jurisdiction to grant relief in cases of oppression and mismanagement is equitable in nature, the absence of a formal entry in the register of members does not automatically disqualify a genuine stakeholder from seeking relief. Therefore, the Court rejected the argument that the name of person not entered in the register of members would lack “locus standi” for filing a petition under Sections 397 and 398 of the Companies Act, 1956 (remedies against oppression and mismanagement).

Rafeek Peedi Yakkal Hassan v. Registrar of Companies : Striking off a company name is reversed if the director provides audited financial statements proving ongoing resort project operations.

11. Rafeek Peedi Yakkal Hassan V/s

Registrar of Companies, Kerala & Lakshadweep NATIONAL COMPANY LAW TRIBUNAL, KOCHI BENCH, 189 taxmann.com 423

Order dated 11th August 2026

Where an appellant, director challenged the strike-off of the company’s name, citing its ongoing business and intention to continue operations, and placed on record audited financial statements and tax returns, restoration of the company’s name was directed, subject to the company filing all pending statutory documents and paying applicable fees, penalties, and costs for previous non-compliances within stipulated timelines, with restoration taking effect as if the company’s name had not been struck off.

FACTS:

  • The appellant–shareholder-director holding 99% of M/s. Salim’s Whitefeather Resort Private Limited filed an appeal under Section 252(3) challenging the strike-off of the company’s name. The company was incorporated in 2019 as a company limited by shares with authorised share capital of about Rs. 10 lakhs and paid-up share capital of about Rs. 1 lakh, with the object of developing a resort project. The appellant stated that the company had acquired land and a building permit but, due to the COVID-19 pandemic and a director being abroad, it could not open a bank account or commence operations. The appellant executed a memorandum of understanding with a construction group, placed on record audited financial statements for FYs 2021-22 to 2024-25 and the income tax return for FY 2024-25, and undertook to file all pending statutory documents with applicable fees. The appeal was filed within the 20-year period prescribed by Section 252(3).
  • The Registrar reported that the company failed to commence business; the subscribers did not pay the subscription undertaken in the Memorandum; and the declaration under Section 10A (1) was not filed within180 days of incorporation. A notice in Form STK-1 was issued under Section 248(1), followed by a public notice in Form STK-5 published in the Gazette. As no valid objections were received from the company or its directors, the company’s name was struck off under Section 248(5) and Form STK-7 was issued. The Registrar also recorded that the appellant admitted non-commencement of business. The Registrar did not oppose the appellant’s request for restoration of the company before the Tribunal.

HELD:

  • Upon examining the facts of the case, the Tribunal was satisfied that the Respondent, the Registrar of Companies, was justified in striking off the name of the Company from the Register of Companies in accordance with the provisions of the Companies Act, 2013. The records demonstrated that the Appellant Company had failed to commence business after its incorporation, as the subscribers did not pay the subscription amount undertaken in the Memorandum, and the declaration under Section 10A (1) of the Companies Act, 2013, was not filed within 180 days of incorporation.
  • Section 252(3) confers powers on the Tribunal to order for restoration of the name of the Company in the Register of Companies maintained by ROC, on an appeal made by the (i) Company (ii) Member (iii)creditor or (iv) workman before the expiry of 20 years from the date of publication in the Official Gazette of the notice under Section 248(5), if the Tribunal is satisfied that the Company was, at the time of its name being struck off, carrying on business or in operation or otherwise just that the name of the company be restored to the Register of Companies.
  • The Respondent/Registrar of Companies has not opposed the relief sought by the Appellant for restoration of its name to the Register of Companies. The Appellant has also undertaken to comply with all statutory requirements and to take necessary measures to regularise the defaults committed by the Company. In the absence of any objection from the Respondent/ROC and having regard to the object and purpose of Section 252, the Tribunal considered it appropriate to take a liberal view and grant the Appellant an opportunity to restore the Company and bring its affairs into compliance with law.
  • Upon perusal of the appeal, this Tribunal was of the considered view that sufficient grounds exist for restoring the name of the Company to the Register of Companies. In the present case, the Appellant, being a shareholder holding 99% of the Company’s share capital, has filed the present appeal under Section 252(3), seeking restoration of the Company’s name. The Appellant has placed on record the audited financial statements for the financial years ended 31st March 2022 to 31st March 2025, which prima facie demonstrated that the Company was in operation and carrying on its business at the time the order under Section 248 was passed. Although the Company had committed certain statutory defaults, the Respondent/Registrar of Companies, after following the procedure prescribed under the Act, struck off the Company’s name from the Register of Companies.
  • Certainly, Section 252(3) does not mandate going into the merits of an order passed under Section 248, but the NCLT usually calls for a report from the ROC. Once a person is eligible to file an appeal and has placed on record prima facie proof that, at the time of the order under Section 248, the Company was carrying on its business or was in operation, the Tribunal, after recording its satisfaction, can pass appropriate orders.
  • The right given to the Company, along with any member, creditor, or workman, to file an appeal under Section 252(3) demonstrates the legislative intent that even a struck-off Company retains a limited statutory personality for the purpose of seeking its revival. If the appellant has established that the Company was carrying on business and was in operation and has the intention to continue with its normal operations, or that the restoration is otherwise just and equitable, the NCLT is empowered to pass appropriate orders under the given circumstances. However, the said orders would not exempt the Company from paying the regular fees and penalties, if applicable, for its previous non-compliances.

Tribunal was of the considered view that the Appellant is a shareholder of the Company and in the light of the above findings, this Company Appeal is maintainable in the eyes of law. Accordingly, the appeal was allowed on the following terms: –

i. The Registrar of Companies, Kerala/Lakshadweep, the Respondent, was directed to restore the original status of the Appellant Company, M/s. Salim’s White Feather Resort Private Limited, as if the name of the Company has not been struck off from the Register of Companies, with the resultant and consequential actions like changing the status of the Appellant Company from “Strike off’ to “Active”.

ii. The Appellant Company was directed to file all pending statutory document(s), including Annual Accounts for the period and Annual Returns along with prescribed fees/additional fees/fines as decided by the Registrar of Companies, Kerala/Lakshadweep, within 45 days from the date on which its name is restored on the Register of Companies maintained by the Registrar of Companies, Kerala/Lakshadweep.

iii. The restoration of the Company’s name was also subject to the payment of Rs.10,000/- (Rupees Ten thousand Only) per financial year for which the Company has not filed its financial returns with the ROC towards cost payable through online payment in www.mca.gov.in under miscellaneous fees by mentioning the particulars as “payment of cost for revival of Company” within thirty days from the date of receipt of the order.

iv. The restoration of the Appellant Company’s name in the Register will be subject to their filing all outstanding documents for the defaulting years as required by law and completion of all formalities, including payment of any late fee or other charges that are leviable by the Respondent for the late filing of statutory returns. The name of the Appellant Company shall then stand restored in the Register of the ROC, as if the name of the company had not been struck off.

v. The appellant company was directed to file a copy of this Order with the ROC within 30 days of the receipt of this Order. ROC was directed to give effect to the Order only after perusal of the Compliance report of the cost imposed.

vi. On such delivery and after due compliance with the above directions, the Registrar of Companies, Kerala/Lakshadweep, was directed to publish the order in the Official Gazette under his office name and seal.

vii. The Order was confined to the violations, which ultimately led to the action of striking off the name of the Company, and it will not come in the way of Registrar of Companies, Kerala/Lakshadweep to take appropriate action(s) in accordance with law, for any other violations/offences, committed by the Appellant Company prior to or during the striking of the Company. The Appellant Company shall make good the offences, if any, arising out of non-compliance with various sections under the Act.

Accordingly company appeal was disposed off.

Margin Trading Facility (MTF): Evolution, Existence and the Future Of Leveraged Investing In India

India’s Margin Trading Facility (MTF) has grown fivefold since FY23, reaching ₹1.3 lakh crore by mid-2026, offering investors leveraged purchasing power. While enhancing capital efficiency, leverage magnifies downside risks like margin calls and forced liquidation.

Regulated by SEBI since 2004, proposed 2026 reforms seek risk-controlled optimisation by harmonising collateral and introducing rebalancing periods to ease operational frictions. Compliance requires strict half-yearly audits by Chartered Accountants. As technology drives correlated trading behaviours, future frameworks must monitor leverage across investor, broker, and systemic levels to maintain market stability.

INTRODUCTION

India’s capital market has undergone significant transformation over the past two decades. The growth of digital trading platforms, easier account opening, affordable internet access and increasing financial awareness have brought a larger number of investors into the securities market. At the same time, investors have increasingly looked for greater purchasing power and flexibility without committing their entire capital upfront, thereby contributing to the growing relevance of the Margin Trading Facility (MTF). India’s MTF market has expanded rapidly, with outstanding positions reaching approximately ₹1.3 lakh crore by mid-2026, around 50% higher year-on-year. From ₹25,000 crore in FY23, the MTF book has grown more1 than fivefold, highlighting its emergence as a significant source of leveraged purchasing power in the cash-equity segment.

MTF allows investors to buy eligible securities by paying only a prescribed portion of the purchase value, while the stockbroker finances the balance. It therefore enables investors to take larger positions with lower upfront capital and can improve the efficiency of capital deployment. However, leverage works in both directions. While it can increase gains when markets move favourably, it can also magnify losses when prices fall. MTF is therefore fundamentally different from ordinary cash-segment investing and requires greater attention to margins, liquidity, funding costs and risk management.

Because MTF creates both exposures, i.e., credit exposure as well as market exposure, it operates within a regulatory framework involving SEBI, stock exchanges, clearing corporations and market intermediaries. Over time, SEBI has developed safeguards around eligible securities, margins, collateral, funding sources, broker exposure, disclosures and liquidation. The latest stage of this evolution is reflected in SEBI’s Consultation Paper dated 18th June 2026, which seeks to improve capital efficiency and operational flexibility while retaining the core safeguards of the MTF framework.

EVOLUTION OF THE MTF FRAMEWORK

SEBI formally introduced the regulatory framework for margin trading in 2004. The objective was to bring leveraged trading within a structured regulatory framework rather than leave financing arrangements entirely to individual broker-client agreements. The framework established requirements relating to broker eligibility, approved securities, margins, sources of fund, exposure limits, and disclosures.

As India’s securities markets expanded, the regulatory framework was progressively strengthened. In 2017, SEBI undertook a comprehensive review covering areas such as collateral management, broker exposure, disclosures and operational controls. In 2022, Group I Equity ETFs were added to the securities eligible for MTF, widening the range of instruments that could be financed while retaining liquidity-based eligibility requirements.

Further changes introduced in 2024 addressed client cash collateral and wrong-way risk. Wrong-way risk arises when the security being financed also serves as collateral. If the security falls in value, the broker’s exposure increases, while the value of the collateral protecting that exposure decreases simultaneously.

SEBI’s 2026 consultation paper marks another stage in this evolution, placing greater emphasis on capital efficiency, funding flexibility and operational simplification while retaining appropriate risk controls.

High-Wire-Act-of-Margin-Trading

REGULATORY ARCHITECTURE OF MTF

The MTF framework begins with determining which securities can be financed. Not every listed security is eligible. SEBI permits MTF against eligible Group I equity shares and Group I Equity ETFs that satisfy prescribed liquidity parameters. This liquidity requirement is important because a broker may need to liquidate a funded position if an investor fails to meet a margin obligation. More liquid securities are generally easier to sell without creating excessive market impact.

The second major component is the margin framework. Investors are required to contribute a part of purchase value based on parameters like Value at Risk (VaR) and Extreme Loss Margin (ELM). The margin requirement does not end when the position is created. Funded securities and collateral are marked to market, and investors must replenish any margin shortfall within the prescribed period. Where the shortfall is not restored, the broker may liquidate sufficient securities to recover its outstanding financing.

Risk controls also operate at the broker level. Borrowing for margin funding is subject to limits linked to the broker’s net worth and own capital. Client and security concentration are also restricted, while brokers are required to maintain Board-approved policies covering concentration across securities, sectors and funding exposures.

Investor protection is further supported through daily valuation, margin calls and Rights and Obligations documents that set out funding terms, interest, margin requirements and liquidation procedures.

SEBI’s 2026 Reforms: From Restriction to Risk-Controlled Optimisation

The significance of the 2026 proposals lies in the regulator’s attempt to move MTF from a restriction-focused framework to risk-based framework.

One of the important proposals is to harmonise MTF collateral requirements with collateral accepted in the cash market. This could reduce operational complexity and improve collateral utilisation by creating greater consistency between the two frameworks. SEBI has also proposed recognising Early Pay-In sell credits as eligible collateral for fresh MTF positions. This could allow settlement-related credits to be used more efficiently instead of remaining operationally underutilised.

Another proposal addresses securities that become ineligible for MTF after a position has already been created. Instead of requiring immediate liquidation, a 30-day rebalancing period is proposed to be granted. This may reduce unnecessary forced selling where the change in eligibility does not represent an immediate deterioration in the security itself.

At the broker level, the proposals seek to improve capital efficiency while ring-fencing capital for core broking activities and retaining an overall leverage ceiling of 5.5 times net worth. The direction of reform is therefore clear: the objective is not unrestricted leverage, but more efficient leverage within a controlled risk framework.

The coexistence of client-fund upstreaming and MTF creates a significant operational and reporting challenge for brokers because ordinary client funds and MTF-related funds cannot simply be treated as one fungible pool. SEBI’s upstreaming framework requires clients’ clear credit balances to be upstreamed to clearing corporations in specified forms, while the MTF framework requires separate client-wise ledgers for funds and securities relating to MTF positions. This creates a reconciliation challenge when the same client simultaneously has normal trading balances and an MTF position. The broker must correctly identify which funds are unencumbered, which are supporting MTF obligations, and which can be upstreamed, while also ensuring accurate margin reporting and avoiding double counting of collateral.

The operational complexity becomes particularly important at end-of-day cut-offs, where errors in ledger mapping, collateral classification or reporting can result in short-collection or compliance issues. The 2026 MTF consultation is notable in this context because SEBI has proposed permitting the fungibility of unencumbered funds or securities between a client’s normal and MTF ledgers, potentially reducing some of these operational frictions while retaining the requirement for separate client-wise MTF records.

Relation of MTF with Traders / Investors

MTF can have different implications depending on an investor’s investment horizon and financial capacity.

For short-term traders, MTF can provide additional purchasing power for positions expected to be held for a few days. The advantage is greater market exposure with lower upfront capital, but the investor remains exposed to financing costs and changes in margin requirements.

For medium-term traders, MTF may provide flexibility while an investment thesis develops over several weeks or months. However, the longer a position remains funded, the more significant financing costs, overnight volatility and liquidity management become.

For the youth and digitally active investors, the increasing availability of MTF through online platforms makes leveraged investing more accessible and can provide greater flexibility in deploying limited initial capital. The ability to access financing digitally may make MTF relevant for investors seeking to pursue specific, shorter-term or customised investment opportunities without committing their entire capital upfront. However, greater accessibility also increases the importance of investor education and risk awareness. Lower transaction friction and easy access to leverage may encourage more frequent trading, while financing costs, margin requirements and the possibility of forced liquidation may not always be fully appreciated. Easy access to leverage should therefore not be confused with easy management of leverage. Nevertheless, MTF should be viewed as a complementary capital-allocation tool rather than an alternative to long-term investing.

MTF GLOBALLY

The risks associated with margin financing are not unique to India. Major financial markets have permitted investors to borrow against securities for several decades, but the regulatory approaches differ in the extent to which they rely on prescribed margin requirements, broker-level financial controls, eligible collateral and risk-based monitoring.

The U.S. model demonstrates the benefits of greater flexibility and a mature margin-financing ecosystem, while Hong Kong demonstrates the value of detailed broker-level monitoring of collateral quality, liquidity and concentration. Singapore similarly illustrates the importance of considering the financial capacity and aggregate indebtedness of the intermediary providing financing. These features can potentially provide useful lessons as India’s MTF market expands.

The more important comparison, therefore, is not simply whether one jurisdiction permits more leverage than another. The critical question is where the risk is being monitored. India’s framework has traditionally placed significant emphasis on the eligibility of securities, and has prescribed margins and limits applicable to individual brokers and clients. International experience suggests that these safeguards need to be complemented by greater visibility into the concentration and interconnectedness of leveraged positions. A broker may remain within its individual exposure limits while several brokers, acting independently, may nevertheless have significant exposure to the same security or sector.

The next stage of India’s regulatory development could therefore focus not merely on how much leverage an individual investor or broker can undertake, but also on where that leverage is concentrated across the market and how the market would respond if several leveraged positions were required to be unwound simultaneously.

MTF – Half-Yearly Reporting and Compliance Certification by Chartered Accountants

A Trading Member that has obtained approval from the Exchange and has commenced offering MTF is required to have its MTF books of account audited on a half-yearly basis and submit the prescribed MTF Compliance Certificate to the Exchange within the stipulated timeline. The certificate is to be issued and signed by a Chartered Accountant and should certify the extent of the Member’s compliance with the applicable MTF conditions.

The Chartered Accountant should verify the MTF books, records and supporting documents, including client-wise MTF ledgers, segregation of MTF and Non-MTF accounts, client consent, eligibility of securities, prescribed initial and maintenance margins, MTM requirements, collateral and funded-stock records, and compliance with applicable exposure and indebtedness limits. The Chartered Accountant should also verify the permitted sources and utilisation of MTF funds and ensure that funds of one client have not been used to finance another client’s MTF position.

The Chartered Accountant should further reconcile the MTF records with daily Exchange reporting, bank and borrowing records, demat and pledge records, and examine compliance with margin calls, liquidation, settlement and corporate-action reporting. Particular attention should be given to the separate identification of MTF collateral and funded securities, and restrictions on utilisation of excess MTF collateral for Non-MTF transactions. The final certificate should be issued only after obtaining sufficient supporting evidence to conclude on the Member’s compliance with the applicable MTF requirements.

AI, Rule-Based Trading and Correlated MTF Behaviour

The increasing use of artificial intelligence and rule-based systems introduces a further dimension to MTF risk. At the individual investor level, technology can strengthen risk management by enabling continuous monitoring of leveraged positions, automated alerts, predefined exit conditions and faster identification of margin deterioration. Such tools may reduce reliance on emotional decision-making and allow investors to respond more systematically to changes in market conditions. However, the same technology can create a different form of risk when a large number of investors rely on similar models, market signals, technical indicators, stop-loss parameters or risk thresholds. If these systems generate similar investment decisions, investors may enter or exit the same securities at or around the same time. The interaction becomes more significant when such positions are financed through MTF. For example, a common market signal may lead several investors to build leveraged positions in the same security; a subsequent decline in its price may then trigger similar margin shortfalls, prompting investors and brokers to reduce positions simultaneously. What begins as an individually rational risk-management response can therefore contribute to collective selling pressure and amplify price movements. The concern, therefore, is not that artificial intelligence or rule-based trading inherently makes MTF riskier, but that technology, leverage and correlated investor behaviour can interact in a manner that increases the speed and scale of deleveraging.

The Future of Leveraged Investing in India

India’s regulatory framework provides important safeguards at the investor and broker levels, while international experience demonstrates the value of monitoring collateral quality, concentration, liquidity and intermediary funding capacity. The future framework should therefore continue to monitor risk at three interconnected levels:

Investor level: adequate margin, transparent disclosures, liquidity planning, and disciplined position management.

Broker level: sufficient capital, diversified funding, liquidity buffers, and concentration controls.

System level: monitoring of aggregate leverage, common exposures, market and concentration liquidity, stress scenarios, and collateral quality.

This three-level approach becomes increasingly important as MTF becomes a larger part of India’s capital-market structure. The growth of leverage should be accompanied by equally strong infrastructure to monitor and contain its risks.

MTF has evolved from a relatively specialised leveraged-trading mechanism into an increasingly key component of India’s capital-market ecosystem. Its principal benefit lies in enabling investors to deploy capital more efficiently
and access investment opportunities with greater flexibility, while its principal risks arise from financing costs, margin requirements, liquidity constraints, and the possibility of forced liquidation.

As MTF becomes increasingly technology driven, the risk framework must also recognise the potential for common exposures and correlated behaviour, particularly where technology, rule-based strategies and leverage interact.

M/s. R. R. Builders v. Nandkumar Mulani and Anr : Tribunals may impose a reasonable three-year completion timeline when allotment letters fail to specify the date of possession.

8. Second Appeal (Stamp) No. 19058 of 2026 with Interim Application No. 5313 of 2026

Bombay High Court

M/s. R. R. Builders v. Nandkumar Mulani and Anr

Date of Order: 22.07.2026

The Appellate Tribunal was justified in imposing a reasonable period of three years for completion of project in absence of date of possession specified in the allotment letter and on failure on the part of the builder / promoter to enter into an agreement for sale and complete the project and handover possession to the allottee.

Treating the date of completion at the time of registration (as against the contractual date or a reasonable period of 3 years) is contrary to the statutory scheme and susceptible to undermine the very object of the Act.

FACTS

The Respondent Allottee was allotted a 3BHK Residential Flat measuring approximately 2144 sq ft. in the project then named Godrej Sky by the Appellant vide allotment letter dated 31.01.2013 for a consideration of Rs. 4,03,07,200. An earnest amount of Rs. 1,00,00,000 was paid by the Respondent Allottee in the beginning. Subsequently, the Respondent Allottee made payments and an aggregate amount of Rs. 2,01,53,600, that is, almost 50% of the aggregate consideration was paid to the Appellant. The Appellant neither executed an Agreement for Sale nor was the project anywhere near completion till the year 2021. The Respondent Allottee, vide letter dated 01.07.2021 demanded the refund of amount paid alongwith interest.

Since the Appellant failed to refund the amount paid by the Allottees, a complaint was filed before the Maharashtra Real Estate Regulatory Authority (MahaRERA) which came to be rejected vide order dated 20.09.2023 holding that the complaint was premature as the project was registered with MahaRERA on 05.08.2017 with a declared completion date of 30.06.2025. Aggrieved by the said order, the Respondent Allottee preferred an appeal before the Appellate Tribunal.

The Tribunal held that in absence of specific date of delivery of possession, the Appellant was under an obligation to deliver the possession within a reasonable time, which, in the circumstances of the case was 3 years. Aggrieved by the said order of the Tribunal, the Appellant filed an appeal before the High Court.

HELD

The High Court held that the Appellate Tribunal acted within its powers in imposing the reasonable period of 3 years for completion of project, else it would amount to granting liberty to the promoter for breach of statutory and contractual obligation thereby allowing him to convert his own default into an advantage – a result wholly inconsistent with the regime of fairness and transparency which RERA sought to achieve. The contention of the Appellant that the date of completion at the time of registration must be treated as conclusive was held to be contrary to the statutory scheme and was susceptible to undermine the very object of the Act. No fault could be attributed to the Respondent, who was not responsible for the Appellant’s default. It was held that the liability of the Appellant was squarely governed by the decision of the Hon’ble Supreme Court in the case of Newtech Promoters and Developers Pvt. Ltd. v. State of UP (2022) 1 SCC 401. The High Court, thus, held that no substantial question of law arose and dismissed the appeal.

Raipur Development Authority v. Anup Kumar Sahu : Allottees have an unconditional right to refund for possession delays, even without formal contracts specifying the target completion date.

7. MANU/CG/0356/2024

Chhattisgarh High Court

Raipur Development Authority v. Anup Kumar Sahu

Date of Order: 17.01.2024

An allottee has an unconditional right to refund under section 18(1) of the Real Estate (Regulation and Development) Act, 2016 when there is delay of possession beyond the stipulated date notwithstanding the fact that delay was due to pending litigation and notwithstanding that there was no written agreement or formal contract expressly recording the date of possession.

FACTS

The Respondent filed an application before the Real Estate Regulatory Authority (RERA) under section 31 of the Real Estate (Regulation and Development) Act 2016, (“the Act”) on the ground that he had not received the possession of the house. It was stated that the Respondent was allotted a 2 BHK Duplex Row House on 10.06.2016 for an amount of Rs. 18,25,000. The Respondent had deposited an amount of Rs. 18,21,250 upto 31.10.2017. However, even after four years of filing the application before the RERA, the Respondent did not get the possession of the said house. Vide a letter dated 27.08.2020, the promoter RDA required the Respondent to deposit an amount of Rs. 23,33,963 wherein the GST amount was also shown.

At the time of purchase of the house, though it was stated that the price was tentative price and the actual price may increase by 2-3%. However, the amount claimed was higher to the extent of 35% instead of 1-2%. The Respondent requested for allotment of house with an increase of 2% and in the alternate requested for allotment of plot in another project known as Indraprastha -2 on the price which was prevailing in the year 2016. Further, the Respondent also submitted that if RDA was not willing to proceed as per the request, the entire deposit amount be refunded to the Respondent.

The Appellant RDA stated that the delay was attributable to the litigation pending before the Green Tribunal and the Supreme Court. Thereafter, there was assembly election and consequently, no development could be carried out. It was stated that the development was carried out upto June 2019 and thereafter application for extension was sought from the State Government. It was stated that the Appellant was ready to return the money and the application be dismissed.

The RERA, vide order dated 02.01.2021 dismissed the application and held that the increased price could not be accepted as there was no agreement executed. However, the application was dismissed, and it was held that since the Respondent failed to deposit the amount he was called upon to deposit by 11.09.2020, the increased amount was not paid, no relief could be granted. Further, it was also held that since the proceedings were pending before the National Green Tribunal and the Supreme Court from 2013 to 2019 and certain orders were passed, the delay caused was reasonable.

Against this order, an appeal was preferred by the Respondent before the Real Estate Appellate Tribunal which was decided in favour of the Respondent vide order dated 07.03.2023 and directions were issued to return the deposit amount of Rs. 18,25,000 paid by the Respondent along with interest at 10.5% from 08.06.2016 within a period of 45 days. Against the said order of the Appellate Tribunal, an appeal has been preferred by the RDA before the High Court.

HELD

The Hon’ble High Court remarked that on perusal of the records of RERA, judgements and stay orders of the Green Tribunal and the Supreme Court were not found on record and therefore, no inference could be drawn. The Hon’ble High Court relied upon the decision of the Hon’ble Supreme Court in the case of Newtech Promoters and Developers Pvt. Ltd. v. State of UP & Others etc (Civil Appeal No. 6745-6749 of 2021]and held that the right of an allotee to seek refund is not dependent upon contingencies and if the allotee has exercised the option to get back the deposit, the allottee cannot be directed to take delayed possession of the house. Further, the High Court observed that even though there was no agreement which fixed the time limit for possession, it could be inferred from the other factual aspects such as date of completion registered with RERA (being 31.03.2019), that the target date of completion was 31.03.2019. The additional amount was demanded in July 2020 which was beyond the target date of completion. The High Court held that when the terms were directed by an institution like RDA and general people at large, imposed faith and deposited the amount, then RDA would be bound by the promise and the promise would be enforceable at the instance of the promisee Respondent in the present case, notwithstanding the fact that there was no consideration for the promise and the promise was not recorded by way of a formal contract. Thus, the High Court held that RDA was not entitled to immunity and was under an obligation to refund the deposit.

Wadhwa Group Housing Private Ltd. v. Vijay Choksi and Ors.: Multiple promoters are jointly liable for refunds under section 18, regardless of direct privity of contract with the allottee.

6. MANU/MH/1177/2024

Bombay High Court

Wadhwa Group Housing Private Ltd. v. Vijay Choksi and Ors.

Date of Order: 26.2.2024

In a real estate project having more than one promoter, every promoter is liable to refund the amount u/s 18 along with interest. A promoter cannot escape the statutory liability on the ground that the consideration was received exclusively by the co-promoter or that there was no direct privity of contract with the allottee.

FACTS

Wadhwa Group Housing Pvt. Ltd. (“the Appellant”) preferred an appeal against the order dated 18th October, 2022 passed by Maharashtra Real Estate Appellate Tribunal, Mumbai (AT) directing both the Appellant herein and SSS Escatics Pvt. Ltd. (Respondent No. 2 herein) to refund of entire amount paid by Vijay Choksi (Respondent No. 1) with interest.

Briefly stated, in respect of a project known as The Nest at Mumbai, the Appellant and Respondent No. 2, entered into a Joint Development Agreement (JDA) agreeing to share the constructed areas between them for being sold to customers. Since the project was incomplete on the date of coming into force of Real Estate (Regulation and Development) Act, 2016 (“the Act”) it was registered as an ongoing project and the Appellant was declared as a Promoter (Investor).

The Respondent No. 1 booked a 3BHK flat, coming to the share of Respondent No. 2, and was issued an allotment letter dated 24.7.2013 by Respondent No. 2. The Respondent No. 1 paid several amounts to Respondent No. 2 from time to time. Since there was a delay in completion of the project, Respondent No. 1 filed a complaint to MahaRERA who held both Respondent No. 1 as well as promoters responsible for violation of provisions of section 4 of the MOFA and held that the Respondent No. 1 could not claim any equity under the provisions of RERA.

Aggrieved, Respondent No. 1 preferred an appeal against the order of the AT. The AT directed both Respondent No. 2 and the Appellant to refund the entire amount paid by Respondent No. 1 with interest to Respondent No. 1.

Aggrieved, by the order of the AT, the Appellant preferred the present appeal (second appeal) to the High Court on the ground that a promoter who has not received any consideration from an allottee cannot be made liable for giving refund with interest under section 18 of the Act. It also contended absence of direct privity of contract with Respondent No. 1.

HELD

The court held that the term `promoter’ has been so widely defined that it virtually includes every person associated with construction of the building. It held that even a person who is merely an investor in the project along with the Promoter and who is entitled to benefit in the real estate project is also covered by the definition of the term `Promoter’. Since it was an undisputed fact that the Appellant is entitled to a share in the constructed area which it is entitled to sell and accept consideration for such sale, the court held that there is no doubt to the position that both Appellant as well as the Respondent No. 2 are Promoters and are jointly liable in respect of the responsibilities under the RERA and Rules and Regulations made thereunder. Therefore, mere falling of flat in the share of Respondent No. 2 under the JDA would not excuse the Appellant from the responsibilities and liabilities under the RERA, Rules and regulations made thereunder qua that flat. RERA does not demarcate or restrict liabilities of different promoters in different areas. The liability is joint for all purposes under the Act, Rules and Regulations.

As regards the contention urged on behalf of the Appellant that this is not a fresh project after coming into force of RERA and that JDA was executed way back in the year 2012, the court held that mere registration of the project as an ongoing project would not make any difference so far as the joint liability of several promoters is concerned. It observed that the circular dated 4.12.2017 was issued particularly with reference to the ongoing project. By continuing the joint venture with Respondent No. 2 at the time of registration of the project, the Appellant has accepted all the liabilities of a Promoter under the Act and he cannot seek to escape the liability on a specious plea that the payments were made to Respondent No. 2 alone.

Section 18(1)(b) casts a liability on the Promoter to return the amount received from the flat purchaser. Since the Appellant is also a `Promoter’ it is jointly liable to refund the amount along with other promoter, Respondent No. 2. Section 18 cannot be narrowly interpreted to include only that promoter who actually received the amount.

When a claim is raised in respect of a real estate project by a flat purchaser, all promoters become jointly liable qua that flat purchaser irrespective of whether there is privity of contract with each of the promoter or not. This is the scheme of RERA and mere absence of privity of contract with a particular promoter does not relieve such promoter in respect of the liabilities under RERA.

The court held that the Appellant cannot escape the liability to refund the amount received towards sale of flat to Respondent No. 1.

Ruma Mehta & Ors v. Parorch Developers LLP : Allotment letters with clear property descriptions and payment schedules constitute valid contracts, enforceable retroactively under the RERA Act.

5. MANU/RT/0304/2026

Maharashtra Real Estate Appellate Tribunal

Ruma Mehta & Ors v. Parorch Developers LLP

Date of Order: 09.06.2026

An allotment letter that discloses the description of the property, flat, consideration amount, payment schedule, and terms and conditions, etc. fulfils all the ingredients of a valid and concluded contract for sale and purchase, which is enforceable under the provisions of the Act.

Since the Act is retroactive, an allotment letter issued prior to coming into force of the Act is enforceable under the Act.

FACTS

The Appellant booked a flat in the project of the Respondent for a consideration of Rs 3.75 crore by paying a sum of Rs 1.00 crore on 17.2.2014 by cheque. Upon receiving the said payment, the Respondent / Promoter confirmed that it will issue an allotment letter and called for further payments. The Appellant paid two more instalments. Thereafter, allotment letter dated 22.4.2014 was issued. The Promoter assured possession of the said flat by mid-2017. The Appellant thereafter paid further amounts to the Respondent making aggregate of payments to Rs 3.25 crore. Despite follow up when the Respondent failed to hand over possession, the Appellant filed a complaint on 19.4.2019 with the Authority seeking refund of amounts paid with interest under section 18 of the Act.

The Authority held that no directions are warranted under the Act since no agreement for sale was been executed and registered between the parties. Moreover, the cause of action for cancellation of booking has taken place prior to the RERA Act, 2016 coming into force.

Aggrieved, the Appellant preferred an appeal seeking to set aside the order of the Authority and a direction to the Promoter to refund the principal amount along with interest.

HELD

The Tribunal noted that despite having received 90% of the consideration amount, the Promoter failed to execute and register the agreement for sale. Since the Respondent failed to hand over the possession by due date, the Appellant was held to be entitled to a refund along with interest under section 18 of the Act.

The Tribunal observed that a closer examination of the allotment letter revealed that it disclosed the description of the property, flat, consideration amount, payment schedule, and terms and conditions, etc. Acceptance of payments in furtherance of the said allotment letter was held to reveal a clear picture of fulfilment of clauses (a) and (b) of section 2 of Contract Act, 1872. It held that the said letter of allotment constitutes a valid and concluded contract of sale purchase transaction, which is enforceable under the provisions of RERA Act, 2016.

Although the promised date of possession was mid2017, the allotment letter did not mention the same. The Tribunal noted that the Apex Court in Fortune Infrastructure (Now known as M/s. Hicon Infrastructure) & Anr. v. Trevor D’Lima & Ors. [MANU/SC/0253/2018 : (2018) 5 SCR 273] has held that if the date of possession is not mentioned in the agreement, the promoter is expected to hand over the possession of the unit within a reasonable time and the period of three years has been held to be reasonable. Therefore, the due date of possession of the said flat would be February 2017.

In the light of exposition of law contained in the decision of the Apex Court in the case of Newtech Promoters and Developers Pvt. Ltd. v. State of U.P. & Others [Civil Appeal No(s). 6745-6749 of 2021 (arising out of SLP (Civil) No(s). 3711-3715 of 2021 decided on 21st November, 2021], the Tribunal held that the said allotment letter which was executed prior to coming into force the RERA Act, 2016 can be enforced under the provisions of RERA Act, 2016.

It held that the appellant is entitled to seek relief under the provisions of RERA Act, 2016 even though the said allotment letter was executed prior to RERA Act, 2016 coming into force.

IBC Acts As a Shield against Cheque Bouncing Proceedings – Fact or Myth?

Section 138 of the NI Act penalises cheque bouncing, blending civil recovery with criminal penalties. Under the IBC, Section 14 imposes a moratorium shielding corporate debtors from legal proceedings, including s.138 actions, to provide “breathing space” for resolution. However, the Supreme Court clarified that this protection only applies to the company; directors and signatories remain personally liable for criminal prosecution. Recent jurisprudence in Surana (2026) complicates this by proposing a “tiered” approach that separates penal and compensatory facets, referring the conflict to a larger bench for final determination.

INTRODUCTION

One of the most popular sections that several businessmen are aware of is s.138 of the Negotiable Instruments Act, 1881 (“the NI Act”), also colloquially known as the cheque bouncing section. This section provides for imprisonment in certain cases of dishonoured cheques issued by a drawer.

On the other hand, the Insolvency and Bankruptcy Code, 2016 (“the Code”) has become one of the most dynamic and fast-changing legislations. The Code provides for the insolvency resolution process of corporate debtors. The Code gets triggered when a corporate debtor commits a default in payment of a debt, which could be financial or operational. One of the important facets of this resolution process is that of a moratorium on legal proceedings against the corporate debtor contained u/s. 14 of the Code.

However, what happens when the sword of s.138 of the NI Act, meets the impenetrable shield of s.14 of the Code? In short, what happens when a cheque issued by a corporate debtor is dishonoured and that corporate debtor has a moratorium on legal proceedings by virtue of s.14 of the Code? Can there be criminal proceedings against the company and its directors/drawers of the cheques? The answer, interestingly, is yes and no! Let us examine this interesting judicial crossroad.

Cheque-Bouncing-and-Bankruptcy

WHEN DOES S.138 GET TRIGGERED?

Let us briefly examine the impugned section. S.138 of the NI Act provides that if any cheque is drawn by a person (drawer) in favour of another person (payee) and if that cheque is dishonoured because of insufficient funds in the drawer’s bank account, then such drawer is deemed to have committed an offence. The penalty for this offence is imprisonment for a term which may be extended to 2 years and/or with a fine which may extend to twice the amount of the cheque.

To invoke the provisions of s.138, the following three steps are necessary:

(i) the cheque must be presented to the bank within a period of 3 months from the date on which it is drawn or within the period of its validity, whichever is earlier;

(ii) once the payee is informed by the bank about the dishonour of the cheque, then he must within 30 days of such information make a demand for the payment of the said amount of money by giving a notice in writing, to the drawer of the cheque; and

(iii) the drawer of such cheque fails to make the payment of the said amount of money to the payee of the cheque, within 15 days of the receipt of the said notice.

A fourth step is specified under s.142 of the Act which provides that a complaint must be made to the Court within one month of the date from which the cause of action arises (i.e., the notice period). A rebuttable presumption is drawn by the NI Act that the holder of the cheque received it for the discharge, in whole or in part, of any debt or other liability. In a case where the drawer is a company- the Directors and the persons concerned for running of the company including the Managing Director or any other officer of the entity with whose consent or connivance the offence has been committed can be prosecuted. Section 141 of the Act regulates offences by companies. Under sub-section (1), every person who, at the time the offence was committed, was in charge of and responsible to the company for the conduct of its business — typically the Managing Director or a whole-time director — is deemed liable, subject to a proviso permitting such person to show that the offence was committed without his knowledge or that he had exercised due diligence to prevent it. Under sub-section (2), a director, manager, secretary or other officer is additionally liable where the offence is shown to have been committed with his consent or connivance, or is attributable to any neglect on his part. Various Supreme Court decisions have held that non-executive directors/independent directors cannot be prosecuted for such offences.

In Vinay Devanna Nayak v. Ryot Sewa Sahakari Bank Ltd. [2008] 2 SCC 305, a Division Bench of the Apex Court referred to the object of s.138 thus:

“16. Section 138 of the Act…. to regulate financial promises in growing business, trade, commerce and industrial activities of the country and the strict liability to promote greater vigilance in financial matters. ……… The provision has been introduced with a view to curb cases of issuing cheques indiscriminately by making stringent provisions and safeguarding interest of creditors.”

A Three-Judge Bench of the Supreme Court in P. Mohanraj v. Shah Brothers Ispat (P.) Ltd., (2021) 6 SCC 258 explained that s.138 shows that the legislature was cognizant of the fact that what was otherwise a civil liability was now also deemed to be an offence, since this liability was made punishable by law. The transaction covered by the section was a commercial transaction between two parties which involved payment of money for a debt or liability. The explanation to Section 138 made it clear that such debt or other liability meant a legally enforceable debt or other liability. This, coupled with fine that may extend to twice the amount of the cheque that was payable as compensation to the aggrieved party to cover both the amount of the cheque and the interest and costs thereupon, showed that it was really a hybrid provision to enforce payment of a bounced cheque if it was otherwise enforceable in civil law. Further, though the ingredients of the offence were contained in the first part of Section 138 when the cheque was returned by the bank unpaid, the proviso gives a second opportunity to the drawer of the cheque. This again made it clear that the real object of the provision was not to penalise the wrongdoer for an offence that was already made out, but to compensate the victim. The Court concluded that it was clear that a s.138 proceeding could be said to be a “civil sheep” in a “criminal wolf’s” clothing, as it was the interest of the victim that was sought to be protected, the larger interest of the State being subsumed in the victim alone moving a court in cheque bouncing cases.

Again, in Kaushalya Devi Massand v. Roopkishore Khore, [2011] 4 SCC 593, it was held that the gravity of a complaint under the Act could not be equated with an offence under the provisions of the Penal Code, 1860 or other criminal offences. An offence under s.138 of the NI Act was almost in the nature of a civil wrong which had been given criminal overtones.

In R. Vijayan v. Baby (2012) 1 SCC 260, the Court held that s.138 was a unique exercise which blurred the dividing line between civil and criminal jurisdictions. It provided a single forum and single proceeding, for enforcement of criminal liability (for dishonouring the cheque) and for enforcement of the civil liability (for realisation of the cheque amount) thereby obviating the need for the creditor to move two different fora for relief. The apparent intention was to ensure that not only the offender was punished, but also to ensure that the complainant invariably received the amount of the cheque by way of compensation.

In Dashrath Rupsingh Rathod v. State of Maharashtra (2014) 9 SCC 129, a three-Judge Bench of the Court held that Parliament was aware that they were converting civil liability into criminal content inter alia by the deeming fiction of culpability in terms of the pandect comprising s.138.

In Meters and Instruments (P) Ltd. v. Kanchan Mehta (2018) 1 SCC 560 it was held that the object of the statute was to facilitate smooth functioning of business transactions. The provision was necessary as in many transactions cheques were issued merely as a device to defraud the creditors. Dishonour of cheque caused incalculable loss, injury and inconvenience to the payee and credibility of business transactions suffered a setback. The object of the provision was described as both punitive as well as compensatory. The intention of the provision was to ensure that the complainant received the amount of cheque by way of compensation. Though proceedings under section 138 could not be treated as civil suits for recovery, the scheme of the provision, providing for punishment with imprisonment or with fine which could extend to twice the amount of the cheque or to both, made the intention of law clear. The offence under s.138 of the NI Act was primarily a civil wrong.

WHAT PROTECTION DOES S.14 OF THE CODE PROVIDE?

Once the insolvency resolution petition against the corporate debtor is admitted by the National Company Law Tribunal (NCLT) and after the corporate insolvency resolution process commences, the NCLT declares a moratorium prohibiting institution or continuation of any suits against the debtor; execution of any judgment of a Court/authority; any transfer of assets by the debtor; recovery of any property against the debtor. The moratorium continues till the resolution process is completed. Thus, total protection is offered to the debtor against any suits/proceedings.

An extract of the relevant provisions of s.14 of the Code is reproduced below:

“Moratorium.

14. (1) Subject to provisions of sub-sections (2) and (3), on the insolvency commencement date, the Adjudicating Authority shall by order declare moratorium for prohibiting all of the following, namely:

(a) the institution of suits or continuation of pending suits or proceedings against the corporate debtor including execution of any judgment, decree or order in any court of law, tribunal, arbitration panel or other authority;

(b) transferring, encumbering, alienating or disposing of by the corporate debtor any of its assets or any legal right or beneficial interest therein;

(c) any action to foreclose, recover or enforce any security interest created by the corporate debtor in respect of its property including any action under the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002 (54 of 2002);

(d) the recovery of any property by an owner or lessor where such property is occupied by or in the possession of the corporate debtor.

(4) The order of moratorium shall have effect from the date of such order till the completion of the corporate insolvency resolution process:”

The Apex Court in P. Mohanraj (supra) has held that the sweep of the provision was very wide indeed as it included institution, continuation, judgment and execution of suits and proceedings. It was clear that the expression “institution of suits or continuation of pending suits” was to be read as one category, and the disjunctive “or” before the word “proceedings” would make it clear that proceedings against the corporate debtor would be a separate category.

TWO ACTS AT LOGGERHEADS – WHICH WINS?

The question that now arises is that if there is a moratorium against a corporate debtor undergoing insolvency resolution, and a cheque issued by such a company has been dishonoured, then would an action under s.138 of the Act survive?

The Supreme Court in the decision of P. Mohanraj held that the width of the expression “proceedings” under s.14 of the Code was the expression “any judgment, decree or order” and “any court of law, tribunal, arbitration panel or other authority”. Since criminal proceedings under the Code of Criminal Procedure, 1973 [“CrPC”] were conducted before the courts mentioned in Section 6, CrPC, it was clear that a s.138 proceeding being conducted before a Magistrate would certainly be a proceeding in a court of law in respect of a transaction which related to a debt owed by the corporate debtor.

The idea was that it facilitated the continued operation of the business of the corporate debtor to allow it breathing space to organise its affairs so that a new management may ultimately take over and bring the corporate debtor out of financial sickness, thus benefitting all stakeholders, which would include workmen of the corporate debtor. The Apex Court further explained that while s.14(1)(a) referred to monetary liabilities of the corporate debtor, s.14(1)(b) referred to the corporate debtor’s assets, and together, these two clauses formed a scheme which shielded the corporate debtor from pecuniary attacks against it in the moratorium period so that the corporate debtor got breathing space to continue as a going concern in order to ultimately rehabilitate itself. Relying on this explanation, the Supreme Court did not allow cheque bouncing proceedings to continue against the corporate debtor u/s. 138 of the Negotiable Instruments Act, 1881. It held that a quasi-criminal proceeding that is contained in Chapter XVII of the Negotiable Instruments Act would, given the object and context of s.14 of IBC, amount to a ‘proceeding’ within the meaning of s.14(1)(a) of the Code and hence, the moratorium would attach to such a proceeding.

ARE SIGNATORIES ALSO SHIELDED?

In the above-referred decision of P. Mohanraj (supra), the Supreme Court also held that it is clear that the moratorium provision contained in Section 14 of the IBC would apply only to the corporate debtor, the natural persons, i.e., its Directors in charge of its affairs continued to be statutorily liable under of the Negotiable Instruments Act. Accordingly, criminal proceedings could continue unabated against the Managing Director / Other Directors who have drawn the bounced cheque.

It is important to note that this very premise — that a director may be prosecuted independently of the corporate debtor — rests on the ratio laid down in Aneeta Hada v. Godfather Travels & Tours (P) Ltd., (2012) 5 SCC 661, where a Constitution Bench held that a director cannot be prosecuted under Section 141 of the NI Act unless the company itself is arraigned as an accused in the same complaint. It is this requirement of joinder that gives the s.14 moratorium its practical effect in the first place: the company, being the primary accused, is shielded and the proceeding qua it stands stayed, while the derivative liability of the directors, being independent of that stay, continues to be prosecuted in the very same complaint.

In Narinder Garg v. Kotak Mahindra Bank Ltd. [2022] SCC Online SC 517, the Supreme Court held that the moratorium provisions contained in s.14 of the Code would apply only to the corporate debtor and that the natural persons mentioned in s.141 of the Act would continue to be statutorily liable under the provisions of the Act.

A subsequent decision of the Supreme Court in Ajay Kumar Radheyshyam Goenka v Tourism Finance Corporation of India Ltd., (2023) 10 SCC 545 has observed:

“What follows from the aforesaid is that for difficulty in prosecuting the corporate debtor under section 138 of the NI Act after the approval of the resolution plan under the IBC, we need not let the natural persons i.e., the signatories to the cheques/directors of the corporate debtor escape prosecution. How can one allow the natural persons to escape liability on such specious plea?”

It held that where the proceedings under section 138 of the Act had already commenced and during the pendency the plan was approved or the company got dissolved, the directors and the other accused could not escape from their liability by citing its dissolution. What was dissolved was only the company, not the personal penal liability of the accused covered under the NI Act.

A distinction, however, deserves to be drawn between the personal liability of the director discussed above and the liability of the corporate debtor itself. S.32A of the Code, upheld as constitutionally valid in Manish Kumar v. Union of India, (2021) 5 SCC 1, expressly extinguishes the liability of the corporate debtor itself for offences committed prior to commencement of the CIRP, once a resolution plan was approved and resulted in a change in the management or control of the corporate debtor. This extinguishment, however, was confined to the corporate debtor as a juristic entity; it did not, on its own terms, touch the personal liability of the erstwhile promoters, directors or officers who were in-charge of the affairs of the company at the time the offence was committed, and it was precisely this gap that Goenka (supra) filled by holding that such natural persons continue to remain answerable under s.138 notwithstanding the corporate debtor’s own liability having been extinguished under Section 32A.

It is worth noting that the ground was already unsettled before the two-Judge Bench took up Surana. The Bombay High Court, in Sheetal Gupta vs. National Spot Exchange Limited, 2023 SCC OnLine Bom 3095, directed a stay of criminal proceedings under s.138 of the NI Act against the concerned persons representing the corporate debtors. The Court read the phrase “any debt” in the IBC widely enough to include the liability that could arise from a s.138 complaint and applied P. Mohanraj’s reasoning that such a proceeding was fundamentally a civil-recovery in character. On that basis, it held the applicant-director’s personal insolvency moratorium was covered and stayed the s.138 prosecution against him.

The Madhya Pradesh High Court, in Surendra Kumar Patwa v. Dharmendra Vohra, 2024 SCC OnLine MP 7371, followed this reasoning along with that of P. Mohanraj and likewise extended the interim moratorium to stay s.138 proceedings against an individual in personal insolvency. The Court held that P. Mohanraj’s rationale was not confined to the corporate moratorium and extended the analogy to the interim moratorium under Section 96 of the Code for an individual/personal guarantor, reading “any legal action or proceeding pending in respect of any debt” as wide enough to sweep in s.138 proceedings. It also treated the decision in Ajay Goenka (supra) as distinguishable/per incuriam on the point, since (in its view) Goenka had not squarely engaged with Mohanraj’s civil characterisation of s.138.

TWIST IN THE TALE

The discussion so far has concerned the corporate debtor’s own moratorium under Section 14 of the Code. The same underlying principle — that a director’s personal liability survives independently of the debtor’s insolvency — was reaffirmed by the Supreme Court in the context of the Part III moratorium governing personal insolvency of individuals, in Rakesh Bhanot v Gurdas Agro (P.) Ltd., (2025) 6 SCC 781, where the Court held that the scope and nature of the proceedings under the Code might result in extinguishment of the actual debt by restructuring or through the process of liquidation. However, such extinguishment could not absolve its directors from criminal liability. S.141 of the Act enabled the prosecution of the persons in charge of the affairs and responsible for the conduct of the business of the company along with the company. The statutory liability against the directors was personal and hence, continued to bind natural persons, irrespective of any moratorium applicable to the corporate debtor. The acceptance of the resolution plan under the Code or its implementation did not have any effect on the prosecution under s.138 of the Act. The distinction between the right to sue based on a dishonoured cheque by initiating a civil suit and launching a prosecution under s.138 of the Negotiable Instruments Act was significant. In the case of the former, the interim moratorium operated, but not in case of the latter.

The Court concluded that allowing the signatories to evade prosecution under s.138 by invoking the moratorium would undermine the very purpose of the NI Act which was to preserve the integrity and credibility of commercial transactions, and the personal responsibility persisted, regardless of the insolvency proceedings.

A two-Judge Bench in Dineshchand Surana v. UCO Bank, 2026 INSC 579 has ignited a fresh controversy. The Bench undertook a fundamental re-examination of the interface between the Act and the moratorium provisions of the Code and in doing so introduced a bifurcated or “tiered” understanding of s.138 that had not previously found articulation in this form. The Court held that s.138 proceedings were not monolithic but comprised of two distinct facets — a penal or criminal facet, directed at conviction, sentence and fine as punishment for the offence of dishonour, and a compensatory facet, under which the trial court may direct payment of compensation to the complainant (a remedy that the Bench described as functionally akin to a civil suit for recovery of debt).

On this analysis, the Bench held that the moratorium under the IBC (governing personal insolvency of individuals and partnership firms) cannot attach to the criminal facet, since permitting a debtor to use the moratorium as a shield against prosecution would defeat the penal and deterrent purpose of s.138 and reward evasion of criminal liability. However, because the compensatory facet was civil in substance and directly affected the debtor’s asset pool during the insolvency process, the Bench held that this facet did attract the protection of the moratorium — extending, notably, even to directors made vicariously liable under Section 141 where they were themselves undergoing personal insolvency.

The controversy that Surana has ignited is, in truth, two-fold. First, it questioned the very foundation laid in P. Mohanraj (supra), which had characterised s.138 in essentially unitary civil-recovery terms — famously as a “civil sheep in a criminal wolf’s clothing” — and had accordingly treated the entirety of such proceedings against a corporate debtor as covered by the s.14 moratorium. By dissecting s.138 into penal and compensatory tiers and doubting whether Mohanraj’s civil characterisation can be sustained without qualification, the Bench in Surana effectively signalled disagreement with the reasoning of a coordinate or higher-strength Bench without formally overruling it. Hence, the Court referred the matter for re-examination to a larger Bench. Second, and just as significantly, the tiered approach sat uneasily against the Court’s own very recent ruling in Rakesh Bhanot (supra), which had taken an unqualified, blanket position that the interim moratorium did not stay any facet of s.138 — criminal or compensatory. It held that the reference to the three-Judge Bench may decide on the following questions:

(i) Whether the provisions of s.138 of the Act and the objective underlying the enactment thereof indicate that it is quasi-criminal in nature with a tilt towards the criminal side?

(ii) Whether the moratorium provisions under the IBC should be made applicable on the entire proceedings under s.138 of the Act or only to the compensatory aspect thereof?

Meanwhile, at the High Court level, the interregnum is already being tested. The Telangana High Court in V. Narayana Reddy v. State of Telangana, (2026) ibclaw.in 193 HC, has held that promoters, directors and nominee directors of a corporate debtor cannot seek quashing of s.138 proceedings merely on the ground that IBC proceedings have been initiated or concluded against the company — an approach consistent with the criminal-facet reasoning in Surana itself, even as the larger constitutional question remains pending before the three-Judge Bench.

CONCLUSION

The decision in the case of Surana(supra) has created a new quandary: until the reference is answered, whether Mohanraj’s broader, protection for corporate debtors under s.14 will survive? It is submitted that since Mohanraj is a decision of a three-Judge bench it would hold the fort till reversed by a larger bench.

Duliram Maurya v. Nandram: Prolonged and unexplained delay in depositing balance consideration under a specific performance decree disentitles the purchaser to time extension.

29. Duliram Maurya v. Nandram

2026 Live Law (AB) 5557

August 6, 2026

Specific performance – Failure to deposit balance consideration within time stipulated in decree – Extension of time under section 28 – prolonged and unexplained delay – Discretion to extend time must be exercised on equitable principles – Wilful negligence of decree-holder disentitles extension. [Specific Relief Act, 1963, S.28]

FACTS

The petitioner and respondent entered into an agreement to sell dated 3 July 1991 for a consideration of `25,000/-. The respondent paid `13,000/- as advance and the balance `12,000/- was to be paid at the time of execution of the sale deed.

The respondent instituted a suit for specific performance, which was dismissed by the Trial Court.
In appeal, the suit was decreed. The petitioner was directed to execute the sale deed within two months, and the respondent was directed to deposit the balance consideration within one month.

The petitioner preferred a second appeal. No interim order was passed therein. The respondent did not deposit the balance consideration within the stipulated period. Execution proceedings were initiated only on 6 August 2012. The second appeal was dismissed on 23 September 2019. Thereafter, the petitioner applied under section 28 of the Specific Relief Act for rescission of the contract. The respondent, however, filed an application on 17 November 2025 seeking extension of time for depositing the balance consideration and condonation of delay. The executing court allowed the application subject to payment of Rs.1,000/- as costs. The revision filed by the petitioner was dismissed.

HELD

The Court held that a decree for specific performance is in the nature of a preliminary decree and the Court does not become functus officio upon passing of the decree. Under section 28, the Court retains jurisdiction, until execution of the sale deed, to either rescind the contract/decree or extend the time for payment of the balance consideration.

The power to extend time is, however, discretionary and equitable. While exercising such power, the Court must consider the attending circumstances, conduct of the parties, length of delay and the equities created in favour of the judgment-debtor. Mere expiry of the period stipulated in the decree does not result in automatic rescission; equally, payment after expiry does not result in automatic extension of time.

In the present case, the respondent had failed to deposit the balance consideration within one month of the decree dated 22 November 2003. Though execution proceedings were initiated in 2012 and an application for extension of time was filed, the respondent did not pursue the application. Even after dismissal of the second appeal in 2019, the respondent waited for more than six years before seeking extension of time in 2025.

The Court held that the conduct of the respondent disclosed wilful negligence and demonstrated that he was not genuinely interested in completing his part of the contract. The pendency of the second appeal could not justify the delay, particularly when no stay had been granted, and the respondent had not even contested the second appeal. The fact that the decree of 2003 merged in the judgment, dismissing the second appeal in 2019, did not assist the respondent. Even thereafter, he waited for more than six years before seeking extension of time. The Court held that the courts below had failed to properly balance the equities and had erred in permitting the respondent to deposit the balance consideration after such prolonged and unexplained delay.

The impugned orders are set aside. The Writ Petition was allowed.

Sanjay Sharma v. Krishnadhan Khaware : Disputed limitation issues for probate applications cannot be decided summarily as the right to apply is a continuous right.

28. Sanjay Sharma @ Sanjay Bhardwaj v. Krishnadhan Khaware & Ors.

2026 LiveLaw (SC) 683

July 15, 2026

Probate – limitation – Article 137 of Limitation Act – right to apply for probate is a continuous right – limitation does not necessarily commence from death of testator – Order VII Rule 11 – Disputed limitation issue cannot be decided summarily. [Indian Succession Act, 1925, Ss.222, 276; Limitation Act, 1963, Art.137; Code of Civil Procedure, 1908, Order VII Rule 11].

FACTS

An application for probate of a Will dated 15 April 1995 was filed in 2005. The testator had died approximately ten years earlier. The objectors applied under Order VII Rule 11 CPC seeking rejection of the probate application on the ground of limitation. The District Judge rejected the probate application and the High Court affirmed the decision.

The issue before the Supreme Court was whether a probate application filed several years after the death of the testator was barred by limitation.

HELD

The Supreme Court held that the Indian Succession Act, 1925 does not prescribe a specific limitation period for an application for probate. Consequently, Article 137 of the Limitation Act, 1963 applies, prescribing three years from the date when the right to apply accrues.

However, the Court rejected the proposition that the right to apply for probate necessarily accrues on the date of death of the testator.

An application for probate represents a continuous right which may be exercised whenever it becomes necessary to obtain the Court’s authority in relation to the Will. The right therefore accrues when the necessity to apply arises, which need not necessarily be within three years of the testator’s death.

In the present case, the necessity to seek probate arose when persons claiming adversely to the Will took hostile steps, including execution of a General Power of Attorney on 8 August 2005. The probate application filed on 31 August 2005 was therefore within limitation.

The Court also dealt with the second issue concerning Order VII Rule 11 CPC. It held that where limitation involves questions of fact – such as the date on which the applicant acquired knowledge of the relevant facts – the issue becomes a mixed question of law and fact and cannot ordinarily be decided summarily at the Order VII Rule 11 stage.

Further, an Order VII Rule 11 application is not the appropriate stage for making findings concerning whether the Will itself is suspicious or genuine. Such questions require appreciation of evidence in the substantive proceedings.

The Supreme Court accordingly restored the matter to the Civil Court for consideration in accordance with law. The Appeal was allowed.

Mahinder v. Puran Singh : Parliament possesses legislative competence to enact preferential rights of co-heirs for agricultural land under Hindu succession entries.

27. Mahinder & Ors. v. Puran Singh

2026 LiveLaw (SC) 625

July 14, 2026

Hindu Succession – Preferential right of co-heirs – Agricultural land – applicability of section 22 of the Hindu Succession Act – Legislative competence – Distinction between succession-based pre-emption and general pre-emption. [Hindu Succession Act, 1956, S.22; Constitution of India, Seventh Schedule, List III, Entry 5]

FACTS

The parties were siblings and had inherited agricultural land from their father as Class-I legal heirs. Some of the defendants sold their respective inherited shares to a third party. The plaintiff instituted proceedings under section 22 of the Hindu Succession Act, 1956 claiming the statutory preferential right to acquire the property.

The Trial Court dismissed the suit, relying upon Atam Prakash v. State of Haryana, 1986 AIR 859, which had struck down a provision of the Punjab Pre-emption Act as unconstitutional. The First Appellate Court reversed that decision, relying upon Babu Ram v. Santokh Singh, Civil Appeal No. 2553 of 2019, which had recognised the applicability of section 22 to agricultural land. The High Court declined to interfere in the second appeal.

The Supreme Court was therefore called upon to determine whether section 22 of the Hindu Succession Act applies to agricultural land and whether Parliament possessed legislative competence to enact such a provision.

HELD

The Supreme Court held that section 22 of the Hindu Succession Act applies to agricultural land. The right under section 22 is fundamentally a succession-based right. It is not a general law regulating transfers of agricultural land. Its purpose is to enable Class-I co-heirs who inherit property from a common intestate to prevent strangers from entering into the family property.

Applying the doctrine of pith and substance, the Court held that the dominant character of section 22 falls within Entry 5 of List III of the Seventh Schedule, dealing with succession. The fact that the exercise of the right may affect a proposed transfer does not transform the provision into a law regulating transfer of agricultural land.

Parliament therefore possessed legislative competence to enact section 22 even insofar as agricultural property is concerned. The Court also held that there was no conflict between the cases of Atam Prakash and Babu Ram.

The Court further held that where proceedings under section 22 were instituted before execution of the sale deed, the requirement that the alienation be “about to happen” stood satisfied. The plaintiff was not subsequently required to institute a separate challenge to the completed sale deed merely because the sale was effected during pendency of the section 22 proceedings.

Thus, the preferential right under section 22 is a limited, succession-based right of Class-I co-heirs and is fully enforceable in respect of agricultural land.

Chaitanya Suresh Kambli v. State of Maharashtra : Removing an auditor from the empanelment panel lacks statutory power for permanent debarment, violating their constitutional professional rights.

26. Chaitanya Suresh Kambli v. State of Maharashtra & Ors.

2026 LiveLaw (Bom) 368

July 29, 2026

Co-operative societies – Auditor’s panel – Removal from panel for one empanelment period – Permanent debarment from future empanelment – Absence of statutory power to impose perpetual embargo – Restriction violative of Article 19(1)(g). [Maharashtra Co-operative Societies Act, 1960, Ss. 75(2A), 81; Maharashtra Co-operative Societies Rules, 1961, R.69(1)(g); Constitution of India, Art.19(1)(g)]

FACTS

The petitioner was a qualified certified auditor and had been empanelled on the State Government’s panel of auditors for several years. He had acted as auditor of a Co-operative Housing Society Ltd. continuously for 13 years. This was contrary to the statutory restriction under section 75(2A), under which the same auditor could not be appointed by the same society for more than three consecutive years.

Following a complaint, the Commissioner/Registrar passed an order dated 7 October 2024 directing removal of the petitioner’s name from the panel of auditors published on 7 February 2024, which was operative only until 31 March 2026. When a fresh empanelment process was initiated for 2026-28, the Government relied upon clause 6(x) of its circular, which provided that an auditor whose name had been removed from the earlier panel under Rule 69(1)(g) would not be eligible for re-inclusion.

The petitioner challenged this restriction, contending that the earlier removal was only for the duration of the particular panel and that there was no statutory provision permanently debarring him from future empanelment.

HELD

The Court noted that section 75(2A) prohibits the same auditor from being appointed by the same society for more than three consecutive years. The statutory scheme therefore regulates the auditor-society relationship; it does not contemplate a permanent prohibition against the auditor being empanelled for other societies or in future panels.

Rule 69(1)(g) specifies circumstances in which the name of an auditor may be removed from the panel. However, the Court found no provision in the Act or Rules creating a permanent embargo against future empanelment merely because an auditor’s name had previously been removed from a panel. The Court held that clause 6(x) of the Government circular, insofar as it permanently prevented such an auditor from applying for subsequent empanelment, was unsustainable. A permanent removal from the State’s panel has serious consequences for the auditor’s professional right to carry on his occupation. Since neither section 81 nor Rule 69(1)(g) contemplated permanent debarment, the restriction was held to be violative of Article 19(1)(g).

The Court therefore held that the petitioner’s previous deplanement from the 2024-26 panel could not prevent him from applying for empanelment for 2026-28.

The Writ Petition was made absolute.

Mumtaz Ahmad Shah v. Chief Executive Officer, SRA : Eviction order implementation is a statutory obligation of the competent authority, and lack of enforcement machinery is no defence.

25. Mumtaz Ahmad Shah v. Chief Executive Officer, Slum Rehabilitation Authority & Ors.

2026 LiveLaw (Bom) 353

July 22, 2026

Slum Rehabilitation – Eviction order – Duty of Competent Authority to implement eviction – absence of enforcement machinery no defence – SRA/MHADA required to ensure mechanism for execution of eviction orders. [Maharashtra Slum Areas (Improvement, Clearance and Redevelopment) Act, 1971, Ss. 2(c), 3E, 33]

FACTS

The petitioner claimed possession of Flat which had been allotted to him. The Competent Authority had passed an order dated 4 July 2023 directing that possession of the premises be handed over to the petitioner. The petitioner approached the Bombay High Court under Article 226 seeking implementation of the eviction order. MHADA did not dispute that an eviction order had been passed but submitted that the Competent Authority did not possess the machinery necessary to execute it and had to depend upon the Slum Rehabilitation Authority (SRA). The SRA, in turn, submitted that the contractor previously engaged for execution of eviction orders was no longer available.

HELD

The Court examined sections 3E and 33 of the Maharashtra Slum Areas (Improvement, Clearance and Redevelopment) Act, 1971. Section 33 specifically empowers the Competent Authority to direct eviction and, for that purpose, to use or cause to be used such force as may be necessary.

The Court held that implementation of an eviction order is a statutory obligation of the Competent Authority. The authority cannot pass an eviction order and thereafter contend that it lacks the machinery to enforce it. Merely passing an eviction order without having the means to implement it would render section 33 meaningless and defeat its very object by encouraging unauthorised occupation.

Although the Competent Authority may seek assistance from the SRA, the SRA’s inability to provide machinery does not absolve the Competent Authority of its statutory obligation. The Competent Authority must devise a mechanism and ensure that adequate machinery is available for execution of eviction orders.

The Court directed the Principal Secretary, Housing Department, in coordination with the Vice President and Chief Executive Officer of MHADA and the Competent Authority, to ensure that the necessary machinery is put in place.

The Writ Petition was allowed and listed for compliance.

Non-Tariff Barriers: The New Face of Protectionism

As traditional tariffs decline globally, countries increasingly deploy non-tariff barriers (NTBs) like technical standards, environmental regulations, and data localization laws to protect domestic industries. While often framed as public health or safety measures, these complex, opaque regulations act as disguised protectionism. They disproportionately restrict market access for developing nations, exacerbating global trade inequalities. Looking ahead, NTBs are here to stay. Emerging technologies like AI and digital compliance frameworks will likely be weaponised by advanced economies to reinforce competitive advantages, creating a new generation of sophisticated barriers.

The globe suddenly isn’t shrinking as much. Increasingly the “global village” resembles independent fiefdoms, with political strongmen emerging as undisputed kings. With social, cultural and political upheaval, economics cannot be left behind. Indeed, arguably, there is no motivator stronger than economics to usher in change, whether social, cultural or political.

Since time immemorial, trade has been used as a strategic tool by shrewd statesmen either to assert heft or to avoid economic annihilation. The simple truth about being alive is best described in a phrase “survival of the fittest”, coined by Herbert Spencer and adopted by Charles Darwin.1 When juxtaposed to economics it translates to “dance with the devil”, or thereabouts!


1 Paul, Diane B. The Selection of the ‘Survival of the Fittest’, Journal of the History of Biology, Vol. 21, No. 3, 1988, pp. 411–24.

There are different measures adopted by States to make the life of a product entering the country difficult – by putting a tax (a tariff or customs duty) at the border, thereby directly adding to the price or by using rules and procedures that are not tax and yet can significantly obstruct trade. Tax is charged at the very threshold, when a product crosses the customs border.2 It is visible and the impact is easy to measure, the non-tariff measures on the other hand are rules framed by States in a manner that they affect trade for eg., health and safety rules for food3, quality standards for products4, special permissions for sensitive goods5 etc. These measures are used to shield domestic industries from foreign competition.


2 Section 12 of the Customs Act, 1962 read with Section 3 of the Section 3 of the Customs Tariff Act, 1975.
3 Food safety and health regulations in India are primarily governed by the Food Safety and Standards Act, 2006, which consolidates various legacy food laws and lays down science-based standards for food items, while regulating their manufacture, storage, distribution, sale, and import. The framework is administered by the Food Safety and Standards Authority of India and is supplemented by rules and regulations, including the Food Safety and Standards Rules, 2011, Food Safety and Standards (Import) Regulations, 2017, Food Safety and Standards (Packaging and Labelling) Regulations, 2011, and the Food Safety and Standards (Contaminants, Toxins and Residues) Regulations, 2011.
4 Quality standards for non-food industrial goods, including electronics, chemicals, and consumer products, fall under the jurisdiction of the Bureau of Indian Standards (“BIS”) and relevant line ministries. The governing framework is anchored in the Bureau of Indian Standards Act, 2016 (which replaced the 1986 Act), establishing BIS as the national standards body responsible for product standardization, marking, and quality certification. Key non-tariff enforcement mechanisms include Quality Control Orders, issued by ministries, which render specified Indian Standards mandatory and prohibit the manufacture, sale, or import of non-compliant goods. The Compulsory Registration Scheme, which mandates testing and registration for notified electronics, IT, and solar products prior to market entry and the Foreign Manufacturers Certification Scheme, which requires overseas manufacturers exporting notified goods to India to obtain a valid BIS licence.
5 Imports and exports of sensitive and dual-use items under the FTP 2023 are governed by Section 3 read with Sections 11, 13, and 14 of the Foreign Trade (Development and Regulation) Act, 1992. Read with Paragraph 2.08, Chapter 2 of FTP 2023, trade in restricted or sensitive items strictly mandates prior import/export authorizations or permissions issued by the Directorate General of Foreign Trade. Specific control over dual-use, defense, and strategic goods is exercised under the SCOMET framework (Chapter 10, FTP 2023), which requires specialized clearances.

A question to ask in today’s interconnected and yet distant world, is – are these “invisible” rules and procedures a larger hindrance to trade than the old-fashioned taxes on import? From an Indian standpoint what does it mean for the country, its people and the businesses involved?

INDIAN PERSPECTIVE: DECLINING TARIFFS, RISING BARRIERS

A bare reading of the Foreign Trade Policy 2023 (“FTP 2023”) indicates that exports and imports are generally “free” unless specifically restricted/prohibited6. A further perusal of the customs tariff structure over the years would show that they have been gradually falling to meet with India’s international commitment7. Indeed, this is not an Indian phenomenon alone, many countries have reduced tariffs through trade negotiations. At the same time, they have introduced rules/regulations and conditions at and behind the border, that are now a major factor shaping trade.


6 Paragraph 2.01, Chapter 2, FTP 2023. 
7 Explainer: What the WTO’s Latest Trade Policy Review Says About India’s Economy and the Road to Viksit Bharat, 29th July 2026, https://indiasworld.in/explainer-what-the-wtos-latest-trade-policy-review-says-about-indias-economy-and-the-road-to-viksit-bharat/ (last accessed on 01.08.2026) & Report of Trade Policy Review: India, Trade Policy Review Body, 26th May 2026, https://www.wto.org/english/news_e/news_docs/S488_e.pdf (last accessed on 01.08.2026).

RISE OF NON-TARIFF BARRIERS IN GLOBAL TRADE

As the globe turned into a “global village”, a term popularized by Canadian media theorist Marshall McLuhan8, trade expanded and with it there was a global push for trade liberalization. While this promoted free trade in principle, it hindered the ability of governments to use tariff measures as protective shields. Newer methods thus were devised by governments, that pivoted to alternative mechanisms that do not fall foul of international norms while yet offering protection to domestic industries.


8 Mass Media and the Global Village, Yale University Press, 17th November 2016, https://yalebooks.yale.edu/2016/11/17/mass-media-and-the-global-village/, (last accessed on 01.08.2026)

FORMS OF NON-TARIFF BARRIERS: REGULATION AS RESTRICTION

Non-tariff barriers can take various forms, either as regulatory mechanism, export control measures or restrictions on technology transfer etc. Technical barriers to trade have particularly become significant. These include product standards, labeling requirements and safety regulations that imported goods are expected to meet. What may often be justified on grounds of consumer protection and environmental sustainability also act as hidden barriers to trade. An instance that readily comes to mind is the stringent environmental standards that the European Union has imposed. Measures such as the Carbon Border Adjustment Mechanism, which effectively levy a carbon cost on imports of emission-intensive goods, and the proposed Packaging and Packaging Waste Regulation9, which mandates recyclability and reuse standards, have significantly elevated compliance thresholds for exporters. These may be difficult for exporters from developing countries to comply with, effectively limiting market access to countries that comprise the global south.


9 Carbon Border Adjustment Mechanism, European Union, https://taxation-customs.ec.europa.eu/carbon-border-adjustment-mechanism_en. (last accessed on 01.08.2026)

Use of sanitary and phytosanitary measures10, that aim to protect human, animal and plant health can also function as trade barriers. Although measures such as these are essential as public health safeguard, their excessive, strict or selective application may operate as non-tariff barriers to trade by imposing additional compliance burdens on foreign producers.


10 In the Indian context, sanitary and phytosanitary measures are implemented through a combination of statutory frameworks governing food safety, plant health, and animal health. These include the Destructive Insects and Pests Act, 1914 read with the Plant Quarantine (Regulation of Import into India) Order, 2003, which establishes phytosanitary requirements for agricultural imports and the Livestock Importation Act, 1898, which regulates sanitary conditions for the import of livestock and animal products.

In current times data localizations laws11, which require companies to store and process data within national borders, is a growing category of non-tariff barrier. Proliferation of these policies are often justified on grounds of privacy and national security concerns and they tend to become obstacles for foreign parties seeking to operate in those markets.


11 In India, data localisation and cross-border data flow restrictions are emerging through the Digital Personal Data Protection Act, 2023, which is to be implemented in a phased manner along with its accompanying rules. The framework emphasises lawful processing, consent-based data use, and conditions governing the transfer of personal data outside India, potentially imposing compliance obligations on foreign entities operating in the Indian market. Comparable regimes in other jurisdictions most notably the European Union’s General Data Protection Regulation (GDPR) and the United Kingdom’s data protection framework under the UK GDPR and the Data Protection Act, 2018, have, in practice, operated as regulatory barriers by imposing stringent requirements on cross-border data transfers, particularly under Chapter V of the GDPR (Articles 44–49), which mandate that transfers of personal data to third countries occur only pursuant to adequacy decisions (Article 45), appropriate safeguards such as standard contractual clauses or binding corporate rules (Article 46), or limited derogations in specific situations (Article 49), thereby increasing compliance costs and operational constraints for foreign service providers seeking market access.

PROTECTIONISM IN DISGUISE: IMPACT ON DEVELOPING ECONOMIES

These are just some examples of use of non-tariff barriers to steer trade, at times creating “disguised protectionist” regimes for domestic producers.12 The impact of these measures significantly impede trade and have pronounced effect on developing economies. These measures especially exacerbate global trade inequalities tilting towards advanced economies. The current atmosphere will not be the first or the last instance of countries turning inwards.


12 Kim Moonhwak, Disguised Protectionism And Linkages To The GATT/WTO, World Politics, Vol. 64, No. 3, 2012, pp. 426–75.

Legitimate concerns regarding weaponization of non-tariff barriers aside, it is important to recognize that not all such measures are protectionist. There are many occasions when governments are required to step in on account of genuine policy objectives, such as protecting public health or ensuring product safety etc. The key, however, lies in distinguishing between honest regulations and those designed to restrict trade. It is precisely in this context that the principles of “necessity” and “proportionality” assume significance. Even where a measure pursues a legitimate objective, it may be inconsistent with international norms if it imposes restrictions that exceed what is required to achieve its purpose. The existence of less trade-restrictive alternatives, or a disproportionate burden on foreign producers, may indicate that the measure is, in substance, protectionist.

Lack of transparency and the resultant difficulty in sifting through the maze of regulations to ascertain the genuineness of a measure is the criticism of a non-tariff barrier. While tariffs are clearly defined and the effect thereof, easy to measure, non-tariff barriers are complex and open to interpretation. The diverse and evolving nature of non-tariff measures make it difficult to fathom and regulate. Opacity of reasons, lack of information, unreasoned restrictions are just some of the hallmarks of arbitrary non-tariff barriers that undermine transparency and predictability in international trade.

CONCLUSION

All criticism notwithstanding, non-tariff barriers are here to stay. In times to come, at least in the near future they are likely to play a dominant role in global trade. In modern times, with increased emphasis on industrialization, rapid technological advancement and data boom one might expect the world order to assume a more socialist than capitalist character, however, such a proposition is far removed from reality. Equal opportunity is a fiction espoused by socialist idealists that is routinely sacrificed at the altar of ever intensifying contemporary global market, that routinely favours economically and technologically advanced nations.

Artificial Intelligence (“AI”), the contemporary buzzword, is often heralded by its proponents as a transformative technology that will create the possibility of abundance, which would be a perfect setting for a socialist set up and an egalitarian society. This argument overlooks a fundamental human flaw – “greed”. The core question remains: in an increasingly polarized world economic order will the benefits be evenly distributed or will it aggravate economic inequality if the current institutional set up, ownership and market structures remain unchanged? The answer assumes particular significance in the context of international trade. As we look around, advanced economies are already deploying cutting-edge digital standards, algorithm driven compliance mechanisms, cybersecurity requirements, data-governance framework, AI-related technical frameworks, ostensibly legitimate but far from egalitarian.

Technological evolution by itself has never resulted in a level playing field. If at all, each wave of technological advancement is followed by sophisticated regulations, amplifying underlying regulatory asymmetry. The age of AI will be no different. Advanced economies with new age technological capabilities will use them to preserve competitive advantage, if not worsen it. AI has the potential to become the catalyst for the emergence of a new generation of non-tariff barrier.

Death with Dignity: Directives

Maharashtra has established a legally mandated healthcare governance framework for end-of-life care, turning the Supreme Court’s rulings on passive euthanasia and Advance Directives into practical, working machinery. Following a landmark public interest litigation, the state has appointed district-level custodians to receive, store, and digitise citizens’ Advance Directives. Additionally, a July 2026 Government Resolution requires all government and private hospitals to constitute Primary and Secondary Medical Boards to evaluate treatment withdrawal requests. This two-tier checking system protects patient rights, shields treating doctors from prosecution, and establishes a strict compliance and liability audit trail for institutions.

On 17 July 2026, the Government of Maharashtra issued a Government Resolution (GR) directing every government and private hospital in the State to constitute medical committees for considering requests relating to passive euthanasia and end-of-life decisions. It reads like an administrative order for the medical fraternity. For Chartered Accountants who audit hospitals, advise charitable trusts, or sit on the boards of healthcare companies, it is something more: a new, legally mandated governance structure, with its own documentation trail, empanelment records and liability exposure, that hospitals must now build and their advisors must understand.

A COMMON DILEMMA

An elderly woman with advanced dementia develops pneumonia and is ventilated in the ICU, with doctors certain that recovery is not possible. She had always said she did not want to be kept alive artificially. Her family does not know if they may ask for the ventilator to be withdrawn, and her doctors, fearing prosecution, hesitate to raise it themselves.

WHAT DOES THE SUPREME COURT PERMIT?

The Supreme Court in Gian Kaur v. State of Punjab, the Court had held that the right to life does not include a right to die by suicide, but left open whether a dignified process of dying might stand on different footing. In Aruna Shanbaug case the Apex Court drew the line India still follows: actively causing death, by lethal injection or similar means, remains a criminal act, while withholding or withdrawing treatment that merely prolongs dying, once recovery is medically impossible, does not.

In 2018, a five-judge Bench in Common Cause v. Union of India went further, holding that the right to refuse treatment is part of the right to life under Article 21, and validating Advance Directives, or Living Wills, as a way to record that refusal in advance. But the 2018 procedure was itself heavy: every directive needed a Judicial Magistrate’s countersignature, and withdrawal required Collector-appointed boards, so cumbersome that almost no state ever implemented it. In January 2023, the same Bench simplified its own guidelines: a directive now needs only two witnesses and attestation by a Notary or a Gazetted Officer, and the decision to withdraw treatment rests with two medical boards rather than magistrates.

Even this remained largely theoretical until March 2026, hence the Apex Court reiterated the principles laid down earlier in Harish Rana v. Union of India. The Court permitted withdrawal of feeding tube for a patient who had been in a vegetative state for over a decade, and held that even artificially administered nutrition and hydration count as “treatment” that can lawfully be withdrawn.

WHY ANOTHER PUBLIC INTEREST LITIGATION WAS NECESSARY

Even after 2018, and again after 2023, most states did nothing to build the machinery the Court had ordered. After executing my own living will, I discovered there was no one authorised to receive or preserve it. I filed Public Interest Litigation No. 3 of 2024 before the Bombay High Court, seeking directions to the Government of Maharashtra to actually implement what the Supreme Court had already decided. The Bombay High Court accepted the concern and directed the State to act in a time-bound manner, well before Harish Rana gave the issue fresh urgency.

THE IMPACT OF THE PIL

The litigation has produced three concrete reforms. The Government of Maharashtra has appointed custodians across every district of the State, in Mumbai, the Medical Officer of each municipal ward, to receive and preserve Advance Directives. The State has begun digitising these directives for secure storage and retrieval. And the 17 July 2026 GR now requires every government and private hospital to constitute medical committees to process requests for withdrawing or withholding treatment. Together, these create, for the first time, machinery through which the Supreme Court’s judgment can actually operate.

HOW THE FRAMEWORK OPERATES

An Advance Directive is not a property will; it governs medical treatment, not inheritance. Any adult with decision-making capacity may execute one, specifying the conditions, such as terminal cancer, irreversible coma or end-stage organ failure, in which it takes effect, and the treatments (ventilation, dialysis, CPR) to be refused, while requesting pain relief and palliative care. It need not be on stamp paper or government-registered; a handwritten document is valid if signed before two witnesses and attested by a Notary or Gazetted Officer, with a copy filed with the designated custodian. It can be revoked or modified at any time.

When treatment withdrawal is proposed, whether under a directive or, absent one, on a family’s request, the hospital constitutes a Primary Medical Board of specialists to assess whether continued treatment merely prolongs dying. If it agrees, an independent Secondary Medical Board, including a government nominee, must reach the same conclusion before treatment can be withdrawn. Under the July 2026 GR, the Primary Board is chaired by the hospital’s Medical Director and includes the treating specialist and two subject experts. The secondary board the Secondary Board is also convened at the same hospital but involving different doctors. There will be one doctor who shall represent the civil surgeon of the district. This two-tier check is designed to protect patients from unilateral decisions and to protect treating doctors from unwarranted prosecution, the latter being precisely what has made many hospitals reluctant to act even where the law already permits it.

THE ROAD AHEAD

Legal recognition does not by itself change clinical practice. Hospitals need standard operating procedures and documented board composition; doctors need training and assurance against liability; boards and trustees need to know this is now a compliance obligation, not a discretionary courtesy. Much as with financial wills and insurance, most citizens still postpone this planning because it feels distant rather than urgent.

CONCLUSION

Maharashtra’s custodianship system, digitisation drive and mandatory hospital medical boards mark real progress in turning a constitutional right into working practice. For healthcare institutions and their advisors, this is no longer a matter of medical ethics alone: non-constitution of these boards, or inadequate documentation of their decisions, is fast becoming a governance and compliance failure with its own audit and liability trail. The measure of success will not be the number of GRs issued or boards constituted, but whether patients can, in practice, exercise their right to a dignified end of life. The goal of my judicial activism was to have citizens a right to die with dignity practically available and implementable and not merely on paper. It seems that the state of Maharashtra is taking leadership role amongst all the states in this regard.

Consolidation of Section 8 Company With The Sponsor Company

Editorial Note: While this article concludes that in the given examples consolidation is appropriate, based on alternative views discussed in the article, the issue has not been free from debate, and diversity in practice continues.

Under Ind AS 110, a sponsor company must consolidate a Section 8 CSR entity if it exercises control. Control requires three simultaneous elements: power over the entity’s relevant activities, exposure to variable returns (including non-financial benefits like reputation and compliance), and the ability to use power to affect those returns.

In wholly-owned scenarios, control is clearly established, requiring consolidation. However, in minority or guarantee-based setups, the assessment is highly fact-dependent on governance arrangements.

Upon consolidation, intra-group transactions are eliminated, presenting only actual external spending as CSR expenditure in the consolidated financial statements.

I. INTRODUCTION

Companies in India which are subject to Corporate Social Responsibilities (CSR) provisions as required under Section 135 of the Companies Act, 2013 may discharge their CSR obligations either directly or through an eligible implementing agency. Such implementing agency may include Section 8 company, a charitable trust under the Indian Trusts Act, 1882 or a society under the Societies Registration Act, 1860.

This article examines the circumstances in which a Section 8 company established for undertaking CSR obligations may require consolidation in the financial statements of the Company that sponsor it (“the Sponsor Company”). The analysis considers the relevant requirements of the Companies Act, 2013 (“the Act”) and the applicable accounting standards, particularly the principles of control under Ind AS 110, ‘Consolidated Financial Statements’ to evaluate whether the Sponsor Company exercises control over the Section 8 Company notwithstanding the absence of an ownership interest or profit motive.

The article further discusses the indicators of control in the context of CSR structures, including governance rights, appointment of directors or trustees, decision-making powers, funding dependence, and the ability to direct relevant activities. Through this analysis, the article seeks to provide practical guidance on determining whether a Section 8 company functioning as a CSR implementing agency should be consolidated with the Sponsor Company.

II. ISSUE UNDER CONSIDERATION

In this article, three illustrative scenarios are analysed below to assess whether, and in what circumstances, a Section 8 Company would be required to be consolidated with the Sponsor Company: –

Scenario – 1: The Sponsor Company, in discharge of its obligations under Section 135 of the Act, has incorporated a wholly owned subsidiary in the form of a Section 8 Company for undertaking CSR activities. The Sponsor Company contributes funds to the Section 8 Company for carrying out such CSR activities. The Section 8 Company receives its entire funding/donation solely from the Sponsor Company.

Scenario – 2: The Sponsor Company, in discharge of its obligations under Section 135 of the Act contributes funds to the Section 8 Company for undertaking CSR activities. The Sponsor Company holds 20% equity interest in the Section 8 Company, while the remaining 80% equity interest is held by two individuals who are employees of the Sponsor Company. The Section 8 Company receives its entire funding/donation solely from the Sponsor Company.

Scenario – 3: The Sponsor Company has incorporated a wholly owned subsidiary in the form of a Section 8 Company for undertaking CSR activities. Unlike the preceding scenarios, the Section 8 Company receives funding/donation from multiple companies, which are utilised towards the implementation of CSR activities.

III. TECHNICAL ANALYSIS

The Sponsor Company needs to determine whether it controls the Section 8 Company as per Ind AS 110 and if yes, then the Sponsor Company would be treated as ‘Parent’ and the Section 8 Company would be treated as ‘subsidiary of the parent’.

Under Ind AS-110, consolidation is required only when all three elements of control are present simultaneously:

a) Power over investee;
b) Exposure, or rights, to variable returns from investee; and
c) Ability to use power over investee to affect the investor’s returns.

Accordingly, each of the three scenarios is analysed below against each of the three elements of the control:-.

POWER OVER INVESTEE

The first element for establishing control is whether the Sponsor Company has ‘power’ over the Section 8 Company.

As per paragraph 10 of Ind AS 110, power exists when an investor has existing substantive rights that provide the current ability to direct the relevant activities of the investee. In this context, ‘current ability’ does not necessarily require the rights to be exercisable immediately. Instead, an investor only needs to have the ability to control relevant activities, and it is not relevant whether the investor exercises this ability.

Therefore, when assessing whether an investor has ‘power’, two critical concepts need to be considered:

  • Identification of the relevant activities; and
  • determination of who has the current ability to direct those activities?

Identification of the relevant activities

Relevant activities are defined as “activities of the investee that significantly affect the investee’s returns.”

Considering the nature and objectives of the Section 8 Company, ‘relevant activities’ may include:
  • identification and implementation of CSR projects;
  • deployment and utilisation of funds;
  • approval of operational programmes and budgets;
  • appointment of key managerial personnel;
  • selection and monitoring of beneficiaries/projects; and
  • strategic and operational oversight of social initiatives.

Assessment of Right to Direct Relevant Activities?

Once the relevant activities are identified, the next step is to determine which investor, if any, has the current ability to direct those activities.

Ind AS 110 requires assessment of substantive rights and not merely legal ownership percentages.

The following factors may indicate existence of power:

  • Board representation by personnel associated with the Sponsor Company;
  • practical ability to influence operational and strategic decisions;
  • dependence of the Section 8 Company on funding/support from the Sponsor Company; and
  • any de facto control arising from governance arrangements.

Conversely, the following factors may indicate absence of power:

  • absence of contractual rights granting unilateral decision-making authority;
  • absence of rights to appoint or remove majority directors;
  • substantive voting rights held by other shareholders; and
  • operational independence of the Section 8 Company.

Accordingly, determination of power would depend upon whether the Sponsor Company, in substance, has the present ability to direct the relevant activities of the Section 8 Company.

Scenario 1: As a wholly owned subsidiary, the Sponsor Company holds 100% of the equity and voting rights in the Section 8 Company and would ordinarily control the appointment and removal of its entire board. This gives the Sponsor Company the current ability to direct all relevant activities of the Section 8 Company. Power is present.

Scenario 2: The Sponsor Company holds only 20% of the equity, with the remaining 80% held by two individual employees of the Sponsor Company. While the Sponsor Company does not hold majority voting rights directly, the relevant question is whether it nonetheless has substantive rights to direct the Section 8 Company’s relevant activities. This could arise, for instance, through its ability to influence the two individual shareholders by virtue of their employment relationship, particularly if the shareholders-cum-employees are, in substance, acting on the direction of the Sponsor Company or through board composition, or governance arrangements. Where the facts establish that the Sponsor Company, in substance, directs the relevant activities — whether through its own minority shareholding combined with influence over the other shareholders or otherwise, power would exist notwithstanding the minority equity stake. Where no such substantive rights can be evidenced and the individual shareholders exercise their voting rights independently, power may not be established merely from the 20% holding. The conclusion is fact-dependent and requires further evidence of substantive rights beyond the equity percentage.

Scenario 3: As in Scenario 1, the Sponsor Company holds 100% of the equity in its wholly owned Section 8 Company subsidiary, giving it the current ability to appoint the board and direct relevant activities. The fact that funding is received from multiple companies does not, by itself, affect the Sponsor Company’s power over the Section 8 Company’s relevant activities, since power is assessed by reference to decision-making rights, not the source of funding. Power is present.

EXPOSURE OR RIGHTS TO VARIABLE RETURNS

The second element of the control assessment under Ind AS 110 requires the investor to assess whether the investor has an exposure, or has rights, to variable returns from its involvement with the investee. Returns can be positive, negative or both.

As explained in Ind AS 110, returns are interpret broadly and need not be limited to financial returns. Variable returns includes:

  • exposure to losses;
  • reputational enhancement or reputational risk;
  • operational synergies;
  • achievement of strategic objectives; and
  • compliance-related benefits.

Scenario 1 and Scenario 3:

In both scenarios, the Sponsor Company is exposed to variable returns through its involvement with the Section 8 Company established to undertake CSR activities. The quality and effectiveness of the Section 8 Company’s operations directly influence the Sponsor Company’s ability to fulfil its obligations under Section 135 of the Act. Consequently, the Sponsor Company is exposed to:

  • reputational enhancement arising from successful CSR initiatives, or reputational damage from ineffective implementation;
  • compliance benefits, or the risk of regulatory scrutiny, depending on whether the CSR obligations are effectively discharged;
  • the achievement (or otherwise) of its CSR and sustainability objectives; and
  • funding and liquidity support requirements, where the Sponsor Company is expected to finance the activities of the Section 8 Company.

In view of above, the Sponsor Company is exposed to variable returns arising from its involvement with the Section 8 Company.

Scenario 2:

Although the Sponsor Company holds only a minority equity interest, its exposure to variable returns remains substantially the same because such returns arise primarily from its role as the Company responsible for discharging its CSR obligations, rather than from its shareholding alone. The Sponsor Company continues to be exposed to variations in reputational outcomes, compliance benefits, achievement of CSR objectives and the effectiveness of CSR implementation. Accordingly, the criterion of exposure to variable returns is also satisfied in this scenario.

ALTERNATIVE VIEW: SECTION 8 COMPANY DOES NOT SATISFY THE “VARIABLE RETURNS” CRITERION

An alternative view is that the Section 8 Company established solely for undertaking CSR activities may not satisfy the “variable returns” criterion under Ind AS 110. The view is based on the fact that:

  • a Section 8 company is prohibited from distributing profits to its members,
  • a Section 8 company cannot distribute its assets to the Sponsor Company upon winding up, and
  • the directors of Section 8 Company are required to discharge independent fiduciary duties in the interests of the Section 8 company.

Consequently, unlike a conventional commercial subsidiary, the Sponsor Company does not possess a residual economic interest in the Section 8 Company. On this basis, some companies have taken the position that a CSR implementing entity of this nature ought not to be consolidated, notwithstanding the Sponsor Company’s involvement in its governance.

As discussed above, Ind AS 110 defines ‘returns’ broadly and does not confine the concept to financial or distributable returns or to a residual economic interest on winding up. Returns include non-financial benefits such as reputational outcomes, achievement of strategic and compliance objectives and operational synergies.

In view of the above, the prohibition on distribution of profits, the absence of a residual economic interest on winding up, and the independent fiduciary duties owed by directors, may not by themselves be conclusive of the absence of variable returns, provided the Sponsor Company continues to derive the non-financial benefits described above from its involvement with the Section 8 Company.

Thus, the alternative view cannot be dismissed outright and the assessment would ultimately depend on the specific facts and governance arrangements in each case.

RELEVANCE OF PROVISION FOR DIMINUTION IN VALUE OF INVESTMENT

It is also relevant to consider whether the accounting treatment adopted by several Sponsor Companies, of fully providing for diminution in the value of their investment in the shares of the Section 8 Company at inception, has any bearing on the assessment of ‘returns’ under Ind AS 110.

Sponsor Companies often recognize a full impairment or diminution in the carrying value of their investment in the equity shares of the Section 8 Company shortly after incorporation on the basis that such investment has little or no real economic value.

The write-down of the investment in the Sponsor Company’s standalone financial statements reflects an assessment of the recoverability of the equity investment carried in its books. The accounting treatment adopted by the Sponsor Company for such investment does not influence the control assessment under Ind AS 110. The existence of control depends upon substantive rights, exposure to variable returns and the ability to use power to affect those returns rather than by the carrying amount assigned to the investment. Accordingly, a full impairment or diminution in the value of the investment neither establishes nor negates control.

ABILITY TO USE POWER TO AFFECT RETURNS

The third element of the control under Ind AS 110 requires the investor to have the ability to use its power over the investee to affect the investor’s variable returns. This element links the first two components of the control model and requires that the investor’s decision-making rights are capable of influencing the returns to which it is exposed. Merely possessing power, or merely being exposed to variable returns, is insufficient in isolation; there must be a demonstrable connection between the two.

Accordingly, this assessment requires establishing linkage between:

  • the investor’s substantive decision-making rights over the relevant activities; and
  • the investor’s exposure, or rights to variable returns arising from its involvement with the investee.

Scenario 1: The Sponsor Company has the current ability to direct all relevant activities of the wholly owned Section 8 Company through its substantive voting and governance rights. The exercise of those rights directly influences the effectiveness of the CSR activities undertaken by the Section 8 company, which in turn has a direct bearing on the Sponsor Company’s CSR objectives, reputational outcomes and compliance position, the linkage criterion is clearly satisfied.

Scenario 2: The linkage would be established only if the Sponsor Company possesses substantive rights that enable it to direct the relevant activities of the Section 8 Company. Where such right exists, the Sponsor Company can influence the outcomes of the CSR programme which has a bearing on its compliance and reputational position. However, if the Sponsor Company merely provides funding and does not have substantive rights, the linkage criterion would not be met.

Scenario 3: As in Scenario 1, the Sponsor Company retains the ability to direct the relevant activities of the wholly-owned Section 8 Company through its substantive voting and governance rights. The participation of other funders towards CSR activities does not dilute this linkage, since these contributors do not acquire decision-making rights over the relevant activities of the Section 8 company. Consequently, the Sponsor Company’s ability to direct the relevant activities continues to influence its own CSR, reputational, and compliance-related returns. Accordingly, the linkage criterion is satisfied.

Conversely, where the Sponsor Company merely provides funding support without possessing substantive decision-making authority, the linkage criterion may not be met.

IV. APPLICABILITY TO SECTION 8 COMPANIES LIMITED BY GUARANTEE

The preceding analysis has been carried out in the context of a Section 8 Company having share capital, where the Sponsor Company holds shares (whether wholly or in part) in the Section 8 Company. In practice, however, a number of Section 8 Companies are incorporated as companies limited by guarantee, without share capital, so that the Sponsor Company holds no shareholding or investment interest in the Section 8 Company. It is, therefore, relevant to consider whether the conclusions reached above would differ in such cases.

The absence of share capital does not, by itself, alter the control assessment under Ind AS 110. Power may exist through contractual or other arrangements, and the standard specifically contemplates that control can arise even where the investor holds less than a majority of the voting rights of the investee, or none at all. Accordingly, in the case of a Section 8 Company limited by guarantee, the ‘power’ element would need to be assessed with reference to substantive rights available to the Sponsor Company through governance arrangements, appointment or removal its members/directors, rights to approve its budgets, projects or key operational decisions, and the extent of the Sponsor Company’s funding of, and consequent influence over, its activities. Where the Sponsor Company holds such substantive rights, power may be established notwithstanding the absence of a shareholding or guarantee-based interest.

The ‘returns’ element would similarly need to be assessed on the same basis as discussed above, namely, whether the Sponsor Company is exposed to non-financial returns such as reputational outcomes, compliance benefits and achievement of its CSR objectives; the absence of a financial or equity interest does not, of itself, preclude the existence of variable returns, since Ind AS 110 does not require returns to arise from an ownership interest.

Consequently, a Section 8 Company limited by guarantee can also meet the definition of a subsidiary of the Sponsor Company under Ind AS 110, provided the power and returns criteria discussed above are otherwise satisfied on the facts, notwithstanding the absence of any shareholding or investment interest. The principles discussed in the preceding scenarios would apply with appropriate modification, having regard to the manner in which power is established in the absence of share capital.

V. PRESENTATION OF CSR EXPENDITURE ON CONSOLIDATION IN CONSOLIDATED FINANCIAL STATEMENTS

The treatment of CSR expenditure under the Companies Act, 2013, can sometimes diverge from the accounting outcomes as required by Ind AS 110, particularly when a “Sponsor Company” utilizes controlled Section 8 Company as its implementation agency.

1. RECOGNITION IN STANDALONE FINANCIAL STATEMENTS

Under Section 135 of the Companies Act, 2013 and the CSR Rules, a Sponsor Company normally recognises its contribution to a Section 8 Company as CSR expenditure in its standalone financial statements at the time the contribution is made, provided all the legal requirements for the discharge of the obligation are satisfied.

2. IMPACT OF CONSOLIDATION ON CSR EXPENDITURE PRESENTATION

In case the Section 8 Company fulfills the above criteria and is consolidated under Ind AS 110, the group is presented as a single economic entity. In the consolidated financial statements (CFS): –

  • the CSR contribution represents an intra-group transaction and is eliminated on consolidation;
  • the amount spent by the Section 8 Company during the reporting period on CSR activities is reflected as CSR expenditure;
  • any unspent amount by the Section 8 Company of the CSR contribution received from the Sponsor Company, remains reflected as asset within the CFS. Consequently, the CFS reflects only CSR expenditure to the extent that the Section 8 Company has utilized the funds for activities with external third parties.

For example, the Sponsor Company contributes 100% of its CSR obligation to the Section 8 Company but only 20% of such contribution is utilized by the Section 8 Company during the year, with the balance remaining unspent. In the standalone financial statements, the entire contribution is reflected as CSR expenditure. In the CFS, only 20% of the contribution is reflected as CSR expenditure while the remaining 80% unspent balance forms part of the group’s net assets (e.g. cash or bank balances).

This presentation difference arises since the parent and subsidiary together represent a single economic entity carrying on a common business. While the Sponsor Company may have discharged its statutory obligation under Section 135 of the Act, whereas, the group as a whole, has not yet consumed the economic resource until it is spent externally.

This presentation anomaly is one of the reasons cited in support of the view that consolidation of a Section 8 Company with the Sponsor Company may not, in every case, result in the most appropriate accounting outcome, and reinforces the need for a careful, facts-based assessment of control under Ind AS 110, rather than a presumption of consolidation (or non-consolidation) based on the legal form of the Section 8 Company.

VI. CONCLUSION

The assessment of control under Ind AS 110 is fundamentally based on substance rather than legal form and requires consideration of all relevant facts and circumstances. Although a Section 8 Company is established for charitable purposes and operates under statutory restrictions that differ significantly from those applicable to commercial entities, those characteristics do not automatically preclude consolidation. Equally, neither the existence of shareholding nor the provision of funding, by itself, establishes control. Each of the three elements of the control model—power, exposure to variable returns and the ability to use power to affect those returns—must be evaluated collectively.

Applying the three-part control test under Ind AS 110 to each scenario yields the following conclusions.

Scenario 1: Where the Section 8 Company is wholly owned by the Sponsor Company and the Sponsor Company possesses substantive voting and governance rights enabling it to direct the relevant activities, all three elements of control are satisfied. The Sponsor Company has power over the investee, is exposed to variable returns from its CSR involvement and can use its power to affect those returns. Accordingly, the Section 8 Company is required to be consolidated in accordance with Ind AS 110.

Scenario 2: Where the Sponsor Company holds only a 20% minority equity interest and the balance is held by individual employee-shareholders, the control conclusion is not automatic and depends on facts beyond the shareholding percentage. The assessment requires a comprehensive evaluation of all relevant facts and circumstances, including the Sponsor Company’s substantive rights, board appointment and removal rights, shareholder arrangements, voting patterns, and whether the remaining shareholders are, in substance, able and willing to exercise their rights independently. If the Sponsor Company is able, in substance, to direct the relevant activities, consolidation would be required notwithstanding its minority shareholding. Conversely, if substantive decision-making rights rest with the other shareholders and the individual shareholders are found to exercise independent decision-making authority. Further, the Sponsor Company cannot direct the relevant activities, control would not exist and consolidation would not be required.

Scenario 3: Where the Section 8 Company continues to be wholly owned by the Sponsor Company notwithstanding that it receives CSR funding from multiple corporate contributors, the source of funding does not affect control assessment. Provided that the Sponsor Company retains the substantive rights to direct the relevant activities of the Section 8 company, it continues to satisfy all three elements of the control model under Ind AS 110. The other contributors merely provide financial support and do not acquire decision-making rights over the relevant activities. Accordingly, the Section 8 company remains a subsidiary of the Sponsor Company and is required to be consolidated.

Reference :

  1. Ind AS 110, ‘Consolidated Financial Statements
  2. Companies Act, 2013
  3. EAC Opinion on Consolidation of the financial statements of a Section 8 Company with the Sponsor Company.

Materiality: A Sustainability Perspective

Materiality refers to the identification and prioritisation of matters that are significant enough to demand attention and action. The concept of materiality is interpreted differently across domains depending on the context in which it is applied. The idea of materiality has evolved in tandem with the transformation in the business environment. From a sustainability perspective, materiality serves as the guiding framework in an organisation for sustainability performance and sustainability reporting. The determination of materiality in sustainability frameworks is anchored in the structured due diligence process which aids organisations in identifying, assessing, prioritising and addressing their impacts on the environment, people and economy. A double materiality assessment builds upon the due diligence process to include aspects of financial risks and opportunities arising from sustainability matters in the analysis. The materiality assessment process is an important step toward an organisation’s ultimate goal of becoming a sustainable business enterprise.

INTRODUCTION TO MATERIALITY

The term materiality is familiar to every Chartered Accountant. The concept is introduced early in our accounting education as a fundamental principle that governs the recognition, presentation, and disclosure of financial information in the financial statements. The principle of materiality implies that information which is sufficiently significant to influence the decisions of users of financial statements warrants separate presentation or disclosure.

While materiality is formally defined and applied mostly in the context of financial reporting, the principle is universal across domains such as risk management, regulatory disclosures, and in sustainability frameworks. Materiality has a common theme in all —the identification and prioritisation of matters that are significant enough to demand attention and action.

DEFINITIONS OF MATERIALITY FROM DIFFERENT PERSPECTIVES

The concept of materiality, though consistent in its theme, is interpreted differently across domains depending on the context and objectives in which it is applied. A few perspectives are outlined below:

  • Materiality under Accounting Standards

As per Ind AS 1, information is considered material if omitting, misstating or obscuring it could reasonably be expected to influence the decisions of the primary users of financial statements1. This reflects a reporting-driven perspective, focused on decision usefulness in financial reporting.

  • Materiality under SEBI LODR Regulations

Under SEBI LODR Regulations, materiality is assessed based on whether the omission of disclosing an event or information is likely to result in discontinuity or alteration of publicly available information and could lead to a significant market reaction if it comes to light later2. This represents a market-driven perspective, centred on investor protection and market sensitivity.

  • Materiality in Risk Management Frameworks

In risk management frameworks, materiality is gauged through the identification of major risks that meet the established criteria for being significant enough to impact the achievement of an organisation’s strategy and business objectives.3 This shows an uncertainty-driven perspective, focusing on potential deviations from expected performance or results.

  • Materiality in Sustainability standards

Under sustainability standards, materiality is viewed from different perspectives depending on the objective of the standard. An Impact materiality perspective emphasises the organisation’s effects on the outside world. Financial materiality perspective focuses on how sustainability-related matters influence the organisation’s long-term value and performance.


1 Ind AS 1
2 SEBI Listing Obligations and Disclosure Requirement Regulations, 2015 (as amended)
3 Risk Significance and Criteria: ISO 310001:2018

EVOLUTION OF MATERIALITY: FROM FINANCIAL TO SUSTAINABILITY PERSPECTIVE

Over time, the focus of investors and other stakeholders has progressively expanded—from evaluating current financial performance to assessing future risks and, more recently, to understanding sustainability-related impacts. This shift in perspective has been accompanied by a corresponding evolution in the concept of materiality also.

Traditionally, materiality was applied in the context of financial reporting, primarily to determine the recognition, classification, and presentation of financial information. As businesses and markets became more complex, it extended into risk management, where materiality began to include risks that could affect the achievement of strategic and operational outcomes. In the current landscape, the concept has further evolved to include sustainability considerations. Materiality now encompasses identifying and prioritising environmental, social, and governance (ESG) topics that are critical to the long-term viability of the organisation.

The evolution of materiality reflects a broader transformation in the entire business environment. Organisations today operate under increased regulatory pressures, heightened investor expectations, and growing exposure to new and unique challenges such as climate change and geopolitical uncertainties. Therefore, materiality is no longer limited to financial significance alone; it now serves as a strategic tool to identify what is truly necessary for building a resilient and sustainable business enterprise.

SIGNIFICANCE OF MATERIALITY IN SUSTAINABILITY FRAMEWORKS

It is prudent to understand the significance of materiality from a sustainability perspective before delving into how materiality is determined in sustainability frameworks. Organisations can prioritise and manage sustainability matters in a structured manner using materiality as a tool. The importance of materiality can be understood through the following dimensions:

a. Channelising organisational focus and resources

Investors and other stakeholders are increasingly showing interest in how the organisations are mitigating the harmful impacts of their operations on the environment, people and economy. Under these circumstances, materiality helps organisations in determining the most significant of such impacts, thereby guiding the organisation where it needs to direct its efforts and resources effectively. For instance, an increase in the frequency of safety-related incidents may make the issue more pressing, necessitating a greater emphasis on external safety audits and certifications.

b. Enabling strategy formulation and implementation

Sustainability has evolved from being an “also have component” earlier to an “integral component of business strategy”. Materiality in sustainability frameworks acts as a guiding framework for formalising strategic priorities and converting them into actionable items such as capital expenditure planning, research and development initiatives, and new projects selection. For example, rising energy costs identified as a material issue can drive investments in energy efficiency projects or R&D efforts in the use of alternative fuels.

c. Strengthening sustainability disclosures in annual reports

Sustainability disclosures form a critical component of the organisation’s annual report. Materiality helps determine the topics which require detailed reporting like setting of time-bound targets, defining key performance indicators (KPIs), and presenting multi-year performance trends. This makes the disclosures more focused and relevant for the users. For instance, if climate change is identified as a material topic, organisations may take net-zero targets and disclose emissions reduction metrics as the performance indicators.

d. Enhancing stakeholder engagement

Materiality also determines the stakeholders which the organisation needs to target for engagement and the manner of such engagement. Organisations can engage with their stakeholders meaningfully if they link the material impacts to the relevant stakeholders. For example, if the transportation of hazardous goods is identified as material issue, the organisation needs to specifically focus on the logistics partners. Engagement would include communication of safety protocols, conducting training programmes, and real-time communication systems.

DRIVERS OF MATERIALITY IN SUSTAINABILITY FRAMEWORKS

As discussed earlier, materiality in sustainability frameworks is defined in terms of an organisation’s most significant impacts on the stakeholders. This definition highlights three key drivers of materiality—impacts, stakeholders, and significance—each of which plays a distinct role in shaping what is ultimately considered material.

IMPACT

Impact is defined as the effect that an organisation’s business operations have or may have on the environment, people, and economy4. These effects could be actual or potential, short-term or long-term, reversible or irreversible, intended or unintended, and negative or positive. The organisation may directly cause the impact, contribute to it, or have a direct connection to it. How the organisation handles the impact depends on how it is involved in it. It might attempt to mitigate the effects that it causes or contributes to. It may play a role in the mitigation of the effects that it is directly associated with.


4 GRI 1- Foundation 2021

The nature of the organisation’s relationship with an impact determines the extent of its responsibility and the appropriate course of action, as illustrated below:

Impact Nature of impact Source of impact Relationship with the impact Action required
Air Pollution Negative Own Operations Caused by Mitigate air pollution
Supplier Non-compliance with Labour Standards Negative Upstream Value Chain Contributed to Influence the vendor for compliance
Data breach in supplier’s organisation Negative Upstream Value Chain Directly linked to Help in remediation to the extent possible

Table 1: Illustrative Classification of Impacts Based on Source, Relationship and Response

STAKEHOLDERS

Stakeholders are individuals or groups who are directly or indirectly affected by the organisation’s operations (physically, financially, in terms of human rights, or otherwise). The organisation’s operations may have an impact on the interests of stakeholders, either positively or negatively. For example, sponsoring the digitalisation of schools in the district benefits the organisation’s local community has a positive impact. Stakeholders could be directly affected or potentially affected. For example. In the case of bribery (cash for the release of vendor payment), the specific vendor is directly affected, while the remaining vendors are potentially affected. This distinction is critical in determining the appropriate future course of action in terms of impact.

Stakeholder perspectives provide valuable information about how impacts become apparent in the real world. Engaging with stakeholders through dialogues, grievance redressal mechanisms, focused group discussions, or other structured communication methods can help organisations better understand the effects.

Different stakeholders have various interests that are impacted. All interests are not material, and they do not need to be treated equally. Identifying stakeholder interests that are negatively impacted by the organisation’s operations should take precedence over other interests. For example, employees’ physical safety at workplace is inherently more critical than sponsoring the education of the employees’ children. All of the aforementioned factors are important in determining materiality for the organisation.

DUE DILIGENCE

As previously discussed, materiality requires organisations to prioritise their most significant impacts. Since organisations cannot address every impact simultaneously, a structured decision-making process is required to identify which impacts demand the highest priority. This determination of materiality is based on the due diligence process5. It is the process by which organisations identify, assess, prioritise, and address their actual and potential impacts on the economy, the environment, and people. It provides a systematic and evidence-based approach to determining materiality, ensuring that material topics are identified through a structured evaluation rather than on an ad hoc basis.


5 OECD Guidelines for Multinational Enterprises on Responsible Business Conduct

The following steps are involved in due diligence process:

Step 1: Defining the Scope

The scope of the due diligence process must be defined i.e. establishing clear boundaries for identifying impacts. It includes the impacts of the organisation’s own operations as well as the relevant upstream and downstream value chains (suppliers, dealers, customers, and consumers). For example, an FMCG company’s scope may extend to include the environmental impact of how consumers use their products and dispose the empty packing material after use.

Step 2: Identifying the Impacts

The impacts on the environment and people must be identified based on a comprehensive assessment of historical data, available evidence, and information about upstream and downstream value chain partners. For example, community complaints, regulatory observations may provide evidence of identifying pollution as an impact.

At this point, the organisation should consult relevant subject matter experts. They also should refer to relevant sector-specific impacts indicated in various sustainability standards (GRI, SASB, and ESRS6).


6 GRI – Global Reporting Initiative, SASB – Sustainability Accounting Standards Board, ESRS- European Sustainability Reporting Standards.

Organisations may consider asking questions during this process, such as:

  • Does this impact relate to a key area of our operations, products, services or value chain?
  • Has this impact led to any actual harm or benefit to communities, workers, environment, or consumers?
  • Could this impact have potential significant affects (positive or negative) in the near or long term?
  • Have we consulted with affected stakeholders (e.g., workers, communities, NGOs) on this topic?

Step 3: Classifying the Impacts

The identified impacts must be divided into two categories: actual impacts (those that have already occurred or are currently occurring) and potential impacts (those that may occur in the future). For example, air pollution is classified as having an actual negative impact, whereas possibility of an industrial accident is a potential negative impact.

Step 4: Assessing the significance of the Impacts

The impacts are assessed based on their severity factor and the likelihood factor.

Severity factor is a reflection of the scale (the amount of harm it can cause), scope (how widespread the harm is) and Irremediability(how difficult to reverse its consequences) of the impact . For example, Climate change is extremely serious because it is an existential threat for all creatures (scale), it affects everyone on the planet(scope), and it will require enormous and co-ordinated efforts from all countries to mitigate the effects (degree of irremediability).

Likelihood factor is only used to assess potential impacts. It represents the probability that the organisation’s operations will have an impact. For example, likelihood shall be used to assess the impact of an industrial accident in a factory dealing with hazardous chemicals. The likelihood of the impact will less if it currently follows all necessary saftey protoccols.

Step 5: Prioritising the impacts

The significance of an impact is assessed based on its severity and, in the case of potential impacts, its likelihood.7 For potential negative human rights impacts, however, severity takes precedence over likelihood.


7 The actual process of scoring of topics based on severity and likelihood is beyond the scope of this article

The most significant impacts identified through this process constitute the organisation’s material topics. This step also involves identifying the stakeholders affected by each material topic and understanding the nature and extent of the impacts on them.

Step 6: Action, Monitoring and Disclosure

As next steps, the organisation has to address these material topics. It has to take actions to prevent, mitigate, or remediate identified significant impacts and periodically monitor the effectiveness of actions taken. It has to disclose the entire process of how material topics are identified, prioritised, and addressed in its sustainability report.

MATERIALITY PERSPECTIVES IN SUSTAINABILITY REPORTING FRAMEWORKS

With the rapid evolution of sustainability reporting, global reporting frameworks have adopted different perspectives on materiality namely impact materiality perspective, financial materiality perspective and double materiality perspective.

Impact materiality, as adopted by GRI, focuses on the actual and potential impacts that an organisation has on the economy, the environment and people. These impacts are assessed based on their severity and, where relevant, their likelihood, irrespective of whether they result in immediate financial consequences for the organisation. For instance, non-compliance with air pollution norms may adversely affect the health of surrounding communities. Even in the absence of immediate financial implications, such impacts are considered material because of their severity and societal relevance.

Financial materiality, as adopted by IFRS S1, focuses on sustainability-related risks and opportunities that could reasonably be expected to affect an organisation’s enterprise value, including its financial position, financial performance, cash flows, access to finance or cost of capital. Continuing the same example, repeated non-compliance with air pollution norms may result in regulatory penalties, operational disruptions or increased compliance costs, thereby affecting the organisation’s financial performance.

Double materiality, as adopted by ESRS, combines these two perspectives. It recognises that organisations should evaluate sustainability matters not only from the perspective of the impacts they have on the environment and people, but also from the perspective of how those sustainability matters may create financial risks and opportunities for the business. (refer Figure 2). Continuing the same example, air pollution may be material from both an impact and a financial perspective if the organisation has a history of regulatory penalties and recurring complaints from local communities, resulting in financial and reputational consequences.

Materiality in BRSR

The SEBI Business Responsibility and Sustainability Report (BRSR) framework is based on the nine National Guidelines on Responsible Business Conduct (NGRBC) principles, which prescribe disclosures on a broad range of environmental, social and governance matters. Unlike GRI, BRSR does not require companies to undertake a formal materiality assessment. However, Question 26 of Section A – General Disclosures requires companies to disclose the material sustainability issues pertaining to environmental and social matters that present a risk or an opportunity to the business. Although not mandatory, Indian companies reporting under BRSR may choose to undertake a formal materiality assessment using internationally recognised frameworks such as GRI or ESRS to strengthen governance, strategy formulation and stakeholder engagement.

DOUBLE MATERIALITY ASSESSMENT

A double materiality assessment builds upon the due diligence process discussed earlier, while incorporating an additional analytical layer—namely, the evaluation of financial risks and opportunities arising from sustainability matters. In essence, while the process of identifying and assessing impacts remains unchanged, organisations are required to simultaneously examine how these impacts translate into financial consequences over different time horizons.

FINANCIAL RISKS

Identification of financial risks is an integral component of double materiality assessment. Dependencies on environmental and social resources—may expose the organisation to financial risks due to its own operations, value chain relationships, geographic exposure, or regulatory environment. For example, a cyberattack in an airline company can disrupt its operations entirely, resulting in loss of revenue, regulatory penalties, and reputational damage. Such an event clearly poses a financial risk to the airline company.

FINANCIAL OPPORTUNITIES

Organisations may also consider financial opportunities arising from sustainability-related matters. These opportunities increase the organisation’s ability to sustain operations, improve efficiency, or access new markets. For example, a power generation company increasing the share of renewable energy in its generation capacity is not only reducing its environmental impact but also catering to a new market in a regulatory environment that encourages low-carbon operations. Such strategies create long-term economic value and resilience.

To support this evaluation, organisations may consider questions such as

  • Is this topic currently causing any financial impact on revenues, costs, access to capital, or license to operate?
  • Could this topic affect our future business i.e. revenues, costs, access to capital, or license to operate?
  • Do investors or regulators consider this topic financially material?
  • Does it create opportunities for innovation, efficiency, or market access?

TIME HORIZON

Another new component of double materiality is the consideration of time horizon. Organisations are expected to categorise financial risks and opportunities across short, medium, and long-term periods. Short term means the impacts start appearing within the reporting period, in medium term impacts may materialize in next five years, in the long term, impacts are expected to occur beyond five years8. For example, impacts of rising fuel prices will impact in the same financial year. However, physical risks associated with climate change will start impacting in the medium or long term. Similarly, sustainability related initiatives may also yield financial implications over different timeframes. For example, energy efficiency measures such as LED retrofits may result in immediate cost savings. Investments in renewable energy or R&D efforts in using alternative fuels may generate benefits over a longer time horizon.


8 Organisation may opt for a different time-horizon depending upon its business cycle.

Similar to impact materiality, the assessment of financial materiality is a function of both the magnitude of financial effects and the likelihood of occurrence. The outcome of the double materiality assessment is a consolidated list of topics that are a) material from an impact perspective, b) material from a financial perspective (risks or opportunities), or c) material from both perspectives.

Organisations may then apply appropriate thresholds to prioritise these topics for management action and disclosure9. This integrated approach ensures that both outward impacts and inward financial implications are systematically captured, enabling more informed decision-making and comprehensive sustainability reporting.


9 The actual process of application of thresholds is beyond the scope of this article

Double materiality effectively bridges the gap between sustainability and enterprise risk management by integrating impact-based assessment with forward-looking financial analysis.

An illustrative mapping of topics across impact and financial materiality dimensions is presented below:

Topic Materiality Perspective Time-horizon Risk / Opportunity Stakeholders affected
Environmental management and compliance Financial + Impact materiality Short–medium term Risk • Local communities

• NGOs

• Investor

• Regulator

Occupational health, safety and employee well-being Financial + Impact materiality Short–medium term Risk and opportunity • Employees

• labour unions

• Regulator

Ethical business conduct and anti-corruption Financial materiality Medium–long term Risk and opportunity • Customers

• Investors

• Business partners

• Regulator

Table 2: Illustrative Mapping of Topics Across Materiality Perspectives, Time Horizon and Stakeholders

PITFALLS IN DETERMINING MATERIALITY IN SUSTAINABILITY FRAMEWORKS

The due diligence process and double materiality assessment inherently involve judgement at multiple stages. This judgement can be influenced by subjectivity of the matter, personal bias of the participants, and limited perspectives. While the objective of the process is to identify the most significant impacts and risks, organisations may not arrive at optimal conclusions due to gaps in approach or execution. Some common pitfalls are discussed below.

A key shortcoming observed in practice is the failure to consider sector-specific topics recommended by established sustainability standards. Frameworks such as GRI and (Sustainability Accounting Standards Board) SASB identify issues that are generally considered material for specific industries. Ignoring these reference points can result in an incomplete or non-defensible materiality assessment. For instance, the preparedness for an emergency event is a recognised material topic by SASB for companies in the chemicals sector and should be evaluated irrespective of the organisation’s internal perception.

Another pitfall is the insufficient consideration of stakeholder perspectives. As discussed earlier, materiality is closely linked to interest of the stakeholders. A materiality assessment would be incomplete if stakeholder input was excluded. In order to validate the identified material topics and capture their varied perspectives, organisations should engage with both internal and external stakeholders. For example, an organisation may consider air pollution not material since it is within regulatory limits. However, local communities may still perceive air pollution as a significant concern in the area.

Organisations also often exhibit a weak linkage between materiality and strategy or risk management. Identifying material topics is only the starting point. The real value lies in integrating these topics into strategic planning and enterprise risk management processes. Unless material impacts and financial risks are embedded within governance frameworks and receive Board-level attention, the exercise becomes a compliance formality rather than a strategic tool.

The quality of a materiality assessment depends less on the scoring methodology and more on the quality of governance, stakeholder engagement and professional judgement supporting it.

A further limitation is failure to update the materiality assessment on a regular basis. Materiality is not a static concept. It evolves. Its evolution is triggered by the changes in the business environment, regulatory landscape, and technological developments. Organisations run the risk of missing new emerging impacts if they don’t regularly review their materiality assessments. For example, Artificial Intelligence was relatively insignificant just a few years ago for IT services companies. However, recent advancements in artificial intelligence have made it the most material topic for such companies today.

CONCLUSION

At its core, the concept of materiality retains a consistent essence across domains— significance of a matter in influencing decisions and outcomes. Materiality has a more prominent role in the context of sustainability. It serves as guiding framework for organisations in identifying their most significant impacts, risks, and opportunities. Therefore, materiality is actually a strategic tool—one that directs organisational energies, helps in informed decision-making, and enhances the organisation’s resilience in an increasingly complex business environment. Organisations must actively perform materiality assessment to build a more informed, responsive, and sustainable business enterprise.

References

1. Global Reporting Initiative Standards (GRI)
2. European Sustainability Reporting Standards (ESRS)
3. Business Responsibility and Sustainability Report (BRSR)
4. OECD Guidelines for Multinational Enterprises on Responsible Business Conduct
5. ISO 31000:2018
6. Indian Accounting Standards

Five Years of AIS TIS: From Nudge to Notice!

The Annual Information Statement (AIS), launched in 2021 to ease compliance, has transitioned from a supportive “nudge” into a harsh enforcement trigger for tax reassessments. Assessing Officers increasingly issue notices based solely on unverified data mismatches, bypassing mandatory statutory inquiry safeguards. This shift is compounded by unreliable third-party reporting, joint-holder mis-attributions, and a confusing maze of internal machine codes. To restore fairness, the author advocates for mandatory officer verification before issuing notices, simplified plain-English explanations, and merging overlapping tax documents into a single self-correction portal.

BACKGROUND

Section 285BB of the Income-tax Act, 1961, read with Rule 114-I of the Income-tax Rules, 1962, mandates the tax department to make available to every assessee an Annual Information Statement (AIS) — a consolidated record of TDS/TCS, Specified Financial Transactions (SFT), tax payments, demand/refund, GST returns, foreign remittances, dividend and mutual fund data reported by third parties (banks, RTAs, depositories, GST Network, and others).1 Alongside AIS sits the Taxpayer Information Summary (TIS), a category-wise aggregated and “processed” version of the same data, and Form 26AS, now restricted to TDS/TCS/Tax Payment/Refunds credits.2 The department’s own FAQ states the object of AIS is to display “complete information’ to the taxpayer before filing, “promote voluntary compliance,” enable pre-filling, and “deter non-compliance.”3


1. Section 285BB, Income-tax Act, 1961, read with Rule 114-I, Income-tax Rules, 1962; incometaxindia.gov.in/annual-information-statement
2. Income Tax Department, “Annual Information Statement (AIS)”, https://www.incometax.gov.in/iec/foportal/ais-faq (Q6, distinction between AIS and Form 26AS effective AY 2023-24)
3. Income Tax Department, “FAQs on AIS”, incometax.gov.in/iec/foportal/ais-faq, Q1

When AIS was formally rolled out on the Compliance Portal on 1st November 2021, the Ministry of Finance described it, through a Press Information Bureau release, purely as a taxpayer facility — “a comprehensive view of information to a taxpayer with a facility to capture online feedback.”4 Significantly, that very release told taxpayers that in case of variation between AIS and the TDS/TCS data on the TRACES portal (Form 26AS), the taxpayer “may rely on the information displayed on TRACES portal” for filing and compliance purposes — an official acknowledgment, at the point of launch itself, that AIS data could be unreliable and was not to be treated as final.5 The 2021 Budget speech situated AIS-linked information squarely in the pre-filling and ease-of-compliance space, speaking only of salary, TDS, capital gains, dividend and interest data being pre-filled to reduce the taxpayer’s burden — not of AIS being used as evidentiary ammunition for reopening assessments.6 The information provided by both these forms are helpful to taxpayers especially those they are missing out to remain compliant.


4. Press Information Bureau, “Roll out of new Annual Information Statement (AIS)”, Ministry of Finance, 1 November 2021, PIB Delhi, Release ID 1768560. pib.gov.in/PressReleasePage.aspx?PRID=1768560
5. https://www.pib.gov.in/PressReleasePage.aspx?PRID=1768560&reg=48&lang=2
6. Budget 2021-2022, Speech of Nirmala Sitharaman, Minister of Finance, 1 February 2021, para 169 (pre-filling of salary, TDS, capital gains, dividend and interest data). indiabudget.gov.in

THE PROBLEM

Nearly five years on, AIS has quietly migrated from an information-sharing facility into the principal trigger for CPC action, assessment, and even reassessment. Practitioners now report that Section 148A show-cause notices — and consequent Section 148 reassessment notices — are increasingly issued on the sole strength of an AIS/TIS figure not matching the return, without any independent enquiry by the Assessing Officer.7 The pattern is now common enough to be documented: notices citing “AIS mismatch,” “high-value transaction reported in SFT,” or “TIS figure exceeds returned income” as the entire basis for reopening a case that may be four, five, or even ten years old.8


7. TaxGuru, “Validity of Reassessment Under Section 148 Based on AIS Mismatch” (June 2025); taxguru.in
8. TaxBuddy, “Section 148A Notice: Reassessment and Response Explained”; taxbuddy.com
The department describes this as data-driven, non-intrusive administration. CBDT’s own 2026 framework for this is candidly named NUDGE — Non-intrusive Usage of Data to Guide and Enable — intended to strengthen “behavioural” tax administration and encourage voluntary correction through better use of data.9 The irony bears stating plainly: an instrument conceived and administratively branded as non-intrusive has, in practice, become the trigger for the most intrusive proceeding in the statute — reopening a completed assessment.

9. SAG Infotech, “CBDT Mandates IT Department Readiness for Upcoming Direct Tax Law Overhaul”, January 2026 — CBDT Chairman Ravi Agrawal’s NUDGE (Non-intrusive Usage of Data to Guide and Enable) framework; blog.saginfotech.com

HOW THE MACHINE ACTUALLY WORKS

AIS, TIS and Form 26AS are not, in truth, three documents produced by one system — they are the visible tip of at least seven or eight distinct back-end systems, most of which the taxpayer never sees or is even told exist.

Data collection: OLTAS captures actual tax payments/challans from banks and RBI. TIN, historically run by NSDL e-Governance (now Protean eGov Technologies), received e-TDS/TCS returns and PAN/TAN applications. The Reporting Portal is where banks, RTAs, depositories, mutual funds and insurers upload SFT returns (Form 61A) and FATCA/CRS data (Form 61B) under Section 285BA. GSTN separately feeds GST turnover data into AIS.

Data processing: Project Insight (being replaced by Insight 2.0) houses INTRAC — the Income Tax Transaction Analysis Centre — which de-duplicates and integrates this data into what becomes the AIS you see. A separate unit, CMCPC, runs the compliance-campaign machinery (emails, SMS, letters, calls).

Reconciliation: CPC-TDS at Ghaziabad runs TRACES, matching deductor TDS/TCS returns against OLTAS challans to generate Form 26AS and Form 16/16A. CPC-ITR at Bengaluru, a separate centre, processes the return itself, matches credits, and issues Section 143(1) intimations and refunds.

Enforcement: None of the above is visible to the Assessing Officer directly — flags are routed into ITBA, the Department’s internal case-management system, which is where an AIS mismatch actually becomes a Section 148A notice.

A citizen who has never heard of OLTAS, INTRAC, CMCPC or ITBA is nonetheless expected to reconcile their outputs correctly, on pain of reassessment.10

What “accepted by taxpayer” and “confirmed by source” actually mean: TIS shows a final “value accepted by taxpayer/confirmed by source” for each income head, which is what gets used to pre-fill the ITR. This sounds like independent verification. It is not. “Accepted by taxpayer” simply means the taxpayer did not dispute the entry — not that anyone checked it. “Confirmed by source” means the same bank or company that originally reported the figure has reaffirmed its own number — not that any independent party audited it. Both labels carry an air of finality that the underlying process does not support.11


10 Income Tax Department, Reporting Portal (Project Insight), report.insight.gov.in; internal CBDT correspondence on Project Insight 2.0 transition (Directorate of Income-tax Systems), 2023-25; Reporting Portal FAQs on SFT, taxheal.com (definitions of INTRAC and CMCPC); CPC-TDS/TRACES architecture note, taxindiaonline.com. Vendor/managed-service-provider details for CPC-ITR and the e-filing portal were not independently re-verified and should be confirmed before publication.
11 Income Tax Department, “AIS — Annual Information Statement” help page, incometax.gov.in/iec/foportal/help/all-topics/e-filing-services/ais-annual-information-statement (definition of “value processed by system” and “value accepted by taxpayer/confirmed by source” in TIS, and its use for ITR pre-filling); AIS FAQ, incometax.gov.in/iec/foportal/ais-faq, Q5

IS IT FAIR?

1. AIS/TIS data is admittedly unreliable — and the Department knew it from Day One

AIS/TIS data is frequently wrong, duplicated, or mis-attributed — and the department knew this at rollout, which is precisely why the very first press release on AIS told taxpayers to prefer Form 26AS/TRACES over AIS wherever the two conflict, and why six categories of taxpayer feedback (“not fully correct,” “relates to other PAN/Year,” “duplicate,” “denied,” among others) were built into the system from inception.12 The existence of that feedback mechanism, and of the official advice to distrust AIS in case of conflict, is itself an admission that raw AIS data is not reliable enough to stand alone. Off-market share transfers get double-counted across depositories; joint bank accounts attribute full interest to both holders; SFT filers routinely report gross consideration where net or exempt amounts were involved. Yet reassessment notices routinely treat the unverified, pre-feedback AIS/TIS figure as if it were settled fact — the very opposite of what “reason to believe” under Section 147 has historically required.


12 Income Tax Department, “FAQs on AIS”, incometax.gov.in/iec/foportal/ais-faq, Q10 (categories of taxpayer feedback)

2. The statutory safeguard of independent enquiry is being bypassed

The legal threshold for reopening an assessment is not a data mismatch; it is “information” that suggests income has escaped assessment, followed by an independent enquiry and an opportunity of hearing under Section 148A — a safeguard Parliament inserted precisely to stop mechanical reopening. Courts have already had to intervene: the Bombay High Court, in PCIT v. Agfa India Pvt. Ltd., held it mandatory for the Assessing Officer to independently apply his mind to the material on record rather than reproduce a computer-generated flag as “reason to believe.”13 That such a basic proposition needed judicial restatement tells its own story about departmental practice.


13 PCIT v. Agfa India Pvt. Ltd., Bombay High Court, as reported in TaxGuru, “Validity of Reassessment Under Section 148 Based on AIS Mismatch” (June 2025). Primary judgment text not independently verified — please confirm citation before publication.

3. The entire burden of reconciliation sits with the taxpayer, none with the reporting entity

If an SFT filer over-reports, the taxpayer must track it down, raise a feedback request, and hope the source confirms or corrects it — all within compressed reassessment timelines that, post the Finance Act 2024/2025 amendments, can still run out to five years and three months for income above ₹50 lakh. There is no reciprocal accountability on the reporting entity for filing an inflated or duplicated SFT return that sets an entire reassessment machinery in motion.

4. This inverts the Taxpayer’s Charter and natural justice

Section 119A obliges the department to treat every taxpayer as honest unless there is reason to believe otherwise, and to be fair, courteous and reasonable. A regime where an unverified third-party entry — one the taxpayer had no chance to contest before its upload — becomes prima facie grounds to reopen a closed assessment does not sit easily beside that Charter commitment, or beside the constitutional guarantee of fair procedure recognised in Maneka Gandhi v. Union of India.14 Natural justice requires that the person be heard before, not merely after, an adverse action is set in motion on data he never had a chance to correct.


14 Maneka Gandhi v. Union of India, (1978) 1 SCC 248; indiankanoon.org/doc/1766147/

5. Faceless reassessment compounds the problem

Once AIS flags a mismatch, the faceless machinery under the National Faceless Assessment Centre generates the notice algorithmically, with limited scope for the taxpayer to explain context to a human officer before the show-cause stage. Genuine explanations — a gift already offered to tax, a reversed transaction, an exempt long-term holding or transmission — often need several rounds of correspondence, converting what should be a two-minute reconciliation into a months-long ordeal, with every deadline enforced strictly against the taxpayer and none against the department. A trend is seen, where the officers simply don’t read or decline a matter of fact without countering it with facts that are otherwise.

6. The taxpayer is handed a maze of documents and codes he had no part in creating

Beyond the substantive mismatch problem lies a subtler unfairness: sheer multiplicity. A single fixed-deposit interest entry alone can appear under an SFT code (e.g. SFT-005 for the deposit, SFT-016 for the interest), a TDS section code (194A), an “Information Source” identifier for the reporting bank, and a separate “Information Description” string — four different labels for one transaction, spread across AIS, TIS and 26AS, none of which is explained in plain language on the document itself.15 The SFT taxonomy alone runs from SFT-001 (cash purchase of bank drafts) through SFT-018 and beyond — codes covering everything from credit card payments to buy-back of shares to immovable property — and a taxpayer is simply handed the code, not a plain-English reconciliation of why the same economic transaction surfaces twice under two different labels.


15 Income Tax Department, “FAQs on AIS”, incometax.gov.in/iec/foportal/ais-faq, Q2 (TDS/TCS and SFT information codes); Studycafe, “What is SFT & SFT Codes used in Annual Information Statement (AIS)”, listing SFT-001 to SFT-018 (Nov 2021); TaxConcept, “All About the New Annual Information Statement (AIS)” (illustrating SFT-016 interest overlapping with TDS section 194A/193 reporting)

These codes were never designed for the citizen. They exist for machine-to-machine handshakes between OLTAS, TIN, the Reporting Portal and INTRAC — internal bookkeeping convenience for the Department’s own systems — and have been passed on to the taxpayer unmodified, as if self-explanatory. A retired pensioner or a small trader, confronted with a printout reading “SFT-016 / Source: XXXX Bank Ltd / 194A,” has no realistic way of knowing whether this is one transaction counted twice or two genuinely different ones — short of hiring a professional merely to translate the Department’s own internal taxonomy back into ordinary language. Codes built for one government system to talk to another have been handed to the citizen as if they were self-explanatory — and then used against him when he cannot explain them.

The Taxpayer’s Charter promise to be fair, courteous and reasonable must surely include a duty to communicate in a form the citizen can actually parse. A regime that requires professional intermediation simply to read one’s own tax data — before any question of accuracy even arises — imposes a compliance cost that falls hardest on exactly those taxpayers least able to afford representation.

7. The taxpayer has no independent way to verify SFT completeness or correctness

Unlike TDS — where Section 203 obliges the deductor to issue the deductee a Form 16/16A certificate as a matter of law — no provision in Section 285BA or Rule 114E requires a bank, mutual fund, registrar or other reporting entity to ever tell the taxpayer what it has filed against his PAN, or to share a copy. An SFT entry, right or wrong, is simply filed with the Department and surfaces, unannounced, in AIS months later.16


16 Income Tax Department, “FAQs on AIS”, incometax.gov.in/iec/foportal/ais-faq, Q3 (AIS “includes information presently available with Income Tax Department” and “there may be other transactions...not presently displayed”). Contrast Section 203, Income-tax Act, 1961, which obliges a TDS deductor to issue Form 16/16A to the deductee — no equivalent obligation exists on an SFT reporting entity under Section 285BA/Rule 114E to inform the taxpayer of what has been reported. See IndiaFilings, “Form 61A Filing Guide”.

Worse, the Department’s own FAQ concedes that AIS “includes information presently available with Income Tax Department” and that “there may be other transactions relating to the taxpayer which are not presently displayed” — an explicit admission that AIS is not guaranteed to be complete.17 A taxpayer can therefore never be certain, from AIS alone, that what he sees is either accurate or exhaustive — yet he is expected to reconcile his return against it, and risks reassessment years later for whatever discrepancy the Department’s systems eventually notice. Completeness is asserted against the taxpayer but not warranted by the Department. This problem is accentuated, when 26AS continues to show joint purchasers of property in its reporting and without TDS verification/correlation in that year and for that property to determine which PAN made payments and corresponding TDS.


17 FAQ, Q 3 - https://www.incometax.gov.in/iec/foportal/ais-faq

8. A one-way 30-day silence rule favours the reporting entity, not the taxpayer

Neither Section 285BA nor Rule 114E gives a taxpayer any right to approach a reporting entity directly and demand an explanation. The only route is AIS feedback — e.g. marking an entry “relates to other PAN/Year” — which the portal forwards to the entity, giving it 30 days to accept or reject.18 If the entity stays silent or denies it, the original entry simply stands, with no penalty on the entity and no appeal for the taxpayer — the same silence that shields the reporting entity would count against the taxpayer if the roles were reversed.


18 Section 285BA, Income-tax Act, 1961, and Rule 114E, Income-tax Rules, 1962 (no provision for direct taxpayer query to reporting entity). Process description: AIS feedback routed to reporting entity, which has 30 days to accept or reject, failing which original entry stands — MyFinancial, “AIS Mismatch Correction: A Step-by-Step Process for AY 2026-27” (2026); VittSphere ONE, “AIS, TIS, Form 26AS reconciliation before filing ITR” (2026); GetBelong, “AIS Mismatch for NRIs” (2026).

9. Case in Point

Benaifer Vispi Patel v. ITO 2025) 475 ITR 704 (Bom)(HC) is a recent case in point which went to High Court. The Court held (paraphrased from itatonline.org):

… the Court held that it cannot be conceived that at all material times, the information available in the electronic mechanism/system, would be free from errors and defects. Once a defect was pointed out on information as available on portal, it would be duty of Assessing Officer to examine version of assessee in pointing out that information was not correct and same would require due consideration for any further action to be taken to issue notice under section 148. When electronic information was available under faceless mechanism and there was other material available, as may be gathered by Assessing Officer or furnished by assessee, it would be incumbent on Assessing Officer to apply his mind to all such materials and only thereafter take a well-considered view of matter to issue a notice under section 148 by dispensing provisions of section 148A. Court held that reopening notice was arbitrary and vitiated by non-application of mind and is set aside. (AY. 2020-21)

Application of mind is increasingly becoming an issue, as many disgruntled officers seem to plainly take the data blindly and start proceedings.

There are numerous cases where Joint Holder is required to be reported. In case of Mutual Fund investments this appears in both taxpayers. The cause is that Rules are wrong – where MFs are mandated to report both holders. Attribution to all holders: As per the Aggregation Rule guidelines under Rule 114E, the reporting entity must attribute the entire value of the transaction to all the persons in whose name the account or transaction is recorded. In the AI age this is backward as belonging to 20th century mind-set.

Recently the author came across a case where Non Resident purchased property. Money came from overseas, and wife was joint holder. Husband filed the ITR disclosing the property. Wife had no income or investments. Notice and demand were received on the wife. Notice was not served properly. Husband had gone through the scrutiny assessment. The matter reached to the point of bank account seizure. The point is the tax officer failed to apply the nexus – to see the joint registration, name of first holder, movement of money, and payment from a bank account and scrutiny assessment in respect of a property. Application of mind is critical and no system can develop this ability of due care by an officer. It shows a bizarre and brazen display of unprofessional behaviour without accountability and causing harassment to a category of people who send MAXIMUM inward remittances for the nation.

In another live matter, where Jt Holder spouse is facing a 148 matter after receiving Section 133(6) Notice, supplying all papers of all payments and mentioning the name, PAN, and amounts of spouse, still ended up facing 148 proceedings. In the age of TDS deductions under section 194I – where even a marginally intelligent officer and in this case a commissioner should have been able to determine where the funds came – after connecting Bank Statement, TDS entries, TDS Certificates, Property Purchase Documents, Invoices. However, lack of application of mind at commissioner level and a mechanical approach with complete and careless disregard for law, facts and taxpayer is becoming the norm.

THE SOLUTION

1. No notice without AO verification. An AO may not cite an AIS/TIS entry in a Section 148A notice without first checking taxpayer feedback on it and recording what was submitted, in the notice, why that feedback was rejected especially when factually and can be counter checked with TDS payments in case of property purchases.

2. A mandatory pre-notice reconciliation window. A 30-day automated window on the AIS portal to fix genuine data errors before any notice is even considered — consistent with the Department’s own 2021 position that TRACES, not AIS, should prevail in case of doubt.

3. Punish false reporting by SFT filers. Reporting entities whose SFT data is repeatedly found wrong on taxpayer feedback should face mandatory penalty under Section 271FAA or fine per error — false or careless reporting cannot be cost-free for the source while the taxpayer alone pays for it in notices.

4. Publish AIS error rates. CBDT should periodically publish AIS/TIS feedback-acceptance statistics, so the reliability of this “evidence” is known before it is used to reopen assessments.

5. Genuine NUDGE, not disguised enforcement. A mismatch should first trigger a soft, non-adversarial email nudge — as already piloted for virtual digital asset discrepancies19 — escalating to Section 148A only if ignored, not as the first response to a data flag.


19 Business Standard, reporting on CBDT NUDGE email campaign addressing under-reported virtual digital asset (crypto) income, 2025; business-standard.com/topic/cbdt

6. Make it understandable. Every SFT/TDS code must carry a mandatory plain-English explanation on the statement itself. If a code is fit to trigger a notice, it must be fit to explain itself.

7. One composite statement — not three. AIS, TIS and Form 26AS should be merged into a single taxpayer-facing statement with one reconciled figure per income head. Three overlapping documents, each a partial and differently-processed view of the same underlying data, is itself a source of confusion and inconsistent departmental action.

8. Make it less surveillance, more self-service. The AIS/Compliance Portal should be administratively and visually de-linked from the enforcement machinery (ITBA) — rebranded and communicated as a self-correction facility, not a watch-list dossier, with soft-touch language replacing the current compliance-and-deterrence framing.

9. Joint Holders. The AIS/Compliance Portal should be administratively and visually de-linked from the enforcement machinery (ITBA) — rebranded and communicated as a self-correction facility, not a watch-list dossier, with soft-touch language replacing the current compliance-and-deterrence framing.

10. Stop Modifications to AIS TIS 26AS after filing of ITR. Once the ITR is filed, taxpayer permission should be required to update these as the taxpayer has already relied on them. There is a problem of constantly changing forms where one has to check several times what has changed.

CONCLUSION

The officially described themes of transparency and pre-filling tool meant should help taxpayers, not indict them. Understandability of numerous documents is the critical missing component – multiplicity of documents, incorrigible entries in many cases, overlapping and duplicate data is far from being helpful. It is clear that since the machine based reporting came, the officers including at high levels, do not apply their minds and are trigger happy to initiate proceedings where taxpayer has everything to loose and tax administrator can illegally claim 20% deposit for appeals with no cost imposed on him if he loses.

A tool meant to nudge voluntary compliance should be one simple, understandable statement that helps the citizen self-correct — not three coercive ones that punish him for not being able to read them. Until it is, AIS remains, for many honest taxpayers, exactly the surveillance instrument it claims not to be.

Beyond SEO: Why Chartered Accountants Must Prepare For The GEO Era

The manner in which clients discover professional expertise is undergoing a significant transformation. Increasingly, individuals are turning to AI-driven platforms such as ChatGPT, Gemini, and Perplexity AI for answers to tax, regulatory, and business queries instead of relying solely on traditional search engines. This shift has led to the emergence of GEO (Generative Engine Optimisation), which focuses on making professional expertise digitally understandable and discoverable within AI-generated responses. For Chartered Accountants, this development has important implications for visibility, positioning, and client discovery. The article examines how GEO differs from traditional SEO, why digital expertise signals are becoming increasingly relevant, and how professionals can adapt to the evolving AI-driven ecosystem.

In the AI era, professional visibility may increasingly depend not merely on expertise itself, but on whether AI systems can recognise, interpret, and associate that expertise with relevant client queries.

For nearly two decades, professional visibility on the internet revolved around one dominant platform — Google. Businesses and professionals focused extensively on websites, search rankings, and SEO strategies because client discovery largely began with a Google search. A prospective client would search for a tax query, browse multiple websites, compare professionals, and then decide whom to approach.

That model is now undergoing a quiet but significant transformation. Increasingly, individuals are no longer “searching” in the conventional sense. Instead, they are directly asking questions to AI-driven platforms such as OpenAI’s ChatGPT, Google Gemini, Anthropic Claude, and Perplexity AI. More importantly, they are receiving complete, contextual, and conversational responses within seconds — often without opening a single website. This behavioural shift has given rise to a new concept: GEO (Generative Engine Optimisation).

UNDERSTANDING GEO

GEO refers to the process of building a digital presence in a manner that enables AI systems to recognise, interpret, and associate a professional with a particular area of expertise while generating responses.

Traditionally, professionals focused on SEO (Search Engine Optimisation), where the objective was to rank higher on search engines. Success was measured by visibility in search results and website traffic. GEO fundamentally changes that framework.

In the AI-driven ecosystem, users increasingly ask complete questions instead of typing fragmented keywords. Rather than displaying a list of links, AI platforms generate consolidated and contextual answers.

Accordingly, the central question is no longer: “How do I rank on Google?”

The more relevant question now is: “How do I become part of the answer generated by AI?”

That distinction lies at the heart of GEO. In practical terms, GEO depends upon how strongly the digital ecosystem associates a professional with a specific subject area. AI systems infer such associations through publicly available digital signals such as articles, blogs, FAQs, professional insights, educational posts, interviews, discussions, and case-based explanations.

For example, if a Chartered Accountant consistently publishes practical insights on startup taxation, FEMA, ESOPs, NRI taxation, or GST-related matters, such content strengthens publicly visible expertise signals that AI systems may be able to interpret when those signals are included within their underlying data sources or retrieval processes. While this can improve discoverability over time, whether a professional is surfaced in any specific AI response will continue to depend on the design, data sources, licensing arrangements, and retrieval policies of the particular AI platform.

The-new-rule-of-visibility-from-seo-to-Geo

This is why GEO is fundamentally different from traditional digital marketing. It is not merely about visibility or promotion. Rather, it is about building digital interpretability of expertise.

It is important to recognise, however, that AI-generated discoverability is not determined solely by the volume of public content or digital signals. Different AI platforms rely on different combinations of training data, licensed content, retrieval mechanisms, freshness of information, and platform-specific filters. Consequently, the professionals or sources surfaced by one AI system may differ from those identified by another. GEO should therefore be viewed as improving the likelihood that a professional’s expertise can be recognised and interpreted by AI ecosystems, rather than as a guarantee of inclusion in AI-generated responses. Consistent, high-quality public expertise remains an important input, but it operates alongside these platform-specific factors.

How it differs from SEO

Aspect SEO GEO
Focus Ranking higher on search engines Being included in AI-generated answers
User Behaviour Keyword searches → list of links Conversational queries → direct contextual answers
Signals Website traffic, backlinks, keywords Digital expertise signals (articles, blogs, FAQs, case notes, interviews)
Outcome People find your website AI understands what you are known for

In simple terms:

  • SEO helps people find your website.
  • GEO helps AI understand what you are known for.

In an era where professional discovery increasingly begins with AI-generated answers, that distinction may become extremely significant.

A simple exercise every Chartered Accountant should try

Open ChatGPT or Gemini and type queries such as:

  • “Suggest good Chartered Accountants in Mumbai for GST registration.”
  • “Who are good CAs for startup taxation in India?”
  • “Best CA for NRI taxation in Mumbai.”

Observe the responses carefully.

Certain patterns become immediately noticeable:

  • AI systems may mention professionals or firms with stronger, well-structured digital visibility, although responses can vary across platforms depending on their training data, licensing arrangements, retrieval methods, and platform-specific filters.
  • They tend to rely on publicly available expertise signals such as articles, blogs, interviews, and professional commentary.
  • Professionals who consistently explain concepts in a structured and accessible manner are more likely to surface.

This leads to an important introspective question:

Would your name, firm, or expertise appear anywhere within that ecosystem today?

The answer to that question itself explains why GEO matters.

WHY THIS SHIFT IS PARTICULARLY RELEVANT FOR CHARTERED ACCOUNTANTS

The Chartered Accountancy profession is fundamentally built upon trust, interpretation, and expertise. Clients approach Chartered Accountants not merely for compliance, but for clarity, guidance, and confidence in decision-making.

Historically, such trust was built primarily through referrals, professional reputation, and personal networks.

Today, however, the first layer of professional validation is increasingly becoming digital. Before contacting a professional, clients now frequently seek preliminary understanding through AI tools. Consider a common example. A business owner wanting to understand the taxability of cross-border SaaS transactions may no longer search: “GST on SaaS services”

Instead, the question may be framed conversationally: “How does GST apply to software services provided to foreign clients from India?”

The response generated by AI is usually structured, practical, and direct. In arriving at such responses, AI systems rely heavily on publicly available digital content — articles, explanatory notes, discussion threads, blogs, interviews, and professional insights that demonstrate subject matter expertise. This development has important implications for professionals.

EXPERTISE WITHOUT VISIBILITY IS GRADUALLY BECOMING INVISIBLE

Consider two Chartered Accountants possessing similar technical competence and experience in GST advisory.

One regularly publishes short practical insights on LinkedIn, writes explanatory notes on emerging industry issues, and discusses case-based interpretations in simple language. The other relies entirely on traditional referrals and maintains virtually no visible digital footprint.

When AI systems repeatedly encounter practical and structured content from the first professional, a digital association gradually develops between that individual and the relevant subject matter. Over time, this increases the likelihood of that expertise being reflected, referenced, or indirectly represented within AI-generated responses.

The second professional, despite being equally competent, remains largely invisible because the digital ecosystem lacks sufficient context to identify and associate expertise with that individual.

This represents the central reason why GEO is becoming increasingly important for professionals.

THE NATURE OF CONTENT IS ALSO CHANGING

Importantly, GEO is not about “gaming algorithms” or creating superficial content purely for visibility. In fact, AI-driven systems tend to favour clarity, consistency, relevance, and usefulness.

Content that performs well within AI ecosystems is typically:

  • Structured and easy to understand
  • Practical rather than purely theoretical
  • Written in conversational language
  • Focused on real-world questions and scenarios
  • Educational in nature

For Chartered Accountants, this presents a significant opportunity because the profession naturally generates practical problem-solving situations every day.

Questions relating to capital gains, ESOP taxation, HUF structures, startup compliance, residency status, FEMA regulations, cross-border transactions, succession planning, and GST implications are inherently explanatory in nature. These are precisely the kinds of subjects users increasingly explore through AI platforms.

A simple illustration highlights this shift.

An article titled: “Analysis of Capital Gains Provisions under the Income-tax Act” may satisfy technical completeness. However, a practical note titled: “Sold a Property After Three Years? Here is How Your Tax Will Actually Be Calculated” is substantially more aligned with how modern users ask questions and how AI systems process contextual understanding. The technical substance may remain identical. The accessibility changes entirely.

GEO AND THE IMPORTANCE OF PROFESSIONAL POSITIONING

Another important dimension of GEO is professional positioning.

Historically, many professionals positioned themselves broadly as “tax consultants” or “practising Chartered Accountants.” In the AI-driven ecosystem, however, sharper positioning creates stronger digital association. Repeatedly discussing focused subject areas: such as startup advisory, NRI taxation, international taxation, forensic audits, FEMA, or real estate taxation, gradually strengthens one’s digital identity in that domain. Over time, expertise that is repeatedly visible becomes expertise that is digitally recognised.

Importantly, this does not imply that every professional must become a social media influencer or produce excessive volumes of content. Consistency and relevance are far more valuable than frequency alone. Even brief but insightful observations, practical interpretations of amendments, FAQs, or case-based explanations can meaningfully strengthen one’s GEO presence.

DISCOVERY IS BECOMING PRE-FILTERED

Perhaps the most significant aspect of this transition is that, in the near future, many clients may never conduct a conventional search at all. Their professional discovery journey may simply become:

  1. Ask AI a question
  2. Receive a refined answer
  3. Identify likely professionals or firms
  4. Reach out directly

In such an environment, professionals who are digitally visible within the AI knowledge ecosystem may enjoy disproportionate discoverability. The significance of this transition is comparable to the early adoption phase of websites and social media. Those who recognised the importance of digital presence early were able to build substantial visibility advantages over time. GEO appears to represent a similar inflection point.

A PRACTICAL 90-DAY GEO ACTION PLAN FOR CHARTERED ACCOUNTANTS

Days 1–15: Build Your Professional Identity

  • Optimise your LinkedIn profile
  • Clearly mention your areas of specialisation
  • Use practical descriptions instead of generic labels

Days 15–30: Create Foundational Content

  • Write short posts answering common client questions
  • Focus on clarity rather than technical jargon
  • Simplify practical concepts

Days 30–45: Build Searchable Expertise

  • Publish FAQs, explanatory notes, and short articles
  • Discuss practical scenarios and industry developments
  • Create educational content consistently

Days 45–60: Strengthen Authority Signals

  • Participate in webinars, panel discussions, and podcasts
  • Share practical observations publicly
  • Engage meaningfully within professional communities

Days 60–90: Develop Consistency

  • Commit to at least two professional posts per week
  • Publish one practical article every month
  • Build one clearly identifiable niche area of expertise

CONCLUSION

GEO is not merely another marketing trend. It represents a structural shift in how professional expertise is discovered in the digital age. For years, professionals competed for visibility on search engines. Increasingly, professionals may now compete for relevance within AI-generated answers. In such a world, technical competence alone may not guarantee discoverability.

The professionals who are likely to stand out will be those whose expertise is understandable, accessible, digitally visible, and consistently communicated.

Ultimately, the question is no longer simply: “Are you a good professional?”

The more relevant question increasingly becoming: “Does the digital ecosystem know that you are one?”
GEO is a powerful tool for enhancing discoverability, but it is not a substitute for professional competence, ethical practice, or traditional reputation-building. Chartered Accountants should treat GEO as a complement to their existing credibility rather than a replacement.

From The President

My Dear BCAS Family,

September in Mumbai is a season of transition. As the monsoon begins to recede and the festive spirit gathers momentum, the city prepares to move forward with renewed energy. This transition invites us to pause and reflect: how can we convert reflection into renewal personally, professionally and institutionally?

The Strength to Forgive

Let’s begin with Paryushan. It is perhaps the one festival that asks something genuinely difficult of us. On Kṣamāpanā, His Holiness the 79th Spiritual Sovereign, Jainacharya Yugbhushan Suriji, posed a question that I cannot shake off: We forgive ourselves so easily; why are we harder on others when it is their turn to be forgiven? Why the double standard? His answer was neutrality; extending to others the same generosity we readily extend to ourselves. This is the strength Gandhiji once located in forgiveness itself. “The weak can never forgive. Forgiveness is the attribute of the strong.” There is a lesson here for all of us. We spend our careers examining other people’s numbers, decisions and mistakes. Perhaps it is time we turned that same scrutiny, and the same grace, inward. So, to every member, staff colleague and friend of this Society whom I may have let down this year, knowingly or unknowingly: Michhami Dukkadam.

Building Trust, Breaking Silos

This spirit of reflection and collective responsibility shaped the BCAS Core Group Leadership Retreat 2026.

The last two months gave the Core Group something rare: an actual pause, though it almost did not happen. The BCAS Core Group Leadership Retreat 2026 was originally planned at Avadh Utopia, but the monsoon had other plans. With just ten days to go and the venue rendered unusable, our team went into overdrive, sourcing, evaluating and finalising a new venue, Pearl Resort in Silvassa, without losing a single day for the 120 members who had already blocked their calendars. Two Managing Committee members personally inspected the venue because a brochure and an actual, seamless experience are two very different things.

I mention this not for the logistics, but because it says something about us; the unglamorous scramble behind the scenes is what makes the visible part look effortless. The Leadership Retreat was conceived with a simple thought: to bring our Core Group together, break down silos and create a shared vision for the future.

The retreat delivered exactly what we had hoped for two days of honest conversations, meaningful connections and trust-building across committees and generations of BCAS. My gratitude to every Core Group member who was part of these two days of conversation for your time, your ideas, your faith and, most importantly, your willingness to serve the Society. Together, we will honour the legacy of BCAS, serve the profession and transform the future.

Extending the Reach of BCAS

As part of our “Reach” initiative, BCAS has been engaging with regulators, law enforcement agencies and corporates through the proactive approach of the 4i Committee, led by CA Chirag Doshi. We had a productive meeting with SEBI Chairman Mr. T. K. Pandey to explore how BCAS can contribute to strengthening corporate governance and building regulatory awareness among professionals serving as KMPs, auditors and Independent Directors.

The Economic Offences Wing of the Mumbai Police has also invited us to train senior officers in reading financial statements and identifying fraud modus operandi.

I also met the Vice-Principal of R. A. Podar College to explore a program focused on sharpening the practical skills of students pursuing commerce and finance courses.

These engagements reflect our larger ambition through “Reach”, to take the expertise of our profession beyond our traditional circles and make it more relevant to regulators, institutions, businesses and society at large.

A Community That Removes Obstacles

This September, we will welcome Lord Ganesh into our homes and pandals. The processions and the scale of the celebrations we see today were not always part of public life. Lokmanya Tilak deliberately revived the public celebration of Ganeshotsav to build a sense of community at a time when public gatherings were restricted. He found his answer in the remover of obstacles. That is a useful lens for a professional body too. At our best, that is what BCAS should be; not merely a directory of contacts, but a genuine community that helps remove the obstacles between a member and their next step. Our own retreat this year was a small example of that spirit – a plan disrupted, a challenge we could not have anticipated, and a community that found a way through it together.

A certain stagnation hits many of us mid-career. You’re competent, established, even respected, yet somehow boxed into a role you’ve outgrown: the tax specialist eyeing advisory, the audit partner curious about ESG assurance, the practitioner good at the work but rarely seen for it. If that’s you, lean into this community rather than work through it alone. A cross-professional conversation, a chance meeting at a seminar, an honest coffee with a senior member: this isn’t networking in the transactional sense. It’s closer to what Balgangadhar Tilak understood; people move through obstacles together, not by individually pushing harder against them.

Beyond-the-ledger

Knowledge with Responsibility

Regulatory update: The Taxation and Other Laws Amendment Bill, 2026 moved swiftly through the Lok Sabha. This reflects the government’s continued push for simpler compliance and a more coherent digitaleconomy framework. We’ll examine its implications in the weeks ahead.

GST collections: Gross GST collections rose 15.4% year-on-year to ₹2.11 lakh crore, providing welcome reassurance despite continued uncertainty across global supply chains.

Events: The 60th Members’ RRC has crossed 200 registrations within its first month. Registrations for the 2nd Direct Tax Retreat are also progressing briskly. Members are encouraged to register early.

Giving back: In keeping with its social commitment, BCAS aspires to plant nearly 10,000 trees in the tribal belt of Jawhar, supporting environmental sustainability while creating a regular income source for tribal farmers who nurture them. I humbly appeal to every reader to support this cause.

Moving Forward Together

As we enter the busiest month of the year, alongside the festive season, thoughtful planning will be essential to complete assignments on time without compromising on quality. Wishing you and your teams a productive tax season. One that is successful, smooth and, hopefully, a little less taxing!

Jai Hind.