

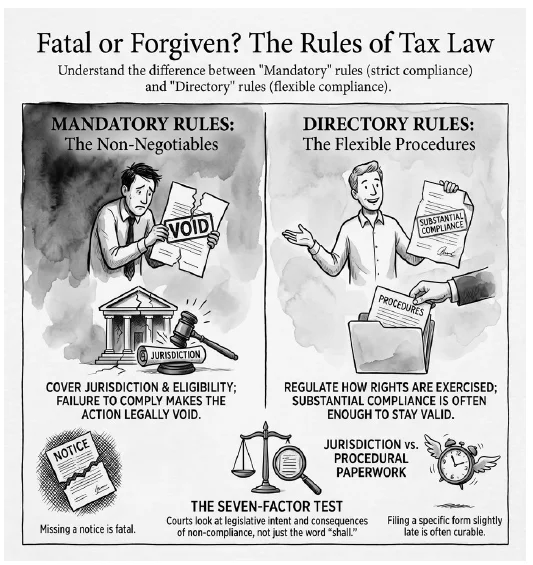
In tax law, statutory provisions are classified as mandatory or directory based on legislative intent rather than literal terms like “shall” or “may”. Mandatory rules govern jurisdiction, limitation periods, and substantive eligibility; strict adherence is indispensable, and failure to comply renders proceedings void regardless of prejudice. Conversely, directory rules regulate procedural and evidentiary mechanisms intended to facilitate administration. Courts allow substantial compliance for directory provisions whenever the underlying statutory purpose is fulfilled and no prejudice is caused. Modern courts apply a seven-factor test examining statutory purpose, non-compliance consequences, curability, and overall legislative scheme to determine a provision’s true legal character.
Statutory interpretation occupies a central position in every fiscal legislation. Unlike private law, where rights and obligations frequently arise from consensual arrangements, tax statutes derive their authority exclusively from legislative command. Every obligation imposed upon the taxpayer, every power conferred upon the Revenue authorities and every exemption, deduction or concession recognised under the statute owes its existence to parliamentary enactment. Consequently, the interpretation of statutory language, particularly whether a provision is mandatory or directory assumes exceptional importance, for it determines not merely the meaning of legislative provisions but also the limits of administrative authority and the conditions governing the exercise of statutory rights.
The jurisprudence governing mandatory and directory statutory provisions has acquired renewed significance following a series of recent judicial pronouncements under the (now repealed) Income-tax Act, 1961 (“the Act”). A controversy arose before the Delhi High Court1, where the validity of a notice issued under section 143(2) was challenged. The petitioner contended that the failure to adhere to the format prescribed by the CBDT2 rendered the notice invalid and consequently vitiated the assessment proceedings initiated thereunder.
1 Bharat Bansal v. NFAC, W.P.(C) 2238/2026, CM APPL. 10798/2026 & CM APPL. 10799/2026

2 Instructions dated 23rd June 2017 and 13th October 2021
Rejecting the challenge, the Delhi High Court (HC) held that the CBDT Instructions were intended solely to regulate the internal functioning of the Income-tax Department and they neither conferred any enforceable rights upon the assessee nor imposed additional jurisdictional conditions beyond those prescribed by the statute. It was observed that the purpose of a notice under section 143(2) is to intimate the assessee that the return has been selected for scrutiny and assume jurisdiction and hence, mere omission to specify the category or reasons for scrutiny in the initial notice did not affect the validity of the said notice. The Court thus drew a clear distinction between statutory requirements governing jurisdiction and administrative instructions regulating departmental procedure, holding that non-compliance with the latter could not invalidate proceedings otherwise lawfully initiated under the Act.
This issue assumed greater significance in recent past as conflicting decisions of various benches of the Income Tax Appellate Tribunal (ITAT) necessitated constitution of a Special Bench3. The Special Bench also adopted a similar analogy as the Delhi HC (supra) in holding that a format prescribed under the CBDT Instructions constitutes an administrative mechanism and cannot be elevated into a statutory condition precedent governing the validity of a notice issued under section 143(2).
On a separate note, the Karnataka HC4, while examining the issue, the High Court considered the object underlying the Document Identification Number (“DIN”) regime, namely ensuring authenticity, traceability and maintenance of an audit trail in departmental communications. The Court noted that the controversy did not involve a case where no DIN had been generated or communicated. Rather, the impugned orders had been uploaded through the prescribed electronic process, the DINs were subsequently communicated through authenticated intimation letters and the accompanying orders contained an incorrect DIN owing to a manual error.
Adopting a purposive interpretation of CBDT Circular No. 19 of 2019 and the related system instructions, the Court held that the requirement of quoting a DIN is mandatory, however, where the correct DIN is communicated through an authenticated intimation identifying the relevant order, the communication would not be rendered invalid merely because the DIN was not originally reflected in the order or was incorrectly mentioned due to a typographical mistake. The court considered the object underlying the DIN regime, and ruled in favour of the tax department by treating such defects are curable irregularities.5
3 M.D. Sons v. Income Tax Officer, [TS-1089-ITAT-2026(Bang)]

4 PCIT v. Unisys India Pvt. Ltd., ITA No. 55/2024

5 It may also be noted that the Finance Act, 2026 has introduced legislative changes dealing with electronic communications and departmental authorisations,
 while CBDT Circular No. 19/2019 governing the DIN mechanism stands withdrawn.
The impact of these developments on pending disputes concerning DIN-related invalidity arguments remains to be judicially tested.
It may be relevant to note here that in the past, a stricter approach to DIN compliance has been adopted by several HCs. The Bombay HC6 and Madras HC7, have held that a subsequent communication on DIN generation would not be sufficient compliance and the original communications were held to be non est in law.
6 Hexaware Technologies Ltd. v. ACIT, [2024] 464 ITR 430 (Bom),
7 CIT v. Laserwords US Inc., [2026] 486 ITR 159 (Madras)
The recent decisions of the HC’s as well as the Special Bench (supra) have thus noted that the format of the notice or insertion of DIN in a subsequent notice is a directory provision and does not prejudice the taxpayers. As long as substantial compliance is adhered to, the same was held to follow the procedure as mandated by law. The matter would have been fundamentally different, though, had there been no notice itself issued under section 143(2) or the DIN was never communicated to the taxpayers. This brings the focus to the germane issue that while certain provisions are so fundamental to the legislative framework that failure to comply necessarily invalidates the action taken under the statute, others merely regulate the way a statutory power is exercised or a statutory right is asserted, such that substantial compliance with the legislative objective may suffice. The logic of this distinction is that while a procedural formality facilitates the enjoyment of a benefit, a substantive condition determines whether the benefit can be claimed in the first place.
MANDATORY AND DIRECTORY PROVISIONS
A mandatory provision is one whose compliance constitutes a condition precedent to the validity of the statutory act. Such provisions ordinarily create jurisdiction, determine substantive rights or impose conditions that Parliament has expressly declared to be essential. Compliance with these requirements is indispensable because the statutory power or benefit itself comes into existence only upon fulfilment of the prescribed conditions. Failure to comply with a mandatory requirement, therefore, ordinarily renders the action void, irrespective of whether any actual prejudice has been demonstrated. The emphasis is not upon the consequences suffered by the parties but upon adherence to the legislative command.
A directory provision, in contrast, regulate the manner in which an existing right or power is exercised. While compliance with such a provision is ordinarily expected, the requirement is not regarded as indispensable to the validity of the proceeding or the existence of the statutory right. The provision regulates the procedure through which an existing right is exercised or established rather than creating that right in the first instance. Consequently, where the legislative purpose has been substantially achieved and the procedural lapse does not defeat the object of the statute or prejudice the interests sought to be protected, courts have often regarded substantial compliance as sufficient.
Broadly, statutory requirements under the IT Act may be classified into three categories. First are judicial requirements, which confer authority upon the tax administration to initiate or continue proceedings. Secondly, substantive eligibility conditions determine whether a taxpayer is entitled to a statutory benefit, exemption or deduction. Thirdly, procedural and evidentiary requirements regulate the manner in which jurisdiction is exercised or statutory rights are claimed. While the first two categories ordinarily receive a mandatory interpretation, the third category is generally construed as directory unless the statute expressly provides otherwise.
Identification of the nature of a provision i.e. whether it is mandatory or directory has been a subject matter of judicial interpretation across statutes. Early judicial decisions tended to adopt a largely literal approach. The use of the word “shall” in a statute was generally treated as indicative of a mandatory requirement, whereas the word “may” was regarded as conferring discretion. However, experience soon demonstrated that such an approach produced inconsistent results. Legislatures frequently used mandatory language in relation to procedural requirements where strict compliance was never intended, while permissive language was sometimes employed in situations where a duty was clearly contemplated.
The Supreme Court8 in a landmark case marked an important departure from purely linguistic interpretation. The Court observed that the determination of whether a provision is mandatory or directory depends primarily upon legislative intent and not merely upon the language employed. This approach was developed further where the Supreme Court9 emphasised that the consequences of non-compliance, the object of the statute and the purpose of the provision must all be examined.
The evolution of the mandatory-directory doctrine within the Income-tax Act may be traced to early decisions that recognised the distinction between substantive statutory conditions and procedural requirements intended merely to facilitate tax administration. An important application was made by the Patna High Court10, wherein the Court examined whether the requirement under section 184(7) that a declaration for continuation of registration of a firm be furnished “along with the return of income” was mandatory or merely directory. Rejecting a purely literal construction, the Court held that the expression could not be interpreted to require physical simultaneity between the return and the declaration. What was material was that both documents were available before the Assessing Officer at the time of making the assessment. The Court observed that an overly technical interpretation would defeat the legislative object and place undue emphasis on procedural form rather than substantive compliance. The decision is significant because it represents one of the earliest judicial recognitions under the Act that procedural requirements intended to facilitate assessment should ordinarily receive a directory interpretation where the legislative purpose has been substantially fulfilled and no prejudice is caused to the Revenue.
The Delhi High Court11 further refined this jurisprudence where the Court was required to determine whether the prescribed time limit for rendering accounts under section 80G(5C)(v) constituted a mandatory condition or a directory procedural requirement. The Court emphasised that the determination could not rest solely upon the language employed by Parliament but required examination of the legislative purpose, the nature of the obligation and the consequences of non-compliance. Since the substantive conditions had already been fulfilled and the delay was procedural in nature, denial of the statutory benefit solely on account of delayed compliance would frustrate the legislative object and produce disproportionate consequences.
An equally significant contribution to the development of the doctrine is found in the Full Bench decision of the Allahabad High Court12. The controversy concerned section 12AA(2), which required the Commissioner shall dispose of an application for registration within six months and hence the question framed was whether failure to adhere to the prescribed time limit resulted in a deemed grant of registration. The Full Bench rejected such an interpretation and held that although the provision employed the expression “shall”, the absence of any statutory consequence for non-compliance indicated that the prescribed time limit was directory rather than mandatory and emphasized that the true test lies in examining the object of the provision, the statutory scheme and the consequences that would follow from either interpretation.
A significant aspect of the mandatory-directory doctrine emerges from the decision of the Sikkim High Court13 wherein the court held that not every statutory prescription carries the same legal consequence upon non-compliance and relied upon the doctrine of substantial compliance i.e. where the essential requirements of the statute have been satisfied, minor procedural deviations should not defeat substantive right.
We will now deal with certain illustrations of mandatory and directory provisions in the context of the Act are in the ensuing paragraphs.
8 State of U.P. v. Manbodhan Lal Srivastava, AIR 1957 Supreme Court 912

9  Raza Buland Sugar Co. Ltd. v. Municipal Board , AIR 1965 Supreme Court 895

10 Commissioner of Income-tax v. Sitaram Bhagwandas [(1976) 102 ITR 560 (Pat.)]

11 Church’s Auxiliary for Social Action v. Director General of Income-tax (Exemptions) [(2010) 325 ITR 362 (Del.)],

12 Commissioner of Income-tax v. Muzaffar Nagar Development Authority [(2015) 372 ITR 209 (All.) (FB)]

13 Balchand Udairam v. State of Sikkim [(1989) 180 ITR 530 (Sikkim)].
A. JURISDICTIONAL PROVISIONS
These are the clearest illustrations of mandatory provisions as jurisdiction constitutes the legal authority to act. If the statute prescribes a particular condition for assumption of jurisdiction, failure to satisfy that condition ordinarily renders the entire proceeding void irrespective of the merits of the case. Consequently, defects going to the root of the notice cannot ordinarily be cured through acquiescence, participation or waiver by the assessee.
The Supreme Court14 has observed that service of the prescribed notice is not merely procedural but constitutes a condition precedent to the validity of reassessment proceedings and the entire proceeding would be rendered illegal where the jurisdictional notice was absent. The doctrine of substantial compliance finds little application in such circumstances because the issue is not whether the power was properly exercised but whether the power existed at all.
The Supreme Court15 in the context of issuance of a notice under section 143(2) has held that it is mandatory act under the statute as it lays the foundation of jurisdiction and hence, is not merely procedural. This principle was reiterated16 by the Supreme Court which clarified that complete absence of notice cannot be cured through section 292BB. While defects in service may in certain circumstances be cured, the actual issuance of notice remains indispensable.
The Delhi and Bombay HC’s17 while examining the validity of approval granted under section 151 before issuance of a notice for reassessment, rejected the Revenue’s contention that the statutory approval constituted a mere administrative formality. The Court held that the approving authority is expected to independently examine the reasons recorded by the Assessing Officer and arrive at its own satisfaction regarding the necessity of reopening the assessment. The judgment, thus, reinforces the principle that procedural safeguards incorporated by Parliament to regulate the assumption of jurisdiction are mandatory in nature and cannot be reduced to mechanical rituals. The requirement of prior sanction exists not for administrative convenience but to protect taxpayers against arbitrary exercise of reassessment powers.
Interestingly, the Finance Act 2026 has inserted section 292BC in the Act to retroactively18 provide that such approvals would be deemed to be administrative and supervisory in nature and shall not invalidate a notice. Although, generally legislature is within its powers to enact an amendment retroactively and can also amend a directory provision to be made mandatory19 whether the wordings in the retrospective amendment in section 292BC are sufficient to convert a mandatory provision into a directory one, without removing any lis or the fundamental basis in the original provision remains to be tested before the Courts, especially in light of the law laid down by the Supreme Court20 in the case of Prithvi Cotton Mills and Indian Aluminium Co. in this regard.
14 Y. Narayana Chetty v. ITO, 1958 (10) TMI 10 - Supreme Court

15 Assistant Commissioner of Income-tax v. Hotel Blue Moon, 2010 (2) TMI 1 - Supreme Court

16  CIT v. Laxman Das Khandelwal, 2019 (8) TMI 660 - Supreme Court

17 CIT v. SPL’s Siddhartha Ltd, [(2012) 345 ITR 223 (Del.)],
 United Electrical Co. (P.) Ltd. v. CIT [(2002) 258 ITR 317 (Del.)];
Svitzer Hazira Pvt Ltd vs Assistant Commissioner of Income Tax, TS-6621-HC-2021

19 Retrospective w.e.f. April 01, 2021

20 Commissioner of Income Tax vs. Natraj Engineers (P) Ltd, Patna HC, TS-5877-HC-2015
B. LIMITATION PROVISIONS
Limitation provisions occupy a unique position in tax law. They do not merely regulate procedure, rather, they define the temporal boundaries within which statutory power may be exercised. Once the prescribed period expires, the authority itself ceases to exist.
The mandatory character of limitation provisions is particularly evident in reassessment cases. The power to reopen completed assessments exists only within the framework prescribed by Parliament. Once the statutory period expires, the authority to reassess stands extinguished. Courts, therefore, refuse to treat limitation periods as mere procedural requirements.
The same principle applies to assessment time limits prescribed under section 153. These provisions serve not merely administrative purposes but also protect taxpayers against indefinite uncertainty. The expiration of limitation, therefore, affects the very competence of the authority to proceed further.
C. EXEMPTIONS AND DEDUCTIONS
The IT Act contains numerous provisions granting exemptions, deductions and preferential treatment. Such provisions often prescribe multiple conditions including filing of returns, reports etc. Judicial decisions consistently distinguish between conditions that determine eligibility and conditions that regulate the manner of claiming the benefit.
An exemption or deduction represents a departure from the normal charging provisions of the Act and hence, eligibility conditions for such exemptions or deductions are ordinarily regarded as mandatory21.
Section 80AC is also one of the clearest illustrations of legislative intent transforming a procedural act into a mandatory condition. The provision links availability of specified deductions to timely filing of the return of income, which clarifies the intent of the Parliament to restrict eligibility of such deductions and exemptions on furnishing of timely returns.22
The requirement to obtain the audit report has also frequently been regarded as substantive because it ensures compliance with the statutory objective of independent verification. However, the requirement regarding the precise timing of filing the report has often been treated as procedural. Consequently, where the report existed and was furnished before completion of assessment proceedings, courts have frequently held that the deduction or exemption should not be denied merely because the report was not enclosed with the original return23.
Particularly in cases of exemption provisions, the Constitution Bench of the Supreme Court24 reaffirmed that exemption provisions in fiscal statutes must be interpreted strictly and that the burden lies on the taxpayer to clearly establish that its case falls within the scope of the exemption. At the same time, the Court recognised the doctrine of substantial compliance, observing that while substantive and mandatory conditions governing eligibility must be strictly fulfilled, mere procedural or directory requirements may be treated more liberally where the essential statutory conditions have been satisfied. The judgment thus draws a crucial distinction between substantive conditions that create the entitlement to a tax benefit and procedural requirements that merely regulate its exercise, making it a cornerstone authority in determining whether a statutory requirement is mandatory or directory. The principles of this decision were echoed by the subsequent Supreme Court’s25 decision wherein the Court in the context of section 10B of the Act (treating it as an exemption section) held that furnishing of the declaration stipulated in section 10B and adherence to the prescribed timeline constituted mandatory conditions.
The Supreme Court26 in a landmark case while dealing with deduction claims where the prescribed audit report had not been filed along with the return but had been furnished before completion of assessment proceedings held that as the purpose underlying the requirement was to ensure that the necessary certification was available to the assessing authority, once the report was furnished during the assessment proceedings and before completion of the assessment, the statutory purpose stood fulfilled.
The Gujarat High Court27 and Calcutta High Court28 similarly recognised that the prescribed report exists to facilitate verification by the Revenue and not to create the substantive entitlement itself and if the report is ultimately furnished during the assessment proceedings, there is no dispute regarding satisfaction of the substantive statutory conditions, delayed filing should not automatically result in denial of the deduction.
21 Shri Prithvi Cotton Mills Ltd. v. Broach Borough Municipality’, [1970 AIR 192],

Indian Aluminium Co. v. State of Kerala [1996 AIR 1431]

22 U.P. Forest Corporation And Anr. V. DCIT, 2007 (11) TMI 699 - Supreme Court

23 Association Of Indian Panelboard Manufacturer v. DCIT, 2022 (12) TMI 1414 - Gujarat High Court

24 Dilip Kumar & Co., 2018 (7) TMI 1826 - Supreme Court (LB)

25 PCIT v. Wipro [2022] 140 taxmann.com 223 (SC)

26 CIT v. G.M. Knitting Industries Pvt. Ltd, 2015 (11) TMI 397 - SC Order

27  Zenith Processing Mills v. CIT [(1996) 219 ITR 721 (Guj.)]

28  Winro commercial (India), ITAT No 237/2022
D. LOWER CORPORATE TAX RATE UNDER 115BAA/115BAB
A contemporary illustration of this debate arises in the context of the concessional tax regimes under sections 115BAA and 115BAB. These provisions permit domestic companies to avail a lower rate of tax subject to satisfaction of specified conditions and the exercise of the option in the prescribed manner through Form No. 10-IC or Form No. 10-ID, as the case may be. A recurring controversy has been whether delay in filing the prescribed form necessarily disentitles an otherwise eligible taxpayer from claiming the concessional rate. While the Revenue has generally viewed timely filing of the form as a mandatory requirement, appellate authorities have increasingly examined the substance of the taxpayer’s conduct, including whether the option was unequivocally exercised in the return of income, whether tax was computed at the concessional rate and whether all substantive statutory conditions were satisfied.
The Allahabad High Court in this context29 held that where the assessee had clearly manifested its intention to opt for section 115BAA in its return of income and audit report, delay in filing Form No. 10-IC could be condoned upon demonstration of genuine hardship, observing that a procedural lapse should not deprive a taxpayer of a substantive benefit.
Similarly, the Gujarat High Court30 condoned the delay in filing Form No. 10-ID under section 115BAB, emphasising that the filing requirement is intended to facilitate exercise of the option and that substantive entitlement should not be denied where sufficient cause for the delay exists. The Mumbai Tribunal31 went a step further and held that even the filing of an incorrect form, namely Form No. 10-IB instead of Form No. 10-IC, constituted a curable procedural defect where the assessee had otherwise satisfied all conditions and unequivocally exercised the option for concessional taxation. These decisions suggest a growing judicial inclination to treat the prescribed forms as procedural mechanisms evidencing the exercise of a statutory option rather than as conditions governing the existence of the entitlement itself.
29 Cell Com Teleservices Private Limited Versus Union of India, [2025] 176 taxmann.com 712 (Allahabad)

30 M/s. Royal Led Equipments Pvt. Ltd. Versus Chief Commissioner Of Income Tax, [2025] 174 taxmann.com 61 (Gujarat)

31 ACIT, Circle -3, Thane Versus Magik Kraft Pvt Ltd, 2025 (10) TMI 1431 - ITAT MUMBAI
E. FORM NO. 67 (FOREIGN TAX CREDIT)
Sections 90 and 91 of the IT Act confer the substantive right to claim FTC, while Rule 128 prescribes Form No. 67 as the procedural mechanism through which the taxpayer furnishes particulars of foreign taxes paid. Judicial decisions, however, have increasingly recognised that the Rule regulates the manner of claiming an existing statutory right and does not itself create the entitlement to FTC.
Several benches of the ITAT have therefore held that the requirement of filing Form No. 67 is directory rather than mandatory, particularly where the form is furnished before completion of assessment or appellate proceedings and the substantive conditions for grant of foreign tax credit are otherwise satisfied32.
32 Hertz Software India Pvt. Ltd. v. ACIT [(2022) 139 taxmann.com 448 (Bang. - Trib.),
Brinda Ramakrishna v. ITO [(2022) 135 taxmann.com 358 (Bangalore - Trib.)],
Bhagwandas Tikamdas Khinani v. NFAC, 2022 (12) TMI 357 - ITAT Mumbai,
Anuj Bhagwati v. DCIT, 2022 (9) TMI 1397 - ITAT Mumbai
F. REVISED RETURNS AND CARRY FORWARD OF LOSSES
Section 80 embodies the legislative principle that the statutory right to carry forward and set off certain losses is contingent upon timely compliance with the return filing requirements prescribed under the Act. The provision expressly disentitles a taxpayer from carrying forward specified losses unless the return claiming such loss is furnished within the time prescribed under section 139(1). The focus of the provision, therefore, is on the existence of a valid and timely loss return, reflecting Parliament’s intention to treat timely disclosure of the loss as a substantive condition for preserving the benefit.
The relationship between original returns and revised returns provides another important illustration of the mandatory-directory distinction. Accordingly, where an assessee has filed the original return within the prescribed period and has validly disclosed the loss sought to be carried forward, a subsequent revised return correcting computational or factual errors should not ordinarily result in denial of the already accrued statutory right. The revised return merely refines the contents of that return and should therefore be viewed as a procedural mechanism regulating the exercise of an existing right.
The Supreme Court’s decision in Prakash Nath Khanna v. CIT33 illustrates the circumstances in which Parliament consciously transforms a procedural requirement into a substantive statutory condition. Interpreting the expression “due time” under the Act, the Court held that a return furnished under section 139(4) cannot be equated with a return filed within the due date prescribed under section 139(1). The legislature had deliberately distinguished between timely compliance and belated compliance, attaching different legal consequences to each. The judgment, therefore, demonstrates that where Parliament expressly links a statutory right or consequence to compliance within a specified period, the courts cannot dilute that requirement by treating subsequent compliance as equivalent. The decision represents an important illustration of legislative intent converting what may otherwise appear procedural into a mandatory statutory condition.
33 Prakash Nath Khanna v. CIT [(2004) 266 ITR 1 (SC)]
TOWARDS A UNIFIED INTERPRETATIVE FRAMEWORK – THE SEVEN-FACTOR TEST
A review of judicial decisions reveals that courts repeatedly return to certain common themes when determining whether a provision is mandatory, directory or discretionary. These tests may be synthesised into a unified interpretative framework.
- First Factor – Nature of the Right or Power Involved
The first inquiry concerns the nature of the right or power affected by the provision. Requirements affecting jurisdiction, limitation or substantive eligibility are more likely to be mandatory than those regulating procedure.
- Second Factor – Legislative Purpose
The second inquiry concerns the purpose sought to be achieved. If strict compliance is necessary to fulfil the statutory objective, the provision is likely to be mandatory. If the purpose can be achieved despite procedural deviation, the provision may be directory.
- Third Factor – Consequences of Non-Compliance
The third inquiry examines whether the statute specifies consequences for non-compliance. Express invalidation generally indicates mandatory intent, whereas silence may support a directory interpretation.
- Fourth Factor – Presence or Absence of Prejudice
The fourth inquiry concerns prejudice. Where non-compliance causes no prejudice and the statutory purpose remains fulfilled, courts are more inclined to treat the requirement as directory.
- Fifth Factor – Curability of the Defect
The fifth inquiry examines whether the defect can be cured without undermining the legislative objective. Curable defects are more likely to be procedural and therefore directory.
- Sixth Factor – Public Interest Considerations
The sixth inquiry concerns broader public interests. Requirements designed to protect public revenue, prevent abuse or maintain regulatory oversight are more likely to be treated as mandatory.
- Seventh Factor – Overall Legislative Scheme
The final inquiry requires examination of the statute as a whole. No provision can be interpreted in isolation. Its true nature emerges only when viewed within the broader legislative framework.
CONCLUSION
The evolution of tax jurisprudence demonstrates a gradual but unmistakable shift away from formalism and towards purposive interpretation. Modern courts increasingly recognise that not every statutory requirement serves the same function. Some provisions confer jurisdiction, some define entitlement, some regulate procedure and others confer discretion. Treating all such provisions identically would undermine legislative intent and distort the statutory scheme.
The distinction between mandatory and directory provisions, therefore, reflects a deeper principle. The law seeks strict compliance where Parliament intended strict compliance. It accepts substantial compliance where Parliament intended procedural facilitation. It requires reasoned decision-making where Parliament intended administrative flexibility. Ultimately, the inquiry is not whether parliament has employed the expression “shall “ or “may”, but whether the requirement under consideration lies at the heart of the statutory scheme or merely facilitates its effective administration. The answer to that question determines not only whether a provision is mandatory or directory, but also the legal consequences that follow its non-compliance. The recent judicial developments reaffirm that courts will continue to preserve this distinction by insisting upon strict compliance with jurisdictional and substantive conditions while applying the doctrine of substantial compliance to procedural requirements that do not defeat the legislative purpose.