Subscribe to the Bombay Chartered Accountant Journal Subscribe Now!

ITAT holds that amendments of Finance Act, 2021 to section 43B and 36(1)(va) apply prospectively

32 Crescent Roadways Pvt. Ltd. [2021] TS-510-ITAT-2021 (Hyd)] A.Y.: 2015-16; Date of order: 1st July, 2021 Section 43B, 36(1)(va)

ITAT holds that amendments of Finance Act, 2021 to section 43B and 36(1)(va) apply prospectively

FACTS

The assessee company had remitted employees’ contribution towards PF, ESI before the due date of filing return u/s 139(1) – but after the due date prescribed in the corresponding PF, ESI statutes. For the year under consideration, the A.O. disallowed the amounts on the ground that they had been remitted after the due date prescribed in the corresponding statute, i.e., under the PF / ESI Acts. On appeal, the CIT(A) confirmed the disallowance.

Aggrieved, the assessee preferred an appeal with the Tribunal.

HELD


The Tribunal held that the legislative amendments incorporated in sections 36(1)(va) and 43B by the Finance Act, 2021 are prospective in application and are therefore applicable w.e.f. 1st April, 2021. Therefore, the disallowance of employees’ contributions towards PF, ESI for the A.Y. under consideration was not sustainable and accordingly deleted the additions made on account of such disallowance.

ITAT holds that corrigendum to the valuation report to be considered in ascertainment of value u/s 56(2)(viib)

31 I Brands Beverages Pvt. Ltd. [2021] TS-546-ITAT-2021 (Bang)] A.Y.: 2015-16; Date of order: 13th July, 2021 Section 56(2)(viib)

ITAT holds that corrigendum to the valuation report to be considered in ascertainment of value u/s 56(2)(viib)

FACTS

The assessee, who was engaged in the manufacture and sale of beverages, allotted 4,80,000 shares of a nominal value Rs. 10 per share at a premium of Rs. 365 per share following the discounted cash flow method as per the valuation report. The A.O. noted that the value per share as per projections was Rs. 37.49 per share and it was mistakenly arrived at as Rs. 374.95 per share, and therefore assessed the difference of Rs. 16.2 crores as income u/s 56(2)(viib). On appeal with the CIT(A), the assessee submitted a corrigendum to the valuation report as additional evidence, contending it to be read with the original valuation report which showed the fair market value at Rs. 374.95 per share. The CIT(A), based on a remand report called from the A.O., held that additional evidence in the form of corrigendum was not admissible and confirmed the additions made by the A.O.

Aggrieved, the assessee is in appeal before the Tribunal.

HELD


The Tribunal observed that the corrigendum to the original report was issued on account of error and it formed part of the original valuation report. It further held that the corrigendum could not be treated as additional evidence by the CIT(A) and therefore there was no reason to reject it. The Tribunal holds that the corrigendum and the original report shall constitute the full report to be examined by the A.O. and accordingly remits the matter to the A.O. for determination of value per share.

DIGITAL WORKPLACE – A STITCH IN TIME SAVES NINE

Till the beginning of the year 2020, working from home instead of travelling a couple of hours daily to office was looked upon as just an excuse by employers. The major change in work style that we saw in 2020 was a paradigm shift from the physical workplace to the digital workplace. The pandemic and lockdowns all over the world forced people to work from home, or stay without working. While initially it seemed almost impossible for firms to survive in a digital environment, all of us have coped quite well.

Clearly, the pandemic is proving to be a blessing in disguise for firms at all levels. Those in the service industry realised that a Zoom call could replace travelling, they were not required to travel to the office daily and, most importantly, it has resulted in huge cost savings on real estate. Of course, physical meetings and the ‘office culture’ won’t be replaced by the complete digital workspace and irrespective of what we call the ‘new normal’, it is believed that once restrictions are over, people will get back to the normal office and physical workplace. But life and office culture will never be the same again. Even if the digital office will not replace the physical office, there is no denying that it will change the way we look at our office and no one can afford to ignore it. To understand this even better, let us first understand the concept of the Digital Workplace.

WHAT IS A DIGITAL WORKPLACE?

Initially, the Digital Workplace was meant to complement the physical office. The idea was to facilitate easy working for employees who may have difficulties in travelling or are working from different locations. However, most people used to travel for even the slightest work, or for meetings, and the ‘9 to 5’ culture was at its prime with employees expected to reach the office physically to be counted as working on a particular day. Remember the struggle we put up with when it was raining just to reach office safe and dry, or come back walking (or rather, wading) during the deluge of 26th July, 2005 in Mumbai? For the last few years, companies have been spending money on technology and remote working but still always expected employees to travel to the office unless it was not possible. However, 2020, the pandemic year, has changed everything. With no scope to travel to the office, everyone was literally forced to adapt to remote working. The proof of the concept was put to use and now businesses have started operating at full capacity at the Digital Workplace.

A Digital Workplace is the basic set of digital tools that employees use to get work done. These include Instant Messaging apps to Meeting Tools and online storing of documents, and even automated workflows to manage the work. Essentially, ‘the Digital Workplace is the virtual, modern version of the traditional workplace where work can be done through devices, anytime, anywhere’.

However, let’s see what a Digital Workplace is not. It is much more than having apps as a part of office workflow. It is more than accessing office files from anywhere. But when the flow of work and monitoring of performance to get measurable results are seamlessly integrated, we can see the Digital Workplace emerge. It starts by understanding what it really is and how it can help your organisation deliver measurable business value.

Why shifting to a Digital Workplace will help an organisation and employees

  •  Talent attraction: A survey1 says that over 60% of employees would not mind being paid less if they get flexibility to work from anywhere. People have started realising the importance of staying at home and spending time with the family, getting those extra few minutes of sleep as they don’t need to rush to catch a train / bus to the office, and so on. Additionally, Work from Home (WFH) means employees can afford a bigger house at a better location rather than fitting in a smaller house to avoid travelling for work daily, or maybe even have a Staycation working with laptops while sipping ginger tea at Shimla!


  •  Improved inclusivity: The one good part of opting for a Digital Workplace is that we can have talent without geographical barriers. With a physical workplace, we were restricted to hiring talent within our cities. But now, someone with an office in Mumbai can hire talent from Delhi or Dubai. The physical location of the employee, except for the time zone, hardly matters.


  •  Economical: Having a Digital Workplace is economical not only for firms, but also for employees. While firms can save on real estate rents, electricity, stationery and support staff to facilitate working at the office, for employees the savings come as reduction in transportation costs, parking charges, travelling time, need for spending on professional wardrobes, lunch and dinner, the need to eat outside and so on.


  •  Less stress of commuting: One of the biggest worries for people living in big cities in India and all over the world is commuting. While many countries have the best of infrastructure, India is still developing the same and incidents like the 2017 stampede at Elphinstone Road railway station during rush hours may be terrifying, but these are a regular risk of travelling on local trains in metro cities. Besides, commuting in public transport exposes employees to the risk of losing their valuables, including office assets, due to theft or damage on account of extraordinary rush on a frequent basis.


1   Business Line


WHAT SHOULD YOUR DIGITAL WORKPLACE INCLUDE?

Technically and practically, a Digital Workplace should include all the technology tools that we need to operate in our profession. These tools should broadly take care of four categories of work: how your employees can communicate, how they can collaborate, how they can connect and how they can deliver the final services and evaluate the work done. Let us take a closer look at each of these:

1. Communications at a Digital Workplace:

We aren’t in a place now where we can meet at the cafe or share ideas at the water cooler in the office. Considering these restrictions, it becomes important that while we have a Digital Workplace we also give employees freedom to communicate which they would have otherwise done at the office. In fact, with a DigiWorkplace around, the communications aren’t restricted to a team or a location. Employees in Mumbai can also communicate with those in Delhi. The basic communication tools should include the following:

  •  Emails – Currently, Google Workspace is very widely used for emails. However, there are many other players like Outlook and the Indian Zoho. Each of these offers its unique advantage over the others. But Gmail, since it gives auto integration to other widely-used apps like Google Drive, Google Photos and Android Phones, has become more popular amongst users. Gmail also provides its search functionality to its email, which means that searching past emails with Gmail is always faster. Though all these companies do provide their free email accounts, it is always advisable to buy a company domain (@yourcompany.com or .in, etc.) instead of using standard emails like ‘@gmail.com’. These are paid services but the company domain always gives a better impression. Besides, all the companies provide additional services for paid versions vis-a-vis free versions.


  •  Instant messaging apps – A Digital Workplace will definitely need an instant messaging app wherein the employees can keep working while having chats on their queries going on. One of the most common messaging apps that comes in handy with Gmail is Google Hangouts. The whole purpose of such instant messaging apps is to facilitate official messages, calls and video calls so that our personal space on WhatsApp or any other personal app isn’t disturbed. Another app which has found its market in the corporate world for instant messaging is ‘Slack’ which comes with all features of instant messaging, calling and video calling. One good part about Slack is that it can be integrated with almost all the other apps and portals.


  •  Other basic communications – Other basic communication toolkits at any Digital Workplace would include customised portals or intranet which may have options to publish news, have blogs or articles, introduce new employees, celebrate birthdays, etc., such as ProofHub, a project-planning software with tools like discussions, notes, Gantt charts, to-do lists, calendaring, milestones, timesheets, etc. Such intranet communication software if implemented well, can solve a lot of communication shortcomings of the Digital Workplace.


2. Collaborations at the Digital Workplace:

To solve business problems and operate productively, organisations must have the ability to leverage knowledge across the enterprise with online, seamless, integrated and intuitive collaboration tools that enhance the employees’ ability to work together. A collaboration toolkit at the workplace should include:

  •  Productivity is a collaborative tool that can’t be ignored. Having tools which can enhance productivity of employees can help them to enable knowledge and perform their work more efficiently. A Digital Workplace should have tools which can help all employees to collaborate on projects / files together. These can include a common drive, word processors, live spreadsheets, presentations, CRMs. Google WorkSpace does give an option for all of these in one place.


  •  Business Applications – To make it easier to collaborate, a Digital Workplace should have basic business applications where employees can work simultaneously. An HR system like FreshTeams which is accessible both on portals and on mobiles indeed suffices as an end-to-end HR function. From on-boarding to maintaining documents and to managing approvals, FreshTeams has us covered for everything. Managing employees’ expenses is another worry that we may face while having a Digital Workplace. However, Expensify is one software that can indeed be very useful. Other business applications that are a must-have for a Digital Workplace include ERPs and CRMs like Tally, SAP, QuickBooks and the recent favourite Zoho.

3. Connect:

Self-sufficiency no longer guarantees effectiveness. Employees need tools that allow them to connect across the organisation, leverage intellectual property and gain insight from one another. The Digital Workplace delivers on these goals by fostering a stronger sense of culture and community within the workplace.

Connectivity apps or data in general help employees to know each other’s profiles, their locations, expertise, etc., to reach out easily. A basic data should include employee directory, organisation chart and rich profile.

4. Deliver the result:

The phrase ‘meet your customer where your customer is’ can take a whole new meaning with a Digital Workplace. While face-to-face interactions delivering reports or presentations have gone for a toss, there are still ways to provide your clients with the same sentiments. Professionals may shift to virtual communication networks like Google Meet, Webex, Zoom, Zoho Meetings, etc. As we deliver results in virtual form, we share some tips to have the same level of interaction as in the physical form:

  •  Hold all the meetings, whether internal or external, on video. You need not keep your video off. Having videos turned on during meetings gives a personal touch;

  •  Send emails or catch up casually with inactive clients to let them know you are still thinking about them and their business;
  •  Try and accommodate to the apps that your clients use so that they do not have to struggle in meetings;
  •  Practise – This is one quality that should always remain, irrespective of whether the presentations are online or offline. Practise screen-sharing, slide moves and presentation flow on how it may look on the communication networks while delivering the same to the client.

LIMITATIONS OF DIGITAL WORKPLACE:

While we see giant leaps in the Digital Workplace, it has its own drawbacks. There are platforms that specialise in making collaboration easier and more effective, but the most important component which is missing in the Digital Workplace is ‘social interaction’. It is not merely limited to non-verbal communication where there are no feelings while reading chats / emails, but a Digital Workplace literally means that staff does not spend quality time together like being in office, so the chances of having team bonding are less. This, too, can lead to communication difficulties since misunderstandings are more likely.

Another sad part is the fact that we are used to seeing employees and colleagues face-to-face, or in real face-time. As far as possible, employees should also meet in person from time to time and use the video call function for important meetings. When an actual meeting is not possible, it is advisable to arrange a video call at least once a month without an official agenda to have team bonding.

CONCLUSION


The way the Digital Workplace is evolving, it may not replace the existing physical office or completely do away with it. We are seeing that companies have already started calling their employees back to offices and soon ‘Work From Home’ may not be available to all. But what this pandemic has shown us is that it is possible to work from home and that there are both advantages and limitations of working from home, but with technology evolving, things are getting better and better. We believe that even if we may not move to a compulsory ‘Work From Home’ culture anytime soon, travelling will become optional and companies will give optional WFH to their employees for a few days in a month. Above all, from the firm’s point of view, the Digital Workplace will become more important as it will be able to cater to the workforce from all over the world without having to spend additional sums on their relocation, etc. Besides, a foolproof Digital Workplace system means the firm can outsource routine and monotonous work to people at remote locations at much cheaper rates and it may work like the Knowledge Process Outsourcing (KPO) model.

In our articles over the next few months, we will also be discussing other considerations for having a Digital Workplace that shall include:

  •  Comparisons between a Physical WorkPlace vs. a Digital Workplace vs. a Virtual Workplace vs. Co-Working Spaces;
  •  How we can manage various functions of our firm – HR, Finance, Marketing, etc., using our Digital Workplaces;
  •  Interviews with industry leaders and practical examples of Digital Workplaces.

(The authors of this article are in no way connected with or influenced by any of the apps or portals mentioned herein, except that they are users. The apps and portals mentioned are recommendatory as they have been useful to us)

COVID IMPACT ON INTERNAL CONTROLS OVER FINANCIAL REPORTING

Yes, you read it right. Just as humans are affected by Covid, internal controls over financial reporting, too, are affected by Covid. As we all know by now, Covid attacks when the immune system is weak. Similarly, operations, and therefore the performance of companies, get affected when their internal controls have deficiencies and weaknesses. When the tide will go down is uncertain. But there are many interrelated implications on financial reporting arising from the pandemic. The way of carrying out operations has changed significantly for a lot of companies either due to the nature of their own operations, or due to the impact felt by their suppliers or customers.

This article highlights how Covid might have impacted the internal controls of companies. Needless to say, when the internal controls have been affected by the pandemic, the auditors of such companies need to consider its impact on their reporting on the adequacy and operating effectiveness of internal controls with reference to financial statements as prescribed u/s 143(3)(i) of the Companies Act, 2013.

The pandemic has hit all organisations globally and India is no exception. Considering this, the Securities and Exchange Board of India (SEBI) issued a Circular dated 20th May, 2020 encouraging listed entities to make timely disclosures about the impact of Covid on their companies. One of the items in the list of information that the Circular states listed companies may consider disclosing is internal financial reporting and controls.

The users of the financial statements, various stakeholders, including investors, lenders, suppliers and customers, Government agencies and so on, are keen to know to what extent the company has been affected by the pandemic. As stated in the ‘Guidance Note on Audit of Internal Financial Controls over Financial Reporting’ issued by The Institute of Chartered Accountants of India (GN on IFC) for the purpose of auditor’s reporting u/s 143(3)(i) of the Companies Act, 2013, ‘internal financial controls over financial reporting’ shall mean ‘a process designed to provide a reasonable assurance regarding the reliability of financial reporting and the preparation of financial statements for external purposes in accordance with generally accepted accounting principles.’ Therefore, to prepare reliable financial statements, internal controls over financial reporting are imperative. If such internal controls are affected by Covid and if the company has not taken adequate steps, the financial statements prepared may not be reliable for external purposes and the stakeholders will lose confidence in the entity’s financial reporting. From the governance perspective, it is important for the Audit Committee and management that new processes for financial statements closure and reporting of results and financial / operational controls are appropriately documented.

EXTENDED REPORTING TIMELINES

SEBI has given extended timelines to listed entities to report their results in 2020 as well as for the 2021 year-end. This was brought out considering that companies were facing challenges to complete the preparation of financial information due to the impact of Covid on their people and processes. However, the question is was the challenge faced by the companies related only to reduced manpower at work to complete the tasks, or did the company effectively use the additional time to ensure that its procedures as required by its internal control framework were completed like in any other year? If it is the latter, it will show how the company is impacted by Covid, how it has assessed such impact and reacted to it. But if the companies have used the extended timeline for slowing down the pace, it shows that the company has not assessed the impact of Covid on its processes.

IMPACT ON FINANCIAL CLOSURES


The shift to remote working is testing the operational endurance and the resilience of critical processes across companies. The financial close is no exception which is facing multiple problems in conducting an efficient and effective close process. The financial closure process of a company is a combination of various documents and components. As explained in the GN on IFC, control activities may be categorised as policies and procedures that pertain to:
(A) Performance reviews
(B) Information processing
(C) Physical controls
(D) Segregation of duties

(A) Performance reviews refer to overall analytical procedures of actual performance with budgets, forecasts, etc. However, it is very likely that the budgets, forecasts, prior period actuals, etc., did not include the impact of Covid at all, or had considered its impact based on information available at that time. In the absence of the robustness of a performance review, what controls does the company need to establish to ensure the reliability of financial information? Let’s understand this by way of an example. A company manufactures white goods such as dishwashers, washing machines, etc. Its volume of production in a given period is predictable as the company had established its plant many years ago. For F.Y. 2019-20, the company was able to run its normal operations throughout the year, except the last week near the year-end due to the lockdown. However, in F.Y. 2020-21, the lockdown was extended and therefore production was completely shut for part of the year. While reviewing the performance of F.Y. 2020-21 and comparing the same with the previous year, the variance can be quantified for that attributable to the period when the plant was shut.

(B) Information processing controls are application controls and general IT controls. Before Covid, these controls were usually based on the assumption that applications were being accessed by users through LAN. This identifies the user and has security firewalls to protect the data in the system to ensure its reliability. In the period of the pandemic, where many organisations had to close their offices and allow employees to work from home, IT systems are being accessed by employees through their home networks. The reduced number of employees may result in reduced controls being adhered to. Vulnerability of security for data protection and its unauthorised access pose a significant threat to the reliability of the financial close process. Further, there is heightened risk of data leakage. For example, a company has IT security through which tenders submitted by potential suppliers can be accessed by the procurement department only through the office LAN. During Covid, when staff is working on their home networks, such control cannot be implemented and needs to be modified without compromising on the security of the data. IT processes or controls that have an increased volume or that need to be performed differently due to changes in work environment or personnel, are likely to have additional risks in areas such as the following:

Access termination – Increased number of access termination requests and fewer people available to process them – this may increase the risk of unauthorised access due to terminated personnel not being removed in time. In many organisations, there is an exit form which the employee fills and after approval from the HR it is handed over to IT to ensure that all access given to that employee is terminated and confirmed by IT by signing the same form showing the date and time of termination. In the Covid scenario, the exiting personnel, HR staff and IT staff are all at different locations. To ensure coordination amongst them for terminating the access immediately when the employee leaves, different controls need to be put in place.

Change management – Verbal approvals may be accepted rather than waiting for approvals to be documented through a ticketing system, and thus there may be increased use of emergency IDs which may not be subject to the same degree or timeliness of monitoring as usually occurs. Whenever any change is required in the IT environment, many companies have a hard copy documentation system showing the requester, the approver and details of the changes made, followed by subsequent testing and implementation. During Covid, such hard copy documentation may not be possible given that the requester, approver, programme writer, testing team and implementation team are at different locations. This may require modification of the existing IT change management controls.

Execution of review controls – The questions to be answered are:
(a) What changes are made to the review process of access control, change management and other IT environment processes?
(b) To what extent are the company’s IT risks affected by the new way of working and what are the mitigating controls introduced to deal with the security threat to the IT systems that process financial data?

Many organisations are changing their strategies to take advantage of digital technology, such as storing data on cloud which can be accessed from anywhere by the authorised personnel. Even if the employee working on such data is not able to access the company’s server from her remote location, such data need not be copied on the workstation of the employee when it is available on cloud. With such changes in strategy, it is obvious that the relevant risk control matrix of the company will undergo a change. The new risks identified will be because the majority of employees are working from different locations. Controls to mitigate such risks, for example, data security risk as discussed above, will be plotted against each of such processes.

(C) Physical controls relate to the existence of assets and authorisations for their access. In the Covid scenario, such authorised person holding custody of the physical assets is away from the office or location of the assets for prolonged periods. How does the company ensure the existence of its assets when the person entrusted with their physical custody no longer has their custody? How has the company changed its internal controls which earlier were physical controls? For example, during partial lockdown, earlier internal controls might have been modified in respect of frequency of physical verification, the authority performing such verification, etc. Such modified controls may also consider any new digital technology implemented by the company or any supplemental controls to the original pre-Covid controls.

Safeguarding inventory
Safeguarding inventories is the responsibility of the management which is required to establish procedures to ensure the existence, condition and support valuation of all inventory. There may be transactions as at the yearend where the company has transferred the control of assets, but where physical possession is with the company such as bill-and-hold arrangements. The internal control framework relating to safeguarding and monitoring of inventories would need to include these considerations, e.g., assessing the inventory shrinkage by location, product type, or other disaggregated basis, comparing the actual inventory value of each location to an expected range, and investigate any individual locations that are outside of the expected range.

Further, with scenarios like localised lockdown, travel restrictions, etc., physical inventory counting would be challenging and in some cases impractical. In certain situations where the conventional method of physical verification is not practicable, management may establish internal controls to undertake physical verification remotely via video calls with the help of technology.

Environmental and safety norms
Companies may be using sensitive chemicals and industrial gases for producing goods. Some of these items are required to be stored in temperature-controlled containers and to be continuously monitored. If there is any leakage of hazardous gases or chemicals, the implications on the company could be very severe and even lead to closure of the factory, thereby affecting the going-concern assessment. Localised lockdowns imposed by various State Governments might induce stress on the monitoring mechanism relating to compliance with environmental and safety norms.

(D) Segregation of duties as a control was put in place by companies to ensure that employees preparing the information, authorising the information, recording the information and holding the custody of the documents are different. In the Covid scenario, the flow of physical documents to different employees performing these different roles is not possible. Further, many organisations had severe staff absences for prolonged periods as even the staff was affected by the pandemic. This requires delegating their responsibility to other staff and modifying internal controls around it. Has the company modified its internal control system and does the revised internal control system ensure effective segregation of duties, this is the question that companies need to answer.

Fraud risks
Fraud risks change in such a time of crisis, as new opportunities are created for internal as well as external parties. Incentives for committing fraud – both misappropriation of assets and financial reporting fraud – may also be heightened, especially if significant terminations are likely or employees suffer significant personal financial stress. As stated in the GN on IFC, ‘When planning and performing the audit of internal financial controls, the auditor should take into account the results of his or her fraud risk assessment.’ In the years when the company is hit by the Covid pandemic, fraud risk assessment of the auditor is expected to be different from the earlier years. The risk of fraud has increased significantly due to changes in the way of working. Such risks can range from the basic documentation process where scanned documents are being relied upon, which can be forged, as against the original signed documents; to frauds in complex transactions where significant estimation is involved such as fair valuation, etc., since these estimates are also significantly impacted by Covid. Some of the areas where fraud risk has increased are:

(i) Physical document approvals are replaced by email approvals in the Covid period. Such approvals carry the risk of emails being compromised.
(ii) Due to the new style of working, the demand for certain goods and services has significantly increased. This has created an opportunity in procurement fraud.
(iii) Owing to lockdown situations, many customers may be facing financial difficulties to pay their dues within the credit period. This increases the risk of financial reporting fraud by resorting to unethical means of recording receipts from debtors which are not genuine.

The auditors, while planning and performing the audit of internal financial control, will need to take into account as well as document how their audit plan is different from the earlier years due to higher risks of fraud, i.e., what is their audit response to such risks.

ASSUMPTIONS FOR THE FUTURE
Ind AS 1 requires the entity to disclose information about the assumptions it makes about the future, at the end of the reporting period, that have a significant risk of resulting in a material adjustment to the carrying amounts of assets and liabilities within the next financial year. In the Covid scenario, the future holds a lot of uncertainty and it will need the company to demonstrate its internal controls for arriving at the estimates, or its estimation process. It may have an impact inter alia on going-concern assessment, impairment of assets, fair valuation, etc., that is, financial statement items that are based on assumptions of the future. Companies faced difficulties in estimating the impact of Covid on their operations beyond the short term. This is an inherent risk because of uncertainty about the future which was never experienced before in history and has resulted from the global pandemic. Due to the disrupted supply chain and distribution models, uncertainty over pricing, etc., projecting future cash flows with acceptable precision is not possible for many companies. Coordination with management experts, such as those heading the strategy department, valuation specialists, etc., when performing impairment tests, assessing fair values of assets such as investment properties, investments, etc., and performing actuarial calculations and analyses, can be more challenging. Many auditors have considered these matters as key audit matters for their audit of the financial year ended 31st March, 2021. The question is do internal controls over the estimation process of the company consider the uncertainty brought by Covid?

Exceptions identified during control testing
It is likely that management will identify exceptions during its testing of controls because controls were designed for a totally different environment. To ensure that sufficient time is available for remediation before the year-end, management will need to modify the design of existing controls and test the operative effectiveness of the new controls during the year. If such remediation does not take place by the year-end, it will have consequences of communication with audit committees and modification in the auditor’s report. Further, in the absence of controls being effective, auditors may need to modify their strategy to evaluate the impact of ineffective controls. Therefore, companies should change their plan of testing controls affected by Covid earlier than usual in the year. If the company has had to incorporate new controls during the year, these controls should be documented in its internal control documentation and appropriately tested.

Planned changes in RCM
Each entity’s internal controls will be uniquely impacted by Covid, e.g., entities with significant dependence on technology will have different challenges to address than those with a more manual control environment. With a majority of staff working from home, manual controls maintained through hard copy documents cannot be adhered to. Technology-dependent controls may need revision with new technology suitable for the new environment. Hence, it is imperative that on a holistic basis the potential changes or shifts in focus, both in terms of scoping and risk assessment, testing approaches, etc., are made and additional controls or control modifications of existing controls are undertaken to address the risks arising from Covid. Based on the experience of Covid, companies will start making changes in their risk control matrix. It will include identification of additional risks posed by Covid, new controls to mitigate those risks, modification to existing controls in view of the ‘new normal’ and removal of some controls which have become redundant. This might include automation of all key manual controls to reduce dependency on people and physical access to the work environment, increased use of continuous monitoring and detection and defining indicators which would suggest that controls may not be operating effectively.

Changes to the design of management’s control may also require the auditor to alter the combination of testing procedures (i.e., inquiry, inspection, observation and re-performance). This includes making inquiries on the changes in the company’s mode of carrying out operations in response to Covid. For example, changes due to people working remotely, and consequently the change in the company’s policies and procedures, including execution of controls, segregation of duties, etc. This would also include evaluating the electronic or digital evidence made available by management, and the controls around the same, specifically with reference to review, reliability, security and storage of such evidence by the management.

Enhancing disclosures
The pandemic would also have wide-ranging implications on the financial statements. Hence, it is crucial that the management adequately presents their ‘side of the story’ in detail. Disclosures might include entity-specific information on the past and expected future impact of Covid on the strategic orientation and targets, operations, performance of the entity as well as any mitigating actions put in place to address the effects of the pandemic. Updating the information included in the latest annual accounts to adequately inform stakeholders of the impact of Covid, in particular in relation to significant uncertainties and risks, going-concern, impairment of non-financial assets and presentation in the statement of profit or loss, have garnered renewed focus.

SNAPSHOT
In short, the way Covid has impacted internal controls over financial reporting of companies is as follows:
a) New normal – The way companies carry out day-to-day transactions from initiation to closure that involves authorisations, recording, cash receipts or payments, etc., has changed. Given that these processes have undergone changes, all pre-Covid controls may not be relevant and new controls may be needed.
b) Risks change due to Covid – Not only are the new processes susceptible to new risks, but existing risks may also be heightened due to the change in the environment. In addition to this, there are certain inherent risks of dealing with the ‘unknown’, i.e., how long the pandemic will continue, what will be its severity and the resulting impact on the organisation, etc.
c) Controls must also change accordingly – Companies will need to thoroughly review their risk control matrix in light of the new risks. It will require addition of new controls (e.g., those relevant to new technology), changes in the existing controls (such as approval process through emails or physical verification of assets through virtual means, etc.), or removal of some of the irrelevant controls (like those related to physical documentation).
d) Audit of internal controls over financial reporting – With the new risk-control matrix, the auditors will need to plan their integrated audits in light of the changed processes of the client, the revised design of controls and testing their operating effectiveness. The auditors will need to evaluate ‘what could go wrong’ with increased audit scepticism considering the high fraud risk in the new reality, the risk of non-compliance with laws and regulations, the impact of uncertainty on the estimation process of the company, and so on.


NEXT STEPS

Companies establish criteria for internal controls over financial reporting. These are dynamic in nature and as the circumstances change, companies need to revisit internal controls on identified risks. The impact of Covid will require them to relook at their existing criteria and identify what changes are required to be carried out to achieve the objective. Many companies have prepared their own checklists to ensure that the internal controls criteria are updated based on the current environment.

At the same time, auditors need to be aware of what changes are being carried out by their clients in their criteria for internal controls and plan their audits accordingly. This may require the auditor to obtain samples of the period when operations were severely affected by Covid (and  therefore have a modified design of internal controls) and when operations were running normally.

A dialogue between the clients and auditors is imperative to discuss the exceptions observed in management testing, changes being made in internal controls, effective date of incorporating the changes, plan of management testing of such controls and ensuring that those are operating effectively.

(The views expressed in this article are the personal views of the author)

VALUATION OF CONTINGENT CONSIDERATION

The billion-dollar acquisitions that we read about, especially of early-stage companies, raise the question, how do deal makers arrive at the deal price? There is seldom a transaction wherein the buyer and the seller would agree on the future outcome of certain critical parameters which could be a point of negotiation, or even the cause of some potential deals falling through with the two parties unable to reconcile on the deal price. It is contingent consideration that helps in breaking this deadlock between two parties because it enables the buyer to pay a part of the deal price to the seller only on the achievement of certain pre-agreed critical milestones. While such contingent consideration is commonly observed in M&A deals, there are several complexities when it comes to the valuation aspects of such consideration.

1. INTRODUCTION TO CONTINGENT CONSIDERATION

Ind AS 103, Para 37 requires the consideration transferred in a business combination to be measured at fair value which is to be calculated as the sum of the acquisition-date fair value of assets transferred by the acquirer, the liabilities incurred by the acquirer to the former owners of the said business, and the equity interests issued by the acquirer. In fact, contingent consideration is one of the forms of consideration as described in Ind AS 103 and it has to be recorded at the acquisition-date fair value as a part of the total consideration. Contingent considerations are typically employed in transactions to bridge the valuation gap between the buyers’ and the sellers’ differences of opinion regarding the target entity’s future economic prospects. It helps to get the buyer and the seller on the same page when it comes to the valuation of the target entity. Let us examine this basic concept by way of an example:

Company A intends to acquire Company B. Company B has just introduced a new product line that is expected to generate significant sales. Company B’s owners have projected a significant amount of sales from the proposed product line and are considering the same to influence the deal size. Company A, on the other hand, believes that there is a risk of uncertainty in the achievement of targets contemplated by the seller and hence there is a disagreement on the deal valuation. By incorporating a contingent consideration clause in the purchase agreement, the seller accepts part of the business risk along with the buyer and also participates in any upside post-transaction.

Contingent consideration may be contingent on different events, for example, on the launch of a product, on receiving regulatory approval, or reaching a certain revenue or income milestone. The achievement of such events often spans over more than a year. Thus, it is necessary to understand the acquisition date as well as the post-acquisition treatment of such contingent consideration.

2. CLASSIFICATION AND MEASUREMENT OF CONTINGENT CONSIDERATION

2.1 Liability vs. equity classification
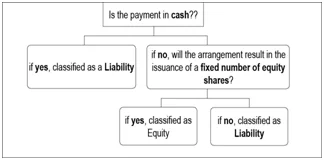
The classification of consideration is essentially driven by the mode of settlement of such consideration. Consideration settled in cash is always classified as a liability. In a scenario where the consideration is to be settled by issue of certain instruments of the buyer, one needs to determine whether the number of instruments to be issued are fixed and determined at the acquisition date. In a scenario where the number of instruments is fixed, then such consideration is classified as equity, and where the number of instruments to be issued is not fixed, then such consideration is to be recognised as a liability. Refer to Figure 2.1.1 for a simplified approach to determining equity vs. liability.

Figure 2.1.1: Classification of contingent consideration

Example: A fixed monetary amount to be settled in a variable number of shares would be classified as a liability.

Contingent consideration classified as a liability is required to be re-measured at its fair value at each reporting period. For example, a consideration depending on revenue achieved over the next three years from acquisition will need to be fair-valued at the end of each year / quarter. Whereas, a consideration classified as equity is not required to be fair-valued post the initial recognition since the consideration has already been determined and locked as at the acquisition date.

3. VALUATION OF CONTINGENT CONSIDERATION / EARN-OUTS

The methods to be followed and the approach will be driven by the way the payment of such contingent consideration or earn-outs is structured. The pay-outs are structured based on a single or more than one metric. The Table below illustrates the various metrics which are commonly observed for contingent consideration:

Financial matrices

Non-financial matrices

Revenue

Gross profits

EBITDA

Profit before tax

Cash flows targets

Stock price

Result of clinical trials

Software development / R&D milestones

Employee retention targets

Customer retention targets

Closing of a future transaction

Number of units sold

Mostly, contingent consideration is paid on achievement of certain revenue or profit targets. Additionally, such payments may be spread over more than just one year. The pay-outs can either be linear pay-outs or non-linear pay-outs.

3.1 Linear pay-outs
Pay-outs which are dependent on a single metric and are expressed in terms of a fixed percentage or the product of a financial or some non-financial parameters, are referred to as linear pay-outs. Considerations that vary based on different levels of revenue or other parameters are non-linear pay-outs. For example:

Target will receive a payment at some future date as follows:

  •  If EBIT < $1 million, the payoff is zero;
  •  If EBIT = $1 million, the payoff is a 10x multiple of EBIT.

The valuation method will be driven by the structure of the contingent consideration pay-outs. There are two broad valuation approaches used to value a contingent consideration.
i) Probably weighted expected return method, more commonly referred to as ‘PWERM’, or scenario-based method (‘SBM’); and
ii) Option pricing method, also referred to as the ‘OPM’.

3.1.1 Probably weighted expected return method (PWERM)
The PWERM assesses the distribution of the underlying matrices based on estimates of the forecasts, scenarios and probabilities. The pay-out computed is then discounted to present value using a discount rate corresponding to the risk inherent in the inputs considered while computing the compensation. The following are the steps followed:
i) Estimate scenarios of outcomes and associated probabilities.
ii) Compute the expected payoffs using the scenario probabilities.
iii) Discount expected payoffs to present value using risk-adjusted discount rates.

Illustration 3.1.1.1

• INR 100 crores payment contingent upon obtaining FDA approval.
• Approval expected in one year.

Solution:

Particulars

Payment

Probability

Prob.-weighted payment

Approval
obtained

Approval
obtained

INR
100

INR
0

75%

25%

INR
75

INR
0

Total

Discount
rate

Present
value factor


100%

10%

INR
75 crores


0.91

Fair
value of contingent consideration

INR
68 crores

Advantages:
i)    Management controls scenarios and probabilities: The scenarios and probabilities are generally prepared by the management because they would be the best source for such data points.
ii)    Understandable: The computation and the flow are understandable to a reader with basic financial knowledge.
iii)    Flexible: The model can be structured to fit most pay-out scenarios.

Disadvantages:
i)    Management controls scenarios and probabilities: While this has been discussed under advantages, management control over these inputs is also counter-intuitive since management tends to be overly optimistic or pessimistic in its assumptions.
ii)    Lots of subjective assumptions: Most of the methods / inputs are subjective and involve judgement, which at times is not the most ideal approach to value such pay-outs.
iii)    Discount rate: Since the methods involve multiple scenarios, it is challenging to estimate the appropriate discount rate.
iv)    Path dependencies: Pay-out scenarios which are path dependent, i.e., the result of one scenario is related to one or more dependent scenarios, are difficult to model in the PWERM. It can lead to multiple nodes and is prone to errors.

3.2 Non-linear pay-outs
Non-linear contingent considerations are either not strictly linear, or they pay a fixed amount based on a milestone correlated with the broader economy; thus, they require an OPM as their complexity and discounting cannot be adequately captured in a PWERM; for example, if the buyer pays INR 50 crores if EBITDA is at least INR 75 crores in the first three years, or if the buyer pays 40% of revenues above INR 50 crores in year two, subject to a maximum of INR 40 crores. Another, more complicated, example: The buyer pays 40% of revenues in years one to three, subject to a minimum of INR 10 crores and a cap of INR 40 crores. In such an arrangement, a PWERM will not work since it’s impossible to adjust the discount rate to align with the risk of such a complex pay-out structure. An option-pricing model is generally used to value such arrangements.

3.2.1 Option-pricing methods
The payoff structures for contingent consideration arrangements that have a non-linear structure are similar to those of options in that payments are triggered when certain thresholds are met. Accordingly, some option-pricing methods may be appropriate for valuing contingent consideration that have a non-linear payoff structure and are based on metrics that are financial in nature (or, more generally, for which the underlying risk is systematic or non-diversifiable). The OPM is implemented by modelling the underlying metrics based on a log-normal distribution that requires two parameters:

* The expected value: The management expectation of the matrices over the term of the arrangement. This is generally provided by the management.

* The volatility (standard deviation) of the metric: The volatility of the metric measures the potential variability from the expected value. This is generally determined by using market-based data. However, volatility for financial metrics like revenue and EBITDA cannot simply be computed using the movement in stock prices of the comparable companies. It needs to be appropriately levered and unlevered to capture the variability in achievement of the metrics.

There are two widely used option-pricing methods, viz., the Black-Scholes Model (‘BSM’) and the Monte Carlo simulation model.

3.2.1.1 Option-pricing method – Black-Scholes Model
BSM treats a pay-out arrangement just like an ordinary option which enables use of the standardised Black Scholes – Merton formula. This approach can work for simpler pay-out structures, for example, if the selling shareholder earns the pay-out only if the target metric hits a threshold, or for linear pay-outs with caps or floors. The consideration is assumed to represent a call option on the future performance of the seller.

Illustration for BSM
Earn-outs are contingent upon the target of achieving a benchmark EBIT of INR 11,25,000 within three years. The EBIT is currently INR 10,00,000. At the end, the acquirer will pay additional consideration equal to the excess EBIT over the benchmark.

The discount rate is 10% and the risk-free rate is 3%. Volatility of earnings is 14% based on historical EBIT.

The inputs to the Black-Scholes Model for this example are:

i)    The current INR 10,00,000 level of earnings is the value of the underlying,
ii)    the benchmark of INR 11,25,000 serves as the exercise price,
iii)    the term is three years,
iv)    the volatility is 14%,
v)    the risk-free rate is 3%, and
vi)    the dividend rate is 0%.

Based on the above inputs, calculations for the Black-Scholes Model can be incorporated into an Excel spreadsheet. The resulting call option value of INR 84,413 will be the value of the contingent consideration.

3.2.1.2 Option-pricing method – Monte Carlo Simulation Model
For more complex structures, a Monte Carlo simulation is preferred. Arrangements that pay over multiple periods or multiple metrics are subject to combined caps or a floor. A Monte Carlo simulation considers the correlation between matrices and pay-outs over multiple periods. The Monte Carlo simulation repeats a process many times attempting to predict all the possible future outcomes. At the end of the simulation, several random trials produce a distribution of outcomes that can be analysed. Random numbers are used to measure possible outcomes and the likelihood of their occurrence. Generally, simulation software are used to generate random numbers. These random numbers are generated based on the applicable distribution driven by the metric triggering the pay-outs.

The following are the important considerations of key inputs for valuing contingent considerations using an option-pricing model:

Discount rate applied based on risk of target metric
For earn-outs that require this kind of discount rate, either the top-down or bottom-up approach may be used to develop the rate. These approaches are well known in the valuation field. They rely on the concept of beta (ß), which reflects the level of market risk reflected in an instrument.

In the top-down approach, ß is based on the deal’s rate of return adjusted for the difference in market risk between the target metric and the overall enterprise value. Adjustments can reflect many relevant factors, such as the general risk in the target metric, leverage, term, size premium and entity-specific risk. In the bottom-up approach, ß is the target metric adjusted for term, size, entity-specific risk and other relevant valuation factors. The bottom-up approach may rely on statistical analysis of the target metric from the entity or its peers.

Volatility
Valuation techniques that rely on options modelling or Monte Carlo simulation require a volatility of the target metric. There are four ways in which such volatility can be computed:

i)    Historical changes in the target metric for the acquired entity and public comparable companies,
ii)    Entity volatility based on the relationship between the target metric and the enterprise value,
iii)    The difference between analyst forecasts and actual results for peer companies, and
iv)    Fitting a distribution to management’s estimates.

With any of these methods, a discussion with management is recommended since a derived volatility may fail to accurately incorporate the economics of the entity’s situation.

Both option-pricing models can get complex and difficult to comprehend for a lot of professionals and they have their share of advantages and disadvantages.

Advantages:
i)    Manage complex payoff structures: Can accommodate a wide range of complex payoff structures.
ii)    Objective assumptions: Most inputs are governed by market-related inputs making it less subjective than the PWERM.
iii)    Discount rate: Since the computations are made using random numbers and volatility, generally risk-adjusted discount rates are used, reducing the need of subjectivity inherent in building discount rates for financial matrices.

Disadvantages:


i)    Perceived to be complex and time-consuming.
ii)    Rigid: OPMs are based on a prescribed formula and are perceived as rigid relative to the PWERM.
iii)    Difficulty in converting real-world cash flows into risk-free cash flows: It is challenging at times to convert the pay-out structure into models to be used with the OPMs.

Valuation of contingent consideration and selection of the appropriate methods for doing so can be quite challenging. Such valuations are continuously evolving as new literature on methods and approaches is published around the world. The selection of methods to value these arrangements is driven by the complexity of the pay-outs and the experience and the qualifications of the valuer to be able to appropriately apply these methods.

The complexity of contingent consideration is not limited to its valuation but has several accounting and taxation implications which need to be considered and analysed. The accounting and tax aspects vary, based on the accounting standard being followed as well as the structure of the transactions. A discussion on these aspects would warrant an independent article, which we intend to cover over the next few issues.

INTRODUCTION TO ACCREDITED INVESTORS – THE NEW INVESTOR DIASPORA

Investors and investments have, over the decades, evolved with respect to form, structure, taxation and compliances involved. The constant need to test and re-invent has led to newer market participants exploring the investment universe.

However, one of the foremost principles of investment and investing, that is, investors should invest in financial products after knowing the risks and returns associated with them, and therefore take an informed decision regarding their investments in line with their risk-return profile, continues to prevail.

SEBI Consultation Paper: On 24th February, 2021, SEBI introduced a ‘Consultation Paper on the Introduction of the Concept of Accredited Investors’ (‘Consultation Paper’) in the Indian securities market.

The Consultation Paper made a case for introduction of the concept of Accredited Investors (AI) in the Indian securities market and covered the following aspects:

  •  Benefits to the Indian Securities Market
  •  Proposed AI eligibility criteria for various categories of investors, namely, Individuals, HUFs, Family Trusts, Bodies Corporate and Non-Resident Investors
  •  Process and validity of accreditation
  •  Procedure for implementation

SEBI Press Release (SEBI PR): Subsequently, on 29th June, 2021, SEBI via PR No. 22/2021, inter alia proposed a formal introduction of the framework for AI in the Indian securities markets.

This article covers the following aspects:

(A) CONCEPT OF AI

The AI framework as proposed by SEBI in India and prevalent framework across different economies; impact on the Indian securities markets vis-à-vis Private Equity, Venture Capital, Portfolio Management Services (PMS) and the Startup ecosystem.

AI, or as they are colloquially called Professional or Qualified Investors, amongst others are a class of investors who possess expert understanding of various financial products, the risks and returns associated with them, coupled with the financial capacity to absorb losses, enabling them to take relatively higher risk in their investing endeavours.

Hence, they are classified as a distinct group to recognise their ability to take informed decisions regarding investments and to selectively eliminate the need for extensive regulatory protection. Such investors may also enjoy relaxations with respect to disclosure requirements, filings of offer documents / prospectus, etc., and enhanced flexibility in respect of investor reporting.

Across the globe, other jurisdictions have also similarly demarcated this investor class considering their distinct knowledge and investment experience, alongside financial capacity.

(B) WHY HAVE ACCREDITED INVESTORS

The investment ecosystem in India today restricts investments in various asset classes based on the capacity of the investor to digest risks associated with that investment. This ability to digest risks is determined by minimum investment thresholds and high net worth requirements.

However, over time, investors have gained requisite knowledge to demonstrate an understanding of the asset class along with the ability to take on the risks associated with such investments.

Therefore, identifying this new investor diaspora as an ‘Accredited Investor’ enables achieving the premise of risk-reward balance coupled with the opportunity to allow investors to invest in asset classes that they understand and follow which would fill in the gap in the current investment and securities regulations. This model has also been successfully implemented globally (see ‘Accredited Investor Ecosystem Globally’ below) and has resulted in the creation of this new investor diaspora.

Overall economic boost in the investment universe and promotion of asset classes which hitherto were inaccessible to a large set of investors would be visible.

(C) THE ACCREDITED INVESTOR FRAMEWORK AS PROPOSED BY SEBI IN INDIA1 AND ACROSS DIFFERENT ECONOMIES:

(I) The eligibility criteria for Resident Investors, Non-Resident Indians and Foreign Entities as proposed by SEBI are as detailed below:

Category of investor

Eligibility criteria for Indian
investor to be an Accredited Investor

Eligibility Criteria for Non-Resident
Indians and Foreign Entities to be Accredited Investors

Individuals, HUFs and Family Trusts

Annual income >= INR 2 crores; or

Net worth >= INR 7.5 crores with not
less than INR 3.75 crores of financial assets; or

Annual Income >= INR 1 crore + Net
worth >= INR 5 crores; with not less than INR 2.5 crores of financial
assets;

Annual income >= USD 300,000; or

Net worth >= USD 1,000,000; with not
less than USD 500,000 of financial assets; or

Annual income >= USD 150,000 + Net
worth >= USD 750,000; with not less than USD 375,000 of financial assets

Trusts (other than Family Trusts)

Assets Under Management >= INR 50
crores

Assets Under Management >= USD 7.5
million

Bodies Corporate

Net worth >= INR 50 crores

Net worth >= USD 7,500,000

Others

Central and State Governments,
Developmental agencies such as SIDBI, NABARD, etc., set up under the aegis of
Government(s), funds set up by Government(s) and QIB’s as defined under SEBI
(ICDR) Regulations, 2018

Multilateral agencies, Sovereign Wealth
Funds, International Financial Institutions and Category – I FPIs


1   SEBI Consultation Paper dated 24th
February, 2021

Manner of determination of annual income, net worth and value of real estate assets
(i) The income and asset details which need to be considered for assessment of eligibility criteria shall be as per the data furnished in the Income-tax Returns filed for the immediately preceding financial year and the financial year in which assessment is being made.

(ii) For calculation of net worth, the value of the primary residence of the investor shall not be included.

(iii) In case the assets of the investor accounted for the assessment of eligibility criteria are in the form of real estate, a ‘ready reckoner rate’ as published by the respective local bodies shall be considered.

Manner of determination of annual income and net worth in case of joint accounts

In case of joint accounts held by individuals, the account shall be considered as an AI account only in the following scenarios:

(i) The First holder of the account is an AI;

(ii) The Joint holders are parent(s) and child(ren), where at least one person is independently an AI;

(iii) The Joint holders are spouses and their combined income / net worth meets eligibility criteria.

Manner of determination of financial capacity in case of bodies corporate

For bodies corporate, the latest statutorily audited information as on the date of application shall be considered for assessment of eligibility.

For trusts, the calculation of Assets Under Management shall be based on the valuation data as included in the Statutory Audit Report of the preceding financial year or as on the date of application.

(II) Accredited Investor Ecosystem Globally

Country

Accredited Investor criteria

Regulation

United States of America

Earned income exceeding USD 200,000 (or
USD 300,000 together with a spouse) in each of the prior two years and
reasonable expectation of a similar earning for the current year, or

SEC Reg 501(d)

United States of America


(continued)

has a net worth over USD 1,000,000,
either alone or together with a spouse (excluding the value of the primary
residence

SEC Reg 501(d)

Singapore

Net personal assets exceeding SGD 2
million (or equivalent in foreign currency), or in case of Corporates – Net
Assets exceeding SGD 10 million (or equivalent foreign currency) or

Income in preceding 12 months should be
not less than SGD 300,000 (or equivalent in foreign currency)

Section

4A(1)(a) of the Securities and Futures
Act (SFA)

Australia

Net assets of at least AUD 2.5 million, or

A gross income for each of the last 2
financial years of at least AUD 250,000

Section 708(8) of the Corporations Act,
2001

United Kingdom

‘Experienced Investor’ definition in the
UK:

A body corporate which has net assets in
excess of
€ 1,000,000 or which is part of a group which has net assets in excess of €
1,000,000;

Trustee of a trust where the aggregate
value of the cash and investments which form part of the trust’s assets is in
excess of € 1,000,000;

An individual whose net worth, or joint
net worth with that person’s spouse, is greater than € 1,000,000, excluding
that person’s principal place of residence

Section 3 of Financial Services
(Experienced Investor Funds) Regulations, 2012

When compared to global benchmarks, the financial parameters (vis-à-vis income and net worth) laid down by SEBI are on the higher side and may indicate a sense of conservative caution which is understandably needed in the advent of the sensitivity and adaptability concerns that surround this critical regulation. However, over time SEBI may consider re-evaluating these parameters as soon as AI investment becomes mainstream and with the imminent need to reduce entry barriers (income and net worth) for a seamless functioning of these crucial market participants.

(D) IMPACT ON THE INDIAN SECURITIES MARKETS VIS-À-VIS PRIVATE EQUITY, VENTURE CAPITAL, PMS AND STARTUP ECOSYSTEM

The Indian financial and securities market ecosystem is evolving with the Startups and the alternative investment space is fast maturing.

The proposed regulations as detailed below create a base for a thriving market and a soft regulatory regime. While the market for customised products for elite investors may not be readily available in the Indian securities market at this juncture, putting in place the required enabling framework will propel innovation in and development of the securities market in time to come.

Category of market participant

Associated effects under proposed
regulations2

Impact (Author’s view) and SEBI PR

Investors

Recognition as AI will help in availing
intended benefits

Portfolio diversification through access
to customised investment products or structured products;

more investment products due to lower
entry barriers such as minimum investment size

Alternative Investment Funds (AIF)

(Venture Capital, Private Equity and
Startups)


and


PMS players

Flexible participation for AI under the
AIF and PMS regulations

This is a welcome step and a much-needed
initiative opening up the investment ecosystem to AIs who were hitherto
restricted from such investments owing to prevalent minimum investment norms


AIFs3 and PMS4
would be able to attract capital from AIs for this fast-growing asset class
helping Startup and Venture Capital investments get the much-needed push
without the minimum investment norm requirements.

Alternative
Investment Funds


and


Portfolio
Management Services players

Beneficial interrelationship of AI with
AIF and PMS

for AI’s with minimum investment of INR
10 crores (PMS) or INR 70 crores (AIF)

Accredited Investors with minimum
investment of

INR 70 crores with AIF may avail
relaxation from regulatory requirements such as portfolio diversification
norms, conditions for launch of schemes and extension of tenure of the AIF

OR
INR 10 crores with registered

Alternative
Investment Funds


and


Portfolio
Management Services players


(continued)

PMS provider may avail relaxation from
regulatory requirements with respect to investments in unlisted securities
and shall be able to enter into bilaterally negotiated agreements with the
PMS provider


The above benefits shall be instrumental
for availing better means for investment structuring, pooling of capital,
co-investments, etc.


However, the threshold of INR 70 / 10
crores seems to be on the higher side and may merit reconsideration

Investment Advisers (IA)

Optimal engagement with IA

The terms of the agreement may be determined
mutually between the IA and the AI client, without diluting the fiduciary
responsibility cast on IAs under the SEBI Investment Advisors Regulations.

AI shall be in a better
position to bargain since the limits and modes of fees
can be governed through bilaterally negotiated contractual terms


2   SEBI PR
dated 29th June, 2021

3   As an illustration, the minimum capital
commitment required to participate in AIFs is INR 1 crore. In case of an
Accredited Investor, the manager may accept a capital commitment less than INR
1 crore

4   As an illustration, any entity may enter into
an agreement with a Portfolio Manager to avail customised asset management,
i.e., portfolio management service with a minimum capital of INR 50 lakhs. Such
capital may be made available to the Portfolio Manager in the form of cash or securities.
In case of a client who is an Accredited Investor, the Portfolio Manager may
accept capital and manage a portfolio of less than INR 50 lakhs

Accreditation Agencies
Accreditation Agencies (AA) can be Market Infrastructure Institutions (MIIs), i.e., Stock Exchanges, Depositories and / or subsidiaries of such MIIs. The modalities of accreditation, including documentation, fees, etc., will be specified by the AA separately.

Accreditation, once granted, shall be valid for a maximum period of one year from the date of accreditation.

The investor shall submit the necessary data and documents to the AA for ascertaining its eligibility to be an Accredited Investor. If eligible as per the approved criteria, the Accreditation Agency shall provide a certificate to this effect, clearly indicating the period of validity. Each certificate of accreditation shall have a unique certificate number.

The AI shall provide a copy of the Accreditation Certificate to the financial product / service provider along with a declaration to the effect that:

(i) The Investor is aware that being an AI, it is expected to have the necessary knowledge or means to understand the features of the investment product / service, including the risks associated with the investment and also has the ability to bear the financial risk associated with the investment.

(ii) The Investor is aware that the investment product / service in which it is proposing to participate may have a relaxed and flexible regulatory framework and may not be subject to the same regulatory oversight as retail products / services.

(E) WELCOME TO THE AI IN INVESTING AND ITS BALANCE
SEBI continues to pursue its ambitious attempts to harmonise the Indian securities market with the staggered introduction of global best practices in investments while giving due recognition to sophisticated market participants for better regulation.

While from a risk minimisation and mitigation perspective for market participants SEBI will need to ensure a robust recognition process and monitor the impact on the asset classes, short-term liquidity boost and transparency of information by parties looking to on-board AI’s with investor protection and interest would remain the paramount factor.

We hope that the accreditation, and acceptance, of specialist investors further propels the quantum of investments into new asset classes and helps drive the Indian economy to greater heights.

SHOULD CHARITY SUFFER THE WRATH OF SECTION 50C?

INTRODUCTION
In this article, the applicability of section 50C in the case of a charitable trust has been deliberated upon. Before we proceed any further, a basic understanding of the method of computation of capital gains in the case of a charitable trust would be very helpful.

COMPUTATION OF ‘INCOME’ IN THE CASE OF A CHARITABLE TRUST

Section 11 of the Income-tax Act deals with computation of income from property held for charitable and religious purposes. Section 11(1) provides the incomes that shall not be included in the total income of the previous year of the person in receipt of the income.

It is well settled that the ‘income’ as referred to in section 11(1) must be computed in accordance with commercial principles and not in accordance with the ordinary provisions of the Act.

In this regard, reference may be made to the following materials:
• Board Circular No. 5P (XX-6), dated 19th June, 1968;
• CIT vs. Ganga Charity Trust Fund [1986] 162 ITR 612 (Guj);
• CIT vs. Trustee of H.E.H. the Nizam’s Supplemental Religious Endowment Trust [1981] 127 ITR 378 (AP);
• CIT vs. Rao Bahadur Calavala Cunnan Chetty Charities [1982] 135 ITR 485 (Mad);
• CIT vs. Janaki Ammal Ayya Nadar Trust [1985] 153 ITR 159 (Mad) (para 13);
• CIT vs. Programme for Community Organisation [1997] 228 ITR 620 (Ker) upheld in CIT vs. Programme for Community Organisation [2001] 248 ITR 1 (SC);
• CIT vs. Rajasthan and Gujarati Charitable Foundation [2018] 402 ITR 441 (SC); and
• DIT(E) vs. Iskcon Charities [2020] 428 ITR 479 (Karn) (para 7).

Section 11(1A) and computation of capital gains in the hands of a charitable trust:
Section 11(1A) provides that for the purposes of section 11(1), where a capital asset held wholly for charitable or religious purposes is transferred and the whole or any part of the net consideration is utilised for acquiring another capital asset to be so held, then, the capital gain arising from the transfer shall be deemed to have been applied to charitable or religious purposes to the extent specified thereunder.

Given that the exemption u/s 11(1)(a) is subject to condition of application or accumulation, the Legislature found that such condition mandating application or accumulation of capital gains could lead to eroding the corpus of the trust. Hence, with a view to ease the onerous condition of requiring application or accumulation of capital gains for religious or charitable purposes, the Legislature introduced section 11(1A) vide Finance (No. 2) Act, 1971 with effect from 1st April, 1962. This is forthcoming from the Circular No. 72, dated 6th January, 1972.

It may be noted that section 11(1A) only deems acquisition of another capital asset held for charitable or religious purposes as application for the purposes of section 11(1). This is clear from the preamble of section 11(1A), which uses the words ‘for the purposes of sub-section (1)’.

It may be noted that the computation of capital gains will also have to be made u/s 11(1) by applying commercial principles as capital gains is also an ‘income’ u/s 11(1) and cannot receive any different treatment. Reference may be made to the Board Circular No. 5P (XX-6), dated 19th June, 1968 which provides that even income under the head ‘capital gains’ will have to be computed under commercial principles in case of a charitable trust.

APPLICABILITY OF PROVISIONS OF SECTION 50C

For section 50C to apply, the following prerequisites must be satisfied:
i) Consideration received or accruing as a result of a transfer of a capital asset is less than the value adopted or assessed or assessable by any Authority of a State Government for the purpose of stamp duty in respect of such transfer; and
ii) The capital asset being transferred is land or building, or both.

Section 50C is a deeming provision which deems the Stamp Duty Value (SDV) adopted, assessed or assessable as the full value of consideration for the purpose of computation of capital gains u/s 48.

It is well settled that the scope of a deeming provision must be restricted to the purpose for which it is created and must not be extended beyond such purpose. Such legal fiction must be carried to its logical conclusion and must not be taken to illogical lengths. One should not lose sight of the purpose for which the legal fiction was introduced. In this regard, reference may be made to the judgments in CIT vs. Mother India Refrigeration Industries P. Ltd. [1985] 155 ITR 711 [SC] and CIT vs. Ajax Products Ltd. [1965] 55 ITR 741 [SC].

Thus, the provisions of section 50C, which deem the SDV as the full value of consideration for the purposes of section 48, cannot be extended to the case of a charitable trust, in whose case the capital gains must be computed in accordance with commercial principles.

Even otherwise, it may be noted that there can be no room for importing a deeming fiction of Chapter IV-E in computing the income of a charitable trust on commercial principles u/s 11(1).

In the following judgments it has been held that section 50C has no application in case of charitable or religious trusts:
• ACIT vs. Shri Dwarikadhish Temple Trust, Kanpur (ITA No. 256 & 257/Lkw/2011, dated 21st August, 2014) (paras 4.3-6.2);
• ACIT vs. The Upper India Chamber of Commerce [ITA No. 601/Lkw/2011, dated 5th November, 2014 (2014) 46-B BCAJ 282] (paras 4 & 5).

It would also be pertinent to note that section 50C was inserted into the Income-tax Act much after section 11(1A) was introduced. However, the Legislature has not chosen to make an amendment to section 11(1A) after insertion of section 50C, thereby indicating that the Legislature does not intend to take away the benefit of section 11(1A) in the case of a trust with the introduction of section 50C into the statute book.

Wherever the Legislature has sought to provide for application of normal provisions of the Act in the case of a charitable trust, it has expressly provided so. It has done so because it is aware that the income of a charitable trust is to be computed in accordance with commercial principles. [See Explanation (ii) to section 11(1A) and Explanation 3 to section 11(1).]

However, it has consciously chosen not to import the fiction of section 50C into sections 11(1) and 11(1A) and hence section 50C would not be applicable in the case of a charitable trust.

It is a settled principle of interpretation that law has to be interpreted in the manner that it has been worded. Nothing is to be read into and nothing is to be implied in it while reading the law. There is no intendment to law. In this regard, reference may be made to the judgment in CIT vs. Kasturi & Sons Ltd. (1999) 237 ITR 24 (SC).

Even otherwise, it may be noted that section 50C is incompatible with the scheme of sections 11(1) and 11(1A) as there cannot be an application or accumulation of any artificial income or consideration created by way of a deeming fiction.

In CIT vs. Jayashree Charity Trust [1986] 159 ITR 280 (Cal), it was held that though section 198 provides that the amounts deducted by way of income tax are deemed to be ‘income received’, what is deemed to be income
can neither be spent nor accumulated for charitable purposes. Hence, the deeming provisions of section 198 should not be construed in a way to frustrate the object of section 11.

It may also be noted that a charitable trust cannot be expected to do the impossible act of applying / accumulating / investing a notional consideration which it has neither received nor is going to receive. In this regard, reference may be made to the judgments in Krishnaswamy S. Pd. vs. Union of India [2006] 281 ITR 305 (SC) and Engineering Analysis Centre of Excellence Private Limited vs. CIT [2021] 125 taxmann.com 42 (SC).

The interpretation that section 50C does not apply to charitable trusts saves the provisions of section 11 from the vice of the absurdity of requiring the application / accumulation / investment of a notional consideration.

Thus, the provisions of section 50C do not apply to the case of a charitable trust.

NON-APPLICABILITY OF SECTION 50C BY APPLYING MISCHIEF PRINCIPLE

By applying the Mischief rule, or Heydon’s rule of interpretation, while interpreting the provision, the real intention behind the enactment of the statute needs to be gone into in order to understand what mischief it seeks to remedy. This principle of interpretation finds support of the judgment in K.P. Varghese vs. ITO [1981] 131 ITR 597 (SC).

The overarching reason for insertion of section 50C would be to curb generation of black money by understating the agreed consideration on records. Under the erstwhile provisions, the A.O. without any evidence to the contrary could not question the consideration stated to have been agreed between the parties to a transaction by presuming the market value to be the full value of consideration. Hence, in order to plug evasion of taxes by understating consideration, section 50C has been inserted into the statute books. In Gouli Mahadevappa vs. ITO [2013] 356 ITR 90 (Karn), it has been held that the ultimate object and purpose of section 50C is to see that the undisclosed income of capital gains received by the assessees should be taxed.

In the case of a charitable trust, there can be no motivation whatsoever to generate any black money as the entire income generated is exempt from taxation if the conditions u/s 11 are met.

In case of a charitable trust, deposit of sale consideration into a Fixed Deposit amounts to utilisation as envisaged in section 11(1A). In this regard, reference may be made to Board Circular No. 833 of 1975 dated 24th September, 1975 and the judgment of the Calcutta High Court in CIT vs. Hindusthan Welfare Trusts [1994] 206 ITR 138 (Cal). Hence, a mere investment in a Fixed Deposit could amount to utilisation.

Thus, when there is no motivation to generate black money in case of a charitable trust, the mischief sought to be remedied by section 50C does not arise.

It may be noted that even qua the buyer of the land or building, the provisions of section 56(2)(x) do not apply by virtue of exception provided in clause (VII) of proviso to section 56(2)(x). Therefore, neither party will have any tax advantage in fixing a consideration lower than the actual consideration.

As discussed earlier, section 11(1A) was brought into the statute to do away with the erosion of the corpus. Thus, when the intention of the Legislature was to ensure that there is no erosion of corpus by way of requiring application of actual income, it can never be the intention of the Legislature to import section 50C into section 11(1A) and require the application or utilisation of an artificial sum, thereby eroding the corpus.

It can never be the intention of the Legislature to give a benefit with one hand and then take the same away with the other. Hence, a sincere attempt must be made to reconcile the provisions to ensure that the benefit given by the Legislature is not taken away. In this regard, reference may be made to the judgment in Goodyear India Ltd. vs. State of Haryana [1991] 188 ITR 402 (SC).

Thus, even applying the mischief rule of interpretation, section 50C cannot be applied in the case of a charitable trust.

IMPACT OF DECISIONS RENDERED IN THE CONTEXT OF INTERPLAY BETWEEN SECTIONS 50C AND 54-54H ON SECTION 11(1A)

Under section 11(1A)(a)(i), if the entire net consideration is utilised in acquiring another capital asset, the whole of such capital gains arising from the transfer shall be deemed to have been applied to charitable or religious purposes.

It may be noted that the definition of ‘Net consideration’ in Explanation (iii) to section 11(1A) is similar to that contained in Explanation 5 to section 54E(1), Explanation (b) to section 54EA(1), Explanation to section 54F(1) and section 54GB(6)(c).

In certain judgments, it has been held that though section 50C must not be applied for the purposes of computing ‘net consideration’ as referred to in sections 54F and 54EC, the capital gains referred to therein will also have to be computed without giving effect to the provisions of section 50C. In the said judgments, it has been held that the capital gains for the purposes of section 45(1) will have to be computed in accordance with section 48 read with section 50C. Thus, the effect would be that though the exemptions under sections 54F and 54EC are based on capital gains computed without applying the provisions of section 50C, the capital gains for the purposes of section 45(1) would be determined after applying the provisions of section 50C, thereby effectively taxing the difference between the deemed consideration as determined u/s 50C and the actual consideration agreed between the parties to the sale.

The same may be demonstrated by way of an illustration:

Particulars

Amount (Rs.)

Amount (Rs.)

Full value of consideration (actual sale consideration – Rs. 20 lakhs
or SDV – Rs. 36 lakhs, whichever is higher) [A]


36,00,000

Less: Indexed cost of acquisition [B]


(1,93,506)

Income chargeable under the head capital gains [C] = [A] – [B]


34,06,494

Less: Exemption u/s 54F [D]


(18,06,494)

Actual sale value [D1]

20,00,000


Less: Indexed cost of acquisition [D2]

(1,93,506)


Capital gain u/s 54F [D3] = [D1] – [D2]

18,06,494


Net consideration received

20,00,000


Amount invested in new asset

20,00,000


Deduction u/s 54F(1)(a) [since the net consideration is invested,
entire capital gains is exempt] [D4]

18,06,494


Taxable long-term capital gains [E] = [C] – [D]


16,00,000

From the above illustration it is clear that though the assessee has invested Rs. 20,00,000 in the acquisition of a new asset which is equal to the net consideration of Rs. 20,00,000, the assessee is suffering tax on a long-term capital gain of Rs. 16,00,000 (Rs. 36,00,000 – Rs. 20,00,000), which is nothing but the difference between the deemed sale consideration u/s 50C of Rs. 36,00,000 and the actual sale consideration of Rs. 20,00,000.

The above implications have been approved in:

• Shri Gouli Mahadevappa vs. ITO [2011] 128 ITD 503 (Bang) upheld in Gouli Mahadevappa vs. ITO [2013] 356 ITR 90 (Karn);
• Jagdish C. Dhabalia vs. ITO [TS-143-HC-2019 (Bom)];
• Mrs. Nila V. Shah vs. CIT [2012] 21 taxmann.com 324 (Mum) / [2012] 51 SOT 461 (Mum).

Without going into the correctness of the said judgments, the ratios laid thereunder have no application in the context of charitable trusts for the following reasons:

• The same were laid down in the context of sections 54F and 54EC and not in the context of section 11(1A).
• Sections 54F and 54EC form part of Chapter IV, whereas section 11 forms part of Chapter III. Thus, section 11 is to be applied prior to the stage of computation of income under Chapter IV which deals with computation of total income, and hence section 50C which forms part of Chapter IV would have no application in the context of section 11.
• Unlike section 54F which deals with exemption from chargeability u/s 45, section 11(1A) provides for computation of capital gains deemed to be applied to charitable or religious purposes. As held by various courts, ‘Application’ can be only of real income.
• Even if one were to conclude that section 50C would be applicable to the case of a charitable trust, the fiction imported for determining the full value of consideration will necessarily have to be imported into the utilisation of such consideration. This is based on the principle of parity of reasoning, which has been upheld by the Supreme Court in CIT vs. Lakshmi Machine Works [2007] 290 ITR 667 (SC) and CIT vs. HCL Technologies Ltd. [2018] 404 ITR 719 (SC).
• The Board, vide Circular No. 5P (XX-6), dated 19th June, 1968, has itself stated that the income of the trust (including capital gains) must be computed by applying commercial principles. Thus, no notional income u/s 50C can be brought to tax in case of a charitable trust.
• The courts have reached the said conclusions keeping in mind the mischief sought to be remedied by section 50C. As discussed above, the mischief sought to be remedied by application of section 50C does not arise in the case of a charitable trust.
• Sections 11(1) and 11(1A) being exemption provisions with beneficial purposes, must be interpreted liberally. In this regard, reference may be made to the judgment in Government of Kerala vs. Mother Superior Adoration Convent [2021] 126 taxmann.com 68 (SC), wherein the five-judge Bench’s decision in Commissioner of Customs vs. Dilip Kumar & Co. [2018] 9 SCC 1 (SC), was distinguished on the ground that the said judgment did not refer to the line of authorities which made a distinction between exemption provisions generally and exemption provisions which have a beneficial purpose.

CONCLUSION
On the basis of the above, it may be argued that section 50C does not have any application in the case of a charitable trust. Hence, the capital gains as referred to in section 11(1A) will have to be computed without applying the provisions of section 50C. Any other interpretation will lead to the absurd result of requiring a charitable trust to apply / accumulate / invest notional gains which have never accrued or arisen to it, which can never be the intention of the Legislature.


Poem For Independence Day

CARO 2020 SERIES: NEW CLAUSES AND MODIFICATIONS INVENTORIES AND OTHER CURRENT ASSETS

(This is the second article in the CARO 2020 series that started in June, 2021)

NEW CLAUSES AND MODIFICATIONS

Whilst the clause on reporting in respect of inventories has been present in the earlier versions, too, CARO 2020 has modified parts of the first clause and added certain reporting requirements in respect of current assets which are given below.

Modifications
a. Whether in the opinion of the auditor the coverage and procedure for physical verification of inventories is appropriate;
b. Whether any discrepancy in excess of 10% or more in the aggregate for each class of inventory was noticed and the same was properly dealt with in the books of accounts.

Additional Reporting
a. Whether at any point of time during the year the company has been sanctioned working capital limits in excess of Rs. 5 crores in aggregate from banks or financial institutions, on the basis of security of current assets;
b. Whether the quarterly returns or statements filed by the company with such banks or financial institutions are in agreement with the books of accounts and if not, to give details.

PRACTICAL CHALLENGES IN REPORTING
The reporting requirements outlined above entail certain practical challenges which are discussed below:

Verification of inventory:
a. On the appropriateness of coverage and procedure for physical verification of inventory, the auditor will have to observe the performance of the management’s physical count taking procedure, control over movement of inventory, adequacy of design and effective operations of internal controls.

b. Apart from ensuring that proper written instructions are issued, it is also incumbent for the auditor to point out specific areas where the instructions are not clear or other procedural lapses like inadequate segregation of duties, cut-off procedures not adhered to especially for sales and work-in-progress in continuous process industries, as may be observed. It is important for the auditor to comment on the specific areas where he feels that the procedures are not adequate rather than commenting that the ‘procedures are generally adequate’.

c. Covid-19: The onset of Covid-19 has caused significant disruptions in the business operations of companies which could pose challenges in conducting physical verification of inventories. This, in turn, would make it difficult for auditors to ensure compliance with SA 501, Audit Evidence-Specific Considerations for Selected Items, which requires the auditor to obtain sufficient appropriate audit evidence regarding the existence and conditions of inventories. SA 501 requires attendance at location/s of physical inventory count, unless impracticable, and performing audit procedures on inventory records to determine whether the records accurately reflect actual inventory count results. Some of the challenges may be broadly analysed under the following situations:

Management does not conduct an inventory count (not even any alternative audit procedure) on the balance sheet date:
In such cases, as per Key Audit Considerations amid Covid-19 issued by ICAI on physical inventory (ICAI’s Covid guidance), the management should inform the auditors and those charged with governance about the reasons for the same. However, if carrying out a count is not feasible, the auditor would need to evaluate the reasonableness of the circumstances and the internal controls with respect to the existence and condition of inventory. Depending upon the materiality, the auditor may use his judgement to modify his audit report in accordance with SA 705 (Revised) Modifications to the Opinion in the Independent Auditor’s Report. Further, its impact on auditor’s opinion on internal financial controls u/s 143(3)(i) of the Companies Act, 2013 (‘ICFR’) also needs to be evaluated, in addition to reporting under this clause regarding coverage of physical verification of inventory.

Physical verification conducted at a date other than the balance sheet date:
In such cases, the design and operating effectiveness of controls over inventory would need to be evaluated before reporting. Further, the following considerations are also relevant:
i.    Whether the inventory records are properly maintained;
ii.    Understanding reasons for differences in the physical verification count and the inventory records;
iii.    Performing roll-backward procedures, if the inventory count is done after the year-end or roll-forward procedures, if inventory count is done during the interim period;
iv.    Evaluating whether any adjustment is required in roll-forward or roll-backward procedures due to differences observed as in (ii) above;
v.    To consider whether the time between inventory count date and balance sheet date reflects appropriate assessment of the physical condition of the inventory.

Impracticable for auditor to attend the physical count:
This issue is relevant for the auditor to issue an audit opinion on the financial statements and not on CARO 2020. However, in order to have complete discussion on physical verification of inventory, specifically its increased importance during Covid pandemic times, the same is also discussed here.

  •  In the event that it is impractical for the auditor to physically attend the inventory count process, the auditor can perform alternative audit procedures to obtain sufficient appropriate audit evidence regarding the existence and condition of the inventory. In addition, to evaluate design and test the operating effectiveness of internal control over physical verification of inventory, the following may be considered:

i. Prepare a document substantiating the impracticality and unreasonableness of observing the count in person, given the Covid-19 situation;
ii. Use of web or mobile-based video-conferencing technologies (i.e., Microsoft Teams, Facetime, WhatsApp). In this case, care should be taken by the auditor that if inventory items cannot be identified with a unique reference number, etc., there is no chance of replacement of inventory during / after the count to avoid double counting. It would be advisable to retain the recording thereof as part of the audit documentation;
iii.    Consider using an external party, e.g., an independent CA firm in that location (ICA) or Internal Auditor (IA), in which case the auditor needs to evaluate
a. Objectivity and independence of ICA / IA;
b. Inquire for any relationships that may create a threat to their objectivity;
c. Evaluate their level of competence;
d. Determine the nature and extent of work to be assigned;
e. Communicate planned use of ICA / CA with those charged with governance;
f. Obtain written agreements from the entity for the use of ICA / IA for providing direct assistance;
g. Direct, supervise and review the work performed by ICA / IA providing direct assistance, including provide instruction / work programme, including sample selection, communicate management’s inventory count instructions, etc., and, if possible, supervise the count while it is in progress.

When inventory is under the custody and control of a third party, e.g., bonded warehouse, job worker / contractor, etc., the auditor shall verify the procedures undertaken by the management to evaluate the existence and condition of that inventory. This could be by way of obtaining confirmation from the third party as to the quantities and condition of inventory held on behalf of the entity and / or perform inspection or other procedures appropriate in the circumstances. The auditor needs to focus on whether inventory with third party is for a longer than normal period and obtain reasons for the same.

In the event the entity has specialised inventory where inventory count is not based on a normal physical verification process but on the confirmation of quantity / quality by an expert, the auditor will review the certification obtained by the entity and compare it with the book records. For example, in the case of coal, tonnage is calculated by considering the height, width, length of the stock yard and the moisture content in the coal to arrive at its tonnage. The entity will normally take the help of engineers in this process who would be internal or external experts.

a. Appropriate coverage: Even if the company has instituted proper procedures for physical verification, it is imperative that the coverage thereof is adequate and appropriate with respect to the nature, size, materiality, location, feasibility of conducting physical verification and risk of material mis-statement involved. This could involve significant judgement and an interplay of several factors, some of which are discussed hereunder:

• Classification of inventory – This is important for assessing the extent of coverage as also for evaluating the impact of discrepancies. Whilst the class of inventory is broadly specified in the Accounting Standards for manufacturing and trading companies, the same is not clear for service companies since all of it may not be amenable for quantification. Further, even if the classification for manufacturing and trading companies is appropriate to determine the adequacy of verification, an A-B-C analysis is desirable for which the basis would need to be evaluated for reasonableness. Further, the auditor also needs to examine whether there is a control system in place to identify and mark slow-moving, obsolete or damaged inventory.

• Periodicity of verification – The auditor would need to verify the periodicity of such verification and whether all the material items of inventory have been covered at least once in a year or as per the systematic plan as designed by the management. This would depend upon the nature of inventory, the A-B-C classification discussed above and the number of locations involved.

b. Dealing with discrepancies: The auditor should, based on his understanding of the business and operating effectiveness of internal controls, verify explanations provided by the management for discrepancies between inventory as per the books and as physically verified and steps taken by them to reconcile. Some of the common causes for discrepancies are:
• Incorrect data entry on receipt
• Issues not recorded
• Misplaced stocks
• Loss due to theft or natural calamity
• Human errors or incorrect unit of measurement used
• Inventory records not updated
• Supplier frauds
• Goods distributed as free samples
• Weight loss / gain due to passage of time

Under the modified (changed) reporting requirement, the auditor will have to report on any discrepancy noticed in excess of 10% or more in the aggregate for each class of inventory. Each class of inventory will have to be identified as per AS 2, ‘Valuation of Inventories’ / Indian Accounting Standard (Ind AS) 2, ‘Inventories’ and the internal policies of the management. The count at the time of physical verification will have to be compared with the book records and discrepancies in excess of 10% or more in the aggregate for each class will have to be reported. It may be worth it to note that the threshold limit of discrepancies of 10% should be applied to the value and not to the quantity. Hence, if the inventory has been valued other than at cost, e.g., net realisable value (NRV), the discrepancy of 10% needs to be compared with NRV.

It is worthwhile to note that this clause deals with discrepancies observed during physical verification only and not with discrepancies observed during audit. Further, even if the management has a valid explanation for the discrepancies, the fact needs to be brought out while reporting under this clause.

Working capital facilities:
a. This is a new reporting requirement wherein the auditor has to review quarterly returns or statements filed by the company with banks and financial institutions in case the sanctioned working capital limits with them are in excess of Rs. 5 crores in aggregate and to report if these are not in agreement with the books of accounts.

b. Collation of all working capital facilities: For calculating the limit of Rs. 5 crores, it is important to note that sanctioned amounts (not disbursed amounts) and both fund and non-fund-based amounts are required to be considered at any point of time during the year (as against only at the year-end) on the basis of security of current assets. This could present challenges in identifying the completeness thereof since sanctioned facilities as well as non-fund-based facilities are not reflected in the books of accounts. Accordingly, the auditor would need to make specific inquiries and obtain a representation and corroborate the same with the requisite documentary evidence like sanctioned letters, confirmations from the lenders, review of the minutes, ROC filings for charge created, etc. The aggregate of the sanctioned limit from all banks and financial institutions is also required to be collated. In case of a company which operates from multiple locations and working capital facilities are negotiated locally, care should be taken to ensure that all such sanctioned facilities are combined for the purpose of reporting under this clause. The auditor will also have to cross-verify the same with the relevant disclosures, if any, in the financial statements.

c. This clause is not applicable to unsecured sanctions or sanctions on the basis of security other than current assets or withdrawals above the sanctioned limit, e.g., in case the company has a combined sanctioned working capital limit of Rs. 4.75 crores but the same is overdrawn by Rs. 0.30 crore. In this case, the total outstanding working capital facility is in excess of Rs. 5 crores, however, since the aggregate sanctioned limit is less than Rs. 5 crores, this clause would not be applicable.

d. Considering the discussion in paragraphs (b) and (c) above, in case the sanctioned working capital limit exceeds Rs. 5 crores, the auditor is required to review quarterly returns and statements filed by the company with such banks / financial institutions and report if they are in agreement with the books of accounts and, if not, give details thereof.

The auditor will have to consider materiality of discrepancies, its relevance to the users of financial statements and their professional judgement while reporting discrepancies.

e. Each bank and financial institution may have its own requirements of submission of statements and returns. These submissions may be monthly, quarterly, yearly or of any other frequency, including event-based. However, for the purpose of reporting under this clause only quarterly statements / returns and that too which have relevance with the books of accounts of the company need to be considered, compared and reported.

Though this clause is applicable only if sanctioned working capital limits are provided based on the security of current assets, however, the responsibility of the auditor is to compare all the information provided in the quarterly statements / returns which can be compared with the books of accounts and is not restricted only to current assets. Such information may include aging of inventory and receivables, trade payable, property plant and equipment, other information, etc. So long as information can be compared with the books of accounts, it will be the responsibility of the auditor to report.

f. Challenges for MSMEs: Reconciliation of the details of statements / returns submitted to the lenders with the books of accounts on a quarterly basis could pose difficulties in case of MSMEs since they may not be regular in updating their accounting records. These MSMEs will have to keep their books of accounts updated based on which statements / returns submitted to banks and financial institutions can be compared, failing which their auditor will issue a disclaimer while reporting under this clause.

g. It is hoped that the introduction of this reporting requirement would lead to better discipline and improvement in internal controls which would result in a win-win situation for companies, lenders and auditors.

IMPACT ON THE AUDIT OPINION

Whilst reporting under these clauses, the auditor may come across several situations where he may need to report exceptions / deviations. In each of these cases, he would need to carefully evaluate the impact and exercise his professional judgement keeping in mind materiality and relevance to the users of financial statements, not only for reporting under these clauses but also on his opinion on ICFR and / or audit opinion on the financial statements, too. These are broadly examined hereunder:

Nature of exception /
deviation

Possible impact on the
audit report / opinion

The coverage and procedure for physical verification of
inventory is not adequate and / or appropriate

• Modification of opinion on ICFR;


• Depending on the facts and circumstances of the case, audit
opinion on financial statements

Physical verification of inventory not conducted by the company

• Modification of opinion on ICFR;


• Depending on the facts and circumstances of the case, audit
opinion on financial statements

Discrepancies in the returns / statements submitted to banks /
financial institutions

• Depending upon the nature of the discrepancy, modification on
audit opinion or reporting on ICFR reporting, if the discrepancy is in the
books of accounts

In such cases, it is imperative that the Board’s Report contains explanations / comments on every reservation / adverse comment in the audit report as per section 134(3)(f) of the Companies Act, 2013 and that there will not be any factual inconsistency between the two if, in the auditor’s judgement, the matter / observation may have any adverse effect on the functioning of the company.

CONCLUSION


The above changes have cast onerous responsibilities on the auditors by making them indirectly responsible to the lenders. Hence, they would also need to go beyond what is stated in the order since the devil lies in the details!

MLI SERIES MAP 2.0 – DISPUTE RESOLUTION FRAMEWORK UNDER THE MULTILATERAL CONVENTION

1. INTRODUCTION
‘Like mothers, taxes are often misunderstood, but seldom forgotten’ – Lord Bramwell

Lord Bramwell’s words reiterate that one cannot escape the rigours of taxation as it is inevitable. There is considerable certainty regarding the levying of taxes by a State, but the certainty buck stops there. The functional features of taxation have led to various complexities, eventually paving the way for tax uncertainty. Tax uncertainty is on account of various factors; the OECD-IMF report on tax certainty1, inter alia identifies an ineffective dispute resolution mechanism as one of the factors for tax uncertainty. Due to the uncertainty element, genuine taxpayers have suffered the wrath inter alia through prolonged disputes, thus losing faith in the system. On the other hand, tax shenanigans have benefited through tax avoidance, leaving the administration with empty coffers. Tax revenue being the cornerstone of a stable economy, the economic impact that tax uncertainty causes is undesirable for all the stakeholders concerned. Therefore, fostering tax certainty remains at the top of the agenda and a need-of-the-hour measure for the States.

As we draw the curtains on this insightful Multilateral Instrument (MLI) Series, we will focus majorly on the dispute resolution framework under the MLI in this final edition. This measure marches to foster tax certainty. However, unlike the other substantive provisions in the MLI, the success of the dispute resolution mechanism relies on an effective procedural framework which will be the focus of our discussion.


1   2019 Progress Report on Tax Certainty (July,
2019)

2. TAX TREATY DISPUTE RESOLUTION – PRE-BEPS ERA

‘No matter how thin you slice it, there will always be two sides’ – Baruch Spinoza
The purpose of tax treaties is to reduce barriers to cross-border trade and investment. The advent and growth of multinational corporations in India created a significant increase in tax treaty and transfer pricing disputes. Characterisation of receipts, arm’s length pricing, treaty entitlement, permanent establishment (PE) and attribution of income, etc., are common cross-border taxation disputes. A tax treaty will only achieve its goals if the taxpayers can trust the Contracting States to apply the treaty in letter and spirit.

If one Contracting State tax authority does not do so, the affected taxpayer has the right to contest this action of the tax authority through that state’s legal system. However, the domestic dispute resolution mechanism may be laborious, time-consuming and expensive.

Therefore, to resolve the double taxation issues, the tax treaty provides for a mechanism by way of Mutual Agreement Procedure (MAP)2, whereby the competent authorities (CA) of the relevant jurisdictions consult each other and endeavour to resolve the differences or difficulties in the interpretation or application of the tax treaty.

However, despite the advantages that MAP offers to resolve disputes, various shortcomings and challenges puncture its effectiveness. Some of the shortcomings in the MAP framework are:

Shortcomings of the MAP 1.0 framework


No impetus and mandate on the CA to solve a dispute.


No deadline or timetables to resolve the disputes; hence the process is
protracted unreasonably and time-consuming.


Lack of domestic law support such as non-implementation of MAP due to
domestic law conflict.


Lack of training and capacity-building initiatives by Governments for its CA
on international tax issues owing to financial constraints.

Shortcomings of the MAP 1.0 framework (Continued)


Lack of guidance in MAP processes for taxpayers in emerging economies on the
procedural and administrative aspects for initiating the MAP.


Lack of dedicated and experienced resource personnel to focus on MAP, leading
to an increase in MAP inventory.


Lack of transparency from the taxpayers’ perspective as they are not involved
in the process; hence, taxpayers are apprehensive about resorting to MAP.


From a taxpayer’s perspective, there are risks of double taxation due to
denial of corresponding adjustments in other state or re-opening of tax
assessments in the other state, delay in issuing refunds, etc3.


2   Article 25 of the Model Conventions (Pre-2017
editions)

From India’s standpoint, despite being one of the developing countries to have a large inventory of MAP cases, the MAP framework has not been effective owing to the shortcomings identified in the Table above. Lack of procedural guidance from the CBDT, clarity, transparency in the process and, more importantly, an extremely time-consuming process with non-TP cases taking more than 100 months to arrive at a resolution4 are some of the pain points. Hence, the need for a more effective MAP framework was imperative considering the ever-increasing inventory leading to tax uncertainty.

3. MAP 2.0 – BEPS MEASURES

The introduction of the BEPS Action Plan (AP) provided various measures to eliminate the scope for tax avoidance. However, the implementation of these measures involved changes in the domestic laws and tax treaty (through MLI). Therefore, with the introduction of BEPS measures and also with the existing MAP framework being inefficient, the possibility of growing tax uncertainty was inevitable. To ensure certainty and predictability for business / taxpayers, AP 14 – Making Dispute Resolution Mechanisms More Effective was initiated. BEPS AP 14 dealt with various aspects to improve the dispute resolution mechanisms (in addition to remedies under domestic laws) and suggested some best practices that countries could emulate to achieve certainty in a time-bound and effective manner.


3   Carlos
Protto Mutual Agreement Procedures in Tax Treaties: Problems and Needs in
Developing Countries and Countries in Transition – Intertax, Volume 42, Issue
3; and Jacques Malherbe: BEPS – The Issues of Dispute Resolution and
Introduction of a Multilateral Treaty

4   OECD MAP 2016 Statistics

5   Information related to the Inclusive
Framework is available at
http://www.oecd.org/tax/beps/beps-about.html


Minimum Standards: Minimum Standards are certain provisions to which all countries and jurisdictions within the BEPS inclusive framework5 have committed and must comply with. AP 14 included a minimum standard for participating countries that should ensure the following aspects:

(i)    Proper Implementation & Process: Treaty-related obligations on MAP are fully implemented in good faith6 and MAP cases are resolved on time.
(ii)    Prevention & Resolution of Disputes: The administrative processes should promote the prevention and timely resolution of treaty-related disputes.
(iii)    Availability & Accessibility to MAP: Taxpayers meeting the requirements under Article 25(1) of the OECD Model Convention can access the MAP.

In addition to the above, the AP 14 also provided certain best practices for implementation. The AP also addressed those members of the Forum for Tax Administration (FTA) who will undertake a peer review mechanism for effective implementation of the minimum standards7. It is to be noted that India is a member of the FTA.

The AP 14 report, which contains the minimum standard and best practice recommendations, is transposed into the CTAs by introducing it in the MLI. Part V of the MLI – Improving Dispute Resolution, focuses on Article 16 dealing with a strengthened MAP Framework for an effective resolution of treaty disputes, and Article 17 –Corresponding Adjustments, deals with MAP accessibility for transfer pricing cases to eliminate economic double taxation.

3.1 Article 16 – MAP 2.0
The salient feature of Article 16 and India’s position is as follows:

Article

Scope

Inference

16(1)


First sentence

Taxpayer considers that action of one or both the contracting
states will result in taxation that is not
according to the CTA
. Therefore, irrespective of the remedy under
domestic law, the dispute can be presented to the CA of either contracting state

Availability and flexibility in access to MAP: Aggrieved taxpayer can
approach for MAP resolution either of the contracting states and not
necessarily its resident jurisdiction

[Continued]


Second sentence

The time limit for presenting the case must be within three
years
from the first notification of the action resulting in taxation

Time Limit: For initiating MAP, the aggrieved taxpayer must
present his grievance within a minimum time limit of three years. This is to
ensure that there is no late claim made to burden the tax administration8
and at the same time give adequate time to the taxpayers to initiate MAP
access

India’s Position:


Article 16(1) First
sentence:

India has reserved the right
to the application of this First sentence. As per India’s view, residents of
the contracting state must approach only their respective CA to access the
MAP.

Consequent to its reservation, India is bound to introduce a
bilateral consultation or notification process if the Indian CA considers the
objection raised by the taxpayer in a MAP request as being not justified. The
recent MAP guidance issued by India9 addresses this aspect,
wherein India will notify the treaty partner about the reasons for which the
MAP application cannot be accepted and solicit the treaty partner’s response
to arrive at a decision.


Article 16(1) Second
sentence:

India has not reserved this sentence as the existing CTA that
India has entered into contains the specified time limit of three years
except for four CTAs10 where the existing timeline for initiating
the MAP is less than three years. India has notified these four CTAs. These
four CTAs will be modified by Article 16(1) of the MLI to include a minimum
time limit of three years, where an aggrieved taxpayer can initiate MAP with
the respective CA where the taxpayer is a resident


6   Echoing Article 31 and 32 of Vienna
Convention

7   OECD (2015), Making Dispute Resolution
Mechanisms More Effective, Action 14 – 2015 Final Report, OECD/G20 Base Erosion
and Profit Shifting Project, OECD Publishing, Paris

Article

Scope

Inference

16(2)


First sentence


Second sentence

If objection appears to be justified and the CA is not able to
achieve a satisfactory solution by himself, then the case must be resolved by
mutual agreement with the CA of the other state – Bilateral MAP

Bilateral MAP – This clause ensures that where the CA cannot
resolve cases unilaterally, the CA concerned must enter into discussions with
his counterpart CA for a resolution

The contracting states’ settled MAP agreement must be
implemented irrespective of the timeline prescribed under the domestic laws

Implementation of MAP agreement: This clause is to provide
certainty to taxpayers that implementation of MAP agreements will not

[Continued]


be obstructed by any time limits in the domestic law of the
jurisdictions concerned

India’s Position:


Article 16(2) First
sentence:

There is no reservation clause for the said
provision. Further, all the CTAs India has entered into contain the said
clause except for the CTAs with Greece and Mexico. India has duly notified
these two CTAs, which do not contain the language equivalent to Article 16(2)
First sentence. Both Greece and Mexico must make a similar matching
notification by including the India treaty in their notification list
according to which the First sentence of Article 16(2) shall apply to these
treaties.


Article 16(2) Second
sentence:

India has not made any reservation to this clause as most of the
treaties it has entered into contain a similar language. However, India has
notified ten CTAs which do not contain the language specified in
Article 16 (2) Second sentence. Therefore, Article 16(2) Second sentence will
apply to these ten CTAs, if these treaty partners make a similar matching
notification by including the India treaty in their notification list.
Failure to notify by any of these ten treaty partners will result in a
mismatch notification, whereby the CTA retains status quo, i.e., it
remains unaltered by the MLI provision

Article

Scope

Inference

16(3)


First sentence


Second
sentence

If any difficulty or doubt arises as to the interpretation or
application of CTA, then the CA shall endeavour to resolve this by mutual
agreement

Dispute Prevention: Cases may arise concerning the interpretation or
the application of tax treaties that are generic and do not necessarily
relate to individual cases. In such a scenario, this provision makes it
possible to resolve difficulties arising from the application of the
Convention

CAs may also consult together to eliminate double taxation in
cases not provided under CTA

This provision enables the competent authorities to deal with
such cases of double taxation that do not come within the scope of the
provisions of the Convention. For example, resident of a third state having
PE in both the contracting states

India’s Position:


Article 16(3) First
sentence:

There is no reservation clause for this provision. Further, all
the CTAs India has entered into contain the said clause except for two
treaties,

[Continued]

i.e., with Australia and Greece. India has duly notified these
two treaties which do not contain the language equivalent to Article 16(3)
First sentence. Therefore, both Australia and Greece shall notify the treaty
with India, according to which Article 16(3) First sentence shall apply to
the CTA concerned and be modified. Failure to notify by these two treaty
partners will result in a mismatch notification, whereby the CTA retains status
quo,
i.e., it remains unaltered by the MLI provision


Article 16(3) Second
sentence:

There is no reservation clause for this provision. Further, a
majority of the CTAs that India has entered into contain the said clause
except for six CTAs11. India has notified the six CTAs
which do not contain the language specified in Article 16(3) Second sentence.
Therefore, the Article 16(3) Second sentence will apply to these six CTAs if
these treaty partners make a similar matching notification by including India
in their notification list. Failure to notify by any of these six treaty
partners will result in a mismatch notification, whereby the CTA retains status
quo,
i.e., it remains unaltered by the MLI provision


8   Para 20 – Commentary on Article 25, OECD
Model Convention, 2017

9   MAP Guidance/2020, F.No 500/09/2016-APA-I,
Dated 7th August, 2020, CBDT, Government of India

10  Belgium, Canada, Italy and UAE

3.2 Article 17 – Corresponding Adjustments

Article

Scope

Inference

17(1)


Unilateral corresponding
adjustment

– Normally, in a transfer pricing adjustment, a taxpayer in a Contracting
Jurisdiction (State A), whose profits are revised upwards, will be liable to
tax on an amount of profit which has already been taxed in the hands of its
associated enterprise in another Contracting Jurisdiction (State B)


In such a scenario, State B shall make an appropriate adjustment
to relieve the economic double taxation

Mitigating economic double taxation: The provision is a
replicated version of Article 9(2) of the OECD Model Convention. Further, the
provision is to ensure that jurisdictions provide access to MAP in transfer
pricing cases

India’s Position:


India has made its reservation under Article 17(3)(a) for the
right not to include the corresponding adjustment clause in the CTAs, which
already contains a similar  clause
[Article 9(2) in the respective tax treaties]. Therefore, Article 17(1) will
have no impact on those CTAs. However, in respect of those CTAs that do not
contain the corresponding adjustment clause [for example, the India-France
CTA12], the corresponding adjustment clause will be included to
modify the same

3.3 The interplay of other articles of MLI with MAP

Part V of the MLI includes mechanism Article 16 of the MLI. As mentioned earlier, the introduction of the BEPS measure through MLI may create significant disputes in the form of disagreement on CTA interpretation, application of anti-abuse provisions and denial of treaty benefits, etc. To effectively address these disputes and eliminate double taxation, taxpayers access MAP to address their dispute through the framework and minimum standard under Article 16 of the MLI. Further, apart from the generic framework under Article 16, there are situations where other substantive provisions of MLI allow taxpayers to access MAP to resolve tax treaty disputes.


11  Australia, Belgium, Greece, Philippines,
Ukraine and UK

12  Synthesised Text between India and France CTA
available at
https://www.incometaxindia.gov.in/dtaa/synthesised-text-of-mli-and-india-france-dtac-indian-version.pdf

India’s position concerning these other substantive provisions is as follows:

Article

Particulars

Scope
– MAP accessibility

India’s
Position

4(1)

Dual Resident Entities

If a person other than an individual is resident in more than
one state, the CA shall endeavour to determine residency for CTA


In the absence of an agreement, the person shall not be entitled
to relief or exemption from tax except to the extent and manner agreed by the
CA. In effect, CAs can agree and provide relief at their discretion

India has notified 91 treaties (except Greece and Libya).
Further, India has agreed to the discretion of CAs to provide relief in a
case where dual residency is not resolved


Australia and Japan have reserved application of discretionary
relief. Hence, discretionary relief cannot be granted under these treaties by
the competent authorities

7(4)

Principal Purpose Test (PPT)

Deny treaty benefits if reasonable to conclude that one of the
principal purposes of the arrangement is to obtain tax benefits


Based on MAP request, the CA can provide treaty relief after
consideration of facts and circumstances

India has not opted for the discretionary relief provision as it
has notified the same under Article 7(17)(b). Therefore, once the treaty
benefits are denied, the CAs cannot provide any relief at their discretion


Notwithstanding the above, the taxpayer can avail the treaty
benefit if it can be established that the tax benefit is in accordance with
the object and purpose of the CTA


[Continued]


as stipulated  under
Article 7(1) without resorting to MAP. Under this circumstance, the tax
authorities can grant treaty benefits

7(12)

Specified Limitation of Benefits (SLOB)

If a person is not a qualified person as per para 7(9) nor
entitled to benefits as per para 7(10)/7(11), the CA may grant relief subject
to certain conditions and requirements

India has opted for the provision of SLOB in addition to PPT13

However, the provision of SLOB shall apply to Indian tax
treaties only if the other contracting states have also notified SLOB
provisions

10(3)

PE situated in a third jurisdiction

Suppose the benefit of CTA is denied under
para 10(1) regarding the income derived by a resident. In that case, the CA
of another contracting state (source state) may nevertheless grant these
benefits subject to consultation with the resident state CA

India is silent on this Article. Accordingly, the Article will
be applicable subject to notification and reservations made by the other
contracting jurisdiction as per Articles 10(5) and 10(6) of the MLI

From India’s standpoint, Article 7 has a significant impact. The application of PPT to evaluate treaty entitlement would create significant interpretation issues and the taxpayers may explore MAP compared to the domestic dispute mechanism.


13  A total of 14 countries including India have
opted for SLOB. Greece opted for asymmetric application as per Article 7(b) of
MLI; this thereby allows India to adopt SLOB along with PPT even though Greece
shall apply only PPT

14  OECD (2019), Making Dispute Resolution More
Effective – MAP Peer Review Report, India (Stage 1): Inclusive Framework on
BEPS: Action 14, OECD/G20 Base Erosion and Profit Shifting Project, OECD
Publishing, Paris,
https://doi.org/10.1787/c66636e8-en

4. MAP 2.0- DOMESTIC MEASURES TAKEN BY INDIA

  •  The BEPS AP 14 had suggested a peer review mechanism to ensure adequate implementation of the suggested minimum standard and recommendations. As a result, the peer review undertaken for India in 201914 highlighted India’s progress on the MAP programme and suggested recommendations for more effective functioning of the MAP. According to the peer review and BEPS AP 14, the Indian tax authorities have taken significant steps to reform the MAP framework and make it productive. Two significant reforms include:

  •  The CBDT amended Rule 44G of the Income-Tax Rules and substituted it with the erstwhile Rules 44G and 44H15. The amended Rule deals extensively with the implementation and the procedural framework for the MAP process.

  • In line with the BEPS AP 14 recommendation, India had released a detailed guidance note on MAP16. The MAP guidance addresses many of the open issues on procedural aspects of MAP and, more importantly, clarifies key practical nuances absent in the pre-BEPS era regime for the taxpayers to resort to.

  •  Broad features of the MAP guidance issued by the Indian tax administration, which acts as a handy tool for taxpayers in understanding the MAP framework, are as follows:

Part

Nature

Brief
aspects covered

A

Introduction and basic information

This part addresses the following aspects:

Manner of filing MAP request (Form 34)

Contents of an MAP application

Procedure to be followed in case MAP is filed in the home
country against the order of the Indian tax authority

Procedure to be followed by CA of India upon receipt of a MAP
request

Participation of Indian CA in multilateral MAP cases

Communication of views between CAs through a position paper

India has committed to resolving the MAP cases within an average
timeframe of 24 months

B

Access and denial of MAP

Access to MAP

Provide instances where MAP can be filed

Commitment to provide MAP access in a situation where domestic
anti-abuse provisions are applied Clarification of MAP access in case of an
order under section 201

[Continued]


B


Access and denial of MAP

The situation where MAP access will be granted but Indian CA
will not negotiate any outcome other than what was achieved earlier – such as
Unilateral APA, Safe Harbour, order of Income-tax Appellate Tribunal. In
these circumstances, Indian CA will request the other treaty partner to
provide correlative relief

Denial of MAP in situations where

Delay in filing MAP application

The objection raised by the taxpayer is not justified – Treaty
partner will be consulted before denial

Incomplete / defective application is not rectified within a
reasonable time, or non-filing of additional information within the time
limit

Cases settled through Settlement Commission

Cases before Authority for Advance Rulings (AAR)

Issues governed by domestic law

C

Technical issues

The CA can negotiate and eliminate all or part of the
adjustments provided it does not reduce the returned income

Recurring issues can be resolved as per prior MAP. However,
issues cannot be resolved in advance

Interest and penalty are consequential and hence not part of MAP

Indian CA will make secondary adjustment as per law

MAP cannot be proceeded with where BAPA or Multilateral APA is
filed

Suspension of collection of taxes will be as per Memorandum of
Understanding (MOU) entered into with treaty partner; in its absence, the
domestic law provision will apply

Adjustment of taxes paid by payer according to order under
section 201 of the Act

D

Implementation
of outcomes

India is committed to implementing MAP outcomes in all cases
except when an order of ITAT is received for the same year before
implementing MAP outcome. In such a case, India will intimate the treaty
partners and request them to provide correlative relief. In addition,
taxpayers are provided with 30 days to convey their acceptance of the outcome


15  Notification No. 23/2020, CBDT dated 6th
May, 2020

16  MAP Guidance/2020, F.No 500/09/2016-APA-I,
dated 7th August, 2020, CBDT, Government of India

5. REFLECTIONS

  •  Based on the discussions in the earlier paragraphs, on juxtaposing the Indian tax treaties with the MLI provisions of Articles 16 and 17, a substantial number of existing CTAs already contain the provisions recommended by the MLI. Therefore, the ineffectiveness of MAP in the pre-BEPS era (MAP1.0) may be attributed largely to procedural infirmities and hassles.
  •  Therefore, for MAP 2.0, the need of the hour is to address the existing shortcomings. In this regard, the Indian tax administration’s recent measures to introduce revised rules and the guidance note on MAP are noteworthy and laudable. They reflect India’s approach to resolve treaty-based tax disputes and stick to its commitment to the BEPS inclusive framework. Further, the implementation of reforms based on the FTA-MAP peer review recommendations on BEPS AP 14 also reflect the approach of the Indian tax administration to rectify its defects in the MAP process.

  •  India’s MAP statistics further support the view that MAP 2.0 is heading in the right direction. One can observe that the timeline for resolving MAP cases has considerably reduced considering that the time taken for MAP resolution was more than five years in the MAP 1.0 era17. Speedy resolution of tax disputes fosters certainty and promotes faith in the system. It is imperative to mention that India’s positive outlook to resolve disputes is also reflected with the OECD conferring India and Japan with the MAP award for effective co-operation to resolve transfer pricing cases18.

MAP caseload as at 2019-end inventory and time
frame of resolving

Particulars

TP
cases

Others

Cases started before 1st January, 2016

380

96

Cases started after 1st January, 2016

410

65

The average time before January, 2016 cases – to resolve MAP
[months]

64.86

61.97

Average time after January, 2016 cases – to
resolve MAP
[months]

18.48

19.02

  •  Amidst all the positive changes that the Indian tax authorities have brought in for an effective MAP 2.0, there are still some aspects that require consideration:

  •  Suspension of collection of taxes – India, in its MAP guidance, has stated that in respect of countries with no MoU, the CBDT Circular governs the suspension of tax collection. However, the Circulars / provisions of stay come with certain riders; for example, u/s 254 the Tribunal does not have the power to grant stay beyond 365 days in certain situations19. Therefore, such impediments could put taxpayers in a difficult situation and could impair the outcome of the MAP. Hence, a more flexible approach to suspending tax collection, pending a mutually agreeable procedure, is desirable.

  •  Resolution for recurring issues – Currently, the aggrieved taxpayer must apply for MAP resolution every year regarding recurring issues. Hence, the Indian MAP guidance precludes the CA from resolving in advance or prior to an order by the Income-tax authorities on recurring issues. For speedier disposal of recurring issues under MAP, the Government may consider introducing a simplified process. Such a mechanism will assist in reducing the timelines for MAP resolution for recurring issues and foster certainty. Further, in the case of change in the CA in future years, the incumbent CA should maintain consistency and follow the prior years’ MAP position without any deviation.

  •  ITAT order overrides MAP settlement – The India MAP guidance suggests that the ITAT order will supersede the MAP settlement in cases where the implementation of MAP settlement has not taken place. The rationale behind this is that the ITAT is an independent statutory appellate body and the CA cannot deviate from it. This proposition is against the commitment granted under the treaty. Besides, in practice, most transfer pricing cases are usually remanded back to the field officers setting aside the original assessment. Considering that a faceless regime for ITAT is on the anvil, it is our humble view that India should reconsider this proposition and make suitable legal amendments to give effect to MAP settlements.


CONCLUSION

The existing MAP regime in India can foster tax certainty only by rectifying its flaws and defects. Thanks to the BEPS initiative and the MLI, the MAP framework has indeed got overhauled. The measures adopted by India by aligning towards its global commitment by providing necessary amendments to domestic law, clarifications and resolving disputes in a shorter period signals that the process is heading in the right direction. Measures undertaken through MAP 2.0 for an efficient dispute resolution framework may not be perfect and completely defect-free. Yet, the measures taken are laudable, bringing an element of clarity and certainty for taxpayers. After all, what is coming is better than what is gone!


17  April, 2014 – December, 2020 about 790 cases
overall were resolved under MAP; Source – Ministry of Finance Annual Report,
2020-21

18  https://www.oecd.org/tax/dispute/mutual-agreement-procedure-2019-awards.htm

19  Pepsi Foods Limited [2021] 126 taxmann.com 69
(SC) – The Supreme Court has held that ITAT can grant stay beyond 365 days, if
the delay in disposal of appeal is not attributable to the assessee

SATYAMEVA JAYATE VS. PROPAGATING LIES

We are entering the seventy-fifth year of India’s independence. Satyameva Jayate – the only words on the state emblem – was meant to be the beacon not only for Government but for our people as the only surviving ancient civilisation became a nation. It encapsulates the essence of the entire Bharatiya traditions.

However, with each passing day, not only in India, not only in Governments or businesses, it is increasingly harder to find what is true. Take the example of the Government proclaiming in Parliament that there were no deaths due to lack of oxygen in the second wave1. At one level it may be ‘true’ but reality backed up by evidence tells a different tale.

Truth is harder to sight. This is so because it is surrounded, if not eclipsed, by half-truth, post-truth, selective truth, lies as truth, packaged truth, paid research truth, legitimised / justified truth, cognitive bias, counter-factual views as news, promising something without expected minimum due care, fake news, possible views, misrepresenting, misleading propaganda, false equivalence and more. It is everywhere – from billboards to institutions, from school textbooks to television.

This Editorial is dedicated to where we see such propagation of lies and how and why we should call its bluff. We all are surrounded by lies (from subtle to blatant), perhaps we have sensed it too, but not noticed it very clearly. Yet, nothing is more important today than extracting ‘the true’ and setting it apart from that which is untrue. The ability to do this and its consistent application will be the true celebration of Bharat, its nationhood and its civilisational heritage.

Take the example of cigarettes. It took 50 years for them to be declared as bad for health in America (one billion people smoke today and governments count on revenues from cigarette sales2). On the other hand, marijuana is incapable of causing deaths3 but is illegal, cigarette smoking annually kills 50 lakh people and yet cigarettes are legal and can be purchased anywhere. In fact, a study says that alcohol is 100 times more lethal than marijuana!

In the area of medicine, according to doctors, for insulin-resistant people giving insulin actually kills. The number of diabetics is increasing like nobody’s business4, but the real cause and therefore the way to cure it, is shoved under the carpet. The real cause is not sugar alone but secretion of insulin due to eating and eating too often. Eating is today a global pandemic for industrialised countries. We are likely to die from excess food rather than starvation as was the case a few hundred years ago. While all this is going on, a private medical association recommends, approves products from anti-bacterial paints (for protection from viral transmissions) to LED bulbs (that kill 85% germs), to Pepsico’s Tropicana Fruit Juice (the first medical association to endorse food) when it has high fructose corn syrup that leads to fatty liver and inflammation (NAFLD)!

Let’s look at the Media (of course not all media, but enough above the acceptable threshold and in the mainstream). It has remained at the forefront of propagating lies. If media were a virus, it would have numerous variants popping their heads out at the opportune time. One variant is the ‘outrage’ variant and the second can be called the ‘silent’ variant. They both selectively create outrage or complete silence when reporting, depending on the circumstances favourable to their agenda. Other variants, and they are global, are: fear, hate, blame, anxiety, negativity, victimhood, sensationalism, rhetoric… for which immunity gained by spotting the truth is the only way to not succumb. Many suffer from diarrhoea of words but constipation of thoughts5.

What about the web? If you search Ayurveda on Wikipedia, the second sentence (the authorship of which is attributed to the same private medical association) calls it the practice of quacks – whereas Sushrut is the father of surgery, having done at least eight types of surgery from plastic surgery to dental surgery to treating fractures and removing stones, full 3,500 years ago! As you can imagine, this has been put up with a purpose, whereas if you look at the Encyclopaedia Britannica, it simply gives facts and not selected negative opinions.


1   https://www.livemint.com/news/india/no-deaths-due-to-lack-of-oxygen-were-specifically-reported-by-states-uts-during-second-wave-govt-told-parliament-11626801416761.html

2   28% + up to 21% cess, but
is fairly low compared to many countries. Approximately Rs. 53,750 crores is
the revenue collection

3   https://www.healthline.com/health-news/can-marijuana-kill-you#More-concerns-with-more-availability

4   In a ten-year period
between 2007 and 2017, diabetics increased from 40.9 m to 72.9 m in India.
Globally, 171 m people in 2000; likely to reach 366 m as per WHO

5 Adapted from what Dr. A.
Velumani wrote recently on social media

It’s there in professions, too. People give ‘possible views’ (we never knew that the possibility of something can become a professional view for there are infinite possibilities and they cannot fit the law just because they are possible). Many of these are outrageously over the top. Here is one: schools selling notebooks to students could ‘possibly’ be treated as service requiring registration under GST.

One actress put out videos stating how firecrackers during Diwali made her run out of breath due to her asthma; and later she celebrated her wedding with a lavish fireworks show. Look at the advertising around us, which often sells what you don’t need and even can’t afford by exploiting fears and insecurities. Or for that matter see who are called our heroes? They are not just actors and entertainers, but rather soldiers, scientists, entrepreneurs, sports persons and many others. The Punjab CM recently tweeted that three goals were scored by Punjab players at the Olympics hockey competition and made it sound as if Punjab alone got the goals. Whereas, in a team sport, players (from six different states in this case) got the ball to a player who then scored a goal.

The top court pushed back a plea for President’s Rule in Bengal due to the killing of innocents in post-poll violence by 15 days but took suo motu cognizance of the death of a judge in Jharkhand. Courts often take suo motu cognizance, but defer cognized facts for another day. Some say it’s because the common man is expendable. Who doesn’t remember the Rs. 1 fine on a top lawyer for criminal contempt of the Supreme Court for ‘scandalising the court’ on Twitter. He had the wisdom to know what behaviour is expected and the ability to pay a reasonable fine. But these selective approaches to the truth continue even from the keepers of the law!

Reservation, a national menace today, was meant to be continued for ten years (1951-61). It is now a mega tool of inducement for votes, appeasement and killing meritocracy. In fact, it is an outright promotion of benefits based on caste (birth-based) rather than class (economic need). This has made people covet and convert to get benefits. This is legitimising the unjust. This is a race, not to the top, but to the bottom.

Each Independence Day let’s increase our ability to extract ‘the true’ and set it apart from lies with courage and sharpness. As professionals, this is what we are trained for and are expected to deliver. Unfortunately, it cannot be defined by laws and depends on context many a time. At a mundane level truth is evidenced by a measurable reality (existence of something or occurrence of something), often it is what is beneficial and not just convenient (punish the wealthy for non-serious offences with a fine rather than imprisonment for they give taxes and generate jobs which can be used for the welfare of many rather than killing their business), sometimes it is worthy of one’s role (Federer was asked for a pass at the Australian Open by a security guard in 2019) and so on. Times are such where the false is promoted as true and so one must prefer and promote the truth. In the words of a famous author: 

Sometimes high-ranking people and institutions sacrifice truth for something else like peace, etc. Martin Luther wrote ‘Peace if possible, truth at all costs.’ Because when truth is lost, all else that remains will be detrimental and ephemeral. In the words of Carl Sagan: If it can be destroyed by the Truth, it deserves to be destroyed by the Truth.

Happy 75th Independence Day! Jai Hind!

Raman Jokhakar
Editor

LOKMANYA

Every educated Indian knows about Lokmanya Tilak. However, very few know about the real greatness, uniqueness and versatility of this multi-faceted son of India. The First of August, 2021 is the 101st anniversary of his death. It will be really inspiring to know about the amazing range of his activities and achievements.

He was born in a very small village in Ratnagiri district. His father was a school teacher. His real name was Keshav but he was popularly known as ‘Bal’. He was one of the well-known trio of Indian patriots called ‘Lal’ (Lala Lajpatrai), ‘Bal’ (Bal Gangadhar Tilak), and ‘Pal’ (Bipin Chandra Pal).

Most leaders of those times did their graduation in literature, political science, history, economics, law, etc. But Lokmanya was a scholar in Mathematics and Astronomy. His brain was like that of a scientist. Once he was asked, ‘Which portfolio would you prefer after India becomes independent?’ He said, ‘It is because of the inaction of people like you that I had to enter politics. After Independence, I would like to be a Professor in Mathematics.’ He wrote two scholastic treatises on Astronomy – ‘The Arctic Home of Vedas’ and the ‘Orion’. He started a ‘panchaang’ (calendar) based on his knowledge of astronomy. His ‘Tilak Panchaang’ is still in vogue. Interestingly, after matriculation and before entering college, he devoted one full year to acquire physical strength. Perhaps he could anticipate the strenuous struggles he would face in his future life.

  •  He established the New English School and Fergusson College. He was a great educationist and his basic aim was national education.
  •  He started two dailies, ‘Kesari’ in Marathi and ‘Marhatta’ in English. He is still respected as a great journalist. The British Government used to be afraid of his editorials.
  •  For almost 20 years of his life, he faced litigations and court proceedings and spent about ten years in jail as a freedom fighter.

His knowledge of the law was amazing. He had done his LL.B. and for a livelihood used to give tuitions in law to students from different states. He inculcated the spirit of patriotism among them. He lost just one case against him in the High Court. He was then sent to Mandalay Jail (kala paani). There, without any reference books, he raised certain points of law and of Hindu traditions (regarding adoption) and he was acquitted by the Privy Council.

His knowledge of philosophy was acclaimed by most world scholars when he wrote ‘Geetarahasya’ (in English) despite the hard and strenuous life of Mandalay. For that, he studied about 400 books from different languages. He also learnt four languages for this purpose.

He was a visionary. He realised the importance of cinema as a powerful medium and supported Dadasaheb Phalke, the first film-maker of India. He encouraged his work through his newspapers and raised funds for him.

He advocated many social reforms. For public education, social reforms and bringing the people together, he started the ‘Ganeshotsav’ and ‘Shivjayanti Utsav’. An anti-alcohol movement was also started by him and he even demanded a prohibition law. This seriously affected the revenue collection of the Government.

He was also an entrepreneur. Hardly anyone knows that he set up his own ginning factory at Latur and a sawmill at Ratnagiri; he also supported the glass factory at Pune. He had a deep sense of commerce and economics. He was one of the promoters of the first Indian joint stock company ‘Bombay Swadeshi Co-operative Stores’, a listed company.

His sacrifice for the freedom of India was unparalleled and he was known as the father of Indian unrest (against British rule).

These are only a few highlights of his life. That was why he was loved and revered by one and all – a real ‘Lokmanya’.

Doesn’t he deserve our humble ‘Namaskaar’?

BOMBAY CHARTERED ACCOUNTANTS’ SOCIETY: ANNUAL PLAN 2021-22

72ND ANNUAL GENERAL MEETING AND 73RD FOUNDING DAY

The 72nd Annual General Meeting of the BCAS was held online on Tuesday, 6th July, 2021.

The President, Mr. Suhas Paranjpe,
took the chair and called the meeting to order. All the business as per
the agenda contained in the notice was conducted, including adoption of
accounts and appointment of auditors.

Mr. Mihir Sheth,
Hon. Joint Secretary, announced the results of the election of the
President, the Vice-President, two Honorary Secretaries, the Treasurer
and eight members of the Managing Committee for the year 2021-22.

The ‘Jal Erach Dastur Awards’ for the Best Articles and Features appearing in the BCAS Journal during the year 2020-21 were also presented on the occasion. For Best Article the Award went to Sandeep Parekh and Manal Shah (both Advocates) for their Article PFUTP Regulations – Background, Scope and Implications of 2020 Amendment. The Award for Best Feature went to CA Vinayak Pai for Financial Reporting Dossier.

The July special issue of the BCA Journal was e-released by Mr. Azim Premji. It carried special articles on Effects of the Pandemic on CA Profession (by CA Ninad Karpe and CA Madhukar N. Hiregange), The Economy (by Niranjan Rajadhyaksha), The Human Psyche (by Dr. Bharat Vatwani) in addition to the regular articles and features. Before the conclusion of the AGM, members, including Past Presidents of the BCAS, were invited to share their views and observations about the Society.

The 73rd Founding Day lecture was delivered at the end of the formal proceedings of the AGM. It was an outstanding oration by Mr. Azim Premji, Founder Chairman of WIPRO, who spoke on the topic ‘Professional Excellence and Social Responsibility’. It was attended online by more than 3,392 professionals on Zoom and the YouTube channel of the BCAS.

OUTGOING PRESIDENT’S REPORT

SUHAS PARANJAPE:
You have just witnessed a short video clip presenting the annual
activities for 2021-22 in summarised form. (The annual report has
already been emailed to members.) You must have also noticed that the
clip ended with my favourite song Jai ho! from the popular movie Slumdog
Millionaire.

During the year just gone by, I received many
answers / solutions / feeds to various situations through intuition,
experience, the observations of many Past Presidents, my Chairmen,
Office-Bearers, Managing Committee members and volunteers. They made my
year successful so that today I can say with pride – ‘Jai Ho!’

I acknowledge the virtual presence of Past President P.N. Shah, Dilipbhai Thakkar and other seniors. I offer my namaskaar, adab to all of you for the opportunity given to me to serve you as President of the BCAS. I thank each and every one of you from the bottom of my heart.

I have had a unique privilege and I feel honoured to say that I am the first-ever ‘virtual’ President of the BCAS in
its 72-year history! At the same time, I sincerely hope and pray that I
would be the last one to have registered such an achievement. I don’t
wish to have any competition in this! On a lighter note, if ever the BCAS decides
to make Past Presidents eligible for Presidentship in the future, I
should be given the honour of being the first in the line! All of you
will agree with me, and since this is a recorded meeting, I can take
this as proof of your agreement!

I do not wish to repeat how
challenging the year was and how we converted all ideas into
opportunities and so on. All of you were part of this endeavour. I will
only say that we explored and exploited the power of the BCAS platform and the power of digitalisation to a large extent to create visibility, to reach higher, to perform better.

Right
from the beginning of my tenure, I had decided that I would try to be
like plain, simple and clean (nirmal) water in which one can mix any
colour that would lead to a colourful experience. My role was only to
ensure that the colours are shuddha, satvik, traditional Indian colours
without any chemicals in them. In actual fact, I never had to play the
role of identifying whether the colours are good, genuine or otherwise.
All the colours during the year were original, shuddha and satvik beyond
my imagination. I am happy that I could carry this thought process to a
large extent to my satisfaction and it made my tenure and term really
colourful and glorious. I thank all of you for the same.

There are two or three initiatives that I would like to mention.

First, the BCAS Chowk.
I had heard this subject being discussed in the Managing Committee
meetings many times and for many years. It became my focus area and I
started working on it immediately after taking over as President. There
were many hurdles and roadblocks in the process. The process is very
long and requires a lot of follow-up. As per the Municipal Corporation’s
policy, special permission is required for names to be given for an
organisation. Had there been no Covid lockdowns, we would have had our BCAS Chowk by now. But we are still trying our best and we hope that we will have BCAS Chowk
added to our address in the next few weeks. I must place on record the
one person, other than our Past Presidents, Office-Bearers and
volunteers, who stood by me, none other than the Maharashtra Industry
Minister, Shri Subhash Desaiji. He considered our request
immediately and set out to honour our voluntary organisation that has
existed for 72 years and which is an outstanding achievement. All of us @
BCAS thank him for his support.

A second initiative which I kept as my focus point was to bring more vibrancy and activity to the BCAS Foundation. All the trustees supported us as we formed our Project Management Committee (PMC) under the chairmanship of CA Dr. Mayur Nayak.
We have started joint activities with other NGOs. But we feel that
there is still a long way to go and much more to be done. I thank all
the trustees and PMC members for their active involvement and support.

Last
but not the least, we had a good fellowship and association with sister
organisations such as the IMC, the CTC, our own WIRC, the regional CA
associations of Ahmedabad, Chennai, Bengaluru, Lucknow and Surat – we
had joint programmes, joint representations and so on. It was easier
with our digital base. For BCAS members we did good networking
with publication services for regular discounted publications and with
software vendors to give competitive pricing.

The pandemic taught
us so much – how to work, how to conduct events / programmes, how to be
educated without attending physical seminars and conferences, how to do
audits and render services without visiting our clients’ place – in a
nutshell, how to remain relevant under all circumstances. The show must
go on and with much more force through innovations. Zoom, Meet, Teams,
etc., became our family members, ‘You are on mute, Sir’ became our tag
line! To be positive became negative and stressful, being and remaining
negative became an honour. We of this generation are lucky to have lived
this experience. But the sad part is that the pandemic also taught
families how to face health crises, financial crises and in a few cases,
even to live without their near and dear ones.

Ironically, the
pandemic created a great deal of financial inequality but it treated
every one equally – the rich, the poor, the elderly, the youngsters, and
there was no gender inequality. One thing is certain now, the ‘new
normal’ is now settled and it will be the future – maybe in a hybrid
manner and for which the BCAS should prepare itself, both mentally and technologically.

I congratulate the incoming new team of Abhay, Mihir, Chirag, Anand and Kinjal – it is a great combination of experience, maturity, technical and tech-savvy people to take BCAS forward
and into a new orbit and zoom towards its 75th year in style with new
hope (asha) and inspiration (akanksha) and to greater heights
(unchaiyaan). I wish them all the best with my support and good wishes.
All of you have played your innings for me and now it’s my turn to help
you in whatever way I can. I wish you all the very best.

I can’t thank my family members enough – my mother Shalini, wife Swati and son Aarav, for their support and encouragement. My senior partners Mayurbhai Vora, Bharatbhai Chovatia and their families kept me motivated all along, as did all my other partners, Kinnari, Bhakti, Ronak and Vinit and
all the team members. I thank everyone in my office for their help and
support. Many of my clients-cum-mentors, friends and relatives always
provided me with inputs and appreciation.

Team BCAS has
always been the backbone of all Presidents. I and my Office-Bearers
hardly met any of them during the year. We are aware that Work From Home
is not always easy. It has its advantages and disadvantages, but all of
them worked to the best of their abilities. There is always a scope for
improvement which will enhance the Office-Bearers’ execution and
productivity. We are all time-bound executives. As our long-term
resources, it is our duty and responsibility to keep team BCAS motivated at all times. I wish all of you a good life ahead.

Covid
is still in the air and it will require a huge effort by the Government
machinery to keep it in control. Besides, there is the vaccination
(which is an external support); but if all of us build our own immunity
(an internal strength), I am sure we would be able to tackle this health
challenge. I wish all of you a healthy and happy life.

I
conclude by bowing down to the huge membership of this large
organisation for its support during the year. May I now request incoming
President Abhay to present his annual plan for the year 2021-22.

INCOMING PRESIDENT’S SPEECH

ABHAY MEHTA: Good evening, BCAS family. My colleagues on the virtual dais, Suhas, Vice President Mihirbhai, outgoing Joint Secretary Samir, Joint Secretary Chirag, Incoming Duo – Treasurer Anand and Joint Secretary Kinjal, virtually assembled, respected Past Torchbearers of BCAS, seniors and fellow professionals.

I heartily welcome you all to the AGM.

I am addressing this august gathering due to the honour showered on me to lead the Temple of Knowledge – BCAS as the President in its 73rd Year.

I have a mixed feeling of elation and responsibility at this moment when I am addressing you all.

Elation, because I have been considered worthy to lead BCAS for a year and Responsibility for upholding and carrying forward the rich legacy of BCAS. I am also excited
that I shall have an opportunity to implement some of the initiatives
which I feel will be able to contribute to the development of the
profession thereby enhancing the image of BCAS.

The responsibilities are manifold. First of all, I have to prove my worth during the year to the torchbearers of BCAS who have reposed their confidence in me to lead the Society. Secondly, I have to meet the high standards set by my worthy predecessors. Thirdly, I am conscious of the dynamic changes which our profession is passing through, where an organisation like BCAS has to play the role of catalyst to empower professionals with relevant learnings.

The role of BCAS over
all these years has been transformational and I am conscious of this
role, which has been passed on over all these years by each President to
follow. Here, I shall be guided by the wisdom of my GURU Mahatria Ra,
who has very well said:

The purpose of knowledge
is not to build memory
but to create
understanding and transformation.


At
this juncture, I would like to bow before Lord Shriji Bawa, for
blessing me and making me worthy for the coveted post of President at BCAS.

I also seek the blessings of my parents Late Rashmikant Mehta and Late Kailas Mehta. I am sure wherever they are, they would shower their blessings and would feel proud to see me at the helm of BCAS. In climbing up the ladder of the profession, there is one critic and well-wisher who has played a vital role by taking care of the responsibilities of the family and also on the social front. She is my wife Nipa,
whom I want to thank profusely for being a solid support in my journey
as a professional. She ensured inculcating values and taking care of the
upbringing of our son Udit, who is also a qualified professional.

Before I share my journey at BCAS and my vision for the year, I take this opportunity to summarise the year gone by under the able leadership of Suhas.

The year had started amidst the pandemic, but the zeal of Suhas was like a double vaccinated person in a hurry to serve BCAS with his selfless service. His Theme for the year was ‘Tradition, Transition and Transformation’. He has excellently steered BCAS as per his theme to take it through the process of Transition in a manner which did not lose the values and ethos of Tradition. He stepped on the accelerator and increased the speed of Transition which brought about many Transformational changes in the way BCAS delivered its offerings to its members and the public at large.

Suhas’s approach made me relive the preaching given by my GURU Mahatria Ra,

‘Make
yourself a success magnet. Begin. Take the lantern in your hand, and
you will always have light enough for your next step. One step at a
time… Go… Keep going… Keep growing.’

I felt he ably
applied the above during the time of the pandemic when things were hazy
and the road was not just less travelled but I would say, it was never
travelled.

During the year, we witnessed Lecture Meetings and Panel Discussions on topics as varied as ‘Building a Professional Services Firm’ to ‘Cryptocurrencies’. The Residential Courses in Virtual Avatar were so engrossing that everybody was saying ‘Yeh Dil Maange More’. The meticulous planning and the thought process which went into organising Group Discussions and General Assembly were immaculate. It is for certain that a trend is set, even after restrictions on physical meetings are lifted, there will be a Hybrid Model to be worked out to serve the interest of participants who may not be able to travel to the destination of the event.

Suhas, I was witness to the interest you took in the planning of each event and the way in which you delegated decision-making for each event in the hands of the able teams backed by effective inputs and guidance wherever required from your end. Though the year was only through Virtual Events, you made your presence felt as if you were there with each one of the executing people involved in the events.

I was a silent observer of your management style and I must admit that you have a humane approach to deal with the situations. You remained calm and composed and were never tensed even during the moments of crisis. I can definitely say that my key takeaway while being deputy has been to remain cool in all situations.

Suhas, I convey my best wishes for the future, with confidence that your contribution during my tenure will be equally valuable in taking BCAS to greater heights.

Now, I turn to my exciting journey at BCAS. I was witness to my father’s passion as a BCAS member as he was an avid reader of the BCA Journal and actively participated in the seminars and RRCs. He always encouraged me to become a member of BCAS, which I did in 1994 and immediately started attending RRCs. In those years the RRC was held in the month of April and I used to celebrate my birthday at RRCs for some years.

My participation at the RRCs and seminars was noticed by our Past President Mr. Rajesh Muni and he invited me to join the Core Group in the year 1999-2000. I convey my sincere thanks to Rajeshbhai, for involving me actively at BCAS. I was inducted in the Accounting & Auditing Committee which gave an impetus to my passion in this area of the profession. I was made Convener of this Committee in the year 2003-04 and continued to serve in that capacity for 15 long years. During my journey as Convener of the Accounting & Auditing Committee, I worked under the Chairmanship of not less than six Past Presidents.
The learnings from each one moulded my outlook towards the profession
and assurance area of practice in particular. I would make a special
mention of Himanshu Kishnadwala, under whom I was convener for
the maximum number of years. He has that sense of urgency with an eye
for detailing, which appealed to me and also inspired me to become
meticulous in approach and to be prompt in responding to the issues. I
served during the past two decades on other committees too, but my heart
was always in the field of Auditing and Company Law.

On my birthday in 2017, Narayanji, who was to take charge as President for 2017-18, approached me to be part of his team. Narayanji,
I convey my sincere gratitude to repose confidence in me and inducting
me as an Office-Bearer. I also got fair glimpses of working at BCAS when my partner and dear friend Chetan had been the President in the year 2016-17.

I can vouch for one thing from my experience, that the model of BCAS with Past Presidents as Chairmen to guide the Conveners and the Committees, is so robust that there is perfect grooming of the young talent to be sound not just academically but also administratively.

I owe a lot to BCAS for improving my skills and outlook towards the profession. The culture at BCAS
is such that the seniors make youngsters really comfortable during
exchange of ideas by frankly sharing their knowledge and experience.

After reminiscing my journey at BCAS, I am now eager to share with you my thoughts on the year 2021-22 where I aspire to contribute to the progress of BCAS and the profession at large. This aspiration is with an approach where I would be heavily banking on the collective wisdom and support of all the Committees. I had occasion to convey my thoughts to each committee when we had our first meeting for planning the activities for the year. I am glad that each committee has wholeheartedly supported the Theme which I have for the year and they have commenced planning events encompassing the theme.

I firmly believe in what my GURU has preached on pursuing goals and achieving the same. He says:

The strength with which an idea is pursued
Will magnetise the resources
that are required
for the accomplishment of the idea.

You
may feel, I am referring many a time to my GURU Mahatria Ra. However, I
would at this juncture share that I have developed a lot of positivity
by going through his teachings. I always remind myself to have a
positive approach whenever I face situations of difficulties or crisis
in my professional or personal life. This approach has always provided
me a path since it is calmness which allows a rational thought process.

Let
me now delve into my theme for the year. It is based on the acronym
which is the current flavour for businesses, professionals, capital
markets and economists. However, the same acronym for my theme is for a
different meaning and purpose. Individually, each word in the acronym is
of critical importance to our profession as well as the country as a
whole.

The Theme for the Year is ‘ESG’.
EMPOWERING     SCALING     GLOBALISING

To achieve Empowering, I have identified certain executable initiatives:

  •  I wish that BCAS becomes an enabler of showcasing latest knowledge on the upcoming areas of professional opportunities to the SMPs and Young CAs.
  •  Concerted efforts be made to create a platform for networking amongst members of BCAS from all over India.
  •  My aim is that the public at large should not view CAs merely as Tax Advisors but they should perceive CAs as Business Advisors.
    Towards this shift BCAS shall aim to equip its members and CA community
    with working knowledge on other relevant ancillary laws.

Scaling up of the Professionals at BCAS is planned through the following initiatives:

  •  We have in all ten committees, professionals with experiences in varied fields of profession and business. It is my endeavour to create a platform, where thought leaders from BCAS Core Group and through the contacts of BCAS members be brought on the BCAS Platform to guide SMPs by providing vision for scaling up their offerings. The dissemination of knowledge
    should be such that they can equip themselves for providing services
    which offers professional satisfaction and in turn adds to the efforts
    towards nation building.
  •  BCAS has been a leading professional association and has its reach throughout India. However, there have been barriers to go on its own beyond a certain reach. A concerted effort shall be made to reach out to various local CA chapters from different parts of the country as well as trade and industry bodies of various states. In reaching out, I have requested each committee to become knowledge partners with them, thereby attracting members and also to jointly create advocacy on critical issues to be taken up with the regulators.
  •  The year gone by has provided glimpses of the changes in the profession which are to come, in fact at a rapid pace on account of adoption of technology in all spheres of life. BCAS shall ensure to design seminars, workshops enabling professionals to embrace technology. This will bring accuracy in the execution of services and efficiencies in deliverables.

Indian
businesses are going places and have internationalised their
operations. Our profession is also spreading its wings. To ensure our
members are provided opportunities to explore Globalising their services, I have plans for BCAS to take the following steps:

  •  To organise programmes creating awareness of the professional services which may be offered by members at a global level.
  •  In this virtual world, distances do not matter. We can now be enlightened by speakers of international repute. Efforts shall be to share latest global developments in varied fields of professional interest through such speakers. Also seminars, workshops shall be planned to disseminate knowledge on latest developments which enables members to equip in rendering services at global level.
  •  There would be professional associations similar to BCAS operating in different geographies worldwide. There will be efforts to tie up with few such associations to cross-sell events and publications. Efforts will also be made to understand best practices from such counterparts and bring to our members to enable them to be globally relevant.

These are my thoughts which I will drive through the year. I am of the humble belief that if our team of dedicated Core Group provides their valued inputs on the aspects of this year’s theme, we shall be able to add at least some additional value to the members’ professional capabilities.

I have been part of the Core Group since two decades. There have been many initiatives over the years, which have developed the Brand BCAS. Over these years and lately since I entered the Managing Committee and have been a part of the Office-Bearers, I have observed that there are various pockets of operations within BCAS, which can be further improved.

We have to make conscious efforts not just in a single year of each President. Rather, a concerted and long-drawn process has to be evolved to improve the functionality within BCAS. With this approach in mind, I discussed my thoughts with the incoming Office-Bearers team. As an outcome of the same, I am laying before you all, the Internal Goal-Setting exercise for BCAS, for which I have taken assurance from the Office-Bearers to continue on the same in the years to come.

I have termed this Internal Goal-Setting as LEAP.

This is my Leap of Faith, that the BCAS will attain much greater heights in the years to come by executing the exercise by the name LEAP.

Again, I am tempted to quote my GURU Mahatria Ra:
Highest manifestation of
Human intelligence is
FAITH

LEAP denotes:
• Leadership for BCAS;
• Excellence
at BCAS;
• Accountability
to BCAS members; and
• Professionalism
in BCAS.

I would like to elaborate each in a few words.

Leadership
BCAS is unarguably one of the leading professional associations. To continue and improve its Leadership position and to be of relevance for the profession, BCAS will have to identify and groom future leaders.

Excellence
Excellence will be possible by keeping a close watch on the latest developments in the profession. There has to be continuous exchange of ideas in each committee and frequent meetings to deliberate on such developments. Once there is such alacrity, then it would be easy to identify relevant offerings for the benefit of members and public at large.

During the pandemic, we have realised the power of technology. Now there are no barriers of distance for bringing on board excellent faculty and for attracting participants for professional offerings. BCAS will initiate all the necessary steps to have an edge technologically while offering learning initiatives so as to be considered as an excellent place to imbibe knowledge.

Accountability
I am aware that we have been receiving lots of grievances related to the website functioning, online payments functionalities, delayed responses to the issues raised by members, etc.

There is a thought process to improve experience of members with the BCAS as an organisation. Towards this end, we shall be creating dedicated email ids for various types of grievances to be monitored by a responsible person at BCAS.

At Office-Bearers level, we shall take on responsibility to monitor the replies given and unattended grievances.

We shall develop a feedback mechanism, whereby professionals can send their experiences for the hardships faced in various compliances as well as their viewpoints on topical subjects for the progress of the profession. The collation of such feedback will be sent to the respective committees to deliberate and on quarterly basis the Managing Committee would discuss to give responses to the respective members regarding the BCAS view and action taken at its end.

Professionalism
BCAS is an organisation run by the professionals and for the professionals. It is of paramount importance to have professionalism inculcated in each area of its operations. We are conscious of the fact that BCAS is run by volunteers and hence there is a need to have technology playing
a greater role in seamless execution of its functions. This year while
passing the accounts, the Managing Committee has allocated a substantial sum of Rs. 35 lakhs towards Technology Fund. We shall ensure effective use of the allocation towards a robust database, efficient execution of events and provision of timely information for the members. We shall take steps to have effective training of the manpower so
as to execute their functions in the most efficient manner. This will
also reduce the burden on the young core group members who have to
devote time and effort during the events’ execution.

I know I have projected many things to be carried out during the year, which may be felt difficult to attain. However, I commence my journey as President with a clear conscience, which is truth. The truth is both honesty and integrity. I want to assure each one in the BCAS family, that my efforts to achieve what I have laid before you all will be with honesty and integrity.

With these words, I conclude my speech and I hope that my efforts with your guidance and support will take BCAS to further heights of glory.

Thank you all.

WORK FROM HOME

In my school days, the most boring thing was ‘Homework’. It was a serious hindrance to my playtime. Even during Diwali and Christmas vacations, there used to be homework. I used to curse the teachers and parents and used to wonder who had invented this stupid idea of homework for school children.

After I grew older and saw the homework assignments of my children, I realised that teachers could not do full justice to teaching in class and expected the parents to take care of the deficiencies in their teaching. When parents realised that their ward had not understood what the teachers taught, they would think of tuitions or coaching classes. That added to the misery of the poor school students. So now, even little kids are occupied at least ten hours a day (!), including school time, tuitions, hobby-class and so on. What a torture.

After the school days were over, I heaved a great sigh of relief – relief from ‘homework’. But destiny can be cruel. Corona and the consequent lockdown are the culprits and the ghost of homework has come back to haunt us again, this time in the form of ‘Work From Home!’

When a person physically attended a corporate office, she used to be occupied for a maximum of 12 hours a day, including commuting time. It is a different story that the new work culture makes a corporate employee start working in the evening. This is actually just to ‘show’ his ‘sincerity and dedication’. One of the pretexts is to sit in late to suit the US timings.

But now this ‘Work From Home’ culture has crossed all limits and keeps us ostensibly occupied for 16 hours a day if not more.

I am told that since we are already in the era of regulations, the Government has tabled a Bill called ‘Work From Home Regulations (Restrictions, Liberties and Facilities) Bill, 2021’.

The salient features of the proposed regulations reveal that in addition to the salary, employers shall pay to the employees:

1) Domestic harassment / violence allowance (at the wife’s hands);

2) Allowance for tea, refreshments and meals that they would have got in the office but not now;

3) ‘Voucher allowance’ – the amount which an employee is deprived of for not being able to claim ‘reimbursement’ of un-incurred expenses.

4) Rent allowance – an employee is required to use some space at his residence. The office saves the corresponding expenses on maintenance of office, electricity, etc. So, a proportionate rent allowance would be paid to the employees;
5) Fitness allowance – In physical working, employees could maintain their fitness by commuting in trains, running to catch buses, some walking, etc. But people sitting at home have to specially spend time and money on exercises and fitness.

The Bill also seeks to regulate working hours at home, holidays and so on.

ICAI has demanded that the implementation of this Act be audited by practising CAs. It has also formed a committee to frame a separate Standard on Auditing for this purpose!

Note:

This may seem like fiction, BUT, please note that France has passed a law that there won’t be any obligation on the part of employees to receive / act upon any instructions or directions from employers on their weekly and other holidays. So there!

Suggestions on the Bill are invited from our valued readers.

Articles 5 and 12 of India-Singapore DTAA – Seconded employee working under control and supervision of Indian company did not constitute service PE – Service PE under Article 5(6) and taxability as FTS under Article 12 cannot co-exist – Services provided did not fulfil ‘make available’ requirement under Article 12 of India-Singapore DTAA

15.
TS–336–ITAT–2020 (Del.)
DDIT vs. Yum
Restaurants Asia Pte Ltd. ITA No.
6018/Del/2012
A.Y.: 2008-09 Date of order: 16th
July, 2020


Articles 5 and 12 of India-Singapore DTAA – Seconded employee working
under control and supervision of Indian company did not constitute service PE –
Service PE under Article 5(6) and taxability as FTS under Article 12 cannot
co-exist – Services provided did not fulfil ‘make available’ requirement under
Article 12 of India-Singapore DTAA


FACTS

The assessee, a
resident of Singapore, was engaged in franchising of certain restaurant brands
in the Asia Pacific region (including India). It entered into a technology
license agreement with its Indian AE (I Co) for operation of restaurant
outlets. I Co in turn appointed a number of franchisees for operating restaurants
in India under brand names KFC and Pizza Hut.


Mr. V was an
employee of the assessee who had been deputed to India to work under the
control and supervision of I Co. Mr. V was working solely for I Co. However,
the assessee continued to pay remuneration to Mr. V. I Co reimbursed the amount
equivalent to the remuneration of Mr. V (after deducting tax) to the assessee.


The A.O. concluded
that Mr. V constituted service PE of the assessee in India. Hence, the amount
reimbursed by I Co to the assessee was in the nature of FTS and taxable in
India. The A.O. further concluded that the assessee had agency PE in India.


In the appeal,
after referring to relevant clauses of the Deputation Agreement and the
evidence furnished by the assessee, the CIT(A) held that Mr. V was not an
employee of the assessee. Hence, he did not have any right / lien over his
employment. Consequently, there was no service PE of the assessee.


HELD

Service PE

  •  The deputation
    agreement between the assessee and I Co mentioned that the assessee was not
    responsible for, or assumed the risk of, the work of assignees; assignees would
    work under the control, direction and supervision of I Co; and the assessee
    released assignees from all rights and obligations, including lien on employment,
    if any.
  •  CIT(A) had given
    the following findings:
  •  An employee of I
    Co leading the business development team had resigned. Mr. V was deputed to
    India as his substitute. Upon expiry of the deputation period, Mr. V was
    inducted as an employee of I Co.
  •  During the
    deputation period, I Co had reimbursed the remuneration paid by the assessee on
    cost-to-cost basis. I Co had also deducted the applicable tax. Mr. V had paid
    tax in India on his remuneration.
  •  All the facts and
    circumstances indicate that Mr. V was an employee of I Co and the assessee had
    merely acted as a conduit for payment of remuneration to Mr. V in Singapore
    since his family was in Singapore.
  •  Other evidence,
    such as attending board meetings of I Co, signing financial statements of I Co
    as its director, etc., also showed that Mr. V was involved in the day-to-day
    management of I Co.
  •  Revenue had also
    not controverted the findings of the CIT(A). Thus, the deputation of Mr. V did
    not constitute service PE of the assessee in India.
  •  Even if a service
    PE of the assessee in India was constituted, no income can be attributed to the
    service PE because for computing profit attributable to PE, expenses incurred
    (in this case, remuneration paid to Mr. V) should be deducted. Having regard to
    reimbursement of remuneration on cost-to-cost basis, the income of the PE would
    be ‘Nil’.


FTS
taxability

  •  Having regard to
    provisions of Article 5(6) read with Article 12 of the India-Singapore DTAA,
    service PE and taxability as FTS cannot co-exist.
  •  Even otherwise,
    services did not fulfil the ‘make available’ condition under Article 12 of the
    India-Singapore DTAA.
  •  Mr. V worked as
    an employee of I Co and paid taxes on his remuneration. Taxing the same again
    as FTS would result in double taxation of the same income.


Agency PE

  •  The A.O. did not
    establish under which limb of definition of agency PE in Article 5(8) of
    India-Singapore DTAA the agency PE of the assessee was constituted in India.


Note: The Tribunal distinguished the Delhi High
Court decision in the case of
Centrica India Offshore Pvt. Ltd. [2014] 364 ITR 336 as not applicable to the facts under
consideration. The exact basis of this conclusion is not clear.
 

Articles 11, 12 of India-Netherlands DTAA; section 9 of the Act – Guarantee charges paid by Indian company to non-resident AE were not: ‘interest’ under Article 11 as there was no debt and income was not ‘from debt-claim’; FTS under Article 12(5) as although provision of guarantee was a financial service, it was not consultancy service contemplated in Article 12(5

14. [2020] 117
taxmann.com 343 (Delhi-Trib.)
Lease Plan India
(P) Ltd. vs. DCIT ITA Nos. 6461 &
6462/Del/2015
A.Ys.: 2009-10
& 2010-11 Date of order: 15th June, 2020


Articles 11, 12 of
India-Netherlands DTAA; section 9 of the Act – Guarantee charges paid by Indian
company to non-resident AE were not: ‘interest’ under Article 11 as there was
no debt and income was not ‘from debt-claim’; FTS under Article 12(5) as
although provision of guarantee was a financial service, it was not consultancy
service contemplated in Article 12(5)


FACTS

The assessee was
engaged in the business of leasing motor vehicles, financial services and fleet
management. It intended to borrow funds for its business from banks in India.
It had an AE in Netherlands (Dutch Co) with which it entered into an agreement
for provision of guarantee to banks in India. On the strength of such
guarantee, banks lent funds to the assessee. As per the agreement, the assessee
paid guarantee charges to Dutch Co.


Before the A.O.,
the assessee contended that the payment being reimbursement of actual expenses,
it was not chargeable to tax in India and hence the tax was not deductible. The
A.O. concluded that since payment was made to a non-resident for rendering
services, it was covered u/s 9(1)(vii) as FTS. As the assessee had not deducted
tax, the A.O. invoked section 40(a)(i) and disallowed the entire amount.


In appeal, the
CIT(A) confirmed the order.


HELD

Whether
guarantee charges interest?

  •  It was undisputed
    that guarantee charges paid by the assessee to Dutch Co were chargeable to tax
    in India. However, it was to be examined whether it was in the nature of
    ‘interest’ in terms of Article 11 of the India-Netherlands DTAA.
  •  2Any
    income can be characterised as ‘interest’ if it is ‘from debt-claim’.
    Thus, two criteria are required to be satisfied. First, capital in the form of
    debt (which can be claimed) should have been provided. This predicates the
    existence of a debtor-creditor (or lender-borrower) relationship. Second,
    income should be from such debt.
  •  In this case,
    Dutch Co had promised the lenders to pay the amount of loan if the assessee
    failed to do so. The assessee paid guarantee charges in consideration for that.
    As Dutch Co had not provided any capital to the assessee, there was neither
    lender-borrower relationship, nor did Dutch Co earn any income from the debt
    claim.
  •  Accordingly,
    guarantee charges paid by the assessee to Dutch Co were not in the nature of
    ‘interest’ in terms of Article 11 of the India-Netherlands DTAA.
  •  This view is also
    supported by the decision in Container Corporation vs. Commissioner of
    Internal Revenue of US Tax Court Report [134 T.C. 122 (U.S.T.C. 2010) 134 T.C.
    5]
    wherein the Court held that guarantee is more analogous to service
    and hence guarantee fee cannot be considered as interest.


2   Tribunal
noted that though another Bench had set aside orders for A.Ys. 2007-08 to
2009-10 for considering additional evidence submitted by the assessee, that
option was not open to it because for the years under consideration, CIT(A) had
decided after considering all the documents


Whether
guarantee charges FTS?

  •  Article 12(5) of
    the India-Netherlands DTAA defines FTS as payment of any kind to any person in
    consideration for the rendering of any technical or consultancy services
    (including through the provision of services of technical or other personnel).
    Article 12(5) further stipulates that such services should either be ancillary
    to grant of license for intellectual property rights (IPRs) or should make
    available technical knowledge, etc.
  •  The provision of
    guarantee was a service. Indeed, it was a financial service. However, there was
    no way it could be termed ‘consultancy service’. Even otherwise, Dutch Co had
    neither provided services which were ancillary to grant of license for IPRs nor
    had it ‘made available’ technical knowledge, etc. Hence, payment for such
    services was not FTS.
  •     Since Dutch Co did not have any PE in India,
    in terms of Article 7 of the India-Netherlands DTAA, payments were not
    chargeable to tax in India.
 

Sections 9, 195, 201(1A) of the Act – On facts, since non-resident supplier had ‘business connection’ in India, the resident payer was required to withhold tax u/s 195

13. [2020] 117 taxmann.com
322 (Indore-Trib.)
Sanghvi Foods (P.)
Ltd. vs. ITO ITA Nos. 743 &
744/Ind/2018
A.Ys.: 2015-16
& 2016-17 Date of order: 3rd
June, 2020


Sections 9, 195,
201(1A) of the Act – On facts, since non-resident supplier had ‘business
connection’ in India, the resident payer was required to withhold tax u/s 195


FACTS


The assessee was an
Indian company engaged in the business of manufacturing plants. It had
purchased spare parts for its machinery from a company in Switzerland (Swiss
Co) for which it made payments during F.Ys. 2014-15 and 2015-16. The assessee
did not withhold tax from the payments on the basis that the purchase was
directly made from a non-resident and that, too, for purchase of capital goods.


The Swiss Co had a
wholly-owned subsidiary in India (I Co)
which was primarily engaged in the manufacture and trading of food processing
machinery, spares and components, and also providing repair, maintenance and
engineering services, etc. In addition, it provided marketing support services
to its group companies, including Swiss Co.


In the course of
his examination, the A.O. found the following:

  •  While the
    assessee had contended that it was not aware whether Swiss Co had any
    representative in India, it had extensive email communication with I Co. Such
    communication showed:
  •  The assessee had
    placed an order on Swiss Co on the basis of the quotation received from I Co;
  •  I Co was
    authorised to negotiate, issue quotation, revise quotation and also confirm the
    order;
  •  The assessee
    confirmed the order on Swiss Co through I Co;
  •  While I Co had an
    active role in concluding the contract, Swiss Co had raised only the final
    invoice.


The A.O. had issued
notice u/s 133(6) of the Act to I Co. In response, I Co provided information
and communication between it and the assessee which supported the findings of
the A.O.


Accordingly, the
A.O. concluded that Swiss Co had ‘business connection’ in India through I Co.
Consequently, the profits arising from the sales to the assessee were subject
to withholding of tax u/s 195 of the Act. Therefore, the A.O. determined 10% of
the amount remitted as net profit and calculated tax @ 41.2% on a gross basis
in respect of both the payments.


In his order, the
CIT(A) observed that the functions performed by I Co proved that it was not a
mere business-sourcing agent but was concluding contracts on behalf of Swiss
Co. This resulted in a business connection in India. He further observed that
irrespective of whether the payment was for the purchase of capital goods, the
payer was obliged to withhold tax once the business connection was established.


HELD

The investigation
of the A.O. and the findings of the CIT(A) show that the role of I Co could not
be ignored at any stage. I Co was involved since the beginning when the assessee
was looking for suppliers of spares. The reply of I Co u/s 133(6) of the Act
further supported this finding.


The activities
performed by I Co for Swiss Co were squarely covered within clauses (a),
(b) and (c) of the definition of ‘business connection’ in Explanation
2
to section 9(1) of the Act.


Based on the facts
and findings on record, Swiss Co had a ‘business connection’ in India through I
Co.


Accordingly, the transaction was subject to section 9(1) and the income
of Swiss Co was deemed to accrue or arise in India. Consequently, in terms of
section 195, the payer was required to withhold tax from the payment 1.

1   It
appears that both the CIT(A) and the Tribunal have discussed only the issue of
‘business connection’ and have not made any observations on the quantum of
profit determined by the A.O.


Section 115JB – Waiver of loan would not assume the character of income and hence, not part of book profit and adjustment in accumulated debit balance of profit & loss account through restructuring account to be disregarded for the purpose of computation of brought-forward losses

11. Windsor Machines Ltd. vs. DCIT (Mumbai) Manoj Kumar Aggarwal (A.M.) and Madhumita Roy (J.M.) ITA Nos. 2709, 2710 and 4697/Mum/2019 A.Ys.: 2013-14 and 2014-15 Date of order: 28th May, 2020 Counsel for Assessee
/ Revenue: Pradip N. Kapasi and Akhilesh Pevekar / Vinay Sinha


Section
115JB – Waiver of loan would not assume the character of income and hence, not
part of book profit and adjustment in accumulated debit balance of profit &
loss account through restructuring account to be disregarded for the purpose of
computation of brought-forward losses


FACTS

The assessee was
declared a sick company under the provisions of the Sick Industrial Companies
(Special Provisions) Act, 1985 (SICA) and a rehabilitation Scheme was
sanctioned. The Scheme envisaged several reliefs and concessions from various
agencies, including certain tax concessions, viz., exemption from the
provisions of sections 41, 72, 43-B and 115JB for a period of eight years from
the cut-off date (i.e., 31st March, 2009 as per the Scheme).

The
assessee’s net worth turned positive on 31st March, 2011, hence the
BIFR discharged the assessee from the purview of SICA vide its order
dated 16th August, 2011. According to the DIT (Recovery), since the
assessee was discharged by SICA on 16th August, 2011 and its net
worth turned positive by virtue of implementation of the revival Scheme, the
assessee was precluded from relief u/s 115JB in view of Explanation 1(vii) to
section 115JB(2) and, therefore, no relief would be available to it from A.Y.
2011-12 onwards from applicability of the provisions of section 115JB. The
assessee prayed for
reconsideration of the order pleading before the DIT (Recovery) that in terms
of the BIFR Scheme, it was entitled to relief u/s 115JB for a period of eight
years, i.e., up to A.Y. 2017-18.


In the meantime, the A.O., referring to the
decision of the DIT (Recovery), held that the assessee would be entitled for
relief u/s 115JB only up to A.Y. 2011-12. Accordingly, he computed book profits
u/s 115JB at Rs. 1,076.27 lakhs which was nothing but profit shown by the
assessee in the financial statements (after excluding exempt dividend income).
The CIT(A), on appeal, upheld the order of the A.O.


HELD

According to
the Tribunal, since the assessee was discharged by SICA on 16th
August, 2011 and its net worth turned positive by virtue of implementation of
the revival Scheme, the assessee was precluded from relief u/s 115JB in view of
Explanation 1(vii) to section 115JB(2) and, therefore, no relief would be
available from A.Y. 2011-12 onwards.


The Tribunal
also found substance in the contention of the assessee that

(a) the
amount credited to profit & loss account on account of waiver of loan would
not assume the character of income and hence should not form part of book
profits u/s 115JB, and

(b)
adjustment in accumulated debit balance of profit & loss account through
restructuring account should be disregarded for the purpose of computation of
brought-forward losses in terms of Explanation 1(iii) to section 115JB(2),


However, the
Tribunal also noted that the issues had not been delved upon either by the A.O.
or by the CIT(A). Therefore, on the facts and circumstances of the case, the
Tribunal remitted the matter back to the file of the CIT(A).


Section 2(22)(e) – No addition can be made u/s 2(22)(e) since as per annual return filed by the assessee, he had transferred his shareholding in borrower company before the advancement of loan by the lender company to the borrowing company

19. [(2020) 117 taxmann.com 451
(Chd.)(Trib.)
ACIT vs. Gurdeep Singh ITA No. 170 (Chd.) of 2018 A.Y.: 2013-2014 Date of order: 26th June, 2020


Section 2(22)(e) – No addition can be made
u/s 2(22)(e) since as per annual return filed by the assessee, he had
transferred his shareholding in borrower company before the advancement of loan
by the lender company to the borrowing company


FACTS

The assessee was a shareholder in two companies, namely, C Ltd. and J
Ltd. During the previous year relevant to the assessment year under
consideration, C Ltd. gave loans and advances to J Ltd. out of its surplus
funds. The A.O. took a view that since the assessee was holding shares in both
companies in excess of ten percent of total shareholding, the amount of loan is
to be taxed as dividend u/s 2(22)(e) of the Act.


The annual return
filed with the Registrar of Companies (ROC) revealed that the assessee held
only one share of C Ltd., whereas the other shares were transferred to J Ltd.
The annual return was belatedly filed with the ROC, along with payment of late
fee, which was accepted by the ROC. Based on the belatedly filed annual return,
the assessee contended that the shares were transferred prior to the
advancement of loan and, therefore, the provisions of section 2(22)(e) were not
applicable. The A.O. did not agree with the submissions made by the assessee
and held the plea of share transfer to be an afterthought since the return with
the Registrar was filed late.


Aggrieved, the assessee preferred an appeal to the CIT(A) who allowed the
appeal since the transfer of shares was accepted by the A.O. while framing assessments
of subsequent years, and also held that the transfer of shares had to be
considered. He also held that the transaction was commercially expedient with
no personal benefit involved.


Aggrieved, the Revenue preferred an appeal to the Tribunal.


HELD

The Revenue could
not establish beyond doubt that the assessee was having substantial interest in
C Ltd. on the date of advancement of loan by C Ltd. to J Ltd. Even though the
annual return was filed belatedly, once accepted by the ROC, it was a legal and
valid document as per law and the effective date for transfer of shares should
be considered as that mentioned in the return filed. To apply a deeming
fiction, the first set of facts is to be proved beyond doubt and the deeming
fiction cannot be applied on the basis of assumption, presumption or suspicion
about the first set of facts. The Tribunal observed that it was the A.O.’s
suspicion that the assessee was holding substantial shares in C Ltd. on the
date of advancement of loan. The Revenue could not rebut the facts beyond
reasonable doubt. The Tribunal upheld the order passed by the CIT(A) and
confirmed the deletion of the addition made u/s 2(22)(e).


The appeal filed by
the Revenue was dismissed.


Section 115BBE, read with sections 69, 143 and 154 – Amount surrendered, in the course of survey, as undisclosed investment in stock and assessed as business income cannot be subsequently brought to tax u/s 115BBE by passing an order u/s 154

18. [(2020) 117 taxmann.com 178
(Jai.)(Trib.)
ACIT vs. Sudesh Kumar Gupta ITA No. 976 (Jp) of 2019 A.Y.: 2014-2015 Date of order: 9th June, 2020


Section 115BBE, read with sections 69, 143
and 154 – Amount surrendered, in the course of survey, as undisclosed
investment in stock and assessed as business income cannot be subsequently
brought to tax u/s 115BBE by passing an order u/s 154


FACTS

During the course of survey, the assessee surrendered an amount of Rs. 21
lakhs as undisclosed investment in stock. This amount was offered to tax in the
return of income as business income. In the assessment completed u/s 143(3) of
the Act, the returned income was accepted.


Subsequently, the A.O. issued a notice u/s 154 proposing to tax the
undisclosed investment of Rs. 21,00,000 in stock u/s 69 and tax thereon levied
u/s 115BBE at 30%. The assessee submitted that the amount admitted as
undisclosed excess stock was on an estimated basis and it had been accepted by
the A.O. in an assessment made u/s 143(3). The A.O. rejected the submission
made by the assessee and passed an order u/s 154 and levied tax on the amount
of undisclosed investment at 30% in accordance with section 115BBE.


Aggrieved, the assessee preferred an appeal to the CIT(A) who allowed the
appeal holding that the A.O. was not justified in invoking the provisions of
section 69 once he had charged it to tax under the head business income while
passing the assessment order u/s 143(3).


Aggrieved, the Revenue preferred an appeal to the Tribunal.


HELD

The Tribunal noted
that the amount of undisclosed investment in stock surrendered by the assessee
was offered as ‘business income’ in the return of income and was accepted by
the A.O. In the course of assessment, there was no adjustment / variation
either in the quantum, nature or classification of income offered by the
assessee. The A.O. had not called for any explanation regarding the nature and
source of such investment during the course of assessment proceedings. Further,
he had neither formed any opinion, nor recorded any satisfaction for invoking
the provisions of section 69. The Tribunal held that since the provisions of
section 69 had not been invoked at the first instance while passing the
assessment order u/s 143(3), they cannot be independently applied by invoking
the provisions of section 154.


The Tribunal
dismissed the appeal filed by the Revenue.

Sections 2(47), 45: When the terms of the sale deed and the intention of the parties at the time of entering into the sale deed have not been adhered to whereby full sale consideration has not been discharged, there is no transfer of land, even though the sale deed has been registered, and no income accrues and consequently no liability towards capital gains arises in the hands of the assessee

17. [2020] 117 taxmann.com 424 (Jai.)(Trib.) CIT vs. Ijyaraj Singh ITA Nos. 91 and 152/Jp/2019 A.Y.: 2013-14 Date of order: 18th June, 2020


Sections 2(47), 45: When the terms of the
sale deed and the intention of the parties at the time of entering into the
sale deed have not been adhered to whereby full sale consideration has not been
discharged, there is no transfer of land, even though the sale deed has been
registered, and no income accrues and consequently no liability towards capital
gains arises in the hands of the assessee


FACTS

The assessee in his
return of income filed u/s 139(1) declared long-term capital gains of Rs.
2,51,85,149 in respect of sale of agricultural land situate in Kota. In the
course of assessment proceedings, the assessee revised his return of income
wherein the income under the head long-term capital gains was revised to Rs.
1,10,18,918 as against Rs. 2,51,85,149 shown in the original return. The reason
for revising the return was that out of three sale deeds, two sale deeds of
land executed with Mr. Rajeev Singh were invalid sale deeds and consequently no
transfer took place and hence no capital gain arises in respect of the two
invalid sale deeds. In respect of these two sale deeds, the assessee had
received only Rs. 63 lakhs towards consideration out of Rs. 803 lakhs. The
cheques received from the buyer were dishonoured and even possession was not
handed over to the buyer. The Rajasthan High Court has also granted stay on the
sale deeds executed by the assessee.


But the A.O. was of
the view that the contract entered into by the assessee was a legal and valid
contract entered into in accordance with the procedure laid down by law. The
assessee voluntarily agreed to register the sale deed before the Registrar and
on the date of execution and also on the date of registration there was no
dispute between the parties. The A.O. computed long-term capital gains by
considering the full value of consideration, including the two sale deeds which
were contended to be invalid, and computed the full value of consideration u/s
50C of the Act.


Aggrieved, the
assessee preferred an appeal to the CIT(A) who held that the transaction in
respect of the two invalid sale deeds is not chargeable to capital gains tax.


Aggrieved, the
Revenue preferred an appeal to the Tribunal.


HELD

The Tribunal noted
that the question for its consideration is that where the full value of
consideration has not been discharged by the purchaser of the impugned land as
per the sale deed, and there is violation of the terms of the sale deed,
whether the impugned transaction would still qualify as transfer and be liable
for capital gains tax, given that the same is evidenced by a registered sale
deed. Having considered the provisions of sections 2(24), 2(47), 45 and 48 of
the Act, and also the decision of the Punjab & Haryana High Court in the
case of Hira Lal Ram Dayal vs. CIT [122 ITR 461 (Punj. & Har. HC)]
where the question before the Court was ‘whether it is open to the assessee to
prove that the sale transaction evidenced by the registered sale deed was a
sham transaction and no sale in fact took place’, and also the decision of the
Patna High Court in the case of Smt. Raj Rani Devi Ramna vs. CIT [(1992)
201 ITR 1032 (Patna)]
, the Tribunal held that the legal proposition
which emerges is that a registered sale deed does carry an evidentiary value.


At the same time,
where the assessee is able to prove by cogent evidence brought on record that
no sale has in fact taken place, then in such a scenario the taxing and
appellate authorities should consider these evidences brought on record by the
assessee and on the basis of an examination thereof, decide as to whether a
sale has taken place in a given case or not. The title in the property does not
necessarily pass as soon as the instrument of transfer is registered and the
answer to the question regarding passing of title lies in the intention of the
parties executing such an instrument. The registration is no proof of an
operative transfer and where the parties had intended that despite execution
and registration of sale deed, transfer by way of sale will become effective
only on payment and receipt of full sale consideration and not at the time of
execution and registration of sale deed.


The Tribunal noted
that no payment was received before execution of the sale deed but only
post-dated cheques were received by the assessee. It held that mere handing
over of the post-dated cheques which have been subsequently dishonoured and
returned unpaid to the assessee, cannot be held to be discharge of full sale
consideration as intended and agreed upon between the parties and there is
clearly a violation of the terms of the sale deed by the buyer.


Although the sale
deed has been registered, given that the terms of the sale deed and the
intention of the parties at the time of entering into the said sale deed have
not been adhered to whereby full sale consideration has not been discharged,
there is no transfer of the impugned land and no income accrues and
consequently, no liability towards capital gains arises in the hands of the
assessee. The Tribunal also held that it is only the real income which can be
brought to tax and there cannot be any levy of tax on hypothetical income which
has neither accrued / nor arisen or been received by the assessee. Since the
transaction fell through in view of non-fulfilment of the terms of the sale
deed whereby cheques issued by the buyer have been dishonoured, there is no
transfer and no income which has accrued or arisen to the assessee. There is no
real income in the hands of the assessee and in the absence thereof, the
assessee is not liable to capital gains. It observed that a similar view has
been taken by the Pune Bench of the Tribunal in the case of Appasaheb
Baburao Lonkar vs. ITO [(2019) 176 ITD 115 (Pune-Trib.)]
.


This ground of
appeal filed by the Revenue was dismissed.

71ST ANNUAL GENERAL MEETING AND 72ND FOUNDING DAY, 6TH JULY, 2020

The 71st Annual General Meeting of the BCAS was, for the first time, held online on Monday, 6th July, 2020.

The President, Mr. Manish Sampat, took the chair and called the meeting to order. All the business as per the agenda contained in the notice was conducted, including adoption of accounts and appointment of auditors.

Mr. Samir Kapadia, Hon. Joint Secretary, announced the results of the election of the President, the Vice-President, two Honorary Secretaries, the Treasurer and eight members of the Managing Committee for the year 2020-21.

The ‘Jal Erach Dastur Awards’ for the Best Articles and Features appearing in the BCAS Journal during the year 2019-20 were also presented on the occasion.

For Best Article the Award went to CA Bangaru Ishwar Teja, CA Nitish Ranjan and CA Dinesh Chawla for their Article: Income Tax E-Assessments – Yesterday, Today and Tomorrow. The Award for Best Feature went to CA Jayant Thakur for Securities Laws.

The July special issue of the BCA Journal was e-released by Mr. Deepak Parekh. It carried special articles on ‘Risk and Technology Challenges for Professionals’ in addition to the regular articles and features. An e-book, ‘MLI – DECODED’, authored by CA Ganesh Rajgopal, was also released.

Before the conclusion of the AGM, members, including Past Presidents of the BCAS, were invited to share their views and observations about the Society.

The Founding Day lecture was delivered at the end of the formal proceedings of the AGM. It was an outstanding oration by CA Deepak Parekh, Chairman of HDFC, who spoke on the topic ‘Chartered Accountants in Uncharted Times’. It was attended online by more than 3,000 professionals on Zoom and the YouTube channel of the BCAS.

OUTGOING PRESIDENT’S REPORT

Manish Sampat: I feel very proud and satisfied as I rise for the last time as President of our illustrious Society. It is an honour and a privilege to have led the Bombay Chartered Accountants’ Society during a memorable and unprecedented year. We continue to march ahead and strive to achieve greater heights of performance year after year by building on the excellent work done by all previous Presidents. The last three months have been challenging and unmatched for us in terms of conducting our normal activities of education, training and spreading knowledge. But we converted all the challenges that came our way into opportunities and continued with our endeavour of spreading knowledge with even more vigour and zeal.

I would like to begin with where I had ended my installation speech. I had mentioned then that the BCAS is a collective organisation and the President, by chance, gets one year to head it. And now, after a year, I am fully convinced about this fact. What I did in the year gone by was the collective effort of the entire team and I was just fortunate to lead this team. As it is said in cricket parlance –‘the captain is as good as the team’. So, you be the judge and you will know just who is worthy of credit for all the good things that took place during the year. But I take responsibility for the debits, if any, that might have accumulated.

In my acceptance speech I had also mentioned that I am indebted and owe a lot to this organisation because it has had a significant role and contribution in my professional development. Contributing to it by heading it was my chance to repay our Society. But I feel that this did not happen. Just like a mother always gives to her children and does not accept anything in return, it was BCAS that kept on giving me more and more during the year rather than me repaying my debts.

It taught me lessons in life, management and leadership.

I learnt how to deal with people and difficult situations.

I have learnt that along with power comes responsibility and you need to be humble and considerate when you are in a position of power.

I learnt management lessons of collective leadership – if you want to be a successful leader you can’t be running alone and you need to take everyone along with you.

By the end of my tenure, I matured as a person and as a leader. I learnt how to be patient and understanding and learnt people management.

But it is nature’s law that in the circle of life you should never take more than what you can give. So I have tried my best and sincerely put in all my efforts in whatever I did as President, to maintain and build upon the goodwill, ethos and value systems of our Society.

Such is the greatness and selfless nature of the institution. It always gives, gives and gives.

I started my journey as President with anxiety, not knowing how the year would pan out but I go back with so many beautiful memories and with wonderful, long-lasting friends made on the way. During the year I also got a lot of support from everyone, at times even from unexpected sources. No doubt, personal relations count but I think the support was more for the Society rather than for me personally. Yes, personally, I became close friends to many Past Presidents, Managing Committee members, Conveners (whom I had just known) and this is going to last for a long time to come.

So far we have been successful and are in meaningful existence for more than seven decades; this in itself is testimony and shows that we have got something right. There is something strong and positive in our DNA, our value system, our processes and the entire structure.

Imagination and innovation do not come with an age limit and have no expiry date. At our Society, we benefit from the diversity in thinking, perspectives, experience and age. We serve our members through expertise developed through experience as well as innovative ideas from the youth. We need a balance between both and cannot do away with any one of them. That is why we remain relevant, committed and respected even today.

During the year we attempted some experiments and did away with some past practices – we tried to do things differently rather than doing different things. I am satisfied and happy to announce that most of our experiments were successful and were appreciated by members. As we move forward we continue to have the same vision of continuing to grow and transform ourselves for the benefit of all our stakeholders who have trusted us and had faith in us. Some of the initiatives include LM in the suburbs, increasing the number of joint programmes with other organisations, industry bodies, outstation programmes, sector- and industry-specific events, Women’s Day LM, Bapu@150, IA RSC, etc. to name a few.

On the financial front, let me be honest. Some may not like this, but I would like to mention it. From the beginning of the year I had decided and aimed for building on our coffers and strengthening our financial position. And our financial performance for F.Y. 2019-2020 speaks for itself. No doubt this year we benefited from an increase in subscription income (without any fall in membership) but this year had other challenges such as the load of two budget meetings in a year, loss of revenue from a couple of well-paying programmes during the last ten days of March and falling interest rates. However, due to strategic efforts on identifying avenues for raising revenue (without overcharging our members), bumper sale of the Referencer, calendar and pocket dairies, financial prudence, cost-cutting measures and avoiding wasteful expenditure, we were able to achieve a financial performance that will come handy on a rainy day.

Things are going to change for me from tomorrow. I cross the floor and go back to the other side. From tomorrow I once again become a common member. The question is what will I miss from tomorrow?

My affair with BCAS comes to an end; but it’s like a nasha – the more you get involved, the greater is the intoxication. Some of the things that will change are:

  • Checking multiple email IDs in the inbox.
  • Many seniors addressed me as ‘President’– so I will become Manish Sampat again from tomorrow.
  • Many of my contemporaries were addressing me with the suffix ‘bhai’. Removing ‘Bhai’ from my name, so that I go back to being just Manish for all of you.
  • My WhatsApp status line before my term was ‘Not responsible for delay in reply’ which I had changed after taking over as President. I hope to go back to my earlier status.
  • I will miss the lessons in MLI, digital economy and EL that I used to compulsorily get from the International Taxation Committee.
  • Writing twelve President’s Columns, month on month (in time) was a real challenge. It was like having twelve deliveries in the year.
  • Most importantly, now I will not be able to make excuses both at home and at office about being busy with BCAS work, which I have got so used to now.
  • There are many more such instances, but I can’t list all of them here.

I need to thank quite a few people who have tolerated all my whims and tantrums during the year.

First, my family – The situation at home is such that I have been completely written off. Initially, I was asked whether I would make it for a late night movie and I was included in the dinner plans; but since the past couple of years I have never been consulted, my ticket is never bought and I have not been a part of any plans by the family. So much so, that on birthdays my wife continues to get surprise birthday cakes and other such gifts and I get a yoga mat as my birthday gift!

My CNK family, partners, staff and more particularly my team… I always had this privilege in office and I was relieved from any responsibilities as I had the excuse of being busy with the BCAS Presidentship, but now I go back and don’t have any excuses left with me. Thank you, CNK family and all my partners and staff for supporting me, for tolerating my weird time schedules and temper at times. But I know that since I have four Past Presidents with me at CNK, they would understand me. Shariqbhai, Gautambhai, Himanshubhai and Sanjivbhai were always there whenever I needed any advice. I must make a special mention of Praful and all others in my team who ensured that work continued smoothly even without my physical involvement.

A big thank you to all the Past Presidents who showered their blessings on me and were always available whenever I called upon them. I hope I have lived up to their expectations and the faith and responsibility they had bestowed on me.

All the Chairmen and Co-Chairpersons of the Committees – I had said that these are the captains of
the tournament and found each and every one of them working harder than anyone else. I believe that since they are all Past Presidents, they know the Society better than anyone else. They can’t go wrong. The entire credit for the success of all the events goes to them and my contribution is limited to giving them a free hand and never getting involved or interfering with their working. Even today, as I speak, a representation has been sent by the Taxation Committee.

In my Management Committee, I got the most wanted support. My thanks to all the Committee members for their active and constructive participation. I was blessed with a very vibrant and vocal Managing Committee and many new ideas and initiatives emerged from it. I believed in empowering it and involving them in the decision-making process because the future leadership of BCAS will evolve and emerge from here. We have to ensure that they are groomed and ready for taking up leadership positions.

As for my Office-Bearers, there was continuous consultation with them and all decisions were taken collectively and unanimously.

  • In Suhas we have a silent worker who does not like to make any noise but contributes in his own style; he was always available and a big supporter.
  • In Abhay we have a very mature and able administrator – custodian of our financial resources, he ensured that we got more than the adequate surplus which I had targeted.
  • In Mihir we have a perfect communicator, observant and very good at all the Committee and back office paperwork.
  • Samir (my old buddy) again is a very silent, dedicated worker, technologically savvy and loyal to the institution to the core.
  • I can say that my ‘wolf pack’ rocked and we had a great time together.
  • I also thank the support staff at the BCAS, Upendra, Shreya, Javed and their team. I might have been harsh on them at times, but I was just acting as a trustee and in the interest of the Society and had no other intentions. I also thank all our vendors, printers and others for their support throughout the year.

Finally, a big Thank You to each and every member. Whatever was achieved during the year is only because of the faith and the patronage of all of you. I got unprecedented support from members every time and for every event. We did not have to cancel even a single programme due to insufficient enrolment. I was lucky that in all the LM, events, workshops, RRCs we had very good attendance and the feedback was very encouraging. Even at live streaming of the budget there was record attendance, better than in the recent past.

All new initiatives executed during the year have been mentioned in detail in the Managing Committee report so I would not like to repeat them; but I would now like to speak about the developments in the last three months.

Speaking today, I think that the pace at which the activities of the BCAS were being carried out, only an external force or an act of God could have stopped them.

It is said that necessity is the mother of invention. So far we were only talking about and planning to go
digital with our activities. But the circumstances since March have forced us to reinvent ourselves. I am happy to inform you that we quickly transited to an online platform and were able to reach a much wider audience and get high profile and knowledgeable speakers for BCAS programmes. To our immense satisfaction, our internal assessment actually shows that we have been successful in delivering more man-hours of training by way of live attendance and follow-up hits on our YouTube channel. We managed to clock almost half of the man-hours of training (during the three months of lockdown) than we were usually clocking in in an entire year through physical meetings.

There a few misses also during the year, some incomplete agenda which I could not complete:

The BCAS mobile App.

The Professional Accountants’ course.

Organising a cricket tournament – the BCA Premier League.

Naming the junction outside our office as BCAS Chowk.

Having a core team in place to start planning and working towards our 75th anniversary.

At times I took time to take a decision and left it till the last, but that perhaps is my working style. I take too much pressure at the end but ultimately deliver. But frankly, I think I enjoy this pressure.

I think you require strong administrative and people management skills to run an organisation and this is what I have benefited from and gained.

Online events are here to stay and this brings a different set of challenges – will we require the administrative set-up that we currently have? We need to reorganise and restructure our internal operations and infrastructure which should be the focus in the coming year.

To conclude, my biggest take-away from my term as President is what I realised and learnt: That difference of viewpoints is healthy for an organisation to grow and remain dynamic. There could be different and completely opposite strong views but all volunteers are working in the interest of the institution and the leader is responsible for building consensus, finding a balance and coming out with a win-win solution acceptable to all.

With these words, I wish the incoming team of Suhas, Abhay, Mihir, Samir and Chirag all the very best. I have worked with them so I am very confident of their capabilities and abilities to have a super successful year ahead.

Now I say a final goodbye and a big thank you and gratitude for all your love, support and affection. I vacate this office with a lot of satisfaction and a sense of achievement.

Thank you.


INCOMING PRESIDENT’S SPEECH

SUHAS PARANJPE: This is a very humble, sentimental and responsible moment for me as I take up the responsibility as President of this august body, the Bombay Chartered Accountants’ Society, BCAS.

Before I start, let me first remember and thank all those who have been part of my journey both in my career and at BCAS.

First and foremost, thank you from the bottom of my heart to all the respected Past Presidents who have contributed so much to this Society. I am humbled that they all considered me fit and proper for this position. The list of all my mentors and guides at BCAS is too long to quote and I just don’t have the words to thank them.

However, since we have just observed the auspicious day of Guru Purnima, let me take this opportunity to seek all your blessings with folded hands and this prayer:

त्वमेव माता च पिता त्वमेव ।

त्वमेव बन्धुश्च सखा त्वमेव ।

Thank you, all Past Presidents and my seniors.

Today, I would like to remember and thank my father, the late Shri Shivaram Paranjpe who always gave me a good perspective and directions at the right time and put me in the right hands which shaped my career. Thank you, Baba.

My mother Smt. Shalini and my wife Swati had full faith and confidence in me and supported and encouraged me throughout this journey. Swati plays the important role of critic for my all-round improvement. Our son Aarav is too young to understand about BCAS and though he entered into our life as per his convenience, he gave us the purpose, the focus and better directions. Thank you, my family.

My sincere thanks go out to the late CA Dr. Rashmibhai Zaveri. It was because of his relations with my father that I got connected with my partners. Thank you, Rashmibhai, and I am sure you are happy and smiling today.

CA Mayurbhai Vora and CA Bharatbhai Chovatia, who have been my partners and mentors for the past three decades, have always been the force behind me in my journey as a professional. They are like the magic stone पारस (paras) that converts things into gold. Their families always treated me as their own member. My younger partners, Kinnari and Bhakti Vora, Ronak Rambia, Vinit Nagda and our enthusiastic but matured youth brigade in the office have always stood behind me. Thank you, my office friends and colleagues.

My special thanks to outgoing President Manish for his guidance and for always making himself available to me for help and assistance. Under your Presidentship, Manish, you could carry out many activities and kept the BCAS flag flying high.

Your year was a combination of Physical + Virtual. With all-round support this year, we could plan for the year 2020-21 an equally vibrant and innovative plan of action, full of experiments and possibilities for the future. As I understand it, the year ahead would be Virtual + Physical. I must say that you have ensured an excellent foundation in the last three months for the Virtual part of the year ahead. We wish you good luck and happy times ahead – both professionally and personally. However, I wish you will continue to be a guiding force for the BCAS in the years to come. Thank you, Manish.

Let me now move ahead.

Since mid-March, 2020, the whole world has been living in challenging times due to the Covid pandemic. The long lockdown has given each one of us a different perspective to life, work, relationships – the challenges and opportunities. All of us have now experienced different situations like Work from Home, Work for home (without domestic help), strict social distancing norms, events on Zoom, Hangout, etc. We are now all familiar with these ‘new normals’.

Let me share with you two situations – (on a lighter note) to give you a different perspective over and above the ‘new normals’ as mentioned above. It relates to the game of lawn tennis, which is my favourite.

We did not see a tennis court for more than three months – an unprecedented situation. As you are aware, in tennis we are allowed to play only singles games and not doubles due to social distancing. In singles, since you do not enjoy the support of a doubles partner, you have to be far more fitter with a lot more stamina. This is the current situation and (I hope) it would change in future.

Secondly, there are no ball boys on the courtside as of now to help the players, they have all gone to their native places or disappeared. When we play, other players become ball boys and vice versa. This is self-help on the tennis court – and it can be termed as an aatmanirbhar experience.

Now let me move to more serious business, to give you a brief of the BCAS Theme for 2020-21 and also our annual plan.

Our focus areas for this year will be:

(1) Higher reach and scalability – all around – to the members and the profession at a reasonable cost;

(2) Hand-holding for MSME / SME businesses and practitioners for a sustainable future;

(3) Digital and technology transformation with experienced hands and youth force.

These focus areas have been articulated in three ideas condensed in three headings, viz.


 ‘Tradition – Transition – Transformation’

In the above logo, the sign of the pen represents ‘TRADITION’. And the six squares at the top represent the digital medium.

  1. TRADITION: OUR FOUNDATION

At BCAS, our core values, our ethical practices, our governance, our tradition of hand-holding by seniors are our foundation and shall continue to guide us during the phase of transition and transformation. BCAS has always been and would continue to be a principle-centred, learning-oriented institute with quality services as its benchmark. In the last three months, BCAS and its dedicated team of volunteers have demonstrated that even in the time of lockdown, BCAS is proactive and adaptable to the changing situations. In other words, TRADITION AS FOUNDATION CONTINUES TO GUIDE US.

  1. TRANSITION

Transition is a process of change. It could be a short-term phase but it is crucial. World organisations and practices cannot just transform themselves tomorrow morning. They have to go through the crucial phases of transition. In nature, there are some of the best examples of transition, such as the metamorphosis of a caterpillar into a beautiful butterfly, or an eagle which starts the process of change at a later stage in life for survival.

Why only nature, we also have Indian corporates transiting from a single textile mill to petrochemicals, to oil and gas, to retail and digital platforms, and with much more to come. You will agree with me that it makes all Indians proud to be a part of such a transition.

In our profession in general, and on the BCAS platform in particular, there are CAs who started as proprietors and transited themselves into bigger / larger personalities and firms consolidating and becoming Indian giants. There are several in-house examples.

This year, with large corporates finalising their accounts with virtual audits, with AGM’s being conducted online, including our own, our events, including RRCs, were and would be conducted online. This is the conceptual change of new experiments and experiences beyond our imagination. In other words, THIS IS THE YEAR OF CHANGE / TRANSITION.

  1. TRANSFORMATION:

Transformation is an outcome of change or transition.

Today, we are in the era of digital transformation. This will help us to enhance our reach and scalability without boundaries and at reasonable costs. Apart from this, it could help us to reach out to the MSMEs / SMEs and our large family of BCAS members by hand-holding them for a sustainable future. Yes, there would be less personal / human touch. But I am sure technology will evolve itself and adopt a human face with innovation and creativity. Sitting in your office or home, ease of technology would give you an experience of being in Vizag or in Kodaikanal or in Bali. It looks like this would be our Residential Refresher Course module this year.

In view of the economy taking a big hit, it has become much more crucial for Chartered Accountants, including the small and medium PR actioners to transform themselves into the role of business advisers apart from helping their clients in compliances.

On the healthcare front which is so critical now, it has become so important to transform ourselves to different levels of body immunity to deal with this virus or other kinds of diseases in future. Each and every one of us should follow a specific fitness and meditation regime to stay healthy and safe – both physically and mentally.

Yes, we need to avoid an overdose of webinars. But with the outstanding quality of our contents, faculties and administrative discipline and capabilities, digital transformation would give us an opportunity to take BCAS to new heights. It would be easier and cost-effective to connect with sister organisations and different regional organisations and their members. There are possibilities that with innovative initiatives we can reach the 10,000 membership mark which has been in our bucket list for a long time.

In the next generation, youth force would be the torch-bearers of this transformation under the guidance and support of experienced mentors. The youth are the technology anchors and are better equipped to handle it. This year all the Committees have added more youth power with the specific aim of giving them opportunities to perform and excel.

A robust and secured technology platform and infrastructure is the backbone of this transformation arena. We might have opted for a particular platform today, based on technical inputs of the Committees, but we would try to be vigilant in respect of the strength and security parameters of the tech platforms. Suggestions and guidance from time to time would be welcome to keep us on track.

This is the ANNUAL PLAN.


BCAS is a dynamic platform to perform. It also gives you the power to perform.

Let me share with you two personal experiences. First, when I was nominated as Vice-President for 2019-20, one of the senior Past Presidents and my BCAS mentor told me that this position offers a kind of power to perform for a purpose and for the profession. How true these words of wisdom have turned out to be when I look back to the year which has just passed by.

The second experience is more than an observation. For the first time in my BCAS journey, I was fortunate enough to make six contributions to the BCAJ in the year 2019-20 by way of Namaskaar, Book Review, an Article and the column Is it Fair. It is like shooting from 0 to 6 – just as in tennis you win a set at 6-0!

For me it was self-appraisal and not self-praise. I only wish to bring to the notice of the next generation that the power of the BCAS platform always encourages you to perform but you need to be focused and maintain self-discipline.

Now a small note on financials.

I wish to state that this year would be financially challenging for businesses, professionals, employees and even to the Government. Similarly, at BCAS it appears as though there would be our usual fixed costs with lesser revenue. But I am confident that my Office-Bearers, Managing Committee members, Committee Chairmen and the entire Core Group would come up with out-of-the-box thinking and present ideas both to augment our revenues and also to increase membership.

To conclude, I wish to assure all of you that with the support of all the Past Presidents and seniors, along with the Office-Bearers, Managing Committee members, the youth power and the assistance of the BCAS staff, we would perform and deliver our best in these challenging times in the year ahead. Please continue to share your thoughts and guide me in this journey.

As I take up the new position, I would like to release the E-Core Group Diary with 250 Core Group members who are the lifeline of our Society. It is a part of digital transformation that we release it today in E-version. I acknowledge the contribution of our Past President Narayan Pasari who always signs off this diary with his eye for detail. Thank you, Narayanji.

We would print it and send it to members in due course when logistics improves.

I thank you for your patient hearing.

SET OFF OF UNABSORBED DEPRECIATION WHILE DETERMINING BOOK PROFIT u/s 40(B)

 ISSUE FOR CONSIDERATION

Section 40(b)
limits the deduction, in the hands of a partnership firm, in respect of an
expenditure on specified kinds of payments to partners. Amongst several
limitations provided in respect of deduction to be claimed by the partnership
firm, clause (5) of section 40(b) limits the deduction for remuneration to the
working partners to the specified percentage of the ‘book profit’ of the firm.


The term ‘book
profit’ is defined exhaustively by Explanation 3 to section 40(b) which reads
as under:


‘Explanation 3 –
For the purpose of this clause, “book profit” means the net profit, as shown in
the profit and loss account for the relevant previous year, computed in the
manner laid down in Chapter IV-D as increased by the aggregate amount of the
remuneration paid or payable to all the partners of the firm if such amount has
been deduced while computing the net profit.’


‘Book profit’, as per Explanation 3, means the net profit as per the
profit and loss account of the relevant year, computed in the manner laid down
in Chapter IV-D. The net profit in question is the one that is shown in the
profit and loss account which is computed in the manner laid down in Chapter
IV-D. This requirement to compute the net profit in the manner laid down in
Chapter IV-D has been the subject matter of debate. Section 32, which is part
of Chapter IV-D, provides for the depreciation allowance in computing the
income of the year and, inter alia, sub-section (2) provides for the
manner in which the unabsorbed depreciation of the earlier years is to be
adjusted against the income of the year. The interesting issue which has arisen
with respect to the computation of ‘book profit’ for the purpose of section
40(b) is whether the net profit for the year should also be reduced by the
unabsorbed depreciation of earlier years and whether the amount of remuneration
to the partners eligible for deduction should be computed with respect to such
reduced amount.


The Jaipur bench of
the Tribunal has held that in computing the ‘book profit’ and the amount
eligible for deduction on account of the remuneration to partners, unabsorbed
depreciation of the earlier years should be deducted from the net profit for
the year as provided in section 32(2). As against this, the Pune bench of the
Tribunal has taken a contrary view and has allowed the assessee firm’s claim of
the remuneration paid to its partners which was computed on the basis of ‘book
profit’ without reducing it by the unabsorbed depreciation of the earlier
years.


THE VIKAS OIL MILLS CASE

The issue first
came up for consideration of the Jaipur bench of the Tribunal in the case of Vikas
Oil Mills vs. ITO (2005) 95 TTJ 1126.


In that case, for
the assessment year 2001-02 the A.O. disallowed the remuneration amounting to
Rs. 1,79,005 paid to the working partners on the ground that the assessee firm
had not reduced the unabsorbed brought-forward depreciation of earlier years
from the profit of the year under consideration while claiming deduction for
the remuneration payable to the partners. Since the resultant figure after
reducing the unabsorbed depreciation of earlier years from the profit of the
assessee firm was a negative figure, the A.O. disallowed the remuneration paid
to the partners. The CIT(A) confirmed this order.


The assessee argued
before the Tribunal that the unabsorbed depreciation was allowed to be deducted
only because of a fiction contained in section 32(2) and that otherwise the
deduction was subject to the provisions of section 72(2). Hence, unabsorbed
depreciation should not be considered for computation of net profit in Chapter
IV-D. On the other hand, the Departmental representative supported the orders
of the lower authorities by submitting that unabsorbed depreciation of earlier
years was part of the current year’s depreciation as per section 32(2) which
fell in Chapter IV-D and, therefore, for computation of book profit unabsorbed
depreciation was to be necessarily taken into account.


The Tribunal
concurred with the view of the lower authorities and held that the remuneration
paid to the working partners was to be reduced from the book profit as per the
provisions of section 40(b)(v). The definition of book profit was provided in
Explanation 3 as per which it was required to be computed in the manner laid
down in Chapter IV-D. Therefore, the Tribunal held that the unabsorbed
depreciation of earlier years had to be reduced as provided in section 32(2)
while determining the book profit for the purpose of determining the amount of
deductible remuneration. However, the Tribunal agreed with the alternative plea
of the assessee for allowing the minimum amount of remuneration which was
allowable even in case of a loss.


RAJMAL LAKHICHAND CASE

The issue
thereafter came up for consideration before the Pune bench of the Tribunal in
the case of Rajmal Lakhichand vs. JCIT (2018) 92 taxmann.com 94.


In this case, for
the assessment year 2010-11 the A.O. disallowed the remuneration to working
partners amounting to Rs. 17,50,000 on the ground that the unabsorbed
depreciation of earlier years was not reduced in computing the book profit
which was contrary to the provisions of section 40(b). Upon further appeal, the
CIT(A) deleted this disallowance by holding that the remuneration to partners
was to be worked out on the basis of the current year’s book profit and
therefore the remuneration was to be deducted first before allowing the set-off
of brought-forward losses. He held that the computation of book profit was as
per section 40(b) while the set-off of brought-forward losses was to be granted
in terms of section 72. Therefore, while arriving at the business income, the
deduction of section 40(b) was to be given first and then, if at all there
remained positive income, the brought-forward losses were to be set off.


Before the
Tribunal, the Income-tax Department assailed the findings of the CIT(A) on the
ground that the unabsorbed brought-forward depreciation became a part of the
current year’s depreciation as per the provisions of section 32(2) and that as
per Chapter IV-D, the book profit was determined only after deduction of
depreciation including unabsorbed depreciation. Since, in the assessee’s case,
there was a loss after deduction of unabsorbed brought-forward depreciation to
the tune of Rs. 10,84,75,430 remuneration to the extent of only Rs. 1,50,000
should have been allowed. Reliance was placed on the decision in Vikas
Oil Mills (Supra)
.


As against that,
the assessee submitted that the remuneration paid to the partners was to be
based on the current year’s book profit derived before deducting the unabsorbed
depreciation and that the set-off of unabsorbed losses and depreciation was
governed by section 72. The unabsorbed business losses were to be set off first
and then the unabsorbed depreciation was to be considered.


The Tribunal upheld
the order of the CIT(A) deleting the disallowance of remuneration paid to the
working partner by the assessee-firm. In addition to accepting the contention
of the assessee, the Tribunal also relied upon the decision of the Ahmedabad
bench of the Tribunal in the case of Yogeshwar Developers vs. ITO [IT
Appeal No. 1173/AHD/2014 for assessment year 2005-06 decided on 13th
April, 2017].
The decision of the Jaipur bench in the case of
Vikas Oil Mills (Supra)
cited before the Tribunal by the Income-tax
Department was not followed by the bench.


OBSERVATIONS

Sub-section (2) of
section 32 provides that where full effect cannot be given to the depreciation
allowance for any previous year, then the depreciation remaining to be absorbed
shall be added to the amount of the depreciation allowance for the following
previous year and deemed to be part of the depreciation allowance for that
year. It further provides that if there is no such depreciation allowance for
the succeeding previous year, then that unabsorbed depreciation of the
preceding previous year itself shall be deemed to be the depreciation allowance
for that year. However, such a treatment of unabsorbed depreciation u/s 32(2)
is subject to the provisions of sub-section (2) of section 72 and sub-section
(3) of section 73 under which first brought-forward business loss needs to be set
off and then unabsorbed depreciation. Therefore, in a situation where the
assessee has brought-forward business loss as well as unabsorbed depreciation,
the combined reading of sections 32 and 72 or 73 required that the
brought-forward business loss shall be set off first against the income of the
previous year and then against the unabsorbed depreciation.


As per
Explanation-3 to section 40(b), all the deductions as provided in Chapter IV-D
including depreciation allowance provided in section 32 have to be taken into
consideration while determining the book profit. Since the provision of section
32(2) treats the unabsorbed depreciation of earlier years at par with the
depreciation allowance of the current year, except where there is a
brought-forward business loss, the issue as to whether the unabsorbed
depreciation should also be deducted from the book profit requires deeper
analysis.


Though the literal
interpretation of all the provisions concerned may appear to support the view
that the amount of depreciation allowance, whether of the current year or the
one which is of the earlier years and has remained unabsorbed, should be
reduced from the net profit for the purpose of arriving at the book profit, one
needs to also consider the legislative history as well as the intent of the
provisions of section 32(2) before accepting the literal interpretation. The
present provision of section 32(2) as it stands today was brought in force by
the Finance Act, 2001 by substituting the old provision with effect from assessment
year 2002-03. The old provision of section 32(2), prior to its substitution by
the Finance Act, 2001, was effective for the assessment years 1997-98 to
2001-02 and it read as under:


(2) Where in the
assessment of the assessee full effect cannot be given to any allowance under
clause (ii) of sub-section (1) in any previous year owing to there being no
profits or gains chargeable for that previous year or owing to the profits or
gains being less than the allowance, then, the allowance or the part of
allowance to which effect has not been given (hereinafter referred to as
unabsorbed depreciation allowance), as the case may be,

(i) shall be set off against the profits and gains,
if any, of any business or profession carried on by him and assessable for that
assessment year;

(ii) if the unabsorbed depreciation allowance cannot
be wholly set off under clause (i), the amount not so set off shall be set off
from the income under any other head, if any, assessable for that assessment
year;

if the unabsorbed
depreciation allowance cannot be wholly set off under clause (i) and clause
(ii), the amount of allowance not so set off shall be carried forward to the
following assessment year and,

(a) it shall be
set off against the profits and gains, if any, of any business or profession
carried on by him and assessable for that assessment year;

(b) if the
unabsorbed depreciation allowance cannot be wholly so set off, the amount of
unabsorbed depreciation allowance not so set off shall be carried forward to
the following assessment year not being more than eight assessment years
immediately succeeding the assessment year for which the aforesaid allowance
was first computed.


It is significant
to note that for the assessment years up to 2001-02, the unabsorbed depreciation
did not become part of the current year’s depreciation and was not to be
reduced from the net profit for the purposes of section 40(b) of the Act; in
short, it was not to be reduced from the book profit. It can be noticed that
the manner in which the unabsorbed depreciation is treated under the old
provision differed greatly from the manner in which it is treated under the
present provision. One of the glaring differences is that before the amendment
it was not being treated as part of the depreciation allowance for the current
year. Instead, it was required to be set off against the profits and gains of
business or profession separately. Sub-clause (a) of clause (iii) of the old
provision made this expressly clear by providing that unabsorbed depreciation
allowance was to be set off against the profits and gains of any business or
profession assessable for the subsequent assessment year as such and not as a
part of the depreciation allowance of that year. Further, the amount against
which the unabsorbed depreciation allowance was required to be set off was the
profits and gains of any business or profession carried on by the assessee and
assessable for that assessment year. The assessable profits and gains of any
business or profession for the purpose was necessarily the profits determined
after claiming all the permissible deductions, including remuneration to the
partners, subject to the limitations provided in section 40(b). Any other
interpretation or connotation was not possible; a contrary interpretation would
have needed an express provision to that effect which was not the case.


As a result, the
requirement under the then Explanation-3 to section 40(b) to compute the book
profit in the manner laid down in Chapter IV-D was to exclude the set-off of
unabsorbed depreciation. Any interpretation otherwise would have led to an
unworkable situation whereunder the amount of unabsorbed depreciation which
could have been set off would then be dependent upon the amount of the
deductible remuneration, and the amount of the deductible remuneration would in
turn be dependent upon the amount of unabsorbed depreciation that could be set
off.


Having analysed the
position under the old provision of section 32(2), let us consider the
objective of its substitution by the Finance Act, 2001 with effect from 1st
April, 2002. The Memorandum explaining the provisions of the Finance
Bill, 2001, which is reproduced below, explains the legislative intent behind
the amendment.


Modification of
provisions relating to allowance of depreciation

Under the
existing provision of sub-section (2) of section 32 of the Income-tax Act,
carry forward and set off of unabsorbed depreciation is allowed for 8
assessment years.

With a view to
enable the assessee to conserve sufficient funds to replace capital assets,
specially in an era where obsolescence takes place so often, the Bill proposes
to dispense with the restriction of 8 years for carry forward and set off of
unabsorbed depreciation.


It can be observed
that the limited purpose of substituting the provision of sub-section (2) of
section 32 was to relax the limitation of eight years over the carry forward of
unabsorbed depreciation. It is worth noting that in order to achieve this
objective, the old provision as it existed prior to its amendment by the
Finance (No. 2) Act, 1996, was being restored. Therefore, effectively, the
present provision of sub-section (2) of section 32 is the same as the provision
as it existed prior to its amendment by the Finance (No. 2) Act, 1996. It was
only for the period starting from the assessment year 1997-98 to 2002-03 that
the provision was different.


In the context of
the old provision prevailing up to assessment year 1996-97, the Supreme Court
in the case of CIT vs. Mother India Refrigeration Industries (P) Ltd.
(1985) 155 ITR 711
has held as follows:


‘It is true that
proviso (b) to section 10(2)(vi) creates a legal fiction and under that fiction
unabsorbed depreciation either with or without current year’s depreciation is deemed to be
the current year’s depreciation but it is well settled that legal fictions are
created only for some definite purposes and these must be limited to that
purpose and should not be extended beyond that legitimate field. Clearly, the
avowed purpose of the legal fiction created by the deeming provision contained
in proviso (b) to section 10(2)(vi) is to make the unabsorbed carried forward
depreciation partake of the same character as the current depreciation in the
following year, so that it is available, unlike unabsorbed carried forward
business loss, for being set off against other heads of income of that year.
Such being the purpose for which the legal fiction is created, it is difficult
to extend the same beyond its legitimate field and will have to be confined to
that purpose.’


In view of these
observations of the Supreme Court and the legislative intent behind section
32(2), it can be inferred that the only purpose of deeming the unabsorbed
depreciation as the depreciation allowance of the current year, post amendment,
is limited to ensuring the benefit of its set off, irrespective of the number
of years, against any income, irrespective of the head of income under which it
falls. In other words the intention has never been to treat it as  part of the depreciation of the year.


Further, in a
situation where the assessee has both, i.e., unabsorbed depreciation and
business loss brought forward from earlier years, the set off of business loss
in terms of sections 72 or 73 needs to be given a preference over set-off of
unabsorbed depreciation as per section 72(2). This again confirms that the
unabsorbed depreciation is given a separate treatment than the business loss
and both are intended to be distinct and separate from each other. The Supreme
Court, in the case of CIT vs. Jaipuria China Clay Mines (P) Ltd. 59 ITR
555
, had held that the reason for such order of allowance is as under:


‘The unabsorbed depreciation allowance is carried
forward under proviso (b) to section 10(2)(vi) of the 1922 Act and the method
of carrying it forward is to add it to the amount of the allowance of
depreciation in the following year and deeming it to be part of that allowance;
the effect of deeming it to be part of that allowance is that it falls in the
following year within clause (vi) and has to be deducted as allowance. If the
legislature had not enacted proviso (b) to section 24(2) of the 1922 Act, the
result would have been that depreciation allowance would have been deducted
first out of the profits and gains in preference to any losses which might have
been carried forward under section 24 of the 1922 Act, but as the losses can be
carried forward only for six years under section 24(2) of the 1922 Act, the
assessee would in certain circumstances have in his books losses which he would
not be able to set off. It seems that the legislature, in view of this gave a
preference to the deduction of losses first.’


The set off of
business loss is governed by section 72 which is part of Chapter VI and not
Chapter IV-D and, therefore, is not required to be considered while computing
the book profit for the purpose of section 40(b). Hence, it would be absurd and
contrary to the provisions to set off the unabsorbed depreciation first only
for the purpose of arriving at the book profit for the purpose of section
40(b), though unabsorbed depreciation is to be set off only after brought-forward
business losses are exhausted in accordance with section 72(2).


Further, if one
analyses the definition of book profits as contained in Explanation 3 to
section 40(b), it refers to ‘net profit, as shown in the profit and loss
account for the relevant previous year…’ 
Therefore, clearly, the intention is only to consider the profit of the
relevant year and not factor in adjustments permissible against such profits
relating to earlier years, such as unabsorbed depreciation.


The better view, in our considered opinion,
therefore is that the brought-forward depreciation should not be deducted while
computing the book profit for
the purpose of
section 40(b).

EXCEL IN WHAT YOU DO – SOME PERSONAL TIPS

I covered some
perspectives on Business Excellence in my previous article1.
In this one, I will share the flavour of Personal Excellence. Often, we
hear people say, ‘follow your heart, pursue your passion, and you will excel’.
How true! That is indeed the way to go. Not only will this lead us seamlessly
on the path of excellence but we will also be happy and derive great
satisfaction. Volumes have been written on how to turn your passion into your
vocation. There are distinguished role models, too, such as Walt Disney, Warren
Buffett and Steve Jobs. If you have cracked this code, great! And perhaps I may
not have anything meaningful to add here.


However, life
is not always so simple. Let’s take two viewpoints:

a) Firstly, do
I know what I am passionate about? If yes, how do I make this my true calling?

b) And if this
does not seem doable at least in the foreseeable future, what do I do to excel
in my chosen path and be happy?


The
growing up years

A child growing
up gets fascinated about multiple things she gets to see, experience or be
impacted by. These come from various quarters – parents, siblings, relatives,
friends, the larger eco-system, television, movies, media, books, success,
appreciation and, of course, now, the internet. Resulting from these,
impressions get formed in the mind of what she would love to do. It is common
for relatives and well-wishers to ask a child ‘Beta, what do you want to
become when you grow up?’ Innocently, children give impromptu answers
which vary across professions – a teacher, a pilot, a judge, a scientist, a
doctor, an environmentalist, an actor, a hotelier, a police officer, an
astronaut and so on. These turn out to be casual conversations and are not
followed through in establishing the real passion or any planning for it. If it
is not a clichéd vocation, some other questions prop up, e.g., will it provide
economic stability? And what about social acceptance? These and more come in
the way of a child moving in the desired direction.


Traditionally,
we have grown up looking at set patterns. The preference is for the science
stream in the senior school curriculum; perhaps this gives the option to switch
later, whereas vice versa is not done. Conventionally, children pursuing
education find themselves propelled towards a closed ABCDE option, that is,
choose between becoming a (chartered) Accountant, (lawyer) Barrister,
Civil services, Doctor or Engineer. Peer pressure has an
influence and in some cultures youngsters are expected to follow the
family tradition, business or profession. It is not uncommon to find a family
of lawyers, Chartered Accountants, doctors or business people to encourage their
kith and kin to follow the family vocation. But the times have changed now. One
could start up in any field from A to Z and be successful. The critical success
factor is personal excellence.


At work

Fast forward
now to life where one has chosen to follow a selected path. By this time, there
could be a growing realisation that our interests lie elsewhere. Sometimes we
may not even feel deeply about this, as daily life gets demanding and time
whizzes by. A simple exercise can be tried out for identifying areas of keen
interest, by connecting the desires with skills as illustrated below (Figure
1)
.


In the above
matrix, we aim to position the areas which bring us little or immense enjoyment
vis-à-vis the qualities intrinsic / developed in the person. Every
individual has unique qualities or areas where s/he is strong or most confident
about. Not only is it important to recognise these, but also necessary to play
to these strong qualities as we go about life. It is also quite possible to
convert areas which need to improve into strengths in the spheres that one
enjoys doing. This, however, is an arduous task or a journey which needs to be
pondered about.


Leveraging
one’s strengths can lead to multiple options and the sweet spot lies in
utilising these in the work area/s which give the most gratification. Such
item/s, which depict confluence of desires and skills indicated in the green
shaded quadrant, will be areas that the person is passionate about and would
derive greatest satisfaction and joy. This ensures that there is a connect
between the enjoyable areas and the required qualities which are necessary to
excel. For example, a person with a feeble voice is unlikely to excel as a
professional singer and his love for music is best kept listening or singing as
a hobby for private enjoyment.


Consider cases where people are keen to
undertake this journey but quite some distance away in getting to convert their
passion into their life purpose. In the foreseeable future, one will therefore
want to excel in the selected sphere of work. In this journey towards personal
excellence
in the chosen engagement, here are some specific tips on actions
or paths that one could find helpful.


GET THE BIG PICTURE

It is important
to comprehend the larger purpose of the activity / function / enterprise that
one is working with. While the day job would be focusing on the nitty-gritty,
the true enjoyment will come from the understanding and the joy of relating to
the higher-level goal. The classic example is of the mason building a mansion,
feeling the pride of building a marvel, while his daily routine may comprise
mundane activities such as laying bricks with cement for a wall.


I have found
great power in communicating this across the organisation so as to touch every
person down the line on the firm’s purpose and facilitate individual connect
and alignment. An impactful way of achieving this is depicted in Figure 2.


While every employee may be clear on their
individual Goals or Key Result Areas (KRAs), this process enables an individual to connect these to the overall organisation purpose.
This whole process executed well is a co-created one involving every person in
the organisation as well as with inputs from key stakeholders. Very briefly
explained, it begins with the organisation’s purpose, the Vision, Mission and Values which are translated
to a Strategic Vision and articulated in a clear, concise manner. Every year,
the Enterprise Balanced Scorecard2 is made which defines the
Strategic Themes and the key Strategic Interventions across four perspectives –
Financial, Customer, Internal Processes and Learning and Growth. These are
cascaded into departmental or functional Strategy Deployment matrices which are
then detailed out into key projects which will deliver the objectives. Every
employee then who is linked to projects is able to derive individual goals for
setting the year’s priorities. At every level there is a linkage to the
relevant processes with the KRAs most aligned to the Level-3 processes. This
way there is a structured alignment amongst individual, departmental, business
and enterprise goals and finely integrated so that the entire organisation
pulls in one direction. At every stage and interval there is a two-way
communication which is the bedrock of a robust cohesive enterprise.


If this process
is not practised in a mature manner, I would suggest that every individual
takes the lead to ascertain this linkage. Like the mason who takes pride in
laying every brick knowing that he is an integral part of creating a wonder,
every individual would then discover a different meaning to their daily routine
which otherwise may seem dreary.


CRAFT A PERSONAL &
PROFESSIONAL GOAL

Equally
important will be to set one’s personal goals. These can be broadly set into
short-term and long-term goals. Like the Balanced Scorecard done in businesses
as referred to above, it may be worthwhile to also cast a personal scorecard.
The perspectives, however, could be different:


(i) Work: What do I wish to achieve on the work
front? Where do I wish to see myself in five to ten years’ time?

(ii) Self: How do I look at improving self over
time? One could consider different aspects such as Health, Finance, Hobby,
Skill-Building, Me-Time and so on.

(iii)
Family:
What are the
various aspects around my immediate and extended family I want to focus on?
Again, it could range from Health to Property to Relationships to Marriage to
Friends.

(iv)
Community:
How can I
contribute to and engage myself for the larger good? With companies engaging in
meaningful CSR activities, it is quite easy to volunteer; as also in this
well-connected world there are many options available for one to venture out
for a greater purpose.


A rounded and
clearer work-life covering the above enhances one’s life’s journey. In all of
the above, the word Balanced may imply that there is equal weightage
given for all the perspectives. While this could be ideal, typically, depending
on one’s needs and stage in life, the weightages can vary. But what must be
borne in mind is that there must be some focus given to each of the four
perspectives.


SHARPEN ONE AREA – BE KNOWN FOR EXPERTISE IN YOUR AREA OF
STRENGTH

Choose one area
and let it be the one which is of interest to you and you enjoy digging deeper
into it. Of course, it should be important to your role and business, e.g.,
GST. Make a conscious effort to develop expertise in that area, so much so that
you begin to be known as the domain expert in that within your team and
enterprise. Furthermore, keep re-skilling yourself in this area so that you
move ahead with the times. By itself, this will open several doors for your
life’s journey.


PICK ONE AREA WHICH IS BOSS’S KEY BUT DESERVES ATTENTION

While it is
imperative that one understands one’s own role thoroughly and does a good job,
it is important to have a broader appreciation of seniors’ roles, in particular
that of the supervisor. It is the desire of every superior to have a deputy
whom he can trust with some critical areas of work; if you can identify one
aspect where you can do a decent job which your supervisor does not have much
inclination for, it is a winner. Not only would you be executing some critical
component of the supervisor’s role, but also be acknowledged for doing it
better. Boss will begin to recognise your potential for taking up higher
responsibilities. Work will take an interesting turn and you will equip
yourself steadily to launch yourself up the ladder.


REINVENT YOURSELF

To make your
job interesting, it is not always necessary to switch. Make a conscious effort
to bring newness into your job. There needs to be a mindful endeavour to
evaluate and improve in a consistent way. If that becomes your way of life, you
will not only see that your job is not really monotonous but also feel it
differently over time. Every period in the role will be different albeit
in the same job. For this process I have found Benchmarking with peers
or the best-in-class a good way to go. This opens up the mind on how others are
progressing and going about things which can be emulated. In today’s times, the
not invented here mindset has no place, and in fact people
copy with pride. Obviously, this is not about infringing patents but
getting inspired from best practices in the public domain as well as learning
from others’ mistakes. The trend today is at the next level of open
innovation
whereby you could put your issues out there for any expert to
opine and help you with innovative ideas.


PREPARE YOUR EXIT

An important
element in making progress is paving the way for moving forward while excelling
in the current role at the same time. Here, both the elements of making oneself
ready for the next superior role as well as grooming the successor are important.
Without this approach, one may find oneself getting stuck in one role or area,
thereby bringing in drudgery and stagnation over time.


Personal
excellence, a perspective

Let me conclude
with a stirring narrative. There are several inspiring examples on personal
excellence
from the Silicon Valley, Fortune 500 Companies, Global Leaders,
Startups or Nobel Laureates, but I chose one from Bollywood – Kishore
Kumar! (Disclaimer: I am a die-hard Kishoreda fan).


Writer Javed
Akhtar3 opines that personal excellence is driven by striving
for next-level performance for one’s own fulfilment and not just for proving it
to others. He recalls an incident. R.D. Burman (Panchamda) hummed a
song, Mere naina saawan bhaadhon (film Mehbooba) which he had
composed based on Raag Sivaranjini. Listening to the tune, Kishoreda
reacted, saying this was meant for Manna Dey. But after some convincing he
agreed to sing; however, he told Panchamda: ‘Isn’t Latabai also
singing this? Do that, I will sing later’. His recording was deferred and Lata
Mangeshkar rendered it first.


Kishoreda
heard this version and practised continuously for seven days! He added his
touch, to make it one of his finest renditions that is cherished to this day.
What is noteworthy is that Kishoreda was at his career peak at that time
and need not have put in such a punitive effort. It would have been a hit
number anyway. But the humility, self-confidence, commitment and the
determination to excel stand out and perhaps this personal excellence
attribute of Kishoreda makes him stand tall amongst the few shining
stars widely remembered in Bollywood even today after so many decades.


ENDNOTE

There is no
perfect occupation, no right time. Just waiting for this to happen may end up
being quite expensive.


The specific
steps enunciated above consciously nurtured will rekindle interest in your
selected path and result in better appreciation and recognition. Who knows, as
you make progress the current engagement itself could become the area you excel
in and turn into your passion.


Is it one way
or the other? Certainly not. While progressing on the selected path, you can
and should also pursue your passion. How do you do this? People often say ‘my
work is so demanding; I have other pressures… I must get some key priorities
in order, and then I will switch to what I love doing’. Unfortunately, this is
a never-ending process and waiting for the perfect time can mean that you are
endlessly in a restive mode. So, do allocate some time outside of work to
follow your passion, whatever it may be. This may challenge your work-life
balance, and could mean doing it in personal space over weekends and holidays.
But in due time satisfaction is bound to come and could even create the
platform for a switch.


So, dream your
passion and… realise your dream!


References:


1. Governance
& Internal Controls: The Touchstone of Sustainable Business – Part II
;
Pp 11-15 BCAJ, June, 2020;

2. The
Balanced Scorecard: Translating Strategy into Action
by David P. Norton and
Robert S. Kaplan;

3. https://youtu.be/U6L8hnsNMak (16:10 – 20:05): Javed Akhtar
remembers Magical Pancham
– Part 02.


‘MUTUALLY ASSURED DESTRUCTION’ IN CORPORATE LENDING

Mutually assured
destruction is a term normally associated with nuclear war.


Its origins go back
to the post-World War II era when the then three superpowers of the world – the
USA, the Soviet Union and China – engaged in a race to spend billions of
dollars to build nuclear weapons. Other countries including India followed
suit. But these countries quickly realised that if and when there is a nuclear
engagement between two nuclear-armed countries, it will lead to disruption and
destruction on such a large scale that perhaps it would destroy life for
generations to come. And the destruction may not be limited only to the
countries engaged in the war, but perhaps to the entire humanity. This
potential destruction caused by a nuclear war is what came to be known in the
US as ‘mutually assured destruction’. The acronym for this, ‘MAD’, is very,
very apt!


‘MAD’ is a term
which today can be widely applied in several areas, including the Indian
Corporate Lending scenario. Just as in nuclear war everyone destroys everyone
else, the stakeholders in this industry have acted in such a way that they have
ended up in a ‘MAD’ state.


WHY THE PLETHORA OF NPAs

Today in the
lending industry in India there is a plethora of NPAs. We have seen the biggest
names in the industry crumble, we have seen insolvencies like never before and
we have seen unprecedented destruction of wealth. The question to be asked is
how did we land up in this scenario? What was it that led to this? To answer
this question, we need to start by looking at corporate lending prior to the
NPAs and prior to the build-up of all those bad loans. To understand this
better, there is a need to comprehend a very simple methodology that any lender
uses while lending money to a corporate. This model is called EIC – basically,
economy, industry and company. A lender will look at not only the company, its
promoters, its business, cash flows, etc., but also look at it in reference to
the industry in which it operates. Thereafter, the industry is analysed based
on the prevalent economic scenario.


There is now one
more ‘E’ to this model and that is environment or the global environment /
economic state. The key point is that none of these elements, i.e., company /
industry / economy can or should be analysed in a silo. The analysis always has
to be comprehensive (or in toto, if you wish).


Statements such as
‘India should grow at 5% or 8% or 10%’ are very naïve, to say the least. All we
need to do is to look around and ask which countries have grown at this pace,
or have even grown at all over the last decade? And, what has growth brought?
Has it ensured equal distribution of wealth amongst all people? Has it pulled
people out of poverty? If not, what good is this growth? India, after all, is
not a bubble which floats around by itself. Its economic state is a result of
what happens around the world. This is typically what is called ‘big picture
dynamics’. Unfortunately, when we forget the big picture and try to look at the
short term and view things in a silo, it inevitably leads to trouble and
destruction.


So, along with the
EIC model, traditionally any lender would also looked at the all-important
three Cs – Company (promoters, business, products, etc.), Cash flow
(serviceability) and Collateral (back-up). This EIC+3 Cs pretty much worked
fine for many years.


Then there was a
huge change in the demand-supply dynamic that came in with licenses being
distributed to a huge number of NBFCs, small finance banks, MFIs, etc. All
these players wanted a piece of the very under-penetrated but very attractive
Indian market. The Indian market though very large, had a certain segment that
the whole industry was after. This segment was already being catered to by
banks. But now these new players also wanted to break in. The question for
these new lenders was what USP could they offer to lure these customers away? Then
began a rat race to grab the all-coveted market share of borrowers.


And this is what
led to the creation of a series of new, innovative, flashy, unthought-of
financial solutions under the domain of structured finance. Structured finance
typically features off-balance sheet funding, name-lending, zero coupon bonds,
etc. Some of these structures were very attractive to the borrowers because
they allowed them to raise debt without disclosing additional leverage on their
financials. While there was nothing inherently wrong with these structures,
what went wrong was that the lenders who were lending under these models
completely forgot and ignored the EIC+3 Cs model. The big picture dynamics also
seemed to have been forgotten. That is what has led us to this mess.


‘NAME-LENDING’ BECOMES
A PROBLEM

While there is no
dearth of examples to prove this, if we can just pick a couple of very well
written and publicised cases which went bad, we will realise how aptly the term
‘MAD’ fits in the corporate lending business. Both of these cases can
technically fall under the domain of ‘name-lending’ which is basically lending
to a reputed customer without thorough analysis and without collaterals (in
most cases).


The corporate
lending business has five critical elements – the borrowing entity, the
promoter, the lender, the auditors and the rating agencies. The best example of
how these five elements collaborated to ensure ‘MAD’ is the downfall of the
IL&FS group. In this particular case, the reason that it stands as one of
the largest NPAs in history is that almost all the stakeholders acted with no
vision, no big-picture dynamics and with a complete ignorance of basics. The
lack of integrity from the management and a total lack of accountability from
the auditors and rating agencies allowed IL&FS to become the mess that it
is today. The lenders, on the other hand, were guilty of showing blind faith in
the name, in the rating agencies and lending without thorough analysis and
collaterals in some cases. This all but ensured their own destruction in the
process, along with the destruction of several corporate entities within the
IL&FS group. This is a classical example of ‘MAD’.


The second apt
example would be Kingfisher Airlines. If we look at this case carefully through
the lens of the EIC+3 Cs model, some glaring, unfortunate decision-making on
the part of the promoter, the company and other stakeholders comes to the fore.


The Indian aviation
industry was booming at the time when KFA was launched. However, for years
together it has been a known fact that globally only five to ten airlines have
ever shown sustainable profitability; and there is a reason for this – this
industry, along with telecom, is completely marred by cut-throat competition.
The fact is the players in this industry cannot really control or decide a
floor price for themselves. Besides, to enter aviation you have to invest large
sums of money and you have to operate almost completely at the mercy of your
competitors who decide the price that customers are willing to pay, on the one
hand, and the ATF and other costs, on the other. There is very little an
aviation company can control on its own. Now, the important thing to note is
that any company to be sustainable has to make profits; possibly after a few years
of operations in industries where there are longer gestation periods. But in
the long run making profits is a must. The revenue model has to be robust
enough to make sustainable profits. In aviation, the only thing you can perhaps
control is a few peripheral costs. But really, without any predictability of a
top line, it is extremely difficult to run a profitable company and to make
sure that it sustains. That’s where the KFA story is very interesting.


At the time of its
launch, we had a reputed promoter who had run a very successful liquor
business. When he launched the airline, he seems to have had this vision that
his airline would resonate the King of Good Times slogan. With that in
mind, KFA was launched with a brand-new fleet, best in-flight entertainment,
best available crew and amazing meals; in short, a fully satisfying customer
experience. All seemed hunky dory for a while. While the airline was not making
too much money, it still seemed to be able to sustain its debt and operate
comfortably. What happened next was just naked ambition – the decision to take
over Air Deccan which was a low-cost carrier.


HIGH COST FOR A
LOW-COST BUY

As it turns out,
this was the starting point of all troubles for KFA. With this takeover, the
airline had a low-cost carrier under its brand and was still trying to match
its ‘best in industry’ service and the other standards that it was known for.
With the pricing of the low-cost carrier being about 30 to 40% lower than the
full-cost carrier, it was a simple case of costs outweighing revenues. It was
unabashedly a failed business model. Typically, any low-cost airline is
supposed to only fly its passengers from point A to point B. No value-added
services are provided because the cost of the tickets is not enough to cover
any other expenses. But KFA Red, which was the low-cost carrier, ignored this
and started operating in its own silo. Again, a case of losing sight of the
basics and losing sight of the big picture. While this happened, to cover the
deficit between income and costs, KFA kept leveraging its balance sheet more
and more and more. The lenders, knowingly or unknowingly, played a crucial role
in allowing this leverage to build up, eventually leading to destruction of
both the company and of themselves.


This was done
through the use of another common concept of corporate lending, i.e.,
‘refinancing’, which is a common end-use stated on the sanction letters of
borrowers in several industries, including real estate. What it means is that
when a Rs. 100-crore loan is up for repayment in the next two to three months,
the borrower approaches another banker and asks for a Rs. 100-crore loan to
repay the first one. And if this cycle continues to go on, it basically means
the borrower never actually repays the principal amount to any lender from his
own pocket. It is like one lender financing another through the borrower’s
balance sheet. This eventually ensures ‘mutually assured destruction’ because
the banker intentionally or unintentionally helps the borrower get
into a habit of never having to repay the principal amount.


MONEY LENT FOR ALL THE WRONG REASONS

Then there is
over-leveraging, another demon that has led to the downfall of most companies.
It is high time the lending industry restrains itself when it realises the
company has passed its ‘sustainable debt’. This is another concept which seems
to be lost on the industry. Lenders keep lending to the same company over and
over again even though its cash flows simply can’t keep up with the piling
debt. What makes it worse is that the money is lent for all the wrong reasons,
such as meeting quarterly targets, eating into another lender’s market share,
name-lending because the promoter is reputed and so on. None of these loans are
lent on the basis of any analysis. Once again, a case of moving away from the
basics, not thinking of the big picture and eventually mutually destructing.


A very important
point to note here is that bankers or lenders are not meant to be in the
business of invoking securities. It is the least productive thing a lender can
do. It basically means that your entire assessment has failed and you are now
relying totally on your back-up. A collateral is just that, a back-up. Yet
today, most lenders spend substantial amounts of time and money in trying to
invoke securities and recover their money.


Now, we can ask
whether all this is too idealistic. Shouldn’t we look at being practical? Who
cares which company survives and which doesn’t? But the problem with this
approach is that it has created a systemic issue of ‘bad credit’. And the
inconvenient thing about ideals is that they are difficult to chase, they
require resilience, they require courage, they require character. But we also
need to remember that if we have all these and we reach our ideals, or even
close to our ideals, very few things can topple us.


Therefore, a lender
needs to have the will and the vision to say ‘no’ when a borrower inches
towards over-leveraging or is struggling with a flawed revenue model.


No promoter who has
built his or her business from the ground up wants to see it destroyed. And
therefore, lenders and rating agencies and other stakeholders need to also
think about sustainability of the businesses they are dealing with and, in
turn, their own sustainability. The sooner this realisation of interdependence
and responsibility comes, the sooner will we start digging ourselves out of our
graves. Perhaps, then, we will automatically also see that there is enough
credit available for the people who need it.


Search and seizure – Block assessment – Sections 132, 158BC, 292CC of ITA, 1961 – Validity of search must be established before block assessment – Computation of income should be based on undisclosed income discovered during search; B.P. 1991-92 to 1998-99

40. Ramnath Santu
Angolkar vs. Dy. CIT
[2020] 422 ITR 508 (Kar.) Date of order: 27th November, 2019 B.P.: 1991-92 to 1998-99


Search and seizure – Block assessment – Sections
132, 158BC, 292CC of ITA, 1961 – Validity of search must be established before
block assessment – Computation of income should be based on undisclosed income
discovered during search; B.P. 1991-92 to 1998-99


The appellant is an individual dealing in real estate and is engaged in
the activity of providing service to landowners for getting compensation in
case of land acquisition for promoting housing schemes, land development and
selling of plots on behalf of the owners on commission or service charges. The
appellant filed his return of income for the A.Ys. 1991-92 to 1998-99. The
aforesaid returns were processed u/s 143(1). On 19th November, 1998,
a search u/s 132 of the Act was conducted in the residential premises of the
appellant and a notice u/s 158BC was issued to the appellant by which he was
required to file his return of income. In response to the aforesaid notice, the
appellant filed the return of income for the block period, i.e., 1st April,
1988 to 19th November, 1998 and declared an additional income of Rs.
4,53,156. Thereafter, a notice u/s 143(2) was issued to the appellant and he
was directed to produce all the details. The A.O. passed an order of assessment
on 28th November, 2000 u/s 158BC(c) and determined undisclosed
income of the appellant at Rs. 1,63,54,846.


Being aggrieved, the appellant filed an appeal before the Commissioner
of Income-tax (Appeals). The appeal was decided by an order dated 23rd
August, 2002 which was partly allowed. The Revenue being aggrieved by this
order, filed an appeal before the Income-tax Appellate Tribunal. The appellant
filed a cross-objection in the aforesaid appeal, to the extent that the appeal
was decided against the appellant. The Tribunal by an order dated 18th
January, 2007, set aside the order of the Commissioner of Income-tax (Appeals)
and remitted the matter to the Commissioner of Income-tax (Appeals) and
directed the issues to be adjudicated afresh by affording an opportunity of
hearing to the parties in accordance with law. The Commissioner thereafter, by
an order dated 30th May, 2008, decided the appeal and partly allowed
the appeal filed by the appellant. The appellant and the Revenue being
aggrieved by this order, again filed appeals before the Tribunal. The Tribunal,
by an order dated 9th September, 2011, partly allowed both the
appeals.


The appellant filed an appeal before the High Court and raised the
following questions of law:


‘(1) Whether the assessment order passed for the block period u/s
158BC(c) of the Act in the name of the individual, when the warrant of
authorisation issued in the joint name of the appellant and others is valid in
law on the facts and circumstances of the case?


(2) Whether the authorities below ought to have examined the validity of
the search and then only proceeded to initiate block assessment proceedings on
the facts and circumstances of the case?


(3) Whether the Tribunal was justified in law in holding that there is
no merit to challenge the action of the A.O. to assess u/s 158BC of the Act
when the conditions precedent are not existing as much as for computation of
income u/s 158BC shall be restricted to seized material on the facts and
circumstances of the case?’


The Karnataka High Court held as under:


‘i)   Section 292CC of the
Income-tax Act, 1961 merely provides that it shall not be necessary to issue an
authorisation u/s 132 or make a requisition u/s 132A separately in the name of
each person. However, it is pertinent to note that where an authorisation is
made in the name of more than one person, the section does not provide that the
names of such persons need not be mentioned in the warrant of authorisation.


ii)   The authorities are under an
obligation to examine the validity of the search and only thereafter proceed to
initiate the block assessment proceedings.


iii)  From a perusal of section
158BC it is evident that while computing the undisclosed income for the block
period, the evidence found as a result of search or requisition of books of
accounts or other books of accounts and such other material or information as
is available with the A.O. and relatable to such evidence, has to be taken into
consideration. In other words, it is evident that the computation of
undisclosed income should be based on such evidence which is seized during the
search which is not accounted in the regular books of accounts.


iv)  The assessment order passed
for the block period u/s 158BC(c) of the Act in the name of the individual,
when the warrant of authorisation was issued in the joint names of the assessee
and others, was not valid in law. Moreover the authorities ought to have
examined the validity of the search and only then proceeded to initiate block
assessment proceedings on the facts and circumstances of the case.


v)   From a
perusal of the material on record, it was evident that there was no seizure
with regard to the A.Ys. 1988-89 and 1989-90 during the course of the search
and seizure operations. However, the A.O. while computing the undisclosed
income had taken into account the income in respect of these years also and
thus the order passed by the A.O. was in violation of section 158BC(c). The
order of block assessment was not valid.’

Revision – Section 263 of ITA, 1961 – Diversion of income by overriding title – Interpretation of Will – Testator’s direction to executor of Will to sell property and pay balance to assessee after payment to trusts and expenses – Expenses and payments to trusts stood diverted before they reached assessee – Order of A.O. after due inquiry accepting assessee’s offer to tax amount of sale consideration – Revision erroneous; A.Y. 2012-13

39. Kumar Rajaram vs. ITO(IT) [2020] 423 ITR 185 (Mad.) Date of order: 5th August, 2019 A.Y.: 2012-13


Revision – Section 263 of ITA, 1961 –
Diversion of income by overriding title – Interpretation of Will – Testator’s
direction to executor of Will to sell property and pay balance to assessee
after payment to trusts and expenses – Expenses and payments to trusts stood
diverted before they reached assessee – Order of A.O. after due inquiry
accepting assessee’s offer to tax amount of sale consideration – Revision
erroneous; A.Y. 2012-13


The assessee was a non-resident. During the
A.Y. 2012-13 he derived income from capital gains and interest income assessed
under the head ‘Other sources’. The assessee’s father bequeathed land and
residential property to him under a Will and testament with directions to the
executor of the Will. The executor was to give effect to the terms and
conditions of the Will and dispose of his properties as stated by him in the
Will. The executor was entitled to professional fees and all expenses for the
due execution of the Will from and out of the estate of the deceased testator.
The executor was to arrange to sell the property after a period of one year
from the date of his demise so as to accommodate his wife for her stay and
distribute the sale proceeds in favour of four charitable institutions
specifying the amount to be paid to each of them after incurring the necessary
expenses towards stamp duty, fees to the executor, etc. The balance sale
consideration was to be paid to the assessee who was to repatriate, according
to the Reserve Bank of India Rules, the amount so received for the education of
his children.


Accordingly, the assessee received a sum of
Rs. 8,19,50,000. The A.O. issued notices under sections 143(2) and 142(1) along
with a questionnaire. In response to the notice u/s 142(1), the assessee
submitted the details including the last Will and testament executed by his
father, a copy of the sale deed, the legal opinion obtained from his counsel
regarding the eligibility for exclusion of the payments to the charitable
institutions and remuneration to the executor in computing the long-term
capital gains on sale of the property. The A.O. accepted the claim of the
assessee in respect of the expenses and passed an order u/s 143(3) and accepted
the sale consideration as mentioned by the assessee in his return of income.
However, the plea raised by the assessee with regard to the indexation of the
cost was not accepted and the A.O. allowed indexation only from the financial
year 2011-12 in accordance with Explanation (iii) in section 48.


The Commissioner issued a notice u/s 263
proposing to disallow the exclusion of the sum of Rs. 68,02,500 being the
payment made to the charitable institutions and the sum of Rs. 8,02,500 being
the professional fees of the executor of the Will and the other expenditure
incurred in connection with the sale of the property. The Commissioner
disallowed the exclusion of Rs. 68,02,500 and directed the A.O. to re-compute
the total income and the tax thereon.


The Tribunal affirmed the order of the
Commissioner that the exclusion of the payments made by the assessee by
applying the diversion of income by overriding the title could not be allowed
and that there was no evidence for professional fee, commission paid, etc.


The Madras High Court allowed the appeal
filed by the assessee and held as under:


‘i) The Commissioner could not have invoked
the power u/s 263. While issuing the show cause notice u/s 263 he did not rely
upon any independent material or on any interpretation of law but on perusal of
the records and was of the view that the expenditure could not be allowed as
deduction u/s 48(i). The Commissioner had conducted a roving inquiry and
substituted his view for that of the view taken by the A.O. who had done so
after conducting an inquiry into the matter and after calling for all documents
from the assessee, one of which was the last Will and testament executed by the
assessee’s father.


ii) The A.O. after perusal of the copy of
the last Will and testament of the assessee’s father, the sale deed of the
property and the legal opinion given by the counsel for the assessee, had taken
a stand and passed the order. Therefore, it could not be stated that the A.O.
did not apply his mind to the issue. It was not the case of the Commissioner
that there was a lack of inquiry or inadequate inquiry.


iii) The testator bequeathed only a portion
of the sale consideration left over after effecting payments directed to be
made by him. The use of the expression “absolutely” occurring in the Will was
to disinherit the testator’s third wife from being entitled to any portion of
the funds and all that the testator stated was not to sell the property for one
year till his wife vacated the house. The sale deed recorded that the
stepmother of the assessee had in unequivocal terms agreed to the sale and had
vacated the property and granted no objection for transfer of the property.
There was a specific direction to the executor to pay specific sums of money to
the charitable institutions, clear the property tax arrears, claim his
professional fee, meet the stamp duty expenses and pay the remaining amount to
the assessee. The order passed by the Commissioner was erroneously confirmed by
the Tribunal.


iv) The Tribunal erred in holding that the
exclusion of payment to charities by applying the principle of diversion of
income by overriding title could not be allowed. The assessee at no point of
time was entitled to receive the entire sale consideration. The sale was to be
executed by the executor of the Will who was directed to distribute the money
to the respective organisations, defray the expenses, pay the property tax,
deduct his professional fee and pay the remaining amount to the assessee.
Therefore, to interpret the Will in any other fashion would be doing injustice
to the intention of the testator and the interpretation given by the
Commissioner was wholly erroneous. The intention of the testator was very clear
that the assessee was not entitled to the entire sale consideration. The
testator did not bequeath the property but part of the sale consideration which
was left behind after meeting the commitments mentioned in the Will to be truly
and faithfully performed by the executor of the Will. The major portion of the
sale consideration on being received from the purchaser of the property stood
diverted before it reached the assessee and under the Will there was no
obligation cast upon the assessee to receive the sale consideration and
distribute it as desired by the testator.


v) The
assessee had produced the copies of the receipts signed by the respective
parties before the A.O. who was satisfied with them in the absence of any fraud
being alleged with regard to the authenticity of those documents. The order of
the Tribunal in not allowing the sum of Rs. 8,02,500 being expenditure incurred
in connection with the sale alleging that there was no evidence when the
evidence in support was on record, was not justified and the expenditure was
allowable u/s 48(i). The Commissioner could not have revised the assessment by
invoking section 263.’


Reassessment – Sections 124(3), 142(1), 143(3), 147, 148 of ITA, 161 – Notice u/s 148 – Assessment proceedings pursuant to notice u/s 142(1) pending and time for completion of assessment not having lapsed – Issue of notice u/s 148 not permissible – That assessee had not objected to jurisdiction of A.O. not relevant; A.Ys. 2011-12

38. Principal CIT vs. Govind Gopal Goyal [2020] 423 ITR 106 (Guj.) Date of order: 15th July, 2019 A.Y.: 2011-12


Reassessment – Sections 124(3), 142(1),
143(3), 147, 148 of ITA, 161 – Notice u/s 148 – Assessment proceedings pursuant
to notice u/s 142(1) pending and time for completion of assessment not having
lapsed – Issue of notice u/s 148 not permissible – That assessee had not
objected to jurisdiction of A.O. not relevant; A.Ys. 2011-12


The Directorate of Revenue Intelligence
received information that the assessee had undervalued the import price of polyester films during the A.Y. 2011-12. At the relevant point of time, it was noticed that the assessee had not filed
his return of income for the A.Y. 2011-12. Therefore, a notice dated 1st December, 2011 u/s
142(1) was issued against the assessee to furnish his return of income for the A.Y. 2011-12 by 9th December, 2011. The assessee did not file his return of income and submitted a letter dated 3rd January, 2012,
stating that his books of accounts and other records were seized by the Directorate of Revenue Intelligence and that he had
applied to be provided with a copy of the books of accounts and other records
and informed the A.O. that he would file his return of income once he was
provided with the books and other records. While the assessment proceedings
initiated u/s 142(1) were pending, the A.O. issued a notice dated 16th January,
2013 u/s 148 against the assessee to file his return of income for the A.Y.
2011-12. The assessment proceedings were completed, making an addition on
account of unexplained expenditure u/s 69C and estimating the net profit.


The Tribunal held that when the assessment
proceedings were already initiated by issuing of notice u/s 142(1) calling for
the return of income, no notice u/s 148 should have been issued and the
assessment was required to be completed within the time limit allowed u/s
143(3) or section 144.


On appeal by the Revenue, the Gujarat High
Court upheld the decision of the Tribunal and held as under:


‘i) It is settled law that unless the return
of income filed by the assessee is disposed of, notice for reassessment u/s 148
cannot be issued, i.e., no reassessment proceedings can be initiated so long as
the assessment proceedings are pending on the basis of the return already filed
(and) are not terminated.


ii) If an assessment is pending either by
way of original assessment or by way of reassessment proceedings, the A.O.
cannot issue a notice u/s 148.


iii) Section 142(1) and section 148 cannot
operate simultaneously. There is no discretion vested with the A.O. to utilise
either of them. The two provisions govern different fields and can be exercised
in different circumstances. If income escapes assessment, then the only way to
initiate assessment proceedings is to issue a notice u/s 148.


iv) Income
could not be said to have escaped assessment u/s 147 when the assessment proceedings
were pending. If the notice had already been issued u/s 142 and the proceedings
were pending, a return u/s 148 could not be called for. The Tribunal had
applied the correct principle of law and had passed the order holding that the
assessment order passed u/s 143(3) read with section 147 was bad in law and
could not be sustained. Section 124(3) which stipulates a bar to any contention
about lack of jurisdiction of an A.O. would not save the illegality of the
assessment in the assessee’s case.’


Sections 2(14), 2(47), 45, 56 – Giving up of a right to claim specific performance by conveyance in respect of an immovable property amounts to relinquishment of capital asset. It is not necessary that in all such cases there should have been a lis pending between the parties and in such lis the right to specific performance has to be given up. The payment of consideration under the agreement of sale, for transfer of a capital asset, is the cost of acquisition of capital gains. Amount received in lieu of giving up the said right constitutes capital gains and is exigible to tax

16. [2020] 117
taxmann.com 520 (Bang.)(Trib.)
Chandrashekar
Naganagouda Patil vs. DCIT ITA No.
1984/Bang/2017
A.Y.: 2012-13 Date of order: 29th
June, 2020


Sections 2(14),
2(47), 45, 56 – Giving up of a right to claim specific performance by
conveyance in respect of an immovable property amounts to relinquishment of
capital asset. It is not necessary that in all such cases there should have
been a lis pending between the parties and in such lis the right
to specific performance has to be given up. The payment of consideration under
the agreement of sale, for transfer of a capital asset, is the cost of
acquisition of capital gains. Amount received in lieu of giving up the
said right constitutes capital gains and is exigible to tax


FACTS

The assessee, an
individual, entered into an agreement dated 9th February, 2005 to
purchase a vacant site in Amanikere village, Bangalore for a consideration of
Rs. 27,60,000. He paid an advance of Rs. 2,75,000 and agreed to pay the balance
at the time of registration of sale deed. The vendor of the property was
required to make out a marketable title to the property. Under clause 8 of the
agreement, the assessee had a right to enforce the terms by way of specific
performance.


On 8th
February, 2011, Mr. Channakeshava as vendor, along with the assessee as a
confirming party, sold the property to a third party for a consideration of Rs.
82,80,000. The preamble to the sale deed stated that the assessee has been
added as a confirming party as he was the agreement holder who had a right to
obtain conveyance of the property from the owner. Out of the consideration of
Rs. 1,200 per sq. feet, a sum of Rs. 500 per sq. feet was to be paid to the
vendor, Mr. Channakeshava, and Rs. 700 per sq. feet was to be paid to the
assessee.


The assessee
considered the sale consideration of Rs. 48,30,000 so received under the head
capital gains. The A.O. was of the view that under the agreement dated 9th
February, 2005, the assessee did not have any right over the property except a
right to get refund of advance paid. Accordingly, he taxed Rs. 45,55,000 under
the head income from other sources.


Aggrieved, the
assessee preferred an appeal to the CIT(A) who confirmed the action of the A.O.
by observing that the assessee did not file any suit for specific performance
and did not have any right over the capital asset.


Aggrieved, the
assessee preferred an appeal to the Tribunal.


HELD

The Tribunal noted that
the Karnataka High Court has in the case of CIT vs. H. Anil Kumar [(2011)
242 CTR 537 (Kar.)]
held that the right to obtain a conveyance of
immovable property falls within the expression `property of any kind’ used in
section 2(14) and consequently it is a capital asset. The Tribunal held that
the right acquired under the agreement by the assessee has to be regarded as
‘capital asset’. Giving up of the right to claim specific performance by
conveyance in respect of an immovable property amounts to relinquishment of the
capital asset. Therefore, there was a transfer of capital asset within the
meaning of the Act. The payment of consideration under the agreement of sale,
for transfer of a capital asset, is the cost of acquisition of the capital
asset. Therefore, in lieu of giving up the said right, any amount
received constitutes capital gain and it is exigible to tax. It is not
necessary that in all such cases there should have been a lis between
the parties and in such lis the right to specific performance has to be
given up. The Tribunal held that the CIT(A) erred in holding that the assessee
did not file a suit for specific performance and therefore cannot claim the
benefit of the ratio laid down by the Hon’ble Karnataka High Court in
the case of H. Anil Kumar (Supra).


The Tribunal
allowed the appeal filed by the assessee.


IS BEING A PROMOTER A ONE-WAY STREET WITH NO EXIT OR U-TURN?

BACKGROUND – CONCEPT OF FAMILY/ PROMOTER-DRIVEN COMPANIES
IN INDIA

A peculiar and important feature of Indian companies and even
businesses in general is that the ownership and management is largely
‘promoter’-driven. There is usually a ‘founder’, an individual who starts a
business which is then continued by his children / extended family for many
generations. The founder family (which may be more than one) usually holds
controlling stake, often more than 50%. The company and group entities are
usually referred to as the ‘X group’ with X representing such family. This is
unlike most companies in the West where, even if founded by an individual whose
family may continue to hold substantial shareholding, the management is often
‘professional’.


Securities laws in India have rightly acknowledged this
feature and there are a multitude of provisions specifically recognising them
and creating an elaborate set of obligations for them. These persons are called
promoters and the various entities (family members, investment companies held
by them, etc.) are called the ‘Promoter Group’. Thus, for example, Independent
Directors are by definition those who are not from or associated with the
Promoter Group. The promoters may be treated as insiders and their trades in
shares of the company regulated. The ‘Promoter Group’ is required to have a
minimum shareholding (at the time of a public issue) and also a maximum
shareholding. It cannot occupy more than a certain number of Board seats. It
has to make regular disclosure of its shareholding. Indeed, the ‘Promoter
Group’ would generally be deemed to be in charge of the company and the buck
for any violation of laws will usually stop at them.


However, there is one curious and difficult area: How can a
person / entity, once designated a promoter, cease to be a promoter? How does
he get an exit and reclassify himself as a non-promoter? As we shall see, and
as particularly highlighted by a recent ‘informal guidance’ by SEBI, it is
relatively easy to become a promoter but extremely difficult to stop being one.


WHO IS A PROMOTER AND WHO BELONGS TO THE PROMOTER GROUP?

There is an elaborate definition of the terms ‘Promoters’ and
‘Promoter Group’ prescribed in the SEBI (Issue of Capital and Disclosure
Requirements), 2018. The Group includes the promoter family and even many
members of the extended family. It also includes specified investment entities
/ group companies / entities. Over time, this list can turn quite long as the
family expands and various new entities are formed and which are covered by the
definition.


The Promoter Group usually gets defined and identified when a
public issue is made, leading to listing of the shares of the company and all
those who are in control of the company are included. Their specified relatives
and group entities are also included. However, as time passes, new relatives
and new entities would get added. But as we will see later, while inclusion is
easy and even automatic, removing even one person is extremely difficult.


REASONS FOR GETTING OUT OF THE PROMOTERS CATEGORY

It has been seen above how easy and automatic it is to become
a promoter. Just being born in the promoter family or otherwise being related
in any of the specified ways could be enough. However, for several reasons, a
person (or an entity with which he is associated in specified manner) may
desire not to be part of the Promoter Group and be saddled with several
obligations and liabilities. There is, of course, the liability of compliance
and even of violations that he remains subject to just by the fact that he is
on the promoter list. If he is in control of the relevant company, this cannot
be escaped.


But there are various reasons why a person may want to be
excluded. He or she may have left the family and may be in employment elsewhere
or carrying on a separate independent business. He may have actually had
disputes with the company and thus no more be part of the core group. He or she
may have married and now not be connected with the company. He may not be
holding any shares or holding insignificant shares and have no say in the
company. In fact, even the whole Promoter Group or a sub-group thereof may have
reason to be excluded if they are reduced to a minority with someone else
taking a higher stake. There would, of course, be the obvious case where a new
promoter acquires most or all of the existing group’s shareholding in a
transparent way (usually by an open offer) and thus takes control of the
company.


There can be many more situations. The question is can an
existing promoter get his name removed from the list of promoters? If yes, how
and what are the conditions?


CONCERNS OF SEBI IN ALLOWING PROMOTERS TO LEAVE THE
CATEGORY

Certain obligations are imposed on promoters who are in
control of the company. If a person who is otherwise in control of the company
or closely connected with persons who are, and is allowed to represent himself
as not a promoter, he would escape this liability. Shareholders, too, perceive
a particular group as the promoters and take decisions accordingly. Thus,
generally, the regulator would want sufficient assurance before allowing the
exclusion of a person from the Promoter Group. However, as we will see below,
the conditions placed are extremely stringent and it may often be difficult for
persons to exclude themselves even for bona fide reasons.


ONCE A PROMOTER, ALMOST ALWAYS A PROMOTER

As mentioned earlier, a person and entities related to him
are required to be declared as promoters at the time of a public issue. Many
entities / persons connected with him in specified ways would also be deemed to
be part of the Promoter Group. Death would do him apart, but then the successors
to his shares would be deemed to be promoters. Thus, the person to whom shares
are willed or even gifted during the (deceased’s) lifetime would become a
promoter.


REQUIREMENT FOR RECLASSIFICATION FROM PROMOTER TO PUBLIC

The requirements relating to reclassification from promoter
to public category are contained in Regulation 31A of the SEBI (Listing
Obligations and Disclosure Requirements) Regulations, 2015 (‘the LODR
Regulations’). These are the outcome of several changes over time and also the
consequence of several discussion papers / committee deliberations. The Kotak
Committee’s report of 2017 on corporate governance had also made detailed
suggestions. SEBI is in the process of proposing yet another round of revision
of the requirements.


There are several conditions that a promoter has to comply
with to be allowed to be reclassified into the public category. Some of these
are obvious and make sense. Such a person (and persons related to him) should
not be holding more than 10% shares in the company. He should not exercise
control, directly or indirectly, over the company. He should not be a director
or key managerial person in the company. He should also not be entitled to any
special rights with respect to the company through formal or informal arrangements.


However, there are further stringent conditions and
requirements if he seeks reclassification. The promoter needs to apply to the
company and needs to demonstrate that he has complied with the other conditions
(i.e., holding 10% or less, not being a director, etc.). The Board of the
company then has to consider this request and place the reclassification
request before the shareholders with its comments. The matter has to be placed
before the shareholders after three months but before six months of the date of
such Board meeting. At such meeting of shareholders, the promoter seeking
reclassification and promoters related to him cannot vote. An ordinary
resolution has to be passed by the remaining shareholders approving such
reclassification. Once so approved, the stock exchanges would then consider the
application and if the requirements are duly complied with, approval would be
granted for reclassification.


Thus, the primary onus and even the decision have been placed
on the Board and the shareholders. In principle, the safeguards may appear
warranted. Leaving the matter to internal decisions also ensures avoidance of
an arbitrary decision by the regulator and also smooth implementation in many
cases. However, the elaborate requirements can make ordinary cases for
exclusion difficult. A family member, for example, may move out of India and
yet he would continue to be a promoter and hence in control unless this
procedure is followed.


There may be disputes
within the family and thus persons seeking exclusion may find their efforts
being sabotaged, even if in principle their requests have to be processed. The
10% shareholding requirement is also too low. At 10% holding, a person / group
has practically no say in the running of the company.


In a recent case (in
re: Mirza International Limited, Informal Guidance dated 10th June,
2020)
it was seen that a promoter gifted shares aggregating to more
than 10% to his daughters who were married and otherwise not involved with the
company. This made them part of the Promoter Group. An informal guidance of
SEBI was sought whether such persons could be reclassified as public instead of
being included in the promoter / Promoter Group. SEBI opined that the fact that
they held more than 10% shares went against the condition prescribed and hence
they could not be reclassified as public.


CONCLUSION AND SUMMARY

There are several
businesses that have seen multiple generations. The businesses may have been
divided. Off-spring may not be interested in the family-controlled companies.
There may be disputes. There may be members of the family who have no say
or even interest in the company. The stringent requirements and procedures are
elaborate and have hurdles which seem unjustified when the primary facts may
show that a person does not have any control or even say in the company.
Indeed, they may not
even hold a single share. Thus, many persons may continue to be deemed to be
promoters and bear the burden of liability in matters in which they have no
say. Such persons may not be promoters by choice and have no easy avenue to get
out. It is high time that the requirements are changed to make them simple and
practical; it is hoped that the coming set of proposed revisions ensures this.

RELIGIOUS CONVERSION & SUCCESSION

INTRODUCTION

Inter-community / inter-faith marriages are increasing in India. It is
becoming common to see a Hindu woman marrying a person professing Islam or Christianity.
Subsequently, she converts to Islam or to Christianity.


In all such cases, a question often arises: whether the Hindu woman who has
converted to another religion would be entitled to succeed to the property of
her parents? Would she be a member of her father’s HUF? Further, what would be
the position of her children – would they be entitled to succeed to the
property of their maternal grandfather? Let us examine these tricky issues in
some detail.


SUCCESSION TO PARENTS’ PROPERTY

Let us first
consider what would be the position of a Hindu woman who has converted to Islam
/ Christianity in relation to her parents’ property. If the parent has made a
Will, then she can definitely be a beneficiary. This is because a Will can be
made in favour of any person, even a stranger. Hence, the mere fact that the
daughter is no longer a Hindu would not bar her from being a beneficiary under
the Will.


However,
what is the situation if the father dies intestate, i.e., without making a
Will? In such a case, the Hindu Succession Act, 1956 would apply. The Class I
heirs of the father would be entitled to succeed to the property of the Hindu
male dying intestate. The daughter of a Hindu male is a Class I heir under the
Hindu Succession Act. Now the question that would arise is whether the
subsequent religious conversion of such a Class I heir would disentitle her
from succeeding to her father’s estate.


The Gujarat
High Court had occasion to grapple with this interesting problem in the case of
Nayanaben Firozkhan Pathan vs. Patel Shantaben Bhikhabhai, Spl. Civil
Appln. 15825/2017, order dated 26th September, 2017.
In this
case, the child of a Hindu wanted to get her name entered in the Record of
Rights of an ancestral land held in the name of her deceased father. The
Collector allowed the mutation in favour of all children except one daughter
who had converted to Islam. It was held that her conversion disentitled her
from succeeding to her father’s estate. The matter reached the Gujarat High
Court. The Court observed that section 2 of the Hindu Succession Act provides
that the Act applies only to Hindus and to persons who were not Muslims,
Christians, Parsis, Jews or of any other religion. However, this section only
provides a class of persons whose properties will devolve according to the Act.
It is only the property of those persons mentioned in section 2 that will be
governed according to the provisions of the Act. Section 2 has nothing to do
with the heirs. This section does not lay down as to who are the disqualified
heirs.


The Court
further analysed the provisions of section 4 which envisages that any other law
in force immediately before the commencement of the Act shall cease to apply to
Hindus insofar as it is inconsistent with any of the provisions contained in
the Act. While a number of Central Acts were repealed as a consequence of this
section, one Act which has not been repealed is the Caste Disabilities
Removal Act, 1850.
This is a pre-Independence Act which consists of one
section which states that:


‘So much of
any law or usage which is in force within India as inflicts on any person
forfeiture of rights or property, or may be held in any way to impair or affect
any right of inheritance, by reason of his or her renouncing, or having been
excluded from the communion of, any religion, or being deprived of caste, shall
cease to be enforced as law in any Court.’


The Gujarat
High Court held that a change of religion and loss of caste was at one time
considered as grounds for forfeiture of property and exclusion of inheritance.
However, this has ceased to be the case after the passing of the Caste
Disabilities Removal Act, 1850. The Caste Disabilities Removal Act provides
that if any law or (customary) usage in force in India would cause a person to
forfeit his / her rights on property or may in any way impair or affect a
person’s right to inherit any property, by reason of such person having
renounced his / her religion or having been ex-communicated from his / her
religion, or having been deprived of his / her caste, then such law or
(customary) usage would not be enforceable in any court of law. Thus, the Caste
Disabilities Removal Act intends to protect the person who renounces his / her
religion.


Further, the
Division Bench of the Madras High Court in the case of E. Ramesh vs. P.
Rajini (2002) 1 MLJ 216
has also taken the same view. It held that the
Hindu Succession Act makes it clear that if the parents are Hindus, then the
child is also governed by the Hindu Law or is a Hindu. It held that the
Legislature might have thought fit to treat the children of the Hindus as
Hindus without foregoing the right of inheritance by virtue of conversion.


Accordingly,
the Gujarat High Court concluded that all that needs to be seen is whether the
daughter was a Class I heir? If yes, then her religion had no locus standi
to her succession to her father’s property.


POSITION OF CONVERT’S CHILDREN

The position
of a person who has converted to Islam is quite clear. Section 26 of the Hindu
Succession Act clearly provides that the descendants of the convert who are born
after such conversion are disqualified from inheriting the property of any of
their Hindu relatives. Thus, the children of a Hindu daughter who converts to
Islam would be disqualified from inheriting the property of their maternal
grandfather.


This section
was explained by the Calcutta High Court in Asoke Naidu vs. Raymond S.
Mulu, AIR 1976 Cal 272.
It explained that this section therefore does
not disqualify a convert. The present Act discards almost all the grounds which
imposed exclusion from inheritance and lays down that no person shall be
disqualified from succeeding to any property on the ground of any disease,
defect or deformity. It also rules out disqualification on any ground
whatsoever except those expressly recognised by any provisions of the Act. The
exceptions are very few and confined to the case of remarriage of certain
widows. Another disqualification stated in the Act relates to a murderer who is
excluded on the principles of justice and public policy. Change of religion and
loss of caste have long ceased to be grounds of forfeiture of property. The
only disqualification to inheritance is found in section 26 which disqualifies
the heirs of a converted Hindu from succeeding to the property of their Hindu
relatives. However, the disqualification does not affect the convert himself or
herself.


POSITION OF CONVERT IN FATHER’S HUF

On the
marriage of a Hindu who has converted to Islam or Christianity, his continuity
in an HUF needs to be considered if his marriage is solemnised under the Special
Marriage Act, 1954
. In such a case the normal succession laws get
disturbed. This would be so irrespective of whether or not the Hindu converts.
All that is required is that the marriage must be registered under this Act.
Section 19 of this Act prescribes that any member of a Hindu Undivided Family
who gets married to a non-Hindu under this Act automatically severs his ties
with the HUF. Thus, if a Hindu, Buddhist, Sikh or Jain gets married to a
non-Hindu under the Special Marriage Act, he ceases to be a member of his HUF.
He need not go in for a partition since the marriage itself severs his
relationship with his family. He cannot even subsequently raise a plea for
partitioning the joint family property since by getting married under the Act
he automatically gets separated from the HUF. Taking the example of the
daughter who converted to Islam, even though she can now be a member of her
father’s HUF by virtue of the Hindu Succession Amendment Act, she would cease
to be a member due to her marriage being registered under the Special Marriage
Act.


SUCCESSION TO THE CONVERT’S PROPERTY

The last
question to be examined is which succession law would apply to such a convert’s
own property? If she dies intestate, would her heirs succeed under the Hindu
Succession Law (since she was once a Hindu) or the Muslim Shariya Law (since
she died a Muslim)? Section 21 of the Special Marriage Act is by far the most
important provision. It changes the normal succession pattern laid down by law
in case of any person whose marriage is registered under the Act. It states
that the succession to property of any person whose marriage is solemnised
under the Act and to the property of any child of such marriage shall be
regulated by the Indian Succession Act, 1925.


Section 21
makes the Indian Succession Act, 1925 applicable not only for the couple
married under the Act but also for the children born out of such wedlock. Thus,
for such a convert whose marriage is registered under the Special Marriage Act,
the succession law would neither be the Hindu Succession Law nor the Muslim Law
but the Indian Succession Act. The same would be the position for her children.
Of course, if she were to make a valid Will, then the Will would prevail over
the intestate succession provisions of the Indian Succession Act.


CONCLUSION

Till such
time as India has a Uniform Civil Code, succession laws are bound to throw up
such challenges. It would be desirable that the succession laws are updated to
bring them up to speed with such modern developments and issues so that legal
heirs do not waste precious time and money in litigation.


Those who always adhere to truth do
not make false promises.

Keeping one’s promises is,
surely,  the mark of one’s  greatness.
(Valmiki
Raamaayan 6.101.52)


THE REAL MEANING OF AHIMSA

There were two old friends Bhaskar and
Avinash who were inseparable. Both became professional lawyers. However, as it
so happens in life, Bhaskar, who was not doing so well in his professional
practice, got an opportunity to provide his services to a big client who was
actually Avinash’s client for several years. The client had approached Bhaskar
to turn over his entire business from Avinash to him in the hope of getting
more economical rates from Bhaskar.


Bhaskar was fully aware that it would be a
deceitful and despicable act if he took over this client’s work and he wrestled
with his conscience for over two days to be able to say ‘no’. Eventually, he
lost the battle with his conscience and agreed to take over the brief. He did
this clandestinely so that Avinash would not know that he had done so.


Avinash initially did not realise that it
was Bhaskar who had taken over the client, but truth always surfaces somehow. A
few days later he came to know from one of his friends working with the client
that it was Bhaskar who had betrayed him. His natural reaction was intense
anger and hatred towards Bhaskar, which was understandable. He wanted to retaliate
by having a showdown with Bhaskar and cutting off all ties with him and
exploring ways of seeking revenge by damaging Bhaskar’s relationship with the
client. He was in a position to do that because in the past he had served that
client for many years and therefore he knew a lot of things about the client
which would have been sufficient to compel him to return to him.


The temptation to take these severe
vindictive steps was very strong and it took him a long time to resist it, but
eventually he did. He decided to look at the past lovely relationship with
Bhaskar and the ‘good’ part within him urged him not to destroy that. When his
mind started thinking such positive thoughts, the creativity of his mind also
increased. He had heard a saying in Gujarati (Sachu bal badlo levama nahin,
pan samhena manas ma badlav lavama chhe)
meaning that real strength is not
in taking revenge but in bringing about a change in the other person. He
finally came to the conclusion that he would not retaliate but actually convey his
good wishes to both the client and to Bhaskar.


He met them both pleasantly and cheerfully
wished them the best for the future and assured them of his support in case of
any need. He assured the client that going to Bhaskar was like going to
Avinash’s family member and that he held no grudge or spite. To Bhaskar he
offered him access to all the client’s files, papers, documents and other
things lying in his office and assured him of all help in any matter in future.
Both the client and Bhaskar were deeply touched. Bhaskar, being an old friend,
realised his grave error and broke down and profusely apologised for having
taken this step and offered to step out, which Avinash lovingly refused. Their
friendship became thicker and Bhaskar was a wiser person thereafter.


Can this act of Avinash be considered ahimsa?
Most certainly yes.


Ahimsa, as is
commonly understood, means practising non-violence but it is much more than
that. It is not restricted to the physical dimension. Real ahimsa
is practised in thought, word and deed. Restricting and controlling our
physical violent reactions is fine but it is incomplete without verbal
and mental congruence with that control. Thus if Avinash had not had a
showdown, it was good, but the real ahimsa was achieved when he
harboured no ill feelings in his mind and went to make peace.
This was not
easy at all. In fact, mental ahimsa is exponentially more difficult than
physical ahimsa. But when practised and implemented, the power that it
can wield is immeasurable and infinite.


The classic example is that of Mahatma
Gandhi himself. His body was lean and frail and perhaps even a little lad could
have easily knocked him down, but the strength which he drew from his ahimsa
was able to move millions of people across India at his call and for any cause
suggested by him. That was because he practised congruence of thought, word and
deed in ahimsa. Ahimsa was strongly advocated by Mahatma Gandhi
during our freedom movement and there is no doubt that perhaps this was the single
strongest weapon which gave us our independence. It is best illustrated by the Dandi
March
when hundreds of Indians stoically endured the Britishers’ beatings
without retaliation.


Though the conduct of ahimsa may
externally appear to be a sign of weakness and surrender, actually it is
exactly the opposite. To practice ahimsa one needs superlative strength
and self-control. It is said that real power or strength is not that which one
can exhibit in a wrestling match or a battle of any kind, but it is that which
is needed to curb one’s anger, hatred, emotions and power itself. Ahimsa
is that supreme power which is needed not to control another person, but one’s
own self. The biggest battle in life is the conquest over one’s own self.


Therefore, friends, let’s try to bring peace
in our minds. Our words and deeds will automatically follow suit. Do not be perturbed by insults, taunts, or situations where anger and hatred are
automatic consequences. The only antidote for such negative emotions is love.


‘INDIA, THAT IS BHARAT’

I hope you and your near and dear ones are well during the most challenging
health emergency that this generation has seen.


A nation is the widest form of society that we identify with and manage.
Individuals form families; and families make a community, a city and a nation
state. Geographically, politically and psychologically we have reached thus far
in the evolution of mankind. A nation is the sum total of all the differences
that we have been able to bring together in a cohesive, interwoven unit. A
nation is meant to bridge differences, like a thread that holds together
different flowers in a garland. Differences assume less importance and get
subsumed in the larger reality of a nation. Backgrounds, ethnicities,
religions, languages, histories and all other nuances must find their
culmination in a nation.
This in my view makes ‘India, that is Bharat’,
as per the first Article of our Constitution.


India is the last ancient, continuously surviving civilization, and it
finds its common denominator within an incomparable variety. For example, there
are many scripts and languages which are influenced by or rotted in Sanskrit; a
common set of civilizational values still becomes the binding force – a SamanVayaKaari
Shakti
.


We are also faced with threats. As citizens we should be able to see
trouble when politics and media focus on our differences and portray
them as divisions. Unlike the Indian approach, the Cartesian approach
sees the universe made up of smaller fragments that are simply put together but
do not have a common continuum. For example, in ‘modern’ India ‘identity’ is
made to stand out. Identity grants benefits – social and religious identities
get concessions, jobs, educational reservation, and so on. So people keep
lesser identity in the forefront above all else. This sorry state of affairs in
our country also results in throwing merit into the dustbin and accentuating separation
to an unimaginable extent.


Another threat is colonisation of the Indian mind that is perpetuated. In
the words of Shri Amitabh Bachchan, we are still ‘respectful and tolerant to
colonial indoctrination’.
He was speaking about branding of words at the
IAA World Congress and gave the example of Thiruvananthapuram which till
recently was known as Trivandrum. He said, Trivandrum meant nothing. Whereas Thiruvananthapuram
means Thiru Anantha Puram – Shelter of the Infinite. Today, many
‘educated’ Indians twist phonetics of Indian words by messing the longs as
shorts and the shorts as longs in imitation. Yog is Yogaa, Raamaayan is
Raamayanaa, Himaalay is Himalaayaa. During a session I attended, this turned
out to be quite embarrassing and funny when a person introduced the next
speaker as Kamini, when her name was Kaamini. Many Dishonest words give
dishonest results, Bachchanji said. He gave the example of Rabindranath Thakur
who is known as Tagore although his family name is Thakur and their house was in
Thakur Baadi. Such usage changes the ‘meaning, perception, concept,
consideration, viewpoint’ of words. We need to pay attention to this and
reclaim the true import of words and their beautiful meanings.


Lastly, as Indians we have to ask – how do we see ourselves and what
makes us feel proud of who we are?
A generation ago it was three Es –
English, Education and Employment. But that is changing. The biggest success
stories today are not necessarily rooted in the three Es. In the last three
decades, we have seen a surge in enterprise, education, and confidence despite
government interference and even obstruction. Yet, we are still aspiring to be AtmaNirbhar.
AtmaNirbhar comes from the word Bhar, which means full or
complete – the confidence that comes from the feeling of being full or complete
in one’s true identity. How can we feel full and complete and interact with a
globalised world with a feeling of incompleteness or lack or neediness? How can
we be rooted in our civilizational ethos and apply it to the current context?
These are some questions as we approach our 74th Independence Day!


Raman
Jokhakar

Editor

Reopening of assessment – Beyond four years – Information from Investigation Wing – Original assessment completed u/s 143(3) – Primary facts disclosed – Reasons cannot be substituted

8. Gateway
Leasing Pvt. Ltd. vs. ACIT (1)(2) & Ors.
[Writ Petition No. 2518 of 2019] A.Y.: 2012-13 Date of order: 11th March, 2020 (Bombay High Court)

[Appellate
Tribunal in I.T.A. No. 5535/Mum/2014; Date of order: 11th January,
2017; A.Y.: 2003-04; Bench ‘F’ Mum.]


Reopening of assessment – Beyond four years
– Information from Investigation Wing – Original assessment completed u/s
143(3) – Primary facts disclosed – Reasons cannot be substituted


The petitioner is a company registered under
the Companies Act, 1956 engaged in the business of financing and investing
activities as a non-banking financial company registered with the Reserve Bank
of India.


Through this petition, the petitioner sought
quashing of the notice dated 31st March, 2019 issued u/s 148 of the
Act by the ACIT Circle 1(1)(2), Mumbai as well as the order dated 26th
August, 2019 passed by the DCIT Circle 1(1)(2), Mumbai, rejecting the
objections raised by the petitioner to the re-opening of its assessment.


For the A.Y. 2012-13 the petitioner had
filed return of income on 20th September, 2012 declaring total
income of Rs. 90,630. Initially, the return was processed u/s 143(1) of the
Act. But the case was later selected for scrutiny. During the course of
assessment proceedings, details of income, expenditure, assets and liabilities
were called for and examined. After examination of these details, the A.O.
passed an order u/s 143(3).


On 31st March, 2019 the A.O.
issued a notice u/s 148 stating that he had reasons to believe that the
petitioner’s income chargeable to tax for the A.Y. 2012-13 had escaped
assessment within the meaning of section 147. The petitioner sought the reasons
for issuing the said notice. It also filed return of income u/s 148, returning
the income at Rs. 90,630 as originally assessed by the A.O. u/s 143(3). By a
letter dated 31st May, 2019, the A.O. furnished the reasons for
re-opening of the assessment.


It was stated that information was received
from the Investigation Wing (I/W) of the Income Tax Department that a search
and seizure action was carried out on the premises of one Mr. Naresh Jain which
revealed that a syndicate of persons was acting in collusion and managing
transactions in the stock exchange, thereby generating bogus long-term capital
gains / bogus short-term capital loss and bogus business loss entries for
various beneficiaries.


From the materials gathered in the course of
the said search and seizure action, it was alleged that the petitioner had traded
in the shares of M/s Scan Steel Ltd. and was in receipt of Rs. 23,98,014 which
the A.O. believed had escaped assessment within the meaning of section 147. It
was also alleged that the petitioner had failed to disclose fully and truly all
material facts necessary for the assessment for the A.Y. 2012-13 for which the
notice u/s 148 was issued.


The petitioner submitted objections to
re-opening of assessment proceedings on 26th June, 2019. Referring
to the reasons recorded, it was contended on behalf of the petitioner that the
original assessment was completed u/s 143(3) where all the details of purchase
and sale of shares of M/s Scan Steels Ltd., also known as Clarus Infrastructure
Realties Ltd. (earlier known as Mittal Securities Finance Ltd.), were disclosed.
While denying that the petitioner had any dealing with the parties whose names
cropped up during the said search and seizure action, it was stated that the
purchase and sale of shares were done by the petitioner through a registered
broker of the Bombay Stock Exchange. Payment for the purchase of the shares was
made by cheque through the BSE at the then prevailing market price. Thus, there
was no apparent reason to classify the receipt of Rs. 23,98,014 as having
escaped assessment. Therefore, it was contended that the decision to re-open
assessment was nothing but change of opinion, which was not permissible in law.


The A.O. by his letter dated 26th
August, 2019 rejected the objections raised by the petitioner and stated that
the petitioner had furnished the details of purchase and other material facts
before the A.O. and the latter, in his assessment order, had totally relied on
the said submissions and accepted the same without cross-verification. It was
further stated that the challenge to the impugned notice was untenable.
Besides, the Act provided for a host of remedial measures in the form of
appeals and revisions. Finally, the Department justified issuance of the
impugned notice and re-opening of the assessment and made a reference to the
report of the I/W. As per the I/W, the petitioner had diluted its income by
adopting manufactured and pre-arranged transactions which were never disclosed
to the A.O. Such action was a failure on the part of the petitioner to make
full and true disclosure of all material facts. The petitioner’s contention
that all primary facts were disclosed were thus disputed. That apart, it was
contended that the Pr. CIT-1 had applied his mind and thereafter granted
approval to the issuance of notice u/s 148.


In its rejoinder, the petitioner submitted
that all details about the purchase and sale of shares of Mittal Securities
Ltd. were furnished. The A.O. was not required to give findings on each issue
raised during the course of the assessment proceedings. The A.O. had applied
his mind and granted relief to the petitioner in the assessment order.
Normally, when the submission of an assessee is accepted, no finding is given in
the assessment order.


The Hon’ble Court, after referring to
various decisions, observed that the grounds or reasons which led to formation
of the belief that income chargeable to tax has escaped assessment must have a
material bearing on the question of escapement of income of the assessee from
assessment because of his failure or omission to disclose fully and truly all
material facts. Once there exist reasonable grounds for the ITO to form the
above belief that would be sufficient to clothe him with jurisdiction to issue
notice.


However, sufficiency of the grounds is not
justifiable. The expression ‘reason to believe’ does not mean a purely
subjective satisfaction on the part of the ITO. The reason must be held in good
faith. It cannot be merely a pretence. It is open to the Court to examine
whether the reasons for the formation of the belief have a rational connection
with or a relevant bearing on the formation of the belief and are not
extraneous or irrelevant. To this limited extent, initiation of proceedings in
respect of formation of the belief that income chargeable to tax has escaped
assessment must have a material bearing on the question of escapement of income
of the assessee from assessment because of his failure or omission to disclose
fully and truly all material facts.


The Court further observed that it would be
evident from the material on record that the petitioner had disclosed the above
information to the A.O. in the course of the assessment proceedings. All
related details and information sought by the A.O. were furnished. Several
hearings took place in this regard after which the A.O. had concluded the
assessment proceedings by passing the assessment order u/s 143 (3). Thus it
would appear that the petitioner had disclosed the primary facts at its
disposal for the purpose of assessment. He had also explained whatever queries
were put to it by the A.O. with regard to the primary facts during the
hearings.


In such circumstances, it cannot be said that the petitioner did not
disclose fully and truly all material facts necessary for the assessment.
Consequently, the A.O. could not have arrived at the conclusion that he had
reasons to believe that income chargeable to tax had escaped assessment. In the
absence of the same, the A.O. could not have assumed jurisdiction and issued
the impugned notice u/s 148 of the Act. That apart, the A.O. has tried to
traverse beyond the disclosed reasons in the affidavit which is not
permissible. The same cannot be taken into consideration while examining the validity
of the notice u/s 148. The reasons which are recorded by the A.O. for re-opening an
assessment are the only reasons which can be considered when the formation of
the belief is impugned; such reasons cannot be supplemented subsequently by
affidavit(s). Therefore, in the light of the discussions, the attempt by the
A.O. to re-open the concluded assessment is not at all justified and
consequently the impugned notice cannot be sustained and the impugned order
dated 26th August, 2019 is also quashed.


Industrial undertaking – Special deduction u/s 80-IA(4) – Industrial undertaking engaged in production of power – Meaning of ‘power’ in section 80-IA(4) – Power would include steam; A.Y. 2011-12

37. Principal CIT vs. Jay Chemical Industries Ltd. [2020] 422 ITR 449 (Guj.) Date of order: 17th February, 2020 A.Y.: 2011-12


Industrial undertaking – Special deduction
u/s 80-IA(4) – Industrial undertaking engaged in production of power – Meaning
of ‘power’ in section 80-IA(4) – Power would include steam; A.Y. 2011-12


For the A.Y. 2011-12 the assessee had
claimed deduction of Rs. 32,51,080 u/s 80-IA(4) of the ITA, 1961. This claim
was on account of the operation of the captive power plant. The assessee showed
income from sale of power to the tune of Rs. 1,23,10,500 and the sale of vapour
at Rs. 6,59,77,170. The A.O. took the view that ‘vapour’ would not fall within
the meaning of ‘power’.


The Commissioner (Appeals) and the Tribunal
allowed the assessee’s claim.


On appeal by the Revenue, the Gujarat High Court upheld the decision of
the Tribunal and held as under:


‘i) Section 80-IA(4) of the Income-tax Act,
1961 provides for special deduction to industrial undertakings engaged in the
production of power. The word “power” should be understood in common parlance
as “energy”. “Energy” can be in any form, mechanical, electricity, wind or
thermal. In such circumstances, “steam” produced by an assessee can be termed
as power and would qualify for the benefits available u/s 80-IA(4).


ii) Steam had
to be considered as “power” for the purpose of deduction u/s 80-IA(4).’

Deemed income – Section 41(1)(a) of ITA, 1961 – Remission or cessation of liability – Condition precedent – Assessee, a co-operative society, obtaining loan from National Dairy Development Board for which state government stood guarantee on payment of commission – Commission claimed by assessee as revenue expenditure in earlier assessment years – State government writing off liability and allowing it to be treated as capital grant to be used only for capital and rehabilitation purposes – Assessee continues to remain liable to repay those amounts – No remission or cessation of liability u/s 41(1)(a) – Cannot be treated as deemed income u/s 41(1)(a); A.Y. 2004-05

36. Principal CIT
vs. Rajasthan Co-Operative Dairy Federation Ltd.
[2020] 423 ITR 89 (Raj.) Date of order: 23rd July, 2019 A.Y.: 2004-05


Deemed income – Section 41(1)(a) of ITA,
1961 – Remission or cessation of liability – Condition precedent – Assessee, a
co-operative society, obtaining loan from National Dairy Development Board for
which state government stood guarantee on payment of commission – Commission
claimed by assessee as revenue expenditure in earlier assessment years – State
government writing off liability and allowing it to be treated as capital grant
to be used only for capital and rehabilitation purposes – Assessee continues to
remain liable to repay those amounts – No remission or cessation of liability
u/s 41(1)(a) – Cannot be treated as deemed income u/s 41(1)(a); A.Y. 2004-05


The assessee, a
co-operative society involved in milk and milk product processing, secured a
loan from the National Dairy Development Board for which the government of
Rajasthan stood guarantor subject to payment of commission of Rs. 25 lakhs per annum.
This was claimed as expenditure by the assessee for several years up to the
A.Y. 2004-05. The amount remained outstanding and was shown as payable to the
government of Rajasthan. The state later wrote off that liability and allowed
it to be treated as a capital grant to be used only for capital and
rehabilitation purposes. The A.O. was of the view that the transaction, i.e.,
cessation of liability, involved the utilisation of receipts which had been
treated as revenue all along and, therefore, treated it as deemed income u/s
41(1)(a) of the Income-tax Act, 1961 for the A.Y. 2004-05.


The Commissioner (Appeals) allowed the
appeal and held that the amount payable to the government was to be treated as
capital grant to be used for rehabilitation or capital requirement of the
assessee and could not be used for any further distribution of dividend or
revenue expenditure, and that it was not a case of remission or cessation of
the liability as envisaged u/s 41(1)(a). The Tribunal concurred with the view
of the Commissioner (Appeals) and dismissed the appeal filed by the Department.


On appeal by the Revenue, the Rajasthan High
Court upheld the decision of the Tribunal and held as under:


‘Both the Commissioner (Appeals) and the
Tribunal had rendered concurrent findings on the facts. The record also
supported their findings in that the loan utilised by the assessee was for
capital purposes and the loan was given by the National Dairy Development
Board. The assessee continued to remain liable to repay those amounts. The
state, instead of fully writing off the amounts, had imposed a condition that
they would be utilised only for capital or rehabilitation purposes. This was
therefore a significant factor, i.e., the writing off was conditional upon use
of the amount in the hands of the assessee which was for the purpose of
capital. No question of law arose.’

IS IT FAIR TO TREAT RCM SUPPLIES AS EXEMPT?

HISTORY OF RCM IN INDIA

Reverse
Charge Mechanism or RCM is not a new concept in the Indirect Tax arena. It was
first introduced in India in 1997 on services provided by Goods Transport
Agency and Clearing and Forwarding Agent. Even the erstwhile Sales Tax and VAT
Laws in some states had a tax similar to RCM, the purchase tax wherein the
buyer or recipient of goods had to pay tax on purchase of specified goods; for
example, Maharashtra levied a purchase tax on cotton. The current GST regime
has only taken this forward, bringing in some more categories of goods and
services under the net of RCM.


India
is not the only country with RCM provisions; most of the developing and developed
nations have RCM provisions including EU VAT, Australia, Singapore, etc. The
underlying reason for introducing RCM in India was to map the unorganised
sector and shift the compliance liability regarding the same to the organised
recipients. It was believed that this would lead to increase in tax revenue
and make administration of the small unorganised sector easy.


From
an economy’s perspective, RCM is a robust check mechanism to ensure that all
supplies are taxed and there is minimal evasion. However, the concept has
certain flaws and repercussions that need to be dealt with.


RCM UNDER GST

RCM
under GST is governed by sections 9(3) and 9(4) of the CGST Act, 2017 which
essentially lay down the following:

(a)  9(3): Supply of specified categories of notified
goods and / or services attract GST under RCM where the recipient is liable to
pay tax on such goods and / or services;

(b)
9(4): Supply made by an unregistered person to a registered person, wherein the
registered recipient shall be liable to pay tax.


Further,
Notification No. 13/2017-CT (Rate) dated 28th June, 2017 notifies
the categories of supplies which shall attract GST under RCM u/s 9(3) of the
CGST Act, 2017. Considering that under the RCM provisions the recipient pays
tax instead of the supplier, the recipient is eligible to avail Input Tax
Credit (ITC) of the tax so paid. However, as per section 17(3) of the CGST Act,
2017 the value of exempt supply shall include reverse charge supplies and
therefore ITC on the inputs and / or input services used for making such
reverse charge supplies is not available. Accordingly, the ITC pertaining to
such supplies stands unutilised and blocked.


While
the recipient certainly bears the brunt of the compliance burden on RCM
supplies, he remains financially unaffected as the tax paid can be availed as
credit (subject to his taxable and exempted supplies). However, this provision
proves to be prejudicial against the supplier who is unable to avail ITC
pertaining to inputs or input services used for supplying RCM supplies and also
leads to double taxation.


Moreover, if such supplier is engaged only in a
single business (i.e., RCM supplies), the entire ITC paid becomes a cost to
him. Let us understand this with the help of a numeric example as given below:


Sr. No.

Particulars

Under normal or
forward charge mechanism

Under reverse charge
mechanism

1

Value of inputs and / or input services used by the supplier

100

100

2

GST paid on 1 above @ 18%

18

18

3

Value addition made @ 30%

30

30

4

Cost of production (COP)

130

130

5

Profit @ 30% of COP

39

39

6

Selling price

169

169

7

GST on selling price @ 18%

30.42

30.42 (paid by recipient)

8

ITC available for set-off

18

9

Net GST paid by the supplier

12.42

18

10

ITC available to recipient

30.42

30.42


In the above example, it is evident
that although the recipient in both cases is eligible to avail the same ITC, it
is the supplier who faces iniquitous treatment.


Under GST, there are exempt,
zero-rated, taxable and non-GST supplies. For supplies that are either taxable
or zero-rated, ITC is available to the supplier. However, for exempt and
non-GST supplies such as essential items, reverse charge supplies, petroleum,
alcohol, etc., the suppliers suffer as they pay GST on the inward side but fail
to avail the set-off of the same as their outward supplies are not taxed. When
GST was being rolled out, the GST Council had received several representations
from sectors such as pharma, poultry, education, etc. to examine the problem of
accumulated ITC on account of exempt supplies. However, the problem remains
unaddressed till now as far as RCM is concerned.


During the Covid-19 outbreak, the
Supreme Court dismissed various pleas which had sought exemption from GST for masks, ventilators, PPE kits and other Covid-19-related equipment
on the premise that granting exemption to these would result in blocked ITC,
thereby increasing the manufacturing cost and occasioning a higher price for
consumers.


The
Council has in the past taken steps to address the issue of inverted duty
structure. However, the businesses which deal in exempted supplies are still
reeling from the impact of accumulated credits. The Council needs to deliberate
on the probable solutions to the above-mentioned concerns. The immediate
actions could include:


(i) Taking stock of items which are
exempt supplies, including the RCM supplies;

(ii) Evaluating the inward supplies used by such suppliers;

(iii) Exempting the inward supplies for the entire
chain of suppliers if feasible, or providing a mechanism of refunds to such
suppliers;

(iv) If not feasible, then
classifying the outward supplies as zero-rated supplies so that ITC is
available to the suppliers;

(v) An
option can be provided to the RCM sellers: whether to be classified as an RCM
supplier or not. This will give an alternative to sellers to evaluate the
trade-off between the cost of compliance and credit lost. Suppliers with
substantial credit can avail the ITC and carry out the compliances themselves
as against the small suppliers who would not like to get into the compliance
hassle. Similarly, this can be indicated in the tax invoice so as to inform the
buyer about whether or not to levy GST under RCM on the basis of the option
chosen by the supplier.


CONCLUSION

Is it fair for the RCM
suppliers to endure the unwarranted loss of credit for the simple reason that
their products or services, viz. sponsorship services, legal services, security
services, GTA services, cashew nuts, silk yarn, raw cotton, etc. are covered by
the said mechanism?


As discussed above, RCM is a tax
concept meant for the small and unorganised sector. Therefore, shouldn’t the
government be extra vigilant about any financial hardships being caused to
these small traders and businesses by the tax mechanism? Every business incurs
certain non-avoidable expenses including rent, audit fees, housekeeping,
business promotion, etc. All these input services are exigible to GST and constitute a large chunk of the
expenditure in the supplier’s profit and loss account. The GST pertaining to these expenses not being allowed as ITC
gives rise to superfluous adversities.


One of the most prominent objectives of GST was to eliminate
cascading effect and double taxation. While the government has, to a large
extent, been able to meet this objective, it remains to be seen whether the RCM
suppliers will also experience the benevolence of the Good and Simple Tax soon
enough!


Wise men say that the root of victory is in consultation with the wise.


  (Valmiki Raamaayan 6.6.5)

Assessment – Notice u/s 143(2) of ITA, 1961 – Limitation – Notice calling for rectification of defects in return u/s 139(9) – Rectification within time allowed in notice – Not a case of revised return but of corrected return which relates back to date of original return – Limitation for notice u/s 143(2) runs from date of original return, not date of rectified return; A.Y. 2016-17

35. Kunal Structure (India) Private Ltd. vs. Dy.CIT [2020] 422 ITR 482 (Guj.) Date of order: 24th October, 2019 A.Y.: 2016-17


Assessment
– Notice u/s 143(2) of ITA, 1961 – Limitation – Notice calling for
rectification of defects in return u/s 139(9) – Rectification within time
allowed in notice – Not a case of revised return but of corrected return which
relates back to date of original return – Limitation for notice u/s 143(2) runs
from date of original return, not date of rectified return; A.Y. 2016-17


For
the A.Y. 2016-17, the petitioner company had filed its return of income u/s
139(1) on 10th September, 2016. Thereafter, the petitioner received
an intimation of defective return u/s 139(9) of the Act on 17th
June, 2017. The petitioner received a reminder on 5th July, 2017
granting him an extension of fifteen days to comply with the notice issued u/s
139(9) and accordingly, the time limit for removal of the defects u/s 139(9) of
the Act stood extended till 20th July, 2017. The petitioner removed
the defects on 7th July, 2017 within the time granted. Subsequently,
the return was processed u/s 143(1) on 12th August, 2017 wherein the
date of original return is shown to be 10th September, 2016.
Thereafter, the impugned notice u/s 143(2) of the Act came to be issued on 9th
August, 2018, informing the petitioner that the return of income filed by it for the A.Y. 2016-17 on 7th
July, 2017 has been selected for scrutiny.


The assessee
filed a writ petition and challenged the notice. The Gujarat High Court allowed
the petition and held as under:


‘i)  A study of the provisions of section 139 of
the Income-tax Act, 1961 shows that under sub-section (1) thereof, an assessee
is required to file return on or before the due date. If one looks at the
language employed in sub-sections (1), (3) and (5) of section 139, a common
thread in all the sub-sections is that the assessee is required to file a
return of income under those sub-sections. However, from the language employed
in sub-section (9) of section 139 of the Act, it does not require any return to
be filed by the assessee. All that the section says is that the assessee is
required to be given an opportunity to rectify the defect in the return filed
by him within the time provided, failing which such return would be treated as
an invalid return.


ii)  Unlike sub-section (5) of section 139 of the
Act which requires an assessee to file a revised return of income in case of
any omission or wrong statement in the return of income filed under sub-section
(1) thereof, sub-section (9) of section 139 of the Act does not require an
assessee to file a fresh return of income, but requires the assessee to remove
the defects in the original return of income filed by him within the time
provided therein. Once the defects in the original return of income are
removed, such return would be processed further under the Act. In case such
defects are not removed within the time allowed, such return of income would be
treated as an invalid return.


iii) There is a clear distinction between a revised
return and a correction of return. Once a revised return is filed, the original
return must be taken to have been withdrawn and substituted by a fresh return
for the purpose of assessment. There is no concept of corrected return of
income under the Act. Therefore, in effect and substance, what the notice under
sub-section (9) of section 139 does is to call upon the assessee to remove the
defects pointed out therein. Therefore, mere reference to the expression “corrected
income” in the notice under sub-section (9) of section 139 of the Act does not
mean that a fresh return of income has been filed under that sub-section. The
action of removal of the defects would relate back to the filing of the
original return of income and, accordingly, it is the date of filing of the
original return which has to be considered for the purpose of computing the
period of limitation under sub-section (2) of section 143 of the Act and not
the date on which the defects actually came to be removed.


iv) The assessee filed its return of income under sub-section (1) of
section 139 on 10th September, 2016. Since the return was defective,
the assessee was called upon to remove such defects, which came to be removed
on 7th July, 2017, that is, within the time allowed by the A.O.
Therefore, upon such defects being removed, the return would relate back to the
date of filing of the original return, that is, 10th September, 2016
and consequently the limitation for issuance of notice under sub-section (2) of
section 143 of the Act would be 30th September, 2017, viz., six
months from the end of the financial year in which the return under sub-section
(1) of section 139 was filed. The notice under sub-section (2) of section 143
of the Act had been issued on 9th August, 2018, which was much
beyond the period of limitation for issuance of such notice as envisaged under
that sub-section. The notice, therefore, was barred by limitation and could not
be sustained.’


Assessment – Notice u/s 143(2) of ITA, 1961 – Limitation – Defective return – Rectification of defects – Relates back to date of original return – Time limit for issue of notice u/s 143(2) – Not from date of rectification of defects but from date of return – Return filed on 17th September, 2016 and return rectified on 12th September, 2017 – Notice u/s 143(2) issued on 10th August, 2018 – Barred by limitation; A.Y. 2016-17

34. Atul Projects India (Pvt.) Ltd. vs. UOI [2020] 422 ITR 478
(Bom.) Date of order: 2nd
January, 2019
A.Y.: 2016-17


Assessment
– Notice u/s 143(2) of ITA, 1961 – Limitation – Defective return –
Rectification of defects – Relates back to date of original return – Time limit
for issue of notice u/s 143(2) – Not from date of rectification of defects but
from date of return – Return filed on 17th September, 2016 and
return rectified on 12th September, 2017 – Notice u/s 143(2) issued
on 10th August, 2018 – Barred by limitation; A.Y. 2016-17


For
the A.Y. 2016-17, the assessee filed its return on 17th October,
2016 and it was found to be defective. The A.O. issued a notice u/s 139(9) of
the Income-tax Act, 1961 and called upon the assessee to remove the defects
which the assessee did within the permitted period on 12th
September, 2017. Yet another notice was issued by the Department on 19th
September, 2017 u/s 139(9) which stated that the return filed on 12th
September, 2017 in response to the directions for removing the defects, was
also considered to be defective. On 29th September, 2017, the
assessee electronically represented to the Department that there was no defect
in the return but this communication was not responded to by the Department. On
10th February, 2018, the A.O. passed an order u/s 143(1).
Thereafter, on 10th August, 2018, the A.O. issued a notice u/s
143(2) for scrutiny assessment u/s 143(3).


The assessee filed a writ petition
and challenged the notice. The Bombay High Court allowed the writ petition and
held as under:


‘i)
The date of filing of the return would be the date on which it was initially
presented and not the date on which the defects were removed. The assessee had
filed its return of income on 17th October, 2016 and it was found to
be defective. The Department had called upon the assessee to remove the
defects, which the assessee did on 12th September, 2017. On a
representation by the assessee, the Department did not raise this issue further
and thus had impliedly accepted the assessee’s representation that there were
no further defects after the assessee had removed the defects on 12th
September, 2017. The notice dated 10th August, 2018 issued u/s
143(2) was barred by limitation.


ii) In the result, the impugned
notice dated 10th August, 2018 is set aside.’

TAXABILITY OF THE LIAISON OFFICE OF A FOREIGN ENTERPRISE IN INDIA

A liaison
office (LO) has been an important mode of entry into India of many foreign entities
wishing to do business and make investments here.

A dispute
has been going on for quite some time about whether an LO has to be considered
as a Permanent Establishment (PE) of the non-resident in India and be subjected
to tax.

In this
article we have discussed various aspects relating to the taxability of an LO
in India, including the recent decision of the Supreme Court in the case of the
U.A.E. Exchange Centre.


1. BACKGROUND

In many
cases, an enterprise usually tests the waters outside its domestic jurisdiction
in an endeavour to expand business. In the initial phase of establishment of
business in the host country, a multinational corporation (MNC) conducts market
research, develops strategies to explore the foreign market, formulates plans, maintains
liaison with the government officials, etc. After such preliminary activities,
it commences operations in the foreign market, controlled or managed either
from the home country or in the foreign host country.


To undertake
such exploratory or precursory activities, MNCs establish an LO in the host
country. The RBI
also permits this, subject to the condition that it is venturing into certain
limited areas of permitted activities only. Undertaking any activity beyond the
rigours of the permitted activities requires an application for conversion of
such LO into a Branch Office or Project Office, or any other body corporate, as
the case may be.


Thus, an MNC
/ foreign company can do business in India either by opening an LO or a branch
office, or a limited liability partnership ?rm, or a subsidiary or wholly-owned
subsidiary, depending upon its business requirements in India. Each of the
above modes of setting up business presence in India is governed by the Foreign
Exchange Management Regulations.


As per
Schedule II read with Regulation 4(b) of the FEM (Establishment in India of a
Branch Office or a Liaison Office or a Project Office or any Other Place of
Business) Regulations, 2016 [FEMA 22(R)], an LO in India of a person resident
outside India is permitted to carry out the following limited activities:

(i)  Representing the parent company / group
companies in India.

(ii)  Promoting export / import from / to India.

(iii)
Promoting technical / financial collaborations between parent / group companies
and companies in India.

(iv) Acting
as a communication channel between the parent company and Indian companies.


Thus, an LO
is not permitted to carry out, directly or indirectly, any trading or
commercial or industrial activity in India. The LO can operate only out of
inward remittance received from the parent company in India. When a foreign
company operates through an LO in India, there is no income that is taxable in
India as it is not permitted to earn any income here. The activities mentioned
above are essentially of a preparatory or auxiliary nature.


2. WHETHER AN LO CONSTITUTES A PE IN INDIA?

As mentioned
above, as per the prevailing FEMA regulations, an LO cannot carry on any
activity in India other than activities permitted as per FEMA 22(R). However,
in practice it is observed in some cases that LOs carry out activities which
may not be limited to acting as a communication channel between the parent
company and Indian companies.


Thus, time
and again doubts arise in respect of the business activities carried out by a
foreign company in India through an LO and whether the said activities can be
taxable in India. The actual activities could vary from case to case. It may be
difficult to presume that an LO will not constitute a PE merely because RBI has
given permission for setting up an LO in India on specific terms and
conditions.


To determine
whether an LO constitutes a PE and consequent taxability of the same in India,
it is very important to examine whether it is carrying out an important part of
the business activities of the foreign company, or only the preparatory and
auxiliary activities as permitted under FEMA 22(R).


3. RELEVANT PROVISIONS OF THE INCOME-TAX ACT, 1961 AND
THE DOUBLE TAXATION AVOIDANCE AGREEMENTS (DTAA
s)

Section 9 of
the ITA, 1961 contains provisions relating to income deemed to accrue or arise
in India and includes all income accruing or arising, whether directly or
indirectly, through or from any business connection in India. Explanation 1(a)
to section 9(1)(i) provides that in case of a business of which all the
operations are not carried out in India, the income of the business deemed u/s
9(1)(i) to accrue or arise in India shall be only such part of the income as is
reasonably attributable to the operations carried out in India.


Further,
Explanation 1(b) to section 9(1)(i) provides that in the case of a
non-resident, no income shall be deemed to accrue or arise in India to him
through or from operations which are confined to the purchase of goods in India
for the purposes of export.


Under
Article 5(1) and (2) of the DTAAs, an LO may be treated as ‘fixed place of
business’ and accordingly a PE in India. However, relief is provided under
Article 5(4) to exclude the activities which are ‘preparatory or auxiliary’ in
nature.


4. PREPARATORY OR AUXILIARY ACTIVITIES TEST – OECD
COMMENTARY

The terms
‘preparatory’ or ‘auxiliary’ have not been defined under the ITA or under the
DTAAs. Various judicial decisions have attempted to define the same. The term
‘preparatory’ has been explained to mean something done before or for the
preparation of the
main task. Similarly, the term ‘auxiliary’ has been interpreted to mean an
activity ‘aiding’ or supporting the main activity.


The OECD
Commentary
on the Model Tax Convention on Income and on Capital dated 21st
November, 2017 in relevant paragraphs 59, 60 and 71 deals with various aspects
of preparatory auxiliary activities. The said paragraphs read as under:


‘59.  It is often difficult to distinguish between
activities which have a preparatory or auxiliary character and those which have
not.
The decisive criterion is whether or not
the activity of the fixed place of business in itself forms an essential and
significant part of the activity of the enterprise as a whole. Each individual
case will have to be examined on its own merits. In any case, a fixed place of
business whose general purpose is one which is identical to the general purpose
of the whole enterprise does not exercise a preparatory or auxiliary activity.


60.  As a general rule, an activity that has a
preparatory character is one that is carried on in contemplation of the
carrying on of what constitutes the essential and significant part of the
activity of the enterprise as a whole.
Since a preparatory activity
precedes another activity, it will often be carried on during a relatively
short period, the duration of that period being determined by the nature of the
core activities of the enterprise. This, however, will not always be the case
as it is possible to carry on an activity at a given place for a substantial
period of time in preparation for activities that take place somewhere else.
Where, for example, a construction enterprise trains its employees at one place
before these employees are sent to work at remote work sites located in other
countries, the training that takes place at the first location constitutes a
preparatory activity for that enterprise. An activity that has an auxiliary
character, on the other hand, generally corresponds to an activity that is
carried on to support, without being part of, the essential and significant
part of the activity of the enterprise as a whole.
It is unlikely that an
activity that requires a significant proportion of the assets or employees of
the enterprise could be considered as having an auxiliary character.


71. Examples
of places of business covered by sub-paragraph e) are fixed places of business
used solely for the purpose of advertising or for the supply of information or
for scientific research or for the servicing of a patent or a know-how
contract, if such activities have a preparatory or auxiliary character.
Paragraph 4 would not apply, however, if a fixed place of business used for the
supply of information would not only give information but would also furnish
plans, etc. specially developed for the purposes of the individual customer.
Nor would it apply if a research establishment were to concern itself with
manufacture. Similarly, where the servicing of patents and know-how is the
purpose of an enterprise, a fixed place of business of such enterprise
exercising such an activity cannot get the benefits of paragraph 4. A fixed
place of business which has the function of managing an enterprise or even only
a part of an enterprise or of a group of the concern cannot be regarded as
doing a preparatory or auxiliary activity, for such a managerial activity
exceeds this level.
If an enterprise with international ramifications
establishes a so-called “management office” in a State in which it maintains
subsidiaries, permanent establishments, agents or licensees, such office having
supervisory and coordinating functions for all departments of the enterprise
located within the region concerned, sub-paragraph e) will not apply to that
“management office” because the function of managing an enterprise, even if it
only covers a certain area of the operations of the concern, constitutes an
essential part of the business operations of the enterprise and therefore can
in no way be regarded as an activity which has a preparatory or auxiliary
character within the meaning of paragraph 4.’


In order to
determine whether an LO of an MNC constitutes its PE in India, an in-depth
analysis is required to be done based on the factual information available, for
example, considering the nature of the activities undertaken by the LO, the
business of the MNC and the overall facts and circumstances of the case. In
this it is very important to consider the various judicial precedents on the
subject.


5. INDIAN JUDICIAL PRECEDENTS

On the issue
of whether an LO constitutes a PE in India, there are mixed judicial
precedents, primarily based on the facts of each case.


In a few
cases, the Tribunals and Courts have held that an LO does not constitute a
fixed place PE in India because the LO was carrying on activities / operations
within the framework of permitted activities by the RBI, i.e. preparatory or
auxiliary activities.
In this regard, useful reference can be made
to the following cases:

• IAC vs.
Mitsui & Co. Ltd. [1991] 39 ITD 59 (Delhi)(SB);

• Motorola
Inc. vs. DCIT [2005] 95 ITD 269 (Delhi)(SB);

• Western
Union Financial Services Inc. vs. ADIT [2007] 104 ITD 40 (Delhi)

• Sumitomo
Corporation vs. DCIT [2008] 114 ITD 61 (Delhi);

• Metal One
Corporation vs. DDIT [2012] 52 SOT 304 (Delhi);

• DIT vs.
Mitsui & Co. Ltd. [2018] 96 taxmann.com 371 (Delhi);

• Nagase
& Co. Ltd. vs. DDIT [2019] 109 taxmann.com 288 (Mumbai-Trib.);

• Kawasaki
Heavy Industries Ltd. vs. ACIT [2016] 67 taxmann.com 47 (Delhi-Trib.).


However, in
a few other cases, Tribunals / Courts have, based on the specific facts of the
cases, held that an LO constitutes a fixed place PE in India because it was
carrying on certain activities which were in the nature of commercial / core
activities of the taxpayer.
A list of such cases is
given below:

• U.A.E.
Exchange Centre [2004] 139 Taxman 82 (AAR);

• Columbia
Sportswear Co. (AAR) [2011] 12 taxmann.com 349 (AAR);

• Jebon
Corporation India vs. CIT(IT) [2012] 19 taxmann.com 119 (Karnataka);

• Brown
& Sharpe Inc. vs. ACIT [2014] 41 taxmann.com 345 (Delhi-Trib.) affirmed in
Brown & Sharpe Inc. vs. CIT [2014] 51 taxmann.com 327 (All.);

• GE Energy
Parts Inc. vs. CIT(IT) [2019] 101 taxmann.com 142 (Delhi);

• Hitachi
High Technologies Singapore Pte Ltd. vs. DCIT [2020] 113 taxmann.com 327
(Delhi-Trib.).


Some other
relevant judicial precedents in this regard are as under:

• Gutal
Trading Est., In re [2005] 278 ITR 643 (AAR);

• Angel
Garment Ltd., In re [2006] 287 ITR 341(AAR);

• Cargo
Community Network PTE Ltd., In re [2007] 289 ITR 355 (AAR);

• Sojitz
Corporation vs. ADIT [2008] 117 TTJ 792 (Kol.);

• Mitsui
& Co. Ltd. vs. ACIT [2008] 114 TTJ 903 (Delhi);

• K.T.
Corpn. [2009] 181 Taxman 94 (AAR);

• IKEA
Trading (Hong Kong) Ltd. [2009] 308 ITR 422 (AAR);

• Mondial
Orient Ltd. vs. ACIT [2010] 42 SOT 359 (Bang.);

• M.
Fabricant & Sons Inc. vs. DDIT [2011] 48 SOT 576 (Mum.);

• Nike Inc.
vs. ACIT [2013] 125 ITD 35 (Bang.);

• Linmark
International (Hong Kong) Ltd. vs. DDIT (IT) [2011] 10 taxmann.com 184 (Delhi);

• CIT vs.
Interra Software India (P.) Ltd. [2011] 11 taxmann.com 82 (Delhi).


6. A BRIEF ANALYSIS OF SOME OF THE DECISIONS based on the nature of the activities of the
LOs is given below to understand the judicial thinking on the subject.

(A) Routine
functions of LO

Earlier, the
ITAT, Mumbai considering the specific facts in the case of Micoperi Spa
Milano vs. DCIT [2002] 82 ITD 369 (Mum.)
had held that maintenance of a
project office in India and incurring expenses for maintaining such office,
cost of postage, telex, etc., indicates that the MNC has a PE in India.


However,
where routine functions are performed by the LO in India and for the purposes
of performing such routine functions the LO has been given limited powers, it
cannot be held that a MNC has a PE in India in the form of its LO.


In Kawasaki
Heavy Industries Ltd. vs. ACIT [2016] 67 taxmann.com 47 (Delhi- rib.)
,
the ITAT held that:

(a) The
powers / rights granted by an MNC to its LO in India such as (i) Signing of
documents for renting of premises, equipment, services with any person,
including Municipal bodies, governments, etc., as may be required for the
operation of the LO; (ii) Execution of contracts for purchase of items for
operation of the LO, etc. are specific to the operations of the LO and the
stand of the A.O., that the power of attorney is an ‘open document’ giving
unfettered powers to the LO, would be outside the scope of the initial approval
granted by the RBI.

(b) Prima
facie
, a reading of the power of attorney does not demonstrate that the
employees of the assessee at the LO are authorised to do core business activity
or to sign and execute contracts, etc.

(c) The A.O.
has not brought on record any material, other than his interpretation of the
terms of the power of attorney, to demonstrate that the LO is carrying on core
business activity warranting his conclusion that the assessee has a PE in
India.


Thus, in
respect of routine functions of the LO, the same may not be considered as
constituting a PE in India.


(B)  Purchase activities for the purposes of
exports

Under
Explanation 1(b) of section 9(1)(i),
purchase
functions or a part thereof, performed by an LO in India has been consistently
held as outside the purview of such LO having any taxable income in India.


In Ikea
Trading (Hong Kong) Ltd. [2009] 308 ITR 422 (AAR),
the AAR has held that
where the LO’s activities are confined only to facilitate the purchase of goods
in India for the purposes of export outside India, such activities are covered
by restriction / relief provided under Explanation 1(b) to section 9(1)(i) of
the Act and, accordingly, no income is deemed to accrue or arise in India with
respect to the operations carried out by the LO in India. A similar view has
been taken in ADIT (IT) vs. Tesco International Sourcing Ltd. [2015] 58
taxmann.com 133 (Bang.-Trib.).


The Karnataka
High Court in Columbia Sportswear Co. vs. DIT (IT) [2015] 62 taxmann.com
240,
reversing the decision of the AAR in Columbia Sportswear Co.
[2011] 12 taxmann.com 349 (AAR),
held that all the activities
undertaken by the LO of an MNC such as designing, manufacturing, identifying
vendors, negotiating with vendors, ensuring quality control of the products
manufactured by vendors, quality assurance, on-time delivery, acting as a
conduit or ‘go between’ between the vendors in India / Egypt / Bangladesh and the
MNC situated outside India, are ‘activities necessary’ for carrying out a
purchase function in India, as otherwise the goods purchased from India would
not find any customer outside India. Accordingly, such activities are not the
‘activities other than sale of goods’ as held by AAR, rather, they are an
extension / necessary part of the purchase function itself, so carried out by
the LO in India. Accordingly, appropriate relief as provided under Explanation
1(b) to section 9(1)(i) of the Act is required to be extended to the taxpayer.


(C) Information collection, research and
aiding activities

Initial
research, information collection and preliminary advertising undertaken by an
LO in India has been held to be in the nature of ‘preparatory’ or ‘auxiliary’
activity, and thus it has been held that the LO does not constitute the PE of
its MNC in India.


The AAR in
the case of K.T. Corporation [2009] 181 Taxman 94 (AAR) held that
the activities in the nature of:

(i)   Holding seminars, conferences;

(ii)
Receiving trade inquiries from the customers;

(iii)
Advertising about the technology being used by the MNC in its products /
services and answering the queries of the customers;

(iv)
Collecting feedback from the customers / prospective customers, trade
organisations and not playing any role in pre-bid survey, etc., before entering
into the agreement with its customers, nor involving itself in the technical
analysis of the products / services, are in aid or support of the ‘core
business activity’ of the MNC and, thus, fall under the exclusionary clauses
(e) and (f) of Article 5(4) of the DTAA between India and Korea. It is
pertinent to note that the AAR also noted that the LO is confined to carrying
out preparatory or auxiliary activities only.


The AAR also
said, ‘However, we may add here that if the activities of the liaison office
are enlarged beyond the parameters fixed by RBI or if the Department lays its
hands on any concrete materials which substantially impact on the veracity of
the applicant’s version of facts, it is open to the Department to take
appropriate steps under law. But, at this stage, we proceed to give ruling on
the basis of facts stated by the applicant which cannot be treated as
ex
facie untrue.’


Similarly,
the Delhi High Court in the case of Nortel Networks India International
Inc. vs. DIT [2016] 69 taxmann.com 47
held that where the Indian
subsidiary of the MNC negotiated and entered into contracts with the customers
of the MNC, the LO of the same MNC could not be held to be a PE of the MNC in
India, especially when the tax authorities had not brought on record any
evidence that the LO had participated in the negotiation of the contracts.


The ITAT,
Mumbai in the case of Nagase & Co. Ltd. vs. DDIT [2018] 96
taxmann.com 504 (Mum.-Trib.)
held that in the absence of any material
or evidence brought on record by the Revenue authorities to the effect that the
LO was executing business or contracts independently with the customers in
India, the plea of the assessee that it was engaged in carrying out only
preparatory or auxiliary activities needs to be accepted and, accordingly, the
taxpayer’s LO in India did not constitute its PE in India.


(D)
Marketing activities

Where the LO
undertakes the preliminary activities of advertising, identification of customers,
attending to queries of customers, such activities would fall within the ambit
of preparatory / auxiliary activities and, accordingly, the LO would not
qualify as a PE of the MNC in India.


However,
where such activities cross the ‘thin-line’ of preparatory / auxiliary
activities and venture into performing income-generating activities, such
activities would require the LO to be treated as the PE of the MNC in India.


The
Karnataka High Court in the case of Jabon Corporation India vs. CIT (IT)
[2012] 19 taxmann.com 119 (Karnataka)
, while upholding the decision of
ITAT, Bangalore in the case of DDIT (IT) vs. Jebon Corpn. India [2010]
125 ITD 340 (Bang.-Trib.)
that the LO has to be treated as the PE of
the Korean parent, held as follows:


‘10. It is on the basis of the aforesaid material, the Tribunal held that
the activities carried on by the liaison office are not confined only to the
liaison work. They are actually carrying on the commercial activities of
procuring purchase orders, identifying the buyers, negotiating with the buyers,
agreeing to the price, thereafter, requesting them to place a purchase order
and then the said purchase order is forwarded to the Head Office and then the
material is dispatched to the customers and they follow up regarding the
payments from the customers and also offer after-sales support. Therefore,
it is clear that merely because the buyers place orders directly with the Head
Office and make payment directly to the Head Office and it is the Head Office
which directly sends goods to the buyers, would not be sufficient to hold that
the work done by the liaison office is only liaison and it does not constitute
a permanent establishment as defined in Article 5 of DTAA.
In fact, the
Assessing Officer has clearly set out that what was discovered during the
investigation and the same has been properly appreciated by the Tribunal and it
came to the conclusion that though the liaison office was set up in Bangalore
with the permission of the RBI and in spite of the conditions being
stipulated in the said permission preventing the liaison office from carrying
on commercial activities, they have been carrying on commercial activities.


11. It was further contended that the RBI has not taken any action and
therefore such interference is not justified. Once the material on record
clearly establishes that the liaison office is undertaking an activity of
trading and therefore entering into business contracts, fixing price for sale
of goods and merely because, the officials of the liaison office are not
signing any written contract would not absolve them from liability. Now that
the investigation has revealed the facts, we are sure that the same will be
forwarded to the RBI for appropriate action in the matter in accordance with
law.
But merely because no action is initiated by RBI till today would not
render the findings recorded by the authorities under the Income-tax Act as
erroneous or illegal.


12. We are satisfied from the material on record that the finding recorded by
the Tribunal is based on legal evidence and that the finding that the liaison
office is a permanent establishment as defined under Article 5 of the DTAA and
therefore, the business profits earned in India through this liaison office is
liable for tax is established.’


The
Allahabad High Court in the case of Brown & Sharpe Inc. vs. CIT
[2014] 51 taxmann.com 327 (All.)
held that the activities such as:

(i)
Explaining the products to the buyers in India;

(ii)
Furnishing information in accordance with the requirements of the buyers;

(iii)
Discussions on the commercial issues pertaining to the contract through the
technical representative, after which an order was placed by the Indian buyer directly to the Korean HO,
would be something more than ‘preparatory’ or ‘auxiliary’ activities and, accordingly, the LO was a PE
of the MNC in India. Further, the incentive plan designed for remuneration of the employees of the LO indicated
that the LO was undertaking not just the ‘advertising’ activities, rather such activities traversed the actual
marketing of products of the MNC in India as it was only on the basis of the
orders generated that an incentive was envisaged / organised for the employees.


In GE
Energy Parts Inc. vs. CIT (IT) [2019] 101 taxmann.com 142 (Delhi)
, the
Delhi High Court held that the LO of GE Energy Parts Inc. (GE US), established
to act as a communication channel, was carrying out core activity of marketing
and selling highly-sophisticated equipments of the US company, and hence the LO
was a fixed place PE of the assessee company in India. The GE LO was a fixed
place PE of GE due to the fact that (a) There was a fixed place of business;
(b) The fixed place of business was at the disposal of the employees of the LO,
more so when GE had not contested that activities of ‘some form’ were not
carried out from such premises and thus it was reasonable to assume that the
activities were carried through such premises; (c) Though the final word with
respect to the pricing of the products was with the HO, however, that won’t mean
that the LO was for mute data collection / information dissemination. The LO
discharged the vital responsibilities or at least had a prominent role in
contract finalisation, viz., extensive negotiations with its customers,
customisation of the products with respect to the requirements of the
customers, negotiating the financial parameters of the products and not
allowing the overseas entity to alter such terms without the consent of GE
India, etc. Accordingly, the LO was not performing merely liaising activities.
Defining the terms preparatory or auxiliary activities as ‘something remote
from the actual realisation of the profits’, the Court held that the
activities performed by the LO would not fall within the exception provided
under Article 5(3)(e) of the India-USA DTAA.


The Court
also held that GE’s overseas entity had agency PE for the following reasons:
(a) Where the expatriates / employees performed activities for different
entities of the same group, then it could not be construed that activities had
been performed for a single enterprise. Accordingly, the GE India (through the
employees of the LO and Indian subsidiary), constituted a dependent agent of GE
overseas MNC; (b) Relying on the decision of the Italian Court it held that the
active and major participation / involvement of the employees / representatives
in the negotiations / meetings with the customers indicated that the agents had
‘authority to conclude contracts’, even if final contracts were concluded by
the GE HO.


7. FUND REMITTANCE SERVICES – Decision of the Supreme Court in the case of
Union of India vs. U.A.E. Exchange Centre

In respect
of fund remittance services, the Supreme Court in Union of India vs.
U.A.E. Exchange Centre [2020] 116 taxmann.com 379 (SC)
held that an
Indian LO of a United Arab Emirates (UAE) company did not constitute a PE in
India.


U.A.E.
Exchange Centre (the assessee), a company incorporated in the UAE, is engaged, inter
alia
, in providing to non-resident Indians in UAE the service of remitting
funds to India. For its India-centric business, the assessee had set up four
LOs in Chennai, New Delhi, Mumbai and Jalandhar after obtaining prior approval
from the RBI u/s 29(1)(a) of the erstwhile Foreign Exchange Regulation Act,
1973.


As per the
business practice followed by the assessee, the funds collected from the NRI
remitters are remitted to India by either of the following two modes:

(i)
Telegraphic transfer: Under this mode the amount is remitted telegraphically by
transferring directly from the UAE through normal banking channels to the
beneficiaries in India and the LOs have no role to play except attending to
complaints regarding fraud, etc.

(ii)
Physical dispatch of instruments: Under this mode, on a request from the NRI
remitter, the assessee sends instruments such as cheques / drafts through its
LOs to beneficiaries in India. For this purpose, the LOs download the
particulars of the remittance (while staying connected to the server in the
UAE), and print and courier the instruments to beneficiaries in India.


In this
case, the contract pursuant to which the funds are remitted to India is entered
into between the assessee and the NRI remitter in the UAE. Moreover, the funds
for remittance as well as the commission are collected in the UAE.


From A.Y.
1998-99 to 2003-04, the assessee was filing Nil returns in India on the basis
that no income had accrued or deemed to have been accrued in India under the
ITA or the India-UAE DTAA. However, owing to some doubt expressed by the
Revenue, the assessee filed an application for advance ruling before the
Authority for Advance Rulings (AAR) in 2003 seeking a ruling on ‘whether any
income is accrued / deemed to be accrued in India from the activities carried
out by the company in India’.


AAR decision

The AAR
ruled that the income of the assessee was deemed to have accrued in India on
the basis that it had a ‘business connection’ in terms of section 9(1) of the
ITA insofar as activities concerning physical dispatch of instruments was
concerned. The AAR observed that without the activities of the Indian LOs, the
transaction of remittance would not be complete. Further, the commission earned
by the assessee covers not only the activities carried out in the UAE, but also
the activities carried out by the LOs in India.


The AAR also
held that the ‘preparatory or auxiliary’ exception to formation of a PE under
the India-UAE DTAA would not be applicable in respect of physical dispatch of
instruments. This was on the basis that a transaction for remittance would not
be completed without the activities of the Indian LOs. Specifically, the AAR
noted that the role of the LOs’ physical dispatch of instruments is ‘nothing
short of performing the contract of remitting the amounts at least in part.’


Delhi High
Court decision

The assessee
challenged the AAR ruling by way of a writ petition in the Delhi High Court.
The High Court noted that the AAR’s discussions and findings on the ‘business
connection’ test under domestic law were unnecessary, considering the scope of
section 90 of the ITA which allows for tax treaties to override domestic law
provisions. Accordingly, the High Court restricted its analysis to the
applicable provisions of the India-UAE DTAA, i.e., Articles 5 and 7.


The Court
held that although an LO comes within the inclusive list of fixed places of
business under Article 5(2)(c), it is subject to exclusions under Article 5(3),
including fixed places of business maintained solely for carrying out
activities which are ‘preparatory or auxiliary’ in nature. While relying on the
common meaning of the terms ‘preparatory or auxiliary’ under Black’s law
dictionary (i.e., activities which aid / support the main activity), the Court
concluded that the activities performed in respect of physical dispatch of
instruments were merely ‘preparatory or auxiliary’ in nature. It observed that
the error committed by the AAR was to read the test of ‘preparatory or
auxiliary’ which permits making a value judgment on whether the transaction
would or would not have been completed without the activities of the LOs and
were, therefore, significant activities. The Court indicated that the test of ‘preparatory
or auxiliary’ is not a function only of whether the activities under
consideration led to completion of the transaction.


In arriving
at its conclusion, the High Court applied the judgment of the SC in DIT
(IT) vs. Morgan Stanley & Co. [2007] 162 Taxman 165 (SC)
and
accorded a liberal and wide interpretation to the exclusionary clause of PE.
The reason for this was that by invoking clauses of PE, income which otherwise
neither accrues / arises in India becomes taxable in India by virtue of a ‘deeming
fiction.’


Supreme
Court judgment

An SLP was
filed by the Revenue against the High Court decision. The core issue before the
Apex Court was whether the activities carried out by the LOs in India would
qualify the expression ‘of preparatory or auxiliary character’ as mentioned in
Article 5(3)(e) of the India-UAE DTAA.


In
confirming the finding of the High Court that the activities conducted by the
LOs were ‘preparatory or auxiliary’ and hence excludable from the purview of
PE, the Supreme Court also referred to the limited permission granted by the
RBI under FERA to the assessee regarding the activities to be conducted by the
LOs.


The Supreme
Court noted that as per the nature of activities allowed for under the RBI
permission, the LOs were only allowed to provide incidental service of delivery
of cheques / drafts drawn on a bank in India. They were not allowed to perform
business activities such as (i) entering into a contract with any party in
India; (ii) rendering consultancy or any other service directly or indirectly
with or without consideration to anyone in India; (iii) borrowing or lending
any money from or to any person in India without RBI’s permission. Thus, it was
amply clear that the LOs in India were not to undertake any other activity of
trading (commercial or industrial) or enter into any business contracts in its
own name in India. On this basis, the Supreme Court concluded that the nature
of activities conducted by the LOs as circumscribed by the RBI constituted
‘preparatory or auxiliary’ in character, and hence outside the purview of PE.


The Court
noted further that through the LOs the assessee was not carrying on any
business activity in India, but only dispensing with the remittances by
downloading the information from the UAE server and printing the cheques /
drafts. The LOs could not even charge commission / fee for their services.
Therefore, no income actually accrued to the LOs u/s 2(24) of the ITA.


The Supreme
Court further held that the activities of the LO of the taxpayer in India are
limited activities which are circumscribed by the permission given by the RBI
and are of preparatory or auxiliary character and, therefore, covered by
Article 5(3)(e). As a result, the ?xed place used by the respondent as LO in
India would not qualify the de?nition of PE in terms of Articles 5(1) and 5(2)
of the DTAA on account of non-obstante and deeming clause in Article
5(3) of the DTAA. Hence, no tax can be levied or collected from the LO of the
taxpayer in India in respect of the primary business activities concluded by
the taxpayer in the UAE.


The Supreme
Court also observed that after the enactment of the Finance Act, 2003,
Explanation 2 to section 9(1)(i) of the Act was inserted which de?ned business
connection as business activity carried out by a person on behalf of a
non-resident. In this regard, the Court held that even if the stated activities
of the LO of the taxpayer in India are regarded as business activity, the same
being ‘of preparatory or auxiliary character’, by virtue of Article 5(3)(e) of
the DTAA, the LO of the taxpayer in India which would otherwise be a PE, is
deemed to be expressly excluded from being so. Since, by a legal ?ction, it is
deemed not to be a PE of the taxpayer in India, it is not amenable to tax
liability in terms of Article 7 of the DTAA.


At present,
there are few precedents which provide guidelines for the ‘preparatory or
auxiliary’ test such as (i) to check whether the activities performed in the
fixed place of business form an essential and significant part of the
enterprise as a whole as held in Western Union Financial Services Inc.
vs. ADIT [2007] 104 ITD 40 (Delhi);
(ii) whether the activities
performed in the fixed place of business form part of the core business
activities of the enterprise, as held in Angel Garments Ltd. [2006] 287
ITR 341 (AAR).


After
analysing the facts, the Supreme Court held the activities of the LOs to be of
‘preparatory or auxiliary’ nature without setting out guidelines for the
application of the ‘preparatory or auxiliary’ test. It would have been
extremely helpful if the Supreme Court would have laid down detailed guidelines
for the application of the ‘preparatory or auxiliary’ test.


The above
ruling is quite relevant for money remittance companies and potentially other businesses
which are primarily operated from outside India with some preparatory or
auxiliary activities in India.


It is to be
noted though that India has introduced an equalisation levy of 2% on certain
non-resident service providers providing services to customers in India, and
its application with respect to the specific facts may need evaluation.


Further, the
above decision is a welcome decision, wherein along with providing comments on
the meaning of ‘preparatory or auxiliary character’, the Court has re-affirmed
the guiding principle of ‘treaty override’ which forms the pillar of the
international tax law in India.


The Supreme
Court has laid emphasis on bringing out the characteristics of what can be
termed as ‘of preparatory or auxiliary character’ which shall be relevant for
future cases. Further, the Court has de?ned the rationale of taxability due to
which the judgment shall hold persuasive value for similar cases.


The decision
seems to lay down a broad guideline that where the activities of an LO are
restricted to the approvals granted by the RBI, such activities should qualify
as preparatory or auxiliary in nature and should not constitute a PE in India.


8. PRECAUTIONS REGARDING LOs FOR NOT BEING
CONSIDERED AS PE
s

The
important point here would be to restrict the activities of the LO to
preparatory or auxiliary work only. Further, the LO should not venture into or
towards activities which could be viewed as commercial or core activities
undertaken on behalf of the foreign entity or its group entity. If it does so,
not only could the LO trigger a PE risk in India, but it could also be seen as
going beyond the domain of the activity permissions granted by the RBI.
Further, appropriate documentation should be maintained to prove that the
activities of the LO are preparatory or auxiliary in nature such as, for
instance, the RBI approval letter in the case of the U.A.E. Exchange Centre,
which reflected that the activities of the LO were mere support services to the
foreign parent entity.


In our view,
one should not presume that an LO or place of business will not constitute a PE
merely because the RBI or a government body has given permission for its
establishment in India. To determine the Indian tax implications, it is
critical to examine whether the LO is carrying out an important part of the
business activity of the foreign company (i.e., a commercial activity which is
core income-generating), or whether it is merely aiding or supporting
activities of the main business.


9. BEPS ACTION 7 AND MULTI-LATERAL INSTRUMENT (MLI)

While
analysing the ‘preparatory or auxiliary’ activities, one may additionally need
to be mindful of the BEPS Action Plan 7 and Article 13 of the MLI which deal
with the issue of artificial fragmentation of activities between various group
companies to avail the benefit of ‘preparatory or auxiliary’ activities.


Specific
activity exemption

In relation
to tax treaties to which the provisions of MLI regarding specific
activity-based exemption apply, it will become important to demonstrate that
the stated activity in the exclusion clause (advertising, storage, delivery,
etc.) is indeed ‘preparatory or auxiliary’ in nature. As the world moves
towards complex and innovative business models which rely on limited physical
presence in the country where the customers reside, foreign players must
assess, based on the facts, whether their Indian presence can still be said to
be merely aiding the core business in order to avail exemption under the
respective tax treaty.


Anti-fragmentation
rules

Article 13
is incorporated in the MLI with a view to address the issue of artificial
avoidance of the PE status through fragmentation of activities between
closely-related enterprises. Thus, businesses carrying out more than one
activity in a country which earlier individually were getting covered under the
term ‘preparatory or auxiliary character’ and hence were not forming a PE in
India, could be subject to the provision of Article 13 of the MLI. Accordingly,
such activities may thus form a PE in India if the activities performed when
seen cumulatively exceed what can be considered as of ‘preparatory or auxiliary
character’.


However, one
would have to first check whether Article 13 of the MLI applies to the relevant
DTAA in question.


With MLI
coming into force and India being a signatory thereto, going forward the
business models would need to be independently examined under the provisions of
the MLI for ascertaining whether or not a PE is established. Now, with
implementation of BEPS and signing of MLIs, litigation on this issue may
further intensify as the Indian tax authorities would now have additional
ammunition to target the LOs.


India has
opted for Option A and anti-fragmentation rules. Accordingly, in India no
specific exemption would be available unless the activities are preparatory or
auxiliary in nature and also there should not be artificial fragmentation of
activities within the group.


10. CONCLUSION

Whether or
not the activities of LOs constitute a PE of the non-resident entity is a very fact-speci?c
and vexed issue. In the past, where an LO has exceeded its scope of permitted
activities, courts have held that such an LO can constitute the PE of the
foreign entity in India. Therefore, it is important to ensure at all times that
an LO in India operates within the limits set out by RBI.


The
determination of the question as to whether any activities of an LO qualify as
preparatory or auxiliary in nature would depend upon the facts of each case and
the nature of business of the taxpayer. In order to decide the status of the
LO, a functional and factual analysis of the activities performed by it needs
to be undertaken.


It is very important to
keep in mind that all the aforementioned judicial precedents should be
critically analysed in the light of BEPS Action Plan 7, MLI and changes in the
OECD Commentary, before applying the same on the factual matrix of a particular
case.


Whether in sorrow or in happiness,
a friend is always a friend’s support.

(Valmiki Raamaayan 4.8.40)
REVERSE FACTORING OR SUPPLIER FINANCING

BACKGROUND

Banks may
offer services to buyers of goods or services in order to facilitate payment of
their trade payables arising from purchases from suppliers. In a reverse
factoring arrangement, a bank agrees to pay amounts an entity owes to its
suppliers and the entity agrees to pay the bank at a date later than when the
suppliers are paid. Reverse factoring arrangements can vary significantly in
both form and substance. When the original liability to a supplier has been
extinguished or there is a change in terms, the following issues arise:

(a)  Whether the resulting new liability to the
bank should be presented as bank borrowing or ‘trade payables.’ A point to note
is that bank borrowing is required to be separately presented from trade
payables under Ind AS Schedule III requirements. Needless to say that
presentation as bank borrowing may have a significant impact on the gearing
ratios and debt covenants.

(b)
Additionally, the entity is also required to consider various disclosure
requirements. Consequently, this issue is very important.


Whether the
resulting new liability to the bank should be presented as bank borrowing or
‘trade payables’?


REQUIREMENTS OF Ind AS
STANDARDS

Before we
embark on answering these questions, let us consider the various requirements
under Ind AS standards:

1. Paragraph
54 of Ind AS 1 –
Presentation of Financial Statements: ‘The
balance sheet shall include line items that present the following amounts:
(a)………….. (k) trade and other payables; (l) provisions; (m) financial
liabilities excluding amounts shown under (k) and (l)……….’


2. Paragraph
57 of Ind AS 1: ‘This Standard does not prescribe the order or format in which
an entity presents items. Paragraph 54 simply lists items that are sufficiently
different in nature or function to warrant separate presentation in the balance
sheet. In addition:

(a) line
items are included when the size, nature or function of an item or aggregation
of similar items is such that separate presentation is relevant to an
understanding of the entity’s financial position; and (b)…’


3. Paragraph
70 of Ind AS 1 explains that ‘some current liabilities, such as trade payables…
are part of the working capital used in the entity’s normal operating cycle’.


4. Paragraph
29 of Ind AS 1 states that ‘…An entity shall present separately items of a
dissimilar nature or function unless they are immaterial …’


5. Paragraph
11(a) of Ind AS 37 –
Provisions, Contingent Liabilities and
Contingent Assets states that ‘trade payables are liabilities to pay for
goods or services that have been received or supplied and have been invoiced or
formally agreed with the supplier’.


6. Paragraph
3.3.1 of Ind AS 109 –
Financial Instruments states: ‘An entity
shall remove a financial liability (or part of a financial liability) from its
balance sheet when, and only when, it is extinguished – i.e., when the
obligation specified in the contract is discharged or cancelled or expires.’


ANALYSIS

Based on the
various requirements of Ind AS standards presented above, an entity presents a
financial liability as a trade payable only when it:

(i)
represents a liability to pay for goods or services;

(ii) is
invoiced or formally agreed with the supplier; and

(iii) is
part of the working capital used in the entity’s normal operating cycle.


Other
payables are included within trade payables only when those other payables have
a similar nature and function to trade payables; for example, when other
payables are part of the working capital used in the entity’s normal operating
cycle.


A point to
note is that bank borrowing is required to be separately presented from trade
payables under Ind AS Schedule III requirements. In assessing whether to
present reverse factoring arrangements as trade payables (whether included with
other payables or not) or bank borrowing, requires further analysis. An entity
will have to assess whether to derecognise a trade payable to a supplier and
recognise a new financial liability to a bank as bank borrowings. Such an
assessment is made in accordance with Ind AS 109 – Financial Instruments.


Under Ind AS
109 if the arrangement results in derecognition of the original liability (e.g.
if the purchaser is legally released from its original obligation to the
supplier), an entity in such a case will have to pay the bank rather than the
supplier. Consequently, in such a case, presentation as a bank borrowing may be
more appropriate. Derecognition can also occur and presentation as bank
borrowing will also be appropriate if the purchaser is not legally released
from the original obligation but the terms of the obligation are amended in a
way that is considered a substantial modification. For example, the payment of
trade payable may not entail transfer of any collateral. However, if collateral
is provided in a supplier financing arrangement, this would mean that the
original agreement to pay to the creditor has been substantially modified. In
such cases, too, presentation of the reverse factoring as a bank borrowing
rather than trade payable may be more appropriate. Even if the original
liability is not derecognised, other factors may indicate that the substance
and nature of the arrangements indicate that the liability should no longer be
presented as a trade payable and a bank borrowing presentation may be more
appropriate.


Analysis of
supply-chain finance is a complex and judgemental exercise. Obtaining an
understanding of the following factors would help in making the decision on the
presentation:

• What are
the roles, responsibilities and relationships of each party (i.e. the entity,
the bank and the supplier) involved in the reverse factoring?

• What are
the discounts or other incentives received by the entity that would not have
otherwise been received without the bank’s involvement?

• Whether
there is any extension of the date by the bank by which payment is due from the
entity beyond the invoice’s original due date?

• Is the
supplier’s participation in the reverse factoring arrangement optional?

• Do the
terms of the reverse factoring arrangement preclude the company from
negotiating returns of damaged goods to the supplier?

• Is the
buyer released from its original obligation to the supplier?

• Is the
buyer obligated to maintain cash balances or are there credit facilities with
the bank outside of the reverse factoring arrangement that the bank can draw
upon in the event of non-collection of the invoice from the buyer?

• Does the
buyer have a separate credit line for these arrangements?

• Whether
additional security is provided as part of the arrangement that would not be
provided without the arrangement?

• Whether
the terms of liabilities that are part of the arrangement are substantially
different from the terms of the entity’s trade payables that are not part of
the arrangement?


Some reverse
factoring arrangements require that a buyer will pay the invoice regardless of
any disputes that might arise over the goods (for example, the goods are found
to be damaged or defective). In the event of a dispute, a buyer who agrees to
such a condition would use other means, such as adjustments on future purchases
from the supplier, to recover the losses. These provisions provide greater
certainty of payment to the bank and may reflect that the arrangement in
substance is a financing to the buyer. However, for a buyer who buys regularly
from a supplier to routinely apply credits for returns against payments on
future invoices, this condition might not be viewed as a significant change to
existing practice. Additionally, this provision may not constitute a
significant change to the terms of the original trade payable if failure by the
buyer to pay on the invoice due date does not entitle the bank to any recourse
or remuneration beyond what is stipulated in the terms of the invoice.


In some
reverse factoring arrangements, the buyer may be required to maintain
collateral or other credit facilities with the bank. These requirements may
indicate a financing arrangement in substance, particularly if a buyer’s
failure to maintain an appropriate cash balance would trigger
cross-collateralisation events on the buyer’s other debt instruments held by
the bank. For the liability to be considered a trade payable, the bank
generally can collect the amount owed by the buyer only through its rights as
owner of the receivable it purchased from the supplier. Some examples are
provided below which help in understanding the above requirements.


Example 1 –
Financing of advances to suppliers made by the buyer

A buyer
makes an advance payment to a supplier for goods to be delivered to the buyer
six months later. For this purpose, the buyer obtains a credit from the bank
based on its own credit rating and credit facility. The supplier is not
involved in the buyer obtaining the credit facility from the bankers. Here, as
far as the buyer is concerned, the buyer obtains credit from a bank and makes
an advance payment to the supplier. The buyer may directly make the advance to
the supplier, or the bank may do so on behalf of the buyer. In this example, it
is not appropriate for the buyer to present the borrowing from the bank and the
advance to the supplier on a net basis. It is also not appropriate for the
buyer to present the borrowing from the bank as trade payable, because no goods
have been received at the date of borrowing.


Example 2:
Bank negotiates with supplier directly on buyer’s behalf

A supplier
approaches a bank for discounting an invoice representing supply of goods to a
buyer. The bank agrees to pay the supplier before the legal due date to obtain
an early payment discount. However, the buyer is not legally relieved from the
obligation under its trade payable. The way the mechanism works is that the
supplier agrees to receive the amount from the buyer net of the early payment
discount at the contractual due date and to pay the bank this same amount only
if it receives the payment from the buyer.
If the supplier fails to pay the
bank, the buyer agrees to pay the bank. The bank charges a fee to the buyer,
which is lower than the early payment discount. This effectively results in the
bank and the supplier sharing the benefit of the early payment discount. In
this example, since the buyer is not legally relieved of his obligation to pay
the supplier (or to the bank on behalf of the supplier), the buyer continues to
recognise the trade payable to the supplier. Furthermore, the buyer does not
provide any collateral to the bank, nor is the arrangement substantially
different from the terms of the entity’s trade payable. The buyer will
recognise the liability as trade payable. Additionally, the buyer also
recognises a guarantee obligation, initially measured at fair value, for its
promise to pay the bank if the bank does not receive a payment from the
supplier.


Example 3:
Receivables purchase agreement

In a reverse
factoring arrangement, a bank acquires the rights under the trade receivable
from the supplier. However, the buyer is not legally released from the payable.
The buyer may be involved to some extent in such an arrangement. For example,
the buyer agrees that he is no longer eligible to offset the payable against
credit notes received from the supplier, or the buyer may be restricted from
making direct payments to the supplier. In this fact pattern, the buyer would
need to consider whether the change to the terms of the trade payable is
significant or not.


If there is
a substantial change, the transfer is accounted for as an extinguishment –
which means, the previous liability should be derecognised and replaced with a
new liability to the bank. The impact of any additional restrictions imposed by
the reverse factoring agreement on the buyer’s rights will need to be properly
evaluated. One possibility is that because the buyer selects each payable at
its sole discretion, it will only select those payables where the effect of any
such restriction is not significant. On the other hand, it may be the case that
the buyer, bank and supplier have agreed initially on a minimum amount of
payables / receivables being refinanced by the bank. In such a case, the buyer
has no further discretion to avoid the change in his rights, even when the
change is significant.


Example 4:
Trade structure / supply chain finance / reverse factoring

• Steel
Limited (SL) purchases raw material and other supplies from various suppliers.

• SL has
negotiated 180 days’ extended credit term with all suppliers, which fact will
be stated in the invoice.

• To address
the working capital issues of suppliers, SL’s bankers have agreed to buy bills
endorsed by SL.

• The
suppliers decide whether they need to transfer bills to SL’s bankers as well as
timing and other terms of transfer. The suppliers can also get their bill
discounted from other bankers. However, it may not be cost effective.

• If a
supplier decides to get bill discounted from SL’s banker, the banker will
consider SL’s credit risk to decide the amount payable on transfer.

• Transfer
does not release SL from its liability toward the supplier. Rather, SL
continues to be liable to pay the amount to the supplier.

• If SL
defaults in payment of dues, the banker can use the court process against SL
for payment but only through the involvement of the supplier.

• SL does
not receive any additional benefit except extended credit period as originally
agreed with the supplier.

• SL does
not have a separate credit line with the bank for these arrangements, nor
provides any collateral.


Response

From the
facts it is clear that:

• SL is not released from its obligation towards the supplier.

• Nor is
there a change in the terms of payable.

• Nor has SL
received any discounts or rebates that would not have otherwise been received.

• There is no
extension of the payment date beyond the invoice’s original due date.

• The
supplier’s participation in the reverse factoring arrangement is completely
optional.

• SL does
not have a separate credit line with the bank for these arrangements, nor does
it provide any collateral.

• These
factors indicate that SL should continue to classify its liability as trade
payable.


Example 5:
Trade structure / supply chain finance / reverse factoring

• SL
purchases raw material and other supplies from various suppliers.

• SL has
negotiated 180 days’ extended credit term with all suppliers.

• Within one
month of purchase, SL can select suppliers who need to get their bill
discounted from SL’s bank. The selected suppliers will transfer their bills to
the bank for immediate cash.

• Assume
that the bill amount is Rs. 100; the bank will deduct Rs. 10 as discounting
charge and pay the remaining amount (Rs. 90) to the supplier.

• Through an
agreement signed between SL and the bank, SL:

• Commits itself to pay to the bank the specified
invoice on its due date.

• Pays a service fee for ‘services’ to the
bank.

• Pays finance cost to the bank (as per a
credit line with the bank).

• In
summary, SL will pay to the bank:

• Nominal amount of the invoice (Rs. 100).

• Less discount for immediate payment
included in the paym
ent conditions between the buyer and SL (Rs.
10).

Plus, the service and finance
commission payable to the Bank (Rs. 5).


Response

• The
supplier appears to have relinquished its obligation to pay to the bank. It
appears that SL has now the obligation for payment to the bank.

• The
substance of the transaction is that SL is paying in advance to the supplier
for getting the benefit of cash discount.

• For this
purpose, it is drawing a credit line from the bank and paying the related
interest expense.

• The
supplier’s participation in the arrangement is decided by SL.

• These
facts indicate that the supplier payable should be reclassified from trade
payable to a bank borrowing.


What are the
various disclosure requirements applicable in a reverse factoring arrangement?


REQUIREMENTS OF Ind AS
STANDARDS

1. Paragraph
6 of Ind AS 7 – Statement of Cash Flows defines: (a) operating activities as
the principal revenue-producing activities of the entity and other activities
that are not investing or financing activities; and (b) financing activities as
activities that result in changes in the size and composition of the
contributed equity and borrowings of the entity.


2. Paragraph 43 of Ind AS 7 states: ‘Investing and financing transactions
that do not require the use of cash or cash equivalents shall be excluded from
a statement of cash flows. Such transactions shall be disclosed elsewhere in
the financial statements in a way that provides all the relevant information
about those investing and financing activities.’


3. Paragraph
44 of Ind AS 7 states: ‘Many investing and financing activities do not have a
direct impact on current cash flows although they do affect the capital and
asset structure of an entity. The exclusion of non-cash transactions from the
statement of cash flows is consistent with the objective of a statement of cash
flows as these items do not involve cash flows in the current period.’


4. Paragraph
44A of Ind AS 7 states: ‘An entity shall provide disclosures that enable users
of financial statements to evaluate changes in liabilities arising from
financing activities, including both changes arising from cash flows and
non-cash changes.’


5. Paragraph 122 of Ind AS 1 – Presentation of Financial Statements states: ‘An entity shall disclose,
along with its significant accounting policies or other notes, the judgements,
apart from those involving estimations, that management has made in the process
of applying the entity’s accounting policies and that have the most significant
effect on the amounts recognised in the financial statements.’


6. Paragraph
112 of Ind AS 1 states: ‘The notes shall: …. (c) provide information that is
not presented elsewhere in the financial statements, but is relevant to an
understanding of any of them.’


ANALYSIS

The analysis
below is consistent with the IFRIC tentative agenda decision in June, 2020, ‘Supply
Chain Financing Arrangements – Reverse Factoring – Agenda Paper 2.’


Cash flow
statement

An entity
that has entered into a reverse factoring arrangement determines whether to
classify cash flows under the arrangement as cash flows from operating
activities or cash flows from financing activities. If the entity considers the
related liability to be a trade or other payable that is part of the working
capital used in the entity’s principal revenue-producing activities, then the
entity presents cash outflows to settle the liability as arising from operating
activities in its statement of cash flows. In contrast, if the entity considers
the related liability as borrowings of the entity, then the entity presents
cash outflows to settle the liability as arising from financing activities in
its statement of cash flows.


Investing
and financing transactions that do not require the use of cash or cash
equivalents are excluded from an entity’s statement of cash flows (paragraph 43
of Ind AS 7). Consequently, if cash inflow and cash outflow occur for an entity
when an invoice is factored as part of a reverse factoring arrangement, then
the entity presents those cash flows in its statement of cash flows. If no cash
flows are involved in a financing transaction of an entity, then the entity
discloses the transaction elsewhere in the financial statements in a way that
provides all the relevant information about the financing activity (paragraph
43 of Ind AS 7).


NOTES TO FINANCIAL
STATEMENTS

Paragraph 44A of Ind AS 7 requires an entity to provide ‘disclosures that
enable users of financial statements to evaluate changes in liabilities arising
from financing activities, including both changes arising from cash flows and
non-cash changes’. Such a disclosure is required for liabilities that are part
of a reverse factoring arrangement if the cash flows for those liabilities
were, or future cash flows will be, classified as cash flows from financing
activities.


Ind AS 107 –
Financial Instruments: Disclosures defines liquidity risk as ‘the risk
that an entity will encounter difficulty in meeting obligations associated with
financial liabilities that are settled by delivering cash or another financial
asset’. Reverse factoring arrangements often give rise to liquidity risk
because:

(a) the
entity has concentrated a portion of its liabilities with one financial
institution rather than a diverse
group of suppliers. The entity may also obtain other sources of funding from
the financial institution providing the reverse factoring arrangement. If the
entity were to encounter any difficulty in meeting its obligations, such a
concentration would increase the risk that the entity may have to pay a
significant amount, at one time, to one counter party.

(b) some
suppliers may have become accustomed to, or reliant on, earlier payment of
their trade receivables under the reverse factoring arrangement. If the
financial institution were to withdraw the reverse factoring arrangement, those
suppliers could demand shorter credit terms. Shorter credit terms could affect
the entity’s ability to settle liabilities, particularly if the entity were
already in financial distress.


Paragraphs 33-35 of Ind AS 107 require an entity to disclose how exposures
to risk arising from
financial instruments including liquidity risk arise, the entity’s objectives,
policies and processes for managing the risk, summary quantitative data about
the entity’s exposure to liquidity risk at the end of the reporting period
(including further information if this data is unrepresentative of the entity’s
exposure to liquidity risk during the period), and concentrations of risk.
Paragraphs 39 and B11F of Ind AS 107 specify further requirements and factors
an entity might consider in providing liquidity risk disclosures.


An entity
applies judgement in determining whether to provide additional disclosures in
the notes about the effect of reverse factoring arrangements on its financial
position, financial performance and cash flows. An entity needs to consider the
following:

(i)
assessing how to present liabilities and cash flows related to reverse
factoring arrangements may involve judgement. An entity discloses judgements
that management has made in this respect if they are among the judgements made
that have the most significant effect on the amounts recognised in the
financial statements (paragraph 122 of Ind AS 1).

(ii) reverse
factoring arrangements may have a material effect on an entity’s financial
statements. An entity provides information about reverse factoring arrangements
in its financial statements to the extent that such information is relevant to
an understanding of any of those financial statements (paragraph 112 of Ind AS
1).

DATA-DRIVEN INTERNAL AUDIT – I

BACKGROUND

The basics of Internal Audit remain the same
– add value and manage risk; but it cannot operate in isolation, and just as
technology continues to revolutionise the way we do business in the 21st
century, Internal Audit is not immune from disruption.


The business environment is changing rapidly
in the face of the data revolution. IDC predicts that worldwide data will
increase by 61% and reach 175 zetta bytes by 2025. What is new is the ubiquity
and volume of data. From big data to data science to predictive analytics, data
is everywhere.


Management today makes use of tools and
technologies like ERP, analytics, visualisation, artificial intelligence, etc.,
and converts available data into information for better, more informed
decisions impacting the business. Should the Internal Auditor be left behind?


Internal Audit is one of the professions
where developments affecting data (data availability, data sources, data
analysis, etc.) are particularly important and impactful.


The opening lines of the popular science
fiction serial of the 1970s, ‘Star Trek – Space, The Final Frontier’,
are: These are the voyages of the Star Ship Enterprise. Its five-year mission
– to explore strange new worlds, to seek out new life and new civilizations, to
boldly go where no man has gone before.
Those words are etched in our
minds.


To draw a parallel to that, the future of
Internal Audit is to explore and apply new tools and technologies. Not just for
the sake of ‘me too’ but to be relevant and –

  •  do more (continuously add value) with less
    resources;
  •  be in tune with audit tools and
    technology, similar to those being adopted by businesses (increasingly,
    management is now working with 4th and 5th generation
    tools and technologies and auditors cannot use 1st or 2nd
    generation tools and technologies any more);
  •  continuously upgrade skills in the face of
    this data revolution.


TOWARDS A DATA-DRIVEN FUTURE – SURVEY

CaseWare IDEA Inc., Canada conducted a
survey in late 2019 wherein about 400 Internal Audit professionals from junior
auditors to the C-Suite level were surveyed and responses were gathered from
around the world on their approach to audit through the lens of technology.


To offer an unbiased assessment of the state
of Internal Audit in 2020, this survey was tool agnostic.


Who was surveyed?


Geographic distribution of the survey


Geographic Distribution

The survey was promoted globally across multiple channels. Although a plurality (42%) of respondents operate out of North America, the survey results reflects the views of audit professionals from all major global geographic regions, including Asia Pacific (20%), Latin America (17%), Europe (11%), Africa (8%), and the Middle East (2%).


 Topics covered in
the survey

Feedback was
sought from the respondents on the following areas:

  • Current and
    planned elements of Internal Audit approaches;
  • Most
    significant Internal Audit challenges;
  • Compliance
    demands;
  •  Data
    analytics in Internal Audit;
  •  Artificial
    Intelligence and Machine Learning in Internal Audit activities;
  •  Cloud
    Technology in Internal Audit;
  •  Training and
    adoption of audit technology;
  •  Priorities
    for 2020, and much more.


Findings
of the survey

The survey
findings suggested that individuals and leadership within the Internal Audit
profession are aware of the unique opportunities that are being offered by new
technologies and data analytics, but they are struggling to:


  •  Embrace and
    adopt these new technologies
  •  Train
    internal audit staff on technology tools
  •  Move from
    traditional, manual processes to data-driven auditing processes.


Compliance
demands – a perennial challenge for Internal Audit – continue to rank as one of
the top priorities for auditors and data ethics is taken seriously by most
respondents.


The year ahead
for Internal Audit will be marked by:

  •  The adoption
    of data analysis technology,
  •  The
    optimisation of existing audit technology,
  •  Training
    auditors on audit technology.


Many of these
challenges and priorities are interconnected and together they represent a
global movement towards data-driven audit.


Top
challenges – an overview

In the survey,
audit professionals were asked to address their biggest audit challenges
currently, and the answers reflect the views of respondents as they stood at
the close of 2019. When asked to name their top Internal Audit challenges,
three clear priorities emerged as the top challenges faced by auditors,
regardless of role or geographic location.


Leading the
charge was the need to move from traditional, manual processes to data-driven
audit, a priority which 62% of respondents named as a top audit challenge.
Close behind were the need to adopt new technology (57%) and addressing the
skills shortage (47%).


Need for
adoption of data-driven audit

Data-driven
audit uses technology, big data, data analytics, and even predictive analytics,
to make auditing a data-centric, risk-sensitive, technology-enabled, continuous
activity.


Data-driven
auditing is an approach marked by:

  •  The use of
    data analytics technology;
  •  A decreased
    reliance on manual tools and processes (e.g., traditional spreadsheets and
    sampling);
  •  Results-based
    decision-making that enables both the auditor and the client to find more value
    in an audit;
  •  Using these
    approaches to enable management to minimise risk.


Data-driven
audit shirks conventional, manual approaches to auditing to realise a future of
data-based decision-making.


BENEFITS OF DATA ANALYTICS – KEY POINTS

Clients,
customers and investors alike have little tolerance when controls fail to
reveal erroneous data used in operational decisions and financial reporting.
Undetected errors in systems and data can also yield opportunities for fraud
and abuse. The best tool that can be used to determine the reliability and
integrity of information systems is data analysis software.


Audit results
gleaned from competent data analysis activities by Internal Audit can shine a
light on the issues lying within the organisation’s data. When properly used by
trained audit staff, data analysis software can be incorporated into audit
plans to provide both assurance and consulting service opportunities to the
organisation’s information systems and thus become the true cornerstone of an
effective audit function.


Some of the key
benefits of the use of data analytics are:

  •  In-depth
    review of process-generated data rather than traditional sample checks which
    are ineffective and inefficient;
  •  Ability to
    reveal surprises and insights which the client management never knew about – true
    value add
    ;
  •  Possibility
    to go beyond controls and focus on cost saving and revenue maximisation;
  •  Concurrent
    use of data analytics in audit significantly reduces compliance costs;
  •  Framework to
    automate complex Management Control ‘MIS’ reports through Automatic Routines –
    ‘Macros’.


DATA ANALYTICS MATURITY DECISION
FOR INTERNAL AUDIT

Different
types of data analytics

Organisations
need to consider different types of data analytics:

  •  Descriptive
    analytics
    interprets historical data;
  •  Predictive
    analytics
    predicts future outcomes based on historical data;
  •  Diagnostic
    analytic
    s examines the data and asks ‘why?’
  •  Prescriptive
    analytics
    identifies the best course of action based on the analysis of
    data.


The data
analytics maturity scale

Whatever the
benefits of automating data analytics, the organisation needs to determine at
the strategic level how data analytics might best contribute to its audit
goals.

This strategic
activity can benefit from considering data analytics in terms of ‘maturity’
stages below:

Traditional
Auditing:
Data
analytics may be used but is mainly descriptive and applied during the planning
phase.

  •  Ad Hoc
    Integrated Analytics: This may include both descriptive and diagnostic
    analytics at the planning and execution phases (e.g., identifying outliers),
    but is carried out in an ad hoc rather than systematic manner.
  •  Continuous
    Risk Assessment and Auditing:
    This may include all types or categories of
    data analytics in a pre-defined automated set. This set provides ongoing data
    to auditors.
  •  Integrated
    Continuous Auditing and Continuous Monitoring:
    A full set of automated
    analytics is deployed and permits continuous monitoring by management, as well
    as a continuous data flow to the audit shop. The systems are largely seamless
    and integrated.
  •  Continuous
    Assurance of Enterprise Risk Management:
    A full set of automated analytics
    is deployed, as with level 4. In addition, there is a further emphasis on
    aligning continuous data analysis with strategic enterprise goals. The internal
    audit plan is ‘dynamic’ in response to risk fluctuation.


CONCLUSION

The road for
internal auditing in 2020 and beyond would be:

  •  Upgrade
    skill-sets and become aware; explore and apply available and emerging tools and
    techniques;
  •  Adopt a
    data-driven approach to auditing, using tools and technologies like audit apps,
    data analytics, machine learning, artificial intelligence, etc.;
  •  To add value
    to the organisation and be a trusted business adviser to management.


The second
part of this article will cover practical cases with steps for using analytics
and conducting data-driven audits.


INTERPLAY OF FIXED ESTABLISHMENT WITH PERMANENT ESTABLISHMENT

Business enterprises with
presence in multiple geographical locations either set up an independent legal
entity (recognised under the host state laws) or operate through extended
establishments such as branch offices, installation / project sites, personnel,
etc. (referred to as multi-location entity – MLE). Such MLEs give rise to
critical tax consequences in both the host state and the parent states. While
the general economic principle in framing fiscal laws for such presence is to
ensure avoidance of double taxation and non-taxation, due to a lack of
consensus on international transactions on the VAT / GST front this objective
is far from being achieved. The issue of taxation is relatively simpler when
the business enterprises set up an independent subsidiary and remunerate them
at arm’s length for all their activities. The complexity arises with presence
through extended establishments as the arrangements between the head office and
these establishments are not clearly discernible or documented for comparison
with external world transactions.


VAT laws globally have termed these extensions as
‘fixed establishment’ – this has been used as a tool to assist them in
identifying the end destination of the service or intangibles. The OECD VAT /
GST guidelines have suggested three approaches in taxation of MLEs for services
and intangibles and to reach the end consumption of the service: (i) Direct use
approach where the focus is on the establishment that uses the services; (ii) Direct delivery approach where the focus
is on the establishment to which the services are delivered (with a presumption that delivery is a good reference
point of use); and (iii) Recharge approach which factors the inefficiencies in
both approaches and requires the MLE to recharge the externally procured costs
to the establishment which ultimately uses the services in order to ensure that
the VAT chain continues to the state of consumption1.

1   It
is probable that the recharge approach has weighed heavily while drafting
Schedule 1 of the CGST Act


The Income Tax law (along with tax treaties) has
recognised the presence of foreign enterprises in India through business
connections / permanent establishments (PE) for the purpose of taxation. The
term ‘permanent establishment’ has been used with a dual purpose – (a) fixing
the taxing rights over the source of income pertaining to the extended presence
in India; and (b) application of Transfer Pricing Regulations for ascertainment
of arm’s length profits of permanent establishments through a process of profit
attribution. Being a nation-wide law, domestic branches really do not alter the
revenue situation from an income tax perspective and have no significance in
this respect.


Under the Indian GST law, not only do we have to
resolve transactions spanning across national borders, we also have to deal
with transactions over state borders. Article 286 of the Indian Constitution
empowered Parliament to play the role of a mediator for inter-state transactions.
Article 286 articulates the location of the supply and also defines the state
which would have exclusive jurisdiction to tax the supply transactions. To give
effect to this geographical jurisdiction, the IGST law, in addition to other
principles, included the concept of ‘fixed establishment’. The objective of
this term is to identify the taxable person, the source and destination of a
supply and the appropriate jurisdiction for taxing the transaction.


Before venturing into a comparative analysis of
fixed establishment (FE) with permanent establishment (PE), it is imperative
that the underlying objectives of both laws are understood clearly. The VAT /
GST laws have introduced the said concept in order to give effect to the
destination principle, i.e., taxation revenues ultimately accrue to the state
in which the services are consumed and the neutrality principle, i.e.,
non-resident and residents are treated in the same manner, while the Income Tax
laws introduced the concept of permanent establishments in line with the
‘source principle’ of taxation, i.e., the country from which the income has
been generated should have the right to tax the said income. This fundamental
divergence would act as a natural impediment to automatic application of the PE
definition to the FE definition.


FIXED ESTABLISHMENT UNDER GST
– CONCEPT

In general, the GST law defines the term FE in
contra-distinction with the term ‘place of business’. The phrase place of
business (PoB) refers to a place from where business is ordinarily carried out
and includes a warehouse, godown or any other place where the supplies are made
or received. FE has been defined to mean a place (other than the registered
place of business) which is characterised with a sufficient degree of permanence
in terms of human and technical resources in order to supply or receive and use
services for its own needs.
The terms PoB and FE are relevant to decide the
‘from’ location and the ‘to’ location of the service activity and consequently
the right location of supplier and recipient of service.


The PoB / FE concept also has some background in
the Service Tax enactment and the Place of Provision of Services Rules. With
similarly worded terms, the education guide on service tax explained the
objective behind the concept of fixed establishment as follows. It was stated
in paragraph 5.2.3 that the term ‘location’ was significant from the
perspective of service provider and recipient in order to ascertain the source
or rendition of a particular service. The paragraph also stressed that the
location also assists in identifying the jurisdiction of the field formation
(under Service Tax being a Central enactment) which would have domain to assess
the transaction. This can probably also support the point that the fixed
establishment concept would play a pivotal role in identifying the appropriate
state to which the taxing domain lies.


FIXED ESTABLISHMENT UNDER
EU-VAT – CONCEPT

The Indian GST definition of fixed establishment
has been influenced by the EU-VAT law. The EU Sixth VAT Directive (Article 43)
adopted the term ‘fixed establishment’ for ascertaining the place of supply of
services. The term was objectively expanded in 2011 by virtue of Articles 11(1)
and 11(2) of the implementing regulations (a procedural law). Prior to this
expansion, certain decisions analysed the definition of fixed establishment,
i.e., the Berkholz2 and ARO Lease3 cases. The Berkholz
case involved gaming machines installed by the taxpayer on on-going sea vessels
with intermittent presence of personnel for maintenance of the machines. The
ECJ on consideration of the cumulative requirement of permanence of human
and technical resources
held that the FE was not established. Similarly, in
the ARO Lease case a company was engaged in leasing of cars to its customers in
Belgium (these cars were purchased by ARO, Netherlands from Belgian dealers and
delivered to the customers directly in Belgium); it was held by the ECJ that
neither the presence of cars of ARO in Belgium nor the self-employed intermediaries
(Belgium dealers) created a sufficient permanent human and technical presence
to constitute an FE.


With Articles 11(1) and (2) of the EU implementing
regulations, the EU-VAT law has categorised fixed establishment into ‘passive’
and ‘active’ fixed establishments4. The IGST law has adopted both in
one definition with the use of the disjunctive phrase ‘or’ in the last few
words of the definition (discussed in detail later). This may be considered as
essential because the concept of fixed establishment has been used to ascertain
both the location of cases where services are either received or provided from
the said fixed establishment.


After the introduction of the implementing
regulation, the Welmory case5 examined a situation where a Cyprian
company had appointed a Polish company to maintain and operate a website for
online auction. The entire process of auction was functioning through the
website maintained by the Polish company. The ECJ stated that the economic
activities of the Polish company and Polish customers does not by itself
constitute a fixed establishment and the services of the Polish company should
be viewed distinctly from that of the Cyprian company to the Polish customers.


PERMANENT ESTABLISHMENT UNDER
INCOME TAX – CONCEPT

In Income Tax, the domestic legislation used the
phrase ‘business connection’ which is of very wide amplitude, but taxpayers use
the benefit of a narrower term PE6 which is used in most tax
treaties (OECD, US or UN model). The term PE has been defined as a fixed place
of business through which the business of an enterprise is wholly or partly
carried out and includes the following: (a) place of management; (b) branch,
office, factory, workshop, warehouse, etc., (c) building, construction or
installation site; (d) provision of services through presence of personnel; and
(e) dependent agency. In case a foreign enterprise constitutes a PE in a host
state, the PE is to be granted a separate entity status and business profits
attributable to the PE at arms’ length are to be taxed in the state in which
the PE is constituted.


Having understood the broad concept of FE and PE in
GST / EU and Income Tax law, we now proceed to identify the points at which the
said terms would converge / diverge through the assistance of illustrations and
then tabulate the same for future reference.


2   ECJ
EC 4th July, 1985, 168/84, ECLI:EU:C:1985:299 (Günter Berkholz),
European Court Reports, 1985

3   ECJ
EC 17th July, 1997, C-190/95, ECLI:EU:C:1997:374 (ARO Lease),
European Court Reports, 1997

4   Passive
FEs being those which only receive / procure inputs / services (cost centres)
and Active FEs which also provide services (profit centres)

5   ECJ
EU 15th October, 2014, C-605/12, ECLI:EU:C:2014:2298 (Welmory),
Official Journal 2014, C 462

6   OECD
Model Convention on Tax Treaties as an example


CONSTITUTION OF A PE / FE –
COMPARATIVE ANALYSIS

(A) Fixed place PE (basic rule): Stability,
productivity and dependence

Article 5 of Income Tax treaties defines a fixed
place PE as ‘fixed place of business’ through which the business of an
enterprise is wholly or partly carried out. The fixed place PE rests on three
primary tests: (a) place of business; (b) location test; and (c) permanence
test. Article 5(2), in fact, enumerates instances such as branch, office,
factory, workshop, warehouse, etc., which by default satisfy the above tests,
especially the place of business test.


The place of business test
postulates that some portion of the business activity of the MLE enterprise is
conducted through the physical office in India. The extent of business activity
conducted in India is ascertained through a FAR analysis (Functions performed,
Assets employed and Risks assumed) of the PE’s operations in India. But there
is one critical exclusion in terms of conduct of preparatory or auxiliary
activities – in effect, where a part of the business activity is conducted in a
territory and such part is preparatory or auxiliary in nature, the MLE is not
considered to have a permanent establishment in the said territory. In the
context of this Basic Rule PE, the Supreme Court in DIT vs. Morgan
Stanley [2007 (7) TMI 201]
was examining whether back-office operations
of a subsidiary constitute a place of business of the parent company. The Court
held that the support function performed would not constitute an extension
of the business activity of the parent.
Similarly, the mere fact that the
business of the parent company is outsourced or support functions are performed
by the Indian subsidiary, was considered as irrelevant for the purpose of concluding that the parent company is having
an establishment in India [ADIT vs. E Funds IT Solutions Inc. 2017 (10)
TMI 1011].
These decisions imply that the business activity should be
understood as an extension of the set-up already in place in the parent company
rather than an independent entity.


The location test requires that there has to be a
physical presence of the business in a specific place (though the place may be
mobile within the defined territory). This test warrants that the business
activity should be capable of being tagged to the physical territory either as
equipment, branch or any such physical infrastructure.


As for the permanence test,
the OECD commentary states that the term ‘fixed’ itself warrants a certain
degree of permanence at the location in which the physical infrastructure is
placed in the taxable territory. The phrase ‘fixed’, as an adjective, also
attaches a certain degree of permanence to the place of business which is a
prerequisite under this Article (also stated in the OECD commentary)7.
In the absence of a defined time period under the treaties, there is some
relativity in the way jurisprudence has developed to identify the degree of
permanence of an activity. While each case produced different results, a recent
decision of the Supreme Court in Formula One World Championship Ltd. vs.
CIT, Delhi [2017] 80 taxmann.com 347 (SC)
examined a Formula One race
arrangement which lasted for approximately three weeks and held that such an
arrangement constituted a fixed place PE. The background to the case involved a
Formula One race conducted by FOWC which involved placement of the entire racing
infrastructure / equipment on Budd International Circuit and FOWC had complete
control over the schedule, equipment and personnel at the location. The Supreme
Court stressed on the disposal test (i.e., FOWC having exclusive and complete
control over the racing circuit) rather than the duration test for testing the
permanence of an activity. In other words, ‘fixed’ was interpreted by the
Supreme Court with reference to the exclusivity and control over the place
rather than the duration of usage (which is relative for each business
activity).


In comparison, the FE definition in IGST law also
relies on a ‘sufficient degree of permanence’. The legislature has used a very
subjective term probably keeping in view varied industry practices. For
example, the Formula One race arrangements which last only for three weeks in a
calendar year at a particular location, was considered as a sufficient degree
of permanence by the Court given the peculiarity of the sporting event.
Moreover, the Court stressed on the adequacy of control over the three-week
period rather than the duration of three weeks. Though speculative, it is
probable that the Court might not have reached the same result in case the
facts were for a long duration project (e.g., oil exploration activities,
etc.). Probably, this test would also be applicable for understanding the FE
definition. Whether the phrase ‘sufficient degree of permanence’ has to be
assessed keeping the disposal test or the duration test in mind, is a question
open for debate.

7   CIT
vs. Visakhapatnam Port Trust 1983 (6) TMI 31

Further, the disposal test
should also be addressed factoring in the nature of supply which is under
consideration, for example, presence of a few weeks would be sufficient for
rendering legal advisory services on a particular issue but a presence of even
a few months would not be sufficient while rendering the very same advisory
services for construction of a building. The service tax education guide states
that the relevant factor is the ‘adequacy’ of the human and technical resources
to render the ‘service’ for deciding whether there is sufficient permanence in
the activity. In the absence of detailed jurisprudence on this subject, one may
imbibe the settled principle under Income Tax while interpreting the FE
definition.


(B) Service PE (Extended PE): Physical presence of
employees

The OECD Model Convention
provides for a service PE if the aggregate presence of the personnel in the
taxable territory is beyond 183 days in a 12-month period8. The
nature of services that are rendered by the personnel could be wide in range.
Physical presence of personnel in the taxable territory rendering a service,
irrespective of the type of service, would be prominent in deciding the
constitution of a service PE. But the Supreme Court in Morgan Stanley
(Supra)
differentiated the services rendered through own employees of
MS USA and deputed employees of MS USA. The Court held that in the case of own
employees performing supervisory / stewardship activities, there is no service being rendered by the presence
of employees in India to the Indian subsidiary, rather the presence of
personnel is for the sole benefit of the parent company in order to ensure
quality control, confidentiality, etc. On the other hand, the employees of MS
India deputed for assisting the operations of MS India were considered as an identifiable service activity to the
Indian subsidiary, hence a service PE was held to be constituted.

8   UN
Model narrows the test to a 6-month period

Under GST, the reference to
personnel is made in the definition of fixed establishment by use of the phrase
‘human resources’. But this aspect is not a stand-alone requirement for
constitution of a fixed establishment. The human capital is required to be
equipped with a degree of permanence and technical resources (depending on the
nature of work) in order to constitute a fixed establishment. The permanence
test applicable to Fixed Place PE may be adopted while examining the FE arising
out of service personnel. It is also important that the human capital should be
‘capable of availing and rendering the service activity’ to the third party
while being present in the taxable territory.


We may recall that the EU-VAT in Berkholz’s case
held that the presence of personnel to maintain the gaming equipment on an
intermittent basis did not constitute a fixed establishment in the foreign
territory. Probably, the IGST law may also have to follow suit and despite a
service PE being constituted under Income Tax, if the human capital is using
technical resources of the end customer there may be a ground to contend that a
fixed establishment is not constituted. From a practical standpoint, many MNCs
appoint personnel for maintenance and on-site repair of machinery. Where repair
and maintenance is partially conducted from the Indian territory with a
significant portion being conducted remotely, one may view the same as not
constituting an FE in India, but where the said personnel (with their
equipment) are capable of rendering the service exhaustively, the said
personnel can be said to have constituted a PE in India.


(C) Agency PE (non-obstante rule):
Dependence (DAPE)

The concept of agency PE was introduced to address quasi-presence
of foreign enterprises through dependent representatives in the taxable
territory. Notwithstanding the requirements of a basic rule PE, Article 5
provides for formation of a dependent agency PE where, (a) the person
habitually concludes contracts or even possesses the authority to conclude
contracts; (b) maintains inventory of goods on behalf of its principal; or (c)
habitually secures orders wholly or primarily for its principal in India. The
primary requirement is that a principal-agency relationship is visible and such
agent, if at all, should be one who is NOT operating in his independent
capacity in his ordinary course of business. Evidently, a principal-agent
relationship would be established if the agent acts in a representative
capacity with an ability to bind its principal to its actions.


The Bombay High Court in CIT vs. Taj TV
Limited [2020 (3) TMI 500]
examined whether revenues under the
exclusive distribution agreement by Taj TV Limited involving fees from cable
operators and granting them viewing and relay rights, were under an agency
relationship. Under the distribution agreement, Taj TV was given independent
rights to market and promote the TV channels and negotiate and conclude
contracts with sub-distributors. In this decision, the Court observed that Taj
TV under sub-distributor agreement and the cable-operator agreement, acted in
its own capacity and the foreign enterprise did not have any privity in
deciding the pricing of the rights. Hence it was concluded that there was a
principal-to-principal relationship. In contrast, the very same Bombay High
Court in DIT Mumbai vs. B4U International Holdings Limited 2015 (5) TMI
277
on those specific facts held that the Indian entity did not have
any authority to conclude contracts on its own and was under the direction and
control of its principal and hence constituted a DAPE in India.


The secondary requirement of constitution of a DAPE
is that the agent should not be of independent status. ‘Legal and economic
independence’ are the two tests which are usually applied for this clause.
International commentaries suggest that if the agent is responsible for its own
actions, takes risks and has its own special skill and knowledge to render the
agency service, such agent would be termed as an independent agent. In certain
AAR rulings9 under Income Tax, the dependency agency test was
applied and held not to be fulfilled on the ground that similar services were
being provided to multiple FIIs and not just one principal. Moreover, the
treaties itself provides for an exclusion where the agent renders its services
to multiple principals, evidencing that it has risk abilities, own skill and
knowledge, etc. to act independently.


As regards the authority to conclude contracts,
paragraph 33 of the OECD commentary states that a person who is authorised to
negotiate all elements of a contract in a binding way on the enterprise can be
said to have the authority to conclude contracts and the mere fact that the
person has attended and participated in negotiations is not sufficient
authority under this PE rule10.


9   XYZ/ABC Equity Fund vs. CIT (2001) 116 Taxman
719 (AAR); Fidelity Services Series VIII in (2004) 271 ITR 1 (AAR)

10  India
has expressed its reservations to the OECD commentary on this aspect and
submitted that mere participation in negotiations is also evidence of authority
to conclude contracts

In contrast, the IGST law does not have a specific
case of agency for the purpose of fixed establishment for a supplier or its
recipient. It would be interesting to note that section 2(105) of the CGST Act
has extended the definition of a supplier to include its agent as well who is
engaged as supplier of services. By virtue of this inclusion, the location of
the supplier would have to be adjudged after taking cognisance of the presence
of an agent in India. As an illustration, if Taj TV was appointed as an agent
of Taj Mauritius for distribution of channels, the location of the supplier for
the services rendered by Taj Mauritius (i.e., channel access fee) would be
liable to be attributed to the Taj TV (as an agent) of Taj Mauritius resulting
in Taj Mauritius being considered as present in India through the FE-agency
relationship. Unlike Income Tax, the agency relationship need not always be one
who is dependent on the principal. The place of business of the agent would be
considered as the place of business of the principal (to the extent of the
agency relationship) and fixed as the location of supplier of such services. Of
course, the basic FE rule under GST such as permanence, human and technical
resources would still have to be satisfied by the agent in order to qualify as
an FE in India.


The location of supplier and
recipient definitions has been limited only for the service activity and not
transactions of supply of goods. One of the reasons may be that the agency FE may
not be applicable to selling / purchasing agents of goods. This is because
agency transactions in respect of supply of goods are covered under Schedule I
of the CGST Act which deems the principal and agent as separate beings. Once
the agent is equated to a purchaser of goods, by way of a deeming fiction, the
agent would be considered as a quasi-supplier for other purposes of the
Act and not as a representative of its principal. Hence, an agency PE under
Income Tax for supply of goods would not translate into an FE for the very same
principal under GST.


(D) Construction / Installation PE

Tax treaties recognises any construction,
installation, project site, etc., including supervisory activities11
of a foreign enterprise as being construction / installation PEs. The treaties
(OECD – 12 months; UN – 6 months) specify the period beyond which the PE is
said to be constituted. All planning and designing activity prior to physical
visit to the site would be included in the PE (UN Model). The Tribunal in SAIL
vs. ACIT (2007) 105 ITD 679
held that supervisory services provided by
a company even though it was itself not engaged in installation activity would
be sufficient to constitute an installation PE.


The IGST law has not carved out a specific instance
of a construction / installation FE. The fixed establishment definition itself
encompasses any presence of human and technical resources as sufficient grounds
to constitute an FE. Moreover, construction activities generally entail direct
procurement and supply of services and hence all the ingredients of
constituting an FE stand established. Unlike the situation in SAIL’s case above
which involved mere provision of supervisory services, such activities may not
constitute an FE in GST law.

11  Only in UN model treaties


(E) Significant Economic Presence (SEP): Digital
footprint

With increasing digital presence globally, BEPS
Action Plan 1 identified the problems of taxation due to advancement of digital
economy. The concept of significant economic presence (SEP), which could be
represented by the digital footprint of an enterprise, was given legal sanctity
in the Income Tax law. The law has prescribed minimum thresholds on the basis
of digital footprint for constituting significant economic presence in the
country – the thresholds could take the form of number of digital users,
revenue per user, etc. The BEPS Action Plan as well as the memorandum
suggesting this amendment stated that the traditional concept of permanent
establishment requiring physical presence in the taxable territory cannot be
possibly applied to digital transactions and hence alternative criteria such as
the above are necessary for viewing significant economic presence.


The Indian GST law has not considered
this aspect for the purpose of defining fixed establishment. The law has
defined a term ‘Online Database and Information Access or retrieval service
activity’
to tax all digital economy transactions. In fact, this law has
alternatively chosen to place a tax liability by adopting a different approach
and treating this transaction as an import of service into India and taxing the
same in the hands of the business user. In case of B2C transactions, the GST
law has placed the obligation on the foreign company to identify a
representative in India for discharging the tax burden on such transaction.


In summary, the GST FE concept and the Income Tax PE concept converge and
diverge at multiple points which can be tabulated as follows (see Table 1):


ATTRIBUTION / RECHARGE
APPROACH

Income Tax attributes income /
profit to the PE based on the FAR approach. This would involve estimations and
approximations; profitability is not traceable to the transaction level.

Table 1

Aspect

Convergence

Limited Divergence

Complete Divergence

Fixed
PE

Degree
of permanence

Disposal
test which does not seem to be a clear prerequisite in FE; no exclusion for
preparatory / auxiliary activity in FE

Capability
of receipt and / or supply of services is not required in PE

Service
PE

Rendition
of services

Duration
test for PE and FE may be differently viewed

Presence
of technical resources are essential for FE

Agency
PE

Agent
constituting PE / FE

Agency
in respect of goods not part of FE test due to deeming fiction in Schedule I

Dependency
not an FE test ~ multi service agents constituting FE

Construction
PE

Construction
site being place of business

Ancillary
activities may form a Construction PE but not an FE

No
time limit specified for FE and relative to nature of work

SEP

NIL

NIL

Treated
as OIDAR and liable for RCM / FCM as the case may be


In GST, India has adopted the
recharge approach in cases of service transactions. For example, with respect
to services directly connected to an FE, the requirement under GST law is to
‘bill from’ the FE / ‘bill to’ the FE which is most directly concerned with the
supply. The FE would then have to recharge the relevant establishment in the
organisation which has consumed the service even partially. In such a manner,
the tax revenues would follow the contractual obligations (with the presumption
that economics would assist in reaching the point of consumption) and hence the
importance of identification of the relevant FE would assume high significance.


However, in cases of agency of supply of goods, the
requirement of the law is to deem them as distinct entities at the outset
itself and equate them to a seller or purchaser of goods. By this approach, the
VAT chain passes through the agent and attempts to reach the end consumption of
goods. This activity takes place at the transaction level rather than
the entity level which is the case in Income Tax. The global apportionment
approach / FAR analysis adopted for attribution of profits to the PE would not
serve any purpose for GST.


In summary, it is observed that though both the concepts are
interconnected at multiple points, there are bound to be divergent answers in
view of the basic structure of both the Income Tax and the GST laws being
different. This concept would be relevant for outbound as well as inbound
presence and hence a balanced interpretation of this concept is essential from
the perspective of all stakeholders. In any case, the attempt should be to
identify the last point in the value chain where the consumption actually takes
place. This destination principle, though unwritten in the law, is the core of
the GST system in place and violation of this principle at the cost of legal
interpretation may cause chaos in the economic distribution of the wealth of
the nation.


IN CELEBRATION OF 74TH INDEPENDENCE DAY INDIA: THE LAND OF CREATIVITY

Since time
immemorial, the land of India has been the loving land of the gods. All avataras,
vibhutis, seers and sages take birth here time and again. The history of
India is overflowing with the stories of such personalities. This has been a
blessed land where one chooses to be born again and again.


‘Far better it is
to win a few moments of life in Bharata than several ages of life in
these celestial regions; in that sacred land, heroic souls can achieve in a
moment the state of fearlessness in God by renouncing in Him all actions done
by their perishable bodies.’ Thus says the Bhagavata Purana, 5.19.21-23.


Indeed, this is the
land which has been the land of the seekers of the Truth, Light and Wisdom; a
land in which a dynamic spirituality holds the key to everything pertaining to
life and the world. This dynamic spirituality has given much strength to the
race that has been able to sustain its creative energy from time immemorial and
has been able to contribute positively towards the progressive evolution of
humanity. India in this sense is not just a loving land of the gods, but a land
of immense creativity.


The seers and sages
of ancient India had an immense scientific temperament. The quest was to find
out the truth of everything, but their method was very different from the ways
and methods of modern science. They did not view science as a test-tube culture
alone, but applied it to every aspect of life. They held a holistic view of
everything. They did not treat mathematics and poetry as two unrelated
subjects. This integrated vision of the seers and sages could create such a
great foundation that not only enriched life, but also gave strength to sustain
the creative energy uninterruptedly.


‘For three
thousand years at least – it is indeed much longer – she has been creating abundantly
and incessantly, lavishly, with an inexhaustible many-sidedness, republics and
kingdoms and empires, philosophies and cosmogonies and sciences and creeds and
arts and poems and all kinds of monuments, palaces and temples and public
works, communities and societies and religious orders, laws and codes and
rituals, physical sciences, psychic sciences, systems of Yoga, systems of
politics and administration, arts spiritual, arts worldly, trades, industries,
fine crafts – the list is endless and in each item there is almost a plethora
of activity. She creates and creates and is not satisfied and is not tired…’


This is what Sri
Aurobindo writes about the prolific creativity of our country in his book, The
Renaissance in India
.


There has been no
branch of human knowledge in which India has not contributed. Most of the
discoveries for which we give credit to European scientists were well known to
ancient Indian sages.


They had the
knowledge of the science of Architecture based on which they could build cities
according to well-laid-out plans, roads with calculated widths, drains with
measured gradients, granaries with ventilation, baths constructed according to
angles of precision and platforms built to protect from the onslaught of
floods.


Some of the notable
ancient writings on Architecture include: Brihat Samhita of Varahamihira
(6th century), Samarangana Sutradhara of King Bhoja (11th
century), Manushyalaya Chandrika of Thirumangalath Neelakanthan
Musath (16th century), Mayamata (11th century), Silparatna
of Srikumar (16th century), Aparjita-Prccha of
Bhuvanadavacharya, Agastya-Sakalahikara of Agastya and Manasara
Shilpa Shastra
of Manasara.


The science of
Medicine was well advanced compared to the system of medicine that existed in
the other parts of the globe during the time when there lived Acharya Sushruta
(Sushruta Samhita, between 6th – 12th century
BCE), Acharya Charaka (Charaka Samhita, between 6th – 12th
century BCE) and Acharya Vagbhata (Astangahrdayasamhita, 6th
century CE). Sage Divodasa Dhanwantari developed the school of surgery. Rishi
Kashyap developed the specialised fields of paediatrics and gynaecology. Sage
Atreya classified the principles of anatomy, physiology, pharmacology,
embryology, blood circulation and much more. Acharya Sushruta is known as the ‘Father of
surgery’. Even modern science recognises India as the first country to develop
and use rhinoplasty (developed by Sushruta). Sushruta worked with 125 kinds of
surgical instruments, which included scalpels, lancets, needles, catheters,
rectal speculums, mostly conceived from jaws of animals and birds to obtain the
necessary grips. He also defined various methods of stitching: the use of
horse’s hair, fine thread, fibres of bark, goat’s guts and ants’ heads.


The way plants were
identified and classified shows the immense scientific temperament of the
ancient seers and sages. They not only made a scientific and systematic
classification of the plants but could discover the exact properties of
hundreds of plants without any sophisticated laboratory tools.


In ancient India
there was also the science of Metallurgy which produced amazing results. With
the knowledge of this, the people could make such minute steatite beads that
300 would weigh only one gram and these they would adorn on beautiful necks. Rasaratnakara
of Nagarjuna (2nd century CE), Rasarnava (12th
century CE), Rasaratnasamuccaya (13th to 14th
century CE), Rasendra Sara Samgraha (9th century CE) are some
of the important works in which one finds the science of Metallurgy.


The credit of
discovery of aviation technology goes to Bharadwaja. His Yantra Sarvasva
covers astonishing discoveries in aviation and space sciences, and flying machines.


Sage Kanada (circa
600 BCE) is recognised as the founder of Atomic theory who classified all the
objects of creation into nine elements (earth, water, light or fire, wind,
ether, time, space, mind and soul). He stated that every object in creation is
made of atoms that in turn connect with each other to form molecules.


In the field of
Chemistry alchemical metals were developed for medicinal use by sage Nagarjuna.
His book Rasa Ratnakara is a fine specimen of India’s contribution to
Chemistry. The knowledge of baking of the earth for changing the soft mud to
hard clay and then painting the clay with colours to make beautiful pots, etc.
was very well known to the people of India.


In the field of
Astronomy and Astrology, India was in a very advanced position. It was possible
for the ancient Indian seers and sages to measure the sky at angles of 30
degrees and the position of stars as they lay randomly scattered in depthless
vistas. Indians were the first in the world to have done this and the Greeks arrived
only 2,000 years later.


Aryabhatiya of Aryabhata (5th to 6th century CE), Panchasiddhantika,
Brihat-Samhita, Brihat-Jataka
and Laghu Jataka of Varahamihira (6th
century CE), Brahmasphutasiddhanta of Brahmagupta (6th to 7th
century CE) are some of the notable texts on Astronomy and Astrology.


The list of the
discoveries by the ancient Indian seers and sages is truly long. There has been
no branch of science in which India has not made its own contribution. One can
keep exploring the immense treasures available in the vast gamut of Sanskrit
literature, many published and many more yet to see the light of day.


The need of the
time is to awaken to the spirit of India and develop a deep sense of Love for
our Motherland, a thirst for the knowledge of her past glories, a burning
aspiration to serve her – this is all that we need to do for our country.


But at the same
time we must remember that we are not expected to make a return to the past,
but to take the glories of the past and map them to the present conditions with
the aim of creating a bright future. Our aim must be the future – the past is
the foundation and the present is the material.


In conclusion, I
present a wonderful passage from the writings of Sri Aurobindo:


‘Not only was India
in the first rank in mathematics, astronomy, chemistry, medicine, surgery, all
the branches of physical knowledge which were practiced in ancient times, but
she was, along with the Greeks, the teacher of the Arabs from whom Europe
recovered the lost habit of scientific enquiry and got the basis from which
modern science started. In many directions India had the priority of discovery
– to take only two striking examples among a multitude, the decimal notation in
mathematics or the perception that the earth is a moving body in Astronomy, – calaa
prithvi sthiraa bhaati
, the earth moves and only appears to be still, said
the Indian astronomer many centuries before Galileo. This great development
would hardly have been possible in a nation whose thinkers and men of learning
were led by its metaphysical tendencies to turn away from the study of nature.
A remarkable feature of the Indian mind was a close attention to the things of
life, a disposition to observe minutely its salient facts, to systematise and
to found in each department of it a science, Shastra, well-founded scheme and
rule. That is at least a good beginning of the scientific tendency and not the
sign of a culture capable only of unsubstantial metaphysics.’ (Sri Aurobindo, CWSA,
Vol.20
, pp. 123–124.)


(The author is
the Director of Sri Aurobindo Foundation for Indian Culture, SAFIC, Sri
Aurobindo Society, Pondicherry. He is a well-known Sanskrit scholar and was
awarded the Maharshi Badrayan Vyas Award for Sanskrit in 2012 by the President
of India. Through his pioneering work through Vande Matram Library Trust, an
open-source volunteer-driven project, he has made available authentic English
translations of timeless Sanskrit scriptures of India.)


Search and seizure – Assessment of third person – Section 153C of ITA, 1961 – Undisclosed income – Assessment based solely on statement of party against whom search conducted – A.O. not making any further inquiry or investigation on information received from Deputy Commissioner – No cogent material produced to fasten liability on assessee – Concurrent findings of fact by appellate authorities; A.Y. 2002-03

41. CIT vs. Sant
Lal
[2020] 423 ITR 1 (Del) Date of order: 11th March, 2020 A.Y.: 2002-03


Search and seizure – Assessment of third
person – Section 153C of ITA, 1961 – Undisclosed income – Assessment based
solely on statement of party against whom search conducted – A.O. not making
any further inquiry or investigation on information received from Deputy
Commissioner – No cogent material produced to fasten liability on assessee –
Concurrent findings of fact by appellate authorities; A.Y. 2002-03


For the A.Y. 2002-03, the assessee declared
income from salary, house property and capital gains. On the basis of
information from the Deputy Commissioner that search and seizure conducted in
the premises of BMG revealed that BMG was engaged in hundi business
wherein previously undisclosed money was arranged from various parties
including the assessee, the A.O. issued a notice u/s 148 and passed an order
including the undisclosed cash transactions with the BMG group as unexplained
income u/s 69A which had escaped assessment.


The Commissioner (Appeals) deleted the
addition. The Tribunal confirmed the order of the Commissioner (Appeals) on the
ground that the issues in appeal were directly covered in its earlier
decisions.


On appeal by the Revenue, the Delhi High
Court upheld the decision of the Tribunal and held as under:


‘i) On the facts and the concurrent findings
given by the Commissioner (Appeals) and the Tribunal, it was evident that the
Department had not been able to produce any cogent material which could fasten
the liability on the assessee.


ii) The
Commissioner (Appeals) had also examined the assessment record and had observed
that the A.O. did not make any further inquiry or investigation on the
information passed on by the Deputy Commissioner with respect to the party in
respect of whom the search was conducted. No attempt or effort was made to
gather or corroborate evidence in respect of the addition made u/s 69A by the
A.O. No question of law arose.’


RELATIVE IS RELATIVE TO THE ACT IN QUESTION

Introduction

Who is a relative? This question
may appear very mundane at first blush, but when viewed in the legal context it
becomes very significant. India is a land of laws and each one of them is an
island in itself. Many of the Acts have defined the term ‘relative’ and each
has done so in its own independent manner, thereby creating multiple
definitions. Hence, the term ‘relative’ is relative to the Act in question,
i.e., it depends on the Act which is being examined.


The generic definition of the term
‘relative’ as contained in the Concise Oxford English Dictionary is a person
connected by blood or marriage. In State of Punjab vs. Gurmit Singh, 2014
(9) SCC 632,
the Supreme Court held that in Ramanatha Aiyar’s, Advance
Law Lexicon (Vol. 4, 3rd Ed.), the word ‘relative’ means any person related by
blood, marriage or adoption. Again, in the case of U. Suvetha vs. State
by Inspector of Police, (2009) 6 SCC 787
it held that in the absence of
any statutory definition, the term must be assigned a meaning as is commonly
understood. Ordinarily, it would include the father, mother, husband or wife,
son, daughter, brother, sister, nephew or niece, grandson or granddaughter of
an individual. The meaning of the word ‘relative’ would depend upon the nature
of the statute. It principally includes a person related by blood, marriage or
adoption. The expression ‘relative of the husband’ came up for consideration in
the case of Vijeta Gajra vs. State of NCT of Delhi (2010)11 SCC 618
where it was held that the word relative would be limited only to the blood
relations or the relations by marriage.


Interestingly, the succession laws
such as the Hindu Succession Act, 1956 do not use the term ‘relative’. Instead,
they use the word ‘heir’ which has a different connotation altogether. An heir
is a relative who comes into being only on the death of a person, whereas a
person would have relatives even when he is alive.


Let us analyse the definitions
under a few crucial Acts and try and bring out the similarities and the
dissimilarities between the different meanings.


Income-tax
Act, 1961

The Big Daddy of all laws has the
biggest list of relatives, no pun intended! The notorious section 56(2)(x) of
the Act taxes certain receipts of property in the hands of the recipient.
However, any receipt of property from a relative is exempt from tax. Hence, it
becomes very essential that the list of relatives is long. This section provides
an exhaustive definition under which the following persons would be treated as
a relative of the donee / recipient:


(i)    spouse
of the individual;

(ii)    brother or sister of the individual;

(iii)   brother or sister of the spouse of the individual;

(iv)   brother or sister of either of the parents of the individual;

(v)   any lineal ascendant or descendant of the individual;

(vi)   any lineal ascendant or descendant of the spouse of the individual;

(vii) spouse of the person referred to in clauses (ii) to (vi).


The term lineal ascendant or
descendant is also an often-used term but never defined in various Indian laws.
It means a straight line of relationship either upwards or downwards. For
instance, a son, his father and grandfather would constitute a lineal
ascendancy. One prevalent myth is that it only refers to male relations. A
daughter, her mother and her grandmother or a son, his mother and his
grandmother would also constitute a lineal relationship. All that is required
is that the relatives should be in a direct straight line. Parallel /
horizontal relations, such as cousins and uncles, would not constitute a lineal
line. One of the most interesting facets of the above definition is that an
uncle / aunt is a relative for a nephew / niece but the converse is not true.
So a nephew can receive a gift from his uncle but the very same uncle cannot
receive a gift from his nephew without paying tax on the same. Strange are the
ways of the taxman, but then law and logic never went hand-in-hand! In this
connection there have been conflicting decisions of the courts as to whether a
gift received by a person from his sibling but made from the bank account of
his sibling’s son would attract the rigours of this section – PCIT vs.
Gulam Farooq Ansari, ITA 230/2017, Raj HC order dated 22nd November,
2017 and Ramesh Garg vs. ACIT, [2017] 88 taxmann.com 347 (Chandigarh – Trib.)


Again, a cousin (e.g., the
recipient’s mother’s sister’s son) does not constitute a relative under this
section – ACIT vs. Masanam Veerakumar, [2013] 34 taxmann.com 267 (Chennai
– Trib.)
An interesting decision was delivered by the Mumbai ITAT that
a relative of a father did not become the relative of a minor recipient just
because the minor’s income was clubbed with his father. Since the minor received
the gift, the relationship of the donor should be with reference to the minor
who was to be treated as ‘the individual’ – ACIT vs. Lucky Pamnani [2011]
129 ITD 489 (Mumbai).
The Act also defines a child in relation to an
individual to include a step-child and an adopted child. Interestingly, this
Act is the only one where one’s in-laws are included in the list of relatives.


This section has become a hindrance
to the untangling of several jointly owned family businesses on account of
certain relatives not being included in the list of exemptions.


Companies
Act, 2013

The new avatar of the
Companies Act has also seen a new meaning to the term ‘relative’. Several old
relations have been severed and the new list in the Companies Act, 2013 is
quite a pruned one compared to the lengthy list contained in the Companies Act,
1956. Given below is a comparison of the definition under the two Acts:


HOW TWO ACTS DEFINE A ‘RELATIVE’


Companies Act, 2013

Companies Act, 1956

Members of an HUF

Members of an HUF

Spouse

Spouse

Father, including step-father

Father, not including step-father

Mother, including step-mother

Mother, including step-mother

Son, including step-son

Son, including step-son

Son’s wife

Son’s wife

Daughter. Notably not including a step-daughter, whereas she was
included under the 1956 Act!

Daughter including a step-daughter

Daughter’s husband

Daughter’s husband

Brother, including step-brother

Brother, including step-brother

Sister, including step-sister

Sister, including step-sister

Father’s father

Father’s mother

Mother’s mother

Mother’s father

Son’s son

Son’s son’s wife

Son’s daughter

Son’s daughter’s husband

Daughter’s son

Daughter’s son’s wife

Daughter’s daughter

Daughter’s daughter’s husband

Brother’s wife

Sister’s husband


The definition under the Companies
Act is relevant not just under that law but even under other statutes which
rely on the definition contained therein. Some of the important places where
the term relative is used in the Companies Act include the ‘related party’
definition; the ‘interested director’ definition; disqualification from being
appointed as an auditor if his relative is an interested party / employee;
disqualification from being appointed as an independent director if his
relative has a pecuniary relationship / is a key managerial personnel; loan by
a company to its director or his relative, etc.


Maharashtra
Stamp Act, 1958

Gifts between relatives carry a
concessional stamp duty as opposed to gifts to non-relatives. Gifts to defined
relatives carry a stamp duty @ 3% + 1% on the market value / ready reckoner
value of the property. The defined relatives for this purpose are spouse,
sibling, lineal ascendants or descendants of the donor. Thus, the list is quite
small as compared to the list u/s 56(2)(x) of the Income-tax Act. Hence, it is
essential to note that what may be exempt from income-tax may not also carry a
concessional stamp duty rate.


In addition to the above, for two
types of properties and six relatives the stamp duty is only Rs. 200 + 1% of
the market value of the property and a registration fee of just Rs. 200. This
concession is available only for residential or agricultural property and only
for the husband, wife, son, daughter, grandson, granddaughter of the donor. Any
other relative not covered within the above six relations would attract the 4%
duty, provided the relation is covered within the above larger list. For
instance, a gift of property to one’s brother would attract 4% duty on the gift
deed. Similarly, even for gift to the six relations if it is a gift of
commercial property / non-agricultural land, then the duty would be 4%, e.g.,
gift of an office to one’s son would attract 4% duty. Unlike section 56(2)(x),
the relatives need to be viewed in relation to the donor and not in relation to
the recipient. Hence, if a son gifts a residential house to his father, then
the gift deed would not attract a concessional duty of Rs. 200 + 1% but would
be covered by the 4% duty!


SEBI
Laws

SEBI Regulations have various ways
of dealing with relatives. The SEBI (Issue of Capital and Disclosure
Requirements) Regulations, 2009
which prescribe the requirements for
making an offer document for public issues, rights issues, etc., define who
constitutes a promoter group of a company making an issue. It includes the
promoter and his immediate relatives, i.e., any spouse or any parent, brother,
sister or child of the promoter or of the spouse. Thus, step-children have also
been covered.


The SEBI (Substantial
Acquisition of Shares and Takeover) Regulations, 2011
exempts any
transfer of listed shares inter se immediate relatives from the
requirements of making an open offer. The definition is the same as given
above.


On the other hand, the SEBI
(Prohibition of Insider Trading) Regulations, 2015
treats the immediate
relative of an insider as a connected person and it is defined to mean the
spouse of a person, and includes parent, sibling, and child of such person or
of the spouse, any of whom is either dependent financially on such person, or
consults such person in taking decisions relating to trading in securities.


The SEBI (Listing Obligations
and Disclosure Requirements) Regulations, 2015
prescribe the meaning of
an independent director for a listed company. For this purpose, a person whose
relative has a pecuniary relationship with / is a KMP of the listed company,
etc., cannot be appointed. Again, beginning 1st April, 2020, the
Chairmen of certain listed companies cannot be related to the MD / CEO. The
definition of relative for these purposes is the same as contained in the
Companies Act, 2013. Thus, different SEBI Regulations have dual definitions
with the term immediate relative being much smaller in ambit than a relative.


FEMA
Regulations

The FEMA Regulations notified by
the RBI under the FEMA Act, 1999 use the concept of relative at various places:


a)   A
gift of shares from a resident to a non-resident requires the RBI approval and
is allowed only for gift to relatives;


b)  Individuals
resident in India are permitted to include a non-resident Indian close relative
as a joint holder in all types of resident bank accounts on ‘either or survivor’”
basis;


c)   Resident
relatives can be added as joint account holders along with the primary holder
in Resident Foreign Currency (RFC) Accounts and Non-Resident (External) / NRE
Accounts;


d)  NRIs/
PIOs can remit up to USD 1 million per financial year in respect of assets
acquired under a deed of settlement made by his / her relatives provided the
settlement takes effect on the death of the settler;


e)   An
NRI or an OCI can acquire by way of gift any immovable property (other than
agricultural land / plantation property / farm house) in India from a person
resident in India or from an NRI or an OCI who is a relative;


f)   An
NRI or an OCI may gift any immovable property (other than agricultural land or
plantation property or farm house) to an NRI or an OCI who should be a relative
of the donor;


g)  Under
the Liberalised Remittance Scheme of USD 250,000, a resident can meet the
medical expenses in respect of an NRI close relative when the NRI is on a visit
to India; maintain close relatives abroad;


h)   Under
the LRS, residents can extend interest-free loans in Indian rupees to NRI / PIO
relatives.


The definition of relatives under
the Companies Act, 2013 is adopted for all of the above purposes.


However, the FEMA Regulations have
a different definition when it comes to acquisition of immovable property
abroad. They provide that a resident can acquire immovable property abroad
jointly with a relative who is a person resident outside India, provided there
is no outflow of funds from India, and for this purpose the definition of
relative means husband, wife, brother or sister or any lineal ascendant or
descendant of that individual.


Agricultural
land laws

The Maharashtra Tenancy and
Agricultural Lands Act, 1948
seeks to govern the relationships between
tenants and landlords of agricultural lands. A person lawfully cultivating any
land belonging to another person is deemed to be a tenant if such
land is not cultivated personally by the owner. Land is said to be
cultivated personally if a (parcel of) land is cultivated on one’s own account
by labour of family members, i.e., spouse, children or siblings in case of a
joint family. A joint family is defined to mean an HUF and in case of other
communities, a group or unit the members of which are by custom joint in estate
or residence. In one case, even a married sister living with her husband has
been regarded as a part of the family – Case No. 8953 O/154 of 1954.
No land purchased by a tenant shall be transferred by him by way of sale, gift,
exchange, etc., without the previous sanction of the Collector. Rule 25A
provides the circumstances in which, and conditions subject to which, sanction
shall be given by the Collector u/s 43. One of them is for a gift in favour of
a member of the landowner’s family.


The Maharashtra Agricultural
Lands (Ceiling on Holdings) Act, 1961
imposes a ceiling on holding of
agricultural land in Maharashtra. Under section 4 of the Act, the ceiling on
the holding of agricultural lands is per ‘Family Unit’. This is a unique
and important concept introduced by the Act. It is very essential to have a
clear picture as to who is and who is not included in one’s ceiling computation
since that could make all the difference between holding and acquisition of the
land. A family unit is defined to mean the following – a person; his spouse or
more than one spouse if that be the case (thus, if a person dies leaving two or
more widows, then they would constitute one consolidated family unit for
considering the ceiling [State Of Maharashtra vs. Smt. Banabai and
Anr.(1986) 4 SCC 281];
his minor sons; his minor unmarried daughters;
and if his spouse is dead then the minor sons and minor unmarried daughters
from that spouse.


Thus, the married daughter of a
person, whether minor or major, would constitute a separate family unit and
hence any land held by such a daughter would not be included in computing the
ceiling of a person. This is the reason why many people transfer excess
agricultural land to their married daughters so as to exclude it from the
ceiling limits. Since a daughter is a relative u/s 56(2)(x) of the Income-tax
Act, the transaction is out of the purview of that section. Similarly, a
daughter is a relative under the Maharashtra Stamp Act, 1958 and hence a gift
of agricultural land to one’s married daughter attracts a concessional stamp
duty of Rs. 200 + 1% of the market value. Further, it is important to note that
a person’s parents are not included in his ceiling and hence, if either or both
of one’s parents are alive and holding land, then the same would not be
included in the person’s ceiling computation. Similarly, land held by one’s
major son and / or his wife is not included in a person’s ceiling computation.


Benami
Act

The Benami Property Transactions Act,
1988 is an Act which has gained a lot of prominence of late. Attachment orders
are being issued by the Competent Authority in respect of benami properties. In
such a situation, it becomes very important to understand what are the
exceptions to benami property. The Act provides for three situations when
property held for the benefit of relatives would not be treated as benami:


(i) Property held by a Karta, or a member of an HUF, as the case
may be, and the property is held for his benefit or the benefit of other
members in the family and the consideration for such property has been provided
or paid out of the known sources of the HUF;

(ii)  Property held by any individual in the name of his spouse / any
child of such individual and the consideration for such property has been
provided or paid out of the known sources of the individual; and


(iii) Property held by any person in the
name of his sibling or lineal ascendant / descendant, whose names and the
individual’s name appear as joint-owners in any document, and the consideration
for such property has been provided or paid out of the known sources of the
individual.


Rent
Act

The
Maharashtra Rent Control Act, 1999 defines a tenant to include, when the tenant
dies, any member of the tenant’s family who is residing with him in case of a
residential property. However, the Act does not define the term family member.
The Supreme Court in S.N. Sudalaimuthu Chettiar vs. Palaniyandavan, AIR
1966 SC 469
has defined the term family (in the context of an
agricultural land law) to mean ‘a group of people related by blood or marriage,
relatives’. Accordingly, the son-in-law was held to be a tenant since he was
residing with the tenant.


Accounting
Standards

For the purposes of the related
party definition, the Accounting Standards also give a definition of the term
relative. AS-18 on Related Party Disclosures defines it as an individual’s
spouse, child, sibling, parent who may be expected to influence or be influenced
by that individual in his / her dealings with the entity. On the other hand,
Ind AS 24 on Related Party Disclosures uses the term close members of the
family of a person and defines it to include the person’s children, spouse /
domestic partner, sibling, parent; children of that person’s spouse / domestic
partner and dependants of that person or his / her spouse / domestic partner.
Thus, the definition under Ind AS is much wider than the one found under Indian
GAAP.


IBC,
2016

The latest law to come out with its
own definition of the term ‘relative’ is the Insolvency and Bankruptcy Code,
2016 as amended by the 2018 Amendment Act. The Act provides that a relative of
a person or his spouse would constitute a related party in relation to that
person. The list of relatives included by the Code for this purpose is very
long:

(i)    members
of an HUF

(ii)    spouse

(iii)   parents

(iv)   children

(v)   grandchildren

(vi)   grandchild’s children

(vii)  siblings

(viii)  sibling’s children

(ix)   parents of either parent

(x)   siblings of either parent 

(xi)  wherever the relation is that of a son, daughter, sister or
brother, their spouses are also included in the definition of relative.


CONCLUSION

Perhaps
the time has come to subsume all these definitions into one consolidated
definition of the term ‘relative’ which could be used in all laws rather than
each legislation coming up with its own definition. However, having said that,
it is also true that what may be good for one law may not be so for another
law. Hence, a very long list of relatives may be beneficial under taxing
statutes but not so under regulatory statutes, such as the Companies Act since
it would increase the number of ineligible persons. However, an effort must be
made to strike a balance and arrive at a consolidated definition. Till that
time, the word ‘relative’ would continue to be a relative term!

DISCLOSURE OF PROMOTER AGREEMENTS: SEBI’S NDTV ORDER

SEBI recently passed an
order against some promoters of New Delhi Television Limited (NDTV). Under the
order dated 14th June, 2019, it debarred certain promoters from dealing in and
accessing the securities markets, acting as directors in listed companies, etc.
The order concerns itself with certain loan and related agreements the terms of
which were not disclosed to the public. SEBI held that such non-disclosure is
fraudulent and harmful to the interests of the public / shareholders. The order
raises wider concerns since this is a common issue. The question would be
whether there is adequate disclosure of terms of shareholders’ agreements and
similar agreements by major shareholders / promoters of listed companies. On
appeal, the Securities Appellate Tribunal on 18th June, 2019 stayed the SEBI
order for the time being.


The bone of contention was
the loans taken by a promoter company under certain terms from two successive
lenders. These terms fell into broadly two categories: One is the grant of
convertible warrants to the second lender such that they could effectively
become almost 100% owners of the promoter company. The second relates to
certain clauses whereby the promoters were obliged to take prior written
permission of the lender before carrying out specified acts in NDTV. This,
according to SEBI, amounted to giving powers to the lender to take decisions in
NDTV. However, these agreements were not disclosed to NDTV or the public in
general. According to SEBI, this amounted to non-disclosure of price-sensitive
information and also fraud, and thus passed the adverse directions against
three promoters.


As stated earlier, some of
the terms are commonly a part of agreements entered into by promoters /
companies. This order ought to be of wide concern since it may lead to charges
of non-disclosure or incomplete disclosure and thus result in serious adverse
consequences.


BACKGROUND AND FACTS

The relevant promoters of
NDTV were RRPR Holdings Pvt. Ltd. (RRPR) and Dr. Prannoy Roy / Ms Radhika Roy
(together the Roys). The Roys owned RRPR. They held in the aggregate during the
relevant time about 61 to 63% of the equity shares of NDTV. It appears that
RRPR had taken some loans from ICICI Bank Limited. To repay those loans, it
took certain loans from Vishwapradhan Commercial Private Limited (VCPL). The
terms of the loans from ICICI Bank and VCPL and the transactions related to the
loans were the areas of concern.


After carrying out certain
internal sale / purchase transactions, RRPR ended up holding 30% shares in
NDTV. As a part of the loan transaction terms with VCPL, share warrants were
issued to VCPL whereby, if such share warrants were fully exercised, VCPL would
hold 99.99% shares in RRPR. Effectively, it would thus become 100% owner in
RRPR. Certain connected agreements also gave an option to associate companies
of VCPL to acquire in aggregate 26% of NDTV from RRPR.


Further, the loan agreements
between RRPR / the Roys and ICICI / VCPL provided for certain terms relating to
the management of NDTV. Several specified important decisions could not be
taken in NDTV without the prior written approval of VCPL. RRPR and the Roys
were required to exercise their shareholding in NDTV to ensure that decisions
in NDTV are not taken in violation of these terms.


THE ALLEGATIONS

SEBI stated that the
promoters did not make the required disclosures of these transactions and
terms. The information was price-sensitive and would have affected the
decisions of the investors / public. SEBI alleged that this non-disclosure was
fraudulent in nature.


The terms of the agreement
whereby share warrants were issued to VCPL amounted for all practical purposes
to transfer of the shares in NDTV by the promoters. Further, agreeing to terms
whereby certain important decisions in NDTV would require prior approval of
ICICI / VCPL also amounted to information that shareholders / public ought to
know. Effectively, decision-making power was transferred / shared with certain
persons of which the public did not have knowledge. They would be looking at
the Roys as the persons in charge.


Thus, multiple provisions
of the SEBI Act and the SEBI PFUTP Regulations were alleged to have been violated
by entering into such transactions without due disclosures.


THE DEFENCE OFFERED BY THE PROMOTERS

The promoters denied the
allegations. They claimed that the loan agreement was a private one and had
nothing to do with NDTV. NDTV was not bound by the terms of the agreement.
Hence, the terms agreed upon did not affect NDTV and thus the public /
shareholders.


Further, it was contended
that these were standard terms in loan agreements.


Importantly, a distinction
was made between their role as shareholders and as directors. It was stated
that they were free to do what they wanted as shareholders in respect of their
shares. They stated that their acts as private shareholders did not conflict
with their role as directors. In any case, they were in the minority on the
board as there were so many other directors.


SEBI’S CONCLUSIONS AND ORDER

SEBI did not agree with
the defence offered by the promoters. It held the agreements were not bona
fide
loan agreements, and indeed were a sham to that extent. Such long-term
loans without interest and without any terms of repayment are not entered into
in the ordinary course of business. The loan agreement was, SEBI concluded, a
sale agreement.


The right of ICICI / VCPL
under the agreement to participate in certain important decisions was vital
information that the promoters should have disclosed to NDTV and the public.
SEBI also rejected the distinction made by the promoters between their role as
shareholders and as directors.


SEBI also rejected the
contention that as just two directors on the Board of NDTV, they could not have
influenced the decisions of NDTV. SEBI noted, ‘This contention is not tenable
in view of the fact that Noticee No. 2 is not only the Director of NDTV but is
the Chairman of the Board of the Company. Secondly, Noticee No. 2 and 3 were
not only the Chairman and Managing Director, respectively, but along with
Noticee No. 1, which is a private limited company of Noticee No. 2 and 3, were
also the promoters and majority shareholders, holding majority voting rights in
NDTV. Therefore, it is inconceivable that Noticee No. 2 and 3 were incapable of
ensuring compliance with the conditions to which they had agreed under the loan
agreements with respect to the affairs of NDTV.’


Further, SEBI pointed to
the code of conduct of NDTV to which the Roys were subject. As per this code,
they were not supposed to put themselves in a position of conflict with the
company. Yet, by entering into such a loan agreement, they had placed
themselves in such a position.


SEBI noted that the Roys
had entered into off-market transactions in the shares of NDTV. Thus, they
dealt in shares of NDTV without disclosing relevant information to the public
who dealt in shares without having such information. SEBI observed, ‘In the
absence of availability of material information relating to VCPL Loan
Agreements 1 and 2 in the public domain, investors were not in a position to
take any informed decision while dealing in the scrip of NDTV. Hence, by
concealing such material information from the public shareholders during the
relevant period when the promoters themselves were dealing in shares of the
company, Noticees have allegedly committed fraud on the minority public
shareholders of the company.’


The terms of the loan
agreement, SEBI noted, apart from being very liberal, were strange. The share
warrants could be converted even after the repayment of the loan. Thus, the
lender could become effectively the owner of RRPR and hence the 30% shares in
NDTV even after repayment of the loan. Thus, it noted, ‘It is not a loan
transaction simpliciter. It appears an outright transfer of 30% stake and
voting rights in NDTV by the Noticees masquerading as a loan agreement which
did not even possess the basic attributes of a normal secured loan transaction.
In my view, the VCPL Loan Agreements 1 and 2 are sham loan transactions
executed by the Noticees only with a motive to sell their substantial stake in
NDTV.’


Accordingly, SEBI ordered
as follows: RRPR and the Roys were debarred from accessing the securities
markets, buying / selling securities or being associated with the securities
markets for two years. Their existing securities, including mutual fund units,
were frozen during this period. The Roys were also debarred from occupying
positions as Director or Key Managerial Personnel in NDTV for two years and in
any other listed company for one year.


APPEAL TO SAT AND STAY

The promoters immediately
appealed to SAT, which has stayed the order for the time being pending final
disposal. SAT held that the conclusions drawn by SEBI need to be examined in
more detail and a company such as NDTV cannot be kept headless in the meantime.
This would be harmful to NDTV and also its shareholders.


IMPLICATIONS AND CONCLUSIONS

It is very common for
parties to enter into shareholders’ and similar or related agreements with
investors / lenders. Certain rights are given to them that include taking their
approval for specified major matters. The SEBI LODR Regulations now do have a
requirement of making disclosures of such agreements. However, this order would
be an eye-opener for parties who would have to ensure that due disclosures are
made. The present case related to events in and around 2008-2010. There may
thus be concerns that even agreements entered into in the distant past may be
covered and SEBI may take action if these have not been disclosed.


Though the facts of this
case are peculiar and though the matter is under appeal, a closer look is
required by companies and promoters to their own cases. It is also suggested
that SEBI itself comes out with clearer directions on this and gives time to
promoters / companies to make specific disclosures, irrespective of what has
happened in the past.

ACCOUNTING FOR CRYPTOCURRENCY

In June, 2019 the IFRIC decided on
the interesting issue of accounting for cryptocurrency. The IFRIC applies to
cryptocurrency that has the following characteristics:


i.   a
digital or virtual currency recorded on a distributed ledger that uses
cryptography for security;

ii.   not
issued by a jurisdictional authority or other party; and

iii.  does not give rise to a contract between the holder and another
party.


Ind AS 38 Intangible Assets
applies in accounting for all intangible assets except:


a. those that are within the scope
of another Standard;

b. financial assets, as defined in
Ind AS 32 Financial Instruments: Presentation;

c. the recognition and measurement
of exploration and evaluation assets; and

d. expenditure on the development and extraction of minerals, oil, natural
gas and similar non-regenerative resources.


A financial asset is any asset that
is: (a) cash; (b) an equity instrument of another entity; (c) a contractual
right to receive cash or another financial asset from another entity; (d) a
contractual right to exchange financial assets or financial liabilities with
another entity under particular conditions; or (e) a particular contract that
will or may be settled in the entity’s own equity instruments.


Cash is a financial asset because
it represents the medium of exchange and is therefore the basis on which all
transactions are measured and recognised in financial statements. A deposit of
cash with a bank or similar financial institution is a financial asset because
it represents the contractual right of the depositor to obtain cash from the
institution or to draw a cheque or similar instrument against the balance in
favour of a creditor in payment of a financial liability. Consequently, cash is
expected to be used as a medium of exchange (i.e. used in exchange for goods or
services) and as the monetary unit in pricing goods or services to such an
extent that it would be the basis on which all transactions are measured and
recognised in financial statements.


Though some cryptocurrencies can be
used in exchange for goods or services, they are not used to such an extent
that it would be the basis on which all transactions are measured and
recognised in financial statements. Consequently, in the present times
cryptocurrency is not cash.
Neither is a cryptocurrency an equity
instrument of another entity. It does not give rise to a contractual right for
the holder and it is not a contract that will or may be settled in the holder’s
own equity instruments.


Ind AS 2 Inventories applies
to inventories of intangible assets. Paragraph 6 of that Standard defines
inventories as assets:


1.  held
for sale in the ordinary course of business;

2.  in
the process of production for such sale; or

3.  in
the form of materials or supplies to be consumed in the production process or
in the rendering of services.


If an entity holds cryptocurrencies
for sale in the ordinary course of business, the general requirements of Ind AS
2 apply to that holding. However, a broker-trader of cryptocurrencies, who buys
or sells commodities for others or on their own account, will measure their
inventories at fair value less cost to sell [Ind AS 2.3(b)].


IFRIC CONCLUSION

Paragraph 8 of Ind AS 38 defines an
intangible asset as ‘an identifiable non-monetary asset without physical substance’.
Paragraph 12 of Ind AS 38 states that an asset is identifiable if it is
separable or arises from contractual or other legal rights. An asset is
separable if it ‘is capable of being separated or divided from the entity and
sold, transferred, licensed, rented or exchanged, either individually or
together with a related contract, identifiable asset or liability’. Paragraph
16 of Ind AS 21 The Effects of Changes in Foreign Exchange Rates states
that ‘the essential feature of a non-monetary item is the absence of a right to
receive (or an obligation to deliver) a fixed or determinable number of units
of currency’. IFRIC concluded that a holding of cryptocurrency meets the
definition of an intangible asset in Ind AS 38 because (a) it is capable of being
separated from the holder and sold or transferred individually; and (b) it does
not give the holder a right to receive a fixed or determinable number of units
of currency. IFRIC also concluded that Ind AS 2 applies to cryptocurrencies
when they are held for sale in the ordinary course of business. If Ind AS 2 is
not applicable, an entity applies Ind AS 38 to holdings of cryptocurrencies.


In addition to other disclosures
required by Ind AS Standards, an entity is required to disclose any additional
information that is relevant to an understanding of its financial statements
(paragraph 112 of Ind AS 1 Presentation of Financial Statements). An
entity provides the disclosures required by (i) paragraphs 36–39 of Ind AS 2
for cryptocurrencies held for sale in the ordinary course of business; and
(ii) paragraphs 118–128 of Ind AS 38 for holdings of cryptocurrencies to which
it applies Ind AS 38. If an entity measures holdings of cryptocurrencies at
fair value, paragraphs 91–99 of Ind AS 113 Fair Value Measurement
specify applicable disclosure requirements.


Applying paragraph 122 of Ind AS 1,
an entity discloses judgements that its management has made regarding its
accounting for holdings of cryptocurrencies if those are part of the judgements
that had the most significant effect on the amounts recognised in the financial
statements. Paragraph 21 of Ind AS 10 Events after the Reporting Period
requires an entity to disclose details of any material non-adjusting events,
including information about the nature of the event and an estimate of its
financial effect (or a statement that such an estimate cannot be made). For
example, an entity holding cryptocurrencies would consider whether changes in
the fair value of those holdings after the reporting period are of such significance
that non-disclosure could influence the economic decisions that users of
financial statements make on the basis of the financial statements.


FORTHCOMING
EVENTS

COMMITTEE

EVENT NAME

SPEAKER

DATE

VENUE

NATURE OF EVENT

FEES

BCAS
FOUNDATION

Jointly with PCGT &
DBM

4th Late Shri
Narayan Varma Memorial Lecture

Mr. Yazdi Malegam

Friday 23rd
August 2019

4th Floor IMC
Hall Churchgate

Lecture Meeting

Free for All

Taxation
Committee

Seminar on Tax Audit

Various Speakers

Friday 23rd
August 2019

BCAS Hall

Seminar

Members:
Rs. 2,065/-


Non-Members: Rs. 2,596/-

study circle

Managing
Committee

Suburban Study Circle
Meeting on “15 CB
Certification – Who, What, When and How”

CA Rutvik Sanghvi

Tuesday, 13th
August, 2019

910, Hubtown
Solaris, C/o
Bathiya & Associates LLP, N. S. Phadke Road,

Andheri (E),
Mumbai 400069

Study Circle


Free for Members


Rs. 300/- for Non-Members


International
Taxation
Committee

GAAR – Case Studies &
It’s Practical Issues

CA Bhaumik Goda

Thursday – 22nd

 August, 2019 from 6.15 p.m. to 8 p.m.


BCAS Hall

Study Circle

Yearly Subscription for BCAS Members –
Rs. 1,180/-


Rs. 118/- for non-members each session.

PERSONAL RESPONSIBILITY OF DIRECTORS UNDER VAT / GST

INTRODUCTION

As per normal
understanding, the directors are not liable for any dues of the company.
Limited companies are basically formed to limit the financial liabilities to
the extent of the assets of the company. However, in spite of such a legal
position, an attempt is made by the authorities to cast liability on the
directors. Normally, directors of a public limited company are not covered for
personal recovery even by any specific provision. However, there may be
specific provisions for casting liability on the directors of a private limited
company. For example, under the Maharashtra Value Added Tax Act, 2002, section
44(6) provides for personal liability of directors of a private limited
company. The said section is reproduced below for ready reference:


‘(6) Subject
to the provisions of the Companies Act, 2013 (18 of 2013), where any tax or
other amount is recoverable under this Act from a private company, whether
existing or wound up or under liquidation, for any period, (but) cannot be
recoverable, for any reason whatsoever, then, every person who was a director
of the private company during such period shall be jointly and severally liable
for the payment of such tax or other amount unless he proves that the
non-recovery cannot be attributed to any gross neglect, misfeasance or breach
of duty on his part in relation to affairs of the said company.’


It can be seen
that the liability of the directors is not blanket but subject to conditions.
In other words, if the director proves that there was no gross negligence,
misfeasance or breach of any duty, then no liability can be attracted. However,
there is also a possibility that the Revenue may try to initiate recovery from
a director in spite of there being no such negligence, etc. on the part of the
director.


DECIDED CASES

There are a
number of judgements wherein the Hon’ble Courts have held that the corporate
veil cannot be lifted for recovery of tax dues unless there are specific
provisions. Reference can be made to the judgement of the Uttarakhand High
Court in the case of Jagteshwar Prasad Bansal & others vs. State of
Uttarakhand
& others (59 GSTR 491) (Uttarakhand). In
this case, the sales tax department tried to recover dues from the directors of
the company, although in the relevant Uttarakhand Value Added Tax Act there was
no specific provision for recovery from a director. However, the department
wanted to lift the corporate veil. The High Court rejected the action of the
sales tax authorities. It held that unless there is any fraud or he / she is
guilty of misrepresentation, the corporate veil cannot be lifted. In the above
judgement, the Court has referred to an earlier judgement in the case of Meekin
Transmission Ltd. vs. State of Uttar Pradesh (58 VST 201) (All.) and
reproduced the following observations of the Allahabad High Court:


‘The legal
position as discerned from the above is that in a case where the corporate
personality has been obtained by certain individuals as a cloak or a mask to
prevent tax liability or to divert the public funds or to defraud public at
large or for some illegal purposes, etc., to find out as to who are those
beneficiaries who have proceeded to prevent such liability or to achieve an
impermissible objective by taking recourse to corporate personality, the veil
of the corporate personality shall be lifted so that those persons who are so
identified are made responsible. However, this doctrine is not to be applied as
a matter of course, in a routine manner and as a day-to-day affair so as to
recover the dues of a company, whenever and for whatever reason they are
unrecoverable, from the personal assets of the directors. If such a course is
permitted, it would lead to not only disastrous results but would also destroy
completely the concept of juristic personality conferred by various statutes
like the Act in the present case and would make several enactments and their
effect to be redundant and illusory.


Moreover, the
shallowness of arguments in favour of making directors personally responsible
can be considered from another angle. In every case the director may not be a
shareholder of the company. He may have been appointed as director for taking
advantage of his expertise in his field of vocation or profession, and for
achieving goals for which the company is incorporated. Such director is paid
remuneration, if any, for the services he rendered. Otherwise he is not at all
a beneficiary of the business or trade, etc., as the case may be, in which the
company is engaged. Such benefit would be available only to the shareholders as
they would only be entitled to share the profits earned by the company in the
form of dividends as decided by the Board of Directors. In such case such
director, though an agent of the company, he is more in the nature of an
officer of the company and not in the capacity of limited ownership by way of
shareholding. Such a director, in our view, unless guilty of misfeasance, fraud
or acting
ultra vires, we are not able to understand
as to how he can be made responsible personally for the dues of the company even
if we apply the doctrine of piercing the veil.


If in such a
case the veil is to be lifted, the persons behind the veil, at the best, would
be the promoters of the company or those who have sought to obtain corporate
personality as a sham or bogus transaction. Similarly, in some of the companies
the financial institutions, who advance funds as loan, etc., nominate their
director/s to keep some kind of monitoring over the functions of the company so
that it may not go in liquidation on account of negligent and careless function
of the Board of Directors. Such directors also, in our view, cannot be included
in the category of the persons who would be responsible personally for the dues
of
the company.


In order to
find out as to who are the persons responsible personally when the veil is
lifted it would be wholly irrelevant as to whether such person is a director or
a promoter shareholder or otherwise of the company since the purpose of lifting
the veil is to find out the person/s who is operating behind the corporate
personality for his personal gain. Such person may be an individual or group of
persons belonging to a family or relatives or otherwise a small group collected
with a common objective of achieving some illegal, immoral or improper purpose,
etc. So long as no investigation is made into various aspects, we are not able
to understand as to how and in what manner a director of a company can
straightway be proceeded (against) personally for recovering dues of a company
unless it is so provided by some provision of the statute.’


The
observations clearly show that unless there is fraud or deliberate misrepresentation,
the corporate veil cannot be lifted to make the directors personally liable.


In the above
judgement, there was no specific provision about recovery from the director of
a Pvt. Ltd. Co. However, even where there is specific provision about recovery
from a director of a Pvt. Ltd. Co., like section 44(6) of the MVAT Act
reproduced above, still recovery is subject to proving negligence, etc. In
other words, the said provision is also in the nature of lifting the corporate
veil. The observations made above will equally apply in case of a specific
provision also.


In view of the
above legal position it can be inferred that whether there is specific
provision or not about recovery from directors, the recovery is subject to
positive involvement for dues by the director, like fraud, etc.


POSITION UNDER GST

Though the
above position is decided in light of the provisions under the VAT regime, the
ratio will equally apply under GST, too. Under GST, there is specific provision
for recovery from directors like section 89 that provides for liability of a
director. The section reads as under:


‘89. (1) Notwithstanding anything contained in the Companies Act,
2013, where any tax, interest or penalty due from a private company in respect
of any supply of goods or services or both for any period cannot be recovered,
then, every person who was a director of the private company during such period
shall, jointly and severally, be liable for the payment of such tax, interest
or penalty unless he proves that the non-recovery cannot be attributed to any
gross neglect, misfeasance or breach of duty on his part in relation to the
affairs of the company.’


Thus, the
provision is similar to section 44(6) of the MVAT Act. The issue of negligence,
etc. is also applicable under GST. The guidelines and observations mentioned in
earlier judgements will be useful for deciding cases under GST also.


CONCLUSION

Normally, limited companies are formed to restrict
personal liability. However, the laws are now being made to make the directors
personally liable. Though the said provisions are for safeguarding the revenue
in case directors play a fraud, the Revenue authorities try to apply them
summarily in all cases. It is expected that such specific provisions should be
applied only in specific cases, that also after observing principles of natural
justice and complying with requirements of the relevant section. 

REAL ESTATE DEVELOPMENT – A ‘REAL’ CONUNDRUM

GST law has recently overhauled the entire taxation scheme of
real estate development activities. Amidst discussions over inclusion of real
estate in the GST fold, the 33rd GST Council made the following broad
announcements on real estate development activities:


a)   GST to be levied at 5% on regular and 1% on
affordable housing (‘final taxes’), without any input tax credit (ITC).
Apartments up to 90 / 60 square metres in non-metro / metro cities having gross
sale value below Rs. 45,00,000 are considered as ‘affordable residential apartments’;

b)   Tax on
development rights / TDR / JDA, lease premium, FSI (‘intermediate taxes’) are
to be exempted for apartments sold pre-completion, and taxable where apartments
are sold after completion, in other words, intermediate taxes would be payable
if final taxes are not applicable.


The
philosophy behind the recommendations was stated as follows:


“i. The
buyer of house gets a fair price and affordable housing gets very attractive
with GST @ 1%;

ii. Interest of the buyer / consumer gets
protected; ITC benefits not being passed to them shall become a non-issue;

iii.
Cash flow problem for the sector is addressed by exemption of GST on
development rights, long-term lease (premium), FSI, etc.;

iv.
Unutilised ITC, which used to become cost at the end of the project, gets
removed and should lead to better pricing;

v. Tax
structure and tax compliance becomes simpler for builders.”


In view of limitations in bringing
the said amendments through primary enactments, the 34th GST Council
adopted the route of issuing notifications to give effect to the said
decisions. The modalities of the scheme were carried out by rate notifications
and other procedural amendments. The rate notifications are the subject matter
of discussion in this article:

Notification 3/2019 – CT(R): Beneficial rates for pure
and mixed residential real estate

CGST sections invoked – 9(1), 9(3), 9(4), 11(1), 15(5),
16(1), 148

Clause

Service description

Effective
tax rate1

Conditions

3(i)

Affordable residential apartment in RREP2  in new / ongoing projects3

1%

NOTE 1

3(ia)

Regular residential apartment in RREP in new projects /
ongoing projects

5%

3(ib)

Commercial apartments in RREP in new projects / ongoing
projects

5%

3(ic)

Affordable residential apartment in REP in new projects /
ongoing projects

1%

3(id)

Regular residential apartment in REP in new projects /
ongoing projects

5%

3(ie)

Affordable residential housing under ongoing projects of
Govt.-specified housing schemes (such as JNNURM, PMAY, etc.) where higher
rate option exercised

8%

NOTE 2

3(if)

All other construction services including commercial
apartments in REP; residential apartments for ongoing projects where option
to continue in old scheme is exercised

12%

3(va)

Works contract service for affordable residential apartments
of new / ongoing projects

12%

NOTE 3

____________________________________________________

1    These rates are aggregate GST rates after
considering the ad hoc land deduction of 33.33%

2    RREP represents a real estate project where
carpet area of commercial apartment is not more than 15%. An REP represents all
the other real estate projects as covered by the RERA law

3    Ongoing projects
represent those cases where commencement certificate has been issued prior to
01-04-2019, actual construction has commenced, the project has not received its
completion / occupancy certificate and at least one apartment has been booked
in such a project. New projects are those which commence after 01-04-2019


Note 1: Cumulative
conditions for the beneficial rate of 1% / 5%

i.    The
taxes should only be paid in cash and not by ITC;

ii.    ITC on goods and services has not been
availed except to the extent of the completed construction activity / supply as
specified in Annexure I / II of the notification. Adverse variance between
computed and availed ITC should be paid either by credit / cash. Favourable
variance permits the developer to take additional ITC to meet the shortfall;

iii.   Landowner’s
area share4 – Developer to pay the tax on constructed area and the
landowner would be entitled to ITC only against taxable supplies (i.e.,
pre-completion supplies);

___________________________________________________

4    Landowner
promoter is the person who transfers land / development rights / FSI to a
developer promoter against area share in the project


iv.   80/20
rule – 80% of input / input services (other than grant of development rights /
lease premium, FSI, etc., electricity, diesel / petrol, etc.) are from
registered persons. Shortfall is liable to tax @ 18% on reverse charge basis
(RCM). In case of cement, it is expected that the entire material is purchased
from registered persons and any shortfall on this front would be liable to tax
@ 28%. The tax liability on account of the shortfall of RCM would have to be
paid by the end of the quarter following the financial year. In case of cement,
the tax would have to be paid in the same month itself;

v.   Project-wise
computations and accounts to be maintained to justify compliance of above
conditions. ITC not availed is required to be reported in the specified column
of GSTR-3B as being ineligible ITC.


Note 2: Conditions
for continuing with the regular rate of 8% / 12% for ongoing projects

i.    It
is mandatory to exercise the option of continuing in old scheme within the
specified time limit of 10th May, 2019 (extended up to 20th
May, 2019). Where the option is not exercised, the new rates / conditions would
automatically be considered as applicable.


Note 3: Conditions
to be satisfied by works contractor

i.    Aggregate
carpet area of affordable residential apartments is more than 50% of the total
carpet area of all apartments.

ii.    In
cases where the above threshold drops below 50%, the beneficial rate would be
denied and developer would have to repay the differential tax on reverse charge
basis

Notifications
4/2019 –CT(R): Exemption to intermediate taxes subject to RCM

CGST sections invoked – 9(1), 9(3), 9(4), 11(1), 15(5),
16(1), 148

Description of services

Amount

Conditions

Services by way of transfer of development rights / FSI on or
after 01-04-2019 for construction of residential apartments intended for sale
prior to completion of the project

Proportionate

Note 4

Upfront lease premium in respect of long-term lease of 30
years or more after 01-4-2019 for construction of residential apartments
intended for sale prior to completion of the project

Proportionate


Note 4: Cumulative
Conditions for the exemption

i.    Exemption
would be limited to the proportionate residential carpet area of the project;

ii.    Developer
would be liable to repay the tax under reverse charge on the proportionate
value of flats remaining unbooked as on date of issuance of completion
certificate. The tax payable is limited to 1% of value of unbooked affordable
and 5% of booked regular residential apartments, i.e., extent of final taxes
otherwise applicable prior to completion;

iii.   The
above liability would be payable on the date of completion / first occupation
of the project, whichever
is earlier;

iv.   Value
of the above services would be the fair market value of residential /
commercial area allotted to the transferor of development rights / FSI nearest
to date of allotment.


Notifications
5/2019 – CT(R): RCM of
intermediate taxes

CGST sections invoked – 9(3)

Description of services

Service provider (e.g.)

Service recipient

Services by way of transfer of development rights / FSI, etc.

Landowner

Developer

Upfront lease premium in respect of long-term lease or
periodic rent for construction

Development authority

Developer


Notifications 6/2019 – CT(R):
Special procedures for developers (Section 148):
Developers receiving
development rights / long-term lease of land on or after 1st April,
2019 would be granted ‘deferment’ of payment of RCM taxes up to issuance of
completion certificate or first occupation, whichever is earlier.


Notifications 7/2019 and 8/2019 –
CT(R) (Section 9(4), 15(5)):
Enabling notifications for payment of RCM on
procurements from unregistered persons beyond the 80/20 rule. The notifications
also provide for RCM on procurement of all capital goods from unregistered
persons and such goods do not form part of the
80/20 rule.


KEY CONCEPTUAL CHALLENGES UNDER NEW SCHEME

Without going into the
constitutionality and / or the vires of the statute to tax real estate
transactions, including development rights / TDRs, FSI, lease premium, etc.,
the key conceptual issues under the new scheme have been discussed herein:


Issue 1 – Whether the real
estate notification(s) is a rate notification / exemption notification? If it
is a rate notification, is it permissible to place conditions in rate
notifications?

Unlike VAT / Excise / Service tax
laws where the base rates are statutorily fixed with exemption powers being
delegated to the Government, the GST law has delegated both the rate fixation
(u/s 9[1]) and exemption powers (u/s 11[1]) to the Government(s) which gives
rise to the confusion over the powers which are being invoked while prescribing
tax rates.


Rate fixation (commonly termed as
tariff / scheduled rate) is an absolute power u/s 9(1). The section requires
the Government to notify tax rates on all supplies with a cap of 40%. Once the
tariff rates are fixed, tax payers are bound by it with absolutely no
flexibility. Section 11(1) then permits the Government to grant exemptions (a)
wholly or partly; (b) in public interest; and (c) with or without conditions.
An exemption always presupposes a fixed base rate. Notifications under both
these sections have to be backed by recommendations from the GST Council.


In this context, the Supreme Court in
Associated Cement Company vs. State of India & others (2004) 7 SCC
642
had stated as follows:


The question of exemption arises
only when there is a liability. Exigibility to tax is not the same as liability
to pay tax. The former depends on charge created by the Statute and latter on
computation in accordance with the provisions of the Statute and rules framed
thereunder if any. It is to be noted that liability to pay tax chargeable under
Section 3 of the Act is different from quantification of tax payable on
assessment. Liability to pay tax and actual payment of tax are conceptually
different. But for the exemption the dealer would be required to pay tax in
terms of Section 3. In other words, exemption presupposes a liability. Unless
there is liability question of exemption does not arise. Liability arises in
terms of Section 3 and tax becomes payable at the rate as provided in Section
12. Section 11 deals with the point of levy and rate and concessional rate.


This decision implies that the
Governments ought to fix the base rate liability for the public at large and
then proceed to grant exemptions in specific circumstances. In GST, the rate
fixation powers are absolute powers with an upper cap of 40%. It appears that
the Governments have thoroughly mixed both these distinct and independent
powers and notifications are issued for effective rates without any base rate
fixation. If one were to examine the GST Council discussions until 1st
July, 2017, the agenda of rate fixation culminated into the said rate slabs –
5%(necessities), 12% (processed commodities), 18% (standard commodities and
services), 28% (luxury products) and NIL rate. The entire exercise of rate
fixation by the fitment committee after the 14th Council meeting
also categorised the rates into the above five rates only. In respect of
services, rates were fixed for taxable services keeping in mind the erstwhile
service tax rates and with majority of the service tax exemptions being
adopted. Therefore, the consensus over services was to tax them at a base rate
of 18% with concessions being given for specific categories.


Let’s take a look at the
notifications issued at the inception of GST which define the rate / exemption
structure:
N– 01/2017 fixed rates for goods u/s 9(1) – this contained a basket of four
rates, i.e., 5% / 12% / 18% and 28%;
N–02/2017 exempted goods u/s 11(1) containing all the NIL rated goods; N–11/2017
was issued u/s 9(1) and 11(1) providing service tax rates between 5%-28% – each
four-digit SAC classification (adopted from the internationally-accepted
standards) was assigned a single rate and in case there were multiple rates
under a single four-digit SAC, the SAC generally contained a residual category
with 18% rate; and N–12/2017 was issued u/s 11(1) exempting services with or
without conditions. The above actions of the GST Council and Governments convey
that services generally had a base rate of 18% and goods had a base rate under
five categories as proposed by the fitment committee.


However, the legal process adopted by
the Governments over rate fixation poses a serious question over all
notifications and in particular the subject real estate notifications which
have prescribed rates and corresponding conditions. The real estate
notification contains various conditions w.r.t. input tax credit, RCM payment,
landowner terms, etc. Placing conditions in rate notifications is clearly not
permissible u/s 9(1). Though the notification also spells out section 11(1) as
its source of power, the above verdict of the Supreme Court presupposing a base
rate liability would come into play. Consequently, ‘conditions’ under the real
estate notifications may be read down as beyond statutory powers.


The alternative view would be that
the Government(s) being the custodian of both powers can choose to combine the
powers and notify the effective tax rates rather than duplicating the process.
While this is certainly alien to indirect tax legislation, it is a possible
view that can be adopted to validate the actions of the Council /
Government(s). In such a scenario, the residuary entry specifying the peak rate
under each service heading could be termed as a base rate, i.e., cases where
the conditions of the specific entry are violated, one may be relegated to the
residuary entry.


Issue 2 – Whether the new real
estate scheme is optional / mandatory?

The new scheme with drastic reduction
in tax rates appears to be highly beneficial from a customer’s standpoint but
raises cost arithmetic of the developer (due to ITC restrictions) requiring a
change in the base price to consumers. This mathematical problem poses a
question whether this new scheme is mandatory at all.


The GST Council and press releases
suggest that the new scheme is mandatory for all new projects and ongoing
projects where the option to continue under the old scheme is not exercised.
The original entry has been completely substituted with this new entry and the
residuary entry specifically excludes services specified in the table from its
ambit.


The issue is also inter-linked with
the fundamental issue of whether N–03/2019 is a ‘rate notification’ or an
‘exemption notification’. It is settled law by the Supreme Court that rate
specifications are mandatory and conditional exemptions are optional.


A cursory view of N–03/2019 clearly
depicts that the notification emerges from ‘public interest’ (refer press
release), contains conditions for availment and has limited its applicability
based on certain parameters (such as flat area, REP conditions, project start
date, etc.). Though both section 9(1) and 11(1) have been invoked, Governments
would certainly be placed in a tricky situation while defending the real estate
rates as being a compulsory levy (as a tariff) or an optional levy (as an
exemption). Where it is contended that the levy is compulsory, all conditions
(such as ITC, RCM, etc.) then stand as a violation of section 9(1) and where it
is contended that the said notification is an exemption with prescriptive
conditions, the notification would be treated as optional.


The implication of treating the entry
as being an exemption also raises a parallel question over the base rate. The
answer to this may probably lie in the residual entry (clause xii) which taxes
services at 18% if not classified elsewhere (though the explanation bars
classification for all the aforesaid real estate entries).


Issue 3 – Can a notification
take away validly availed ITC on transition?

N–03/2019-CT(R) requires the
developer to re-state the ITC balance as on 1st April, 2019 for new
and on-going projects under the beneficial rate scheme based on futuristic
arithmetical formulation. Annexure I and II of the said notification specify
the ITC to be retained / repaid based on an extrapolatory formula once the
beneficial rates are availed. The intent is to deny dual benefit of low tax
rate and ITC during the transitory phase, especially where percentage of
construction and percentage billing are at variance.


In
simple terminology, the formula attempts to extrapolate the actual ITC availed
on inputs or input services (whether utilised or not) up to 31st
March, 2019 to a statistical number until project completion. This is then
proportionately reduced for residential or commercial apartments booked prior
to 1st April, 2019 to the extent of instalments collected from such
apartment buyers. For example, Rs. 10 ITC on a project which is 10% complete is
extrapolated to 100 and then attributed to the value of advances for booked
apartments until 1st April, 2019 for which tax would have been
payable at the original rates. Assuming 20% flats are booked as on 1st April,
2019 and 25% of the advance has been collected, the restated ITC would be Rs. 5
(100*20%*25%). Since the developer has already availed Rs. 10, the balance Rs.
5 becomes repayable as excess ITC availed. If there is a shortfall, the
developer becomes entitled to take additional ITC to the extent of the
shortfall. In effect, ITC would be available only to the extent of value of
supply taxed at rate 8% / 12%.

The said formulation is based on
multiple statistical assumptions:

a)   Uniformity in ITC availment during the tenure
of the project;

b)   Similarity in the schedule of advance
payments from customers;

c)   Consistency on the pattern of construction by developer;

d)   Correlating percentage of invoicing with
percentage of construction completion;

e)   Accuracy of total project costs, etc.


In a transaction-based levy, has the
Government been empowered to restrict ITC based on statistical results? Is it
also empowered to retroactively reverse ITC rightfully availed and / or
utilised? The answer may probably be NO. The Supreme Court in various instances
has held that ITC rightly availed in compliance with statutory provisions on
the date of availment is as good as ‘tax paid’. It is an absolute right which
cannot be withdrawn, more so by delegated legislations. The Supreme Court has
also stated that ITC is a benefit / concession and hence statutory conditions
need to be strictly complied with.


The notifications have been issued
drawing powers from section 11(1) which permits prescription of certain
conditions for complete or partial exemptions. Explanation 4(iv) to the
notification requires that ITC is reversed as a condition to the availment of
the exemption. This seems to be the apparent source of power for the
Government.


But, section 17(1) and (2) specify
reversal of ITC only in cases of wholly exempt supplies and does not extend to
partially exempt supplies. The section also does not envisage any delegation of
powers for restricting ITC. Section 16-18 permits reversals of validly availed
ITC to the electronic credit ledger only through statutory provisions. However,
the notification requires reversal of ITC of both availed and utilised ITC. The
notification fails to appreciate that attribution of an input invoice
(especially services) to a taxable / exempt activity can be performed only at
the time of its availment and once the credit is rightfully availed, it loses
its original identity. Therefore any attempt to trace a credit after availment
/ utilisation to a taxable / exempt activity for purpose of reversal in
computations would be a futile and inaccurate exercise.


Another issue in this condition is
whether this reversal is ‘person specific’, ‘project specific’ and / or ‘period
specific’. While the notification says that the accounts are to be maintained
project-wise, the computation mechanism gives mixed views – for example, where
a project is taken over by a new developer, would the incoming developer have
access to this 80/20 criterion from project inception or from its take-over?
The formula certainly does not capture this scenario. What happens where there
is a shortfall in the 80/20 rule in initial years (due to sand / jelly
purchase) and sufficiently complied when viewed from a project level at its
finishing stages? The notification suggests that each year is independent on
this front. The press release states that the calculation has to be performed
project-wise and year-wise.


On the other hand, there is an
attempt (through amendments in Rule 42) to reverse credit based on ‘carpet
area’, a clear departure from the requirement of section 17 which specifies
‘value’-based computations. Rule 42 goes on to require reversal right from the
commencement of the project without considering the year of availment of the
credit. This clearly disturbs the uniform law that ITC is final by the end of
the September returns following the financial year closure. Real estate
projects which face delays crossing more than five years would be saddled with
the task of going back to the origin of the project. Thus, one school of
thought clearly raises red flags over the vires of the notification to
prescribe reversal of ITC from multiple fronts.


The other conservative school of
thought would be that real estate notifications are more akin to exemption
notifications and the powers of conditional exemptions are wide enough to
provide substantive and procedural conditions, and this would cover ITC
restrictions in any form even though not empowered under the ITC provisions.
Being an optional notification and having opted for the exemption, one may have
to strictly abide by the conditions of exemption or otherwise continue paying
tax at the higher rate.


Issue 4 – Whether imposition of
RCM under 80/20 procurement rules, booked / unbooked apartment ratio rule,
i.e., on future contingencies, is a sustainable legal condition?

80/20
procurement rule

N–07/2019 imposes RCM on the
developer where the procurements of the project from registered persons fall below
80%. Tax is to be paid at 18% on the shortfall on reverse charge basis except
for cement which is taxable at 28%. There is a requirement of apportionment of
credit exclusively to commercial segment at standard rate, commercial segment
at beneficial rate, residential segment at beneficial rate, common credits and
then test the same at the project level. This condition has certain
shortcomings:


a.   This
condition is based on an outcome which may be known only at the end of the
financial year;

b.   In
a transaction levy regime where ‘supply’ has to be identified, it appears to
defeat the basic cannon of taxation of identifying the subject of levy;

c.   The
notification imposes a tax on an ad hoc figure @ 18% which clearly runs
contrary to the requirements of section 9(3)/9(4). These sections envisage only
a ‘supply / transaction’-based RCM levy and not a result-based RCM levy;

d.   One
would not be in a position to raise the self-invoice on RCM transactions of
9(4) under 80/20 rule.


Unbooked
apartment RCM rule

N–04 and 05/2019 impose RCM on
intermediate transactions to the extent of unbooked residential apartments at
the end of the project. This is on the premise that unbooked completed
apartments are outside the ambit of GST. The tax payable is determined based on
carpet area ratios of booked / unbooked apartments, a ratio completely foreign
to GST law. Such ratios also deviate from the economic value-add of a service
and result in disparity in the cost burden to end-customers on the basis of
carpet area ignoring commercial value. Moreover, it appears to be a back-door
entry to tax completed apartments also evident from the cap fixed to that of
underconstruction apartments.


The
fundamental rule of taxation is that there should be certainty on the subject,
time and measure of levy. The Supreme Court in Govind Saran Ganga Saran
vs. Commissioner of Sales Tax and Ors (1985 AIR 1041)
held that the
components which enter into the concept of a tax are well known. The first is
the character of the imposition known by its nature which prescribes the
taxable event attracting the levy, the second is a clear indication of the
person on whom the levy is imposed and who is obliged to pay the tax, the third
is the rate at which the tax is imposed, and the fourth is the measure or value
to which the rate will be applied for computing the tax liability. If these
components are not clearly and definitely ascertainable, it is difficult to say
that the levy exists in point of law. Any uncertainty or vagueness in the
legislative scheme defining any of those components of the levy will be fatal
to its validity. These futuristic conditions appear to make the levy uncertain
and vulnerable to challenge.

Issue 5 – Notification grants
benefit to ‘A’ by fulfilment of conditions by ‘B’?

The notification distinctly has
scenarios where benefit to one is subject to the actions of another. This is
absurd


Instance 1: N–03/2019 grants
beneficial works contract rate for affordable housing projects to contractors
subject to fulfilment of the minimum 50% carpet area by the developer. The
exemption is topped with a condition that any shortfall in area would result in
withdrawal of exemption by way of an RCM payment by the developer. Moreover,
the notification 7/8-2019 does not back this levy with an amendment in the RCM
table u/s 9(3).


Instance 2: N–03/2019 grants
beneficial rates to developer provided landowner discharges all the taxes on
his share of apartments sold prior to completion and reversal of ITC on
unbooked apartments. Non-fulfilment of conditions by the landowner on his share
may adversely affect the availment of beneficial rate.


The above conditions of the
notification would necessarily have to be whittled down suitably for its
sustenance.


Issue 6 – Whether condition of
prohibiting tax payment through credit is within the
vires of tax
discharge?

N–03/2019 mandatorily directs the
developer to discharge all beneficial rate taxes only through cash. This rule
emerged from discussions in the GST Council that developers are discharging
only 1-5% of their output through cash ledgers. With this assumption, the
Council decided that the new scheme debarring availing of input tax credit
should not result in any credit balance and hence payments should be directed
to be made through cash ledgers only. This runs contrary to the mandate of
section 49(4) which permits rightful electronic credit ledger balance to be
used for payment of any output taxes. Input tax credit is as good as tax paid
and differential treatment to this would defeat this value-added tax scheme.
Developers having input tax credit balance would be left with a dead number if
it is not permitted to be utilised against output taxes. For a developer
engaged only in construction activity, this condition effectively lapses the
input tax credit balance accumulated over the years of operation of the
company.


Issue 7 – What would be the
implication in case of change in any variable of the real estate project (such
as cancellation of flat, valuation of affordable flat, change in project
composition, cancellation of project, etc.)?

The
real estate notification has set up a complex matrix based on project variables
such as apartment dimensions, residential to commercial composition, pre- and
post-1st April, 2019 flat inventory, etc. For example, a new
commercial plan may emerge in the third year of the project reclassifying the
project from an RREP to an REP. This changes the entire dynamics of rate
structure and transitional ITC working right from 1st April, 2019.
Another example could be a flat previously treated as booked and WIP as on 1st
April, 2019 is subsequently cancelled. Clause 22 of the real estate FAQ
provides some guidance on this matter but this has multi-faceted implications
on RCM, ITC, etc. The notification does not provide for any claw back of
previous workings. The developer would fall into a situation where the entire
cost structure is impacted and the burden of additional taxes cannot be
recovered from any one. Once again, the Supreme Court’s verdict in Govind
Saran Ganga Saran (supra)
may come to the rescue of the tax payers.


The above complexities are just the
tip of the iceberg. The real estate notifications have been intermingled with
the RERA law which is itself in an adolescent stage – any ambiguity will have
repercussions on tax computations, making it difficult for managements to take
decisions. The functioning of this entire scheme through exemption
notifications makes matters very complex. A tax payer who is denied exemption
on certain facts on a future date would be placed in severe hardship as there
is no mechanism to undo all compliances ancillary to the exemption and
reinstate it to the base rate scenario. A fundamental question also lingers
whether this is interfering with fundamental rights in taking business
decisions?


The real estate sector needs to be boosted and
this can take place only with simple laws and tighter monitoring. The
philosophy of the GST Council to simplify real estate tax structure has
evidently taken a back seat. This would be an opportune moment to remember what
Sir Winston Churchill had said: ‘We contend that for a nation to try to tax
itself into prosperity is like a man standing in a bucket and trying to lift
himself up by the handle.

Article 7, 12 of India-Singapore DTAA – Provision of standard bandwidth services could not be classified as FTS or royalty under India-Singapore DTAA

18. TS-305-ITAT-2019 (Mum.)

DCIT vs. Reliance Jio Infocomm Ltd.

ITA No.: 936/Mum/2017

A.Y.: 2016-17

Date of order: 10th May, 2019


Article 7, 12 of India-Singapore DTAA – Provision of
standard bandwidth services could not be classified as FTS or royalty under
India-Singapore DTAA


FACTS

Taxpayer, an Indian company, was engaged in the business of
providing telecom services in India. During the year under consideration,
Taxpayer entered into an agreement with a Singapore Company (FCo) for availing
bandwidth services. As per the terms of the agreement, Taxpayer withheld taxes
on payments made to FCo for rendition of services.


However, Taxpayer subsequently appealed before the CIT(A) u/s
248 of the Act on the ground that the amount paid for bandwidth services was
not taxable in India and hence was not subject to withholding u/s 195 of the
Act on the basis of the following:


Bandwidth charges were in the nature of business income for
FCo and in the absence of permanent establishment (PE) or business connection
in India, it was not taxable under Article 7 of the India-Singapore DTAA.


Provision of the bandwidth services was fully automated and
did not involve any human intervention. Hence, such services did not qualify as
FTS under the Act or the DTAA.


Payments made to FCo were merely for receiving standard
bandwidth services and not for making any use of a ‘process’, whether secret or
not; therefore, it does not qualify as ‘royalty’ under the Act as well as the
DTAA.


CIT(A) observed that
Taxpayer had only received an access to service and all the infrastructure and
processes required for provision of bandwidth services were always used and
remained under the control of FCo and were never given either to Taxpayer or to
any person availing such services. It was thus concluded that the payments made
by Taxpayer to FCo for provision of bandwidth services could not be classified
as FTS or royalty either under the Act or the DTAA. The payment made was in the
nature of business profits, not taxable in India in the absence of PE or any
business connection of FCo in India.


Aggrieved, the AO appealed before the Tribunal1 .

___________________________________________________

1.  The
AO did not assail the observation of the CIT(A) that payment made for bandwidth
services did not qualify as FTS and hence this aspect was not discussed before
the Tribunal.


HELD

The consideration paid by Taxpayer to FCo for provision of
bandwidth services was in the nature of business income and cannot be
classified as ‘royalty’ under the Act or the DTAA for the following reasons:


Pursuant to the terms of the agreement, Taxpayer had only
received standard facilities, i.e., bandwidth services from FCo.


All infrastructure and processes required for provision of
bandwidth services were always used and under the control of FCo and the same
were never given either to Taxpayer or to any person availing the said service.


Taxpayer did not have access to any process used in providing
the bandwidth services. Besides, since the process involved in providing the
bandwidth services was a standard commercial process that was followed by the
industry players, and the IPR in the process was not owned / registered in the
name of FCo, it did not qualify as a ‘secret process’. Besides, as the payment
was neither towards the use of any equipment nor secret formula or process, it
did not qualify as royalty under the DTAA.


Further, the amendment to
explanation 6 of section 9(1)(vi)2 
will not override the treaty and hence will have no bearing on the
definition of ‘royalty’ as contained in the DTAA.
 

___________________________________________________________

2. 
Explanation 6 to section 9(1)(vi) defines a process to include transmission by
satellite, cable, optic fibre or any other similar technology whether or not
such process is secret


Article 12(5) India-Finland DTAA – Payment made for obtaining test results in India is taxable in India under Article 12(5) of India-Finland DTAA irrespective of whether the testing process is done outside India

17.  TS-311-ITAT-2019
(Kol.)

Outotec (Finland) Oy, Kolkata vs. DCIT (International
Taxation)

ITA No.: 2601/Kol/2018

A.Y.: 2015-16

Date of order: 31st May, 2019


Article 12(5) India-Finland DTAA – Payment made for
obtaining test results in India is taxable in India under Article 12(5) of
India-Finland DTAA irrespective of whether the testing process is done outside
India


FACTS

Taxpayer, a Finnish
company, earned income from rendering of testing and other services to Indian
customers. Taxpayer contended that the services were carried on from its office
/ laboratories located outside India and none of its employees visited India
for providing these services to Indian customers. Thus, as the services were
performed outside India, income from these services was not taxable in India as
per Article 12(5) of the India-Finland DTAA.


But the AO contended that
the services can be said to be performed only when they were used by the
beneficiary. Since the intended use of the services tested in the laboratories
in Finland was ultimately in India, service can be said to be performed in
India and income from such services were taxable in India under Article 12(5)
of the DTAA.


Taxpayer appealed before
the DRP who upheld the AO’s order. Still Aggrieved, Taxpayer appealed before
the Tribunal.


HELD

Article 12(5) of the DTAA provides that the FTS shall be
deemed to arise in a contracting state where the payer is located. However, as
an exception to this in cases where the services for which the FTS is paid is
performed within a contracting state, then it shall be deemed to arise in the
state in which the services are performed.


For applying the exception
to Article 12(5) it is necessary that the payment should be made for services
and such services should be performed in the other state (i.e., Finland). In
the present case, payment was made not for the testing but for obtaining the
results of the testing which was used in India. Thus, even where testing was
done outside India, the exception of Article 12(5) does not apply.


As services were availed in India, the fee for testing
services was taxable in India.

Section 9(1)(vii) of the Act; Article 13 of India-France DTAA – Reimbursement of salary of seconded employees does not qualify as FTS – By virtue of the MFN clause in India-France DTAA, managerial services do not qualify as FTS

16.  [2019] 56 CCH 0235
(Pune – Trib.)

Faurecia Automotive Holding vs. DCIT (IT)

ITA No.: 784/Pun/2015

A.Y.: 2011-12

Date of order: 8th July, 2019


Section 9(1)(vii) of the Act; Article 13 of India-France
DTAA – Reimbursement of salary of seconded employees does not qualify as FTS –
By virtue of the MFN clause in India-France DTAA, managerial services do not
qualify as FTS


FACTS – 1

Taxpayer, a company resident in France, was engaged in
designing and building moulded plastic parts for passenger car interiors.
During the year under consideration, it seconded an employee (Mr. X) to an
Indian group entity (ICo). During the relevant year, Taxpayer paid the salary
to Mr X on behalf of ICo, which was then reimbursed by ICo without any mark-up.
Taxpayer contended that the reimbursement received from ICo was not subject to
tax.


However, the AO contended that the amount received from ICo
was FTS under the Act and hence subject to tax in India.


Aggrieved, Taxpayer appealed before the DRP who upheld the
AO’s order on the contention that Mr. X made available his technical knowledge,
experience and skills, etc. to ICo and hence qualifies as FTS under the DTAA.


However, Taxpayer went in appeal before the Tribunal.


HELD – 1

FTS under the Act is defined to mean any consideration for
the rendition of managerial, technical or consultancy services, unless such an
amount is chargeable to tax under the head ‘salaries’ in the hands of the
recipient.


What is of relevance is the real recipient and not the
literal recipient. If an amount is paid to the expatriate of an NR but the real
recipient is the NR, then the nature of that amount may be FTS. However, if the
real recipient is the employee and the NR is merely a person acting as a post
office on behalf of the employee, then the payment made would be in the nature
of salary. Such amount will then not qualify as FTS.


For the following reasons it can be said that the amount paid
by ICo is in the nature of salary payable by ICo to the employee and the
Taxpayer merely receives it on behalf of the employee and hence such payment
does not qualify as FTS:

  •    The remuneration of Mr. X was fixed by ICo;
  •    A perusal of the employment agreement clearly
    indicated that Mr. X was employed by ICo and was rendering services to ICo;
  •    Mr. X was working under the control and
    supervision of ICo;
  •    Taxpayer had no role to play in the rendition
    of services by Mr. X to ICo, except that a part of the salary payable by the
    Indian entity was initially paid by Taxpayer in France, which was later on
    recovered without any profit element from ICo.


FACTS – 2

Taxpayer provided Global Information Support services to ICo
which inter alia included assistance in running the operations of ICo,
technical support, etc. Taxpayer contended that such services did not make
available any technical knowledge, experience, skill or knowhow, etc. to ICo
and hence the fee received for such services does not qualify as FTS under the
DTAA.


The AO, however, contended that the amount received by
Taxpayer was in the nature of ‘royalty’ as well as ‘FTS’ under the Act and also
the DTAA.


Aggrieved, the Taxpayer appealed before the DRP who upheld
the AO’s order. Taxpayer then approached the Tribunal.


HELD – 2

Perusal of the agreement indicates that the services rendered
by the Taxpayer catered to various facets of business operations, including
management, marketing, accounting and finance, human resources, IT support
services, etc. These services are in the nature of managerial services as well
as technical services and hence qualify as FTS under the Act as well as the
DTAA.


However, having regard to the Most Favoured Nation (MFN)
clause of the India-France DTAA, the limited scope of FTS under the India-UK
DTAA is to be read into the India-France DTAA.


Article 13(4) of the
India-UK DTAA defines FTS to mean technical or consultancy services which ‘make
available’ technical knowledge, experience or skill, etc. to the recipient.


As the FTS definition in the India-UK DTAA does not include
‘managerial services’, the services rendered by Taxpayer which are in the
nature of managerial services will not qualify as FTS. Further, as the
technical services rendered by Taxpayer did not make available any technical
knowledge or skill, it will not qualify as FTS under the DTAA.


Further, as the payment was received for
rendering of services, it does not qualify as ‘royalty’ under the Act as well
as the DTAA.

Section 54 r.w.s. 139 – Assessee would be entitled to claim exemption u/s 54 to extent of having invested capital gain on sale of old residential flat towards purchase of new residential property up to date of filing of his revised return of income u/s 139(5)

24.  [2019] 199 TTJ
(Mum.) 873

Rajendra Pal Verma vs. ACIT

ITA No.: 6814/Mum/2016

A.Y.: 2013-14

Date of order: 12th March, 2019


Section 54 r.w.s. 139 – Assessee would be entitled to claim
exemption u/s 54 to extent of having invested capital gain on sale of old
residential flat towards purchase of new residential property up to date of
filing of his revised return of income u/s 139(5)


FACTS

The assessee had e-filed
his return of income on 31st July, 2013. Thereafter, the assessee
filed a revised return of income on 15th November, 2014. The AO
observed that the assessee had during the year under consideration sold an old
residential flat and the entire long-term capital gain (LTCG) on the sale of
the old flat was claimed as exempt u/s 54. The assessee had purchased a new
residential flat as per an agreement dated 29th December, 2014 with
the builder / developer, as per which the construction of the property was
expected to be completed by September, 2017. However, the AO observed that the
assessee had failed to substantiate his claim of exemption u/s 54 amounting to
Rs. 1.75 crores; hence he declined to allow the same.


Aggrieved by the order, the assessee preferred an appeal to
the CIT(A). The CIT(A) was of the view that the assessee was entitled for claim
of exemption u/s 54 only to the extent he had invested the LTCG up to the due
date of filing of his return of income for the year under consideration, i.e.,
assessment year 2013-14 as envisaged u/s 139(1), therefore, he had restricted
his claim for exemption up to the amount of Rs. 83.72 lakhs.


HELD

The Tribunal held that on a perusal of section 54(2), it
emerges that the assessee in order to claim exemption u/s 54 remains under an
obligation to appropriate the amount of the capital gain towards purchase of
the new asset as per the stipulated conditions of section 54.Where the capital
gain was not appropriated by the assessee towards purchase or construction of
the residential property up to the date of filing of the return of income u/s
139, then in such a case the entitlement of the assessee to claim the exemption
by making an investment towards purchase or construction of the new asset would
be available, though subject to the condition that the assessee had deposited
the amount of such capital gain in the CGAS account with the specified bank by
the due date contemplated u/s 139(1). Further, in case any part of the capital
gain had already been utilised by the assessee for the purchase or construction
of the new asset, the amount of such utilisation along with the amount so
deposited would be deemed to be the cost of the new asset.


On the basis of the
aforesaid deliberations, it was viewed that the outer limit for the purchase or
construction of the new asset as per sub-section (2) of section 54 was the date
of furnishing of the return of income by the assessee u/s 139. It was viewed
that the date of furnishing of the return of income u/s 139 would safely
encompass within its sweep the time limit provided for filing of the return of
income by the assessee u/s 139(4) as well as the revised return filed by him
u/s 139(5). It was found that the instant case clearly fell within the sweep of
the aforementioned first limb, i.e., sub-section (1) of section 54. As the
assessee in the instant case had utilised an amount of Rs. 2.49 crores (i.e.,
much in excess of the amount of LTCG on sale of the residential property) up
till the date of filing of his revised return of income u/s 139(5) on 15th
November, 2014, therefore, his claim of exemption u/s 54 in respect of the
investment made towards the purchase of the new residential property up to the
date of filing of the revised return of income u/s 139(5) was found to be in
order.


Therefore, the assessee in the instant case was entitled to
claim exemption u/s 54 to the extent he had invested towards the purchase of
the new residential property under consideration up to the date of filing of
his revised return of income u/s 139(5), i.e., on 15th
November,  2014.

Article 12(5) of India-Netherlands DTAA – Rendering of a bouquet of services where the predominant nature is managerial in nature will qualify for exemption from FTS, even if some of the services have the trappings of technical and consultancy services

15.  [2019] 106
taxmann.com 24 (Mum – Trib.)

DCIT vs. Hyva Holdings B.V.

ITA Appeal No.: 3816 (Mum.) of 2017

A.Y.: 2012-13

Date of order: 30th April, 2019


Article 12(5) of India-Netherlands DTAA – Rendering of a
bouquet of services where the predominant nature is managerial in nature will
qualify for exemption from FTS, even if some of the services have the trappings
of technical and consultancy services


FACTS

Taxpayer, a company incorporated in the Netherlands, had
entered into a service agreement with its Indian subsidiary (ICo) for rendition
of a bouquet of services (provision of IT, R&D, strategic purchasing
services, etc.) which involved providing certain expertise to support ICo to
grow, expand and achieve business independence. Taxpayer contended that the
services rendered to ICo are ‘managerial’ in nature and in the absence of
coverage of ‘managerial services’ in the Fee for Included Services (FIS)
Article of the India-Netherlands DTAA, it would not trigger source taxation
under the DTAA.


On a perusal of the service agreement, the AO noted that the
nature of services provided by the Taxpayer were not confined to managerial
service alone but were all-inclusive, comprising managerial, technical and
consultancy services. As the services rendered by Taxpayer made available
technical knowledge, experience, knowhow and skill, it qualified as FTS under
Article 12 of the DTAA.


Aggrieved, the Taxpayer
filed an appeal before the CIT(A) who reversed the AO’s order and concluded
that services rendered by Taxpayer were in the nature of managerial services
and hence did not fall within the ambit of FTS under the DTAA. Further, even if
such services qualify as technical services, in the absence of satisfaction of
make-available condition, it did not qualify as FTS under the DTAA.


But the aggrieved AO appealed before the Tribunal.


HELD

A perusal of the service agreement indicated that while the
services to be rendered under the agreement were termed as management services,
some of the services such as information technology, R&D, etc. rendered by
Taxpayer were in the nature of technical or consultancy services. Nevertheless,
the core activity of Taxpayer under the agreement was rendering managerial
services.


Further, as the AO did not demonstrate that the amount can be
attributed towards technical or consultancy services, the payment received by
Taxpayer does not qualify as FTS under the DTAA.


Without prejudice, even if the services are held
to be in the nature of technical or consultancy services, as Taxpayer has not
made available any technical knowledge, experience, knowhow, skill, etc., to
ICo for its independent use, the amount received by Taxpayer did not qualify as
FTS under the DTAA.

Section 273B read with section 272A(2)(k) – Delay in filing TDS return for want of PAN considered as reasonable cause and penalty imposed was deleted

11.  Sai Satyam
Hospitals Private Ltd. vs. Addl. CIT-TDS Range

Members: Sandeep Gosain (J.M.) and Manoj Kumar Aggarwal
(A.M.)

I.T.A. No.: 3220/Mum./2018

A.Y.: 2011-12

Date of order: 15th July, 2019

Counsel for Assessee / Revenue: Dr. Prayag Jha / Chaudhury
Arun Kumar Singh


Section 273B read with
section 272A(2)(k) – Delay in filing TDS return for want of PAN considered as
reasonable cause and penalty imposed was deleted


FACTS

For a delay of 389 days in filing TDS return in Form No. 26Q,
a penalty of Rs. 38,900 u/s 272A(2)(k) was imposed by the AO. The CIT(A), on
appeal, confirmed the order.


Before the Tribunal, in order to make out a case of
reasonable cause, the assessee inter alia pleaded that the delay was due
to non-availability of the PAN of the deductees, without which the return could
not be uploaded; there was no evasion of tax or loss to the government since
the assessee had deducted and paid the taxes to the Government.


HELD

The Tribunal noted that the directors of the assessee company
were doctors who may not be well-versed with the technicalities of TDS
provisions; besides, in the TDS return filed, there were 30 deductees’ records
and the PAN was quoted in all the records; moreover, due TDS had been deducted
and deposited by the assessee in the Government treasury.


The Tribunal also noted the fact that many changes had been
brought about in the financial year 2010-11 by the Act in filing of e-TDS
returns wherein it was necessary to quote cent percent valid Permanent Account
Numbers of the payees in the e-TDS returns and only thereafter could the e-TDS
returns be validated and uploaded in the Income-tax System.

Therefore, for the reason that there was no loss
to the Revenue and the delay in filing of the e-TDS returns was unintentional
on the part of the assessee, and keeping in view the assessee’s background, the
penalty imposed by the AO was deleted.

Section 37(1) – Compensation received in lieu of extinction of right to sue is capital receipt not chargeable to tax

10.  Chheda Housing
Development Corporation vs. Addl. CIT (Mumbai)

Members: G.S. Pannu (V.P.) and Pawan Singh (J.M.)

ITA No.: 86/Mum./2017

A.Y.: 2012-13

Date of order: 29th May, 2019

Counsel for Assessee / Revenue: Dr. K. Shivaram and Rahul K.
Hakkani / H.N. Singh and Rajeev Gubgotra


Section 37(1) – Compensation received in lieu of extinction
of right to sue is capital receipt not chargeable to tax


FACTS

The assessee, a partnership firm, was engaged in the business
of construction and development of property. During FY 2004-05, the assessee
had entered into a memorandum of understanding (MOU) with one Mr. Merchant, the
landowner, for the development of his land and paid the sum of Rs. 2.5 crores.
In terms of the MOU, the parties had agreed to execute a joint development
agreement and the landowner was to obtain the commencement certificate from the
local authorities. However, the landowner did not provide the certificate.
Besides, the assessee came to know that the landowner had transferred the
development rights of the land to a company owned by his family.


The assessee filed a suit before the Bombay High Court
seeking specific Performance of the MOU and to execute the joint development
agreement. In the alternative, the assessee claimed damages for breach of
contract. A criminal complaint was also filed alleging fraud. Litigation in
various forums continued till 2011 when, through the intervention of a
well-wisher, the parties agreed to a settlement. As per the terms of the
settlement, the assessee agreed to withdraw the criminal complaint and the
civil suit. The assessee also agreed not to create any third party right, title
or interest in respect of the right created under the MOU. On execution of the cancellation deed in
September, 2011, the assessee was paid Rs. 20 crores.


For the year under appeal, the assessee had filed a Nil
return. The AO treated the receipt of Rs. 20 crores as income and taxed the
same as long-term capital gain. The CIT(A), on appeal, confirmed the AO’s
order.


Before the Tribunal, the Revenue justified the orders of the
lower authorities and contended that the right to execute the joint development
right of immovable property falls within the expression of ‘property of any
kind’ as used in section 2(24) and consequently was a capital asset. And giving
up a right of specific performance as claimed by the assessee, amounted to
relinquishment of capital asset. Therefore, there was a transfer of capital
asset.


HELD

The Tribunal noted that the assessee received a sum of Rs. 20
crores on execution of the cancellation deed in September, 2011. Referring to
the relevant clause in the deed, the Tribunal observed that as per the deed,
the assessee had not transferred any rights, which was sought to be confirmed
in the MOU. In fact, those rights were already transferred by the landowner in
favour of the company owned by his family before the date of the MOU. The
assessee received compensation which consisted of refund of the amount paid by
way of advance along with interest, towards loss of profit / liquidated damage,
for loss of opportunity to develop the property and sale of flats in the open
market, and towards the cost of litigation.


Therefore, relying on decisions of the Delhi High Court in CIT
vs. J. Dalmia (149 ITR215)
, the Bombay High Court in CIT vs.
Abbasbhoy A. Dehgamwalla (195 ITR 28),
the Supreme Court in CIT
vs. Saurashtra Cement Ltd.
(325 ITR 422) and of the
Mumbai Tribunal in ACIT vs. Jackie Shroff (194 TTJ 760), it was
held that the amount received by the assessee in excess of the advance was on
account of compensation for extinction of its right to sue the owner, and so
the receipt is a capital receipt not chargeable to tax. According to the
Tribunal, the case of K.R. Srinath vs. ACIT (268 ITR 436 Madras)
relied on by the Revenue was distinguishable on facts. In the said case the
amount was received as consideration for giving up the right of specific
performance which was acquired under an agreement for sale. However, in the
case of the assessee here, the owner of the land had already transferred such
right to a third party. Rather, the original agreement was cancelled.


Accordingly, the appeal of the assessee was
allowed.

Section 72 r.w.s. 254, Section 154 – Business loss determined and carried forward by the AO pursuant to an order passed in accordance with directions of the Tribunal u/s 143(3) r.w.s. 254 can be set off in subsequent years though such claim is not made in the return of income. The AO is duty-bound to give relief to the assessee which has resulted pursuant to the order passed by the appellate authority and which has a cascading effect on the subsequent assessment years

26.  [2019] 107
taxmann.com 92 (Pune)

Maharashtra State Warehousing Corporation vs. DCIT

ITA Nos.: 2366 to 2399/Pune/2017

A.Y.s: 2003-04 to 2006-07

Date of order: 3rd June, 2019


Section 72 r.w.s. 254,
Section 154 – Business loss determined and carried forward by the AO pursuant
to an order passed in accordance with directions of the Tribunal u/s 143(3)
r.w.s. 254 can be set off in subsequent years though such claim is not made in
the return of income. The AO is duty-bound to give relief to the assessee which
has resulted pursuant to the order passed by the appellate authority and which
has a cascading effect on the subsequent assessment years


FACTS

The assessee, a State Government Undertaking, was engaged in
providing warehouse facilities in the State of Maharashtra. For A.Y. 2002-03,
while assessing the total income of the assessee, the AO made certain additions
to the returned income. The assessee contested the additions in an appeal
before the CIT(A) as well as before the Tribunal. The Tribunal restored the
matter back to the AO with certain directions.

The AO passed an order u/s 143(3) r.w.s. 254 and allowed the
final net business loss to be carried forward.


Subsequently, the CIT
invoked section 263 of the Act and held the order passed by the AO u/s 143(3)
r.w.s. 254 to be erroneous and prejudicial to the interest of the Revenue.


The assessee challenged the action of the CIT before the
Tribunal. The Tribunal quashed the order passed by the CIT u/s 263. As a
result, the order passed by the AO based on the directions of the Tribunal
stood restored.


Thereafter, the assessee, in order to claim the set-off of
brought-forward business loss of A.Y. 2002-03, filed an application for
rectification of assessment orders for A.Y. 2003-04 to A.Y. 2006-07. The AO
rejected this application.


Aggrieved, the assessee preferred an appeal to the CIT(A) who
dismissed the appeals of the assessee on the ground that since the set-off was
not claimed in the return of income, the same could not be allowed to the
assessee at a belated stage.


The assessee preferred an appeal to the Tribunal.


HELD

The Tribunal observed that by the time the order u/s 143(3)
r.w.s. 254 was passed whereby loss was determined and allowed to be carried
forward, the assessee had already filed return of income for the subsequent
assessment years and hence the assessee had no occasion to claim set-off of
brought-forward business loss and it was a case of supervening impossibility.
The Tribunal held that the AO is duty-bound to give relief to the assessee
which has resulted pursuant to the order passed by the appellate authority and
which has a cascading effect on the subsequent assessment years.


Further, the Tribunal relied on the decision of the Bombay
High Court in the case of CIT vs. Pruthvi Brokers & Shareholders (P)
Ltd. [2012] 349 ITR 336
wherein it was held that the assessee is
entitled to raise additional ground not merely in terms of legal submissions
but also additional claims which were not made in the return filed by it. It
was thus held that the assessee was entitled to claim set-off of
brought-forward business loss in A.Y.s 2003-04 to 2006-07.


The Tribunal decided the appeal in favour of the
assessee.

Section 22 r.w.s. 23 –Under section 22 annual value is chargeable to tax in the hands of the owner – The assessee, SPV, promoted by the State Housing Board, was merely a developer and not the owner. Accordingly, notional annual value of unsold flats, held as stock-in-trade by the assessee, could not be assessed u/s 23

25.  [2019] 106
taxmann.com 346 (Kol.)

Bengal DCL Housing Development Co. Ltd. vs. DCIT

ITA Nos.: 210/Kol/2017 & 429/Kol/2018

A.Y.s: 2011-12 & 2012-13

Date of order: 24th May, 2019


Section 22 r.w.s. 23 –Under section 22 annual value is
chargeable to tax in the hands of the owner – The assessee, SPV, promoted by
the State Housing Board, was merely a developer and not the owner. Accordingly,
notional annual value of unsold flats, held as stock-in-trade by the assessee,
could not be assessed u/s 23


FACTS

The assessee was a
joint-sector company promoted by the State Housing Board with DCPL for
undertaking large-scale construction of housing complexes within the state to
solve basic housing problems subject to the supervision and overall control by
the State Government. Pursuant to a development agreement, the assessee
undertook construction of a housing complex known as ‘U’. The assessee treated
unsold constructed flats as its stock-in-trade.


These flats, in respect of which annual value was sought to
be computed by the AO, were allotted by the assessee to various persons. The AO
noted that the expression ‘allotment’ in the terms and conditions of allotment
was defined to mean ‘provisional allotment’; the definition also stated that
allotment will remain provisional till a formal deed of transfer is executed
and registered in favour of the allottee for his apartment. In respect of the
flats for which no formal deeds were executed and registered, the AO held the
assessee to be the owner. The AO computed and charged to tax the notional
annual value of unsold finished apartments held by the assessee.


Aggrieved, the assessee preferred an appeal before the
Commissioner of Income-tax (Appeals) [CIT(A)] who confirmed the action of the
AO. Still aggrieved, the assessee preferred an appeal to the Tribunal.


HELD

The Tribunal observed that in order to attract charge of tax
under the head ‘house property’, the AO must prove that the assessee is the
owner of the same. The term ‘owner’ for the purposes of Chapter IVC is defined
in section 27. The Tribunal observed that though the value of finished
apartments was included under the head ‘Inventory’ disclosed in the balance
sheet, yet, for the purposes of section 22 the assessee could not be considered
to be the owner of the apartments. The Tribunal noted that the apartments were
allotted prior to the balance sheet date and in respect of such allotments a
substantial part of the consideration was received and reflected by way of
liability in the books of the assessee. Consequent to allotment and receipt of
consideration, the right of specific performance and right to obtain conveyance
accrued in favour of the purchaser. The assessee was debarred from claiming ownership
rights in the apartments already allotted to the flat purchasers.


The Tribunal also observed that the apartments did not have
occupancy certificate. And in the absence of a valid occupancy certificate, the
property could not be said to be in a position to be let or occupied. Thus, the
notional annual value of unsold apartments could not be assessed in the hands
of the assessee u/s 23 of the Act.


The Tribunal decided the appeal in favour of the assessee.

IS IT FAIR TO MAKE OBTAINING VALID TDS CREDITS TEDIOUS?

BACKGROUND

Getting credit for TDS has become a prickly
point in many of the intimations issued u/s 143(1) of the Income tax Act, 1961
and even in the case of assessments. The Government has tried to automate the
process, which was expected to simplify the grant of credit for TDS and issue
of refunds. However, the computerised system is unable to solve certain issues
to the required extent, which gives a substantial headache to the assessee. She
needs to tackle the demands that are created due to non-grant of correct credit
of the TDS entitlement or issue of incorrect refunds. The process becomes more
complicated, especially because the assessee has to deal with a Centralised
Processing Centre (CPC) which does not entertain any human interaction!


Some of the major issues faced by an
assessee in respect of TDS credit are as follows:


Non-payment of TDS by the deductor to the
Government or non-filing or incorrect filing of relevant TDS return by him is a
major problem.


A different system of accounting followed by
the deductee and the deductor, resulting in a different year of deduction by
the deductor and the claim of TDS by the deductee, is another one.


Statutory postponement of claim of TDS as
per Rule 37BA of Income-tax Rules, due to which TDS is not allowed to be claimed
unless the relevant income is offered to tax by an assessee. In many cases this
results in non-grant of TDS credit to the assessee in the year of such claim.


Deduction and payment of TDS being made in a
subsequent year by the deductor as compared to the year of accrual of the
relevant income as per the accounting system followed by the deductee, more
often than not results in deprival of TDS credit to the deductee in the
relevant year.


WHY IS IT UNFAIR?

After TDS has been deducted, the deductee
remains at the mercy of the deductor for securing the credit for the same. If
the deductor does not pay the TDS or file the relevant return, or makes
mistakes in the return affecting the deductee, the deductee can suffer
financial loss as well as hardship in respect of his own tax liability. If such
TDS credit is not granted, he will not only have to pay the tax but also pay
interest for no fault of his.


The return of income has provided for
stating the following details:


(i) Brought forward TDS from
the previous years;

(ii) Credit of TDS granted in
Form 26AS for the
current year;

(iii) TDS claimed during the current year;

(iv) TDS carried forward to the next year.


However, the intimations received from CPC
u/s 143(1) in many cases are not able to auto-fetch the correct TDS entitlement
of the assessee for the year. The credit given is either less or equal to
the TDS claimed by the assessee. There is no mechanism to understand which TDS
credit claim has not been accepted by the CPC.


When the tax is recovered by the Government
on behalf of the assessee as TDS, it may not be fair not to grant credit of the
same for the year on the ground that the relevant income is not offered to tax
in the said year. Deduction of TDS is a process of payment of tax on behalf of
the deductee and it need not be connected with the declaration of corresponding
income by the deductee as the same is declared as per the facts of the case and
the governing law. Declaration of relevant income for the claim of credit of
the relevant TDS may not be fair to the assessee, though it is in favour of the
Revenue. Lest we forget, TDS is primarily a mechanism for collection of tax
at source and not a mechanism for controlling avoidance of tax.


Is it not fair to grant the credit of the
TDS to an assessee for the year in which the relevant income is offered to tax
by him, irrespective of the fact that the TDS is paid by the deductor in a
subsequent financial year? This is so, especially in the light of the fact that
the TDS credit is not granted when the relevant income is not offered to tax in
the year in which the TDS is deducted.


The TDS
provisions take away the right of the deductee to recover the amount of TDS
from the deductor.
Is
it not fair to grant him the credit of the tax because his recourse to the said
amount is substantially weakened, if not lost? This is more so as Government
has full right and effective means to recover the TDS amount from the deductor.


SOLUTION

The credit of
tax deductible should be granted to the deductee once the deductor deducts the
same, irrespective of the payment of the same by the deductor or filing of the
relevant TDS return by him. Onus of proof should be transferred to the deductor
or Government which, under law, requires the deductor to make that deduction.


Credit of the tax deductible at source may
be granted in the year in which the relevant income is offered to tax, even if
the relevant tax is not deducted in that year but deducted in a later year by
the deductor.


The credit of the TDS may be granted even if
it is not appearing in Form 26AS, when the assessee can submit the proof of
deduction by the deductor; this is because Form 26AS is not generated out of
any action of the deductee. It only reflects third-party data. A
technology-driven mechanism should be rolled out by the income tax department
to deal with the mismatch.


The credit of the TDS may be granted in the
year of deduction, irrespective of whether or not the relevant income is liable
to be offered to tax for that year. Rule 37BA grants credit of TDS provided the
corresponding income is declared in the return of income of the year in which
the TDS is claimed.


This has made the process of claiming TDS
cumbersome and it also results in denial of credit by CPC in many cases. It may
be desirable to do away with the Rule to grant credit in the year in which tax
is deducted. This will make obtaining legitimate TDS credit less tedious and
fair for the deductee.


INTERNATIONAL DECISIONS IN VAT/GST

This  article 
introduces case laws  on  VAT  /  GST developing  in various parts of the world.  After each decision,  the 
compiler  has given  in 
a  note  stating ‘Principles applicable to Indian  law’. 
This note draws attention  to  specific 
propositions  and  contextualises the decision in the Indian  scenario. It goes without saying that the
legal provisions in India and abroad may not be identical  and 
therefore the decisions should  be
read accordingly. These determinations intend 
to give a perspective on global 
developments, reading  them  in 
juxtaposition  with  the 
Indian  GST law would add value to
local reader.


I.
EU VAT/UK VAT


1   Nexus – Inputs and output
supply – Whether University carrying on ‘economic activity’?


Revenue and
Customs Commissioners vs. The Chancellor, Masters and Scholars of the
University of Cambridge [Judgement dated 3rd July, 2019 in case
C-316/18]


EUROPEAN COURT OF
JUSTICE

The University of
Cambridge is a not-for-profit educational institution which provides
principally education (not taxable) as also taxable supplies like commercial
research, sale of publications, consultancy services, catering, accommodation
and the hiring of facilities and equipment. The activities are financed in part
through donations and endowments, which are placed into an investment fund for
producing income for the University. That fund is managed by a third party to
whom certain management fees are paid. The question is whether the tax charged
on management fees can be taken as input tax credit against the taxable
supplies.


HELD

The Court has held
that the activity of collecting donations and endowments is not ‘for
consideration’ and is in the nature of charitable activities and not an
‘economic activity’ as is required under EU VAT law. Furthermore, the act of
investing these donations and endowments is a mere extension of the activity of
collecting and the University acts much like a private individual who invests
his surplus wealth. All these activities are not taxable. The management fee is
incurred in relation to this investment and generation of income by the
University, and hence cannot be taken as input tax credit. Even the cost of the
management of fund is not really included in the price of the output supplies.
There is no direct and immediate link in the present case either between the
management fee and a particular output transaction or between the management
fee and the activities of the University of Cambridge as a whole. No input tax
credit is therefore available.


Principles applicable to Indian law:

The European
concept of ‘economic activity’ is similar to, though not identical to, our
concept of ‘business’ in section 7 of the Indian GST Act. This judgement turns
partly on the University being a charitable institution and thus not carrying
on ‘business’. In our law, an activity is considered a business even without
‘profit motive’. However, the Hon’ble Supreme Court has explained in CST
vs. Sai Publication Fund (2002) 126 STC 288 (SC)
that even if profit
motive is irrelevant under the statute, the activity must still have an
underlying commercial nature. The Supreme Court has explained that even after
the ouster of the profit motive by statute, universities and educational
institutions continue to be outside the ‘business’ definition and has held that
the judgements of University of Delhi vs. Ram Nath AIR 1963 SC 1873 and
Indian Institute of Technology, Kanpur vs. State of UP (1976) 38 STC 428 (All)

continue to be good law despite amendment in the definition of ‘business’ in
sales tax law making the profit motive irrelevant.


The European judgement also says that collecting donations and
endowments is not an ‘economic activity’ since it is not ‘for consideration’.
The better analysis, suited for our GST law (which would not lead to a change
in the ultimate conclusion) would be that the collections of donations and
endowments are gifts of money and charity and not ‘consideration’ for any
supply made by the University. As such, that activity falls outside the remit
of our GST law.


The second prong of
the judgement, that of investment of fund created by the University being
comparable to investment activity of private individuals, is again an activity
which would otherwise fall outside the definition of ‘business’ under the
Indian law [Bengal and Assam Investors Ltd. vs. CIT (1966) 59 ITR 547
(SC)].


2   Whether a Diary is a ‘Book’?


Gardasson (t/a
Action Day aIslandi) vs. RCC [2019] UKFTT 0441


UK FIRST TIER TRIBUNAL

A diary which was
styled in such a manner as to teach time management to its buyers is a ‘book’
within the zero-rating provisions of the UK VAT Act. The fact that there is a
writing space and that the main function of a diary is not reading, does not
affect the conclusion, since writing spaces are provided even in students’
working books.


Principles applicable to Indian law:

This decision is
instructive about the rules of classification followed by other countries.


3   Whether a default on a loan changes the
character of the original supply? Whether litigation fees paid in connection
with such default can be claimed as input tax credit?


Newmafruit Farms Ltd. vs. RCC [2019] UKFTT 0440 (TC)


UK FIRST TIER TRIBUNAL

A loan of money
remains a loan even if there is a subsequent default in repayment. As such, the
exempt character of the original loan under the UK VAT Act does not change
merely because there is no repayment.


A loan of money being
exempt from UK VAT, any litigation fees paid in connection with the default of
such a loan is directly and immediately linked to the exempt supply of loan and
not eligible for input tax credit. Simply because the business of the appellant
is to give such loans does not mean that the input tax credit must be given in
respect of such transactions. Furthermore, even though there is a substantial
time gap between the making of the loan and the litigation fee, the direct and
immediate link is not affected by such passage of time. Such fees are also
indirectly factored into the cost of making the loan and thus the direct and
immediate link exists.


Principles applicable to Indian law:

Direct and
immediate link is a test evolved by European Courts to determine whether an
input supply has sufficient nexus with output supply. It is useful in the
Indian context where, though nexus is generally not required, it is still
needed where an output supply is ineligible for credit u/s 17 of the CGST Act.


4   Overpaid parking fees – Whether consideration
for ‘supply’?


National Car
Parks vs. HMRC [2019] EWCA Civ 854


UK COURT OF APPEAL

The appellant
operates, among others, ‘pay and display’ car parks in which there are ticket
machines which take cash. A board or boards will specify the amounts that must
be paid to park for different lengths of time. Someone wishing to leave his car
for a particular period has to insert coins to the value of at least the figure
given for that period in order to obtain a ticket which must be placed in his
vehicle’s windscreen. Once the requisite coins have been accepted by the
machine, the customer will be able to obtain his ticket by pressing a button.
Each machine indicates that no change is given and that ‘overpayments’ are
accepted.


The issue involved
in this appeal is whether such overpayments are subject to taxation under the
UK VAT Act.


HELD

Article 73 of
Council Directive 2006/112/EC on the common system of value-added tax (‘the
Principal VAT Directive’) reads as follows: ‘The taxable amount shall include
everything which constitutes consideration obtained or to be obtained by the
supplier, in return for the supply, from the customer or a third party…’


In the present
case, a contract between the appellant and the customer will have been
concluded no later than the point at which the customer chose to press the
green button to receive her ticket. The customer could have paid the exact
price, but chose to pay more. There was an explicit warning that no change
would be given and the tariff board indicated that ‘overpayments’ were
accepted.


Taken together, the
tariff board and the statement that overpayments were accepted and no change
given, indicated, looking at matters objectively, that the appellant could be
said to have set a minimum price for which the parking would be provided;
however, more was always welcome if the customer chose not to pay the exact
minimum price. The contract price in such case will always include the
overpayment.


Principles applicable to Indian law:

Under the Indian
GST law, every ‘supply’ must be made for a ‘consideration’. The definition of
‘consideration’ in section 2(31)(a) covers ‘any payment made… in respect of, in
response to, or for the inducement of’ a supply. This decision shows how an
overpayment which is made by the recipient despite due notice that it will be
appropriated by the supplier towards the contract, can be treated as
consideration under the UK VAT law. The same principle will apply in India.


5   Deceiving or cheating a person is not a supply
of ‘service’


Owen Francis
Saunders vs. HMRC [2019] TC 9922


UK FIRST TIER TRIBUNAL
(TAX)

The Appellant had
recovered excess consideration from his customers by way of deceit / fraud.
This excess consideration was confiscated by the Crown Court in the UK under
the Trading Standards law.


The appellant was
assessed to tax taking all the payments received from his customers into
account for calculating registration threshold, including the excess
consideration which was received by way of fraud and deception and which was
subsequently confiscated by the Court.


HELD

There was no
underlying ‘supply’ against which the excess consideration could be said to be
‘consideration’ under the Act. To deceive or to cheat is not a ‘service’ and
any amount received by deception or cheating cannot therefore be consideration
for any ‘supply’. The Tribunal considered that otherwise every fraudster and
scamster would become liable for UK VAT.        


Principles applicable to Indian law:

Section 7 of the
CGST Act taxes not only a completed supply, but also a ‘supply… agreed to be
made’. Similarly, the definition of ‘consideration’ in section 2(31) does not
only take the consideration actually paid or given, but also a ‘payment… to be
made’. Even otherwise, the term ‘consideration’ in the Indian contract law is
understood as including not just a payment actually made, but also a promise to
pay in future.

Under the contract
law, consideration procured by fraud is void. Though the GST law does not
include all the legal principles relating to a contract, this UK judgement
throws light on how the general principles of contract can sometimes aid
in understanding the concept of ‘consideration’ in the GST / VAT law, for just
like the Indian definition, the UK definition does not expressly exclude
payments made under deception and it is only on general contract principles
that the UK Court has arrived at this view. Though this judgement takes a
reasonable view, readers must not derive a general principle that the entire
body of contract law principles applies to the GST concept of ‘supply for
consideration’.


6   Whether construction of one building and
furbishing of another in the same project amounts to a single supply?


Glasgow School
of Art vs. HMRC [2019] UKUT 0173


UK UPPER TRIBUNAL

The appellant is a
Higher Education Institution Art School. It carried out a redevelopment project
which consisted of the demolition of two buildings, the partial demolition,
reconstruction and refurbishment of a building known as the assembly building
and the construction of a new building called the Reid Building. The assembly
building was then let out to the student union for low rent.


Due to ITC
attribution rules between taxable and exempted supplies, the question which
arose was whether the construction works, etc. relating to the assembly
building can be treated as a separate supply from the other work and whether
the assembly building was used for taxable supply to the student union?


HELD

There was a single
supply in this case. The economic and commercial reality of the construction
contract was a single development of the site as a whole. There was a single
delivery strategy. Funding was required and obtained for the project as a
whole. The decision not to demolish the assembly building altogether, but rather
to retain its facades and roof, was taken for reasons of value for money.
Partial demolition and refurbishment of the building on its own was never
contemplated. Additional features supporting the single supply characterisation
are the fact that there was a single contract with payment being made during
the construction phase in accordance with invoices issued for the whole
project. While no particular weight can be attached to the existence per se
of a connecting doorway, the reason for its existence, i.e., that it was
considered necessary in order to meet the environmental assessment requirement
for external funding, reinforces the view that the project should be regarded
as a single supply from an economic point of view and that a split between the
two buildings would
be artificial.


Although the
appellant wanted and obtained two separate premises with different functions,
that cannot lead to an inference that there were two separate supplies. It was
always the appellant’s intention that the project should consist of both.


Principles applicable to Indian law:

The Indian law on
composite supplies is contained in section 2(30) of the CGST Act. This decision
is instructive of the principles which can be followed in India while
determining whether a supply is composite or not.


7 ‘Direct and
immediate link’ – Nexus between input / input services and output supplies for
purposes of ITC attribution


Royal Opera
House vs. HMRC [2019] TC 7157


UK FIRST TIER TRIBUNAL

The appellant is an
internationally-renowned producer of operas. Under the UK VAT law, admission to
opera or ballet is an exempt supply. However, the appellant also makes certain
supplies which are taxable and the question involved in this appeal was whether
there was a sufficient nexus, formulated as a ‘direct and immediate link’ test
by EU and UK Courts, between the production costs and these supplies for ITC
attribution mechanism under that law. These taxable supplies are:


(1) Catering income
(bars and restaurants);

(2) Shop income;

(3) Commercial
venue hire;

(4) Production work
for other companies; and

(5) Ice cream
sales.


HELD

Catering income
(bars and restaurants)

It is the opera or
ballet that is central to everything that the Opera House (the appellant) does.
It is these performances that bring the restaurants and bars of the Opera House
their clientele. Taking an economically realistic view, the performances at the
Opera House, and therefore the production costs, are essential for the
appellant to make its catering supplies. It therefore follows that the purpose
of the production costs, objectively ascertained, is not solely for the
productions of opera and ballet at the Opera House but also to enable the Opera
House to attract clientele to the restaurants and bars and to maintain its catering
income. Therefore, the production costs do have a direct and immediate link
with the catering supplies in the bars and restaurants of the Opera House.


Shop income

The shop in the
Opera House, at its premises and online, and the sale of tickets for performances
at the Opera House are ‘separate and “freestanding” supplies.’ It was not
disputed that the production costs do have a direct and immediate link to the
sale of recordings, both audio and visual, of the Opera House productions.


However, with respect
to the remaining supplies that the shop makes, which although there is a
connection to the repertoire of the Opera House and therefore the production
costs, there is no direct and immediate link.


Commercial venue
hire

There is a direct
and immediate link between the production costs and production-specific events,
such as a gala dinner in support of a production by a sponsor. However, that
cannot be the case for other commercial events which are unconnected with the
productions themselves.


Production work
for other companies

The reputation of
the Opera House and its productions play a significant part in it receiving
orders from other opera and ballet companies to construct scenery and make
costumes. However, this is not sufficient to enable a finding that a direct and
immediate link with the production costs exists. This is because this work is
undertaken by the Opera House at a fixed price, which includes material and
labour, and as such the production costs cannot be a cost component of these
supplies.


Ice cream sales

As with catering,
the Opera House productions, with their associated costs, are essential for the
sale of ice creams. Accordingly, the production costs do have a direct and
immediate link to the sale of ice creams.


Principles applicable to Indian law:

Direct and immediate link is a test evolved by European Courts to
determine whether an input supply has sufficient nexus with output supply. It
is useful in the Indian context where, though nexus is not required generally,
it is still required where an output supply is ineligible for credit u/s 17.

II. NEW ZEALAND GST

8 Provident
Insurance Corporation Ltd. vs. CIR [2019] NZHC 995


NEW ZEALAND HIGH
COURT

The overarching
purpose of GST is to tax consumption expenditure and to tax the widest range of
goods and services with as few exceptions as possible. An exemption in GST law
must therefore be strictly construed.


Principles applicable to Indian law:

This dicta appears in a case relating to interpretation of exemptions,
the factual details of which are not necessary for the present purposes.


The normal rule of taxation is that exemptions should be strictly
construed against the taxpayer on the basis of the theory that the charging
provisions in taxing laws should be strictly construed, and therefore any
exemption from the taxing law should also be strictly construed.


The New Zealand
High Court has, in this case, given an additional and novel justification for
strict interpretation of exemptions in GST law.


DE-LAYERING RELATED PARTY TRANSACTIONS THROUGH INTERNAL AUDIT

Virtually every
business has transactions with related parties. They are a business necessity.
Businesses have related entities and they transact in a regular and routine
manner. These could be genuine transactions executed in the same manner as any
other transaction with a non-related party. However, of late the phrase Related
Party Transaction (RPT) has taken on a kind of negative connotation. Is it
justified? Perhaps not. Is it true? Perhaps not. Is it due to a few events –
real as well as alleged – where the blame for a business failure / business
loss is placed on related party transaction/s? Perhaps.


Firstly, it is not
correct to paint all RPTs with the same brush. Further, to ensure that an RPT
is genuine and fulfils business needs, laws and regulations are already in
place. The Companies Act requires approval of RPTs by the Board of Directors
and confirmation that they are at arm’s length. Similarly, SEBI (Listing
Obligations and Disclosure Requirements) Regulations prescribe a comprehensive
mechanism for the manner of dealing with related party transactions, from
approval to monitoring. The Income-tax Act requires a justification of the
transaction to ensure that there is no disallowance while computing taxable
income, as well as to ensure that there is no adjustment in a transfer pricing
assessment. Accounting standards – both Indian and international – necessitate
disclosures of RPTs. All in all, there are sufficient checks and balances in
various regulations that businesses have to adhere to vis-à-vis RPTs.


A scrutiny
mechanism is in place to achieve / assess compliance with the requirements.
This scrutiny takes place at various levels and in diverse manners. Each
scrutiniser’s objective is different and that impacts the manner and detailing
of scrutiny. The various genres of scrutinisers and their objectives can be
summarised as under:


Management – they have primary responsibility to assert that the RPT is
necessary, genuine, at arm’s length pricing and at par with any other business
transaction. They are also responsible for seeking the required approvals, from
the Board of Directors / Audit Committee of the Board, as the case may be,
before entering into RPTs;

Board of
Directors
– assertions of internal control over
financial reporting and adequacy of internal financial controls rests finally
with the Board of Directors. Apart from according approvals to
management-recommended RPTs, the Board also has governance responsibility to
ensure the adequacy of IFC and ICFR. As part of this responsibility, the Board
scrutinises the RPTs before blessing them;

Statutory
Auditor
– true and fair opinion is the deliverable
of the statutory auditor. In arriving at this opinion, he / she needs to
scrutinise the RPTs, ensuring due authorisations are in place. He / she also
signs off the proper disclosures in tandem with accounting and other reporting
standards;

Tax authorities – they scrutinise with the intention of determining whether any
adjustment is required while computing taxable income or determining adjustment
for transfer pricing. The focus of such a scrutiny is pricing and not so much
the due authorisation of the RPT;

Other regulators – this scrutiny includes the process of approvals and disclosures;

Shareholders – a body that has in the recent years heightened its scrutiny by
ensuring the appropriateness of the RPT as well as its pricing. There have been
occasions where Board-approved RPTs have been scrutinised and inquired into by
shareholders.


What about scrutiny
by internal auditors? Does the internal audit fraternity consider RPT as a
major element to be audited? There are varied experiences across industries and
sectors. For RPTs to be covered by internal audit, it would be appropriate to
consider the following factors:


Is it part of the
internal audit charter or policy document? Many large and mature organisations
have a formal IA Charter / Policy. We need to determine whether such a document
has a reference to auditing RPTs;


Does the management
have a desire of including RPTs within the ambit of internal audit? It may so
happen that managements themselves identify RPTs to be an element to be
audited;

Whether the
internal auditor has determined RPTs to be a significant business component or
/ and a significant control parameter? In both these situations the internal
auditor will need to discuss with the management and convince them of the need
of auditing RPTs;


Lastly, the view of
the Audit Committee of the Board (ACB) is also to be considered. They may
desire all or certain RPTs to be covered by internal audit. They may desire
that the process of RPTs be audited because under governance norms, the buck
stops at the ACB.


Based on the
outcome of the above processes, it is advisable for the internal auditor to
perform a risk assessment of the processes around the RPT. On such an
assessment the audit universe for the RPTs can be determined and agreed upon
with the auditee management.


THE AUDIT PROCESS

First, one needs to start with identifying related parties and examining
transactions with them. Usual source points will be the entity’s mechanism of
identifying the related parties. Are the declarations of Directors sufficient?
Or does the internal auditor need to prod beyond them? In my view, the
internal auditor will need to do an assessment of the governance process of the
company and then arrive at his / her own conclusion on the robustness and
adequacy of the same.
If reliance can be placed on the governance process
it would be easy for the internal auditor to depend on the process of
identifying the related parties. The internal auditor could also look at the
various declarations that the company would have filed with, say, MCA or with
tax authorities (for transfer pricing or GST), as also declarations made to
customs authorities during cross-border transactions. Another important source
of information would be the one submitted to bankers and lenders on who are the
related parties. The internal auditor can inquire about the group structure of
the entity, both at its parent / holding company level, as well as the
subsidiaries (including step-down subsidiaries), associates and joint ventures,
both in India and overseas.


A major risk of
audit is not identifying all the related parties and, on the basis of the above
information, the internal auditor needs to determine whether reliance can be
placed upon the information furnished. In case the auditor determines that
complete reliance is not possible, he / she will need to scrutinise further.
There will be a need to scrutinise the ledgers of the entity and identify the
possibility of the entity missing out on identifying a related party. The
auditor’s eyes and ears should be open to spotting whether there are entities
who would qualify as related parties – entities with similar sounding names or
pattern of names, entities structured as trusts, overseas entities, and so on.
This scrutiny will also give comfort to the internal auditor on the
completeness of the identification of the related parties and the transactions
with them. Needless to say, in today’s terminology the word scrutiny is
substituted by data mining. With the ERP systems deployed across organisations
and the tools available to internal auditors, data mining, if done correctly,
throws up significant information.


The second
part of the audit process involves the pricing of the RPT. And pricing is the
culmination of a business process that involves recommendation and approval by
the persons who have the authority to do so. As an internal auditor the focus
will be on the mechanism of the company to ensure that the transaction is
priced appropriately. The following sources of information and inquiry will
help the audit process:


Does the entity
have a pricing policy for RPTs?

Is it clear and
unambiguous?

Is it applied
uniformly and consistently?

Does the policy
permit deviations? If so, how are the deviations authorised?


Assess the number
of instances of deviations – how many, for which related party, for any product
or service? Data mining on the deviations will certainly throw out signals for
the internal auditor to follow and assess the genuineness of the same;


Business groups,
and multi-national groups in particular, usually have a group pricing policy.
This policy lays down the criteria of how a product or service is priced. This
policy can also have differentiating factors based on geographies or even on
product offerings;


The views taken by
tax authorities are another important source of information. Though such views
may be taken with a completely different objective, but they definitely give a
perspective from an internal audit point of view;


Consider the nature
of the transactions. Are they within ordinary course of business, or are they
not in the ordinary course of business? Depending upon this, there would be
different processes followed by the company which the auditor needs to be aware
of. A transaction within the ordinary course will have a different approval
process or would be carried with omnibus approvals of the Audit Committee or
the Board. A transaction not within the ordinary course would require a
specific approval. These processes would be defined in the various policy
documents or would be indicative of the practices followed. It may be noted
that for transactions not in the ordinary course of business, the auditor would
need to examine whether the processes followed remain consistent or not. Any
inconsistency in processes also needs to be examined further.


All these sources
of information, when properly applied, will give reasonable comfort to the
auditors on the appropriateness of the pricing of the RPT.


The most important
part of the audit process is the deployment of professional scepticism
by the internal auditor. In fact, this needs to be deployed by the auditor all
through the audit process. This will help the internal auditor to de-layer the
RPTs and determine their genuineness or otherwise, as well as their
appropriateness or otherwise. Businesses enter into RPTs consistently and
across financial years. Transactions with some related parties are more
frequent than with others. They could also be more voluminous than others. In
such an environment, the auditor will need to dig deeper into his skills,
remain sceptical and inquire into the various decision-making processes of the
auditee vis-à-vis related party transactions. Such inquiries with various
levels of management, corroborated by further supporting evidence, will help
the auditor opine on the appropriateness of the RPTs.


With so much glare
on the rightfulness or perceived wrongfulness of RPTs, internal auditors need
to walk that extra mile and de-layer RPTs to come to a proper opinion on their
reasonableness. The following checklist is just a pointer on how to handle this
de-layering and may not be considered as exhaustive:


CHECKLIST FOR HANDLING DE-LAYERING OF RPTS


Sr.
No.

Particulars

Basic points

1

Internal approval
by

2

Nature of
transaction

3

Whether the same is
in ordinary course of business? Basis for deciding ordinary course of
business:

MOA, AOA for nature
of transactions

Frequency of such
transactions entered

4

Whether transacted
on an arm’s length basis

Agreement specific

5

Tenure of agreement

6

Whether the Related
Party Transaction would affect the independence of an independent Director?

7

Rationale for
entering into the RPT

8

Is there any
non-monetary consideration given?

9

Terms of payment

10

Any other expenses

11

Interest

Points related to
arm’s length pricing

12

Documenting the
arm’s length price

13

Whether the same
pricing is used as that for other vendors?

14

Whether the terms
of the RPT are fair and on arm’s length basis to the company and would apply
on the same basis if the transaction did not involve a related party? (such
as advance payment / received, pricing, supply and other terms)

15

Has a vendor / customer
rating been done for the related party like it is done for any non-related
party, and if so, how well do they compare?

16

Is this activity
with related party needed for the company to generate revenue or achieve its
purpose or objective?

17

How are the above
terms different for a related party from a transaction entered into with a
non-related party?

18

How is the pricing
arrived at? Are there any terms which are not mentioned in the contract for
arriving at price?

Company specific

19

Relation with
related party

20

Commencement of
business with related party

21

Other services
provided by / to same related party (estimated)

22

Whether the service
is provided on a regular basis or non-regular?

23

Whether the same
service is provided by vendor on sole basis or with other vendors (may be
related or not)?

24

Whether this
activity is very uniform when it happens?

25

How far is the
financial scale of this activity compared to the relevant common denominator?
(the denominator being total sales if selling to a related party, or total
purchase if buying from a related party, or total financial expenses if
paying interest on loans to a related entity

26

Secured / unsecured

27

Whether the price
charged / paid by the company can be considered at arm’s length pricing?


REPORTING

The internal auditor will need to report his / her opinion
on the appropriateness of RPTs and the adequacy of compliance with laws,
regulations as well as internal policies and procedures. On the basis of the
above audit processes, the internal auditor will need to indicate in the report
at a minimum the following:


Existence of due
approvals for the RPT;

Reasonability of
arm’s length pricing;

Execution of the
transaction in accordance with the approvals and the pricing; and

Deviations and
exceptions, if any.

Of course, all
other principles of reporting – materiality, brevity and preciseness – remain
fundamental.


Based on the scope
and objective of the internal audit, a report on RPT could be a distinct audit
area or it could be bundled into another audit area, e.g. if one is auditing a
P2P process all the above facets around an RPT can be examined; similarly for
any other area under audit.

CONCLUSION

In my view one of the key result areas of the internal
audit function is that when placing reliance on its reports, the top management
derives comfort on the existence of controls. It has been the experience that
comfort of existence of controls enables the Board and top management to take
appropriate risk-driven business decisions. Auditing RPTs fulfils a significant
management control function. It is time that the management (Audit Committee /
Board) extends the internal audit scope to specifically cover the audit of the
process of identification of related parties, fair pricing of RPTs, their
approval and full and fair disclosures and reporting. Inclusion of this area in
Internal Audit scope is necessary to empower the Internal Auditors to gain
access, ask relevant questions and undertake a deep-dive to ensure that the
process adopted is adequate and that the organisation is complying with the
regulations relating to related parties, not just in form, but also in spirit.

The BCAJ will
carry a sequel to this article where practical examples based on Internal Audit
of Related Party Transactions will be covered
.  


BANNING THE AUDITORS

1.
    BACKGROUND


1.1     This article deals with some of the complex
issues relating to the auditor’s role and responsibilities relating to
financial reporting in the context of fraud and business failures and the
provisions of the Companies’ Act, 2013 that pertain to the removal and barring
of auditors, including firms for failure to report material misstatements
arising out of the above.


The integrity of
financial statements is important because millions of stakeholders rely on them
for decision-making. Unreliable financial reporting has serious implications;
they lead to financial losses, loss of jobs and, most importantly, they shatter
investor confidence. The law is settled: it is the primary responsibility of
management to maintain proper books of accounts and  build an effective governance framework,
including internal financial controls. However, external auditors provide the
most critical link between the company and its stakeholders. They are appointed
by the members, vested with powers specified under law and they report directly
to the members. They have access to the company’s records, systems and
processes, all the key members of management who are charged with governance:
the board, the audit committee, and all relevant management; they evaluate all
significant and other accounting policies; in essence, they do all the work
that is necessary for expressing the opinion of “true and fair” on the
financial statements.


1.2     The Ministry of Corporate Affairs (MCA)
recently launched prosecution against several auditor firms (‘current and
former’) for their alleged role in “perpetuating the fraud” in a leading
financial services and infrastructure company, a matter that has been widely reported
in the media. The MCA moved the National Company Law Tribunal (NCLT) for
debarment of these audit firms and their audit partners. It sought interim
attachment of their properties, including bank accounts and lockers.


1.3 In this context,
the ICAI Regulations provide for various actions against an individual member
for professional misconduct arising from not discharging professional
responsibilities in the manner as required. In the matter of disciplinary
action in the Satyam case, the Institute of Chartered Accountants of India
(ICAI), in an e-mailed statement, had told PTI that it has no powers to take
disciplinary action against chartered accountant firms and that a request that
was sent to the government in this regard in 2010 was yet to be acted upon… status
quo
remains even as on date. This article examines some of the complex
issues relating to the banning of auditors, this being a complex and
exceptional event. The aspects relating to the legality and powers, etc., of
the various regulatory bodies in this specific context is clearly beyond the
scope of this article.


1.4 The present law
for the removal of auditors is contained in sections 140(5) and 143(12) of the
Companies’ Act 2013, which sections we shall examine in detail because of the
wide import of these sections and the manner in which these are currently being
interpreted in terms of what actions can be (and need to be) taken against
individual engagement team members, the practice and the firm. We shall also
examine the impact that these developments will have on several contentious
issues such as, for example, the detection and reporting on fraud and business
failures during the course of audit and the consequences of failure to not
report on these matters specifically, on the engagement partner and team
members and the firm… and the profession. The MCA claims that invoking section
140(5) of the Company’s Act in the case would allow debarring an audit firm for
at least five years; the validity of these claims is being evaluated by the
NCLT.


1.5 The asymmetry
between the auditor’s role in the detection and reporting for risks of fraud
and business failures and stakeholders’ expectations is widening. In this
environment, regulators and shareholders seeking action against auditors for
not adequately addressing the risks that lead to these failures… trying to
find audit failures behind every business failure needs to be addressed.

Stakeholders, particularly the Regulators and shareholders, expect the auditors
to be vigilant and address the risk of business failures and fraudulent
practices through better audit procedures and communication. Auditors are no
longer perceived as “assurers” but as professionals, who by virtue of the role
they play and the position in which they are placed, considered as a critical
line of defense and are considered responsible in addressing the twin risks of
business failure and fraudulent conduct of managements.
The aspect of audit
failures is also a harsh reality and regulators in other countries… particularly
the UK and US are concerned about these audit failures, looking at serious
action and reforms in the auditing market.


2.
BUSINESS FAILURES AND FRAUD: THE AUDITOR’S RESPONSIBILITIES AND STAKEHOLDER EXPECTATIONS


2.1 The recent
example of business failures of large companies has clearly brought into focus
what the responsibilities of auditors are to address the related potential and
inherent risks and “red flags,”    in
their audit approach, audit tests and communications with those charged with
governance and where required under law, escalating to the regulatory
authorities cases of fraudulent conduct. Business failures happen due to
diverse reasons: economic downturns, market disruptions, liquidity crises, poor
governance, and even significant acts of fraudulent conduct by management are
factors that can individually or jointly cause businesses to fail. Hundreds of
companies in India have lined up for insolvency under the IBC; loss to
stakeholders run in several thousands of crores of rupees. Similarly, the NPA
crisis in the commercial banking sector is estimated to have caused losses that
run upward of Rs. 7 trillion…  the
economy is yet to recover from credit not flowing adequately as a result; NBFCs
as a sector have also come under severe stress, with the risk of mega failures
looming large.


2.2 Regulators and
other stakeholders not only rely on audited statements but also take financial
decisions that impact wealth, savings, investments and taxes. Business failures
and more particularly, those arising due to fraudulent conduct, result in
significant losses to lenders, investors and shareholders. The role of the
Board, the audit committee, management and auditors are invariably subject to
scrutiny and investigation. The provisions of the law provide for penalties,
imprisonment in case business failures are also on account of governance and
fraudulent conduct. Specifically, section 140(5) of the Companies Act, 2013
provides for removal of the auditor(s) if it is established that the auditor
has either acted in a fraudulent manner or abetted fraud by the company or its
officers. The NCLT’s order also renders the auditor and the firm ineligible for
appointment as auditors of any company for a period of five years. (We shall
deal with the debarring of auditors and firms later).


2.3 Since the
collapse of Enron, there have been several other large failures in the US, the
UK and India. In the UK recently, where there has been a spate of business
failures, regulatory authorities have commented on the failure of audit to
demonstrate adequate scepticism, challenge managements and constantly shifting
blame from one to another. The conclusions were unmistakable: the public and
key stakeholders had become disillusioned with the reliability of audits and
distrustful of the performance of directors. While the Competition Commission,
the Financial Reporting Council and others acknowledged the fact that there
exists an ‘expectations gap’ between what an audit does and what are the
stakeholders’ expectations from audit, the truth was that audits too often fell
short on quality and expectations.


2.4 In India, ever
since Satyam, various stakeholders have urged on the need for reform in the
audit market by way of stricter regulations and penalties and the amendments to
the Companies Act, 2013, the formation of the NFRA and the increasing role of the
SFIO are all steps in that direction.


3.
PROVISIONS UNDER THE COMPANIES’ ACT, 2013 FOR REMOVAL (INCLUDING DEBARRING)  AND RESIGNATION OF AUDITORS


3.1 Section 140(1)
provides for removal of auditors before the expiry of their term only by
special resolution and approval of the Central Government. There is also a
requirement for the auditor to be heard and to make representation to the CAG
indicating the reasons and provide facts that may be relevant.


3.2 Let us examine the provisions of
Section 140(5)


i. The
provisions of Section 140(5) provide that the NCLT can,
suo moto or based on an application from the Central Government
or a concerned person, direct change of auditors (that is, remove the auditors)
if it is satisfied that the auditor has acted in a fraudulent manner or abetted
or colluded in any fraud by the company or its directors and officers.


ii. The NCLT
passes final order for removal of the auditor (including the firm) and also rendering the auditor (including the
firm) ineligible for appointment as auditor of any company for a period of five
years, including being liable for action and punishment for fraud u/s 447 of
the Act.


3.3 Let us
examine some of the key and relevant implications (of i. and ii. above):


3.3.1 Section
140(5) does not define under what circumstances can the NCLT hold that the
auditor acted in a fraudulent manner or abetted / colluded in any fraud by the
company or its officials.
The words, ‘directly or indirectly’ appear to
qualify and may be interpreted to mean both direct participation or “tacit”
approval to fraudulent behavior by the auditor and fraud by the management.
Situations that can potentially come under the realm of “indirect fraudulent
behavior” or “indirectly abetting or colluding management fraud” could possibly
include:


– absolute, gross
negligence or turning a blind eye to what appears apparent to any reasonable
person (in position as auditor) or what the SEC describes as “reckless conduct”
by the auditor. The serious risk is that gross negligence in evaluating key
inherent risks and absence of internal controls, choosing not to pursue serious
irregularities that came to the auditor’s attention during audit and raised by
audit staff could be perceived as “tacit approval” of fraudulent conduct;

-where it is
established that the auditor was aware of serious and material irregularities
but chose not to discuss, escalate or report to those charged with governance
and to the shareholders and government and instead chose to rely on sham
representations from management;

– agreeing not to
report to shareholders serious risk of defaults in the settlement of material
obligations that could impact the sustainability of the business;

– agreeing to not
deal with serious lapses in governance, internal controls, material frauds
detected by management including non-compliance with certain laws and
regulations;

– serious conflicts
of interest that result in loss of independence as auditor to express an
opinion of true and fair.


3.3.2
Debarring the firm


To debar a firm would
mean the “direct or indirectinvolvement of every partner in the
firm to the fraudulent behavior or the act of conniving to abet or collude with
management. Debarring a firm is not unique to India; the SEC also provides for
suspending license to practice where “reckless behavior” is clearly established
at a firm-wide level. Three illustrative instances are provided to highlight
circumstances under which a firm could run the risk of being debarred:


Where the leadership
of the practice comprising of (say) the senior partners, was not only actively
involved on the engagement including managing audit quality, discussions with
management but agreeing to act in a manner clearly demonstrative of “utter
disregard” to discharge professional obligations on the engagement…

say, for example,
agreeing with management to suppress material facts that reveal involvement of
management in serious fraud. In such cases, it would therefore not be necessary
for the NCLT to hold that ‘every partner’ was involved because ‘the firm is
clearly perceived to act in disregard for professional obligations.’


Where the rendering
of non-audit services are significant; even in normal circumstances, auditors
will do well to review all non-audit services that they render to remain free
of the charge of “conflict of interest” and “independence” as these could make
them vulnerable to the risk of complicity in case of failure to detect serious
frauds and other irregularities. In this context, the rendering of non-audit
services that fall under ‘prohibited services’ as defined in section 144 of the
Act can put to risk the entire practice getting debarred in case of charges of
fraudulent behavior, connivance, etc.


Absence of firm-wide
audit methodology, ethics, risk and independence policy because regulators may
perceive the risk of audit failure as systemic and ‘waiting to happen”’any
time.


3.3.3
Complexities relating to a firm-wide ban:


Except as stated in
circumstances in 3.3.2 above, it is only under certain unique circumstances
that an entire firm could be charged with fraudulent behavior or in abetting
and colluding with management. A firm-wide ban means that all partners and
employees (including non-professional employees) are being accused and charged
under the section for fraudulent conduct or for complicity. Where the NCLT
Order has the effect of banning an entire firm for a period of five years, it
has to be established that the entire firm comprising the firm leadership, the
audit partners (not only from the engagement team but also from other teams and
other locations) and the tax and advisory partners in that firm
had all connived with or abetted in the fraudulent activities in the company.
Without a detailed investigation into the affairs of the firm, and its risk
management policies, every correspondence, every mail box, the risk management
policies, the audit methodology… the list is endless! How can an authority
establish beyond all reasonable doubt that the entire firm was involved in
abetting or conniving with management, especially when over a hundred partners
typically work in these large firms in different disciplines and departments
remains a challenge! The provisions appear arbitrary and rigid… this can
only cause serious harm to the entire process of reforms that the Regulators
are working towards.


3.3.4 Learning
from global best practices: How SEC, PCAOB, deal with major audit failures and
suspension of licenses:


i. The SEC/PCAOB
Regulations provide for Removal, Suspension, or Debarment of Accounting Firms
or Offices of firms. The rules identify factors the Regulators consider in
determining the appropriate penalty and remedy. Under current regulations
governing practice, the Regulator can remove, suspend, or debar a firm by
naming each member of the firm or office in the order of suspension or
debarment. The Regulations provide that, in considering whether to take action
against a firm and the severity of the sanction against a firm, the Regulator
may assess the gravity, extent of involvement of firm personnel, including the
leadership, scope, or repetition of the act or failure to act; the adequacy of
and adherence to applicable policies, practices, or procedures for the firm’s
conduct of its business and the performance of audit services; the selection,
training, supervision, and conduct of members or employees of the firm involved
in the performance of audit services; the extent to which managing partners or
senior officers of the firm participated, directly or indirectly through
oversight or review, in the act or failure to act; and the extent to which the
firm has, since the occurrence of the act or failure to act, implemented
corrective internal controls to prevent its recurrence. Section 140(5) contains
no such mitigating provisions. None of the regulatory agencies in India,
barring the ICAI have any mechanism or laid down procedure to examine these
aspects.
The results can only be arbitrary and harm the profession.


ii. There is no
exhaustive list of factors and circumstances may present other facts that the
Regulator will take into account in determining whether to take an action
against a firm. The Regulators anticipate that there may be circumstances in
which it will not be appropriate to remove, suspend, or debar an entire firm,
but that action should be taken against a particular office or specific offices
of the firm. The Regulator would hold hearings on removals, suspensions, and
debarments under rules that are consistent with the relevant Rules of Practice
and Procedure including, provide among other things, for written notice to the
respondent of the intended action and the opportunity for a public hearing
before an appropriate judge. Reckless and ‘disreputable conduct’ including
mainly, aiding and abetting violations, of specified laws and the reckless
provision of false or misleading information, or reckless participation in the
provision of false or misleading information also may lead to removal,
suspension, or debarment of firms. The most important point is, except in a
case where the continuance of a firm could cause irreparable damage to the
Regulatory environment because of extreme and reckless behaviour, it was felt
that an immediate suspension would not stand up to any legal scrutiny.


iii. The provisions
of Section 140(5) appear limited in scope in terms of dealing with the removal
of auditors for fraudulent conduct and connivance and not with past cases of
audit failures. The Companies Act also appears clearly ill-equipped to
prescribe elaborate procedures for determining professional misconduct of the nature
described in Section 140(5).
An independent agency will need to be set up
on the lines of the PCAOB to inspect firms (public interest entity audits may
be taken up) on quality, risk and independence. That agency will frame
regulations on various aspects of audit so that there is a comprehensive and
professional basis for evaluating firms on risk, independence and quality…
Section 140(5) cannot be used as a ‘lone wolf’ provision to penalise and debar
auditors. The Regulators cannot step in only to penalise auditors; they have a
more constructive role to play for the development and sustenance of the
profession.


iv. The US and the
UK have framed regulations on similar lines that deal specifically with removal
and debarring of auditors. But, these are all based on a comprehensive
framework and procedures to proactively deal with audit risk and quality.
Section 140(5) needs to be backed by a similar structure before enacting laws
for removal and debarring of auditors. The PCAOB and its equivalent in the UK
have been therefore effective in identifying audit failures and disciplinary
actions taken by regulators against firms including the Big Four act as a
deterrent for reckless audit. Firms and partners are penalised and there is a
specific plan that is laid down by the regulator for the audit firm to
implement. These form the basis for the regulator to conclude whether auditors
indulge in repeated wrongful behaviour… to conclude whether the firm needs to
be considered for debarment. Matters are referred to a judicial authority to
decide on the case. These processes and procedures are designed to ensure that
the regulators and auditors work together and play an important role in the
improvement of the financial markets and the financial reporting process.


v. The current
scenario where several investigative agencies investigate and interrogate
auditors on the same issues is gross and counter-productive because they have
otherwise no role to play in the development of the profession. The SEC and the
PCAOB in the US and the FRC in the UK are known to be extremely methodical in
their approach but, their credibility arises on account of their deep knowledge
of all aspects of the financial reporting process and also, their role in
developing auditing standards, building audit quality and risk management.


3.3.5 Section
447 and the “intent to deceive”


 i. Section 447 of the Act defines ‘Fraud’ to
include any act, omission, concealment of any fact or abuse of position
committed by any person by himself or by connivance with an ‘intent to deceive.’ This imposes a challenge
because the auditor does not have the benefit of scrutinising and identifying
fraudulent financial transactions in the books because ‘intent to defraud’
would in most cases reflect in the financial books at some future date.


ii. The start point
for an auditor would be a detailed evaluation of the key inherent risks, based
on a deep understanding of the business, the overall control environment and
the company’s history of internal control failures, manifestation of business
risks and incidence of frauds.


iii. Detailed
consultation with those charged with governance is necessary; the primary
responsibility for maintaining internal financial controls and books of
accounts that are free of material misstatements is that of management. The
auditor will need to discuss the risk of fraud with the audit committee and the
internal auditors because they are best placed to discuss “red flags” in
the system.


iv. In all this, it
is extremely important for the auditor to remain compliant with the mandatory
accounting standards and the standards on auditing.


3.3.6 Business
failure and fraudulent reporting


i. Businesses fail due to a myriad of reasons ranging from economic
downturns, liquidity crisis in the markets, project failures not within the
control of the business, market disruptions, and internal factors such as poor
quality of leadership, serious governance failures including frauds, diversion
of funds for other than agreed upon end use, etc.


ii. To understand
the asymmetry on the expectations between auditors and stakeholders on business
failures, let us examine these situations:


(a) It is common and an inherent risk for a company which is in the
business of infrastructure, of a future asset-liability mismatch arising on
account of a project that is not getting completed for reasons beyond the
control of management. Loan instruments with a repayment schedule of more than
ten years are few and involve complexities because they are mostly
quasi-equity, lenders are inherently averse to fund long term, etc. There is a
continuing risk of the project getting delayed, resulting in a serious asset
liability mismatch. The risk that a delay can seriously weaken the company’s
ability to service debt on the due dates can be seriously jeopardised in the
matter of a single quarter, leaving the auditor with an extremely small window
to call out the risk of not honouring a payment on the due date.
“Round-Tripping” is therefore a common occurrence in the financial sector and
is ordinarily not associated with a collapse. It is common practice for lenders
to “roll-over” loan instalments that fall due for payment and the parties enter
into an arrangement to pay at a later pre-determined date where the borrower
pays a few days after the due date. The lenders also understand that these are
“acceptable  aberrations” that occur
because of temporary mismatch in cash flows… all is accepted because of the
knowledge that the borrower is not a “fly-by-night” operator. But recent
examples prove that a single case of “round-tripping” can cause a series of
defaults.


(b) The auditors
would have, in the course of audit, examined and documented the risk of such
aberrations as “moderate” because of the overall solvency and profits. Also,
past record of payments on due dates would have resulted in the risk being
classified as “moderate”. In a case where the default happens on a
date subsequent to the balance sheet date but only a few days before audit sign
off and the lender communicates his unwillingness to “roll over,” there could
be a serious crisis and a chain reaction where no lender trusts the ability of
the business to honour its debts on due dates. The classification of audit risk
as “moderate” could become suddenly a matter of “suspect judgement.”

(c) Due to the
adoption of  fair value accounting, the
carrying value of a project may undergo a significant downward revision on
account of impairment close to balance sheet date. Estimates and year-end
valuations continue to pose the biggest challenge to auditors and more so in a
case where the business failure results in a roving inquiry into the entire
gamut of governance. Post-IFRS and Ind-AS, implementation and the use of
fair values, the “cushion” that was available in historical cost regime no
longer exists. Regulators and other stakeholders need to accept the fact that
these errors in estimates are inherent to the adoption of fair value
accounting.


3.3.7 The
challenges of Holding Subsidiary company relationships:


i. In India, the
auditing standards require the auditors of the consolidating entity to rely on
the work of the component auditor without having to review all of the work
papers of the subsidiaries. The Companies Act 2013 provides the consolidating
auditors access to the work papers of all the component auditors.


ii. However, SEBI plans
to make it mandatory for auditors of parent companies to review the work of all
the auditors of subsidiary companies before being approved by the board. This
possibly arises on account of the crisis at IL&FS where Regulators believe
that auditors of the parent companies were not familiar with the processes and
risks at the subsidiary level, resulting in various irregularities including,
mainly, the misuse of funds transfers and “ever-greening” of loans at the
subsidiaries’ level.


iii. The
traditional view that each company is an independent legal entity is being
challenged by authorities all over the world because of certain specific
reasons.
The Holding Company invariably exercises significant control over
all major board decisions at the subsidiary level by controlling the board
composition, centralised operating decisions such as purchases, funding,
significant transactions between the parent and the subsidiaries, common
statutory and internal auditors and policies on risk ethics and compliance. Given
all these inter-dependencies, it is very difficult to hold that the subsidiary
boards and management are independent and responsible for their
governance-related matters. As a result, members on the board of a holding
company are no longer insulated against charges of governance failures at the
subsidiary level. The same holds good for auditors of the holding company: in
most instances, almost all the material subsidiary accounts are audited by
them, they circulate detailed audit instructions and in a few cases, almost all
significant audit matters are discussed by them with the component auditors of
the material subsidiaries, their audit committees and respective boards.


iv. The SEBI
believes that parent company auditors cannot be merely “consolidating” without
an understanding of the key audit risks and significant audit matters by the
respective component auditors and, how they have been discussed and dealt with
in the auditors’ reports.


v. Parent company
auditors will therefore need to extend their involvement to obtain detailed
understanding of all key matters including key risks identified during audit
planning meetings risk, how the audit tests were designed to deal with these
risks including the risk of fraud and internal control weaknesses.


4. HOW DO AUDITORS RESPOND IN THIS HEIGHTENED LEVEL OF RISK AND LITIGATIVE ENVIRONMENT?


We shall deal with
the three top level changes that auditors must make in their audit
strategy to address the heightened level of risk of frauds and business
failures and the litigative environment that exists. These are in addition to
the audit tests prescribed in the standards of auditing prescribed by the ICAI:


(a) Audit
Planning:
More often than not, the time and qualitative attention that
auditors devote to plan the audit is inadequate. Audit planning must focus
categorically on the issue of various aspects of risk: Risks inherent to the
business are the most critical because they define what the risk framework
should be. Hitherto there has been a lack of focus on factors that could
significantly impact business continuity and these risks typically include the
main risks of business and governance failure. This risk summary will be a
critical document that needs to be updated at every stage of the audit because
new risks emerge as the auditor gains deeper insights into the business. The
auditor must discuss this list internally with the team and with all those who
are entrusted and charged with governance: the Board, the management, the audit
committee and the internal auditors at key stages of the audit to assess how
these risks are being addressed. These discussions must be documented in
detailed manner such that the principle of ‘due care’ is established;


(b) Evaluating
the Corporate Governance Framework:
Assess the quality and
independence of the Corporate Governance Framework: Typical “red flags” include
a weak set of “independent directors” who typically do not stand up to discuss
potential risks to governance, internal auditors who structurally report to the
finance head, the presence of significant related party transactions,
reluctance to discuss incidents of fraud, ignoring whistleblower incidents…as a
result, the auditor is the only effective link in the entire corporate
governance structure.


(c) Paying
attention to the ‘Critical Audit Matters’ (CAM)
section at every stage
of the audit: Most often discussion on CAM happens in the later stages of
audit, an area that is, in the current context, the most effective line of
defence. Clients also demonstrate resistance to discuss CAM at the last minute,
exposing the auditor to serious risks.


(d) Evaluating
the Directors’ Report and MD&A:
These two sections are typically
areas of inadequate focus because they are made available only a couple of days
before audit sign off. It is critical to examine these two sections for
inadequacies in management reporting of business risks, key business developments
such as dealing with potential failures to meet loan repayment obligations,
etc.


(e) Making
effective use of Management Rep Letters:
It has been established time
and again that Rep Letters are not a critical line of defence and do not
substitute substantive audit verification tests that the auditor is required to
perform. However, ‘Minutes’ of discussions and explanations received from
Management serve as ideal “back up.” It is also common practice to discuss
Management Rep Letters with Audit Committees for the important representations
made by management. As a rule, auditors should expect Rep Letters to help only
in situations where no alternative sources of “comfort” exist or are available.
In such case too, auditors must consider drawing attention to important
representations made in the audit report by way of EoM or in extreme cases by
way of a “Qualification.”


5. CONCLUSIONS


While the primary
responsibility for the prevention and detection of fraud continues to rest with
management, auditors must accept that the responsibility to adopt robust audit
procedures and ferret out “red flags” that are indicative of imminent failures
in governance, risk and even business. For example, significant erosion of
asset values due to ‘mark to market’ considerations should seriously bother the
auditor not only from an asset impairment perspective but from the ability of
the business to service external debt. Similarly, asset liability mismatches
that could seriously erode the confidence and comfort of lenders require
significant audit attention; this is the new reality that auditors must accept;


It is imperative for
auditors to get audit files and documentation on Public Interest Entity (PIE)
audits “cold reviewed” by an independent team before date of sign off. This
process involves time and must be ‘in-built’ into the time commitment made by
the auditor to the client on date of audit closure;


Management
Discussion & Analysis (MD&A) and Board Reports are important documents
that the auditor should review before audit clearance since they communicate
what the management “holds out” in terms of what management perceives are the
key risks and how they are being dealt with… the structure of the 10K that
SEC Registrants file would be a good benchmark.


Non-audit services
proposed to be rendered should be subject to internal ‘risk clearances’ and
audit
committee approvals to avoid any vulnerabilities that may arise in case a
serious fraud is detected and the question of auditor independence becomes the
subject matter of litigation.


Communications with
those charged with governance is as much a cultural issue as it is a technical
one. Special skills are necessary to structure these conversations such that
the auditor can establish to any regulatory authority that the auditors have
done all that was expected to be done.


Section 40A(9) – Business disallowance – Contribution to a fund created for the healthcare of the retired employees – The provision was not meant to hit genuine expenditure by an employer for the welfare and benefit of the employees

15.  The Pr. CIT-2 vs. M/s State Bank of India
[Income tax Appeal No. 718 of 2017;

Date of order: 18th June,
2019

(Bombay High Court)]


M/s State Bank of India vs. ACIT
Mum., ITAT


Section 40A(9) – Business
disallowance – Contribution to a fund created for the healthcare of the retired
employees – The provision was not meant to hit genuine expenditure by an
employer for the welfare and benefit of the employees


The assessee
claimed deduction of expenditure of Rs. 50 lakhs towards contribution to a fund
created for the healthcare of retired employees. The Revenue contented that
such fund not being one recognised u/s 36(1)(iv) or (v), the claim of
expenditure was hit by the provisions of section 40A(9) of the Income-tax Act.
The CIT(A) upheld the AO’s order.


On appeal, the
Tribunal held that the assessee had made such contribution to the medical
benefit scheme specially envisaged for the retired employees of the bank.
Sub-section (9) of section 40A of the Act, in the opinion of the Tribunal, was
inserted to discourage the practice of creation of bogus funds and not to hit
genuine expenditure for welfare of the employees. The AO had not doubted the bona
fides
of the assessee in the creation of the fund and that such fund was
not controlled by the assessee-bank. The Tribunal proceeded on the basis that
the AO and the CIT(A) had not doubted the bona fides in creation of the
trust or that the expenditure was not incurred wholly and exclusively for the
employees. The Tribunal thus allowed the assessee’s appeal on this ground and
deleted the disallowance.


Aggrieved with
the ITAT order, the Revenue filed an appeal in the High Court. The Court held
that sub-section (9) of section 40A disallows deduction of any sum paid by an
assessee as an employer towards setting up of or formation of or contribution
to any fund, trust, company, etc. except where such sum is paid for the
purposes and to the extent provided under clauses (iv) or (iva) or (v) of
sub-section (1) of Section 36, or as required by or under any other law for the
time being in force. It is clear that the case of the assessee does not fall in
any of the above-mentioned clauses of sub-section (1) of section 36. However,
the question remains whether the purpose of inserting sub-section (9) of
section 40A of the Act was to discourage genuine expenditure by an employer for
the welfare activities of the employees. This issue has been examined by the
Court on
multiple occasions.


The very
purpose of insertion of sub-section (9) of section 40A thus was to restrict the
claim of expenditure by the employers towards contribution to funds, trusts,
associations of persons, etc. which was wholly discretionary and did not impose
any restriction or condition for expanding such funds which had possibility of
misdirecting or misuse of such funds, after the employer claimed benefit of
deduction thereof. In plain terms, this provision was not meant to hit genuine
expenditure by an employer for the welfare and the benefit of the employees.


In the case of
Commissioner of Income Tax vs. Bharat Petroleum Corporation Limited (2001) Vol.
252 ITR 43
, the Division Bench of this Court considered a similar issue
when the assessee had claimed deduction of contribution towards staff sports
and welfare expenses. The Revenue opposed the claim on the ground that the same
was hit by section 40A(9) of the Act. The High Court had allowed the assessee’s
appeal.


In the case of
Commissioner of Income-tax-LTU vs. Indian Petrochemicals Corporation
Limited (2019) 261 Taxman 251 (Bombay),
the Division Bench of the
Bombay High Court considered the case where the assessee-employer had
contributed to various clubs meant for staff and family members and claimed
such expenditure as deduction. Once again the Revenue had resisted the
expenditure by citing section 40A(9) of the Act. The Court had confirmed the
view of the Tribunal and dismissed Revenue’s appeal.


In view of same, the Revenue appeal was dismissed.

14. Section 271(1)(c) – Penalty – Concealment – Two views are possible – When two views are possible, penalty cannot be imposed

14.  Section 271(1)(c) – Penalty – Concealment –
Two views are possible – When two views are possible, penalty cannot be imposed


The assessee is a co-operative
bank. It had incurred expenditure for acquisition of three co-operative banks.
Claiming directives of the RBI contained in its circular, the bank amortised
such expenditure over a span of five years. The Revenue was of the opinion that
the expenditure was capital in nature and that the claim of expenditure would
be governed by the Income-tax Act, 1961 and not by the directives of RBI. The
expenditure was therefore disallowed.


The AO initiated proceedings for
imposition of penalty u/s 271(1)(c) and held that the assessee has deliberately
made a wrong claim of deduction which is otherwise inadmissible. Accordingly,
the AO proceeded to pass an order imposing a penalty of Rs. 1,41,30,553 u/s
271(1)(c).


Being aggrieved at the penalty
order so passed, the assessee preferred an appeal before the CIT(A). The CIT(A)
observed that the AO had taken a view that the expenditure is capital in nature
due to the enduring benefit accruing to the assessee, but as per the RBI
circular the assessee is allowed to amortise 1/5th of the expenditure over a
period of five years. He, therefore, inferred that there exist two different
views with regard to the assessee’s claim. Accordingly, he held that the issue
on which the addition was made being a debatable one, it cannot be said that
the claim made by the assessee is totally inadmissible. The assessee has
furnished all requisite particulars of income, so it cannot be said that the
assessee has furnished inaccurate particulars of income or concealed its
income. The Commissioner (A), relying upon the decision of the Hon’ble Supreme
Court in CIT vs. Reliance Petroproducts Pvt. Ltd. [2010] 322 ITR 158
(SC),
deleted the penalty imposed by the AO.


But Revenue, now aggrieved by the
order of the CIT(A) preferred an appeal before the ITAT. The Tribunal held that
the addition on the basis of which penalty was imposed by the AO as on date
does not survive. Moreover, on a perusal of the circular issued by the RBI as
referred to by the CIT(A), it is seen that the acquirer bank is permitted to
amortise the loss taken over from the acquired bank over a period of not more
than five years, including the year of merger. It is also noticed that in the
case of Bank of Rajasthan, the Tribunal has allowed it as revenue expenditure.
Therefore, the claim made by the assessee cannot be said to be totally
inadmissible, or amounts to either furnishing of inaccurate particulars of
income or misrepresentation of facts. It is possible to accept that the
assessee being guided by the RBI circular has claimed the deduction. In such
circumstances, the assessee cannot be accused of furnishing inaccurate
particulars of income, more so when the assessee has furnished all relevant
information and material before the AO in relation to the acquisition of three
urban co-operative banks.


The
High Court held that, in relation to the assessee’s claim of expenditure, two
views were possible. Even otherwise, the Revenue has not made out any case of
concealment of income or concealment of particulars of any income. As is well
laid down through a series of judgements of the Supreme Court, raising a bona
fide
claim even if ultimately found to be not sustainable, is not a ground
for imposition of penalty. In the result, the Revenue Appeal was dismissed.

Jalaram Enterprises Co. P. Ltd. vs. DCIT [ITA No. 4289/Mum./2014; Bench: J; Date of order: 29th April, 2016; Mum. ITAT] Section 68 – Cash credits – Unsecured loans received – The assessee has proved identity, genuineness of the transaction and the creditworthiness of the lenders – no addition can be made

13.  Pr. CIT-15 vs. Jalaram Enterprises Co. P.
Ltd. [Income tax Appeal No. 671 of 2017;

Date of order: 7th
June, 2019;

A.Y.: 2010-11 (Bombay High
Court)]


Jalaram Enterprises Co. P. Ltd. vs.
DCIT [ITA No. 4289/Mum./2014; Bench: J; Date of order: 29th April,
2016; Mum. ITAT]


Section 68 – Cash credits –
Unsecured loans received – The assessee has proved identity, genuineness of the
transaction and the creditworthiness of the lenders – no addition can be made


The assessee is a private limited
company engaged in the business of trading in real estate and grains. The
assessee had shown borrowings of Rs. 3 crores. The AO verified the same and was
of the opinion that the transactions were not genuine. He made addition of Rs.
2,66,00,000 out of the said sum of Rs. 3 crores u/s 68 of the Act.


The CIT(A) in his detailed order
allowed the assessee’s appeal and deleted the addition. He noted that out of 12
lenders, nine were parties to whom the assessee had allotted the shares of the
company on 1st April, 2010. The amounts deposited by these parties
therefore were in nature of share application money. He also noted that in
response to summons issued by the AO, the assessee had submitted the reply and
response of all the lenders with supporting material. He noted that all 12
parties had confirmed the transactions, produced their bank statements and a
majority of them had filed their income tax returns, in which computation of
their income for A.Y. 2010- 11 was also available. The CIT(A) therefore held
that the transactions were genuine and that the assessee had established the
source and the creditworthiness of the lenders.


The Revenue took the matter before
the Tribunal. The Tribunal held that the AO made addition u/s 68 of the Act in
respect of 12 parties holding that the creditors had not appeared in response
to the summons issued u/s 131 of the Act; he also held that the genuineness of
the transaction and creditworthiness of the creditors was not established.


The assessee has proved the
identity and genuineness of the transaction and the creditworthiness of the
lenders by furnishing the requisite details, like confirmations, PAN details,
return of income, bank statements, etc. It is the finding of the CIT(A) that
first deposits were received through bank transfers from the lenders’ accounts
and thereafter they were given to the assessee company by account payee cheque.
In the circumstances, the order of the CIT(A) in deleting the addition made u/s
68 of the Act was upheld.


Being
aggrieved with the ITAT order, the Revenue filed an appeal to the High Court.
The Court held that the entire issue is based on appreciation of evidence. The
CIT(A) and the Tribunal had come to the concurrent conclusions on facts which
were shown not to be perverse. The Revenue appeal was dismissed.

Sections 194, 194D and 194J of ITA, 1961 – TDS – Works contract or professional services – Outsourcing expenses – Services clerical in nature – Not technical or managerial services – Tax deductible u/s 194C and not u/s 194J TDS – Insurance business – Insurance agent’s commission – Service tax – Quantum of amount on which income-tax to be deducted – Tax deductible on net commission excluding service tax

38.  CIT vs. Reliance Co. Ltd.; 414 ITR 551 (Bom.)

Date of order: 10th
June, 2019

A.Y.: 2009-10


Sections 194, 194D and 194J of ITA,
1961 – TDS – Works contract or professional services – Outsourcing expenses –
Services clerical in nature – Not technical or managerial services – Tax
deductible u/s 194C and not u/s 194J


TDS – Insurance business –
Insurance agent’s commission – Service tax – Quantum of amount on which
income-tax to be deducted – Tax deductible on net commission excluding service
tax


The assessee,
an insurance company, deducted tax at source u/s 194C of the Income-tax Act,
1961 on payment of outsourcing expenses. The Department held that the tax ought
to have been deducted u/s 194J on the ground that the payments were for
managerial and technical services. The assessee deducted the tax at source on
the agent’s commission excluding the service tax component, which it directly
deposited with the Government. The Department contended that the service tax
component ought to have been part of the amount on which tax was required to be
deducted at source.


The
Commissioner (Appeals) and the Tribunal found that the services outsourced were
clerical in nature and that the payments made by the assessee were neither for
managerial services nor for technical services and that the charges for event
management paid by the assessee were for services in the nature of travel agent
and allowed the assessee’s claim. The Tribunal referred to the Circular of the
CBDT wherein it was provided that the deduction of tax at source was to be made
in relation to the income of the payee and held that tax was deductible on the
net insurance commission of the agent after excluding the service tax component
from the gross commission.

On appeal by
the Revenue, the Bombay High Court upheld the decision of the Tribunal and held
as under:


“(i)   The work outsourced by the assessee was in
the nature of clerical work. The Tribunal was justified in holding that the tax
at source was deductible u/s 194C and not u/s 194J.


(ii)         The
commission payment made to the agent was the net commission payable excluding
the service tax component which was required to be directly deposited with the
Government. The Tribunal was justified in holding that the tax was deductible
from the payment of net commission to the agents, after excluding the service
tax component from the gross commission.”

Sections 132 and 133A of ITA, 1961 – Search and seizure – Survey converted into search – Preconditions not satisfied – Action illegal and invalid

37.  Pawan Kumar Goel vs. UOI; [2019] 107
taxmann.com 21 (P&H)

Date of order: 22nd
May, 2019


Sections 132 and 133A of ITA, 1961
– Search and seizure – Survey converted into search – Preconditions not
satisfied – Action illegal and invalid


The respondent tax officials
entered the business premises of the assessee and he was allegedly asked to
sign documents without disclosing their contents. Upon raising a question the
respondents supplied him with a copy of summons u/s 131 of the Income-tax Act,
1961 informing him that the officials wanted to carry out a survey operation
u/s 133A. The assessee submitted that although the summons indicated survey
operations but the procedure was converted into search and seizure which was
impermissible in law.


The assessee therefore filed a writ
petition with a prayer that the process of search and seizure conducted by the
respondents on his business premises be quashed and set aside.


The Punjab and Haryana High Court
allowed the writ petition and held as under:


“(i)   The respondents have not demonstrated from any material as to
whether the assessee failed to co-operate, which is an eventuality where the
income-tax authority would be required to record its reasons to resort to the
provisions of section 131(1) and convert the whole process into search and
seizure. But this is completely missing from the process.


(ii)   This, to our minds, is fatal to the cause of the respondents
because in a procedure like this which can often turn draconian the inherent
safeguard of at least recording a reason and satisfaction of non-co-operation
to resort to other coercive steps needs to be set out clearly by the income-tax
authority.


(iii)   The action of the respondents is therefore bad in the eye of law.
Besides, the summons issued to the assessee was totally vague. No documents
were mentioned which were required of the assessee and neither was any other
thing stated.


(iv)  Similarly, the argument of the assessee that provisions of section
131(1) could be invoked only if some proceedings were pending is agreeable. In
the instant case there was only a survey operation and no proceedings were
pending at that point of time. But the income-tax authority exercised the
powers of a court in the absence of any pending proceedings.

(v)   Thus,
the income-tax authority violated the procedure completely. Nowhere was any
satisfaction recorded either of non-co-operation of the assessee or a suspicion
that income has been concealed by the assessee warranting resort to the process
of search and seizure.


(vi)        For the reasons above, it is to be
concluded that the instant petition deserves to succeed. The impugned action of
the respondents is quashed. The consequential benefits would flow to the
assessee forthwith.


Ordered accordingly.”

Section 4 of ITA, 1961 – Income or capital – Assessee a Government Corporation wholly owned by State – Grant-in-aid received from State Government for disbursement of salaries and extension of flood relief – Funds meant to protect functioning of assessee – No separate business consideration between State Government and the assessee – Flood relief not constituting part of business of assessee – Grant-in-aid received is capital receipt – Not taxable

36.  Principal CIT vs. State Fisheries Development
Corporation Ltd.; 414 ITR 443 (Cal.)

Date of order: 14th
May, 2018

A.Y.: 2006-07


Section 4 of ITA, 1961 – Income or
capital – Assessee a Government Corporation wholly owned by State –
Grant-in-aid received from State Government for disbursement of salaries and
extension of flood relief – Funds meant to protect functioning of assessee – No
separate business consideration between State Government and the assessee –
Flood relief not constituting part of business of assessee – Grant-in-aid
received is capital receipt – Not taxable


The assessee was engaged in
pisciculture and was a wholly-owned company of the State Government. It
received certain amounts as grant-in-aid from the State Government towards
disbursement of salary and provident fund dues and for extension of flood
relief. The AO treated the amount as revenue receipts on the ground that the
funds were applied for items which were revenue in nature and disallowed the
claim for deduction by the assessee. It was contended by the assessee that
though the funds were applied for salary and provident fund dues, the object of
the assistance was to ensure its survival.


The Tribunal allowed the assessee’s
claim.


On appeal by the Revenue, the
Calcutta High Court upheld the decision of the Tribunal and held as under:


“(i)   The finding of the Tribunal that the amount received by the assessee
from the State Government in the form of grant-in-aid utilised for clearing the
salary and provident fund dues and flood relief was capital in nature was
correct.


(ii)   The amount received by the assessee was not on account of any
general subsidy scheme. Though the grant-in-aid was received from the public
funds, the State Government being a hundred per cent shareholder, its position
would be similar to that of a parent company making voluntary payments to its
loss-making undertaking. It was apparent that the actual intention of the State
Government was to keep the assessee, facing a cash crunch, floating and
protecting employment in a public-sector organisation. There was no separate
business consideration on record between the grantor-State Government and the
recipient-assessee.


(iii)        Since flood relief did not constitute
part of the business of the assessee, the funds extended for flood relief could
not constitute revenue receipt.”

Section 5 of ITA, 1961 – Income – Accrual of income – Mercantile system of accounting – Bill raised for premature termination of contract and contracting company not accepting bill – Income did not accrue – Another bill of which small part received after four years – Theory of real income – Sum not taxable – Any claim of assessee by way of bad debts was to be adjusted

35.  CIT(IT) vs. Bechtel International Inc.; 414
ITR 558 (Bom.)

Date of order: 4th June,
2019

A.Y.: 2002-03


Section 5 of ITA, 1961 – Income –
Accrual of income – Mercantile system of accounting – Bill raised for premature
termination of contract and contracting company not accepting bill – Income did
not accrue – Another bill of which small part received after four years –
Theory of real income – Sum not taxable – Any claim of assessee by way of bad
debts was to be adjusted


The assessee was in the
construction business. It did not include in its return two sums of Rs. 26.47
crores and Rs. 59.51 crores, respectively, for which it had raised bills but
had not accounted for in its income. The AO rejected the assessee’s contention
that those amounts had not accrued to it and that even on the basis of the
mercantile system of accounting followed by it, the amounts need not be offered
to tax. But the AO was of the opinion that since the assessee had raised the
bills, whether the payments were made or not was irrelevant since the assessee
followed the mercantile system of accounting.


The
Commissioner (Appeals) held that the sum of Rs. 59.51 crores, for which the
assessee had raised the bill after the termination of the contract, could not
have been brought to tax since the bill pertained to the mobilisation and site
operation cost; but in respect of the sum of Rs. 26.47 crores, he did not grant
any relief on the ground that the bill pertained to the construction work that
had already been carried out before the termination of the contract. The
Tribunal found that in respect of the sum of Rs. 59.51 crores, the assessee was
awarded the contract of the project of the parent company of the contracting
company, that the parent company was in severe financial crises, that the
assessee raised the bill after the termination of contract, that the bill was
not even accepted by the contracting company and that the income never accrued
to the assessee. In respect of the amount of Rs. 26.47 crores, the Tribunal
found that due to the financial crises of the parent company of the contracting
company, the assessee could not receive any payment for a long time and could
recover only 8.58% of the total claim and, inter alia applying the
theory of real income, deleted the addition. The assessee had also in a later
year claimed the same amount by way of bad debts. The Tribunal while giving
relief to the assessee ensured that any such amount claimed by way of bad debts
was to be adjusted.


On appeal by the Revenue, the
Bombay High Court upheld the decision of the Tribunal and held as under:


“(i)   The Tribunal did not err in holding that no real income accrued to
the assessee as only 8.58% of the total claim was received, applying the real
income theory, bill amount of Rs. 26.47 crores due to the financial crises of
the parent company of the contracting company, and in respect of the sum of Rs.
59.51 crores on the ground that the bill was raised after the termination of
the contract and the bill was not even accepted by the contracting party.


(ii)         The claim of Rs. 59.51 crores was for
damages for the premature termination of the contract. Any further examination
of the issue would be wholly academic since the assessee could have claimed the
amount by way of bad debts. In fact, such claim was allowed, but in view of the
further development, pursuant to the decision taken by the Tribunal, such claim
was ordered to be adjusted.”

Sections 2(24) and 4 of ITA, 1961 – Income – Meaning of – Assessee collecting value-added tax on behalf of State Government – Excess over expenditure deposited in State Government Treasury – No income accrued to assessee

34.  Principal CIT vs. H.P. Excise and Taxation
Technical Service Ltd.; 413 ITR 305 (HP)

Date of order: 7th
December, 2018

A.Ys.: 2007-08 to 2011-12 and
2013-14


Sections 2(24) and 4 of ITA, 1961 –
Income – Meaning of – Assessee collecting value-added tax on behalf of State
Government – Excess over expenditure deposited in State Government Treasury –
No income accrued to assessee


The assessee-society was registered
under the Societies Registration Act, 1860 on 27th August, 2002.
Under the objects of its formation the assessee was entrusted with the
responsibility of collection of value-added tax. The assessee maintained all
the multi-purpose barriers in the State of Himachal Pradesh from where all
goods entered or left the State in terms of section 4 of the Himachal Pradesh
Value-Added Tax Act, 2005. A form was to be issued to the person declaring the
goods at a cost of Rs. 5 per form till the levy was further enhanced to Rs. 10
w.e.f. 18th May, 2009. In terms of the bye-laws, the assessee used
to deposit Re. 1 per declaration  form
with the Government Treasury out of the Rs. 5 received till the year 2009; this
was later enhanced to Rs. 2 after the tax amount was increased from Rs. 5 to Rs
10 per declaration form. The assessee had been showing the surplus of income
over expenditure in its income-expenditure statements. The AO, therefore,
issued notices u/s 148 of the Income-tax Act, 1961 for taxing the excess of
income over expenditure. For the A.Y.s 2007-08 and 2010-11 the assessee
contested the notices stating that all the surplus income was payable to the
State Government and, therefore, it had earned no taxable income. The AO rejected
the assessee’s claim.


The Tribunal considered the
memorandum of association of the assessee as well as the details of its
background, functional requirements, operation and model, accounting structure
and ultimate payment to the exchequer of the Government. It also went into the
composition of the governing body, organisational structure, funds and
operation of the accounts of the assessee as enumerated in its bye-laws. It
held that the amount was not assessable in the hands of the assessee.


On appeal by
the Revenue, the Himachal Pradesh High Court upheld the decision of the
Tribunal and held as under:

“(i)   The assessee neither created any source of income nor generated
any profit or gain out of such source. The assessee merely performed the
statutory functions under the 2005 Act and collected the tax amount for and on
behalf of the State and transferred such collection to the Government Treasury.
Even if the tax collection remained temporarily parked with the assessee for
some time, it could not be treated as ‘income’ generated by the assessee as the
amount did not belong to it.


(ii)   The Tribunal had rightly concluded that the surplus of income over
expenditure, as reflected in the entries or the returns filed by the assessee,
also belonged to the State Government and was duly deposited in the Government
Treasury. Hence, it did not partake of the character of ‘profit or gain’ earned
by the assessee.


(iii)        The non-registration of the assessee u/s
12AA of the Act was inconsequential.”

Section 14A of ITA, 1961 r.w.r. 8D(2)(iii) of ITR, 1962 – Exempt income – Disallowance of expenditure relating to exempt income – Voluntary disallowance by assessee of expenditure incurred to earn exempt income – AO cannot disallow expenditure far in excess of what has been disallowed by assessee

33.  Principal CIT vs. DSP Adiko Holdings Pvt.
Ltd.; 414 ITR 555 (Bom.)

Date of order: 3rd
June, 2019

A.Y.: 2009-10


Section 14A of ITA, 1961 r.w.r.
8D(2)(iii) of ITR, 1962 – Exempt income – Disallowance of expenditure relating
to exempt income – Voluntary disallowance by assessee of expenditure incurred
to earn exempt income – AO cannot disallow expenditure far in excess of what
has been disallowed by assessee


The assessee was in investment
business. It earned interest income from investment in mutual funds. It claimed
total expenses of Rs. 24.19 lakhs and voluntarily disallowed an amount of Rs.
7.79 lakhs as expenditure relatable to earning tax-free income u/s 14A of the
Income-tax Act, 1961. The AO rejected such working and applied Rule 8D(2)(iii)
of the Income-tax Rules, 1962 and made a disallowance of Rs. 2.19 crores.


The Commissioner (Appeals)
restricted the disallowance to Rs. 24.19 lakhs, the amount which was claimed as
total expenses. The Tribunal reduced it further to the assessee’s original
offer of Rs. 7.79 lakhs.


On appeal by the Revenue, the
Bombay High Court upheld the decision of the Tribunal and held as under:


“(i)   The computation of the AO would lead to disallowance of
expenditure far in excess of what was claimed by the assessee itself. The
assessee’s entire claim of expenditure in relation to its business activity was
Rs. 24.19 lakhs out of which the assessee had voluntarily reduced the sum of
Rs. 7.79 lakhs in relation to income not forming part of the total income u/s
14A which was accepted by the Tribunal.


(ii)   Quite apart from the correctness of the approach of the Tribunal,
accepting the stand of the AO would lead to disallowance of expenditure far in
excess of what is claimed by the assessee itself. No question of law arose.”

Sections 37 and 43B(g) of ITA, 1961 – Business expenditure – Deduction only on actual payment – Assessee paying licence fee to Railways for use of land – Railways enhancing licence fee and damages with retrospective effect and disputes arising – Assessee making provision for sum payable to Railways – Nature of fee not within description of ‘duty’, ‘cess’, or ‘fee’ payable under law at relevant time – Sum payable under contract – Deduction allowable

32.  CIT vs. Jagdish Prasad Gupta; 414 ITR 396
(Del.)

Date of order: 25th
March, 2019

A.Y.: 2007-08


Sections 37 and 43B(g) of ITA, 1961
– Business expenditure – Deduction only on actual payment – Assessee paying
licence fee to Railways for use of land – Railways enhancing licence fee and
damages with retrospective effect and disputes arising – Assessee making
provision for sum payable to Railways – Nature of fee not within description of
‘duty’, ‘cess’, or ‘fee’ payable under law at relevant time – Sum payable under
contract – Deduction allowable


The assessee was allotted lands by
the Railways and the licence fee was collected for the use of the land. The
Railways revised the licence fee periodically and also claimed damages,
unilaterally, on retrospective basis applicable from anterior dates. These led
to disputes. Therefore, the assessee made provision for the amounts which were
deemed payable to the Railways but which were disputed by it and ultimately
became the subject matter of arbitration proceedings. For the A.Y. 2007-08, the
AO disallowed the claim for deduction of the amounts on the ground that it fell
within the purview of section 43B of the Income-tax Act, 1961 and that by
virtue of the conditions laid down in section 43B, especially (a) and (b), the
licence fee payable periodically and the damages as well could not have been
allowed as deduction since they were not paid within that year in accordance
with the provision.


The Tribunal allowed the assessee’s
claim.


On appeal by the Revenue, the Delhi
High Court upheld the decision of the Tribunal and held as under:


“(i)   The reference to ‘fee’ in section 43B(a) had to be always read
along with the expression ‘law in force’. According to the documents placed on
record, the transaction between the parties was a commercial one, while the
land was allotted for a licence fee.


(ii)   The Notes on Clauses to the Bill which inserted section 43B(g)
stated that the amendment would take effect from 1st April, 2017 and would
accordingly apply only to the A.Y. 2017-18 and subsequent years. Thus, the
notion of clarificatory amendment would not be applicable. The contentions of
the Department with respect to applicability of section 43B were untenable.


(iii)        The assessee was entitled to deduction
on the enhanced licence fee in the year in which such enhancement had accrued
even though it was not paid in that year.”

Sections 48, 54F, 19 and 143 of ITA, 1961 – Assessment – Duty of Assessing Officer – It is a sine qua non for the AO to consider claims of deduction / exemption made by the assessee and thereafter to return the said claims if the assessee is not entitled to the same by assigning reasons

31.  Deepak Dhanaraj vs. ITO; [2019] 107
taxmann.com 76 (Karn.)

Date of order: 28th
May, 2019

A.Y.: 2016-17


Sections 48, 54F, 19 and 143 of
ITA, 1961 – Assessment – Duty of Assessing Officer – It is a sine qua non
for the AO to consider claims of deduction / exemption made by the assessee and
thereafter to return the said claims if the assessee is not entitled to the
same by assigning reasons


For the A.Y. 2016-17 the
petitioner-assessee had filed a return of income on 30th March, 2018
offering to tax the capital gains along with other sources of income. The said
return was held to be a defective return. The assessee thereafter filed a
revised return on 18th September, 2018 declaring long-term capital
gains and claiming deduction u/s 48 and exemption u/s 54F of the Income-tax
Act, 1961. The AO completed the assessment u/s 143(3) without considering the
return and the revised return and the claims for deduction / exemption u/ss 48
and 54F.


The assessee filed a writ petition
challenging the order. The Karnataka High Court allowed the writ petition and
held as under:


“(i)   Ordinarily, the Court would have relegated the petitioner-assessee
to avail the statutory remedy of appeal available under the Act provided the
principles of natural justice are adhered to. As could be seen from the order
impugned, the respondent has not whispered about the revised return filed by
the assessee except observing that the returns filed by the assessee were
invalidated being defective returns. If that being the position, no opportunity
was provided to the assessee u/s 139(9) to remove the defects in the returns
pointed out by the AO, nor was an opportunity provided to file a return
pursuant to the notice issued u/s 142(1). Even assuming the arguments of the
Revenue that no revised returns could be accepted enlarging the claim of
deduction / exemption beyond the time prescribed under the Act, it is a sine
qua non
for the AO to consider the claims of deduction / exemption made by
the petitioner-assessee and thereafter to return the said claims if the
assessee is not entitled to the same by assigning the reasons. The impugned
assessment order prima facie establishes that the deduction claimed u/s
54F is not considered while computing the taxable turnover. This would
certainly indicate the non-application of mind by the respondent / Revenue.


(ii)   It is clear that recording of ‘reasons’ is a sine qua non
for arriving at a conclusion by the quasi-judicial authority and it is
essential to adopt, to subserve the purposes of the justice delivery system.
The reasons are the soul and heartbeat of the orders without which the order is
lifeless and void. Where the reasons are not recorded in the orders, it would
be difficult for the Courts to ascertain the minds of the authorities while
exercising the power of judicial review.


(iii)   It is a well-settled legal principle that there is no bar to
invoke the writ jurisdiction against a palpable illegal order passed by the
Assessing Authority in contravention of the principles of audi alteram
partem.
On this ground alone, the order impugned cannot be approved. There
is no cavil with the arguments of the respondent placing reliance on the
judgement of the Apex Court in Goetze (India) Ltd. vs. CIT [2006] 157
Taxman 1/284 ITR 323
that no claim for deduction other than by filing a
revised return can be considered but not in the absence of the AO analysing,
adjudicating and arriving at a decision by recording the reasons. It is
apparent that no reasons are forthcoming for rejecting the revised returns as
well as the claims made u/s 54F. Such a perfunctory order passed by the AO
cannot be held to be justifiable.


(iv)  Hence, for the aforesaid reasons, without expressing any opinion on
the merits or demerits of the case, the order impugned and the consequent
demand notice issued u/s 156 as well as the recovery notice issued by the
respondent are quashed. The proceedings are restored to the file of the
respondent to reconsider the matter and to arrive at a decision after providing
an opportunity of hearing to the petitioner, assigning valid reasons as
aforementioned.”

Hustling the Taxpayer

Almost every
government department is on a digital drive. Many of them ask for the same
information from a taxpayer to serve their individual needs. Many a times,
administrators seem to believe that good intentions can justify bad
implementation. Recent changes in ITR software is a case in point which was
justified by the CBDT as if 11th July was the most auspicious time
for tweaking the utility for a 31st July deadline! Such times make a
taxpayer and tax filer feel helpless and insignificant.

There is a
consistent and ceaseless endeavour on the part of the tax department to make
changes and tinker with ITRs and schema despite court orders against doing so.
Add to that changes in ITR itself – say, asking for directorship details.
Aren’t they available with MCA? Isn’t MCA part of the same government? Cannot a
Director based on PAN be matched with the tax data and serve the purpose of the
tax department? The talk of ease of doing business doesn’t seem consistent with
such actions. Many such actions send a message to the entrepreneur that there
are strong forces preventing him in his flight to success. To the habituated
and compliant taxpayer, it signals lack of care and respect by the authorities.

In all
fairness can a taxpayer ask – what do I get in return for my taxes? Taxes are
not a consideration, yet taxes are paid for a reason and ease of compliance and
clear outcome is the least a taxpayer can expect. The collector of taxes and
those who decide on spending them have an obligation directly towards a
taxpayer. Taxes are not a charge on taxpayer’s industriousness and patience.
Most middle class pays 20-30 per cent of earnings as direct taxes. Firms and
individuals have a surcharge (a sneaky and shaky way to collect more). On
dividend government taxes a risk-taking investor three times on his potential
gain – at company level, at dividend distribution level and then 10% if the
investor receives a sum greater than Rs. 10 lakhs. And if he wants to sell the
shares at profit he can do so up to Rs. 1 lakh without tax. And of course you
are not spared at the time of spending, with GST of 18%. Seems like the
taxpayer works, spends, invests and saves to pay taxes!

What is the
obligation of the collector of taxes towards a taxpayer? Government is under a
social contract to spend taxes well and for the benefit of the taxpayers too
and not just for its vote banks. One wonders how taxpayers feel about their tax
monies being spent and whether that spending has something in it for them, at least
in respect of a fair, just and timely tax administration.

As taxpayers,
many feel that their taxes don’t yield a bang for the buck. Someone said
that my taxes actually work against me, they end up as reservations in
education and work against my own children’s future. A taxpayer is not able to
perceive a clear and direct nexus between taxes paid and benefits received. Tax
payment is a service to the nation and the nation above all owes to the
taxpayer some service, too. Does a taxpayer receive a reasonable medicare? Or
dependable infrastructure? Or emergency services? Or access to a timely,
corruption-free and fair justice system? For many facilities the taxpayer pays
directly. Say airport charges or tolls or road tax. Add to that the taxpayer
money which covers up tax-free incomes of wealthy kisans who take even
say several crores of income tax free. Let’s not talk about mismanaged funds
like the NPAs of banks – an inefficiency or even mismanagement funded by taxpayer
monies.

A
pre-Independence mindset is deep-rooted with a very damaging perspective on
taxes. India is yet to develop its own taxation philosophy. The old and
imported socialist mindset looks at taxes as a wealth-distribution mechanism.
However, that is primitive, negative and a secondary approach which has failed.
The rich have found places to hide income and pay little taxes. And the
middle-income people get squashed and hustled. It is time that tax
administrators introspect more on questions such as these – how do I make a
taxpayer see her taxes as an investment which yields direct returns? What can
the government do to make the entire process feel smooth and easy? What will
make a taxpayer see her taxes as an investment in nation-building but also as a
contribution towards building her own future?


Raman Jokhakar

Editor

CONFLICT

Confrontation (conflict) will lead to losses on
both sides

—Xi Jinping, Chinese
President


How true. As a matter of fact, no one has ever won an
argument because in the end both winner and loser end up being miserable. Yet
the irony is that inherently an individual is always in conflict;
the issues are:

  •   a majority of us are in conflict; hence, is
    conflict a gift from God or is it His curse?
  •   can we humans convert conflict into a gift
    from God?!


I think we can if we accept the fact
that there is conflict. Most of us despite realising the existence of conflict
don’t accept, nay, don’t want to accept that there is conflict. The fact is
that when there is conflict in our mind and in our life we push it under the
carpet and pray that it will fade away rather than face the conflict and
attempt to solve it. This is the irony of being human.


Let us accept that conflict is a
part of human nature and exists everywhere, leading to stress, unhappiness and
a strained mind. Can we learn how to manage conflict? Let us examine a few
examples of how some have
managed conflict:


  •   Gandhi experienced conflict in his mind, body
    and soul when he was discriminated against because of his colour, creed and
    religion. He accepted the presence of discrimination in society and his
    solution was non-violence. Even when he was hit, he bore the pain and
    did not retaliate.
  •   President Kennedy accepted the presence of the
    Russian armada in the Pacific as conflict and his response was retaliation – a
    show of power. The result was that he won and the Russians retreated from the
    Pacific – the famous Cuba affair.
  •   Martin Luther King, Jr. accepted the
    discrimination that existed in American society despite the promise of equality
    in the Constitution and the assassination of President Lincoln. His response
    was Gandhian.
  •   Nelson Mandela accepted discrimination – he
    suffered pain and was jailed for years and won independence by following
    Gandhi.
  •   President Nixon created Watergate – he did not
    accept it and had to resign as President.
  •   Prime Minister Nehru never anticipated
    conflict with China (incursion or war) in 1962 or if he anticipated it, he
    ignored it. The result was that he died in 1964 a disappointed and disheartened
    man. His doctrine of panchsheel had failed.
  •   Me Too – The conflict is whether to
    accept or not to accept. Those who accept, resign; those who don’t, will face
    investigation and legal action.
  •   The patriarch and founder of the Birla Empire,
    Mr. G.D. Birla, foresaw and accepted a looming conflict in his business empire;
    his solution was division of the Birla assets between him and his brothers – a
    far-sighted action. The result is continuation of businesses yielding respect,
    prosperity and harmony in the Birla clan.


There are others who have avoided
conflict in the family by taking appropriate and timely action.


Firstly, to resolve or dissolve a
conflict we must accept that there is conflict; secondly, be at peace
with ourselves; thirdly, do not respond to conflict emotionally; and fourthly,
think clearly to seek a solution, a solution that brings harmony.


On the other hand, where conflict is
not accepted or after accepting it no attempt is made to resolve it, there is
disturbance and destruction resulting in loss of harmony, health and wealth.
Voltaire says “Conflict means that both parties are wrong”.


In society conflict results in
divorce, quarrels amongst siblings – even between parents and children and
amongst those who were once friends and colleagues. The legendary conflict
which resulted in the Mahabharata and the destruction of a clan was because of
Duryodhan who, after creating conflict and going back on his promise, refused
to accept a solution.


“To be or not to be” is the perennial Shakespearean
dilemma. Hence, let us accept that conflict exists in our daily existence. It
is rightly said – wherever there is choice there is conflict. We need to
accept the existence of conflict of choice and deal with it by choosing
with a clear and cool mind.


The paradox of conflict is
that conflict exists in every mind because of caste, creed and greed and the
result is confusion. These three give birth to conflict. Success lies in
managing these three. Conflict can be managed only by clarity. Clarity about
our objective and circumstances – understanding the reasons or the basis of
conflict; and, above all, –an intense desire to solve the conflict. It is then
and only then that conflict can be resolved. The solution lies in “accept
and act”.
Stop fighting conflict because fighting only leads to more
conflict – it is like adding fuel to fire.


I will conclude by quoting William Hazlitt: “Nothing was
ever learnt by either side in a conflict”.
And so I reiterate: Conciliation
or resolution with clear thinking is a gift from God. Both conflict and clarity
are also giftsfrom God.


BCAS – E-Learning Platform
(https://bcasonline.courseplay.co/)

Sr. No.

Course Name

Name of the BCAS
Committee

Course Fees (INR)**

Members

Non –
Members

1

Three Days Workshop on
Advanced Transfer Pricing

International Taxation
Committee

5550/-

6350/-

2

Four Day Orientation
Course on Foreign Exchange Management Act (FEMA)

International Taxation
Committee

7080/-

8260/-

3

Workshop on Provisions
& Issues – Export/ Import / Deemed Export/ SEZ Supplies

Indirect Taxation
Committee

1180/-

1475/-

4

7th
Residential Study Course on Ind As

Accounting & Auditing

Committee

2360/-

2360/-

5

Full Day Seminar on
Estate Planning, Wills and Family Settlements.

Corporate & Allied
Laws Committee

1180/-

1180/-

6

Workshop on “Foreign Tax
Credit”

International Taxation
Committee

1180/-

1475/-

7

Panel Discussion on
Analysis of PE Constitution – “Recent Judicial Pronouncements including
MasterCard, Nokia Networks and Formula One.”

International Taxation
Committee

472/-

708/-

8

12th
Residential Study Course on GST

Indirect Taxation
Committee

5900/-

N. A.

9

Seminar on Tax Audit

Taxation Committee

2065/-

2596/-

10

Full Day Seminar on
Charitable Trusts – Critical Aspects

Corporate & Allied
Laws Committee

2301/-

2773/-

11

Long Duration Course on
Goods and Services Tax

Indirect Taxation
Committee

14,160/-

17,700/-

12

Half Day Workshop on GST
Audit

Indirect Taxation
Committee

1500/-

1500/-

13

Full Day Seminar on GAAR and Anti-avoidance Provisions

International Taxation Committee

4200/-

5400/-

14

Seminar on Capital Gains and Income from Other Sources

Taxation Committee

2124/-

2596/-

15

Half Day Workshop on GST Annual Return 9

Indirect Taxation Committee

295/-

295/-

16

BCAS Initiative – Educational Series on GST

Indirect Taxation Committee

Free

Free

17

GST Training Program for Trade, Industry and Profession

Indirect Taxation Committee

Free

Free


**Course Fee is inclusive of 18% GST.

For more details, please contact Javed Siddique at 022
– 61377607 or email to events@bcasonline.org

PERIOD OF INTEREST ON REFUND IN CASES OF DELAYED CLAIMS OF DEDUCTIONS

ISSUE FOR CONSIDERATION

Section 244A(1) provides for the grant of
simple interest in cases where refund is due to the assessee – simple interest
at the rates prescribed for different circumstances and for the periods
specified in the section. No interest is payable if the amount of refund is
less than 10% of the tax as determined u/s 143(1) or on regular assessment. In
a case where the return of income is not filed by the due date specified u/s
139(1), the interest is payable for the period commencing with the date of
filing the return. Ordinarily, interest is calculated at the rate of 0.5% for
every month or part of a month. Additional interest at the rate of 3% per annum
is granted in cases where the refund due as the result of appellate or
revisional orders is delayed beyond the period of the time allowed u/s 153(5)
of the Act. The amount of interest granted gets adjusted on account of
subsequent orders which have the effect of varying the amount of refund.


Where the proceedings resulting in the
refund are delayed for reasons attributable to the assessee, wholly or in part,
the period of the delay attributable to him is excluded from the period for
which interest is payable as per the provisions of sub-section (2) of section
244A. In deciding the question as to the period to be excluded, the decision of
the Commissioner shall be final.


Often, the refund arises or its amount
increases where a claim for deduction is made after filing the return of income
by filing a revised return, or placing the claim in the assessment or appellate
proceedings. In such cases, an interesting issue arises about deciding whether
the period for which the claim is deferred can be excluded for calculation of
the interest due to the assessee. Conflicting views of the courts are available
on the subject of excluding the period or otherwise. Gauhati and a few other
high courts have taken a view that the refund can be said to have been delayed
due to the failure of the assessee in claiming the deduction in time and the
period in question should be excluded while granting the interest on refund.
The Bombay, Gujarat and the other high courts have held that such situations of
deferred claims cannot be held to reduce the period for which the interest is
otherwise allowable to the assessee under
sub-section (1).


THE ASSAM ROOFING LTD. CASE

The issue came up for consideration in the
case of Assam Roofing Ltd. vs. CIT, 11 taxmann.com 279
(Gauhati)
. In that case the assessee filed its return of income on 31st
December, 1992 for the assessment year 1991-92, including the receipt of the
transport subsidy in the total income. In the note it was claimed to be a
capital receipt, though during the assessment proceedings completed on 16th
May, 1994 u/s 143(3) no separate representation was made by the assessee
claiming that subsidy was not taxable. An appeal was filed against the
assessment order for contesting the addition on account of the said subsidy
which was decided in its favour by the Commissioner (Appeals) by an order dated
27th October, 1994 directing that the transport subsidy amounting to
Rs. 98,79,266 be deleted from the total income. The AO passed an order dated 13th
December, 1994 to give effect to the appellate order, deleting transport
subsidy amounting to Rs. 98,79,266. He also allowed interest u/s 244A on the
amount of refund that was found due to the assessee as a result of the
appellate order for a period of 33 months, i.e., from 1st April,
1992 to 13th December, 1994.


Subsequently, in the rectification
proceedings, the AO held that the grant of refund was delayed for reasons
attributable to the assessee and, as a consequence, interest on refund was held
to be payable only for a period of eight months, that is, from 16th
May, 1994 (date of completion of assessment) to 13th December, 1994,
that is, the date of order giving effect to the appellate order. The appeal by
the assessee against the order reducing the interest was allowed by the
Commissioner (Appeals) and his order was confirmed by the Tribunal. The
following substantial question of law was raised: ‘Whether on the facts and
in the circumstances of the case, the Tribunal was justified and correct in
allowing interest u/s 244A of the Income-tax Act, 1961 to the assessee for the
period of delay in granting refund of tax where such delay is due to reasons
attributable to the assessee?’


The Revenue contended that the assessee had
voluntarily included the amount received on account of transport subsidy as
taxable income and on the said basis the assessment was made; at no point of
time in the course of the assessment proceedings had the assessee taken the
stand that the amount received on account of transport subsidy was not taxable;
the issue was raised by the assessee only in the appeal filed before the
Commissioner (Appeals) which was disposed of by the order dated 27th October,
1994; thereafter, on 13th December, 1994 the amount of transport
subsidy earlier included in the taxable income of the assessee was deleted and
orders were passed for the refund.


Relying on the provisions of section 244A(2)
of the Act, it was contended that the payment of refund was made at the
particular point of time only because of the conduct of the assessee in not
raising the said issue at any earlier point of time and the payment of refund, therefore,
got delayed for reasons attributable to the assessee; consequently, the
assessee was not entitled for interest for the period for which he was at
fault.


In reply the assessee contended that the
provisions of Chapter XIX of the Act made it abundantly clear that the grant of
refund was not contingent on any application of the assessee and such refund
u/s 240 of the Act was consequential to any order passed in an appeal or other
proceedings under the Act; no claim for refund was required to be lodged; the
provisions of section 244A(2) of the Act had no application to the case
inasmuch as the refund was consequential to the appellate order, no proceeding
for refund could be visualised so as to hold the assessee responsible for any
delay in finalisation of such a proceeding.


Relying on the decision in Sandvik
Asia Ltd. vs. CIT, 280 ITR 643
, it was contended by the assessee that
there was a compensatory element in the interest that was awardable u/s 244A of
the Act and that such interest mitigates the hardship caused to the assessee on
account of wrongful levy and collection of tax. Reliance was also placed on the
decision of the Punjab and Haryana High Court in the case of National
Horticulture Board vs. Union of India, 253 ITR 12
to contend that interest
on refund was automatic and consequential and did not depend on initiation of a
proceeding for refund or on raising a claim for refund, as the case may be.


Section 244A of the Act, the Court observed,
contemplated grant of interest at the specified rate from the first day of
April of the assessment year to the date on which refund was granted in case of
payments of tax as contemplated by sub-clauses (a) and (b) of sub-section (1).
It further noted that under sub-section (2) of section 244A if the ‘proceedings
resulting in the refund’ were delayed for reasons attributable to the assessee,
no interest was to be awarded for the period of such delay for which the
assessee was responsible. Significantly, the Court took note of the expression ‘proceedings
resulting in revision (to be read as “refund”)’
appearing in sub-section
(2) of Section 244A to hold that the scope of section 244A(2) was not limited
to the cases of sections 238 and 239 but covered the cases of the refunds
arising on account of any order under the scheme of the Act; the expression
‘proceeding’ referred to in sub-section (2), more reasonably, would mean any
proceeding as a result of which refund had become due; viewed thus, the
expression ‘proceeding’ might take within its ambit an appeal proceeding
consequential to which refund had become due. The Court supported its decision
by relying on the decision of the Punjab and Haryana High Court in the
National Horticulture Board
case (supra).


The Court in
deciding the issue noted the fact that the assessee itself declared the amount
of transport subsidy received by it to be taxable and voluntarily paid the tax
and no claim to the contrary was raised in the course of the assessment
proceeding; it was only in the appeal filed that the issue was raised and was
allowed by the Commissioner (Appeals) and a consequential refund was granted.


The Court ruled that in the above
circumstances, it could not but be held that the assessee was responsible for
the delay in grant of refund and it would be correct to hold that the interest
was payable only with effect
from 16th May, 1994 till the date of payment of the refundable amount.


The Gauhati High Court allowed the appeal of
the Revenue and reversed the order of the Tribunal by holding that the delay in
grant of refund was attributable to the assessee and as a consequence the
period for which interest on refund was to be granted required to be reduced.

MELSTAR INFORMATION TECHNOLOGIES LTD. CASE

The issue recently arose in the case of the CIT
vs. Melstar Information Technologies Ltd., 106 taxmann.com 142 (Bom.)
.
In this case, the assessee had not claimed certain expenditure before the AO
but raised such a claim before the Tribunal which remanded the proceedings to
the Commissioner (Appeals) who allowed the claim of expenditure. The deduction
so allowed resulted in a refund of taxes paid and it is at that juncture that
there arose the question u/s 244A of payment of interest on such refund.


It appears that there was a dispute about
the period for which the interest was to be granted to the assessee, or about
the eligibility of the assessee to interest. The AO seemed to be of the view
that no interest was payable to the assessee for the reason that the delay in
granting the refund was entirely attributable to the assessee inasmuch as he
had delayed the claim for deduction. The AO, while granting refund, seemed to
have denied the interest by relying on the provisions of section 244A(2) after
taking the approval of the Commissioner. The Tribunal, on an appeal by the
assessee, held that an appeal was maintainable against the order refusing the
interest on refund and further held that the delay could not be held to be
attributable to the assessee and, therefore, the Tribunal directed the payment
of interest.


The Revenue, aggrieved by the order of the
Tribunal had raised the following question for the Court’s consideration: ‘Whether
on the facts and circumstances of the case and in law, the ITAT has erred in
law in assuming jurisdiction to hear the appeal when no such appeal lies before
the ITAT or before CIT(A) because as per the provisions of Section 244A(2) of
the Income Tax Act, decision of CIT is final as held by Kerala High Court in
the case of Kerala Civil Supplies 185 taxman 1?’


The Court noted that the issue pertained to
interest payable to the assessee u/s 244A of the Act where the Revenue did not
dispute the assessee’s claim of refund and its eligibility to interest thereon
in ordinary circumstances. However, since the delay in the proceedings
resulting in the refund was attributable to the assessee, by virtue of
sub-section (2) of section 244A of the Act the assessee was not entitled to
such interest.


The Court observed that there was no
allegation or material on record to suggest that any of the proceedings were
delayed in any manner on account of reasons attributable to the assessee and
therefore the Tribunal was correct in allowing the interest to the assessee.


The Court, in deciding that there was no substantial
question of law involved in the appeal of the Revenue, relied on the decision
in the case of Ajanta Manufacturing Ltd. vs. Deputy CIT, 391 ITR 33
(Guj.)
wherein a similar issue was considered. In that case, the
assessee had made a belated claim for deduction during assessment on filing a
revised return of income, and the Revenue had denied the interest by
attributing the delay in grant of refund to the assessee on applying the
provisions of sub-section (2) of section 244A of the Act. The Court noted with
approval the following observations of the said decision:


“16. We would also examine the order
of the Commissioner on merits. As noted, according to the Commissioner the
assessee had raised a belated claim during the course of the assessment proceedings
which resulted into delay in granting of refund and therefore, the assessee was
not entitled to interest for the entire period from the first date of
assessment year till the order giving effect to the appellate order was passed.
We cannot uphold the view of the Commissioner. First and foremost requirement
of sub-section (2) of Section 244A is that the proceedings resulting into
refund should have been delayed for the reasons attributable to the assessee,
whether wholly or in part. If such requirement is satisfied, to the extent of
the period of delay so attributable to the assessee, he would be disentitled to
claim interest on refund. The act of revising a return or raising a claim
during the course of the assessment proceedings cannot be said to be the
reasons for delaying the proceedings which can be attributable to the assessee.
(The) mere fact that the claim came to be granted by the Appellate Commissioner
would not change this position. In essence, what the Commissioner (Appeals) did
was to allow a claim which in law, in his opinion, was allowable by the
Assessing Officer. In other words, by passing order in appeal, he merely
recognised a legal position whereby the assessee was entitled to claim certain
benefits of reduced tax. Surely, the fact that the assessee had filed the
appeal which ultimately came to be allowed by the Commissioner, cannot be a
reason for delaying the proceedings which can be attributed to the assessee.


17. The Department does not contend that
the assessee had needlessly or frivolously delayed the assessment proceedings
at the original or appellate stage. In absence of any such foundation, (the)
mere fact that the assessee made a claim during the course of the assessment
proceedings which was allowed at the appellate stage would not ipso facto imply
that the assessee was responsible for causing the delay in the proceedings
resulting into refund. We may refer the decision of the Kerala High Court in
case of CIT vs. South Indian Bank Ltd., reported in (2012) 340 ITR 574 (Ker)
in which the assessee had raised a belated claim for deduction which was
allowed by the Commissioner (Appeals). The Revenue, therefore, contended that
for such delay, interest should be declined under Section 244A of the Act. In
the said case also, the assessee had not made any claim for deduction of
provision of bad debts in the original return. But before completion of the
assessment, the assessee had made such a claim which was rejected by the
Assessing Officer. The Commissioner allowed the claim and remanded the matter
to the Assessing Officer. Pursuant to which, the assessee became entitled to
refund. Revenue argued that the assessee would not be entitled to interest in
view of Section 244A(2). In this context, the Court held in Para. 6 as under
(page 578 of 340 ITR):


‘6.
Sub-section (2) of section 244A provides that the assessee shall not be
entitled to interest for the period of delay in issuing the proceedings leading
to the refund that is attributable to the assessee. In other words, if the
issue of the refund order is delayed for any period attributable to the
assessee, then the assessee shall not be entitled to interest for such period.
This is of course an exception to clauses (a) and (b) of section 244A(1) of the
Act. In other words, if the issue of the proceedings, that is, refund order, is
delayed for any period attributable to the assessee, then the assessee is not
entitled to interest for such period. Further, what is clear from sub-section
(2) is that, if the officer feels that delay in refund for any period is
attributable to the assessee, the matter should be referred to the Commissioner
or Chief Commissioner or any other notified person for deciding the issue and
ordering exclusion of such periods for the purpose of granting interest to the
assessee under section 244A(1) of the Act. In this case, there was no decision
by the Commissioner or Chief Commissioner on this issue and so much so, we do
not think the Assessing Officer made out the case of delay in refund for any
period attributable to the assessee disentitling for interest. So much so, in
our view, the officer has no escape from granting interest to the assessee in
terms of section 244A(1) (a) of the Act’.”


OBSERVATIONS

The issue under consideration revolves in a
narrow compass; whether the claim for deduction, made subsequent to the filing
of return of income, can be held to be attracting the provisions of sub-section
(2) of section 244A for excluding the period of delay in claiming the deduction
from the period for which interest is granted u/s 244A on the amount of refund
that has resulted or has increased due to the grant of deduction pursuant to
the delayed claim.


The relevant sub-section reads as under: (2)
If the proceedings resulting in the refund are delayed for reasons
attributable to the assessee, whether wholly or in part, the period of the
delay so attributable to him shall be excluded from the period for which
interest is payable under sub-sections (1) or (1A), and where any question
arises as to the period to be excluded, it shall be decided by the Principal
Chief Commissioner or Chief Commissioner or Principal Commissioner or
Commissioner whose decision thereon shall be final.


The requirement of sub-section (2) is that
the proceedings resulting into refund should have been delayed and the delay
should be for the reasons attributable to the assessee. Only where such
requirement is satisfied, the interest relating to the period of delay so
attributable to the assessee would be denied.


On a careful reading of the provision of
sub-section (2) it is gathered that the said provisions are attracted only in
cases where the twin conditions are cumulatively satisfied: the proceedings
resulting into refund have been delayed, and further that the delay is for
reasons that are attributable to the assessee. Non-satisfaction of any one of
the conditions would not disentitle the assessee from the claim of interest on
refund; for this purpose it may be essential to appreciate the contextual
meaning of the term ‘proceedings’. Can the acts of filing the revised return or
claiming the reliefs in assessment or appellant proceedings be construed to be
‘proceedings’ for attracting the provisions of sub-section (2)? May be not. The
proceedings referred to in sub-section (2) should, in our opinion, mean and
co-rate the proceedings in respect of assessment or adjudication of appeals and
it is here that the assessee should be found to have delayed such proceedings
in any manner for disentitling him from the claim of interest.


Revising the return or placing the claim
during such proceedings cannot be considered to be part of proceedings
resulting in refund. It is essential that the proceedings in question should
further result in refund. Only assessment, rectification, revision or appellate
proceedings can be considered to be proceedings that result in refund. It is
such proceedings that should have been delayed and not the claim of deduction
or refund, and further the delay in such proceedings should be attributable to
the assessee. It is for these reasons some of the Courts have given emphasis to
ascertain whether the assessee had contributed to delay the assessment
proceedings on frivolous grounds without placing their analysis of provisions
in so many words in the orders.


Our understanding is further strengthened by
the amendments of 2016 for insertion of clause “a” in sub-section (1) of
section 244A with effect from 1st June, 2016 to provide that the
interest would be paid for the period commencing from the date of filing of
return of income where such return is filed outside the due date prescribed u/s
139(1). In the absence of such an amendment, interest could not have been
denied to the assessee for the delay in filing the return of income as was held
by some of
the Courts.


The Court in the Assam Roofing Limited
case rightly held that the meaning of the term ‘proceedings resulting in
refund’ was not limited to cases of sections 238 and 239 of the Act but also
cover the other cases of refund and would include any proceedings resulting in
refund and such proceedings also included the appellate proceedings. Having
held that, the Court failed in appreciating that the assessee was not
responsible for delaying any of the proceedings that resulted in refund or said
to have been delayed. Instead, the Court held that the act of filing the claim
in the appellate proceedings was to be construed as an act of delaying the
proceedings that resulted in refund. It therefore held that putting a claim at
the appellate stage was responsible for delay in grant of refund and therefore
the interest for the period up to the date of putting the claim was not
allowable. It is respectfully submitted that this was a classic case of missing
the wood for the trees; the case where the Court was preoccupied with the delay
in placing the claim for deduction, overlooking the important fact that what
was relevant for the application of sub-section (2) was delay in the proceeding
and not the delay in grant of refund as a consequence of the delayed claim. It
might be that the assessee was responsible for making belated claim but
certainly not delaying
the proceedings.


It is required to be appreciated that the
interest is the consequence of payment of excess tax. Accordingly, once excess
tax is found to have been paid at whatever stage, the tax was required to be
refunded. And as a consequence interest was bound to be paid unless the
assessee is shown to be responsible for delaying the proceedings and not the
refund. Putting a delayed claim for the deduction, otherwise allowable under
the Act, under no circumstances could be construed as an act of delaying the
‘proceedings’, when it was otherwise the duty of the authorities to compute the
correct total income by allowing all deductions that were allowed under the Act
and simultaneously excluding all such receipts that were required to be
excluded. (Please see circular No. 26 dated 7th July, 1955.)


The act of revising a return or raising a
claim during the course of the assessment proceedings cannot be said to be part
of the proceedings for refund and cannot also be said to be the reasons for
delaying the proceedings which can be held to be attributable to the assessee.
This understanding will not change on account of the claim for deduction
outside the return of income. What happens on allowing the claim is something
which is otherwise required to be allowed as per the law by the AO. In other
words, by passing an order he merely recognises a legal position whereby the
assessee is entitled to claim certain benefits of reduced tax. Surely, the
claim in the proceedings ultimately resulting in refund cannot be construed as
an act of delaying the proceedings that can be attributed to the assessee. In
the absence of any finding that the assessee was responsible for delaying the
proceedings, the mere fact that the assessee made a claim during the course of
the assessment proceedings which was allowed at the appellate stage would not ipso
facto
imply that the assessee was responsible for causing the delay in the
proceedings that resulted into refund.


In the case of Ajanta Manufacturing
Limited, 72 taxmann.com, 148 (Guj.),
the assessee company had included
the receipt of subsidy in total income and paid tax thereon while filing the
return of income. During the course of assessment, a claim was made under a
letter for excluding the subsidy for receipt from income. The claim of the
assessee was allowed in appeal by the Commissioner (Appeals) and the reduction
in income resulted in refund. In deciding the period for which the interest
should be allowed for such refund, the High Court held that the disabling
provisions of sub-section 2 and section 244A were not attracted in the facts of
the case and the interest should be granted for the full period as per the
provisions of section 244(1) of the Act.


In the case of Sahara India Savings
& Investments Corporation Limited, 38 taxmann.com 192 (All.)
the
refund was not granted for not filing TDS certificates with the return of
income. Subsequently, the refund became due on filing of the certificates;
while the refund was granted, the interest thereon was denied on the ground
that the refund was delayed due to non-filing of TDS certificates with the
return of income. The Allahabad High Court held that a delay in application for
refund could not be construed as a delay attributable to the assessee and the
provisions of sub-section (2) were not attracted in the facts of the case.


In the case of Larsen & Toubro,
330 ITR 340 (Bom.),
again in the circumstances where the TDS
certificates were not filed with return of income, the Court upheld the order
of the Tribunal holding that interest u/s 244A could not be denied only on the
ground that certificates were not filed with the return of income.


The Supreme Court in the case of H.E.G.
Limited, 334 ITR 331 (SC),
held that interest was payable to the
assessee u/s 244A for withholding of the refund by the AO on account of denial
of credit for TDS.


The Punjab and
Haryana High Court in the case of National Horticulture Board, 253 ITR 12
(P&H),
held that the interest u/s 244A could not be denied on the
ground of the delayed application for refund of the taxes paid.


In the case of South Indian Bank
Limited, 340 ITR 574 (Ker.),
the Commissioner (Appeals) had allowed the
related claim for deduction. The interest on resulting refund was denied by the
income tax authorities on the ground of the delayed claim for deduction which
was made, outside the return of income, in the assessment proceedings. The
Kerala High Court held that the AO had no escape from granting interest to the
assessee.


The Kerala High Court, in the case of Pala
Marketing Co-Op. Society Limited, 79
taxmann.com 438 (Ker.), however,
held that the assessee was not entitled to interest on refund where he had
delayed the filing of return of income even where such delay was condoned
following its own decision in the case of M. Ahammadkutty Haji, 288 ITR
304.
However, the Rajasthan High Court in the case of Dariyavie
Singh Karnavat, 18 taxmann.com 180
, held that the interest was payable
in similar circumstances ignoring the decision of the Kerala High Court in the M.
Ahammadkutty
case cited before
the Court.


Interestingly, the Karnataka High Court in
the case of Dinakar Ullal, 323 ITR 452 (Kar.), ruled out the
application of circular No. 12 dated 30th October, 2003 and circular
No. 13 dated 22nd December, 2006 issued by CBDT. In granting the
interest on refund due on an application for condonation of delay in claiming
the refund of taxes paid, the said circulars provided that no interest on
refund should be granted in cases where the delay in application of refund was
favourably condoned.


Recently, the Bombay High Court in the case
of State Bank of India in ITA No. 1218 of 2016 held that interest
on refund could not be denied in a case where the refund arose on account of
the claim for deduction made during the assessment proceedings… following its
own decision in the case of Chetan M. Shah, 53 taxmann.com 18.


The better view appears to be the
one in favour of granting interest for the full period commencing from the
first day of the assessment year to the date of the grant of refund.


Gift From ‘HUF’ and Section 56(2)

Issue for
Consideration

Under the provisions of section 56(2)(x) of
the Income-tax Act, 1961, receipt of any sum of money or any property  without consideration or for inadequate
consideration (in excess of the specified limit of Rs. 50,000) by the assessee
is chargeable to income-tax under the head “Income from other
sources”. The term ‘property’ is defined for this purpose as immovable
property, shares, securities, jewellery, bullion and artistic works like
drawings, paintings etc. The Finance Act, 2017 while inserting this new provision
has widened the scope of the old 
provision by making the new 
provision applicable to all types of assessees, as against the erstwhile
provision of section 56(2)(vii), which was applicable only to an individual or
an HUF.


The taxability as provided in section
56(2)(x) is subjected  to several
exceptions. One of the important exceptions from taxability is when any such
sum of money or property is received by the assessee from his relative. The
Explanation to clause (x) of section 56(2) provides that the expression
‘relative’ shall have the same meaning as is assigned to it in the Explanation
to clause (vii). The said Explanation to clause (vii) defines ‘relative’
separately for individual and HUF in an exhaustive manner. In case of an
individual, ‘relative’ means –


(a).  spouse of the individual;

(b).  brother or sister of the individual;

(c).  brother or sister of the spouse of the
individual;

(d).  brother or sister of either of the parents of
the individual;

(e).  any lineal ascendant or descendant of the
individual;

(f).   any lineal ascendant or descendant of the
spouse of the individual;

(g).  spouse of the person referred to in items (B)
to (F).


In case of an HUF, ‘relative’ means any
member of such HUF. Till 1st October 2009, there was no definition
of relative qua an HUF. The definition of “relative” qua an HUF
was inserted by the Finance Act 2012, with retrospective effect from 1.10.2009.


The definition of ‘relative’ for  an individual does not include his HUF. In
other words, the definition of the term ‘relative’, qua an individual,
does not specifically exclude the receipt of a gift by an individual from an
HUF from the scope of taxation u/s. 56(2) (x). Therefore, the issue has arisen,
in the context of a receipt by an individual from his HUF,  as to whether an HUF can be regarded as the
relative of the individual, if all the members of that HUF are otherwise his
relatives as per the above definition. While the Rajkot bench of the Tribunal
has taken the view that gift received from an HUF, whose members comprised of
the  relatives of the recipient, is not
taxable, the Ahmedabad bench of the Tribunal has taken the view that HUF does
not fall in the definition of relative, so as to qualify for the exemption from
taxability. The view of the Rajkot bench has been confirmed by the decisions of
the Mumbai and Hyderabad benches.


Vineetkumar Raghavjibhai Bhalodia’s case:

The issue first came up before the Rajkot
bench of the Tribunal in the case of Vineetkumar Raghavjibhai Bhalodia vs.
ITO 46 SOT 97.


In this case, relating to assessment year
2005-06, the assessee i.e. Vineetkumar Raghavjibhai Bhalodia received a gift of
Rs. 60 lakh from Shri Raghavjibhai Bhanjibhai Patel (Bhalodia) HUF in which he
was a member. The assessing officer held that the HUF was not a  ‘relative’ of the recipient and  the gift of Rs. 60 lakh received from the HUF
was  taxable.


The CIT(A) confirmed the view of the
assessing officer. He observed that if the legislature wanted that money  received by a member of the HUF from the HUF
should also not be chargeable to tax, it would have specifically mentioned so
in the definition of ‘relative’. The CIT(A) also rejected the alternative
submissions of the assessee that the said gift was exempt u/s. 10(2), on the
ground that the sum was not received on total or partial partition of the HUF.
He held that the exemption u/s. 10(2) was available only in respect of that
amount which could be apportioned to the member’s share in the income of his
HUF. Since the assessee failed to establish whether the amount received was
equal to or less than the income which could be apportioned to his share, the
exemption was denied.


Before the Tribunal, on behalf of the
assessee, it was argued that HUF was a ‘relative’, in as much as the HUF was a
collective name given to a group consisting of individuals, all of whom were
relatives as per the definition. The HUF was a conglomeration of relatives as
defined under section 56(2)(v)[1].
Section 56(2)(v) should be interpreted in such a way that  avoided absurdity. Alternatively, it was also
contended that the receipt was exempt u/s. 10(2). Section 10(2) used the
language “paid out of the income of the family” and not “paid
out of the income of the previous year of the family” as was interpreted
by the assessing officer. Finally, it was submitted that if two views were
possible, the one beneficial to the assessee had to be adopted.


On behalf of the revenue, it was pointed out
that ‘person’ had been defined u/s. 2(31) of the Act and HUF was a separate
person thereunder. The revenue also relied upon the definition of ‘relative’
given in section 2(41), wherein also HUF was not included. Regarding
applicability of section 10(2), it was submitted that its object was to provide
exemption only in respect of partition, and not in case of gift.


The Tribunal held that the expression
“Hindu Undivided Family” must be construed in the sense in which it
was understood under Hindu Law. HUF constituted all persons lineally descended
from a common ancestor and included their mothers, wives or widows and
daughters. All those persons fell in the definition of “relative” as
provided in Explanation to clause (v) of section 56(2). The gift received from
“relative”, irrespective of whether it was from an individual
relative or from a group of relatives, was exempt from tax. Though it was not
expressly defined in the Explanation that the word “relative”
represented a single person. It was not always necessary that singular remained
a singular. Sometimes a singular could 
mean more than one, as was in the present case of the gift from  an HUF.


Regarding exemption u/s. 10(2), the Tribunal
disagreed with the view of the CIT (A) that only the amount received on partial
partition or on partition was exempt, as well as only up to the extent of share
of assessed income of HUF for the year. According to the Tribunal, for getting
exemption u/s. 10(2), two conditions were to be satisfied. Firstly, he must be
a member of the HUF, and secondly he received the sum out of the income of such
HUF, may be of an earlier year. Since there was no material on record to hold
that the gift amount was part of any assets of the HUF, it was out of the
income of the family to a member of the HUF. According to the Tribunal,
therefore, the same was exempt u/s. 10(2).


A similar view has
been taken by the Hyderabad and Mumbai benches of the Tribunal in the following
cases –

(i).   Hemal D. Shah vs. DCIT [IT Appeal No.
2627 (Mum.) of 2015, dated 8-3-2017]

(ii).  Dy. CIT vs. Ateev V. Gala [IT Appeal
No. 1906 (Mum.) of 2014, dated 19-4-2017]

(iii). ITO vs. Dr. M. Shobha Raghuveera [IT
Appeal No. 47 (Hyd.) of 2013, dated 3-3-2014]

(iv). Biravelli Bhaskar vs. ITO [IT Appeal No.
398 (Hyd.) of 2015, dated 17-6-2015]


Gyanchand M. Bardia’s case

The issue again came up before the Ahmedabad
bench of the Tribunal in the case of Gyanchand M. Bardia vs. ITO 93
taxmann.com 144.


In this case, relating to assessment year
2012-13, the assessee received a gift of Rs.1,02,00,000 from an HUF, which
consisted of the assessee, being Karta, his wife and son. This gift was claimed
to be exempt by the recipient. The assessing officer rejected the claim of the
assessee on the ground that the definition of ‘relative’ of an individual
recipient did not include HUF as a donor. He made the addition of the impugned
amount u/s. 68.


The CIT (A) confirmed the addition made by
the assessing officer. In doing so, he 
observed that the relevant provision had been amended to exempt the gift
received by the HUF from its members. Though the Hon’ble Parliament brought
amendment to the statute declaring gift from member to HUF as tax free, it did
not consider it proper to make a gift from the HUF to a member as tax free. The
reason might  be that if such provision
was made, the Karta of an HUF might 
misuse the provisions and gift the corpus of the HUF to himself, as
other members of the HUF had no control over managing affairs of the HUF.
Further, the CIT (A) also noticed that the assessee could not produce the gift
deed in respect of the said gift received by him.


Before the Tribunal, on behalf of the
assessee, it was emphasised that besides him, the other two members of the HUF
i.e. assessee’s wife and son were also 
covered in definition of “relative”. Accordingly, it was
claimed that the said gift received was not taxable, by placing reliance on the
decision in the case of Vineetkumar Raghavjibhai Bhalodia (supra). Apart
from this contention, the assessee also claimed exemption u/s. 10(2), which had
not been decided by the lower authorities, though it was claimed before them on
an alternative basis.


The Tribunal held that the ratio of the
decision in the case of Vineetkumar Raghavjibhai Bhalodia (supra) was no
more applicable in view of the subsequent legislative developments vide Finance
Act, 2012 w.r.e.f. 01.10.2009. The legislature substituted clause (e) to
Explanation in section 56(2)(vii) defining the term  “relative” to be applicable in case
of an individual assessee as well as HUF; with retrospective effect from
01.10.2009. The legislature had incorporated clause (ii) therein to deal only
with an instance of an HUF donee receiving gifts from its members. Therefore,
by implication, the legislative intent was very clear that a receipt from an
HUF was not to be taken as one from a relative 
in the hands  of an individual
recipient. Accordingly, the assessee’s plea of receipt of valid gift from his
HUF being exempt, was declined.


Regarding the claim of exemption u/s. 10(2),
it was held that a sum which was not eligible for exemption under the relevant
specific clause could not be considered to be an exempt income u/s. 10(2).


Observations

An HUF is a separate assessable unit for the
purpose of the Income-tax Act. Under the general law, it is  the members who constitute and represent it.
It being so, the gift received from the HUF may also be viewed as a gift
received from all the members of the said HUF and if that be so, such receipt
should be treated as the one from a relative of the donee and not  liable 
to tax.


The Ahmedabad bench of the Tribunal in the
case of Gyanchand M. Bardia (supra) did not follow the decision of the
Rajkot bench for the  reason that  the amendment made by the Finance Act, 2012  altered 
the definition of the term ‘relative’ 
to specifically provide for relationship 
vis-à-vis an HUF recipient and the amendment did not do so for an
individual in receipt of a gift from an HUF. The bench observed that a  gift from an HUF, post amendment, will not be
exempt from tax for the reason that the 
legislative intent  was  clear from the amendment that post amendment  only a 
receipt of gift by an HUF from its members is exempt from tax.  Since this amendment is effective from
1-10-2009, receipts during the pre-amendment 
period was not taxable as per the Rajkot bench. No other reason was
provided by the bench for upholding the taxability in the hands of the
individual. One fails to appreciate  how
an amendment providing for an exemption for a particular situation changes  the understanding derived for taxation or
otherwise in an altogether  different and
converse situation. The kind of deductive interpretation applied by the bench
is  not comprehensible. In our considered
view, the  bench was bound to follow the
decision of the Rajkot bench and was required to refer the matter to a special
bench, if it disagreed with the said decision. 


A useful reference may be made to the
memorandum explaining the insertion of the new definition of the term
‘relative’.  A bare reading of the same
clarifies that there is nothing therein that conveys that the legislature
intended that it wanted to disturb the understanding supplied by the Rajkot
bench. The better way of appreciating the amendment is to accept that the
legislative intent was contrary to what was held by the Ahmedabad bench. The
legislature clearly intended not to provide that a gift from an HUF will not be
treated as  from  a 
relative and will be taxable,  in
view of its  awareness  of the 
five decisions in favour of the interpretation exempting the gift
received  by an individual from an
HUF.  Not having  so provided, the intention should be held to
be favouring the exemption, and not otherwise.


The issue can be looked at from another angle
also. A coparcener can make a gift of his undivided interest in the coparcenary
property to another coparcener[2]
or to a stranger with the prior consent of all other coparceners. Such a gift
would be quite legal and valid. Therefore, when the karta of the HUF gifts
coparcenary property after obtaining the consent of all the coparceners, it may
be regarded as the gift of undivided interests in that property by all the
coparceners individually. Accordingly, the gift of property received from the
HUF may also be viewed as the gift of undivided interests in that property by
all the coparceners of that HUF. In such a case, if all the coparceners are
relatives of the recipient assessee, then the said gift cannot be taxed under
the provisions of section 56(2)(x). Alternatively, the receipt can  be considered as the one for the body of
individuals where all the individuals are related to the recipient and the
receipt therefore is made eligible to exemption from tax. 


Another important aspect is the intention behind
the provisions under consideration. In Circular No. 1/2011 dated 6-4-2011, it
has been mentioned that the provisions of section 56(2)(vii) were introduced as
a counter evasion mechanism to prevent laundering of unaccounted income. The
gifts received from relatives have been kept out of the purview of this
provision obviously because the possibility of such laundering of unaccounted
income does not exist or is very less. Therefore, taxing such gifts received
from the HUF, consisting of members who all are relatives, would not be in
consonance with the object of the provision.


Looking at the intention of the relevant
provision and the legal understanding of the concept of HUF, the view taken by
the Rajkot, Mumbai and Hyderabad  benches
of the Tribunal seems to be the more appropriate view. 


There is even otherwise a flaw in the view
that views the relationship in one direction only. This view holds that A is
the relative of B but B is not a relative of A. Such an absurdity in
interpreting the law should be avoided in preference to the harmonious reading
of the provisions under which the relationship is a two way affair whereby A is
a relative of B and B is therefore a relative of A and A and B are relative of
each other. Needless to say that the view beneficial to the tax payer should be
adopted in a case where two views are possible.   


In the end, it may be useful to examine the
competence of the Karta or an HUF to deal with and dispose of the property of
the HUF by way of gifts. A gift may be rendered invalid where it is held to be
not permissible under the general law  as
the one made beyond the competence of the person making it. One also needs to
examine whether such gifts when made, though not permissible in law, are void ab
initio
or are voidable at the option of the parties to the gift. The issue
regarding validity of such gift given by the HUF needs to be examined. The
Supreme Court, in the case of R. Kuppayee & Anr. vs. Raja Gounder (2004)
265 ITR 551
, has dealt with this issue and held as under:


“Combined reading of these paragraphs shows
that the position in Hindu law is that whereas the father has the power to gift
ancestral movables within reasonable limits, he has no such power with regard
to the ancestral immovable property or coparcenary property. He can, however,
make a gift within reasonable limits of ancestral immovable property for
“pious purposes”. However, the alienation must be by an act inter
vivos
, and not by will. This Court has extended the rule in para. 226 and
held that the father was competent to make a gift of immovable property to a
daughter, if the gift is of reasonable extent having regard to the properties
held by the family.”


Thus, HUF’s property can be gifted by its
manager or karta only to a reasonable extent, and of immovable property only
for pious purposes. The Courts have given extended meaning to the ‘pious
purposes’ and validated the gift of ancestral property made by the father to
the daughter within reasonable limits. However, such extended meaning given to the
words ‘pious purposes’ enabling the father to make a gift of ancestral
immovable property within reasonable limits to a daughter has not been extended
to the gifts made in favour of other female members of the family. Rather it
has been held that husband could not make any such gift of ancestral property
to his wife out of affection on the principle of ‘pious purposes’.


However, gift of HUF’s property in excess of
reasonable limit or not for pious purposes is not void but voidable  and that too at the instance of other members
of the family and not strangers. In Pollock on Contracts, page 6 (twelfth
edition), this distinction between the terms ‘void’ and ‘voidable’ has been
explained as follows:


“The distinction between void and
voidable transactions is a fundamental one, though it is often obscured by
carelessness of language. An agreement or other act which is void has from the
beginning no legal effect at all, save in so far as any party to it incurs
penal consequences, as may happen where a special prohibitive law both makes
the act void and imposes a penalty. Otherwise no person’s rights, whether he be
a party or a stranger, are affected. A voidable act, on the contrary, takes its
full and proper legal effect unless and until it is disputed and set aside by
some person entitled so to do.”


In the case of R.C. Malpani vs.
CIT  215 ITR 241
, the Gauhati High
Court held that the income derived from the property which is alienated by the
Karta without any legal necessity is not assessable in the hands of the HUF, as
it is only voidable and not void. Similarly, any gift received from the HUF may
be required to be considered (whether income or not) under the provisions of
section 56(2)(x), even if it is impermissible and voidable, unless the Court
has declared it to be void.


[1] In this case, the
Tribunal was dealing with the assessment year 2005-06 and the relevant clause
applicable in that assessment year was clause (v) of Section 56(2) which had
similar provisions

[2] Thamma Venkata
Subbamma (By Legal Representative) vs. Thamma Rattamma [1987] 168 ITR 760 (SC).

The Story of Two Investors


Grace Groner was orphaned at age 12. She
never married. She never drove a car. She lived most of her life alone in a
one-bedroom house and worked her whole career as a secretary. She lived a
humble and quiet life. This made the $7 million she left to charity after her
death in 2010 at age 100, all the more confusing. People who knew her asked:
Where did Grace get all that money?

Grace took humble savings from a meager
salary and enjoyed eighty years of hands-off compounding in the stock market.
That was it.

Weeks
after Grace died, an unrelated investing story hit the news.


Richard Fuscone, former vice chairman of
Merrill Lynch declared personal bankruptcy, fighting off foreclosure on two
homes, one of which was nearly 20,000 square feet and had a $66,000 a month
mortgage. Fuscone was the opposite of Grace Groner; educated at Harvard and
University of Chicago, he became so successful in the investment industry that
he retired in his 40s to “pursue personal and charitable interests.” But heavy
borrowing and illiquid investments did him in. The same year Grace Groner left
a veritable fortune to charity, Richard filed for bankruptcy.

It
is the study of how people behave with money. And behaviour is hard to teach.


The Promise Of The New Economy

Computation power, networks and storage will affect investment area in a big way. The author discusses new platforms that will emerge in a decentralised model that will give birth to powerful new organisations. Siddharth, an IIM graduate, worked heading a equity derivates and algorithmic trading desk, but his life completely changed when he stayed at the Sabarmati Ashram for four years to find answers to some burning questions.

Blockchains and distributed ledger technology have had their share of hype. Bitcoin, Ethereum and cryptocurrencies have enjoyed the limelight, but what is their potential? While there are enough technical articles on how blockchains function, the true challenge lies in articulating their potential.

Simply put, these technologies allow us to maintain a distributed consensus for the ledger. As opposed to a centralised authority maintaining information, we can now do so in a distributed manner. What are the far reaching consequences of this for us? To answer this question, we need to grasp the context of the larger shift that is underway in technology. Blockchain technology, or distributed ledger technology is revolutionary in itself, but part of a much greater puzzle that is falling into place.

Think of the pieces of this puzzle as the holy trinity of technology. Computational power, networks and immutable storage.

Until the advent of the personal computer in the 1980’s, computing was restricted to large institutions due to sheer expense and access to resources. The average person barely caught a glimpse of a computer, let alone engaged with one. However, the computing revolution over the last three decades have allowed us all access to remarkable computational power with the swipe of a finger.

Networks were heavily centralised too, until the advent of the internet. In a world where a simple data connection allows us to broadcast to millions via smart phones, we have reduced our dependence on centralised broadcasting technologies like the printing press, television and radio stations.

There is no doubt that we have all benefited from revolutions like personal computing and the internet. However, we are yet to see their full power manifest. It could be argued that we are on the verge of the last piece of the holy trinity falling into place i.e. immutable storage.

By immutable storage, we mean the ability to store data of any kind without risk of it being lost, deleted or tampered with, unless mandated by a set of rules. In the past we have had to rely on large institutions to store this data for us. For example, governments for holding our land/ birth records, banks holding our financial information, or even large institutions like Facebook or other cloud hosting services holding our intimate information for social networks and apps.

However, several moments in the past few years have exacerbated the need to move to newer models of storing our information. The 2008 crisis called to light our over-dependence on Wall Street banks, while the Cambridge Analytica fiasco at Facebook showed us how misuse of our data can have disastrous impact. Back in India, the problem of fake news is posing new kinds of threats to us – from attacking mobs motivated by false information, to voters making decisions based on facts that are not entirely based on truth.

These problems have asked us all to collectively stop and ask deep question of ourselves. Wasn’t technology supposed to help address these issues? Perhaps, and that is why one could argue that the solution lies in building more resilient, humane platforms that are worthy of us in the twenty first century.

How does Distributed Ledger Technology help in this regard? Well, thanks to innovations in blockchains and distributed ledger technology, we are now seeing massive decentralisation in the ability to offer immutable storage. Instead of reliance on large institutions to store data for us, any individual, collective or organisation can now provide immutable storage to its community/users/customers for significantly cheaper costs.

The power to provide immutable storage can create fascinating new possibilities – you could have micro-entrepreneurs providing services for land records, currencies, smart contracts. In fact, much of 2017 was about establishing new business models with this technology.

But what more could we be building with this? When you look at the holy trinity of technology – computation, networks and storage falling into place, one realises that the sum of the three is way larger than the three individual parts by themselves.

Decentralisation in computation, storage and networks are allowing us to build a whole new future – that of distributed economies. If the catch-phrase of the twentieth century was ‘Opening-up of Economies’ the mantra of the twenty-first is Open sourced economies.

When we use the word ‘Economy’ we typically think of large nations like the United States of America, or Great Britain, or India.

The word economy however, has roots in Greek: oikos, nomos: i.e. rules of the house. This essentially means setting in place rules which allows a community or group of people to interact with each other and function. An economy essentially consists of three layers: governance, reputation and a material currency to keep track of transactions among people.

With the holy trinity mentioned above falling into place, we are now seeing possibilities where anyone leveraging decentralised storage, computation and networking can create and operate their own economy.

In a way, we are moving to a world where local economies or communities of people can self-organise and create, validate and amplify value that is important to them. Why would we want to do this? Because different groups of people can honour different kinds of value. So far, we have been limited to one economic design, or one economic language for all value creation. However, open-sourced economies allow each network or group of people to shape their own contracts and code that they would abide by. Think of these as networks which frame a set of laws for reputation within their community and their own currencies.

What is the motivation for moving towards such a system? It can be summarised best in the words of Gandhi. Through my time spent at the Sabarmati Ashram, I had the opportunity to engage with and interact with stalwarts of Gandhian movements over the last 60-70 years. It was here that I had the opportunity to dive into Gandhian/distributed economics. Think of this as a stream of economics that was dedicated to the beauty of distributed and local economies.

In the 1930s, 40s and 50s, this philosophy took shape in the form of movements like Gram Swaraj, where communities came together to build self-reliant economies. Such economies have been proven over the centuries to be much more resilient and inclusive. But such movements lacked sustainability due to the inherent frictions associated with them. Local economies suffered from issues of weak governance and patriarchy. More over, wealth created within a local economy could not be ported out of the community easily. Such issues caused us to move towards highly centralised, efficient models of money.

The technological revolution spoken of above, helps reverse some of the changes over the past 50 years. Distributed ledgers allow us to enforce rules in a simple, transparent manner. It allows us to build governance in democratic ways as opposed to relying on small groups of people to shape rules.

More importantly, it allows us to port wealth across networks and communities at ease, in spite of diverse designs. How? Well, to understand this better, it is important to tap into an entire stream of distributed economics (the foundational work for this stream was initially articulated by JC Kumarappa, a renowned Gandhian economist, and later developed in the west by economists such as EF Schumacher). It is a vastly different, yet fascinating new world. While the traditional economy i.e. capitalist system is designed to build material capital, distributed economies amplify networks and communities. While the former is built on principles of a zero sum game, the latter uses principles of sufficiency. While the former relies on efficiency, the latter builds resilience i.e. the ability to confine failures to restricted zones. While the former requires centralised regulators, the latter uses ‘reputation systems’ for tracking the behaviour of each individual. Reputation systems are critical for peer to peer networks, which is why the distributed economy is sometimes synonymous with the reputation economy.

To understand this better, here are four fundamental tenets of the reputation economy1

12. It is linked to identity: Within a social network, or community of people, if I have a reputation as a ‘good dentist’ or a ‘film-enthusiast’ it is a reputation that is firmly fixed with me. It cannot be transferred to another entity like we do with money.

  1. It is NOT fungible: What does this mean? The fact that I’m a good dentist cannot be ‘bought’ by someone else. Sure, my reputation as a good dentist can be monetised as a practicing doctor, but I cannot sell it in return for money. That would be absurd.

  1. Multi-dimensional and Diverse: When we qualify people, or describe them to others, we do so using multiple labels. We do not rate our friends using one uniform scale i.e. from 0 to 100. In fact, when we engage with people we are newly introduced to, it is always better to have multiple data points. I might be a food lover, a good speaker, a cyber security expert— they are all records of my reputation. We cannot ‘add’ up all these individual reputations to present one meta score for Siddharth like a 65 out of 100. In fact, you might say he is a 4 star cyber security expert, a 65/100 food lover, a ‘fantastic’ speaker and more. In fact, the more diversity you have in categories and scales, the better it is.

More importantly, each reputation is designed differently. Earning a reputation as a good dentist might take me decades of blemish free practice and deep knowledge. A reputation as a food-blogger could be attained in weeks. They each have different scales and representations – some can be numbers, others scales, other binary classifications. The bottom line, diversity is celebrated in this world as opposed to uniformity.

It is vastly different from the traditional economic system, where everyone’s net-worth can be summed up in one scale i.e 5mn USD, or 150mn USD and so forth.

  1. Reputation can be staked and ported: Does this mean we can ‘invest’ reputation and create a portfolio? Well, no, but it is like ‘lending your name’ or credibility to different intentions. If I ask you for movie recommendations, you are lending your name to the 5 films that you love. If it turns out that they are not great, your reputation in my lens drops, and vice versa. In this way, staking reputation on other initiatives can bring us a corresponding increase or decrease in reputation.

What is interesting here is that my reputation isn’t a ‘zero sum game’. If I had a 100 dollars to invest across 10 new organisations, I am limited by this number. I cannot make commitments for 500 dollars. But with reputation I could lend my name to innumerable initiatives, it is just that I have to be prepared for the consequences of my actions!

So how will all of this be enabled? Over the last couple of months, we have seen some heavy-weights move in this direction to build the nuts and bolts for this economy. Hub, initiated by the co-founder of LinkedIn, Colony.io and Holochain are just some examples of protocols that will allow us to design and play with reputation in this way.

It’s critical to understand the importance of these initiatives. They are allowing network effects to play into reputation, which was not considered immutable in the past. This immutability is important, because it allows reputation to attain money-like qualities, something it did not possess in the past. These rapid innovations are allowing entrepreneurs to start plugging into networks and provide all kinds of benefits and utilities to reputation – something that will allow us as users to feel secure in its ability to provide for our needs.

While we will have protocols in place to allow reputation to be captured and ported, some of the fundamental issues with this kind of an economy is that the diversity can sometimes be confusing. We are soon foreseeing a world with thousands or millions of distributed economies – each with its own scale and design and benefits. In the past, we moved away from the inconvenience of barter and distributed economies towards the convenience of one single design for money. These technologies however, help simplify this problem. With that in mind, Sacred Capital is helping address issues in this space in two ways:

  1. Taxonomy i.e building relationships between the varied kinds of reputation. Is my reputation established in ‘women empowerment’ related to social-justice? Or is it related to my love for food?

  1. Inter-portability i.e. how does my ‘women empowerment’ score translate to sustainability. Is a 4 star rating equivalent to 75 in sustainability?

This is where Sacred Capital comes in. Through conversations on our platform, and by establishing precedents of who stakes what for which initiative we are going to be able to derive intelligence for both taxonomy and inter-portability of reputation. It is like crowd-sourced research, but for the reputational economy. Think of us as the inter-change, or an exchange, but for reputation.

In the past we have only been able to influence value at scale with money, but we now have countless levers at our disposal. That means individuals and entrepreneurs such as you will be able to initiate distinct conversations, shape movements, and explore new dimensions of value creation. All of this because you can port, scale, leverage and stake reputation to give birth to new kinds of networks!

In summary, we should say that this is not a radical new concept that will see adoption in Silicon Valley before other regions. In fact, you could argue that these designs for wealth resonate intuitively with people in India, Latin America and S. E. Asia because they are fundamentally diverse and heterogeneous in their way of life. Instead of relying on centralised institutions, they have relied on social fabric for their well-being over centuries. Even today, communities in India pride themselves in their ability to look out for each other, circulate capital for commerce and entrepreneurial ventures through these social networks.

Some argue that this is a new form of literacy. Over the last 500 years, huge benefits have accrued to mankind due to a vast rise in literacy across the globe. 500 years ago, only 1% of the world’s population was literate, however, we now have more than 87% of the world benefiting from literacy. It is not just access to jobs, but the ability to organise, innovate and the ability to create value where there was none. Think about how that might translate to the open-sourcing of economic language i.e. allowing people to articulate and validate value that is important to them, as opposed to restricting themselves to one centralised way of sustaining themselves. The possibilities are endless.

Real Estate – A Viable Investment?

The author is also a law graduate, with
more than twenty-five years of experience in real estate business including
founding and leading a property consulting firm in India. Prior to real estate,
Mr Vakil worked in senior roles at several listed entities and a fortune 500
company.


Over the years, Real Estate has evolved
into a full fledged investment class. In this free flowing article, the author
discusses the realities and myths about investing in real estate.


For individuals, is investment in real
estate still a viable investment option? Or should individuals invest through
REITs? How should an individual evaluate whether to invest in real estate? What
should be the investment strategy? These are some of the issues addressed in
this article. What follows are some important issues, beliefs and myths that
are prevalent in real estate.


1.  Returns on Real Estate:

Out of the 10 richest persons in the world,
7 have become rich due to Real Estate. Need I say more!! If you had an option,
to invest in Real Estate say in 1992, when the industry was liberalised by Dr.
Manmohan Singh, the comparison would be somewhat like this:


   Real Estate in south Mumbai
up by at least 100 times


   Investment in BSE Sensex
stocks up approximately 70 times


   Gold, with all its fluctuations,
would have given you 7 fold increase and Silver about the same.


   If you were permitted to
invest in USD, it would have been twice.


The conclusion is
obvious, that in the long run, Real Estate, if chosen wisely and at a good
location, would probably out beat any other asset class.


2.  Issue of Sizing and Pricing:

Lesser the size of Real Estate, bigger is
the universe of buyers. Bigger the size of Real Estate and value, the universe
of buyers shrinks and, at time, shrinks disproportionately. For a developer to
be successful and for a buyer to succeed, the mix of size and price has to be
optimum. This is because “the rate per sq.ft.”, will have no meaning beyond the
affordability level. Having said this, the quality of construction plays a very
important role. There is a developer in Bangalore, who provides quality at
competitive price, that is unmatched by any other. He goes to the extent of
rounding off all edges of walls to ensure that children don’t get hurt! The
plug points are at the right place and even in high rise buildings the windows
withstand the onslaught of rain and extreme breeze.


3.   Location:

The mantra for Real Estate is: LOCATION,
LOCATION, LOCATION.


It has a double whammy. Exit or
disinvestment is easy and quick and appreciation is almost guaranteed. There is
no other factor that scores over a good location. Do you know that Altamount
Road in Mumbai is the 10th most expensive location in the world?


4.   Tax Breaks and Incentives:

Over the years, the Government has done a
lot to encourage investment in Real Estate, both for the investor and a little
bit for the developer. Chartered Accountants will remember section 80-IB
(though not many developers have succeeded in taking advantage) and now section
80-IBA. Affordable housing is a new mantra and the good thing is that it has
reference only to the size (30 sq. Mtrs. for the four metro cities and 60 sq.
Mtrs. for the rest of India). The result is that over 80 percent of the
development would qualify to be included as “affordable housing”, on which the
developer gets full tax break. The end result is that a compact 2 bedroom flat
outside the four metro cities would still qualify as “affordable housing”. I have
seen a number of developments in Chennai recently, which fall into this
category and selling despite recessionary market conditions.


5.   Government Levies and Taxes:

Stamp Duty is a State subject and continues
to be high at 5 per cent and more in the metros.


Property taxes in certain metros have
created avoidable litigation and a lot of confusion. The change of basis from
annual lettable value to capital values have yet to fully stabilise. There is a
need to bunch up similar issues and get a ruling, which can apply to most
pending cases,  concerning property
taxes.


The major problem for Real Estate is the
Ready Reckoner values or jantri, as known in some States. Over 30 percent of
flats in south Mumbai, are not getting sold because the market value is up to
30 per cent below the Ready Reckoner value. As CAs you know the implication of
this mismatch. It not only results in higher stamp duty, which is levied with
reference to Ready Reckoner value, but there is a deeming provision both for
the seller and the buyer. The difference between the Ready Reckoner value and
the sale value has to be offered for taxes, both by the buyer and seller.


For the developer, there are issues on how
profit is computed on “under construction” projects and for CAs the new Accounting
Standards (Standard 115) offers a major challenge.


GST will take some time to stabilise and
there is no guarantee that the benefit accruing to the developer, will be fully
passed on to the buyers. For under construction property the GST is a huge
additional cost, which in most cases, the developer, under the present
recessionary market, is required to absorb fully or partly.


6.  Investible Quantum:

Real Estate as an investible class is for
people with deep pockets. The minimum surplus required is at least Rs.2 crores
for cities like Mumbai and at least Rs.50 lakhs for other locations.


The investor should remember that exit can
be time consuming and expensive. Also Real Estate is incapable of being broken
down or split. In most cases, either you keep the property or sell it, but
selling “in parts”,
is not possible.


7.  Titles:

Please do not save on legal fees, at least
when you buy a property. Titles can be really complicated and a legal scrutiny
is a must. The acid test is “can you sell the property at will, without any
possible issues?” One has to be careful about the mortgages, the lock in
periods, combined or joined flats (known as Jodi flats), terraces that have
been sold to prospective buyers, etc. etc.


There is a recent development, which is
really going to help small investors – “a title insurance”.  It’s expected that insurance companies will
now also offer “title insurance” in line with what is happening in developed
countries.  This is path breaking and
will definitely benefit a buyer/investor.


8.  Investment basket:

I would recommend that not more than 30
percent of your investible wealth should be invested in Real Estate, not
counting the house in which you live. It would not be wise to put substantial
amounts of your liquid assets in Real Estate as not only it would be volatile
but exiting would be difficult.


9.  REITS:

REITS will not only change the way
investment in Real Estate is done, but make it possible for smaller investors
to invest in Real Estate. Broadly REITs would operate like a Mutual Fund, where
the investments are in commercial Real Estate, earning rental yields. REITs
will make investment decisions broad based and spread over wider geographies.
With the spread of risk, the returns would also marginally come down. The good
thing is it gives an opportunity to a smaller investor to invest into real
estate.


There are certain issues like stamp duty,
capital gains, etc. that are hindering the success. It is expected that
over a period of time, this will be resolved and REITs will become successful.


The day when REITs begin to invest in
residential Real Estate like in the US, we will begin to see real
professionalism and a reach, that we have never seen before.


Investment into commercial properties today
gives a yield of up to 7 percent, whereas residential properties
barely provide yield of 2 percent. However, if the  appreciation for the period of investment is
taken into account probably, the residential REITS will fetch more than
commercial REITs.


10. Investment in Real
Estate abroad:

Investors who
have substantial surpluses and who desire to diversify their investment into
Real Estate abroad, will now have an option. Reserve Bank permits remittance of
upto USD 250,000 per person, per year, for investments. If we take 2 or 3
family members together then the investment could exceed USD 1 million, which
is a decent investible amount. Currently, UK, Dubai, Singapore and certain
parts of US are attractive for such investments.  Also there are possibilities of investing in
a newer class of investments like students housing, old age or retirement
homes, etc.


For a long period of time, Rupee has
depreciated vis-a-vis the US Dollar. Any investment made abroad will provide
insulation to the investor from such currency depreciation.


11.   Conclusion:

Over a 10 to 20 year period, investment in
Real Estate, if done wisely with good titles and at a good location would give
a return that can exceed any other asset class. I have seen this happen in my
career and I am confident of the future. The key word is “patience”. Don’t be
desperate if prices stagnate, don’t be greedy if prices escalate beyond
targeted appreciation. I recommend investing in Real Estate, without borrowing
money, excepting for the primary home you stay in.


The real thing about Real Estate is that it
is tangible, it is real and more certain than other asset classes.


Good luck to you! Jai Ho! 


Equities – Simple, But Not Easy

In this
simple and easy article, the author shares his perspective on equity and funds.
The article walks you through many data points and tables to make a point about
equity markets. The author is the chief investment officer and fund manager of
a leading fund house. An IIT and IIM graduate and a CFA, Prashant talks about
taking a long view of equity markets. Prashant has been in the markets for more
than 25 years and manages several thousand crores of assets under various funds
under him.


Nature
of Equities

Equities are
remarkably simple. An equity share is simply volatile in the short run, but in
the long run, its returns are close to the growth of the underlying business.
This implies that for a diversified portfolio, the long term returns will be
close to the nominal GDP growth of the country (real growth + inflation). This
is so because all businesses together make the economy and thus the average
growth of different businesses will be similar to the economy’s growth rate.


The chart
below depicts real decadal GDP growth
n and inflation n
for India since 1980


Exhibit 1


Source: World Bank
data


It is
interesting to note that the decadal average growth in India’s nominal GDP has
been fairly constant. This is despite the changing headlines over the decades –
different governments, several global and local crises like Gulf crisis, ASEAN
crisis, 9/11, global financial crisis post Lehman, European debt issues etc.,
periods of high and low interest rates, periods of high and low oil prices etc.
etc. 

The persistent
real growth in India is explained by:


   Excellent demographics – rising population,
even faster growth in number of families

   Falling dependency ratio and a healthy
savings rate

   Ample availability of  natural resources

   Large availability of skilled, young, English
speaking and competitive manpower

   Low penetration of consumer goods and
improving affordability


It is
interesting to note that these drivers of real growth are not affected by
change in governments, global developments etc., and this is what explains the
remarkably steady growth in India. Further, in periods of high inflation i.e.
1991-00, as interest rates move higher, EMI’s increase thus reducing
affordability and hence real growth; and vice versa. This is why the nominal
growth rates (real growth plus inflation) has remained more or less constant.


The
When, Where and How Much of equities?

Someone with
an interest in equities typically asks the following three questions:


When should I
invest?


Where (which
funds / stocks) should I invest?


How much
should I invest?


When
should I invest?

The table
below depicts Sensex rolling returns for 1, 5, 10 and 15 years since its
inception in 1979 :


Exhibit 2


Sensex % Return CAGR

YEAR END

SENSEX

Rolling 1 year

Rolling 5 years

Rolling 10 years

Rolling 15 years

(1)

(2)

(3)

(4)

(5)

(6)

Mar-79

100


Mar-80

129

29


Mar-81

173

35


Mar-82

218

26


Mar-83

212

-3


Mar-84

245

16

20


Mar-85

354

44

22


Mar-86

574

62

27


Mar-87

510

-11

19


Mar-88

398

-22

13


Mar-89

714

79

24

22


Mar-90

781

9

17

20


Mar-91

1168

50

15

21


Mar-92

4285

267

53

35


Mar-93

2281

-47

42

27


Mar-94

3779

66

40

31

27

Mar-95

3261

-14

33

25

24

Mar-96

3367

3

24

19

22

Mar-97

3361

-0.2

-5

21

20

Mar-98

3893

16

11

26

21

Mar-99

3740

-4

0

18

20

Mar-00

5001

34

9

20

19

Mar-01

3604

-28

1

12

13

Mar-02

3469

-4

1

-2

14

Mar-03

3049

-12

-5

3

15

Mar-04

5591

83

8

4

15

Mar-05

6493

16

5

7

15

Mar-06

11280

74

26

13

16

Mar-07

13072

16

30

15

8

Mar-08

15644

20

39

15

14

Mar-09

9709

-38

12

10

6

Mar-10

17528

81

22

13

12

Mar-11

19445

11

12

18

12

Mar-12

17404

-10

6

18

12

Mar-13

18836

8

4

20

11

Mar-14

22386

19

18

15

13

Mar-15

27957

25

10

16

12

Mar-16

25342

-9

5

8

14

Mar-17

29621

17

11

9

15

Mar-18

32969

11

12

8

17

Probability of loss

13/39

3/35

1/30

0/25


Source: Bloomberg


Sensex
returns are computed for 1,5,10 &15 years from the date of investment.
Returns for 1 year are absolute and above 1 year CAGR.


CAGR: The
rate at which an investment grows annually over a specified period of time.


Column 2:
shows the value of BSE index at the end of month of the respective year.
Probability of gains is the number of times the investor would have made
positive returns.


Column 3 to
6: Represents the return earned on the investment for the referred period. For
e.g. If you invested in Mar-79 when SENSEX Index was 100, then 1 year returns
(in Mar-80) would have been 29%, 5 years returns (in Mar-84) would have been
20%, 10 year returns (in Mar-89) would have been 22% and 15 year returns (in
Mar-94) would have been 27%.


As the column
of 1 year return shows, returns in short run are simply volatile. Since there
is no pattern of one year returns, it is evident that it is futile to time
the markets in the short run. This is also why equities are considered risky in
the short run and are only recommended for long time horizons
. Interestingly,
long term returns are less volatile and as holding period increases, returns
converge close to nominal GDP growth rate of 14-15% (S&P BSE SENSEX has
returned close to 16% since its inception in 1979 till June 2018). Further,
chances of losses reduce as holding period increases, thus reducing risk in
equities.


Interestingly,
not only is it difficult to time the markets in the short run, timing hardly
matters over the long term. For example, whether someone invested at a Sensex
of 510 in Mar 87 or at 398 in Mar 88 hardly made a difference ten years later
when the index was 4000 in 1998!


The key to
successful investing is actually not in timing but in something that is
becoming increasingly rare in times of whatsapp and e-commerce – and that is
patience.
As India is a growing economy, the size and value of businesses
also keeps on growing. This implies that the longer one remains invested – the
more the wealth is likely to be created. Invariably, successful investors are
also the most patient investors. Afterall, if someone had simply remained
invested in the Sensex for last 39 years – through good and bad times, through
bullish and bearish times would have made his wealth 350 times –  which is hard to match by the traders and
timers !


Finally, while
short term timing is very difficult, it is possible to take a medium to long
term view of the market based on the past returns of the markets vs. nominal
GDP growth. As explained earlier, over the long term, stock market indices in
India are growing around the same rate as the nominal GDP (GDP Growth +
Inflation) of India. This implies that when in any extended period of, say
10 years, indices grow significantly less than nominal GDP (i.e. 1992-2002),
they tend to make up in the future by delivering higher returns and vice versa.


Where
should I invest?

Each business
has specific risks. These risks are increasing by the day due to rapid changes
in technology and due to several disruptive business models that are emerging.
To reduce business specific risks, it is strongly recommended to maintain
effective diversification when investing in equities, irrespective of whether
one is investing directly or through mutual funds. To discuss more than this
about security selection here is neither desirable nor feasible. Suffice to say
that security selection deals with the future, with uncertainty and even
professionals make several mistakes. It is best to leave this to experts
therefore unless one really understands equities i.e., prefer mutual funds over
direct investments. In my experience, the majority of direct investors have not
done well – the most popular stocks in 1992 were in cement; in 1999 it was the
turn of IT stocks; in 2007 it was the turn of the infrastructure related
stocks, similarly pharma companies were in favour around 2015. On each
occasion, these popular investments did not perform as expected. These
observations give us an insight to a common mistake that investors tend to make
in equity investments. It has been experienced that many investors simply
invest based on past trends i.e. when a sector or a group of stocks does well
for few years these become increasingly popular and attract higher
participation and vice versa. In reality, high returns of the past (especially
when they are disproportionate to business growth) could indicate over
valuation and vice versa. In view of the above, such investors who do not have
proper understanding of equities are probably better off with mutual funds.


Choosing
a right Fund

John C.
Bogle
, founder of the
Vanguard group has suggested in his book “Common Sense on Mutual Funds
that three to five mutual fund schemes that have done well across market cycles
are all that an investor needs for one’s equity portfolio.


With a
tailwind of ~15% p.a. economic and Sensex growth highlighted earlier, it is no
surprise therefore that around 74% of equity and hybrid equity funds with more
than 15 year history have delivered more than 15% CAGR and around 88% of equity
and hybrid equity funds have delivered more than 12% CAGR over last 15 years.
The better ones have delivered returns close to 20% CAGR over this period. (Source:
NAV India)


Interestingly,
while funds proudly display long term returns of 15 – 20%, only a small
minority of investors have experienced similar wealth creation. This is so
because, the vast majority of investors moved in and out of equity funds
several times in this period, from equity funds to liquid and back, from lower
rated funds to higher rated only to witness role reversal of funds in some
time, from large cap to mid cap or vice versa etc. etc. In other words, the
majority frequently churned their funds and refused to stay put. Only a small
minority that simply remained invested in a few carefully chosen funds for
these entire period reaped immense benefits.


To take an
analogy from the game of cricket, the good batsman is not the one who scored
the highest in the last game but is the one who has the best batting average in
say, last 10 or 20 matches.


Just as one
match cannot be used to judge a good batsman, similarly one year’s performance
is too short a time to judge equity funds. Instead, there is merit in assessing
equity funds’ over 3-5 year or longer periods


Funds that
have a good track record across market cycles are likely to be investor’s best
bets and 3-5 such funds is all that an investor needs in my opinion.


How much
should I invest in equities?  The
Importance of Asset Allocation in Equities


Equities are a
great compounding machine (as mentioned earlier, Sensex itself is up 350 times
since 1979) and India has good growth prospects. However, while equities hold
promise over long term, in the short to medium term, equities almost invariably
carry significant risks as the past has repeatedly reminded us.


This suggests
that an investor should assess and allocate one’s risk capital only (that
portion of capital which can be kept aside for few years and on which
volatility can be tolerated) to equities. This simply put, is asset allocation.

Asset
Allocation is critical to successful investing. Unfortunately, it is often
neglected, as more attention is given to timing, security selection, moving
across funds etc.


After
optimal asset allocation, all that an investor needs is patience and discipline:
Patience to remain invested for long
periods in equities / equity mutual funds to allow compounding to work and the
discipline of not panicking and on the contrary increasing allocation to
equities when the returns over the past few years have been disappointing or in
simple words when the P/Es are low.


The
illustration below highlights the significant impact asset allocation has on
wealth creation over longer time periods:


Exhibit 3

Initial investment of Rs 100

Value at Year 10

10 year CAGR (%)

Equity %

Debt %

100

0

404

15.0

80

20

367

13.9

60

40

328

12.6

40

60

291

11.3

20

80

253

9.7

0

100

216

8.0


For
illustration purposes only.  For
calculation purpose CAGR returns has been taken as 15% CAGR for equities and 8%
CAGR for debt. Returns are not assured / guaranteed.


Economic
Prospects of India

As explained
earlier, India is a secular growth economy. Interestingly, other macro
parameters also like fiscal deficit, current account deficit, FDI, inflation
etc. have witnessed significant improvement over last 5 years as can be seen
from the table below.


Slowdown in
GDP growth in FY17 and FY18 is due to adverse short term impact of
demonetisation and GST. Going forward as this effect neutralises, GDP growth
should accelerate. The table below summarises the key macro-economic indicators
and forecasts for India: 

Exhibit 4

Improving macros

FY13

FY14

FY15

FY16

FY17

FY18

FY19E

GDP at market price (% YoY)

5.5

6.4

7.5

8

7.1

6.7

7.2

Centre’s fiscal deficit (% GDP)

4.8

4.4

4.1

3.9

3.7

3.5

3.3

Current Account Deficit (CAD) (% GDP)

4.7

1.7

1.3

1.1

0.7

1.9

2.5

Net FDI (% of GDP)

1.1

1.2

1.5

1.7

1.6

1.2

1.2

Consumer Price Inflation (CPI) (Average)

9.9

9.4

6

4.9

4.5

3.6

4.6

India 10 year Gsec Yield % (at year end)

7.9

8.8

7.8

7.6

6.8

7.6

Na


Source: CEIC, Macquarie Macro Strategy;
Economic Survey, E-Estimates


Some of the
macro parameters are likely to witness some deterioration in FY19 primarily as
a result of higher oil prices. These are nevertheless expected to remain at
healthy / reasonable levels. GDP growth should however accelerate with improvement
in capex in housing, urban infrastructure and industrial capex led by oil &
gas, metals, fertilizers etc.  Capex in
roads, railways, power T&D has already seen material improvement. RBI has
estimated GDP growth of 7.4% and 7.7% in FY19 and FY20 respectively vs. 6.7% in
FY18.


Equity
Markets Outlook

Equity markets
in India have lagged nominal GDP growth for several years now. As a result,
Market cap to GDP ratio at 70% is below long term average. Market cap to GDP
ratio for CY20 at 62% which will become relevant one year from now looks
particularly attractive. Market cap to GDP ratio is a better tool to analyse
markets instead of P/E in current environment as corporate profitability is
below long term averages.


Exhibit 5

India market cap to
GDP ratio, calendar year-ends 2005-18 (%)


Source: Kotak Institutional Equities, updated till 30th
June, 2018


Note:

a) From
2005-17, S&P BSE SENSEX PE is based on 12 month forward estimated EPS.

b) For 2018 and
2019, Kotak has calculated S&P BSE SENSEX PE based on estimates as of Mar
19 and Mar 20 end and used market cap as of June 30, 2018.


In the last
seven years, corporate profits as % to GDP have fallen from 5.6% in FY10 to
3.0% in FY17 (chart below).  As a result,
despite improving macro as seen in Exhibit 4 earlier, NIFTY profit growth has
been weak at 7.7% CAGR between FY10 and FY18. This phase of weak earnings
growth now appears to be ending. Driven by improving fundamentals of key
sectors like corporate banks, capital goods, metals etc., the profit growth
should improve in future.


Exhibit 6


Source: Morgan Stanley Research, year is
Fiscal Year


A recent
development in equity markets has been the underperformance of small caps and
midcaps. This underperformance has to be viewed in the backdrop of sharp
outperformance in last 3 and 5 years as seen in the table below:


Exhibit 7


Absolute Returns %

as on June 30, 2018

1 year

3 years

5 years

Nifty 50 (A)

12.5%

28.0%

83.4%

Nifty Midcap (B)

2.5%

39.8%

147.6%

Outperformance vs NIFTY 50 (B – A)

-10.0%

11.7%

64.2%

Nifty Smallcap (C)

-1.8%

34.8%

146.9%

Outperformance vs NIFTY 50 (C – A)

-14.4%

6.8%

63.5%


 Source: Bloomberg

At this
juncture, given the large outperformance of midcaps / smallcaps in last 3, 5
years and expected revival of NIFTY profit growth as can be seen from the table
below, risk-reward ratio appears to be more in favor of largecaps.


Exhibit 8

Fiscal year

2018

FY19E

FY20E

CAGR FY18 to FY20E

EPS

449

546

664


NIFTY Earnings growth (%)

2.3

21.6

21.6

21.6


Source: Kotak Institutional Equities


Markets are
trading near 18x CY18 (e) and 15x CY19 (e) (Source: Bloomberg Consensus as
on June 30, 2018)
. These are reasonable multiples especially in view of
improving profit growth outlook. Markets thus hold promise over the medium to
long term in our opinion. Adverse global events, sharp moderation in equity
oriented mutual funds flows and delays in NPA resolution under NCLT are key
risks in the near term. 


Conclusion:

In conclusion,
equities are a simple asset class. However, getting the best from equities is
not easy. That needs clear understanding of equities, lots of patience and
faith in difficult times. The prospects of equities are closely tied to the
long term prospects of the economy which are promising for India. To benefit
from equities investors should estimate their risk capital and invest the same
in a few carefully selected funds and then hold these for long periods.
Remember that the successful equity investors also tend to be the ones who
think and hold equities / funds for the longest.


Note: The views expressed are of Prashant
Jain, Executive Director and Chief Investment Officer, HDFC Asset Management
Company Limited as on 23rd July, 2018 and not necessarily those of
HDFC Asset Management Company Limited (HDFC AMC). Neither HDFC Asset Management
Company Limited and HDFC Mutual Fund (the Fund) nor any person connected with
them, accepts any liability arising from the use of this document. Past
performance may or may not be sustained in the future. Readers before acting on
any information herein should make their own investigation and seek appropriate
professional advice and shall alone be fully responsible / liable for any
decision taken on the basis of information contained herein.


Mutual Fund
investments are subject to market risks, read all scheme related documents
carefully.

Emerging Canvas Of Investment – Opportunities And Risks

This article walks us through the opportunities and risks
of investing in India.  People are all
ears to the India story, the author takes us through the risks and
opportunities. Dr Uma Shashikant is a founder and chairperson of CIEL and holds
a doctorate in finance. She is well known as a writer, speaker, researcher,
consultant and trainer.


India as an investment opportunity is a theme that has
persisted for a long time, since we opened up to global capital inflows in
1993. The novelty about India as an emerging market was very high in the
initial period, and then the story was tempered by several ups and downs in the
last 25 years. There was a time when the primary attraction of India was its
insulation from global markets, evidenced by a low correlation with most
markets. During periods of crisis and collapse elsewhere, Indian stock markets
seemed unscathed. All that changed soon. By 2007 it was clear that India was
not decoupled from the world, but quite amenable to being impacted by global
head winds. Investing in India still remains an attractive proposition, both
for global and local investors due to the sheer opportunity for growth.


The attractiveness of emerging markets like India, and the
returns such markets offer to investors arising from the potential that a
growing economy offers. Benefits of market expansion, development of new
technologies and innovations, growth in infrastructure, services and
manufacturing sectors, higher rate of GDP growth compared to the rest of the
world, stability from elected governments, free press and democratic
traditions, and modernisation arising from increased exposure to the world, are
all enduring factors that make India an attractive investment story. Domestic
investors who in the thick of all the action taking place, are better poised to
make the most of these opportunities. Several institutional investors, domestic
and global, view India as a very profitable long term investment play and
returns on investments corroborate that assessment.


Quality concerns

Where do the risks lie? The primary risk to an investor in
India is the quality of businesses they choose. Private equity investors are
quite used to an intense search for investment opportunities, but they would
also testify to the difficulties in finding good businesses to invest in India.
There is an underlying culture of exploitative capitalism in play, made worse
by favouritism, corruption and lack of enforcement of the rule of law, that
make Indian markets very risky to the investor. There are innumerable examples
of business success that came about not because of innovative entrepreneurship,
but mere crony capitalism at play. It takes a while to understand how nefarious
players could spoil otherwise thriving and growing opportunities in coal,
power, mining, roadways, banking, real estate, jewellery, and airways to name a
well-known few, to short cut the process for private profits. Many businesses
have emerged to be a kind of mafia in their own right, encumbering upon public
goods for private gains, making many investors wary.


There are world class businesses that India has built; there
are innovations that the country and its entrepreneurs can be proud of; there
are foreign collaborations that have worked excellently to bring quality
products to India and benefit from the growing markets here. However, to the
discerning investor, the problem of not knowing whether a business succeeds
from strong strategy or the existence of crony capitalism hiding from plain
sight is a tough one. Selecting the right businesses to back remains a
challenge for the investor in Indian markets.


The second big challenge to investors is the burden of
historical baggage. Nowhere is this evident more starkly than in the banking
sector in India. The policy misstep of nationalising banks many years ago and
stripping the banker of accountability in lending decisions has created
tremendous damage to the banking sector. Despite the opening up of the sector
to competition and the implementation of various recommendations to strengthen
the system, the problem of poor quality assets has only grown with time, and is
now large enough to threaten the existence of erstwhile strong banks. From a
time when we believed that the public sector would lead the economy and build
institutions of benevolence in a socialistic model, we have taken a turn to
embrace capitalism and the market economy. However, we still have several
businesses owned by the government in a range of sectors from airlines, mining,
transportation, metals, beverages, hotels, telecom, and insurance. While
accepting that the government has no business to be in business, we have
neither privatised these, nor dismantled the bureaucracy that supervises them.


To the investor, the existence of these pockets of
inefficiency that simultaneously enjoy government patronage, is a risk. How
would one evaluate the banking sector, for instance? Would one see it as a
growth business that can exploit the low penetration of banking services, the
huge potential to expand credit, and the opportunity to formalise several
informal sectors? Or would one see it as a risky business with a systemic risk
of a possible bank failure from NPAs? Or is it a sector with the lack of clear
policy guideline with respect to the treatment of a bad asset, its recovery and
rework of the balance sheet? To an investor the presence of historical baggage
is an unresolved risk that makes an investment decision needlessly complicated.


There are always fears of the immediate events and factors
that may matter in the foreseeable future. That 2019 is an election year is a
factor that weighs on the minds of several investors. They would worry about
policy decisions that pander to the electorate and interest groups of the
ruling party, and about reckless decisions with an eye on the ballot. Or they
would worry about possible destabilisation from a result that may not bring a
majority government. One of the primary reasons for our inability to forge
ahead the path of reforms we set upon in 1991 has been the various ragtag
coalitions that have ruled the country and investors continue to be wary of
that risk. However, the resilience of Indian businesses to the political risks
and changes in the parties that ruled has also been established in the last 25
plus years. Therefore the long term investment story for India is more about
the opportunities offered to businesses by the unique factors that enable growth, than about the risks from the political
environment.


Enough has been written about the demographic advantages of
India, the high GDP number, the opportunity for the economy to double in record
time, and the growth from growing global exposure. Let’s consider two
overarching themes that will matter to the long term investor, who would like
to stay invested and make the most out of the opportunities offered by an
emerging economy like India.


The first theme is the consumption story that will primarily
drive India’s growth and offer the highest potential for investment returns.
The second theme is the one that will temper these returns and remain outside
the realm of control of the investor – the changing global trends. An
investment strategy that considers both these factors is likely to benefit the
investor the most, in terms of balancing risks and return.


Consumption

The Indian consumption story has been told with various
modifications and nuances ever since the economy opened up in 1991 and the
theory that consumers will propel growth gained ground. The liberalised Indian
market place of the last 27 years has been undoubtedly driven by consumers.
Most sectors that saw significant growth and gains in those years, from telecom
to automobile and tourism to fashion have benefitted from the ability and
willingness of the Indian middle class to spend more. Boston Consulting Group estimates
that India’s household spending will triple to $4 trillion by 2025. The middle
class is estimated at 600 million, a number that is about twice the population
of the US, about 60 million short. It is tough to ignore the impact of the
wallet of the middle class Indian.


The consuming Indian had not been easy to stereotype. Many
global brands have watched in dismay when fake versions of their produce flood
the market with cheap lookalikes. They reported that the Indian consumer was
willing to compromise quality for price. Even before they began to generalise
that Indians may be unwilling to pay top dollars, the expansion of the markets
for luxury goods left most observers stumped. From luxury homes to cars,
jewellery to destination weddings, Indians seemed quite willing to splurge.
Early observers looked at urbanisation as the trigger for consumption. Soon
enough, the demand for goods and services from rural markets began to outpace
urban markets, and many producers modified their strategy to capture the imagination
of Bharat, rather than India alone. Before we theorise that the new demand will
be driven by the millennials, there are studies that show the emerging spending
power of the newly retiring Indian who is ready to buy more toys, travel the
world and pay for a new experience. Tracking the trends in the Indian
consumption story has thus remained a challenge. The risk in this sector also
stems from these changing assumptions about consumer spending.


We can divide consumption into two categories – essential and
discretionary. The rate of growth in discretionary spending is estimated to be
much higher than the rate of growth in essential spending. There are two
primary reasons: First, the rate of inflation that applies to essentials has
been lower, while prices of discretionary items have been increasing more
rapidly. Second, the availability of bank loans and the increased use of formal
credit by households has enabled a higher discretionary spend. The amount a
household spends on transport and travel is no longer dictated by cost of
public transport, when it is easier to obtain a bank loan and get to work in a
personal vehicle.


The investment opportunities triggered by the consumption
story are quite vast, wide spread and subject to a steady and sustainable
growth over a long period of time. A long term investment strategy will ride
the consumption story and the growth prospects it holds. Food and beverages,
alcohol and entertainment, clothing, fashion and accessories, automobiles,
telecom, housing and communications are all sectors that directly benefit from
the Indian consumption story.


Investors in the consumption driven sectors have a diverse
range of opportunities: Several PE firms and boutique investment firms
routinely chase consumption stories for their growth opportunity. Portfolio
managers offer thematic plays that focus on consumption to provide a
concentrated bet; mutual funds offer both diversified portfolios and thematic
funds to capture this opportunity; and the simple low cost index funds offer a
diversified bet that also has significant weightage to consumption stories.
Growth investing in India would not ignore consumption driven sectors.


Global Trends

The changing world order is always a challenge to investors.
Much as one would like to invest within the local context and primarily in
domestic businesses, the performance of those businesses as well as the stock
markets where these businesses are valued, are significantly impacted by global
trends and policies of various governments. Returns and risk of various asset
classes is impacted by these global trends. The emerging risks to oil from the
growing tension in the Middle East, and the broad projection that we are headed
towards $100 per barrel for crude, alters so much for the Indian markets. As a
net importer of crude, and as a country with high dependence on oil and a lower
level of export engagement with the world, rising oil prices will impact our
balance of payments, lead to a depreciation in our currency, and also impact
our fiscal balances.


There is then the question of FII flows, which are impacted
by both strategic and tactical allocations based on the global trends. If there
is a negative global outlook arising from rising oil prices, tense global trade
and policy relations, and uncertainty about the direction the developed world
would take, overall strategic allocations to emerging markets would fall, as
money remains risk averse and in home markets of global investors. In that
context, the tactical allocations between various emerging markets and the
relative share of India in global capital flows would not matter much. It is an
overall positive scenario for global flows that the relative attractiveness of
India in terms of its GDP growth, market performance, domestic consumption and
investment, and quality of government and policy will matter more.


The risk of a no holds barred trade war will have its own
ramifications for the global economy, and most leaders are keen to avoid an
escalation of the retaliatory stance on tariffs and protection. Years of work
done by the WTO to dismantle destructive tariffs are now under the risk of
being undone, and the carving out of nations by their protective measures will
impact many economies. Given India’s limited engagement with the world, this
may not seem like a big impact on our economy, as compared to other
export-dependent regimes. However, global trade wars combined with restrictions
on immigrants in Western economies can seriously impact technology and services businesses.


The interest rate cycle is another matter of concern. While
India has begun to increase its rates, it does seem to have done so
reluctantly, and the expectation that US would not increase rates too much too
soon underlies the monetary policy assumptions of many economies including
India. However, it has become quite complicated to venture into the business of
projecting how the developed economies, especially the United States would
perform in the next few years. While there is optimism about resilience and revival
of the economy and the possibility of a sustained 4% GDP, there is worry about
the trade and tariff policies unraveling to the detriment of the US. Many
Western nations as well as exporters like Japan and China, and many nations in
Asia and the Middle East are known to be grouping up to work together in the
light of what is seen widely as disruptive trade policies of the US. Greater
the unknowns, greater the risks to the investor.


Plan of action

How does an investor develop a strategic outlook for investing
in the Indian markets given these opportunities and risks?


First, every market offers the opportunity for beta returns
that come from investing in the broad market and the alpha returns that come
from outperformance. Investors should target a combination of the two. It is
quite common for investors to focus too much on alpha. Many would think that
investing in equity is not worthwhile if extraordinary returns are not earned.
It is important to see that stable long term story that India represents is
best captured by the index or a diversified portfolio of stocks that broadly
invests across sectors. Such a portfolio may not include the spectacular stars,
but it holds the merit of being a default choice to invest, an easy decision to
make during all times, a theme that is worth investing in for the long term,
and being diversified a low-risk choice for most investors. A diversified
portfolio that offers market returns should be the base, over which all else
can be built.


Second, the dilemma of
large cap versus mid cap is a tough one to resolve in the Indian markets. While
large cap stocks offer stability, the returns from the mid cap opportunity is
too high to ignore. In an emerging market like India, it is the business that
begins small, shows agility to grow rapidly, and become a blue chip in a short
span of time, that holds investor interest. There are several examples of
business that became big thus. However, the risks of failure are high in the
mid and small cap space as not all businesses succeed in what they set out to
do. An investment strategy that has a core and a satellite component, with
large cap as core and mid and small caps as satellite would help balancing the
portfolio. The relative weights can be modified to overweight large caps during
times of uncertainty and overweight mid and small caps during times of optimism.


Third, investors love the
idea of being value driven and like to see themselves as chasing good
investment opportunities at a reasonable price. However, a market like India
offers more opportunities for growth and momentum, than value. A beaten down
business may not represent a cheap buy, but an incorrigible loss. Most money in
Indian markets has been made from growth and momentum than from value. Momentum
is risky but holds the lure of a quick gain, making short term day traders out
of once innocent bystanders. It is astonishing how many try to make money
staring at blinking screens and staking too much money on what they see as
going up. Investors have to make their choices – to invest is to choose
carefully and focus on the return; to trade is to have an algorithm or action
plan and focus on the capital. The two are completely different tactics and
need different kinds of skills and attitudes.


There is money to be made in the long term on a diversified
portfolio across sectors, built carefully, monitored regularly, and pruned
sensibly. It just boils down to implementation, which most investors admit is
tougher than assumed.


View and Counterview : Market Returns: Is Direct Investing the Best Approach?

For
decades, investors put their money directly into the market. A traditional
investor swears by buying shares directly for their returns! Many have made
humongous returns from investing directly in shares that turned out to be
‘multi baggers’ while some lost all they had.


For the
new investors, the busy lot or even the risk averse, there are several options
of investing indirectly through mutual fund and other schemes. This option
offers a reasonable risk- return profile. Indirect investing has allowed a
large number of citizens to participate in corporate growth stories and make a
decent return over the long term.


This fifth
VIEW and COUNTERVIEW aims to tell the story from both perspectives. Both
writers, connected to their respective areas for years, give two perspectives
for you to consider. Deven R. Choksey, an entrepreneur in the business of
shares and securities and a leading voice for the markets in media, shares his
views from his more than thirty years of experience. Aniruddha Sarkar, a principal
fund manager with an AMC, shares his perspective on indirect investing.


VIEW: direct
investing is the best form of investing


Deven r. choksey  


Direct Investing is like
driving your own car versus Indirect Investing is equivalent to commuting in
public transport. Destination being the common goal while travelling, both
comfort and time are key differentiators in public versus private mode of commutation.
Similarly, Investing is done with an objective. It can be fulfilled via direct
investments or indirect mode of investments, like Mutual funds etc.
Investment products have buyers across multiple investor segments i.e.,
Institutional, Family offices, High Net worth Individuals- HNI’s, Ultra HNI’s,
Retail investors. Therefore, there remains advantage and disadvantage between
investing through either Direct or Indirect route, depending upon the category
or segment of investor
one belongs to.


Primary objective across
various customers segment is generation of Returns, managing Risk and having
adequate Liquidity. Both the routes, whether direct and indirect, have their
pros and cons under each of the above aspects. As we all know, returns and risk go hand in hand, in case
of direct investments substantial knowledge on subject matter to support
decision making & considerable research is required before venturing in. I
would not call this as a hindrance for direct investment route, as nowadays we
have professional advisors to assist us into the decision making process. Let
me bring out one interesting fact to your attention, direct individual
investments in equities commands nearly 16.5% of the market capitalisation
versus around 5.4% of the Indian market capitalisation that is held through
Equity funds. Clearly, individual preferences remain with direct investments
versus indirect route of investments. In US markets also there has been clear
shift from direct investments versus investments through mutual funds; there
has been decent rise in Independent Advisors therein who cater to individuals
for investments.


Let us see how the
following primary objectives are managed under respective routes of
investments:


a.   Returns b. Risk c. Liquidity d. Cost


a.
Returns: For the last 5 years, investments into Direct Equity, say for
eg., Current top 5 companies by market capitalisation have fetched 30.8% CAGR
vs. Top 5 Equity – Large Cap Mutual fund CAGR returns of 20.1%. One needs to
bear in mind while choosing the indirect route the demerits of change in fund
manager at Asset management companies, change in purpose of schemes, non
customisation of portfolios. Compulsions of common pool investments as required
to be followed in MF acts as deterrent whereas direct investment has its own
character in managing the returns objective.


b. Risk: Investors
risk profile tends to change with segment and category they fall into. The
preferences to attain final objective for aggressive investor will be different
from those who are believers to passive style of investments. In case of Direct
Investments the customisation stands as an advantage based on individual risk
profile needs versus Indirect Investments which is more standardised instead of
being customised.


c. Liquidity:
Benefits of direct investing is generation of adequate liquidity
within 2-3 working days. In case of indirect investing, one may witness
additional burden in form of exit loads to find speedy liquidation.


d. Costs:
In case of indirect investments management charges are levied under individual
schemes, which are not in case of direct investments.


While we
have seen the pros and cons under individual’s primary objectives of Returns,
Risk, Liquidity and Cost, let us also find out how secondary objectives are
dealt under direct and indirect investments.


1. Build
knowledge capital & Earn [Earn-Edge vs ROI]
: It
is always beneficial to know the company that one invests versus knowing your
fund manager. Which means it is better to be dependent on company management in
which funds are deployed rather than on fund manager who will be deploying your
money. Think about it, isn’t it assuring to have financial gains with knowledge
capital versus only financial gains. My take is, direct investing is all about
individual’s passion for growth in investments vs passive growth approach.


2.
Investment Advisor:
To put it simply, one good
book is knowledge, one good friend is equal to 100 books,
an ocean of
knowledge, and a friend as an investment advisor is a navigator in the
journey of wealth creation.
Professional investment advisors are a great
help and preferred support for active management of investment goals. One can
gain expertise and develop analytical skill with guidance of investment
advisors. According to me, there is no match to information sourced from tips,
social media or likes of Google or any other media sources that always limits
itself to information and does not compliment to the conviction extended by
investment advisor. Regular review and monitoring mechanism can help achieve
the objective with higher conviction on end results.


3. Easy
to maintain as any other Asset Class:
In case
of direct investments, at times it is found that maintaining of records is
tedious and disadvantageous. I believe, maintaining own investments is as easy
as maintaining investments in any other assets including MF, insurance etc. We
need to follow discipline to invest in sets. SIP in MF, Annual Premium in
Insurance are in-built investment systems. Direct Investments help us to invest
with conviction whereas indirect investment is often swayed with sentiments.


4.
Diversification not a suitable solution:
  An investment in indirect route generally
comes with diversification and involves  
investing    into    companies in excess of 30-50 at times in
individual schemes. Wealth creation is matter of investing in value and growth
companies and not supportive of diversification which tends to dilute the
successful ones with unsuccessful stories.


Direct investments have an
inbuilt character of allotting higher weight to growth and it is a science. All
it needs is an attention. Simply the ability to add dynamic weight produces
extraordinary results.


As long as trading instinct
is brought under control and CAGR is allowed to be employed, direct equity
produces better ROI. Classic example of wealth creation is depicted in table 1:


TABLE:
1

Performance of Direct
Investments for last 10 Years

Indian
Cos

Market
cap Rs Bn – 2008-2018

10
yr CAGR

MRF

14.4

316

36.2%

Infosys

99.2

2800

39.7%

TCS

840.4

7000

23.6%

International Cos

Market cap $ Bn – 2008-2018

10 yr CAGR

Google

165.3

779.5

16.8%

Facebook

66.48

562.48

42.7%

Amazon

30.6

824.7

39.0%

Apple

147.61

909.84

19.9%


5.
Customisation to objectives:
While
the broader goals and objectives can be met both under direct and indirect
route of investments, when it comes to meeting of objective within stipulated
parameters, investing through direct route, is always beneficial. In case of
indirect investment customisation beyond a point is not possible because of
productised approach. Let me explain with an example, say for an individual
investor has an expertise and understanding in manufacturing industry based on
his background. It will be inappropriate for him to invest in a product that
offers Pharma companies or any other business, since his knowledge would be
insufficient to assess the risk he is engaging himself into.


Finally, we have seen that investing route
direct or indirect is subject to type of individual you are and preferences to
primary objectives, as spelt earlier with respect to travel; we are well versed
with different level of comfort in 3 modes of travel i.e. Self Driven Vehicle,
Driving with a Driver and Travelling as a Passenger. Investing in direct
equities is no different from the satisfaction received through individual’s
own decision to investments versus decision taken by fund manager. One may also
bear in mind the modes of investment also depends on ticket size of investment.
In case of small investor, the preferred route of indirect investments will be
beneficial and vice-versa for large investors.


In case one has urge to
gain exponential returns with substantial risk taking ability, then direct
investment is a better avenue as compared to indirect investing.


counterVIEW: INDIRECT
INVESTMENTs WORK BETTER FOR MOST PEOPLE


Aniruddha Sarkar 


Though the culture of
equity investing has been prevalent in India for many decades now, yet equity
investing in India is still at its nascent stage. The penetration of equity
exposure among the households is merely 3-4% which includes all the organised modes
of investments (Mutual Funds, PMS, AIF) as well as direct equity exposure. This
figure is small by all global standards and has a great scope for increasing
penetration going ahead. In this regard a key question which comes to an
investor’s mind is which is the better suited path to take when it comes to
equity investing. Earlier investors had only two options to choose from; namely
direct equity and mutual funds. Then came Portfolio Management Services (PMS).
Now, since the last few years AIF has taken the industry by a storm. So, the
dilemma has increased even more for investors as to what is a better way ahead
for equity investing.


We believe, unless an
individual can devote a substantial amount of time in studying and
understanding the market and at the same time keeping track of events and news
flow that pertains to the equity market and his portfolio stocks, one should
always give his money to be managed by professional money managers like Mutual
Funds, PMS and AIF. Equity investing is one of the most dynamic activities and
cannot be done in a silo. Would like to break-up the benefits of having an
indirect exposure into equity markets through professionally managed route into
the following broad heads:


   Managing
Risk and Return; making more informed decisions:
Equity
returns is all about managing risk and return and getting the balance right
makes all the difference. Investors most often expose their direct equity
portfolios to very high risk and not take risk which is commensurate with the
returns expected. Risk has many facets of it and can be in various forms. Lack
of adequate information before investing in a company and not keeping track of
developments in the portfolio companies is a major information risk which
direct equity investing is faced with. Also, concentration risk is there when
too much capital is allocated to a few stocks and if something goes wrong in
any of the high concentrated stocks, then it impacts the whole portfolio
returns. Unlike in a Mutual Fund or in a PMS, the investment manager and his
team is always on top of all developments that keep happening in the markets
and their portfolio companies. This helps in making quicker and more informed
decisions regarding portfolio changes. Also, portfolio managers balance risk
and return aspect in a more scientific manner by not exposing the clients’
money to high risk, as there are several internal checks within the asset
management companies to monitor this aspect.


  Access
to companies for making decisions
: When
investors approach equity investment directly, their access to company
information gets limited to accessing annual reports and earnings transcript
and reading online public information. However, for professional money
managers, access to company management, plant visits, institutional access and
analysts meetings is something which helps them to make more informed decisions
when it comes to equity investing.

   AIF
platform offers diverse financial products
:
With the
AIF platform being launched by SEBI in 2012, the ability of the investment
managers to offer diverse products on the platform has taken a huge leap in
financial innovation. Within the three categories (CAT I, CAT II and CAT III)
of AIF, we now have diverse product offerings spread across listed equity,
unlisted equity, debt instruments, Real estate and Commodities. Having a
diverse basket of these products along with Mutual Funds and PMS, helps in
having the right Asset Allocation for the investors which is of prime
importance in the journey of making long term wealth. There are some financial
products wherein investors are also given access to investing into overseas
equities, which is otherwise very cumbersome if one has to go directly. 


  Freedom
to choose investment managers and switch between them
:

During different periods different investment managers outperform others. As an
investor, you have a choice to switch between the managers and at the same time
have a basket of investment portfolios which is managed by different investment
managers. This helps in generating a more balanced return for the portfolio at
a consolidated level.


   Less
hassle and professional approach at competitive fees
:

We have come a long way in Indian Equity markets from the days of Open cry in
the ring at BSE. Equity investments are now managed by professional fund
managers and SEBI which governs and controls all operations of the Mutual Fund,
PMS and AIF industry. This has helped in bringing the best global practices of
the financial service industry to Indian investors. Access to single statement
which shows all holdings of investors across investment managers, ease of tax
statements and lower fees due to increased competition in the financial
services industry is something which makes life a lot easier for investors
coming through the indirect route for equity investing.


Thus, we see that where there is paucity of time and where investors do
not have the bandwidth to spend a lot of time on understanding companies, on
reading annual reports and in understanding financial statements, it is best
not to enter the equity markets directly and better to invest via the mutual
funds, PMS or AIF route. What we have seen in the past is that when the bull
markets happen, more and more investors get lured into the equity markets and
start buying stocks directly based on hearsay and ‘tips’. These are recipes for
disaster and investors should be careful about not burning their hands in this
manner. At the same time, if there is any investor who thinks he has the
bandwidth and time to devote to the equity markets, he should gradually start
taking baby steps in the market through direct equity and invest only after
doing detailed analysis of the portfolio companies. This would also help in
building more discipline in the investing style and in building great amount of
knowledge about companies and markets. The benefits of professional investment
managers cannot be ruled out even for a client who likes to do direct investing
because of the access to a plethora of different financial products which are
otherwise not available when doing directly.


Interview: Rakesh Jhunjhunwala

What is stopping us is the peoples’ feeling of right of entitlement and India’s bureaucracy

In celebration of its 50th Volume – the BCAJ brings a series of interviews with people of eminence, the distinct ones we can look up to, as professionals. Those people who have reached to the top of their chosen sphere, people who have established a benchmark for others to emulate.


This third interview is with Mr. Rakesh Jhunjhunwala. He is well known in the fraternity of investors in the stock market and a Chartered Accountant by training.Mr. Jhunjhunwala, has a fairy tale story of entering the market with Rs. 5000 when the index was 150 and making it bigger than what most people can dream of. He has served on several Boards, produced a mainstream movie and is best known as India’s most successful investor.


In this interview, Mr. Jhunjhunwala talks to BCAJ Editor Raman Jokhakar and BCAJ Past Editor Gautam Nayak about his formative years, how the Chartered Accountancy training helped him, role of auditors in present times, and modestly sharing his investment mantras …..

(Raman Jokhakar): You have spent a long time in the market and made the most out of it. As you look back, do you find some roots of your dream like success in your childhood?

Sir, when you make a vegetable. Now you don’t know – there are various ingredients. Now it is some amount of ingredients, which makes that vegetable. If I have to say as to which particular ingredient was important – every ingredient was important, I can say every ingredient was important. I think, in my childhood love for stocks, background of a speculative nature by ancestry, polishing of the financial skills by Chartered Accountancy.

Then you know the fact that when I came here, India came on a growth path, Sensex was 100, today Sensex is 35000. I think all factors have contributed for me in India and finally it is luck, where all we are is because of the grace of God.

(Gautam Nayak): Can you tell us a bit about your childhood – what were your formative years like?

See, the most important part of my formative life was my curiosity and my father’s encouragement of curiosity. I was a very curious child. My father always inculcated that curiosity and I think that helped me build a lot of knowledge. Also my father let me think independently, always encouraged me to think independently and he always told me that – you do whatever you want to do in life, but be responsible. And you know I had sickness when I was young. I had meningitis. So I think, these are the main important factors. Otherwise, I had a very normal childhood.

(R): You were always in Mumbai?

Yes. I was born in Hyderabad but I came here when I was 2 years old and last 56 years I am here.

(G): Your father was an Income Tax Officer in the Income Tax Department.

Also in my formative years, I met (because my father was in the Income Tax Dept.) a lot of important people. I developed an attitude where I did not have any fear of authority. I was not in awe -‘This fellow is this, this fellow is this’.

(G): About Chartered Accountancy – why did you choose Chartered Accountancy course – a trait or attribute you that you learnt then – that made a difference in what you do now?

See, every Income Tax Officer wanted his son to be in practice and my brother was already a Chartered Accountant. My father always wanted me to do what I enjoyed. But he said that you must have a kind of financial security and chartered accountancy is a good education. My father’s guidance and then my interest in financial matters was why I did my chartered accountancy.

(R): Any kind of attributes, something that you learnt then, do you feel helped you in this kind of…….

Lots of things. Lots of things. I think, even if you ask me today, chartered accountancy is the best education, far better than an MBA from America. If you want to work and remain in India, chartered accountancy gives you an expertise of accountancy, finance, company law. It gives you a basic thought process. It matures you because when you do the articleship, you have to behave. So I think, it is very wonderful education and it has contributed a lot to my success.

(R): What attracted you to the stock markets? You didn’t have that background from your father’s side and Chartered Accountancy does not mean stock market. What prompted you to enter the investment business?

You know my father used to invest in the market and he and his friends would discuss the market in the evening. I would be 10-12-13 years old, and I would notice the fluctuations in prices. As usual, I would quiz my father and my father would say “See, look, there is an information about Gwalior Rayon.” Next day, the price would move up. So this price information, then relating it to the news and then trying to understand it, really fascinated me. That’s what I thought and, you know, we are basically Aggarwals from Rajasthan, we are basically business community and we are very good at speculation. My grandfather and my uncle were speculators. So, you know, I have that in my blood.

(G): Who were your role models or mentors, and how did they influence you and your investing style?

See, my real mentor was Radheshyam Damani. He is not a mentor, he is a friend. Mr. Radheshyam Damani, who owns Dmart. He is my best friend. He is a person from whom I learnt a lot by observation. Mentor is one who sort of guides you. He was not a guide to me, but I learnt a lot of things from him. My role model in life really are the House of Tatas. We must do economic activity and use that economic activity for social work. In that way, my role models are Tatas. As far as skills of investing in trading is concerned, we should read, observe but try and make independent decisions. We should not subjugate our mind to an individual. You should not think, this individual is too great, so whatever he has said is the gospel truth. But these are markets. They are dynamic. There is no gospel truth.

(R): Difference you see from those days – before SEBI – and now after SEBI – as an investor?

I think, SEBI has contributed greatly for Indian investors and traders. We have gone from the Wild West to the absolute well regulated markets…….See, there have been excesses by SEBI, but that is the function of evolution. I am thankful to SEBI for the way they have conducted the markets. Some excesses have been done somewhere.

(R): Role of auditors: we saw some resignations – some last minute resignations. As an investor, were you satisfied with the action of the auditors, reaction of markets and regulatory response? 

I think Society is underestimating the importance of auditors. I think, auditors are also taking their roles lightly.

You see, faith is the basis of capitalism. Basically, that faith in terms of accounting is certified by auditors. So that’s why I say that society is underestimating the role of auditors. If you got auditors like Arthur Anderson for Enron in all companies, then what would happen? Capitalism itself would get shaken. The auditors don’t understand the importance of what they are certifying. So, personally I feel, first, the monopoly of the Big 4 is not good, and I think the role of auditors has to change. They have to be more responsible and it will evolve with time.

(R): Why you say more responsible, in what sense? Meaning would you like auditors to report something else beyond what they are doing presently?

These are substantive matters. Auditors want to look at procedural matters and I don’t know what are the reasons? I feel, I am also guilty that I am not contributing to the setting of accounting standards, which I can as a member of the Institute. The issue is that a lot of the accounting standards are also not practicable. And, second thing is, I feel, that after all, accounting also carries a lot of opinions. This fact that under the Companies Act, that a qualification by an auditor means a black mark on the Board is not right, because I can differ from the auditor and I as a member of the Board of Directors have the right to counter the auditor’s observations without any black marks right? The auditors themselves differ on certain things. I think, the role of auditors has to be better understood and discharged with greater responsibility, greater understanding and greater practicality.

(R): And presently do you feel that auditors have enough incentive e.g. the board appoints the auditor effectively. Effectively, you have the general meeting, which is composed of promoters largely. They are appointing the auditors. What is the incentive to auditors to speak up and to speak up against those same people? 

That is why you are professionals, you know. That is why you are supposed to uphold your professional standards. Do you want to compromise your professional standards? So, that will depend upon the general morality of our profession. It is you who set the standards of the profession. If we chartered accountants, all together, start giving independent opinions, regardless of whether we are appointed or not, then what will the directors do? What will the promoters do? So, it is for us to improve the standards and have more transparency, and not clamour only for more work.

(G): Do you see the role of auditors should undergo a change in the years to come – considering the scams from Satyam to Carillion in UK? Is assurance expected these days to be more of insurance?

They should undergo a change. But see, it cannot, and will not happen in a jiffy. It will not happen by me or you desiring it. It will happen with evolution.

(R): In other words, what would be the next stage of that evolution that you as an investor and a director look forward to?

That is difficult for me to point out specifically– right? I mean, say, suppose somebody is resigning from Manpasand Beverages. I want, to tell that auditor: what has changed from the year before? Right? I know for one, all the members, my fellow members don’t like it. I am very happy that the power to take disciplinary action has been taken away from the Council. I think, that is why. Partly because SEBI is getting more vigilant – see what has happened to Pricewaterhouse case in Satyam- right? Therefore, this will evolve with time.

(G): Coming to the stock markets – What are the fundamental stumbling blocks that the Indian Economy generally and Stock market specifically face, which need to be changed immediately for a sustainable long-term growth?

Stock Market and Economy, what are you asking, Stock Market or Economy?

Both – mainly the economy, because once the economy grows, the stock market will automatically grow.

My personal observation, that in India, we Indians are more disciplined. Why? Because we think, we can grow far better and we can have better civic and Government than what we have. But see, in the backdrop of the kind of diversity we have, the kind of economic inequality we have, our growth, we are evolving. And this change, we are an elephant, you cannot make it jump faster beyond a point. But it is evolving. Everything is bottom up. So, I think, with evolution, growth will go up. I think, what is stopping us most, is the peoples’ feeling of right of entitlement and India’s bureaucracy. I suddenly feel entitled to everything, I have to do nothing. And bureaucracy feels they can obstruct everything. So that is what is really stopping us – but nothing can stop India.

(R): Today there is a lot of study, knowledge and analysis involved in investing. Yet there is an element of ‘future’ and therefore ‘uncertainty’ that one feels being in the market. If you have to rank skill, courage, risk taking and good luck or God’s grace – what weightage would you give each or how would you rank them?

You may have ninety nine things right in a way. If you don’t have salt it will make food tasteless. So, you need everything in proper measure.

(G): From an economic perspective – what are the areas you can see in future will be the real growth areas, specific sectors you feel would outperform in the next decade?

Everything. India is going to grow! What is it that is not going to grow?

(G): Any specific sectors, any sector you feel has greater potential?

I think, financial sector is very underdeveloped in India. There are lot of sectors. Pharma. Everything in India – is like a buffet! There are so many dishes – eat what you want, do not overeat. (Laughter)

(R): Your advice to Chartered Accountants – especially the younger lot – what should they do more, do less and stop doing completely?

Hard work.

(R): Current generation

And we have to understand that growth and success is a process. Nothing comes in a hurry. And see, you have to be practical in this world but we have got to keep our integrity and keep professional ethics above results.

(G): Corporates are a small portion of the economy – government, agriculture and even unorganised sector is quite significant. Do you see this ratio change? These are some of the factors that are holding back the society.

It is a normal process of Society that as you develop more and more, more and more sectors will get organised, consolidated. So, it is a process, and I think, government’s role in business will diminish. Diminish not by selling government stakes, but by allowing private sector to grow. So, they take out market share.

(R): If you were to interview Warren Buffet – what questions would you like to ask him?

What is the secret of his health? He eats most unhealthy in the world. He is so active at 87. I will ask him the secret of his health. (Laughter)

(R): Anything else you would want to ask if you had to ask a second question?

No. He is an open book.

(G): A long-term investor looks at several factors before investing in a company. One factor is the quality of the management and promoters. Today, when so many promoters who were once upon a time considered as top quality, are now discovered to be frauds, how do you make a decision about the quality of the management and promoters before taking stakes in companies?

How do you gauge if your wife will be good? So, it is intuitive. One test I keep is, you try and find out if the management is playing in the market.

And then if you meet them, you understand the attitude, purpose.

(G): Do you feel that the changes in management being brought about on account of the Insolvency Code would make promoters more accountable, cautious and transparent, and therefore is in the interest of investors or it has its flip side?

Absolutely. It will change the credit culture in India and it will raise the rate of return on capital.

(G): Today, I think, promoters are worried about being replaced.

Worried means, they are being replaced. There is no chance. So, the question is, the insolvency code – firstly is evolving, it will change credit culture and credit behaviour in India. If you raise return on capital, you will use assets more efficiently and they will not inflate capital cost. I think, it is a game changer.

(R): How do you protect yourself against the significant unpredictable legal and regulatory risk faced by companies in India, e.g., Supreme Court ban on mining in Goa, cancellation of coal mine allocations and telecom licences, ban on copper smelting in Tamil Nadu, change in gold import norms, etc. – the sudden slaps.

One is – we don’t know. We can try to protect ourselves from the known, but we can’t protect ourselves from the unknown. We try to not invest in controversial areas – sectors and companies.

(R): Many CAs miss the woods for the trees. How does one master the art and the craft of investing? This is the secret mantra we want from you (Laughter)

Well (laughter) I am trying for the last 38 years since 1980. I still have not mastered it, because the process to learn is a journey, not a destination. One thing that is most important – have an open mind, experience, read, analyse, understand, have an independent opinion. These are some of the factors.

(G): The change today is not only constant – but is faster than ever before. How do you keep up with all this and remain informed to keep up with the pace of change?


I am not so technologically savvy, but there are a lot of things which don’t change. Change can bring – the structural change can bring opportunity. It does bring opportunity. By reading.

(G): What do you read regularly?

I read The Economist and India Today. India Today tells me what is happening in India. The Economist makes me form an opinion about what is happening in the world.

(G): And how long have you been doing this now?


For the last 15-20 years or even more. Now actually, my reading quotient has come down.

(R): As someone linked to the markets in the superfast digital age – How do you prevent burnout and keep good health and well-being?

Well-being of the mind comes from 3 things: Happiness, Contentment and Tolerance. And acceptance of defeat with a smile. See, life is not about regrets, it is about learning. Once you accept that, you are always mentally healthy.

(R): Ideas of Success and Achievement drive people. What does Success mean to you? Has that idea changed over the years for you?

See I have always done what I enjoyed. I enjoy what I do. I came to the markets in 1985. By the 1990s, I had enough to provide me for a life time. No wealth is enough, no success is enough. But I have never been motivated by the quantum of wealth. I do what I enjoy, enjoy what I do. I have far less than what people think but far more than what I need. So for me, the job what I am doing is far more enjoyable, the hunt is more enjoyable than the game. Success is by-product of what I am doing and I will be lying to say that I don’t like to be wealthy and successful. But I am in no rat race.

God has given me wealth at least far beyond my own imagination. Sometimes, I wonder what will I do with that? What do I need it for?

@15.August.2018

Thank you for your wonderful feedback on the
July 2018 Special Issue. Each issue in this 50th year series is
curated with Golden Content. We are delighted to present another interview, a
view and counterview and four articles on wealth creation through investing. I
hope you enjoy reading them.


Independence Day

We celebrate 72nd Independence
Day on 15th August this month. I like to ponder on India and its
freedom during this month since Freedom and Liberty are priceless and are at
the root of all human values. This editorial is a sequel to the Editorial of
August 2017. Here are some thoughts:


Legend says that one day the truth and
the lie crossed.

Hello, said the lie. Hello, told the
truth.


Nice day, continued the lie. So the truth
went to see if it was true. It was. Nice day, then answered the truth.


The lake is even prettier, said the lie
with a nice smile. So the truth looked at the lake and saw that lie was telling
the truth and nodded.


The lie ran into the water and
launched…water is even more beautiful and warm. Let’s go swim! The truth
touched the water with her fingers and she was really beautiful and warm. Then
the truth trusted the lie. Both took their clothes and swam quietly.


A little later, the lie came out, she
dressed up with the clothes of truth and left.


The truth, unable to wear the clothes of
the lie started walking without clothes and everyone went away by seeing her
naked. Saddened, abandoned, the truth took refuge in the bottom of a well.
Since then people prefer to accept the lie disguised as truth than the naked
truth.


(The
truth out of the well by Jean-Léon Gérôme, 1896)


This story is about lie, yet the truth about
the lie has not changed in aeons. Today, in spite of so much information, the
challenge of spotting a lie dressed as truth remains.


We live amidst changing differentiations
which are perceived by each based on his belief, background, and situation.
This concoction results in the ‘portrayal’ of the actual. In other words: Perception
is reality, but not the truth.
Consider these examples:


1.  Recently I came across a photo of a British
prince. From the side it seemed like he was showing a finger (the one you do
not expect a prince to show) to the crowd. However, another picture from the
front showed that he had last three fingers up. (Q: Can one believe what is
shown from one angle?)


2.  Driving through a forest, you brake suddenly
seeing a deer crossing the road. The driver thinks: what the hell, a deer is
obstructing my way. Yet, the deer is just walking in his home where the road is
intruding. (Q: An individual standpoint restricts the whole perception?)


3.  Terror is portrayed consistently by media.
Factually, nearly 4-5 times more people get killed by accidents due to potholes
and far more in road accidents. That doesn’t get the same coverage. Fear and
insecurity of dying at the hands of a gun-toting maniac is much more than that
of death due to a careless driver. Statistical fact[1]
is that road accident kills many more than a terrorists bullets. (Q: Why is one
type of fear of death portrayed excessively over the other?)


4.  Consider the monsoon sale displays. The
biggest words are: SALE and DISCOUNT PERCENTAGE. The smallest words are: UP TO.
Legitimate and clever. (Q: Isn’t ‘up to’ as important as the other two words?)


5.  Word play: Two potentially different words in
the way people use and understand them are mixed. Say Retail therapy. They give
a subliminal message of something that alleviates pain. (Q: Don’t we have too
many of them?)


6.  A media house reports a story. The story has a
subtle shade of agenda or self-interest. The story is perhaps about a big
client with a big advertisement contract. A lay reader takes it as news. (Q:
How does one know what is true and how much of it can be relied upon?)


7.  A website wants to give you ‘free content’.
Nevertheless, it wants you to register with some personal information. (Q: If
it was free, why ask for registration?)


The point is –
gigabytes and decibels – scramble for our attention and attempt to shape our
perception persistently. We need new heuristics to deal with this situation and
search for truth at a mundane level.


As Chartered Accountants we are somewhat
trained to look out for substance. Since seeing is often not believing, we have
to look harder for truth. Truth has many hues. The three notable ones are:
Reason, Facts and Testing words with actions.


Gurudev Tagore wrote about this in his poem
laying out his dream of India:


Where the
mind is without fear and the head is held high, where knowledge is free.

Where the
world has not been broken up into fragments by narrow domestic walls.

Where words
come out from the depth of truth, where tireless striving stretches its arms
toward perfection.

Where the
clear stream of reason has not lost its way into the dreary desert sand of dead
habit.

Where the
mind is led forward by Thee into ever widening thought and action.

In to that
heaven of freedom, my father, LET MY COUNTRY AWAKE!”

Every day, rhetoric seeks to suppress the
stream of reason. Our elected representatives use rhetorical verbiage, often
entertaining too, but more often deflecting from the core point. Take an
example of some failure
or questioning on a given matter. You can pick their likely answer/s from the
following options:


1.  Denial – I didn’t do it, this did not happen,
there is no problem

2.  It’s a conspiracy (sometimes external too)


3.  Politically motivated (someone is trying to
throw me out / off)


4.  Victim mode: I am targeted because – I am of
xyz caste/region/background/ religion


5.  Excuse: Someone else before me was even worst


6.  Cherry pick data … and so on


Try to remember when you last heard the
following words: I own it up, I am sorry, I take responsibility. When was the
last time that someone stayed on the core point without deflecting? 


Facts are antidote of falsehood. Someone has
said: In God, we trust, for everything else bring data to the table. Facts
are available more than before, yet they require one to uncover them, for even
they come packed in deceptive agenda. 


Consider two recent words: post-truth[2]
(Word of the year 2016 per Oxford Dictionary) and alternative facts (from Trump
Election). These mixed up incoherent words supply a narrative which is
untenable. Many present, protect and promote such verbosity with fierce
confidence (and sometimes with added theatrics too). When you test words, you
can observe that actions don’t match up to them.


The point is: we have to be watchful. Our
eyes need more focus. Ears have to listen to what is not said. The mind has to
cull out deception from perception. Few look for the naked truth, but most
prefer the lie dressed as truth. Yet we can try and spot it. And we may not
succeed. Perhaps the search for truth is as eternal as time. Like the Sura?gama
Sutra
says: Things are not what they appear to be: nor are they
otherwise.


Raman Jokhakar

Editor


[1] Globally,
about 3200 people die every day in fatal road accidents, plus 20-50 million are
injured or disabled each year.


[2] Relating to or denoting circumstances in
which objective facts are less 
influential in shaping public opinion than appeals to emotion and
personal belief

Detachment

‘ Detachment is not that you should own anything. But nothing should own you’.
                            Alibin abi Talib

Have we ever reflected and realised that consciously or unconsciously we live a life of attachment. Attachment to our parents, spouse, siblings, children and friends. We are also attached to our possessions and neighbourhood, city and country. Above all, we are attached to our work and our thoughts. Our attachment to our thoughts makes us what we are – thoughts control our actions at home, at work and our behaviour in our social interactions. In short we live a life possessed by possessions as we consider we possess all those to whom we are attached. Let us examine what attachment does to us. Attachment creates feeling of helplessness. It converts us into a mini slave. It makes us restless and we rarely realise that sub-consciously it generates ‘fear’ – fear of loss of person, possession or work. When we lose a person to whom we are attached – a mini death occurs in us. Loss of possession or work makes us unhappy. There are occasions when death of person generates grief not only to the family but also nations – three examples come to mind – death of Mahatma Gandhi, President John F. Kennedy and Princess Diana – these were mourned by many in the world.

It has been rightly said that attachment is a fetter and is the intrinsic cause of unhappiness. The issue is : how to get over the fear of loss, eliminate grief and bring happiness in our life. In other words, what is the antidote to attachment. The antidote in the author’s view are ‘acceptance and detachment’. Acceptance establishes the role of destiny in our life and detachment ushers in calm. Detachment converts us from doers to observers – observers who have no reactions. In short, develop detachment from people, places and property without being callous. Develop the ability to let go and accept. Further all religions in one form or the other advise us : ‘do your best and accept the result as a gift from God’. I would conclude by quoting Charlie Chaplin :

-Nothing is permanent in this wicked world – not even our troubles’.

Hence, to have a happy life let us live our life by adopting ‘attachment with detachment’.

69th Annual General Meeting on 6th July 2018

The 69th Annual General
Meeting of the Society was held at the Garware Club, Churchgate, Mumbai on
Friday, 6th July 2018.


CA. Narayan Pasari, President of the
Society, took the Chair. Since the required quorum was present, he called the
meeting in order. All businesses as per the agenda given in the notice were
conducted including adoption of accounts and appointment of auditors.


CA. Manish Sampat, Hon. Jt.
Secretary announced the results of the election of the President, Vice
President, two Secretaries, Treasurer and eight members of the Managing
Committee for the year 2018-19. The names of members as elected unopposed for
the year 2018-19 were announced. He also announced the names of the co-opted
members for the year 2018-19.


Office
Bearers

President                            CA. Sunil Gabhawalla

Vice President                    CA. Manish Sampat

Joint
Secretary                   CA. Abhay
Mehta

Joint
Secretary                   CA. Mihir
Sheth

Treasurer                            CA.
Suhas Paranjpe           


Committee Members

CA. Anil Doshi                     CA. Kinjal Shah

CA. Bhavesh
Gandhi           CA. Mayur Desai. 

CA. Chirag
Doshi                 CA. Rutvik Sanghvi

CA. Divya Jokhakar             CA. Samir Kapadia


Co-opted
Members

CA. Anand
Bathiya              CA. Pooja
Punjabi 

CA. Ganesh Rajgopalan      CA. Shreyas Shah

CA. Mandar Telang              CA. Zubin Billimoria


Ex-officio

Immediate Past
President       CA. Narayan Pasari

Member (Editor and               CA. Raman Jokhakar
Publisher-BCAJ)                 


Later, the “Jal Erach Dastur
Awards” for best feature and best article appearing in BCAS Journals during
2017-18 were announced. The winners were: CA. Sunil Gabhawalla, CA. Rishabh
Singhvi and CA. Parth Shah for the best feature and CA. Akeel Master and CA.
Rupali Adhikari Sawant for the best article.


The Special Issue of July 2018
Journal along with BCAS Publications: “Thought Mailers-A Compendium-Volume 1
& 2” and “Presumptive Taxation” were released at the hands of CA. Nilesh
Shah, Managing Director, Kotak Mahindra Asset Management Company Ltd. at the 70th
Foundation day of the Society celebrated after the Annual General Meeting of
the Society.


At the end, guests including Past
Presidents of BCAS were invited on the dais to share their views and
experiences about the Society.


Outgoing President’s
Speech

NAMASKAR DOSTO !


My office bearers and friends on
dais Sunil, Manish, Suhas. Abhay, Incoming OB my dear friend Mihir, Respected
Past Presidents of the Society, Dear Managing Committee members, Vibrant Core
Group members, Members of my family and my Dear Members of BCAS.


Good Evening to All of you !


In my capacity as the President of
this lively Organisation, I speak to you for the last time.


I start by thanking the “Almighty”
for being with me always!!


Football is in the air…The FIFA
World Cup is currently the epidemic that has gripped the world. It is estimated
that around 4.5 billion people; some in the distant corners of the world are
watching football with a contagious passion.


And the influence of football, referred
by many as ‘the world’s greatest and beautiful game’ has also ‘infected’
my talk this
evening.


It has been wisely said, “In life,
as in football, you won’t go far unless you know where the goalposts are”.

Goals become the focus and the motivation that truly lead you on.


And so, at the kick-off last year
in July 2017, when I took over as President, I defined four goals to give
direction to my roadmap, for the betterment of BCAS.


TRANSFORMATION, YUVA SHAKTI,
DIGITISATION AND NETWORKING


I would like to take this
opportunity to make a few ‘passes’ about the progress in the game played so
far!


TRANSFORMATION is a goal
that all professionals need to keep scoring. With the rapid pace of change
impacting all facets and geographies of the world, it is essential that we stay
abreast of the latest trends and technologies to stay competitive.


At BCAS we tackled the challenge on
two fronts, first by widening the scope of subjects and topics and secondly, by
using various events, publications and media to disseminate this knowledge.
Here are a few examples:


1   Experts enumerated and
deliberated on contemporary topics at regular intervals throughout the year.


2    BCAJ introduced three new
features – Decoding GST, Revisiting FEMA and Statistically Speaking.


3    In October 2017, we
provided free access on social media to short videos on 28 topics related to
GST which got over 39,000+ views. This week we launched the 2nd
series of 9 videos on GST. This idea is the brainchild of our incoming
President CA. Sunil.


4    “BCAS at your Door
Step” is a new initiative which will be launched soon to offer tailor-made
interactive dialogues to help corporates grow and excel through greater
expertise. Incoming Vice President CA. Manish will be piloting this project.


Despite being only 19 years of age,
Senegal player Moussa Wague who never netted an international goal before,
became the hero of the hour when he netted his country’s second goal against
Japan few days ago.


Another teenage sensation, Kylian
Mbappe sealed the deal for France as they beat Argentina to sail through to the
quarter-finals of the World Cup. He is the 5th teenager to score
more than once in the world cup game. 


This is the power of YUVA SHAKTI. The young
ones are the GenNext Leaders and if given a chance, they can create history by
outperforming their past achievements.


At BCAS we inducted youth in
leadership roles to generate a synergy of talent and experience. With 22% of
our core group members below 35 years, Yuva Shakti got abundant opportunities
at many of our events and a platform to express themselves.


Some of the Yuva Shakti initiatives
both new and old continue…


1   Society conducted “Success
in CA Exams” programmes on two occasions with different faculties to help young
students to prepare well in all aspects.


  2 A felicitation program was
organised for newly qualified CAs – 110 new entrants participated in the
interactive and motivational session which was taken up by our own Yuva Shakti
member.


3   5th Youth
Residential Refresher Course was held with the theme – “Are you future ready?
Participants got an opportunity to brush up their knowledge and personality.


4   Tarang 2K18 – the Jal
Erach Dastur 11th edition CA Students Annual Day offered youth a
platform to showcase their talents and creativity…it was a great success with
over 550+ participants.


The digital thrust was given added
momentum so that more and more of our members can easily access the vast
knowledge base and the pool of resources BCAS possesses. With greater DIGITISATION,
knowledge can now be shared with greater convenience across geographical and
time boundaries. In this direction, here are some of the key executions during
the year…


1   BCAS E-Learning Platform –
“Course Play” was launched. This offers features that enhance
learning through greater ease without physical presence. Live learning is now
possible at your convenient time and place! This initiative was mooted during
the term of my predecessor and friend CA. Chetan Shah.


2   The power of social media
was explored with greater enthusiasm. In the course of the year we crossed
22000+ followers on our handle @bcasglobal across various social media
platforms. Successful campaigns were conducted on the Budget 2018 and now there
are ongoing campaigns on initiatives, nostalgia and BCAJ.


3   YouTube is another avenue
through which BCAS’ popularity is spreading. There are over 6000+ subscribers
who regularly tune in to our videos to catch up on the many initiatives of the
Society.


4   This year for the first
time we conducted a live Facebook event on “Understanding the Finance Act
2018”, which was a big hit.


5   Partnering with the
Government to help spread awareness about GST, we made the BCAJ July 2017 issue
– a special GST issue available to ALL on BCA E-Journal platform.


This last goal called NETWORKING
that we had focussed on, revolves around fostering and reinforcing
relationships. Our efforts are directed towards strengthening ties with ALL
with whom BCAS works. Some key initiatives in the Networking sphere, include:


1    Organizing GST training
programs with NACIN for our own members, retail traders and public at large.


2    To give an impetus to the Government’s Start
Up India campaign and network with industry, the Society organised a two-day
Start Up Conference at Bengaluru, jointly with the Karnataka State Chartered
Accountants’ Association.


3    Joint Programs were
conducted with Indore Management Association, Direct Tax Practitioners
Association-Kolkata, Jaipur Chartered Accountants Group and Chartered
Accountants Association, Ahmedabad. BCAS was also endorsed as the Knowledge
Partner for GST Summit at the Fin-bridge Expo in Mumbai.
4    Several representations were made to the
Finance Ministry / CBDT jointly with other professional bodies.


Another nostalgic programme
highlight during the year was the 53rd Lecture Meeting of the
Society on the Direct Tax Provisions of the Finance Bill 2018. The lucid
insights provided by Senior Advocate Mr. Soli E. Dastur
were eagerly
viewed by over 12,000 including many in other countries as it was streamed
live. As desired by Mr. Dastur, this was his 30th and last lecture
on Finance Bill on the BCAS Platform.


We would like to acknowledge Mr.
Dastur’s efforts and affection for BCAS for all these years and sincerely thank
him. We will miss him in future.


I would also like to draw your
attention to the BCAS Foundation which was set up sixteen years ago. It has
been the Society’s social outreach initiative that has been silently giving
back to the less privileged.


During the past year…


1    Donations were made for
the “Needy Child Project” and for purchase of diagnostic equipment at
the Tata Memorial Hospital.


2    A Blood Donation Drive
and Health Check-up was organised for the second year in a row.


3    Significant contributions
were made for the various needs at Dharampur, which included Tree Plantations,
Eye Checking Camps, Cataract Operations and other welfare activities for the
tribals.


4  We jointly organised the 2nd
Narayan Varma Memorial Lecture on the “The Role of Giving in Responsible
Citizenry” with DBM and PCGT.


The secret of
change is to focus all your energy, not on fighting the old but on building the
new. I realise that though we’ve come a long way, we still have a long way to
go.


Ideas are no
one’s monopoly; Think New & Think Ahead.., was our mantra for the
year. The power to think is colossal and perpetual, so is the journey for any
organisation.


What’s trending in the morning
possibly is an old story by evening. It is essential to have a futuristic
outlook and think ahead of time.


Seniors currently in most
organisations have started to act as mentors to the New Yuva and empowering
them to take up leadership roles of the organisation that’s the real wisdom
which will ensure vibrancy and continuity of the respective organisations!


With this, I now pass the mantle to
CA. Sunil Gabhawalla, the new President of BCAS and his team of very able
office bearers. I promise to be easily accessible to encourage and render
whatever small assistance I can, to the new team as they continue to keep the
BCAS flag flying high.


And now it’s time to thank and
congratulate the teams and winners that have toiled tirelessly to make the past
year so enriching and eventful.


For the “Golden Ball” award
which goes to the most outstanding player, we have an entire team that truly
deserves it. Ladies and gentlemen, please put your hands together for the team
that comprises the PAST PRESIDENTS, CHAIRMEN, CO-CHAIRMAN and ALL the MEMBERS
of the NINE SUB COMMITTEES that have truly made BCAS an outstanding and
exciting hub of activity and knowledge.


And for the much sought-after award
the “Golden Boot” which goes to the
highest scorer, here again it goes to a highly distinguished team, comprising
of all my OFFICE BEARERS Sunil, Manish, Suhas and Abhay who worked diligently
with me to steer BCAS on the way to success throughout the year; along with the
CONVENORS, COORDINATORS, CONTRIBUTORS, SPEAKERS and OTHERS who have scored high
in raising the standards for which BCAS is known for. Please join me in
congratulating them all with a round of applause!


Then there’s the “Golden Glove”
award
, which goes to our very own BCAS Office Team consisting of the Head
of Departments of the teams heading the Events, Accounts, Knowledge,
Communications, IT and Marketing Teams and their respective members along with
the Office Boys who through their hard work and team spirit have always supported
and helped us all to be good ‘goalkeepers’. Let us applaud them in appreciation
for all their dedicated efforts. They are called the Back Office, but they are
the real Back Bone of the organisation!


Before I talk about the “Golden
Trophy”
let me thank my family.


First, my father Late CA. R. G.
Pasari who though not with me, always guided me with his “Invisible Hand”. Then
my mother who throughout the year asked me how my tenure with BCAS is faring.
Pranam Mummy ! Then – I thank my better half Seema & my sons Chetan and
Meet and the new addition in our family Shailja who were always supportive of
all my activities during the year. Eye for detail is in our genes, I borrowed
it from my father
and my son Chetan from me. He helped me with his inputs on many of my contents.
Thanks Chetan !


In this era of digitisation, I
should profoundly thank my
iPhone’ & ‘My Surface Pro’ the
2 very active partners during my term.


And finally, there’s the glittering
6.1 kg trophy of 24 carat gold
, standing over 14 inches high which is being
awarded to ALL of YOU…and all the over 9,000 BCAS FAMILY MEMBERS
who through your unwavering support and participation have made BCAS such a
recognised and well-respected SOCIETY.


Thank You and Jai Hind!


Incoming
President’s Speech


Thank you Narayan for a wonderful
BCAS year 2017-18 with lots of learnings and fun. Your DP says it all – “Life
is BCAS now”. Organisational policies mandate a periodic change of guard but
emotions know no such delineations. Looking at your emotional involvement with
the institution, I am confident that your DP message will continue to remain
the same.


Respected Past Presidents, Office
Bearers Manish, Suhas, Abhay and Mihir, my fellow colleagues in the Managing
Committee, Seniors in the Profession and my dear friends.


It is indeed an honour to lead this
august institution as it relentlessly marches towards seven decades of
harnessing talent and providing quality service. My personal journey to this
echelon ever since I entered the Core Group in the year 2003, to say the least,
has been very memorable. Starting with the role as contributor to the Computer
Interface Feature and thereafter moving into varying roles and responsibilities
in the Indirect Tax Committee, followed by being a member of the Managing
Committee and ultimately reaching the current position, my persona evolved over
a period of time and I am grateful to BCAS and all its volunteers who
facilitated this journey. While accepting this privilege, I seek the divine
blessings of my late parents. I also acknowledge the role of my uncle who
doubled up as an excellent principal and to whom I owe my practical training.
We all fondly call him CMG. Without the special support and contribution of my
better half Jayshri and my wonderful kids Prakruti and Hriday, I could not have
commenced this journey at all. As I enter this crucial phase of my BCAS Career,
I am confident that all the friends of BCAS will continue to support me in the
initiatives that I plan to undertake.


Formed only six days after the ICAI
was established, the Society has grown to be the largest non-government
association of accounting professionals in India. This itself suggests that the
Society has done something fabulous. However, it is not the ethos of the
Society to rest on its past laurels but to look forward. Therefore, respecting
this ethos of the Society, while acknowledging the whole hearted efforts put in
the past, I would like to focus on the initiatives that I wish to undertake in
the near future and more specifically during my term.


Inspired by some success stories of
the common man in the last decade and by the clarion call of the Hon’ble Prime
Minister to develop Big 8 Indian Accounting Firms, I choose to adopt the theme
of “Common Man” for this year. My talk today is in the narrative of what a
common man (general practising-chartered accountant, in the context of BCAS)
expects from such an august institution and my endeavour would be to prioritise
BCAS activities to align with such member expectations.


The general practising chartered
accountant has done reasonably well over the past seven decades. The intensity
of the CA Curriculum provided a strong intellectual foundation with an ability
to put in sincere hard work. Equipped with the armoury of knowledge,
understanding of the processes and the relationships built by him with various
stakeholders, the common man achieved reasonable economic and social success.
However, times are changing. Knowledge is available for free at the drop of the
hat on various social media. It is not uncommon for clients to know about a
relevant judgement before the CA knows about it. One finds technology and robots
much more capable of handling routine processes like TDS, income tax returns
and GST Returns than human beings. In an increasingly transactional world,
relationships may no longer remain a key driver of success. In such changing
times, the expectation of the common man from the Society is:


Can the Society help me Re-engineer
my Profession?


The Society regularly holds events
like lecture meetings, workshops, seminars, short and long duration courses,
residential courses and the like. These events epitomise an ocean of knowledge
and help the common man to keep pace with the latest developments in the
profession. The Technical Committees at BCAS have been doing a wonderful job
and will continue to do so.


With discussions around the new
Direct Tax Code gathering momentum and many changes in the direct tax law
towards a more stricter compliance regime, the ‘bread and butter’ practice of
the common man needs to evolve. The Taxation Committee led by Ameet Patel will
focus on events around this domain.


GST is the flavour of the century.
The Indirect Tax Committee under the leadership of Deepak Shah has its’ task
fairly cut out. Focus on GST and nothing else. Be it long duration courses,
residential study courses, study circles or lecture meetings, leave no stone
unturned. Over and above the routine, a special focus on GST Audit along with a
publication thereon will be the priorities of this Committee. In fact, a long
duration course on GST covering the entire law through a series of 36 sessions
is already planned in the month of October and the announcements will be made
next week. I would request members to enrol at the earliest to avoid
disappointment.


The task before the International
Taxation Committee under the leadership of Mayur Nayak is also intense. Long
duration courses both at the beginner as well as advanced level on transfer
pricing, FEMA, DTAA, etc. have remained popular over so many years and no
second thought is required on their continuity. Members can also look forward
to more focussed programs on emerging topics like BEPS, GAAR, etc., with a
variety of speakers including international speakers. The flagship ITF
Conference to be held in August has received wonderful response and bookings
are nearing closure.


With sweeping changes in the regulatory
domain, introduction of various accounting and auditing standards, the
Accounting and Auditing Committee led by Himanshu Kisnadwala will organise long
duration courses on Ind-AS and some innovative sessions around valuation,
implementation of Ind-AS, etc.

I can go on and on. The knowledge
bank at BCAS is endless. However, the need of the hour is to build upon the
knowledge and talent base and convert the same into wisdom so that the common
man can provide holistic solutions to his clients.


The Journal Committee, under the
able leadership of Raman Jokhakar has precisely demonstrated that. In its 50th
year of publication, the BCAJ has donned a new look, with new interactive
features and experiences. The golden pages will be continued throughout the 50th
year. We will also look at more incisive articles on topics of relevance.
Special attempts will be made to increase the reach of the Journal.


Appreciating the need of the hour
to move to an orbit of deliverable higher than knowledge, at BCAS, events will
be made more interactive such that the participants can interact with the
faculties and grasp the concepts better. The expert chat and the panel
discussion formats will be more integrated into the mainstream events so that
experiences are communicated rather than merely rote information being
delivered. In fact, an interactive panel discussion on 14th July has
already been announced by the International Tax Committee to debate upon
various issues emanating out of ‘some recent rulings in the context of
permanent establishments’.


Last year, we tried an innovative
way to disseminate knowledge through a series of short educational videos of
GST. The said initiative was very popular. Building upon the said initiative,
the Direct Tax Committee has planned a series of monthly videos under the title
“Tax Guru Cool”. The first video by our Cool Guru Ameet Patel is already
published and will be released today.


Most of the events cater to
specific domains like accounting, direct tax, GST, international tax, etc.
However, the need of the industry is not only isolated specialised knowledge in
specific domains but also a holistic solution across multiple domains. The
Society will conduct more events which cater to specific issues or industries
spanning across a wide spectrum of domains to equip the common man to look at
the entire problem of the client more comprehensively. Effectively, this can
transform the common man from an enquiry booth to a business enabler.


As traditional domains of audit and
tax get more saturated, it is also time to develop new domains. Long duration
study courses are best equipped to address this nascent need. A special GRC sub
group under the Accounting and Auditing Committee has been created under the
leadership of Nandita Parekh to concentrate on GRC and internal audit where the
focus again will be to build a talent base of GRC professionals through long
duration courses along with certification from reputed educational
institutions. The sub group would also meet regularly to discuss various
aspects of internal audit. The first such interaction is already planned for 13
July and has received a good response.


The Corporate and Allied Laws
Committee, under the leadership of Chetan Shah will not only design programs
around the Companies Act but will also concentrate on further opportunities in
the fields of IBC, real estate law, succession planning, independent
directorships, charities and trust laws, etc. 


A focus on inter-domain events,
interactive events and events on emerging domains will definitely equip the
common man to stay relevant in the changing times. However, the long term
survival of the profession, to my mind, will depend on how successfully the
profession and the common man is able to integrate technology into the service
offerings and provide a value proposition to the industry which is fairly
distinct from the deliverables offered by technology. In effect, the
competition is not within the profession (against the Big 4 or large firms) or
even outside the profession (like the legal profession or company secretaries) but the competition for the common man is against
supercomputers and organised businesses. The re-created Technology Initiatives Committee
under the able leadership of Nitin Shingala will line up a series of curtain
raiser programs and events to sensitise the common man of the challenges and
opportunities due to the technological advancements in the field.


The Society had organised a panel discussion of successful
professionals in the 51st RRC. In a candid talk, all the professionals across domains attributed “passion” as one of the most
important reasons for their success. Indeed, passion is the fulcrum of all
successful endeavours.In a crystal maze of due dates and deadlines, uncertain and non-implementable
laws and less than optimal support
infrastructure, the common man loses passion towards the profession resulting
in a compromised position of success. In these circumstances, the common man
turns to organisations like the BCAS to provide thought leadership and guide
the way back. The common man asks:Can the Society help me Re-kindle my
Passion?


The flagship Residential Refresher
Course is an ideal breeding ground where participants from diverse domains,
geographies, cultures, seniority come and stay together to learn some technical
concepts and also network amongst themselves.


The reconstituted Seminar &
Membership Development Committee led by Narayan Pasari & Pradip Thanawala
will introspect and redesign the RRC so as to create an ideal balance between
the knowledge content and the passion content and make it much more relevant in
the changing times. The Human Resource Development Committee under the able
leadership of Rajesh Muni & K K Jhunjhunwala will also spend valuable time
and efforts in bringing in the passion amongst the members especially the youth
and students. More interactive sessions on practice management, career
alternatives, industry roundtables, etc., will be organised during the year to
re-kindle the passion towards the profession.


The long term survival of any
profession or career also depends on its reputation and the pride that the
existing members feel towards the profession. A few incidents in the recent
past and out of proportion media coverage of these incidents has left the
common man bruised and wounded despite no fault of his. Whether we like it or
not, the fact is that a few black sheeps have tarnished the image of the
profession. During such chaotic times, the common man asks:


Can the Society help me Re-store
my Pride?


The entire issue, to my mind, has
four distinct dimensions – (i) building a strong ethical base and nurturing the
values that enable “the right way of doing things”, (ii) building technical
capabilities , (iii) bridging the expectation gaps (iv) handling and
communicating perception.


While the Society has always
concentrated on the first two dimensions and has done reasonably well in both
those dimensions, I believe the changing times require the Society to foray
into the other two dimensions as well. More events and publications clearly
showcasing what a chartered accountant can do, what he cannot do and what he
ought not do, is the pressing need of the hour. These imperatives need to be
showcased not only to membership at large but also to all the external
stakeholders. The BCAS will strive to work hand-in-hand with the ICAI and also
conduct various joint programs with industry associations where technical
content of our members is garnished along with the ethical aspects of the
profession. BCAS will also actively engage with the media including social
media and act as a voice of the profession. Effective representations towards
bringing sane and clean laws will also help the Government appreciate the role
of the professionals in general and BCAS in particular. I am glad to share with
you that recently, the Indirect Tax Team of BCAS suggested a simplified GST
Audit Format to the Government and had the occasion to meet top revenue
officials both at the State Level as well as at the North Block to explain the
said format. The responses in both the meetings were very positive and we look
forward to some simplification in this direction.


So, the common man expects an
august institution like BCAS to help him:


  •    Re-Engineer my Profession
  •   Re-Kindle my Passion
  •    Re-store my Pride


The common man knows that only an
exemplary apolitical institution like BCAS can perhaps meet these high
expectations. In that sense, the common man needs BCAS, not only for today and
the next decade, but for decades together. An institution like BCAS is built
when volunteers selflessly devote time, energy and passion to the common cause.
Seven decades of existence brings with it maturity and experience. Along with
these virtues, the association also builds in conservatism, prides and
prejudices. In this world of choices and a structural disconnect of no CPE
hours, the common man asks:


Can the Society help itself and me
to Re-juvenate my BCAS?


Excellence, it is said, is a
journey rather than destination. Without sounding judgemental, the journey
towards higher orbits of excellence for BCAS will depend on answers to many
random thoughts.


  •     Can we look at a Society
    where despite the maturity, experience and conservatism, there are no personal
    prejudices?


  •     Can BCAS be a forum where
    everyone is important and is made to feel important?


  •     Can the Society bring
    more focus on its initiatives and objectives and stay away from activities
    which have very remote connection to its objectives?


  •     Can we do something to
    build excitement around the events of BCAS?


  •     Can we assure the
    volunteers a merit driven, objective career progression path at BCAS?


  •     Can the Society be a
    magnet which attracts the best talent in the profession towards it?


If we are able to achieve this, the
ever-elusive membership mark of 10000 may be just a by-product. This is the
dream of the common man for his BCAS.


Ladies and Gentlemen, on behalf of the 5 Office
Bearers, 16 Managing Committee Members, 219 Core Group Members and 9000 members
and subscribers, I welcome you to My BCAS, our BCAS. I place the annual plan
before this august gathering and seek your full-fledged support in its
implementation. Thank you for a patient hearing.
  

Society News

11th Jal Erach Dastur CA Students’ Annual Day – ‘Tarang 2k18’ held on 9th June 2018

BCAS Students’ Forum under the auspices of HDTI Committee organized 11th Jal Erach Dastur CA Students’ Annual Day on 9th June, 2018 at K. C. College, Churchgate under the banner Tarang 2K18. In this mission, the Students’ Team embarked upon the journey with an apt theme ‘New India’ for Tarang 2k18. The Forum comprised of a fleet of 36 dedicated and enthusiastic students. The event was truly an event ‘OF CA students, FOR CA students and BY CA students’. It completely changed the personality perception regarding CA students while witnessing them as event managers, anchors, talented dancers and also photographers!

The theme of ‘New India’, as envisaged by our Hon. Prime Minister, focuses on innovation and improvisation. This year ‘Tarang’ reinvented its decade old elocution competition (sponsored by Smt. Chandanben Maganlal Bhatt Elocution fund) into Talk Hawk on the lines of the famous TEDx program. Also, this edition saw the reintroduction of Antakshari competition which had formed a part of the 1st edition of this event in 2008. The year set a new benchmark for ‘Tarang’ with the participation reaching a new high with 294 entries comprising seven different competitions.

The event commenced with a dance performance with lezim beats invoking the blessings of Lord Ganesha. It was followed by Ganesh Arti performed by CA. Narayan Pasari, President, BCAS who also paid tribute to Shri Jal E. Dastur along with the members of the Managing Committee & HDTI Committee.

The three finalist teams of the reinvigorated ‘Antakshari Competition’ named as ‘Deewane’, ‘Parwane’ and ‘Mastane’ were the first to occupy the stage. The Antakshari had fun-filled and innovative rounds to test quick thinking of the participants. Everyone were astonished to witness the talent of CA students even in the arena of Bollywood songs and trivia. The event was hosted by CA. Vijay Bhatt accompanied by CA. Meena Shah and Tej Bhatt.

The next event was ‘Talk Hawk’ (sponsored by Smt. Chandanben Maganlal Bhatt Elocution fund) wherein the three finalists had to give a 6 minute TED Talk on any topic of their choice. This enabled a level playing field for all participants who gave their impressive performances on their respective topics. During the Talk Hawk, the auditorium was graced by the presence of Senior Advocate, Shri Sohrab. E. Dastur who is a constant source of inspiration to this event.

Post Talk Hawk, the winning film of Short-film making competition – ‘The Screenmasters’ was played. The message of winning film – ‘Smile’ did moist eyes of the audience. This was the second year of the Short-film making competition and it truly scaled a new height. All the entries of short films had a beautiful message for the theme of ‘New India’ and were very precisely shot.

Next, the best photographs from the Photography Competition ‘Khinch Le’ were displayed. This event, too, was reinvented with a concept of ‘Public Choice award’ wherein photographs short listed by judges were put to vote on the Facebook Page and the photograph with maximum votes would be the winner. Participants were given themes on which they had to click creative photographs and post it on the Facebook Page with an innovative tagline based on the theme selected. This competition saw record participation of 75 entries and kept the Facebook Page thundering.

Thereafter, the stage witnessed a surprise entry of the Chief Guest of the evening – the witty Cyrus Broacha, a well-known TV personality and satirist, most popularly known for his show ‘MTV Bakra’ and ‘The Week That Wasn’t’. He used his gifted humorist skills to tickle the funny bone of the audience. He was felicitated by our President CA. Narayan Pasari and the event coordinator Parth Patani proposed a vote of thanks for Mr. Cyrus Broacha.

Then the time had ripened for the most awaited event of the evening – CA’s Got Talent. The singers had assembled, guitars and keyboards were in place, dancers were on their feet and actors began polishing their lines before they could thrill the audience with their mesmerising performances. To give a spirited kick start to this most awaited event, the students’ team presented a 4 minute flash mob which was choreographed by CA. Rishikesh Joshi.

And rightly then, the 12 performances in singing, dancing and other performing arts category enthralled the audience. The judges were fascinated, rather bewitched, by the talent of young CA students. They indeed had a mountainous task of choosing the winner.

With the clock-ticking, the participants began crossing their fingers as the ice was about to be broken. The winners of the competition representing their firms were finally announced. The list goes as follows:

Essay Writing Competition ‘Awaken the Writer Within’

Prize Name of Student Name of Firm
1st Prize Winner Kanika Mangal —————————–
2nd Prize Winner Rakshita Yadav CNK & Associates LLP
3rd Prize Winner Ronak Thakker Vyas  & Associates

Talk Hawk – ‘Aspire to Inspire’

Winner Gauri Kakraniya Singrodia Goyal & Co.
Rotating Trophy went to Singrodia Goyal & Co.

Talent Show ‘CA’s Got Talent’

1st Prize (Singing Category) Sagar Shah Raju & Prasad
1st Prize (Dancing Category) Niti Shah Mukund M. Chitale & Co.
1st Prize (Other Performing Arts Category) Vivek Rajpurohit Sara & Associates

Antakshari Competition – ‘Suro ke Sartaaj’

Winning Team Kasturi Kolwankar Natwarlal Vepari & Co.
Vaibhav Mandaliya D.H. Chheda & Company
Romil Goyal Gupta & Ashok
Best Individual Performer Khushbu Shah Mehta Chokshi and Shah

Sketch & Slogan Competition ‘Leave your Mark’

1st Prize Winner Kasturi Kolwankar Natwarlal Vepari & Co.
2nd Prize Winner Deevesh Chudasama Khandelwal Jain & Co.
3rd Prize Winner Romil Goyal Gupta & Ashok

Photography Competition ‘Khinch Le’

Judges’ Choice Prize Chinmay Jagtap M.P. Chitale & Co.
Public Choice Prize Sophia Pereira J.H.Gandhi & Associates

Short Film Making Competition ‘The Screenmasters’

1st Prize Winner Pratik Hingu and Team Bhikubhai H. Shah & Co.

Hearty Congratulations to all the winners and their firms.

Judges for the Various Competitions were as follows:

Competition Elimination Round Final Round
Essay Writing CA. Gracy Mendes and CA. Sangeeta Pandit
Talk Hawk CA. Vipul Choksi

CA.Mukesh Trivedi

CA. Atul Bheda

CA. Mudit Yadav

Talent Show CA. Ryan Fernandes

CA. Devansh Doshi

CA. Manori Shah

Shri. Nipun Nayak

Antakshari Competition CA. Toral Mehta, CA. Ryan Fernandes and CA. Kartik Srinivasan
Sketch & Slogan Competition CA. Raman Jokhakar and CA. Chirag Doshi
Photography Competition CA. Kamlesh Vikamsey and Mrs. Vineeta Muni
Short Film Making Competition CA. Divyesh Muni and CA. Rajesh Pabari

The entire evening was marvellously anchored by Mr. Kedar Pandey, Ms. Gauri Kakraniya and Mr. Nilay Gokhale with their sheer display of energy coupled with mind blowing performances. The anchors were also supported by Ms. Devyani Choksi and Ms. Preksha Shah in hosting the show.
Mr. Sahil Tanna proposed the well-deserved vote of thanks to Mr. Sohrab Erach Dastur for sponsoring the annual day in the fond memory of his brother late Jal Erach Dastur, the family of Smt. Chandanben Maganlal Bhatt for sponsoring the Elocution Competition, the members of the Managing Committee and HDTI Committee, the Coordinators of the Annual Day, the Event Moderators, Judges of various competitions, BCAS Staff and the vibrant team of student volunteers and all the students for participating in big numbers.

A scrumptious dinner was arranged after the event for all those who marked their presence at the annual day. Finally with a sense of satisfaction, joy of success, lasting motivation and with some unforgettable memories, it was called a day.

“Power Up Summit” held on 16th June, 2018 at Orchid Hotel, Mumbai

The Human Development and Technology Initiative Committee organised a one day programme “The Power Up Summit: Reimagining Professional Practice”, on June 16, 2018, at the Orchid Hotel, Mumbai. This Summit was in continuation of a series of Power Summits organised annually since 2011.

The Power Up Summit, conducted by a team of 3 faculty members, CA. Nandita Parekh, CA Ameet Patel and CA. Vaibhav Manek was attended by 73 members. The entire programme was conducted and well-coordinated by the faculty members in a seamless manner. The presentations were creative, colourful and intertwined with short videos that drove the points home in an entertaining manner.

The Summit raised important issues dealing with succession planning and sustainability of professional practices, the merger mathematics and valuation of professional practices, the challenges and opportunities arising due to technological advances and the need to get ready to “thrive” in these disruptive times, and not just survive.
The interest of the participants was evident in terms of the involved discussions and the incessant questions raised after each session. The Summit succeeded in generating a lot of interest among the participants in learning the art and science of practice management.

INDIRECT TAX STUDY CIRCLE

Indirect Tax Study Circle Meeting held on 16th June, 2018 at BCAS Conference Hall

Indirect Taxation Committee organised a Study Circle Meeting on 16th June 2018 at BCAS Conference Hall, to discuss the important definitions under the GST Law. The discussion was led by CA. Yash Parmar and the group was guided by CA. Naresh Sheth and CA. Rajat Talati. The Group discussed definition of “goods”, “services”, “aggregate turnover”, “taxable supply”, “exempt supply”, “non-taxable supply”, “composite supply”, “mixed supply”, “job work” and “works contract”. The importance of expression “unless the context otherwise requires ” used in the definition clause was also discussed. Related judicial pronouncements and Advance Authority Rulings were mentioned in the discussion.

The meeting was quite interactive and participants benefitted a lot from the session.

Celebration of International Yoga Day on 21st June, 2018 at BCAS Conference Hall

HDTI Committee, jointly with Indian Spiritual Healing (ISH) Foundation, organised a Yoga Session on 21st June 2018 at BCAS Conference Hall to mark the celebration of “International Yoga Day” which falls on the same day.
Mr. Pradeep Thakkar, a Professional Yoga teacher and also an active member of ISH Foundation guided the participants to perform different Asanas with ease, comfort for healthy body and mind relaxation. He also demonstrated some powerful Asanas to improve memory, maintain mental fitness and also to keep the body flexible and tone the muscles of the body.

Participants had good learning of Yoga Asanas for healthy body and peaceful mind.

Report on 12th Residential Study Course (RSC) on GST held at Kochi from 21st to 24th June, 2018

The 12th RSC of Indirect Taxation – GST was planned and organised by the Indirect Taxation Committee at Hotel Marriott, Kochi from 21st to 24th June, 2018. The Timing was perfect as GST law was nearing its first completed year after implementation. Looking at the complexity and frequent changes in the law, the RSC was attended by many delegates from various parts of the country. RSC was attended by 218 members.

The RSC for the first time was extended by a day to a 3 nights & 4 days course. The Course comprised of three group discussions on case papers prepared by eminent speakers and discussed by members in five different groups headed by group leaders. The Speakers also presented their views on the cases discussed by the members. The Group discussion and presentation of views of speakers was followed by presentation of two important topics by eminent speakers. The Highlight of the course was the Talk Show arranged by the Indirect Taxation Committee.
On the first day of RSC, post registration, there was a session of Group Discussion on Paper I by Adv. Rohit Jain on “Case Studies in Levy, concept of Supply with related schedules, Scope of ‘Business’ under GST (Including Mixed and composite supplies)”. The case study exhaustively covered the topic within the groups.

Subsequently, there was an inaugural session which commenced with the inaugural address by the President of BCAS, CA. Narayan Pasari. He briefly addressed the gathering and also gave a brief about the activities of BCAS and benefits to its members. Later, chairman of the Indirect Taxation committee, Deepak Shah gave introductory remarks on the design and structure of the course and the purpose of selection of the topics for group discussion as well as presentation. Thereafter, the keynote address was given by Mr. D.P. Nagendra Kumar D.G. (South) (GST), Chennai & Mr. Pullela N. Rao, Chief Commissioner, Kochi. Both the speakers got well connected to the participants and gave an insight into the provisions of the law and also responded to all the queries posed to them.

Second day started with Presentation of Paper I by Adv. Rohit Jain. All the questions were diligently covered by the speaker who well explained the concept of Mixed Supply, Composite Supply and Works Contract. Post that, the group got together for discussion on Paper II by CA. Divyesh Lapsiwala on “Place of Supply, Cross-Border transaction (including between states) under GST (including mixed and composite supplies)”. All the cases given by the presenter were well discussed and the points highlighted by the presenter were on day to day issues faced by the practitioners.

Post lunch, Presentation paper on “GST Audit and state of preparedness” by CA. Naresh Sheth was well articulated and reference material was given to all the members present, to work on GST Audit. He gave a framework for the professionals to conduct the audit and gave an exhaustive list of reconciliations for consideration.

A Talk show on GST related practice was also organised which was anchored by Vice President, BCAS, CA. Sunil Gabhawalla & Senior member CA. A.R. Krishnan and panel comprised of CA. Naresh Sheth, CA. Rajiv Luthia, CA. Divyesh Lapsiwala & CA. Jatin Harjai. All the four panellists were requested to share their preparedness for GST during the initial days of act coming into existence, the Working culture and best practices they followed. It was followed by a presentation paper on “Procedure under GST, Payment, Returns etc. – issues” by CA. Rajiv Luthia. The Speaker made a presentation on the issues related to the procedural aspects of payments & returns which covered a variety of problems faced with possible solutions. Day ended with entertainment program and authentic Kerala dinner called Sadhya.

Day Three started with group discussion on Paper III by Adv. G. Shivadass “Classification issues under GST, Works Contract and Job Work” pointing out various issues under classification, works contract and job work. After that, presentation of Paper II was made by CA. Divyesh Lapsiwala and his colleague. The speaker gave all his views on the topic and covered all the questions given in the paper book. It was followed by lunch and sightseeing for the participants with boat ride arranged by BCAS for all the participants. Last day started with presentation of Paper III by Adv. G. Shivadass who very well presented his thoughts and covered all the questions in the designated time.

The Concluding session was presided over by Chairman CA. Deepak Shah and he acknowledged contribution of the faculty and group leaders, as well as active participation of all participants and support from BCAS staff for the success of the RSC. Some of the participants gave their views on the course and conveyed their satisfaction at the format, topics covered and structure of the course. Participants were also quite happy and satisfied with the arrangements made by BCAS at the venue and learnt a lot from RSC sessions.

Lecture Meeting on “Transforming Mumbai – Challenges and Opportunities” held on 26th June, 2018

Bombay Chartered Accountants’ Society organised a lecture meeting on ‘Transforming Mumbai – Challenges and Opportunities’ on 26th June 2018 at Indian Merchants’ Chamber which was addressed by the guest speaker Mr Ajoy Mehta, Hon. Municipal Commissioner of Mumbai.

President, CA. Narayan Pasari, introduced the Speaker and gave the opening remarks while explaining the vision and various activities of BCAS including our 50th year Journal, Annual Referencer, Representations and social activities such as RTI, Charitable Trust and Accounting & Auditing Clinic etc. He also touched upon the subject with particular reference to challenges of transforming Mumbai and the role of MCGM and its good governance.

Mr. Ajoy Mehta, Hon. Municipal Commissioner of Mumbai took forward the discussion and explained the challenges and the opportunities to overcome those challenges of Mumbai. He started with the introduction of Mumbai and mentioned that Mumbai is having 476 Sq. Km. of area with population of 1.24 crore. If we leave aside the mangroves, roads and coastal regulatory zones etc., we are left with very little area for use of the public at large. So, he enumerated the following key factor attributed to Mumbai:

Area: He explained that going by the demographic history, the population growth has considerably reduced from 38 % increase in 1990-91 to 3.7 % in 2001-2011. Till 2021, we are going to see growth in population. As per 2034 vision, we feel that after 2021, population growth of Mumbai will drop because of the satellite cities like Thane, Vashi etc. developing fast. We just need to push infrastructure, transportation etc.

He also discussed how to deal with the issues which the local body (Corporation) faces while implementing the policies. There are two instruments namely. (i) Budget and (ii) Land Use to overcome the obstacles. He told that the Corporation has made the development plan for the next 20 years.

Further, the Speaker enumerated the key challenges being faced by Mumbai which need to be dealt with by MCGM aggressively viz. (i) Services (ii) Long Term Infrastructure (iii) Regulatory Roles ((iv) Employment Generation (v) Affordable Housing (vi) Social Equity Issues (vii) Water (viii) Waste Disposal (ix) Health Care etc.

The Hon. Speaker explained that the Corporation has made most of the services IT enabled like online payment, building permit etc. On the environment front, every tree in the city has been mapped and we are going to develop a very strong IT equipped engine to cover more services under its umbrella and thereby give better services.

Mr. Ajoy also explained about the ongoing projects like the Coastal Roadway and Urban Transport amongst others and the widening role of MCGM to cope up with the challenges ahead in meeting the infrastructure requirements of the Mumbai Metro City. He also emphasized the need for a futuristic outlook and vision, to prepare a draft plan to execute efficiently with the passage of time without any bottlenecks.

The meeting was followed up by Q&A session where the Speaker thoroughly responded to all the queries raised by the participants.

The participants were hugely enlightened with the insights provided by the Speaker.

Lecture meeting on “Filing of Income Tax Return for A.Y. 2018-19” held on 2nd July, 2018

A lecture meeting on topic “Filing of Income Tax Return for A.Y. 2018-19” was held on 2nd July, 2018 at K. C. College auditorium. CA. Devendra Jain dealt with legal aspects of Return Filing and CA. Divya Jokhakar dealt with procedural aspects of Tax Return Filing.

During his presentation CA. Devendra Jain discussed and explained various amendments of Finance Act 2017 relating to Rates of taxes, exemptions etc. He touched upon legal aspects of Income from House Property, Capital Gains, Business Income, changes in Depreciation, Other Sources etc.

CA. Divya Jokhakar in her presentation explained procedural aspects of Income Tax Return such as Applicable forms for various types of assessees, Mode of submission etc. She also updated the participants on the
latest changes in Income Tax Return.

Both the speakers replied to the questions raised by the participants.

The lecture meeting provided a hands-on guidance to the participants, many of whom were young members.

70th Foundation Day Lecture Meeting on “India – 2019 & Beyond” held on 6th July, 2018 at Garware Club House, Churchgate, Mumbai

A lecture meeting on “India – 2019 & Beyond” was held on 6th July, 2018 on the occasion of 70th Foundation Day of the Society which was addressed by CA. Nilesh Shah, MD, Kotak Mahindra AMC Ltd. President CA. Narayan Pasari briefly touched upon the perspective of India’s economic growth and shared the profile of Mr. Nilesh while welcoming the Chief Guest and then requested him to address the august audience.

At this occasion, BCAS publications: Thought Mailers – A Compendium Volume 1 & 2, Presumptive Taxation under sections 44AD, 44ADA and 44AE and BCA Journal – July 2018 were released by the hands of the Speaker CA. Nilesh Shah.

On the topic of the Lecture Meeting “India – 2019 & Beyond”, the Speaker explained the challenges to overcome to achieve the growth story of India beyond 2019. He lucidly drove the inherent challenges which India has to face on account of following: (i) India being equivalent to a continent, (ii) savings allocation being poor, (iii) Poor tax compliance (iv) Poor job creation (v) Global liquidity crisis (vi) Deteriorating macro outlook viz. crude oil, current account deficit, fiscal deficit etc. (vii) Credit squeeze.

He also discussed about basic market forces which are leading to the growth of economy and enumerated some of them as follows:(i) Increased Urban consumption, (ii) Overall increase in auto sales, (iii) Aviation sector doing well, (iv) Tourism growing fast, (v) MFI recovery in rural sector is good, (vi) Railways is on fast track, (vii) GST buoyancy, (vii) NPAs getting solved and (viii) PE Ratio being above average.

The Speaker further talked about the reforms of Modi Government which will contribute to faster development of the economy from 2019 onwards namely Lower inflation, Minimum Government-Maximum Governance, Free markets, Improving quality of public spending, Fiscal Prudence, Attracting FDI amongst others.

At the end, there was Q&A session where the Speaker responded in a pragmatic manner to the queries of the audience.

The audience got mesmerised with presentation skills of CA. Nilesh Shah and gained a lot from the insights from his spectacular speech.

SUBURBAN STUDY CIRCLE

Suburban Study Circle Meeting on “Provisions of ICDS Revelant to SME’s” held on 7th July, 2018

The Suburban Study Circle organised a meeting on “Provisions of ICDS Revelant to SME’s on 7th July, 2018 at Bathiya & Associates LLP, Andheri (E) which was addressed by CA. Namrata Dedhia.

The speaker CA. Namrata Dedhia made a detailed presentation on the provisions of ICDS which are specifically applicable to SMEs. The major points discussed were (a) Applicability of the ICDS and the background (List of ICDS notified) of ICDS which had its basis and comments from the Delhi HC ruling. (b) Major changes and recent developments (c) Other provisions of ICDS. The speaker also discussed what confusions are still around, the best available stand we should take to avoid penalties and non-compliance. The speaker shared practical examples on her experience with the clients and tax authorities.

The participants learned a lot from the presentation shared by the speaker.

BEPS STUDY CIRCLE

Meeting on “Disclosure Rules for CRS Avoidance Arrangements and Opaque Offshore Structures under BEPS measures” held on 7th July, 2018 at BCAS Conference Hall

International Taxation Committee organized a Study Circle Meeting on “Disclosure Rules for CRS Avoidance Arrangements and Opaque Offshore Structures under BEPS measures” on 7th July 2018 at BCAS Conference Hall which was led by Group Leader CA. Shweta Ajmera.

The group leader explained about BEPS Action Plan 12 (i.e. Mandatory Disclosure Rules) and OECD Model Disclosure rules to address Common Reporting Standard (CRS) Avoidance Arrangements and Opaque Offshore Structures which was released on 8th March 2018. So far, the exchange of information is done between Governments. The new guideline would require intermediary of an arrangement to disclose factual disclosure of the arrangement including service providers and to identify the jurisdiction in which the Arrangement is available to implement. It also includes intermediaries providing services for such an arrangement if they are in a position to know that such arrangements avoid reporting. The model rules would require intermediary to make the disclosure 30 days after the intermediary makes the arrangement available to implement or after the intermediary provides what are “Relevant Services”.

The Speaker also explained that now the game is over for CRS avoidance. The objective of Mandatory disclosure rule is to provide tax administrators with information on CRS Avoidance Arrangements and Opaque structures. This information is used by the jurisdiction for compliance purpose as well as to decide future policy tax design. Intermediary or user of a CRS avoidance arrangement or Opaque Offshore structure has to disclose certain information to its tax administration. If the user is resident of another jurisdiction, then information will be shared with that jurisdiction.
By rules, the tax administrators will get information about various schemes- their suppliers, users for use in compliance activities, exchange with treaty partners to tax policy design. Five key elements of rules are:

  • Description of arrangements that are required to be disclosed (i.e. Hallmark of Disclosable scheme)
  • Who will disclose – Description of persons required to disclose such arrangements (i.e. intermediaries that are subject to reporting obligations under the rules)
  • What to disclose: A trigger for the imposition of a disclosure obligation (i.e. when an obligation to disclose crystallises under the rules and any exception from reporting)
  • A description of what information is required to be reported
  • Appropriate penalties or other mechanisms to address non-compliance.

Considering the above rules the members also deliberated as to how will it affect the advice rendered by Chartered Accountants and other tax advisors.

The speaker further shared her knowledge and experience on various related issues which was a valuable takeaway for the participants.

Lecture Meeting on “Taxation of Transactions in Securities” held on 11th July, 2018

Taxation Committee of BCAS organised a lecture meeting on Taxation of Transactions in Securities on 11th July, 2018 at Indian Merchant Chambers, Mumbai which was addressed by CA. Yogesh Thar.

CA. Sunil Gabhawalla, President, BCAS introduced the Speaker and gave opening remarks while explaining about BCAS activities and also touched upon the subject in brief. At this occasion, BCAS publication “Interest Limitation Provisions under Section 94B” was also released by the hands of the guest Speaker.

CA. Yogesh Thar broadly covered the following key elements of Taxation of Transactions in Securities in detail:

1. Business Income vs. Capital Gains: Under this. he talked about relevant judicial pronouncements and legislations covering past assessment records, methods of valuation, nature and quantities of purchase and sales, ratio between purchase and sale and period of holding, frequency, continuity and regularity of transactions, source of acquisition, transfer of control and management along with shares, bonus stripping, amendments to Sec. 145 A etc.

2. Impact of Taxation of Transactions in Securities other than shares: He discussed about investment in units of equity mutual funds, purpose of MAT, one time settlement agreement, Accounting Policies and Changes, Demergers and Debentures etc.

3. Re-introduction of Long Term Capital Gains Tax: Under this topic, he explained about provisions prior to introduction of section 112A, its applicability from AY 2019-20 and analysis. He also talked about determination of cost of acquisition under section 55 (2)(ac) etc.

4. Section 50CA & section 56(2) & Valuation Rules: Under this segment, the Speaker explained about interplay between section 50 CA and 56 (2)(x). Section 50CA presupposes consideration, Rights and Bonus Issue, Convertible Instruments under section 56 (2)(x) etc. He also touched upon multi-layer shareholdings and the rules and issues on rules and other issues etc.

5. Taxability of ESOPS: Under this aspect, CA. Yogesh Thar deliberated upon the grant, vesting and exercise of options, sale of shares, recent development in taxability of stock option rights (SARS), issues under DTAA, Deductibility of ESOP Expenses and IndAS MAT implications amongst others.

6. GAAR Applicability to Transactions in Securities in particular for FPIs: The Speaker also talked about the circular no 7 of 27.01.2017 by CBDT, Draft Guidelines for GAAR implementation under Direct Tax Code Bill 2010 and analysis thereof.

7. Penny Stocks: He further shared his thoughts on taxability under section 115BBE, Safeguards against Transactions being treated as fictitious, documents required to prove genuineness and judicial analysis etc.

8. Transfer Pricing: Under this subject, the Speaker explained inbound and Outbound Investments and whether transfer pricing provisions would apply for buy back taxable under section 115 –QA.

Apart from the above, Mr. Thar also briefly touched upon Implications of long term capital gains tax on securities, Source of acquisition, Investment Portfolio, Listed and unlisted securities and transfer of unlisted shares, Debentures, Investment in Mutual Fund Units, Units of MF held as stock in trade, Valuation of cost to market value, Value of inventory as per RBI Guidelines and measurement of financial assets etc.

The Speaker also briefed about the case laws and circulars issued relevant to transactions in securities. He further spoke on introduction and purpose of MAT and unrealised and notional gains.

The lecture was followed by Q&A session and the Speaker replied to all the queries of the participants in a very
lucid manner.

ITF STUDY CIRCLE

ITF Study Circle Meeting on “Discussion on MasterCard AAR Ruling / Recent rulings on Permanent Establishment (‘PE’)” held on 12th July 2018 at BCAS Conference Hall

International Taxation Committee conducted a meeting on “Discussion on MasterCard AAR Ruling / Recent Rulings on Permanent Establishment” on 12th July, 2018 at BCAS Conference Hall. Meeting started with deliberation on facts of the case along with modus-operandi of the payment solution provider “MasterCard” by the Group Member and presenter CA. Nilesh Lilani.

After the brief explanation of the facts, the floor was opened for the members to discuss peculiar aspects from the perspective of different forms of Permanent Establishment (‘PE’). Revenue’s acknowledged the significant activities of the MasterCard in eccentric way which bring solace for the participants to discuss all the sweeping remarks made by AAR in relation to PE, Royalty and Fee for Technical Service and withholding obligations.

During the meeting, participants exuberantly discussed the significance of MasterCard Interface Processor (‘MIP’), MasterCard Network, Indian Subsidiary in determining the fixed place PE, rendering of services by employees in determining service PE and agency activities by Indian Subsidiary in determining dependent agent PE.

Further discussion took place amid consideration of implication with respect to restructuring in MasterCard India, Transfer Pricing Report of Indian Subsidiary, reply under section 133(6) of the Income Tax Act, 1961 by Banks in India, mark-up charged on technology upgradation services of MIP, taxation of MasterCard in other jurisdiction such as Australia, preparatory and auxiliary nature of services and other related considerations.

Indeed, it was bolstering and interactive meeting and the participants got enormously benefitted from the discussion and insights provided during the meeting.

Meeting on “Making Internal Audit Count: Raising to the Expectations – A Curtain Raiser” held on 13th July at BCAS Conference Hall

Internal Audit has long been acknowledged as one of the four pillars of Corporate Governance. Is the pillar of Internal Audit strong enough to support Corporate Governance? To discuss the issue at length, the newly formed GRC Subgroup of the Accounting and Auditing Committee hosted an interesting “curtain-raiser” event titled “Making Internal Audit Count – Rising to the Expectations” at the BCAS Conference Hall on 13th July, 2018. This event marked the beginning of the year long series of events and initiatives planned by this subgroup to create a platform for GRC professionals to interact and ideate, teach and learn. The Annual Calendar of events planned was also released at this event.

The speakers for the evening, CA. T. N. Manoharan and CA. Mario Nazareth, enthralled the audience with their intellect, humour and wisdom – a rare combination indeed. Their years of experience in senior management and leadership positions translated into deep insights. The carefully curated presentations added colour and charm to the evening; their emphasis on professional responsibility, ethics and integrity, and the need to make a positive contribution raised the bar for the audience by several notches. The large turnout at the event, from industry and profession resulted into a packed hall and an overflow in the foyer where there was live display on the screen.

With the success of this launch event, the GRC subgroup of the Accounting & Auditing Committee is confident of moving forward with the series of initiatives planned for the year with focus on Internal Audit.

The sessions were very interactive and enlightening for the participants who benefitted a lot from the rich experience of the learned speakers.

“Panel Discussion on “Analysis of PE Constitution- “Recent Judicial Pronouncements including MasterCard, Nokia Networks and Formula One.” held on 14th July, 2018 at BCAS Conference Hall

The international taxation committee held a half-day panel discussion on 14th July 2018 at BCAS Conference Hall, on the contentious topic of Permanent Establishment with special reference to the recent Advance Ruling in the case of MasterCard, the Supreme Court decision in Formula One case and Tribunal’s Special Bench ruling with regard to Nokia Networks OY.

The Panel consisted of three eminent personalities in the field of international taxation namely Mr. Kamlesh Varshney, Commissioner of Income-tax; Mr. Uday Ved, Partner, KNAV and Mr. Rishi Kapadia, partner, Dhruva Advisors. The panel was moderated by Mr. Akshay Kenkre, Founder, TransPrice Tax Advisors LLP.

The decision of Advance Ruling Authorities (AAR) for the MasterCard Singapore was the highlight of the day. Mr. Kamlesh Varshney gave a detailed understanding of the fact pattern of the decision. It was deliberated that the essential element to hold MasterCard Singapore as having a Permanent Establishment in India was the location of the MasterCard Interface Processor (MIP) that connects the MasterCard’s network and processing centres.

Although the Indian subsidiary owned the MIP, the control over the asset exercised by MasterCard Singapore and it is not the ownership but the control over the risk and the asset that are essential elements for the creation of a Permanent Establishment. Here the test of disposal was one of the debated topics amidst the panel.

Further, the importance of Functional, Asset and Risk (FAR) Analysis was brought out during the discussion. The importance of FAR in the transfer pricing study is well known, however, it was brought to attention that such a FAR shows the true substance of a transaction and therefore, could also be relied upon by the international tax authorities to arrive at a conclusion to address a question on the permanent establishment.

The next in line was the Formula One decision by the Supreme Court. The decision gives an interpretation of the test of permanence for determination of Permanent Establishment. The panel considered the pros and cons of the determination of duration test of as short as 3 days to be considered as a Permanent Establishment. If the economic activity is conducted over the entire period of the tournament, then the test of duration is considered to be met. Also, the intention to conduct such activities on a year on year basis is an important proof to hold such transaction to lead to a Permanent Establishment.
The last discussion was on Nokia Networks OY, where it was held that Nokia Networks OY does not create a Permanent Establishment in India. This was a contradictory decision to the earlier two decisions discussed and thus was deliberated on factual grounds.

It was discussed that the activities of the Indian subsidiary cannot be reckoned to constitute a fixed place Permanent Establishment as it did not fulfil any of the triple tests of a fixed place, permanency and disposal, which are prerequisites to constitute an entity as a Permanent Establishment.

The panel gave an all-around perspective in all the three judgements and provided insights taking various live cases and examples to substantiate the explanation which was a huge takeaway for the participants.

INDIRECT TAX STUDY CIRCLE

Meeting on “Supply and Definition of Business under GST” held on 24th July, 2018 at BCAS Conference Hall

Indirect Taxation Committee organised a study circle on ‘Supply and Definition of Business under GST’ on 24th July, 2018 at BCAS Conference Hall which was addressed by the Group Leader CA. Rahul Thakar under the mentorship of CA. Vikram Mehta and CA. Jayraj Sheth. The Speaker made an in depth analysis of both the definitions and cited various past case laws relevant to the terms used in the definitions. Both the mentors guided well not only the leader but also ensured that the overall discussion and coverage completed well in time. Meeting was very interactive and participants immensely benefitted from the session.

37 Section 80-IA – Appeal to Appellate Tribunal – Limitation – Order of revision and consequential order of assessment – Appeals from both orders – Tribunal considering appeal from order of assessment – Dismissal of appeal from order of revision on ground of limitation – Not valid Industrial undertaking – Special deduction u/s. 80-IA – Undertaking engaged in distribution of electricity – Computation of profits for purposes of deduction – Penalty recovered from suppliers for delay in execution of contracts, unclaimed balances of contractors, rebate from power generators and interest on fixed deposits for opening letter of credit to power grid corporation includible in profits – Miscellaneous recovery from employees, difference between written down value and book value of released assets, commission for collection of electricity duty and rental income not part of profit

Hubli
Electricity Supply Co. vs. Dy. CIT; 404 ITR 462 (Karn); Date of order : 9th
February, 2018

A.
Ys.: 2006-07 to 2008-09

The
assessee, a wholly owned company of the Government of Karnataka was engaged in
the business of distribution of electricity. The assessee was entitled to
deduction u/s. 80-IA of the Income-tax Act, 1961 (hereinafter for the sake of
brevity referred to as the “Act”). In the A. Y. 2006-07, it treated
as “income from profits and gains of business” penalty for delay in execution
of work by contractors, rebate from power generators, interest from fixed
deposits, the difference between the written down value and the book value of
assets, commission for collection of electricity duty, rental income, and
miscellaneous recovery from employees. The claim was accepted by the Assessing
Officer. Thereafter the Commissioner invoked the provisions of section 263 of
the Act and set aside the scrutiny assessment, without directing a fresh
assessment. A belated appeal filed against the order of revision was dismissed
by the Tribunal on the ground of limitation. Subsequently, the consequential
assessment order u/s. 143(3) read with section 263 of the Act was passed by the
Assessing Officer disallowing the said claims. The Assessee’s appeal was
dismissed by the Commissioner. The assessee filed further appeal before the
Tribunal. In the mean time, assessment orders for the A. Ys. 2007-08 and
2008-09 were concluded on the same lines, disallowing the deduction u/s.
80-IA(4)(iv)(c) and treating the items of income claimed as “other income” and charging
them to tax. Against these matters, the appeals were filed before the Tribunal.
All these appeals were clubbed together, heard and disposed of by a common
order. The Tribunal accepted some of the claims by the assessee.


On appeal,
the Karnataka High Court held as under:


“i)  The dismissal of the appeal by the Tribunal on
the ground of limitation without going into the merits of the case was
unjustifiable when the issue was considered on merits while adjudicating the
consequential orders.


ii)   The penalty recovered from suppliers and
contractors for delay in execution of works contract, unclaimed balances
outstanding pertaining to security deposits of contractor written back in the
books of account, rebate from power generators, interest income (fixed deposit
for opening of letter of credit to Power Grid Corporation Ltd.) had to be taken
into account while computing the deduction u/s. 80-IA(4).


iii)  Miscellaneous recovery from employees, the
difference between the written down value and book value of released assets,
commission from collection of electricity duty and rental income could not be
taken into account while computing the deduction u/s. 80-IA(4).”


38 Section 2(22)(e) – Deemed dividend (Loans and advances to shareholder) – Where transactions between shareholder and company were in nature of current account, provisions of section 2(22)(e) would not be applicable

CIT vs. Gayatri Chakraborty; [2018] 94
taxmann.com 244 (Cal); Date of Order : 3rd 
May, 2018 A.
Y.: 2009-10

The
assessee was a director in a company, BAPL in which she held 25.24 per cent
equity shares. There were transactions between the assessee and BAPL of giving
money by the assessee to BAPL as well as by BAPL to the assessee. The Assessing
Officer from the ledger account of BAPL in books of the assessee, took note
only of the transactions whereby BAPL gave money to the assessee and was of the
view that the same was ‘loan or advance’ within the meaning of section 2(22)(e)
by a company (BAPL) to a person who held substantial interest in the company
(BAPL) and had to be brought to tax as deemed dividend to the extent the
company possessed accumulated profits.


The
Tribunal held that the said sum received by the assessee could not constitute
loan attracting the deeming provision contained in section 2(22)(e).


On appeal
by the Revenue, the Calcutta High Court upheld the decision of the Tribunal and
held as under:


“i)  Law on this point is clear in the event
transactions between a shareholder and a company in which the public were not
substantially interested and the former had substantial stake, create mutual
benefits and obligations, then the provision of treating any sum received by
the shareholder out of accumulated profits as deemed dividend would not apply.
The company in the instant case fits the description conceived in the aforesaid
provision to come within the ambit of section 2(22)(e). The controversy which
falls for determination is whether the sum received by the assessee formed part
of running current account giving rise to mutual obligations or the payment
formed one-way traffic, assuming the character of loan or advance out of
accumulated profit.


ii)   The Tribunal analysed the ledger account of
the company so far as the payment made to and received from the assessee was concerned
and found that a copy of the ledger of the assessee in the books of BAPL was
placed. A copy of the statement showing the balance after every transaction in
the assessee’s ledger in the books of BAPL was placed. A perusal of the
statement of balances of transactions between the assessee and BAPL shows that
BAPL owed assessee certain sum. BAPL paid the assessee certain sum and the
assessee owed BAPL certain sum. The amounts given in the bracket in the last
column of the enclosed balances in the running current account is the amount
which BAPL owed to the assessee. Mutual transactions go on in this fashion
throughout the previous year and as on the last date of the previous year the
account is squared i.e., neither the assessee owes BAPL nor BAPL owes assessee
any sum. The assessee was beneficiary of the sums given by BAPL at some point
of time during the previous year and BAPL was the beneficiary of the sums given
by the assessee at another point of time during the previous year. It was case
of mutual running or current account which created independent obligations on
the other and not merely transactions which created obligations on other side,
those on the other being merely complete or partial discharge of such
obligations and there were reciprocal demands between the parties and the
account was mutual.


iii)  In this factual and legal perspective, payment
of the aforesaid sums to the assessee cannot be treated as dividend out of
profit. No perversity has been pointed out on behalf of the revenue so far as
such a concurrent finding of fact is concerned by the two statutory appellate
fora. One is not inclined to disturb such finding of fact, which the Tribunal
has backed with detailed analysis. If one embarks on a fresh factual enquiry
into the accounts of the assessee or that of the company involved, such
exercise would entail reappreciation of evidence. Such enquiry is impermissible
at this stage. The Tribunal’s order, thus, stands confirmed and the question
formulated is answered accordingly, in favour of the assessee.”

Beneficial/Benami Holdings In Companies – Disclosure Requirements Notified

Background

Section 90 and related provisions of the
Companies Act, 2013, have finally been brought into force on 13th June
2018 along with related Rules. They apply to all companies, with a small set of
specified exceptions. “Significant beneficial owners” of such companies are
required to make certain declarations. The intention appears to be that those
natural persons (i.e. individuals) who have significant ownership of or
influence in or control of a company need to come forward and disclose their
names. From the point of view of transparency, it would be known who really
controls/owns the company, even if the ownership/control is through holding
entities such as companies, LLPs, Trusts, etc. or through contracts,
arrangements etc. The other major intention and consequence may be that
benami holdings could be identified, or at least required to be.


However, as we will see, the wording not
just of the provisions in the Act but also of the Rules has ambiguities and
uncertainties. This is owing to poor drafting, undefined important terms, etc.
which could lead to problems in implementation. Indeed, it is even difficult to
be clear what is the real intention. For example, is the intention to target
only those cases where the real owners are behind the scenes through certain
structures? Or is the intention to require that all persons with significant
ownership/control be brought on record? If the latter is the intention, there
will be a one-time massive exercise since lakhs of companies will have to make
such disclosures.


This column had discussed earlier some
issues on section 90, at a time when the new provisions were made part of the
Act through the Companies Amendment Act 2017 but were not brought in force. Now
that they have been duly notified and brought into force and require action,
and that the detailed Rules/Forms too are also released, the provisions and
their implications deserve a fresh and closer study.


It may be added that several other
provisions of law such as those relating to money laundering, certain
securities laws, etc. already have provisions requiring disclosures
under certain circumstances. The Benami Transactions (Prohibition) Act, 1988,
too deals with comparable provisions.


Relevant provisions

The relevant provisions are section 90 of
the Companies Act, 2013, with a definition of a term in section 89(10), and the
Companies (Significant Beneficial Owners) Rules, 2018. While the sections give
the primary requirements, the Rules provide for further definitions, the
benchmark at which a shareholder would be treated as a significant beneficial
owner, the process to be followed when shareholders are companies, LLPs, etc.
and the forms, records, etc.


Definition of a “Beneficial Interest”

Section 89 deals with disclosures by persons
with beneficial interests in shares. A person whose name is entered in the
register of members as the holder of shares but who does not hold the
beneficial interest is required to make disclosures. The term “beneficial
interest” has been defined quite broadly in section 89(10) and reads as
follows:


“(10) For the purposes of this
section and section 90, beneficial interest in a share includes, directly or
indirectly, through any contract, arrangement or otherwise, the right or
entitlement of a person alone or together with any other person to—


(i) exercise or cause to be exercised any
or all of the rights attached to such share; or


(ii) receive or participate in any
dividend or other distribution in respect of such share.”


However, while Section 89 requires
disclosure for all cases of shareholding without beneficial interest, section
90 (read with Rules) requires disclosure where there is at least 10% beneficial
shareholding (which would make it a ‘significant beneficial holding’). Section
90 of course applies also to cases where a person has or exercises significant
influence or control.


Terms such as “through contract, arrangement
or otherwise” and “alone or together with any other person” are used but not
defined.


Requirements relating to disclosure

Section 90 (read with relevant Rules)
requires, to simplify a little, a “significant beneficial owner” to make
disclosure. This includes persons having at least 10% beneficial shareholding
or having the right to exercise or who actually exercises “significant
influence” or “control”.


The term “control” has been defined in
section 2(27). The term “significant influence” has not been defined in the Act
or Rules and hence there can be uncertainty. Interestingly, the definition of
the term “associate company” in section 2(6) does define this term, though for
purpose of that clause. It means having “control of at least twenty per cent of
total share capital, or of business decisions under an agreement”.


Holding in shares or other securities

While sections 89/90 refer to the beneficial
interest in shares, the Rules extend it also to global depository
receipts, compulsorily convertible preference shares and compulsorily
convertible debentures. However, no further details are given as to how these
will be applied.


Holding through companies, LLPs, etc.

The intention appears to be to ascertain
those natural persons (i.e., individuals) who are the real owners of a company
and who control it. If the shareholders are persons other than individuals, it
would be necessary to go behind these entities and find who are the significant
owners behind them. Hence, for this purpose, the Rules essentially require the
natural persons who have at least 10% interest in such entity. However, while
one can gauge the intention here, in practice, the wording does not seem to be
sufficient to unravel complex structure of holdings/control. 


The method to determine significant
beneficial owners (SBO) in such cases has been specified as follows.


Where the member is itself a company, SBOs
would be the natural persons who directly or indirectly or alongwith other
natural persons or through other persons/trusts hold at least 10% of the share
capital or who exercise significant influence or control through other means.
Where the member is a partnership firm, the principle is the same except that
the holding may be in terms of capital or entitlement to the profits. In any of
these two cases, if the SBOs can still not be ascertained, then the natural
person who is the senior managing official would be deemed to be the SBO. If
the shareholder is a Trust, the persons to be disclosed are the Trustees, the
beneficiaries who have at least 10% interest in the Trust, and any other
natural person “exercising ultimate effective control over the trust through a
chain of control or ownership”.


Residence of significant beneficial owner

The significant beneficial owner or
intermediary entities may be in India or abroad.


When are disclosures to be made?

The required disclosures have to be made to
the Company within 90 days of the new law coming into force. The Company would
then have to make disclosures to the Registrar within 30 days of receipt of
such disclosures.


There is a one time requirement of making
disclosures and thereafter, disclosures have to be made for changes as well as
for acquisition by new acquirers.


Applicable to which companies?

The new provisions are applicable to all
types of companies, small or big, public or private. The Rules make exceptions
for shareholdings of certain SEBI regulated entities. Clearly, then, lakhs of
companies will have to examine whether these new requirements apply to them.


Do only significant beneficial owners who
are not legal owners have to make disclosures?

Section 89 requires disclosure by a person
who holds shares in his name, but does not have the beneficial holding in them.
Section 90 contains no such limitation. The question then is whether a person
who holds 10% or shares legally and beneficially, would also be required to
disclose? If yes, then practically each and every company will see such
disclosures. The Rules define the term “significant beneficial owner” as a
person specified in section 90(1) who holds at least 10% beneficial holding in
shares, but “whose name is not entered in the register of members of a company
as the holder of such shares”. However, section 90 has much wider scope and,
for example, includes persons having significant influence or control. Hence,
while the Rules may have intended to specify disclosure where there are
beneficial holders who are not legal holders, the wording does not seem to be
clear enough.


Disclosure by institutional shareholders

Though the language is not wholly clear, it
appears that shareholders who are pooled investments funds (regulated under the
SEBI Act), such as the following, do not have to make disclosures under these
provisions:


1.  Mutual Funds

2.  Alternative Investment Funds

3.  Real Estate Investment Trusts

4.  Infrastructure Investment Trust


Obligation on company to inquire
into/report

Obligation has also been placed on the
Company to require persons to make disclosures if it has reason to believe that
such persons are covered by these provisions. If such persons still do not make
a disclosure, the Company has to refer the matter to the National Company Law
Tribunal for directions that may include restrictions over such shares.


Implications for non-disclosures/false
disclosures

If the persons who are obligated to make
disclosures – i.e., the significant beneficial owner and the company – do not
make the prescribed disclosures, they will be subject to fines. False
disclosures may result in prosecution that can be stringent.


Benami transactions

The provisions will surely apply to
legitimate significant beneficial owners. There may be persons who have reason
to hold shares through companies, trusts, etc. or through other complex
structures. However, they could also apply even to persons holding shares
benami as specified in the Benami Transactions Prohibition Act, if the
requirements of that Act are attracted. Disclosure by such persons may result
in very stringent consequences under that Act.


Conclusion

There are several other laws that already
require disclosure of those persons who are the ‘real’ owners/controllers of a
company. The object of each of these laws may be different ranging from
prevention of money laundering, to protection of shareholders, to preventing
tax evasion/corruption, etc. Some such as the Takeover Regulations are
fairly elaborate and while they are complex, the specific nature of provisions
leaves lesser aspects to uncertainty. In other cases, the requirements broadly
describe what is to be ascertained in general terms and then give detailed
clarifications which generally help cover a large variety of situations. The
newly introduced provisions in the Act/Rules make certain well meaning and
significant requirements. However, there are ambiguities in several places that
raise concerns whether the objective would be achieved at all. In many cases,
the provisions may be simple to apply and persons may even err on the side of
caution (even though the disclosures carry the risk of inviting inquiries).


There will however be several situations
where the provisions may be difficult to apply on the facts. One hopes that
clarifications/FAQs with examples of several alternative situations are given
so that there is clarity for at least the vast majority of companies.


Property Tax

Introduction

The Municipal Corporation
of Greater Mumbai (“BMC”) has revised the Property Tax system applicable in the
city of Mumbai. Instead of the earlier rateable value system which was in
force, the property tax was quite low and remained constant for years together.
However, the BMC now has a Capital Value System for levying property tax which
levies tax on the basis of the Stamp Duty Ready Reckoner of the property. This
system is expected to garner substantial revenue for the BMC as it would link
the values to more realistic figures instead of the rent capitalisation values
which were quite low.


Capital Value based System

Under the new system,
property tax is computed as a percentage of the Stamp Duty Ready Reckoner Value
of the property. Currently, the Reckoner of 2015 is adopted as the basis for
this purpose. This value would be adopted for a period of 5 years starting from
1-4-2015. Hence, the capital value would remain unchanged for 5 years, i.e.,
till 2020. After 5 years, as per the present system the Reckoner Rates would be
increased. However, if a building is constructed after 2015, then the Reckoner
rate of the year in which it was constructed would be adopted and would remain
in force till 2020. The rates for levying tax on this capital value depends
upon the Category of the property and are as follows:


    Residential
with metered water supply in City and suburbs @ 0.359%


   Residential
with un-metered water supply in City @ 0.775%


    Residential
with un-metered water supply in suburbs @ 0.552%


    Shops
/ commercial / industrial with metered water supply in City and suburbs @
0.880%


    Shops
/ commercial / industrial with un-metered water supply in City @ 1.90%


   Shops
/ commercial / industrial with un-metered water supply in suburbs @ 1.280%


    Open
Land with metered water supply in City and suburbs @ 1.630%


    Open
Land with un-metered water supply in City @ 3.518%


    Open
Land with un-metered water supply in Suburbs @ 2.370%


In
addition, the BMC has exempted houses in the city with a carpet area up to 500
sq. ft. from property tax. The BMC is also considering passing a proposal for
concession in property tax for houses measuring between 500 sq. ft. and 700 sq.
ft.


The BMC has announced that
soon, personalised property tax bills will be issued, to the people who own
flats in those buildings that have Occupancy Certificates (OCs). However,
property tax of the unsold flats and common areas, will be paid by the builder.
Under the earlier system, the BMC issued a common property tax bill to a
housing society, which then collected the tax dues from the flat owners and
paid the amount to the BMC. The main problem with the earlier system, was that
if a member failed to pay the property tax, then, all the members were
penalised. Now, in the personalised property tax billing system, this will
stop.


Valuation Rules


Valuation of Open Land

Capital Value of open land,
i.e., land which does not have anything built upon it and which is not
appurtenant to a building is computed as follows: Value of open land under the
Reckoner * Weightage of user category * FSI permitted * Area of Land. The
weightage factor is given separately in Schedule A to the Rules for different
types of properties.


Valuation of Building / Flat

The Rules for valuing a
building / flat / premises for computing property tax are as follows:


(a) Capital Value of a Building / Flat is computed
as follows:  Value of building under the
Stamp Duty Ready Reckoner * Weightage of user category (depending upon whether
the building falls under Part II, III or IV of Schedule A) * Weightage for Age
of Building * Weightage for Floor factor for Lift * Carpet Area of Building.
The weightage factors are given separately in Schedule A for different types of
properties.


There are eight major steps
to using the Stamp Duty Ready Reckoner which are as follows:


(i)      Find out the Village Number and Village
Name in which the property is located;


(ii)      Ascertain the Zone and the Sub-Zone;


(iii)     Find out the CTS No. of the property;


(iv)     Determine the type of property, e.g.,
Residential, Office, etc.;


(v)     Calculate the Carpet Area of the Flat /
Office. Stamp Duty is paid on the basis of Built-up Area but for Property Tax
the Carpet Area is adopted;


(vi)     Find out the Market Value for the type of
Property;


(vii)    Ascertain if there are any Special Factors
as prescribed in the Reckoner;


(viii) The
Market Value of the Property for Stamp Duty purposes = Adjusted Fair Market
Value * Carpet Area of the Property

(b) The following are the weightages given while
valuing a building or a flat or office:


(i)  User category


(ii)  Nature and type of building~ weights have been
assigned for open terrace, dry balcony, porch, etc.


(iii) Age of building


(iv) Floor factor of building with Lift


For
instance, in the case of a residential building the Schedule provides some
weightages in the following manner:


User Category of Building weightage to reckoner
Rate (UC)

Nature and Type of Building weightage (NTB)

Weightage for Age Factor of Building (AF)

Weightage for Floor Factor (FF)

Residential
user 0.50

RCC
1.00

0-5
years 1.00

Car
Park basement 0.70

Five
Star Hotel 1.00

Pucca
Building 0.70

5-10
years 0.95

Ground
Floor 1.00

Factory
1.25

Semi
permanent Building 0.50

10-15
years 0.90

1st
-10th  Floor 1.00

Shops
and Commercial 0.80


15-20
years 0.85

11th
-20th Floor – 1.05


20-25
years+ 0.80

21st
-30th Floor – 1.10


31st
– 50th Floor – 1.15


(c) The formula for
computing the Capital value of a Building is prescribed as follows:


CV = BV *
UC * NTB * AF * FF * CA

Where

CV = Capital Value of a
Building

BV = Base Value of the
building as per the Stamp Duty Ready Reckoner

UC = User category of
residential, shop, open land, etc.

NTB = Nature and Type of
Building, i.e., RCC, semi-pucca, etc.

AF = Age Factor
Depreciation

FF = Floor Factor
Adjustment for Building with Lift

CA = Carpet Area

(d) Some examples of computation of the capital
value of a property is as follows:


Illustration
-1
: Carpet area of a Residential flat of 1000 sq.ft.on the 5th
floor of a RCC constructed building at Colaba. The building is 40 years old and
as per the Reckoner of 2015, it falls in Zone 1/3 where the rate for
residential building is Rs. 497,500 per sq. mt. The weightages of various
factors would be as follows:


Particulars


Weightage

Base
Value as per Reckoner (BV)

497,500

Carpet
area (CA)

1000 sq. ft / 92.90 sq. mt


Weightage
for User Category (UC)

Flat

0.50

Weightage
for Nature and Type of Building (NTB)

RCC Building

1.00

Weightage
for Floor Factor (FF)

5th -10th Floor

1.05

Weightage
for Age of Building (AF)

35-40 years

0.65


Thus, the Capital Value of
the Flat would be worked out as under:


497,500 * 0.50
*1.00*1.05*0.65* 92.90 =Rs. 1,57,71,807


On this Capital Value, the
Property Tax for a Residential property @ 0.359% would be Rs. 56,620 per year
or Rs. 4,718 per month.


Illustration-2:
Carpet area of an Office is 10,000 sq.ft. and is located on the 15th floor of a
RCC constructed building at Bandra Kurla Complex. The building is more than 10
years old and as per the Reckoner of 2015 it falls in Zone 31/72 where the rate
for an Office is Rs. 155,300 per sq. mt. The weightages of various factors
would be as follows:


Particulars


Weightage

Base
Value as per Reckoner (BV)

Rs.155,300

Carpet
area (CA)

10,000 sq. ft / 929.02 sq. mt.


Weightage
for User Category (UC)

Office

0.80

Weightage
for Nature and Type of Building (NTB)

RCC Building

1.00

Weightage
for Floor Factor (FF)

11th – 20th Floor

1.10

Weightage
for Age of Building (AF)

10-15 years

0.90


Thus, the Capital Value of
the Flat would be worked out as under:


155,300 * 0.80
*1.00*1.10*0.90* 929.02 =Rs. 11,42,67,230


On this Capital Value, the
Property Tax for an office property @ 0.880% would be Rs. 10,05,551 per year or
Rs. 83,796 per month.


Conclusion

The Capital value based
Property Tax system is based on the Ready Reckoner and hence, suffers from the
same flaws which the Reckoner is infamous for. However, a good part is that for
residential properties, only 50% of the reckoner rate is adopted. Nevertheless,
double rates for the same property, non-consideration of various factors, such
as, differences in areas / properties, condition of flats, etc., would
all apply even to this system.
 

CONSOLIDATION OF CSR TRUSTS UNDER Ind AS

Background

Many Indian corporates have set up
Special Purpose Not-for-Profit Entities (NFP) to undertake corporate social
responsibility (CSR) activities as required u/s. 135 of the Companies Act,
2013. The CSR activities are either undertaken by the Company directly or
through a charitable trust under The Indian Trusts Act, 1882, section 8 company
under the Companies Act 2013 or a society under the Societies Registration Act,
1860. The sponsoring company will provide adequate funds or donations to the
trust, society or the section 8 company so that it can carry out the relevant
activities as required under the Companies Act, 2013. A question arises as to
whether such NFP should be consolidated under Ind AS 110, Consolidated
Financial Statements
by the sponsoring company.


Under Ind AS 110, an investor
controls an investee and consequently consolidates it when it is exposed, or
has rights, to variable returns from its involvement with the investee and has
the ability to affect those returns through its power over the investee. Thus,
an investor controls an investee if and only if the investor has all the
following:


(a) Power
over the investee,


(b) Exposure,
or rights, to variable returns from its involvement with the investee, and


(c) The
ability to use its power over the investee to affect the amount of the
investor’s returns.


Arguments supporting consolidation of the
NFP

Following are the arguments
supporting consolidation:


  • Under Ind AS 110, variable returns are seen more broadly, and
    will include exposure to loss or expenses from providing funds, donation,
    credit or liquidity support and intangible benefits on reputation and image
    from good governance practices. By hand-picking the members of the governing
    body of the NFP, the sponsor of the NFP ensures that it has power over the NFP
    either explicitly or implicitly. Using these powers, the sponsoring company
    ensures that the NFP undertakes the desirable CSR activity, which meets its compliance
    and other needs.


Ind AS 110 does not apply to
post-employment benefit plans or other long-term employee benefit plans to
which Ind AS 19, Employee Benefits, applies. However, there are no such
exemptions for NFPs. Moreover, the accounting for long term employee benefit
plans under Ind AS 19 effectively recognises the net assets and liabilities of
the Trust, i.e., the net defined benefit liability (asset) is determined after
taking into account the fair value of the plan assets and the relevant disclosures
are included in the separate financial statements and CFS of the company.


The NFP is controlled by the
sponsoring company for its own benefit and is not specifically exempted from
preparing CFS. Hence, an NFP should be consolidated.


  • CSR activities prior to the Companies Act, 2013 were undertaken
    voluntarily. After the Companies Act, 2013, it has also become a
    quasi-mandatory requirement. If a company does not spend on CSR, as required by
    the Companies Act, 2013 it has to make appropriate disclosures in the
    Director’s report. There are numerous activities a company has to undertake for
    the purposes of complying with the various laws of the land. The cost of all
    such compliance activities are included in the separate and consolidated
    financial statements (CFS). Since CSR is a cost incurred to conduct business in
    the country as required by legislation, it should be included and consolidated
    in the financial statements. The NFP is merely an extension of the Company
    created to ensure compliance with the Companies Act, 2013. A company that
    undertakes CSR activities directly would have in any case included the CSR
    spend in its separate financial statements and CFS. Whether the CSR activities
    are under taken directly or through a trust, society or company, the outcome
    with respect to financial statements should be the same.


  • Even in cases, where the CSR activity is not linked to compliance
    but is undertaken for altruistic purposes, consolidation will still be
    required. This is because in such cases, for reasons already described above,
    the company has an exposure to variable returns in the form exposure to loss
    from funding or providing liquidity support for running the CSR entity. In
    addition, there will be intangible returns by way of enhancement or damage to
    reputation and image.


Conclusion

The
author believes that the NFP created for CSR activities should be consolidated
in accordance with the requirements of Ind AS.

PENALTIES : TO ERR IS HUMAN – IS GST HUMAN?

Payment of taxes is considered a
civil obligation and breach of such obligation results in penal
consequences.  The nuances of a duly
enacted statute provide the contours under which the taxes need to be
discharged and penal provisions accompany such legislations for its effective
enforcement.  Yet, it is well known that
no statute is enacted with an object to impose penalties. Rather, they are
intended to operate as a deterrent to violating of any provision. Courts have
frequently held that penalty is imposed only in cases of contumacious conduct
by the tax payer. The GST enactment is no different and this resonates from the
Statement of objects and reasons placed before the Parliament while introducing
the Central Goods & Services Tax Bill, 2017:


“…. (i) To make provision for
penalties for contravention of the provisions of the proposed legislation … ”


Practical experiences depict a
contrasting picture. One would have experienced tax administrators (both Centre
and the State) applying the penal provisions mechanically without appreciating
the purpose and instances for which penal provisions are enacted. The following
statements are a common feature in show cause notices and adjudication orders:


“Assessee has intentionally
contravened the provisions of the Act and hence liable for penalty …;
suppressed this information from the revenue with an intention to evade tax
payment….; deliberately avoided the payment of taxes knowing fully well that
the transaction is taxable;….”


Not a single order goes without
imposition of penalty even in cases where the tax demand is under debate at
higher forums. All the tax payers are painted by a single brush leading to
undesirable litigation. Sometimes, administrative authorities do not even
consider it necessary to state that penalty is being imposed and one is
enlightened about the imposition only from the demand notice or computation at
the end of the order. There is a tendency to invoke and adjudicate the penalty
merely by a stroke of a pen, leaving the battle to be fought by the assessee.
Though, Courts have time and again held that penalty is not an ‘additional tax’
rather ‘an addition to the taxes collected’, this starking difference has been
ignored by tax administrators. With this foreward, we have examined the penal
provisions under the CGST law in the subsequent paragraphs:


General Principles of Penalty


Certain principles set down by Courts
while dealing with matters on penalty have been enlisted below:


    Penal
provisions should be strictly construed without much play. Yet, one should
ensure that the constructions fall within the contours of its Statute.


    There
has been considerable debate on whether mensrea is an essential
requirement for imposition of penalty towards civil offences. While it is
certainly clear that mensrea need not always be proved for
penalty, the statutory provisions should be examined to reconcile this debate:
(a) examine the statutory provisions for any express or implied requirement of
a guilty mind (such as use of the phrases like suppression, concealment, etc.
have an inbuilt requirement of mens-rea to be established); (b) identify
if the penalty has been intended to be a civil offence or a criminal offence
since the requirement of mens rea in civil offences is comparatively
lower than in criminal offences; and (c) once the requirements of the
provisions have been met, there is no discretion with the officer over the
quantum of penalty for such offence or referring back to the presence or
absence of mens-rea

    The
road to all assessments need not necessarily end with penalty. Though every tax
evasion arises out of non-payment, every non-payment should not be equated with
tax evasion. It has been famously cited that penalty should not be imposed
merely because one has been empowered to do so.


    The
onus is on Revenue to establish that the circumstances warrant imposition of
penalty. Only when this onus is effectively discharged that the tax payer is
required to defend his/her bonafide. Mere suspicion / surmises cannot form the
ground for penalty. Evidences and actions should be placed on record.


    Penalty
should be invoked under a specific clause/ provision and expressly stated out
in the notice/ order. The tax payer cannot be left to search for the provision
under which he/she has been penalised (Amrit Foods vs. CCE, UP 2005 190 ELT
433 (SC)
).


    Penalty
invoked under clause (a) cannot be upheld under clause (b). The grounds of
invoking penalty and upholding the same would have to be reconcilable.


    Penalty
should be commensurate with the tax involved. 


    Unequals
should not be treated as equals. A mala-fide tax payer and bonafide tax payer
cannot be saddled with same quantum of penalty merely on the ground of non-payment.


    Penalty
cannot be imposed for a future action on the theory of possibilities.


    One
cannot be penalised retrospectively, even in retrospective legislations. Penal
provisions prevailing on the date of offence should be applied.


    If
two reasonable views are possible or in cases of ambiguity, the lineal
construction should be adopted.


Statutorily recognised principles
of penalty (section 126)


The CGST / SGST law for the first
time has penned down certain disciplines for imposition of penalty. These are
principles from settled judicial decisions in the context of penalty:


   Minor
breaches (Tax effect < Rs. 5000) or omission in documentation without
fraudulent intent should not be subjected to penalty.


   Penalty
should be commensurate with the degree and severity of breach.


   Prior
notice and personal hearing should be granted prior to imposing penalty.


   Order
imposing penalty should be speaking about the nature of breach and the
applicable provision under which the penalty is being imposed.


   Voluntary
disclosure prior to discovery of breach of law should be dealt with leniency.


However, this section has given
limited applicability only to penal provisions where a fixed quantum or fixed
percentage has not been prescribed i.e. cases where discretion has been
bestowed upon the officer over the quantum of penalty.


Examination of legal provisions –
Scheme of Penalty under the GST law


The GST Law has elaborately spread
the provisions for penalty across various Chapters. Principally, penalties can
be classified into those which are imposed based on findings on the merits of
the issue in the course of adjudication proceedings (sections 73 and 74) and
those penalties which can be imposed by the proper officer independent of the
adjudication proceedings (broadly similar to that followed in Income tax) by
issuing a separate order i.e. once the ingredients of the respective penal
provisions are satisfied (section 127). There is also a third set of penalties
imposable in cases of goods in transit or evasive acts where goods are liable
for confiscation. On a reading of the entire set of penal provisions, there
appears to be a significant amount of overlap between provisions leading to
multiple touch points for an officer to invoke for imposing penalty.


The overall scheme of penalty has
been depicted in the following chart. In simplistic terms, section 127 r/w
section 73, 74 and 129/130 has carved out three broad pillars on the basis of
which penalty can be imposed.


General understanding of key
terminologies


Prior to examining the above scheme in detail, it is important to
examine the meaning of some terms used in these sections, to be applied
contextually under respective facts and circumstances only:


Term

Understanding
as per Black’s law dictionary and other sources

Offence

A violation of the law; a
crime, often a minor one.

Non-compliance

Failure or refusal to
comply.

Opposite – Compliance- The acting in accordance with a
desire, condition etc.

Contravention

An act of violating a legal
condition or obligation

Fraudulent/ Fraud

Fraud- A known misrepresentation or concealment of a
material fact made to induce another to act to his or her detriment


Fraudulent- Conduct involving bad faith, dishonesty, a lack
of integrity, or moral turpitude


Other legal sources


Mere omission to give
correct information is not suppression of facts unless it was deliberate to
stop the payment of duty. Suppression means failure to disclose full information
with the intent to evade payment of duty. When the facts are known to both
the parties, omission by one party to do what he might have done would not
render it suppression

Suppression

GST law – Explanation 2 to
section 74 defines suppression as ‘non-declaration of facts or information
which a taxable person is required to declare in the return, statement,
report or any other document furnished under the Act or failure to furnish
any information asked by the proper officer

False/Falsifying document

False – Untrue, Deceitful; lying. Not genuine,
inauthentic


Falsifying a record – The crime of making false entries or otherwise
tampering with a public record with the intent to deceive or injure, or to
conceal wrong doing


Other Sources:


“Erroneous, untrue, the
opposite of correct, or true. The term does not necessarily involve turpitude
of mind. In the more important uses in jurisprudence the word implies
something more than a mere untruth; it is an untruth coupled with a lying
intent, or an intent to deceive or to perpetrate some treachery or fraud.


“In law, this word usually
means something more than untrue; it means something designedly untrue and
deceitful, and implies an intention to perpetrate some treachery or fraud”

Tampering/ destroying

Tampering– The act of altering a thing; esp., the act of
illegally altering a document or product, such as written evidence or a
consumer good.


Destroying– To damage something so thoroughly as to make
unusable, unrepairable or non-existent; to ruin.

Tax evaded

The willful attempt to
defeat or circumvent the tax law in order to illegally reduce one’s tax
liability.

Detention

The act or an instance of
holding a person in custody; confinement or compulsory delay.


Not allowing temporary
access to the owner of the goods by a legal order/notice is called detention.
However the ownership of goods still lies with the owner. It is issued when
it is suspected that the goods are liable to confiscation.

Seizure

Seizure is taking over of
actual possession of goods with right of disposal for recovery of dues by the
department in case of perishable / highly depreciable goods. Seizure can be
made only after inquiry/investigation that the goods contravened provisions
of the Act. Title continues with the supplier-owner.

Confiscation

Confiscation of the goods is
the ultimate act after proper adjudication. Once confiscation takes place,
the ownership as well as the possession forcefully goes out of the hands of
the original owner and into the hands of the Government Authority.


A)      Adjudication related
penalties (section 73 and 74)


Under the erstwhile scheme, penalty
(u/s 11AC of the Central Excise Act and 78 of the Finance Act) and extended
period of limitation emanated from a common trigger point i.e. fraud,
suppression, etc (prior to amendment by Finance Act, 2015). In cases where
extended period of limitation was dropped, penalty could not be imposed even in
respect of the normal period. In a particular case penalty was dropped even
though extended period of limitation was invoked against the assessee[1]. This
position was altered by Finance Act, 2015 where penalty was imposed even in
respect of cases not involving fraud, suppression, etc albeit at lower scale.
The amendment prescribed various scales of penalty for short payment depending
on the reasons for such non-payment. The GST law has toed the line prevalent
after the 2015 amendment and delinked both the concepts resulting in penalty
being imposable even for bonafide acts.


Section 73 (normal period
assessments) and 74 (extended period assessments) are parallel to the
adjudication provisions of section 73 of the Finance Act, 1994 and section 11A
of the Central Excise Act, 1944. The said provisions empower the proper officer
to initiate adjudication proceedings in cases of short payment/ non-payment,
irregular input tax credit and erroneous refund. During the course of such
proceedings, the proper officer would have an opportunity conclude on the
reasons for non-compliance by the tax payer and classify the cases on the basis
of intent.


The penalty would be imposed in the
order issued under the said section depending on the stage at which the tax
payer makes the payment of the taxes demanded. The important take aways from a
reading of the said provisions are:


1)  Penalties
provided under the said section are absolute without much discretion being
granted to the proper officer on the quantum of penalty.


2)  There
is no provision parallel to the erstwhile section 80 of the Finance act, 1994
wherein officers were granted powers to waive the penalty if ‘reasonable cause’
is shown by the tax payer.


3)  Penalties
are directly linked to the alleged revenue loss to the respective Government.


4)  Imposition
of penalties under these section are subject to an outer time limit of 3-5
years from the relevant date (due date of filing the annual return).


B)  Non-adjudication related
penalties (section 122 to section 128)


Chapter XIX of the CGST/ SGST law –
‘Offences and penalties’ is a code for imposition of penalties in specific
cases. The said penal provisions u/s. 122 to 128 have been structured to lay
down the triggers for penalty in enlisted cases including detention and
confiscations. Under section 127, these penal provisions would apply only where
the proceedings of sections 62, 63, 64, 73, 74, 129 and 130 do not impose
penalty. The said provisions are as follows:

Section 122(1) – Specific Penalties

This section provides for 21
instances when penalty can be imposed on the tax payer. On a reading of certain
clauses, it appears that the law makers have targeted the issues at a micro
level in many cases.  The section 122(1)
can be divided into two sub-parts for a better understanding:


   Part A : Enlists the
triggers for penalty; and

   Part B : Prescribes the
penalty for the enlisted circumstances as follows:


Ad-hoc penalty : 10,000 being the
bare minimum penalty;

(OR)

Proportionate penalty : 100%
penalty to tax evaded; tax not deducted/ collected; short-collected
or not paid
; input tax credit availed or passed on or distributed
irregularly or refund claimed fraudulently whichever is higher.


A clause by clause analysis of
section 122(1) has been tabulated below. In the table the author has
categorised the possible reasons underlying a non-compliance into – (a)
clerical errors generally considered as bonafide; (b) interpretative in view of
ambiguity in law and deemed as bonafide; and (c) evasive where it is
intentional.


Clause

Trigger
of penalty

Some
examples

Attributable  reasons

Possible
Quantum

(i)

Supply without invoice or
incorrect or false invoice

Clandestine removal

Evasive

10000 or 100% penalty


Human error of not raising
valid invoice

Clerical

10000


Ambiguity in continuous
supply of services/ goods

Interpretative

10000

(ii)

Invoice issued without
supply of goods/ services

Bill Trading

Evasive

10000 or 100% penalty


Invoice issued but goods not
removed

Clerical

10000

(iii)

Collected any tax but fails
to pay within 3 months[2]

Collected and failed to pay

Evasive

10000 or 100% penalty


Failed to include in
GST-3B/1 due to mistake though accounted liability in books of accounts

Clerical

10000

(iv)

Collection in contravention
of the law coupled with failure to pay within 3 months

Tax collected on exempted
goods and not recorded in accounts

Evasive

10000 or 100% penalty

(v) & (vi)

Fails to deduct or collect
tax or after such deduction or collection failed to pay this entire amount

Tax collected on exempted
goods and not recorded

Evasive

10000 or 100% penalty

(vii)

Takes or utilises input tax
credit without actual receipt of goods/ services

Accommodation bills

Evasive

10000 or 100% penalty

(viii)

Fraudulently obtains refund

Falsifying ITC claims

Evasive

10000 or 100% penalty

(ix)

Takes or distributed input
tax credit incorrectly

Falsifying ITC claims

Evasive

10000 or 100% penalty


Incorrect distribution
formula applied

Interpretative

10000


Formula error

Clerical

10000

(x)

Falsifies or substitutes
financial records with intent to evade taxes

Forgery

Evasive

10000 or 100% penalty

(xi)

Fails to obtain registration

Clandestine supplies

Evasive

10000 or 100% penalty


Incorrectly ascertains the
location of supplier

Interpretative

10000

(xii)

Furnishes false information
in respect of registration

Fictitious address

Evasive

10000 or 100% penalty

(xiii)

Obstructs or prevents any
officer

Fails to unlock a godown on
demand

Considered evasive

10000 or 100% penalty

(xiv)

Transports without
appropriate documentation

E-way bill not raised

Clerical

10000


Clandestine supply

Evasive

10000 or 100% penalty

(xv)

Suppresses turnover

Clandestine supply

Evasive

10000 or 100% penalty

(xvi) & (xvii)

Fails to maintain
appropriate records/ information or furnishes false information

Non-submission of inventory
records

Clerical

10000

Non-maintenance

Clerical

10000

False data

Evasive

10000 or 100% penalty

(xviii)

Supplies, transports or
stores any goods liable for confiscation

Clandestine goods

Evasive

10000 or 100% penalty

(xix)

Issues invoice by using
another registered person’s number

Fraud

Evasive

10000 or 100% penalty


Wrong GSTIN of same entity
used

Clerical

10000

(xx)

Tamper material evidence

Fraud

Evasive

10000 or 100% penalty

(xxi)

Tampers with goods under detention

Fraud

Evasive

10000 or 100% penalty


The following observations emerge
from the above tabulation of examples:


1)  Prima-facie,
the clauses seem to address all types of non-compliance and not just tax
evasion


2)  Evasive
action is omnipresent in every clause, either impliedly or expressly


3)  Interpretative
or clerical non-compliance seems to be missing in cases where phrases such as
fraudulent, tampering, falsification, etc are present


4)  The
chapter title and section title use the phrase ‘Penalty for certain offences’
indicating that the section is addressing unacceptable defaults or defaults
having the ingredient of a gross violation which is non-curable resulting in
revenue law


5)  In
certain cases, proportionate penalty on the basis of ‘tax evaded’ would not be
ascertainable resulting in a situation where there is no comparative to the
adhoc penalty of Rs. 10,000. This throws up two alternative theories:


(a) Section
122 only addresses actions involving tax evasion and not every non payment
(such interpretative / clerical cases); or


(b) Section
122 addresses both cases, but in cases where there is no evasive action, the
penalty imposable for any default is limited to Rs. 10,000


The questions emerging from the
above table are:


Q1 – Whether 21 clauses are
mutually exclusive to each other?


Section 122(1) contains cases which
could fall under more than one clause eg. supply without invoice (clause (i))
and suppression of turnover (clause (xv)). An assessee could be penalised under
either of the clauses – for example transport of goods without invoice would
trigger both clause (i) and (xiv). Though clauses are overlapping, the tax
payer can be imposed with penalty only under one of the clauses for the same offence.


Q2 – Does the prescription of
adhoc and proportionate penalty apply to each of the clauses or only to
specific clauses? In other words, does penalty proportionate to tax evasion, etc. apply to all cases of tax evasion
(express or implied) or only to cases where the clauses specifically use the
phrase ‘tax evaded’.


The provisions of section 122(1)
targets actions which are evasive impliedly and expressly. One argument could
be that the proportionate penalty applies only to cases where tax evasion is
specifically expressed in the clause (such as (x), (xv), etc.). Similar
phrases accompanying the proportionate penalty such as tax short deduction/
collection, input tax credit irregularly availed, refund fraudulently availed
are directly relatable to specific clauses. Since accompanying phrases are
directly relatable to a specific clause(s), the prescription of proportionate
penalty on tax evasion should also apply to specific clauses only.


However, the other argument would
be that once tax evasion has been established, proportionate penalty can be
imposed on the tax evaded irrespective of there being an express prescription
of tax evasion in the clause. Tax evasion is inbuilt in the manner in which the
clauses are worded (such as (i)). The above table depicts that every clause
seems to capture an evasive act even though the term tax evaded has not been
expressly spelt out. The intent of this provision is to address cases of tax
evasion with rigorous penalty equalling the amount of tax evaded. This is the
only way full force may be given to
section 122(1), else the said provision may become a toothless tiger. 


Q3 – If the ingredients of tax
evasion have limited applicability, what would be the comparative figure to Rs.
10,000 in cases where the 100% penalty does not apply ?


For eg, if a tax payer issues an
incorrect invoice of Rs. 100,000 taxable @ 18% citing a wrong place of supply,
would one have to compare Rs. 10,000/- and Rs. 18,000 for imposition of penalty
or one can claim that there being no tax evasion, penalty of only Rs. 10,000/-
can be imposed? The answer to this question is dependent on the tax position
adopted on the scope of section 122(1). In cases where the scope of section
122(1) is considered as only addressing ‘offences’ and not all tax
non-compliance, no penalty can be imposed for clerical/ interpretative reasons
as cited in the above case. But where a stand is taken the section 122(1)
extends beyond cases of tax evasion, then a purposive effect to this stand can
be given as follows:


This chart implies that in non-tax
evasion cases, in the absence of a comparative figure, one should consider the
same as zero and then make a comparison leading to the inevitable conclusion
that Rs. 10,000/- would be the applicable penalty. Therefore, in case of a
wrong place of supply, the tax payer may be subjected to a maximum penalty of
only Rs. 10,000/-.  This is the only
possible interpretation where penalty for substantive and procedural defaults
can be given effect to.


In summary, the reasonable
interpretation of section 122(1) would be it primarily addresses cases of tax
evasion / tax non-deduction etc. and every clause addresses cases of tax
evasion either expressly or impliedly. Hence, equal penalty can be imposed on
the tax payer irrespective of which clause the case falls under. Section 122(1)
does not have any applicability over procedural/ non-evasive defaults. But if
one were to still extend this provision to procedural defaults, the penalty
imposable would only be Rs. 10,000/-.


Section 122(2) – Tax liability/ refund related penalties


Section 122(2) – This section
provides for two levels of penalty depending on the reasons for non-payment.
The said section has recognised that mens-rea/ state of mind would
establish the gravity of the offence and hence the quantum of penalty. Unlike
section 122(1), the law makers have targeted the non-payment at a macro level
purely on the test of whether there is a short payment of tax to the exchequer
and have not listed down actions resulting in such short payment:


Any reason other than fraud

10,000 or 10% of the tax due whichever is higher

The clause specifically uses
the phrase tax due rather than tax evaded

Fraudulent reason

10,000 or 100% of the tax evaded
whichever is higher


Section 122(2) provides some
inferences as to interpretation of section 122(1) as well as 122(2):


1)  Section
122(2) captures all cases of non-payment of tax and imposes a basic penalty of
10% of tax due which can jump to 100% in fraud cases.


2)  Though
section 122(2) does not use the term ‘intent to evade’, it is implied by use of
the phrases – fraud, wilful misstatement, suppression, etc.: tax evasion
is always malafide and one cannot evade taxes without having the
intention to do so.


3)  Use
of the expression ‘tax due’ in section 122(2) and tax evaded in section 122(1)
clearly establish the distinct domains that each of the clauses address.


4)  Section
122(2) is general in its scope and presence of specific clauses in section
122(1) may exclude them outside the scope of section 122(2).

5)  Proportionate
penalty u/s. 122(1) is at the same scale as that applicable to fraudulent
actions specified u/s. 122(2)(b). By this interpretation, the first theory over
section 122(1) is strengthened. The legislature would not have in its wisdom
treated non payment for clerical errors at par with those due to evasive acts
u/s. 122(1). It has therefore provided a reduced penalty of 10% or Rs. 10000
only to cases where the penalty is not on account of fraud, etc. and
section 122(1) does not extend its scope over clerical / interpretative
defaults.


Reconciling section 73/74 and
section 122(2)


Section 122(2) seems to be a close
replica of the penal provisions contained in section 73 and 74. Legal
provisions should not be out rightly held to be surplusage. The possible
reconciliation of this overlapping could be:


a.  Section
122(2) provides an outer boundary / parameters under which penalty can be
imposed and section 73/74 operate within this confine.


b. Section
73(1) states that penalty would be imposed ‘under the provisions of this Act’,
possibly hinting at section 122(2). Section 73 and 74 grant concessions in
cases of early tax payment along with interest and penalty promoting dispute
resolutions and amicable settlement between the tax payer and the Government.


c.  Section
127 which seems to be creating two separate branches is only a surrogate
section. Its role seems to empower the officer to play catch-up by imposing
penalty even if the same has not been imposed under adjudication proceedings;
this section by itself does not make section 122(2) mutually exclusive to
section 73/74.


Section 122(3) – Other Penalties

Section 122(3), provides for
ancillary circumstances or connected persons where penalty of Rs. 25,000 can be
imposed:

    Transporters,
employees, tax professionals, chartered accountants, purchaser of goods, tax
officials, etc. accompanying the assessee, who aid or abet an offence
could also be saddled with a penalty.

    Any
person who acquires or receives goods or services with knowledge that such
receipt is in contravention of provisions of the Act (for eg. procuring a
taxable services/ goods from an unregistered person for more than 20 lakhs in
aggregate in a financial year).

    Failure
to appear or issue invoice or account such invoice in book of accounts.


Section 122(3) also validates the
position that clerical actions which results in tax dues cannot be covered in
section 122(1) since clerical defaults have a fixed penalty of Rs. 25,000 only.


Section 125 – Miscellaneous penalty not specific elsewhere


Penalty of Rs. 25,000 in cases
where no penalty has been prescribed for a contravention of the act or the
rules.


Section 129 – Penalties in case of detention, seizure of goods in
transit


The GST law provides for imposition
of penalties for movement of goods which are in contravention of the statutory
provisions. The said provisions are non-obstante in nature. Two levels
of penalties are prescribed herein:


(a) Owner
comes forward for payment of tax and penalty: Penalty of 100% of the tax
payable or 2% of value of exempted goods or Rs. 25,000 whichever is less.


(b)        Owner
does not come forward for payment of tax and penalty : Penalty of 50% of
taxable value of goods or
5% of value of exempted goods or Rs. 25,000 whichever is less.


Two primary ingredients are
required for invoking penalty under this section –(a) the goods should in
transit and are intercepted by the proper officer u/s. 68; and (b) the proper
officer should come to a conclusion that the movement of goods is in
contravention of the provisions of the Act.


It may be important to note that
this section is qua the goods under question and not the transaction
i.e. this section applies equally to transactions having the character of
‘supply of goods’ or ‘supply of services’ in terms of Schedule II to the law as
long as there are goods in movement, for eg. a works contractor engaged in
supply of services (exempted/ taxable) attempting movement of goods would still
fall under this section for production of delivery challan and e-way bills. The
possible areas of contravention could be:


Examples of cases involving
evasion

Examples of cases not
involving evasion

  Presence / validity e-way bill accompanying
the consignment

  Non-accompanying invoice/ delivery challan

  Variance in the physical and invoiced
quantity

  Prima-facie variance in description of physical goods and
that stated on invoice

  Clear diversion of goods to unreported
locations

  Non-reporting all details in e-way bill/
invoice/ delivery challan

  Failure to seek extension of e-way bill on
expiry

 Incorrect reporting of details in e-way bill
eg.
prima-facie
place of supply being in direct contradiction with address

  Supply of goods reported as supply of
services


Generally, the term ‘contravention’
is used in cases where severity of non-compliance is relatively high compared
to a procedural non compliance. For example, a person raising the e-way bill
fails to update the correct vehicle number on account of clerical reasons and a
person consciously conceals revealing details of the vehicle number ensure
multiple trucks use the same e-way bill. While both have failed to comply with
the law in letter, rationally the degree of the offence and the penalty should
be higher in the case of the latter rather than the former. The law cannot
treat unequals as equals. Given the quantum of penalty, it appears that this
section is only towards addressing revenue loss and not procedural/ clerical
defaults. Applying this intent, a person complying with the law but erring in
reporting the vehicle number should not be saddled with penalties of the
magnitude as prescribed in the section. 


Further, the terms ‘detention’ or
‘seizure’ when used on conjunction imply severe cases of non-compliance. As
tabulated earlier, detention followed by seizure forcefully restricts the right
of possession of goods from its original owner. It breaches the right in rem
over the goods of its owner. In a welfare state, this is usually done where the
gravity of the offence is high and not otherwise. One can take a stand that
this section can be applied only to substantive offences where the owner of the
goods has escaped payment of taxes.


However, very recently, the Madhya
Pradesh High Court in Gati Kintetsu Express Pvt Ltd vs. CCT of MP
(2018-TIOL-68-HC-MP-GST)
held that Part B of e-way bill is mandatory
and non-compliance of this requirement is amenable to penalty u/s. 129 of the
CGST/ SGST law. The court incorrectly distinguished an earlier favourable order
in VSL Alloys (India) Pvt Ltd vs. State of UP (2018) 67 NTN DX 1
which held that penalty cannot be imposed in case where Part-B of the eway bill
was
not completed.


This section also imposes penalties
on exempted goods with reference to its value upto a maximum of Rs. 25,000.
Impliedly, it equates the offence with a procedural violation since they do not
have any tax revenue impact. But ‘exempted goods’ should not be equated with
exempted supplies. The term exempted goods should be understood on a standalone
basis de-hors whether the transaction under question is enjoying any
benefit under Notification 12/2017-Central Tax (Rate). 


Section 130 – Confiscation of goods/ conveyance


Section 130 are penal provisions
invoked as a consequence of either an inspection or interception activitiy. The
instances where this section can be invoked are enlisted below:


1) Undertakes
supply or receipt of goods in contravention of any legal provision with
malafide intent to evade tax – for eg. clandestine removal of goods from
premises or even receipt of goods by the fraudulent buyer.

2) Fails
to account for the goods which are liable for tax – unaccounted sales.

3) Supplies
goods without having any registration or even applying for the same.

4) Contravention
of any provision with intent of evasion of payment of tax.

5) Conveyances
used for illegal activities with connivance of the owner of such conveyance.


The provisions impose penalty or
fine (also called redemption fine) in lieu of confiscation (i.e. for release of
goods). However, in no case will the aggregate of penalty and fine be less than
the market value of goods. In case of confiscation of conveyance along with the
goods, the quantum of fine in respect of the conveyance would be equal to the
tax payable on the goods under transportation. This section applies without
prejudice to the imposition of tax, interest and penalties.


In summary, the possible comparatives between the three pillars
can be tabulated below:

Parameter

Section
73/74

Section
122-128

Section
129 & 130

Type

Transactional penalties

Behavioural penalties

Behavioural but specific to
goods

Source

Books of accounts/ audit, etc.

External information

Interception/ Inspection

Timing of the proceeding

Post-mortem analysis

No specific timing

Real time while in
possession of goods

Time Bar

3/5 years

No specific time bar

Until goods in transit/
possession

Waiver/ Discretion over
quantum

No discretion once
ingredients satisfied

No discretion once
ingredients satisfied

Discretion over imposition
but not quantum except in section 130 where there is a discretion on quantum

Exempted Transactions

NIL

Upto Rs. 10,000/- or
25,000/-

Rs. 10,000/-

Procedure

Part of adjudication
proceedings

Independent of adjudication

Part of enforcement/
vigilance activities

Strength of Evidence

Medium

High

High

Onus

Revenue

Revenue

Revenue

Penalty type – Specific over
general

Specific

Relatively general

Highly Specific

Independent appeal/ linked
to adjudication

Part of adjudication

Independent

Independent

Impost on

Tax payer

Tax payer and accompanying
persons

Owner/ Transporter


In a self-assessment scheme, the
onus of accurate tax computations, reporting and payments lie on the tax payer.
In an era where disclosures are of paramount importance, the tax payer is
expected to disclose as much detail as possible to its officers and establish
its bona fide before courts in subsequent proceedings. Ideally, disclosure to
the officer exercising administrative jurisdiction over the tax payer would be
regarded as sufficient proof of bona fide.


On the other side, tax
administrators should appreciate that unlike taxes, penalty provisions should
be studied on a factual basis rather by a strait jacket formula. Any
subjectivity would deliver adversarial results and everyone expects that the
current order undergoes a shift under the GST law.


[1] Sree Rayalaseema Hi-Strength Hypo
Ltd vs. CC Ex, Tirupathi, 2012 (278) ELT AP 167

[2] Twin condition of collection and 3
months from due date of payment should be compulsorily satisfied for this
clause to apply

PROVISIONS OF TDS UNDER SECTION 195 – AN UPDATE – PART II

In Part I of the Article we have
dealt with overview of the relevant provisions relating to TDS u/s. 195 and
other related sections, various aspects and issues relating to section 195(1),
section 94A and section 195A.


In this part of the Article we are
dealing with various other aspects and applicable sections.


1.     Section
195(2) Application by the Payer


Section 195(2) of the Act reads as
under:


“195(2) Where
the person responsible for paying any such sum chargeable under this Act (other
than salary) to a non-resident considers
that the whole of such sum would not be income chargeable in the case of the
recipient
,
he may make an application to the Assessing Officer to
determine, by general or special order, the appropriate proportion of such sum so chargeable, and upon
such determination, tax shall be deducted under sub-Sec (1) only on that proportion
of the sum which is so chargeable.


1.1     It is important to note that no specific
rule or form has been prescribed under the Income-tax Rules, 1962. The
application has to be made on a plain paper / letter head.


1.2     An issue often arises as to whether an
application can be made u/s. 195(2) for ‘nil’ withholding order.


The judicial opinion is divided on
the issue. In the following cases it has been held that an application can be
made u/s. 195(2) for ‘nil’ withholding order:

   Mangalore Refinery and Petrochemicals Ltd.
vs. DDIT 113 ITD 85 (Mum)


   Van Oord ACZ India (P.) Ltd. [2010] 323
ITR 130 (Del.)


However, a
contrary view has been taken in the following cases:

   GE India Technology Centre (P.) ltd.
[2010] 327 ITR 456 (SC)

   Czechoslovak Ocean Shipping International
Joint Stock Company vs. ITO 81 ITR 162 (Cal)

   Graphite Vicarb India Ltd. vs. ITO 28 TTJ
425 (Cal) (SB)

   Biocon Biopharmaceuticals (P.) Ltd. vs.
ITO IT 36 taxmann.com 291 (Bang)
.


It appears that in practice,
application u/s. 195(2) is used for both ‘nil’ as well as ‘lower’ TDS rate
order.


1.3     Another question arises as to in case a
work involves multiple phases, in such scenario, is it sufficient if order u/s.
195 is obtained for phase I of the work or whether order is to be obtained for
all the phases of the work. In Mangalore Refinery and Petrochemicals Ltd.
vs. DDIT 113 ITD 85 (Mum)
it has been held that the payer should apply
fresh and obtain order for all phases of the work.


1.4     Whether order u/s. 195(2) of the Act is
subject to revision u/s. 263 by the PCIT or CIT. It has been in the case of BCCI
vs. DIT (Exemption) [2005] 96 ITD 263 (Mum)
that order u/s. 195(2) of the
Act is subject to revision
u/s. 263.


1.5     An important point to be kept in mind is,
order u/s. 195(2) are not conclusive and the Assessing Officer (AO) can take a
contrary view in the assessment proceedings. This has been held by the Bombay
High Court in the case of CIT vs. Elbee Services Pvt. Ltd. 247 ITR 109 (Bom).


1.6     Section 195(2) does not
prescribe any time limit for passing order u/s. 195(2). The Citizens Charter
2014 prescribed that decision on application for no deduction of tax or
deduction of tax at lower rate should be taken in 1 month. However, in
practice, such orders take longer time.


1.7     It has to be noted that application u/s.
195(2) cannot be made for Salary payment.


1.8     Appeal under section 248


a)  It is important to note that an order
u/s.195(2)/(3) is appealable, under a separate and specific section under the
Act.


b) Section 248 of the Act reads as follows:


“Appeal by a person denying
liability to deduct tax in certain cases.


248.   Where under an agreement or other
arrangement, the tax deductible on any income, other than interest,
under section 195 is to be borne by the person by whom the income is payable,
and such person having paid such tax to the credit of the Central
Government, claims that no tax was required to be deducted on such income,
he may appeal to the Commissioner (Appeals) for a declaration that no
tax was deductible on such income.”


c)  Section 248, as amended by the Finance Act,
2007 read with section 249(2)(a) provides for an appeal
u/s. 195, subject to fulfillment of following conditions:


i.   The tax is deductible on any income other
than interest;


ii.  Only if the tax is to be borne by the payer
under the agreement or arrangement. If tax is borne by the payee, a payer
cannot file an appeal u/s. 248 of the Act.


iii. The payer has to first pay the tax to the
credit of the Central Government;

iv. The appeal has to be filed within 30 days of
payment of tax [section 249(2)(a)].


d) It has been held that liability of TDS can be
appealed before CIT(A) u/s. 248 even without order from AO. CMS (India)
Operations & Maintenance Co. 38 taxmann.com 92 (Chennai).


2.     Section
195(3), (4) and Section 197 – Application by Payee


2.1     Section 195(3), (4) and section 197 of the
Act apply in respect of application for lower or nil deduction of tax under
specific circumstances and on fulfillment of certain prescribed conditions. The
distinctive features of the aforementioned provisions are discussed below.


2.2     The text of the section 195(3), (4) and
section 197 is given for ready reference and better appreciation of the
distinct language and purposes of the said sections, which relates to
application by the payees for lower or nil deduction of tax at source.


Section 195(3)
“Subject to rules made under sub-section (5),
any person entitled to receive any interest or other sum
on which income-tax has to be deducted under
sub-section (1) may make an application in the prescribed form to the Assessing
Officer for the grant of a certificate authorising him to receive such interest
or other sum without deduction of tax
under that sub-section, and where any
such certificate is granted, every person responsible for paying such interest
or other sum to the person to whom such certificate is granted shall, so long
as the certificate is in force, make payment of such interest or other sum
without deducting tax thereon under sub-section (1).”


Section 195(4) “A
certificate granted under sub-section (3) shall remain in force till the
expiry of the period specified therein or,
if it is cancelled by the
Assessing Officer before the expiry of such period, till such cancellation.


Section 197(1)“Subject
to rules made under sub-section (2A), where, in the case of any income of
any person
or sum payable to any person, income-tax is required to
be deducted at the time of credit or, as the case may be, at the time of
payment at the rates in force under the provisions of sections 192, 193, 194,
194A, 194C, 194D, 194G, 194H, 194-I, 194J, 194K, 194LA, 194LBB, 194LBC and 195,
the Assessing Officer is satisfied that the total income of the recipient
justifies the deduction of income-tax at any lower rates or no deduction of
income tax,
as the case may be, the Assessing Officer shall, on an
application made by the assessee in this behalf, give to him such certificate
as may be appropriate.”


2.3     Section 195(3) read with rule 29B and Forms
15C and 15D, in short, provides as follows:


Section 195(3) provides that a
payee entitled to receive interest or other sums liable to TDS and satisfying
certain conditions prescribed in rule 29B can make an application (Form 15C for
banking companies or Form 15D for non-banking companies) i.e.


a.  Has been regularly filing tax returns and
assessed to Income-tax;

b.  Not in default in respect of tax, interest,
penalty etc.

c.  Additional conditions for non-banking
companies:


i.   has been carrying on business or profession
in India through a branch for at least 5 years


ii.  value of fixed assets in India exceeds Rs. 50
lakh.


d.  Certificate issued by the AO valid for the
financial year mentioned therein unless cancelled before.

e.  Application
for fresh certificate can be made after expiry of earlier certificate, or
within 3 months before expiry.


2.4     Section 197 read with rule 28AA and Form
13, in short, provides as follows:

a.  Any payee can apply for no deduction or lower
rate of deduction

b.  Prescribed form – Form 13

c.  Prescribed conditions (Rule 28AA):


   Total income / existing
and estimated tax liability justifies lower deduction;

   Considerations for
existing and estimated tax liability justifying lower or nil TDS;

   Tax payable on estimated
income of previous year;

   Tax payable on assessed /
returned of last 3 previous years;

   Existing liability under
the Act;

   Details of advance tax,
TDS & TCS.


d. 
AO to issue certificate indicating rate / rates of tax, whichever is
higher, of the following:


    Average rate determined
on the basis of advance tax; or

   Average of average rates
of tax paid by the taxpayer in last 3 years.


e.  
Certificate issued by AO can be prospective only


f.     Payment / credit made prior to the date of
the certificate is not covered. Circular No. 774 dated 17th March
1999.


3.     Lower
withholding – A Comparative Chart


The above discussion and the
comparative features of the aforesaid provisions are summarised in the table
given below.


Particulars

Section 195(2)

Section 195(3)

Section 197

Overview

Payer having a belief that portion (not the whole amount) of any
sums payable by him to non-resident is not liable to tax in India, may make
an application to AO to determine taxable portion.

Payee may make an application to AO for granting him a
certificate to receive income without TDS.

Payee may make an application to AO for granting him certificate
of ‘Nil’ or ‘lower’ withholding.

Application by

Payer

Non-resident Payee

Payee

Purpose

Determination of portion of such sum chargeable to tax.

No withholding

Lower / Nil withholding

Form

No Specific Format

Rule 29B – Form 15C and 15D

Rule 28 -Form 13

Outcome

AO to determine the appropriate proportion chargeable to tax and
issue order accordingly.

Certificate issued by the AO subject to conditions specified in
Rule 29B.

Certificate to be issued by AO subject to conditions specified
in Rule 28AA.

Remedy


Order can be appealed
u/s. 248.

uThere is no provision under Chapter XX of the
Act, to appeal against the certificate issued.


u Possible to pursue application u/s. 264.


u Possible to explore writ jurisdiction – Diamond
Services International (P.) Ltd. [2008] 169 Taxman 201 (Bom).


In which cases and circumstances
one should make and application for lower or nil TDS u/s. 195(2) or 197, should
be determined keeping in view the above discussion.


4.     Section
195 – Various situations


The various situations could be
faced by a payer as well as a payee has been very lucidly and succinctly
explained in the case of ITO IT vs. Prasad Production Ltd. [2010] 125 ITD
263 (Chennai)(SB),
which is summarised as follows:


a)  If the bona fide belief of the payer is
that no part of the payment has any portion chargeable to tax, he will submit
necessary information u/s. 195. However, if the department is of the view that
the payer ought to have deducted tax at source, it will have recourse u/s. 201.


b)  If the payer believes that whole of the
payment is chargeable to tax and if he deducts and pays the tax, no problem
arises.


c)  If the payer believes that only a part
of the payment is chargeable to tax, he can apply u/s. 195(2) for deduction at
appropriate rates and act accordingly.


d)  If the payer believes that a part of
the payment is income chargeable to tax, and does not make an application u/s.
195(2), he will have to deduct tax from the entire payment.


e)  If the payer believes that the entire
payment or a part of it is income chargeable to tax and fails to deduct tax at
source, he will face all the consequences under the Act. The consequences can
be the raising of demand u/s.201, disallowance u/s. 40(a)(i), penalty,
prosecution, etc.


f)   If the payee wants to receive the
payment without deduction of tax, he can apply for a certificate to that effect
u/s. 195(3) and if he gets the certificate, no one is adversely affected.

g)  If the payee fails to get the
certificate, he will have to receive payment net of tax.


5.     Refund
of Tax withheld under section 195


A very important and practical
issue arises as to whether it is possible to obtain refund of tax withheld and
paid u/s. 195.


5.1     Circular No. 7/2007 dated 23-10-07 and
Circular No. 7/2011 dated 27-9-2011 prescribe various situations and conditions
under which refund can be obtained.


Conditions to be satisfied for
refund:


   Contract is cancelled and no
remittance is made to the NR


   Remittance is duly made to the NR, but the
contract is cancelled and the remitted amount has been returned to the
payee


   Contract is cancelled after partial
execution
and no remittance is made to the NR for the non-executed part;


   Contract is cancelled after partial execution
and remittance related to non-executed part made to the NR has been returned
to the payee or no remittance is made but tax was deducted and deposited
when the amount was credited to the account of the NR;


   Remitted amount gets exempted from tax
either by amendment in law or by notification


   An order is passed u/s. 154 or 248 or 264
reducing the TDS liability
of the payee;


   Deduction of tax twice by mistake from
the same income;


   Payment of tax on account of grossing up
which was not required


   Payment of tax at a higher rate under
the domestic law while a lower rate is prescribed in DTAA.


5.2     In the
following cases it has been held that pursuant to favorable appellate order
whether u/s. 248 or otherwise, refund of TDS has to be granted:


Telco vs.
DCIT [2005] 92 ITD 111 (Mum)
;

Samcor Glass
Ltd. vs. ACIT [2005] 94 ITD 202 (Del)
;

Kotak
Mahindra Primus Ltd. vs. DDIT TDS [2007] 105 TTJ 578 (Mum)
.


5.3     In
the case of Tata Chemicals Ltd. [2014] 363 ITR 658 (SC), the apex
court has held that an assessee is entitled to interest on refund of excess
deduction or erroneous deduction of tax at source u/s. 195.


Pursuant to the aforementioned
decision of the SC, CBDT has issued Circular 11/2016 dated 26-4-16 and mentioned
that, ‘In view of the above judgment of the Apex Court it is settled that if a
resident deductor is entitled for the refund of tax deposited under section 195
of the Act, then it has to be refunded with interest under section 244A of the
Act, from the date of payment of such tax.’


6.     Consequences
of non/short deduction/ reporting failures


6.1     The consequences of non-deduction, short
deduction as well as failure to report transactions have been summarised in the
Chart 1.


6.2     Disallowance
u/s. 40(a)(i) or section 58(1)(a)(ii)


A question often arises as to if
tax is deducted u/s. 195 though at incorrect rate, whether the disallowance
u/s. 40(a)(i) or section 58(1)(a)(ii) can be made.


In the following cases a favorable
view has been taken and it has been held that there should be no disallowance
if tax is deducted though at incorrect rate:


–   Apollo Tyres
Ltd. vs. DCIT 35 taxmann.com 593 (Cochin)

–   UE Trade
Corpn. (India) Ltd. vs. DCIT 28 taxmann.com 77 (Del)

–  ITO vs.
Premier Medical Supplies & Stores 25 taxmann.com 171 (Kol)

–  DCIT vs.
Chandabhoy & Jassobhoy 17 taxmann.com 158 (Mum)

–   CIT vs. S.
K. Tekriwal [2014] 46 taxmann.com 444 (Calcutta).

However, in the case of CIT vs.
Beekaylon Synthetics Ltd. ITA No. 6506/M/08 (Mum)
it has been held that in
such case there would be proportionate disallowance.


6.3     An issue arises for consideration is that
if the Indian company has not deducted tax at source u/s. 195, can the
Department proceed to recover the tax from both the Indian party as well as
foreign party?


In this regard, explanation to
section 191 provides as follows:


“Explanation.—For the removal of
doubts, it is hereby declared that if any person including the principal
officer of a company,—


(a)     who
is required to deduct any sum in accordance with the provisions of this Act; or


(b)     referred
to in sub-section (1A) of section 192, being an employer,


does not deduct, or after so
deducting fails to pay, or does not pay, the whole or any part of the tax, as
required by or under this Act, and where the assessee has also failed to pay
such tax directly, then, such person shall, without prejudice to any other
consequences which he may incur, be deemed to be an assessee in default within
the meaning of sub-section (1) of section 201, in respect of such tax.


Section 205 provides as follows:


“Bar against direct demand on
assessee.

205. Where tax is deductible
at the source under the foregoing provisions of this Chapter, the assessee
shall not be called upon to pay the tax himself to the extent to which tax
has been deducted
from that income.”

A conjoint reading of the
Explanation to section 191 read with section 205 suggest that the department
cannot proceed to recover the tax from both the Indian party as well as foreign
party.


7.     Tax
Residency Certificate and Implications of 206AA


7.1    Tax Residency
Certificate – Section 90(4)


–  Finance Act,
2012 has introduced sub-section (4) to section 90 w.e.f. 1-4-2013 to provide
that a non-resident will not be entitled to claim benefits under the Treaty
unless he obtains a tax residency certificate from the Government of his
residence country/territory certifying that he is a tax resident of that
country.


–  The
requirement applies to all Non-residents, whether Individuals, Companies, LLPs
etc., irrespective of the quantum of relief to be obtained.


–   Furnishing
TRC is a mandatory requirement.


–  Rule 21AB(1) mandates submission of following information
in Form 10F:


i.   Status (individual, company, etc) of the
assessee;


ii.   Nationality or country or specified territory
of incorporation or registration;


iii.  Assessee’s tax identification number in the
country or specified territory of residence and in case there is no such
number, then, a unique number on the basis of which the person is identified by
the Government of the country or the specified territory of which the assessee
claims to be a resident;


iv.  Period for which the residential status, as
mentioned in the certificate referred to in sub-section (4) of section 90 or
sub-section (4) of section 90A, is applicable; and


v.  Address of the assessee in the country or
specified territory outside India, during the period for which the certificate,
as mentioned in (iv) above, is applicable.


–   Declaration
not required, if TRC contains above particulars.


7.2    Skaps Industries India
(P.) Ltd. vs. ITO [2018] 94 taxmann.com 448 (Ahmedabad – Trib.)


This is an important decision in
the context of mandatory requirement of TRC u/s. 90(4). The ITAT after very
extensive discussion, held and observed as follows:


(i)      The
ITAT states that as per the provisions of section 90(2) of the Act, the
provisions of the Act shall apply only to the extent they are more beneficial
to that the assessee and the same was often referred to as “treaty override”

.

(ii)      The ITAT also observed that the provisions of section 90(4) do
not start with a non-obstante clause vis-à-vis section 90(2) of the Act. In the
absence of such non-obstante clause, the ITAT has held that section 90(4)
cannot be construed as limitation to the tax treaty superiority as stipulated
in section 90(2) of the Act. Accordingly, the Tribunal has held that even in
absence of a valid TRC, provisions of section 90(4) could not be invoked to
deny tax treaty benefits.


(iii)     The Tribunal has, nevertheless, emphasised that though the
requirement to furnish TRC is not mandatory, the US Co. had to establish that
it was a USA tax resident. The onus was on the assessee to give sufficient
and reasonable evidence to satisfy the requirements of Article 4(1) of the tax
treaty, particularly when the same was called into question.


(iv)     This decision lays down a very important proposition that that
the tax treaty benefits cannot be denied merely on the basis of
non-availability of TRC. Further it also lays down that, when a non-resident
assessee has substantiated its residential status by way of sufficient and
reasonable documentary evidence, the requirement of furnishing TRC would be
persuasive and not mandatory.


8.     Section
206AA Requirement to furnish PAN


8.1     Section 206AA provides as follows:


“206AA (1) Notwithstanding
anything contained in any other provisions of this Act,
any person
entitled to receive any sum or income or amount, on which tax is deductible
under Chapter XVIIB (hereafter referred to as deductee) shall furnish his
Permanent Account Number to the person responsible for deducting such tax
(hereafter referred to as deductor), failing which tax shall be deducted at the
higher of the following rates, namely:-


i.   at the rate specified in the relevant provision
of this Act; or


ii.  at the rate or rates in force; or


iii.  at the rate of twenty per cent. ……….”

8.2     Section 206AA is very significant in the
context of TDS from payments to non-residents. It is pertinent to note that if
no tax deductible at source in view of the applicable provisions of the Act or
DTAA, provisions of section 206AA would not apply. There are various issues and
aspect relating to section 206AA are dealt with below.


8.3    Whether DTAA prevails over section 206AA


A very important question arises as
to whether section 206AA override provisions of section 90(2) and in cases of
payments made to non-residents, assessee can correctly apply rate of tax
prescribed under DTAAs and not as per section 206AA because provisions of DTAAs
are more beneficial.


Various benches of ITAT and Delhi
High Court have held that section 206AA does not override section 90(2) of the
Act and accordingly held that lower TDS as per favourable DTAA provisions is
applicable and not higher rate
u/s. 206AA. Some of the favourable decisions are as follows:


   DDIT vs. Serum
Institute of India Ltd. [2015] 68 SOT 254 (Pune)

   DCIT vs. Infosys BPO
Ltd. [2015] 154 ITD 816 (Bang.)

   Emmsons International
Ltd. vs. DCIT [2018] 93 taxmann.com 487 (Delhi – Trib.)

   Danisco India (P.) Ltd.
vs. UoI [2018] 90 taxmann.com 295 (Delhi)

   Nagarjuna Fertilizers
& Chemicals Ltd. vs.  ACIT [2017] 78
taxmann.com 264 (Hyderabad-Trib.)
(SB)

It is
pertinent to note that Article 51(c) of the Constitution states as follows:
“State shall endeavor to foster respect for international law and treaty
obligations in the dealings of organised peoples with one another; and
encourage settlement of international disputes by arbitration.”


The above decisions are in line
with the aforementioned constitutional mandate and spirit. Thus, in case
provisions of a DTAA is applicable, TDS would be at a lower rate as per the
DTAA even if non-resident deductee fails to furnish PAN.


8.4    Applicability of
surcharge or education cess on maximum rate of 20% as per section 206AA


It is pertinent to note that the
relevant clauses of the Finance Acts do not include section 206AA in their
ambit for the purpose of levy of surcharge or education cess.


The ITAT in the case of Computer
Sciences Corporation India (P.) Ltd. vs. ITO (IT) [2017] 77 taxmann.com 306
(Delhi-Trib.)
after considering various aspects, held that there no
surcharge and education cess would be leviable on the rate of 20% prescribed
u/s. 206(1)(iii).


8.5    Whether it is
applicable to those who are exempt from obtaining PAN?


a)  Section 139A(8)(d) provides
that the Board may make rules providing for class or classes of persons to whom
the provisions of section 139A shall not apply. Rule 114C (1) (c) (prior to its
substitution wef 1-1-2016) provided that the provisions of section 139A regarding
allotment PAN shall not apply to the non-residents referred to in section
2(30). Section 272B provides for a penalty for failure to comply with the
provisions of section 139A of Rs. 10,000/-.


b)  In the case of Smt. A. Kowsalya Bai vs UoI
22 Taxmann.com 157 (Kar)
, the Karnataka High Court held that the assessees
having income below the taxable limit were not required to obtain Permanent
Account Numbers as per section 139A of the Act and still the provisions of
section 206AA were invoked to deduct tax at higher rate from the amount of
interest income paid to them as a result of their failure to furnish the
Permanent Account Numbers to the payers/deductors. Taking note of this
contradiction between the provisions of sections 139A and 206AA, Hon’ble
Karnataka High Court read down the overriding provisions of section 206AA and
made them inapplicable to the persons, who were not even required to obtain the
Permanent Account Numbers by virtue of section 139A.


c)  In this regard, the Special bench of the
ITAT in the case of Nagarjuna Fertilizers & Chemicals Ltd. vs ACIT
[2017] 78 taxmann.com 264 (Hyderabad-Trib.) (SB)
held that


“26. Although
the facts involved in the present case are slightly different, inasmuch as, the
non-resident payees in the present case were having taxable income in India,
the facts remain to be seen is that they were not obliged to obtain the
Permanent Account Numbers in view of section 139A(8) read with Rule 114C. There
is thus a clear contradiction between section 206AA and section 139A(8) read
with Rule 114C, as was prevailed in the case of Smt. A. Kowsalya Bai (supra)
and by applying the analogy of the said decision, we find merit in the
contention raised on behalf of the assessee that the provisions of section
206AA are required to be read down so as to make it inapplicable in the cases
of concerned non-residents payees who were not under an obligation to obtain
the Permanent Account Numbers.”


d)    It is pertinent to note that Rule 114B and
114C have been substituted wef 1-1-16 and the rule relating to non-application
of provisions of section 139A regarding allotment PAN to the non-residents
referred to in section 2(30), is no more there except as provided in clause
(ii) of 3rd proviso to substituted rule 114B(1).


8.6     Whether TDS deducted at higher rate on
account of section 206AA can be claimed as a refund by filing a return u/s. 139
by the non-resident?


Yes. A non-resident can claim
refund of TDS deducted at higher rate on account of section 206AA by filing
appropriate return of income after obtaining PAN.


8.7    Section 195A vis-à-vis
Section 206AA


a)  
A very significant question arises in the context of application of
section 195A read with section 206AA, whether section 195A will apply in cases
where section 206AA is made applicable


There are different views possible
in this regard which are as follows:


i.   View 1 – No grossing up required.

Neither
section 195A makes reference to section 206AA, nor section 206AA provides for
grossing up.


ii.   View 2 – Grossing up required only
vis-à-vis clause (ii) of section 206AA(1), since section 195A refers to
grossing up is required where TDS is at the rates in force.


iii.  View 3 – Grossing up is required in all
the three clauses (i) to (iii) of section 206AA(1).


In our view,
View 2 seems to be a better view.


b)  Manner of grossing up

In cases
where rate in force is 10%* – Whether grossing up should be on 10% being rate
in force or on 20%?

The
different possible scenarios could be as under:


Particulars

Option 1

Option 2

Option 3

Option 4

Net of Tax Payment to non- resident

100

100

100

100

(+) Grossing up

11.11

11.11

21.11

25

Total

111.11

111.11

121.11

125

(-) TDS

11.11

22.22

21.11

25

Payment to be made to the non-resident

100

88.89

100

100


* Assuming a treaty rate of 10%


In Bosch Ltd. vs. ITO IT
[2012] 28 taxmann.com 228 (Bang)
it was held that higher rate of
deduction at 20% under section 206AA is not applicable for tax grossing-up u/s.
195A, if TDS is borne by the Indian payer.


Higher TDS rate u/s. 206AA is
applicable only where non-resident recipient has income chargeable to
tax in India and does not furnish PAN.


In this regard, the ITAT observed
as follows:


“22. As regards
the grossing up u/s 195A of the Income-tax Act is concerned, we find that the
provision reads
as under:


“In a case other than that
referred to in subsection (1A) of sec. 192, where under an agreement] or other
arrangement, the tax chargeable on any income referred to in the foregoing
provisions of this Chapter is to be borne by the person by whom the income is
payable, then, for the purposes of deduction of tax under those provisions such
income shall be increased to such amount as would, after deduction of tax
thereon at the rates in force for the financial year in which such income is
payable, be equal to the net amount payable under such agreement or
arrangement.


23. Thus, it
can be seen that the income shall be increased to such amount as would after
deduction of tax thereto at the rate in force for the financial year in which
such income is payable, be equal to the net amount payable under such agreement
or arrangement. A literal reading of sec. implies that the income should be
increased at the rates in force for the financial years and not the rates at
which the tax is to be withheld by the assessee. The Hon’ble Apex Court in the
case of GE India Technology Center (P.) Ltd. (cited Supra) has held
that
the meaning and effect has to be given to the expression used in the section
and while interpreting a section, one has to give weightage to every word used
in that section. In view of the same, we are of the opinion that the
grossing up of the amount is to be done at the rates in force for the financial
year in which such income is payable and not at 20% as specified u/s 206AA of
the Act.”


8.8    Section 206AA and Rule
37BC


a)   As per section 206AA(7), the section shall
not apply to a non-resident/foreign company, in respect of:


–  payment of
interest on long-term bonds referred to in section 194LC


–  any other
payment subject to such conditions as may be prescribed.


b)  Rule 37BC inserted wef 24-6-2016


Rule 37BC provides that section
206AA shall not apply on the following payments to non-resident deductees who
do not have PAN in India, subject to deductee furnishing the specified details
and documents to the deductor:

       Interest;

       Royalty;

       Fees
for Technical Services; and

       Payment
on transfer of any capital asset.


c)   In respect of the above, the deductee shall
be required to furnish the following to the deductor:


–  Name, e-mail
id, contact number


–  Address in
the country outside India of which the deductee is a resident


–   A certificate of his being resident from the Government of that country
if the law provides for issuance of such certificate


–  Tax
Identification Number of the deductee/ a unique number on the basis of which
the deductee is identified by the Government.


d)  
The interplay between provisions of a DTAA, section 206AA and section
90(4), in connection with TDS under section 195, is explained in the diagram
below.


9.     Conclusion

In this part we have dealt with
some of the important procedural and other aspects relating to the TDS from
payments to non-residents. In the third and concluding part, we will deal with
some remaining aspects relating to TDS from payments to non-residents.

22. TS-274-ITAT-2018(Del) Daikin Industries Limited. v. DCIT A.Ys: 2006-07, Dated: 28th May, 2018

Article 5 of
India-Japan DTAA – marketing activities of Indian distributor constitutes
dependent agent PE (DAPE) for the Japanese parent in India; additional profits
were to be attributed to the DAPE by taking into account the functions and risks
that were not considered for TP analysis of the agent (distributor).


Facts

Taxpayer, a Japanese
company was engaged in the business of development, manufacture, assembly and
supply of air conditioning and refrigeration equipment. During the year, Taxpayer
sold air-conditioners in India directly to third party Indian customers (direct
sale) as well as to an Indian distributor, I Co who was the wholly owned
subsidiary of Taxpayer in India.


In addition to acting as
the distributor of Taxpayer’s products in India, I Co entered into a commission
agreement with the Taxpayer to act as a communication channel between the
Taxpayer and its customers in India. As per the agreement, I Co was responsible
for forwarding customer’s request to the Taxpayer as well as forwarding
Taxpayer’s quotations and contractual proposals to the customers in India. In
consideration of the said services, I Co charged a commission of 10% on direct
sales made by the Taxpayer in India.


As the Taxpayer failed to
produce the evidence showing its involvement in the marketing of products sold
by way of direct sales in India, AO held that the activities of identifying
customers, approaching, presentation, demonstration, price catalogue,
negotiation of prices and finalisation of prices etc. were carried on by I Co
on behalf of the Taxpayer in India, in addition to the activities set out in
commission agreement. Consequently, it was held that I Co constituted a DAPE of
the Taxpayer in India under India-Japan DTAA.


The CIT(A) upheld AO’s contention.
Aggrieved, the Taxpayer filed an appeal before the Tribunal.


Held


On DAPE


  The air-conditioning and refrigeration
industry in which the Taxpayer was involved was highly competitive and
tremendous efforts are required for effecting sales in such market. This is
also evident by the fact that I Co had to incur huge selling and distribution
expenses for selling the same products in its capacity as a distributor. It is
hard to comprehend that the Taxpayer managed to make direct contact with customers,
scattered all over India for effecting sales to them directly, without any
marketing efforts.


   The contents of the emails exchanged between
the Taxpayer and I Co demonstrate that the entire deal was negotiated and
finalised by Indian customers with I Co and the role of I Co was not confined
merely to a communication channel as contended by the Taxpayer.


   In absence of any evidence indicating direct
involvement of Taxpayer in marketing activities in relation to direct sales in
India and the emails indicating the involvement of I Co in finalising the deals
with customers in India, the inescapable conclusion is that the entire activity
starting from identification of customers, approaching them, negotiating prices
with them and finalisation of prices was done by I Co in India not only for the
products sold by them as distributor, but also for the direct sales made by the
Taxpayer.


   Although I Co did not have authority to
finalise the contract of direct sales in India, the substantial activities of any
sale transaction like the activities of negotiating and finalising the
contracts were performed by I Co.


   Thus I Co was habitually exercising an
authority to conclude contracts in India on behalf of the Taxpayer. The mere
fact that the Taxpayer was formally signing the contract of sale does not alter
this position in any manner.


   Also, I Co was securing orders in India
‘almost wholly’ for the Taxpayer as all the substantive parts of the key
activities in making sales were carried on by I Co in India.


   Exclusion of independent agent activities is
not applicable as the Taxpayer had not contested the dependent status of I Co.


On Attribution of profits
on determination of ALP


   Since the Taxpayer did not maintain TP
documentation nor did it furnish the TP report with respect to commission
payments to I Co, its contention that the payment of commission is at arm’s
length cannot be accepted.


   SC in the case of Morgan Stanley (292 ITR
416) held that, if the independent agent is remunerated at arm’s length by
taking account all the risk-taking functions of the enterprise, there can be no
further attribution to DAPE. SC further held that if the TP analysis does not
reflect the functions performed and risks assumed by the enterprise, then
additional profits are to be attributed to the PE by taking into account the
functions and risks that are not considered for TP analysis.


   The commission of 10% was paid to I Co only
towards the services rendered as per the commission agreement. However,
evidences in the form of emails correspondences between Taxpayer and I Co as
well as I Co and customer supported the contention of the revenue that the
functions performed by I Co were beyond the services covered by the commission
agreement and included all the activities in relation to negotiation and
finalisation of the price and other contractual terms of the customer
contracts.


   Hence, the determination of arm’s length
commission of 10% did not reflect the functions performed and the risks assumed
by the PE. Therefore, as held by SC in Morgan Stanley (292 ITR 416), additional
profits should be attributed to the DAPE (i.e., I Co) for the additional
functions undertaken by DAPE in India.
 

21. TS-330-ITAT-2018(Ahd) Skaps Industries India Pvt Ltd. vs. ITO A.Ys: 2013-14 & 2014-15, Dated: 21st June, 2018

Section 90(4),
90(2) of the Act- in the absence of a non-obstante clause u/s. 90(4), it
cannot limit treaty superiority contemplated u/s. 90(2)- mere non-furnishing of
the TRC cannot disentitle a taxpayer from claiming tax treaty benefits.


Facts

The
Taxpayer, an Indian company, made payments to a US entity for services in
relation to installation and commissioning of certain equipment purchased by
the Taxpayer. The Taxpayer did not withhold any taxes as it was not falling
within the ambit of fees for included services (FIS) under the DTAA.


The
AO was of the view that such payments were in the nature of FIS under the DTAA
and, thus, the Taxpayer was liable to appropriately withhold taxes. The CIT(A)
ruled in favour of the AO and also observed that, in the absence of a TRC, the
US entity was not entitled to protection under the DTAA.


Aggrieved,
the Taxpayer filed an appeal before the Tribunal.


Held

   Section 90(2) of the Act provides for an
unqualified treaty override wherein provision of the Act are applicable only to
the extent more beneficial to the Taxpayer. The only exception to the treaty
override principle is in case where the general anti-avoidance provisions
(GAAR) are invoked.


   The restriction on the application of tax
treaty benefits on failure to provide a TRC does not have an overriding effect
over section 90(2) (as opposed to GAAR).


   The requirement to furnish a TRC was
introduced so that the TRC is regarded as sufficient evidence for granting tax
treaty benefit and the AO is denuded of the powers to demand further details in
support of the tax treaty benefits claimed[1].
The TRC provision cannot be construed as a limitation to the superiority of the
tax treaty over the domestic law.


   Thus, mere non-furnishing of a TRC cannot be
a reason to deny tax treaty benefit. However, the Taxpayer should substantiate
its eligibility to claim tax treaty benefits by means other than a TRC.
Substantiating residential status by any other mode is far more onerous
compared to TRC, as the TRC can be easily obtained from the US authorities for
a modest user fee after filing a statutory form.


   A mere declaration by the US entity, without
any material to substantiate the basic facts set out in the declaration, cannot
be accepted as legally sustainable foundation for a finding of fact. Also, same
does not amount to certification by any authority and hence did not prove its
residential status.


   As the Taxpayer was earlier not asked to
submit evidence other than a TRC to prove residential status of the US entity,
the matter was remanded to the AO for fresh adjudication, with direction to
give the Taxpayer a fresh opportunity to furnish evidence not limited to, but
including, the TRC in support of the US entity’s entitlement to the tax treaty
benefits of the DTAA.


[1] Reliance was placed on an Authority
for Advance Rulings order in the case of Serco BPO Pvt. Ltd. [(2015) 379 ITR
256 (P&H)]

20. TS-321-ITAT-2018 (Mum) DCIT v. D.B. International (Asia) Ltd A.Y: 2011-12, Dated: 20th June, 2018

Article 11, 23
of India-Singapore DTAA –relief from capital gains taxation in India cannot be
termed as ‘exemption’ – conditions for trigger of Limitation of Relief clause
not satisfied.


Facts

The Taxpayer, a tax
resident of Singapore, was carrying on its business operations including
trading in securities from Singapore. It did not have any PE in India. During
the year, Taxpayer earned capital gain on sale of shares, debt instruments and
derivatives (collectively referred to as “securities”) in India and claimed it
as non-taxable in India under the DTAA which provides exclusive taxation rights
on such gains to Singapore as resident country.


The AO contended that
since capital gains were not remitted/repatriated to Singapore, capital gain
benefit under the DTAA cannot be allowed. This resulted in non-satisfaction of
Limitation of Relief (LOR) article under the DTAA which restricts exemption in
source country (India) to the extent of repatriation of such income to resident
country (Singapore).

As against this, the
Taxpayer contended that the gains were not taxable in India because under
capital gains article, gains from sale of securities in India are taxable only
in Singapore. Once the entire worldwide income was assessed at Singapore, a
part of it cannot be taxed in India as it will amount to double taxation of the
same income. Thus, LOR provision is of no relevance in this case. In support of
its contention, the Taxpayer relied on Mumbai Tribunal ruling in the case of
Citicorp Investment Bank Singapore Ltd[1].


The Dispute Resolution
Panel (DRP), ruled in the favour of the Taxpayer. Aggrieved by this the AO
appealed before the Tribunal.


Held

u   The LOR provision applies if income derived
from a source state is either exempt from tax or taxed at a reduced rate in
that source State. The above condition is not fulfilled in the present case as
capital gains derived by the Taxpayer from sale of Indian securities is taxable
only in the resident state, i.e., Singapore. The provision is clear and
unambiguous and expresses itself as not an exemption provision but it speaks of
taxability of particular income in a particular State by virtue of residence of

the Taxpayer.


u   The expression “exempt” with reference to the
capital gain derived by the Taxpayer has been loosely used. Therefore, capital
gain which was not taxable in India due to allocation of exclusive taxation
rights to country of residence cannot be termed as an “exemption”. This is also
supported by Mumbai Tribunal ruling in the case of Citicorp Investment Bank
Singapore Ltd. as referred by the Taxpayer.


u   LOR provisions are thus not applicable to the
facts of the case.


[1] 2017–EII–59–ITAT–MUM–INTL]