Subscribe to the Bombay Chartered Accountant Journal Subscribe Now!

Miscellanea

1. TECHNOLOGY

#Experts Suggest Crowdstrike Update Behind Global Outage Likely Skipped Key Checks

Security experts have indicated that CrowdStrike’s routine update of its widely used cybersecurity software, which led to a global system crash on Friday, apparently did not undergo sufficient quality checks before being deployed. The lack of thorough testing is believed to have contributed to the widespread disruption affecting clients’ computer systems worldwide.

According to a report by Reuters, the recent update to CrowdStrike’s Falcon Sensor software was intended to bolster security for clients by refreshing the list of threats it protects against. Unfortunately, the update contained faulty code, which triggered one of the most significant tech outages in recent years. This disruption affected numerous companies relying on Microsoft’s Windows operating system, leading to widespread system crashes and operational issues.

“What it looks like is, potentially, the vetting or the sandboxing they do when they look at code, maybe somehow this file was not included in that or slipped through,” said Steve Cobb, chief security officer at Security Scorecard, which also had some systems impacted by the issue.

The massive disruption to Microsoft systems has included flight delays and cancellations, as well  as impacting hospitals, banks, supermarkets and millions of businesses.

Close to 7,000 flights were cancelled globally on Friday—equating to 6.2 per cent of all scheduled flights, according to Aviation analytics firm Cirium.

Patrick Wardle, a security researcher specialising in operating system threats, identified the code responsible for the outage. He explained that the issue lay in a file containing either configuration details or signatures—code used to detect specific types of malicious software or malware.

Wardle noted that it is common for security products to update their signatures regularly, often daily, to continuously monitor for new malware and ensure protection against the latest threats.

Wardle suggested that the frequent nature of updates might explain why CrowdStrike did not test this particular update as thoroughly. It remains unclear how the faulty code was introduced into the update and why it was not detected before being released to customers.

Other security companies have faced similar issues in the past. For example, McAfee’s problematic antivirus update in 2010 caused hundreds of thousands of computers to stall.

(Source: International Business Times – By Litty Simon, dated 21st July, 2024)

2. SPORTS

#Paris Braces For ‘Most Incredible’ Olympics Opening Ceremony

Thousands of athletes are set to sail through central Paris on Friday during an unprecedented and high-risk Olympics opening ceremony that will showcase the country’s hugely ambitious vision for the Games.

The parade on Friday evening will see up to 7,500 competitors travel down a six-kilometre (four-mile) stretch of the river Seine on a flotilla of 85 boats.

Compared to the Covid-blighted 2020 Tokyo Olympics, which were delayed by a year and opened in an empty stadium, the Paris show will take place in front of 300,000 cheering spectators and an audience of VIPs and celebrities from around the world.

“Tomorrow you will have one of the most incredible opening ceremonies,” French President Emmanuel Macron promised at a pre-Games dinner for heads of state and government at the Louvre museum on Thursday evening.

The line-up of performers is a closely guarded secret but US pop star Lady Gaga and French-Malian singer Aya Nakamura—the most listened-to French-speaking singer in the world—are rumoured to be among them.

It will be the first time a Summer Olympics has opened outside the main athletics stadium, a decision fraught with danger at a time when France is on its highest alert for terrorism.

For months, organisers have been dogged by questions about whether they would need to scale back or move the procession, but they had insisted throughout that there was no plan B.

A huge security perimeter has been erected along both banks of the Seine, guarded round-the-clock by some of the 45,000 police and paramilitary officers who will be on duty on Friday evening.

Another 10,000 soldiers are set to add to the security blanket along with 22,000 private security guards.

“Without any doubt, it is much more difficult to secure half of Paris than to secure a stadium, where you have 80,000 people and you can frisk them and send them through turnstiles,” Frederic Pechenard, an ex-director general of the French police, told AFP.

Police snipers are set to be positioned on every high point along the route of the river convoy, which is overlooked by hundreds of buildings.

An assassination attempt on US presidential candidate Donald Trump on 13th July has focused minds.

Armed officers will also be on the boats, a security source told AFP.

The Israeli and Palestinian teams will be given extra protection, with the tensions caused by Israel’s offensive in Gaza, where nearly 40,000 people are estimated to have died, already spilling into the Games.

Organisers will be on guard against fresh protests on Friday evening after the Israeli football team’s first match on Wednesday was marked by the waving of Palestinian flags and the booing of the Israeli anthem.

The opening ceremony is likely to define the mood for the rest of the 26th July–11th August Games, which organisers have pledged will be “iconic”.

Around 3,000 dancers are set to perform from the banks of the river and nearby monuments, including Notre-Dame cathedral, in a show that will promote diversity, gender equality and French history.

The landmarks and architecture of the City of Light, one of the world’s best-loved destinations, is set to feature as a backdrop both to Friday night’s show and much of the sport afterwards.

“The opening ceremony is a huge event and one that, arguably, sets the tone for the next 17 days,” Hugh Robertson, the minister charged with delivering the 2012 London Olympics, told AFP recently.

(Source: International Business Times by Adam Plowright, dated 25th July, 2024)

3. HEALTH

#People Now More Mindful of Health and Natural Healing After Worldwide COVID Crisis, Says Global Healing Founder

The COVID-19 pandemic was the worst health crisis the world has faced in the past century, resulting in more than 7 million deaths. The early days of the pandemic were also some of the scariest for people, and the only surefire way to deal with the disease was to avoid getting infected and to strengthen one’s immune system to fight off the virus.

While the worst days of the pandemic are over and life has returned to almost normal, many people still remember the fear and uncertainty it caused, with a study finding that 60% of consumers are now more conscious of preventing health problems through adopting a healthier lifestyle using more natural solutions.

People are now more aware of the importance of whole-body wellness, and they are more open to doing their own research. However, this trend has also led to the proliferation of misinformation, spread by groups or individuals who want to make a quick buck. This is why there is a great need for information and products that are supported by scientific research.

For more than 25 years, Global Healing has been helping health-conscious individuals build a self-healing body and thrive in a lifestyle that aligns with nature’s design through science-backed products and education.

With a philosophy of cleansing the body of accumulated toxins and embarking on a personalised wellness journey, Global Healing was built on the idea that everyone, everywhere, should have access to research-backed health information and personal control over their health outcomes.

Global Healing

According to Global Healing Founder, Dr Edward F Group III, DC, NP, the growing health consciousness of people and the accompanying spread of misinformation has strengthened the need for Global Healing to uphold and improve its already-high standards and maintain the integrity of the market.

This begins with education, with Global Healing dedicated to teaching the community how to address the root cause of disease with a holistic approach and allow the body to heal itself.

Its website contains a wealth of articles discussing various health topics, and it is active on its various social media accounts, sharing knowledge about how people can become the healthiest, strongest, best versions of themselves. Dr. Group has also authored multiple books on health and holistic medicine.

“Global Healing sets the bar for discussions and developments in our industry with valuable insights, reliable guidance, and thoughtful perspectives,” he says. “We advocate for a holistic lifestyle that promotes whole-body wellness, such as natural remedies over pharmaceuticals, mindfulness practices over mind medications, exercise over diet pills, and
sleep over caffeine.”

Dr. Group believes that, as part of the natural wellness industry, it is Global Healing’s responsibility to provide correct and up-to-date information to its customers. He looks at things through the eyes of the customers, who are looking up information about various supplements, vitamins, detoxes, or cleanses because they’re concerned about something in their body, whether it’s their gut and digestive health, respiratory health, mental wellness, or any other component of health.

Across its wide array of products, Global Healing has maintained its dedication to quality and purity, sourcing botanicals from small farms. Many of its sources are certified USDA-organic, GMO-free, and vegan. The company also implements strict quality control procedures, with a rigorous testing process that involves both internal and third-party testing.

It hand-reviews every batch of ingredients, choosing only those that meet its stringent specifications for proper plant identification, potency levels, microbial presence, and heavy metal content.

Through its proprietary Raw Herbal Extract™ technology, Global Healing does not use heat, alcohol, or harsh chemicals in processing ingredients, resulting in a raw, all-natural, pure, and potent formula. Furthermore, all its equipment that comes into contact with the products does not use plastic, protecting it from contamination with potentially toxic compounds.

Dr. Group believes that the growing interest in all-natural and holistic health will result in more scrutiny of companies in this industry, and this is a great thing. With more attention placed on the industry, there will be more demand to improve standards.

“The COVID pandemic forced everyone to give more thought to their health, and people are getting smarter and smarter,” Dr Group says. “I’ve observed that they are holding companies to a higher standard and are more conscious about what’s in the food they eat and the air they breathe. ”As public demand for better and more natural health solutions grows, corporations will be held more accountable for how they process things and what they put into their products.

”People are demanding to know more, and they won’t fall for the smoke and mirrors. In this evolving market, Global Healing is dedicated to providing science-backed cleansing regimens and premium supplements that nurture the body’s innate ability to heal from within.”

(Source: International Business Times by Karcy Noonan, 11th July, 2024)

Statistically Speaking

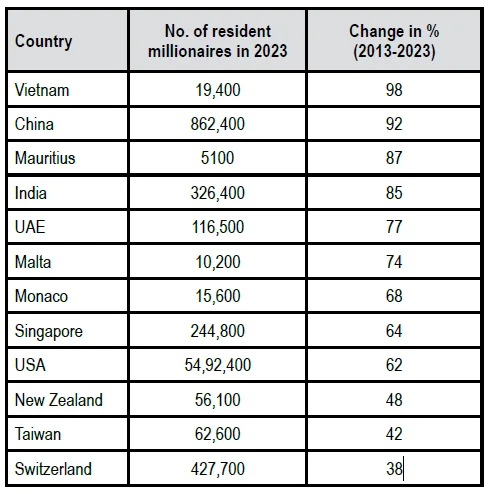
1. Rise In Resident Millionaires’ Population By Country

Source: Henley Private Wealth Migration Report 2024

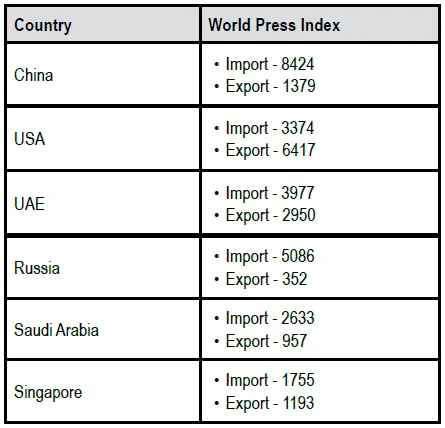
2. India’s Import And Export Trade With The World (In INR Billion)

Source: Department of Commerce

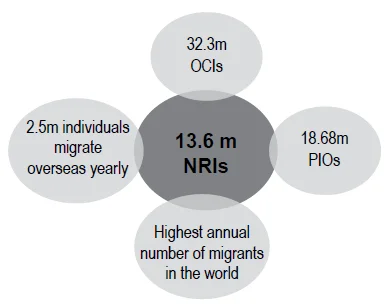
3. India — A Key Contributor to Global Migration

Source: OECD Economic Outlook

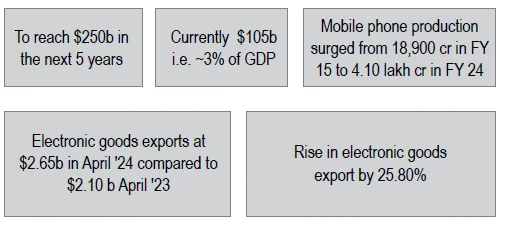
4. Rise in Electronic Manufacturing in India

Source: India Cellular and Electronics Association (ICEA)

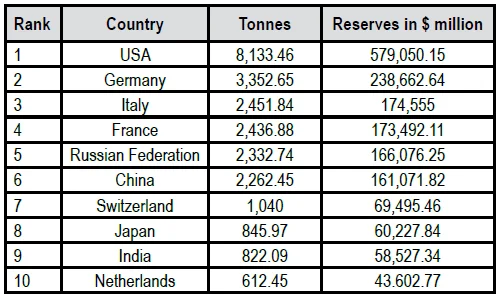
5. Countries that own the most gold

Source: World Gold Council (as on Q1 of 2024)

Learning Events at BCAS:

SOCIAL OUT-REACH INITIATIVES:

Round Table discussions on Viksit Bharat:

The Finance, Corporate and Allied Laws Committee (FC&AL) of the Bombay Chartered Accountants’ Society (BCAS) organized two round table discussions on Viksit Bharat: Ideas and Suggestions in July 2024. The aim was to gather insights from experienced Chartered Accountants and promising young professionals to contribute to Prime Minister, Shri Narendra Modi’s vision to make a Viksit Bharat by 2047. The first round table discussion was held on Saturday 6th July 2024 at the International Fiscal Association – India Branch in BKC, Mumbai where eminent Chartered Accountants shared their perspectives on various aspects of public policy and economic development crucial for India’s progress. The second roundtable discussion took place on Saturday 20th July 2024 at ATLAS SkillTech University, Mumbai. This event brought together top-ranking CA Finals and Intermediate students, along with MBA students, to provide a fresh perspective on India’s future.

MOU with Bombay Industries Associations (BIA):

The Society entered into a collaboration agreement with BIA on 18th July 2024 under which both bodies of eminence will mutually collaborate by leveraging strengths and enabling commerce. In this one of its kind partnership, both organizations, with 75 years of history, will combine their resources and capabilities towards collaborative learning opportunities, advocating for ease-of-businesses, offering policy suggestions, and engaging members from both associations with an aim to reinforce the overall economic structure.

BCAS Membership Survey:

Our members are at the centre of everything we plan and do. The Society believes in delivering high-quality professional experience for our members and community at large. Keeping that in mind, BCAS conducted a Membership Survey on 16th July, 2024 and received an overwhelming response. We thank our beloved members for participating in the survey. Some of the statistics of the survey are as follows:

  •  Relevance of Topic at BCAS Learning Events —Average rating 4.4
  •  Quality of Speakers and Content at BCAS Learning Events: Average rating 4.3
  •  Format of BCAS Learning Events- Average rating 4.1
  •  Venue, Food, and other logistics at BCAS Learning Events — Average rating 3.9
  •  Pricing for BCAS Learning Events — Average rating 3.9

The Society has also received many well thought suggestions from the members in the survey, and we shall strive to take that into consideration in our future activities.

Social Media Reach:

The Society has been striving to increase its reach to professionals and society and large and social media has been one of the relevant tools of current times to achieve the same. We are happy to announce that we have crossed 10,000 followers on Linkedin. Our Whatsapp channel is also live and within two days we have crossed 1000 followers. With these, our overall social media spread has reached 57,189 followers and counting.

BCAS WhatsApp Chatbot:

In a constant endeavour to bring ease to our members, the Society is delighted to introduce its own Whatsapp Chatbot. Now, all our members and non-members can access and register for BCAS events and other activities through the ease of WhatsApp. Readers can explore the chatbot by sending a simple Hi on the chatbot number — 9082634642 to get started.

LEARNING EVENTS AT BCAS:

1. 76th Founding Day Lecture Meeting on Viksit Bharat — Role of Accounting and Finance Professionals held on 6th July, 2024 at ITC Grand Central Hotel Parel.

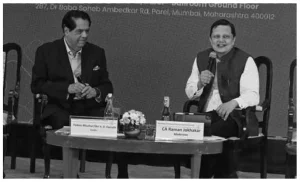
The 76th Foundation Day of the Society was marked by a significant event, featuring an interactive talk with the esteemed Padma Bhushan Shri K. V. Kamath. The topic, ‘Viksit Bharat — Role of Accounting and Finance Professionals,’ is a testament to the evolving landscape of India’s economy and the pivotal role that accounting and finance professionals play in it. Shri Kamath, with his extensive experience spanning over five decades, provided invaluable insights into India’s journey towards becoming a developed nation. As an inter-generational witness of India’s transformation, his dialogue with CA Raman Jokhakar, past president of the Society, highlighted the transformative changes that technology brought and the contribution of the Country’s infrastructure development plan, reflecting on the progress and the road ahead for India. He broadly spoke about the following.

Role of CAs: Since his early days at ICICI in 1971, Shri Kamath has witnessed first-hand the pivotal role of Chartered Accountants in shaping financial strategies and strengthening accounting practices. He reminisced about his experience in 1980, when he was leading a standalone division at ICICI acknowledging how chartered accountants assumed the role of technology architects in bringing technology to ICICI. Shri Kamath stated that people in the accounting and finance professions have to be leaders in absorbing and leveraging technology in a bigger way. According to Shri Kamath, the role of Chartered Accountants is going to be closely interwoven with technology for in the next 25 years, it will be difficult to differentiate between where the accounting stops and the technology comes in. He further stated that CA’s are the conscious keepers for the companies, Government and the public at large. That role is going to be more important as we go along with the new technology. He also emphasized the necessity of setting one’s mind on skilling and upskilling and getting everybody’s mindset aligned towards the technology part of the profession.

Learnings from the past: Talking about his learnings from driving and executing IT in ICICI, he said that the integration of technology into ICICI Bank’s operations between 2000 and 2005 marked a transformative era in Indian banking. The introduction of ATMs and the centralization of back-office operations, along with the establishment of call centres, significantly reduced the volume of in-branch transactions. He acknowledged that between 2020 and today, it has virtually revolutionized the way payments are made by individuals and corporations NPCI and QR technologies are taking over.

Characteristics of Viksit Bharat: On being asked about the characteristics/features of Viksit Bharat, he said that Viksit Bharat envisioned as a developed India, is characterized by its focus on rapid infrastructural growth, mirroring the transformative journeys of Japan, the Asian Tigers, and China. This vision is embodied in Mumbai’s current infrastructure projects like MTHL (Atal Setu), Eastern Freeway, and various metro and coastal road projects. According to Shri Kamath this seamless development will happen in every city, and town and will pervade down to every village and that according to Shri Kamath, will be a very visible sign of Viksit Bharat. He further explained that the infrastructure becomes the first building block as it adds to GDP during the implementation phase becoming the first ‘virtuous cycle’ leading to economic utilization of the said infrastructure in the next 15-20 years. With the fruits of infrastructure reaching every corner of the country, wealth will increase which will lead to more consumption leading to a second virtuous cycle.

Growth Rate and Per Capita Income: Speaking about the 10 per cent aspirational growth rate, and higher per capita income, Shri Kamath highlighted that given the size of the population, India has no challenge to put up new infrastructure for the next 25 years and put the same to utility. The country has had an agenda for over 20 years that provides momentum for sustainable development. The mark of 8-10 per cent is the combination of growth driven by infrastructure, consumption and other constituents like services, agriculture etc. In his view, the country should have a goal of achieving a growth rate of 8 per cent and a 25 trillion economy by 2047. According to him, funding is not a challenge today. It’s also not true to say that the private-sector capex cycle is not happening. With improvement in cash equivalence, and with very minimum access to borrowings, companies are now investing in themselves on a just-in-time basis without waiting for demand to develop. The new indicator of capital expenditure is therefore the increase in the gross fixed assets and capital working progress and not bank lending.

YouTube Link:
https://www.youtube.com/watch?v=OxSpLouU8Iw

QR Code:

2. Suburban Study Circle meeting held on Friday, 12th July, 2024 @ Bathiya & Associates LLP Andheri.

The meeting was held on Friday, 12th July, 2024 at Bathiya & Associates LLP Andheri. The meeting was led by Group Leader — CA Amit Purohit. CARO 2020 represents a significant shift in the audit reporting landscape, with enhanced requirements aimed at improving transparency and accountability. While these changes present challenges, they also offer opportunities for auditors to add value through more detailed and insightful reporting.

Key discussions in the meeting were about:

  •  Property, Plant, and Equipment: Detailed disclosure regarding title deeds, revaluation, and proceedings involving Benami Property.
  •  Inventory and Working Capital: Reporting on discrepancies of 10 per cent or more in the aggregate of each class of inventory.
  •  Loan Advances and Guarantees: Scrutiny of loans, guarantees, and advances to related parties, including reporting on terms, conditions, and repayment status.
  •  Fraud Reporting: Specific requirements to report any fraud noticed or reported during the year, including actions taken by the auditor. Ensuring the accuracy and completeness of data, especially for inventory and property, can be challenging.
  •  Internal Audit System: Reporting on the existence and effectiveness of an internal audit system. The detailed nature of the new requirements means auditors must perform more comprehensive and in-depth audits.
  •  Maintaining detailed documentation to support the new disclosures is essential but time-consuming.

The group leader shared practical insights to help auditors navigate these challenges and emphasized the importance of ongoing learning and adaptability in the ever-evolving field of audit and assurance.

3. International Economics Study Group meeting on the topic of ‘Analysing Parliament Election Results of 2024’

The meeting was held on Tuesday, 2nd July 2024 through a Virtual platform by Group Leaders CA Harshad Shah and CA Pramod Jain. The unexpected outcome of India’s 2024 election has reasserted the unpredictable nature of its politics — and the strength and resilience of our democracy. The BJP’s significant drop of 63 seats marked a return to coalition politics, presenting significant challenges in parliament. The passage of bills will require substantial compromise, a stark contrast to the previous government’s majority passing. There is no clear sign of pan-India anti-incumbency, especially on the economic front. Mr Jain shared his views on inequality, highlighting ten areas of disparities. He questioned whether Indian democracy will ever mature and emphasized the role of professionals as the “fifth pillar” for the success of Indian democracy.

4. Lecture Meeting on ‘Obligations of Chartered Accountants under PMLA’.

The lecture meeting on “Obligations of Chartered Accountants under PMLA” jointly with the National Institute of Securities Market (NISM) was held virtually on Friday 28th June 2024. More than 200 participants attended the webinar. The lecture was delivered by Mr. Krishnan Vishwanathan. The key takeaways of the session are:

  •  Under PMLA it is an offence to assist in money laundering, and accountants may be responsible for detecting and preventing it, especially regarding predicate offences like bribery.
  •  Only those professionals holding a Certificate of Practice from ICAI, CWA, or ICSI and conducting activities like managing client money or property are obligated to comply with PMLA.
  •  Documentation of AML policies and procedures is crucial to avoid penalties, and these include client acceptance methodologies.
  •  Procedures for periodic reviews and client’s due diligence are essential under PMLA.
  •  Extra caution is needed when dealing with clients in Tax Havens due to the increased risk of money laundering and tax evasion. One has to be aware of beneficial ownership structures, shell companies, and politically exposed persons (PEPs).
  •  Reporting to the Financial Intelligence Unit (FIU) is required, but only for truly suspicious activities with documented justification to avoid overwhelming the authorities.
  • Training for employees and maintaining records for five years are mandatory.
  •  Chartered Accountants can play a role in identifying proceeds of crime like unexplained cash or suspicious accounting entries.
  •  Chartered Accountants need to be cautious when offering professional services, especially certifications or acting as collection centres, to avoid indirectly facilitating money laundering.

BCAS Lecture Meetings are high-quality professional development sessions which are open to all to attend and participate. The readers can view the lecture meeting at the below-mentioned link/code:

YouTube Link:
https://www.youtube.com/watch?v=DJDX-mic1tw&t=19s

QR Code:

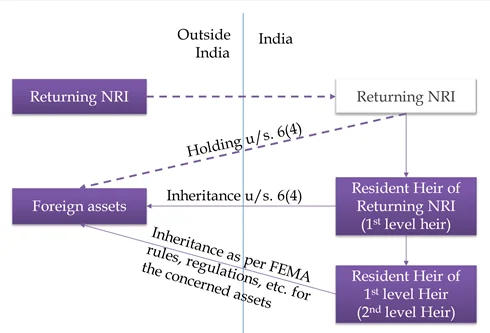
5. FEMA Study Circle Jointly with ITF Study Circle meeting on ‘Cross Border Structuring for Individuals — FEMA and Tax Implications’

The meeting was held on 13th June, 2024, at BCAS in hybrid format. The following relevant points were discussed in the meeting by the group leader — CA Bhavya Gandhi:

  •  Key considerations for cross-border structuring include compliance with FEMA regulations and adherence to Indian tax laws.
  •  Outbound investments must follow the Liberalized Remittance Scheme (LRS) limits and reporting requirements.
  •  Tax residency status of the individual significantly impacts global income tax liabilities.
  •  Proper documentation and valuation are essential to avoid penalties and ensure legal compliance.
  •  Double Taxation Avoidance Agreements (DTAA) should be leveraged to minimize tax burdens.
  •  Repatriation of funds to India requires careful planning to ensure compliance with both FEMA and tax regulations.
  •  Estate planning and inheritance tax implications must be considered in cross-border structuring.
  •  Continuous monitoring and review of the structure are necessary to adapt to any regulatory or tax law changes.

The meeting was attended by 79 members and was well appreciated.

6. Suburban Study Circle Meeting on “Income Tax Aspects of Redevelopment of Society”.

The meeting was held on 05th May and 23rd May, 2024 at Golden Delicacy, Borivali (W)led by CA Sharad Sheth as Group Leader and chaired by CA Nihar Jambusaria and discussions were spread over two sessions.

Group Leader prepared an interesting list of various situations arising in the redevelopment of the Housing Society and shared their views on the following:

  •  When does the transfer of capital assets arises.
  •  Income tax liability on transfer of tenancy right.
  •  When does the benefit of section 45(5A) be availed.
  •  When can exemptions under sections 54 and 54F be claimed.
  •  Analysis of various caselaws on the relevant topic.

The session was thought-provoking with comprehensive discussion on practical issues faced. The session saw lively engagement from 55 + participants and the interactive nature of the discussion enriched the experience of everyone involved.

7. Indirect Tax Laws Study Circle on ‘Export Driven Custom’s Schemes — MOOWR, AEO — Benefits from Customs Perspectives’

The meeting was held virtually on Thursday, 23rd May 2024. The key discussions are done by the Group Leader — CA. Shravan Gehlot, Chennai and Group mentor —Adv. Vikram Naik, Mumbai were as follows:

  •  Manufacturing & Other Operations in Warehouse (MOOWR)
  •  The application and registration process for availing the benefits and covered the key benefits, customs norms for activities in the warehouse and who must opt for the same.
  •  The Authorised Economic Operator (AEO) scheme.
  •  The AEO road map in India since 2001, eligibility criteria, benefits for importers as well as exporters, Customs clearance norms, registration & post registration compliances and other key considerations.
  •  The professional opportunities for the Chartered Accountants in the MOOWR and AEO Scheme.

Around 50 participants all over India benefitted while taking an active part in the discussion on the 2 FTP Customs Schemes.

8. Indirect Tax Laws Study Circle meeting on ‘Issues in Logistic Sector’

The meeting was held virtually on Tuesday, 14th May 2024 Group leader — CA. Darshan Ranavat had prepared case studies and a presentation covering various issues & challenges faced by taxpayers in the Logistic Sector under the GST law. The session was mentored by CA. A R Krishnan. The case studies covered the following aspects for detailed discussion:

  1.  Taxability of clearing & forwarding agents including the claim of pure agent benefits.
  2.  Issues relating to classification and RCM concerning the vessel charter business.
  3.  Issues relating to classification and place of supply concerning the freight forwarding business.
  4.  Issues relating to services provided by GTA to GTA.
  5.  Specific issues in services provided to SEZ

Around 65 participants all over India benefitted by taking an active part in the discussion.

Disallowance under section 13 relating to benefit to interested persons cannot apply to charities notified under section 10(23C)(iv).

33 ITO vs. Theosophical Society

(2024) 163 taxmann.com 770 (ChennaiTrib)

ITA No.: 624 (Chny) of 2024

A.Y.: 2014–15

Date of order: 10th June, 2024

Sections: 10(23C), 13

Disallowance under section 13 relating to benefit to interested persons cannot apply to charities notified under section 10(23C)(iv).

FACTS

The assessee was a society notified under section 10(23C)(iv) and also registered under section 12A(1)(a) of the IT Act. The assessee filed its return of income on 26th September, 2014, admitting NIL income after claiming exemption under section 11.

The AO denied exemption under section 11 on the grounds that two individuals who had made donations to the society [“interested persons”] had stayed in the lodging facilities of the society by paying nominal maintenance charges, and therefore, the society had violated section 13(1)(c)(ii).

CIT(A) allowed all the grounds of appeal of the assessee-society and observed that:

(a) On perusal of details of interested persons, it was seen that those individuals were providing services to the society without remuneration and their stay in guest house was for theosophical work. It was debatable whether such donors to society will be qualified as interested persons. People staying in society lodgings to serve the society are obviously not benefitting from the society as such.

(b) Even if it was so, then such instance would only affect the case of an assessee since sections 11 to 13 relating to interested persons could not be imported to deny exemption under section 10(23C) as per CBDT Circular No.557 dated 19th March, 1990.

Aggrieved, the revenue filed an appeal before ITAT.

HELD

The Tribunal noted that it was an admitted fact that the society was notified under section 10(23C)(iv) and registered under section 12A(1)(a) and held that the conditions prescribed under section 13 of the IT Act were not applicable, as per CBDT Circular No.557 dated 19th March, 1990, once the society was notified under section 10(23C). Similarly, the AO could not make any disallowance under section 11 as the society was an organisation notified under section 10(23C)(iv) of the IT Act.

Author’s note: The law has undergone a change by the insertion of the 21st proviso to section 10(23C) w.e.f. A.Y. 2023–24.

Deeming provision of section 50C is not applicable to leasehold rights in property.

32 Shivdeep Tyagi vs. ITO

(2024) 163 taxmann.com 614(DelTrib)

ITA No.: 484(Delhi) of 2024

A.Y.: 2011–12

Date of order: 18th June, 2024

Section: 50C

Deeming provision of section 50C is not applicable to leasehold rights in property.

FACTS

The assessee, a salaried employee, filed his return of income without declaring capital gains on sale of leasehold property for ₹60,00,000.

Subsequently, based on AIR information, the AO reopened the case. Since the assessee did not file any proof of cost of acquisition of the leasehold property, the assessment was completed under section 143(3) / 147 by taxing the entire sale consideration of ₹75,94,850 for stamp duty purposes under section 50C as against the actual sale consideration of ₹60,00,000.

The assessee did not succeed in the appeal filed before CIT(A). CIT(A) also did not adjudicate on the issue of validity of reopening of assessment.

Aggrieved, the assessee filed an appeal before ITAT.

HELD

Since the issue of validity of reopening of the assessment had not been adjudicated by CIT(A), the Tribunal restored the matter of validity of reopening of the assessment to the file of CIT(A) to decide it afresh.

On merits, the Tribunal observed as follows:

(a) It is axiomatic that the leasehold right in a plot of land is neither “land or building or both” as such nor can be included within the scope of “land or building or both”. The distinction between a capital asset being “land or building or both” and any “right in land or building or both” is well recognised under the Act, as can be seen from section 54D, which shows that “land or building” is distinct from “any right in land or building”;

(b) Section 50C is a special provision for full value of consideration in certain cases and is a deeming provision; therefore, the fiction created therein cannot be extended to any asset other than those specifically provided therein;

(c) Following decision of the coordinate bench in the case of Noida Cyber Park (P.) Ltd., (2021) 123 taxmann.com 213 (Delhi Trib), section 50C, being deeming provision, is not applicable to leasehold right in a plot of land;

(d) However, the AO was empowered to compute capital gains as per the IT Act, without invoking the provisions of section 50C.

Interest earned by a co-operative housing society on investment with co-operative banks in Maharashtra is eligible for deduction under section 80P(2)(d).

31 Ashok Tower “D” Co Op Housing Society Ltd. vs. ITO

(2024) 163 taxmann.com 598 (Mum Trib)

ITA No.: 434(Mum) of 2024

A.Y.: 2015–16

Date of order: 21st June, 2024

Section: 80P

Interest earned by a co-operative housing society on investment with co-operative banks in Maharashtra is eligible for deduction under section 80P(2)(d).

FACTS

The assessee, a cooperative housing society, filed its return of income, claiming deduction under section 80P(2)(d) on the interest income of ₹14,72,930 earned by it from its investment in co-operative banks.

During scrutiny proceedings, the AO denied the deduction under section 80P(2)(d) on the grounds that such deduction is available only in case of investment in another co-operative society and co-operative banks cannot be regarded as “co-operative society” under section 2(19) of the IT Act.

CIT(A) rejected the contentions of the assessee and confirmed the addition made by AO.

Aggrieved, the assessee filed an appeal before the ITAT.

HELD

Noting that a “co-operative bank” is defined under section 2(10) of the Maharashtra Co-operative Societies Act, 1960 to mean a “co-operative society” which is doing the business of banking, the Tribunal held that the amount of investment in fixed deposit receipts or in savings bank account made by the assessee with co-operative banks in Maharashtra is also investment made in co-operative society, and therefore, interest earned thereon is also eligible for deduction under section 80P(2)(d) of the IT Act.

Where assessee sold a land and made investment in new land from sale proceeds of old land in name of his son, assessee is entitled to exemption u/s 54B even if investment was made before registration of sale deed.

30 Siddhulal Patidar vs. ITO

[2024] 111 ITR(T) 541 (Indore – Trib.)

ITA No. 110 (IND.) of 2023

A.Y.: 2011–12

Date of order: 28th February, 2024

Section 54B

Where assessee sold a land and made investment in new land from sale proceeds of old land in name of his son, assessee is entitled to exemption u/s 54B even if investment was made before registration of sale deed.

FACTS

The assessee sold a land vide agreement dated 29th September, 2006 for ₹35,00,000, which was registered on 6th September, 2010. The assessee made a new investment of ₹53,29,440 on 20th June, 2007 in purchase of an agricultural land in the name of his son, Shri Rameshwar Patidar. On the strength of this investment, the assessee had claimed exemption u/s 54B.

The AO had denied the exemption u/s 54B for two reasons, namely:

  •  the new land was purchased in the name of son and not in the name of assessee himself;
  •  the new investment was made on 20th June, 2007 whereas the sale deed was registered on 6th September, 2010; thus, the investment has been made before the date of transfer which is not permitted u/s 54B.

Aggrieved by the assessment order, the assessee filed an appeal before the CIT(A). The CIT(A) confirmed the order of the AO. Aggrieved by the order, the assessee filed an appeal before the ITAT.

HELD

The ITAT followed the decision of Hon’ble Jurisdictional High Court of Madhya Pradesh in PCIT vs. Balmukund Meena ITA No. 188/2016 and held that the assessee can be said to be entitled for exemption u/s 54B even if the registration was taken in the name of son.

As for the second reason, the ITAT relied on the following decisions wherein it is already established that the assessee is eligible for exemption u/s 54B where the investment was made by assessee after execution of sale agreement but before registration of sale deed, from the moneys received under sale agreement:

  •  Dharmendra J. Patel vs. DCIT [2023] 152 taxmann.com 465 (Ahmedabad – Trib.)
  •  Ramesh Narhari Jakhadi vs. ITO [1992] 41 ITD 368 (Pune)
  •  Smt. Narayan F. Patel vs. PCIT [2023] 152 taxmann.com 53 (Surat-Trib.) – It followed the decision of Hon’ble Bombay High Court in Mrs. Parveen P Bharucha vs. Union of India WP No. 10437 of 2011 dated 27th June, 2012 (Para No. 12 of order).

In the result, the appeal of the assessee was allowed for the above-mentioned issue.

EDITORIAL COMMENT

The Hon’ble Punjab and Haryana High Court in the case of Bahadur Singh vs. CIT(A) [2023] 154 taxmann.com 456 (P&H) had rejected assessee’s claim of exemption u/s 54B on the basis of purchase of land in the name of wife and the assessee’s SLP against the said decision was dismissed by Hon’ble Supreme Court vide order dated 29th August, 2023 published in [2023] 154 taxmann.com 457/295 Taxman 313 (SC). The ITAT followed the view favourable to the assessee by relying on the decision of CIT vs. Vegetable Products [1973] 88 ITR 192 (SC) and also mentioned that the Hon’ble SC had dismissed the assessee’s SLP against the decision of Hon’ble Punjab & Haryana High Court by passing a one line summary order; therefore, as per settled judicial view, such dismissal cannot be treated as pronouncement of final law by the Hon’ble Supreme Court.

75th Annual General Meeting and 76th Founding Day

The 75th Annual General Meeting of the BCAS was held on Saturday, 6th July, 2024 at ITC Grand Central Hotel, Ballroom Ground Floor, 287, Dr Baba Saheb Ambedkar Rd, Parel, Mumbai – 400012.

The President, Mr. Chirag Doshi took the chair and called the meeting to order. All the business as per the agenda contained in the notice was conducted, including the adoption of accounts and appointment of auditors.

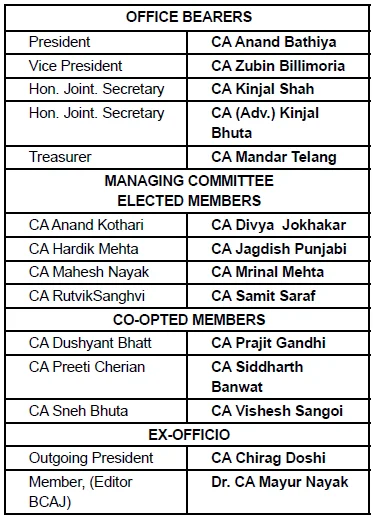
Mr. Mandar Telang, Hon. Joint Secretary, announced the results of the election of the President, the Vice-President, two Honorary Secretaries, the Treasurer and eight members of the Managing Committee for the year 2024–25.

The following members were elected unopposed for the year 2024–25:

Dr CA Mayur Nayak, Editor of the BCAJ, announced the ‘Jal Erach Dastur Awards’ for the Best Article and Best Feature appearing in the BCA Journal during the year 2023–24. The ‘Best Article Award’ was awarded to CA Bhavya Gandhi & CA Naresh Ajwani, for their article ‘Liberalised Remittance Scheme — How Liberal it is? (An Overview and the Recent Amendments’. The ‘Best Feature Award’ went to CA Jagdish Punjabi, Adv. Aditya Bhatt & Adv. Devendra Jain for ‘Tribunal News Part A — Domestic Taxation’. The Editor then announced the ‘S V Ghatalia Foundation Award’ for the ‘Best Article on Audit’. The award went to CA P R Ramesh for the article ‘Future Audit: The Transformation Agenda’.

Before the conclusion of the AGM, members, including Past Presidents of the BCAS, were invited to share their views about the Society.

The July 2024 special issue of the BCA Journal on Bharat and BCAS — The March towards a Centenary was released by the Chief Guest – Padma Bhushan Shri K.V. Kamath.

At the end of the formal AGM proceedings, the 76th Founding Day Lecture was delivered to a packed auditorium. Members and attendees benefitted from the astute deliberation on Viksit Bharat – Role of Accounting and Finance Professionals by Padma Bhushan Shri K.V. Kamath. The meeting formally concluded with CA Kinjal Shah thanking the speaker for sharing his visionary thoughts on a relevant topic with the attendees.

[The video of the lecture can be accessed on the BCAS YouTube Channel, and a Report on the Founding Day lecture is provided in the ‘Society News’ section of this journal.]

OUTGOING PRESIDENT’S SPEECH

Chirag Doshi- “As we celebrate the momentous occasion of the 75th anniversary of the Bombay Chartered Accountants Society (BCAS), we reflect on a rich legacy of excellence, integrity, and innovation. Over these seven and a half decades, BCAS has consistently strived to uphold the highest standards in the profession, fostering a community that values continuous learning and ethical practice. This year, we take pride in commemorating our journey, marked by significant milestones and transformative contributions to the field of chartered accountancy.

5-year plan

Starting this year, the BCAS Managing Committee has initiated the presentation of a comprehensive 5-year plan for the Society. This strategic plan aims to enhance the Society’s reach, foster professional development among its members, provide ample networking opportunities, advocate for important causes, empower the youth through Yuva Shakti initiatives, and drive impactful change through the Chartered for Change program. This endeavour marks a significant step forward in shaping the future trajectory of BCAS and its contributions to the accounting profession.

New initiatives

1. Reach — Social media, Print media, hoarding, new paper ads, outstation meetings. MODI letters, invitees to various meetings before the budget, C&AG, Dubai branch, Abu Dhabi branch, Rakeez authorities, AAA association, MSME panel, jointly with IMC maximum events, BIA felicitation.

2. Professional development — Adaan Pradhan 75 mentees in a year, CAMBA, various Seminars on technology, International webinars, Seminar on FIAS standards, 75 hours duration course on Accounting and Auditing, Professional accountancy courses, International Women’s Day Celebrations – ‘Present Positive = Future Ready’, Full Day Workshop — Use of Technology in GST Compliance

3. Networking — BCAS engage platform, Pan India Networking events for members, RRC and other events had networking focus initiatives, NFC cards at reimagine

4. Advocacy / Research and publications – 1. KYC 2. IND AS 3. Representation to charity commissioners 4. 75 Laws Relevant to Direct Taxes

5. Yuva Shakti – Tarang, JhanCAr was back with a bang and maximum participation, CAMBA, Digital branding seminar, BCAS youth WhatsApp group

6. CA for Change — Digitalisation of schools, science labs, computer labs, BCAS Van.

Various other events: More than 75 events in one year were organized including Lecture Meetings on current topics, webinars, outstation meetings, RRCs, NRRC, student events, study circle meetings, workshops, seminars and non-technical sessions and events

Reimagine – The 75th year ……..

Journey of Re-Imagine: Started in February 2023, when 2 committees were formed the technical committee led by Past presidents — Shariq Contractor, Anil Sathe, Abhay Mehta and the celebrations committee led by Pranay Marfatia, Uday Sathaye and Narayan Pasari. I remember attending my first president’s meeting (many call them mothers-in-law, I call them my biggest supporters and guides), there were big thoughts and expectations in the eyes of each of the Presidents. Despite the big responsibilities they had put on my shoulders, they also had kept their both hands on my head. Post that I spoke to my OB team about the big bash in the year we can achieve and only one common word came we can and let’s go for it. The youth Managing Committee was all geared up to take their part in responsibilities and never even once hesitated for the task allocated to them. I just loved the power, enthusiasm and kuch kar gujarne ki chahat of this young and vibrant Office Bearers Team and Managing committee.

It was not as easy as it looked, 12 topics with no tax clauses, no case studies, no Accounting standards, no Auditing Standards, chosen by each committee of BCAS and the Technical team. 50+ Stalwarts Speakers 3 Padma accolades, 7 CFOs, 2 International Speakers, 2 Media Anchors, 5 Founders, several senior professionals, lawyers, capital market regulators and players, MBAs, bankers and venture capitalists, top-notch moderators and many more.

Friends, it was not as easy as it looked and was made by the celebration committee, opening ceremony, organising and arrangement for sponsors, souvenirs, managing seamless registration of 1200 professionals, 3 lunches, 2 dinners, family registrations, kits, speakers travel to stay and all other arrangements were so seamless.

It was not as easy as it looked, communications, pre-meetings, lounge interviews and engagement, use of technology like pigeon hole, the seamless sound and light support, graphics and timely changing of slides, adhering to minute-to-minute planning, social media push, 21+ journalists and 41+ media covering the event, no cancellation or delay of speakers.

Friends, it was the achievement of a miracle with the complete dedication of all of us together.The famous dialogue comes to my mind, Jab tum kisi cheez ko dil se chahete ho to sari kyanat tumara saath deti hai.

Thanking everyone,

First and foremost, I sincerely thank the Past Presidents, whose invaluable guidance and support have been instrumental to my effective functioning. I express my deepest appreciation to my Office Bearer colleagues for their unwavering support and active involvement in our planned activities. I am profoundly grateful to all the Managing Committee members, Trustees of the BCAS Foundation, Chairmen (Manish bhai, Abhay bhai, Nitin bhai, Deepak bhai, Sunil bhai, Rajesh bhai, Mayurbhai, Udaybhai, Ameet bhai, Mihir bhai and Co-Chairmen of the committees Anil bhai, Chetan bhai, Raman bhai, Nandita ben and Anand Kothari), convenors, coordinators, YUVA Shakti, students forum and core group members and the entire team of BCAS for their steadfast support across various initiatives. My special thanks to Nileshbhai Vikamsey, Raj Mullick, Manish Sampat, Sudhir Soni, Anil Desai, Anand Vashi, Rajaramji, Purvi Malani, Gautam Nayak and Gautam Shah for their support during Re-Imagine.

I also extend my heartfelt thanks to our Members, Subscribers, Speakers, Students, Social Media followers, Staff, Vendors, Donors, Sponsors, Printers of our publications, Service providers, Statutory and Internal auditors, Consultants, and Office Bearers of various sister organisations, Contributors to the journal, all of whom who have wholeheartedly supported our initiatives throughout the year. The success of our Society is a testament to your faith and patronage. At this moment I would like to thank my grandmother whom we lost this year at the age of 99, my father and my mother, my ever-supportive wife Khushboo and my all-time problem solver, my daughter Jhalak.

As we move forward, our focus must remain sharply attuned to understanding the evolving times and the needs of our members. I am confident that the newly elected President Anand Bathiya and his team of Office Bearers, the Managing Committee, and the Core Group will continue to uphold and advance the vision of the Society, further enhancing its legacy. I wish them every success in the coming year.

Jai hind! Jai BCAS!”

INCOMING PRESIDENT’S SPEECH

CA ANAND BATHIYA—

Excerpts from the address of the Incoming President (Scan here to watch the full video).

Youtube link: https://www.youtube.com/watch?v=rzW4eqHlIcY&t=1525s

“Good evening and a very warm welcome to this momentous and historical 75th AGM of our beloved Society.

A. Context

75 years is a very big milestone in the lifetime of an organization. The mere fact that an organization ‘survives’ for such a long period is in itself an exception, forget being a thriving, growing and vibrant organization like BCAS.

BCAS today is not just an organization but an Institution, an Institution that has stood the test of time and delivered on its promise exceedingly well.

It is a curious case of how a handful group of people who used to meet on Wednesdays today snowballed into a mammoth organization with members spread across 350+ towns and cities in India. With no regulatory powers, and no mandatory learning hours support, how is it that thousands of professionals each year look up to an organization as an epitome of Professional Development? The journey of BCAS is a textbook case study on Institution Building that outlives generations and continues to operates for its cause.

At this cusp of 75 years, we are celebrating durability, we are celebrating continuity, we are celebrating adaptability, and we are celebrating Longevity. It would be only right for us to reflect on what have been the real ingredients that shaped BCAS longevity as we see it today. What have been the differentiators that gave BCAS this longevity?

In these characteristics might also lie the answers to our future.

As I pondered through my journey at BCAS, first as an observer, then as a member, then as a Core Group Member and as an Office Bearer, I credit this longevity of BCAS to three distinct themes:

1. Selfless Volunteerism — Swayam Sevak

– High-quality volunteers working shoulder to shoulder for a greater purpose. The organization has somehow institutionalised the process of filtering committed volunteers, motivating, grooming and taking them up the ladder.

– When high-quality volunteers work with a ‘Seva’ mindset, it creates wonders.

– Volunteer-led selfless service of Seva has translated into Strong Successive Leadership that keeps the flag high.

– It is this combination of Swayam and Seva that has created the right Sanskaar at BCAS.

2. Staying relevant& building capabilities–Saksham

– There is constant urge in the collective consciousness at BCAS, to stay relevant and build capabilities.

– Be it around professional development challenges, having younger members, adopting technology or any such contemporary challenge.

– BCAS has over the years remained relevant and adapted to changing times.

– That organizational consciousness and alertness have held us high — The Sanskrit Subhashitam that we hold in our emblem – Na Bhaya Chasti Jagrata, is a reflection of this spirit. The one who is conscious and alert, need not fear.

3. Staying Focused & purposeful —Seem it

– Single-mindedness of purpose, remaining apolitical and not spreading ourselves too thin.

– At BCAS we realise our limitations as well, which is very important.

– It is unconventional but very deep to:

  • Opt for Stability over Growth.
  • Opt for Values over Value.
  • Opt for Commitment over Competence.
  • Opt for Depth over Breath.

– Sometimes being Best is more important than being Big.

These three pillars of Swayam, Saksham and Seem it have become our Swabhaavat BCAS.

We are built not for a sprint, but for a long marathon and better still a relay marathon. This has been our character; this has been our Swabhaav and it is this Swabhaav of BCAS that has allowed us to witness this beautiful day today.

It is from our Swabhaav that our Strengths and Weaknesses emerge, and it is in our Swabhaav that our Challenges and Opportunities lie.

B. My Journey at BCAS

Though my formal tryst with BCAS started as a Core Group member exactly 10 years before in 2014, my first engagement with BCAS started in 2011 when I was invited to speak at a session on IFRS in the year 2011. I distinctly remember, that I had my ICAI convocation on the same day, and a young convenor of the Accounting & Auditing Committee in the form of Manish Sampat called me to take up this session. We spoke and for whatever reason I chose to speak at the BCAS session and gave a pass to my convocation. And I jokingly tell people that I got convocated at BCAS.

The journey then continued with Power Summitsto then being again invited to present the first paper at the first Youth RRC held in 2013. This was the place where we made lots of friends Chirag, Kinjal, Mandar, Rutvik, Mahesh, Shreyas and many more who are now a part of the Managing Committee or Office Bearer pools.

It was in 2014 that Naushadbhai Panjwani inducted me to the Membership and Public Relations committee and I became a close on-looker to the inner functioning of the BCAS subsequently spending more time with the Corporate and Allied Laws Committee.

All through these 10 years, it’s been a journey of immense learning and realization both professionally as well as personally. Each passing day, month and year has been an occasion of tremendous learning and extreme satisfaction.

My father used to narrate a very nice story of 3 masons/construction workers. These 3 masons were working at a construction site. A passer-by comes and asks one mason,“Brother what are you doing?” The first mason replies, “I am laying a brick.” The passer-by walks on and asks the other mason, “Brother what are you doing?” The second mason replies, “I am making a wall”. The passer-by walks on and asks the third mason, “Brother what are you doing?” The third mason replies, that “I am making a temple”.

Throughout these 10 years, travelling through committees we had the privilege to pass through these stages where we visualised ourselves as ‘laying a brick’, to ‘building a wall’ and over the last year understanding the ‘Temple that we are building and supporting’ consciously or unconsciously.

So much so that over the last fortnight, me and Zubinbhai have had the privilege to attend 10 Committee meetings and those really opened up our understanding of the strength of BCAS and the Core Group. Imagine each of the chairpersons (who are much senior and much-established professionals) before they start the meeting, requested the President to provide ‘guidance’ on the year forward. To us, it was a lesson in humility and organization building.

When I was young, in our colony during Janmashtami, we had the Dahi-Handi festivities. I would be 9–10 years of age and they decided to make me the symbolic Krishna and decked me up with the robes, head gears etc. The seniors in the colony painstakingly made human pyramids, fell a few times but yet got up and finally when it was settled, popped me up to break the Dahi Handi. On that day I felt so much joy, so much sense of achievement that it was me and everyone clapped for me.

Today is a similar day, whilst I may have the symbolic pleasure of being appointed as the President, it is sitting on the strong shoulders of multiple past presidents and core group volunteers who have held the pyramid and laid the foundation.

It is completely to their wisdom, judgment and vision that we stand here today and I really hope and pray that we can make our community proud and live up to the high expectations.

C. Team and Plan for 2024–25

As they say, sitting on the shoulders of giants, we can see how far, we will use this occasion to move further in the coming year with our agenda of Professional Development. Fresh on the back of a very successful 75th year, we will further enhance the momentum that we gained in the last year.

In a voluntary setup like BCAS, there is no task that is easy ‘without’ the support of the Team and there is no task that is difficult ‘with’ the support of the Team. Over the last 45 days, we have worked towards assembling a committed Team that will enable realizing plans for the coming year.

In Zubin Billimoria, we have a formidable Vice President who brings decades of experience to the table, unmatched commitment and attention to detail.

In Kinjal Shah and Mandar Telang, we have a combination of strong capabilities and technological prowess to navigate us further. And now with the welcome addition of Kinjal Bhuta to the Office Bearers team, we have a very well-balanced Office Bearersteam with high execution capabilities.

Happy to share that we perhaps have an all-time young Office Bearers team, with an average age of 43 years, significantly down from the average age of 54 years just 5 years before.

The Managing Committee is our altar of governance as well as our reservoir of future leaders. It is this managing committee that is going to lead our Society through the glorious years of Amrit Kaal. We have consciously opted for continuity and this young team has gotten younger with the addition of Prajit Gandhi, who holds a lot of promise. The average age of MC today stands at 42 years, again down from 49 years 5 years before.

This year we had a lot of churnat chairmanship for 10 committees at BCAS. One of the years when we effectuated changes to chairmanship in 5 out of 10 committees. In another, we have a non-past president as a co-chairman in a Technical Committee as Rutvik Shanghvi takes the position of Co-Chairmanship of the very important International Tax Committee.

With many new additions to the Core Group as well, I remain confident of being in pole position to set sail into the Amrit Kaal for BCAS.

Last year we decided to move away from an Annual Thematic Plan to a 5-Year Strategic Plan. We plan to accelerate on the tenants of that 5-Year Strategic Plan and build on the back of the success we experienced last year. As we move forward on our 6-point Hexagonal Plan, we will amplify our impact by:

1. Putting in the rigours of Execution: Ideas are only as good as our execution abilities, and we plan to bring the rigours of effective execution through this dedicated team of volunteers.

2. Harnessing Technology to the maximum: This is one thing that we have been working on for the past few years and we now have a reasonably equipped tech stack. We plan to further build on this to ease the challenges of execution and enhance our member experience.

Amongst the Key Projects that we will focus on include:

1. Mount 11,000 — A membership enhancement and reach project.

2. BCAS Academy — Implementing a self-paced learning digital infrastructure.

3. Sherpa Project — Complete the appointment of 75 sherpas across 75 towns \ cities in India.

4. Collaborations — Research and Industry collaborations.

5. BCAS Studio — Building in-house audio\visual capabilities.

6. BCAS Podcasts — New way of consuming content.

7. BCAS BroadCASt — Member communication initiative.

8. Membership Formats — Evaluate different membership formats, timings, nature, etc.

9. Member Townhalls — Regular engagements, orientations and inductions.

10. Digital Certifications & Tech Enablement — WhatsApp Chatbot, digital badge and certification

Whilst we will do a few Different Things, we will do a lot of things Differently. Realizing the need for continuity in some of these initiatives, the capabilities at the back office have also been strengthened.

D. Conclusion

In no uncertain words, I would like to express my deepest gratitude and thanks

(i) to the BCAS members, Core Group, Past Presidents and the Managing Committee members for expressing their faith in me,

(ii) to my parents, who are here today for always being a guiding light in my personal and professional journey,

(iii) to my life partner and backbone Silky, who has graciously agreed to share me for one more year as I embark upon this journey,

(iv) to my younger brothers Janak and Haseet for the rock-solid support they offer, both at home and at the office.

With these words, the blessing of the almighty and seniors, love and support of friends and family, I humbly bow down with great humility as I accept this prestigious responsibility as the 76th President of Bombay Chartered Accountants’ Society. Thank you once again”.

Addition made by Assessing Officer during reassessment proceedings, not being based on any incriminating material during search and seizure action, was to be deleted.

29 Ashish Jain vs. DCIT

[2024] 111ITR(T)152 (Chd – Trib.)

ITA No. 352 (CHD) of 2023

A.Y.: 2012–13

Date of order: 23rd January, 2024

Section: 153A

Addition made by Assessing Officer during reassessment proceedings, not being based on any incriminating material during search and seizure action, was to be deleted.

FACTS

A search and seizure operation u/s 132(1) was carried out at the residential and business premises of M/s Jain Amar Clothing Pvt. Ltd. Group of cases on 26th February, 2016, and the assessee’s premises were also searched on the said date. Thereafter, a notice dated 28th September, 2016 u/s 153A was issued upon the assessee.

The assessee had purchased 1,700 equity shares of M/s. Maple Goods Pvt. Ltd. in F.Y. 2010–11 through share broker S.K. Khemka. M/s. Maple Goods Pvt. Ltd. was later on amalgamated with M/s. Access Global Ltd. and as against 1 share of M/s Maple Goods (P) Ltd., 47 equity shares of M/s Access Global Ltd. were allotted. The shares of M/s. Access Global Ltd. were received in D-Mat account of the assessee. The assessee had sold these shares in F.Y. 2012–13 and earned long-term capital gains (LTCG) of ₹87,04,733 thereon.

The AO had referred upon the report of the Directorate of Income-tax (Inv.), Kolkata dated 27th April, 2015, which stated that the share of M/s Access Global Ltd. and M/s Maple Goods (P) Ltd. resembled the character of Penny Stocks and provided accommodation entries in the guise of LTCG. The AO further referred to the documents so seized from the locker no. 194, HDFC Bank, Ludhiana which belonged jointly to Shri Sunil Kumar Jain, the father of the assessee and Smt. Kamla Jain, the grandmother of the assessee and that documents so seized were share certificates of M/s Maple Goods (P) Ltd. in respect of shares purchased by the assessee through Shri S.K. Khemka and the copy of the contract cum bill notes issued by Shri S.K. Khemka. The AO also referred to the statement recorded on oath on 13th March, 2015 of Shri S.K. Khemka who had admitted to provide “kachhapanna” [Purchase Contract Notes] of M/s Maple Goods (P) Ltd. and provided bogus LTCG entries to the assessee.

During the course of assessment proceedings, the assessee submitted that no incriminating material was found during the action of search but the AO stated that the said contention is not tenable and treated the LTCG of ₹87,04,733 as bogus and added to the total income of the assessee treating the same as unexplained cash credit under section 68 of the Act.

Aggrieved by the assessment order, the assessee filed an appeal before the CIT(A). The CIT(A) in its order held that the assessment order and remand report of the AO dated 5th February, 2020, clearly brought on record the share certificates and the contract bills seized from the bank locker no. 194, HDFC Bank which belonged jointly to Shri Sunil Kumar Jain, the father of the assessee and Smt. Kamla Jain, the grandmother of the assessee on the basis of which bogus LTCG had been claimed by the assessee were incriminating in nature as they had a direct bearing on the estimation of correct income of the assessee. Further, on merits as well, various contentions raised by the assessee were rejected, and the findings and order of the AO was confirmed.

Aggrieved by the order, the assessee filed an appeal before the ITAT.

HELD

The ITAT observed that it was an undisputed fact that the assessee had purchased 1,700 equity shares of M/s. Maple Goods Pvt. Ltd. in F.Y. 2010–11 through share broker S.K. Khemka, which were later on amalgamated with M/s. Access Global Ltd and received 79,900 shares of M/s. Access Global Ltd. The assessee had earned LTCG gains of R87,04,733 in A.Y. 2012–13 from sale of these shares which were disclosed in the original return of income u/s 139(1) of the Act.

The only issue was whether the documents seized from the bank locker no. 194, HDFC Bank – share certificate / contract cum bill notes in the name of the assessee issued by Shri S.K. Khemka for purchase of shares of M/s. Maple Goods Pvt. Ltd were incriminating material found during the course of search in case of the assessee.

The assessee had submitted that:

  •  it is a case of unabated assessment, and during the course of search on the assessee, no incriminating material / evidence was found in respect of LTCG on shares;
  •  the share certificates and the contract notes relating to purchase of shares cannot be an incriminating material; rather the said documents support the case of the assessee that the purchase of shares is genuine and is backed by proper documents;
  •  the statements of Shri S.K. Khemka and Shri Sunil Kumar Kayan and others had nothing to do with the search proceedings of the assessee as these were recorded during their respective investigation proceedings way back in the year 2015.

The ITAT held that the term “incriminating material” has to be read and understood in the context of one or more of the conditions stipulated in section 132(1) of the Act, on satisfaction of which a search can be authorised and search warrant can be issued. Therefore, the information in possession of the competent authority at the time of authorisation of search becomes relevant, and on the basis of the same, his satisfaction that search action is warranted coupled with material actually found and seized during the course of search which has not been disclosed or produced or submitted in the course of original assessment.

The ITAT further held that in case of unabated assessment, the reassessment can be made on the basis of the satisfaction note pursuant to which the search has been initiated and books of account or other documents not produced in the course of original assessment but found in the course of search which indicate undisclosed income or undisclosed property, and the reassessment can be made on the basis of the undisclosed income or undisclosed property which is physically found and discovered in the course of search.

Applying the aforesaid legal proposition, the ITAT held that it was not the case of the revenue that the locker from which the documents were seized was in the possession of the assessee or was being operated by the assessee, and thus, what was found and seized was from the possession of third persons, who no doubt were part of the assessee’s family and covered as part of the same search proceedings, but the same cannot be held as found during the course of search in case of the assessee.

The ITAT further observed that though the assessee was part of the search proceedings and action was initiated u/s 153A in his case, the same doesn’t take away the statutory requirement of recording of satisfaction note by the AO of family members whose locker was searched and from where the documents belonging to the assessee were found and seized.

The ITAT held that:

  •  it was an admitted and undisputed position that the assessee had purchased the shares of M/s Maple Goods (P) Ltd. during the F.Y. 2010–11 relevant to A.Y. 2011–12 and thus, the said transaction doesn’t pertain to impugned A.Y. 2012–13 and cannot be held as incriminating in nature for the impugned A.Y.;
  •  the assessee had purchased the shares wherein the payment was made through normal banking channel and the transaction was duly reflected and disclosed in the bank statement;
  •  proceedings for A.Y. 2011–12 were also reopened u/s 153A pursuant to search action and the reassessment proceedings were completed u/s 153A r/w 143(3) vide order dated 29th December, 2017 where the AO has not recorded any adverse findings regarding the aforesaid purchase of shares;
  •  the transaction of sale and purchase of shares have been duly disclosed as part of the original return of income, and the assessment thereof stood completed / unabated as on the date of search;
  •  the share certificates and contract notes represent and corroborate a disclosed transaction of purchase and sale of shares as part of the original return of income and cannot be termed as incriminating material so found and seized during the course of search;
  •  where there is no incriminating material found during the course of search, the statement of Shri S.K. Khemka (and what has been stated therein) which is recorded well before the date of search in case of the assessee and in the context of some other proceedings, independent of the impugned search proceedings, is availability of certain “other material / documentation” with the AO during the course of reassessment proceedings but not material / documentation which is incriminating in nature found during the course of search in case of assessee for the impugned assessment year.

In view of the aforesaid discussion and in the entirety of facts and circumstances of the case, the ITAT was of the view that the addition of ₹87,04,733 made by the AO during the reassessment proceedings completed u/s 153A is not based on any incriminating material found or seized during the course of search and seizure action u/s 132 of the Act in case of the assessee. Being a case of completed / unabated assessment, in absence of any incriminating material found during the course of search, the addition so made cannot be sustained and was directed to be deleted.

In the result, the appeal of the assessee was allowed.

The loss incurred on the sale of shares on stock exchange platform, where STT was duly paid, is eligible to be set of against the long-term capital gain earned by the assessee from sale of unlisted shares.

28 Rita Gupta vs. DCIT

ITA No. 46/Kol./2024

A.Y.: 2014–15

Date of Order: 6th June, 2024

Sections:10(38), 45, 70, 74

The loss incurred on the sale of shares on stock exchange platform, where STT was duly paid, is eligible to be set of against the long-term capital gain earned by the assessee from sale of unlisted shares.

FACTS

The assessee filed return of income on 31st July, 2014, declaring total income of ₹18,31,980. The Assessing Officer (AO) assessed the total income of the assessee, making various additions including the addition of ₹47,90,616, resulting on non-allowance of set off of loss from sale of equity shares on recognised stock exchange with STT paid against the profit on sale of unquoted equity shares. The AO held that the long-term capital gain on sale of quoted shares is exempt u/s 10(38) of the Act and similarly, the loss incurred was also not liable to be set off against the other taxable income.

Aggrieved, the assessee preferred an appeal to the CIT(A) who dismissed the appeal of the assessee and confirmed the action of the AO on this issue on the same reasoning that since long-term gain from sale of securities / shares are exempt in terms of provisions of Section 10(38) of the Act, and therefore, on the same analogy, the long-term capital loss resulting from the sale of equity shares with STT paid cannot be allowed to be set off against the taxable long-term capital gain resulting from sale of any other asset.

Aggrieved, assessee preferred an appeal to the Tribunal.

HELD

The Tribunal having perused the provisions of sections 2(14), 45, 47, 70 to 74 held that it is only the long-term capital gain resulting from sale of shares / securities which was granted exemption u/s 10(38) subject to the fulfilment of certain conditions and not the entire source which was excluded from the aforesaid sections. Therefore, when the entire source is not excluded from the charging section and only special type of income is excluded, then the interpretation of law has to be made strictly and cannot be deemed to include any other income or loss resulting or falling within the same source. The case of the assessee is squarely covered by the decision of Hon’ble jurisdictional High Court in the case of Royal Calcutta Turf Club vs. CIT [144 ITR 709 (Cal)].

The Tribunal noted that:

i) the Co-ordinate Bench in another decision in the case of Raptacos Brett & Co Ltd. [69 SOT 383] has also decided the similar issue by following the decision of Calcutta High Court in the case of Royal Calcutta Turf Club vs. CIT (supra) and by considering the decision of CIT vs. Hariprasad & Co. Pvt. Ltd. [99 ITR 118] as relied by the CIT(A);

ii) the decision of Hon’ble Apex Court in the case of CIT vs. Hariprasad & Co. Pvt. Ltd. (supra) did not apply to the case of the assessee as the principle laid down in the above decision would be applicable if entire source is excluded from the charging section.

The Tribunal having perused the decision relied upon by the CIT(A) found that except two decisions of the coordinate benches namely Nikhil Sawhney [119 taxmann.com 372] and DDIT vs. Asia Pacific Performance SICAV [55 taxmann.com 333] and decision of Gujarat High Court in the case of Kishorebhai Bhikhabhai Virani vs. ACIT [367 ITR 261], all others are distinguishable of facts.

In the case of Nikhil Sawhney (supra), the Co-ordinate Bench has relied on the decision of Supreme Court in the case of CIT vs. Hariprasad& Co. Pvt. Ltd., which has been rendered on the different principle that the income includes loss; however, the said legal proposition would apply only when the entire source is exempt and not liable to tax and not as in a case where the income falling within such source is treated as exempt. The Hon’ble Supreme Court in the case of Hariprasad & Co. Pvt. Ltd. (supra) has held that the expression “income” shall include loss because the loss is nothing but negative income. But in our opinion, the principle laid down by the Hon’ble Apex Court that income includes negative income can be applied only when the entire source of income falls within the charging provision of Act but where the source of income is otherwise chargeable to tax but only a specific kind of income derived from such source is granted exemption, then in such case, the proposition that the term “income” includes loss would not be applicable. Thus, if the source which produces the income is outside the ambit of charging provisions of the section, in such case negative income or loss can be said to be outside the ambit of taxing provisions. Consequently, the negative income is also required to be ignored for tax purpose. In other words, where only one of the streams of income from a source is granted exemption by the legislature upon fulfilment of specified conditions, then the concept of income includes loss would not be applicable. Similarly, the second decision of DDIT vs. Asia Pacific Performance SICAV (supra) has relied on the decision of Hariprasad & Co. Pvt. Ltd. [55 taxmann.com 333], CIT vs. J H Gotla [156 ITR 323], and CIT vs. Gold Coin Health Food Pvt. Ltd. [304 ITR 308], which are distinguishable of facts. In the case of Kishorebhai Bhikhabhai Virani vs. ACIT [367 ITR 261], the issue was decided against the assessee; but in the said decision, the decision of Hon’ble Calcutta High Court in the case of Royal Calcutta Turf Club (supra) has not been referred at all, and considering the ratio laid down by the Hon’ble Supreme Court in the case of CIT vs. Vegetable Products Ltd. 88 ITR 192 (SC), where there are two construction, then the construction / interpretation which is in favour of the assessee has to be followed.

The Tribunal held that the loss incurred on the sale of shares on stock exchange platform, where STT was duly paid, is eligible to be set of against the long-term capital gain earned by the assessee from sale of unlisted shares.

Letter to the Editor

To,

The Editor,

BCAJ,

Mumbai

Dear Sir,

Greetings. I have been regularly reading the versatile “Bombay Chartered Accountant Journal” edited by you.

The varieties of subjects cater to the needs of all strata of practising/in industry Chartered Accountants.

I look forward to reading the “Editorial” every month.

The icing on the cake in June journal was “Who died” by Vazeji.

Keep up the excellent work you are doing.

All the best.

Payment made by assessee to tenants of a co-operative housing society towards alternate accommodation charges / hardship allowance / rent are not liable for deduction of tax at source under section 194I.

27 ITO vs. Nathani Parekh Constructions Pvt.

ITA Nos. 4088 and 4087/Mum/2023 and 4101 and 4100/Mum/2023

A.Ys.: 2013–14 & 2016–17

Date of Order: 21st May, 2024

Sections: 194I, 201

Payment made by assessee to tenants of a co-operative housing society towards alternate accommodation charges / hardship allowance / rent are not liable for deduction of tax at source under section 194I.

FACTS

The assessee, a real estate developer, engaged in the business of development and construction, entered into a redevelopment agreement with M/s Dalal Estate Co-operative Housing Society Ltd. In the course of survey conducted under section 133A(2A) of the Act, it was found that the assessee has debited amounts under the head “Alternate Accommodation / Rent” in each of the four years under appeal.

The Assessing Officer (AO) called upon the assessee to explain why tax has not been deducted at source in respect of the payments debited under the head “Alternate Accommodation / Rent”. The assessee submitted that it has entered into a re-development agreement dated 30th April, 2017 with M/s Dalal Estate Co-operative Housing Society Ltd., which was encumbered with more than 300 tenants and that for the purpose of vacating the premises, the assessee had agreed to pay compensation of hardship according to the nature of tenancy occupied by each tenant. The assessee further submitted that these tenants could not be provided the alternate accommodation, and therefore, the assessee agreed to pay the above amount as compensation for the hardship of the tenants. The assessee also submitted that the amount paid towards alternate accommodation / hardship allowance does not fall within the definition “Rent”, and therefore, tax was not liable to be deducted at source on the said payments. The assessee accordingly submitted that no tax was deducted at source from the payment of alternate accommodation charges / rent.

The AO did not agree with the contentions of the assessee and held that the payment made by the assessee is liable for deduction of tax at source under section 194I of the Act.

Aggrieved, the assessee preferred an appeal to the CIT(A) who allowed the appeal of the assessee by relying on the decisions of the Co-ordinate Bench in the case of Jitendra Kumar Madan (32 CCH 59, Mumbai), Sahana Dwellers Pvt. Ltd. [2016] 67 taxmann.com 202 (Mum. Trib.) and Shanish Construction Pvt. Ltd. in ITA Nos. 6087 and 6088/Mum/2024 dated 11th January, 2017.

Aggrieved, the revenue preferred an appeal to the Tribunal.

HELD

The Tribunal noted that the common issue arising in each of the four appeals preferred by the Revenue is “Whether the payment made by the assessee to the tenants of M/s Dalal Estate Co-operative Housing Society Ltd. towards alternate accommodation charges/hardship allowance/rent are liable for tax deduction under section 194I of the Act.”

On behalf of the assessee, it was contended that:

i) the impugned payment is made in lieu of the alternate accommodation which the assessee could not provide to the tenants / members of the society;

ii) the definition of term “Rent” as per the provisions of section 194I which states that the payment which is made towards use of land or building. In assessee’s case, the payment is made not towards the use of land or building but as a compensation for the hardship that the tenants would undergo by vacating the property for the purpose of re-development;

iii) the CIT(A) has correctly relied on the various decisions of the Co-ordinate Bench which has been consistently holding that the amount paid towards compensation / hardship allowance is not taxable in the hands of the tenants for the reason that the same is not paid towards use of land or building but for the hardship in vacating the property for re-development;

iv) the Hon’ble Bombay High Court in the case of Sarfaraz S. Furniturewalla vs. Afshan Sharfali Ashok Kumar & Ors in Writ Petition No. 4958 of 2024, has held that the “transit rent” i.e., the rent paid by the developer to the tenant who suffers due to dispossession is not a revenue receipt and is not liable to be taxed. As a result, there will not be any question of deduction of TDS from the amount payable by the developer to the tenant.

The Tribunal having quoted the decision of the Bombay High Court in Sarfaraz S. Furniturewalla (supra) observed that the Hon’ble High Court in the above decision has held that the transit rent which is paid to the tenant who suffers hardship due to dispossession does not fall within the definition “rent” under section 194I. It held that in assessee’s case, the payment is made towards compensation for handing over the vacant possession of the property and towards rent if any payable by the tenants in the alternate accommodation until the completion of the re-development.

Applying the ratio of the decision of the Hon’ble High Court, the Tribunal held that the payment made by the assessee towards “Alternate accommodation charges / rent” is not liable for tax deduction under section 194I, and accordingly, the Tribunal upheld the order passed by the CIT(A) for A.Y. 2013–14 to 2016–17, setting aside the order of the AO treating the assessee as an assessee in default for non-deduction and non-payment of TDS under section 194I of the Act.

Section 9(1)(vi): Supply of software — “Royalty” — Article 12 under the Indo-US DTAA.

11 CIT (IT) -3 Mumbai vs. M/s. Lucent Technologies GRL LLC

Income Tax Appeal (L) Nos. 3695 & 3693 of 2018

A.Ys.: 2006–07 & 2010–11 alongwith other companion appeals

Dated: 1st July, 2024 (Bom) (HC)

Section 9(1)(vi): Supply of software — “Royalty” — Article 12 under the Indo-US DTAA.

The Revenue has raised the following question of law:

“Whether on the facts and in the circumstances of the case and in law, the Tribunal has erred in not holding payments received by the assessee for supply of software to Reliance Infocomm Limited (now Reliance Communication Limited) to be in the nature of “royalty” under Section 9(1)(vi) of the Income Tax Act, 1961?”

In the connected Appeals, the question of law as raised is similar, which by consent of the parties was re-framed as under:

“Whether on the facts and circumstances of the case and in law, the Tribunal has erred in holding that the payment made to assessee did not amount to income of the payee by way of ‘royalty’ under Section 9(1)(vi) of the Income Tax Act, 1961?”

The Respondent-assessee filed its return of income declaring NIL income, and also claimed Tax Deducted at Source (TDS) from the payments received from the purchasers (referred as “Reliance”). The return as filed by the Respondent was taken up for scrutiny. The Assessing Officer was of the view that receipts of the amounts in question from Reliance were on account of supply of the copyright software as per the terms of the Wireless Software Assignment and License Agreement. However, the case of the assessee was to the effect that the amount was a business income and was not taxable in India, in the absence of assessee having a Permanent Establishment (PE) in India.

The Respondent-assessee contended that the Revenue receipts were in terms of the sale, as the software supplied to Reliance was not a customised software but a software which was sold to several clients. The AO did not agree with the assessee’s case, and held that the supply of such software amounted to a transfer of intellectual property rights, and hence, the consideration paid to the assessee was in fact towards a license to use the software as no title or interest in the software was transferable to the user. The AO, accordingly, held that the transaction not being a sale of the software and being a payment received for the license to use such software, it was taxable as “royalty” in terms of Section 9(1)(vi) of the Act, read with relevant Article of the Double Taxation Avoidance Agreement (DTAA) (i.e., Article 12 under the Indo-US DTAA and similar clauses in the other DTAA’s). Thus, the amount received by the assessee from Reliance was assessed as royalty and, accordingly, was sought to be taxed.

The assesee’s appeal was adjudicated by the CIT(A) taking into consideration the agreements in question, as also the transaction being viewed and considered on the applicability of Section 9(1)(vi) of the Act and the relevant Articles of the DTAA, namely, Article 12. The CIT(A) accordingly held that such amount received by the assessee did not amount to receipt of “royalty” within the meaning of Section 9(1)(iv) of the Act.

The Revenue being aggrieved by such orders of the CIT(A) carried the proceedings before the Tribunal. By the impugned orders, the Tribunal confirmed the orders passed by the CIT(A) by upholding the contentions as raised on behalf of the assessee and recording finding against the Revenue.

The Hon. Court observed that the question whether the payments made by Reliance Communication Limited for obtaining computer software, whether were liable to be taxed in India as ‘royalties’ under the provisions of Section 9(1)(vi) of the Act, had fallen for consideration of the Court in a batch of appeals filed by the Revenue on similar issues filed against Reliance Industries Ltd., came to be disposed of by an order dated 24th June, 2024.

The Respondent-assessee submitted that once in respect of the party making payment to the assessee, such question of law had fallen for consideration of the Court, and when the Court had come to a considered view that the payment for software which was supplied by the assessee was not liable to be taxed as “royalty” under the provisions of Section 9(1)(vi) of the Act, then certainly, the present assessee, which had in fact supplied the software, cannot be treated differently and the same parameters of law would be required to be applied.

The Hon. Court observed that the question of law as raised by the Revenue in the present batch of appeals would stand covered by the orders in Income Tax Appeal No. 1655 of 2018 and also a batch of appeals decided on 24th June, 2024 in Income Tax Appeal No. 28 of 2018 and other connected appeals.

The Court further observed that the order dated 24th June, 2024 passed in Income Tax Appeal No. 28 of 2018 is also required to be noted.

The Hon. Court observed that the question of law would stand covered by the authoritative pronouncement of the Supreme Court in the case of Engineering Analysis Centre of Excellence (P.) Ltd. vs. Commissioner of Income Tax 2. [2021] 125 taxmann.com 42 (SC).

The Revenue appeals were accordingly dismissed.
No costs.

Section 148 / 151: Reopening of assessment — Beyond three years — Sanction by the specified authority.

10 Cipla Pharma and Life Sciences Limited vs. Dy. CIT Circle – 1(1)(1)

WP NO. 149 OF 2023

A.Y.: 2016–17

Dated: 2nd July, 2024, (Delhi) (HC)

Section 148 / 151: Reopening of assessment — Beyond three years — Sanction by the specified authority.

The primary ground of challenge before the Hon. High Court was that the impugned notice u/s. 148 of the Act had been issued in breach of the provisions of Section 151 of the Act, which provides for a sanction by the specified authority before issuance of notice.

The Petitioner-assessee contended that the sanction to issue the impugned notice dated 30th July, 2022 was issued by the Principal Commissioner which itself is contrary to the provisions of Section 151(ii), in as much as admittedly the impugned notice was issued after a period of more than three years having elapsed from that of the relevant assessment year 2016–17. Accordingly, such sanction ought to have been issued by the Specified Authority as set out in Section 151(ii) and not by an authority falling under clause (i) of the said provision. It was contended that once such compliance itself was lacking, the impugned notice issued under Section 148 would be rendered illegal, and on such count, would be required to be quashed and set aside. In support, reliance was placed on the decision of the Division Bench of this Court in Siemens Financial Services Pvt. Ltd. vs. Deputy Commissioner of Income Tax, Circle 8 (2)(1), Mumbai &Ors. (Writ Petition No. 4888 of 2022, decided on  25th August, 2023).

The Hon. Court observed that on a plain reading of Section 148A, it is clear that the Assessing Officer (AO) before issuing any notice under Section 148 is required to follow the procedure as set out in clauses (a) to (d) of Section 148A. One of the pre-conditions as ordained by clause (d) of Section 148A is that an order under such provision can be passed by the AO only with the approval of “Specified Authority”. Thus, necessarily when clause (d) of Section 148A provides for prior approval of specified authority, it relates to the provisions of Section 151 of the Act providing for “Specified authority for the purposes of Section 148 and Section 148A of the Act”. In the present case, Section 151 as amended by the Finance Act, 2021 and Section 148A as also introduced by Finance Act, 2021 have become applicable, as although the assessment year in question is 2016–17 in respect of which the assessment is sought to be reopened by issuance of notice under Section 148, which is dated 30th July, 2022. Such amended provision would squarely become applicable the date of notice under section 148 itself being 30th July, 2022.

The Hon. Court further observed that the record clearly indicates that the sanction in the present case was issued by the Principal Commissioner which can only be in respect of cases if three years or less than three years have elapsed from the end of the relevant assessment year, as would fall under the provisions of clause (i) of Section 151 of the Act. As in the present case, the assessment year in question is 2016–17 and the impugned notice itself has been issued on 30th July, 2022, it is issued after a period more than three years having elapsed from the end of the said assessment year. Accordingly, clause (ii) of Section 151 of the Act was applicable, which required the sanction to be issued by either Principal Chief Commissioner or Principal Director General or where there is no Principal Chief Commissioner or Principal Director General, Chief Commissioner or Director General for issuance of notice under Section 148 of the Act.

The Hon. Court further observed that such an issue fell for consideration of the Division Bench of this Court in Siemens Financial Services Pvt. Ltd. (supra), wherein the Division Bench considered the provisions of Section 151 of the Act read with the provisions of Section 148A(b). The latter provision clearly provided that prior to issuance of any notice under Section 148 of the Act, the AO shall provide an opportunity of being heard to the assessee, only after considering the cumulative effect of Section 148A(b) read with Section 151 of the Act. As provided under sub-clause (d), the AO shall decide on the basis of material available on record, including reply of the assessee, whether or not it is a fit case to issue a notice under Section 148 by passing an order, with the prior approval of specified authority within one month from the end of the month in which the reply is received. The sanction of the specified authority has to be obtained in accordance with the law existing when the sanction is obtained. Therefore, the sanction is required to be obtained by applying the amended Section 151(ii) of the Act, and since the sanction has been obtained in terms of Section 151(i) of the Act, the impugned order and impugned notice are bad in law and should be quashed and set aside.

The Hon. Court further observed that the respondent’s case based on the notification dated 31st March, 2020 issued under the Taxation and Other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020 (for short, “TOLA”) was concerned, the Court held that such notification was a subordinate legislation, and it could not override the statute enacted by the Parliament and in that regard, the position in law was discussed by the Division Bench in Siemens Financial Services Pvt. Ltd. (supra), paragraph 27 of the said decision.

The impugned notices are quashed and set aside, the petition is allowed.

Writ — Competency to file writ petition — Chartered Accountant authorised to represent assessee in income-tax matters — Chartered Accountant could file writ against order of assessment.

36 TiongWoon Project and Contracting Pte. Ltd. vs. CBDT

[2024] 463 ITR 641 (Mad)

A.Ys. 2012–13 and 2013–14

Date of order: 22nd January, 2024

ART. 226 of Constitution of India

Writ — Competency to file writ petition — Chartered Accountant authorised to represent assessee in income-tax matters — Chartered Accountant could file writ against order of assessment.

The petitioner is a company incorporated in Singapore and engaged in undertaking turnkey construction projects involving erection, installation and commissioning activities. In these two writ petitions, the petitioner assails a common order dated 3rd November, 2023 refusing to condone delay in filing the return of income of the petitioner for the A.Y. 2012–13 and 2013–14. The writ was signed by the chartered accountants. The assessee-company had authorised the chartered accountants to represent it in relation to its Income-tax assessments and all other proceedings arising therefrom.

The standing counsel for the respondents raised the preliminary objection that the writ petition should not have been filed by the chartered accountants of the petitioner. By referring to the authorisation issued by the petitioner to the chartered accountants, it was submitted that the authorisation does not extend to the conduct of proceedings before this court. A reference was also made to the ethics code of the Institute of Chartered Accountants of India and the annual report of TiongWoon Corporation Holding Ltd. to contend that the chartered accountants through whom the writ petitions were filed were the statutory auditors of one of the subsidiaries of the above-mentioned holding company, and that the chartered accountants should not act as authorised representatives in such situation.

Rejecting the preliminary objection of the Respondents, the Madras High Court held as under:

“The authorisation in favour of the chartered accountants was on record and the assessee-company had authorised the chartered accountants to represent it in relation to its Income-tax assessments and all other proceedings arising therefrom. Although proceedings before the court were not expressly referred to the language of the authorisation was wide enough to embrace these proceedings. As regards the alleged breach of the ethics code, even if established, that could not be the basis to reject this petition.”

Regulatory Referencer

I. DIRECT TAX: SPOTLIGHT

1. Forms 3CN, 3CS, 3CEC, 3CEFB, 59 and 59A shall be furnished electronically – Notification No. 01/2024-25 dated 24th June, 2024

II. COMPANIES ACT, 2013

No News to report

III. SEBI

1. “Saarthi 2.0” app with tools, calculators, and modules, offering financial insights to investors launched: SEBI has launched “Saarthi 2.0” mobile app, enhancing its user-friendly interface and providing comprehensive financial tools. The app includes financial calculators, modules on KYC procedures, mutual funds, ETFs, and the stock exchange, as well as investor grievance mechanisms and the Online Dispute Resolution platform. It aims to empower investors, especially young ones, with unbiased and essential insights into the securities market, adapting to evolving market conditions. [Press Release No. N.10/2024, dated 3rd June, 2024]

2. Master Circular for ‘Bankers to an Issue registered with SEBI: SEBI has issued an updated master circular for ‘Bankers to an Issue registered with SEBI’. This circular compiles all existing circulars issued till date. This is done in order to enable the stakeholders to have an access to all the applicable circulars/directions at one place. [Circular No. SEBI/HO/AFD/AFD-POD-2/P/CIR/2024/72, dated 30th May, 2024]

3. FPI norms amended: SEBI has notified SEBI (Foreign Portfolio Investors) (Amendment) Regulations, 2024. It states that a foreign portfolio investor (FPI) must pay the registration fees as provided in Part A of Second Schedule for every block of 3 years before the beginning of such a block. However, registration fees shall be considered paid if FPI pays fee along with late fee within 30 days from expiry of preceding block. [Notification No. SEBI/LAD-NRO/GN/2024/183, DATED 31st May, 2024]

4. FPI Master Circular modification: SEBI has modified the Foreign Portfolio Investors (FPI) Master Circular. The amended norms provide flexibility to foreign portfolio investors (FPIs) in dealing with their securities after their registration expires. Similar changes have been carried out in the Foreign Portfolio Investors (FPI) Master Circular. [Circular No. SEBI/HO/AFD/AFD-POD-2/P/CIR/2024/76 AND 77, dated 5th June, 2024]

5. SEBI mandates direct pay-out of securities by clearing corporation to demat accounts of clients: At present, securities received in payout are pooled by the broker before being credited to the respective client demat accounts. However, the direct payout to client accounts was already made available on a voluntary basis as per the circular dated 1st February, 2001. It has now been decided that the process of direct securities payout to client accounts will become mandatory. The provisions of this circular will come into effect on 14th October, 2024. [Circular No. SEBI/HO/MIRSD/MIRSD-POD1/P/CIR/2024/75, dated 5th June, 2024]

6. SEBI notifies framework of ‘Financial Disincentives for Surveillance Related Lapses’: The SEBI has notified a framework for Surveillance Related Lapses at Market Infrastructure Institutions (MIIs). This shall be applicable to lapses emanating from non-adherence to the requisite surveillance activities / decisions. [Circular No. SEBI/HO/ISD/ISD-POD-1/P/CIR/2024/73, dated 6th June, 2024]

7. Guidelines on ‘Anti-Money Laundering Standards and Combating Financing of Terrorism’ for intermediaries: SEBI has issued guidelines on ‘Anti-Money Laundering Standards and Combating Financing of Terrorism’ for intermediaries. The guidelines set out the essential principles for combating Money Laundering (ML) and Terrorist Financing (TF) and provide detailed procedures and obligations for all registered intermediaries to follow and comply with. Also, intermediaries may require clients to specify additional disclosures to address concerns about ML and suspicious transactions undertaken by clients. [Master Circular No. SEBI/HO/MIRSD/MIRSDSECFATF/P/CIR/2024/78, dated 6th June, 2024]

8. ‘Master Circular on KYC norms’ for KRAs Integration with Central KYC Records Registry: SEBI has notified amendment in ‘Master Circular on KYC Norms’ with respect to Uploading of KYC information by KYC Registration Agencies (KRAs) to Central KYC Records Registry (CKYCRR). Now, KRAs shall ensure that existing KYC records of legal entities and of individual clients are uploaded on to CKYCRR within a period of 6 months from 1st August, 2024 ill 1st February 2025. Also, KRAs shall integrate with CKYCRR and start uploading KYC records by 1st August, 2024. [Circular No. SEBI/HO/MIRSD/SECFATF/P/CIR/2024/79, dated 6th June, 2024]

9. Updated Master Circular on ‘Portfolio Managers’: SEBI has issued an updated master circular on ‘Portfolio Managers’. This will facilitate access to all the applicable requirements at one place, all the circulars issued till 31st March, 2024. [Circular No SEBI/HO/IMD/IMD-POD-1/P/CIR/2024/80, dated 7th June, 2024]

10. Demat and Mutual Fund accounts won’t be frozen over non-submission of nomination: Earlier, SEBI extended the deadline for submitting the ‘choice of nomination’ for Demat accounts and mutual fund folios to 30th June, 2024. Now, SEBI has clarified that non-submission will not result in freezing these accounts. Further, security holders with physical securities will receive payments and services even without submitting the nomination. Also, existing investors are encouraged to submit nominations to ensure smooth transmission of securities and prevent unclaimed assets. [Circular No. SEBI/HO/MIRSD/POD-1/P/CIR/2024/81, dated 10thJune, 2024]

11. Introduction of a ‘special call auction mechanism’ for price discovery of scrips of listed investment companies: SEBI has introduced a ‘special call auction mechanism for effective price discovery of scrips of listed investment companies (ICs) and investment holding companies (IHCs). SEBI directs that ICs or IHCs must be identified based on uniform industry classifications provided by stock exchanges. Further, scrips of ICs or IHCs must have been listed and available for trading for a period of at least 1 year. The first special call auction must be conducted by stock exchanges in the month of October 2024. [Circular No. SEBI/HO/MRD/MRD-POD-3/P/CIR/2024/86; dated 20th June, 2024]

12. Updated ‘Master Circular for Electronic Gold Receipts (EGRs)’: Now, in order to enable the stakeholders to have access to all the provisions mentioned in the earlier issued circulars at one place, SEBI has issued an updated master circular incorporating all subsequent circulars issued on EGRs till 31st May, 2024. [Master Circular No. SEBI/HO/MRD/MRD-POD-1/P/CIR/2024/87, dated 24th June, 2024]

13. Updated ‘Master Circular for Mutual Funds’: SEBI has been issuing various circulars from time to time to effectively regulate the Mutual Fund Industry. Now, in order to enable the stakeholders to have an access to all the regulatory requirements at one place, SEBI has issued an updated master circular incorporating all subsequent circulars issued till date. The master circular supersedes the master circular for mutual funds dated 19th May, 2023. [Master Circular No. SEBI/HO/IMD/IMD-POD-1/P/CIR/2024/90, dated 27th June, 2024]

IV. FEMA

I. Draft Import and Export Regulations issued for public response:

The Notifications dealing with Import and Export are in force since RBI has decided to rationalise regulations that cover export and import transactions. The proposed regulations are intended to promote ease of doing business, especially for small exporters and importers. They are also intended to empower Authorised Dealer banks to provide quicker and more efficient service to their foreign exchange customers. The draft regulations under FEMA and draft directions meant for Authorised Dealer banks are available online on RBI’s website for public response. Comments / feedback on the draft proposals (regulations as well as directions) may be forwarded by 1st September, 2024. Readers are welcome to share their feedback with BCAS which will compile and share response to RBI.

[Press Release: 2024-2025/615 dated 2nd July, 2024]

II. Limits applicable on remittances allowed with online filing of Form A2 now removed:

RBI has allowed online filing of Form A2 for remittances for transactions with an upper limit of USD 25,000 for individuals and USD 100,000 for corporates. RBI has now decided to allow remittance through online filing of Form A2 without any limit.

[A.P. (DIR SERIES 2024-25) CIRCULAR NO. 12, DATED 3rd July, 2024]

III. Form A2 applicable for all cross-border remittances:

For any current account transaction up to USD 25,000 Authorised Dealers are permitted to release foreign exchange on the basis of a simple letter containing basic information. No other documents were required including Form A2. However, RBI has now decided that Authorised Dealers shall obtain Form A2 in physical or digital form for all cross-border remittances irrespective of the value of transaction.

[A.P. (DIR SERIES 2024-25) CIRCULAR NO. 13, DATED 3rd July, 2024]

IV. IFSCA designates 4 additional currencies as ‘specified foreign currencies’:

IFSCA has notified IFSCA (Banking) (Amendment) Regulations, 2024. An amendment has been made to the First Schedule relating to ‘specified foreign currencies’. The IFSCA has designated four additional currencies as ‘specified foreign currencies’ under First Schedule. These currencies include Swedish Krone (SEK), New Zealand Dollar (NZD), Danish Krone (DKK) and Norwegian Krone (NOK).

[Notification IFSCA/GN/2024/004 dated 4th July, 2024]

V. RBI expands the scope of Foreign Currency Account held by Residents in IFSC:

At present, remittances under LRS to IFSCs can be made by Residents only for:

a. Making investments in IFSCs in securities except those issued by entities/ companies resident in India (outside IFSC); and

b. Payment of fees for education to foreign universities or foreign institutions in IFSCs for pursuing gazetted courses.

For these permissible purposes, resident individuals can open Foreign Currency Account (FCA) in IFSCs.

On a review, RBI has decided that Authorised Persons may facilitate remittances for all permissible purposes under LRS to IFSCs for:

a. Availing financial services or financial products as per the International Financial Services Centres Authority Act, 2019 within IFSCs; and

b. All current or capital account transactions, in any other foreign jurisdiction (other than IFSCs) through an FCA held in IFSCs.

This brings FCA in IFSC at part with FCA in any other foreign jurisdiction for remittances of all current and capital account transactions covered under the LRS.

[A.P. (DIR SERIES 2024-25) CIRCULAR NO. 15, DATED 10th July, 2024]

VI. Extension in deadline for filing of FLA returns to 31st July 2024:

The deadline for filing the Annual Foreign Liabilities and Assets (FLA) Return for Financial year (FY) 2023-24 was 15th July, 2024. However, there were technical glitches on RBI’s Foreign Liabilities and Assets Information Reporting (FLAIR) portal where the return is to be uploaded. Therefore, RBI has extended the due date to 31st July, 2024.

[Announcement on RBI’s FLAIR System]

Revision — Powers of Commissioner — Commissioner (Appeals) holding amounts included in fringe benefits tax return not chargeable to fringe benefits tax — Revision application for refund of fringe benefits tax — Revision application rejected on grounds of delay — Commissioner conferred with power to condone delay to do substantial justice — Commissioner (appeals) taking long time to dispose of appeal — Commissioner ought to have condoned delay — Order rejecting revision application quashed — Direction to condone delay and consider revision application on merits and pass reasoned order.

35 Hindalco Industries Ltd. vs. UOI

[2024] 464 ITR 236 (Bom.)

A.Y. 2007–08

Date of order: 17th January, 2024

Ss. 115WD(1) and 264 of the ITA 1961

Revision — Powers of Commissioner — Commissioner (Appeals) holding amounts included in fringe benefits tax return not chargeable to fringe benefits tax — Revision application for refund of fringe benefits tax — Revision application rejected on grounds of delay — Commissioner conferred with power to condone delay to do substantial justice — Commissioner (appeals) taking long time to dispose of appeal — Commissioner ought to have condoned delay — Order rejecting revision application quashed — Direction to condone delay and consider revision application on merits and pass reasoned order.

For the A.Y. 2007–08, the Commissioner (Appeals) by order dated 31st August, 2016, held the amounts included in the fringe benefits tax return as not chargeable to fringe benefits tax. Since the Commissioner (Appeals) allowed the claim of the assessee, the assessee filed an application u/s. 264 of the Income-tax Act, 1961 for refund of the fringe benefits tax return. The Commissioner rejected the revision application on the grounds of substantial delay in filing the application and that the intimation u/s. 143(1) of the Act was not an assessment order.

The assessee preferred a writ petition contending that the Commissioner (Appeals) took almost five to six years to decide that the amounts included in the fringe benefits tax returns were not chargeable to fringe benefits tax and hence there was no delay in filing the revision application. The Bombay High Court allowed the writ petition and held:

“i) On the issue of condonation of delay in an application filed u/s. 264 of the Income-tax Act, 1961, courts have held that the authorities should not take a pedantic approach but should be liberal. The courts have held that the words ‘sufficient cause’ should be given a liberal construction so as to advance substantial justice when no negligence or inaction or want of bona fides is imputable to the assessee. The courts have held that the principle of advancing substantial justice is of prime importance and while considering the question of condonation, the revisional authority is not all together excluded from considering the merits of the revision petition.

ii) U/s. 264 of the Act, the Commissioner is empowered either on his own motion or on an application made by the assessee to call for the record of any proceedings under the Act and pass such order thereon not being an order prejudicial to the assessee and this power has been conferred upon the Commissioner in order to enable him to give relief to the assessee in cases of over-assessment.

iii) The Commissioner having been conferred power to condone the delay to do substantial justice to parties by disposing of the matter on the merits should, considering the facts and circumstances of the case, in particular that it took a long time for the Commissioner (Appeals) to dispose of the assessee’s appeal, have condoned the delay. The order rejecting the application u/s. 264 of the Act was quashed and set aside. The Commissioner was directed to condone the delay and consider the application u/s. 264 of the Act on the merits and pass a reasoned order in accordance with the law.”

Revision — Rectification of mistake — Time limit — Computation of long-term capital gains — Sale of flat inherited by the assessee and three others — Omission of claim of deduction of indexed renovation expenses in return of income — Rejection of application for rectification and revision on grounds that new claim not raised earlier — Revision Application within one year from the date of rectification order — AO accepting indexed renovation expenses in case of co-owner — Amount accepted in co-owner’s case to be accepted as correct and allowance to be made while computing long-term capital gain.

34 Pramod R. Agrawal vs. Principal CIT

[2024] 464 ITR 367 (Bom.)

A.Y.: 2007–08

Date of order: 13th October, 2023

S. 48, 143(3), 154 and 264 of ITA 1961

Revision — Rectification of mistake — Time limit — Computation of long-term capital gains — Sale of flat inherited by the assessee and three others — Omission of claim of deduction of indexed renovation expenses in return of income — Rejection of application for rectification and revision on grounds that new claim not raised earlier — Revision Application within one year from the date of rectification order — AO accepting indexed renovation expenses in case of co-owner — Amount accepted in co-owner’s case to be accepted as correct and allowance to be made while computing long-term capital gain.

The assessee was a co-owner of a flat which was inherited by the assessee along with three others. The assessee’s share was to the extent of 25%. In the return of income, the assessee offered capital gains from the sale of the said flat. The assessee offered the capital gains without claiming the indexed cost of improvement in respect of the renovation expenses incurred. On the advice of the chartered accountant that a co-owner had sought rectification and had been allowed deduction of the entire renovation expenses of the flat from full value of consideration, while computing the share of capital gains, the assessee also filed an application u/s. 154 of the Act seeking rectification by allowing deduction of indexed cost of improvement being renovation expenses not claimed in the original return of income. The assessee’s application for rectification was rejected on the grounds that the claim was made for the first time in the application u/s. 154 and it was never brought to the attention of the lower authorities earlier. Against this order rejecting the assessee’s application for rectification of mistake, the assessee filed a revision application u/s. 264 of the Act which application was also rejected.

Against this order rejecting the assessee’s application u/s. 264, the assessee filed a writ petition before the High Court. The Bombay High Court allowed the petition and held that:

“i) Section 264 confers wide jurisdiction on the Commissioner. The proceedings u/s. 264 of the Act are intended to meet a situation faced by an aggrieved assessee who is unable to approach the appellate authorities for relief and has no alternate remedy available under the Act. The Commissioner is bound to apply his mind to the question whether the assessee was taxable on that income and his powers are not limited to correcting the error committed by the sub-ordinate authorities but could even be exercised where errors are committed by the assessee. It would even cover situation where the assessee because of an error has not put forth legitimate claim at the time of filing the return and the error is subsequently discovered and is raised for the first time in an application u/s. 264 of the Act.

ii) There was no delay in filing the application u/s. 264 of the Income-tax Act, 1961 because the application u/s. 264 of the Act was against the order passed u/s. 154 of the Act and not that passed u/s. 143(3) of the Act. The order u/s. 154 of the Act was passed within one year from the date of application filed u/s. 264 of the Act.

iii) In the assessment order passed in the case of another co-owner of the flat, the Assessing Officer had accepted certain amount as the cost of indexed renovation. Therefore, the amount had to be accepted as correct and suitable allowance should be made while arriving at the long-term capital gains. The order is quashed and set-aside. The matter was remanded for de novo consideration and to pass a reasoned order after providing the assessee with an opportunity of hearing.”

Return of income — Delay in filing revised return — Condonation of delay — Power to condone — Meaning of “genuine hardship” — Power vested in authority to be judiciously exercised — Compensation received on compulsory land acquisition inadvertently declared as income — Payment of tax more than liability is “genuine hardship” — Department to enable assessee to file revised return of income.

33 K. S. Bilawala and Others vs. Principal CIT

[2024] 463 ITR 766 (Bom.)

A.Y. 2022–23

Date of order: 16th January, 2024

S. 119(2)(b) of the ITA 1961

Return of income — Delay in filing revised return — Condonation of delay — Power to condone — Meaning of “genuine hardship” — Power vested in authority to be judiciously exercised — Compensation received on compulsory land acquisition inadvertently declared as income — Payment of tax more than liability is “genuine hardship” — Department to enable assessee to file revised return of income.

For the A.Y. 2022–23, the assessee inadvertently declared as income the compensation received by him on acquisition of its land under the provisions of the Right to Fair Compensation and Transparency in Land Acquisition, Rehabilitation and Resettlement Act, 2013. The return of income was processed u/s. 143(1) of the Income-tax Act, 1961 and the assessee received an intimation. Thereafter, the assessee filed an application u/s. 119(2)(b) for condonation of delay and leave to file a revised return. The application was rejected on the grounds that he did not show any genuine hardship which was caused due to delay in the application.

The assessee filed the writ petition challenging the rejection order. The Bombay High Court allowed the writ petition and held as under:

“i) The phrase ‘genuine hardship’ used in section 119(2)(b) of the Income-tax Act, 1961 should be considered liberally. There cannot be a straitjacket formula to determine what is genuine hardship. The power to condone delay has been conferred to enable the authorities to do substantial justice to the parties by disposing of matters on the merits. While considering these aspects, the authorities are expected to bear in mind that no applicant stands to benefit by filing delayed returns. Refusing to condone the delay can result in a meritorious matter being thrown out at the very threshold and the cause of justice being defeated, but, when the delay is condoned, a cause would be decided on the merits after hearing the parties.

ii) When the assessee felt that the amount of compensation that it received under the 2013 Act need not have been offered to tax, under the 1961 Act, the authority should have condoned the delay and considered the matter on the merits. The fact that an assessee had paid more tax than what he was liable to pay would cause hardship and that would be a ‘genuine hardship’. The delay in filing the revised return was to be condoned and accordingly the Department was to enable the assessee to file the revised return for the A. Y. 2022-23. Thereafter, the authority could decide whether or not the compensation received by the assessee under the 2013 Act was liable to tax.”

Reassessment — Notice — Sanction of Authority — Application of mind to material on basis of which reopening of assessment sought for by AO — Discrepancy in quantum of escapement of income in order in initial notice and order for issue of notice — Not noticed by concerned Sanctioning Authorities — Non-application of mind in passing sanction order — Orders and consequent notice set aside.

32 Vodafone India Ltd. vs. Dy. CIT

[2024] 464 ITR 385 (Bom.)

Date of order: 19th March, 2024

Ss. 147, 148, 148A(b), 148A(d) and 151 of the ITA 1961

Reassessment — Notice — Sanction of Authority — Application of mind to material on basis of which reopening of assessment sought for by AO — Discrepancy in quantum of escapement of income in order in initial notice and order for issue of notice — Not noticed by concerned Sanctioning Authorities — Non-application of mind in passing sanction order — Orders and consequent notice set aside.

In this case, the petitioner is impugning a notice dated 30th March, 2023, u/s. 148A(b) of the Income-tax Act, 1961, an order dated 19th April, 2023 passed u/s. 148A(d) of the Act and a notice dated 19th April, 2023 issued u/s. 148 of the Act on various grounds. One of the grounds raised across the Bar is that the sanction for issuance of the order u/s. 148A(d) of the Act has been granted without application of mind by all the five officers involved.

The Bombay High Court allowed the petition and held:

“i) The power vested in the sanctioning authorities u/s. 151 of the Income-tax Act, 1961 to grant or not to grant approval to the Assessing Officer to reopen the assessment u/s. 147 is coupled with a duty. The sanctioning authorities are duty bound to apply their mind to the proposal put up for approval considering the material relied upon by the Assessing Officer and cannot exercise their power casually on a routine perfunctory manner. While recommending and granting approval it is obligatory on the part of the officers to verify whether there is any genuine material to suggest escapement of income on all the authorities and the Principal Chief Commissioner in particular to consider whether or not power to reopen is being invoked properly.

ii) The contention that the record had been carefully considered before granting approval u/s. 151 was an incorrect statement made by the Principal Chief Commissioner. The information annexed to the notice issued u/s. 148A(b) had stated the quantum of income that had escaped assessment more than the amount mentioned in the order passed u/s. 148A(d) without any explanation as to how the amount had changed or had been reduced. In the affidavit it was stated that in the notice the value of the transaction in question was taken gross and subsequently it was seen that there were duplicate entries which were corrected while passing the order u/s. 148A(d). The notice did not contain any duplicate entries. If there were duplicate entries, the Assessing Officer was duty bound to clarify in the order and also give details of what were those duplicate entries and should have come clean on the error made. If the Principal Chief Commissioner or the other officers had seen the records and had applied their mind those errors would not have crept in. This displayed non-application of mind by all those persons who had endorsed their approval for issuance of notice u/s. 148.

iii) Had the authorities read the record carefully, they would have never come to the conclusion that this was a fit case for issuance of notice u/s. 148 and would have either told the Assessing Officer to correct the amounts or would have sent the papers back for reconsideration. They had substituted the form for substance, important safeguards provided in sections 147 and 151 were treated lightly by the concerned officers. The order of approvals u/s. 151, having been granted mechanically and without application of mind in a most casual manner, were quashed and set aside. The order passed u/s. 148A(d) and the consequent notice issued u/s. 148 were also quashed and set aside.”

Offences and prosecution — Compounding of offences — Application for — Limitation — Application can be filed either before or subsequent to launching of prosecution — Circular issued by CBDT stipulating limitation period of 12 months — Contrary to legislative intent of provision — Application for compounding rejected as barred by limitation period prescribed in circular issued by CBDT — Not sustainable — Relevant clause of Circular struck down — Matter remitted to decide application on the merits.

31 Jayshree vs. CBDT

[2024] 464 ITR 81 (Mad)

A.Y.: 2013–14

Date of order: 3rd November, 2023

S. 119(1) and Explanation to S. 279(2) of the ITA 1961

Offences and prosecution — Compounding of offences — Application for — Limitation — Application can be filed either before or subsequent to launching of prosecution — Circular issued by CBDT stipulating limitation period of 12 months — Contrary to legislative intent of provision — Application for compounding rejected as barred by limitation period prescribed in circular issued by CBDT — Not sustainable — Relevant clause of Circular struck down — Matter remitted to decide application on the merits.

During the previous year relevant to the A.Y. 2013–14, the assessee sold an immovable property and reinvested the capital gains in the purchase of another immovable property. The Assessee was under the impression that since there was no liability to pay income tax, she was not required to file return of income and, therefore, did not file her return of income. The return of income was filed belatedly on 13th June, 2016. Subsequently, she was prosecuted for delay in filing of the return. In view of provisions of section 279(2) of the Act, the assessee filed an application for compounding of offence in the year 2021. The application was rejected on the grounds that it was filed beyond the time limit of 12 months from the date of launching prosecution which was prescribed under the Circular F. No. 285/08/2014-IT(Inv.) 147 dated 14th June, 2019.

The assessee filed the writ petition and challenged the order of rejection. The Madras High Court allowed the writ petition as under:

“i) The power of the CBDT u/s. 119(1) of the Income-tax Act, 1961 to issue circulars, directions and instructions should not be exercised beyond the scope of the Act. The CBDT is not empowered to fix the time limit for filing the application for compounding of offences u/s. 279, which is contrary to the provisions of section 279(2) in terms of which the assessee can file the application for compounding of offences either before or subsequent to the launching of the prosecution. The Explanation to section 279 which empowers the CBDT to issue circulars is only for the purpose of implementation of the provisions of the Act with regard to the compounding of offences and not for the purpose of fixing the time limit for filing the application for compounding of offences.

ii) Nowhere in section 279(2), had a time limit been mentioned for filing an application for compounding of offences u/s. 279 though the Explanation thereunder, stated that the CBDT was empowered to issue orders, circulars, instructions and directions for the purpose of implementation of the Act. The intention of the legislation for bringing section 279(2) was to permit the assessee to file an application for compounding of offences either before institution of proceedings or after institution of proceedings. The fixing of a time limit by the CBDT by way of a Circular was contrary to the intention of the legislation and amounted to amendment of section 279(2). Since the idea of the legislation was that the compounding of offences was permissible either before or after the institution of the proceedings, the CBDT could not issue a circular contrary to the object of the provisions of section 279. Clause 7(ii) of Circular F.No. 285/08/2014-IT(Inv.V)/147, dated June 14, 2019 was beyond the scope of the Act and hence, that portion of the circular was to be struck down.

iii) The matter was remitted to the authority to decide the application on the merits in accordance with law.”

Offences and prosecution — Failure to file returns in time — Relief from prosecution — Effect of proviso to s. 276CC — Prepaid taxes resulting in NIL liability — Prosecution u/s. 276CC not valid.

30 Manav Menon vs. DCIT

[2024] 463 ITR 752 (Mad)

A.Y. 2013–14

Date of order: 17th November, 2023

S. 276CC of ITA 1961

Offences and prosecution — Failure to file returns in time — Relief from prosecution — Effect of proviso to s. 276CC — Prepaid taxes resulting in NIL liability — Prosecution u/s. 276CC not valid.

For the A.Y. 2013–14, the Assessing Officer filed complaint for the offence punishable u/s. 276CC of the Income-tax Act, 1961 for non-filing of income-tax return. The crux of the complaint is that the accused is an assessee within the jurisdiction of the respondent. During the course of proceedings for assessment, the respondent detected that the petitioner failed to file his return of income for A.Y. 2013–14. As per section 139(1) of the Income-tax Act, the petitioner ought to have filed the return of income on or before 30th September, 2013.

The assessee filed a criminal writ petition for quashing the prosecution proceedings. The Madras High Court allowed the writ petition and held as under:

“i) Filing of the Income-tax return is mandatory in nature u/s. 139(1) of the Income-tax Act, 1961 and failure to file the Income-tax return is punishable u/s. 276CC of the Act, 1961. The proviso to section 276CC gives some relief to genuine assessees. The proviso in clause (ii)(b) to section 276CC provides that if the tax payable determined by regular assessment as reduced by advance tax paid and tax deducted at source does not exceed ₹3,000, such an assessee shall not be prosecuted for not furnishing the return u/s. 139(1) of the Act. Therefore, this proviso takes care of genuine assessees who either file their returns belatedly but within the end of the assessment year or those who have paid substantial amounts of their tax dues by prepaid taxes from the rigour of the prosecution u/s. 276CC.

ii) A perusal of the records revealed that admittedly the assessee had failed to file his return of income for the A. Y. 2013-14. However, the assessee had paid taxes under the heads of advance tax, tax deducted at source, tax collected at source, and self assessment tax to the tune of ₹23,75,066. According to his returns, the total tax and interest payable by him was ₹23,74,610. Therefore, he had claimed a refund of ₹460 and the proviso (ii)(b) to section 276CC would come to the rescue of the assessee from the rigour of the prosecution u/s. 276CC of the Act. Therefore, the initiation of prosecution for the offence punishable u/s. 276CC of the Act could not be sustained.”

Accrual of income — Meaning of accrual — Time of accrual — Assessee terminating lease following dispute — Assessee not accepting lease rent — Matter before Small Causes Court — Small Causes Court allowing lessor to deposit lease rent in Court specifying that deposit was allowed without prejudice to rights of contestants — Matter still pending in Small Causes Court — Lease rent did not accrue to the Assessee.

29 T. V. Patel Pvt. Ltd. vs. DCIT

[2024] 464 ITR 409 (Bom.):

A.Ys. 1986–87 to 1991–92, 1993–94

Date of order: 4th December 2023

Ss. 4 and 5 of the ITA 1961

Accrual of income — Meaning of accrual — Time of accrual — Assessee terminating lease following dispute — Assessee not accepting lease rent — Matter before Small Causes Court — Small Causes Court allowing lessor to deposit lease rent in Court specifying that deposit was allowed without prejudice to rights of contestants — Matter still pending in Small Causes Court — Lease rent did not accrue to the Assessee.

The assessee entered into a sub-lease agreement with IDBI on an annual lease rent of ₹3,42,720. The said income was offered for tax under the head “Income from Other Sources”. During the previous year 1980–81, dispute arose between the assessee and IDBI for breaches committed by IDBI, which lead to termination of the sub-lease agreement by the assessee, and subsequently, the assessee refused to accept rent from IDBI post termination of the agreement. In October 1981, IDBI filed a Declaratory Suit in the Small Causes Court and obtained injunction against the assessee from terminating the sub-lease agreement.

In March 1984, the Department issued a garnishee notice u/s. 226(3) in respect of the outstanding tax arrears of the assessee and directed IDBI to pay rent to the Department. In response to the notice, the assessee informed the Department that the sub-lease agreement had been terminated and there was no rent due and payable to the assessee and, therefore, the notice issued by the Department was illegal. The Assessee also addressed a letter to IDBI about the termination and recorded that IDBI should not make payment to the Income-tax Department. However, IDBI made the payment to the Department despite the fact that the agreement was terminated.

Thereafter, in the year 1984, the Assessee filed a suit for eviction and claimed reliefs. On an application made by IDBI to the Small Causes Court, the Small Causes Court allowed IDBI to deposit the lease rent in Court. The assessee, however, did not withdraw any amount.

In the return of income for A.Ys. 1982–83 to 1986–87 filed by the assessee, the lease rent was not offered for tax. The assessments were completed and no addition was made. Subsequently, the assessment for A.Y. 1986–87 was re-opened for assessing the lease rent which the assessee had not offered for tax in the return of income for A.Y. 1986–87. In the re-assessment order, the AO added the amount of annual lease rent agreed between the assessee and IDBI.

On appeal before the CIT(A) and the Tribunal, both dismissed the appeal of the assessee. The reason for dismissing the appeal was that the claim for arrears of rent and compensation was pending before the Court. The consideration under the agreement had been paid by IDBI. The assessee was demanding compensation over and above the amount of rent. It was held by the Tribunal that the consideration did accrue to the assessee and it was being utilised for payment of tax arrears.

Against the order of the Tribunal, the Assessee filed an appeal before the High Court. The Bombay High Court allowed the appeal and held as follows:

“i) Section 5(1)(b) of the Income-tax Act, 1961 provides for scope of total income to include all income which ‘accrues’ or ‘arises’ or ‘is deemed to accrue or arise’ in India during such year. The words ‘accrue’ or ‘arise’ have different meanings attributed to them while the former connotes the idea of a growth or accumulation, the latter connotes the idea of crystallisation of the former into a definite sum that can be demanded as a matter of right. For determining the point of time of accrual, two factors are relevant. The first is a qualitative factor and the second is a quantitative factor. The qualitative factor is relatable to the terms of the agreement or the conduct of the parties for determining when the legal right to receive income emerges. The quantitative factor is relatable to the exact sum in respect of which the qualitative factor of legal right to receive is applied. These two factors have no order of priority between them. When both converge, there is a legal right to receive a certain sum of money as income. Such convergence determines a point of time of accrual. In order that the income may be said to have accrued at a particular point of time, it must have ripened into a debt at that time, that is to say, the assessee should have acquired a right to receive payment at that moment, though the receipt itself may take place later. There must be a debt owed to the assessee by somebody at that moment or, as is otherwise expressed, ‘debitum in praesentisolvendum in futuro’. Until it is created in favour of the assessee, the debt due by somebody, it cannot be said that he has acquired a right to receive any income accrued to him.

ii) There is also a difference between ‘accrue or arise’ or ‘earned’. Earning income is not the same as accrual of income but is a stage anterior to accrual of income. A person does not have a legal right to receive the income by merely earning income. Although, earning of income is a necessary prerequisite for accrual of income, mere earning of income without right to receive it does not suffice. A person may be said to have ‘earned’ his income in the sense that he has contributed to its production by rendering service and the parenthood of the income can be traced to him but in order that the income may be said to have ‘accrued’ to him an additional element is necessary that he must have created a debt in his favour.

iii) There is a distinction between cases where the right to receive payment is in dispute and it is not a question of merely quantifying the amount to be received and cases where the right to receive payment is admitted and the quantification of the amount received is left to be payable in amount. The principle of law as laid down in various decisions is to the effect that if the matter is pending before the judicial forum or the amount is allowed to be withdrawn by the party, till the case is decided finally by the judicial forum, it cannot be said that the assessee has acquired a right to receive the income for the purposes of section 5 of the Act. The time of accrual for taxing income gets postponed till the dispute is adjudicated by the civil court.

iv) In the present case, it was not disputed that the cross suits filed by the assessee and the tenant against each other were pending before the Small Causes Court. It was also not disputed that the assessee had not accepted the rent from the tenant post termination of the sub-lease agreement in the year 1981. The Small Causes Court had permitted the tenant to deposit the lease rent in the court till the rights of the parties were decided and the order of deposit of the rent was without prejudice to the rights and contentions of the parties. In the light of these facts, whether the sub-lease agreement between the tenant and the assessee subsisted post 1981 termination by the assessee, was itself a subject matter of dispute between the assessee and the tenant which was pending adjudication. In the light of these facts, it could not be said that the assessee was entitled to receive a sum of ₹3,42,720 under the sub-lease agreement with the tenant or a right was vested in the assessee to that sum. The determination of the amount payable by the tenant to the assessee as prayed for by the assessee in its suit was to be determined by the Small Causes Court and when the Court passed a final decree one could not say that the right to receive the sum decreed by the Small Causes Court had accrued to the assessee. Till then, the right to receive any sum by the assessee was in jeopardy and sub judice before the Small Causes Court. Therefore, the Revenue was not justified in bringing to tax the sum of ₹3,42,720 as accrued income for the A. Y. 1986-87 and for the other years being A. Y. 1988-89 to 1991-92 and 1993-94.”

Applicability of Section 50c to Rights in Land

ISSUE FOR CONSIDERATION

Section 50C of the Income Tax Act, 1961 provides for substitution of the actual consideration by the stamp duty valuation on the transfer of a capital asset, being land or building, if the consideration is less than the stamp duty valuation, for purposes of computing capital gain under section 48. In other words, the full value of consideration, in such cases, shall be deemed to be the value adopted for the purpose of levy of stamp duty. Section 50C reads as follows:

“Where the consideration accruing as a result of transfer of the capital asset, being land or building or both, is less than the value adopted or assessed or assessable by any authority of a State Government (hereinafter in this section referred to as the “stamp valuation authority”) for the purpose of payment of stamp duty in respect of such transfer, the value so adopted or assessed or assessable shall, for the purposes of section 48, be deemed to be the full value of consideration received or accruing as a result of such transfer.”

The issue has arisen before the Courts as to whether this deeming fiction of s. 50C applies to a case of transfer of leasehold or other rights in land or building, which are not ownership rights and are not land and building simpliciter. While the Rajasthan High Court has held that the provisions of section 50C do apply to such leasehold and other rights, the Karnataka and Bombay High Courts have held that the provisions of section 50C do not apply in such cases.

RAM JI LAL MEENA’S CASE

The issue had come up before the Rajasthan High Court in the case of Sh. Ram Ji Lal Meena s/o Sh. Bachu Ram Meena vs. ITO 423 ITR 439 (Raj).

In this case, the land was sold by the assessee under a registered sale deed for a consideration of ₹11,70,000. The Registering Authority adopted the value of the property at ₹53,11,367 for stamp duty purposes. The assessee or the transferee did not file any appeal against such valuation by the stamp authorities before the appellate authorities appointed under the stamp duty law. The land in question had been allotted by a cooperative society to the assessee’s predecessor, from whom the assessee had purchased the land. The land was acquired by the Government for the public purpose for RIICO after its purchase / allotment by / to the co-operative society. A writ petition for validating the purchase / allotment of land was filed by the co-operative society, which was allowed by the Rajasthan High Court. At the time of validation of the sale to the society, an appeal by RIICO against the Rajasthan High Court’s order was pending before the Supreme Court. Subsequent to the sale by the assessee, the Supreme Court reversed the High Court’s order on an appeal by RIICO, and upheld the acquisition by the Government for RIICO.

The assessee did not file any tax return either u/s 139(1) or in response to a notice received for reassessment u/s 148. During reassessment proceedings, he merely filed a computation of total income, disclosing a capital loss of ₹1,22,303. In reassessment proceedings, the assessee objected to the stamp duty valuation. The Assessing Officer referred the matter to the Departmental Valuation Officer, who returned the reference stating that statutory references normally required 120 days, and it was not possible to take up the case, as it was getting time barred by 31st March 2016.

The assessee contended that section 50C was not applicable as the land was under dispute, and the assessee had only sold out / transferred the rights to the land under dispute. The Assessing Officer did not accept the assessee’s contention and made an addition of ₹41,80,805 to the capital gains by applying the provisions of section 50C.

The Commissioner (Appeals) dismissed the appeal of the assessee.

The Tribunal, on appeal by the assessee, held that there was a transfer of a plot of land, by the assessee, and not just rights in land as claimed by the assessee, because the Rajasthan High Court’s order, which had held that the co-operative society was entitled to the land, was in force at the point of sale of the land by the assessee and as such the assessee sold the land in his capacity as the owner of the land. The Tribunal however restored the matter to the file of the Assessing Officer to decide the matter afresh after obtaining a valuation report from the Departmental Valuation Officer.

The assessee filed an appeal to the High Court against the order of the Tribunal. Before the Rajasthan High Court, it was argued on behalf of the assessee that this was not a case of transfer of land, but the transfer of rights therein, since the land was under acquisition by the Government for RIICO. Due to upholding the order of acquisition by the Supreme Court, it was claimed that the land vested in the State Government, and the possession remained with RIICO and not with the assessee. It was therefore urged that it was wrongly taken as a transfer of land when what was transferred by the assessee was only rights in land. Therefore, it was submitted that section 50C was not applicable.

It was also submitted that as per the revenue records the rights in land were khatedari rights, the ownership of the land vested with the Government and not the assessee, and the assessee had leasehold and not freehold rights over land, and as such section 50C could not have been invoked. Reliance was placed on various decisions of the Tribunal and the decision of the Bombay High Court in the case of Greenfield Hotels & Estates Pvt Ltd 389 ITR 68, to support the contention that section 50C would not be applicable when there was a transfer of leasehold land. It was contended that the assessee had rights similar to that possessed by a leaseholder, and therefore section 50C would not apply.

The High Court observed that a sale deed was executed for the sale of land, and the assessee had received consideration. The sale deed was registered by the Sub-Registrar. A transfer of a capital asset existed and for a valuable consideration received by the assessee. There was a dispute regarding possession of the property, which possession according to the assessee was with RIICO, but according to the revenue, the possession was with the assessee. The High Court noted that the material on record did not show any possession with RIICO, as only a notification for the acquisition of land had been issued, and there was no award passed for the acquisition by the Government for RIICO. It was the notification, the court noted, that was in dispute before the Supreme Court and not the possession of the land.

The High Court held that no question of law was involved in the case, as the dispute had been raised on facts, and the Commissioner (Appeals) and the Tribunal had held that section 50C would apply in the circumstances. According to the High Court, the appeal preferred by the assessee against the order passed by the Tribunal could not be admitted.

The Rajasthan High Court rejected reliance placed on behalf of the assessee on the decision of the Ahmedabad Tribunal in the case of Smt Devindraben I Barot vs. ITO 159 ITD 162 (Ahd), on the ground that in that case there was a relinquishment without there being a relinquishment deed and that the tribunal had decided the case without examining what was the difference between sale of the land and relinquishment of right therein. The Rajasthan High Court also rejected the reliance placed by the assessee on the Jaipur Tribunal decision in the case of ITO vs. Tara Chand Jain 155 ITD 956 (Jp), on the ground that the finding in that case that the assessee had transferred only the right in the land for valuable consideration and thereby did not transfer the capital asset, was recorded without proper scrutiny of facts and without elaborate finding on the issue. The tribunal in that case had not examined how the land and building or both were disclosed by the assessee in the balance sheet had not been taken note of, nor had it been shown how it was not a transfer of capital asset.

Referring to the decision of the Bombay High Court in the case of Greenfield Hotels & Estates Pvt Ltd (supra), the Rajasthan High Court observed that a bare perusal of section 50C did not show that transfer of a capital asset for consideration should be other than that of leasehold property or khatedari land, and that the Court could not rewrite the provision. According to the Rajasthan High Court, if the analogy taken by the Bombay High Court was applied in general, then section 50C would not be applicable in the majority of the cases as it was not allowed for leasehold property. The Rajasthan High Court further observed that the Bombay High Court had not referred to how the land was reflected in the balance sheet, whether as a capital asset or not. It therefore expressed its inability to apply the ratio of the judgment of the Bombay High Court to the case before it.

The Rajasthan High Court dismissed the appeal, holding that it did not find any question of law involved in the case before it.

V S CHANDRASHEKHAR’S CASE

The issue had also come up before the Karnataka High Court in the case of V S Chandrashekhar vs. ACIT 432 ITR 330.

In this case, the assessee had entered into an unregistered agreement for the purchase of land from Namaste Exports Ltd for a consideration of ₹4.25 crore. Under the agreement, the assessee was neither handed over the possession of the land nor was power of attorney executed in his favour. Namaste Exports Ltd. subsequently sold the land to another person, to which agreement the assessee was a consenting party.

The assessing officer of the assessee made an addition under section 50C, in his hands, in respect of the capital gains offered by the assessee for the transaction of consenting to the transfer by Namaste Exports Ltd. of the land. The appeals by the assessee to the Commissioner (Appeals) and the Tribunal confirmed the order of the assessing officer.

Before the Karnataka High Court, on appeal by the assessee, it was claimed that the provisions of section 50C were not applicable to the case of the assessee, since he was merely a consenting party in the transaction of transfer of land by a third party. It was urged that section 50C, being a deeming provision, required strict interpretation, and applied to the transfer of the land, by Namaste Exports Ltd. In its hands, and not to the assessee, who was a consenting party and not the transferor / co-owner of the property. It was further argued that since the assessee was only a consenting party, he had no locus standi in the transaction of transfer of land. It was further pointed out that section 50C used the expression ‘capital asset’ as being ‘land, building or both’, and the expression ‘being’ was more like ‘namely’, and therefore section 50C did not deal with interest in land but only dealt with land.

It was also urged on behalf of the assessee that where the language of the statute was clear and unambiguous, there was no room for the application of either the doctrine of ‘causes omissus’ and external aids for interpretation of the provision of s.50C could also not be taken recourse to. It was submitted that the assessee could not be taxed without clear words for the purpose and that every Act of Parliament must be read according to the natural construction of words.

Various alternative arguments were made on behalf of the assessee, including that the land was stock-in-trade and that section 50C did not therefore apply.

On behalf of the Revenue, besides rebutting the arguments that the land was stock-in-trade, it was contended that section 50C mandated the adoption of consideration on the basis of guidance value prescribed by the State Government for the purposes of stamp duty, as the consideration reflected by the assessee was much less than the guidance value provided by the Government of Karnataka. Therefore, the assessing officer had rightly adopted the stamp duty valuation in terms of section 50C.

It was also argued on behalf of the revenue that since the assessee had entered into a purchase agreement and had paid substantial consideration to the extent of 80%, rights had accrued in his favour, which had been extinguished by the sale deed, which would amount to transfer under section 2(47). Reliance was placed on the decision of the Supreme Court in the case of Sanjeev Lal vs. CIT 365 ITR 389 for this proposition that consideration had rightly been subjected to capital gains.

The Karnataka High Court examined the provisions of section 2(47) and section 50C. It noted that explanation 1 to section 2(47) used the term “immovable property”, whereas section 50C used the term “land or building or both” instead of “immovable property”. The Karnataka High Court was of the view that it was pertinent that wherever the legislature intended to expand the meaning of land to include rights or interest in land, it had said so specifically; viz., sections 35(1)(a), 54G(1), 54GA(1), 269UA(d) and Explanation to section 155(5A). According to the Court, section 50C therefore applied only in the case of a transferor of land, which in the case before the court, was Namaste Exports Ltd., and not the assessee, who was only a consenting party and not the transferor or co-owner of land.

According to the Karnataka High Court, the assessee had certain rights under the agreement, but from the clear, plain and unambiguous language used in section 50C, it was evident that it did not apply to a case of rights in land. According to the Karnataka High Court, it was a well-settled rule that in interpreting the taxing statutes no charge should be applied where the words used in the law by the legislature are clear and not ambiguous and the words used in the statute should be given natural meaning when they were clear and unambiguous, and the extended meaning should not be read into such words in the name of legislative intent and for any other reason.

For these reasons, the Karnataka High Court was of the view that the provisions of section 50C were not applicable to the case of the assessee.

OBSERVATIONS

The issue under consideration though moves in a narrow compass has a wider application. Other provisions of the Act namely, s.2(42A), s. 43CA and 56(2)(x) apply in the same context of bringing to tax the difference between the agreement value and the stamp duty value in respect of the transfer of land or building or both or for determination of the period of holding a capital asset. Besides these direct provisions, the Act is replete with provisions that use the term ‘immovable property’ in preference to the term ‘land or building or both’. They are found in s.27, 35(1)(a), 54G(1), 54GA(1), 269UA(d) and Explanation to section 155(5A) of the Act. The Transfer of Property Act and the General Clauses Act also deal with immovable property instead of land or building. All of these make one thing clear that the term immovable property is wider in its scope and embraces in its sweep the terms land and building, though the converse of the same is not true.

Various benches of the tribunal and some high courts have held that the profits and gains on transfer of rights in the land or building are not exigible to the deeming provisions being discussed herein. This is based on the application of the understanding that the terms ‘land or building’ have narrower meaning than the term ‘immovable property’ which is wider to include in its scope the rights and interest in the land or building, besides the land or building. These decisions hold that tenancy rights, leasehold rights, and rights in buildings under construction and development rights are not the same as the ‘land’ or ‘building’.

It’s useful to refer to the meaning of the term ‘immovable property’ provided under s.269UA of the Income Tax Act s.3 of the Transfer of Property Act (“TOPA”) and s.3 of the General Clauses Act (“GCA”). Immovable property, under TOPA and GCA, is defined to mean “Immovable property does not include standing timber, growing crops and grass”,. and “Immovable property shall include land benefits to arise out of the land, and things attached to the earth ”, respectively. S. 269UA of the Income-tax Act defined the term as under;

“immovable property” means-

(i) any land or any building or part of a building, and includes, where any land or any building or part of a building is to be transferred together with any machinery, plant, furniture, fittings or other things, such machinery, plant, furniture, fittings or other things also.

Explanation. – For the purposes of this sub-clause, “land, building, part of a building, machinery, plant, furniture, fittings and other things” include any rights therein;

(ii) any rights in or with respect to any land or any building or a part of a building (whether or not including any machinery, plant, furniture, fittings or other things, therein) which has been constructed or which is to be constructed, accruing or arising from any transaction (whether by way of becoming a member of, or acquiring shares in, a co-operative society, company or other association of persons or by way of any agreement or any arrangement of whatever nature), not being a transaction by way of sale, exchange or lease of such land, building or part of a building;

A bare reading of the definitions leaves no doubt that the term ‘immovable property’ as defined, is wider in its scope and includes the terms land or building while the latter terms are not defined and would be assigned their natural meaning, and not the wider meaning to include the rights in the land and building.

Importantly, the legislature in framing the different provisions of the Income Tax Act has a clear perception and understanding of the difference between these terms which is made clear by the use of different terms at different places with different objectives. Had the intention been to cover the cases of the rights in land too in the ambit of the provisions being examined namely, s.43CA, 50 C and 56(2), the legislature would have used the term’ immovable property’ in place and stead of the terms ‘land’ or ‘building’. S.27, 35(1)(a), 54G(1), 54GA(1), 269UA(d) and Explanation to section 155(5A) of the Act use the term ‘immovable property’ whose meaning would be supplied reference to the enactments which define this term while the meaning of the terms ‘land’ or ’building’ used in the Act should be gathered by the natural meaning of these terms.

This issue had first come up before the Bombay High Court in the case of CIT vs. Greenfield Hotels & Estates (P) Ltd 389 ITR 68. In that case, the Bombay High Court noted that the tribunal had followed its decision in Atul G Puranik vs. ITO 132 ITD 499, which had held that section 50C is not applicable while computing capital gains on the transfer of leasehold rights in land and buildings. In that case, the counsel for the revenue stated that the revenue had not preferred any appeal against the decision of the tribunal in the case of Atul G Puranik (supra). The Bombay High Court therefore stated that it could be inferred that the tribunal decision in Atul Puranik’s case had been accepted by the Government. The High Court referred to its own decision in the case of DIT vs. Credit Agricole Indosuez 377 ITR 102 and the decision of the Supreme Court in the case of UOI vs. Satish P Shah 249 ITR 221, for the salutary principle that where the revenue had accepted the decision of the court / tribunal on an issue of law and not challenged it in appeal, then a subsequent decision following the earlier decision cannot be challenged. Therefore, the Bombay High Court had taken the view that no substantial question of law arose in that case.

An identical view had been taken by the Bombay High Court on the same reasoning earlier in CIT vs. Heatex Products Pvt Ltd 2016 (7) TMI 1393 – Bombay High Court. However, in a subsequent matter in the case of Pr CIT vs. Kancast Pvt Ltd 2018 (5) TMI 713Bombay High Court, the Bombay High Court took note of its decisions in Greenfield Hotels & Estates (P) Ltd (supra) and Heatex Products Pvt Ltd (supra) and observed that these were decided on the basis that no appeal had been filed against the Tribunal’s decision in the case of Atul G Puranik (supra). The High Court observed that in the case before it, reliance had been placed on the Tribunal decisions in the case of Atul G Puranik (supra) and ITO vs. Pradeep Steel Re-Rolling Mills Pvt Ltd 2011(7) TMI 1101 – ITAT Mumbai (supra). The counsel for the Revenue pointed out that the Revenue had preferred an appeal against the Tribunal’s order in Pradeep Steel Re-Rolling Mills Pvt Ltd (supra), which was admitted. It was however later withdrawn in view of the low tax effect.

The Bombay High Court noted that when both appeals in Greenfield Hotels & Estates Pvt Ltd (supra) and Heatex Products Pvt Ltd (supra) were not entertained by it, the decision of the Court in Pradeep Steel Re-Rolling Mills Pvt Ltd (supra) admitting the appeal on the same question had not been brought to its notice. It therefore admitted the appeal on the substantial question of law in Kancast Pvt Ltd’s (supra) case. Therefore, the issue is still pending for decision before the Bombay High Court.

However, in a decision of the Bombay High Court in the case of Pr CIT vs. MIG Co-op. Hsg. Soc. Group II Ltd 298 Taxman 284 (Bom), in the context of a redevelopment agreement entered into by a co-operative housing society, the Bombay High Court noted with approval the following observations of the Tribunal in the case before it:

“We also hold that Society was only the lessee  and what was transferred to the developer is development rights, not land or building. Section 50C of the Act stipulates as under:

“Where the consideration received or accruing as a result of the transfer by an assessee of a capital asset, being land or building or both.….…”

No authority is required to hold that terms’ land or building’ ‘or both’ do not include development rights and that in the case before (them) there was the transfer of such rights only.”

Looking at the number of judicial decisions, including various decisions of the Tribunal, it appears that the majority of the Courts and the Tribunals seem to favour the proposition that given the express language of section 50C, referring to “capital asset, being land or building or both” and not using the broader term “immovable property”, the intention clearly seems to be that only land building per se was intended to be covered, and not all types of immovable property.

The facts in both cases are highly peculiar. In the case before the Rajasthan High Court, the subsequent order of the Supreme Court has made the entire transaction of the transfer by the assessee non-est and not enforceable in law, and the assessee would have been better off by contending that no capital gains could be said to have arisen out of a non-est transaction by relying on the settled position in law including by the decisions of the Supreme Court in the case of Balbir Singh Maini,86 taxmann.com 94 and Ranjit Kaur, 89 taxmann.com 9. In the facts of the assessee before the Karnataka High court the assessee had never acquired any land or building, nor had he acquired even the rights in the land, nor had he possessed the land, neither had he transferred the land, nor was he capable of doing so; he was just a consenting or confirming party and was included for the reason of he having made the part payment to the extent of 80% of the consideration agreed. In such facts, it was not possible for the court to have come to any other conclusion other than the one delivered by it.

Therefore, the better view is that rights in immovable property which are inferior to ownership rights, such as leasehold rights or the right to acquire immovable property, would not be covered by section 50C.

Part A | Goods and Services Tax

HIGH COURT

33 AU Finja Jewels vs. Assistant Commissioner Div. V CGST and Cx.

[2024] 164 taxmann.com 278 (Bombay)

Dated 21st June, 2024

Where the invoice issued to the customer indicates the gross value of the jewellery and also shows a reduction in respect of the gold supplied by the customer free of cost, the value as per GST invoice for the purpose of computing refund should be the gross value and the value of gold supplied free of cost can be treated as a payment in advance.

FACTS

Petitioner is a jewellery processor and manufacturer of jewellery and in the course of his business, imports gold and exports gold jewellery in accordance with the Foreign Trade Policy of the Government of India. The issue that arises in this petition is, what is the value of the goods that have to be considered while working out the refund of Integrated Goods and Services Tax (IGST) to be sanctioned? The FOB value as per the invoice was USD 2,24,846.75. However, the net realisable value after considering the value of gold supplied by the customer free of cost was USD 6,479.39. The department considered net realisable value as the value of goods declared on the export invoice.

HELD

The Hon’ble Court held that the value of export goods should be considered as the gross value and the value of gold given by the customer free of cost should be treated as advance payment.

34 Fabricship (P.) Ltd vs. Union of India

[2024] 164 taxmann.com 80 (Bombay)

Dated 21st June, 2024

When imported machinery under ECPG scheme is transported from the port to the petitioner’s factory, there is no supply and hence in the absence of any evidence that the goods were being supplied to a third party, the penalty under section 129(1)(a) is not payable. However, such a movement will qualify as an “exempt supply” to attract a penalty under section 129(1)(b) of the Act. As sections 129(1)(a) and 129(1)(b) are mutually exclusive, an order imposing penalties under both sections is an order without application of mind.

FACTS

The petitioner imported machinery at port from China which was fully exempted since it was covered by the EPCG scheme. Petitioner, thereafter, arranged a transporter to transport the said machinery from the port to its factory at Surat. The said vehicle was intercepted in Maharashtra and it was found that no e-way bill was prepared. However, the Bill of Entry accompanying the vehicle contained all the details. The State GST authority imposed a penalty under section 129(1)(a) and under section 129(1)(b) of the MGST Act. The petitioner submitted that as there was no Customs duty or IGST liability since goods are exempt under notification no.16/2015-Customs read with notification no.18/2020-Customs, the penalty was not imposable. The petitioner also informed that it had given a bank guarantee; however, the said bank guarantee has expired and has not been renewed.

HELD

The Hon’ble Court observed the fact that the machinery imported is exempted from Customs duty and IGST and that the machinery was being transported from port to the petitioner’s own factory at Surat post clearance by the Customs Authorities is not disputed. Further, there is no evidence indicating the movement of machinery to the outside buyer out of the State of Maharashtra. The Hon’ble Court held that when the petitioner imports machinery and after Customs clearance transports the said machinery to its own factory, it cannot be said that such a transportation would fall within the definition of the term supply’ as defined by section 7 as for a ‘supply’ to fall under section 7 there has to be more than one person or entity between whom the transaction of supply should take place. It further held that the movement of goods cannot fall under schedule I, II and III of the Act. The Hon’ble Court held that the applicability of the rate of tax would get triggered only if a transaction falls within the meaning of the term ‘supply’ as per section 7 of the MGST Act. Therefore, the first limb of Section 129(1)(a) is not applicable. However, when a person transports the goods imported, after Customs clearance to his own factory premises then it is a non-taxable supply and would fall within the category of “exempted goods” as it does not attract tax and consequently, the case will be covered within the second limb of section 129(1)(b) of the Act attracting the penalty of ₹25,000 in the present case.

On the simultaneous imposition of penalty under sections 129(1)(a) and 129(1)(b), the Hon’ble Court held that both these provisions are mutually exclusive and hence order imposing penalty under section 129(1)(a) as well as under section 129(1)(b) is an order passed without application of mind. Since the petitioner failed to keep the bank guarantee in force, the Hon’ble Court imposed a cost of R15 lakh on the petitioner.

35 Pedersen Consultants India (P.) Ltd vs. Union of India

[2024] 164 taxmann.com 67 (Delhi)

Dated 19th March, 2024

When the petitioner was forced to pay GST on invoices due to the non-filing of returns by the supplier and subsequently, the supplier filed the returns, thereby creating a scenario of double tax payment to the Government, the Hon’ble Court permitted the petitioner to file the refund application.

FACTS

Petitioner had been coerced into depositing the tax on the said invoices as the supplier had not filed returns within time. Subsequently, the said supplier filed the returns and consequently, double payment was made to the department. The claim of the petitioner was not considered as petitioner did not file an appropriate refund application as required under section 54 of the Central Goods & Service Tax Act, 2017.

HELD

Assessee / Petitioner was directed to file a refund application under section 54 of the Central Goods and Services Tax Act, 2017. However, relying on Notification No.13/2022 dated 5th July, 2022, the period between 1st March, 2020 to 28th February, 2023 was directed to be excluded for computation of period of limitation. Also, the period between filing of the subject petition till the passing of the High Court’s order was also directed to be excluded for filing the refund application.

36 Amarjyothi Carrying Corporation vs. Assistant Commissioner (ST)

[2024] 164 taxmann.com 11 (Madras)

Dated 20th March, 2024

Where the entire tax liability has arisen on account of an inadvertent error committed while filing the GSTR 1 return which was subsequently rectified in GSTR-3B and GSTR-9 return and the petitioner did not submit the reply before the authorities in time, the Hon’ble Court thought it just and proper to remand the matter setting aside the impugned Order.

FACTS

While filing the GSTR 1 return for the month of October 2019, it is stated that the petitioner inadvertently failed to indicate that GST was leviable on the service on reverse charge basis. However, this mistake was corrected in the GSTR 3B return for the relevant month and also in the annual GSTR 9 return. The department recovered the outstanding demand from the petitioner by attaching the bank account. The Order was challenged primarily on the ground that the petitioner was not provided a reasonable opportunity.

HELD

The Hon’ble Court held that when the entire tax liability has arisen on account of an inadvertent error committed while filing the GSTR 1 return which was subsequently rectified in GSTR-3B and GSTR-9 return and just because the petitioner did not submit the reply before the authorities in time, it is just and necessary to provide the petitioner opportunity. The Hon’ble Court therefore remanded the matter with a direction that amounts appropriated pursuant to the impugned order shall be subjected to the outcome of the remanded proceedings.

37 Maurya Industries vs. Union of India

(2024) 19 Centax 273 (Del.)

Dated 11th March, 2024

Cancellation of GST registration must be based on objective criteria, ensuring that registration can only be cancelled retrospectively when the consequences are intended and warranted.

FACTS

Petitioner applied for cancellation of its registration on 12th April, 2023 as the firm was discontinued due to losses incurred. It had also duly furnished the required documents. However, the application was rejected via a SCN dated 6th June, 2023, citing an inspection by the Anti-Evasion Branch on 30th May, 2023 that found the petitioner’s principal place of business non-existent. Subsequently, an order was issued in line with the Show Cause Notice, retrospectively cancelling the petitioner’s registration from 26th October, 2022. Being aggrieved by impugned order passed by respondent, petitioner preferred this petition before Hon’ble High Court.

HELD

The High Court held that retrospective cancellation is invalid as the petitioner had applied for cancellation before the inspection on the basis that business was discontinued thereby implying that his place of supply was not existing any more. According to section 29(2) of the CGST Act, a taxpayer’s registration can be cancelled with retrospective effect only where such consequences are intended and are warranted. In the present case, such cancellation would have unwanted repercussions such as invalidation of the ITC claimed by petitioner’s customers.

Further, such cancellation cannot be based on subjective assessment but must be based on objective criteria. Mere non-filling of returns cannot be the reason for retrospective cancellation of registration, as it also covers the period when the returns were filled. Accordingly, writ petition was disposed of, reserving all the rights and contentions of the parties.

38 Aditya Steel Trading vs. Joint Commissioner, Central Goods and Services Tax and Central Excise (2024) 19 Centax 469 (Bom.)

Dated 18th June, 2024

Show Cause Notice issued without attaching the impounded documents mentioned therein renders the petitioner unable to effectively respond to the SCN.

FACTS

Petitioner was issued a SCN dated 25th October, 2023, however copies of impounded documents along with the SCN were provided only on 25th December, 2023. This reduction in time lead to non-filing of reply by petitioner. Consequently, an order was issued on 28th December, 2023, supplemented by another order of 20th December, 2023. Being aggrieved by impugned order passed by respondent, petitioner preferred this petition.

HELD

The High Court held that impugned orders were passed without giving an opportunity to reply to SCN. It was observed that without access to copies of the impounded documents, the petitioner would have been unable to adequately address the SCN. Consequently, the impugned Order was deemed to be set aside, and the matter was remanded.

Glimpses of Supreme Court Rulings

6 Special Leave Petition — Dismissed on grounds of efflux of time — Question of Law kept open

PCIT vs. Atlanta Capital Pvt. Ltd.

(2024) 464 ITR 346 (SC)

A notice dated 27th March, 2008 u/s. 148 of the Act for the assessment year 2001–02 was issued to the assessee at an old address, though the Assessing Officer had served letters dated 8th August, 2007 and intimation u/s. 14(1) dated 25th January, 2008 for the assessment year 2006–07 at the new address. The Tribunal quashed the reassessment proceedings holding that there was no proper service of notice. The Delhi High Court dismissed the appeal holding that there was no substantial question of law. According to the High Court, the mere fact that an assessee participated in the reassessment proceedings despite not having been issued or served with the notice u/s. 148 of the Act in accordance with law will not constitute a waiver of the jurisdictional requirement of the issuance and the service of notice.

The Supreme Court observed that the said notice as followed by the order passed by the Assessing Officer/Commissioner was set aside by the Income-Tax Appellate Tribunal on 21st June, 2013. Subsequently the order of the Tribunal was upheld by the High Court on 15th September, 2015. The proceeding initiated in 2008 was concluded by the order of the High Court in 2015. Yet another decade had passed thereafter. Under the circumstances, while keeping the question of law open for consideration in another case, the Supreme Court decided not to interfere with the judgment of the High Court.

7 Business Expenditure—Expenditure cannot be disallowed merely because no income is earned SLP dismissed since it was accepted that the business had commenced
PCIT vs. Hike Pvt. Ltd (2024) 464 ITR 394 (SC)

The assessee filed its return of income for the assessment year 2014–15 declaring a loss of ₹42,24,57,146. The assessment order u/s. 143(3) was passed determining total income at ₹78,83,350. The Assessing Officer inter alia disallowed the expenses of ₹43,01,40,500 for the reason that the assessee had not earned any revenue from its business. The only income that it had earned was income from other sources, i.e., interest earned on fixed deposits.

On an appeal, the Commissioner of Income-tax (Appeal) inter alia confirmed the disallowance of expenses.

The Tribunal reversed the view taken by the Commissioner of Income-tax (Appeals) noting that for AY 2012–13, the Assessing Officer had accepted the stand of the assessee that the expenses incurred by it were on revenue account and the later order passed by the Commissioner u/.s 263 for AY 2012–13 was quashed by the Tribunal.

Before the High Court, the Revenue contended that the expenditure was incurred before the business was set up and therefore not allowable. The High Court noted that the objection of the Assessing Officer was that the said amount was spent in building a brand for future utilization, therefore, was not in the nature of revenue. The High Court noted that even in AY 2012–13 the expenses were disallowed because according to the Assessing Officer, the business was not set up and the software purchased was not put to use.

The High Court considering that the assessee was in the business of software development did not interfere with the order of the Tribunal.

On a special leave by the Revenue, the Supreme Court declined to interfere with the High Court judgment as it was accepted that the business had commenced.

Recent Developments in GST

A. NOTIFICATIONS

i) The Government has published the GST Appellate Tribunal (Recruitment, Salary and Other Terms and Conditions of Service of Group “C” Employees) Rules, 2024, dated 21st June, 2024 by Notification No. G.S.R 340(E), dated 21st June, 2024.

B. CIRCULARS

The following circulars have been issued by CBIC.

i) Monetary Limit for filing appeals by Department — Circular no.207/01/2024-GST dated 26th June, 2024.

By the above circular, monetary limits are indicated for the filing of appeals by the department. Different limits are provided for appeals to different forums like GSTAT, High Courts and Supreme Court.

ii) Clarifications in respect of manufacturers of specified commodities — Circular no.208/02/2024-GST dated 26th June, 2024.

By the above circular, various issues regarding compliance with special procedures in respect of specified commodities like Pan Masala and tobacco products are clarified.

iii) Clarification regarding Place of Supply — Circular no.209/03/2024-GST dated 26th June, 2024.

In the above circular, clarification is given about the Place of Supply in case of supply to an unregistered person. It is clarified that if the delivery address is different from the billing address, then the delivery address should be considered as the place of supply.

iv) Clarification on the valuation of Import Services- Circular no. 210/04/2024-GST dated 26th June, 2024.

In case of import of services between related parties, the importer is liable to pay tax under RCM, even though there is no consideration. By the above circular, clarification is given about valuation in such cases.

v) Clarification regarding ITC of Tax paid under RCM— Circular no.211/05/2024-GST dated 26th June, 2024.

In case, there are any inward supplies, received from unregistered suppliers, on which the recipient is liable to pay tax under RCM, in the above circular it is clarified that the year for considering the time limit under section 16(4) for availing ITC should be the year in which the self-invoice is created for such supply.

vi) Clarification regarding deduction towards discount — Circular no.212/06/2024-GST dated 26th June, 2024.

As per section 15(3)(b)(ii), if any discount is given by the supplier to the recipient then such discount is deductible from the value of such supply. One of the conditions for getting the claim is that the recipient should reduce his ITC proportionately. However, at present there is no facility to know the reduction made by the recipient. The circular has provided that, in such cases, a self-declared undertaking can be obtained from the recipient about a reduction in ITC and if such reduction is more than 5 lakhs, then a certificate from CA/CMA should be obtained.

vii) Clarification regarding Taxability of Shares / Securities – Circular no.213/07/2024-GST dated 26th June, 2024.

By the above circular clarifications are given about the taxability of ESOP / ESPP / RSU (Issue of Shares/Securities) provided by the Company to its employees through its overseas holding Company. Mainly it is clarified that such transactions are related to Shares / Securities, which are neither goods nor services, hence not liable to tax under GST as import of services.

viii) Clarification about reversal of ITC in case of Life Insurance — Circular no.214/08/2024-GST dated 26th June, 2024.

When there is an exempt supply, the ITC is required to be reversed on a proportionate basis. In the above circular it is clarified that in respect of the amount of premium for taxable life insurance policies, which is not included in taxable value as determined under Rule 32(4), there is no need for reversal of pro rata ITC.

ix) Clarification regarding taxability of Salvage — Circular no.215/09/2024-GST dated 26th June, 2024.

In the case of the insurance claim for goods, there are pre-determined terms for the treatment of salvage while deciding the claim amount. In the above circular, clarifications are given about taxability and valuation of salvage/wreckage.

x) Clarification regarding GST liability and ITC in case of Warranty— Circular no.216/10/2024-GST dated 26th June, 2024.

In the above circular, various clarifications are given with respect to GST liability and availability of ITC in cases involving warranty / Extended Warranty. This is in continuation of earlier circular no.195/07/2023-GST- dated 17th July, 2023.

xi) Clarification regarding ITC to the Insurance Companies — Circular no.217/11/2024-GST dated 26th June, 2024.

By the above circular, clarifications are given about the entitlement of ITC by insurance companies on the expenses incurred for the repair of motor vehicles in case of reimbursement mode of insurance claim settlement.

xii) Clarification regarding Taxability of providing loan — Circular no.218/12/2024-GST dated 26th June, 2024.

In the above circular, clarifications are given about the taxability of transactions of providing a loan by an overseas affiliate to an Indian affiliate or by a related person.

xiii) Clarification about ITC on Ducts and Manholes — Circular no.219/13/2024-GST dated 26th June, 2024.

By the above circular, clarification is given about the applicability of Section 17(5)(d), i.e., regarding the blocking of ITC with respect of ducts and manholes used in the network of optical fibre cables (OFCs).

xiv) Clarification about the place of supply in case of Banks — Circular no.220/14/2024-GST dated 26th June, 2024.

By the above circular clarifications are given about the place of supply applicable for Custodial Services, provided by the bank to Foreign Portfolio Investors.

xv) Clarification regarding Time of supply in case of Construction services of Road — Circular no.221/15/2024-GST dated 26th June, 2024.

In the above circular, clarifications are given about Time of supply in relation to the supply of services of construction of road and maintenance thereof of National Highways of the National Highways Authority of India under a Hybrid Annuity Mode.

xvi) Clarification about Time of supply in case of Spectrum Uses — Circular no.222/16/2024-GST dated 26th June, 2024.

By the above circular, clarifications are given about the time of supply of services Spectrum uses and other similar services.

C. ADVANCE RULINGS

19 GST on EPC/Turnkey Contract vis-à-vis Imported goods

M/s. Tecnimont Private Limited (AR Order No.GUJ/GAAR/R/2024/02 (In Application No.Advance Ruiling/SGST& CGST/2023/AR/15) dt. 5th January, 2024 (Guj)

The applicant M/s Tecnimont Private Limited has entered into a turnkey contract with Indian Oil Corporation Ltd. (for short — IOCL), vide contract No. 44AC9100-EPCC-1 dated 19th January, 2021, for executing EPC work of Acrylic Acid Unit (90 KTA) and Butyl Acrylate Unit (150 KTA) of Acrylic/Oxo-Alcohol Project’, located at IOCL Dumad Complex, Nr. Gujarat Refinery, Vadodara.

The applicant has stated that, in terms of the contract, all imported materials required to be supplied under the contract will be sold by the applicant to IOCL on High Seas Sale [HSS] basis by endorsing bill of lading in favour of IOCL who will be filing the bill of entry for warehousing and subsequently for home consumption by paying the applicable customs duty and IGST.

The applicant has further clarified that the contract value is fixed as a lump sum price of ₹18,72,00,48,047.50 comprising of:

“(i) ₹14,70,30,56,131 for domestically sourced material and supply of service;

(ii) Foreign Exchange Euros of € 4.55.18,322 (i.e., converted @ 1 EURO = INR88.25 as on the date of opening of price bid ₹401,69,91,916.5) based on the terms and conditions of Contract No. 44AC9100-EPCC-1 towards goods imported outside India;

(iii) ₹32,89,75,280.89 towards custom Duty & SWS on Foreign Component imported which is reimbursable according to contractual terms.”

As per the applicant, during the course of importation, before the goods reached the Customs frontiers of India, they entered into an HSS agreement with IOCL, transferring the ownership of the goods to IOCL at the price agreed in the contract. The applicant raises a Custom Invoice with respect to goods sold to IOCL under HSS without charging GST. IOCL then files a bill of entry as an importer of the said goods and discharges customs duty and IGST by clearing the goods for warehousing or home consumption. The applicant intends to treat this portion of the supply of imported goods as a separate supply of goods distinct from the works contract supplies.

In other words, the applicant wanted to say that the contract No. 44AC9100-EPCC-1 entered into with IOCL, identifies two separate sets of supplies for the turnkey project, (i) works contract for EPC work and [ii] supply of imported materials for the said work.

With respect to consideration mentioned in respect of contract part at (i) above, the applicant intends to charge GST @ 18 per cent, as works contract service.

In respect of part (ii), the applicant intends to claim exemption from the levy of tax in terms of para 8(b) of Schedule-III of CGST Act,2017;

As per above entry 8(b) in Schedule-III, the sale by transfer of documents of title to goods before goods are cleared for home consumption is exempt.

With the above background, the applicant has put forth the following questions before the ld. AAR for its ruling:

“1. Whether the transaction of sale of goods by Tecnimont Pvt. Ltd. (TCMPL) to Indian Oil Corporation Ltd. (IOCL) on a High Seas Sale basis in terms of Contract No. 44AC9100-EPCC-1 would be covered under Entry No. 8(b) of Schedule III of the CGST Act and shall be excluded from the value of work contract service for charging GST?

2. Whether the transaction of sale of goods on a high seas sale basis by the Applicant to IOCL in terms of Contract No. 44AC9100-EPCC-1 would be treated as a works contract and whether Applicant is liable to charge GST on the goods sold on a high seas sale basis to IOCL? If yes, what will be the applicable rate of tax on such goods supplied?”

The ld. AAR went through the agreement and minutes recorded in follow-up to the award of the contract. The ld. AAR referred to various clauses in the agreement and observed about scope of important features of the contract as under:

“18. The contract in question is in respect of a turnkey EPC contract. The terms ‘Turnkey’ and ‘EPC contract’ are not defined under the CGST Act. Now, what constitutes an EPC contract? We find that an Engineering, Procurement and Construction (‘EPC’) contract is a particular form of contracting arrangement wherein the EPC contractor is made responsible for all the activities right from design, procurement, construction, commissioning, and thereafter handover of the project to the end-user or owner. Likewise, Turnkey contracts, place the responsibility for designing, engineering, procurement, and construction of the entire project on a single contractor. Such contracts further ensure that following completion, the client receives a ready-to-use facility. Further, these contracts are usually ‘fixed price’ contracts.”

The ld. AAR noted that in contrast to the above features of the contract, the applicant has submitted that there are two separate contracts within the EPC contract i.e.,

“[i] supply of imported materials for the project; and

[ii] works contract for EPC work pertaining to EPCC-1 project.”

In this respect, the ld. AAR referring to the definition of ‘works contract’ given in section 2(119) analyzed the aspects of said definition as under:

  • “works contract must be in relation to any immovable property;
  • composite supply undertaken on goods say fabrication or paint job would perse not fall within the ambit of works contract under GST; such contract would continue to remain composite supplies;
  • In terms of Schedule-II, para 6(a), works contract shall be treated as a supply of services;
  • GST aims to put at rest the controversy by defining what will constitute a works contract (applicable for immovable property only) by stating that a works contract will constitute a supply of service and specifying a uniform rate of tax applicable on the same value across India.”

The ld. AAR referred to important judgment about the implication of transactions being works contract-like, judgment in the case of Kone Kone Elevator India Private Limited [2014 (304) E.L.T. 161 (S.C.) — 2014-VIL-12-SC-CB] and other judgments.

Based on the ratio of the above judgments the ld. AAR observed that the contract dated 19th January, 2021, entered into by the applicant & IOCL, is to execute the work of “EPCC-1 Package for Acrylic Acid & Butyl Acrylate Unit of Acrylic/ Oxo-Alcohol Project” which is a lump sum turnkey EPC contract. The ld. AAR observed that to divide a turnkey EPC contract into two parts is legally not tenable. It is tenable if they have entered into two different contracts.

In respect of HSS sales of imported goods to IOCL, the ld. AAR held that the sale is covered by entry 8(b) of Schedule III and hence not liable to GST.

However, in respect of the liability of the applicant, the ld. AAR refers to provisions of section 15 of the GST Act which provides for the valuation of Taxable Supply.

The ld. AAR, amongst others, referred to section 15(2)(b) which reads as under:

“(b) any amount that the supplier is liable to pay in relation to such supply but which has been incurred by the recipient of the supply and not included in the price actually paid or payable for the goods or services or both;”

The ld. AAR observed that in terms of the contract, the applicant is liable to provide the goods [supplied on an HSS basis] and hence the submission that this value is not to be included in the transaction value in respect of the works contract service is legally not tenable. The ld. AAR observed that, in terms of section 15, the value of such imported goods would form a part of the transaction value for payment of GST in the hands of the applicant.

In this respect the ld. AAR made reference to the Judgment decided by the Hon’ble Chhattisgarh High Court in the case of M/s. Shree Jeet Transport [Writ Petition (T) No. 117/2022 decided on 17th October, 2023] – 2023-VIL-764-CHG.

In this case, the diesel supplied free by contractee to the contractor providing transport services is held liable to tax in the hands of the contractor.

Applying said principle, the ld. AAR held that the value of imported goods is to be included in taxable contract value.

Based on the above analysis the ld. AAR gave the ruling as under:

“1. The transaction of sale of goods by Tecnimont Pvt. Ltd. (TCMPL) to Indian Oil Corporation Ltd. (IOCL) on a High Seas Sale [HSS] basis in terms of Contract No.44AC9100-EPCC-1 is covered under Entry 8(b) of Schedule III of the CGST Act. However, in terms of the findings recorded supra, the value of such HSS supply would form a part of the transaction value under section 15, ibid, for computing the value of work contract service for charging GST.

2. The transaction of sale of goods on a high seas sale [HSS] basis by the applicant to IOCL in terms of Contract No. 44AC9100-EPCC-1 as has been held supra, is covered under entry 8(b) of Schedule III of the CGST Act, 2017 and is therefore the HSS supply is neither a supply of goods nor a supply of services.”

20 ITC vis-à-vis Solar Plant for Captive Consumption

Unique Welding Products P. Ltd. (AR Order No.GUJ/GAAR/R/2024/01 (in application no. Advance Ruling/SGST & CGST/2023/AR/14) dt. 5th January, 2024 (Guj)

The applicant, M/s Unique Welding Products Pvt. Ltd., is engaged in the business of manufacturing and sale of welding wires and it is registered with the GST department.

The applicant supplies its products i.e., Welding Wires etc. after discharging GST @ 18 per cent. The applicant has entered into an interconnection agreement with power distribution licensee (Madhya Gujarat Vij Company Ltd) for captive use of power generated by Roof Top Solar System and has installed a rooftop solar system with a capacity of 440 KW (AC) on the factory roof for power generation. The applicant generates power solely and captively for use in its manufacturing activity of welding wires within the same premises.

The applicant further submitted that their business of manufacturing and sale of welding wires from their manufacturing plant constitutes as ‘business’ as per section 2(17) of the CGST Act, 2017 and is eligible for ITC as per section 16(1).

In light of the above background, the applicant has sought an advance ruling on the below-mentioned questions:

“1. Whether the applicant is eligible to take ITC as ‘inputs/capital goods’ or ‘input services’ on the purchased rooftop solar system with installation & commissioning in terms of sections 16 & 17 of the CGST/GGST/IGST Act?

2. Whether the rooftop solar system with installation and commissioning constitutes plant and machinery of the applicant which are used in the business of manufacturing welding wires and hence not blocked input tax credit under section 17(5) of the CGST/GGST/ IGST Act?”

In the course of the hearing, the applicant provided a copy of the Ruling in the case of M/s. The Varachha Co.op Bank Ltd., Surat.

Copy of the Annual report of the applicant for the FY 2022–23, showing addition to Plant and machinery under fixed assets, copy of the invoice from rooftop solar plant and copy of interconnection agreement signed with MGVCL for rooftop solar plant were filed before the Ld. AAR.

The applicant further clarified that the solar rooftop plant is bolted to the factory roof by means of screws and bolts for operational efficiency and safety. Further, it was clarified that the rooftop solar plant can be dismantled and sold if required. Accordingly, it was submitted that, the rooftop solar plant is not permanently fastened to the building hence it will not be an immovable property. It was further submitted that the rooftop solar plant qualifies as a plant and machinery used for the furtherance of the business of supplying taxable goods and hence not covered under blocked credit mentioned in section 17(5)(d) of the CGST Act, 2017.

The ld. AAR referred to relevant provisions like a definition of business, the scope of ITC as per section 16 and blocked credit u/s.17(5) of the CGST Act.

The ld. AAR also referred to the later issued by Additional Chief Engineer (RA&C), Madhya Gujarat Vij Company Limited, Vadodara addressed to Superintending Engineer, Circle Office, MGVCL, granting approval to the applicant, for grid connectivity of Solar Roof Top Photo-Voltaic systems as per the provisions of the Gujarat Solar Power Policy-2021. The relevant paras are reproduced in the AR as under:

“With reference to the above subject, it is to state that application of M/s. Unique Welding Products P Ltd for the installation of a 440.00 KW(AC) Solar Roof Top Photo Voltaic System has been registered by GEDA.

Now regarding the connectivity with MGVCL network for injection of Solar Energy from 440.00 KW Solar Power Plant, consumer M/s. Unique Welding Products P Ltd hearing consumer no. 15453 has paid connectivity charges of ₹50000 and executed a connectivity agreement with MGVCL.

The connectivity has been granted for a period of 25 years. Accordingly, the connectivity agreement has been executed for 25 years and it shall be in force for the period of 25 years only.

Copy of the connectivity agreement, connectivity charge paid receipt, CEI approved single line diagram, earthing diagram, wiring diagram and installation charging approval received from CEI is attached herewith.”

Based on the above documents and legal provisions, the ld. AAR observed as under:

“17. It is therefore, clear that the roof solar plant, affixed on the roof or the building is not embedded to earth. Accordingly, it is not an immovable property but a plant and machinery, which is utilized to generate electricity which is further solely and captively used in the manufacture of welding wires. The applicant is engaged in the business of supply of welding wires on payment of GST at the applicable rates. The applicant has further stated that they have capitalized the roof solar plant in their books of accounts. The Roof Solar Plant, as is evident is not permanently fastened to the building. Thus, it qualifies as a plant and machinery and is not an immovable property, hence, it is not covered under blocked credit as mentioned in 17(5)(d) of the CGST Act, 2017. Therefore, we hold that the applicant is eligible for input tax on roof solar plant.”

With the above background the ld. AAR gave a ruling on pertinent questions as under:

“1. The applicant is eligible to avail of ITC rooftop solar system with installation & commissioning under the CGST/GGST Act.

2. The rooftop solar system with installation and commissioning constitutes as plant and machinery of the applicant and hence is not blocked ITC under section 17(5) of the CGST/GGST Act.”

21 Catering Services to Education Institution

M/s. Sri Annapurneshwari Enterprises (AR Order No.KAR ADRG 04/2023 dt. 23rd January, 2023 (Kar)

The applicant, M/s. Sri Annapumeshwari Enterprises is a Partnership firm registered under GST. The applicant is engaged in the business of hotel and catering services.

The applicant has sought an advance ruling in respect of the following question:

“i. Whether providing catering services to Educational Institutions from 1st standard to 2nd of Pre University Course (PUC) is taxable or not according to Notification No. 12/2017- Central Tax Rate –under Heading 9992.”

The applicant has stated that they are carrying on the business of the hotel and they are supplying ready-to-eat breakfast, and lunch to the KLE Independent Pre University (PU) College, Bengaluru. They are not collecting any charges from the students. They are billing to college and college is paying the amount.

In this respect the ld. AAR noted that the applicant is providing catering services to Educational Institutions from 1st Standard to 2nd PUC and referred to entry No.66 of Notification No. 12/2017-Central Tax (Rate) dated 28th June, 2017 as amended vide Notification No.02/2018-Central Tax (Rate) dated 25th January, 2018 and reproduced the same as under:

“Sl. No. Chapter, Section, Heading, Group or Service Code (Tariff) Description of Services Rate (per cent.) Condition
66 Heading 9992 Services provided –

(a) by an educational institution to its students, faculty and staff;

Nil Nil
(aa) by an educational institution by way of conduct of entrance examination against
consideration in the form of entrance fee
(b) to an educational institution, by way of,-
(i) transportation of students, faculty and staff;
(ii) catering, including any mid-day meals scheme sponsored by the Central Government, State Government or Union territory;
(iii) security or cleaning or housekeeping services performed in such educational institution;
(iv) services relating to admission to, or conduct of examination by, such institution;
(v) supply of online educational

journals or periodicals:

Provided that nothing contained in sub-items (i), (ii) and (iii) of item

(b) shall apply to an educational institution other than an institution providing services by way of preschool education and education up to higher secondary school or equivalent.”

The ld. AAR observed that the services provided by way of catering to an educational institution, which is providing services by way of pre-school education and education up to higher secondary school are exempted from GST.

The ld. AAR also referred to the meaning of recipient of service as defined in section 2(93) and further observed that the concerned education institution is the recipient and it also fulfils the condition of being an Education Institution as defined in clause (v) of para 2 of the Notification no.12/2017-Central Tax (Rate) dated 28th June, 2017.

The ld. AAR arrived at the conclusion that since the applicant is providing ready-to-eat food by way of catering to a Pre-University College, the services provided by the applicant under question are covered under entry No.66 of Notification No. 12/2017-Central Tax (Rate) dated: 28.06.2017 as amended further and hence exempted from GST.

The ld. AAR issued a ruling accordingly.

22 Unit Run Canteen — Tax Position

M/s. Central Police Canteen (AR Order No. KAR ADRG 35/2023 dt. 16th November, 2023 (Kar)

The applicant is a subsidiary canteen of the Central Police Force Canteen System (CPFCS/CPF Canteen System), which is set up vide letter No.27011/75/2011-R&W dated 18th November, 2011, issued by the Resettlement & Welfare Department, Police Division-II, Ministry of Home Affairs, Government of India. They have claimed that they are entitled to avail of CPF Canteen facilities.

The applicant has quoted the Notification No.7/2017-Central Tax (Rate) dated 28th June, 2017, contending that their canteen is covered under “Unit Run Canteens” and thus the supply of goods by them to the authorized customers is exempted from levy of GST.

The applicant also contemplated that they are entitled to claim a refund of fifty per cent of the applicable central tax paid by it on all inward supplies, under notification no. 06 of 2017— Central Tax (R) dated 28th June, 2017

Applicant has put the following questions for the ruling of AAR.

“a. Whether the applicant being a recognized Unit Run Canteen be exempted from levying CGST on goods sold by it to authorized customers?

b. Whether similar exemption can be availed under State GST also?

c. Is the applicant eligible to claim a refund of CGST and SGST paid by it on goods purchased to date?”

The ld. AAR considered each question. In respect of the first question about exemption from the levy of CGST on goods sold by it to authorized customers, the learned AAR referred to Notification No. 07/2017-Central Tax (Rate) dated 28th June, 2017. Said Notification contemplates to grant exemption as under:

“Sl. No. Tariff item, sub-heading,

heading or Chapter

Description of Services of Goods
(1) (2) (3)
1. Any Chapter The supply of goods by the CSD to the Unit Run Canteens
2. Any Chapter The supply of goods by the CSD to the authorized customers.
3. Any Chapter The supply of goods by the Unit Run Canteens to the authorized customers.”

The heading CTH 8711 and 8713, are described as under The ld. AAR observed that CSD i.e., Canteen Stores Department, Unit Run Canteens of the CSD and the authorized customers of CSD mentioned in the above notification are under the Ministry of Defence, Government of India. Applicant is a subsidiary canteen of the Central Police Force Canteen System (CPFCS), under the Ministry of Home Affairs, Government of India, formed in terms of permission granted vide letter No. DAVII/ SC-CP/2013 dated 28th November, 2013.

Therefore, the ld. AAR held that the applicant is not covered under the Unit Run Canteen as they are a subsidiary canteen of CPF canteen under the Ministry of Home Affairs. Accordingly, the ld. AAR held that the applicant is not entitled to claim the exemption provided under Notification No.7/2017-Central Tax (Rate) dated 28th June, 2017.

In respect of the second question, exemption under SGST, the ld. AAR held that, like CGST, no exemption is eligible under SGST.

Regarding, the third question about a refund, the ld. AAR referred to Notification No. 6/2017-Central Tax (Rate) dated 28th June, 2017, which reads as under:

“In exercise of the powers conferred by section 55 of the Central Goods and Services Tax Act, 2017 (12 of 2017), the Central Government, on the recommendations of the Council, hereby specifies the Canteen Stores Department (hereinafter referred to as the CSD), under the Ministry of Defence, as a person who shall be entitled to claim a refund of fifty per cent, of the applicable central tax paid by it on all inward supplies of goods received by it for the purposes of subsequent supply of such goods to the Unit Run Canteens of the CSD or to the authorized customers of the CSD.

2. This notification shall come into force with effect from the 1st day of July, 2017.”

Since the above notification covers CSD under the Ministry of Defence, as a person who shall be entitled to claim a refund, the ld. AAR held that the applicant cannot be covered by the above notification as it is not under the Defence Ministry but under the Home Ministry.

Thus, all questions are answered in negative.

23 Scope of Article 243G and 243W vis-à-vis Exemption.

M/s. Sanjeevini Enterprises (AR Order No.KAR ADRG 03/2023 dt. 23rd January, 2023 (Kar)

The applicant has sought an advance ruling in respect of the following questions:

“i. Whether works contract service provided to Bio Centers, Department of Horticulture and Center of Excellence are exempted as per GST Exemptions?

ii. Whether other services like data entry operator and security, provided to the Horticulture Department attract GST?

iii. Whether materials like fertilizers, soil, and sand supplied for use of bio centres exempted as per GST?”

The applicant has stated that they are bidding for a tender called by the Department of Horticulture which includes the supply of manpower for Bio-Centre, Department of Horticulture, Centre of Excellence for Floriculture, Tunga Horticulture Farm, Shivamogga, which includes the following works:

1) Department of Horticulture: Handling the complete process of tissue culture production of various agriculture plants and mushroom research, growing under the guidance of the agriculture officer including cleaning and maintenance of equipment used for production under the tissue culture process.

2) Center for Excellence, Tunga Floriculture Center: Handling the complete process of research on flowers, planting and growing process and maintenance under the guidance of the agriculture officer including cleaning and maintenance of equipment used and handling of wastage.

The ld. AAR referred to entry no.3 of the Notification No.12/2017-Central Tax (Rate) dated 28th June, 2017 which reads as under:

“Pure Services (excluding works contract service or other composite supplies involving any goods) provided to the Central Government, State Government or Union territory or local authority by way of any activity in relation to any function entrusted to a Panchayat under article 243G of the Constitution or in relation to any function entrusted to a Municipality under article 243W of the Constitution.”

The ld. AAR observed that the applicant has to satisfy two conditions:

“1. Pure Services (excluding works contract service or other composite supplies involving any goods) provided to the Central Government, State Government or Union territory or local authority

2. by way of any activity in relation to any function entrusted to a Panchayat under article 243G of the Constitution or in relation to any function entrusted to a Municipality under article 243W of the Constitution.”

The ld. AAR observed that the first condition of supplying pure services to the Karnataka Government is satisfied.

The ld. AAR refers to functions listed under Articles 243G and 243W. The ld. AAR found that the activity of the applicant is not directly covered by any entry in the above articles. The ld. AAR examined whether it can fall under the entry for Agriculture.

The ld. AAR held that the issue certainly cannot amount to agriculture and there is no other direct entry to cover the above activity in Article 243G/243W.

The ld. AAR answers negative as under:

“i. Works contract service provided to Bio Centers, Department of Horticulture and Center of Excellence are not exempted from GST.

ii. Providing Manpower services like data entry operator, and security to the Horticulture Department is exigible to GST at 18 per cent (CGST @ 9 per cent and KGST @ 9 per cent).

iii. Materials like fertilizers, soil and sand supplied for use of bio centres are not exempted under GST.”

Part A | Company Law

6 In the Matter of M/s Nextgen Animation Media Limited

Registrar of Companies, Mumbai

Adjudication Order No. ROC(M)/NEXTGENMEDIALTD/ADJ-ORDER/92/101

Date of Order: 3rd June, 2024

Non-filing of Annual Return within a period of 60 days from the due date of Annual General Meeting amounts to violation of Section 92 of the Companies Act, 2013.

FACTS

The Registrar of Companies, Mumbai, Maharashtra (ROC) observed from MCA 21 database that NAML had defaulted in filing of Annual Return for the financial year ended on 31st March, 2019. Hence M/s NAML had not complied with the provisions of Section 92 of the Companies Act, 2013 by not filing Annual Return. A default period of 326 days was noticed.

Thereafter, a show-cause notice was issued to NAML and its officer in default on 21st October, 2020 under section 454 of the Companies Act, 2013, for adjudication of offence under Section 92(5) of the Companies Act, 2013.

However, no reply was received from NAML and its officers in default.

PROVISIONS

Section 92(4): Every company shall file with the Registrar a copy of the annual return, within sixty days from the date on which the annual general meeting is held or where no annual general meeting is held in any year within sixty days from the date on which the annual general meeting should have been held together with the statement specifying the reasons for not holding the annual general meeting, with such fees or additional fees as may be prescribed.

Section 92(5): If any company fails to file its annual return under sub-section (4), before the expiry of the period specified [therein], such company and its every officer who is in default shall be liable to a penalty of [ten thousand rupees] and in case of continuing failure, with further penalty of one hundred rupees for each day during which such failure continues, subject to a maximum of [two lakh rupees in case of a company and fifty thousand rupees in case of an officer who is in default].

HELD

Adjudication Officer (AO) has considered the facts and circumstances of the case that NAML and its officer in default had failed to reply or neglect or refuse to appear as required. Hence, AO imposed the penalty on NAML and its officer in default. AO imposed a penalty of ₹1,65,200 (one lakh, sixty-five thousand and two hundred only) on NAML and its officer in default (who is Mr. KKS being Managing Director of the NAML and considered as officer in default).

The AO further ordered to pay the penalty amount through MCA portal and proof of payment was asked to be produced for verification within 90 days of receipt of the order.

Burden of Proof in Case of Cheque Bouncing Cases

INTRODUCTION

Section 138 of the Negotiable Instruments Act, 1881 (“the Act”) is a very well-known provision even amongst laymen. It imposes a punishment in the form of an imprisonment in case a cheque, which has been issued, bounces. Whilst this is a very simplistic explanation of this very important provision, a very vital ingredient is what is the burden of proof in case of a cheque bouncing case and who is it on? The Supreme Court in its verdict in the case of Rajesh Jain vs. Ajay Singh, 2023 AIR(SC) 5018 has laid down clear-cut guidelines on the same. In the case on hand, the accused had borrowed funds from the complainant and was not returning the same. Finally, he issued a post-dated cheque which bounced on presentation. Accordingly, the complainant filed a case under Section 138 of the Act.

The Trial Court held that the only question which remained for determination was whether a legally valid and enforceable debt existed qua the complainant and the cheque in question was issued in discharge of the said liability / debt? The Trial Court answered the issue in the negative. It held that the complainant had failed to prove his case beyond reasonable doubt. It has been observed that the defence led by the accused has created a doubt regarding the truthfulness of the complainant’s case. Accordingly, the Trial Court dismissed the case against the accused.

The Punjab & Haryana High Court also found no merit in the appeal and upheld the order of acquittal passed by the Trial Court. The High Court reasoned that the accused had discharged his onus in rebutting the statutory presumption raised under Section 139 of the Act. The onus, then, once again had shifted to the complainant to prove that the cheque had been issued in respect of a legally enforceable debt, and the complainant had failed in discharging the onus to prove that cheque was issued in respect of a legally enforceable debt.

The matter, thus, travelled up to the Supreme Court.

The Apex Court held that the limited question to be considered was whether the accused could be said to have discharged his ‘evidential burden’, for the lower courts to have concluded that the presumption of law supplied by the Act had been rebutted?

ESSENCE OF SECTION 138

At the outset, one must understand the essence of Section 138 of the Act. In Gimpex Private Limited vs. Manoj Goel (2022) 11 SCC 705, the Supreme Court had explained the ingredients forming the basis of the offence under Section 138 of the Act as follows:

(a) The drawing of a cheque by person on an account maintained by him with the banker for the payment of any amount of money to another from that account;

(b) The cheque being drawn for the discharge in whole or in part of any debt or other liability;

(c) Presentation of the cheque to the bank arranged to be paid from that account;

(d) The return of the cheque by the drawee bank as unpaid either because the amount of money standing to the credit of that account is insufficient to honour the cheque or that it exceeds the amount;

(e) A notice by the payee or the holder in due course making a demand for the payment of the amount to the drawer of the cheque within 30 days of receipt of information from the bank in regard to the return of the cheque; and

(f) The drawer of the cheque failing to make payment of the amount of money to the payee or the holder in due course within 15 days.

In K. Bhaskaran vs. Sankaran Vaidhyan Balan, (1999) 7 SCC 510 the Apex Court had summarised the constituent elements of the offence in fairly similar terms by holding:
“14. The offence Under Section 138 of the Act can be completed only with the concatenation of a number of acts. The following are the acts which are components of the said offence:

(1) drawing of the cheque,

(2) presentation of the cheque to the bank,

(3) returning the cheque unpaid by the drawee bank,

(4) giving notice in writing to the drawer of the cheque demanding payment of the cheque amount,

(5) failure of the drawer to make payment within 15 days of the receipt of the notice.”

BURDEN OF PROOF

The Court laid down principles of burden of proof and held that there were two senses in which the phrase “burden of proof” was used in the Indian Evidence Act, 1872:

(a) One was the burden of proof arising as a matter of pleading — this was called the “legal burden” and it never shifted during a case. The legal burden was the burden of proof which remained constant throughout a trial. It was the burden of establishing the facts and contentions which supported a party’s case. If, at the conclusion of the trial, a party failed to establish these to the appropriate standards, he would lose to stand. The incidence of the burden was clear from the pleadings and usually, it was incumbent on the plaintiff or complainant to prove what he pleaded or contended.

(b) The other was the one which deals with the question as to who has first to prove a particular fact — this was called the “evidential burden” and it shifted from one side to the other, Kundanlal vs. Custodian Evacuee Property (AIR 1961 SC 1316). The evidential burden could shift from one party to another as the trial progressed according to the balance of evidence given at any particular stage; the burden rested upon the party who would fail if no evidence at all, or no further evidence, as the case may be was adduced by either side.

PRESUMPTIONS

The Court next explained the meaning of presumptions — it literally meant “taking as true without examination or proof”. Presumptions were of two kinds: presumptions of fact and of law.

Presumptions of fact were inferences logically drawn from one fact as to the existence of other facts. Presumptions of fact were rebuttable by evidence to the contrary.

Presumptions of law may be rebuttable or irrebuttable (conclusive presumptions), so that no evidence to the contrary may be given. A rebuttable presumption of law was a legal rule to be applied by the Court in the absence of conflicting evidence. Rebuttable presumptions could be further bifurcated into discretionary presumptions (“may presume”) and compulsive or compulsory presumptions (“shall presume”).

EVIDENCE UNDER SECTION 139

The Court further held that Section 139 of the Act was an example of a reverse onus clause and required the accused to prove the non-existence of the presumed fact, i.e., that cheque was not issued in discharge of a debt / liability.

It held that the Act provided for two presumptions: Section 118 and Section 139:

(a) Section 118 of the Act inter alia directed that it shall be presumed, until the contrary was proved, that every negotiable instrument was made or drawn for consideration.

(b) Section 139 of the Act stipulated that “unless the contrary is proved, it shall be presumed, that the holder of the cheque received the cheque, for the discharge of, whole or part of any debt or liability”. The Court held that the “presumed fact” directly related to one of the crucial ingredients necessary to sustain a conviction under Section 138. As per the Court, Section 139 of the Act, which took the form of a “shall presume” clause was illustrative of a presumption of law. Because Section 139 required that the Court “shall presume” the fact stated therein, it was obligatory on the Court to raise this presumption in every case where the factual basis for the raising of the presumption had been established. However, this did not preclude the person against whom the presumption is drawn from rebutting it and proving the contrary as was clear from the use of the phrase “unless the contrary is proved”.

The Court also held that it will necessarily presume that the cheque had been issued towards discharge of a legally enforceable debt / liability in two circumstances.

Firstly, when the drawer of the cheque admitted issuance / execution of the cheque and secondly, in the event where the complainant proved that cheque was issued / executed in his favour by the drawer. The circumstances set out above form the fact(s) which bring about the activation of the presumptive clause. [Bharat Barrel vs. Amin Chand] [(1999) 3 SCC 35].

In Bir Singh vs. Mukesh Kumar, (2019) 4 SCC 197, the Supreme Court held that that presumption took effect even in a situation where the accused contended that “a blank cheque leaf was voluntarily signed and handed over by him to the complainant”. Therefore, the Court concluded that mere admission of the drawer’s signature, without admitting the execution of the entire contents in the cheque, was now sufficient to trigger the presumption. It further held that as soon as the complainant discharged the burden to prove that a cheque was issued by the accused for discharge of debt, the presumptive device under Section 139 of the Act helped shift the burden on the accused. The effect of the presumption, in that sense, was to transfer the evidential burden on the accused of proving that the cheque was not received by the bank towards the discharge of any liability. Until this evidential burden was discharged by the accused, the presumed fact will have to be taken to be true, without expecting the complainant to do anything further.

REBUTTAL

The Apex Court held that in order to rebut the presumption and prove to the contrary, it was open to the accused to raise a probable defence wherein the existence of a legally enforceable debt or liability could be contested. The words “until the contrary is proved” occurring in Section 139 did not mean that accused must necessarily prove the negative that the instrument was not issued in discharge of any debt / liability, but the accused had the option to ask the Court to consider the non-existence of debt / liability so probable that a prudent man ought, under the circumstances of the case, to act upon the supposition that debt / liability did not exist, Basalingappa vs. Mudibasappa (AIR 2019 SC 1983).

Thus, as per the Court, the accused had two options:

(a) Proving that the debt / liability did not exist. This was to lead defence evidence and conclusively establish with certainty that the cheque was not issued in discharge of a debt / liability.

(b) Prove the non-existence of debt / liability by a preponderance of probabilities by referring to the particular circumstances of the case. The preponderance of probability in favour of the accused’s case could be even 51:49 and arising out of the entire circumstances of the case, which included the complainant’s version in the original complaint, the case in the legal / demand notice, complainant’s case at the trial, as also the plea of the accused in the reply notice, his statement at the trial as to the circumstances under which the promissory note / cheque was executed. All of them could raise a preponderance of probabilities justifying a finding that there was “no debt / liability”.

It also held that the nature of evidence required to shift the evidential burden did not have to necessarily be direct evidence, i.e., oral or documentary evidence or admissions made by the opposite party; it could comprise circumstantial evidence or presumption of law or fact.

The accused may adduce direct evidence to prove that the instrument was not issued in discharge of a debt / liability and, if he did so, then the burden again shifted to the complainant. At the same time, the accused may also rely upon circumstantial evidence and, if the circumstances so relied upon were compelling enough, then the burden again shifted to the complainant. It was open for him to also rely upon presumptions of fact. The burden of proof may shift by presumptions of law or fact.

It further alluded that once the accused gave evidence to the satisfaction of the Court that on a preponderance of probabilities there existed no debt / liability in the manner pleaded in the complaint, the burden shifted back to the complainant and the presumption “disappeared” and does not haunt the accused any longer. The onus having now shifted to the complainant, he was now obliged to prove the existence of a debt / liability as a matter of fact and his failure to prove would result in dismissal of his complaint case. Thereafter, the presumption under Section 139 did not again come to the complainant’s rescue. Once both parties have adduced evidence, the Court had to consider the same and the burden of proof lost all its importance, Basalingappa vs. Mudibasappa, AIR 2019 SC 1983; Rangappa vs. Sri Mohan (2010) 11 SCC 441.

FINDINGS OF THE COURT

In the backdrop of the above legal analysis, the Supreme Court examined the conduct of the accused to ascertain whether there was evidence against him or had he rebutted it?

It noted the following fallacies and inconsistencies in the conduct of the accused:

(a) He neither replied to the demand notice nor has led any rebuttal evidence in support of his case.

(b) He had suggested that an employee of his had colluded with the complainant and falsely given a blank cheque containing his signature to the complainant. This was denied by the employee and the evidence was not sustained in cross-examination. Further, the Court noted that no action had been taken by way of registering a police complaint in order to prosecute the alleged illegal conduct of his blank cheque having been misused.

(c) The Court noted that on an overall consideration of the record, it found that the case set up by the accused was thoroughly riddled with contradictions. It was apparent on the face of the record that there was not the slightest of credibility perceivable in the defence set up by the accused.

(d) It also noted that the accused in some of his statements agreed that he had taken a loan from the complainant, but later on he stated that he had no financial dealings with the complainant.

(e) The Court observed that the signature on the cheque having not been disputed, and the presumption under Sections 118 and 139 having taken effect, the complainant’s case satisfied every ingredient necessary for sustaining a conviction under Section 138.

The case of the defence was limited only to the issue as to whether the cheque had been issued in discharge of a debt / liability. The Court concluded that the accused having miserably failed to discharge his evidential burden, that fact will have to be taken to be proved by force of the presumption, without requiring anything more from the complainant.

The Supreme Court also held that there was a fundamental flaw in the way both the lower Courts proceeded to appreciate the evidence on record. Once the presumption under Section 139 was given effect to, the Courts ought to have proceeded on the premise that the cheque was, indeed, issued in discharge of a debt / liability. The entire focus would then necessarily have to shift on the case set up by the accused, since the activation of the presumption had the effect of shifting the evidential burden on the accused.

The nature of inquiry would then be to see whether the accused has discharged his onus of rebutting the presumption. If he failed to do so, the Court can straightaway proceed to convict him, subject to satisfaction of the other ingredients of Section 138. If the Court found that the evidential burden placed on the accused has been discharged, the complainant would be expected to prove the said fact independently, without taking aid of the presumption. The Court would then take an overall view based on the evidence on record and decide accordingly.The course of action when the courts concluded that the signature had been admitted should have been to inquire into either of the two questions (depending on the method in which accused has chosen to rebut the presumption):

(a) Had the accused led any defence evidence to prove and conclusively establish that there existed no debt / liability at the time of issuance of cheque?

(b) In the absence of rebuttal evidence being led the inquiry would entail: Had the accused proved the nonexistence of debt / liability by a preponderance of probabilities by referring to the “particular circumstances of the case”?

The Supreme Court came down heavily on the Trial Court’s perverse approach. According to the Trial Court, the question to be decided was “whether a legally valid and enforceable debt existed qua the complainant and the cheque in question was issued in discharge of said liability / debt”. The Supreme Court observed:

“When the initial framing of the question itself being erroneous, one cannot expect the outcome to be right.”

The onus instead of being fixed on the accused had been fixed on the complainant. Lack of proper understanding of the nature of the presumption in Section 139 and its effect resulted in an erroneous Order being passed by the Trial Court.

It next took up the erroneous approach by the High Court. The High Court had found that the complainant has proved the issuance of cheque, which (as per the Apex Court) meant that the presumption would come into immediate effect. Further, the High Court rightly observed that the burden was on the accused to rebut such presumption.

However, as per the Supreme Court, in the very next paragraph, the High Court found that the accused had rebutted the presumption by putting questions to the complainant. There was no elucidation of material circumstances / basis on which the High Court could have reached such a conclusion. The Supreme Court held that the High Court rather shockingly concluded that:

“If the complainant had given loans on various dates, he must have maintained some document qua that, because it was not a one-time, loan but loan along with interest accrued on the principal, ….”

Therefore, according to the High Court, “the burden was primarily on the complainant to prove the debt amount”. This as per the Apex Court was a fundamental error. The High Court had questioned the want of evidence on part of the complainant in order to support his allegation of having extended loan to the accused, when it ought to have instead concerned itself with the case set up by the accused and whether he had discharged his evidential burden by proving that there existed no debt / liability at the time of issuance of cheque.

Finally, the Supreme Court set aside the acquittal verdict given by the High Court and allowed the complaint filed under Section 138 of the Act and convicted the accused.

CONCLUSION

This decision has explained very clearly the process of alluding evidence in cases of cheque bouncing and when and how the onus shifts from one party to another.

Allied Laws

20 Central Bank of India vs. Shanmugavelu

AIR 2024 Supreme Court 962

2nd February, 2024

Auction of property — Highest bidder — Earnest money paid — Unable to pay the balance — Sale terminated by the bank — Earnest money forfeited by the bank — Banks not liable to refund earnest money. [R. 9(5) Security Interest (Enforcement) Rules, 2002; S. 73, 74, Indian Contracts Act, 1872].

FACTS

A property was set up for auction by the Appellant Bank under the provisions of the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Act, 2022 (SARFAESI Act). The Respondent emerged as the highest bidder and purchased the property after paying 25 per cent as earnest money. However, he was unable to pay the remaining 75 per cent of the balance amount owing to a delay in acquiring the loan. Thus, the Appellant Bank cancelled the auction sale and refused to refund the earnest money as per the provisions of Rule 9(5) of the Security Interest (Enforcement) Rules, 2002 (SARFAESI Rules). Aggrieved by the refusal of refund money and cancellation of the sale, the Respondent filed an application before the Debt Recovery Tribunal. The Tribunal held that the Respondent was entitled to refuse the refund of the earnest money. However, the same was limited only to the extent of loss or damage caused to the Appellant Bank as envisaged in sections 73 and 74 of the Indian Contracts Act, 1872 (Contracts Act). Therefore, the Appellant Bank was directed to refund the earnest money after deducting a minuscule amount as expenditure/loss incurred. Aggrieved, the Appellant bank approached the Madras High Court. However, the decision of the Tribunal was confirmed by the High Court with a slight enhancement of expenditure/loss amount.

Aggrieved by the decision of the High Court, an appeal was filed before the Supreme Court (Three-Judge Bench).

HELD

The Supreme Court held that the provisions of sections 73 and 74 of the Contracts Act do not apply to the auction process conducted under the SARFAESI Act. Further, the Court also noted that the SARFAESI Act was a special legislation which overrides the general legislation. Furthermore, the Court also held that Rule 9(5) of the SARFAESI Rules cannot be read down just because of its harsher consequence. Thus, the appeal filed by the Appellant Bank was allowed and the order of the Madras High Court was set aside.

21 N.H.A.I vs. Hindustan Construction Company Ltd

2024 LiveLaw (SC) 361

7th May, 2023

Arbitration — Majority Award — Appeal to courts only if an award is in violation of the public policy of India — Courts cannot sit in appeal over Arbitral Tribunal’s interpretation of contract [S. 34, 37, Arbitration and Conciliation Act, 1996].

FACTS

The Appellant had awarded a four hundred crore contract to the Respondent for road construction in the Allahabad Bypass project. Thereafter, a dispute arose between the parties and the parties were referred to an Arbitral Tribunal (Tribunal). The Arbitral Tribunal after taking into consideration the contract agreement and the facts of the case, passed an award (2:1) in favour of the Respondent and directed the Appellant to pay additional cost to the Respondent. Aggrieved by the award of the Arbitral Tribunal, a petition under section 34 of the Arbitration and Conciliation Act, 1996 (Act) was filed before the Delhi High Court (Single Judge Bench). The High Court, however, dismissed the appeal on the ground that the view taken by the majority needed no interference from the Court. Aggrieved, an appeal was filed under section 37 of the Act before the Division Bench of the Delhi High Court. The appeal was, however, dismissed by the Hon’ble Court on similar grounds.

Aggrieved by the order of the Delhi High Court (both, Division and Single Bench), an appeal was preferred before the Supreme Court.

HELD

The Supreme Court, at the outset, observed that the jurisdiction of the courts is very limited under section 34 of the Act, and the restrictions are even greater while adjudicating cases under 37 of the Act. The Supreme Court, concurring with decisions of the Delhi High Court, held that only when the award is in conflict with the public policy of India, the Court would be justified in interfering with the arbitral award. Further, when a court is applying the ‘public policy’ test to an arbitration award, it does not act as a court of appeal over the findings and interpretation of the arbitrator.

Thus, the award of the Tribunal was confirmed.

22 Dell International Service India Pvt Ltd vs. Adeel Feroze and Ors

W.P. (C) 4733 of 2024 (SC)

2nd July, 2023

Evidence — Admissibility of electronic data/evidence — Mandatory Certification required — [S. 65B, Indian Evidence Act, 1872].

FACTS

A plea was filed by the Respondent before the Consumer Dispute Redressal Commission (District Commission) against the Petitioner. The Learned District Commission had refused to condone the delay by the Petitioner in filing its written submission. The counsel for the Petitioner had contended before the District Commission that he had not received the copy of the entire complaint along with all the annexures and it was received by him much later. However, the Learned District Commission after going through postal receipts of the documents held that the application of condonation of delay of the Petitioner was not bonafide. Thus, an appeal was filed by the Petitioner before the Delhi State Consumer Dispute Redressal Commission (State Commission). The State Commission also dismissed the appeal on the ground that the condonation of delay application was not bonafide.

Aggrieved, a Petition was filed under Articles 226 and 227 of the Constitution before the Delhi High Court.

HELD

The Petitioner in its plea before the Delhi High Court demonstrated by way of screenshots of WhatsApp chats between the Petitioner and the Respondent regarding the missing annexures of the complaint copy. However, the Delhi High Court observed that the said screenshots of WhatsApp chats were not certified as mandated by section 65B of the Indian Evidence Act, 1872. Therefore, the Hon’ble Court held that the screenshots cannot be taken into evidence.

Thus, the Petition was dismissed and the orders of the District and State Commission were not interfered with.

23 Bano Saiyed Parwaz vs. Chief Controlling Revenue Authority and Inspector General of Registration and Controller of Stamps and Ors.

2024 LiveLaw (SC) 426

17th May, 2024

Stamp Duty — Registration – Conveyance deed — Stamp duty paid — Fraud — Cancellation thereof – Refund Application — Cancellation Deed — Cancellation deed executed after making application of refund — Mere technicalities — Refund granted. [S. 47, 48, Maharashtra Stamps Act, 1958.].

FACTS

A conveyance deed, for purchase of property was executed by the Appellant and the vendor on 13th May, 2014. The stamp duty was duly paid by the Appellant on the same day. Thereafter, the Appellant came to know that the property was already sold by the vendor to some other party. Therefore, she (Appellant) decided to cancel the conveyance deed. On 22nd October, 2014, the appellant filed an application before the stamp duty authority (Respondent) seeking a refund for the stamp duty already paid by her on 13th May, 2014. However, she was unable to execute a cancellation deed due to the non-availability of the vendor. It was only with the help of law enforcement that the Appellant was able to execute a cancellation deed on 13th November, 2014 (i.e. six months and one day after registration of the original conveyance deed). The Respondent refused the application on the ground that the said cancellation deed was time-barred as per the provision laid down in section 48 of the Maharashtra Stamp Act, 1958 (Act). Further, the cancellation deed was executed after the application for refund was made. Aggrieved, a writ was filed before the Bombay High Court. The disallowed the petition.

Aggrieved, a Special Leave Petition was filed before the Hon’ble Supreme Court.

HELD

The Hon’ble Supreme Court observed that the Appellant had immediately filed for a refund as soon as she gained knowledge of the fraud. Further, she was unable to execute the cancellation deed due to the unavailability of the vendor, and the same was done only with the help of law enforcement. Thus, there was no lax approach on the part of the Appellant. Therefore, the Supreme Court held that the Respondent was not justified in denying a refund to the Appellant on mere technicalities. The Court further held that since the application was filed before six months (though registration was done after six months), the Appellant was not time-barred as per section 48 of the Act.

Thus, the Petition was allowed, and the Respondent was directed to refund the stamp duty.

From Published Accounts

COMPILERS’ NOTE

The Companies Act, 2013 does not require any mandatory transfer to Reserves based on quantum of dividend declared by a company. Companies may now want to utilise such Reserves (created based on provisions of the earlier Companies Act, 1956) for payment of dividend or other purposes. Given below are instances of two companies who have obtained the approval of the National Company Law Tribunal (NCLT) or have filed an application for the same for such transfer from General Reserve to Retained Earnings.

NESTLE INDIA LIMITED (15 MONTHS ENDED 31ST MARCH, 2024)

Disclosures for Scheme of Arrangement in Standalone Financial Statements:

A) From Director’s Report

Scheme of Arrangement

The Board of Directors, at its meeting held on 28th July, 2021, had approved the Scheme of Arrangement between the Company and its members under Section 230 of the Companies Act, 2013 as amended (“the Act”) read with other applicable provisions of the Act and Rules made thereunder (“the Scheme”), which envisaged transfer of the entire balance of ₹8,374.3 million standing to the credit of the General Reserves to Retained Earnings. Your Company had filed an application with Hon’ble National Company Law Tribunal, Delhi Bench (Hon’ble NCLT) on 22nd March, 2022, for the sanction of Scheme. After requisite formalities, the Hon’ble NCLT, vide its Order dated 15th September, 2023, had sanctioned the Scheme. Certified copy of the Order sanctioning the Scheme was filed with the Registrar of Companies, Delhi, and the Scheme became effective from 19th October, 2023. Accordingly, the entire amount of ₹8,374.3 million standing to the credit of the General Reserves of the Company was reclassified and credited to the ‘Retained Earnings’ of your Company and constitute accumulated profits of your Company for the previous financial years, arrived at after providing for depreciation in accordance with the provisions of the Act and remaining undistributed in the manner provided in the Act and other applicable laws. Pursuant to the Scheme, the amount so transferred is available for utilization and payout in accordance with the terms of the Scheme.

B) From Statement of Changes in Equity

a) Other Equity

Reserves and Surplus Items of Other Comprehensive Income Total
General Reserves Share-based Payment Capital Reserve Retained Earning Equity Instrument through Other Comprehensive Income Effective portion of Cash Flow Hedges
Balance as on
31st December, 2021
8,374.3 (250.8) 10,694.9 (330.0) 11.2 18,499.6
Profit after tax 23,905.2 23,905.2
Other comprehensive income 1,139.2 (17.7) (2.1) 1,119.4
Total comprehensive income 25,044.4 (17.7) (2.1) 25,024.6
Transfer of Equity Instruments through other (347.7) 347.7
Comprehensive income to Retained Earnings
Dividend (Refer note 43) (20,247.3) (20,247.3)
Share-based Payment Expense 143.7 143.7
Recognition of liability towards Share

Based Payments

(143.7) (143.7)
Other changes in net assets of Pet Food Business 350.6 350.6
Balance as on
31st December, 2022
8,374.3 99.8 15,144.3 9.1 23,627.5
Profit after tax 39,328.4 39,328.4
Other comprehensive income (429.0) (0.4) (429.4)
Total comprehensive income 38,899.4 (0.4) 38,899.0
Transfer of General Reserve to Retained Earnings* (8,374.3) 8,374.3
Dividend (Refer note 43) (30,081.8) (30,081.8)
Share Based Payment Expense 206.8 206.8
Recognition of liability towards Share Based Payments (206.8) (206.8)
Balance as on 31st March, 2024 99.8 32,336.2 8.7 32,444.7

* The Shareholders of the Company had, at the Court Convened Meeting held on 25th July, 2022, approved the Scheme of Arrangement (‘Scheme’) which envisages transfer of the entire balance of ₹8,374.3 million standing to the credit of the General Reserves to Retained Earnings. The Company had accordingly filed a petition for sanction of the Scheme with the Hon’ble National Company Law Tribunal, New Delhi Bench (“Hon’ble NCLT”). The Hon’ble NCLT, vide its order dated 15th September, 2023 (“Order”), has sanctioned the Scheme. The Appointed Date as fixed in the Scheme is 1st January, 2022. The Scheme has been made effective on and upon filing of the certified copy of the Order with the Registrar of Companies.

C) From Notes to Accounts: Note 17: Other Equity

a) Nature and description of reserve

(i) General Reserve: General reserve are free reserves of the Company which are kept aside out of Company’s profits to meet the future requirements as and when they arise. The Company had transferred a portion of the profit after tax (PAT) to general reserve pursuant to the earlier provisions of the erstwhile Companies Act, 1956. It is not mandatory to transfer the profit to reserve under the provisions of the Companies Act, 2013 (“Act”).

The Shareholders of the Company had, at the Court Convened Meeting held on 25th July, 2022, approved the Scheme which envisages transfer of the entire balance of ₹8,374.3 million standing to the credit of the General Reserves to Retained Earnings. The Company had accordingly filed a petition for sanction of the Scheme with the Hon’ble National Company Law Tribunal, New Delhi Bench (“Hon’ble NCLT”). The Hon’ble NCLT, vide its order dated 15th September, 2023 (“Order”), had sanctioned the Scheme. The Appointed Date as fixed in the Scheme is 1st January, 2022, and the Scheme became effective from 19th October, 2023, the date on which the certified copy of the order was filed with the concerned Registrar of Companies.

VEDANTA LIMITED – YEAR ENDED 31ST MARCH, 2024

A) From Director’s Report

Scheme of Arrangement between Vedanta Limited and its Shareholders under Section 230 and other applicable provisions of the Companies Act, 2013

The Board of Directors of the Company, basis the recommendation of the Audit & Risk Management Committee and Committee of Independent Directors of the Company, at its meeting held on 29th October, 2021, approved the Scheme between the Company and its shareholders under Section 230 and other applicable provisions of the Act. The Scheme provides for capital reorganisation of the Company, inter alia, providing for transfer of amounts standing to the credit of the General Reserves (as defined in the Scheme) to the Retained Earnings (as defined in the Scheme) of the Company with effect from the Appointed Date.

The NCLT, Mumbai Bench vide its order dated 26th August, 2022 (“NCLT Order”), inter alia, directed the Company to convene meeting of its equity shareholders to seek their approval to the Scheme; and file consent affidavits of all the secured creditors and unsecured creditors of at least value of 90% of unsecured creditors, at the time of filing the Company Scheme Petition.

In this regard, a meeting of the equity shareholders of the Company was held on 11th October, 2022, and the proposed Scheme was approved by the equity shareholders with requisite majority. The Company is in the process of complying with the further requirements specified in the NCLT Order.

Pursuant to the Scheme, the Company will possess greater flexibility to undertake capital-related decisions and reflect a much efficient balance sheet of the Company. The Scheme is in the interest of all stakeholders including public shareholders.

B) From Notes to Accounts: Note 15: Other equity

a) General reserve: Under the erstwhile Companies Act, 1956, general reserve was created through an annual transfer of net income at a specified percentage in accordance with applicable regulations. The purpose of these transfers was to ensure that if a dividend distribution in a given year is more than 10% of the paid-up capital of the Company for that year, then the total dividend distribution is less than the total distributable reserves for that year. Consequent to introduction of Companies Act, 2013 (“Act”), the requirement to mandatorily transfer a specified percentage of the net profit to general reserve has been withdrawn.

The Board of Directors of the Company, on 29th October, 2021, approved the Scheme of Arrangement between the Company and its shareholders under Section 230 and other applicable provisions of the Act (“Scheme”). The Scheme provides for capital reorganisation of the Company, inter alia, providing for transfer of amounts standing to the credit of the General Reserves to the Retained Earnings of the Company with effect from the Appointed Date.

Post the requisite approvals obtained from Stock Exchanges and pursuant to the National Company Law Tribunal (“NCLT”), Mumbai Bench Order dated 26th August, 2022 (“NCLT Order”), the proposed scheme was approved by the shareholders with requisite majority on 11th October, 2022.

The Company is in the process of complying with the further requirements specified in the NCLT Order.

HINDUSTAN UNILEVER LIMITED – FY 2018–19

A) Director’s Report

Scheme of Arrangement

The Members of the Company, had, at the Court Convened Meeting held on 30th June, 2016, approved the Scheme for transfer of the balance of R2,187 crores standing to the credit of the General Reserves to the Profit and Loss Account. The Company had accordingly filed the petition for sanction of the Scheme of Arrangement with the Hon’ble High Court of Mumbai (jurisdiction later changed to NCLT). The Hon’ble NCLT, Mumbai Bench, vide its order dated 30th August, 2018, has sanctioned the aforesaid Scheme. With Scheme becoming effective, the balance of R2,187 crores standing to the credit of the General Reserves has been transferred to the Profit and Loss Account.

B) Statement of changes in equity

Reserves and Surplus Items of Other Comprehensive Income (OCI) Total
Capital reserve Capital Redemption

Reserve


Securities Premium Employee Stock Options Outstanding Account General Reserve Retained Earnings Other Reserves Remeasurements of net defined benefit plans Debt instruments through OCI
As on 31st March, 2017 4 6 116 30 2,187 3,953 9 (32) 1 6,274
Profit for the year 5,237 5,237
Other comprehensive income for the year (11) (1) (12)
Total comprehensive income for the year 5,237 (11) (1) 5,225
Dividend on equity shares for the year (Note: 37) (3,896) (3,896)
Dividend distribution tax (Note: 37) (755) (755)
Issue of equity shares on exercise of employee stock options 11 (11)
Equity settled share-based payment credit 11 11
As on 31st March, 2018 4 6 127 30 2,187 4,539 9 (43) 0 6,859
Profit for the year 6,036 6,036
Other comprehensive income for the year (4) 1 (3)
Total comprehensive income for the year 6,036 (4) 1 6,033
Dividend on equity shares for the year (Note: 37) (4,546) (4,546)
Dividend distribution tax (Note: 37) (913) (913)
Transfer to retained earnings (refer note b below) (2,187) 2,187
Issue of equity shares on exercise of employee stock options 15 (15)
Equity settled share-based payment credit 10 10
As on 31st March, 2019 4 6 142 25 7,303 9 (47) 1 7,443

C) The Shareholders of the Company, had, at the Court Convened Meeting held on 30th June, 2016, approved the Scheme for transfer of the balance of ₹2,187 crores standing to the credit of the General Reserves to the Profit and Loss Account. The Company had accordingly filed a petition for sanction of the Scheme with the Hon’ble High Court of Mumbai [jurisdiction later changed to NCLT). The Hon’ble NCLT, Mumbai Bench, vide its order dated 30th August, 2018, has sanctioned the aforesaid Scheme. The Company has received the said Order on 27th September, 2018 and filed the Order and the Scheme with Registrar of Companies (ROC) on 5th October, 2018 and has subsequently reclassified the amount standing to the credit of the General Reserves to the Retained Earnings.

D) Note 18: Other Equity

(a) General Reserve: The Company had transferred a portion of the net profit of the Company before declaring dividend to general reserve pursuant to the earlier provisions of Companies Act, 1956. Mandatory transfer to general reserve is not required under the Companies Act, 2013. During the year, the Company has reclassified the amount standing to the credit of the General Reserves to the Retained Earnings subsequent to approval by Hon’ble NCLT on the Scheme.

Ind AS 2023 Amendments – Ind AS 1 Presentation of Financial Statements

DISCLOSURE OF ACCOUNTING POLICY INFORMATION

Ind AS 1 Presentation of Financial Statements is amended to require disclosure of material accounting policy information, instead of disclosure of significant accounting policies. Because ‘significant’ is not defined in Ind AS Standards, entities can have difficulty assessing whether an accounting policy is ‘significant’ and understanding the difference, if any, between ‘significant’ and ‘material’ accounting policies. Because ‘material’ is defined in Ind AS Standards and is well understood by stakeholders, the standard setters decided to require entities to disclose their material accounting policy information instead of their significant accounting policies.

Accounting policy information is material if, when considered together with other information included in an entity’s financial statements, it can reasonably be expected to influence decisions that the primary users of general-purpose financial statements make on the basis of those financial statements. An entity shall apply the change for annual reporting periods beginning on or after
1st April, 2023.

Accounting policy information that relates to immaterial transactions, other events or conditions is immaterial and need not be disclosed. Accounting policy information may nevertheless be material because of the nature of the related transactions, other events or conditions, even if the amounts are immaterial. However, not all accounting policy information relating to material transactions, other events or conditions is itself material.

Accounting policy information is expected to be material if users of an entity’s financial statements need it to understand other material information in the financial statements. For example, an entity is likely to consider accounting policy information material to its financial statements if that information relates to material transactions, other events or conditions and:

(a) the entity changed its accounting policy during the reporting period and this change resulted in a material change to the information in the financial statements;

(b) the entity chose the accounting policy from one or more options permitted by Ind ASs;

(c) the accounting policy was developed in accordance with Ind AS 8 Accounting Policies, Changes in Accounting Estimates and Errors in the absence of an Ind AS that specifically applies;

(d) the accounting policy relates to an area for which an entity is required to make significant judgements or assumptions in applying an accounting policy, and the entity discloses those judgements or assumptions in accordance with paragraphs 122 and 125 of Ind AS 1; or

(e) the accounting required for them is complex and users of the entity’s financial statements would otherwise not understand those material transactions, other events or conditions — such a situation could arise if an entity applies more than one Ind AS to a class of material transactions.

Since the above list is not exhaustive, entities also need to consider if there are any other qualitative factors that would make accounting policy information material to the financial statements. For example, an entity could act as a principal in some classes of transactions and as an agent in other similar transactions depending on whether it controls the goods or services before transferring them to the customer or not. In such instances, in addition to the disclosures about significant judgements, a primary user could require accounting policy information explaining the two situations and the accounting policy differences to understand the related information in the financial statements.

Accounting policy information that focuses on how an entity has applied the requirements of the Ind ASs to its own circumstances provides entity-specific information that is more useful to users of financial statements than standardised information, or information that only duplicates or summarises the requirements of the Ind ASs.If an entity discloses immaterial accounting policy information, such information shall not obscure material accounting policy information. An entity’s conclusion that accounting policy information is immaterial does not affect the related disclosure requirements set out in other Ind ASs. For example, if an entity applying the amendments decides that accounting policy information about intangible assets is immaterial to its financial statements, the entity would still need to disclose the information required by Ind AS 38 Intangible Assets that the entity had determined to be material.

An entity shall disclose, along with material accounting policy information or other notes, the judgements, apart from those involving estimations, that management has made in the process of applying the entity’s accounting policies and that have the most significant effect on the amounts recognised in the financial statements.

In many cases, information about the measurement basis (or bases) used in preparing the financial statements is material. However, in some cases, the measurement basis (or bases) used for a particular asset or liability would not be material and, therefore, would not need to be disclosed. For example, information about a measurement basis might be immaterial if:

(a) an Ind AS Standard required an entity to use a measurement basis—in which case an entity would not apply choice or judgement in complying with the Standard; and

(b) information about the measurement basis would not be needed for users to understand the related material transactions, other events or conditions.

In assessing whether accounting policy information is material to its financial statements, an entity considers whether users of the entity’s financial statements would need that information to understand other material information in the financial statements. An entity makes this assessment in the same way it assesses other information: by considering qualitative and quantitative factors. The diagram below illustrates how an entity assesses whether accounting policy information is material and, therefore, shall be disclosed.

Entity-specific qualitative factors include the involvement of related parties, uncommon or non-standard features in transactions, other events or conditions and unexpected variations or changes in trends. The context in which the entity operates could also impact the relevance of information to the primary users; this is referred to as external qualitative factors. Examples include geographical locations, industry sector, and the state of the economy in which the entity operates. Sometimes the absence of an external qualitative factor is relevant, for example, if the entity is not exposed to a certain risk to which many other entities in its industry are exposed, information about that lack of exposure could be material information

Determining whether accounting policy information is material

Paragraph 117B of Ind AS1 includes examples of circumstances in which an entity is likely to consider accounting policy information to be material to its financial statements. The list is not exhaustive but provides guidance on when an entity would normally consider accounting policy information to be material.

Paragraph 117C of Ind AS 1 describes the type of material accounting policy information that users of financial statements find most useful. Users generally find information about the characteristics of an entity’s transactions, other events or conditions—entity-specific information—more useful than disclosures that only include standardised information or information that duplicates or summarises the requirements of the Ind AS Standards. Entity-specific accounting policy information is particularly useful when that information relates to an area for which an entity has exercised judgment—for example, when an entity applies an Ind AS Standard differently from similar entities in the same industry.

Although entity-specific accounting policy information is generally more useful, material accounting policy information could sometimes include information that is standardised, or that duplicates or summarises the requirements of the Ind AS Standards. Such information may be material if, for example:

a. users of the entity’s financial statements need that information to understand other material information provided in the financial statements. Such a scenario might arise when an entity applying Ind AS 109 Financial Instruments has no choice regarding the classification of its financial instruments. In such scenarios, users of that entity’s financial statements may only be able to understand how the entity has accounted for its material financial instruments if users also understand how the entity has applied the requirements of Ind AS 109 to its financial instruments.

b. an entity reports in a jurisdiction in which entities also report applying local accounting standards.

c. the accounting required by the Ind AS Standards is complex, and users of financial statements need to understand the required accounting. Such a scenario might arise when an entity accounts for a material class of transactions, other events or conditions by applying more than one Ind AS Standard.

Paragraph 117D of Ind AS1 states that if an entity discloses immaterial accounting policy information, such information shall not obscure material information.

Example A—making materiality judgements and focusing on entity-specific information while avoiding standardised (boilerplate) accounting policy information

Background

An entity operates within the telecommunications industry. It has entered into contracts with retail customers to deliver mobile phone handsets and data services. In a typical contract, the entity provides a customer with a handset and data services over three years. The entity applies Ind AS 115 Revenue from Contracts with Customers and recognises revenue when, or as, the entity satisfies its performance obligations in line with the terms of the contract.

The entity has identified two performance obligations and related considerations:

(a) the handset—the customer makes monthly payments for the handset over three years; and

(b) data—the customer pays a fixed monthly charge to use a specified monthly amount of data over three years.

For the handset, the entity concludes that it should recognise revenue when it satisfies the performance obligation (when it provides the handset to the customer). For the provision of data, the entity concludes that it should recognise revenue as it satisfies the performance obligation (as the entity provides data services to the customer over the three-year life of the contract).

The entity notes that, in accounting for revenue it has made judgements about:

a. the allocation of the transaction price to the performance obligations; and

b. the timing of satisfaction of the performance obligations.

The entity has concluded that revenue generated from these contracts is material to the reporting period.

Application

The entity notes that for contracts of this type it applies separate accounting policies for two sources of revenue, namely revenue from:

(a) the sale of handsets; and

(b) the provision of data services.

Having identified revenue from contracts of this type as material to the financial statements, the entity assesses whether accounting policy information for revenue from these contracts is, in fact, material.

The entity evaluates the effect of disclosing the accounting policy information by considering the presence of qualitative factors. The entity noted that its revenue recognition accounting policies:

(a) were unchanged during the reporting period;

(b) were not chosen from accounting policy options available in the Ind AS Standards;

(c) were not developed in accordance with Ind AS8 Accounting Policies, Changes in Accounting Estimates and Errors in the absence of an Ind AS Standard that specifically applies; and

(d) are not so complex that primary users will be unable to understand the related revenue transactions without standardised descriptions of the requirements of Ind AS 115.

However, some of the entity’s revenue recognition accounting policies relate to an area for which the entity has made significant judgements in applying its accounting policies—for example, in deciding how to allocate the transaction price to the performance obligations, and the timing of revenue recognition.

The entity considers that in addition to disclosing the information required by paragraphs 123–126 of Ind AS 115 about the significant judgements made in applying Ind AS 115, primary users of its financial statements are likely to need to understand related accounting policy information. Consequently, the entity concludes that such accounting policy information could reasonably be expected to influence the decisions of the primary users of its financial statements. For example, understanding:

(a) how the entity allocates the transaction price to its performance obligations is likely to help users understand how each component of the transaction contributes to the entity’s revenue and cash flows; and

(b) that some revenue is recognised at a point in time, and some is recognised over time is likely to help users understand how reported cash flows relate to revenue.

The entity also notes that the judgements it made are specific to the entity. Consequently, material accounting policy information would include information about how the entity has applied the requirements of Ind AS 115 to its specific circumstances.

The entity, therefore, assesses that accounting policy information about revenue recognition is material and should be disclosed. Such disclosure would include information about how the entity allocates the transaction price to its performance obligations and when the entity recognises revenue.

Example B—making materiality judgements on accounting policy information that only duplicates requirements in the IFRS Standards

Background

Property, plant and equipment are material to an entity’s financial statements.

The entity has no intangible assets or goodwill and has not recognised an impairment loss on its property, plant or equipment in either the current or comparative reporting periods.

In previous reporting periods, the entity disclosed accounting policy information relating to the impairment of non-current assets which duplicates the requirements of Ind AS 36 Impairment of Assets and provides no entity-specific information. The entity disclosed that:

“The carrying amounts of the group’s intangible assets and its property, plant and equipment are reviewed at each reporting date to determine whether there is any indication of impairment. If any such indication exists, the asset’s recoverable amount is estimated. For goodwill and intangibles with an indefinite useful life, the recoverable amount is estimated at least annually.

An impairment loss is recognised in the statement of profit or loss whenever the carrying amount of an asset or its cash-generating unit exceeds its recoverable amount.

The recoverable amount of assets is the greater of their fair value less costs to sell and their value in use. In measuring value in use, estimated future cash flows are discounted to present value using a pre-tax discount rate that reflects current market assessments of the time value of money and the risks specific to the asset. For an asset that does not generate largely independent cash inflows, the recoverable amount is determined for the cash-generating unit to which the asset belongs.

Impairment losses recognised in respect of cash-generating units are allocated first to reduce the carrying amount of any goodwill allocated to that cash-generating unit and then to reduce the carrying amount of the other assets in the unit on a pro-rata basis.

An impairment loss in respect of goodwill is not subsequently reversed. For other assets, an impairment loss is reversed if there has been a change in the estimates used to determine the recoverable amount, but only to the extent that the new carrying amount does not exceed the carrying amount that would have been determined, net of depreciation and amortisation, if no impairment loss had been recognised.”

Application

Having identified assets subject to impairment testing as being material to the financial statements, the entity assesses whether the accounting policy information for impairment is, in fact, material.

As part of its assessment, the entity considers that an impairment or a reversal of an impairment had not occurred in the current or comparative reporting periods. Consequently, accounting policy information about how the entity recognises and allocates impairment losses is unlikely to be material to its primary users. Similarly, because the entity has no intangible assets or goodwill, information about its accounting policy for impairments of intangible assets and goodwill is unlikely to provide its primary users with material information.

However, the entity’s impairment accounting policy relates to an area for which the entity is required to make significant judgements or assumptions, as described in paragraphs 122 and 125 of Ind AS1. Given the entity’s specific circumstances, it concludes that information about its significant judgements and assumptions related to its impairment assessments could reasonably be expected to influence the decisions of the primary users of the entity’s financial statements. The entity notes that its disclosures about significant judgements and assumptions already include information about the significant judgements and assumptions used in its impairment assessments.

The entity decides that the primary users of its financial statements would be unlikely to need to understand the recognition and measurement requirements of Ind AS36 to understand related information in the financial statements.

Consequently, the entity concludes that disclosing a summary of the requirements in Ind AS36 in a separate accounting policy for impairment would not provide information that could reasonably be expected to influence decisions made by the primary users of its financial statements. Instead, the entity discloses material accounting policy information related to the significant judgements and assumptions the entity has applied in its impairment assessments elsewhere in the financial statements.

Although the entity assesses some accounting policy information for impairments of assets as immaterial, the entity still assesses whether other disclosure requirements of Ind AS 36 provide material information that should be disclosed.

Example C — Disclosures of the accounting policies on revenue recognition

Background information

V-Trade is an AC retailer. As per local law, V-Trade is required to repair any damages to the AC up until 12 months after delivery, to the extent that the damage relates to defects existing at the delivery date (“assurance warranty”). Each AC sold also includes an obligation for V-Trade to perform specific services beyond the mandatory warranty requirements for a period of three years (extended warranty).

V-Trade does not sell extended warranties separately, but the sales contracts for the ACs explicitly identify which services are included. V-Trade’s competitors do not bundle such service plans into their sale of cars by default but offer similar extended warranty as an option for an extra price. V-Trade concludes that the extended warranty meets the Ind AS 115 definition of a service-type warranty.

Customers are charged the total contract price upon delivery of the AC, which includes the extended warranty. V-Trade recognises revenue when, or as, it satisfies its performance obligations. It has identified two performance obligations in the contracts: (1) the AC and (2) the extended warranty. Consequently, V-Trade allocates the transaction price to each performance obligation and recognises revenue, separately, as it satisfies each performance obligation.

V-Trade determines that its performance obligation for an AC is satisfied at the point in time when the AC is delivered to the customer (and at the same time recognises an obligation for the mandatory warranty). The performance obligation for the extended warranty is satisfied over the three-year service period. At year-end 31 March 20×1, V-Trade concluded that revenues from both AC sales and extended warranty are material in its financial statements.

Question

V-Trade is preparing its financial statements for the year ending 31 March 20X1. Should accounting policy information on revenue recognition be disclosed?

Answer

V-Trade observes that:

  • the accounting policies were unchanged during the year;
  • the accounting policies applied are not chosen from an available set of alternatives;
  • accounting policies for revenue recognition are described in Ind AS, and not derived by V-Trade from paragraphs 10–12 of Ind AS 8; and
  • the accounting policies are not very complex.

However, V-Trade observes that the revenue amounts are material to the financial statements and that judgment has been used in applying the accounting policies, for example in:

  • identification of performance obligations, in particular concluding that its extended warranty service is distinct from the sale of the AC even though they are not sold separately;
  • determining if any significant financing component exists in the prepaid warranty plan;
  • allocating the contract price to the performance obligations; and
  • determination of when the performance obligation for the extended warranty (service-type warranty) is satisfied.

Consequently, to sufficiently understand the amounts presented, primary users of V-Trade’s financial statements might need information about how the accounting policies for revenue recognition have been applied by V-Trade.

Hence, entity-specific information about accounting policies for revenue recognition would likely be disclosed, in addition to the disclosures of significant judgements made in the application of paragraphs 123–125 of Ind AS 115
and other relevant disclosure requirements in Ind AS 115.

Measurement of operating segment profit or loss, assets and liabilities

The accounting policy information about policies of the operating segments is the same as those described as part of the significant accounting policy information, except that pension expense for each operating segment is recognised and measured on the basis of cash payments to the pension plan. Diversified Company evaluates performance on the basis of profit or loss from operations before tax expense not including non-recurring gains and losses and foreign exchange gains and losses.

Transition and comparative information

The amendments affect the disclosure of narrative and descriptive information. Comparative information is only required for narrative and descriptive information if it is ‘relevant to understanding the current period’s financial statements’ (paragraph 38 of Ind AS 1). Providing comparative accounting policy information would be unnecessary in most circumstances because
if the accounting policy:

(a) is unchanged from the comparative periods, the disclosure of the current period’s accounting policy is likely to provide users with all the accounting policy information that is relevant to an understanding of the current period’s financial statements; or

(b) has changed from the comparative periods, the disclosures required by paragraphs 28–29 of Ind AS 8 are likely to provide any information about the comparative period’s accounting policies that relevant to an understanding of the current period’s financial statements.

Dematerialisation of the Securities of Private Company

INTRODUCTION

Dematerialisation (Demat) of securities has gained its importance for a very long time. The Government has, from time to time, widened the scope and applicability of the same from listed companies to closely held public companies and now private limited companies.

As per the Companies Act, 2013, it is mandatory for all listed companies to have their shares and other securities1 in demat form for their smooth trading on Stock exchanges. The Ministry of Corporate Affairs (MCA), vide notification dated 10th September, 2018, inserted Rule 9A in the Companies (Prospectus and Allotment of Securities) Rules, 2014 (‘PAS Rules’), mandating every unlisted public company to hold and issue securities only in demat form.


1.“Securities” shall include all kinds of securities – shares, debentures, preference shares etc.

Recently, the Ministry of Corporate Affairs (MCA) vide notification No. GSR 802 (E) dated 27th October, 2023, has introduced Rule 9B after Rule 9A vide — Companies (Prospectus & Allotment of Securities) Second Amendment Rules, 2023 (‘Present Amendment’), and has extended such requirements for private companies.

Compliances under the new notification for the dematerialisation of the Securities shall have twofold compliances to be observed: One by Companies and the other by the security holders of such companies, making this a very important provision to be understood by the private limited corporate entities as well as security holders.

UNDERSTANDING THE COMPLIANCES TO BE FOLLOWED BY THE COMPANIES:

Every private company that is not a small company as per the audited financial statements as on the last day of the financial year ending on or after 31st March 2023, shall, within 18 months from the closure of such financial year, ensure that it:

  • issues the securities in dematerialised form only;
  • facilitates the dematerialisation of its securities;

in accordance with the provisions of the Depository Act, 1996 (22 of 1996) and regulations made thereunder.

and

  • dematerialises the entire holding of securities of its promoters, directors and key managerial personnel before making any offer for the issue of any securities, buyback of securities, issue of bonus shares or rights offer after the above-ascribed timelines.

With this Notification, all private Companies which are not small companies as of the last date of the financial year end on or after 31st March, 2023 are under a mandatory requirement of dematerialising their securities.

The applicability test begins with deciding the status of the company, whether a company being a private company is a small company or not. As per the revised definition of the “small company” (as per the amended Rule under the Companies (Specification of Definition Details) Amendment Rules, 2022, effective from 15th September, 2022), a small company is such a company,

a. Whose paid-up capital does not exceed ₹4 crore and

b. Whose turnover [as per profit and loss account for the immediately preceding financial year (for this Rule, it is 31st March, 2022] does not exceed ₹40 crores.

c. There are other categories of companies which are exempted from the definition of the small company, i.e., they are not considered as a small company irrespective of their paid-up capital and turnover.;

i) a holding company or a subsidiary company;

ii) a company registered under section 8; or

iii) a company or a body corporate governed by any special Act;

Let us understand these criteria with the help of the following examples:

Paid-up capital and Turnover as of the last date of the financial year ending on (Paid capital R4 core or more and Turnover above R40 crore or more) Demat applicability (mandatory)
31st March, 2022 31st March, 2022 31st March, 2022 Effective date (18 months from the date of such financial year end when the private Company cease to be a small company.
Company A -Less than the limit prescribed -small company. -Less than the limit prescribed –small company. -Less than the limit prescribed –small company. Not applicable.
Company B -More than the limit prescribed –Not a small company. -Less than the limit prescribed – small company. -Less than the limit prescribed –small company. To demat before 30th September, 2024.
Company C More than the limit prescribed – not a small company. More than the limit prescribed – not a small company. Less than the limit prescribed –small company. To demat before 30th September, 2024.
Company D Less than the limit prescribed –small company. More than the limit prescribed –Not a small company. Less than the limit prescribed –small company. To demat before 30th September, 2025.
Company E Less than the limit prescribed –small company. Less than the limit prescribed –small company. More than the limit prescribed –not a small company. To demat before 30th September, 2026. (Company E shall cease to be a small company as of 31st March, 2025)
A Holding Company, A Subsidiary Company, a Section 8 Company (except a company limited by guarantee), a company or body corporate governed by any special Act; Not a small company by definition, irrespective of paid-up capital and turnover Not a small company by definition, irrespective of paid-up capital and turnover Not a small company by definition, irrespective of paid-up capital and turnover To demat before 30th September, 2024.
a Government Company. Not a small company by definition, irrespective of paid-up capital and turnover Not a small company by definition, irrespective of paid-up capital and turnover Not a small company by definition, irrespective of paid-up capital and turnover Not applicable, as the Government company is not covered


CONCERNS FOR PRIVATE LIMITED COMPANIES

Correctly identifying the promoters and Key Managerial Personnel (KMP)

To observe the proper implementation of the rules, the Government has also mandated events relating to share capital like right issues, bonus issues, private placement, etc., which can be exercised by the Company only and only if the securities held by the promoters, directors and KMP of the Company are dematerialised before making any such offer for the issue of any securities.

This means that the persons who are promotors, directors and KMP as of 31st March, 2023 and thereafter must have their respective securities in demat form.

This could be a challenging exercise as the private companies are not under a mandatory requirement of appointing KMP under Section 203 of the Companies Act, 2013, except for the appointment of a Company Secretary on exceeding the threshold limit of paid-up capital of ₹10 Crores or more. Hence, such Companies shall exercise due care in identifying the promoters and KMP as per the Companies Act, 2013 and rules made thereunder before making any further issue of the securities.

Transfer of securities

Private companies, by their Articles, restrict/control the transfer of securities, with the Board having the power to approve or deny the said transfer in the best interest of the Company.

It was possible to adhere to these provisions of the Articles of Association where the shares are in
physical form. Now, with the dematerialisation of securities, the shares become freely tradable, and the Depository Act, of 1996, do not restrict any such transfer. It may lead to a dangerous situation for Private Limited Companies and may result in hostile takeovers. In addition to that, these provisions may result in transfer-related issues wherein the Articles relating to the transfer of shares, especially the clause related to the “Right of First Refusal”, may need to be amended or redrafted in accordance with the said amendment.

One solution to the above problem could be to use the facility of freezing one’s account with the Registrar and Transfer Agents (RTA). RTA provides ‘freeze–unfreeze’ options to the companies, wherein the debit of securities is frozen by the RTA under the company’s mandate and shall only unfreeze for a day or more as per the company’s instructions in writing. The companies will have to check for the cost involved in the same for the arrangement with RTA.

Non-Applicability of Rules

As per Rule 9B sub-rule 6 of the Companies (Prospectus and Allotment of Securities) Second Amendment Rules, 2023, the provisions of these rules are not applicable to Government Companies.

In conclusion, a company which is not a small company as defined above and which meets the criteria mentioned in the table above, needs to demat its securities by 30th September, 2024 or any other date, as may be applicable.

Procedure for Dematerialisation of Securities

To comply with the abovementioned provisions of the Companies Act, 2013 and the Rules made thereunder, a company should take the following steps:

a. Appoint RTA for Dematerlising its securities

b. Register itself with Depository (NSDL/CSDL). (India has two registered depositories, National Securities Depository Limited (NSDL) and Central Depository Services (India) Limited (CDSL).)

c. Obtain ISIN (International Security Identification Number) for all existing securities issued by the Company;

d. Facilitate dematerialisation of all existing securities (as and when a request is received from the holder of such securities);

e. Ensure that the entire holding of its promoters, directors and KMP are held in dematerialised form only prior to making any offer for issuance or buyback of securities on or after 30th September, 2024, or any other applicable relevant date.

f. Issue all securities in dematerialised form only after the due date;

Compliances by a Security Holder

Each holder of the securities of a private company that satisfies the abovementioned conditions shall mandatorily dematerialise the securities before

  • initiating the transfer of such securities

and

  • subscribing to any private placement offer, bonus shares or rights offer of such private company.

Process to be followed by a Security Holder

1. A Security holder needs to have a PAN or obtain a PAN number (This is also mandatory for foreign security holders)

2. Depository: India has two registered depositories, National Securities Depository Limited (NSDL) and Central Depository Services (India) Limited (CDSL).

3. Depository Participant (DP): The Investors (security holders) have to interact with the Depository through DPs, which are entities like public financial institutions, stock brokers, banks, clearing corporations/clearing houses, etc. The investor can choose a DP and either of the depositories to have their shares into a demat account.

4. Open a demat account with Indian Depository Participants (List of SEBI registered participants can be accessed through the NSDL and CDSL site.) and undertake the process of demat by filing a demat request form. If the investor already has a demat account then, he need not open a separate account.

5. Deposit the share certificates along with the DRF (Dematerialised Request Form) and all other documents and forms as required by the Depository Participants (DP).

6. The DP shall take up the further process and on cross-checking the correctness of all documents with the RTA, shall register the dematerialisation of shares.

Key points to be noted by the Security Holders

– Security holder can dematerialise only those security certificates that are already registered in the security holder’s name in the records of the issuing company/its RTA. i.e., he shall be a registered owner.

– The shares must be free from any lien, charge or encumbrance.

– In a case, where the security certificates are in joint names, the demat account shall also be opened in the same order of names.

– The new Rules do not mandate the security holders to have the securities in demat; they can continue to have the securities in physical form. However, after the due date, they will not be able to transfer the securities unless they are demated. Similarly, they will not be able to subscribe to new securities unless they have a demat account.

Private limited companies which are under the ambit of provisions under Rule 9B of Companies (Prospectus & Allotment of Securities) Second Amendment Rules, 2023, shall note the following:

– After 30th September, 2024, the securities which are in physical form will not allowed to be transferred unless they are dematerialised. (The securities can be transferred before 30th September, 2024).

– The security holders will not be able to subscribe to any private placement offer, bonus shares or rights offer of such private company unless the securities are demated.

– The Companies will mandatorily be required to issue and approve the transfer of the securities from the said date, on or after 30th September, 2024 (or the relevant date).

– A security holder, unless a promoter, director or KMP, may continue to hold shares in physical form even after 30th September, 2024. However, the said securities will not be permitted to transfer until dematerialised.

– Further, the security holder will be able to subscribe to any further issue only after ensuring the dematerialising of the securities. Also, the security holder will have to ensure that he has a demat account.

– The private companies are required to ensure compliances applicable to unlisted public companies under sub-rule (4) to (10) of Rule 9A (RULE 9A: (applies mutatis mutandis to private companies) with respect to payment of timely fees to depository and RTA agent, maintaining the security deposit at all times, adhering to SEBI and Depository guidelines to the extent applicable, grievances to be addressed to Investor Education and Protection Fund Authorities etc.

– Private companies will be required to file Form PAS-6 to the ROC within sixty days from the conclusion of each half-year. Therefore, for the half-year period from April to September, the due date to file Form PAS-6 will be 29th November, and for the period from October to March, the due date will be 30th May every year.

Advantages of Demating Securities

Although there could be teething troubles in following procedural and technical aspects to dematerialise the securities, the demat of securities is a very beneficial and welcome step taken by the Government for the private companies as well as the shareholders. There are certain benefits which are enumerated as under;

1. There is a well-defined electronic system which is well regulated by laws (under SEBI -Securities and Exchange Board of India) for keeping the securities in the demat form.

2. As there are no physical securities, it is safe to hold the securities of a company. There is no fear of loss, deface, mutilation or stealing.

3. Convenient — can be easily transferred electronically from one person to another.

4. Instant transfer of securities on authorisation, No stamp duty on transfer of securities.

5. There is no risk of bad delivery of shares — fake share certificates, delays, bad delivery, missing certificates, etc., Minimal paperwork.

6. Reduction in transaction costs and legal costs for the security holders. However, there is a possibility of an increase in cost due to annual maintenance charges of the demat account by RTA.

7. As there is no security certificate, even one share can be transferred without long paperwork and hassles.

8. All information of the security holder is easily maintained and stored electronically and can be easily amended and changed as required.

9. Automatic credit to account on stock split, bonus, right issues etc.,

10. A single demat account of an investor can hold multiple securities.

11. Better transparency of securities.

12. The security holder can have easy access to his security holding status.

CONCLUSION

The complete essence of the said provisions can only be achieved if it is followed and complied with by the company and its shareholders in their true spirit.

All in all, it is a good move towards disciplining private limited companies and removing manipulations in the case of physical securities. It will also enable investors to find all their holdings in one place and it will help successors to lodge claims and transfer securities in their names.

Chatting Up About India: When a $10 Trillion Economy Won’t Make a Difference

“India assimilated the worst stupidities of the democratic system.” – Charlie Munger

It is August, the month of our Independence Day — a time to look at the state of the nation, or for me, its different facets. One of the ways to look at things — to develop a perspective on things — is by questioning all the information we have and challenging the axioms we are programmed with. Looking at the stage we are in as a country, I wonder whether the time has come to MODIFY the phrase “ask not what your country can do for you, ask what you can do for your country”, especially in the context of taxpayers and honest citizens. For one, those words by JFK seem like a “perpetual one-sided idea” and therefore, not sustainable. It could be used as an excuse by politicians when their performance falls short compared to expectation and responsibility. I feel as taxpayers, we need to ask: “We do what we should do for our country, but is my country doing what it is expected to do for me and everyone else?”

Most of us seem happy to see many wonderful things around us as India marches towards its aims. At the same time, we are also concerned about much of what is happening around us. Thinking more deeply, I have come to conclude that the problems can be articulated and classified under these causal categories:

I. India against Indians II. Indians against India
III. India against India IV. Indians against Indians

These categories mean we take responsibility for the condition we are in. I thought most of our problems as a nation and its people could fit into these baskets. Here is a brief description of what these four baskets are:

I. The State and Nation are against the individual or collective of citizens. For example, there is lack of accountability in the state administration.

II. Individual or collective citizens against the Nation / State. For example, people spitting and dirtying public spaces with complete disregard.

III. The State and Nation are against the cultural, social and heritage of its people. Here, the administration goes against the ethos and values of the civilisation and culture. For example, the government mismanaging civilisation heritage that is priceless or the state treating citizens consistently unequally via reservation.

IV. Individuals and part of collective citizenry against other individuals or collective citizenry. For example, rampant and pervasive double-sided driving, even in Mumbai, where citizens don’t care about fellow citizens on the road.

The government/s, and for that matter, government as an institution, like to exhibit their achievements and hide their shortcomings, failures and disasters. One can consider this at a human level to be part of one’s nature; but at an institutional level, it is dishonesty. India goes a step further when it deifies or exalts its leader/s in a disproportionately larger way and tries to show that there is one person/leader responsible for all good and all credit is due to that leader alone, but all the wrongs have no connection with the leader/s at all.

EDUCATION: THE PATH TO A BRIGHTER FUTURE

In this article, I wish to cover a critical aspect that will pave the way to a great future — Education. We don’t hear much about education in the news; definitely not as much as we hear about Vande Bharat trains, bridges and houses being built, etc. Culture and Education are fundamental building blocks of a nation. By culture, we mean integrity, ethics and value systems displayed in individual and collective behaviour. Education is perhaps a more empirical aspect, which means developing and cultivating skills and capabilities to make the country and individual lives better. Culture and Education have a link as they both feed each other.

Today, what we see clearly shows that education is lacking and lagging: Lacking, in elements and focus, and lagging momentum in transformation and impact. These are visible for all to see; one doesn’t have to be a statistician or keen observer.

The Problem: More or Better?

The Government controls education; largely, the states take care of elementary education and many other bodies. The approach has been: Let’s give more public money, and things will sort itself out. More money, more schools, more teachers and more students. Bigger, better, faster. There isn’t much data about the effect of such spending, and the Government as an institution stands for spending without rigorous accountability. India gives about 3 per cent to education in budgets as against the target of 6 per cent of GDP (National Education Policy 2020 and 1964–66 Education Commission recommendation). In so many decades, this target has never been met. Brazil and South Africa allocate above 6 per cent to education. The benefits from a social perspective are even more. As Pythagoras stated 2,000 years back, “Educate the children and it won’t be necessary to punish the men.”

Output and Outcome

India focuses on Output; for e.g., number of people enrolled in schools. But it doesn’t focus as much or even adequately on Outcomes: are students able to have a grip on language and arithmetic that is expected at a certain age? Even today, the poorest people send their children to private schools no matter how badly situated they are. Despite higher fees charged by private schools, government schools are not preferred1. We have recently seen UP teachers protesting for being asked to come on time.


1. James Tooley’s research calls this grassroots privatisation. These schools, even if run by unqualified teachers, outperformed state-run schools. His book The Beautiful Tree is well acclaimed.

Private schools are better in terms of outcomes. The government doesn’t provide or collect much data about Per-Pupil Expenses. We all know that even legislators, at all levels, have their children enrol in private schools rather than public schools. Some experts suggest that the government would perhaps be better off transferring money directly to individual students to join any school they want on the lines of Direct Benefit Transfer (DBT). What is happening currently is on the lines of PDS. We need to fund schooling and not schools. Let students and parents decide where their child should study. It is a matter of concern and even shock that after 75 years, we are struggling with aspects as important as education; despite taking cess from taxpayers, its outcome seems questionable and certainly, below optimal.

ASER2 Surveys3 – These surveys are carried out in 28 districts in 26 states, reaching 34,745 youth in the 14–18-years-old category in 30,374 households in 1664 villages. 25 per cent of students in Class V cannot read Class II texts in their own language fluently. The 2023 report found that among 14–18-year-olds, 1 out of 4 could not read Class II texts. More than 50 per cent could not do the basic division of dividing 3 digits by 1 digit. However, there are many positive findings, too, and trends of improvement.


2. Annual Status of Education Survey
3. https://asercentre.org/wp-content/uploads/2022/12/ASER-2023_Main-findings-1.pdf

OECD PISA – Runs a random sample of 15-year-olds on fluid general intelligence. India doesn’t like it much. Once it carried this OECD PISA measurement in two states. India is no longer participating in this global survey.

Qualitative Aspects

Much of the nature of education was and is meant for developing babus and industrial workers to run the industrial administrative machine. It means learning that is rote, not based on problem-solving, not broad enough, too many irrelevant things for too long, not focussed on common flow intelligence and so on. This is a whole area in itself and therefore, let’s leave it at that. Many schools pass students all the way to Class X. While this has some good effects, there are side effects too that people who come out are not capable enough to do basic language, arithmetic, science, general intelligence and critical thinking. There is also caste-based education where students are asked for caste certificates in cities like Mumbai for admission. This not only reinforces divisive aspects of lower identity (instead of national identity or being a student) in students but also slows things down.

Social Problems

Now, India has this failed theme called socialism, where the private sector is abhorred. Look at the airlines — we bought tickets from Indian Airlines, which cost ₹16,000 to Delhi 20–30 years ago, when very few took flights to Delhi on two Sarkari airlines. We didn’t have landlines except without waiting. Education remains in control of the Sarkar. Higher education, like Engineering colleges and medical colleges, charge a lot of fees out of reach for most middle-income families and are controlled by politicians. Its root can perhaps be summarised in what Nehruji said to J R D Tata: “Never talk to me about the word profit; it is a dirty word.”

But it is possible, as see in the cases of hospitals like Narayan Hrudayalay, Indian pharma companies like Cipla developing the cheapest medicines in the world, etc. Yet, they all need to make profits whether for taking on that venture or for ploughing back for expansion. India continues to control everything instead of letting markets play out through competition like it has happened in airlines or retail, or license raj regime and so on.

Reservations

An issue that segregates people to give birth-based benefits has over-lived its life since envisaged reservations were first considered. They were to end in 10 years, which was way back in the ’60s. Benefits should be based on need – a poor person needs something; he cannot obtain it and therefore must be provided for. How is a need attached to anything but lack? India attaches need based on caste or religion or some such lower identity. This is insane, to use a decent word. Charlie Munger, when asked about India, said that India “assimilated the worst stupidities of the democratic system”. Look at the recent case of the IAS trainee who faked her certificates4. For medical, there is about 74 per cent reservation in Maharashtra, not only in UG but in PG levels too. How far can reservation continue? Despite SC’s decision to cap, state governments can’t just stop raising it above the 50 per cent limit. What it does is make Indians vie to obtain a lower identity to obtain reservation benefits. It is forcing more and more people to call themselves “deprived” and “destitute” in identity! I wonder whether such a thing would be happening anywhere else. Bangladesh recently had riots, causing the newly announced reservations of just over 50 per cent to be struck down.


4. Pooja Khedkar news reports

This monster doesn’t stop at education. It continues at the job level too. We have become a country where so many people dream of leaving India or are pushed out as they cannot find a job on merit. Yet, most think this pattern is akin to living the key word in the he preamble of the constitution: Equality.

Skills Crisis

We have people with degrees who cannot find jobs. There is unemployment, and there is un-employability. On one side, we have too many people with degrees looking for jobs; and on the other side, we have too many jobs that cannot find people with the requisite skills. We see peon jobs being applied for by unemployed PhDs. But that’s just the tip of the iceberg. So often, we see lacs of people apply for a few thousand vacancies. Adani was in the news due to a request to allow the Chinese to come here as they couldn’t find suitable staff for their projects. The same is true for TCS and L&T, as reported in recent news.

The 2024 Economic Survey says 50 per cent of Indian graduates are not employable and 65 per cent of people under the age of 35 have no skills5. This is not good news; although the trend is reported to be improving. We need to have education that leads to capabilities and then to employability. With things becoming less menial, this problem will be accentuated. The recent budget of July 2024, after 10 years, seems to have realised that skills are important and higher education will make a difference. Countries like Germany have a scheme where college students start at a real-life place to obtain skills. Indian UG medical students take classes for three years before being exposed to real-life medical situations or hospitals. Nurse colleges are today not linked to hospitals like medical schools as per Dr Devi Shetty6. This situation is made worse by absolutely ridiculous policies. Today, as per Dr Shetty, known as the “Henry Ford of heart surgery”, he cannot teach in a medical college as the system doesn’t allow him despite him being one of the top surgeons in India. This is how India defeats Indians.


5. Para 5.14, Page 158
6. https://youtu.be/v_jj3198IuE?si=nrlAgbe6VB2hhqq9 – recent interview with Smita Prakash

The UP school teachers’ protest for being asked to come on time shows the discipline level the teachers demonstrate. Most Sarkari jobs mean – once you are permanent, then people chill or rather become less effective. Job is more important and not outcome that the job is meant to deliver. They are entitled but not accountable. This is why, there is a big rush for Sarkari job openings. Of course, nothing can be generalised, but, certainly much of this is not an aberration.

What to do?

Well, it’s written on the wall but not on Sarkari walls. We need to fund schooling and not necessarily schools. The government tries to get into everything. Just as roads are built on PPP, “we” need to do this more and involve the private sector. In Sweden, government-funded vouchers can be used to go to any school. Give money to parents. Education vouchers (Milton Friedman’s idea) are needed and not necessarily government schools. This is the only way to beat reservation. It’s unfair to say, “If you come to a government school, I have money to spend on you, if you attend a private school, I have nothing to give you”. At many locations, in the experience of those who work in the sector around Umbergaon, Gujarat, the teachers are empowered and a healthy competition is developed by encouraging teachers to bring students up.

Because the government wants to provide benefits with so many conditions, it cannot control how this funding is done. Today, the data is there from Aadhaar and other means, and with technology government knows who needs what. DBT database is available. Education vouchers can easily be given if Mobile – Aadhaar – Schools are linked. Recently like India Stack, we saw Agriculture Stack. We perhaps now need an Education Stack also. Private entities can monitor public schools instead of the Sarkari system. Most people in OECD countries attend public schools. Why does this not happen in India? Why can’t public school teachers not be sent to private schools for some time or vice versa? Can private schools adopt a class or a subject in public schools? There is obviously political control and obstruction. We need more ideas to remove the lack and faster execution to remove the lag.

CONCLUSION

Add all the issues: paper leaks, low-quality public infrastructure, low quality of teachers in government schools, people running away to other countries for jobs after education if they can, so many seeking certificates of being deprived or of certain identity for benefits, government control, huge competition from age two to get admission, shortage of nutrition and the rest, and the resulting answer is that India is far away from its ideal and off track all over the place.

The point is if this area of education is not fixed, then a $5 trillion economy won’t matter. Considering the $2,800 per capita GDP of India and the mindset of leadership and people, the situation is grim. After massive reservations, along with frauds built into that system, without fixing education on a war footing, even the $10 trillion economy won’t make the desired difference. To me, for the economy to be a $5 or $10 trillion economy, education would have to be made into an engine and not a side ministry.

Previous Article on Chatting up about India: Technology not just for a few, but for all, BCAJ, September 2023.

Is Surplus in Profit and Loss Account a Free Reserve?

When I pose this question, the immediate answer is, “Any Doubt?” If we see the provisions of the Companies Act, 2013 (CA 2013) as well as the previous Act (CA 1956), one will note that the answer is not free from doubt.

CA 2013 contains several provisions where limits under the sections are calculated as per cent of Paid up Capital and Free Reserves such as section 68 (Buy Back of shares), section 73 (Acceptance of Deposits), section 180 (Borrowing Powers of the Board), section 186 (Loans and Investments by companies). If these calculations are incorrectly made by including an item wrongly in Free Reserves, it can involve a violation under CA 2013.

Let us, therefore, see some of the related provisions of the CA 1956/2013, and related rules and seek a reply to our query regarding surplus in the Profit and Loss Account.

I. PRESENTATION OF SURPLUS IN BALANCE SHEET

Let us have a look at the provisions of Schedule III Part I for the presentation of Reserves and Surplus.

Reserves and Surplus:

i) Reserves and Surplus shall be classified as: (a) Capital Reserves; (b) Capital Redemption Reserve; (c) Securities Premium; (d) Debenture Redemption Reserve; (e) Revaluation Reserve; (f) Share Options Outstanding Account; (g) Other Reserves — (specify the nature and purpose of each reserve and the amount in respect thereof);

(h) surplus, i.e., balance in Statement of profit and loss disclosing allocations and appropriations such as dividend, bonus shares and transfer to/from reserves etc. (Additions and deductions since last Balance Sheet to be shown under each of the specified heads) (ii) A reserve specifically represented by earmarked investments shall be termed as a ‘fund’. (iii) Debit balance of statement of profit and loss shall be shown as a negative figure under the head ‘Surplus’. Similarly, the balance of ‘Reserves and Surplus’, after adjusting the negative balance of surplus, if any, shall be shown under the head ‘Reserves and Surplus’ even if the resulting figure is negative.

We thus note that surplus is referred to as Balance in the Statement of profit and loss Account and stands on a different footing as compared to Reserves which are mentioned in (a) to (g) above.

II. FREE RESERVES UNDER COMPANIES ACT, 1956 (CA 1956)

CA 1956 did not have the definition of Free Reserves in the definition chapter. However, for the limited purpose of its section 372A, the term ‘Free Reserves’ was defined as under:

“372A. Explanation (b)— ‘Free reserves’ means those reserves which as per latest audited balance sheet of the company are free for distribution as dividend and shall include balance to the credit of the securities premium account but shall not include share application money.”

This definition is not exhaustive. The term ‘Free Reserves’ is also defined in other enactments and rules. Under rule 2(d) of the Companies (Acceptance of Deposits) Rules, 1975 (AODR 1975), it is defined as under:

‘Free reserves’ include the balance in the share premium account, capital and debenture redemption reserves and any other reserves shown or published in the balance sheet of the company and created by appropriation out of the profits of the company, but does not include the balance in any reserve created: (i) for repayment of any future liability or for depreciation in assets or for bad debts; (ii) by the revaluation of any assets of the company.”

It is interesting to note that Section 372A was introduced in the statute book by the Companies (Amendment) Act, 1999 w.e.f. 31st October, 1998. Therefore, till then, one needed to refer to the definition of Free Reserves for the limited purpose of AODR 1975. These rules dealt with the Acceptance of Deposits, and for the said purpose, limits were prescribed based on Paid Up Capital and Free Reserves. A clarification was sought from MCA regarding Free Reserves and MCA clarified as under:

Rule 2(d): Whether amount of surplus in the profit and loss account forms part of “free reserve” as defined in the rules?

After re examination of the matter in detail, it has since been decided that the amount of “surplus” shown in the profit and loss account carried forward under the heading “Reserve and Surplus” appearing in the balance sheet of company, may be treated as part of “free reserve”, as defined under the Rules, subject, of course, its satisfying condition that it arises by appropriation out of the profits of the company. [LETTER NO. 3/1/80 CL X, DATED 3rd, February, 1982.]

In fact, this clarification is also conditional, and one needs to look into the highlighted portions at the beginning, which indicates that this clarification is given on re-examination. (Does it mean that there was a contrary view before?) The closing condition that surplus arises out of appropriation of profits is further confusing. But be that as it may, this clarification is for a limited purpose of AODR 1975 and speaks very less and confuses more.

III. RESERVE AND SURPLUS AS DEFINED IN GUIDANCE NOTE* ON TERMS USED IN FINANCIAL STATEMENTS

Para 14.04 Reserve: The portion of earnings, receipts or other surplus of an enterprise (whether capital or revenue) appropriated by the management for a general or a specific purpose other than a provision for depreciation or diminution in the value of assets or for a known liability. The reserves are primarily of two types: capital reserves and revenue reserves.

Para 15.21 Surplus: Credit balance in the profit and loss statement after providing for proposed appropriations, e.g., dividend or reserves.

*Although this Guidance note is withdrawn later on.

Thus, we note that both the terms are not used interchangeably. In fact, one will have to keep in mind a basic premise of how the Reserve comes into existence. The reserve comes into existence with the appropriations from the Profit and loss Account (i.e., surplus), whereas a surplus is the Balance remaining after appropriations. Surplus is a balancing figure, unlike reserves. Thus, the Reserve is an end result arising from the source, which is a Surplus in the Profit and loss Account.

IV. DEFINITION OF FREE RESERVES UNDER CA 2013

As mentioned before, the term Free Reserves is now defined in the Definitions Chapter in the CA 2013. Section 2(43) of CA 2013 defines Free Reserves as:

Section 2(43) ― free reserves means such reserves which, as per the latest audited balance sheet of a company, are available for distribution as dividend:

Provided that — (i) any amount representing unrealised gains, notional gains or revaluation of assets, whether shown as a reserve or otherwise, or (ii) any change in carrying amount of an asset or of a liability recognised in equity, including surplus in profit and loss account on measurement of the asset or the liability at fair value, shall not be treated as free reserves;

If we paraphrase this definition, one notes following essential elements:

  • Definition is exhaustive.
  • Only Reserves are included (such reserves).
  • Such reserves are as per the latest audited balance sheet.
  • Such reserves are available for distribution as dividend.
  • Proviso carves out an exception as to few notional gains etc.

If we look at the essential elements of this definition, prima facie surplus in the profit and loss account does not satisfy the condition because it is not a reserve created from the profit and loss account. It represents a balance in the profit and loss account after appropriations. It satisfies a latter condition of being available for the distribution of dividends, but it is not a reserve.

At this stage, it will not be out of place to note the observation of Mumbai Tribunal in the matter of LIC Housing Finance limited vs. DCIT 2(2), Mumbai (180 ITD 45). The tribunal has observed as under in Para 2.4 of the order:

2.4 We have carefully considered the rival submissions and deliberated on cited decision of the Tribunal. As per the provision of Sec 36(1)(viii), certain specified assesses are eligible to claim deduction to the extent of 40% from profit derived from specified business upon creation of special reserve. As per the proviso, if the amount carried to such special reserve account, from time to time, exceeds twice the amount of the paid-up share capital and of the general reserves, no allowance under this clause shall be made in respect of such excess. The expression used in the proviso is the general reserves. The term general reserves have been used in plural sense and preceded by the words which would indicate that it carries special meaning and connotes general reserves only to the exclusion of other. In our considered opinion, the reserves are created as an appropriation out of Profit & Loss Account and the terms Profit & Loss Account & General reserves as mentioned in the proviso could not be equated with each other, in the manner, as suggested by Ld. AR by relying upon the letter* of Department of Company Affairs. The said circular, in our considered opinion, would have limited applicability in the context of which it has been issued and designed to apply in certain specific situation only. The expression used in the proviso are quite clear which mandates the inclusion of only the general reserves and nothing else. As per doctrine of literal interpretation, when the wordings in the statute are clear, the same has to be given the full effect. Therefore, we are unable to accept the arguments raised by Ld.AR, in this regard. Our view is duly supported by the cited decision of the Tribunal rendered on identical set of facts and circumstances. The coordinate bench has confirmed the stand of learned first appellate authority in excluding the balances in Share premium account, Profit & Loss Account and special Reserve account while computing the general reserves. Nothing on record would suggest any change in facts or as to how the said ruling is not applicable to the facts of the case.

* LETTER NO. 3/1/80 CL X, DATED 3rd February, 1982, is referred in Para 2.3 of the order which is referred in Part II of this article above.

We are reading this judgment only to note the observation that reserves are created out of the Profit and loss Account. In my view, reserves do not come into existence on their own but derive their existence from the source from which they are created.

V. PAYMENT OF DIVIDEND OUT OF RESERVES

As per the provisions of section 123 of CA 2013, dividends can be paid from the following sources:

  • 1(a) out of the profits of the company for that year arrived at after providing for depreciation in accordance with the provisions of sub-section (2), or out of the profits of the company for any previous financial year or years arrived at after providing for depreciation in accordance with the provisions of that sub-section and remaining undistributed, or out of both; or

The Second and third proviso to sub-section 1 of Section 123 reads as under:

  • Provided further that where, owing to inadequacy or absence of profits in any financial year, any company proposes to declare dividends out of the accumulated profits earned by it in previous years and transferred by the company to the reserves, such declaration of dividend shall not be made except in accordance with such rules as may be prescribed in this behalf:
  • Provided also that no dividend shall be declared or paid by a company from its reserves other than free reserves:

We thus note that dividends can be paid from current or past profits as well as from the reserves. However, when dividends are declared out of Free Reserves, The Companies (Declaration and Payment of Dividend) Rules, 2014 (DP Rules, 2014) apply. The crucial words in the second proviso are underlined. This indicates that if there is a balance in the profit and loss account, then provisions of DP Rules, 2014 do not apply since word and is used.

This view is supported by the clarification from ICSI in its Guidance Note on Dividends. The clarification reads as under:

This is to clarify that the declaration of Dividend out of profits for previous year which are disclosed under the head ‘Surplus’ in the Financial Statements will not tantamount to declaration of Dividend out of reserves and accordingly will not attract the statutory requirements relating to declaration of Dividend out of reserves.

So, this is another instance where the legislature itself has distinguished between Free “Reserves” and “Surplus in profit and loss account”.

An interesting proposition was introduced by a few large companies such as Nestle India, and HUL, who have reclassified Reserves and transferred a balance standing in the Reserves to the Profit and Loss account and after that distributed larger dividends.

If we take the case of HUL, the scheme of arrangement was approved by the shareholders and thereafter endorsed by NCLT.

What did HUL achieve in this case?

Rationale and Significant Benefits of the Scheme

The Board of Directors have clarified that “the Company has built up significant reserves from its retained profits by way of transfer to General Reserves. Although the excess reserves can be profitably utilised for overall growth strategy, however, the Board of Directors is of the view that even after considering the foreseeable investments required for such opportunities over the next few years, the funds represented by the General Reserves are in excess of the Company’s current and anticipated operational needs.”

The Board further clarified that the “Company has strong cash flow delivery and the accumulated General Reserves being more than what is needed to fund growth. Further, with a view to providing greater flexibility for the utilisation of such funds, the Company proposes to transfer the amount lying in the credit of General Reserves to the head of the Profit and Loss Account.

Pay-out of Surplus Funds to Members

Upon the Scheme becoming effective, the amount so credited shall be paid out to the Members of the Company, from time to time, by the Board of Directors, at its sole discretion, in such manner, quantum and at such time as the Board of Directors may decide.”

Since HUL desired to make pay-out to its shareholders by reclassifying 100 per cent General Reserves to Profit & Loss Account it was necessary to create a Scheme of Arrangement.

Why it was necessary to frame the Scheme of Arrangement

In terms of the provisions of Section 123 of the Companies Act, 2013, a company generally transfers a certain percentage of profits to the reserves before declaring any dividend during a financial year. Based on that, HUL has created its reserves by transferring profits from time to time.

Rule 3 of the Companies (Declaration and Payment of Dividend) Rules, 2014 provides that in the event of inadequacy or absence of profits in any year, a company may declare dividends out of free reserves provided, amongst others, that the total amount to be drawn from such accumulated profits shall not exceed one-tenth of the sum of its paid-up Share Capital and Free Reserves as appearing in the latest audited financial statement. It means that during any financial year dividends can be declared from Free Reserves only in case of inadequacy or absence of profits and only to the extent of 10 per cent of the paid-up capital and free reserves.

Since HUL desired to make a pay-out to its shareholders by reclassifying 100 per cent General Reserves to Profit & Loss Account and a combined reading of the above provisions puts restrictions for the same, it was necessary to create a scheme of Arrangement. Framing a Scheme of Arrangement was the only option for HUL to reclassify General Reserves to Profit & Loss Account.

All the above discussion will show that one needs to strike a correct balance while transferring profits to reserves. If you transfer more than the required, dividends cannot be freely distributed. If you leave more balance in the Profit and Loss Account, one can pay larger dividends, but such balance may not be treated as the free reserve for certain purposes. This also supports the view that a surplus in the Profit and Loss Account is not a reserve created.

VI. WHY THIS DISCUSSION ON FREE RESERVES IS IMPORTANT

We find several references in the Act to Free Reserves and a few of them are given hereunder:

Section What does it cover Remarks
2(43) Definition.
63 Issue of Bonus Shares. Out of Free Reserves permitted.
68 Power of the company to purchase its own securities. Power to buy back out of free reserves.
73 Prohibition on acceptance of deposits from the public. Limit is w.r.t. Paid up Capital and Free Reserves.
123 Declaration of dividend. Criteria for declaration of dividends out of Free Reserves.
180 Restrictions on powers of the Board. Borrowing up to aggregate of paid-up capital, Free Reserves, and securities premium account.
186 Loan and investment by the company. Criteria for loans and investments tied with Free Reserves being one of the components for determination.

Sections 2(43), 73 (Acceptance of Deposits) and 123 of CA 2013 are already discussed above. As regards sections 180 and 186 of CA 2013, they do not pose a threat because limits can be enhanced by resolution/s passed at AGM. This leaves us with the most popular section of the corporate world regarding Buy Back of Shares.

Section 68 prescribes various sources from which buy back can be made, namely Free Reserves / The Securities Premium / Proceeds of the issue. Sub-section 1 of Section 68 gives these sources as separate sources [sub-section 1(a) to (c)]. However, Explanation II to Section 68 provides that for the purposes of this section (section 68), “free reserves” includes securities premiums. The said explanation thus does not mention about the surplus in the profit and loss account being included in Free Reserves. It is therefore advisable to exercise caution in the matter of buy back, especially when one has a large component of profit and loss account under Reserves and Surplus.

Therefore, having discussed relevant provisions / rules as applicable, one cannot conclusively say that surplus in profit and loss account forms part of free reserves for all purposes. In fact, the discussion made above will lead to the conclusion that Free Reserves do not include a surplus in the profit and loss account. Wherever legislature wanted to clarify that surplus is to be included in Free Reserves, it has done so. However, if one does not come across such a clarification, a caution is advised.

VII. CONCLUDING REMARKS AND SUMMARY AND SUGGESTIONS

  • A surplus in the Profit and Loss Account is presented separately in Financials under Reserves and Surplus, and the Surplus denotes a balancing figure before appropriations.
  • Free Reserves were not defined under CA 1956 except for a limited purpose of section 372A of the CA 1956. In respect of AODR 1975, MCA specifically issued a clarification to state that Free Reserves included surplus in the Profit and Loss Account only for a limited purpose of rule 2(d) of AODR 1975.
  • Guidance Note on Terms used in Financial Statement also clarified that surplus in the Profit and Loss Account only represents a balancing figure and reserves come into existence only from appropriations.
  • The definition of Free Reserves under CA 2013 is exhaustive. Mumbai tribunal has succinctly brought out a difference between surplus in Profit and Loss Account and Reserves.
  • Payment of dividends out of Reserves Rules 1975 and DP Rules, 2014 both do not apply to the payment of dividends from surplus in the Profit and loss Account since surplus in the Profit and Loss Account is not a General Reserve.
  • Treating surplus in the Profit and Loss Account as part of Free Reserves may lead to unwanted complications with the regulators in the absence of clarity in the matter of interpretation.
  • If one is confronted with such a situation of huge surplus in the Profit and Loss Account, one may call for an AGM / EGM and explore the possibility of transfer to Reserves so as to serve one’s purpose. At least that is not restricted presently. This situation can be common these days since the transfer of Profits to Reserves is not mandated under any rules, even in the case of dividend-paying companies.

AI and the Future of Accounting

Applications of Artificial Intelligence (AI) have been around for over five decades. Even my doctoral dissertation some 27 years ago was about the use of AI in helping individuals make asset allocation decisions. My AI model assisted the user by evaluating the complexity of the task (e.g., the cognitive demands of collecting information, framing the problem and generating alternatives), the context (e.g. financial condition of the user and multiplicity of financial objectives) and the user’s background (e.g., the level of experience and expertise of the user in various asset classes). Current incarnations of which are the robo-advisors offered by many financial services companies.

However, the inflection point for AI really happened about a year and a half ago when OpenAI introduced ChatGPT. Since then, AI has proliferated into every aspect of our life. Just as mechanical automation and electric power created the Industrial Revolution and changed many jobs in the last century, this AI revolution is likely to change the nature of jobs in professional services. Accounting will not be spared.

On one side, the integration of AI into accounting services offers many opportunities for increasing the efficiency and effectiveness of services and bringing innovations. AI tools can undertake repetitive tasks with high productivity, so accountants can elevate themselves to strategic thinking and advisory roles, offer analytic intelligence and create differentiating value for clients. AI can also help accounting firms focus more on client service, including providing anytime financial data and customised reports and answer basic client questions through AI chatbots.

On the other side, AI poses a serious threat to traditional careers in accounting. AI is not expected to fully replace humans any time soon in highly diverse and fragmented accounting activities and processes. However, it is likely to replace human accountants in many laborious and routine subtasks that are conventionally performed by accountants in junior positions. This does not necessarily mean that young people will be out of jobs or traditional small accounting firms will disappear. Rather, it means that people and firms that are continuously learning and adapting to the evolving environment will thrive and grow by using AI technologies to their advantage.

AI AND ACCOUNTING

AI is not just one piece of software or an application; it rather consists of a number of varied tools and techniques. They include the identification and processing of repetitive tasks, automation of workflow and cognitive processes, data analytic tools for predictive and prescriptive analytics, neural network algorithms, fuzzy logic, genetic algorithms, expert systems, machine learning, natural language processing and generation, deep learning, large language models, computer vision, etc. Let us look at how these AI tools and techniques can affect various aspects of the professional side of accounting.

ACCOUNTING & BOOKKEEPING

Accountants and bookkeepers spend a lot of time on many repetitive tasks. AI can mimic actions performed by humans and perform these tasks quickly and accurately. Once trained for a specific use case, it can do invoice preparation and processing, transaction data entry, receivable and payable reconciliations, payroll processing, transaction characterisation and categorisation, bank reconciliation and generating reports. It can process large volumes of financial data quickly and liberate accountants to focus on more strategic activities. AI-enabled tools like Booke and UiPath can be integrated into your existing accounting software like Xero or QuickBooks Online to automate your tedious tasks.

AI algorithms can also review large volumes of data for error. They can cross-check information across different systems and reports, such as point-of-sales registers, expense reports, procurement systems and payment approval workflows. They can do this with very high precision compared to humans, minimising errors in financial records and improving the reliability of financial statements. They can help you identify inconsistencies in financial data, reduce human errors and improve the accuracy of financial statements and reports.

Al can also work continuously — day and night — on accounting and bookkeeping tasks at a very high speed. AI can also help manage the workflow involving humans by automating task assignments and tracking progress. This can significantly improve efficiency and reduce operational costs associated with these tasks.

Another benefit of AI is scalability. Every Chartered Accountant knows the crunch she faces at the time of a quarter / fiscal year-end. To help with the additional, and often unexpected, workload, they need to deploy additional temporary accountants and burn the midnight oil. AI-powered systems can help in such seasonal and fluctuating workloads as well as easily scale with the growth of your accounting services business. You can increase the volume of work without a corresponding increase in hiring human resources.

AUDITING & FINANCIAL REPORTING

Government agencies, such as the Comptroller and Auditor General of India (CAG), and professional associations, such as the Institute of Chartered Accountants of India (ICAI), issue standards and guidance for auditing attestation and quality control. Compliance with these standards and guidance is essential to ensure the authenticity of the audit and financial reporting. These rules are updated frequently. It is often difficult to percolate them to every accountant in every corner of the country. AI tools can easily integrate new rules into your systems and continuously monitor adherence to them in audit procedures. Simultaneously, they can also check for mathematical accuracy, saving time and reducing human error.

A key objective of auditing is to ensure the accuracy of and trust in financial statements. Auditors go through reams of data to spot unusual transactions and flag potentially fraudulent activities. AI tools can help you detect possible fraud by analysing financial data, determining historical patterns and identifying discrepancies in them. Advanced analytics deployed using AI can identify subtle indicators of fraud that might be missed by traditional auditing methods.

Traditional auditing methods involve sampling from a large pool of financial data. This is akin to finding a needle in a haystack. However, AI tools, under the parameters properly set by auditors, can analyse the entire pool of financial data rather than a sample of such data. Even when sampling is needed, AI can help improve sampling by more closely adhering to appropriate sampling methods and reducing human biases in sampling. This can help you focus your auditing efforts on the areas of high risk.

Continuous auditing is often touted to enhance risk management, improve financial reporting quality, increase auditing efficiency and timely detection of financial misconduct. AI tools integrated with automated reconciliation of accounts and transactions can enable continuous auditing without deploying a significant number of human resources. They can offer enhanced planning and efficient use of finite resources. AI can help journal entry testing very early through continuous audit, such that the initial risk assessment is performed immediately, especially for high-risk transactions. So you can identify issues as they arise rather than waiting for periodic audits.

Another tedious aspect of auditing and financial reporting is report generation. AI tools can help generate various types of financial reports automatically by extracting and summarising relevant data from various sources. They can also help provide narrative explanations for financial figures so stakeholders with limited financial expertise can also understand the reports. For internal use in the organisation, AI tools can also create customised reports relevant for various departments, functions and organisational levels. Additionally, you can maintain consistency in financial reporting by standardising report generation using AI tools.

FINANCIAL MANAGEMENT

Chartered Accountants work closely with CFOs of companies to help them in the financial management of companies. They help with cash flow management and reporting. Here, AI can play an important role. AI can determine cash flow patterns, help optimise working capital and improve accounts receivable and payable processes. It can further optimise cash flow by analysing payment terms, invoices and credit lines. It can also automatically categorise and track expenses, reducing errors and improving compliance. In addition, AI algorithms can assess credit risks associated with accounts receivable from customers more effectively than traditional methods — mathematical credit rating formula, as they are better able to incorporate the contextual information and changing economic conditions in creditworthiness assessments.

Another important aspect is forecasting the financial needs of the company in both the near term and long term. AI tools can collect and analyse historical data, market trends and exogenous factors to provide more accurate cash flow predictions. Well-trained AI can even predict future expenses to help companies manage their liquidity requirements. AI can analyse customer data to predict behaviour and preferences and, based on that, predict which customers are likely to pay late or default, allowing for proactive management of accounts receivable. AI can enable better inventory management by predicting demand under various conditions, such as seasonality, economic conditions, and market trends. So, AI can help improve working capital efficiency by optimising the balance between accounts receivable, inventory and accounts payable to improve working capital efficiency.

AI can help in the budgeting processes too. It can aid you in creating more accurate budgets based on historical patterns and need analysis. It can analyse spending patterns and suggest appropriate allocation of budget, potentially improving resource optimisation. It can also develop and analyse multiple financial scenarios and help you develop adaptive budgeting.

AI can assist in complex financially material events like M&A, valuation and revenue recognition. AI can process huge amounts of financial and market data to identify and evaluate potential acquisition targets. It can process multiple variables and scenarios to determine the appropriate level of valuation. AI can also provide real-time analysis of key performance indicators (KPIs), allowing for more timely data-driven decision-making.

TAXATION & TAX ADVISORY

As Benjamin Franklin said more than two centuries ago, there are only two certainties in life — death and taxes. Death is simple; it happens only once in a life, and one does not have to live with it. Taxes are complicated; they happen every day, and we have to live with them.

While AI cannot make taxes go away, it can certainly help reduce the complexity. AI tools can assist you in tax research by identifying relevant regulations across different jurisdictions and help you in optimising tax strategies. AI can keep track of changes in tax laws and regulations and alert you about new requirements and opportunities. It can extract relevant information from complicated tax documents and interpret and summarise them. This ensures compliance and enhances tax planning.

AI can also provide data-driven insights and individualise tax-efficient strategies by interpreting complex tax codes and regulations for individual situations. AI tools can analyse vast amounts of financial data from various sources, identify trends, determine anomalies and come up with potential tax optimisation opportunities. AI algorithms can develop and analyse various tax scenarios to recommend tailored tax strategies for individuals and companies. AI can forecast tax liabilities based on historical data and current financial course. This can assist you in creating much more accurate budgets and financial plans.

In the process of preparing documents for tax filings, AI can extract data from various sources, classify them and organise tax-related documents. This can significantly reduce the time and effort required for manual data entry. AI can quickly process vast amounts of financial data and detect unusual patterns that may indicate errors and anomalies that might be relevant for tax purposes. Identifying potential red flags in a timely manner and evaluating tax positions appropriately can help clients make informed decisions and reduce audit risks and penalties. AI-based co-pilots or assistants can instantaneously offer answers to tax-related queries as well as provide guidance on deductions, credits and other tax matters. Finally, AI tools can automate the preparation and submission of tax returns and compliance reports, ensuring they are accurate and submitted on time.

FINANCIAL ADVISORY

Many companies and high-net-worth individuals rely on chartered accountants for tax-efficient financial advice. AI can help CAs shift from reactive problem-solving to proactive advisory. AI tools, like Fathom and Jirav, can assist you in analysing historical and current financial data to identify trends and patterns that humans may miss. They use historical data to forecast financial trends, budgeting, and cash flow management, providing chartered accountants with actionable insights for financial advisory. They can help you offer predictive insights and strategic guidance to your clients that go beyond traditional accounting.

AI tools can tailor financial advice based on the specific financial situation of a business. They can analyse market data, competitor pricing, supply chain bottlenecks and customer behaviour to suggest optimal pricing and operational strategies. You can use these to help your client optimise financial performance and achieve better business planning.

AI algorithms can help make better financial decisions, specifically related to identifying investment opportunities. They can generate insights on financial performance and forecast future financial performance. They can provide real-time, deeper insights into a target company’s financial health by continuously monitoring transactions and identifying trends, anomalies and potential issues. This enables more informed decision-making for long-term financial needs related to special business activities.

REGULATORY COMPLIANCE

AI compliance tools can assist in understanding and interpreting complex regulatory documents and standards. They can help you keep up with the ever-changing regulatory environment without scouring the websites of relevant government or regulatory agencies. They can track changes in regulations and offer impact analysis. This helps in taking actions about updating compliance protocols in accounting systems and ensuring that reports comply with the latest rules and standards.

AI systems can also periodically and automatically generate compliance reports. This safeguards timely and accurate submissions to regulatory bodies. Also, automated compliance checks can reduce the risk of non-compliance and associated penalties.

RISK MANAGEMENT

Risk assessment and risk management are essential parts of doing business. Missing a predictable risk or overreacting to a small risk can have significant implications on financial and operational performance. AI algorithms and tools like ComplyAdvantage can identify patterns and anomalies in financial data that might indicate the risk of fraud or errors. AI can also assess the risk of financial misstatements, flaws in internal controls and liabilities in processes by analysing historical data and trends.

Once the risk factors are identified, AI tools can help assess the potential impact of the risk and what types of preventive measures you need to undertake. AI tools also provide valuable insights and help you prioritise mitigating actions.

AI tools can prepare multidimensional data visualisations to enable the identification of trends and outliers among key performance indicators. Once identified, you can deeply investigate them to assess the risk they pose. Interactive dashboards facilitated by AI tools allow you to drill down into data for deeper insights.

FORENSIC ACCOUNTING

Forensic accountants are regularly tasked with deciphering and reviewing countless complex financials in any given investigation. AI-powered risk intelligence tools like SymphanyAI, MindBridge and ThetaRay can help forensic accountants filter through vast volumes of data quickly, recognise patterns and detect abnormal transactions that might elude detection in a traditional investigative setting. Data classification techniques can furnish the foundation for forensic accounting to separate clusters of suspicious activities.

AI algorithms utilising natural language processing (NLP) can extract information from structured data sources, such as documents, contracts and invoices, as well as unstructured data sources, such as emails, social media chats and social media posts. They can review millions of lines of text at lightning speed, which would be practically impossible or cost-prohibitive for human reviewers. In addition, these tools can also conduct sentiment analysis on emotional aspects in texts and in identifying collusion among target individuals. All these can immensely help forensic accountants in determining fraudulent activities, their temporal sequence and associated culprits.

HOW DO I PREPARE MYSELF AND MY FIRM?

All these possibilities of using AI in accounting naturally raise the question: how do I prepare myself and my firm to take advantage of AI opportunities? Well, here are some quick suggestions:

  • Data analytics forms the basis for conducting any analysis with AI. Accountants with strong analytical skills will be able to use appropriate AI models to the given need and interpret AI-generated insights to make data-driven decisions. So, learn the basics of AI and data analytics to leverage AI tools effectively.
  • The effectiveness of AI depends on the quality and integrity of the input data. Insights generated by AI algorithms are as good as the data fed into them. Additionally, if the data used for training these AI models are flawed, the models will provide erroneous insights. Therefore, high-quality data are the foundation of good AI systems. So, learn about various data governance standards and data management practices.
  • According to a survey conducted by Thomson Reuters, the adoption rate of AI tools remains very low; only one in ten accounting and tax professionals are currently using them in their work. The lack of training often tops the list of reasons why accounting and audit teams do not use AI. Keep yourself knowledgeable about the latest developments in AI technologies and get trained on how they can help you and your organisation in improving the accounting services you provide.
  • Standalone AI tools are useful. But their real benefits are achieved by integrating them into your existing accounting software and systems. Compatibility and interoperability of these tools are crucial for their effectiveness and seamless utilisation. This can be complicated and may require a significant amount of investment in time and resources. If you understand your accounting systems and are comfortable using them, you will find integrating AI tools much less challenging and highly rewarding.
  • We can deploy AI to automate many tasks, but AI is just another tool. It can malfunction or be misused. Human oversight is essential when using this tool, especially in interpreting results, making decisions and handling exceptions. It is important that you understand the underlying assumptions and the limitations of the AI tools and techniques you are deploying.
  • AI involves the use of confidential financial information. Handling such sensitive proprietary data requires robust measures to protect against security breaches and ensure privacy. Additionally, when a breach does occur, there should be immediate activation of standard protocols to terminate the breach, control the damage and comply with data protection regulations. Learn about cybersecurity principles to ingrain cybersecurity awareness into your thinking and actions.
  • Using AI tools requires a critical thinking and problem-solving mindset. AI tools can provide information and insights but humans will have to interpret them and use them to make decisions. You can get insights using AI tools about some financial weaknesses in your client’s business. But the client has little knowledge about what sound financial management is so you will have to explain various parts of the financial report and implications for the client. There will be a growing need for accountants who can interpret AI-generated insights and apply them to business strategy and operations. So, enhance your analytical and explanatory skills through complex problem-solving exercises and real-world case studies.
  • AI is a double-edged sword which can cut both ways. Responsible use of AI is crucial for professional integrity and sound business practices. Transparency, accountability and compliance of AI tools with legal and ethical standards are essential for maintaining trust in your relationship with your clients and regulators. Learn about and adhere to stringent ethical standards and practices.

As discussed above, AI has the potential to transform accounting into an unprecedented level of efficient, accurate and insightful function. AI can not only help bring innovations and create growth opportunities but also redefine what it means to be an accountant. The Big Four accounting firms are investing billions of dollars in developing their own AI tools, such as KPMG Ingnite, Deloitte Cognitive Advantage, EY.ai, and PwC’s Responsible AI Framework. However, many small and medium-sized accounting firms are also increasingly developing and deploying AI into their systems and processes to remain competitive and create differentiation.

AI is making progress much faster than we think, but still there are kinks to be worked out. Humans will have to remain in the loop to provide oversight against embarrassing hallucinations by AI systems, especially generative AI models. Adopting a new technology like AI will always be a bumpy journey; but if you try to enjoy the ride, you will come out a happy winner.

References and Further Readings

  • “AI In Accounting and Bookkeeping: Braving the New Digital Frontier” by Bo Davis. 11th September, 2023. Forbes. https://www.forbes.com/sites/forbestechcouncil/2023/09/11/ai-in-accounting-and-bookkeeping-braving-the-new-digital-frontier/
  • “AI Use Cases” by Ernst & Young (EY). https://www.ey.com/en_gl/services/ai/use-cases
  • “How will AI affect accounting jobs?” by Thomson Reuters Tax & Accounting. 31st October, 2023. https://tax.thomsonreuters.com/blog/how-will-ai-affect-accounting-jobs/
  • “Latest Version of ChatGPT Passed a Practice CPA Exam” by S. J. Steinhardt. 23rd May, 2023. NYS Society of CPAs. https://www.nysscpa.org/article-content/latest-version-of-chatgpt-passed-a-practice-cpa-exam-052323
  • “PricewaterhouseCoopers to Pour $1 Billion into Generative AI” by Angus Loten. 26th April, 2023. The Wall Street Journal. https://www.wsj.com/articles/pricewaterhousecoopers-to-pour-1-billion-into-generative-ai-cac2cedd
  • “The Dawn of a New Era: AI’s Revolutionary Role In Accounting” by Neil Sahota. 22nd April, 2024. Forbes. https://www.forbes.com/sites/neilsahota/2024/04/22/the-dawn-of-a-new-era-ais-revolutionary-role-in-accounting/
  • “The Impact of Artificial Intelligence on Accounting and Finance” by Qi “Susie” Duong. 29th January, 2024. Institute of Management Accountants. https://www.imanet.org/research-publications/ima-reports/the-impact-of-artificial-intelligence-on-accounting-and-finance.
  • “The Role of Artificial Intelligence in Forensic Accounting and Litigation Consulting: Should Experts Be Concerned?” by David Zweighaft and Clay Kniepmann. Spring 2024. AICPA & CIMA. https://www.aicpa-cima.com/resources/download/the-role-of-artificial-intelligence-in-forensic-accounting-and-litigation
  • “What AI can do for auditors” by Anita Dennis. 1st February, 2024. Journal of Accountancy. https://www.journalofaccountancy.com/issues/2024/feb/what-ai-can-do-for-auditors.html.

Emigrating Residents and Returning NRIs – Part-II

This article is part of the ongoing series of articles dealing with Income-tax and FEMA issues related to NRIs. This is the second part of the two-part article on the interplay of Income-tax and FEMA issues for Emigrating Residents and Returning NRIs. Part-I of this article was published in the June 2024 edition of the BCAS Journal. It dealt with concepts and controversies related to migrating residents and change of citizenship. One can refer to Paragraphs 1 to 4 at the start of Part-I for introductory points in relation to movement from one country to another. Part-II — this part — is in continuation to Part-I and covers issues related to Returning NRIs. At the end of this article certain considerations which are common to both sets of people — migrating residents and returning NRIs — are also dealt with in Para C.

B. Returning NRIs

A recent survey highlights that at least 60 per cent of NRIs in the US, UK, Canada, Australia, and Singapore are considering returning to India after retirement1 . Apart from retirement, there are several other reasons due to which NRIs return to settle back in India — to stay with family members in India; due to their or their family members’ health reasons; citizenship issues in the foreign country; political instability in the foreign country; etc. In our experience, some of them are also returning for new and better business opportunities which are available in India now.

Under FEMA, there are different and overlapping classifications for non-residents like Non-resident Indian (NRI), Persons of Indian Origin (PIO), and Overseas Citizen of India (OCI) cardholders. This article covers all such people and collectively refers to all non-residents of India who come to India and become Indian residents as “Returning NRIs.” Such persons, if they are foreign citizens, should also refer to Para 11 to 16 in Part-I of this Article2 , which covers issues pertaining to change of citizenship.


1. https://retirement.outlookindia.com/plan/news/60-of-nris-consider-returning-to-india-after-retirement-sbnri-survey
2. Refer June 2024 issue of the BCAJ – 56 (2024) 251 BCAJ

The Income-tax and FEMA issues pertaining to Returning NRIs are explained in detail below:

B.1 Income-tax issues of Returning NRIs

17.13 Residential status

If a Returning NRI is determined to be Resident & Ordinarily Resident (ROR), their global incomes are taxable in India. Further, such a person needs to disclose all their foreign assets (including those which were acquired when the person was non-resident) and foreign incomes in their tax return. Any non-compliance exposes the person not only to interest and penalties under the Income-tax Act, but also the penal provisions under the Black Money Act4 for non-disclosure of foreign incomes and assets. Therefore, the first and foremost step under the Income-tax Act is to ascertain the residential status of the individual. Section 6, sub-sections (1), (1A) and (6), are relevant to determine the residential status of individuals.


3. The paragraph references continue from Part-I of this article
4. Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015

17.2 In the case of Returning NRIs, the individual is coming back for good. He is not coming on a visit to India. Hence, the relief pertaining to “being outside India and coming on a visit to India” provided under Explanation 2 to Section 6(1)(c) of the Income-tax Act (ITA) is not available. Consequently, the relief of staying up to 181 days in India is not available to them. In other words, the basic “60 + 365 days test”5 applies to Returning NRIs, and if it is met, the individual becomes a resident u/s. 6(1) of the ITA. A couple of nuances pertaining to this were dealt with in detail in the December edition of the BCAS Journal. For completeness’s sake, they are briefly touched upon below:

a. Benefit of visit not allowed:

A person returned to India after resigning from her employment in China. The Authority for Advance Rulings (AAR) held6 that relief under Expl. 2 to S. 6(1)(c) of the ITA will not be available to her since the facts and circumstances show that the reason for coming to India is not just a visit. Hence, the “60 + 365 days test” test will apply.

b. Is hair-splitting between visit and permanent stay allowed during the same year?

Karnataka High Court has held7 that when the individual – being outside India, was on a visit to India – such stay should be tested against the 182-day test and not considered for the “60 + 365 days test.” Later, during the year, if the person returns to India, only the stay after such return needs to be considered for the “60 + 365 days test.” However, in the decision by AAR referred to herein above in sub-para (a), the hair-splitting between a visit and a permanent stay in India was not allowed. Hence, hair-splitting of a person’s stay between ‘visit’ and ‘permanent stay’ during the same year is litigious.


5. “60 + 365 days test” means that the individual has stayed in India for 60 days or more during the relevant previous year and for 365 days or 
more during the four preceding years
6. Mrs. Smita Anand, China [2014] 42 taxmann.com 366 (AAR - New Delhi)
7. Director of Income-Tax, International Tax, Bangalore vs. Manoj Kumar Reddy Nare [2011] 12 taxmann.com 326 (Karnataka)

17.3 If the person was a non-resident of India in 9 out of the preceding 10 previous years; or if his or her stay in India in the preceding 7 years was less than 729 days, such an individual would be Resident but Not Ordinarily Resident (“RNOR”). These provisions of Section 6(6)(a) of the ITA have been explained in detail in the December 2023 edition of the BCAJ. In general, before the amendments by the Finance Act 2020, a returning Indian could claim RNOR status for 2 or even 3 years if one of the above tests of Section 6(6)(a) is met. The amendments by the Finance Act 2020 have diluted the RNOR status for Returning NRIs. This is explained in detail below.

17.4 If an individual does not become a resident, u/s. 6(1), one should also consider the provisions of Section 6(1A) wherein an Indian Citizen is considered a resident under specific circumstances8, where he is not liable to tax in any other country by reason of residence, domicile, or any other criteria of similar nature. If an individual becomes a resident by virtue of Section 6(1A), he is always considered as RNOR as per Section 6(6)(d).


8. Where his or her income from sources within India exceeds ₹15 lakhs in that year(s).

Individuals who are covered u/s. 6(1A) become deemed RNORs. Even if they do not visit India for a single day, they are residents but not ordinarily residents under the ITA. This has an impact when they return to India for good. Let us say, an Indian citizen, Mr Kumar has been employed and staying in Oman since 2010. Mr Kumar came on visits to India totalling a period of 65 days every year with clarity that he would remain a non-resident of India due to relief available of a visit to India as per clause (b) to Explanation 1 to Section 6(1)(c). On 1st April, 2024, he retired and came back to India for good. In the absence of Section 6(1A), he would have been a non-resident since 2010. Hence, after returning to India, he would have been RNOR for at least the first two years.

However, Oman does not tax individuals. Post Finance Act 2020, as per Section 6(1A), such an Indian citizen would be RNOR and not NR for the PYs 2020-21, 2022-23, 2023-24. This means he does not meet the first test u/s. 6(6)(a) of being NR for at least 9 years out of the last 10 years. The relief u/s. 6(6)(a) has thus been diluted due to Section 6(1A). In simple words, he will be ROR from PY 2024-25 and will be liable to Indian tax on his global income. Similar would be the situation for an Indian citizen or person of Indian origin9 who visits India for 120 days or more during each year, and his stay in the preceding 4 years is 365 days or more. Such a person gets covered by the amended portion of clause (b) of Explanation 1 to Section 6(1)(c) and consequently would be RNOR as per Section 6(6)(c)10.


9. A person shall be deemed to be of Indian origin if he, or either of his parents or any of his grand-parents, was born in undivided India – Explanation to clause (e) of Section 115C of ITA.
10. Where his or her income from sources within India exceeds ₹15 lakhs in that year(s).

17.5 Normally, a Returning NRI would be considered as RNOR if he had not spent more than 728 days during the preceding 7 years. This should be the case generally for 2 or even 3 years after a person returns to India. But for persons like Mr Kumar, who visits India every year and then settles in India, they may not meet the test of stay in India of less than 729 days during the preceding 7 years after the first year of returning to India. Hence, those individuals who stay abroad and are planning to settle in India need to be aware of the dilution of their RNOR status due to the provisions of Section 6 as amended vide Finance Act 2020.

18 Disclosure and source of foreign assets

Since AY 2012-13, Indian residents (ROR) are required to disclose their assets located outside India in their Income-tax return form. This is required even if such a resident is otherwise not required to file a tax return. Returning NRIs would, in most cases, have savings, assets, and investments abroad when they come back. On becoming ROR, all such foreign assets need to be disclosed in the tax return. The person would have acquired these assets when he was staying abroad and was a non-resident. The source of funds for acquiring these assets is not required to be explained or disclosed in the tax return. However, practically, things are quite different.

There is 360-degree profiling by the regulators these days. The CBDT has formed Foreign Asset Investigation Units (FAIUs) in all the 14 investigation directorates across India. Their job is to analyse the plethora of information received by India from foreign jurisdictions under Automatic Exchange of Information (AEoI) agreements, CRS, DTAAs, etc. If they come across any red flags, they issue a notice asking for detailed information pertaining to each and every foreign asset held by the person since its acquisition. The red flags could be a variance between the data received by them vis-à-vis the foreign assets disclosed in the tax return by the assessee; or foreign assets disproportionate to the transactions or profile of the assessee, etc. They even ask for decades-old data and documents supporting such data. Hence, maintaining documents becomes particularly important.

In such cases, until and unless it is proven through documentary evidence that a foreign asset was acquired from bonafide sources, the matter is not closed. This becomes a big hassle. There are cases where the assessees did not retain their old bank statements and other documents. In fact, foreign banks and brokers do not provide old statements easily and they also charge heftily for obtaining old statements. Further, foreign banks and financial institutions do not retain records beyond a certain number of years, in which case, it becomes almost impossible to provide the documents to the officer. Hence, Indians who are staying abroad, whether they plan to return to India someday or not, should keep proper and complete data of all their assets. If and when they return to India, such a record would become important. Further, they need to maintain documents to justify their increase in net worth by their sources of incomes during the years when they were non-resident. If there is any violation in the disclosure of foreign assets; or if the officer is not satisfied with the explanation or documents, proceedings can be initiated under Section 10 of the Black Money Act11 (BMA) and the harsh penal provisions of the BMA are also invoked in certain cases. This has happened in even bona fide cases where innocent errors are made in disclosing foreign assets.


11. Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015

19 Other Disclosures in ITR Form

Apart from foreign assets and incomes, other disclosures are also required to be made in the Income-tax return form, which are tabulated below:

Particulars ROR NOR NR
Unlisted equity shares To be disclosed of all companies. To be disclosed only of Indian companies.
Directorships To be disclosed in all companies across the globe. To be disclosed in all Indian companies & only in such foreign companies which have income accruing or deemed to be accruing in India.
Schedule AL Global assets. Only Indian assets.
Schedule FSI Foreign-sourced incomes are included in the Total Income (largely relevant only for RORs.)
Schedule EI Incomes exempt under the Income-tax Act or DTAA.

20 Treaty relief

Similar to migrating Indians, even for Returning NRIs, there can be an overlapping period wherein the person is a resident of India as well as of the country he is returning from. This leads to dual residency, for which tie-breaker tests are prescribed under Article 4(2) of the Double Tax Avoidance Agreement (DTAA). There could also be a possibility of the concept of split residency being applicable. Accordingly, the provisions of the DTAA can be applied. These provisions have been explained in detail in the second article of this series (January 2024 edition of the BCAJ). In essence, there could be benefits vide the DTAA in the foreign jurisdiction as well as in India. The credit of tax paid in a foreign jurisdiction as per the DTAA can be availed against the tax payable in India. Necessary forms will be required to be filed along with supporting documents to claim credit.

21 Continuing foreign employment or business

Many people continue their employment or business abroad after returning to India. This has become easier in today’s globalised technology-driven era. In fact, the Covid lockdown saw many Indians stuck in India
or coming back to India and continuing their foreign business or employment from India. However, it is pertinent to note that the economic activity is being done from India. It should be checked whether any income directly accrues in India on account of such activity due to specific provisions which can get triggered in such a case, of which the most common ones are explained below:

21.1 Salary: Section 9(1)(ii) deems the salary proportionate to the period when the employment was exercised from India to be accruing in India. Hence, even if a person is NR or NOR, the amount of salary proportionate to the days he exercises employment from India is deemed to accrue in India. This provision applies not only to Returning NRIs, but to everyone. Prima facie, the proportionate salary is taxable under ITA, and one should go under the applicable DTAA to claim relief, if any.

21.2 Place of Effective Management: A foreign company is considered as resident of India if its Place of Effective Management is, in substance, in India, during that year12. The CBDT has prescribed detailed guidelines through Circulars 6, 8 and 25 of 2017. It should be noted that this provision applies only to companies having a turnover of more than INR 50 crores during the financial year.

21.3 Business Connection and Permanent Establishment: When an individual works in India for a foreign entity, he may constitute a “Business Connection” of the foreign entity in India. In that case, the income pertaining to the activities carried out through such Business Connection is deemed to accrue in India13 . Further, if there is a DTAA between India and the country where the entity is resident, generally, the business profits of the foreign entity would be taxable in India only if the foreign entity has a Permanent Establishment (PE) in India. Every DTAA has different criteria for determining whether there is a PE. Hence, it needs to be checked whether the individual constitutes a Business Connection of such entity in India, and if yes, whether he constitutes a PE of such entity in India as per the applicable DTAA. This can be possible in cases where the foreign company is run almost exclusively by the Returning NRI.


12. Section 6(2) of ITA
13. Section 9(1)(i) of ITA

B.2 FEMA issues regarding Returning NRIs

22 Residential status

The provisions pertaining to residential status under FEMA were dealt with in detail in the March 2024 edition of BCAJ. In essence, as per Section 2(1)(v) of FEMA, when a person comes to India for or on taking up employment in India; or for carrying on business or vocation in India; or under circumstances which indicate his intention to stay in India for an uncertain period — he becomes an Indian resident under FEMA. Hence, when a person comes to settle down in India for good, he or she becomes a resident under FEMA from the date of their return to India. This is because the person is coming to India in such circumstances, which indicates his intention to stay in India for an uncertain period. Hence, from the day a person returns to settle in India or for the purposes mentioned above, all provisions under FEMA meant for residents become applicable to such person.

23 Scope of FEMA as applicable to Returning NRIs

Apart from the assets and transactions covered u/s. 6(4) of FEMA and the balances in RFC accounts (explained in detail below), all other transactions outside India (whether in foreign currency or INR); all Indian transactions in foreign currency and all transactions with non-residents (whether in or outside India) come under the purview of FEMA. This can impact Indian transactions of the Returning NRI with other non-resident family members. As non-residents, they would have had the liberty to transfer funds between their NRO accounts. However, there will be several restrictions on transactions between a Returning NRI (who is now a resident individual) and a non-resident. Thus, gifts, loans and even payments made to or on behalf of non-residents can have implications under FEMA. Thus, a change of residence requires a change in mindset, as otherwise, Returning NRIs may end up committing violations under FEMA.

24 Holding foreign assets abroad

24.1 Background of FERA: Under FERA, as it was enacted, when a person became an Indian resident, he was required to liquidate all his foreign assets and bring the foreign exchange into India unless approval was obtained from RBI. This was liberalised in July 1992 when the Government of India issued six notifications granting exemptions from several different provisions of FERA to the returning Indians. These notifications were covered with a press note and a circular issued by RBI in Sept. 1992 — ADMA Circular No. 51 dated 22nd September, 1992. It explained the notifications. A summary of all the provisions is that on return to India, the Returning NRI retain all his assets abroad — provided that the assets were not acquired in violation of FERA and that the person was a non-resident for at least one year before becoming resident. There was no need to make any declaration under FERA. He could change his assets in the sense that he could sell one asset and buy another. He could retain dividends / interest / rent and other incomes earned on the assets. He could reinvest these incomes or spend the same. He was at liberty to bring the assets to India or to retain them abroad. He could gift these assets to anyone. On death, his foreign assets would pass to his heirs without any restrictions. If the Returning NRI held shares in any company, the shares would be considered as his investments. The company could continue business abroad. One could say that FERA did not apply to such wealth of the person and the incomes generated on such wealth. The person was free to do anything with the same.

24.2 Provisions under FEMA: Under FEMA, unfortunately, such liberalisation has been provided in a very brief manner through Section 6(4), which is reproduced below:

“(4) A person resident in India may hold, own, transfer or invest in foreign currency, foreign security or any immovable property situated outside India if such currency, security or property was acquired, held or owned by such person when he was resident outside India or inherited from a person who was resident outside India.”

It is provided that any foreign currency, foreign security, and immovable property situated outside India which were acquired when the person was a non-resident, can be continued to be held or owned after becoming a resident.

24.3 Section 6(4) of FEMA does not clearly specify the transactions which are allowed as was quite apparent as per the circulars issued under FERA. On making a representation, RBI issued A.P. Dir Circular No. 90 dated 9th January, 2014, which prescribes the transactions covered u/s. 6(4). Those are as follows:

a. Foreign currency accounts opened and maintained by the Returning NRI when he or she was resident outside India.

b. Income earned through employment or business or vocation outside India taken up or commenced while such person was resident outside India, or from investments made while such person was resident outside India, or from gift or inheritance received while such a person was resident outside India.

c. Foreign exchange, including any income arising therefrom, and conversion or replacement or accrual to the same, held outside India by a person resident in India acquired by way of inheritance from a person resident outside India.

d. Returning NRIs may freely utilise all their eligible assets abroad as well as income on such assets or sale proceeds thereof received after their return to India for making any payments or to make any fresh investments abroad without approval of the Reserve Bank, provided the cost of such investments and / or any subsequent payments received therefor are met exclusively out of funds forming part of eligible assets held by them and the transaction is
not in contravention to extant FEMA provisions.

Thus, such assets can be sold, and proceeds may even be reinvested abroad. There is no requirement to repatriate the income earned on these assets or sale proceeds thereof into India.

24.4 One can consider that broadly, the restrictions under FEMA do not apply to assets covered u/s. 6(4) of FEMA. One of the important clarifications in this regard pertains to overseas investments by resident individuals, which are allowed under the Overseas Investment Rules14 (OI Rules) of FEMA only if specific conditions are met. However, when it comes to foreign assets covered u/s. 6(4), Rule 4(b)(iii) of the OI Rules clearly provides that the OI Rules do not apply to any overseas investment covered u/s. 6(4). It would thus also cover any asset or investment which a resident may otherwise either not be permitted to invest in; or permitted only within a certain limit; or only after fulfilling attendant conditions — under the OI Rules. For instance, resident individuals are not allowed to make Overseas Direct Investment in a foreign entity which is engaged in financial services activity. However, if a non-resident had invested in such a company abroad and later on, he or she becomes an Indian resident, such person can continue holding shares of the foreign company. The income thereon and the sale proceeds thereof can be retained abroad. If the individual wants to make any further investment in the foreign entity engaged in financial services activities out of funds lying in his Resident bank account in India, he or she will not be generally permitted to do so15.


14. Foreign Exchange Management (Overseas Investment) Rules, 2022 – Notification No. G.S.R. 646(E) issued on 22nd August 2022.
15. Refer Rule 13 of the OI Rules read with paragraph 1 of Schedule III to OI Rules.

24.5 Other assets not specified u/s. 6(4) of FEMA: Section 6(4) specifies only three assets. Further, the circular also does not provide complete clarity. A person may own several other assets. For instance — the person can have an interest in a partnership firm or LLC or can own gold, jewellery, paintings, etc. As a practice, the RBI has taken a view since 1992 that a person is eligible to continue owning / holding all the foreign assets after turning resident, which he had acquired as a non-resident. This also includes such assets or investments which he could not have otherwise owned or made as a resident.

24.6 Insurance abroad: Returning NRIs may have different types of insurance policies issued by insurers in India as well as outside India. As explained above, funds covered under Section 6(4) of FEMA and lying abroad can be utilised for any purpose, including premium payment for insurance policies. FEMA provisions pertaining to s the utilisation of Indian funds for foreign insurance policies16 by Returning NRIs are as follows:

a. Health insurance policy can be continued to be held by a Returning NRI provided the aggregate remittance including the amount of premium does not exceed the LRS limit.

b. Life insurance policy can be continued to be held by a Returning NRI if it was issued when he was a non-resident. Further, if the premium due on such policy is paid by remittance from India, the maturity proceeds or amount of any claim due on the policy should be repatriated to India within 7 days of receipt.

24.7 Loans abroad: If a person has taken a loan abroad as a non-resident and becomes a resident later, he can service such loans subject to such terms, conditions and limits as specified by RBI. In general, RBI has not objected to a Returning NRI using his or her foreign funds covered under Section 6(4) of FEMA to service such loan repayments.

24.8 Foreign currency: Returning NRIs may need to bring in foreign currency notes and coins into India. Notification No. FEMA 6(R)17 provides that such person can bring into India without limit foreign exchange (other than unissued notes) from any place outside India. However, a declaration needs to be made to the Customs authorities.


16. Para 2 of Master Direction on Insurance - FED Master Direction No. 9/ 2015-16 - last updated on 7th December 2021.
17. Reg. 6(b) of Foreign Exchange Management (Export and import of currency) Regulations, 2015.

24.9 Inheritance of assets covered under Section 6(4) of FEMA: The first limb of Section 6(4) allows residents to hold assets abroad which they had acquired as a non-resident. The second limb further allows a resident heir of such Returning NRI to inherit these foreign assets from him or her. This is in line with the reliefs provided through the circulars issued earlier under FERA. However, it should be noted that this provision covers only one level of inheritance, i.e., from the Returning NRI to his or her heir. Later, if a resident heir of such heir wants to inherit these foreign assets, it is not covered by Section 6(4). The relevant notifications, rules, etc. under FEMA corresponding to the concerned assets need to be checked for the same. A summary of the holding and inheritance of foreign assets under Section 6(4) of FEMA can be summarised as follows:

Exceptions to this rule are for overseas immovable properties18 and foreign securities19, inheritance for which is allowed up to any generation if the investment and holding of such foreign property were as per extant FEMA regulations.


18. Rule 21(2)(i) of OI Rules.
19. Para 9(b) of Schedule III to FEMA Notification 5(R)/2016-RB – FEM (Deposit) Regulations,2016.

It should be noted that there are several controversies surrounding Section 6(4) of FEMA, including the interpretation of its second limb. We have not discussed all the controversies here, considering this is an article on a broader topic.

25 Impact on Indian assets

25.1 Bank and demat accounts: Returning NRIs need to designate their NRO bank and demat accounts as normal Resident accounts once they become residents20.
There are some special types of accounts in which non-residents can hold funds like NRE, FCNR, etc. On becoming a resident, NRE accounts need to be closed; however, FCNR deposits are permitted to be continued till maturity. Funds in both these accounts can be either transferred to the Resident account (becomes non-repatriable) or to the RFC account (repatriability continues, and such funds remain out of FEMA purview). Returning NRIs are permitted to hold foreign exchange in India in RFC accounts. The funds lying in an RFC account can be remitted abroad without any restrictions and can be used or invested for any purpose. The provisions of FEMA do not apply to the same. The provisions for such accounts will be discussed in detail in the upcoming articles in this series of articles.


20. Para 9(b) of Schedule III to FEMA Notification 5(R)/2016-RB – FEM (Deposit) Regulations, 2016.

25.2 Loan from NRI / OCI to a resident: If an NRI / OCI has given a loan to a resident (as per the FEMA guidelines) and he becomes a resident later, the repayment may be made to the designated account of the lender maintained with a bank in India as per the RBI guidelines, at the option of the lender.

25.3 Privately held investments in India: There could be investments in Indian companies, LLP, partnership firms, etc., made by Returning NRIs when they were non-residents. The implications of such investments due to a change of residence are explained below:

25.3.1 Indian assets held on a non-repatriable basis: NRIs and OCIs are permitted to invest in India on a non-repatriable basis, which has minimal restrictions and no reporting requirements. In such cases, if the person becomes a resident of India, there is no change in the character of the holding. The investment was anyway treated at par with domestic investment and no reporting, etc., is required. Normally, there is no formal record to be kept by the investee entity regarding the residential status of the person if the investment is on a non-repatriation basis. However, if there is any such record maintained, the residential status should be updated therein.

25.3.2 Indian assets held on a repatriable basis: Let us say the person has made investments in India on a repatriable basis. As a non-resident, he can remit full sale proceeds abroad without any limit. Now, if such a person returns to India and becomes a resident, the resultant structure is that an Indian resident is holding an Indian asset. The repatriable character of the investment is lost! This is a particularly important provision. All investments held by a non-resident on a repatriable basis become non-repatriable from the day he becomes a resident. In fact, there is nothing like repatriable or non-repatriable investment for a resident. Every Indian asset of a resident is considered as a domestic investment. It is only assets covered under Section 6(4) and the funds transferred to the RFC account, which are free from FEMA. This becomes a critical point, which every Returning Indian should consider in advance. When a non-resident holding an investment in an Indian entity on a repatriable basis becomes a resident, he should intimate it to the entity, and the entity should record the shareholding of the person as domestic investment and not foreign investment.

25.3.3 Indian assets held through a foreign entity: Let us say, a non-resident invests in Indian assets on a repatriable basis. However, instead of investing in his personal name (as explained in the above para), the investment is made by his foreign entity. Thereafter, the person becomes an Indian resident. The resultant structure is that an Indian resident owns a foreign entity which has invested in India on a repatriable basis. This enables the following:

a. Holding in Foreign entity: The ownership in the foreign entity by the Returning NRI is covered under Section 6(4). He can thus continue to hold such investments.

b. Repatriability of Indian assets: The Indian assets continue to be held on a repatriable basis by the foreign entity. All incomes and sale proceeds therefrom can be remitted abroad by the foreign entity without any limit. Had the individual directly held Indian assets and became resident, the repatriable character would have been lost — as highlighted above in Para 25.3.2. However, one should consider the tax implications of such a structure, especially with regard to POEM, Transfer Pricing and Permanent Establishment provisions under the ITA, as explained in para 21 above.

26 Remittance facilities for resident individuals

Liberalised Remittance Scheme: LRS is the remittance facility available for resident individuals. The LRS limit of USD 250,000 per financial year is the ceiling for all current and capital account transactions covered under the Current Account Transaction Rules. Barring exceptions like exports and imports and certain relaxations21 which are available in limited situations, the remittance facilities for a person resident in India under FEMA are constrained to the LRS limit. Returning NRIs should hence note that their remittances from India will be restricted to a considerable extent compared to what they were allowed as non-residents22. Even the liberty of remitting current incomes without any limit is not available for resident individuals.


21 Like use of International Credit Card while being on a visit outside India; higher amount of remittance allowed for educational or medical expenses; or for acquisition of ESOPs, sweat equity, etc.
22 Please refer to Para 7.6 in Part-I of this article for USD 1 Million Scheme which is available to NRIs.

27 Fresh incomes earned abroad

Let us say the individual earns fresh income abroad after becoming a resident – like salary, royalty or even receiving a gift of funds from a non-resident. A resident individual cannot retain such foreign exchange abroad. He is required to take all reasonable steps to realise the foreign exchange due or accrued to him and repatriate the same within 180 days of the date of receipt23.


23. Section 8 of FEMA r.w. Regulation 7 of FEMA Notification 9(R)/2015-RB.

C. OTHER RELEVANT ISSUES COMMON TO CHANGE OF RESIDENTIAL STATUS

28 Change of Citizenship

Change of citizenship has several ramifications beyond change of residence, especially under FEMA. The issues to be kept in mind when a person has obtained foreign citizenship are elaborated in Para 11 to 16 in Part-I of this Article covered in the June 2024 issue of the BCAJ. Returning foreign citizens should consider the implications of the country of their citizenship on their move to India — especially where such countries are taxing them based on their citizenship, exit taxes and estate duty or inheritance tax — all of which are explained briefly below.

29 Change of residence for a short period

One can see that the scope of FEMA and the Income-tax Act changes drastically with the change of residential status. This article attempts to cover aspects where there is a change of residence for good. If the residential status of a person changes for a short period of time, caution should be exercised before taking the benefits of a change of residence. Consider a situation where a resident goes abroad; claims to be a non-resident under FEMA or the Income-tax Act; takes benefit of such change (for example, by remitting USD 1 million from India or taking a treaty benefit as a non-resident of India); and again, becomes an Indian resident — all within a short period of time. In such cases, the regulator or tax officer may question the whole arrangement and consider that the change in residence is not genuine. Action can be taken based on anti-tax avoidance provisions under the Act and relevant treaty (please refer to para 35 below). Hence, there should be clarity on residential status; bonafides of transactions and genuineness of arrangements. In fact, sometimes it is ideal and safe if benefits are availed of only after the person is certain about his or her change in residential status and it is maintained over a period of time.

30 Succession Planning

There are several laws which need to be considered for succession planning like the applicable succession laws, Sharia law in the case of Muslims, Trust laws in case of Trusts, FEMA for cross-border transactions & assets, corporate laws in case of securities, stamp duty laws, Income-tax laws, Inheritance / Estate Tax etc. Hence, succession planning from a holistic approach is especially important wherever the family members or the assets are spread over more than one country. In fact, FEMA itself contains several complexities regarding inheritance. There are only a few provisions specifically dealing with inheritance and gifts under FEMA. These provisions are spread over many notifications. For several assets and situations, provisions are completely missing. To top it all off, everything changes when a person shifts residence from one country to another. The whole succession planning exercise needs to be re-considered in such cases — especially due to FEMA provisions.

31 Inheritance Tax or Estate Duty

31.1 Migrating persons, as well as Returning NRIs, should consider the inheritance tax or Estate Duty laws of the foreign jurisdiction. Different countries levy such taxes based on different criteria like citizenship, visa (green card in USA), domicile (UK), etc. In the USA, there is the Federal Estate Tax as well as the State Estate Tax. Residents of countries where such taxes or duties are applicable should have proper Estate Duty planning done. There have been cases where Estate Duty or Inheritance Tax is payable in the foreign country where a large amount of wealth was in the immovable properties which cannot be sold since the person is staying in the same. Further, if substantial wealth is situated in India, the limits on remittances abroad can also create a hindrance for paying such taxes. The following basic questions can be considered:

a. Applicability of such tax and the taxable events.

b. Connecting factors including domicile, citizenship, residence, etc.

c. Assets covered.

d. Thresholds applicable, if any, and tax rates.

e. Implications of gifts between family members.

f. Whether it applies to the inheritance of Indian assets received by the person on the death of his parents who are staying in India.

g. Treaties in relation to Double Taxation Relief for Estate Duties.

31.2 One common question asked is whether the Indian Government will bring in Estate Duties or Inheritance taxes. There is an unsupported fear in people’s minds of such duties impacting their wealth leading them to create Trust structures for protecting their wealth from such duties. The Government has earlier been on record to state that no such Estate Duties are planned. Further, even if such duties are introduced, they would have enough anti-avoidance provisions to counteract against any planning undertaken by taxpayers.

32 Exit Tax: Some countries have a concept of Exit Tax to prevent loss of revenue, if any, upon change of residential status / citizenship. It is levied when a person revokes citizenship or visa (like revocation of citizenship or green card in the USA) or if a person shifts his residence to another country (like Departure Tax in Canada). One may carefully plan the timing of their change of residence to minimise the impact of such taxes wherever possible.

33 Transfer Pricing

In simple words, Transfer Pricing triggers in case of a transaction which can give rise to income (or imputed income) between associated enterprises, of which at least one party is a non-resident. On change of residence, the migrating resident’s or Returning NRI’s continuing transactions with associated enterprises may come under the purview of Transfer Pricing provisions. All such transactions must be on an arm’s length basis. The implications under Transfer Pricing on the shift of a person from or to India should hence be considered.

34 Section 93 of ITA

Section 93 is a complex anti-avoidance provision which targets certain transfers of assets in a manner which leads to the income being earned by a non-resident, but the transferor still has the power to enjoy such incomes. The provision targets such transfers whereby incomes would have been chargeable to tax in the hands of the transferor if the transferor had earned such incomes directly. For example, a Returning NRI who transfers assets to another person before returning to India, but with a condition that income earned by such other person would be in control of the NRI, would be caught by this provision. There are several conditions and nuances in the provision, and one must note that any tax planning done before a change of residence can be impacted due to this provision.

35 Anti-tax avoidance provisions

While there are several Specific Anti Avoidance Rules (SAARs) prescribed under the Income-tax Act – POEM, Business Connection, Transfer Pricing, etc. – one should also consider General Anti Avoidance Rules (GAAR), which have been notified under Sections 95 to 102. GAAR would apply to an arrangement if it is regarded as an Impermissible Avoidance Arrangement (IAA). There are detailed provisions on the same. The ramifications of GAAR are massive. Once an arrangement is determined as IAA, the officer can treat the place of residence of such person at a place other than their claimed place of residence; ignore one or more transactions; deny benefits of a DTAA; recompute the income and tax of the assessee; and so on. While the Department has invoked GAAR in very few cases till now, it looks evident that GAAR will be invoked more frequently in the times to come. Recently courts have decided on the matter of applicability of GAAR in certain situations. Further, after the advent of the Multi-Lateral Instrument, several treaties that India has entered with other countries and jurisdictions have brought in anti-tax avoidance provisions where the change of residence is only for the purposes of claiming treaty benefit. These include the broader Principal Purpose Test and amendment in the preamble to the treaty, as well as the specific anti-tax avoidance measures that are today part of many double-tax avoidance treaties that India has signed.

36 Documentation and record-keeping

Change of residence typically leads to several queries from the tax department or regulator — especially for Returning NRIs in relation to their foreign assets. They would like to know that the foreign assets of such a person were acquired in a bona fide manner as a non-resident. One can refer to para 18 above explaining the same. Therefore, full documentation should be maintained. A few key areas where documentation should be maintained are:

a. Calculation of number of days of stay in India in each year and determination of residential status.

b. Passport copies to substantiate travel details and number of days stayed in India.

c. Relevant documents for every foreign asset and transaction, especially the opening statements, along with an explanation of the source of funds (irrespective of residential status).

d. Tax returns and other documents filed in the foreign jurisdiction.

e. Disclosure of foreign assets including in case of joint ownership, nomination, authorised signatory, etc.

f. Employment contract, salary slips, visa, etc.

g. Details and documents substantiating the purpose of immigration or emigration.

37 Impact of other laws

37.1 Transferring physical or movable assets from or into India: While FEMA permits holding assets in or outside India migrating or returning individuals may plan to move valuable assets with them from or into India – like gold, jewellery, art, etc. One should consider the permissibility and limits under Baggage Rules, 2016 of the Customs Act, along with the disclosures required thereunder. Further, certain movable items like art and antiques, as well as those dealing with wildlife, etc., need to be imported or exported only as permitted under the relevant laws24. Similarly, a migrating resident needs to check the parallel provisions of the country to which they are migrating.


24. The Antiquities and Art Treasures Act, 1972 and The Wild Life (Protection) Act, 1972, etc.

37.2 Indirect taxes: Indirect taxes have a significant impact, especially in a situation where the individual works in a personal capacity instead of employment. For instance, if Returning NRI continues working for a foreign entity as a consultant or in a similar manner, the applicability of GST and other indirect taxes needs to be checked.

37.3 Stamp duty laws: Certain individuals end up entering into gift deeds, powers of attorney, etc., on change of residence. Any document executed or brought within India can attract stamp duty. The stamp duty laws need to be checked before executing any such document. Similarly, the stamp duty law of the foreign country should also be considered.

37.4 Other laws: There are several other laws which could apply while executing a transaction or on account of a change of residence. It could be visa and citizenship rules; laws pertaining to family and marriage; labour, and social security regulations/norms. These laws should be considered for India as well as the host country.

38 Geopolitical, Economical, and Cultural Considerations / Challenges

Moving base has its own set of challenges. Certain personal factors can be dealt with by the individual concerned to a large extent. However, such individuals should also appreciate that there are several factors which are beyond their control. These relate to the economic situation of the country they are moving to the cultural change they or their family members must deal with. Further, the global geopolitical environment has seen dramatic upheavals in the last decade. Apart from the economic and legal considerations, one should also keep the geopolitical developments in mind, especially in relation to India and the host country where they are migrating to or from.

Conclusion

One can see that a change of residence leads to a substantial change in the tax liability, compliances, and regulatory provisions applicable to the person. Further, the Income-tax and FEMA laws themselves have grey areas, with differing views between various stakeholders causing prolonged litigation. When we bring in laws of another country and their interplay with Indian laws to the same transaction or income, it leads to increasing complexities, contradictions, and uncertainties. When a person shifts residence from abroad to India or from India to abroad, the whole legal position surrounding the person takes a 180-degree turn. It is like turning the table halfway through in a game of chess! In such cases, it is ideal to consider all the legal implications in advance, so that informed decisions can be taken. Otherwise, it could happen that the person is “physically” moving to a particular location with several plans in mind, but “legally” spearing into uncharted territory with far-reaching consequences.

From ICAI President

We have reached milestones that are far beyond what I expected. – J. Hope

Today, while I am here to pen down my thoughts at this juncture, I think this quote is quite apt, as the Bombay Chartered Accountants Society (BCAS), established in 1949, has completed 75 years of its sagacious journey. This is even more special as the Institute of Chartered Accountants of India (ICAI) has also completed 75 years of existence – a journey of Trust, Independence, Integrity, and Excellence. During these 75 years, ICAI has become ‘the World’s Largest Accounting Body’.

BCAS has endeavoured to be a principle-centered, learning-oriented organisation promoting quality professional education, networking, and excellence in the profession of Chartered Accountancy.

At this juncture, I would like to say that it is a time to reflect on the past, learn from it, and envision the future based on the experiences and wisdom gained. The past should serve as a motivation to propel us further towards growth and transformation, helping us shape the landscape and build the foundation for the future.

On this note, I would like to congratulate the President, Vice-President and all other office-bearers of Bombay Chartered Accountants Society for their invaluable contribution and their efforts towards this professional body, and in turn, to the profession as a whole.

May you soar to much greater heights.

Namaskaar

!! योजकस्तत्र दुर्लभ: !!

This line is very often used as a proverb. There are many idle persons around, many apparently useless things around. We discard them as useless. People wonder what is to be done of such persons or such things. This shloka is an answer. It says:

अमंत्रमक्षरं नास्ति नास्ति मूलमनौषधम् !

अयोग्य: पुरुषो नास्ति योजकस्तत्र दुर्लभ: !!

This is indeed a great thought. It reflects the richness of our Indian culture.

अमंत्रम् अक्षरं नास्ति – There is not a single letter or alphabet that is not used in a ‘mantra’. Mantra is a powerful verse or shloka or ‘sutra’. It is a form of prayer which is to be chanted repeatedly.

In such prayer, any letter is capable of being used. Hence, you cannot discard any alphabet as useless.

नास्ति मूलम् अनौषधम् – There is not a single root or herb that has no medical value. Ayurveda recognised this principle. The sages knew which herb could be used as a remedy for which disease. A herb may look ugly, smell ugly or taste bad; it may even be poisonous. Still it can be used in some medicine or the other. Even the poison of animals is utilised for preparing appropriate medicines.

अयोग्य: पुरुषो नास्ति – There is no single individual who is absolutely useless. Every person has some qualities and skills. A man may be a dull, slow learner, physically or mentally challenged, old or too weak to work. A man may be indisciplined, arrogant, timid, lazy, self-centred, moody, eccentric or even stupid. But it depends on the leader or a wise person to make use of him.

योजकस्तत्र दुर्लभ – It is rare to find a visionary leader to make use of such persons.

We are aware that physically disabled persons are employed in responsible positions, and even criminals are employed in certain trades. Many school dropouts have performed amazing tasks in life. They have made wonders. Albert Einstein was labelled as a dull boy in his school days. The word Einstein means a big stone!

What is necessary is a visionary leader. He can visualise and create different tasks to be performed by very ordinary people. Let us not go to the extreme illustrations but understand the spirit. In an organisation, you do have people to whom you do not allocate any work since you distrust their ability. You feel they will spoil it. But a good HR Manager can find some useful work for them. ‘Right man at the right place’ is the basic principle of Human Resource Management.

Similarly, we have examples of creating artistic articles from garbage, domestic gas from cow dung (gober), fertilisers from garbage and many such things.

Shivaji Maharaj had not trained the army. He gathered ordinary peasants from villages, the ‘mavlas’, trained them and made them great warriors! They used even big stones to kill the invaders. For Lord Shri Ram, monkeys built the Setu (bridge over the sea). With the same objective, the Government has set up a Skill Development Ministry. They train people with not much formal education in various skills. They make such people employable. They aim at transforming an ordinary driver into a chauffeur, a simple cook into a chef. Even the nurses and yoga teachers have huge opportunities abroad.

In short, we need a visionary leader, be it for a country or for any organisation, or even for a family.

BCAS President CA Anand Bathiya’s Message for the Month of August 2024

Dear BCAS Family,

On July 6th, 2024, our Society completed 75 revolutions around the Sun. Our history chronicles the evolution from a small group of dedicated professionals gathering on Wednesdays to what is now the largest and oldest voluntary body of Chartered Accountants in India, with representation spanning over 350+ cities and towns nationwide. It is a fascinating phenomenon as to why, year-after-year, thousands of Chartered Accountants continue to revere our Society as a hub to fulfil their intellectual hunger and admire our Society as a pinnacle in enabling professional development.

The single most important reason for this incredible evolution and longevity of our Society over the last many decades has been the ‘constant urge and effort to stay relevant’. Being an observer of the inner functioning of our Society, I had the privilege to closely witness this continuous process of institutional self-reflection and the enduring drive towards ‘staying relevant’ to our community. This attribute of ‘staying relevant’ hinges on remaining conscious and alert to changing times and changing needs of our community.

It is of no surprise that with great honour, our Society wears the Sanskrit aphorism, “न भयं चास्ति जाग्रत:” (na bhayam chasti jagratah) as its esteemed emblem, signifying that those who remain conscious and alert, have no reason to fear.

Throughout the last decades, our profession has encountered numerous challenges, and our Society has been pivotal in augmenting our community’s ability to meet these challenges head-on and even transform them into opportunities. Our challenges today are much different, both in terms of their nature as well as their impact, and our Society’s role in the face of these challenges is of vital importance.

Last month, we carried out a Membership Survey with extensive participation from our community, gathering their valuable insights. A significant inquiry within the survey asked members: “What are the primary challenges you believe our Profession faces?”. The collected responses have been organized as follows:

While all of the above challenges deserve our undivided attention and dedicated efforts, the challenges related to technology, talent, and regulatory risks particularly distinguish themselves. Each of these will require concentrated efforts involving awareness, learning, upskilling, upgradation as well as advocacy.

Swamped with our July deadlines, September deadlines, October deadlines and deadlines after deadlines, we would need to introspect on these challenges and also our response to these challenges.

Within these challenges, exists the chance to excel and expand our professional pursuits, whether in our practice outfits or in our employment roles. Embracing contemporary technologies, enhancing our talent practices and managing risks will need to be the cornerstone of our efforts in the coming times.

Our Society remains committed to concentrating its efforts on tackling these contemporary challenges, aiding our community in enhancing its relevance.

Budget @ BCAS

Last month, the Indian Tax and finance community experienced a significant day with the presentation of the Union Budget for the fiscal year 2024-25. Speaking at the Public Lecture Meeting on Finance (No. 2) Bill, 2024, Shri CA. Pinakin Desai aptly summarised the budget as ‘On an overall basis, it is a satisfactory budget, with aberrations on both sides’. The Finance (No. 2) Bill, 2024,affecting more than 80 sections of the Income Tax Act of 1961 promises some impactful changes to the status quo.

While the drive towards simplification, streamlining, and standardisation is praiseworthy, specific measures such as the tax implications of share buybacks, the evaporation of indexation benefits, and the increased scope of TDS necessitate a more thorough impact evaluation.

The Society conducted two distinct Public Lecture Meetings on (i) Direct Tax Provisions under Finance (No. 2) Bill, 2024 by Shri CA. Pinakin Desai and (ii) Indirect Tax Provisions under Finance (No. 2) Bill, 2024 by Shri CA. Sunil Gabhawalla, both lectures were very well received and viewed in large numbers. The coveted and unbiased BCAS Budget Analysis is open for ordering and do order your copies soon.

Viksit Bharat

In the session before Union Budget Day, the Economic Division of India’s Department of Economic Affairs, Ministry of Finance, presented the Economic Survey 2023-24 at the Parliament. The Survey largely reflects the robust condition of the Indian economy but openly recognises the distinct challenge that India’s journey towards a developed nation by 2047 represents, compared to China’s ascent from 1980 to 2015. It points out 4 (four) challenges being de-globalization, geopolitical shifts, climate change and artificial intelligence as potential obstacles to maintaining high growth trajectory for India in the forthcoming years and decades.

Each of us holds a share in our progress towards Viksit Bharat, and being members of the intellectual community, it is our responsibility to express our opinions and set forth our views for its development. Our Society has begun a quest to capture the perspectives of varied stakeholders with distinct interests to further define the concept of Viksit Bharat. By organising multiple roundtable discussions as part of its outreach efforts, our Society aims to synthesise these insights into a research paper, which will then be shared with the decision-makers within the Government. Last month, two round tables were conducted, (i) with stalwart Chartered Accountants and (ii) with Chartered Accountancy students and management students, with more discussions being lined up towards this important initiative.

Our Society extends a hearty congratulations to the 20,446 Chartered Accountancy pass-outs and warmly welcomes them into our community. The future looks bright for India and our profession, and we wish them a satisfying and successful professional journey ahead.

Collaboration with BIA

Building upon our agenda to collaborate with peers, our Society has formalised a collaboration with the Bombay Industries Association. Both organisations have had a history of working together, and this formal collaboration outlines a unified strategy for future joint efforts.

In this special Industry:Profession partnership, both organisations, with 75 years of rich history, will combine their resources and capabilities to reinforce the economic structure of Mumbai, Maharashtra, and India. This includes collaborative learning opportunities, advocating for ease of business, offering policy suggestions, and engaging members from both groups.

In closing, I am profoundly thankful for the faith placed in me to serve as the 76th president of the Bombay Chartered Accountants’ Society. Sincere gratitude to CA. Chirag Doshi for his exemplary leadership during the important 75th year of the Society.

Best wishes for the festive season and 78th Independence Day!

Union Budget 2024 – A Step Towards Viksit Bharat

The Finance Minister, Smt. Nirmala Sitharaman created history on 23rd July, 2024 by presenting the 7th Union Budget in a row. This was also the first budget of the 3rd term of PM Narendra Modi-led government, and therefore, it attempts to lay a road map for the next five years. The budget has identified 9 priorities for sustained efforts towards ‘Viksit Bharat’. In each of the priority areas, sizable allocations are made, and various schemes are announced to achieve the goals. The government must be complimented for keeping the fiscal deficit in check and clearly listing priorities which will keep the growth momentum high.

The budget claims to focus on employment, skilling, MSMEs, and the middle class. Let’s look at some of these focus areas:

THE MIDDLE CLASS

The general perception of the middle class is that the budget has not given enough to them and, in some sense, taken away more than giving. Various schemes announced by the government are beyond the reach of the middle class due to various conditions attached and red tape. Some of the longstanding expectations of the middle class include restoration of travel concessions to senior citizens, exemption of dividend income/long-term capital gains, higher deductions for school fees paid for children’s education, increased standard deductions for salaried employees (at least to take care of their necessities), availability of cheaper credit for homes, good medical facilities at reasonable rates etc. In short, the middle class wants a dignified life and “ease of living”.

INDIA’S MITTELSTAND1

MSMEs constitute 30 per cent of GDP, 45 per cent of manufacturing output and employs 11 crore people2. MSMEs have played a key role in some of the major economies of the world. The budget has announced various schemes, increased allocations and measures for MSMEs. However, the MSME sector continues to face extensive regulation, compliance requirements and significant bottlenecks in funding. “Licensing, Inspection, and Compliance requirements that MSMEs have to deal with, imposed particularly by sub-national governments, hold them back from growing to their potential and being job creators of substance”.3


1. Mittelstand commonly refers to a group of stable business enterprises in Germany, Austria and Switzerland that have proved successful in enduring economic change and turbulence. It is usually defined as a statistical category of small and medium-sized enterprises. [Source: Mittelstand - Wikipedia]
2. Invest India, 2023 (https://tinyurl.com/56393ekz)
3. Economic Survey 2023-24 – Page 159-160

EMPLOYMENT AND SKILLING

India’s workforce is estimated to be nearly 56.5 Crore, of which more than 45 per cent are employed in agriculture, 11.4 per cent in manufacturing, 28.9 per cent in services, and 13.0 per cent in construction4. According to UN population projections, India’s working-age population (15-59 years) will continue to grow until 2044, and for that Indian economy needs to generate nearly 78.51 lakh jobs annually in the non-farm sector to cater to the rising workforce. This will require faster job creation in the non-agriculture sector as the agriculture sector has a lot of disguised employment with low productivity. The alarming facts revealed by the Economic Survey suggest that “Sixty-five per cent of India’s fast-growing population is under 35, and many lack the skills needed by a modern economy5. Estimates show that about 51.25 per cent of the youth is deemed employable6.” In other words, almost 50 per cent of graduates are not employable.


4. Ministry of Health and Family Welfare
5. Helping India build a skilled, inclusive, workforce for the future, World Bank, 2023 (https://tinyurl.com/2tp4xpab)
6. Economic Survey 2023-24 – Page 158

The government is aware of the massive challenges listed above and addressed some of them in the Union Budget, which has many balancing provisions. Many macro-level provisions will further accelerate India’s economic growth and take the country forward towards Viksit Bharat. The private sector and NGOs in social sectors will have key roles to play in addressing some of these challenges.

Turning to the provisions of the Finance Bill 2024, there are mixed responses. Some provisions are good, while some are harsh and need reconsideration. Reduction in the holding period to 12 months from 36 months for qualifying as a long-term capital asset, in respect of a unit of a unit of a REIT / INVIT on which Security Transaction Tax has been paid, is a welcome proposal. An increase in the limit and scope of disclosure of any movable foreign assets under the Black Money Act by a resident individual in Schedule FA of the income-tax return will give some relief to taxpayers. It is important to note that the penalty of ₹10 lakh for failure to disclose the foreign asset is very harsh, as the Assessing Officers are levying separate penalties to each spouse in respect of joint investments and for every year of non-disclosure. Some more concession in the amount of penalties in genuine cases of lapses and joint holdings is the need of the hour. Clarification on tax incidence on gifts by companies will reduce litigation and stop aggressive tax planning. The abolition of the angel tax will give much-needed relief to start-ups and unlisted companies. The reduction of tax rates for foreign companies by 5% is also a welcome change.

However, there are some hard-hitting proposals as well.

REVAMPING OF CAPITAL GAINS

Withdrawal of the indexation benefit for long-term capital gains is viewed as one of the harshest proposals. Even though the impact is sought to be reduced by lowering the tax rate to 12.5 per cent from 20 per cent, there will be some loss to the taxpayers. Moreover, there is no surety that the rate will not be increased in future.

The amendment sought is retroactive in nature, as it will take away indexation benefits for all existing properties. This amendment may encourage understatement of consideration. Over the past decade until 2022, consumer price inflation in India averaged 5.5 per cent7. Indexation is necessary to adjust the reduction in the value of the rupee every year. It is suggested that the proposed amendment may be reconsidered or modified.


7. https://www.focus-economics.com/country-indicator/india/inflation/

It may be noted that non-residents are better placed as no change is proposed to the 1st proviso of section 48 whereby they will continue to get the benefit of computing capital gains on the sale of shares and debentures of an Indian company in the same currency in which original investment was made, which usually takes care of the impact of inflation and changes in interest rates.

BUYBACK OF SHARES

Gross consideration from the buyback of shares is proposed to be taxed in the hands of the shareholder as dividends, and the cost of shares is to be treated as capital loss. This provision needs reconsideration as it will deprive taxpayers of claiming the cost of acquisition if there are no capital gains to offset losses, besides the adverse impact on cash flow due to timing mismatch and the differential tax payable on artificial classification as dividends and capital loss. Alternatively, the cost of acquisition should be allowed as a deduction from the buyback consideration taxable as dividends.

TDS BY PARTNERSHIP FIRMS UNDER SECTION 194T

A TDS @ 10 per cent is proposed on partners’ salaries, remuneration, commission, bonus and interest. No rationale is given for this amendment. This provision will further increase the compliance burden for MSME firms.

When one looks at the Budget Proposals, one gets a good feeling of macro measures towards a ‘Viksit Bharat’ – focus on MSME, Infrastructure, Ease of Doing Business, etc. However, when one looks at the proposals of the Finance Bill, one finds that there is no change in the trend of tinkering with well-settled provisions, retroactive amendments, nullifying court decisions in favour of taxpayers, and increasing tax compliances. Taxpayers are often at the receiving end in complying with TDS provisions, where instead of being rewarded for services to the government, they are penalised even for a venial breach.

May we expect some positive changes while passing the Finance Bill 2024?

Individually and collectively, let us commit ourselves to contribute our might towards ‘Viksit Bharat’ to provide a better and brighter future for our children.

I wish a happy 78th Independence Day to all our readers!

68th Annual General Meeting on 6th July 2017

The 68th Annual General
Meeting of the Society was held at the Garware Club, Churchgate, Mumbai on
Thursday, 6th July 2017.

CA. Chetan Shah, President of the
Society, took the Chair. Since the required quorum was present, he called the
meeting in order. All businesses as per the agenda given in the notice were
conducted, including adoption of accounts and appointment of auditors.

Mr. Suhas Paranjpe, Treasurer
announced the results of the election of the President, Vice President, two
Secretaries, Treasurer and eight members of the Managing Committee for the year
2017-18. The names of members as elected unopposed for the year 2017-18 were
announced. He also announced the names of the co-opted members for the year
2017-18.


Later, the “Jal Erach Dastur
Awards” for best feature and best article appearing in BCAS Journal during
2016-17 were announced. The winners were: Dr. Anup P. Shah for the best
feature, and CA. Gautam Nayak/ CA. Pradip N. Kapasi for best article.

The Special GST issue of the
Journal of July 2017 exclusively on “GST Features” and BCAS Publication Audit
Checklist- 7th Enlarged Edition-July, 2017 were released at the
hands of Hon’ble Minister of State (IC) for Power & Renewable Energy Mr
Piyush Goyal at the 69th Foundation day of the Society celebrated after the
Annual General Meeting of the Society.

At the end, guests including Past
Presidents of BCAS were invited on the dais to share their views and
experiences about the Society.

Outgoing President’s Speech

My colleagues on the dais, Past
Presidents, Ladies and Gentlemen, Good
Evening members!

This is Spencer West.

There aren’t many people in the
world like him. At the age of five, he tragically lost both his legs. But the
Canadian-born 31-year-old defied all the odds and climbed Mt. Kilimanjaro! This
is a story of determination, courage, focus, perseverance and hard work. A
story of months of intensive training to overcome extreme physical pressure.


What caught my eye is the message
on his T-Shirt – “Redefine Possible.” At BCAS, as we gather here on our
Founding Day, I believe we too have lived this motto. As a group of dedicated
volunteers, driven by a vision, have travelled a long way to reach this …
Founding Day. So many people here, including my colleagues on the Dias, have
overcome situations when we were up against the wall and we persevered, when
there were moments of frustration and we showed temperance, things often seem
to take longer than they should have but we firmly stayed the course. So many
have given their personal and family time and made these years and particularly
the last one year fruitful for members. As I stand here on my last day as the
President I can say that as we surmount we now have the confidence to DREAM
BIGGER!

Having said that I would like to
walk you through “The News this Year,” and to make it a little more
interesting I am going to give it a sports flavor.

So,
let’s start at the beginning of the 67th Annual General Meeting in July last
year…when I was handed OVER the torch, I chose to adopt a theme which was close
to my heart to be our guiding light for the year ahead. The theme was “Today’s
Vision, Tomorrow’s Reality.” The wisdom contained in these four words were
influenced by the famous twentieth-century poet, painter and philosopher Khalil
Gibran. He said, “We are not limited by our abilities, but by our vision.” And
I realized that we need to focus on developing a powerful, telescopic vision at
BCAS, rather than merely looking at our combined abilities.

To best understand how we
proceeded with the task ahead, let us look at the athlete who throws the
javelin. After scanning the vast sky above and the distant horizon, he throws
the javelin with all his arm and body muscles working seamlessly.

At BCAS, we embarked on the task
of discovering where we want to go…and identifying what route should we take to
get there. We met on many occasions in managing committee, other core
committees and with past torch bearers to draw up a suitable game plan. In the
process of planning, we gauged several untapped potentials and even pinpointed
any possible pitfalls. Some of the key points that emerged at this stage were:

•    Harness technology to enhance
access to BCAS

•    Explore new opportunities for
members to learn

•    Consolidate presence on
national front

•    Organize programs at the
doorsteps of  outstation members

•    Engage with related bodies to
multiply reach

•    Encourage and Empower students
to be future leaders and

•    Make crisp and effective
representations to ensure our voice is heard in the decision makers’ corridors.

With these findings, we moved to
the next phase where we gained insights from the world of basketball. We needed
to proceed ahead dodging several obstacles such as other commitments and
numerous time constraints. We also practiced more teamwork as we ‘passed’ the
assignment at hand to other members who were also better ‘positioned’ to take
it ahead. At this stage, we learned how to seize opportunities and move towards
implementation of the plans by getting logistics in place.

We
were now perfectly poised to take the LEAP (high jump) … SPRINT AHEAD (100
meters)…or take the PLUNGE (swimming)! And that’s what we did, moving swiftly
from one program to another is quick succession with high-quality deliverables.
And as you will shortly see they were all gold performances…and some more
golden!
Now let’s take a look at the
winners in no particular order!

Quantum Leap – Technology Edge

BCAS
took a quantum leap akin to long jump into the digital arena which was an
enabler to provide easy access to all members. Live streaming technology for
live webcast and posting of our programs on YouTube channel has been a boon to
our outstation and distant suburb members to view at their convenience.
Facebook and LinkedIn are increasingly used as a face of the  society for important updates. Payments can
be made online and our website has been revamped. An e-learning portal will be
launched shortly to extend training beyond geographic and time boundaries.

Hitting Bulls’ Eye – Experts
Chat

The
target questions by the moderators were pointed as in the game of Archery.
Experts Chat was a new game at the Society but Panelists, were veterans in
their knowledge reservoir, which was evidenced in their profound replies and it
developed into an excellent knowledge sharing platform. Six Experts Chat
sessions held this year command equal marks as they all drew increasing
attendance and viewership.

BCAS RRCs – Each RRC is like
20-20 Cricket Tournament where you learn so many subjects in a short span of
time.

The T20 matches was played at
various locations domestic and international. The Seminar Committee played at
Jaipur where the fiftieth edition of the RRC, the flagship program of the
society was conducted. It drew a record 275 participants from across India. The
International Taxation Committee played at Sri Lanka. The first time at an
international location was the ITF Conference. The Indirect Tax committee
played it at Pune with more than 330 participants. The Accounting and Auditing
committee played IndAS RSC at Silvassa. The MPR Committee played the Youth RRC
at Alibaug jointly with ICAI.

Each game was individually very
well played by all committees

Union Budget Lecture – Marathon
Run

The
Marathon run this year too was led by Senior Advocate Shri S.E. Dastur who
continued to wow the crowds with his powerful presentation. His detailed
analysis of the “Direct Tax Provisions of the Finance Bill, 2017” was a
remarkable run witnessed by 3,000 avid listeners at the auditorium, while over
10,000 watched it live from across India.

Besides
the RRC being played at various locations we chose not to play football within
BCAS but jointly with various other related organisations. Many joint programs
were conducted with other organizations to reach out to a larger audience in
Mumbai. Forum of Free Enterprise, Chamber of Tax Consultants, AIFTP, Indo-
American, ISME…were some of the organizations we worked with on these programs.
The game brought in a lot of cohesiveness in the game of the profession.

The reach of the Olympics was far
and wide this year. Members at various locations invited us to conduct programs
for the benefit of locals. To be more inclusive, BCAS reached out to its
outstation members with programs in Ahmedabad, Kanpur, Indore, Aurangabad and
Kolkata. Medals were in the form of increased membership and enrolment for
RRCs.

The novel concept of Inter
Committee Cricket Tournament was executed with thorough excitement and fun this
year.

To improve skill sets of its
members the society took up new initiatives. These are akin to introducing new
games to the Olympics. CAMBA a dedicated CA-MBA Course jointly with ISME was
launched to sharpen management skills and call the shots at par with MBAs in
the Society.

A Coach acts as a guide for every
sportsman (Virat Kohli may be an exception), anyway in the true spirit
of sportsmanship we continued the Mentorship program. 

As
the Society succeeded in playing different games and enhanced its reach, it
created its visibility which made Organisations to join as FRIENDS of BCAS. A
new concept where various benefits are extended
to members.

Role in Governance

The interaction by profession with
the government is like a game of tennis. There is always a rally between the
players which is healthy for developing good governance

The society made 16
representations to various authorities…some were made jointly with other
organizations. IDS, ICDS, Rotation of Audit Firms and GST were some of the key
issues the society took up with the government.

Welcoming Students

Sprint
run by the Society was for the benefit of students. The run involved in
mentoring and motivating students and felicitating newly qualified CAs. The
final dash was 10th Jal Erach Dastur Students Annual Day where
talent bloomed at its best and brought together over 250 students.

BCAS disseminated knowledge to
students at the NM College and HR college.

Useful Publications

BCAS brought out a record number
of 17 publications this year. Referencer was the bestseller with over 5,000
copies. But the blockbuster is the BCAJ July special issue with a print run off
over 16,000 copies which will be 
released today. There are two e-publications in Flipbook format that are
free for the members.

Education at BCAS

BCAS imparted knowledge through 40
Lecture Meetings with a total participation of 9,084 people, 58
Seminars/Courses/Workshops with a total participation of 7,065 people and a
record 110 study circle/study group meetings with a total participation of
2,552. These figures exclude thousands who have seen the videos online. This
enabled to add 943 new members and our social media presence augmented. More
statistics are in the Annual Report.

On attending many of these
meetings was itself a learning curve for me. But the Flip side is that by
attending so many meetings I have formed a habit of eating chocolates and
sweets sitting behind the desk.

BCAS Foundation

The
BCAS Foundation is the philanthropic expression of the society. Thank you,
members, for your large heartedness which enabled BCAS to collect more than Rs.
20 lakhs for the noble cause of improving pediatric cancer care to Tata
Memorial Hospital! With their generosity, we could contribute to the wellbeing
of 120 children suffering from this dreaded disease. However, we cannot rest on
the past laurels, and there is a lot we can do for such cause. I again exhort
all my fellow professionals to come forward and contribute each one’s might to
such a noble cause.

I now pass the baton to Narayan
Pasari, the new President of BCAS and the new core group members and office
bearers.  I will definitely continue to
stand and cheer for Team BCAS, in fact run along as we keep raising the bar and
setting new records.

It is time to say a big thank you to the entire
team that has worked so tirelessly and painstakingly to make this year’s
performance so eventful and if I might add…successful too!

Let me begin this ode of gratitude
by expressing my sincere thanks to the Past Presidents a few of whom were at
the helm of our nine sub committees. Their invaluable insights and vast reservoir
of experience are what keeps driving the committees to push the limits…and
excel. As Chairmen and Co Chairmen of the sub committees they have been a
beacon of inspiration, enabling the committees to grapple with many challenges;
and win!

Let us have a round of
applause for our hardworking though silent Chairmen and their amazing teams.

Next, I must thank my Managing Committee and the
Office Bearers who have diligently shared vital expertise and invested long
hours in planning and facilitating the smooth flow of programs and events of
the society. With all my heart, I thank ……

Narayan who has an eagle’s
eye for details that compliments his exemplary admin skills in ensuring our
numerous programs run flawlessly.

Sunil has demonstrated
credentials in the sphere of IT besides GST and has played a pivotal role in
the Society’s IT initiatives, particularly now he is engaged in the launching
of e-learning platform.

Suhas who as Joint
Secretary willingly devoted his time and eagerly participated with many
innovative suggestions.

Manish who as treasurer,
kept an eye on the numbers and helped all of us to stay in balance and
perspective.

Please join me in thanking them
with a round of applause.

Then
there is the incredible BCAS Team comprised of Jyoti Malkani who was with us
until April as GM; Shreya, Javed, Upendra, Nikhil, Rathi, Kamaljeet, Bilal,
Reema, Sachin, Baboo, Harish, Prakash, Mamta, Rajaram, yes, the entire team and
not to forget my office boys. A big thank you for your unfailing and unstinted
support in keeping the wheels of BCAS turning smoothly.

Last but not the least, I would like to thank all
my partners and my firm for backing me in my journey especially Abhay, whose
abundant wisdom and good judgment helped me to chart new routes in the face of
obstacles. And how I can forget to thank my wife for bearing my early exit and
late entry to our abode, but she was adequately cautioned by the PPs…

And
special thanks to all the conveners, coordinators, contributors, speakers, our
publishers Finesse and Spenta, sister organisations and asociations and well-wishers
who have together made BCAS shine bright this year too.

It
would be most inappropriate for me to end this speech by saying goodbye…because
goodbye sounds so final, almost like closing a door…or escaping to some remote
place never to see each other again. Instead, I would like to say Fare Well,
not as in one word, but as two words – Fare Well! Because I believe the road
for BCAS stretches a long way ahead…Yes, there will be bumps and curves to
navigate, but more importantly, there will be many milestones to cross and many
mountains to conquer. And so, to everyone at BCAS, starting with President
Narayan, the Chairmen & the managing committees and members, I wish you all
a heartfelt Fare Well!

Thank
You!

Incoming
President’s Speech


My President Chetan, Vice
President Sunil, Joint Secretaries Manish and Abhay, Treasurer Suhas, Respected
Past Presidents present and in absentia, Members of the Managing Committee,
Core Group Members and my dear friends

Let me start my innings by
remembering my father Late CA. R. G. Pasari whom I lost 5 years ago. He would
have been a really happy man today as he always pushed me into the BCAS
activities. This was because he had worked with the likes of S. P. Mehtaji, B.
L. Kabraji and others who always had the highest respect for BCAS. He also read
the BCA Journal regularly till his demise.

I recognize the presence of my
mother Smt. Parvati Devi who is the source of my strength after my father and
also other members of my family.

To reach at this prestigious
position, I also thank my principal Late CA. Mangalbhai Vatsaraj under whom I
completed my articleship, CA Pravinbhai Dharia 
(our auditor) and CA. B. L. Sardaji under whom I also took training post
my articles. Thanks is also due to the firms and the partners with whom I
worked during the last 2 and half decades. 

As far as BCAS is concerned, a
small peep into my journey so far would be in order today. I became a LIFE
MEMBER in 1990 and started participating in the activities thanks to two of our
Past Presidents CA Harish Motiwalla and CA Pradip Thanawala. I was inducted
into the Core Group of the Society in 1994-95 
and became a Committee Member in the Seminar Committee. I was appointed
a Convenor of this Committee in 1996-97 for the first time and have been an
integral part of this Committee for a fairly long time till I became a Office
Bearer under CA. Nitin Shingala. I served CA. Raman Jokhakar and CA. Chetan
Shah also during their Presidentship.
 

Before
I leap into the future with some of the many plans I have chalked out, I would
like to take time out to thank Chetan for his sincere and dedicated service as
President during the past year. It has been a tremendous learning experience
for me as I learnt not to get fettered or limited by a lack of experience or
ability. Instead Chetan always encouraged us all to think beyond and allow
vision to be the defining force in all our endeavors. In supporting Chetan over
the last many months I got invaluable exposure to multi-tasking and problem
solving.

So once again, let me welcome
and thank you all for coming here in such large numbers, and giving me this
opportunity to serve you as the 69th President of the BCAS.

We
are living in exciting times with considerable change happening both in India
and in the global arena. And these numerous changes provide an array of
challenges and incredible growth opportunities for all of us.

In
analyzing the Indian population we find it is comprised largely of young people
who are getting more and more literate and educated. They are also earning a
lot more than in earlier years and have greater disposable incomes. Their
buying power and consumption are playing a vital role in stimulating the
markets and growing the economy.

The Indian economy has defied many hurdles to cross
growth of over 7%. Stock exchanges have registered soaring indices and high
volumes of trading activity. Foreign Direct Investment is pouring in…in fact we
are the number one destination for FDI in the world, beating both United States
and China. Confidence in India’s economy is surging, thanks to the numerous
programs and reforms undertaken by the NDA Government with Prime Minister
Narendra Modi as its driving force.

Keeping pace with the phenomenal growth in the
Indian market are the vast array of services and products. And to ensure a
level playing field that’s fair and free, Indian companies have several new
laws and compliances to meet translating into enhanced business for all of us.
Globalization too is another stepping stone for all Indian companies keen on
getting more lucrative returns and a package of benefits. Here again as volumes
and diversity of exports grow, we have vast potential to harness greater
business.

As President, I have given myself
the task and responsibility of facilitating BCAS’ growth. I believe that if all
of us put an arm to the wheel, we can make BCAS a society that’s will be far
more recognized and respected within our profession and in financial circles.

Keeping this in perspective, I
have drawn up a plan that focuses on “Building Bridges”.

A bridge is a structure that is
built over an obstacle to provide connectivity. And building bridges is the
underlying theme of how I plan, with all of you, to take BCAS ahead!

Bridges connect us and help us to
understand each other’s challenges… they also enable us to figure out how we
can help each other and show that we appreciate one another. Building bridges
also helps to prevent isolation. Because isolation can breed prejudice,
misunderstanding, mistrust; and impede effectiveness of working together.

I propose four main bridges
and hope you will help me in building them and BCAS!

1. TRANSFORMATION

High on my list of priorities is
task of increasing the resources of BCAS and growing the membership list. I
believe the Society needs to be more visible in order to attract more members.
On the resources front too, we have to look at all possibilities of
capitalizing on the reputation and goodwill we already have. There is plenty of
knowledge and expertise within, which I think can be leveraged to enhance the
image of BCAS. With the shrinking of the world to a global village we need to
explore options to benefit from this trend.

Let’s move to a sincere wish I
have!

2. YUVA SHAKTI

The youth! They are our future and
they can be the catalyst of evolution in our Society. I look forward to
encouraging new blood to take up key roles. And to ensure that happens I would
like to implement special incentive schemes to get more youth to join BCAS.
Having done that I would also like to ensure they get more opportunities and
platforms to express their ideas and vision. Recently, I heard about the
concept of “Shadow Committees” and I would like to set up Yuva Shadow
Committees. These groups of young minds will think aloud fresh ideas and approaches
on the same challenges faced by the managing committee…and I hope it will lead
to some positive change. 

3. DIGITIZATION

Digitization is not a fad or a passing trend that
some companies or individuals flaunt. Digitization is essential…it has become the
need of the hour! With digitization we will be better empowered to manage our
resources and conduct our business. I look forward to digitizing as much as I
can of BCAS’ operations and resources. A good start has already been made in
this direction and I would like to add momentum to the entire process. In
addition to being able to disseminate knowledge, we would be able to translate
information into action more effectively.

Finally I
would like to tackle a relatively ignored activity of our Society…

4.
NETWORKING

Networking
is a mantra that is much advocated by many of the management gurus. At BCAS, I
feel we should work harder in this area. Be it the government, corporate or
fraternity level, we need to step up our efforts. I hope we will be able to
take some giant strides in this area by organizing some events to reflect the
“Start Up India and Digital India” initiatives undertaken by the government. We
could even re-look at some of events and tweak the format to include moments of
interaction and networking. Using our digitized resources and media, we could
reach out to a wider audience and serve the members better. BCAS could provide
more platforms in the form of events for networking among accounting firms.
Networking Power Summit is one format which could be organized more frequently
or modified to pave the way for greater networking.

These
are just some of my ideas that I have put together to set the ball rolling.
While I and my colleagues remain open to various suggestions and infact welcome
it, I would like to call upon each one of you to join us in this process of
transformation
of society to the needs of the present times by
mobilizing the power of yuva-shakti & digitization to build
bridges for expansion by creating robust networks.  I am sure I will continue to receive the same
love and affection from you in this very important journey of life.

Thank
You

Society News

fiogf49gjkf0d
Lecture meeting on Legal and Tax aspects of Trusts with special reference to REITs, INVSTs and AIFs on 17th June 2015

Mr. Dilip V. Lakhani, Past President of BCAS, addressed the audience in regard to special categories of Trusts. He also explained various structures and implications under Incometax thereon.

He highlighted the controversy around the status of the trust and the consequences of taxability of its income. In his view the status of the trust is dependent upon the status of its Beneficiaries. He drew attention to the fact that if the trust is revocable, then the income is taxable in the hands of the Settlor. He explained how trust can be an important tool for inheritance planning.

He further explained REIT structures and income tax implications on various parties to REIT. He expressed a view that capital gains tax on the sponsor in respect of transfer of the property through SPV to REIT is not exempt, but is deferred, which is one of the reasons for this structure not being popular in India. He mentioned a simple rule of taxation for income of REIT and its unit-holders:

INVSTs are similar to REIT.
Alternate Investment Fund: Finance Act 2015 has provided pass through status to only Category I [usually providing seed capital to start-up ventures] and Category II [usually providing funds to real estate] Funds, whereas Category III [usually have complicated, hybrid structures] Funds have not been granted such pass through status.

Mr. Dilip Lakhani’s presentation and explanation on private trusts with special reference to REITs, INVSTs and AIFs in a lucid manner was of immense benefit and was well appreciated by the audience.

9th Residential Study Course on Service Tax & VAT

Venue: Leonia Resort, Hyderabad
Dates: 19th June, 2015 to 21st June, 2015

Residential Study Course (RSC) is gradually becoming a very sought-after annual event of the BCAS considering the importance and the relevance of the subject in the current economic scenario. This year, the RSC was held at Hyderabad. More than 150 delegates from all over India participated and exchanged their knowledge and experience. In spite of heavy rains, water logging and delayed flights from Mumbai, all the participants made it to the RSC in time thus displaying their commitment to such an event. The Resort located on the outskirts of Hyderabad was a unique destination spread in sprawling greenery and natural rock formations with an ambience of luxury and warm hospitality.

Day 1 – 19th June, 2015
The RSC started in the afternoon with a group discussion on the paper titled “Case Studies on Taxation of Services” written by Advocate S. Thirumalai. The group leaders were CA Abhishek Doshi, CA Mandar Telang, CA Sudhir V. S. and CA Virendra Parwal. Case Studies on Valuation, Exemption, Point of Taxation and Place of Provision of Service were debated with active participation of all the delegates.

This was followed by the Inauguration Session – lighting of the lamp at the hands of Vice President CA Raman Jokhakar and the Chairman of the Indirect Taxes Committee – CA Govind Goyal. The Committee’s latest publication on “Service Tax – Basic Concepts and Procedures”, authored by CA Mandar Telang, was released at the auspicious hands of Advocate S. Thirumalai.

The inaugural session was immediately followed by the first technical session wherein Advocate S. Thirumalai gave his views on the case studies in his paper and also replied to other related issues raised during the group discussion. The session was chaired by CA Sunil Gabhawalla.

Day 2 – 20th June, 2015

The morning started with a group discussion on the paper “Case Studies on Cenvat Credit” written by Advocate L. Badri Narayanan. The group leaders were CA Leena Talathi, CA Nilesh Suchak, CA Sanjay Burad and CA Srikant Shenoy. The groups had a tough time completing all the issues in the paper as the subject was so vast and complex.


The second technical session was a presentation paper by Advocate J. K. Mittal on “Controversies in Service Tax”. In his inimitable style, he explained the controversies surrounding the Service Tax law, the contradictory judgments and challenges faced by the practitioners. The participants were left asking for more. This session was chaired by CA Sanjay Dhariwal.


In the third technical session, Advocate L. Badri Narayanan replied to the queries raised by the participants in the group discussion on his paper. He explained the complexities of the Cenvat Credit Rules and explained in detail so as to clear all the doubts of participants. This session was chaired by CA Uday Sathaye, Past President of BCAS.


In the evening, on the eve of International Yoga Day, a yoga session was organized under the guidance of CA Rajesh Kothari, Past President of BCAS. The response was overwhelming and on request of the participants, one more session was held on Sunday morning at 6 am.

Day 3 – 21st June, 2015

The morning started with a yoga session, it being the International Yoga Day.

The last paper for Group Discussion was of Advocate K. Vaitheeswaran on “Service Tax & VAT on IT, IT Enabled Services and E-Commerce Transactions”. The Group Leaders were CA Jayesh Gogri, CA Pranav Mehta, CA Samir Kapadia and CA Vikram Mehta. The case studies on the subject generated a lot of debate and fruitful participation.

During the fourth technical session, CA Jayraj Sheth presented a paper on “GST – Recent Developments & Expectations”. It was a wonderful presentation with facts and statistics about India’s progress towards GST. This session was chaired by Advocate Shailesh Sheth, who also shared his views on the subject.

CA Samir Kapadia, a member of the Indirect Tax Committee, made a small presentation on the initiative proposed to be undertaken by BCAS to prepare the professionals and the stakeholders to meet the challenges of new law on Goods & Services Tax (GST).


Thereafter, in the fifth and last technical session, Advocate K. Vaitheeswaran replied to all the queries raised by the participants. The paper writer’s exposure and his in-depth analysis made his talk very useful and interesting to the participants. He referred to various court decisions and explained the grey areas to the satisfaction of all. This session was chaired by CA Parind Mehta.

The RSC concluded with the Chairman of Indirect Taxes Committee CA Govind Goyal thanking all the paper writers, delegates for their co-operation and active participation, chairmen of technical sessions, the group leaders, all committee members, the BCAS staff, management of the Resort and all others who made this RSC a very successful event. He specially thanked the President CA Nitin Shingala and the Vice President CA Raman Jokhakar for their wholehearted support. Vice President, CA Raman Jokhakar thanked the Chairman CA Govind Goyal for his untiring efforts to make this RSC a memorable one.

After lunch, the participants departed to their respective destinations, cherishing the memories of the 9th RSC and with a promise to meet again next year at the 10th RSC.

Workshop for Independent Directors (in association with the National Stock Exchange of India) on 3rd July 2015

The Workshop for Independent Directors was inaugurated by CA Nitin Shingala (President), CA Kanu Choksi (Chairman), alongwith Mr. V. S. Sundaresan (CGM, SEBI) and Dr. V. R. Narasimhan (Chief Regulations, NSE)

Dr. Narasimhan gave the keynote address on the topic, citing some of the examples of mishaps in corporate world leading to stringent corporate governance norms being prescribed by the regulators. He mentioned that compliance requirements prescribed by law have arisen out of past experiences. Thereafter, Mr. Sundaresan gave a presentation on the expectations from the regulator’s perspective.

The Chairman mentioned that BCAS can conduct such workshops regularly, which can be recognised as a familiarisation programme for Independent Directors by the regulators.

Mr. Mahesh Athavale, Company Secretary by profession, appraised the participants about the duties, responsibilities and rights of Independent Directors. He shared some interesting practical experiences and case studies.

Mr. Mukund M. Chitale, Past President of BCAS, discussed the role of Independent Directors in an audit committee, board room dynamics and board evaluation. He shared his experiences as an independent director.

Practical issues faced by an Independent Director were discussed by a panel of Dr. V. R. Narasimhan (Chief Regulations, NSE), CA N. Venkatram, Mr. Madhu Bhagwat (Independent Director), led by CA Nawshir Mirza (also an Independent Director)

41 members took the benefit of the workshop. Participants were given ‘Certificate of Participation’ at the hands of the Panelists.

Monsoon Trek to Kothalighad on 11th July 2015

Human Development & Technologies Initiative Committee of the Society had organised a one day trek on Saturday, 11th July 2015 from Ambivali Village near Karjat to Kothaligad Peth.

The Trek was through thick jungle, close to nature surrounding the valley, and hills all around it. It got better as the trek reached greater heights. Considering that climate that day was favourable and cloudy with partial rain, the trek turned out to be enjoyable. Participants were high on energy and fully enjoyed the nature and were disciplined enough to be serious to the extent required for ‘safety’ and were environment friendly too. The 25 participants under the guidance of 3 experienced volunteers from Explorers & Adventurers Club completed the trek successfully. After the exhausting and enjoyable trek, the lunch at a small hotel at the base of Ambivali Village was lot more enjoyable. The return journey brought all back to the concrete jungle.

Lecture Meeting on Current Issues in International Taxation 15th July 2015

Mr. Pinakin Desai, the learned speaker for the lecture meeting held on 15th July 2015 covered various issues in International Taxation explaining various practical issues that one might face. The learned speaker commenced his talk with India-Mauritius DTAA, stating that the existing DTAA is under the process of negotiations and will undergo changes, resulting into a new revised DTAA which could be finalised in a couple of weeks. Then the speaker threw some light on the Black Money Act, 2015 which can have far serious implications on a Non-Resident becoming Resident and Ordinary Resident in India and explained the same with a few practical examples. Thereafter, the speaker drew attention to issues arising on indirect transfer of capital asset read in conjunction with Circular 04/2015 clarifying that the dividends declared and paid by a foreign company outside India in respect of shares which derive their value substantially from assets situated in India would not be deemed to be income accruing or arising in India by virtue of section 9(1)(i) of the Income-tax Act (ITA). Further, the speaker drew attention to the provisions of deemed international transaction by virtue of section 92B(2) of the ITA. Lastly, the speaker threw light on issues arising to foreign companies post amendment of section 6 of the ITA by the Finance Act 2015, which incorporated the test of POEM (Place of Effective Management) for determining the residential status of a Company. The lecture meeting ended after the speaker explained various issues as summarised above and their impact in practical implementation.

Society News

fiogf49gjkf0d
Lecture Meetings

Filing of Returns for AY 2014-15: Amendments & Precautions on 25th June, 2014. The meeting was held at the Jai Hind College Auditorium. The speaker Mr. Jagdish Punjabi, Chartered Accountant dealt with the various aspects of filing of returns of income and amendments applicable for the same. More than 600 persons including students benefited from the expert deliberations and knowledge shared by the speaker

Founding Day Lecture on ‘Discovering our Sweet Spot in Life’ on 7th July, 2014


L to R : Mr. Rajiv Vij (Speaker), Mr. Narayan R. Pasari, Mr. Raman H. Jokhakar, Mr. Nitin P. Shingala (President), Mr. Naushad A. Panjwani, Mr. Mukesh G. Trivedi, Mr. Sunil B. Gabhawalla

The lecture meeting was held at the Walchand Hirachand Hall, IMC. Mr. Rajiv Vij, Internationally acclaimed Life & Executive Coach based at Singapore addressed the Founding Day lecture. He explained on how despite all the success and economic growth there is still an underlying occurrence of unhappiness in one’s life and how we can deal with it and still discover a sweet spot in life. More than 200 members benefited from his talk.

Three books were released on this occasion:
1. G ita for Professionals – Second edition ( English and Gujarati) by Chetan Dalal was released by Mr. Y.P. Trivedi

2. T axation of Fees for Technical Services – a Referencer by Anil D. Doshi & Tarunkumar G. Singhal ; Released by Mr. Narayan K. Varma

3. FA Qs on Accounting Standards by Abhay R. Mehta, Ashutosh A. Pednekar, Atul H. Shah, Chirag H. Doshi, Jayesh M. Gandhi, Manish P. Sampat & Nalin M. Shah ; Released by Mr. Arvind H. Dalal

Direct Tax Provisions of the Finance (No. 2) Bill, 2014 on 14th July, 2014


L to R : Mr. S. E. Dastur (Speaker), Mr. Chetan M. Shah, Mr. Narayan R. Pasari, Mr. Raman H. Jokhakar, Mr. Nitin P. Shingala (President), Mr. Naushad A. Panjwani, Mr. Mukesh G. Trivedi, Mr. Sunil B. Gabhawalla (not in frame)

Mr. S. E. Dastur, Senior Advocate, addressed the annual lecture meeting on Direct Tax Provisions of the Finance (No. 2) Bill, 2014 at Yogi Sabhagrah. Nearly 2500 members packed the auditorium to hear Mr. Dastur and 2028 viewers joined the live Web Cast. All of them benefited from the masterly analysis by the speaker. The viewers were from over 25 cities across the globe including Singapore, Salem, Melbourne, London, Erode, Abu Dhabi, Lagos, Zurich & New Jersey.

Indirect Tax Provisions of the Finance (No. 2) Bill, 2014 on 16th July, 2014

The lecture meeting was held at the Walchand Hirachad Hall, IMC. Ms. Bhavana Doshi, Chartered Accountant and Mr. Vikram Nankani, Advocate addressed the audience on various aspects of Indirect Tax Provisions of the Finance (No. 2) Bill, 2014. More than 300 Members and Students benefited from the expert analysis and knowledge shared by the speakers.


L to R : Mr. Vikaram Nankani (Speaker), Mr. Sunil B. Gabhawalla, Ms. Bhavna G. Doshi (Speaker), Mr. Nitin P. Shingala (President), Mr. Raman H. Jokhakar

Indirect Tax Provisions of the Finance (No. 2) Bill, 2014 on 17th July, 2014

The lecture meeting was held at the Walchand Hirachad Hall, IMC Ms. Bhavana Doshi, Chartered Accountant and Mr. D. B. Engineer, Solicitor and Advocate addressed the audience on various aspects of Indirect Tax Provisions of the Finance Bill, 2014 at this lecture meeting which was held jointly by the Forum of Free Enterprise & Council for Fair Business Practices. The audience included many young Professionals and Senior Members of the CA Fraternity who gained immensely from the analytical insights given by the learned faculties.

Visit to Orphanage on 2nd June, 2014


Mr. Mayur B. Nayak and Ms. Gracy M. Mendes representing BCAS.

Human Resources Committee had organised this visit to Orphanage at Parel. The Orphanage has a total 22 orphans and is managed by 7 staff members. The visitors distributed snacks to the children. They had a walkthrough of the place and were also amazed by the entertainment items presented by the orphans who specially prepared the songs & dances for the Members visiting the orphanage.

Three-Day Residential Refresher Course (RRC) on Companies Act, 2013 from 27th June, 2014 to 29th June, 2014


L to R : Mr. Harish N. Motiwalla, Mr. Manish P. Sampat, Mr. Naushad A. Panjwani (President), Mr. Anil Singhvi (Keynote speaker), Mr. Kanu S. Chokshi


Group photograph of the participants


Mr. Naushad A. Panjwani

The Accounting & Auditing Committee had organised this RRC at Fariyas Resort, Lonavala, with an aim to equip the participants with an in-depth understanding on some of the important provisions of the Companies Act, 2013 along with Rules notified thereunder. The RRC was structured in an innovative manner of building case studies around critical provisions which were analysed in depth by the participants and deftly dealt with by the speakers.


Mr. Harish N. Motiwalla

The course commenced with the inaugural address by the President of BCAS, Mr. Naushad Panjwani. He was happy with the response received to the Course from all over India and was particularly pleased to have a strong participation from the Industry. Later, the Chairman of the Accounting and Auditing Committee Mr. Harish Motiwalla, gave introductory remarks on the design and structure of the course and the purpose of selection of the topics for group discussion as well as presentation. He also acknowledged the presence of the Chief Guest of the RRC Mr. Anil Singhvi. Then there was the lighting of the lamp by all the dignitaries present to commence the course.


Mr. Anil Singhvi

Mr. Anil Singhvi in his keynote address on “Corporate Governance and Independent Directors” shared his experiences as part of the Board of various companies as well from the research work carried out on the functioning of corporate and directors. He was of the opinion that the Companies Act, 2013 is a good piece of legislation and will improve the functioning of the corporate sector.


Mr. Sudhir Soni

After the inaugural session there was a group discussion on first paper of Mr. Sudhir Soni on “Case Studies on Provisions for Related Party Transactions/Loans/Investments.” The case studies were highlighting the provisions to be complied with as well as the contentious issues which arise in implementing the relevant provisions. During the presentation on his paper Mr. Soni aptly dealt with the case studies and also covered the issues raised during the group discussion in a very immaculate manner. The session was chaired by Mr. Kanu Choksi, Co-Chairman, Accounting & Auditing Committee.


Mr. Ashish Ahuja

The last session was a presentation on the topic “Cross Border M&A, Minority Buy-Outs, Exit Options, Rehabilitation, etc” by solicitor and advocate, Mr. Ashish Ahuja. He took the participants through a comparison of the of the provisions of the earlier act and the newly introduced provisions dealing with the protection of investor rights. Mr. Rajesh Muni, past- President of BCAS Chaired this session.


The second day started with a group discussion on the paper    by    Mr.    Nawshir    Mirza    on    “Case    Studies    on    Directors, independent directors, Corporate governance (incl. schedule V – managerial remuneration).” The case studies highlighted the onerous  duties of KMPS and  independent directors while steering the company as well as the role of Board towards various stakeholders. Later,     Mr.     Mirza,     made     a     presentation on his paper and shared his vast experience as a director as well as chairman of various committees of directors, which was of immense value to the participants. Mr. Kishor Karia Past Presidents of BCas chaired this session.

In the evening, there was a presentation on the topic of “audit and accounting (incl. schedule  ii and  iii)” by Mr. Mukund m. Chitale. It was a session that will be remembered by each participant for a long time, as he dealt with the subject with his expertise in such depth that he dealt with the queries of the participants while he was going through the clauses in the act. The session was addressed by him for nearly three hours and was ably chaired by Mr. Arvind H. Dalal, a past-President of the BCAS.

The last day commenced with group discussion on paper by Mr. K. Sairam on the topic “Case studies on acceptance of deposits and CSR.” Mr. K. Sairam had circulated to the participants background material also along with the case studies.  his case studies covered all the     finer     and     contentious     aspects    which require attention as professionals and were debated in depth during the group discussion. He later addressed the  participants in the general assembly along with a presentation on the topic and also dealt with the queries raised by the participants during the group discussion. The session was chaired by the Vice President Mr. Nitin Singhala.

The concluding session was presided over by  Mr.  Kanu Choksi.  he acknowledged contribution of the faculty as well as active participants for the success of the RRC.  Some of the participants gave their views on the course and conveyed their satisfaction of the format and  structure of the course.

Jal Erach dastur Students Annual day on 28th June, 2014 – A Report

The Jal Erach Dastur students annual day is an event that is organised by the Bombay Chartered accountants society (BCas) every year.  This year the event celebrated its 7th anniversary at the navinbhai thakkar auditorium at Vile Parle (east).

This is organised by the student members of BCAS for the CA students. This platform enables CA students to come together and interact with each other.  The event commenced with a short prayer sung by the student committee members followed by the anchors introducing the honorable Chief guest, Dr. Bhaskar das, CEO of the Zee group. The chief guest inaugurated the event with the lamp lighting ceremony and spoke to the CA students at length on the importance of communication in today’s corporate world and answered the queries that the students put forth. He emphasised on the difference between volition and motivation. According to him, volition comes from within, whereas, motivation comes from without and therefore the former is more important in life than the latter. The President of the society, Mr. naushad Panjwani, welcomed students and advised them for the balanced growth in life. The Chairman of the Human Resources Committee, Mr. Mayur Nayak, delivered his address on “dare to dream.”  In his short speech, he emphasised on the need to dream big. Miss Priya  Nangalia introduced  Mr.  Narayan Varma, the Past-President of the BCAS and an ardent supporter of the students’ activities, and showed his message through a video clip as he could not remain present due to his ill health.

Mr. Raj Khona and Mr. Smith Madlani enlightened students about various students’ activities such as study Circle, monsoon treks, sports day, etc. thereafter,  a small skit was performed by students on the theme of “jan andolan”.  Post this,   the “Chandanben manganlal Bhat  elocution Competition” was  held    where    finalists    of the    elimination    round    battled    it    to    win the  coveted trophies. in the tea break, the students feasted   on the delicious  mumbai vada pav along with a cup  of tea/coffee.

The    post    break     session    witnessed     the    most    awaited    quiz round. The four selected teams from the eliminations competed    with    each    other     in    a    very    heated     time-bound    quiz    competition.    The    finalists    were    on     their     toes    while    answering    mind    boggling questions. the audiences also actively participated in     the    quiz.    The     football    scoring    approach    adopted    by     the quizmaster,    Mr.    Aashish    Fafadia    was    an    instant    hit    amongst    the    audience.    The    quiz    was    ably     scored    by    Miss    Dhwani    Shah    and    Mr.    Rajesh    Pabari.    On    completion    of     the    quiz,    a    short      audience round was held by Mr. Harshil mehta and other   students’ Committee members. The audience was in splits with most of them participating very enthusiastically and lifting up the spirits.
 
The much awaited talent round was next on the list. Nineteen     finalists     competed     with     each     other     in     various     fields    like singing, dancing and playing instruments. With the end of this round, the judges of the talent round performed and mesmerised the audience with their singing and   instrumental music.  The winners of the various contests held,  i.e.,    Elocution,    Quiz,    Essay    Writing    Competition    and    the    Talent    Show    were    distributed    prizes    and    certificates    and    were felicitated for their performances.

The entire show was very ably anchored by Mr. Pawan shukla and miss Aneri Merchant. Mr. Raj Khona was felicitated for securing highest number of registrations. Mr. Chintan shah, Mr. Raj Khona and Mr. Smith Madlani’s efforts were recognised for coordinating students’ study circles during the last year. Mr. Samarth Patil proposed the vote of thanks to Mr. Sohrab Erach Dastur for sponsoring the annual day in fond memory of his brother, the late Jal Erach Dastur, the family of the Chandanben manganlal Bhat for sponsoring the elocution Competition and all those who had contributed to making the programme a success. In all, 366 students registered for the annual day. The motto of the event – to gather CA students on a single platform to showcase their talent and their extra-curricular
skills was very well achieved.

65th Annual general Meeting, 7th July 2014,   Walchand  Hirachand Hall,   4Th FlOOR,    Indian    Merchants’    Chamber, Charchgate, Mumbai 400 020

The 65th annual general meeting of the Bombay Chartered accountants’ society was held on monday, 7th july 2014, at  Walchand  hirachand  hall,  4th  floor,  indian  merchants’ Chamber, Churchgate, mumbai.

Mr. Naushad A. Panjwani, President of the society, took the Chair. All items as per the agenda given in the notice were undertaken including adoption of accounts and appointment of the auditors amongst other things.

Mr. Mukesh G. Trivedi, hon. joint secretary, announced the results of the election of the President, the Vice President, two secretaries, the treasurer and eight members of the managing Committee for the year 2014-2015. Mr. Mukesh G. Trivedi announced the names of the following members as elected unopposed for the year 2014-2015. also, the names of co- opted members and ex-officio members were announced. the “Jal Erach Dastur awards” for best feature and best article appearing in BCas journal during 2013-14 was announced. the winners were: Bhavesh dhupelia, shabbir readymadewalla, Vijay mathur for the feature on auditing standards. Ankit V. shah and Tarunkumar singhal for the article on Powers of the tribunal to stay demand beyond 365 days.

The special edition of the journal july, 2014 on “future of india youth’s Perspective” was released at the hands of mr. arvind h. dalal, past-President of the society. the editor, mr.anil j. sathe, announced that this edition has six special articles namely “imagining india from the eyes of young Pro- fessionals”, “Gazing Through the Crystal Ball”, “Reinventing india – a youth Perspective”, “arbitration Law in india – the Way forward”, “my india” … a decade from now …” and “to- wards a healthy india.” the youth of the society who had contributed articles to this edition were felicitated by being given the special edition.

Thereafter, the outgoing and incoming Presidents, mr. nau- shad A. Panjwani & Mr. Nitin P. Shingala respectively, addressed the members.

Outgoing  president Naushad Panjwani’s speech

Incoming President, nitin shingala, all my colleagues on the dais, respected past presidents, seniors and friends.

As i stand before you for one last time as the President of BCAS, i have an option on what i speak for the next ten minutes or so. I can either spend time thanking a lot of people who i should and want to and will. Or i can give advice to the incoming team, which i shouldn’t and i won’t. and even if i did where will they listen to me. did i listen to deepak’s advice? or i could list out all the activities that were carried out by the team in the year gone by, which i don’t want to do. It’s a team achievement and i cannot stake credit or seek accolades.

What i would like  to do is to compliment  the entire  team  of managing committee members,  chairmen,  co-chairmen, convenors, coordinators, core group members, the youth group, Cassem and the other staff of BCAS and shrutika. My special gratitude to the spouses of the core group members for getting involved in many BCAS programs. I request you to help me thank all of them by applauding the splendid work done by the team. having thanked others’ spouses, if i did not thank my own spouse, mere achche din khatam ho jayenge. so thank you afsheen for your support and understanding.

I couldn’t have asked for better office bearers. And as the events of the year transpired, i saw how each one of them stood up to take charge of the challenges on hand. Showing great grit, determination and character.

Nitin, I thank you for being my confidant. Your ever smiling demeanour eased so many pressure situations. you are a Trupt aatma and i pray that you remain so forever. under your leadership BCAS will scale new peaks. They say that you must learn from the foolishness of others and nitin, for that, i am ever at your service.

Raman, your suggestions in crunch situations were like a ray of light or as they say in sanskrit – Rashmi.

Chetan, was ever so cool and he faced everything with so much Sheetalta.

Mukeshbhai, thank you for bringing so much passion and Bhavna in everything you did.

Congratulations to narayan and sunil for joining the A-Team as the new secretaries.

This year, we lost two past-Presidents in Mr. B V dalal and Mr. Navin Kishnadwala. Both have contributed immensely to the society and we will all miss them.

My transition from a practicing CA to a business leader happened when i was the secretary of the society in 2006. I soon realised that the work pressures and timings are so different that I forget being an office bearer, even contributing otherwise is so challenging. That was the reason that i kept shirking this responsibility for some time. as most know, i accepted the challenge to lead BCAS at the behest of narayan Varma and a few others. But once i got into the mindset, the support that i received from all gave me new wings.

Jab aapka hukm mila toh maine tarq mohabbat kar di, Dil magar uss pe woh dhadka ke phir qayamat kar di.

I have thoroughly enjoyed my year as president of BCAS. I have gained a lot in the process. The president’s page received a lot of accolades and i am mighty pleased with that. But writing is something i have always been comfortable with. it is public speaking that i was absolutely paranoid of. So much so that i have goofed up even while reading from a prepared speech. i had to just look at Mr. Kishor Karia in the audience to know when i goofed up and know that i had to correct myself. But being president meant that mumbling or fumbling, i had to keep speaking at all events and slowly i found my fear disappearing.

Being on the dais along with various speakers i had the opportunity to observe their style and preparation. The one speaker who impressed me the most was Mr. N. P. sarda. in one of the talks on accounting standards, for which he spoke non-stop for about two hours and kept the audience spell bound, I was amazed to see that he had no books, no speech, no presentation or even any notes. all he had was a chit of paper with two words written on it. Obviously i was curious. after the talk i took a peek and saw what those words were. Those two words were Naushad Panjwani. That was the only thing he was probably not sure if he would remember correctly.

The theme for this year’s annual report is “time.” Fittingly, so. in the journey of time, the society has grown from strength to strength. the membership has consistently grown. the pro- grams have grown manifold. Every year so many new initia- tives are incubated. the society has kept inventing and reinventing itself constantly. Each President has contributed to this in his own way. To keep up with the needs of the time we have enabled a non-past president to be appointed as a co- chairman of a committee. And I congratulate Nandita Parekh for being the first such co-chairperson.

The youth group was formed this year and, as we have seen, has rejuvenated the core group. i am happy that most committees have now included a lot of youth members. To the youth i would like to say, be bold, be respectful and be effective. have your say. Don’t lose your exuberance. Be sincere but don’t be serious. have fun.

Zindagi Zinda dili ka naam hai Murda dil kya khaak jiya karte hai

Having covered all the important aspects i could end my speech here. But just a few minutes back i proclaimed that i am no longer afraid of public speaking, hence i would like to speak for a few more minutes.

Mandir ki taraf dur se naman kar lun, Ya buth ka aakhri nazaara kar lun, Kuchh der ki mehmaan hai jaati duniya,
Tauba kar lun ya Ek aur gunaah kar lun?

I would like to touch upon two areas which i think are necessary for the society to remain relevant in these times of google and youtube. Knowledge is available there too.

I have viewed our society as a matrix organisation. While on one hand we have our domain expertise like direct tax, indirect tax, international tax, accounts etc., on the other hand, we have the various categories of our membership like the practicing CA, members from industry, the CfOS, members Presidents, seniors and fellow members. it is a great honour to be bestowed with the responsibility of leading the Bombay Chartered accountants’ society, an institution that has a glorious past and strong foundation built through selfless contribution, dedication and perseverance of from Psus, the youth, the senior CA so on and so forth. We have tried to understand the needs of each constituent and attempted to design programs for each. this is the new service level expectation. We must continue to do this and in the years to come we will see the impact of this.

To be relevant we need to be heard in the corridors of power. this year we were fortunate that the union revenue secretary Mr. Rajiv Takru sought us out through Shariq Contractor and we had a great closed door meeting with him. But this is not enough. the society is a non-political voluntary body and makes representations on behalf of the general tax payers without any vested interest of any group or industry. We must reinforce our position as such. We must be visible. We must be effective. We must stop being shy.

Before assuming office, I had sought Rajesh Kapadia’s ad- vice and the only thing he said to me was “BCAS is a very prestigious organisation and the role of the President is a huge responsibility. As the flag bearer conduct yourself with dignity.” As I reflect on the year gone by, I hope I have lived up to his advice.

Tujh ko ruswa na kiya, khud bhi pashemaan na hue, Ummeed hai Ishq ki rasm ko iss tarah nibhaya humne.

As I step down today, I am satisfied and relieved. But the realisation has already sunk in that starting tomorrow I will join the august group of past presidents. The past presidents of BCAS have continued to contribute so much to the society and I am excited by the prospect of doing my bit. And for this I will have more than a year to do so.

Sitaaron se aage jahaan aur bhi hain, Abhi ishq ke imtehaan aur bhi hain,
Gaye din ki tanha tha main anjuman mein, Yahaan ab mere razdaan aur bhi hain.

Incoming President Nitin Shingala’s speech

President  naushad,  my  dear  colleagues  raman,  muke- sh, narayan, sunil, Chetan in absentia, respected Past its founders and successive leaders. i accept this responsibil-
ity with sincerity and promise to work, andto live up to the highest expectations! my team and i are committed to work ceaselessly and tirelessly to the serve interests of the BCas, pursue our vision and endeavour that the society continues to scale new peaks.

It has been a zestful year under Naushad’s leadership with the Society’s flag continuing to fly high. With style, vigour and his trademark innovative approach, naushad put into action several path breaking initiatives such as connecting with the youth brigade, the Cfos and senior chartered accountants, besides maintaining high standards for various regular activi- ties. While facing any crisis, naushad led from the front and pursued win-win solutions. my heartiest compliments to nau- shad for his memorable leadership and an excellent year!

Peter drucker once  said,  ‘a  voluntary  organisation  ex-  ists to bring about a change in individuals and in the soci- ety.’ in today’s fast paced life, a few questions  do arise:  Why volunteer? how does it help me? Well, i found the answer to these pertinent questions in the following quote by swami Vivekananda:

“Ask nothing; want nothing in return. Give what you have to give; it will come back to you – but do not think of that now, it will come back multiplied a thousand fold.”

Friends, I am one of the countless beneficiaries to whom  the BCAS has given back what we gave, multiplied a thou- sand fold.

The  Business  Consultancy  studies  (BCs)  course  during 1998-99 brought me closer to the BCAS. Soon, I was invited to join the Core group in 2000. This BCS programme conceptualised by shri Narayanbhai, Nandita and other seniors, changed the course of many lives including mine.

I have learnt and gained a lot during the last 15 years of being in close association with the BCAS. Seniors have welcomed me with open arms and made me feel a part of this magnificent family. I have gained so many endearing friends. In hindsight, i wish i could have become active in the BCas much earlier. As a member of the Core  group,  one  gets  an  opportunity to observe the seniors closely. I found them very gracious and easily approachable, ever ready to share their knowledge and help the juniors in overcoming their difficulties.

Pradyumnabhai and arvindbhai teach us that the quest for knowledge is a lifelong commitment. At the Company Law rrC held recently, i found arvindbhai and Kishorbhai amongst the participants, ever eager to learn new developments. this made me nervous. I felt I was not learning enough! Narayanbhai teaches us how to be innovative, think big and differently for the larger good and remain forever young. Pradeepbhai shah has been a great emotional support when trupti and i needed the most. he has been helping all of us to keep our hearts and emotions in the right places. my daughter, Parnasi too, is an ardent fan and admirer of Pradeepbhai! Learning from stalwarts such as Pinakinbhai sharpens our understand- ing of core subjects. each stalwart inspires and teaches us, in his own unique manner, the qualities and the abilities that an accomplished professional must cultivate and imbibe.

Consider this modern definition of a Professional in today’s context by subroto Bagchi, a noted management thinker and an entrepreneur. he says, “…to be a Professional takes more than just aptitude. It takes a commitment to doing what’s right, not only for your business, but for the society as a whole.”

My belief in the value system became stronger by observing these stalwarts adhering to the highest standards of ethics and values. the BCAS provides the right environment and impetus through selfless mentoring to chartered accountants to be outstanding professionals.

This mentoring at the BCas is important to members from all backgrounds. Members from small and medium practices get to learn from their seniors and can find support to grow. Members from large global firms get a collaborative and neutral platform to enrich themselves with academic pursuits. members from the industry get the opportunities to spruce up their knowledge and network. the value proposition that the BCAS offers is great. We need to ensure that this message is driven home, louder and clearer, to help spread the benefits widely. I look forward to the membership and Public relations committee led by naushad to pursue this with greater fervour.

While coping with complexities in the ever changing world and the resultant uncertainty, it is helpful to understand the elements that remain constant. nicole Baker, an american researcher  in  the  subject  of  futurology,  stresses  on  three such constants that capture the essence of our social fabric regardless of the time period:

•    the drive to explore;
•    the desire for interpersonal relationships; and
•    the need to make sense of the world around us.

I find the activities of the BCAS encompass each of the above elements and the annual plan for 2014-15, circulated to you, also underscores these elements. The plan focuses on ex- ploring new frontiers of knowledge, developing outstanding professionals, mentoring and fostering relationships, and con- tributing to the nation building. I am happy to outline specific thrust areas for the ensuing year.

•    Laws, Regulations and governance
India is in the process of modernising key corporate and tax laws. We must commend and support the government in this overdue exercise. However, the journey so far has been far from satisfactory with the legislature and the bureaucracy falling short. The experience with the Companies act 2013 and its implementation so far has been very agonising. even the drafts of the direct tax code have been heavily criticised.

While we have very  high  expectations  of  “acche  din”  from our Prime minister, narendra modiji, it must be re- alised that we need to grow beyond complaining and contribute proactively. In the presidential address last month, the new government has committed to participative governance and promised to engage directly with people in policy making and administration.

our Vision statement states that the BCas shall be the catalyst for bringing out better and more effective government policies and laws and clean and efficient administration and governance. It is thus important for us to step up the efforts. My team and I look forward to working with the Chairmen of various committees to ensure that we continue to make effective representations so and that our voice is heard.

a separate committee, ‘Corporate and securities Laws’ has been set up to focus on this area of growing importance.

•    Practice Management
The  accounting  industry  presents  a  fragmented  scenario where small and medium firms constitute a large number of practitioners. Low entry barriers, low switching costs for clients and high exit barriers are the main reasons for the fragmented nature of our profession. this can be countered by helping small and medium sized firms to network and grow and adapt to the best practices. the infotech and 4i committee has been conducting annual power summits for this purpose. My team and i look forward to the committee to build further and take up new initiatives in this area, including contributing to a regular column on this subject in the BCA journal.

•    CFOs and Corporate Members
The role of Chartered accountants in the industry has been expanding into leadership. It is therefore important to build further on our initiative to reach out to and connect with the CFOs in general and various specific industry groups in particular. My team and I look forward to working with various technical committees and the membership and Public relations Committee for specific programmes for this segment.

•    Youth Group
Today’s  youth  are  tomorrow’s  leaders!  I  am  sure  that  the membership and Public relations Committee led by naushad will give further momentum to this very important initiative in the ensuing year. I call upon each one of the youth group members to benefit from this gratuitous mentoring and look forward to them as our future leaders.

•    Students
The  students  are,  after  all,  our  future. The  HR  committee is doing excellent work in this area through innovative programmes. The professors in accountancy are a vital link to the students. many of us have been lecturers in the past. the BCas needs to connect with this community in a structured manner. Another brilliant suggestion has come from nandita that the BCAS should encourage the principals to sponsor their article students for short-term internships at various ngos and at the society itself. This will help the students to widen and deepen their learning and provide a holistic experience. My team and I look forward to working with the hr committee led by mayur and nandita on converting these excellent ideas into actions.

•    Technology
All aspects of our lives, profession included, are being impacted by the ever-changing technology. We must understand and leverage the relevant technology in conjunction with our core competencies, to deliver superior services. The infotech and 4i committee has been doing a lot of work in this area. I request Chairman ameet to ensure that the committee continues to address the growing requirements of the members.

The BCAS itself has been generally proactive in embracing the technology changes. recently, our revered BCA jour- nal embraced an e-avatar. Further, the team is working to build a revamped portal to improve knowledge sharing and connecting with the members. In addition, we will continue to explore various digital mediums such as WebtV to over- come distances in dissemination of knowledge and to extend the reach of our programmes.

•    Staff and office infrastructure
Our annual report carries an important statistic about hours of education the BCas delivers. the annual hours of educa- tion have grown from approx. 25,000 in the year 1993-94 to 38,000 in 2003-04 and in 2013-14, it was little over 132,000, an increase of over 500% in last 20 years. Our staff has been putting in very hard work and we must acknowledge it. At the same time the increasing workload and expectations are re- sulting in gaps in delivery. This requires us to strengthen the team and help them build their capacity through appropriate training. The improvement in office infrastructure, including systems and processes, is a continuous mission and we are committed to pursue excellence in this area.

It’s football time and my friend, Kuntal reminded me that i must refer to this flavour of the season. Courtesy of my son mohak, i am now a part of the growing football fan club in india. Even then, i could not take the accountant out of me. So I looked at how the role of a Captain is defined. The Football association, english football’s governing body, states that as a captain, you have no special status or privileges under the Laws of the game, but you do have a degree of responsibility for the behaviour of your team. I feel the same today, with one advantage. I have many more coaches to guide and support me.

Dhishat, my other good friend, has a different perspective. He says the role of the President is more akin to that of an orchestra Conductor whose primary duties are to unify performers, set the tempo, execute clear preparations and beats, and to listen critically and shape the sound of the ensemble.

Either way, the key leadership lessons from these two examples are:

•    One must surround himself with talent; and
•    One must play the game and play the notes through sheer hard work, discipline and commitment

I must say i have been fortunate to have loads of talent in our Core group. My team and i promise to play with hard work, discipline and commitment to continue building upon our rich heritage and leave a memorable legacy.

Thank you.

Society News

fiogf49gjkf0d
Study Circle on “International Economics” held on 30th May, 2016

1. BCAS – International Economic Study Circle had taken up the following subject for discussion: “How the Prime Minister’s dreams can assure 12% GDP growth for the next 20 years”. Mr. Rashmin Sanghvi, Member, made a presentation on the subject on 30th May, 2016. The speaker explained to the meeting that the PM had not made any claim about GDP growth. If however the dreams he had about the country were fulfilled, then in the speakers opinion India would achieve a GDP growth of 12%.

2. The presentation was circulated in advance to the members. In brief, he explained as under:

3. Prime Minister has more than 16 different dreams. These dreams are listed below:

Dream Projects: (1) House for every family by year 2022; (2) Toilets for every house; (3) Road Network; (4) River linking Projects; (5) Sea-coast Transport; (6) Employment for everyone; (7) Bringing Indian residents’ foreign wealth into India; (8) Smart Cities; (9) Infrastructure; (10) Digital India; (11) Mobile Banking; (12) Aadhaar – Related Banking; (13) Direct subsidies to Beneficiary; (14) Financial Inclusion; (15) Electricity for all; (16) Start-up India.

Mr. Sanghvi showed detailed calculations of how the execution of this dream can boost Indian GDP tremendously. At this stage, he clarified: “I am not a politician. I am neither a supporter/fan nor a critic of any politician. This analysis is a pure analysis by an accountant.”

4. The core themes are as under:

4.1 GDP Growth means increase in GDP :

India has half the population that does not get proper food, clothing, housing, education and medical services. Providing these to the people of India means – someone has to spend money. One person’s expenditure is another person’s revenue. As a nation, it is GDP.

4.2 Every expenditure by Government is Revenue for someone. The Revenue will attract, Excise & Sales Tax. Net profit in the revenue will attract income-tax. When money is created, there are multiplier effects.

4.3 India is blessed by nature. We have enough resources to provide for the whole population and more. We have resources. We have needs. Now what prevents us from matching the two? Need is converted into demand when the needy person has income to buy.

4.4 If we use all domestic resources and provide necessities for the whole country, for the next twenty years, we can have a continuous GDP growth @ 12% or more. In this presentation, only attempt is to show that India can continuously grow for next twenty years. Attempt is not to praise or criticize Government plans but to see if a practical way emerges for India’s growth.

4.5 Housing – Paradox.

Today, crores of people are without houses. And simultaneously, housing sector is in recession. Lakhs of flats are lying vacant, unsold, unleased. This is classic case of unbalanced market. Problem is, the builders want to build luxury and super luxury houses. They are not interested in low cost housing for the poor. And the cartel of Builders-Politicians and Bureaucrats has artificially jacked up the prices beyond the reach of the buyer.

5. The Study Circle considered following statistics:

5.1 As per census report of the year 2011, India’s population in the year 2011 was 121 crores. This population is growing annually at 1.82%.

The present homeless figure of 65 crore will grow @ 1.85% in the year 2022 to 80 crores., requiring 16 crore houses, which will be 2.66 crore houses per year, which will translate into a construction cost of Rs.9 trillion per year considering a house of 270 sq feet per household. Comparing the additional house construction of Rs. 9 trillion –with the present GDP of Rs. 134 trillion – there will be an additional growth in the GDP of 6.7%.

5.2 Construction Material:

Construction of houses requires additional production of cement & steel. At present, due to recession, many steel & cement plants are running far below their capacity. They are incurring losses. A substantial amount of increased production can come from better utilization of existing capacities. However, additional construction of require additional installation of capacities for cement & steel.

These two commodities are taken as an illustration. For a house construction, many other things are also required.

5.3 Transport:

This additional material will also require massive transport through railways & roadways. It will require fuller utilization of wagon manufacturing & truck manufacturing. We will also need to install additional capacities for manufacture of wagons & trucks, for laying railway lines and so on.

With detailed calculations, Mr. Sanghvi explained the multiplier effect of a single dream translating into massive economic expansion. When 16 dreams are attempted together, imagine the massive expansion possible.

This figure of Rs. 9 trillion additional GDP comes from only part of the first dream. That is enough to cause 6% GDP growth. When 16 dreams are taken together, there can be 12% GDP growth.

In fact, Central Government total budget including budgetary deficits is Rs. 16 trillion. Hence nobody can expect Government to spend Rs. 9 trillion on single dream. Forget total spending of 16 dreams.

The factor beyond accountancy & economics is that: when someone has dream to serve the society at large, and then does more than his best, help comes from unknown, unexpected sources and work gets done. Or, one can say that God Helps. And the dreamer goes beyond his dreams.

So far, no one in India had the courage to dream. This PM has several dreams. This itself is very important.

7. Revenue:

Increased GDP means increased incomes in the hands of the people and increased income-tax revenue for the Government. Increased production of steel, cement, etc. and sale of houses mean -increased excise and sales tax revenue – for the Government of India. By one estimate, out of the total GDP, Government gets 15% as tax revenue. To this extent, first year’s increased expenditure finances second year’s revenue.

8. Capital:

India is considered a capital deficient country. We need substantial import of capital. Present policy of Government of India & Reserve Bank of India encouraging depreciation of Indian rupee is causing substantial losses to the foreign investor. Both – GOI & RBI together must adopt a policy of stabilizing the rupee & causing annually 1% to 2% of appreciation of Indian rupee. Such a policy can cause massive inflow of capital into India. With such dreams the Indian economy can create a situation of sustained high growth in the economy, stabilization & appreciation of Indian rupee; and overall gross domestic happiness.

The study circle meeting concluded on a note of optimism.

Workshop on “Practice Management & Technology” held on 18th June 2016

CA Raman Jokhakar, President BCAS welcomed the participants. CA Nitin Shingala gave opening remarks for the workshop. CA Ameet Patel set the tone by highlighting relevance of the topic, need and concerns to be addressed on practice management in the changing era of time – realignment of human capital, a paradigm shift in the profession from auditing and tax practice to specialized service providers and niche services. He emphasized on the need to overcome the restraints, hindrances and obstacles and using technology to the advantage of the profession.

Session-1: Running a Niche PSF

Mr. Nishith Desai provided valuable insights on settingup and managing a professional firm. His concept of operating a ‘Nano Firm – Small Size, Big Impact’ was an exceptional element of his presentation. His session enabled participants to have one-on-one interaction with Mr. Desai and learn from the vast pool of experience he has to offer.

Session-2: Running a Niche PSF

Ms. Nita Menezes through the journey of their organization, explained how to deliver services to clients by emphasizing on risk reduction of clients and not only higher returns. She also explained the approach adopted by the organization – Plan, Process and Develop Product, deliver services for successful functioning and client satisfaction. She explained practical insights for SME firms to start, build and keep the firm aligned for growth.

Session-3 & 4: Aligning Human Capital

CA Vaibhav Manek explained the importance of aligning a firm’s human capital and the benefits derived thereof. He touched upon topics like partner revenues, employee attritions, utilizing individual’s strength to firm’s benefit, employee evaluation, compensation and benefits. .

This helped the participants to gain insights and better understanding on need to realign human capital, commanding higher fees and developing higher per partner revenues, niche practice development for concentrated efforts of specializing in service areas, consolidation of firms and its operations to become full service firms with partners focusing on specific service areas and sub-service areas.

Session-5: Tools for Practice Management

Mr. Debajit Roy explained the concept of iFirm, a tool for practice management and how it can be used to enhance firm’s practice in terms of technology, time and turnover.

Session-6: Technology for CA Firms
CA Rajeev Sharma touched upon IT enabled business trends for decades ahead and opportunities that can get generated due to technological developments; need to have cloud based/ semi cloud based outsourcing service. He took up few survey analysis reports and projections on advancements in technology, profession and services.

He also emphasized on tools for practice management in SME sector, Client Relationship Management Software for professional firms.

Session-7: Panel Discussion

CA Nandita Parekh, CA Ameet Patel & CA Nitin Shingala took up the panel discussion round for the participants where various topics and issues faced by practicing professional firms were addressed – How to grow and partner in a firm, challenges and opportunities of collaborating, taking new partners and expanding, necessity for defining strategy for professional firms, passing on leadership and retirement, to have compliance driven practices, use of technological advancements for better servicing of client requirements.

The overwhelming response from diverse spectrum of participants – practice, local and out station participants, BCAS members and Non-members showcased the interest in the subject cutting across wide spectrum of stakeholders. The workshop was attended by 95 participants.

CA Kinjal Shah proposed vote of thanks to all the speakers and participants for making this workshop a grand success.

Lecture Meeting on “Insolvency & Bankruptcy Code, 2016-Boost to ease of doing Business” held on 22nd June, 2016

A lecture meeting on “Insolvency & Bankruptcy Code, 2016-Boost to ease of doing Business” was held on 22nd June, 2016 at BCAS office which was addressed by Mr R K Bansal, Executive Director, IDBI Bank Limited. Mr Bansal explained about the meaning, importance and relevance of Bankruptcy Law in the present scenario.

He also deliberated upon the present procedure of Bankruptcy Law and told that before a company goes into liquidation, the debtors and creditors follow a complex procedure which involves the following:

a) JLF/CDR
b) SDR
c) SARFAESI
d) DRT
e) BIFR
f) Winding Up

In the present scenario, creditors extend the funding, restructure the debt but the entire process to achieve turnaround is solely dependent on the capability of the present promoters except in case of SDR where lenders search for a new promoter for the company.

He discussed about the measures to take the commitment from defaulting promoters i.e. marking the accounts as Special Mention Accounts (SMA and SMA2) where bankers form a joint lender forum with revival plan for Promoters who are unable to repay the debts, through restructuring of NPAs

He also enlightened about the proposed procedure to file a bankruptcy application with NCLT ( National Company Law Tribunal ) or DRT ( in case of Firms and Individuals). 

He further mentioned that one of the fundamental features of the Bankruptcy Code is that it allows creditors to assess the viability of a debtor as a business decision, and agree upon a plan for its revival or a speedy liquidation. The Code creates a new institutional framework, consisting of a regulator, insolvency professionals, information utilities and adjudicatory mechanisms that will facilitate a formal and time bound insolvency resolution process (1st stage of Bankruptcy) and liquidation (2nd stage of Bankruptcy). When insolvency process fails, the liquidation procedure comes into force where the assets of the debtor (including the proceeds of liquidation) vest in the liquidation estate. A total of 50 participants attended the meeting

The meeting concluded with a formal vote of thanks by Mr K K Jhunjhunwala

Overall the lecture was very informative and well appreciated by the Audience.

10th Residential Study Course on Service Tax & VAT held on 24th June, 2016 to 26th June, 2016 at Lavasa

The Indirect Taxation Committee (IDTC) of BCAS successfully conducted the 10th Residential Study Course on Service Tax & VAT , at Hotel Mercure and International Convention Centre at Lavasa, from 24th June 2016 to 26th June 2016.

This series of Residential Study Courses (RSC), which is fully devoted to the studies of indirect taxes, is becoming more and more popular among the members of BCAS. . The venue, Lavasa, located about 65 kms. from Pune, at a height of about 2100 ft. amidst the Shayadri Mountains, and the monsoon rains gave the perfect blend of nature and atmosphere for focused studies and fellowship.

A new feature, added this year, i.e. the concept of ‘group mentors’ received kudos from all the participants. The group discussions reached a high level of maturity and the knowledge sharing could become much more meaningful. The five ‘group mentors’ namely CA Ashit Shah, CA Bharat Shemlani, CA Naresh Sheth, CA Rajiv Luthia and CA Udayan Choksi provided valuable guidance to all the groups throughout the program.

Day 1 – 24th June, 2016

The RSC started in the afternoon with group discussion on the paper titled “Case Studies on Taxation of Services” written by CA A. R. Krishnan. The group leaders were CA Ankit Joshi, CA Anil Kumar Beewada, CA Mandar Telang, CA Manindar Kakarla and CA Nilesh Suchak. Case Studies on taxability of different services and various “live” situations faced by tax advisers on daily basis were articulated. Valuation, Exemption, Point of Taxation and Place of Provision of Service were debated with active participation of all the delegates.

This was followed by the Inauguration Session – lighting of the lamp at the hands of CA Dilip Sheth, a very senior member of the BCAS, President CA Raman Jokhakar and the Chairman of the Indirect Taxes Committee – CA Govind Goyal. The lighting of the lamp was followed by a brief key note address by CA Dilip Sheth.

Inaugural session was immediately followed by the first technical session wherein CA A. R. Krishnan (the mentor of IDTC) gave his views on the case studies in his paper and also replied to other related issues raised during the group discussion. His masterly analysis of various provisions of law and his guidance to participants on “thought process and the reasoning that should go while arriving at a conclusion’” will always be remembered by all those who participated in this RSC. The session was chaired by the president CA Raman Jokhakar.

Day 2 – 25th June, 2016

The morning started with the group discussion on the paper “Case Studies on CENVAT Credit” written by CA S. S. Gupta. The group leaders were CA Ganesh Prabhu Balakumar, CA Keval Shah, CA Shreyas Sangoi, CA Shruti Kakaria and CA Vaibhav Jajoo. The issues were debated since most of the issues had a variety of angles involved and had day-today relevance.

The second technical session was a presentation paper by CA Divyesh Lapsiwala on “Indirect Tax Benefits in Foreign Trade Policy”. In his inimitable style, he briefly explained the five most common schemes of the Government’s Foreign Trade Policy which can benefit the exporters i.e. (a) Export Promotion Capital Goods Scheme (b) Services Exports from India Scheme (c) Status Holders (d) Software Technology Park Scheme and (e) Special Economic Zone Scheme. This session was chaired by CA Hasmukh Kamdar.

In the third technical session CA S. S. Gupta provided solutions to the issues raised in his paper on case studies on CENVAT Credit. The issues were explained in details and also the new issues that have surfaced due to recent amendments through Finance Act 2016. This session was chaired by CA Uday Sathaye, Past President of BCAS.

The afternoon was free for the participants to explore the hill city of Lavasa, take a walk on the river side promenade and enjoy the wonderful atmosphere. In the evening a musical evening was organized “for the members by the members”. The members here got an opportunity to show case their hidden talents.

Day 3 – 26th June, 2016

The last paper for Group Discussion was written by by CA Parind Mehta on “Case Studies on Sale v/s Service – Composite Transactions (Taxability under VAT and Service Tax)”. The Group Leaders were CA Chirag Mehta, CA Samir Kapadia, CA Sanjay Dhariwal, CA Vikram Mehta and CA Yash Dhadda. The case studies highlighted certain very relevant issues which a transaction could have and were probably not even envisaged by many participants.

During the fourth technical session, CA Sagar Shah presented a paper on “Role of CAs in GST – Realignment Requirements”. A very crisp and brief analysis of how as a professional we need to gear up for the challenges as well as opportunities this new law will generate for Chartered Accountants. This session was chaired by CA Sunil Gabhawalla.

Thereafter, in the fifth and the final technical session, CA Parind Mehta replied to all the queries raised by the participants and also gave his views on the issues raised in the case studies. The reference material provided along with his paper listing out a whole lot of case studies would be a very useful to all the participants. This session was chaired by CA Deepak Thakkar.

The RSC concluded with the Chairman of Indirect Taxes Committee CA Govind Goyal thanking all the paper writers and delegates for their co-operation and active participation, chairmen of technical sessions, the group mentors, the group leaders, all committee members, the BCAS staff, management of the Hotel and the Convention Centre and all others who made this RSC a very successful event. He specially thanked the President CA Raman Jokhakar for his wholehearted support. The President CA Raman Jokhakar thanked the chairman, conveners and all members of IDTC for their untiring efforts to make this RSC a memorable one. A total of 175 participants attended the Study Course.

After lunch, the participants departed to their respective destinations cherishing the memories of the 10th RSC, with a promise to meet again next year at the 11th RSC.

IT STUDY CIRCLE WORKSHOP ON “SUPER ADVANCED EXCEL FOR PROFESSIONALS ’ PART III” HELD ON 28th JUNE, 2016

The Technology Initiatives Study Circle of the BCAS recently held a multi-session workshop on ‘Super Advanced Excel for Professionals’ by the learned speaker CA Nachiket Pendharkar.

Nachiket is a Microsoft certified corporate trainer for MS Excel and Excel VBA. He is the founder & CEO of ViN Learning Centre, a corporate training institute based in Mumbai. Nachiket was shortlisted in the top 30% candidates across the world in the Excel Model Off competition (a global competition on financial modelling using MS Excel) in their 2015 edition.

This was the third session of the series, held on 28th June 2016. The first two sessions were held on 24th May 2016 and 7th June 2016 respectively.

This third session covered unique topics such as Alternatives to nested if, Data Tables – multi variable simulations, ASAP utilities Add in, Table and Table Tools and Array formulae, Advanced features of Pivot Tables.

The session witnessed a large audience which saw good interaction between the speaker and the participants. The speaker answered a lot of queries that were posed by the participants. A total of 30 participants attended the Workshop. All participants have benefited immensely through these enriching sessions.

Lecture Meeting on “Model GST Law” by Shri Shailesh Sheth on 29-6-2016

BCAS organised a lecture meeting on 29-6-2016 on the Model GST Law at IMC. At a juncture when the fate of the 122nd Constitutional Amendment Bill is yet to be known and everyone is waiting for its passage in this monsoon session of the Parliament, on 14-06-02016, the Model GST Law was placed in the public domain by the government after the nod of the Empowered Committee. Shri Shailesh Sheth gave wonderful insights on the model law. The views of the speaker on the Model GST Law were commendable and a guiding force for all. The speaker in a nutshell described to the members present the various provisions of the model law and how the model law has been drafted as a mixture of the existing indirect tax laws like State Level VAT , Central Excise and Service tax. The meeting received an overwhelming response with the venue packed with around 250 audience.

The session ended with a vote of thanks to the speaker by Mr Chirag Mehta

Full day “Seminar on the Finance Act, 2016” with emphasis on Income Declaration Scheme held on 1st July, 2016

The Full day seminar on Finance Act, 2016 was held by the Taxation Committee at BCAS Gulmohar Hall. President Raman Jokhakar gave the opening remarks followed by introductory words from the Chairman of the Taxation Committee, Mr. Sanjeev Pandit.

Various topics were taken up at the Seminar by the following Speakers:

Mr Yogesh Thar: Provisions relating to The Direct Tax Dispute Resolution Scheme, 2016, Equalisation Levy, Residence & Chapter XXBC, Transfer Pricing, Return of income, Advance Tax, Assessment and Intimation u/s 143(1) and Provisions dealing with special rate of tax like 115BA, 115BBDA etc.

Mr. Yogesh Thar explained the important features of The Direct Tax Dispute Resolution Scheme, 2016 and Equalisation Levy. . He further discussed the provisions related to special rate of tax for certain companies under Section 115BA and Section 115 BBDA dealing with additional 10% tax on dividends in the hands of recipient. He also brought out various issues arising out of the above amendments and answered the queries of the participants.

Mr Rajesh Kadakia: Amendments related to Charities (with special reference to Chapter XII-EB), Immovable Properties (Sec. 50C), Capital Gains related provisions and Deduction of profits from housing projects of affordable residential units –Sec. 80IBA etc.

Mr. Rajesh Kadakia started his talk by highlighting the amendments relating to charitable institutions. He explained the intention and rationale behind the said changes and highlighted the effects of the same for the existing charitable institutions and their activities. He gave an insight into the provisions relating to Immovable Properties (Sec. 50C), Capital Gains related provisions and deduction of profits from housing projects of affordable residential units – Sec. 80IBA etc.


Mr Praful Poladia: Provisions relating to The Income Declaration Scheme, 2016, Presumptive Taxation and related provisions as to tax audit and maintenance of books of account, buy back of shares.

Mr. Praful Poladia started with case studies highlighting the amendments to Presumptive Taxation for persons engaged in business and profession and related provisions i.e. tax audit and maintenance of books of account. He also gave detailed examples in relation to amendments to buyback of shares and how it affects business structuring. He explained to the participants the new Income Declaration Scheme, 2016 and took them through three sets of clarifications issued by CBDT on the Scheme.

Ms Sonalee Godbole: Amendments in relation to Penalties (with special reference to Sec. 270A), Chapter VI-A deductions, Provisions relating to Income from Business & Profession (other than Presumptive Taxation), Income from Salary, Rules regarding Provident Fund, Income from House Property, TDS provisions
.

Ms. Sonalee Godbole gave a detailed presentation on amendments in relation to penalties (with special reference to sec. 270A), Chapter VI-A deductions, provisions relating to Income from Business & Profession (other than Presumptive Taxation), Income from Salary, Income from House Property and TDS provisions. The speaker touched upon a wide number of judgments during the course of her talk. She also answered all the questions raised by the participants.

There was also a session on Income Declaration Scheme, 2016 where the Principal CCIT Mr D. S. Saksena along with Pr. CIT – 1 Mr. D.C. Patwari addressed the participants about the features and procedural aspects of the said Scheme. They also answered the queries raised by the participants and were receptive to the clarifications sought by them. They told that the issues where clarifications are necessary would be forwarded to the CBDT for further clarification. They also asked the participants to make their clients aware of the scheme and assured that the details provided by assesse under the scheme would be kept confidential. Mr Patwari also briefly spoke about the Dispute Resolution Scheme, 2016.

The sessions in the Seminar were very interactive and the speakers answered a lot of queries that were received from the participants. The participants benefited immensely with the interactive sessions and detailed discussions with the speakers and Income Tax Department Officials. The event saw attendance by over 100 participants.

68th Founding Day Lecture Meeting on “Achieving Sustainable Profitable Growth on a Perpetual Basis” held on 7th July, 2016

A lecture meeting on Achieving Sustainable Profitable Growth on a Perpetual Basis was held on 7th July, 2016 at Walchand Hirachand Hall, 4th Floor, IMC, Mumbai after Annual General Meeting and Foundation Day of the Society. The meeting was addressed by Mr Harsh Mariwala, renowned industrialist and Chairman of Marico Limited. Through his vision and mission in mind, he is instrumental in maintaining Marico’s business at a sustainable and profitable growth pace.

He explained that the growth both in business and profession has to result in profits for associates, shareholders and stakeholders. He gave examples as to how he faced the key challenges in achieving and sustaining growth in his company which filters from top to bottom.

Further, the speaker took through the journey of Marico which was a family run business and how it was modelled to bring about value principles and policies to bring expansion and growth. He talked about his journey of culture building in the organization through involvement of its people and seeking commitment from them. He also emphasized the need of quarter to quarter performance to measure topline and bottomline growth.

The lecture was well attended by around 200 participants and got a thunderous applause from the audience. The meeting concluded with a vote of thanks by CA Narayan Pasari, Vice President, BCAS

Study Circle on Simple Techniques of “Yoga to Live Healthy” held on 8th July, 2016

A lecture meeting on Simple Techniques of “Yoga to Live Healthy” was held on 8th July, 2016 at BCAS, 7, Jolly Bhavan No -2, New Marine Lines, Mumbai-400020. The meeting was addressed by CA Dr. Kishore Gada, renowned practising CA since 1998, Convenor of Ghatkopar CA CPE Study Circle and also a Yoga teacher. He has authored 3 thesis on the topic Jainism and Yoga, which remarks his passion and interest for Yoga. Through his vision and mission in mind, he is instrumental in maintaining a proper work life balance with the help of Yoga and conveying this message to maximum people.

He started with a peaceful Yoga prayer and explained the true definition of Yoga that is a state of connection of body and mind. He then explained how various organs and various system of human body are connected to the spinal cord and brain and how wrong body postures while at work, studying, sleeping break the connection of mind and body.

Afterwards he travelled through the journey of meditation, breathing exercises and all practically experienced the power of “OM Mantra” to relieve stress.

Overall, it was a very refreshing and learning experience. Practical and simple techniques through which we can live happily without stress and fear were conveyed in the best possible manner and he got a huge applause from the audience. BCAS President CA Chetan Shah appreciated the efforts taken by renowned speaker and assured this lecture would be conducted at a larger scale for the benefit of the maximum. . The meeting concluded with vote of thanks by Jekin Dedhia, Students study circle in-charge of Bombay Chartered Accountant Society (BCAS).

Full day Workshop on “Heal without Medicines” held on 9th July, 2016

Human Development and Technology Initiatives Committee organized a full day program on “Heal Without Medicines” on Saturday, 9th July, 2016 at Directi-I-Plex, Andheri (East)

Atul Shah is an active propagator of Natural diet. He himself was miraculously cured from a so-called incurable condition called Avascular Necrosis (AVN) that affects the hip joint. When modern medical science could not offer a solution, Atul started reading about this unprocessed natural food diet after being introduced to it through a contact and turned to it as a last resort. It worked wonders for him and he was cured of AVN within a year of rigorously following this diet regimen.

The theme was “to die young and as late as possible, i.e. to live long and live young and always vibrant and bubbling with energy and reverse the ageing process.”

Atul Shah spoke on How to Have Good Health without Medicines?

We learnt how Raw Food Diet can help to Maintain Natural Healthy Life Style.

How to feel at ease and feel calm and Cool at all times by eating the right foods.

He spoke on how raw food diet can make us free from all Diseases and Discomforts.

How Your Food can be Your Medicine.

Little Changes in Your Daily Diet can make a Big Difference to your Life and Health

We can get rid of all types of lifestyle diseases like Joints Pain, Diabetes, Blood pressure,

Acidity, Migraine, Asthma, Kidney Disease, Heart Problems, Skin Diseases and many more…

We also got to know the sharings of people who have restored vibrant health with this NATURAL HEALTHY LIFESTYLE!

We also learnt what can cause harm to health.

Raw food lunch was served to the participants. Also relished the taste of Green Juice.

Members had come with their spouse and family members. It was good to come together to learn and share meal together. A total of 137 participants attended the workshop

Human Development Study Circle Meeting on “Human Engineering” held on 12th July, 2016

Human Development Study Circle Meeting to watch the DVD – Video Talk on “Human Engineering” by Mahatria was held on 12th July, 2016 at BCAS Conference Room. CA Vinod Jain gave a small introduction before the DVD was screened. The talk was so absorbing that it was an undisturbed screening of 90 minutes. The Lessons learnt from this video talk were discussed. The learning from this:

We are designed to be with smile, laughter, tears, compassion and love. We can live our potential life, with our ability to express our emotions. Our “ego” should not come in the way. By loving humans, we love creations of God.

As a nation, we lack one very important quality “Discipline”. Our education system does not teach how to enjoy heterogeneous relationships, deal with failures and communication skills. But we must learn them, since they are important. History should inspire us, telling all legendary figures were born normal but they took up something exceptional and became legendary figures. Same way we have potential to be infinitely greater than what we are today.

We must live a holistic life and balance our physical, mental, intellectual, emotional and spiritual life.

Physical: We must give one hour to our body daily through exercise etc., then body can take our care for next 23 hours. We must push our body little more and eat little less.

Mental: We must take care of our subconscious mind, since it is 7/8th part of total mind. Anything positive, we must speak in 5 sentences and get emotionally involved. Anything negative, we should finish it in one sentence and analysis it intellectually. Any one joining our organization to be celebrated and someone leaving should just be analyzed.

Intellectual: Sub-ordinate your likes and dislikes to your purpose of life. Otherwise, you will subordinate your purpose of life, to your likes and dislikes. Ordinary people when they identify themselves with a cause larger than themselves, they would unfold legendary possibilities in their life.

Emotional: When something goes wrong or we see wrong happening around us, we generally crib. Instead of cribbing and doing nothing, we need to channelize our emotions for a higher purpose and make thing better in this world e.g. Gandhi channelized his emotions to free India from British.

Spiritual: Our spirits are like power house, unless we are charged up internally, we cannot perform. We transcend in our life and get energy from universe, where we lose sense of time and space, be it creating something, meditating, caring, listening music, sharing, playing etc.

The participants were interested in more such video screenings for Study Circle Meetings.

Lecture Meeting on “Tax Issues in Business Re-organisation-LLP / Companies” held on 13th July, 2016

Lecture Meeting on Tax Issues in Business Re-organisation- LLP / Companies by Shri Pinakin Desai was held at IMC. President Chetan Shah gave the opening remarks.

Mr. Desai explained the meaning of reorganisation and touched upon various areas under the Income-tax Act, 1961 that would have to be examined in a business reorganising scenario.

The various concepts were explained with the help of case studies that enabled the participants to understand the issues with ample clarity.

Mr. Desai touched upon the following aspects in course of his presentation:

(a) Section 115BA in the context of a manufacturing company undergoing a demerger / slump sale

(b) Carry forward of losses in case of conversion of firm to LLP

(c) Demerger of company, conversion of company into LLP and subsequent withdrawal from LLP

(d) Merger and subsequent conversion into LLP

(e) Demerger between unrelated parties including accounting for demerger in the books of Demerged company and the resultant company in the light of Ind-AS

(f) Merger of companies under Court Scheme with reference to General Anti Avoidance Rules (GAAR) prescribed under the Income-tax Act, 1961 which are yet to become effective

(g) Share acquisition followed by Capital reduction and merger

(h) Business reorganization in light of sections 92B(1) and 92B(2)

(i) Indirect transfer of assets including tax neutrality to the foreign amalgamating company, Indirect transfer mitigation amongst others

(j) Real Estate Investment Trust – where SPV is a company and where SPV is an LLP

(k) Tax neutrality of demerger – where consideration is discharged by (i) parent company (ii) foreign parent of transferee company

Mr. Desai also elaborated on evaluating the impact of GAAR grandfathering under various scenarios such as rights issue, bonus issue, etc

It was a very informative and insightful learning experience for all the participants present. The event saw attendance by over 400 participants. The session ended with vote of thanks by Ms Pooja Punjabi.

Direct Tax Study Circle Meeting on “Issues relating to Dispute Resolution Scheme, 2016” & the Income Declaration Scheme, 2016 held on 14th July 2016

The Group leader, CA Devendra Jain commenced the meeting by commenting upon the intention of the Government behind introduction of Dispute Resolution Scheme 2016, which is to reduce the pendency of litigation existing as on 29th February 2016. He explained the provisions of the Scheme in brief and pointed out the persons who can avail this Scheme.

He gave a hypothetical example wherein the assessment order u/s 143(3) was passed before 29th February 2016 and the time limit for preferring an appeal against this order has not lapsed by this date. Then in such a case, there could be a question of availability of this Scheme since the appeal is not pending on 29th February 2016 but the assessee has got time to file the appeal; hence a clarification is required for such cases.

Thereafter, he touched upon the provisions of the Income Declaration Scheme 2016 and the valuation methods prescribed under the Rules. He pointed out the various FAQ’s released by the CBDT in relation to this Scheme and the far reaching implications of the same. He mentioned that as per the Circular No. 27/2016, provisions of this Scheme [section 197(c)] would override section 148 of the Income Tax Act, 1961 and there could be questions on the constitutional validity of such a provision. At the end, various issues which one could face while implementing this Scheme were discussed by the Group. A total of 30 participants attended the Study Circle.

Workshop on Maharashtra VAT & CST Held on 16th July 2016

The Indirect Taxation Committee (IDTC) of BCAS organized a Workshop on Maharashtra VAT and CST, wherein two important subjects were discussed i.e. (1) “Preparation and filing of returns under the new automation process” and (2) “Maharashtra Settlement of Arrears in Dispute Scheme, 2016”. It was held on Saturday 16 July 2016, at the Conference Hall of BCAS.

Shri Rajiv Jalota (Commissioner of Sales Tax – State of Maharashtra) was the Chief Guest, Mr. Nitin Shaligram (Dy. Commissioner of Sales tax, Mumbai) and members of his team, and, Mr. A S Gorde (Dy. Commissioner of Sales tax, Mumbai) were the speakers for the day.

CA. Chetan Shah (President, BCAS) welcomed the participants and highlighted the relevance of the topic in view of the proposed ‘automation process’ and expected implementation of the GST in April 2017. CA. Govind Goyal (Chairman IDTC) briefly introduced the speakers and topics allocated to each speaker for discussion. Thereafter, the speakers were felicitated by the CA. Deepak Shah, (Co- Chairman IDTC).

Mr. Nitin Shaligram, opened the discussion with a brief background about the new returns templates and the automation process. He explained the basic background of the new initiative and the objective with which they had started. He and his colleagues enlightened the participants about the steps to be followed for preparing and uploading the returns for the periods commencing on or after 1st April 2016. .

The Hon. Commissioner of Sales tax, State of Maharashtra, enlightened the participants about the various initiatives taken up by the State of Maharashtra. The Hon. Commissioner highlighted that the new automation process was the first of its kind in terms of scale, given that it was the largest implementation of a tax administration system ever in the history of SAP and that its success would ease several difficulties being faced by the tax payers. .

The second session was led by Mr. A S Gorde. He gave a comprehensive presentation on the nitty-gritties of Maharashtra Settlement of Arrears Scheme and key aspects of process related to settlement and related issues. In the ensuing interaction, the speakers gladly addressed the queries raised by the participants. CA Kiran Garkar and CA Samir Kapadia were the moderators.

In his closing remarks, CA. Govind Goyal appreciated the efforts made by the tax team and acknowledged their willingness and address all the queries raised on the floor. The workshop was attended by more than 110 participants.

The meeting concluded with a well-deserved hearty vote of thanks.
Society News – II

GST Seminar at Ahmedabad
jointly with CA  Association of Ahmedabad
held on 23, June, 2017

BCAS held a one day seminar on GST jointly with Chartered
Accountants’ Association of Ahmedabad (CAA). The object of the conference was
to disseminate the views of eminent faculties who have carried out in depth
study of newly enacted law of GST together with their vide experience in
profession. CA Puloma Dalal, CA Chirag Mehta and CA Dushyant Bhatt, faculties
from our Society spoke on various areas of GST at length at the full day
seminar. The seminar was attended by 85 participants.  

CA. Puloma Dalal

CA. Chirag Mehta

CA. Dhushyant Bhatt

In the first session CA
Puloma Dalal gave the participants an overview of GST law including the concept
of Supply under GST and provisions relating to liability to pay Tax and Time
and Value of Supply

CA Chirag Mehta gave a
detailed presentation on provisions relating to return filing and took the
participants through the process of filing of returns. He also discussed the
statutory provisions relating to Input Tax Credit under the GST Law and the
concept of matching of ITC under the GST Law

CA Dushyant Bhatt
discussed the provisions relating to job work and dealt with various issues to
be addressed by the entity carrying out job work as well as by the entity
sending material for job work, payment of tax, TDS and E-Commerce provisions
including TCS.

A one and half hour long
interactive panel discussion was held where various questions of the
participants were taken up by the three speakers. Participants benefitted a lot
from the meeting.

GST Workshop with IMA Indore held on 24th June,
2017 at Indore

BCAS jointly with Indore Management Association (IMA)
organized Exclusive Workshop on Saturday, June 24, 2017 at Brilliant Convention
Centre, Indore titled “Fasten Your Seat Belt-GST ready for take off”.

Faculty for this workshop
representing BCAS comprised of CA. Rajat Talati, and CA. Deepak Thakkar. CA.
Santosh Muchhal, President, IMA welcomed the delegates and thanked BCAS for
this workshop. President (Elect) of BCAS CA. Narayan Pasari in his welcome
speech introduced BCAS to the gathering. He also mentioned that GST is a
win-win reform for everyone and will have lasting benefits for businessmen,
Government, consumers and professionals.

CA Rajat Talati started the first session by stating that GST
is an Integrated Tax Regime which will reduce Policy Paralysis in Indian
Economy. It will also avoid Double Taxation problem which of late is posed as a
major threat for the Indian Economy.

CA. Talati explained that
Goods and Service Tax (GST) is a destination based tax on consumption of goods
and services. It is proposed to be levied at all stages right from manufacture
up to final consumption with credit of taxes paid at previous stages available
as setoff. In a nutshell, only value addition will be taxed and applicable tax
is to be borne by the final consumer.

CA Deepak Thakkar took the
2nd Session and explained that Goods and Services Tax (GST) will be
levied at multiple rates ranging from 0 per cent to 28 per cent. GST Council
finalized a four-tier GST tax structure of 5%, 12%, 18% and 28%, with Zero to
lower rates for essential items and the highest for luxury and de-merit goods
that would also attract an additional cess. Goods and Service Tax on services
will go up from 15% to 18%. The services being taxed at lower rates, owing to
the provision of abatement, some services such as train tickets etc will fall
in the lower slabs.

It would be a dual GST with the Centre and States
simultaneously levying it on a common tax base. The GST to be levied by the
Centre on intra-State supply of goods and / or services would be called the
Central GST (CGST) and that to be levied by the States would be called the
State GST (SGST). Similarly Integrated GST (IGST) will be levied and
administered by Centre on every inter-state supply of goods and services. The
GST will be shared by the Centre and the respective State equally.

CA. Rajat Talati

CA. Deepak Thakker

He also mentioned that
there are many benefits available to small tax payers under the GST regime. The
two speakers answered the many questions raised by the participants at the end
of their sessions.

The joint workshop was a very enriching experience for the
140 participants.

Two days seminar on GST
for Trade, Industry and Professionals held on 24th& 25th
June 2017 at Ghatkopar

This two day seminar was held at
Zaverben Auditorium, Ghatkopar where 725 participants attended comprising of
chartered accountants and members of trade and industry.


CA. Sunil Gabhawalla


CA.Mandar Telang


CA. Shreyas Sangoi


CA. Ashit Shah

The Seminar covered almost
all aspects of Final GST law comprising of Integrated Goods and Service Tax
Act, Central Goods and Service Tax Act and State Goods and Service Tax Act
along with the rules enacted by the Government. The eminent Speakers explained
the salient features of the law including the concept of supply, classification
of goods and services, time and place thereof, value of supply, charging
provision, threshold exemption, transition provisions, composition scheme,
registration, maintenance of records, tax invoice, payment of GST including
under reverse charge, returns and other compliances, input tax credit including
Input Service Distribution Mechanism, export and import of goods and services
including SEZ, job work under GST, etc. The learned Speakers from BCAS included
CAs Sunil Gabhawalla, Samir Kapadia, Rajkamal Shah, Naresh Sheth, Jayesh Gogri,
Mandar Telang, Ashit Shah and Shreyas Sangoi. Advocate Shailesh Sheth also gave
his valuable inputs on GST at the Seminar. At the end of the seminar, there was
specific industry wise panel discussion covering, textile and garment
manufacturers, gem and jewellery, stock brokers, mutual fund and insurance
agents, transport and logistics, C & F agents, tour operators and travel
agents, builders & developers, works contractor, co-operative housing
societies, caterers, hotels & restaurants, SMEs, retailers, traders and
small scale manufacturers, leasing and right to use goods, job worker and
service providers. The overview of the new indirect tax law replacing plethora
of numerous laws and detailed discussion on each subject and dissemination of
latest knowledge alongwith industry specific panel discussion generated lot of
interest amongst the participants making the seminar interactive to a large
extent. All participants were fully enriched by the deliberations at the
Seminar.

CA. Naresh Sheth

CA. Rajkamal Shah

CA. Samir Kapadia

Lecture Meeting on GST
& CAs – Impact on Compliance & Practice held on 27th June,
2017

Indirect Taxation
Committee of BCAS organised a lecture meeting on “GST & CAs – Impact on
Compliance & Practice” on 27th June, 2017 at K. C. College Auditorium,
Churchgate which was addressed by CA. Sunil Gabhawalla.


CA. Sunil Gabhawalla

With GST becoming a reality,
there were many issues which were faced by the practising chartered accountants
like the impact on billing under the Service Tax law and receipt under the GST
regime, paying tax on procurements from unregistered vendors, concept of supply
and place of supply with respect to clients being located in other states, a
multi-locational firm etc. CA, Gabhawalla explained about the new GST Law, its
challenges and compliances and how it is going to impact practicing Chartered
Accountants. He also enlightened on the Composition Tax and monthly return
filing process under GST. 

The speaker explained in detail and in candid way the
challenges that a practising chartered accountant would face, He also answered
a few queries raised by the members.

The participants benefitted a lot from the meeting.

‘New Curriculum of CA
Course – Has the bar been raised? organised on 5th July, 2017 at
BCAS.

HDTI Committee had organised a talk on ‘New Curriculum of CA
Course – Has the bar been raised?’ by Member of Central Council of ICAI, CA
Nihar Jambusaria.

The talk was organised for students who are eligible to
appear for CA exams under new syllabus and having their doubts regarding the
same.

CA Nihar Jambusaria meticulously explained each and every
aspect of the new curriculum and also provided a comparative analysis between
the old and new curriculum. The talk was followed by an extensive ‘Q&A’
session wherein students sought clarifications for their doubts and the speaker
positively answered all their queries.

The talk received overwhelming response from the student
fraternity. Further, quite a lot of students also took the benefit of live
streaming of the seminar at their respective places or CA firms.

The talk provided valuable
guidance to all students and was widely appreciated. 

Study Circle Meeting on
Technology Trends: Impacts of Artificial intelligence, Machine learning,
Drones, Big Data held on 5th July, 2017 at BCAS Conference Hall.

At this study circle meeting, Mr. Nikunj Sanghvi, a Mobile /
Digital Professional from USA, shared his insights on the upcoming technology
trends and their probable impact on businesses going forward. He started by
explaining the trend of expectations towards new technologies – how they
initially reach a peak followed on by disillusionment as the technologies are
not as good as expected and later on get slowly accepted by public at large. He
covered many different innovations including drones, augmented reality, digital
twins, big data, artificial intelligence & machine learning, intelligent
apps, autonomous vehicles, speech recognition and voice interfaces, block chain
and crypto currencies.

Mr Sanghvi also explained these innovations and their impact
which are already seen in some business areas. For example, using drones,
auditors are doing a physical check of goods in large warehouses in a day which
otherwise would take them weeks! On giving such other examples, the immediate
query from the group was what will happen to many existing jobs. Mr Nikunj
mentioned that while there may be jobs which are lost as and when these
technologies become mainstream, he was positive that there will be many newer
jobs which people will be able to fill in. His point was that Man’s wants are
unlimited and even if a few wants are met by these new technologies, there will
be many more which will remain unfulfilled. Therefore, there may be no need to
worry unnecessarily for job losses.

The meeting ended on this positive note and participants
benefitted a lot.

69th
Foundation Day Lecture Meeting on “ENERGising India-Changing Paradigm for
Professionals” held on 6th July, 2017 at Garware Club House,
Churchgate, Mumbai

A lecture meeting on “ENERGising India-Changing Paradigm for
Professionals” was held on 6th July, 2017 on the occasion of 69th
Foundation Day of the Society which was addressed by our Hon’ble Union Minister
of State (IC) for Power & Renewable Energy CA. Piyush Goyal.  President CA. Chetan Shah briefly touched
upon the GST regime and also shared the profile of Mr Goyal while welcoming the
Chief Guest and then requested him to address the august audience.

CA. Piyush Goyal – Minister
of State for Power, Coal, New
and Renewable Energy and
Mines (Independent charge)

Mr Goyal started his oration with the past memories of his
BCAS membership and appreciated the caricature of the cover design of GST issue
of July Journal stating that the cover design is very well presented. He then
talked about the GST Bill and explained how GST Council has been empowered to
function without any interference from the Government. Mr Goyal also emphasized
that GST is a great testimony with the culmination of 17 taxes into one tax
“GST” where the Traders, Businessmen, Manufacturers and others will get the
Input Tax Credit when goods move from one place to another. This transformation
would help to curb inflation, bring transparency, eradicate the atmosphere of
uncertainties and corruption, eliminate black money etc. This revolutionary
step has been taken by the Government in the national as well as public
interest without any political opportunism. 


BCA Journal – GST Special Issue Release
L to R : CA. Sunil Gabhawalla, CA. Narayan Pasari, Shri Piyush Goyal (Speaker), CA.
Chetan Shah (President), CA. Manish Sampat, CA. Suhas Paranjpe, CA.Abhay Mehta.

On the topic of the Lecture Meeting “ENERGising
India-Changing Paradigm for Professionals”,
he cited Mahatma Gandhi Quote
that we are the trustees of the Planet and it is our collective responsibility
to keep the environment clean, abolish pollution and adapt to healthy and
hygienic climate changes for better quality of life for 1.25 billion Indians.
Our inhabitants especially in the rural areas cannot afford to live without
electricity, shelter, transportation, medical facilities etc and Government has
taken strong steps to provide these amenities to majority of the villages and
would reach the zero defect in a phased manner. Mr Goyal also informed the
gathering that at present, India is energy surplus and self-sufficient in Power
Distribution. As per the world standards, we are contributing to clean energy
and reducing pollution levels. He also urged upon the citizens to use LED bulbs
to conserve the energy and contribute in Nation Building. Besides, Mr Goyal
also remembered our armed forces and assured to provide them with the most
modern equipment and technology to fight any internal and/or external threat.


Audit Checklist Publication Release
L to R : CA. Raman Jokhakar, CA. Sunil Gabhawalla, CA. Narayan Pasari, Shri
Piyush Goyal (Speaker), CA Chetan Shah (President), CA. Manish Sampat, CA.
Suhas Paranjpe, CA Abhay Mehta

He thereafter appealed to the Chartered Accountants
Fraternity to strengthen and upgrade the audit standards to curb the Tax
evasion/avoidance and further transform the future of India, because CAs are
the force to reckon with in the professional industry.

At the end, he expressed confidence that Chartered
Accountants can do a lot for the public good and make India again.

The audience got mesmerized with Mr Goyal’s presentation
skills and gained a lot from the insights straight from the heart and from his
spellbinding Speech.

Lecture Meeting on “Recent Developments in Taxation of
Capital Gains” held on 11th July, 2017.

Taxation Committee of BCAS organized a Lecture Meeting on
Recent Developments in Taxation of Capital Gains on 11th July, 2017
at IMC, Churchgate, Mumbai. The first meeting of the year at BCAS which
commences from the Founding Day, 6th July, was addressed by CA.
Pinakin Desai wherein he explained about the Notional Taxation w. r. t. Fair
Market Value (FMV) of unlisted equity shares under Sec 50CA, shift of base year
for indexation from 1981 to 2001 to compute the cost of bonus shares and
amendment to Sec 10 (38) with background and notification on 3rd proviso
to Sec 10(38). He also discussed about the Protocol to India – Mauritius Treaty
with emphasis on Mauritius and Multilateral Treaty (MLI) and protocol amending
India-Singapore Treaty. CA. Pinakin Desai further explained about the valuation
of shares under Normative Valuation with draft valuation rule notified u/s. 50
CA and issues under normative valuation. He also deliberated on Sec 195 –
withholding actual or notional consideration for Sec 50 CA. 


CA. Pinakin Desai

Mr Desai also explained the
above topics with case studies on (i) resolving normative valuation of shares
as per draft notification, (ii) valuation of unquoted equity shares, (iii)
acquisition in IPO, (iv) acquisition pursuant to merger, (v) gift of shares,
(vi) Inter-se promoter transfer, (vii) direct transfer vs. indirect transfer,
(viii) impact of dividend distribution and (ix) case study under
India-Mauritius Treaty.

The hall was packed with
the audience and it was a very fulfilling and enriching experience for the
participants to benefit immensely from the meeting.

GST Training Seminar Jointly with NACIN held from 13th
July to 15th July, 2017 at BCAS Hall

With the roll out of GST on
1st July, 2017, the 3rd batch of GST Training Seminar for
Trade, Industry & Profession was organised by Indirect Taxation Committee
of BCAS jointly with the National Academy of Customs, Indirect Tax and
Narcotics (NACIN), to make understand the intricacies and the importance of GST
laws & provisions.

CA. Mandar Telang

CA. Shreyas Sangoi


CA. Chirag Mehta

CA. Govind Goyal

The purpose of holding such training workshop
was dual – one to educate the trade and industry about the new legislation and
more importantly, partnering Government in disseminating information about this
landmark “One Nation One Tax”.

 The speakers at the Seminar were BCAS members
accredited by the NACIN as GST Trainers, and a few officials from the GST
department. The faculty from BCAS included CAs Chirag Mehta, Dushyant Bhatt,
Govind Goyal, Mandar Telang, Naresh Sheth, Rajkamal Shah, Shreyas Sangoi and Ms
Vishaka Borse, & Mr, Shrikant Shaligram from the GST Department.

CA. Naresh Sheth

CA. Dushyant Bhatt


CA. Shrikant Shaligram


CA. Rajkamal Shah

The participants immensely benefited from the training
programme.

Dharampur Noble Social Cause Visit – on 15th &
16th July, 2017

The visit to Dharampur was
organised for two days by the Human Development and Technology Initiative


Dharampur Noble Social Cause Visit

Committee of BCAS jointly
with BCAS Foundation, for Tree Plantation, Eye Camp project and visit to
various NGOs, at Dharampur. These NGOs are engaged in the various social
welfare activities for Holistic growth of Tribals located in the remote
interiors. A Team of 24 enthusiastic volunteers including students who were
willing to take active participation in this noble mission joined the trip.

Sarvoday Parivar Trust (SPT)

The SPT is a NGO, following
Gandhian philosophy and engaged in various tribal welfare activities in the
field of Education / Health / Agriculture / Water management / Environment,
etc. The BCAS Foundation committed for plantation of 3,000 trees to SPT. The
team also visited the Residential School run by the SPT which is home to more
than 350 children from nearby villages.. This residential school has encouraged
poor labourers and farmers in the tribal areas to send their children for
further studies. It has helped in reducing child labour, child marriage and
other social evils which takes place mainly due to illiteracy and poverty.
Members had good interactions and time with them. The School premises are old
and needs to be renovated and upgraded to provide better amenities to children.
BCAS Foundation has committed its full support for the redevelopment and
upgradation of school/ hostel.

Avalkhandi Kelavani Trust (AKT)

The AKT is an NGO which
carries out various activities in Education & Water Management in the
villages of the most backward forest of Dharampur, running a government School
where approximately 300 students are studying & has one Chhatralaya whereby
180 children are accommodated for stay from other villages who would have
otherwise been deprived of education. The BCAS Foundation committed for
plantation of 2,500 trees to AKT. On behalf of BCAS Foundation, team
distributed kits for outdoor games like cricket / Football/ Badminton  / Flying Dish etc  and many educational games at AKT for their
children. The BCAS Foundation contributed Rs. 30,000/- for setting up a library
in the Chhatralaya.

The team viewed the various
check dams created on mountains in the process of water management.

Dhanvantri Trust (DT)

The trust is founded and
managed by Dr. Kirtikumar Vaidya, from Mumbai who left Mumbai at a young age
& has dedicated his life for socio economic rural development of tribal
villages of South Gujarat. With divine blessings he started an Eye Hospital in
Vansda. Our team member had contributed Rs. 63 lakh for setting up Hospital
with latest Equipment & Technology for treating and curing all types of Eye
Surgeries.

BCAS Foundation sponsored 201 Eye Surgeries for poor Tribals & has
dedicated support for 50 more, thanks to contribution & support of Esteemed
Donors, amounting to Rs.2.01 lakh.

Dr. Vaidya proposed to set up a school in Vansda. BCAS Foundation has
committed their support for the same.

The   trip for Tree plantation
drive and the Eye Camp was truly enriching, enlightening and educational too
for the visiting members and students. The memories treasured from the trip,
would always encourage and motivate them to participate more in such events
which would be beneficial to the society at large.

Direct Tax Study Circle Meeting on ‘Income Computation
Disclosure Standards; ICDS V Tangible Fixed Assets, ICDS IX Borrowing Costs
& ICDS X Provisions, Contingent Liabilities & Contingent Assets’ on 15th
July 2017

The Chairman of the
Meeting, CA. Anil Sathe gave his opening remarks and raised some issues
relating to ICDS which could face litigation in the long run. The Group leader,
CA. Dhaval Desai drew attention to an extract from the Supreme Court decision
in Woodward Governor 312 ITR 254 wherein the Hon’ble Supreme Court observed
that for income tax purposes, profits are to be computed in accordance with the
ordinary principles of commercial accounting unless, such principles stand
superseded or modified by legislative enactments and this is where section
145(2) comes into play.

Thereafter, the group
leader briefly explained the provisions of ICDS IX ‘Borrowing Cost’-
recognition principle, definitions of borrowing cost and qualifying assets. He
explained the provisions of capitalisation in respect of specific borrowings
and general borrowings and the provisions relating to commencement and
cessation of the capitalisation. He mentioned that as per Accounting Standard
16, an asset qualifies to be a Qualifying Asset only if it takes substantial
period of time to get ready for its intended use or sale, however ICDS has done
away with the criteria of ‘substantial period of time’ (except for inventories)
and this would lead to a huge difference between the capitalisation of
borrowing costs as per books and capitalisation as per ICDS.

The group leader further
touched upon the provisions of ICDS X ‘Provisions, Contingent Liabilities and
Contingent Assets’. He mentioned the yardstick for recognition of a provision
‘probable’ as per Accounting Standard 29 has become stricter under ICDS wherein
the term ‘probable’ has been substituted with ‘reasonably certain’. Similarly,
in case of contingent assets, the term ‘virtual certainty’ used for recognition
as per AS 29 has been substituted with ‘reasonably certain’ under ICDS. He
commented that such provisions would certainly lead to preponement of income
and postponement of deduction of expenses. The group leader touched upon
transitional provisions contained in ICDS X.

Subsequently, CA. Dhaval
briefly explained the provisions of ICDS V ‘Tangible Fixed Assets’. He
highlighted one of the differences between existing AS and ICDS with regard to
treatment of expenditure between trial run and commercial production. In this
context, Revised AS 10 mandates such expenditure to be revenue in nature
whereas CBDT clarification on ICDS states that such expenditure should be
treated as capital expenditure.

The participants benefitted a lot from the
meeting.

Society News -I

Full day seminar on
“Income Computation and Disclosure Standards” held on 19th May, 2017

This seminar was held by
the Taxation Committee at Navinbhai Thakkar Hall at Vileparle (East). President
Chetan Shah gave the opening remarks followed by introduction from the Chairman
of the Taxation Committee, Mr. Ameet Patel. The event was attended by 235
participants. Topics taken up and Speakers were as under:

    Overview of ICDS:- Mr. Pawan Kumar, CIT
(Jalandar)

    ICDS III & VIII:- Constructions
Contracts & Government Grants :  CA.
Paresh Vakharia

    ICDS I & ICDS X:- Accounting Policies
& Provisions, Contingent Liabilities & Contingent Assets: CA. Vishesh
Sangoi

    ICDS IV & IX:- Revenue Recognition &
Borrowing Costs: CA. Vinita Krishnan

    ICDS VI & VIII:- Foreign Exchange
Fluctuations & Securities: CA. Kushal Jain

  ICDS II & V:- Valuation of Inventories
& Tangible Fixed Assets: CA. Nihar Jambusaria

Mr. Pawan Kumar, CA.
Vishesh Sangoi and CA. Kushal Jain spoke on the BCAS platform for the very
first time. 

Mr. Pawan Kumar gave an
overview of the ICDS. He also shared with the participants on why ICDS were
needed and how it came into existence. He being one of the members of Expert
Committee for drafting of ICDS shared his experiences with the participants
which was appreciated by all.

CA. Paresh Vakharia gave
his opening remarks on ICDS and explained the purpose of the said legislation.
He dealt with both the ICDS allotted to him in detail and explained nuances and
issues arising from them.

CA. Vishesh Sangoi started
his presentation by explaining the basic issues arising from ICDS I and X. He
explained various changes which would take place while undertaking Tax Audit in
post ICDS scenario compared to earlier ones with the help of various case
studies. He also touched upon disclosure requirements in Form 3CD for both
ICDS. He also responded to queries from various participants.

CA. Vinita Krishnan gave a
detailed presentation on ICDS IV & IX. She explained the basic
considerations arising out of them and also discussed the issues which one may
face while applying them. She discussed ICDS on revenue recognition with
respect to different type of incomes like dividend, royalties, interest etc.
She also answered queries from the participants.

CA. Kushal Jain explained
ICDS on securities with the help of case studies and also examples on how it
would be applied. He also explained various terms which are used in both the
ICDS. He also dealt with how the accounting entries would be affected in case
of ICDS on foreign exchange fluctuations.

CA. Nihar Jambusaria
explained the background and general principles of ICDS. He highlighted the
journey of evolution of ICDS. He also brought out the differences which will be
encountered between Ind AS and ICDS. He compared ICDS of Valuation of
Inventories with AS 2 and brought the changes between them. He also compared AS
10 with ICDS on Tangible Fixed Assets and explained the treatment under ICDS V.
He enlightened the participants with the disclosure requirements under both
ICDS and also addressed various questions from the participants. 

The sessions in the Seminar
were interactive and the speakers shared their insights on the subject and
guided the participants on how to approach the subject of ICDS while performing
a Tax Audit. The participants benefited immensely with the interactive sessions
and detailed analysis of each ICDS by the faculties.

Full day seminar on
“Practical issues in TDS” held on 20th May, 2017 at BCAS

The Full day seminar on
Practical issues in TDS was held by the Taxation Committee at BCAS Conference
Hall on 20th May, 2017. The event was attended by over 80 participants.
President Chetan Shah gave the opening remarks followed by introductory words
from the Chairman of the Taxation Committee, Mr. Ameet Patel.

Various topics were taken
up at the Seminar by the following Speakers:

    Sections 194C, 194DA, 194EE, 194F and 194J :
CA. Saroj Maniar

    Sections 195, 206AA, Rules 37BB and 37C :
CA. Ritu Shaktawat

    Sections 192, 194H, 194LB, 194LBA, 194LBB,
194LBC : CA. Anita Basrur

    Sections 194A, 194I, 194IA, 194IB, 194IC and
recent case laws on TDS : CA. Nitin Shingala

    Issues in e-filing of TDS statements,
Sections 200A, 201 and 205 : CA. Avinash Rawani

CA. Ritu Shaktawat and CA.
Anita Basrur spoke on the BCAS platform for the first time.

CA. Saroj Maniar gave an overview of the various sections,
the case laws and circulars applicable and relevant in their context. The
speaker elaborated on the provisions of Sections 194C and 194J and covered some
industry specific issues as well as the interplay of these sections with other
sections of the Act.

CA. Ritu Shaktawat
explained the applicability of section 195. She highlighted the risk arising
out of non-compliance of applicable sections as well and provided insight on
issues surrounding Forms 15CA and 15CB. She also touched upon issues under
Section 206AA, Rules 37BB and 37C. The Speaker elaborated on contractual
remedies that one could pay attention to and should incorporate in the
agreements such as indemnity, representations and warranties, escrow,
insurance. She also explained the provisions and their application through case
studies.

CA. Anita Basrur started
her presentation by explaining the provisions of section 192 and 194H,
practical issues arising thereunder using relevant case laws and recent
circulars. This was followed by in depth discussion on sections governing TDS
on income received by securitisation trusts, business trusts and units of
Investment Funds.

CA. Nitin Shingala gave a
detailed presentation on various aspects governing sections 194A, 194I, 194IA,
194IB and 194IC. He explained the applicable provisions, issues under each of
them, supporting them by relevant case laws and circulars.  The Speaker touched upon a wide number of
judgments during the course of his talk on various sections pertaining to
deduction of tax at source.

CA. Avinash Rawani highlighted
the practical issues that arise in e-filing of various TDS statements such as
returns, correction statements, challan corrections, replies to be filed to
online communication from the TDSCPC amongst others. In addition to
highlighting the issues, the Speaker shared a lot of practical dos and don’ts
in relation to the filing of these statements.


CA. Saroj Maniar


CA. Ritu Shaktawat


CA. Anita Basrur


CA. Nitin Shingala


CA. Avinash Rawani

The sessions in the Seminar
were very interactive and the Speakers answered a lot of queries that were
received from the participants. The participants benefited immensely with the
interactive sessions and detailed discussions.

Half
day seminar on “Digital Transformation and GST – Opportunities and Challenges
in ERP environment” on 26th May, 2017 at BCAS

A half day seminar on
Digital Transformation and GST was organised by Human Development &
Technology Initiative Committee jointly with Indirect Tax Committee at BCAS
Conference Hall on 26th May 2017. CA. Nikunj Shah, Convenor, HDTI
Committee introduced the speakers to the participants.

The speakers – Mr. Richard
D’Souza (Vice President & Head Business Solutions-Corporate IT Mahindra
& Mahindra Group ) & Mr. Rakesh Pawaskar (General Manager Business
Solutions – Corporate IT Mahindra & Mahindra Group) made an excellent presentation
on the Technology transformation undertaken by them in their organisation. They
also explained and demonstrated through audio visual presentation, the nuances
of GST implementation, the GST implementation process at their group and how
the said group is supporting their vendors for GST implementation using state
of the art technology platform.

The seminar witnessed
excellent participation from members in practice as well as from Industry. The
objective of the seminar was to understand the innovation in technology leading
to change in accountants role from pure accounting to analytics and decision
making & to highlight how GST implementation could be achieved leveraging
technology.


Mr. Richard D’Souza

 Mr. Rakesh Pawaskar

The participants were
immensely benefitted from the Seminar.

GST Training for Trade,
Industry & Profession held on 29th, 30th & 31st
May 2017 & 19th, 20th & 21st June
2017 at BCAS

The Government’s decision
to roll out the GST Law on 1st July, 2017 made it all the more
important that BCAS organise more programs so as to educate and train as many
people on the intricacies and the importance of these laws.

BCAS organised two such
programs one in May from 29th to 31st and the other in
June from 19th to 21st at BCAS Conference Hall. The
purpose of holding such training workshops was dual – one to educate the trade
and industry about the new legislation and other, more importantly, being a
partner of the Government in disseminating the information about this One
Nation One Tax One Market.

These programs were conducted jointly with the National
Academy of Customs, Indirect Taxes and Narcotics (NACIN) and the sessions were
taken by members of BCAS who were accredited by the NACIN as GST Trainers and a
few officials from the Sales Tax department and NACIN also. The faculty from
BCAS included CAs Chirag Mehta, Dushyant Bhatt, Govind Goyal, Jayesh Gogri,
Mandar Telang, Naresh Sheth, Rakjamal Shah, Samir Kapadia, Shreyas Sangoi and
Sunil Gabhawalla. 

CA. Rajkamal Shah

CA. Samir Kapadia

CA. Chirag Mehta


CA. Shreyas Sangoi


CA. Sunil
Gabhawalla

The participants immensely
benefited from both the programmes.

BEPS Study Circle Meeting
held at BCAS Conference Hall on 3rd June 2017

BEPS Action Plan 6 read
with Action Plan 15 (Multilateral Instrument i.e. ‘MLI’): Preventing the
Granting of Treaty Benefits in Inappropriate Circumstances was held on 3rd
June, 2017 at BCAS Conference Hall.

Discussion was led by CA. D
S Sharma, CA Monika Wadhani and CA. Rutvik Sanghvi

This was the third meeting
on Action Plan 6: The group leaders covered overview of Article 6 to 8 of the
MLI and detailed comparison of LOB clause.

In the meeting, the group
leaders had taken up detailed discussion on following Articles of MLI read with
Article X of Action Plan 6 and had concluded discussion with emphasis on the
following:

  Article 8 of MLI  Dividend transfer transaction intends
to introduce a minimum shareholding period of 365 days to be entitled to
beneficial rate of taxation on dividend.

  Article 9 of MLI – Capital Gains from
alienation of shares or interests of entities deriving their value principally
from immovable property intends to give taxing rights to the Contracting State
where immovable property situated, if at any time during the 365 days preceding
the alienation of shares, such shares derived value principally from such
immovable property.

  Article 7(1) of MLI – Principal Purpose
Test (‘PPT Clause’): It intends to introduce a minimum standard in form of PPT
clause to be adopted by the Contracting States. The group leaders discussed the
meaning and possible interpretations of various words contained in the PPT clause
(like meaning of “benefit”, “one of the principal purposes”, etc.) and
explained each and every example given in the commentary to Action plan 6. The
group leaders also highlighted the difference and the interplay between the
Indian GAAR provisions and the PPT clause. For example, under the Indian GAAR
provisions, requirement is “if main purpose is tax benefit”vis-à-vis the PPT
clause, requirement under the MLI being “one of the principal purposes is tax
benefit”, etc. It was also discussed that PPT clause will be relevant to
consider the applicability of a tax treaty and if PPT clause is invoked then
treaty benefits shall not be available and many transactions could get
impacted. It was also discussed whether GAAR provisions can be invoked where
transaction is covered by a tax treaty.

The meeting got
enthusiastic response and the participants benefitted a lot from the
discussions

10th Jal Erach
Dastur CA Students Annual Day held on 3rd June 2017

The Jal Erach Dastur CA
Students’ Annual Day this year reached a new scale as it celebrated its 10th
Edition captioned under tagline ‘Tarang 2K17 – Tarasho Apne Talent Ke Rang.’ at
Navinbhai Thakkar Auditorium, Vile Parle on 3rd June 2017.


Students lining up to witness the most
awaited event of the year

This event was organized by
the Human Development and Technology Initiatives Committee of the BCAS for the
CA students. The event was truly an event ‘OF CA students, FOR CA students and
BY CA students’. It showcased their mesmerizing talents and creativity on
variety of extra-curricular activities such as elocution, debate, sketch and
slogan, photography, short film making and other talents such as singing, music
etc.

Then Vice President CA. Narayan Pasari
felicitating the Chief Guest of Tarang –
Mr. Dhaval Bathia

President Chetan Shah, Vice President
Narayan Pasari along with members of
HDTI Committee witnessing the lighting
of auspicious lamp to commence the
event

The six finalists of the Chandanben Maganlal
Bhatt ‘Elocution Competition’ were the first to witness the stage. The topics
this time were both challenging as well as riveting. This enabled a level
playing field for all participants who gave their impressive performances on
their respective topics.

CA. Nitin Shingala & CA. Meena Shah
presenting the award to the winner of
Elocution Competition ‘Speak Up’ – Miral
Majmundar

Then BCAS President CA. Chetan Shah
presenting the award to the winner of
‘CA’s Got Talent’ – Deevesh Chudasama

Post Elocution, the
winners of Photography Competition ‘Khinch Le’ were announced. This being the
second year of the competition, received unprecedented response from students.
They were given themes on which they had to click creative photographs and
mention an innovative tagline based on the theme selected.

CA Ryan Fernandez moderating the
debate competition – ‘War of Words’

Students Committee performing the flash mob

Chief Guest Mr. Dhaval Bathia giving the
keynote address

As a part of continuous improvement and innovation, this
year, a new event ‘The Screenmasters – Short-film making competition’ was also
introduced. The competition received good response from the students with 9
entries in the very first year itself. The students had to a shoot a short-film
of not more than five minutes on the given theme. The entire audience was
amazed by the professionalism and meticulousness of CA students, even in the
arena of film-making.

Mesmerising display of talent – Spray
Painting

Audience enjoying light hearted games during the break time

BCAS Students Committee, Tarang
Volunteers along with members of HDTI Committee

The final round of the
Debate Competition ‘War of Words’ followed the Photography Competition. The debate
was moderated by CA. Ryan Fernandes with two teams of four students each. The
debate had the undivided attention of the audience as each finalist defended
their case with enthralling wit and vigour. Adding some spice to the event,
this year a fourth round was introduced wherein the teams had to interchange
their erstwhile position vis-à-vis the topic. The participants as well as the
audience enjoyed the debate to the core.

After this, the students presented a 3 minute “flash mob”
which was choreographed by CA Hrishikesh Joshi. This short stint kept the
audience alive and cheering.

After the flash mob, the charged up audience were enchanted
by the Keynote address of the Chief Guest Mr. Dhaval Bathia, a well-known
author and speaker as well as Guinness Record Holder. His speech was both
motivational and thought provoking as he used day-to-day anecdotes and examples
to convey his message. He emphasized on the need to think out-of-the-box and
‘go deep’ into the realm of your work to carve out definite success. He also
touched upon finer aspects of ‘Digital India’ and how it has revolutionized the
style of working, even for the CA fraternity.

Immediately after that,
the stage was set for the flagship and most awaited competition the ‘The Talent
Show’. To kick-start the event, a ‘Students Band’ comprising of Tej Bhatt,
Sridisha De, Aagam Jain and Jigar Jain rocked the stage. These students
volunteered for this special performance to strike the chord for the upcoming
competition.

Finally the guitars were
tuned, the keyboard was ready, the dancers were tapping their feet, and the
stage was then taken over by young and talented CA students who showcased their
talent ranging from dance, singing, instrumental, mimicry and spray painting.
All 9 finalists gave amazing performances and the audience were left spell
bound. The cheering of the crowd with claps and whistles increased with each
performance as the finalists kept on raising the bar. The judges who were
captivated by the charm of the performances had a Himalayan task in choosing
the winners.

With the clock-ticking,
the winners of the competition representing their firms were finally announced as under:

The entire evening was
hosted fabulously by Mr. Pushkar Adhikari, Ms. Tanvi Parekh, Ms. Miral Majumdar,
Ms. Aadhira Dinesh and Mr. Manthan Rawat with their astounding performances,
display of energy and loads of wit and humour. 

Mr. Prathamesh Mhatre
proposed the well-deserved vote of thanks to each and everyone involved in the
success of the event. A total number of 492 students registered for the 10th
Jal Erach Annual Day, setting an overwhelming benchmark.

Essay Writing Competition ‘Awaken the Writer Within’

Prize

Name of Student

Name of Firm

1st Prize Winner

Salonee Kabra

SRBC & Co LLP

2nd Prize Winner

Kanika Mangal

Dinesh & Agarwal

3rd Prize Winner

Anisha Talesara

Kailash Chand & Co

Rotating Trophy
went to Salonee Kabra

Elocution Competition ‘Speak Up’

1st Prize Winner

Miral Majumdar

CNK & Associates LLP

2nd Prize Winner

Tanvi Parekh

Sanjay & Snehal

3rd Prize Winner

Apurva Wani

Aneja & Associates

Rotating Trophy
went to Miral Majumdar

Talent Show ‘CA’s Got Talent’

1st Prize Winner

Deevesh Chudasama

Khandelwal Jain & Co

2nd Prize Winner

Tej Bhatt

CNK & Associates LLP

3rd Prize Winner

Vivek Rajpurohit

Sara & Associates

Rotating Trophy
went to Deevesh Chudasama

Debate Competition ‘War of Words’

Winning Team

Tanvi Parekh (Best Team Member )

Sanjay & Snehal


Hardik Adenwala (Best Team Member)

KNAV & Co


Sonal Agrawal (Best Team Member )

R M Ajgaonkar & Co


Salonee Kabra (Best Team Member )

SRBC & Co LLP

Best Debater

Tanvi Parekh

Sanjay & Snehal

Rotating Trophy
went to Tanvi Parekh.

Sketch & Slogan Competition ‘Leave your Mark’

1st Prize Winner

Chandrika Chaudhari

Khimji Kunverji 
& Co

2nd Prize Winner

Eashan Gokhale

Gokhale & Sathe

3rd Prize Winner

Vishishta Goyal

N P Shah & Associates LLP

Photography Competition ‘Khinch Le’

1st Prize Winner

Deevesh Chudasama

Khandelwal Jain & Co

2nd Prize Winner

 Neel Khimasia

GBCA & Associates.

3rd Prize Winner

Aurobindo Chatterjee

R R Muni & Co

Short Film Making Competition ‘The Screenmasters’

1st Prize Winner

Anirudh Parthasarathy

R T Jain & Co

Hearty Congratulations to all the
winners and their firms.

Judges for the Various
Competitions were as follows:

Competition

Elimination Round

Final Round

Essay Writing

CA Mukesh Trivedi
& CA Gracy Mendes

Elocution Competition

CA Meena Shah & CA Mihir Sheth

CA Mayur Nayak & CA Divya Jokhakar

Talent Show

Devansh Doshi & Kartik Srinivasan

Pallavi Choksi & Neetu Shah

Debate Competition

CA KK Jhunjhunwala & CA Ryan Fernandes

CA Narayan  Pasari
& CA. Shalin Divatia

Sketch & Slogan Competition

CA Chirag Doshi
& CA Divya Jokhakar

Photography Competition

CA Anand Kothari
& CA Nikunj Shah

Short Film Making Competition

CA.  Mihir Sheth & Mr Pratik Palan

The entire evening was
hosted fabulously by Mr. Pushkar Adhikari, Ms. Tanvi Parekh, Ms. Miral
Majumdar, Ms. Aadhira Dinesh and Mr. Manthan Rawat with their astounding
performances, display of energy and loads of wit and humour. 

Mr. Prathamesh Mhatre
proposed the well-deserved vote of thanks to each and everyone involved in the
success of the event. A total number of 492 students registered for the 10th
Jal Erach Annual Day, setting an overwhelming benchmark.

Study Circle Meeting on
“Build Brand U for
Professional
Success” at BCAS on 13th June, 2017

Human Development and Technology Initiatives Committee of
BCAS conducted a Study Circle Meeting on “Build Brand U for Professional
Success” (Enhancing your Image as Professional) on June 13, 2017

The meeting was addressed by Mr Sunil Kini, Managing Director
& Principal Trainer; Gurukul Training & Consulting Pvt Ltd. Mr Kini in
his presentation on the subject in a very succinct but effective manner
explained that “Managing one’s image is the key to success in any walk of
life”. Your Image says a lot about you. A right Image can go a long way in your
life.

Each one of us presents an
image on the basis of which people form impressions about us. These impressions
pave the way in our professional growth path.

Whether as a self-employed professional or working with an
organization presenting ones best is an important ingredient for professional
accomplishments

The Workshop deliberated upon the following basic synopsis of
life:

    Develop Self-Image for Superior Perception
Management

    4 A model for Professional  Growth

    Look the part

    Appearance Management-Gateway to creating an
Impact

    Importance of Professional Decorum and
Kinesics

    Build Brand You.

    Everyone needs image management, only the
intelligent realize in time.

The session ended with a quote: Do not underestimate the
Power of your Appearance, Build your Personal Brand for SUCCESS

The participants felt enriched with request for more such
programmes in future.

FEMA Study Circle Meeting held on 15th June, 2017
at BCAS

FEMA Study Circle Meeting was held on 15th June,
2017 on the topic “External Commercial Borrowing (ECB)”.

The group was led by CA Palav
Shah Parekh.

The depth of the
presentation was excellent with members’ interactions on various case studies
presented. The case studies were very engaging and informative. This gave
participants a 360 degree perspective of the subject.

The speaker covered updates
which were as recent as 8th June.

The participants also
benefited due to the practical exposure of the speaker who shared many insights
about Authorised Dealer’s interaction with the RBI on ECB matters.

Direct Tax Study Circle
Meeting on ‘Income Computation Disclosure Standards; ICDS VI “Effect of changes
in Foreign Exchange rates” on 20th June 2017 at BCAS Conference
Hall.

The group leader, CA.
Abhitan Mehta briefly explained the scope of ICDS VI ‘Effect of changes in
foreign exchange rates’ and the definitions of important terms mentioned in the
standard. He explained the concept of ‘foreign currency transaction’ and the
provisions pertaining to initial recognition of these transactions. The
Chairman of the session, CA Gautam Nayak commented upon the anomalies created
due to introduction of ICDS wherein the law makers have merely picked up the
language of the accounting standards and inserted them in the form of ICDS
without realising the difference between the recognition of items in books of
accounts and computation of income.

Thereafter, CA. Mehta
touched upon the provisions contained in Rule 115 of Income Tax Rules which
talks about the rate of exchange for conversion into rupees, of income
expressed in foreign currency. He also highlighted that in case of difference
between the provisions of ICDS and Income Tax Rules, the Income Tax Rules would
prevail.

CA. Mehta then explained
the difference between monetary and non-monetary items and highlighted a
practical issue which one may face when debentures / preference shares
(optionally convertible) need to be classified either as monetary or
non-monetary assets. Thereafter, he gave an overview of the year end valuation
rules for assets and liabilities and provisions of section 43A of the Income
Tax Act. 

The group leader also
discussed various SC and HC decisions such as Shell Company of China Ltd.
(22 ITR 1) (CA), CIT vs. Tata Locomotive And Engineering Co. Ltd (60 ITR 405
(SC), Sutlej Cotton Mills Ltd. vs. CIT (116 ITR 1)(SC), State Bank of India vs.
CIT, CIT vs. Jagatjit Industries Ltd. (337 ITR 21) (Delhi HC)
and CIT
vs. PVP Ventures Ltd (211 Taxman 554) (Madras HC)
whereby the Courts in the
context of allowability of foreign gain / loss as expenditure, have held that
nature of gain/loss – capital or revenue needs to be identified.

CA. Mehta also explained
the provisions relating to foreign operations and treatment of opening balance
of foreign currency translation reserve (FCTR) existing on 01.04.2016 as
clarified by CBDT in the FAQ’s. Lastly, he touched upon provisions regarding
forward exchange contract and the differential treatment for premium/discount
under Accounting Standards and ICDS.

The participants were
thoroughly enlightened by the presentation on the subject.

Yoga Day Celebrations held on 21st June, 2017 at
BCAS

Human Development and Technology Initiatives Committee had
organised a yoga session jointly with Indian Spiritual Healing (ISH) Foundation
on Wednesday 21st June 2017 at BCAS Conference Hall, to commemorate
the International Yoga Day.

Mr. Pradeep Thakkar, a Professional Yoga teacher and an
active member of the ISH Foundation guided the participants who attended this
programme.

He demonstrated and guided
participants to perform different asanas with ease and comfort for a healthy
body and mind relaxation.

Participants were also
taught various pranayama to cure diseases. The session ended with positive
affirmations, energy balancing and Omkar Sadhana. Many participants requested
for a regular/long duration yoga course. It was a good learning of Yogasana and
Pranayam for healthy body and peaceful mind.

BCAJ August 1969

BCAJ August 1970

BCAJ August 1971

BCAJ August 1972

BCAJ August 1973

BCAJ August 1974

BCAJ August 1975

BCAJ August 1976

BCAJ August 1977

BCAJ August 1978

BCAJ August 1979

BCAJ August 1980

BCAJ August 1981

BCAJ August 1984

BCAJ August 1985

BCAJ August 1986

BCAJ August 1987

BCAJ August 1988

BCAJ August 1991

BCAJ August 1992

BCAJ August 1993

BCAJ August 1994

BCAJ August 1995

BCAJ August 1996

BCAJ August 1997

BCAJ August 1999

BCAJ August 2000

BCAJ August 2001

BCAJ August 2002

BCAJ August 2003

BCAJ August 2004

BCAJ August 2005

BCAJ August 2006

BCAJ August 2007

Tech Update

Computer Interface

Most of you may have read the various news reports about
results of the financial stress review recently concluded in the European Union.
The primary aim of the review was to assess the strength (or weakness) of banks
to meet the challenges prevailing currently. Fortunately, the results brought a
fair amount of cheer for all and the sundry. All but 5 of the banks passed
(quite opposite to the recently announced CA final results in which less than 5%
passed). But while the various members of the finance ecosystem were doing an
assessment exercise, members of the mobile ecosystem were doing some
housekeeping themselves. The media was filled with reports of certain emerging
trends, setbacks, projects / ventures being shelved.


Emerging trends :

The word ‘trend’, in general, means the popular taste at a
given time, a general tendency to change, a general line of orientation or a
general direction in which something tends to move
and then again it
also means to turn sharply, change direction abruptly. It’s funny
when you stop to think about it, how the same word conveys different messages,
in this case more or less opposite meaning. Trends for some is the most
obvious thing which makes choice easy and then there are others who would say
they never saw it coming. Not convinced ? Look at the state of the US financial
system and the arguments on the current scenario . . . . many say we went hoarse
shouting bloody murder and the Feds says we never saw it coming.

Coming back, here are some fairly interesting developments
(trends) that may interest you:

Broadband service a legal right in Finland :

Apparently, Finland is the first country in the world to make
access to broadband services a legal right for its 53 lakh citizens. Under the
new law, which came into effect earlier this month, telecommunications companies
will be obliged to provide all citizens with broadband lines that can run at a
minimum of 1 Mbps (megabites per second). While making this announcement, the
Finnish Ministry said “Internet was part of everyday life for Finnish people and
it was the government’s priority to provide high speed Internet access to all.
Internet services are no longer just for entertainment, Finland has worked hard
to develop an information society and a couple of years ago we realised not
everyone had access”. It is believed up to 96% of the Finnish population are
already online and that only about 4,000 homes still need connecting to comply
with the law. The government has also promised to connect everyone to a 100 Mbps
connection by 2015.

You may recall, the Indian Government had also made certain
promises (among others) when it unveiled India’s broadband policy in 2004.
Instead, all we’ve got so far is more dug-up roads and the ever-increasing
frequency (not to mention duration) power outages. Suffice to say we have a long
way to go for now.

E-reader Kindle outpaced sales of hardcover books on Amazon :

Earlier this month Amazon.com, one of US’ largest
booksellers, announced that for the past three months, sales of books for its
e-reader, the Kindle, outnumbered sales of hardcover books. In that time, Amazon
is said to have sold 143 Kindle books for every 100 hardcover books (including
hardcovers for which there is no Kindle edition). Amazon.com added that in the
past four weeks sales rose to 180 digital books for every 100 hardcover copies.
Apparently the pace is quickening. It may interest you that Amazon has 630,000
Kindle books, which is a small fraction of the millions of books sold on the
site.

Meanwhile, Penguine launched the first electronic book with a
video tie-in. Penguin Group and Liberty Media’s Starz Media began selling the
first version — for Apple’s iPad — of a novel with accompanying video from a TV
mini-series based on the same tome. News reports suggest that the deal may serve
as a model for other cross-media partnerships. Priced at $ 12.99, above the
$ 9.99 industry norm for e-books (read Kindle books), Penguin’s iPad
version of Ken Follett’s 12th century England epic ‘The Pillars of the Earth’
will let users read the novel and watch scenes from the mini-series.

While book lovers mourning the demise of hardcover books with
their heft and their musty smell, publishers may need a reality check. Here’s
why. A CEO of media company, which advises book publishers on digital change
said that “This was a day that was going to come, a day that had to come”. He
even predicted that within a decade, fewer than 25% of all books sold would be
print versions. Another CEO commented that “the shift at Amazon is
astonishing
when you consider that we’ve been selling hardcover books for 15
years, and Kindle books for 33 months”. (there you have it, the obvious
and the oblivious — and they coexist in the same business).

India unveils prototype of $ 35 tablet computer :

It looks like an iPad, only it’s 1/14th the cost : India has
unveiled the prototype of a $ 35 basic touchscreen tablet aimed at students,
which it hopes to bring into production by 2011. “This is our answer to MIT’s
$ 100 computer,” Human Resource Development Minister Kapil Sibal told the media
when he unveiled the device.

In 2005, Nicholas Negroponte — co-founder of the
Massachusetts Institute of Technology’s Media Lab — unveiled a prototype of a
$ 100 laptop for children in the developing world. India rejected that as too
expensive and embarked on a multiyear effort to develop a cheaper option of its
own. Negroponte’s laptop ended up costing about $ 200, but in May his
non-profit association, One Laptop Per Child, said it plans to launch a basic
tablet computer for $ 99.

News reports indicate that the tablet can be used for
functions like Word processing, web-browsing and video-conferencing. The tablet
doesn’t have a hard disk, but instead uses a memory card, much like a mobile
phone. The tablet design cuts hardware costs, and the use of open-source
software also adds to savings. It has a solar power option too, though that
add-on costs extra. Without discounting the cost, it seems like a real blessing
when one considers the ever-increasing frequency, not to mention the duration,
of power blackouts in India. A Ministry spokesperson, said falling hardware
costs and intelligent design make the price tag plausible. Apparently, several
global manufacturers, including at least one from Taiwan, have shown interest in
making the low-cost device, but no manufacturing or distribution deals have been
finalised.

India plans to subsidise the cost of the tablet for its students, bringing the purchase price down to around $?20. Kapil Sibal turned to students and pro-fessors at India’s elite technical universities to develop the $?35 tablet after receiving a ‘lukewarm’ response from private sector players. The stated goal is to get the cost down to $?10 eventually.

If the Government can find a manufacturer, the Linux operating system-based computer would be the latest in a string of “world’s cheapest” innovations to hit the market out of India, which is home to the 100,000 rupee ($?2,127) compact Nano car, the 749 rupees ($?16) water purifier and the $?2,000 open-heart surgery. But given the past, one doesn’t know whether this project will die a quick death within this year, or a painful government-funded one over the next two.

Tax returns on Twitter:

Before you jump to any conclusions, it ain’t happening in India yet. Savvy politicians are no strangers to Twitter and Facebook, using it for their own political ends (Obama, Shashi Tharoor, Lalit Modi to name a few of the celebrated users).

Incidentally, Filipinos are among the most prolific users of social networking and text messaging in Asia. Earlier this month, the Philippines’ new government turned to social networking, using it to meet some serious social and economic ends for the country. When most nations are fretting about their fiscal deficits, Manila thought of an innovative way out to bridge the gap: enlisting Twitter and Facebook to boost tax collections. Honest citizens will be allowed to complain about tax evasion and corruption, by posting an update on Facebook or Twitter, when they smell a tax cheat.

No prizes for guessing if this would work in India. After all, India is not just growing to be the land of enthusiastic tweeters, but also the very land of tax evaders and Swiss bank account holders. The question that begs to be answered is, are Indians morally outraged enough about cheating the government that they start telling on their neighbours or will they continue to remain mute spectators? (Jaago re!!!…….)

(The concluding part of this write-up will be printed in the next issue of the Journal)

Vikram Aur Vetal

Cancerous Corruption

Vikram was fond of moving around in the graveyard in the
horrifying night to catch Vetal after day-long practice as chartered accountant.
For Vikram friendship with Vetal was real education. Vetal being a spirit of
intelligent human being frustrated in its lifetime was still on the earth
posthumously to find answers to innumerable questions lingering in his mind
during his stint as human being. He developed friendship with Vikram. After
playing hide and seek game Vikram used to catch Vetal in the wee hours of
morning. Then he would put Vetal on his shoulders and tread through woods of the
graveyard. Vetal would laugh weirdly in the silence of graveyard and thunder :

“So Vikrambhai, you succeeded to catch me once again, keep
walking, don’t look back, if you speak a word I will vanish. Well, I would tell
you an episode you may find utopian. Gopal was an Assessing Officer in the
Income-tax Department. Occasionally he would take bribes from taxpayers, most of
the times under pressure from the higher ups. Otherwise he was Mr. Clean in the
Income-tax Department. At times he would revere social values. His helping
nature was known to all. But his demeanour was utter nuisance for those
indulging in rampant corruption particularly for Duryodhan, an assessing officer
having his cabin next to Gopal’s. He was always on the lookout to trap Gopal and
demolish him. So he would spy in Gopal’s activities in and off the office.

On that fateful day it was post-lunch session. Gopal was
desperate to ‘settle’ the assessment of Dhanraj. Dhanraj along with his
consultant was sitting in front of Gopal and whispering something as Gopal was
busy on the phone. In the previous hearings Gopal had detected a number of
irregularities in Dhanraj’s assessment. Finally those irregularities resulted in
additional income. Anticipating those additions, Dhanraj being a ‘seasonsed’
tax-dodger had already been hinting Gopal about his willingness to ‘comply’ with
his demand to hush up the case with reasonable additions. It was two days
before that fateful day that Gopal had agreed to settle the case for fifty
thousand, most reasonable amount of bribe for a hardcore tax-dodger like Dhanraj.

As I told you earlier, Gopal was not a hardcore corrupt
bureaucrat. Gopal finished his call and said,

“So Dhanraj, did you bring the amount ?”

“Yes Sir” replied Dhanraj.

Again the phone rang. Gopal was listening intently to the
caller on the other end. He responded,

“I will try my level best to arrange something. Don’t keep on
postponing the surgery of your son, come down to my office”.

As soon as he finished the call his assistant peeped in and
informed.

“Sir there is a call from bada sab

While getting out of the chair Gopal said,

“Dhanaraj, I will be back in 10 minutes”

Gopal left the cabin. En route he met Duryodhan who was just
returning back to his cabin. They just greeted each other. As usual Duryodhan
addressed him sarcastically “How are you Dharmaraj ?” Gopal did not respond
verbally, he just chuckled nervously. Driven by suspicion and hatred Duryodhan
intruded in Gopal’s cabin. He saw Dhanraj along with his consultant and
overheard their whispering about how reasonable the ‘amount’ was. Dhanraj being
‘old customer’, Duryodhan greeted him with smile.

“What’s up Dhanraj ?” asked Duryodhan.

“My case is selected for scrutiny Sir” responded Dhanraj.

“Any trouble” queried Duryodhan.

“No trouble Sir, the case will be over today only”said
Dhanraj.

” How much ?” Duryodhan.

“Very reasonable” Dhanraj.

Duryodhan got the required ‘ammunition’ to demolish
‘Dharmaraj’ Gopal, he left the cabin hurriedly. Gopal was still with Bada Sab
nearabout half an hour after Duryodhan’s exit. Dhanraj and his consultant were
anxiously waiting for Gopal’s arrival. There was a knock on the door and an aged
person in his sixties entered the cabin.

“Where is Mr. Gopal ?” he asked with bewildered look at
Dhanraj and his consultant.

“Sir has gone to Bada Sab” Dhanraj replied.

The aged person was about to ask the next question, when
Gopal entered in the cabin and hurriedly sank in the chair. He asked the aged
person to take a seat.

“So Dhanraj, you’ve brought the money ?” asked Gopal.

“Yes Sir” Dhanraj replied.

“Hand over that money to Mr. Sudam (the aged person). Let me
tell you in brief. After two hours from now his son aged about 14 will be
operated for heart ailment, the only hope of Sudam and being retired person he
is not in a position to pay for the operation on his own” explained Gopal. The
moment the envelope containing the money was being handed over by Dhanraj to
Sudam, two persons barged into the cabin.

“Don’t move, stay where you are” ordered one of the two.

“We are from Anti-Corruption Bureau” said one. Gopal realised
that he was caught red handed, but he did not lose his cool. Quickly he
recovered from the shock and requested,

“Sir I am guilty of accepting bribe from Dhanraj, but Sir
please let Mr. Sudam go with the money. I am here to face your interrogation.”

Duryodhan, the protagonist of the raid of ACB, could not
control his excitement and joy. He deliberately came out of his cabin to watch
the ‘demolition drama’. Meanwhile the news of the raid spread like wild fire.

So Vikarmbhai, my question, how do you reckon the acts of
Gopal and Duryodhan ?”

“Vetalbhai, legally speaking Gopal is guilty of accepting bribe, he cannot plead social cause behind the bribe since the Goddess of justice is blind. However socially I still hold Duryodhan guilty of manipulating the law to demolish Gopal who by his conduct invoked Duryodhan’s conscience. He manipulated the law for his own convenience.

Apparently one may appreciate Duryodhan for his alertness to unearth corruption. Vetalbhai, you will agree with me that persons like Gopal are always in minority. Further, a manipulator of law is more dangerous than an occasional offender of law in the society.”

“Vikrambhai, you have broken the silence. I am vanishing” again Vetal’s laugh was echoing in the graveyard.

ICAI And Its Members

ICAI & Its Members

I. CPE programme exemption to senior citizens withdrawn :


1. ICAI has introduced the Continuing Professional Education
(CPE) Scheme under which members are required to attend certain CPE programmes
for specified number of hours. Under this Scheme, exemption was given to members
who have attained the age of 60 years. It is surprising that when our Institute
is entering the 60th year and we are celebrating the Diamond Jubilee year, this
exemption has been withdrawn with effect from 15th May, 2008. One may ask
whether this is a gift to our members who are senior citizens. Notification to
this effect has been published in C.A. Journal for July, 2008 on page 200.

2. CPE learning programms are divided into two parts viz.
structured and unstructured learning as under :

(i) Structured Learning :


(a) Attendance at conferences, seminars and symposia
organised by ICAI, its branches, regional councils, study circles and other
institutions or organisations approved by CPE Committee of ICAI.

(b) Presentation of papers, delivering lectures, acting as
faculty at such conferences, seminars, etc.

(c) Contributing articles in ICAI Journal.

(d) Undertaking technical research under the aegis of ICAI.

(e) Such other activities as may be prescribed by CPE
Committee of ICAI.

(ii) Unstructured learning :


(a) Web-based learning modules.

(b) Self-learning modules and courses (use of audio-tapes,
video-tapes, correspondence courses, computer-based learning programmes).

(c) Reading and individual home study (Reading and
individual home study may constitute reading articles in the C.A. Journal,
reading technical, professional, financial or business literature).

(d) Group or bilateral discussion on technical issues.

(e) Acting as visiting faculty or guest faculty at various
universities, management institutions or institutions of national importance.

(f) Participation in CPE teleconferencing programmes
without the supervision of the Programme Organising Unit (POU).

(g) Providing solutions to questionnaires, puzzles
available on web or professional journals.

(h) Internal training programme being organised by firms of
Chartered Accountants having seven or more partners.

Details of the above learning programmes can be obtained from
pronouncements on Continuing Professional Education Publication of ICAI as well
as from CPE portal (www.cpeicai.org) and ICAI website (www.icai.org).

3. Members residing in India, who are below 60 years of age
and who hold Certificate of Practice, (unless they are exempted) are required
to :

(i) Complete at least 90 CPE Credit hours in each rolling
3-year period (2008-2010). Out of this 60 CPE credit hours should be of
structured learning.

(ii) For the above purpose such member will have to
complete minimum of 20 CPE Credit hours of structured learning in each year.

From the above it will be noticed that structured learning is
mandatory for such member for 60 CPE Credit hours. He will have the option to
devote balance 30 CPE Credit hours in unstructured learning.

4. Members residing in India, who are below 60 years of age
and who do not hold Certificate of Practice as well as all members residing
abroad (whether holding Certificate of Practice or not), unless exempted, are
required to

(i) Complete at least 45 CPE Credit hours of structured or
unstructured learning in each rolling 3-year period (2008-2010).

(ii) For the above purpose, such member will have to
complete minimum of 10 CPE Credit hours of structured or unstructured learning
in each year.


From the above it will be noted that structured learning is
not mandatory for such members. They can take up unstructured learning for the
entire period of 45 CPE Credit hours.

5. As stated earlier, members who have attained 60 years of
age (Senior citizens) were exempt from complying with this requirement. However,
the Council of ICAI has now withdrawn this exemption w.e.f. 15-5-2008. Since 4½
months have passed in the current year, the total period of CPE Credit hours
required to be completed in the rolling period of 3 years (2008-2010) has been
reduced to (i) 70 in the case of such members residing in India and holding
Certificate of Practice and to (ii) 35 in cases of members residing abroad
(whether holding certificate of practice or not) and other members residing in
India and not holding certificate of practice. It may be noted that all such
Senior Citizens will have an option to undertake structured or unstructured
learning. In other words, structured learning is not mandatory for them and they
can select unstructured learning for the entire period of CPE Credit hours.

6. Notification published on page 200 of CA Journal for July
2008 states that Senior Citizen Members (unless exempted) have to complete CPE
Credit hours of structured or unstructured learning as under :

(i) Senior citizen members residing in India and holding
Certificate of Practice — 70 CPE Credit hours in the rolling 3-year period
(2008-2010). Out of this minimum of 10 CPE hours should be in 2008 and minimum
of 20 CPE hours should be in 2009 and 2010 each, respectively.

(ii) Senior citizen members residing in India and not
holding Certificate of Practice and those residing abroad (whether holding
certificate of practice or not) — 35 CPE Credit hours in the rolling 3-year
period (2008-2010). Out of this, minimum of 5 CPE Credit hours should be in
2008 and minimum of 10 CPE Credit hours should be in 2009 and 2010 each,
respectively.


7. It may be noted that under the CPE Scheme, exemption from
the above requirements is available to the following members :


(i) A member, for the year during which he gets his membership for the first time.

(ii) A member or class of members to whom the CPE Committee or its sub-committee may, in their absolute discretion, grant full/partial exemption either specific/general, on account of facts and circumstances of the case which in their opinion prevent such member from compliance with the requirements of completing CPE credit hours

 8. CPE Scheme provides for detailed procedure for keeping records by the Institute about attendance of members who attend structured learning programmes of the Institute and other eligible entities. This enables ICAI to issue certificates for CPE Credit hours completed by the members in every calendar year.

9. As regards unstructured learning, the member who wants to take CPE Credit hours, the requirement is that he should submit a self-declaration Form to the Institute every year. This Form is to submitted to the decentrallsed / sub-decentralised offices of the Institute every year before 31st May. The format of this Form is given on the next page.

10. Considering the above requirements of unstructured learning for members who are senior citizens, it appears that the most convenient mode of learning will be as under:

i) Reading and individual home study i.e., reading articles in the CA. Journal, reading technical, professional, financial or business literature.

ii) Group or bilateral discussion on technical issues –

This will include attendance in group discussions at workshops, study groups, seminars, symposia, conferences, etc. organised by any voluntary body such as a society, association, chamber, group, etc. on technical issues relating to the accounting profession.

iii) Participation at internal training programme organised by firms of Chartered Accountants having seven or more partners.

11. With the above coverage of all senior citizens under the CPE Scheme, it has become mandatory for all members of the Institute (over 1.46 lacs members) to comply with the CPE Scheme. The Institute will have to create a machinery to scrutinise over 1.46 lacs self-declaration forms received from members every year and determine whether all members have complied with the requirements of CPE. In this exercise, the records maintained by the Institute for attendance of members in structured learning programmes will also be required to be considered. ICAI will have to issue comprehensive guidelines about the punishment to be awarded to defaulting members who are holding certificate of practice and those who are not holding certificate of practice.

II. ICAI News

(Note: Page Nos. given below are from c.A. Journal for July, 2008)

1. General amnesty for restoration of names of members and C.P.:

ICAI has introduced an amnesty scheme for restoration of names of members with retrospective effect on payment of certain fees and filing Form No.9. The member can also apply for certificate of practice in Form No.6 prospectively on payment of fees. This scheme will be in force up to 31-12-2008. Details of the scheme are on page 198.

2. Data of members on Board of directors of companies:

ICAI is compiling data about members who are presently working as executive/non-executive/in-dependent directors of public companies (whether listed or not) so that they can share their experience with other aspiring Board members. Such details have to be furnished in the format given on page 201.

3. Chapter at Muscat:

ICAI has decided to set up  a chapter in Muscat. Details are given on page  201.

4. Campus placement programme:

As in the past, ICAI has organised campus placement programme for candidates who qualify in May, 2008, Final examination. The schedule is as under;

(i) 2-9-2008 to 5-9-2008 :
Ahmedabad, Baroda, Chandigarh, Coimbatore, Ernakulam, Hyderabad, Indore, Jaipur, Kanpur, Nagpur, Nashik, Pune and Surat.

ii) 17-9-2008 to 25-9-2008 (excluding  Sunday)  :
Bangalore, Chennai, Kolkata, Mumbai and New Delhi (Details on page 203).

5. Guidance Notes:

The following Guidance Notes issued by Research Committee have been withdrawn by ICAI.

i) Mode of Valuation of Fixed Assets (Revised in 1976)

ii) Guidance  Note  on Accounting  for Changing Prices (Issued in 1982) ./ (Refer page 204)

6. Advertisement by practising CAs:

In July issue of BCA Journal (P. S09) details about this issue are given. ICAI Notification in this respect is published on pages 206 and 208.

7. Approval of Accounting Standard (AS-32) :

The Council of ICAI has approved Accounting Standard (AS) 32, ‘Financial Instruments; Disclosures’. The objective of this Accounting Standard is to require entities to provide disclosures in their financial statements to enable users to evaluate the following;

i) the significance of financial instruments for the entity’s financial position and performance; and

ii) the nature and extent of risks arising from financial instruments to which the entity is exposed during the period and at the end of the reporting period, and how the entity manages those risks.

In view of the above, the Accounting Standard will bring about greater transparency in the disclosures related to financial instruments, such as derivatives and the exposures to the risks related to such financial instruments, and how the entity manages its risks.

It may be noted that ICAI has already issued the related Accounting Standards, namely, Accounting Standard (AS) 30, ‘Financial Instruments; Recognition and Measurement’ and Accounting Standard (AS) 31, ‘Financial Instruments: Presentation’. Issuance of this standard completes Accounting Stardards on the subject of Financial Instruments. Like AS-30 and AS-31, the Council has made AS-32 recommendatory from 1st April 2009 and mandatory from 1st April 2011.

From The President

From The President

Dear Esteemed Readers,

It is indeed a matter of pride and pleasure for me to put
across my thoughts as the newly elected President of this august body. I
visualise your expectations, having been addressed by some of the luminaries in
the profession in the past through this column. Well, it is my privilege to
communicate with you for the next twelve months and I shall strive my utmost to
meet with your expectations.

It is heartening to have received so many compliments from
all over the country upon assumption of office as President of BCAS redounding
to the credit, reputation and popularity that the Society enjoys in the
profession. I sincerely thank one and all for their expression of love,
affection and consideration to me and the BCAS.

Communication is complete when it is well received, so I look
forward to your feedback and suggestions for improvement not only in respect of
my writings but also in respect of any branch of activity of the Society. You
are also at liberty to raise issues concerning the profession as well as social
causes and macro issues concerning citizens at large that you would like to be
addressed by the Society. I believe that intellectuals generally carry greater
responsibility of Nation-Building. Swami Chinmayananda had said : “This Nation
suffers more from the passiveness of good people than aggressiveness of bad
people”. The result is evident in the quality of our national leaders (if at all
they can be called as such). We, therefore, need to become aggressively good. We
must not take injustice lying down. We must take lead in restoring peace and
communal harmony, spreading education amongst the poor and prevent mother earth
from the hazards of global warming by turning it green. We intend to take up
this year many such initiatives which could provide our members opportunities to
participate in nation-building activities along with members of their families.

One area where professionals need to contribute their mite is
in eradication of corruption. Lack of accountability on the part of Government
employees is one of the reasons for this cancerous growth. The Society has
represented to the Government on several occasions to bring about accountability
in the Income-tax Department and has repeated its demand, especially in the
context of the proposed Direct Tax Code. The DTC proposes to introduce General
Anti Avoidance Rules (GAAR) with wide powers to officers. Gandhiji said, “Power
corrupts, and absolute power corrupts absolutely”. Indeed, there is a need for
matching accountability with bestowal of authority. Lack of accountability
coupled with wide powers would worsen the vulnerability of the hapless
taxpayers. The need is to address the issue from the other side of the coin,
i.e., taxpayers must not be lost sight of. To quote Gandhiji again, “There is
enough in the world for man’s need, but not for man’s greed”. According to one
estimate, if only the black money parked abroad by Indians (politicians
included) can be brought back to the country, it can wipe out our external debt.
There can be no two views that tax evasion should be dealt with severely.
However, it should not be at the cost of innocent taxpayers. More often than
not, tax- payers indulge in corruption to buy peace of mind. Given an
opportunity of clean administration and fair assessment, the majority of the
taxpayers would not encourage corruption. In this regard professionals also
carry the responsibility to encourage and support ethical practices. However,
the tug of war is on between the Income-tax Department to extract more from
taxpayers on the one hand, owing to unreasonable targets set for tax collection,
and the inclination of the taxpayers to save more due to greed/provision for the
rainy day on the other. In this context, the approach and transparent
functioning of the Reserve Bank of India is to be appreciated. It is one of the
finest institutions of India. How I wish this culture spreads to every
department of Government.

Computerisation and use of related technology may well be one
of the ways to reduce corruption. Recently a newspaper covered a report about
the wonders wrought by the Government of Chhattisgarh by computerising the
Public Distribution System (PDS). This is how the miracle worked. Chhattisgarh
first created a network of computers across the State, which covered 146
development blocks in 18 districts where details of every beneficiary are put
online. Each beneficiary can also keep track of food stocks through SMS, which
is sent immediately after a PDS shipment is sent from a distribution centre to a
local fair-price shop. SMS informs the beneficiary of everything, including the
date, time, the vehicle number and the stock.

The fair-price shop owners received incentives to stop
pilfering food stocks, and commission for each shop was increased from Rs.8 to
Rs.30 per quintal, with shipments tracked online.

The Public Distribution System is one of the largest leakages
of public money fuelling corruption. It is estimated that there are 23 million
fake ration cards eligible for subsidised food and civil supply. Each fake card
guzzles Rs.8500 of the annual subsidy. With computerisation, regular reviews and
frequent verification, the Government of Chhattisgarh cancelled 1.3 lakhs (below
poverty line) cards during 2002-09. Thus, the reforms in PDS have resulted in a
whopping saving of Rs.100 crore plus, for the State Government so far.

This clearly shows what technology can do or achieve with
political will. Dr. Raman Singh, the Chief Minister of the Chhattisgarh is an
Ayurvedic Doctor and has been re-elected for his good work. The motto of his
Government is aptly reflected on the official website of the State : ‘http://cg.gov.in’ :
“Our focus is on two areas — good governance and good infrastructure. If we can
provide these two, the rest will follow.”

On the ensuing 65th Independence Day, let us all resolve to
contribute our mite to rebuilding India.

Coming back to brass tacks, one of the focal areas this year
would be to bring BCAS to your doorstep by organising various programmes for the
benefit of members in the far-flung suburbs of Mumbai and other important towns
in India. We also intend to organise focussed programmes for members in Industry
and to this end, a Focus Group on ‘Corporate Affairs and Members in Industry’
has been formed. We wish that the benefit of the Society’s activities and the
Journal reach to more and more members, which is why I hereby appeal to our
readers to inform their friends, colleagues and peers about BCAS and its
activities. I am happy to inform you that members from Ahmedabad, Hyderabad,
Indore, Nashik and Surat (who attended the recently concluded Residential Study
Course on Service Tax) have promised to induct new members in order to spread
the activities of the Society. The Study Course was attended by about 80
participants and the level of discussion and bonding amongst members were simply
unparalleled.

I do not wish to deal with other focal areas as the same have
been dealt with in my inaugural address to members published elsewhere in this
Journal.

On the BCAS’s Founding Day Celebrations held on 6th July 2010, the Chief Guest, CA Keki Mistry, Vice-Chairman and the CEO of HDFC Ltd., addressed our members on ‘Lessons from the Global Financial Crisis and the Role of Housing in the Indian Economy’. He shared his optimism for India’s growth in housing sector over the next decade or so, resulting from, inter alia, the demographic advantages and strong banking norms for lending in the housing sector. The lecture was webcast and people around the world watched it live.

The first lecture meeting of the Society for 2010-11 was addressed by the past President of the Society, CA Pinakin Desai on 14th July 2010 on the subject of ‘Recent Developments in Direct Taxation’. It received an overwhelming response, with many members returning home for want of space. I sincerely regret the inconvenience caused to them, but members can simply resort to listening to this lecture from the Society’s website.

By the time you would receive this edition of the Journal, the hectic schedule of July must have been over and the festive August must have made its entry.

It is said, “Coming together is a beginning, keeping together is progress and working together is success”. Let us work together to make BCAS a more powerful force to be reckoned with, comprising proactive, pragmatic and progressive chartered accountants determined to make a positive difference to the profession and the country for a better tomorrow, God willing.

In conclusion, let me wish you all —

A Happy Independence Day, for this memorable day is yonder and it is fitting that we dedicate ourselves — thought, word and deed at the altar of freedom, liberty and independence we all cherish.

So be it.

From The President

From the President

Dear BCAJ Lovers,

It is my proud privilege to
address my first communication to you as the newly elected President of BCAS.
I am daunted by the huge responsibility that is cast upon me and I hope to
complete the year ahead with ease on the back of unstinted support of members
and well wishers of this august body. The large number of congratulatory
messages that I received on my assuming the post of President have left me
speechless. I am thankful to every one of them.

The BCAS year 2009-10 has
begun with a very encouraging event. For the first time in its history, the
BCAS celebrated its Founding Day by combining it with the Budget lecture
meeting. S. E. Dastur, as usual, addressed a packed house of more than 2,000
people in his inimitable style. Apart from these people, a large number of our
members and others also took advantage of the lecture by viewing it online on
a real-time basis. We had arranged a live webcast of the AGM and the lecture
meeting for the benefit of a larger audience. This facility was welcomed by
several members and the response that we received is truly amazing. The web
statistics show that people from USA, UK, Switzerland, Singapore and UAE also
watched the webcast, apart from the large number of our members from all over
the country. This has given us the reassurance that we need and, in future, we
hope to bring more programmes to our members through webcasts.

In the year ahead, we hope to
usher in certain changes at the Society to improve its functioning and also to
reach out to more and more people. We will also strive to encourage younger
members to come forward and take up leadership positions in the Society.

Budget 2009 was preceded by
the usual hype on the part of media. But, it turned out to be much ado about
nothing. Considering the fact that the Finance Minister has promised to table
the new Direct Tax Code very soon, the large number of changes announced in
the Budget could have been held back. The minor tinkering with the threshold
limits will hardly make any difference to the tax payment by individuals.
However, the abolition of surcharge is welcome. The salaried class in the
higher income group will stand to benefit by this change. The abolition of the
infamous FBT will hopefully close a painful chapter in the history of the
Indian tax regime. However, one major grievance that most tax professionals
would have against the Finance Minister would be the manner in which the
Finance Bill is sought to be converted into law. Hardly any time has been set
aside for discussion on the floor of the Parliament. It is obvious that due to
lack of time, the possibility of professionals and trade bodies making
representations to the Government and the chances of the Finance Minister
having the time to read such suggestions are very remote. This is most
unfortunate and does not augur well for a healthy manner of legislation.

The postponement of the new
rules for TDS was expected and was badly required. The unnecessary hurry with
which the CBDT has tried to bring in such sweeping changes without putting in
place the infrastructure to implement the changes could have easily been
avoided. One hopes that in future, the Govt. consults professionals before
taking such decisions. The CBDT must realise that in order to bring about
major changes, it is essential to first win the confidence of the tax-paying
community. In contrast to the attitude of our CBDT, I was amazed to read about
the US Govt.’s proposal to bring in mobile telephone expenses under Fringe
Benefit Tax. There, when the Govt. wanted to bring in one item of expense
under the FBT, the proposal has been placed on the IRS website for public
comment for more than 2 months ! The new rules for remittance of funds out of
India are now in place. The system appears to be working well. However, one
will have to wait and watch how the Income-tax department uses the information
that it will collect. Let us hope that this is not used by them as one more
tool for hounding honest taxpayers and deductors.

The ICAI has recently set up
a Women Steering Group. This group is dedicated to serving women
Chartered Accountants and female students aspiring to be the members of the
ICAI. This is a welcome development. A few years ago, the BCAS had conceived
the idea of creating a special forum for women CAs and it had met with a good
response. Recently, it is observed that the percentage of girl CA students and
lady members has risen considerably. I am sure that with ICAI now taking up
this initiative in a big way, more ladies will stand to benefit.

Finally, as I write this
page, the media has reported that the lone terrorist captured alive during the
Mumbai terror attacks has confessed to his crime. Finally, justice will be
done and the perpetrator of a heinous crime will be suitably punished. This
will not bring back the hundreds of lives which were lost on those fateful
days of November. But at least the world now knows for sure what our
neighbours have been up to.

Ameet Patel

levitra

From The President

From The President

Dear Professional Colleagues,

I wish you all a very happy Diamond Jubilee Year. The Bombay
Chartered Accountants’ Society celebrated its 59th founding day and entered the
Diamond Jubilee Year. I am grateful to all of you for having reposed your trust
in me, and bestowing on me the honour of being the president of this august
institution in a landmark year. I am conscious of the responsibility that this
office carries and I will make every effort to discharge it to the best of my
ability.

I have already expressed my thoughts for the ensuing year in
my acceptance address at the Annual General Meeting, which appears elsewhere in
this issue. To recapitulate, the thrust areas would be


  • A
    comprehensive programme for students — our future.


  • Programmes to reach out to members in industry.


  •  
    Events/programmes to make the busy professional a complete individual.


  • To spread awareness of the activities of the Society among the public.


In this year, various committees of the Society and the
Diamond Jubilee Celebration Committee headed by K. C. Narang and Narayan Varma,
will organise number of programmes to celebrate this year. One of them will be
the Diamond Jubilee Conference scheduled on 8th November 2008. I would request
you to mark the date in your diary.

As I write this piece, the Government has just won a trust
vote. The high-voltage drama which commenced three weeks ago has ended.
Newspapers are filled with stories of how events unfolded in the Parliament.
Many citizens feel that the actions of many to whom we have entrusted the
responsibility of governance, are shameful. When such events occur we feel sad,
but that sadness does not translate into action.

We must share a part of the blame. When enlightened citizens
shy away from public duty, the nation suffers. Corruption is one of the greatest
ills that our country suffers from. The short-term remedy is to keep the members
of the public well informed. To meet that objective, the Right to Information
Act is serving as an excellent tool. However, I fear that its overuse may blunt
this weapon and unscrupulous users may reduce its credibility. In the long term,
an educated citizen will act as a great check to the spread of corruption. I am
under no illusion that education will eradicate this evil, being aware that it
exists in most developed countries where the entire public is expected to be
well educated. It will however, act as a strong deterrent.

In this context of education, I must commend the ‘Teach
India’ initiative. Projects like this must receive all the support they deserve.
I appeal to each one of you, your relatives and family members to enrol for the
programme in whatever capacity possible. We at the BCAS must also find ways and
means and explore as to how as an organisation we can contribute to this cause.

This brings me to the aspect of education in our profession.
Over the last year or so, the curriculum has been changed in a manner that
students entering the course are of a far younger age. Like every change, this
change has had its share of criticism. Every change has its own advantages and
problems. While the technical content of the curriculum is at the same level
that it was earlier, there is little provision to take care of the inherently
lower levels of maturity of the students. The young students joining the course
are bright and many of them are focussed on their careers. However, the
significance of the practical training that is imparted during the period of
articleship is not fully appreciated. This results in conflict and a great gap
between the expectations of students and their employers. The need of the hour
is counselling of students, their parents and Chartered Accountants as well.

This year is also the Diamond Jubilee Year of our alma mater,
the Institute of Chartered Accountants of India (ICAI). The ICAI entered its
Diamond Jubilee Year on 1st July 2008. We at the Society are just 6 days
younger. The Society has always believed that it can play a role complementary
to that of the ICAI. The selfless devotion of its founders, its illustrious past
presidents, its enthusiastic core group have made the Society a premier
institution. In this Diamond Jubilee Year, it is this brand image of the BCAS
that we have to protect, promote and enhance.

For the success of the programmes that the Society will
undertake, I will need your support and I am sure I can bank on it. What I need
further is your response and feedback. Please feel free to communicate with me
or my team, about your thoughts, suggestions and yes, your criticism, for I am
sure that you have the interests of the Society at heart.


With warm regards.
Anil Sathe

levitra

ICAI And Its Members

ICAI and Its Members

1. ICAI News :


(Note : Page Nos. given below are from C.A. Journal
for July, 2010)

(i) Invitation to join CFO Guild/Members in Industry
Guild :


The Committee for Members in Industry of ICAI has invited
members of the ICAS to join two guilds.

1. CFOs Guild (Corporate Accountants Guild) :


This guild is for members who are occupying high positions
(CEO/CFO/Treasury Head/Head of Analyst, GM or above) in industry. The primary
objective of setting up such a guild is to develop a platform where highly
intellectual and talented pool of people from various organisations can discuss
various issues concerning the profession in general and Members in Industry in
particular.

2. Members in Industry Guild :


Members in Industry Guild is for Members serving in
Industries. The primary objective of setting up such a guild is to develop and
maintain an industrywise database of the members of our Institute serving in
industries.

They can plan, formulate and strategise policies for
improving the image of Chartered Accountants in the eyes of the industry.
Industry-specific seminars/conferences/round table meetings can also be
organised to discuss the matters pertaining to the industry and make them the
brand ambassadors of the profession. The Members shall also be appraised of the
various happenings of the Institute, from time to time.

(ii) Formation of CPE Study Circles for Members in
Industry of ICAI :


29 CPE Study Circles for Members in Industry have already
been formed so far by the CMII. A separate helpline for forming CPE Study for
Members in Industry has been established at the Headquarters of our Institute
with Email : cmii_events@icai.in.

(iii) Retention of period of audit documentation :


The Council of the Institute of Chartered Accountants of
India had in August 2009, pursuant to the provisions of Rule 12 of the Chartered
Accountants (Procedures of Investigations of Professional and Other Misconduct
and Cases) Rules, 2007 had amended the audit documentation retention period
appearing as ten years in paragraph 83 of Standard on Quality Control 1 to seven
years.

(iv) For the attention of the candidates who aspire to
appear in various Chartered Accountancy (CA) examinations scheduled during
November, 2010 :


In order to reduce the time taken in processing the OMR
application forms and also to ensure accuracy in the data pertaining to name,
registration No., group/centre/medium opted, it has been decided to make the
filing of examination application forms online at the url http://icaiexam.icai.org/
as the only mode of application for various CA examinations with effect from
May, 2011.

(v) Invitation for articles on XBRL :


To create awareness about XBRL by developing a pool of
knowledge and sharing it, ICAI invites articles on XBRL from members and others
with knowledge/experience in XBRL for publishing in the Chartered Accountant
Journal. Articles may pertain to relevant topics such as basics of XBRL; its
benefits and uses to various users, such as chartered accountants, banks,
income-tax department, financial analysts and others; challenges in implementing
XBRL, etc.

(vi) Recognition to profession :


Our member CA Piyush Goel has been elected to Rajya Sabha
from Maharashtra recently, and our Past President Kamlesh Vikamsey has been
appointed as the Member of Audit Advisory Committee of United Nations
Development Programme. Our heartiest congratulations to them.

(vii) Non-submission of Form 112 :


The following course of action be adopted for dealing with
the cases of condonation of Regulation 65 w.e.f. 1st April, 2010.

It is clarified that the cases for condonation of breach of
Regulation 65 and 78 received up to 31st March, 2010 would be dealt with in
terms of the Announcement dated 8th January, 2010 i.e., general amnesty.

In case a breach of regulation 65 is noticed at the time of
enrolment as a member, the decisions are as follows:

(viii) ICAI publications :


The Committee on Public Finance and Government Accounting is
coming out with a publication ‘Issues on Public Finance’.

(see pages 200 to 203)

2. Transfer price for the purpose of segment reporting (EAC
Opinion) :


Facts :

A company is a public sector enterprise under the
administrative control of the Ministry of Mines, Government of India and is
engaged in mining of bauxite, manufacturing of alumina and aluminum, generation
of power at a captive power plant for use in smelter, and selling of alumina and
aluminum both in domestic and international market.

Cost of power constitutes about 30% of cost of production of
aluminum. The captive power plant is set up exclusively to supply uninterrupted
power to smelter. It is also connected to State grid to take care of the supply
of emergency power to smelter in case of any breakdown or failure at the captive
power plant. Any surplus power after meeting the requirement of smelter is
automatically transmitted to State grid and treated as sale, as per agreement
with company ‘G’, which is a State Government undertaking.

As per the querist, even though the cost of generation of
power is higher, transfer price of power of the purpose of segment reporting is
considered only at 110 paise/kwh, which results in segment loss in case of the
captive power plant (even though the unit is functioning efficiently and up to
the satisfaction of the management) and higher revenue for chemical and aluminum
segments.

Segment report for the quarter ended December 31, 2008 was
examined by the statutory auditors at the time of limited review and they were
of the opinion that though the unit is performing well, as a result of
compliance with the provisions of AS-17 for inter-segment transfers, as stated
hereinbefore, the power segment reveals loss, which does not appear to be a
proper disclosure.

As per the querist, in case the company is allowed to sell
power to parties other than company ‘G’, revenue earned will be at least three
to four time more. However, since the company is largely dependent upon company
‘G’ for emergency power and back-up power, it will not be practicable to delink
from company ‘G’.

From the aforesaid facts, according to the querist, it is
revealed that the circumstances have arisen only because of non-remunerative
sale price and will continue to be the same till the rate charged from company
‘G’ is revised.

Query :

The querist has sought the opinion of the Expert Advisory Committee as to whether in the circumstances explained above, the loss disclosed in the segment report can be explained by way of giving a note with reference to the provision of Accounting Standard or whether any other formula for transfer pricing can be adopted, which may necessitate revision of AS-17 ?

The Committee noted that the basic issue raised by the querist relates to pricing of inter-segment transfers for segment reporting under Accounting Standard (AS-17) Segment Reporting.

The Committee observed that inter-segment transfer pricing is an accounting policy which relates specifically to segment reporting and that inter-segment transfers should be measured on the basis of the enterprise actually used to price those transfers. In other words, the price that is actually used in the books of accounts to reflect the transactions between different segments and the price that is used to reflect segment results for the purpose of segment reporting under AS-17, should be the same. The Committee further observed that AS-17 neither requires nor recommends that inter-segment transfers should be priced in any particular manner, such as competitive markets prices charged to unaffiliated customers for similar goods as stated by the querist.

EAC opinion :

On the basis of the above, the Committee is of the opinion that the company is free to choose any appropriate pricing policy for inter-segment transfers. Thus, the question of explanation of the loss with reference to any provision/requirements of AS-17, if the existing policy of transfer pricing is continued to be followed, by way of a note to the segment report, does not arise. However, if the company chooses, the loss may be explained by way of a note to the segment report, the note should not state that AS-17 requires adoption of that particular pricing policy. Further, revision to AS-17 with respect to the issue raised by the querist is not required.

(see pages 183 to 185)

ICAI And Its Members

1. Disciplinary case :

    In the case of ICAI v. Shri Basab Kumar Sarkar, (C.A. Journal, July, 2009, P. 99) the Bank of Baroda had filed a complaint against the member alleging that the member had misappropriated the funds of its client. According to the Bank, the member opened an SB A/c. (No. 7831) with one of its branches. After some time, the member added the name of his client in the above account as a joint account holder without his client’s knowledge. His client had a separate account in the same branch of the Bank. When its client gave 14 cheques of Rs.22.11 lacs to the member for depositing these cheques in his A/c., the member deposited these cheques in his A/c. 7831 and withdrew the funds. Similarly, certain FDRs of Rs.5 lacs belonging to its client were also used by the member to take loan from the bank and this money was misappropriated by him.

    The Disciplinary Committee found the member guilty of ‘Other Misconduct’. The Council of ICAI accepted this finding and recommended to the High Court to remove the name of the member from the Register for 3 months. The Kolkata High Court, in its order, observed that the member had not co-operated during the course of inquiry. The member did not make any submissions before the High Court. Considering the facts of the case, the High Court has accepted the above finding of the Council and ordered that the name of the member be re-moved from the Register of Members for 3 months.

2. Provision for LTC benefits :

    A Government company was accounting expenditure on leave travel concession (LTC) to employees in the year of availment of leave due to uncertainties in accrual.

    The Expert Advisory Committee has given an opinion that ‘accrual’ being one of the fundamental accounting assumptions, the cost of providing benefits to employees in return for the services rendered by them in an accounting period should be accounted for in that period. AS-15 (revised) 2005 recognizes that the liability towards employee benefits should be provided as and when the services are rendered. Further, this falls in the category of ‘other long term employee benefits’. As per AS-15, LTC benefits should be measured on actuarial basis using the Projected Unit Credit Method. The actuarial basis of valuation takes into account various uncertainties. Therefore, the method adopted by the company was not in compliance with the existing Accounting Standard and the standard accounting principles. (Please refer Pages 136 to 137 of C.A. Journal of July, 2009]

3. Enhancing Audit Quality :

    Financial Reporting Review Board (FRRB) has made certain observations about non-compliance in the published financial statements and Auditor’s Report on P. 138-139 of C.A. Journal, July, 2009. These observations are made on review of the published financial statements with a view that the audit quality is enhanced. These observations are as under :

        (i) AS-20 — Earnings per share :

        (a) Some enterprises disclose the numerators and denominators used in calculating basic and diluted earnings per share. However, they do not disclose the reconciliation between the two denominators which is not in accordance with AS-20.

        (b) In some cases, the enterprises are not considering the weighted average number of equity shares outstanding during the period. This is not in accordance with AS-20.

        (c) In some cases, the enterprises determining the weighted average number of equity shares outstanding during the period considering the number of equity shares as at the beginning and at the end of the year without adjusting the same for the effects of all dilutive potential equity shares.

        (ii) AAS-28 — The Auditor’s Report on Financial Statements :

        In some cases the auditor/partner of Audit Firm does not give his Membership Number. This is in contravention of AAS-28.

        (iii) CARO Report :

            (a) In some cases the auditors do not report on the second part of para 4(iv) which requires the auditor to state whether there is a continuing failure to correct major weaknesses in internal control system.

            (b) In some cases it was noticed that CARO report is addressed to directors whereas it is required to be addressed to the members.

4. Secondment of articled assistants :

    It is possible to send an articled assistant to another member entitled to train articled assistants for an aggregate period of one year during the period of articleship. The following Rules for this purpose are given on P. 150 of C.A. Journal, July, 2009.

    (i) A principal may, with the consent of the articled assistant, second from time to time the articled assistant to other member or members with a view to provide the articled assistant the opportunity of gaining practical experience in areas where the principal may not be in a position to provide the same.

    (ii) The articled assistant shall be seconded only to a member who is entitled to train one or more articled assistants in his own right or to a member in industry who is entitled to train one or more industrial trainees.

    (iii) The member to whom the articled assistant is seconded will not be entitled to train more than two such assistants on secondment at a time.

    (iv)(a) The maximum period of secondment shall be one year which may be served with a single eligible member.

    (b) The Council may permit secondment with more than one such member provided the minimum period of secondment shall be four months and the aggregate period served on secondment with such members shall not exceed one year.

    (v) Where an articled assistant is seconded to a member in industry, the total period spent in industry by the articled assistant, including the period of industrial training under the Regulations, shall not exceed one year.

    (vi) During the period of secondment, the member with whom the articled assistant is seconded shall pay the stipend as provided under the Regulations.

    (vii) The member with whom the articled assistant is seconded shall be responsible for imparting training during secondment. He shall maintain records of practical training undergone by the articled assistant during secondment and forward the same to the principal on completion of period of secondment. The principal shall include required particulars in the report to the Council under Regulation 64.

viii) A statement in the form approved by the Council shall be sent to the Secretary for records within thirty days from the date of commencement of training on secondment.

5. Accounting  and  Internal  Audit  Standards:

i) Exposure  Draft  of AS-16  :

Borrowing Costs (Revised) has been published by ICAI for comments before 10th August. There is no major difference between the revised AS-16 and IAS-23 except in respect of application of the standard to borrowing costs that are directly attributed to the acquisition, construction or production of inventories that are manufactured or otherwise produced in large qualities on a repetitive basis. (Refer P.155 of CA. Journal, July, 2009).

ii) Exposure Draft of Standard Internal Audit (SIA) :

This standard deals with ‘Consideration of Laws and Regulations in an Internal Audit’. This standard deals with Internal Auditor’s responsibility to consider laws and regulations when performing an Internal Audit or such other review exercise with the objective of providing assurance thereon. The draft is published on pages 168-173 of CA. Journal of July, 2009.

6. Accounts and Audit of Limited Liability Partnership (LLP) :

LLP Act and Rules have now come into force from 1-4-2009. The Sections relating to conversion of firms and private and public unlisted Companies into LLP have also come into force from 31-5-2009. The Finance (No. 2) Act, 2009, recently enacted, provides that LLP will have to pay tax under the Income-tax Act in the same manner as a Firm. Therefore, LLP will not be required to pay MAT, Dividend Distribution or Wealth tax. The provisions relating to accounts and audit of LLP are as under:

i) U / s.34 of the LLP Act, an LLP has to maintain the books of accounts as prescribed in Rule 24. Such books may be maintained either on cash basis or accrual basis of accounting.

ii) LLP has to follow accounting year from April to March only. It cannot choose any other accounting year.
    
iii) Rule 24 provides that the above books of accounts should be preserved for 8 years.

    iv) The above accounts have to be audited by Chartered Accountant(s) if the turnover of LLP exceeds Rs.40 lacs or the contribution by the partners exceeds Rs.25 lacs.

    v) The designated partners of LLP or the partners shall appoint an auditor or auditors as under:

  • For first financial year before the end of the year.
  • For subsequent years, atleast 30 days before the end of the year.
  • For filling up the casual vacancy in the office of the auditor.
  • For filling up the vacancy caused by removal of an auditor.

    vi) The auditor appointed as above shall hold office for the financial year for which he is appointed. He shall hold such office till any other person is appointed as auditor.

    vii) The partners of LLP can remove an auditor from his office at any time by following the procedure in LLP agreement.

    viii) An auditor of LLP can resign by giving notice to LLP. If he does not want to be reappointed he shall give atleast 14 days notice.

    ix) The remuneration of the auditor may be fixed by the designated partners of LLP or by fol-lowing the procedure laid down by the LLP Agreement.

    x) LLP has to get the accounts audited each year on or before 30th September and file Statement of Account and Solvency in Form No. 8 with ROC on or before 31st October with the pre-scribed fee. LLP is also required to file Annual Return in Form No. 11 with ROC with pre-scribed fee within 60 days of the close of the financial year (i.e., before 31st May).

    xi) The LLP Act or Rules do not prescribe the form of profit & loss A/c. and balance sheet or the form of audit report which the auditor has to give. Therefore, ICAI will have to recommend these forms for the guidance of our members. Form No. 8 provides for information to be given to ROC about assets, liabilities, income and expenditure. It also states that auditor will have to give a certificate in the following form.

“It is hereby certified that I have verified the particulars in the statement of Account and Solvency including the Statements of Assets and Liabilities as at ……………. and the Income and Expenditure for the period ending …………….. from the accounting records and other books and papers of (LLP) and found than to be true and fair.”

7. New  Publications  of ICAI :

  •     Technical Guide on Estimation of Future Cash Flows and Discount Rates for the purpose of AS-28 – Impairment of Assets (P. 146 of CA. Journal, July, 2009).
  •     Study on Benefits of Preferential Trade Agreements (P. 153 of CA. Journal July, 2009).
  •     Taxation of Charitable Trusts and Institutions – A Study.
  •     Data Analysis for Auditors (Practical Case Studies on using CAA T’s).
  •     Motor  Third  Party  Claims  Management.
  •     Clean Development Mechanism and Carbon Credits – A Primer.
  •     Professional Opportunities for Members – An Appraisal.

Miscellaneous

From Published Accounts

Section B: Miscellaneous


4 Qualification regarding non-provision of disputed statutory
liabilities

Sterlite Technologies Ltd. — (31-3-2010)

From Notes to Accounts :

The Company had in an earlier year received an order of
CESTAT upholding the demand of Rs.188 crores (including penalties and excluding
interest) (Rs.188 crores as at March 31, 2009) in the pending excise/custom
matters on various grounds. The Company’s appeal with the Honourable High Court
of Mumbai was rejected on the grounds of jurisdiction. The Company preferred an
appeal with the Honourable Supreme Court of India against the order of CESTAT,
which has been admitted. The Company has reevaluated the case on admission of
appeal by the Supreme Court. Based on their appraisal of the matter, the legal
advisors/consultants are of the view that under the most likely event, the
provision of Rs.5 crores made by the Company against the above demand is
adequate. The management is confident of a favourable order and hence no further
provision is considered against the said demand.

From Auditors’ Report :

As stated in Note No. 8 of Schedule 21, the Company had in an
earlier year received an order of CESTAT upholding a demand of Rs.188 crores
(including penalties and excluding interest) (Rs.188 crores as at March 31,
2009) in a pending excise/customs matter. The Company’s appeal against this
order with the Supreme Court has been admitted. Based on the current status and
legal advice received, provision for liability as recorded in the accompanying
financial statements is considered adequate by the management. In the event the
decision of the Supreme Court goes against the Company on any of the grounds of
appeal, additional provision against the said demand may be required. Pending
disposal of the matter by the Supreme Court, the amount of excise/customs duty
payable, if any, is currently unascertainable. Our audit report on the financial
statements for the year ended March 31, 2009 was qualified in respect of this
matter.

In our opinion and to the best of our information and
according to the explanations given to us, the said accounts give the
information required by the Companies Act, 1956, in the manner so required and
subject to the effect of the matter referred to in paragraph vi above give a
true and fair view in conformity with the accounting principles generally
accepted in India.

5 Provisions made in earlier year towards loss of inventory,
expected higher sales returns and expected reversal of export benefits partly
reversed during the year

Ranbaxy Laboratories Ltd. — (31-12-2009)

From Notes to Accounts :

On 16 September 2008, the Company received two warning
letters and an Import Alert from the United States of America (USA) FDA,
covering 30 generic drugs being manufactured at its Paonta Sahib and Dewas
manufacturing facilities in India. The issue raised in the warning letters
relate to ‘Current Good Manufacturing Practice’ being followed at the said
plants and does not in any way raise questions on product’s quality, safety or
effectiveness.

In 2008, consequent to Import Alert, the Company was not able
to sell the products covered under Import Alert, and accordingly, it had
recorded a


provision of Rs.2,631.11 million in that year, towards inventory, expected sales
return and related exports benefits.

On 25 February 2009, the Company received a letter from the
US FDA indicating that the Agency had invoked its Application Integrity Policy
(‘AIP’) against the Paonta Sahib facility (the ‘facility’). The management of
the Company believes that there was no falsification of data generated at the
facility and also believes that there is no indication of a pattern and practice
of submitting untrue statements of


material facts and there was no other improper conduct. Accordingly, the
Company, based on opinion from its legal council, believes that there is no


incremental present obligation existing at the balance sheet date on account of
these notices.

The Company continues to fully cooperate with the concerned
authorities for their final clearance, pending which there would be delays for
new


product approvals and sale of existing products in the United States of America.
During the current year, the Company has performed a re-assessment of the amount
of provisions created in 2008 and reversed a provision of Rs.937.81 million
which is included in unclaimed balances/excess provisions written back, which in
view of the Company is no longer required now.

In the year 2008, the Department of Justice (DOJ), USA had
filed certain charges against the Company citing possible issues with the data
submitted by the Company, in support of product filing. The Company continues to
work diligently with the concerned authorities towards resolution of the issue.

From Auditors’ Report :

Without qualifying our opinion, we draw attention to Note 2
on Schedule 23 of the financial statements. Consequent to the Food and Drug
Administration (FDA) of the United States of America import alerts and the FDA
letter dated 25 February 2009 imposing the Application Integrity Policy, the
Company had recorded provision of Rs.2,631.11 million during the year ended 31
December 2008 towards loss of inventory in hand, expected higher sales returns
and, expected reversal of export benefits. The basis and assumptions used by the
management in calculating these provisions were based on significant judgment
and estimates due to involvement of uncertainty, and actual result could have
been different from the management’s estimate.


6 Non-provision of diminution in Consolidated Financial
Statements (CFS) for fall in value of loan given by Joint Venture company to
ESOP Trust

Godrej Consumer Products Ltd. — (31-3-2010)

From Notes to Accounts to CFS :


Stock options have been granted to eligible
employees of the Joint Venture of the Company under an ESOP scheme instituted
by the Joint Venture company. The equity shares of Godrej Industries Ltd. are
the underlying equity shares for the stock option scheme. The ESOP is
administered by an independent ESOP trust created with IL&FS Trust Company
Limited which acquires by subscription/purchase or otherwise, the shares of
Godrej Industries Ltd. equivalent to the number of options proposed to be granted.
The Joint Venture Company has given a loan of Rs.5,940.00 lac to the ESOP trust
to finance the purchase of such equity shares. As at March 31, 2010, the market
value of the equity shares of Godrej Industries Ltd. are lower by Rs.2,239.69
lac as compared to the cost of acquisition of these equity shares. The
repayment of the loan granted to the ESOP trust is dependant on the exercise of
the options by the employees and the market price of the underlying shares of
the unexercised options at the end of the exercise period. The fall in the
value of the underlying equity shares is on account of current market
volatility and the loss, if any, can be determined only at the end of the
exercise period. In view of the aforesaid, provision for diminution of
Rs.2,239.69 lac has not been considered necessary in the accounts of the Joint
Venture. The Group’s 40% share in the above diminution amounts to Rs.1097.45
lac.


From Auditor’s Report on CFS :

We draw attention to Note 15(i), Schedule
15 : Notes to Consolidated Accounts, where it has been stated that a Joint
Venture company has given a loan of Rs.5,940.00 lac to its ESOP trust to
finance the purchase of the equity shares of Godrej Industries Ltd., being the
underlying equity shares for the stock option scheme. As at March 31, 2010, the
market value of the equity shares of Godrej Industries Ltd. are lower by
Rs.2,239.69 lac as compared to the cost of acquisition of these equity shares.
The repayment of the loan granted to the ESOP trust is dependant on the
exercise of the options by the employees and the market price of the underlying
shares of the unexercised options at the end of the exercise period. The fall
in the value of the underlying equity shares is on account of current market
volatility and the loss, if any, can be determined only at the end of the
exercise period. In view of the aforesaid, provision for diminution of
Rs.2,239.60 lac has not been considered necessary in the accounts of the Joint
Venture. The Group’s 49% share in the above diminution amounts to Rs.1,097.45
lac.

Section B : Miscellaneous

ORDERS OF CIC

fiogf49gjkf0d

Right to information

Part A: ORDERS OF CIC


S. 8(1)(e) & (h), S. 11 and S. 22 :


The first time a multi–member Bench of the Central
Information Commission has not given a unanimous decision. It is a split
decision. Two Information Commissioners : Mr. A. N. Tiwari and Mr. Satyananda
Misra delivered one decision and Information Commissioner Mr. Shailesh Gandhi
delivered the counterdecision.

Mr. C. Seetharamaiah (Mr. CS) made an RTI application to the
Commissionerate of Customs and Central Excise (CCCE), in which he requested for
the correspondence, telephone conversations, etc. between the Central Bureau of
Investigation (CBI) and CCCE in connection with the prosecution under the
Prevention of Corruption Act launched
on his son who was working as an Inspector of Central Excise.

The CPIO and the AA denied the information stating that if
furnished, it would impede the process of prosecution, exemption being covered
u/s.8(1)(h).

Further, the AA stated that as the information sought for
includes the third party’s (CBI) investigation report, the matter was referred
to CBI and it had replied that the same may not be revealed as the case is under
trial and parting with these documents would impede the prosecution of
offenders.

Due to the fact that certain important points of law needed
to be decided, the matter was referred to a three-member Bench by Mr. A. N.
Tiwari.

In the proceedings of this matter, all 3 parties viz.,
Mr. CS, CCCE and CBI made extensive submissions: Mr. CS submitted that the very
purpose of the RTI Act would be defeated if such information is not furnished.
“The officers who are being prosecuted for matters pertaining to discharge of
their official duties, if innocent, have to go through the vexatious prosecution
for years together. Revealing of information, as provided under the Right to
Information Act, 2005, may hasten the judicial process and help the innocent. As
already held by the Central Information Commission, there cannot be misuse of
the truth and the information available to a prosecutor should be made available
to the alleged offender also. It would be appreciable for everyone if the pace
of the judicial process is increased with the help of information obtained under
spirit of democracy.”

The CCCE and CBI argued that an accused in an ongoing
prosecution should not be allowed to access any information which may be
evidence in that prosecution. An accused in ongoing prosecution is free to
demand such information from the Trial Court and it is a matter which is
entirely within the jurisdiction and the discretion of the Trial Court.

Two members stated that the word ‘impede’ used in
S. 8(1)(h) holds the key to whether information requested by the appellant
should be allowed to be disclosed.

It was also the two members’ view that information which is
evidence or is related to evidence in an ongoing prosecution comes under the
control of the Trial Court within the meaning of S. 2(j) of the RTI Act, which
states as follows :


‘ “right to information” means the right to information
accessible under this Act which is held by or under the control of any
public authority and includes the right to . . . . . .’


I now reproduce 3 paras (part or full) of the decision :

28. It is significant that this S. 2(j) uses two
expressions about the location of given information, i.e., ‘held’ and
‘under the control of’. In our view, expression ‘held’ implies that a public
authority has physical possession of given information. The word ‘under the
control of’ implies that the information, regardless of which public authority
holds it, is under the control of a specific public authority on whose orders
alone it can be produced in a given proceeding. In the present case, the
material sought by the appellant is undoubtedly related to an ongoing Court
proceeding and hence it can be rightly said to be under the control of the
Trial Court, who alone can decide how the information is to be dispensed. Any
action under the RTI Act or any other Act for disclosure of that information
to the very party who is arraigned before the Trial Court or to anyone
representing that party, would have the effect of interfering with the
discretion of the Court, thereby impeding an extant prosecution proceeding.

29. Since the Information requested by the appellant is
under the control of the Trial Court, it is open to the appellant to approach
that Court through an appropriate proceeding under the criminal laws or if he
so wishes, u/s.6(1) of the RTI Act. The Court can then take action u/s.2(f) of
the RTI Act in case it decides that the petitioner should be allowed access to
the information he had requested. The key point is that either of these two
actions has to be before the Trial Court and not the respondent-public
authority (viz. Office of Commissioner of Customs, Central Excise and
Service Tax) or the third party (viz. CBI) as in this case. We agree
with the respondents that the integrity of a criminal proceeding before a
Trial Court in matters of what to allow to be produced as evidence should be
taken by the Court itself and not otherwise. We also note the fact that under
criminal laws, a public authority is authorised not to produce a certain
information or record in the Trial Court unless so directed by the Court
itself. Forcing the public authority to part with any such information — which
it would otherwise not have disclosed before the Trial Court — through an RTI
— proceedings would amount to imposing on the prosecuting public authority,
obligations which it was not obliged to bear.

30. It is, therefore, important that all determinations
about disclosure of any information relating to an ongoing prosecution should
be through the agency of the Trial Court and not otherwise.

The two members further noted :

33. According to the preamble to the RTI Act, one of the
purposes the Act designed to sub-serve was to combat corruption. We look
askance at any effort to convert the RTI Act into a tool to weaken the edifice
of law which seeks to bring to book errant public servants, especially when
such public servants have all the means available to them to present their
case before the Trial Court and seek from it the very information they now
want them to be provided through the RTI Act.


34.       The two members also noted that their
decision is also backed by the fact that the whole matter falls within the
ambit of S. 11(1) read with S. 7(7) of the Act since “it relates to or has been
supplied by a third party and has been treated as confidential by that third
party…..”


CBI had argued
that its objection to disclosure of information u/s.11 can be ignored only if
“public interest in disclosure outweighs in importance any possible harm or
injury to the interests of such third-party”.


CBI had argued
that there was no public interest. On the contrary, public interest is
positively harmed when interested parties are given the privilege of
interrogating a prosecuting agency about its actions vis-à-vis that party
through an RTI — proceeding when the prosecution before a Trial Court is
already extant.


Based on the
above, two members took the view: “Neither the provisions of the RTI Act, nor
the canons of justice, or equity commend disclosure of information as requested
by this appellant.”


Dissenting
decision:


IC Shailesh
Gandhi came to the conclusion that the information sought must be disclosed,
since there are no reasons in law to deny the information. IC writes thus:

“The
Commission’s decisions have been unanimous so far, and I am hesitant to break
this tradition. But I believe when there are different views on transparency,
it is worthwhile to voice them. I am inspired by Justice Mathew who had said in
the Supreme Court in State of UP v. Raj Narain (1975), ‘in a government of
responsibility like ours, where all the agents of the public must be
responsible for their conduct, there can be but few secrets. The people of this
country have a right to know every public act, everything that is done in a
public way, by their public functionaries. They are entitled to know the
particulars of every public transaction in all its bearing. The right to know,
which is derived from the concept of freedom of speech, though not absolute, is
a factor which should make one wary, when secrecy is claimed for transactions
which can, at any rate, have no re-percussion on public security. To cover with
veil of secrecy, the common routine business, is not in the interest of the
public. Such secrecy can seldom be legitimately desired. It is generally
desired for the purposes of parties and politics or personal self-interest or
bureaucratic routine. The responsibility of officials to explain and to justify
their acts is the chief safeguard against oppression and corruption.” I
sincerely believe that India could benefit immensely from RTI which is but a
search for the truth as it exists on the records of public authorities. Denial
of information must be an exception, since it is a denial of the fundamental
right of the sovereign citizen of India, and must rigorously meet the
requirements of the exemptions of S. 8(1) of the RTI Act. I cannot agree to
views which I feel do not reflect the law in letter and spirit.


He first dealt
with submissions of CBI that S. 8(1)(e) and S. 8(1)(h) and S.11 are applicable.


He held that for
S. 8(1)(e) to apply, there must be a fiduciary relationship and the holder of
information must hold the information in his fiduciary capacity. All
relationships usually have an element of trust, but all of them cannot be
classified as fiduciary. In these relationships, the lawyer and the doctor act
on behalf and in the interest of their client and patient. But in the present
case the Department would not be considering the report on behalf of CBI or in
the interest of any particular entity or individual. Therefore exemption
u/s.8(1)(e) claimed by the CBI is not tenable under the Right to Information
Act.


Mr. Shailesh
Gandhi then referred the provisions of S. 22.


“S. 22
provides:

The provisions
of this Act shall have effect not-withstanding anything inconsistent therewith
contained in the Official Secrets Act, 1923, and any other law for the time
being in force or in any instrument having effect by virtue of any law other
than this Act.”


He quotes
Justice Sanjeev Khanna of the High Court of Delhi in ‘Union of India v. CIC’:

“S. 22 of the
RTI Act gives supremacy to the said Act and stipulates that the provisions of
the RTI Act will override notwithstanding anything to the contrary contained in
the Official Secrets Act or any other enactment for the time being in force.
This nonobstante clause has to be given full effect to, in compliance with the
legislative intent.”


The two members
had taken the view that S. 8(1)(h) applies. Two reasons were given for it.


One: Disclosing
names of the officials involved in the report would impede the prosecution. Mr.
Gandhi argued?: “The officials may claim exemption u/s.8(1)(g), but this would
again be open to judicial scrutiny by the Commission and would not be
necessarily accepted. Even if this were accepted, the Commission u/s.10 could
direct severance of the names of the officers mentioned in the report.”


Two: According
to Mr. Gandhi, no reasons have been advanced showing how the prosecution would
be impeded by disclosing the information. When denying a right to the citizen,
it has to be established beyond doubt that prosecution or apprehension of an
offender would be impeded. This has not been done. If the Parliament wanted to
exempt all information which was the subject matter of a prosecution, it would
have said this. The Parliament has specifically exempted only the information
which would ‘impede’ the process of investigation or prosecution.


Further, he
writes:


“The argument
that the information can be made available to the appellant’s son in
accordance with the provisions of the Criminal Procedure Code is in itself
self-defeating. This is because it establishes that CBI and the prosecuting
agencies have no objection in the appellant’s son accessing the information per
se. Their objection is to the route adopted and to the fact that the Commission
may order the disclosure of information. The majority decision appears to subscribe
to this. With regard to the Right to Information Act, the Commission is the
final decision-making body. The Trial Court has jurisdiction over matters
coming before it, but not over appeals and complaints under the Right to
Information Act. The Commission cannot abdicate its re-sponsibility and
authority in deciding about disclosure of information under the RTI Act to any
Court. The existence of an alternative route to access information, does not in
itself provide an exemption to disclosure u/s.8(1) of the RTI Act. Unless the
information sought is proven to be exempt u/s.8(1) or 9 of the RTI Act, the
Commission cannot accept any other exemption external to either of these
provisions. The CBI has not advanced any spe-cific argument to show how the prosecution
would be impeded to claim exemption from disclosure u/s.8(1)(h).


Mr. Shailesh
Gandhi contradicts the interpretation of the majority decision on S. 2(j)
referred to in para 28 (supra). He states:


“The word used
in the provision is ‘or’ and not ‘and’. Thus information may be sought either
from the public authority holding the information or the public authority
having control over the information. The Parliament has deliberately drawn this
distinction as in some cases these two public authorities may be two entirely
different entities. Therefore, if a public authority holds the information, it
must provide the same to the RTI applicant in accordance with the provisions of
the RTI Act. It is not at all necessary for that public authority to control
that information as well. In the present case, the Trial Court may have control
over the record, but the CBI is the public authority holding the SP report.
Therefore, the SP report can be sought from the Commissioner of Customs &
Central Excise or from the Trial Court. Since the appellant has sought it from
the Commissionerate, the public authority holding the information must provide
the same.”


As to arguments
advanced for application of S. 11,

Mr. Shailesh
Gandhi writes:

“It is clearly
stated at S. 11(1) that ‘submission of third party shall be kept in view while
taking a decision about disclosure of information’. S. 11 does not give a third
party an unrestrained veto to refuse disclosing information. It only gives the
third party an opportunity to voice its objections to disclosing information.
The PIO will keep this in view and take a decision about disclosure of
information. If the PIO comes to the conclusion that the exemptions of S. 8(1)
apply, he may refuse to disclose the information.”


“S. 11 of the
RTI Act is a procedural provision which requires the PIO to approach a third
party if the information sought relates to such third party. S. 11 is not a
substantive provision and therefore is not an exemption in addition to those
provided in S. 8(1) and S. 9. Once the PIO receives the objections, raised by
the third party, he must keep these in view while deciding whether to disclose
the information or not. This decision has to be in consonance with the other
provisions of the RTI Act and therefore exemptions claimed by the third party
have to be justified by the PIO u/s.8(1) or S. 9. The provision of S. 11(4)
gives the right to the third party to appeal against the decision of the PIO.
This would not have been relevant if the mere denial by the third party of
disclosure of information were to be considered to be final.


Then disagreeing
with the contention raised in para 33 (supra), he writes?:

“I most
respectfully disagree with this contention since it appears to propound a
principle that an accused in a corruption case can be denied his fundamental
right. Right to Information is a fundamental right of the citizens codified by
the RTI Act, 2005. A fundamental right cannot be curtailed arbitrarily and
without the sanction of law. It does not matter if the person accessing the
information or the person in relation to whom information is sought is a
convict or an accused. He cannot be denied his fundamental right. The duty of
the Commission is to ensure that the RTI Act is implemented properly and to ensure
that it does not take into account extraneous considerations while deciding on
appeals and complaints before it.”


Finally, paras
51 and 52 of his decision:

51.  To summarise:


(a)        The information sought is not exempt
u/s.8(1)(e) or (h) for reasons explained above.

(b)        The RTI Act clearly overrides all other
prior Acts in matters of disclosures of information as per S. 22.

(c)        Refusal of information can only be based
on the RTI Act, when an application is made under this Act. The Commission is a
creation of the RTI Act and can only agree to denial of information which is
expressly exempted u/s.8(1) or u/s.9 of the RTI Act.

(d)       If there are various routes by which a
citizen can access information, it is his prerogative to use one which he finds
convenient.

(e)        S. 11 is not a provision which can be
used to justify exempting information from being disclosed, unless it is
covered by S. 8(1).


52.       In view of the reasons stated above, I
find the arguments put forward for the denial of information to be untenable.
Hence I cannot agree with the majority decision, and it is my considered
opinion that the information sought by the appellant is not covered by the
exemptions of S. 8(1) of the RTI Act and hence should be disclosed.


Note?: Full
decision shall be posted on website of BCAS and PCGT for anyone interested in
reading these extremely well-reasoned two counter decisions.


[Mr. C.
Seetharamaiah v. Commissionerate of Customs & Central Excise (Third Party?:
Central Bureau of Investigation)?: Appeal No. CIC/ AT/A/2008/01238 dated
19-9-2008 — decision dated 7-6-2010]


PART B: THE
RTI ACT


Payment of
fee under the RTI Act, 2005:


S. 6(1), S. 7(1)
& S. 7(5) provide for fee payable for accessing information being
application fee and fee for information supplied in photocopies, print or in
any electronic format. Proviso to S. 7 states that the fee prescribed by the
rules shall be reasonable. DoPT of Persmin, Government of India vide office
Memorandum (No. 12/09/2009.IR) has issued some clarifications on this subject.
The same are summarised hereunder?:


  •        
    The Rules or the Act do not give power to the
    PIO to charge any fee other than prescribed in the Fee and Cost Rules.
  •    
    Attention is drawn to the common order of the
    CIC in one appeal and one complaint which reads as under:

            “Thus, there is provision for
charging of fee only u/s.6(1) which is the application fee: S. 7(1) which is
the fee charged for photo-copying, etc. and S. 7(5) which is for getting
information in printed or electronic format. But there is no provision for any
further fee and if any further fee is being charged by the public authorities
in addition to what is already prescribed u/s. 6(1), u/s.7(1) and u/s.7(5) of
the Act, the same would be in contravention of the Right to Information Act.
The ‘further fee’ mentioned in S. 7(3) only refers to the procedure in availing
of the further fee already prescribed under 7(5) of the RTI Act, which is
‘further’ in terms of the basic fee of Rs.10. S. 7(3), therefore, provides for
procedure for realising the fees so prescribed.”


·        
It is hereby clarified that where a Public
Information Officer takes a decision to provide information on payment of fee
in addition to the application fee, he should determine the quantum of such fee
in accordance with the fee prescribed under the Fee and Cost Rules and give the
details of such fee to the applicant together with the calculation made to
arrive at such fee. Since the Act or the Rules do not provide for charging of
fee towards postal expenses or cost involved in deployment of manpower for
supply of information, etc., he should not ask the applicant to pay fee on such
account.


Part 3 :
INFORMATION ON & AROUND


·        
Appointments of Information Commissioners


The Government
will be appointing 22 commissioners this year. Of the 22 commissioners who are
retiring, six are with the Central Information Commission, including its chief
Wajahat Habibullah.


In August 2008,
DoPT recommended its Secretary S. N. Mishra, Annapura Dixit, Ashok K.
Mohapatra, R. B. Shreekumar, M. L. Sharma and Shailesh Gandhi for appointment
as information commissioners in the Central Information Commission.


Except  Gandhi, 
whose  name  was 
proposed  by several RTI
activists, names of the others were not recommended by anyone. But their
bio-data got included in the proposal for appointment of information
commissioners.


On the other
hand, three persons — Ravi Shankar Singh, Sudhanshu Ranjan and Dr. Krishna
Kabir Anthony — who applied and were also recommended by politicians did not
find a place in the agenda for the selection committee headed by the Prime
Minister. There were 12 others like them.


Arvind Kejriwal
who got the above info under RTI query says:

“it appears the
DoPT has become the de facto selection committee and the selection committee
provided under the law has been reduced to an endorsement committee.”


·        
BMC employees not being transferred:


Months after
Bandra residents managed a landmark victory forcing the transfer of at least
eight engineers who had been tossed around in the H-West ward for 20 years, an
RTI query has revealed that a similar situation exists in Andheri as well. As
many as 50 employees, including peons, engineers and clerical staff, haven’t
been transferred, some since the 80s.


The RTI query
filed by activist Aziz Amreliwala revealed that despite the BMC Rules that make
rotation of officials mandatory every three years, at the K/East ward, 11
engineers, including sub, junior and assistant engineers, have enjoyed the same
post for several years. In fact, some of them have even been promoted. Experts
blame a nexus between officials and politicians that make the transfers of
employees impossible.


·        
Maharashtra Chief IC


Dr. Suresh
Joshi, Chief Information Commissioner retires on 12-10-2010 (exactly on the 5th
anniversary of RTI).


Political
activist Chandrashekar Prabhu, additional chief secretaries M. Rameshkumar and
Bhupati Prasad Pandey, retired bureaucrats Leena Mehandale, S. S. Hussain and
state human rights commission member Subhash Lala are prominent among the
150-and-odd persons competing for the post of the State CIC.


Dr. Joshi has
gone on leave and entrusted his task to the junior-most IC, Ramanand Tiwari.
Other Information Commissioners who are senior to Mr. Tiwari have taken
objection to the decision of Dr. Joshi.


Ever since the
appointment of retired IAS officers as info commissioners, a cold war is on
between IAS and non-IAS commissioners. When the process of appointment of
Information Commissioners was in progress, activist Anna Hazare had personally
called on the then CM and President of India, saying that the Government should
not appoint retired babus for such sensitive posts. Currently out of the 7
commissioners, 3 are retired IAS and 4 are non-IAS officers.


Meanwhile, over
42 serving and retired IAS officials and 89 individuals have applied for the
post of info commissioners. The Nashik Information Commissioner’s post is lying
vacant. Aurangabad IC died in July 2010.


·        
Panchayati Raj Ministry:


The Panchayati
Raj Ministry, responsible for decentralisation and local governance in states,
but more importantly, empowering the rural poor, has been spending crores every
year as rent on space acquired at a 5-star hotel in south Delhi being 5,500
sq.ft. space on the sixth floor of Samrat Hotel in Chanakyapuri.


This information
came to light in reply to an RTI application filed by a Delhi-based activist.
Rent per month was `190 per sq.ft., for a period of two years commencing from
September 1, 2006, to be extended further with an increase of 8% after expiry
of the tenure. After the period lapsed on August 30, 2008, the present rate of
rent became `210.60 per sq.ft., from September 1, 2008. The total adds up to
more than `5 crore spent as rent so far.


·        
Corruption Eradication Committees:


Maharashtra
State Government’s commitment to combating corruption is facing its real test
in Thane, where a citizen activist has put a spotlight on the District
Collectorate for failing to comply with rules concerning the setting up of
Corruption Eradication Committees (CEC) at the taluka and district level.


The watch-dog
committees, comprising 10 citizens, selected after police verification, besides
a team of administrative and police officials, have been armed with the authority
to inquire into complaints of corruption. The anti-graft panels, initiated in
1996 during the Shiv Sena-BJP regime, raised hopes of finally getting justice
among aggrieved citizens as non-official members would ensure redressal of
public issues during monthly meetings.


The Thane
Collectorate, however, seems to be an exception to the rule aimed at equipping
people with the authority to question the corrupt. Of the 15 talukas, none has
a fully constituted CEC. In fact, the district CEC has just three non-official
representatives as against the mandatory ten.


·        
Cost of getting the information:


Citizens and RTI
activists have a reason to cheer. Now, they can save thousands of rupees which
they pay fee to get ‘readily available’ information under the RTI Act,
According to the Information Commission, they will get the information for Rs 2
per page, as stipulated in the Act.


Several RTI
applicants had complained that they were made to pay through their nose,
particularly while seeking information from BMC’s property-related departments,
such as assessment. Also officers often did not sign or attest papers while
giving information. When they were asked to sign on the documents, they used to
ask applicants to pay as per the BMC rate card which existed before the RTI Act
came into existence. The practice continued despite the fact that the RTI Act
has a superseding effect on all prior rules.


For example,
certified copies were charged at `230 per property in the assessment
department. If the applicant had to ask property details or building details
for more than one property, they would pay in thousands. Apart from this, the
inspection of voluminous information that is free for the first hour and `5 for
every 15 minutes was being charged `150 per hour.


The order from
Information Commission comes after a sustained battle of over one and a half
year by NGO, Mahiti Adhikar Manch, and some active citizens. The State Chief
Information Commissioner, Dr. Suresh Joshi, who heard the matter in March 2009,
passed order dated July 9, 2010, after a series of meetings with additional
municipal commissioners.

Right to Information

Part A : Decisions of CIC

l S. 2(f) and S. 7 :

    Mr. Rakesh Agarwal sought the following information under RTI application to Mr. K. S. Rawat, PIO, Tis Hazari Courts, Delhi :

    1. Whether intimations are sent by each traffic court of Delhi presided over by Spl. M.M.S. as required by S. 210 of the Motor Vehicles Act 1988 ?

    2. If not, reasons for the same.

    3. If yes, copies of all such intimations that pertain to convictions on 9 and 10 January 2008 across all Traffic Courts of Delhi.

    The PIO held that information sought for was not held by or under the control of any public authority and therefore did not fall u/s.2(f) of the RTI Act, which defines ‘information’.

    Further, the PIO stated that the appellant was representing his newspaper/magazine called ‘Nyay Bhumi’ and had filed 3 RTI applications in 15 days and the appellant was working for promotion of his business rather than serving social interest. Hence, it was a blatant misuse of the RTI Act.

    The First Appellate Authority (FAA) directed the PIO to collect the information from the Courts dealing with traffic cases and send it to the appellant within 20 days. The order was passed by FAA beyond 45 days and no hearing was given.

    The following two were grounds of appeal before CIC :

  •     The PIO demanded payment for providing information thereby violating S. 7(6)

  •      FAA did not afford a hearing to the appellant and received the FAA’s order on 25-2-2009 thereby exceeding the time limit set in the Act.

    It may be noted that the PIO had first held that information sought was not covered u/s.2(f) and only when FAA directed to furnish information, he agreed to provide it but only on payment of prescribed fee (i.e., Rs.2 per page). While the appellant’s contention was that having not validly denied supply of information, the same has to be submitted free as provided u/s.7(6) which reads as under :

        S. 7(6) : Notwithstanding anything contained in Ss.(5), the person making request for the information shall be provided the information free of charge where a public authority fails to comply with the time limits specified in Ss.(1).

CIC in the decision stated :

    “It is a basic tenet of statutory interpretation that words of a statute should be interpreted keeping in mind the context in which they appear. Information is to be provided free of cost if S. 7(1) is not complied with. Rejection of a request for any of the reasons specified in S. 8 or S. 9 has to be valid rejection in law. If a ground for exemption from disclosure is wrongly relied upon, then it does not amount to ‘rejection of a request’ as started in S. 7(1). It is absurd to contend that the appellant must be made to pay the additional fees when the PIO wrongly denies information. The Commission finds the PIO’s deliberate misconstruction of the law unacceptable. This is an attempt to obstruct the implementation of the RTI Act and to delay the provision of information to the appellant without any reasonable cause.

    CIC also observed that the PIO on several occasions, all of which are on record, has made unwarranted and irrelevant observations which give the impression that the PIO is malafidely denying information to the appellant. The Commission strongly advised the PIO to refrain from making such comments in future.

    Based on the above, the Commission directed the PIO to provide the information to the appellant free of cost. He was also asked to show cause as to why penalty should not be imposed and disciplinary action be not recommended against him u/s.20(1) of the RTI Act.

    [Mr. Rakesh Agarwal v. PIO, Tis Hazari Courts, Delhi, CIC/SG/A/2009/000675/3390, dated 22nd May 2009]

Ration card :

    The appellant had applied for a ration card in 2006 and in spite of repeatedly being shunted to various places did not get any ration card. The PIO stated that the Government has subsequently declared as to how many BPL cards will be issued and time was set for applications to be made for BPL cards. The Delhi Government accepted applications for BPL cards in February-March 2009 and decided on a maximum number of cards which are to be given. He stated that the applications were received and sent to a Vigilance Committee headed by MLA of the area. He admited that these cards are supposed to be given in 45 days, but the time at the Vigilance Committee headed by MLAs takes indefinite time.

CIC Shailesh Gandhi in the decision stated :

    The appellant has not been given any appropriate reply indicating what is happening to her ration card application. The approximate loss to her per month of free foodgrain and kerosene is about Rs.500 per month. The appellant should have got proper answer to her RTI application by 6-4-2009. The loss of free foodgrain due to her is already for three months by which she has suffered loss of Rs.1500. The Commission also feels that the loss of time and trauma which she suffered on account of not getting her due entitlement and pursuing this application and appeal should be compensated with another Rs.1000. Hence the Commission awarded a total compensation of Rs.2500 to the appellant for loss of entitlement and to compensate for the effort and the trauma suffered in pursuing this matter.

    The PIO was directed to give the information to the appellant before 10th July 2009 about the status of her application giving names and designations of the officers who have dealt with the BPL card application and where the application is presently.

    [Smt. Nagina Devi, Delhi v. PIO, Food Supplies & Consumer Affairs, GNCT of Delhi, CIC/SG/A/2009/001213+1214/3969, dated 2nd July 2009]


Part B : The RTI Act

Annual Report Maharashtra State Information Commission :

Please refer to RtoI of June, 2009. Under other news, I had reported some statistics as covered in the Annual Report of Maharashtra State Information Commission. Now the report in English is published and Dr. Suresh Joshi, CSIC has kindly sent me a copy.

It is Third Annual Report of the year 2008. Some interesting extracts from it:

  • 1,23,000 applications in 2006, 3)6,000 in 2007 and 4,16,090 in 2008 have been received respectively. In bigger States of our country less than one lakh applications come in one year. In the international arena England receives about 60,000, Mexico about 94,000. Similarly the Central Government receives about two and a half lakh applications. Thus it is seen that the people of Maharashtra have given tremendous response to this Act.

  • Understanding the important issues touching the lives of the people by using this Act agitating them on proper platform, fighting injustices, checking corruption, increasing the commitment of government employees to work and increasing the overall transparency in government functioning – many such like issues have been addressed due to the use of this Act.

  • Many young people have thrown themselves in this movement of the Right to Information. Similarly, many people above 60 years have also participated in spreading awareness about right to information. It is heartening to see that associations of officers, employees of the Government of Maharashtra have declared their support for this Act and have appealed to their members to give maximum information to the people through this Act. All these factors have proved useful in obtaining people’s support for this Act.

  • Maharashtra is the only State in the country where Benches of the Information Commission have been set up at the Division, level. Greater Mumbai, Konkan, Pune, Aurangabad, Nagpur already have Benches. Towards the end of 2008 Amravati Bench was constituted and on 24 December 2008 the Information Commissioner was appointed there. Only Nashik Bench now remains to be established and I am hopeful that it would be done soon.

  • Due to the formation of Divisional Benches the Commission’s work has reached nearer to the people. Commissioners have not only heard appeals at the divisional headquarters, but have attempted to hear them at the District level. Therefore people realised that ‘the Commission has come to our doors’ and this was perhaps one of the reasons for increasing number of RTI applications.

  • In 2007 the Commission decided 3611 appeals and complaints. This number is 15026 for the year 2008. The Commission has also started arranging hearings through video conferencing.

Annual Report 2006-07 of Central Information Commission :

(continuing from  July 2009)

v) Collection of Charges by Public Authority (Vide: S. 25(3)(e) of RTI Act) : All the Minis-tries/Departments/ Apex-level Offices taken together collected Rs.30,71,167 in the year 2006-07. In the year 2005-06, the amount collected was Rs.5,08,490. There is six times increase in the amount collected in year 2006-07 over the previous year. Top 10 Ministries collected a total of Rs.22, 82,984 (74.33% of the total) in the year 2006-07.

vi) Disposal  of appeals  (Vide:  S. 25(3)(c) of RTI Act) : All the Ministries/Departments/ Apex-level Offices, on an average, disposed 75% of the appeals received during the year 2006-07. Out of 57 Ministries/Departments/ Apex-level Offices, 22 Ministries have disposed 100% appeals during the year and 65 Public Authorities have received more than 50 appeals.

vii) Implementation   of the Act (Vide:  S. 25(3)(f) of RTI Act) : Efforts taken by Public Authorities to administer and implement the spirit and intention of RTI Act include launching of website to disseminate information with respect to Act and developing Public Grievance Redressal and Monitoring System (PGRMS) by some Ministries. Suggestions were received from Public Authorities about increasing fee for seeking information, for filing first and second appeals, increase in time to respond for older records, and taking up more capacity building programmes.

viii) Recommendations   for Reforms,  etc. (Vide:  S. 25(3)(g) of RTI Act) : The Central Information Commission has made valuable recommendations for reforms and with respect to specific Ministries with a view to make RTI Act more effective. The recommendations include (a) streamlining the procedure of dealing with RTI applications, (b) strengthening of the staff for efficient disposal of RTI applications, (c) implementation of homogeneous fee structure, (d) full conformance with spirit of RTI Act, (e) respect for dignity of citizens. In addition CIC made some observations with similar objectives. These observations are with respect to (a) promotion of employees of Public Authorities, invasion of the privacy, (c) interpretations of rules and Acts, (d) language issues, (e) communication issues, (f) adherence to record retention policies and process of weeding out information, (g) computerisation, (h) training of the staff, and status of governing body and strengthening of staff grievances redressal system.


Part C : Other News

•  Unclaimed money in the banks:

Coming down heavily on banks that keep funds in ‘suspense accounts’, the Central Information Commission has asked RBI to disclose details regarding ICICI Bank. CIC also directed RBI to provide information in 10 days if other banks, including govt-run ones, were following this practice. In his order, Information Commissioner Satyananda Mishra asked RBI to give a “comprehensive reply stating categorically if the RBI had ever issued any instruction on the subject and if according to them such practice was being followed in other banks including public sector banks”. The decision could have far-reaching impact in bringing information on unclaimed money into the public demain.

•  File notings    :

[Further to file notings as appeared in July 2009 issue]

In a Circular issued in the third week of June, DoPT has stated, “It is hereby clarified that file notings can be disclosed except those containing information exempt from disclosure u/s.8 of the Act.” DoPT’s move comes after the CIC had issued notice to two Department officers seeking reason why they should not be prosecuted for disobeying its orders. The Commission had asked the Department to correct its website which said notings couldn’t be disclosed under the Act. DoPT Minister Prithviraj Chavan has said that notings were not part of the proposed amendments to the RTI Act.

•  BSE and  SEBI :

Yogesh Mehta, a former sharebroker, and whom BCAS foundation RTI clinic on ongoing basis provides assistance has again received an order from CIC in his favour. CIC in a landmark order has directed the SEBI to procure information from the BSE’s Investor Protection Fund (IPF) and provide it to Mr. Mehta whose shares worth lakhs of rupees are lying impounded with IPF since last 13 years.

While BSE did not have any objection in providing information to SEBI, it was of the view that SEBI cannot provide the same to the citizen under the RTI Act. It is learnt that now a big battle awaits between BSE, SEBI and the applicant.

•  Mediclaim Policy refund:

The RTI Act has come to the help of thousands of Mediclaim policy holders who have been struggling to get refund for the excess premium they have paid. The Central information Commission (CIC) has directed New India Assurance Company Ltd. to make public the details of the total number of policy holders who are still to get a refund for the excess premium charged. The CIC has asked the company to provide the information on the company’s website and send a copy of information to the Insurance Regulatory Development Authority.

Is vacation an excuse to delay on RTI application?

CIC has ruled that there is no law that allows Courts to give up their obligation under the Right to Information Act even if many staff members are on vacation. CIC’s disapproval came on HC’s failure to furnish an RTI response to an applicant on the ground that staff is lean owing to vacation.

“The Commission finds it difficult to accept that any public authority can claim vacation from RTI for one month which is not provided for in law,” Information Commissioner Shailesh Gandhi noted in a recent decision.

Some Recent Judgments

fiogf49gjkf0d
Service TaxI. HIGH COURT :

    1. Whether bottling of liquor amounts to packaging service ?

    Maa Sharda Wine Traders v. UOI, 2009 (15) STR 3 (MP)

    In this case, the question arose as to whether bottling of liquor amounted to packaging activity, liable for service tax considering that alcohol is not dutiable under the Central Excise Act (although it is liable under the State Excise Laws). The appellant among various others had filed a writ in the High Court primarily to challenge constitutional validity of the definition of packaging activity [S. 65(76b) of the Finance Act, 1994]. However, it was felt that justice would be done even on adopting apposite interpretative process whereby conclusion could be reached as to whether bottling of liquor could be treated as service liable for service tax or treated as ‘manufacture’ u/s.2(f) of the Central Excise Act and therefore, not liable under the service tax law. After doing a detailed analysis of the terms ‘manufacture’ and ‘excisable goods’ and considering the Department’s clarification vide CBEC Circular No. 249/1/2006-CX-4, dated October 27, 2008 in consonance with the statutory provisions as well as the law laid down by the Apex Court in Sir Shadilal Distillery and Chemical Works v. State of Uttar Pradesh, (1998) 8 SCC 428, it was held that bottling of liquor being incidental or ancillary to the completion of a manufactured product was ‘manufacture’ for the purpose of S. 2(f) of the Central Excise Act and since this is excluded from the definition of ‘packaging activity’ under the service tax law, it was held as not liable for service tax. Decision in the case of Vindhyachal Distilleries Pvt. Ltd. 2006 (3) STR 723 (LMP) was accordingly overruled.

    Note :

    The case has been reported in the July issue of BCAJ under the citation SOM Distilleries Pvt. Ltd. & Ors v. UOI & Ors., 2009 TIOL 292 HC MP ST LB. It may be noted further that to render the decision ineffective prospectively, Budget 2009 has sought to amend the definition of ‘business auxiliary service’ by excluding ‘manufacture of excisable goods’ instead of mere ‘manufacture’ in terms of S. 2(f).

    2. Penalty :

    CCE Jalandhar v. Darmania Enterprises, 2009 (14) STR 741 (P&H)

    The Commissioner in this case enhanced the penalty imposed by the Assistant Commissioner while exercising revisional power u/s.84 of the Act from Rs.1,000 to Rs.31,652. The Commissioner also recorded suppression. However, the Tribunal set aside revision order and restored the original order by observing that leniency considered in view of S. 80 did not suffer any illegality and therefore, could not have been interfered by the revisional authority. The Court observed that since no evidence was produced before the revisional authority to prove fraud, misrepresentation, etc., no jurisdiction was acquired by the authority to impose penalty and dismissed the appeal stating that no question of law arose for determination of the Court.

II. TRIBUNAL :

    3. Binding precedent :

    S. V. Colour Lab v. CCE, 2009 (15) STR 231 (Tri. Bang.)

    The issue of excluding cost of paper, chemicals, etc. being covered by the Tribunal decision in case of Shilpa Colour Lab & Others v. CCE, 2007 (5) STR 423 (Tri.-Bang), the Tribunal held that finding of the Commissioner (Appeals) that the Tribunal decision was distinguishable was wrong and against the judicial discipline and allowed the appeal.

    4. Cargo Handling Service :

    ITW India Ltd. v. CCE, Hyderabad 2009 (14) STR 826 (Tri.-Bang)

    The issue in this case related to whether packaging viz. strapping of steel items, a part of manufacturing process which already suffered excise duty, was chargeable to service tax as cargo handling service. Packaging activity was brought under service tax only from 16-6-2005 and the assessee paid service tax from this date. The decision of the Calcutta Tribunal in the assessee’s own case reported at 2007 (8) STR 490 as well as B. K. Thakkar’s case 2008 (9) STR 542 (Tri.) were distinguished. Relying on the Rajasthan High Court’s decision in the case of S. B. Construction Co. v. UOI, 2006 (4) STR 545 (Raj.), wherein it was held that when goods are packed for transport, it should be followed by transportation of the same in order to be covered by cargo handling service. It was held that later amendment in the definition of cargo handling service also linked service of packaging together with transportation of cargo and therefore, demand of service tax under the category of cargo handling service was not sustainable.

    5. CENVAT Credit : Document for availing credit :

(i) CCE Vapi v. Jindal Photo Ltd., 2009 (14) STR 812 (Tri.-Ahd.)

    Credit was taken based on invoices not containing registration number of Input Service Distributor (ISD) viz. the head office of the appellant. However, the receipt of services was not in dispute. Considering that the omission took place when relevant rules were being implemented, credit was held as admissible in terms of the proviso to Rule 9(2) and Rule 14 of the CENVAT Credit Rules.

(ii) Rohit Surfactants P. Ltd. v. CCE, 2009 (15) STR 169 (Tri.-Del)

    Holding that the words ‘directly and indirectly’ used in relation to ‘manufacture’ in the definition of input service had to be given very wide meaning, and relying on the decision in the case of Keltech Energies Ltd. v. Commissioner, 2008 (107) STR 280 (Tri.), it was held that banking & other financial services, general insurance service and courier agency service are to be treated as input service; stay petition was allowed.

6. Chartered Accountant’s Service — whether explanation had retrospective effect ?

    Sridhar & Santhanam v. CCE (ST) Chennai, 2009 (14) STR 756 (Tri.-Chennai)

    Exemption under Notification 59/2002-ST was not extended to a C.A.s’ firm by applying explanation in Notification No. 15/2002-ST re-trospectively. The Notification did not indicate retrospective effect in specific terms, so it was held that the amendment had to be held effective from the date of issue of Notification. Observing that the benefit available on plain reading could not be made retrospective by issuing Notification, the appeal was allowed.

7. Penalty: Levied  u/s.78, whether reducible?

CCE, Mumbai v. Ria Travels & Tours (I) Pvt. Ltd., 2009 (15) STR 124 (Tri.-Mum.)

In this case, the assessee was registered as a travel agent for its multi-locational business. On investigation by DCCEI authority, short payment of service tax was discovered. After upholding the service tax liability as demanded in the SCN, the Divisional Bench was divided on the view of levying penalty u/s.78. The Member Judicial held that in terms of the decision in the case of CCE&E v. Ashish Vasantrao Patil, 2008 (10) STR 5 (Born), the Tribunal has the power to reduce the penalty imposed u/ s.80. The fact that only in one out of twenty branches, the infraction was brought on record, the penalty of Rs.50 lakh in place of Rs.10 cr. would meet the ends of justice. However, the other Member dissented and per majority decision, it was held that mandatory penalty u/s.78, was not reducible as held by the Supreme Court in the case of UOI v. Dharmendra Textile Processors, 2008 (231) ELT 3 (SC) where the suppression was found deliberate. It was further held that the non-obstante S. 80 provided for NIL penalty in case of bonafide belief. The Member Judicial however did not hold that there was bona fide belief. Citing Dharmendra Textile Processor (supra), it was further observed that the Court could interpret the law and not legislate the same and accordingly, the wordings of the statute in S. 78 had to be given full effect by virtue of which the penalty had to be equal the amount of short payment. As such, the penalty of Rs.10 cr. was held as sustained.

8. Valuation:

Sky Gourmet Pvt. Ltd. v. CST, Bangalore 2009 (14) STR 777 (Tri.-Bang.)

The appellant’s services being those of supply of food, beverages, etc. to airlines, were registered as outdoor catering service provider. Supply of food was claimed as exempt under Notification No. 12/ 2003-ST and on which due VAT was paid. Demand was made to receive service tax on gross receipts and agreeing to grant only abatement under Notifications 20/2004-ST and 1/2006-ST but not benefit under Notification No. 12/2003-ST. Invoices evidencing sale were available on records. Considering both the Notifications as mutually exclusive and relying on BSNL v. UOI, 2006 (27) STR 161 (SC), the appellant’s right to avail option of more beneficial Notification was upheld.

Some Recent Judgments

I.          HIGH
COURT :


1.         Applicability
of Service Tax :


Whether laying pipes in
wall/roof/floor, etc. or fixing cable trays and digging earth to lay cables,
etc. liable under ‘Erection, Commissioning or Installation service’.


Commissioner of C. Ex., Chandigarh v.
Rajeev Electrical Works, 2010 (18) STR (P&H)


The appellant, engaged in electrical
fittings obtained registration under ‘Erection, Commissioning or Installation
service’ on 30-11-2004. Since the service was taxable from 1-7-2003, a
show-cause notice was issued for recovery of tax with interest and penalty for
the period 1-7-2003 to 30-11-2004.


The appellant contended that they were
engaged in laying pipes in wall/roof/floor for crossing of wires, fixing the
junction box, etc. and were not involved in any services in relation to
installation of plant, commissioning, machinery and equipment for the period
under dispute.


In Department’s appeal, the High Court held
that laying pipes in wall/roof/floor for crossing of wires, fixing the junction
box, etc. would not amount to installation of plant, commissioning, machinery
and equipment, and therefore was not liable to service tax. A reference was
made to Circular No. 62/11/2003, dated 21 -8-2003 where it was clarified that
putting up electric wires and fitting in residential premises would not be
covered in the definition of taxable service and thus not liable to service
tax.


2.         Applicability
of Service Tax on Rent-a-cab :


Whether tourist permit is essential for
levying tax on tour operator under Rent-a-cab service.


Commissioner of C. Ex., Chandigarh v.
Kuldeep Singh Gill, 2010 (18) STR 708 (P&H)


The respondent was providing transport
service to Indian Oil Corporation (IOC) for which service tax was demanded
under ‘Rent-a-cab’ category.


The Commissioner (Appeals) upheld the levy
of tax and penalty u/s.76.


However, the Tribunal held that since the
cabs were not leased to IOC for use of the vehicles at its own discretion,
service tax was not leviable.


In Department’s appeal to the High Court,
relying upon the decision in Secretary Federation of Bus Operators v. Union of
India, 2006 (2) STR (Mad.), it was observed that S. 65 of service tax
articulates a tourist vehicle and not holding a permit under the Motor Vehicle
Act as necessity for levy of tax. Just because it is essential to hold a permit
under the Motor Vehicle Act, the same cannot be made squarely applicable to
service tax.


Hence, it was held that the respondent
provided transport service and was liable for service tax under Rent-a-cab service.


3.         Order
:


Whether a letter from Commissioner
can be treated as order.


Chief Commissioner, LTU, Bangalore v.
TNT India Pvt. Ltd., 2010 (19) STR 5 (Kar.)


The respondent engaged in door-to-door
international courier service, approached the Additional Commissioner
questioning the applicability of service tax on the service provided by them.
The Additional Commissioner confirmed that the service was not taxable vide
order dated 23-12-2004.


Subsequently the Revenue realised that the
said order was against the Circular No. 341/43/96 TRU dated 31-10-1996 and
hence the order of Commis-sioner was void-ab-initio. A letter dated 9-1- 2006
was issued in this respect. The respondent filed an appeal before the Tribunal
contending that the letter dated 9-1-2006 was an order and the same was
appealable. The order was passed without providing opportunity of being heard
and hence was bad in law. The Tribunal passed the order in favour of the
respondent.


The Revenue then preferred an appeal before
the High Court where the main issues involved were :


(a)        Whether
Tribunal was correct in concluding that the letter of Commissioner was an order
appealable u/s.86, even though same was not passed u/s.73, u/s.83A, u/s.84 or
u/s.85 of the Finance Act, 1994 ?


(b)        Whether
‘International Flight’ activity was taxable service ?


The Revenue asserted that the letter of
Commissioner was only a clarificatory letter and powers conferred u/s.73,
u/s.83A, u/s.84 or u/s.85 of the Finance Act, 1994 were not exercised and
consequently S. 86 for appeals to the Appellate Tribunal could not be made
applicable. Hence, the order passed by the Tribunal was not maintainable.


The respondent contended that the letter
issued by the Commissioner was a valid order u/s.84 and was passed without
providing opportunity of being heard. Similarly the letter issued to the
respondent was different from the letter issued to the lower authorities. The
letter was incomplete and did not contain footnote, which contained directions
to the lower authorities to issue a show-cause notice for recovery of service
tax and interest thereon.


The High Court examined S. 84 pertaining to
revision of orders by the Commissioner and affirmed that any exercise of power
u/s.84 was an order within the meaning of the Finance Act, 1994. The Court
opined that order of the Additional Commissioner was reviewed by the
Commissioner. Therefore, the Commissioner should have provided opportunity of
being heard.


Hence, the High Court held that the
Tribunal was correct in concluding that the letter of the Commissioner was an
order, it was appealable and directed the competent authority to pass a valid
order on the issue of taxability after providing opportunity of being heard.


4.         Powers
of Director General of Service Tax (DGST) :


Whether DGST has power to entertain
appeal against order of lower authorities?


Aircargo Agents Association of India v.
Union of India, 2010 (18) STR 715 (Bom.)


The High Court in its order against writ
petition directed the parties to approach the DGST and the DGST to grant a
hearing before passing an order.


However, the parties contended that the
DGST had no power to entertain appeal against order of the lower authorities
and pass order.


The High Court held that the DGST did not
have power to pass orders.


II.        TRIBUNAL
:


5.         Applicability
of Service Tax :


Whether secondary services provided
towards export of services are exempt ?


Ruth Shipping Agencies Pvt. Ltd. v.
Commissioner of C. Ex., Thirunelveli, 2010 (19) STR 39 (Tri-Chennai)


The appellant, a CHA received brokerage
from steamer agent for arranging containers on which service tax was demanded
as ‘Business Auxiliary Service’. The appellant contended that the service was
non-taxable and the same was accepted by the Assistant Commissioner. However a review
order was passed by the Commissioner who held that the appellant was liable to
tax.


In an appeal preferred to the Tribunal, the
appellant relying on Circular No. 56/5/2003, dated 25-4-2003 contended that
secondary service of arrang-ing a container were primarily used by exporter of
services and they get consumed/merged with exported services, they were not
liable to tax.


The Tribunal holding that the view of the
appellant was corroborated by Lee & Muirhead Pvt. Ltd. v. Commissioner of
Service Tax, Bangalore, 2009 (14) STR 348, the demand was set aside.


6.         Burden
of proof of suppression :


Whether Department owns the burden to
prove suppression of facts by the assessee ?


R. A. C. Steels v. Commissioner of
Central Excise, Salem, 2010 (18) STR 775 (Tri-Chennai)


The Department levied penalty u/s.76,
u/s.77 and u/s.78 of the Finance Act, 1994 invoking extended period of
limitation.


The appellant pleaded to the Tribunal of
their ignorance. However, their prayer that the burden to prove that there was
suppression of facts by the appellant was not discharged by the Department was
accepted and penalties were set aside.


7.         CENVAT
Credit :


Whether CENVAT credit on washing
machines used in factory allowable ?


Commissioner of C. Ex. & ST, LTU,
Bangalore v. Micro Labs Ltd., 2010 (18) STR 771 (Tri-Bang.)


The respondent utilised CENVAT credit on
indus-trial washing machines falling under Chapter 84 of CETA and used for
washing uniforms of employees. The Department denied the credit on the machines
contending that the same are not used in manufacture of final products.


The matter was decided in favour of the
respondent by the Deputy Commissioner, LTU as well as the Commissioner
(Appeals).


The appellant relied upon India Cements
Ltd. v. CCE, Trichy 2006 (205) ELT 170 (Tri-Chennai) where it was held that any
capital goods which do not take part in the process of manufacture are not
eligible for CENVAT credit.


According to the assessee, industrial
washing machines fall within the definition of ‘capital goods’ as defined in
Rule 2(a) of the CENVAT Credit Rules, 2004. Further, the Commissioner (Appeals)
found that requirement of clean clothes is mandatory as per Rule 5.4 of the
Drugs & Cosmetics Act, 1945. The assessee also relied upon the case of
Toyota Kirloskar Motor Ltd. v. CCE, Bangalore-III, 2002 (148) ELT 402
(Tri-Bangalore).


The Tribunal held that the industrial
washing machines fall within Rule 2(a) and as they are used in factory of
manufacture, credit was admissible.


8.         CENVAT
credit on construction :


Whether CENVAT credit on construction
of staff quarters allowable?


The Laxmi Vilas Bank Ltd. v.
Commissioner of Central Excise, Trichy 2010 (19) STR 40 (Tri-Chennai)


CENVAT credit on construction of staff
quarters was disallowed on the ground that the staff residential quarters
located within the bank premises cannot be construed as office relating to bank
premises.


The Tribunal held that construction
services used in staff residential quarters located within the bank premises
are covered under the definition of input service as per Rule 2(l) of the
CENVAT Credit Rules, 2004. So, the CENVAT credit on construction service was
allowed.


9.         Penalty
:


Whether penalty u/s.76 and u/s.78 is
mutually exclusive ?


AR. AS. PV. PV. Motors Erode (P) Ltd. v.
Commissioner of Central Excise, Salem, 2010 (18) STR 722 (Tri-Chennai)


The appellant was ordered to pay penalty
u/s.76 and u/s.78 of the Finance Act, 1994 where service tax and interest were
already paid prior to com-munication of adjudication order.


The appellant contended that the penalty
u/s.76 and u/s.78 was mutually exclusive and since they had paid the penalty
u/s.78 @25%, the penalty imposed u/s.76 was liable to be set aside.


The appellant relied upon S. 78(1) of
service tax and the Tribunal’s decision in the case of M/s. Safe Test
Enterprises v. Commissioner of Central Excise, Salem and argued that since
service tax and interest had been paid prior to communication of the order,
penalty u/s.78 was liable to be reduced.


The High Court agreed with both the
contentions and set aside the penalty u/s.76 and reduced penalty u/s.78 to 25%
of service tax demanded.


10.       Refund
:


Whether refund can be denied on the
grounds beyond the scope of show-cause notice ?


Caliber Point Business Solutions Ltd. v.
Commis-sioner of Service Tax, Mumbai, 2010 (18) STR 737 (Tri-Mumbai)


The appellant, a BPO service provider filed
refund claim under Rule 5 of the CENVAT Credit Rules which was rejected on
technical grounds like ab-sence of registration number on input invoices,
non-availability of original invoices and absence of nexus between input and
output services. How-ever, no explanation was provided for absence of nexus.


The appellant filed an appeal wherein
rejection was made on the ground of absence of nexus, non-utilisation of CENVAT
credit and difference between ST-3 and refund claim. The later two grounds were
not a part of the original show-cause notice.


Relying on Reckitt & Colman of India
Ltd. v. CCE, 1996 (88) ELT 641 (SC), it was held that the Tribunal cannot
travel beyond show-cause notice and favour the Revenue and require the
appellant to meet demands which were never required to be met before the
Revenue.


Regarding the absence of nexus in case of
rent-a-cab service, air travel service and BPO service, the appellant relied
upon CST, Delhi v. Conver-gys India Pvt. Ltd., 2009 (16) STR 198 (Tri-Del.)
wherein it was held that without questioning the CENVAT credit, its eligibility
for rebate cannot be questioned.

Further the refund claim was allowed as the
appel-lant proved the nexus between rent-a-cab service, air travel service and
BPO service.


Refund — GTA service :


Whether service tax on transport
service paid by GTA as well as consignor can be refunded to GTA ?


Commissioner of C. Ex., Cochin v. Garuda
Transport, 2010 (18) STR 773 (Tri-Bangalore)


The respondent filed refund claim of
service tax on transport service paid twice. The tax was paid by him and the
consignor also. The refund claim was rejected by the lower authorities on the
ground of inadequacy of records. An appeal to the Commissioner (Appeals) was
filed by the Revenue.


The Commissioner (Appeals) in his findings
record-ed that the respondent had submitted audited final accounts, freight
bills, challans, CA certificate as to absence of unjust enrichment and
certificate from the sole consignor and accepted double payment of service tax
and held refund claim as valid.


The Revenue contended that the Commissioner
(Appeals) did not verify the documents to prove absence of unjust enrichment.
However, the Tribunal held that findings in order of the Commissioner (Appeals)
indicate that he had verified all the relevant documents and hence the refund
claim was accepted.


11. Review order : Scope :


Whether a review order can be passed
after appeal is filed against the original order ?


Avery India Ltd. v. Commissioner of
Service Tax, Delhi, 2010 (18) STR 760 (Tri-Delhi)


A refund claim of the appellant was accepted
by the Department but was credited to Consumer Welfare Fund. The Commissioner
(Appeals) how-ever passed the order that refund be credited to the appellant’s
account.


On receipt of order from the Commissioner
(Appeals), the Commissioner issued a show-cause notice to review the original
order passed by the lower authorities and later passed an order rejecting the
claim of refund.


The appellant contended that the original
order of the lower authority got merged with the order of the Commissioner (Appeals).
They also claimed that an appeal was filed by the Revenue against the order of
the Commissioner (Appeals) before the date of review order by the Commissioner
and hence the review order and order of rejection of refund based on review
order were not established.


The Tribunal observed that revision powers
of the Commissioner u/s.84 of the Finance Act, 1994 are restricted. As per S.
84(4), “no revision order could be passed by the Commissioner if any issue in
the order was pending before the Commissioner (Appeals).” In the instant case,
the order of the Commissioner (Appeals) was also appealed before the Tribunal.
Hence, the review order was set aside.


12.       Show-cause
notice :


Whether an order, which is at
variance with show-cause notice, is sustainable in law


Glass Fibres v. Commissioner of Central
Excise, Cochin, 2010 (18) STR 726 (Tri-Bangalore
)


The appellant was engaged in the activity
of receipt and stacking operation, loading, packing, repacking, storage, etc.
and was registered as ‘Cargo Handling’ agency. The client of the appellant
refused to pay tax on the activity relating to storage, as it was not covered
as ‘Cargo Handling’ service. The appellant filed a refund claim of
non-reimbursed tax.


The original authority rejected the plea on
the ground that it was covered as ‘Cargo Handling’ services. However, the
Commissioner (Appeals) held that the activities related to storage, stacking
and shifting should be more appropriately classifiable under ‘Storage and
warehousing’ services.


Being aggrieved with the order of
Commissioner (Appeals), the appellant filed an appeal before the Tribunal and
contended as follows :


The Commissioner affirmed the order on the
grounds not mentioned in the show-cause notice. The appellant relied on various
case laws for taking such stand and contended that the order should be seen in
the light of show-cause notice and order-in-original and that the order at
variance of show-cause notice is not sustainable in law.


The Tribunal held that the judicial
authorities amply support the case of the appellant and in facts of the case,
the appeal was allowed and that the appellant was held not liable for service
tax even though the activity was as such taxable for the reason that the demand
was not conformed to the services alleged in the show-cause notice.

Part B — Some recent judgments

fiogf49gjkf0d
New Page 1

1. Supreme Court :

Clearing and forwarding service : Consignment
agent :

Super Polyfabriks Ltd. V. CCE, Punjab, 2008 (10) STR
545 (SC)

The appellant under an agreement with Gas Authority of India
is a ‘consignment stockist’. The period in question was from 1-9-1999 to
31-7-2002. Both the Appellate Authority and the Tribunal dismissed respective
appeals. The short question was, whether in the facts and circumstances of the
case, the petitioner was providing services of clearing and forwarding. The
appellant pleaded that lower authorities proceeded only on the premise that the
agent was clearing and forwarding agent relying on the decision in the case of
Prabhat Zarda Factory P. Ltd. V. CCT, Patna 2002 (145) ELT 222 —
which was subsequently overruled by a Larger Bench in the case of Larsen &
Toubro Ltd. V. Commissioner,
2006 (3) STR 321. The Supreme Court relying on
the decision in the case of V. Lakshmanan v. B. R. Mangalagiri & Others,
(1995 Supp 2 SCC 33) opined that for determination of the liability, the
agreement has to be read as a whole. The purport and object in a contract could
be ascertained only from terms and conditions thereof. Neither nomenclature nor
a particular activity would be decisive. Whether in substance and effect the
person was a clearing and forwarding agent must be ascertained from the terms of
the agreement and conclude whether job of clearing and forwarding agent’s
operation was incidental to the main activity of getting the orders and selling
to clients or otherwise. Matter was remitted back to the assessing authority as
the orders were passed ex-parte because the appellant had not appeared
either before the assessing authority or the Appellate Authority.

2. High Court :

2.1 Construction service : Whether value of material
supplied free of charge includible in the value of taxable service ?

Era Infra Engineering Ltd. V. UOI, 2008 (11) STR 3
(Del.) :

The petitioner, engaged in providing commercial or industrial
construction service, received material free of cost from the owner company, was
issued show cause notice proposing to levy Service Tax on such free supply of
material, based on the explanation in Notification No. 1/2006-ST, which provides
for inclusion of value of goods supplied, provided or used by the provider of
construction service. Relying on the provisions of S. 67(3) and interim order in
the case of Larsen & Toubro v. UOI, 2007 (7) STR 123 (Mad.), the High
Court ruled that until conclusion of adjudication proceedings, material value
supplied free of charge would not be added for determining the taxable value and
that explanation in the Notification would not be applied to the detriment of
the petitioner. [CESTAT Delhi in the case of Millennium Constructions Pvt.
Ltd. V. CST, Delhi,
2008 TIOL 838 CESTAT Del. Waived pre-deposit of interest
and penalty levied when Service Tax demanded on addition of cement and steel
value received from recipient of services was already paid by the  appellant.]

2.2 Penalty : Whether reducible below the minimum prescribed limit ?

UOI v. Aakar Advertising, 2008 (11) STR 5 (Raj.)

The Tribunal in the appeals in question :


à
reduced the penalty imposed to 10% of the duty demanded

à
Entertained an appeal on merits when order was passed dismissing the appeal
for non-payment of pre-deposit.


Short questions that arose in the two appeals aggregated
were :


à
Whether the Tribunal could reduce the penalty imposable u/s.76 below the
minimum prescribed limit ?

à
Whether the Tribunal could entertain an appeal on merits when the Commissioner
(appeals) rejected the appeal because of default in making pre-deposit u/s.35F
of the Central Excise Act, 1944 ?


For the question no. 2, it was pleaded that since the
Tribunal already allowed the appeal, the assessee be granted reasonable time to
comply with requirement of pre-deposit even at such stage and set aside the
order of the Commissioner (Appeals) and direct the Commissioner to decide on
merits. The High Court acceded to such request and directed the Commissioner to
decide the appeal on merits on condition of complying with pre-deposit within 4
weeks’ time.

As regards the question no. 1, it was held that if cause of
failure was reasonable, penalty may be set aside. Penalty could be played with
only between minimum and maximum prescribed limits and could not be reduced
below the minimum prescribed limit under the garb of any discretion. Yet it was
not always necessary to impose maximum penalty. The matter was remitted back to
the Commissioner (Appeals) with a direction to decide the penalty afresh
objectively and dispassionately after hearing the parties and in view of the
above observations in the instant order.

3. Tribunal :

3.1 Cargo handling service :

M/s. Jet Airways (India) Ltd. V. CST, Ahmedabad, 2008
TIOL 979 CESTAT Ahm.

The appellant, an airlines that transports passengers and cargo by air, receives booking of cargo to be transported by themselves at the booking office or through lATA agents appointed at various locations all over the country. The Revenue demanded Service Tax considering the appellant as cargo handling agency, although the appellant neither collected cargo from the premises of consignor, nor delivered the same to the consignee. The appellant contende ‘ that the service of transportation of goods by air was ” made taxable w.e.f. 10-9-2004 without disturbing any of the existing entries. Further that, the Board’s Circular F. No. B/11/1/2002, dated 1-8-2002 while detailing cargo handling services cited illustrations of services provided by Airports Authority of India, Inland Container Depot, Container Freight Station, etc. did not refer to any airlines undertaking transportation of goods. Accepting these pleas and relying on the Tribunal decisions inter alia cases of Dr. Lal Nath Lab. (P) Ltd. v. CCE, 2006 (4) STR 527 (Tri. Del.) and Glaxo SmithKline v. CCE, 2005 (188) EL 171 (Tri.-Mum.), it was held that when new entry is introduced without disturbing existing entries, it has to be held that the new entry was not covered by any previous entry.

3.2 CENVAT Credit:

Hindustan Coca Cola Beverages Pvt. Ltd. v. CCE, Meerut, 2008 TIOL 1022 CESTAT Del.

Considering that manpower supply service was not liable for Service Tax prior to 16-6-2005, the credit of Service Tax paid by the contractor of the company was denied. Stay application was allowed on the ground that since the Revenue accepted Service Tax paid by the contractor, applicant had prima facie – strong case.

3.3 Construction Service:

M/s. Greenview Land & Buildcon Ltd. v. CCE Chandigarh, 2008 TIOL 900 CESTAT Del.

The appellant, a developer and a builder, constructed complex himself without engaging a contractor and sold flats. The order of the original authority was based on DGST Circular dated 16-2-2006, which provided that Service Tax was attracted on such construction. The Commissioner (Appeals) rejected the appeal for non-fulfilment of pre-deposit vide – stay order. The plea of the appellant was that CBCE Circular No. 96/7/2007-ST of 23-8-2007 suppressed the DGST Circular and clarified that when builder did not engage contractor for construction, no service provider-service recipient relationship existed to attract provision of Service Tax. This was accepted by the Tribunal and the matter was remanded for de novo consideration in the light of Circular No. 96/ 7/2007 and without insisting on pre-deposit.

3.4  Export of service:

i) Blue Star Ltd. v. CCE, Bangalore, 2008 (11) STR 23 (Tri.-Bang.)

The appellant booked orders of foreign principals and received commission in convertible foreign exchange and accordingly, contented that such business auxiliary services were provided from India and used outside India fulfilled conditions to construe the services as ‘exports’ in terms of Export of Services Rules, 2005. The Department’s contention was that services were provided in India and refund of Service Tax paid on ‘exported’ services was rejected. The Tribunal held that refund be granted as the conditions of Rule 3(2) were satisfied and the appellant’s services were held as exports. The Tribunal allowed the appeal stating that the Commissioner had not considered the clause in the agreement relating to services rendered by the appellant.

ii) M/s. National Eng. Industries Ltd. v. CCE, [aipur, 2008 TIOL 939 CESTAT Del.

The appellant, an agent of General Motors, USA provided services of sourcing them on contract with Indian Railways. The appellant, although ‘exported’ service, paid Service Tax on the commission received from General Motors through Indian Railways. Refund claim was rejected on the ground that the commission from General Motors was received through Indian Railways in Indian rupees in lieu of foreign exchange and therefore, condition of Rule 3(1)(b) of the Export Rules was violated. According to the appellant, the purchase order of the party provided that agency commission of certain amount of US dollars be paid in equivalent non-convertible Indian rupees at prevailing exchange rate on relevant date and based on this, Indian Railways paid to the foreign party net of the said commission amount.

The Tribunal held that the purpose of Rule 3(2) was to extend benefit of exemption of Service Tax to persons earning convertible foreign exchange and since the equivalent amount payable to the appellant was not released to Indian Railways, the appellant complied with the provision of Rule 3(1)(b). The appeal was allowed while stating that machinery of a statute should be interpreted so as to promote the object and purpose of the scheme and the case should be decided in fulfilment with the legislative intention.
 
3.5  Import of Services: Effective date: Whether 18-4-2006 or 16-8-2002 ?

CCE Raipur  v. Jindal Steel Power Limited,  2008 (11) STR 14 (7)

Contention of the Revenue that services provided by foreign-based commission agent were liable for Service Tax prior to 18-4-2006 under the category of business auxiliary service under Rule 2(1)(d)(iv) of the Service Tax Rules was rejected as the issue is considered settled in the case of Foster Wheeler’s [2007 (7) STR 443], wherein it was held that services provided by a service provider not having an office in India is taxable with effect from 18-4-2006 only with the insertion of S. 66A of the Finance Act, 1994.

3.6  Subcontractor’s services:

JAC Air Services Pvt. Ltd. v. CCE, New Delhi, 2008 TIOL 839 CESTAT DEL

The appellant provided cargo handling services in terms of agreement with Airports Authority of India for import of cargo. Relying on the Board’s instructions contained in F. No. 43/5/97-TRU of 2-7-1997 as to sub-consultancy, the plea of the appellant that they were subcontractors to Airports Authority of India was considered and waiver of pre-deposit was granted.

3.7 Refund: Under Rule 5 of the CENVAT Credit Rules, 2004:

Caliber Point Business Solutions Ltd. v. CCE, Belapur, 2008 (11) STR 15 (Tri.-Mum.)

The appellant exported taxable services and availed CENVAT credit on input services. Refund claim filed under Rule 5 of the CENVAT Credit Rules, 2004 was rejected on the premise of non-application of the said rule to service providers prior to 14-3-2006. Relying on the decision in the case of MNS Global Services (P) Ltd. v. CCE, 2008 (10) STR 273 (7), wherein it was held that any claim filed on or after 14-3-2006 even pertaining to the past period satisfying other requirements of the Rule and the Notification cannot be turned down on a ground which was not a condition of the Rule or Notification, it was held that the issue being identical, the ruling was binding on the Bench. The matter was remanded for a limited purpose of verifying other conditions of Notification 5/2006 CE(NT) as earlier rejection was  made only  on the  ground of non-applicability of Rule 5.

Right to Information

fiogf49gjkf0d

New Page 3


Part A : CIC’s decisions


Public Notaries

Mr. Dhiresh Shah, advocate and notary of Ahmedabad made an
application-appeal to the Central Information Commission in connection with the
processing of the applications of Public Notaries for the renewal of their
licences issued by the Department of Legal Affairs.

During the hearing of the appeal, Mr. Shah pointed out that
there were gross and avoidable delays in renewing the licences of Notaries,
which not only frequently resulted in breaks in their service as Public
Notaries, but also caused them financial hardship and mental worry, and in some
cases, even loss of reputation. He pointed out that the main purpose of his
coming before the Commission was to ensure that a transparent and accountable
system was kept in place, so that not only the renewal applications of Public
Notaries were attended to with speed, but also there was certain accountability
about timely renewal of these licences.

CPIO, Implementation Cell, Department of Legal Affairs,
Ministry of Law and Justice, New Delhi submitted that the information as
requested by the appellant was not centrally maintained. As such, it was beyond
their power to collect and collate it in order to supply it to the appellant.

Upon hearing the parties, the impression the Commission got
was that the respondents were aware of the shortcomings in the system of renewal
of licences of Public Notaries, which caused unexplained and avoidable delays in
effecting these renewals. There was no centralised monitoring of receipt of
renewal applications, their processing and issue of renewal certificates.

The Commission felt that this is one system which was crying
out for reform. The Commission recommended to the public authority — the
Department of Legal Affairs — to institute a system of centralised monitoring of
receipt, processing and final approval of all applications received from Public
Notaries for renewal of their licences. This information should be placed on the
website in order to enable those whose interest it touched to keep themselves
informed about the progress of their renewal applications. Since the number of
such applications in a year is not more than 500 to 600, there is no reason why
centralised monitoring for it could not be put in place. The effort on the part
of the public authority should be to renew the licences well before the expiry
of the time for which the licences were initially issued. This system will not
only save Public Notaries a good deal of anxiety and botheration, it will help
bring to the system much needed accountability and transparency.

Based on the above, CIC directed the head of the public
authority, viz. Secretary, Department of Legal Affairs, to apprise the
Commission within two months of the receipt of the order as to the action taken
by it in respect of the above recommendation of the Commission [S. 19(8)(a) of
RTI Act].

In the course of the hearing, Mr. Shah also pointed out that
the public authority was required to publish in an Official Gazette all
notary-related information which included the issue of notary licences and their
renewals. This has not been done for the past several years.

The Commission also directed that a notice be issued to the
head of the public authority as to why a compensation of Rs.15,000 (Rupees
fifteen thousand only) not be awarded to the appellant for the detriment
suffered by him.

However, Mr. Shah pointed out that he was not interested in
either imposition of a fine or penalty on the respondents, nor was he interested
in compensation. What he actually wanted was that the system must be so improved
as to free it from its several shortcomings which affected a broad cross-section
of Public Notaries. The Commission appreciated the appellant’s position.

We also appreciate Mr. Dhiresh Shah’s spirit.

[No. CIC/AT/A/2007/01451 of 22-4-2008 : Shri Dhiresh
Shah v. Department of Legal Affairs, Ministry of Law and Justice, New Delhi
]


Travel cost of RTI applicant :

This is the case of complaint by Mr. Yogesh Mehta of Mumbai (BCAS
Foundation assists him in his fights from time to time) requesting for penalty
[S. 20(1)] on SEBI and compensation from SEBI [S. 19(8)(b)].

In one RTI application received by SEBI on 6-2-2006,
information was furnished on 14-7-2006. In the other RTI application received by
SEBI on 13-2-2006, information was furnished on 29-9-2006.

The Order of CIC is as under :

  •  The main contention of the respondents (SEBI) is that delay on their part was not intentional and occurred as the requested information was not readily available with SEBI and has to be obtained from BSE. They have emphasised the fact that, as acknowledged by appellant, all information has been provided to him. The respondents have maintained that the information requested by the appellant/complainant, Mr. Yogesh Mehta pertained to several transactions and agencies, collecting and collating the same naturally took time. They have urged that the delays were not without reasonable cause.

  •  On perusing the records and hearing the submissions of both parties, it is decided that no penalty need by imposed on the respondents, because the delay that has occurred in providing the information to the complainant is attributable to the complex nature of the information request

  • On perusing the records and hearing the sub-missions of both parties, it is decided that no penalty need by imposed on the respondents, because the delay that has occurred in providing the information to the complainant is attributable to the complex nature of the information requested, which needed time-consuming collection and collation process, which brings it within the ambit of ‘reasonable cause’ u/s.20(1) of the RTI Act.

  • However, the Commission cannot be oblivious to the fact that the delays in this matter have resulted in detriment to the complainant and has impacted the complainant’s rightful claim to timely information under the RTI Act. He has been compelled to attend CIC hearings on several dates at his own cost for pressing his complaints against the respondents. He has suffered avoidable expenditure in doing so. It is, therefore held that the complainant is entitled to a suitable compensation under Section 19(8)(b) of the RTI Act.

  • In view of the above, it is directed that the public authority, viz. SEBI shall pay an amount of Rs. 10,000 (Rupees Ten Thousand only) as compensation to the complainant within 2 weeks from the date of receipt of this order and intimate the fact of payment to the Commission within 1 week of effecting it. The compensation amount may be paid from the resources of the public authority, viz. SEBI.

[No. ClC/ AT/ A/2006/00591 & 00592 of 26-6-2008 : Mr. Yogesh Mehta v. SEBI]

Income-tax records of a Charitable Trust:

A very significant issue of the concept of personal information vis-a-vis public charitable trust is involved in this case. Mr. J. K. Sachdeva sought information from Directorate General of Income-tax (Exemptions) of one NGO, the Institute of Business Studies and Research, Belapur, Navi Mumbai.

He sought  the following information:

a) Have the trustees filed income-tax returns fo;: years 2004-05 and 2005-06 ?

b) If yes, how  much  income-tax  they have paid for the trust? Copies of the audited statements be provided to me.

c) Has all the expenditure incurred by them been for charitable purpose?

d) How much salaries either in cash or in kind/ movable properties been drawn by the trustees?

e) Have they accounted for all the cash amount received as advanced premium from the students?

f) Have they submitted to the department the purchase agreements of all the properties bought in personal name or in the name of trustees? If yes, copies may be provided to me please.

Information was provided for (a) above, but PIa declined to disclose the rest citing exemption u/ s. 8(1)0) read with S. 11(1) of the RTI Act and on re-lying on number of CIC’s decisions in similar cases.

The Commission, however, noted that this appeal is different from other petitions regarding access to income-tax-return-related information, in the sense that the present appeal is about information regarding a public charitable trust. Given the character of a public charitable trust, it is important to decide whether the income-tax-related information of such trust, when all of its activities are open to public scrutiny, at all be allowed to remain confidential. In other words, whether or not to disclose such information will have to be examined in the context of the Indian Trusts Act, 1882 and whether there could be a public interest in disclosure of such information u/s.8(2) of the RTI Act. Applying S. 8(1)(j), which speaks about personal and private information, to a public charitable trust also needs to be closely examined.

The Commission then felt that these matters should be first seen at the level of the public authority (Appellate Authority) given the public authority’s experience in similar matters. Income Tax Commissioners enjoy the power, u/ s.138(b) of the Income-tax Act, to decide whether confidentially held information, such as certain classes of income-tax returns, be disclosed in public interest. A determination regarding whether to disclose in public interest income-tax returns of public charitable trust, is thus quite in order.

In view of the above, the Commission remitted back the matter to the Appellate Authority (AA), Mr. Laxman Das, Director General of Income Tax (Exemptions), with a direction that he shall give a earing to the parties, including the third-party, and take a decision in this matter within 4 weeks from the date of receipt of this Order.

We shall follow up this case with interest as to what is the final decision in the matter (hopefully shall report in BCAJ next issue).

[No. CIC/ AT/ A/2008/00170 of 30-6-2008: Mr. J. K. Sachdeva v. Directorate of Income-tax (Exemptions)]


Part B : The RTI Act

I am of the opinion that S. 4 of the RTI Act, which provides for ‘Obligations of public authorities’, is the most important Section of the Act to achieve its objectives. To enable the public authorities to comply and carry out these obligations effectively, the Act which received the assent of the President of India on 15-6-2005, vide S. 1(3) read with S. 4(1)(b) provided that every public authority shall publish within one hundred and twenty days (i.e., 12-10-2005) from the enactment of this Act (i.e., 15-6-2005) 17 different items of information.

It is the experience of all that many public authorities even more than 32 months after 12-10-2005 have not complied with these obligations.

Conference was held of all CICs and SICs on 17-10-2007. One of the topics of the discussion was:

“Enforcement of S. 4 of the RTI Act and creation of ‘E-Districts”‘. Some of the major recommendations (9 out of 17) of the conference are hereunder listed:

1. The duty of the Government is to pro-actively make available key information to all. The Public Authorities to ensure that all records that are appropriate to be computerised are, within a reasonable time and subject to availability of resources, computerised and connected through a network all over the country on different systems so that access to such records is facilitated.

2. It is suggested that strict directions be issued by the Central Government, that all the State Governments/Public Authorities should fulfil their obligations laid down u/ sA of the RTIAct, 2005. Failing which, it may lead to penal provisions being invoked against such Public Authority. Secretary of the Department may be held responsible in this regard and be clearly held culpable in case of non-compliance of S. 4(1)(b).

3. The Central and State Governments must necessarily make adequate fiscal allocations for computerisation and connectivity from Information Commission level to Mandal/Taluk level Public Authorities, so as to effectively operationalise the provisions of the RTI Act.

4. Standardisation of procedure is a must for the disclosures mandated u/ sA of the Act.

5. Make all Government services accessible to the common man in his locality, through common service delivery outlets and ensure efficiency, transparency and reliability of such services at affordable costs to realise the basic needs of the common man.

6. Citizen-centric approach to delivery of selected (bulk) services through Common Service Centres (CSC) involving back-office enablement, by way of digitisation of relevant records, process redesign and automation of processes/work-flow.

7. Notification of e-District services u/sA(l) of the Act to enable and legally enforce sharing of information as prescribed, electronically.

8. e-District  to act as an enabler  for facilitating objectives/services relating to RTI being achieved/ delivered. RTI’s legal framework to be leveraged by e-District to make information sharing/ e-services irreversible.

9. Need/feasibility of notifying CSCs as APIOs under the Act.


Part C : Other News

•  Personal Information:

Residential phone number, mobile number and e-mail fall under the category of personal information. This was decided by the Information Commission in response to the RTI application seeking such details for the President of India.

•  PIO provides false information:

PIO of the Brihanmumbai Municipal Corporation (BMC) replied in response to an RTI query that BMC has already written to SSC Board when asked as to what BMC is doing to make instructions in Tamil medium possible up to class X, which presently is only up to class VII in select BMC schools. Fact is that such letter was not written and was written a few days after such a query was raised. Interesting point is that when BMC Commissioner Jairaj Phatak was informed on this issue, he said: “There must have been some technical error. What they would have meant is that the letter was in the process of being drafted.”

•  Cabinet    documents:

Mr. Suresh Joshi, SIC, Maharashtra holds the view that u/s.8(1)(i) of the RTI Act, all the documents brought before the State Cabinet are confidential and there is no access to such documents under the RTI. The senior official in the Secretariat also says “Once decisions are taken, we will issue specific orders. However, applicants are asking for the cabinet note, which contains stringent remarks on all the departments. In our opinion, such documents should not be made public.”

However, it is the view of the Central Information Commission that all file notings are available for access in the RTI. Further, S. 8(1)(i) which provides for exemption also has proviso thereto restricting the exemption. Clause with two provisos is as under:

8(1)(i):    Cabinet papers including records of deliberations of the Council of Ministers, Secretaries and other officers:

Provided that the decisions of Council of Ministers, the reasons thereof, and the material on the basis of which the decisions were taken shall be made public after the decision has been taken, and the matter is complete, or over:

Provided further that those matters which come under the exemptions specified in this Section shall not be disclosed.

•  Information on FIls under the RTI Act:

Acting on an RTI appeal over SEBI’s denial to divulge details on yearly net investment figures by each FII during 2005, 2006 and 2007, the apex information panel has asked SEBI to consult other stake-holders like the Finance Ministry, the RBI and over 800 FII and decide on the matter afresh. SEBI has to take a call on this matter within two months.

While issuing the order, Information Commissioner, A. N. Tiwari said: “SEBI would examine the matter closely in terms of extant practices/instructions, consult all or a section of stakeholders, examine international practices and obtain views of top functionaries in the field and the Government, before formulating a response.”

Even as the Commission had brought stock exchanges under the RTI last year, the Bombay Stock Exchange and the National Stock Exchange havo challenged it before the Courts. Ironically, in that case the SEBI stood against the Finance Ministry to argue that bourses should be brought under the transparency law.

Air-travel on Air India of high-profile passengers:
Air India has requested the Government to exempt travel information on high-profile passengers -like politicians, businessman and film stars – from being divulged under the Right to Information (RTI) Act as it would hamper its business interests.

In the request made, it is stated: Aviation is a competitive industry and only Air India is covered under the RTI. We will lose out on business interests if we give out details.

Air India is also troubled with a recent query by a TV channel on how Judges were holidaying at public expense, which class the Judge (and his wife) travelled. According to some report, “The Chief Justice of India, K. V. Balkrishnan, made seven tripss abroad in 2007 travelling first class with his wife at Rs.39 lakh (air fare) – something that no other airline would ever divulge.”


OECD — RECENT DEVELOPMENTS — AN UPDATE

International Taxation

In June, 2010 issue of BCAJ, we covered various important
developments at OECD till then. In this issue, we have covered further major
developments after publication of the last Edition of OECD Model Tax Convention
(‘MC’) and developments in the field of Transfer Pricing and work being done at
OECD in various other related fields and have included the same in this update.
We shall endeavor to update the readers on major developments at OECD at regular
intervals. Various news items included here are sourced from various OECD
Newsletters.

A. Amendments to OECD Model Tax Convention :


1. Draft contents of the 2010 update to the Model
Tax Convention — 21st May, 2010 :


The OECD Committee on Fiscal Affairs has just released the
draft contents of the 2010 update to the OECD Model Tax Convention prepared by
Working Party 1 of the Committee. The update will be submitted for approval of
the Committee in June and the OECD Council in July.

The 2010 update will include the changes that were previously
released for comments in the following discussion drafts :

  •  The
    granting of treaty benefits with respect to the income of Collective Investment
    Vehicles :


The draft report was released on 9th December 2009 (see
http://www.oecd.org/dataoecd/47/3/44211901.pdf). It was based on an earlier
report by the Informal Consultative Group on the Taxation of Collective
Investment Vehicles and Procedures for Tax Relief for Cross-Border Investors,
which itself was released for comments on 12th January 2009 (see http://www.oecd.org/dataoecd/34/26/41974553.pdf).
The changes to the Commentary on Article 1 included in the report were slightly
modified, based on the comments received at the February 2010 meeting of Working
Party 1 (WP1) on Tax Conventions and Related Questions (the CFA subsidiary body
responsible for changes to the OECD Model Tax Convention).

  •  
    Revised discussion draft of a new Article 7 of the OECD Model Tax Convention :


The draft was released on 24th November, 2009 (see http://www.oecd.org/dataoecd/30/52/44104593.pdf).
That revised draft reflected a number of changes made to the first version of
the new Article released on 7th July, 2008 (see http://www.oecd.org/dataoecd/37/8/40974117.pdf).
A few additional changes were made, based on the comments received on the
revised draft, at the February 2010 meeting of WP1.

  •  
    Application of tax treaties to State-owned entities, including Sovereign Wealth
    Funds :


The draft was released on 25th November 2009 (see http://www.oecd.org/dataoecd/59/63/44080490.pdf).
The changes included in this note reflect a few modifications made at the
February 2010 meeting of WP1 in light of the comments received on the changes
proposed in that draft.

  •  Tax
    treaty issues related to common telecommunication transactions :


The draft was released on 25th November, 2009 (see http://www.oecd.org/dataoecd/59/62/44148625.pdf).
The changes included in this note reflect a few modifications made at the
February 2010 meeting of WP1 in light of the comments received on the changes
proposed in that draft.

  •  
    Revised changes to the Commentary on paragraph 2 of Article 15 :


The first draft of these changes was released in April, 2004
(see http://www.oecd.org/dataoecd/52/61/31413358.pdf). Based on the comments
received and a public consultation meeting with business representatives and
other interested parties held on 30th January, 2006, a number of modifications
were made and revised proposals were released for comments on 12th March, 2007
(see http://www.oecd.org/dataoecd/36/32/38236197.pdf). The final version of the
changes included in this note reflects a number of additional changes made
following the comments received on that second discussion draft.

As all the substantive contents of the 2010 update have
previously been released for comments through these discussion drafts, this
draft is released for information only and not for additional comments. The
introduction to the draft summarises how the main comments received on these
discussion drafts have been dealt with.

The update will also include a number of changes to OECD
countries’ reservations and observations and to non-OECD countries’ positions,
which will be added to the update in the next few weeks. Among these will be the
elimination of all reservations and positions on Article 26 (Exchange of
Information), which the OECD Council has already approved.

The Committee on Fiscal Affairs has been asked to discuss and
approve the draft update at its June, 2010 meeting. A revised version of the
Model Tax Convention that will incorporate the changes made through the update
is expected to be released in September, following the approval by the OECD
Council.

2. OECD Releases Report on Granting of Treaty
Benefits with respect to the Income of
Collective Investment Vehicles — 31st May,
2010 :


The OECD Committee on Fiscal Affairs has released a Report on
‘The Granting of Treaty Benefits with respect to the Income of Collective
Investment Vehicles’ which contains proposed changes to the Commentary on the
OECD Model Tax Convention dealing with the question of the extent to which
either collective investment vehicles (CIVs) or their investors are entitled to
treaty benefits on income received by the CIVs. These changes are expected to be
included in the 2010 update to the Model Tax Convention (the draft contents of
which were released on 21st May, 2010) and the Report would then be included in
volume II of the loose-leaf and electronic versions of the Model.

The Report is a modified version of the Report ‘Granting of Treaty Benefits with respect to the Income of Collective Investment Vehicles’ of the Informal Consultative Group on the Taxation of Collective Investment Vehicles and Procedures for Tax Relief for Cross-Border Investors (‘ICG’) which was released on 12th January 2009. In that original Report, the ICG addressed the legal and policy issues specific to CIVs and formulated a comprehensive set of recommendations addressing the issues presented by CIVs in the cross-border context. The Committee referred the recommendations by the ICG to its Working Party 1 (‘WP1’) on Tax Conventions and Related Questions (the Committee’s subsidiary body responsible for changes to the OECD Model Tax Convention) for further consideration. The WP1 Report was issued as a discussion draft on 9th December 2009 and modified in response to public comments.

The main conclusions and recommendations of the Report are similar to those in the ICG Report, with some modifications that reflect the varied experiences of the tax authorities of the OECD countries. Like the ICG Report, the Report therefore analyses the technical questions of whether a CIV should be considered a ‘person’, a ‘resident of a Contracting State’ and the ‘beneficial owner’ of the income it receives under treaties that, like the OECD Model Tax Convention, do not include a specific provision dealing with CIVs (i.e., the vast majority of existing treaties). Further, the Report includes changes to the Commentary on the Model Tax Convention to reflect the conclusions of the Committee with respect to these issues.

Although these changes to the Commentary will clarify the treatment of CIVs, it is clear that at least some forms of CIVs in some countries will not meet the requirements to claim treaty benefits on their own behalf. Accordingly, the Report also considers the appropriate treatment of such CIVs under both existing treaties and future treaties.

With respect to existing treaties, the Report concludes that, if a CIV is not entitled to claim benefits in its own right, its investors should in principle be able to claim treaty benefits. The Report reflects different views regarding whether such a right should be limited to investors who are residents of the Contracting State in which the CIV is organised, or whether that right should be extended to treaty-eligible residents of third States. In any event, administrative difficulties in many cases effectively prevent individual claims by investors. Accordingly, the Report concludes that countries should adopt procedures to allow a CIV to make the claim on behalf of investors.

With respect to future treaties, the Report endorses the ICG recommendation that the Commentary on Article 1 of the Model Tax Convention should be expanded to include a number of optional provisions for countries to consider in their future treaty negotiations. Inclusion of one or more of these provisions in bilateral treaties would provide certainty to CIVs, investors and intermediaries. The favoured approach for such a provision would treat a CIV as a resident of a Contracting State and the beneficial owner of its income, at least to the extent that its investors would themselves be eligible for benefits from the source country, rather than adopting a full look-through approach. Because different views were expressed on the issue of whether treaty-eligible residents of third countries should be taken into account in determining the extent to which the income of a CIV should be entitled to treaty benefits, the proposed Commentary includes alternative provisions that adopt different approaches with respect to the treatment of treaty-eligible residents of third countries. The proposed Commentary also includes an alternative provision that would adopt a full look-through approach, under which the CIV would make claims on behalf of its investors rather than in its own name. The look-through approach would be appropriate in cases where the investors, such as pension funds, would have been eligible for a lower, or zero, rate of withholding had they invested directly in the underlying securities.

B.    Amendments to OECD Transfer Pricing Guidelines:

1.    OECD invites comments on the Transfer Pricing Aspects of Intangibles — 2nd July, 2010:

The OECD is considering starting a new project on the Transfer Pricing Aspects of Intangibles and is inviting comments from interested parties on the scoping of such a project. Comments should be sent before 15th September 2010 to Jeffrey Owens, Director, CTPA (jeffrey.owens@oecd.org).

The OECD’s Committee on Fiscal Affairs is now completing its work on two transfer pricing projects which the OECD Council will be asked to approve by the end of July in the form of revisions to the Transfer Pricing Guidelines for Multinational Enterprises and Tax Administrations (TPG)?: its review of Comparability and Profit Methods and its report on the Transfer Pricing Aspects of Business Restructuring.

In these two projects, transfer pricing issues pertaining to intangibles were identified as a key area of concern to governments and taxpayers, due to insufficient international guidance, in particular on the definition, identification and valuation of intangibles for transfer pricing purposes.

OECD guidance on the transfer pricing aspects of intangibles is currently found in the TPG, especially in Chapters VI and VIII. Further and updated guidance will be available in the revised Chapters I-III of the TPG and in the final report on the Transfer Pricing Aspects of Business Restructuring once those are approved by the Council and publicly released. Intangibles are also addressed in the July 2008 Report on the Attribution of Profits to Permanent Establishments and in the Commentary on Article 12 of the Model Tax Convention.

The OECD is now considering starting a new project on the Transfer Pricing Aspects of Intangibles which could result in a revision of Chapters VI and VIII of the TPG. Working Party No. 6 of the Committee on Fiscal Affairs is still at the stage of scoping such a possible new project and would welcome the views of interested parties on?: what they see as the most significant issues encountered in practice in relation to the transfer pricing aspects of intangibles; what shortfalls, if any, they identify in the existing OECD guidance; what the areas are in which they believe the OECD could usefully do further work; and what they believe the format of the final output of the OECD work should be. Comments should be sent before 15th September 2010 in Word format to Jeffrey Owens, Director, CTPA (jeffrey.owens@ oecd.org).

Selected business commentators will be invited to meet with Working Party No. 6 on 9th November 2010 in Paris.

C.    Tax Transparency and Exchange of Information Agreements:

1.    OECD updates — Brazil, Indonesia ranked as implementing International Information Standard — 3rd June 2010?:

As a result of details provided to the Global Forum on Transparency and Exchange of Information for Tax Purposes, Brazil and Indonesia are now ranked in the category of jurisdictions that have substantially implemented the internationally agreed tax standard.

The OECD said it had updated its progress report, first issued in conjunction with the G20 London summit in April 2009, to take account of communications from Brazil and Indonesia on their legal and regulatory frameworks for exchange of information.

According to the information provided, Brazil has more than 25 bilateral tax treaties that provide for exchange of information in tax matters to the internationally agreed standard while Indonesia has 53 agreements that meet the standard. The two countries joined the Global Forum last September.

A full description of the two countries’ legal and regulatory frameworks will be included in the Global Forum’s 2010 annual assessment to be published later this year. As with all members of the Global Forum, both the countries will undergo peer reviews of their exchange of information laws and practices, Brazil in 2011 and 2012 and Indonesia in 2011 and 2013. Brazil is a member both of the Forum’s Steering Group and of its Peer Review Group.

Since April 2009, more than 500 bilateral tax information exchange agreements have been signed worldwide, with 28 jurisdictions joining those ranked as having substantially implemented the internationally agreed standard.

For more information, visit the following sites:
www.oecd.org/tax
www.oecd.org/tax/transparency
www.oecd.org/tax/evasion

B.    Amendments to OECD Transfer Pricing Guidelines:

2.    A boost to multilateral tax cooperation: 15 countries sign updated Convention on Mutual Administrative Assistance in Tax Matters — 27th May, 2010:

In April 2009, the G20 called for action “to make it easier for developing countries to secure the benefits of the new cooperative tax environment, including a multilateral approach for the exchange of information.” In response, the OECD and the Council of Europe developed a Protocol amending the multilateral Convention on Mutual Administrative Assistance in Tax Matters to bring it in line with the international standard on exchange of information for tax purposes and to open it up to countries that are neither members of the OECD, nor of the Council of Europe.

On 27th May 2010, the updated Convention was presented to Ministers and Ambassadors attending the annual OECD Ministerial meeting held in Paris and was signed by 11 countries already Parties to the Convention (Denmark, Finland, Iceland, Italy, France, the Netherlands, Norway, Sweden, Ukraine, the United Kingdom and the United States). In addition, Korea, Mexico, Portugal and Slovenia signed both the Convention and the amending Protocol.

The Convention provides for a wide range of tools for cross-border tax co-operation including exchange of information, multilateral simultaneous tax examinations, service of documents, and cross-border assistance in tax collection, while imposing extensive safeguards to protect the confidentiality of the information exchanged (see background brief for more information). Once the Protocol has entered into force, the Convention will become a more powerful tool for multilateral tax cooperation as it will enable a wider group of countries to become parties and will require full exchange of information on request in all tax matters without regard to a domestic tax interest requirement or bank secrecy for tax purposes.

3.    Three Caribbean jurisdictions move up on OECD progress report — 19th May, 2010:

Dominica, Grenada and Saint Lucia have been moved into the category of jurisdictions considered to have substantially implemented the standard on transparency and exchange of information, having now all signed at least 12 exchange of information agreements conforming to the standard.

This brings to 28 the number of jurisdictions that have moved into this category since April 2009. The move affecting Dominica, Grenada and Saint Lucia follows the signature of a series of agreements involving these three jurisdictions plus Antigua and Barbuda, which had already reached 12 agreements on 7th December 2009, and the Nordic countries (Denmark, Faroe Islands, Finland, Greenland, Iceland, Norway and Sweden).

Following these signatures, Antigua and Barbuda has now signed a total of 20 agreements meeting the international standard. Dominica and Grenada have now signed 13 agreements each, and Saint Lucia has signed 15 agreements.

As members of the Global Forum on Transparency and Exchange of Information for Tax Purposes, each of these jurisdictions agreed to participate in a peer review of their laws and practices in this area. According to a schedule published by the Global Forum, Antigua and Barbuda, Grenada and Saint Lucia will undergo reviews of their legal and regulatory framework for exchange of information in 2011 and reviews of their information exchange practices in 2013. Dominica’s peer reviews will take place in 2012 and 2014.

For more information, visit: www.oecd.org/tax/transparency/ www.oecd.org/tax and www.oecd.org/tax/evasion.

Limited Liability Partnerships

1. Introduction :

    1.1 31st March, 2009, the last day of the financial year 2008-09, saw the Notification of the Limited Liability Partnership Act, 2008 (‘the Act’). The desirability of LLP as a business entity has been expressed by various committees, such as the Bhat Committee (1972); Naik Committee (1992); Expert Committee on Development of Small Sector Enterprises headed by Sh. Abid Hussain in 1997; Study Group on Development of Small Sector Enterprises (SSEs) headed by Dr. S. P. Gupta (2001), Naresh Chandra Committee on Regulation of Private Companies and Partnerships (2003); Dr. J. J. Irani Committee on New Company Law (2005).

    In spite of these recommendations, India has been a bit late in recognising this extremely popular form of a business entity, considering that countries such as the USA have enacted a law dealing with Limited Liability Partnerships (‘LLPs’) as far back as in the early 1800s. Internationally, most venture capital funds/private equity funds/hedge funds are structured in the form of LLPs.

    Nevertheless as the old adage goes, ‘better late than never’, India has come out with a law on LLPs at a time when the Small and Medium Sector is growing rapidly and entity such as an LLP is the right answer for this sector. The Finance (No. 2) Bill, 2009 has provided for taxation of LLPs.

    1.2 LLPs lie somewhere in between the corporate sector which have limited liability but are highly regulated and the unregulated partnership sector which has unlimited liability. LLPs provide a great deal of flexibility and also limited liability. It is important to note that even though the term LLP signifies a partnership, the Act falls within the purview of the Ministry of Corporate Affairs (MCA) and the Registration and all other procedures are carried out by the RoC and not the Registrar of Firms.

    1.3 By a series of Articles, let us examine some of the key features of the Act and some possible issues which may arise.

2. Features of an LLP :

2.1 Body corporate :

    The most important aspect of an LLP is that it is treated as a body corporate, i.e., it is an independent legal entity with a distinct identity which is separate from its partners. As compared to this a partnership firm does not have an identity separate from its partners. An LLP has the following features of a body corporate :

    (a) It has a perpetual succession.

    (b) Its existence is not dependent upon its partners and hence, even if there were to be a change in its partners, the LLP’s status would remain unchanged. Death, insolvency, retirement of any partner has no bearing on the LLP.

    (c) The property of an LLP is its own property and not the property of its partners. It can own property, whether immovable, movable or tangible, in its own name since it is a separate legal person.

    (d) It is capable of suing and being sued in its own name.

    (e) It can have a common seal.

2.2 Liability :

    The liability of an LLP is to be met out of its property only and the liability does not extend to the partners. Thus, unlike in the case of a partnership firm, the partners are not personally liable for the dues of the LLP. This feature of an LLP is similar to a company where the shareholders and the company are separate legal entities. If the partner, knowingly, does any act which is outside the scope of his authority, then the LLP will not be bound by any such act. If the LLP does or the partners do any act with an intent to defraud, then the LLP and the partners shall have unlimited liability for all the debts of the LLP.

3. Incorporation Document :

    3.1 To incorporate an LLP, the following steps must be taken :

    (a) Two or more persons must come together to carry on any lawful business with a view to earn profits.

    (b) They must subscribe to an ‘Incorporation Document and Statement’ in eForm-2. The Statement is to be digitally signed by a person named in the incorporation document as a designated partner and he must have a DPIN. The Statement must also be digitally countersigned by an advocate/company secretary/chartered accountant/cost accountant in practice who is engaged in the formation of LLP. In case of foreign nationals residing outside India and seeking to register an LLP in India, their signatures and address on the incorporation documents and proof of identity, where required, shall be notarised before the notary of the country of their origin.

    (c) The RoC after satisfying himself about compliance with relevant provisions of the LLP Act will register the LLP, within a maximum period of 14 days of the filing of eForm-2 and will issue a certificate of incorporation in Form-16.

    3.2 An LLP should have a registered office. Its name should be as per the guidelines laid down in this respect. The last words of the name should be limited liability partnership or LLP, e.g., the name of an LLP could be ‘Apex Venture Fund LLP’.

    3.3 The partners of the LLP have to enter into an LLP Agreement.

4. Partners :

    4.1 Just as a company has members, an LLP has partners. As per S. 5 of the Act, any individual or any body corporate can be a partner of an LLP. However, in any of the following cases, an individual cannot be a partner in an LLP :

    (a) If he is adjudged to be of unsound mind by a Court.

    (b) If he is an undischarged insolvent.

    (c) If he has applied to be adjudicated as an insolvent and his application is pending.

    Any body corporate can also be a partner of an LLP. The term body corporate has been defined u/s.2 of the Act to mean a company as defined in S. 3 of the Companies Act, 1956, and also includes an LLP registered under the Act, an LLP incorporated abroad, a company incorporated abroad. However, it does not include a corporate sole, a co-operative society and any other body corporate so notified by the Government. Since an LLP is also a body corporate, one LLP can become a partner in another LLP. Two or more companies can also come together to form an LLP. LLPs could be the future for consortium type of arrangements.

4.2 Each LLP must have a minimum number of 2 partners. This feature is at par with a partnership. There is no limit on the maximum number of partners which an LLP can have. A partnership or an AOP cannot have more than 20 partners/members or else it becomes an illegal association. A private limited company cannot have more than 50 members. However, an LLP has no limit on the number of partners. Thus, in this respect it is at par with a public limited company. It is this feature of an LLP which makes it a very attractive structure from a VC/PE perspective since the fund can have as many investors as it likes.

4.3 Designated Partner:

    a) The concept of a ‘Designated Partner’ has been introduced by the Act. S. 7 requires an LLP to have at least 2 designated partners, both of whom should be individuals and one of whom should be a resident in India. If there are only 2 partners in an LLP, then both should be treated as designated partners.

    b) In case, both the partners are LLPs/companies, then partners of such LLPs or nominees of such companies should become designated partners.

    c) The Act incorporates a part of the definition of the term ‘resident in India’ from S. 2 of the Foreign Exchange Management Act, 1999. A resident has been defined to mean a person who resided in India for not less than 182 days during the immediately preceding financial year.

    d) The individual must give his prior consent to become a designated partner.

    e) To become a designated partner, an individual must obtain a Designated Partner Identification Number (DPIN).

    f) A designated partner is one who is responsible for carrying out all the compliance obligations of the LLP imposed by the Act. He is also liable to all the penalties imposed on the LLP for contravention of any of these provisions of the Act. One may loosely equate him with the Managing Director of a company.

    g) Any person can be appointed as a designated partner and he may retire also. Any vacancy must be filled within 30 days.

4.4 Relationship of Partners:

a) The mutual rights and duties of the partners of an LLP are governed by the LLP agreement. If there is no such agreement, then S. 23(4) of the Act provides that the mutual rights and duties of the partners shall be as set out in the First Schedule to the Act. Such an agreement and any changes, therein, must be filed with the RoC.

b) For the purposes of the business of the LLP, every partner of an LLP is an agent of the LLP but not of the other partners. This is a fundamental difference between an LLP and a partnership firm, wherein mutual agency is a key condition of the partnership. Each partner is an agent of the firm and of the other partners. S. 4 of the Partnership Act defines a partnership as “the relation between persons who have agreed to share the profits of a business carried on by all or any of them acting for all”.

4.5 A person can resign from the LLP by giving a notice to other partners. A person would cease to be a partner on his death or on dissolution of the LLP or if he is declared to be of an unsound mind or if he has been adjudged as an insolvent. When a person ceases to be a partner, the LLP shall file a notice in the prescribed form with the RoC.

5. Contributions:

5.1 A partner of an LLP contributes towards the capital of the LLP. The obligation of a partner to contribute shall be as per the LLP Agreement.

5.2 The contribution can be in the following forms:

a) Tangible, movable, immovable, intangible property or a;ny other benefit to the LLP, e.g., land, goods, IPRs, etc.

b) Money, promissory notes, agreement to contribute cash or property and contract for services to be performed.
 

The monetary value of the contribution of each partner should be accounted for and disclosed in the accounts.

5.3 If the contribution is in kind, then the same must be valued by a practising CA or an approved valuer. No methodology has been prescribed for the valuation.

6. Tax Treatment:

6.1 The Finance (No. 2) Bill has prescribed the tax treatment for LLPs. The provisions are effective from A.Y. 2010-11. LLPs would now be taxed at par with partnership firms. Thus, the LLP will pay tax on its profits and the partners will receive their share in the LLP tax-free [5. 10(2A)]. The LLP will pay tax @ 30%. The Finance Bill has abolished the surcharge of 10% payable by firms and hence, even LLPs will not have to pay any surcharge. The 3% cess continues and hence, the net rate will be 30.9%.

6.2 LLP will get a deduction for remuneration paid to its working partners. The limits of S. 40(b) have been streamlined and simplified both for firms and LLPs:

a) On the first Rs.3 lakhs of book-profit – A deduction which is the higher of Rs.1.5 lakhs or 90% of the book-profits

b) On the balance book-profits – A deduction @ 60% of book-profits.

Any interest payment by the LLP to a partner in excess of 12% p.a. would be disallowed and any salary, remuneration, commission to non-working partners would be disallowed.

6.3 There will be no incidence of MAT or Divi-dend Distribution Tax or liability to Deemed Dividend on the LLP.

6.4 S. 45(3) would apply to the admission of a partner and S. 45(4) would apply to the dissolution of an LLP or retirement of a partner.

6.5 There is no express provision for the tax treatment of merger or demerger of two LLPs. The provisions contained for amalgamation or demerger in the Income-tax Act, only apply to companies and not to LLPs. It would be beneficial if the Finance Act, 2009 provides for this situation.

Readers View

fiogf49gjkf0d
The Editor,
BCAJ,
Mumbai – 400 020.

17th July, 2013

Dear Sir,

Re: FDI Reforms

Faced with harsh economic environment, both domestic as well as global, the Dollar starved Government has ushered in FDI Reforms. It has increased FDI Limits in 12 sectors (excluding Civil Aviation, Multi Brand Retail and News Media). In several sectors, 49% limit has been changed to Automatic Route from the FIPB Route. The decision was taken by 11 Key Ministers by consensus. Same day it was reported that Posco of South Korea has junked its $5.3 billion Karnataka Steel Project because of inordinate delay in getting iron ore mining rights. Other FDI Projects in Steel Sector proposed in last 10 years by Arcelor Mittal and others have not yet seen fructification due to delays in Land Allotment and getting exclusive Coal and Iron Ore Mining rights.

Besides the Reforms at Policy Level, the FDI Regulations are such a maze of Press Notes, Circulars, Notifications, Clarifications etc. that leave aside a foreigner, even the Regulators and Expert Consultants cannot find their way through . At times, the RBI does not implement the policy level changes made by the Finance Ministry, Commerce Ministry and DIPP.. Therefore, there is an urgent need to cut thru the clutter of such Press Notes, Circulars and Notifications and ensure that all the concerned ministries and their Officials and RBI are on the same page.

Further, the Reform Mindset has to percolate down to the State Government and the Municipal Authorities Today, it is seen that the Local Bureaucrats and Politicians, whether high or low, are not concerned with development of the State or the Country; their only concern is how do they get their pound of the flesh. They look for opportunities to milk the Businessmen and Industrialists, who are, therefore, looking for greener pastures abroad.

The decision to open up some sectors of the economy to greater foreign investment is a step in the right direction, coming as it does at a time when the country needs such investment to plug a yawning current account deficit. But the idea will not work if the government imposes unreasonable restrictions which put off investors.. While ensuring that loopholes are not exploited, the effort must be to make implementation of rules investor-friendly. The rules themselves must be fair and transparent. Only then will the benefits flow. If Governments, both at the Central and at the States, do not take care of the above, the policy relaxations will remain on paper and would not result in inflow of Foreign Exchange as earnestly hoped by the Union Cabinet and such hope will only remain a “Maya” (illusion).

Yours sincerely,

Tarun Singhal

levitra